CNA Financial Corporation Third Quarter 2026 Results November 2, 2026
Notices and Disclaimers Forward Looking Statements The statements made in the course of this presentation and/or contained in the presentation materials may include statements that relate to anticipated future events (forward-looking statements) rather than actual present conditions or historical events. These statements are made pursuant to the safe harbor provisions of the Private Securities Litigation Reform Act of 1995 and generally include words such as “believes,” “expects,” “intends,” “anticipates,” “estimates” and similar expressions. Forward-looking statements, by their nature, are subject to a variety of inherent risks and uncertainties that could cause actual results to differ materially from the results projected. Many of these risks and uncertainties cannot be controlled by CNA. For a detailed description of these risks and uncertainties, please refer to CNA’s filings with the Securities and Exchange Commission available at cna.com. Any forward-looking statements and other financial information contained in this presentation speak only as of the date hereof. Further, CNA does not have any obligation to update or revise any forward-looking statement made in the course of this presentation and/or contained in the presentation materials even if CNA’s expectations or any related events, conditions or circumstances change. Reconciliation of GAAP Measures to Non-GAAP Measures This earnings presentation contains financial measures that are not in accordance with accounting principles generally accepted in the United States of America (GAAP). Management utilizes these financial measures to monitor the Company's insurance operations and investment portfolio. The Company believes the presentation of these measures provides investors with a better understanding of the significant factors that comprise the Company's operating performance. Reconciliations of these measures to the most comparable GAAP measures can be found in the Appendix to this presentation. For additional information, please refer to CNA's filings with the Securities and Exchange Commission, available at cna.com. Available Information and Risk Factors CNA files annual, quarterly and current reports and other information with the SEC. The SEC filings are available on the CNA website (cna.com) and at the SEC's website (sec.gov). These filings describe some of the more material risks we face and how these risks could lead to events or circumstances that may have a material adverse effect on our business, financial condition, results of operations or cash flows. You should review these filings as they contain important information about CNA and its business. "CNA" is a registered trademark of CNA Financial Corporation. Certain CNA Financial Corporation subsidiaries use the "CNA" trademark in connection with insurance underwriting and claims activities. Copyright © 2026 CNA. All rights reserved. 2
Third Quarter Overview • Net income of $196 million versus $403 million in the prior year quarter; core income of $203 million versus $409 million in the prior year quarter. • P&C core income of $397 million versus $456 million, reflects lower underlying underwriting results and higher catastrophe losses. • Life & Group core loss of $171 million versus $22 million in the prior year quarter, reflects an unfavorable after- tax impact of $137 million in 2026 from our annual long-term care reserve assumption updates. However, the unfavorable reserve assumption updates are almost entirely offset by a favorable economic impact from recent investment portfolio actions, the anticipated benefit of which is not reflected in current period earnings under GAAP accounting. • Corporate & Other core loss of $23 million versus $25 million in the prior year quarter. • Net investment income of $635 million, reflects a $23 million decrease from limited partnerships and common stock to $48 million and a $20 million increase from fixed income securities and other investments to $587 million. • P&C combined ratio of 97.0%, compared with 92.8% in the prior year quarter, including 2.8 points of catastrophe loss impact compared with 1.5 points in the prior year quarter. There was no net prior period development impact in the current or prior year quarters. • Catastrophe losses of $78 million pretax versus $41 million in the prior year quarter. • P&C underlying combined ratio was 94.2%, compared with 91.3% in the prior year quarter. P&C underlying loss ratio was 64.1%, up 2.2 points from the prior year quarter, and the expense ratio was 29.7%. Both the underlying loss ratio and the expense ratio were consistent with the first half of 2026. • P&C segments generated net written premium growth of 3% in the quarter. P&C renewal premium change of +3%, with written rate of +2%. • Book value per share of $37.80; book value per share excluding AOCI of $46.11, a 5% increase from year-end 2025 adjusting for $3.44 of dividends per share paid. • Board of Directors declares regular quarterly cash dividend of $0.48 per share. 3
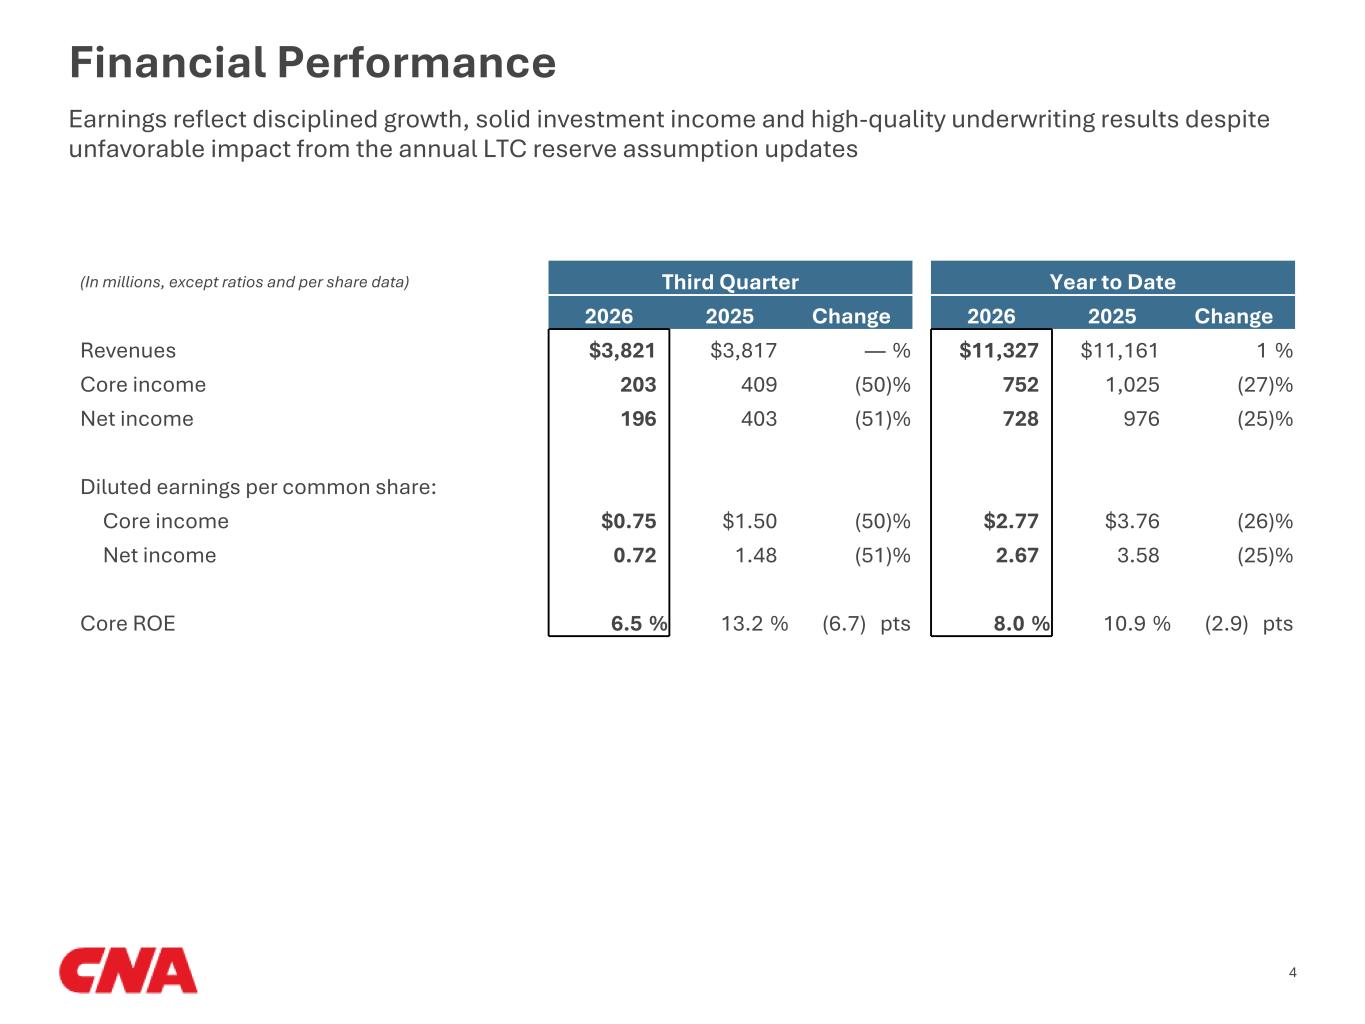
Financial Performance 4 (In millions, except ratios and per share data) Third Quarter Year to Date 2026 2025 Change 2026 2025 Change Revenues $3,821 $3,817 — % $11,327 $11,161 1 % Core income 203 409 (50) % 752 1,025 (27) % Net income 196 403 (51) % 728 976 (25) % Diluted earnings per common share: Core income $0.75 $1.50 (50) % $2.77 $3.76 (26) % Net income 0.72 1.48 (51) % 2.67 3.58 (25) % Core ROE 6.5 % 13.2 % (6.7) pts 8.0 % 10.9 % (2.9) pts Earnings reflect disciplined growth, solid investment income and high-quality underwriting results despite unfavorable impact from the annual LTC reserve assumption updates
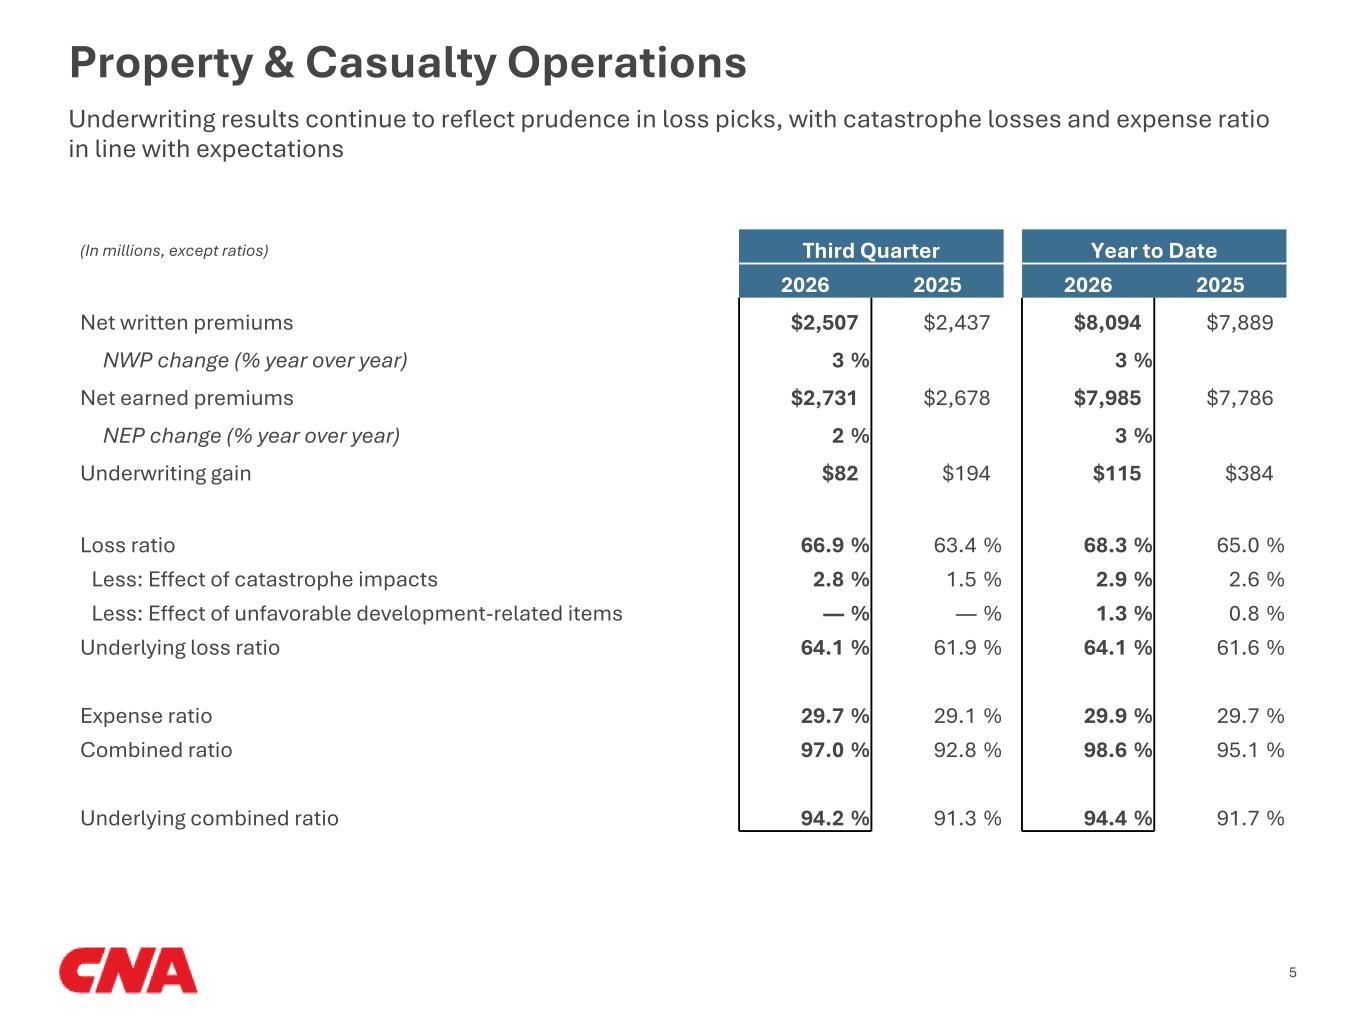
Underwriting results continue to reflect prudence in loss picks, with catastrophe losses and expense ratio in line with expectations Property & Casualty Operations 5 (In millions, except ratios) Third Quarter Year to Date 2026 2025 2026 2025 Net written premiums $2,507 $2,437 $8,094 $7,889 NWP change (% year over year) 3 % 3 % Net earned premiums $2,731 $2,678 $7,985 $7,786 NEP change (% year over year) 2 % 3 % Underwriting gain $82 $194 $115 $384 Loss ratio 66.9 % 63.4 % 68.3 % 65.0 % Less: Effect of catastrophe impacts 2.8 % 1.5 % 2.9 % 2.6 % Less: Effect of unfavorable development-related items — % — % 1.3 % 0.8 % Underlying loss ratio 64.1 % 61.9 % 64.1 % 61.6 % Expense ratio 29.7 % 29.1 % 29.9 % 29.7 % Combined ratio 97.0 % 92.8 % 98.6 % 95.1 % Underlying combined ratio 94.2 % 91.3 % 94.4 % 91.7 %
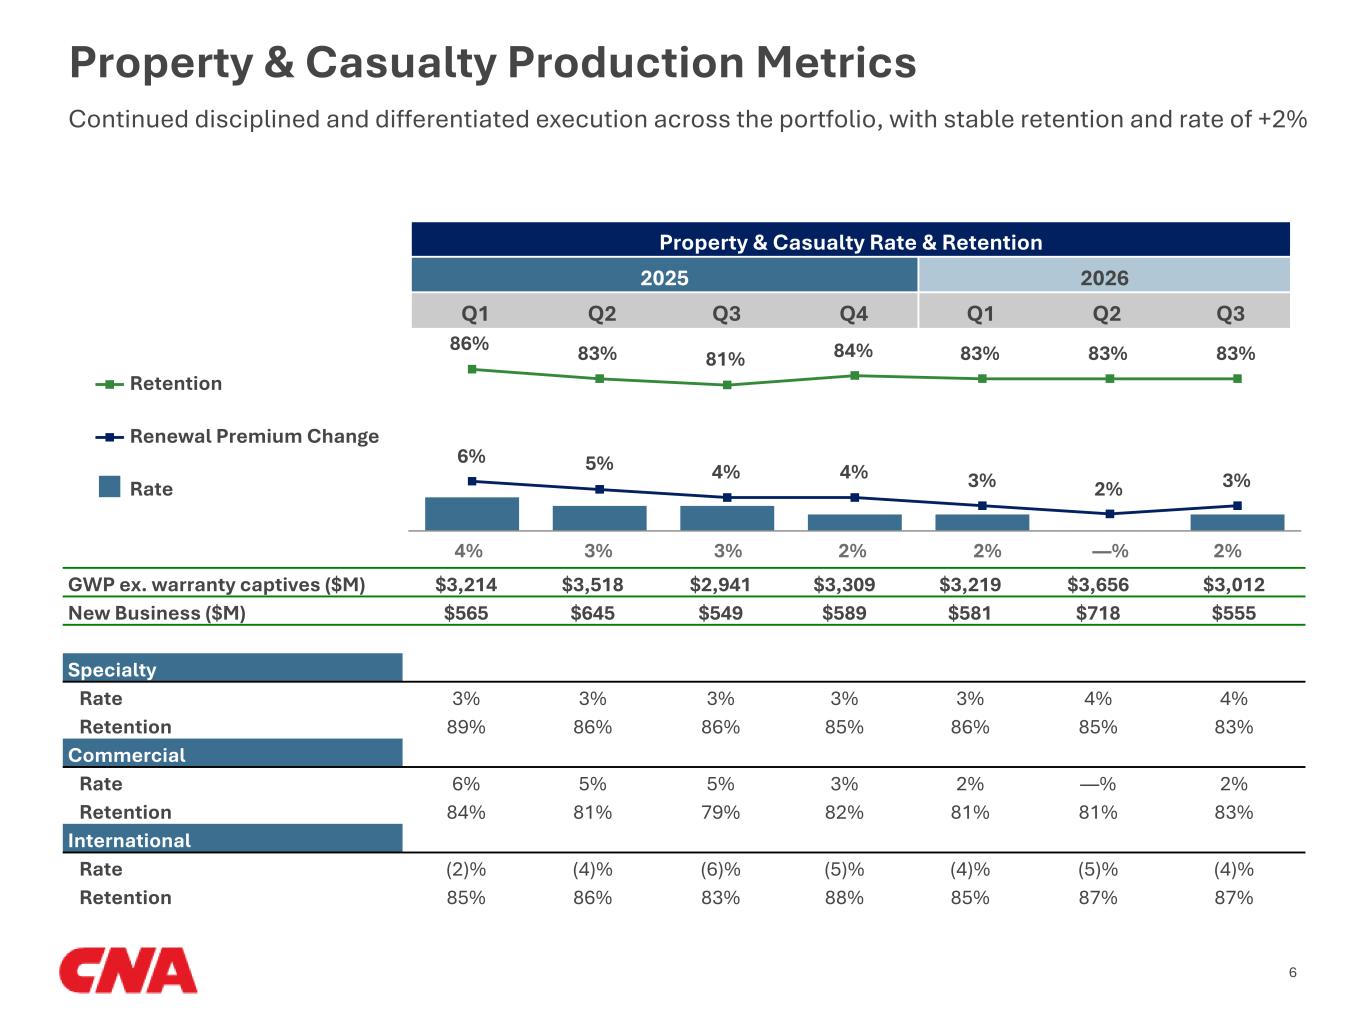
Property & Casualty Production Metrics Continued disciplined and differentiated execution across the portfolio, with stable retention and rate of +2% 6 Property & Casualty Rate & Retention 2025 2026 Q1 Q2 Q3 Q4 Q1 Q2 Q3 6% 5% 4% 4% 3% 2% 3% 86% 83% 81% 84% 83% 83% 83% Retention Renewal Premium Change Rate GWP ex. warranty captives ($M) $3,214 $3,518 $2,941 $3,309 $3,219 $3,656 $3,012 New Business ($M) $565 $645 $549 $589 $581 $718 $555 Specialty Rate 3% 3% 3% 3% 3% 4% 4% Retention 89% 86% 86% 85% 86% 85% 83% Commercial Rate 6% 5% 5% 3% 2% —% 2% Retention 84% 81% 79% 82% 81% 81% 83% International Rate (2)% (4)% (6)% (5)% (4)% (5)% (4)% Retention 85% 86% 83% 88% 85% 87% 87% 4% 3% 3% 2% 2% —% 2%
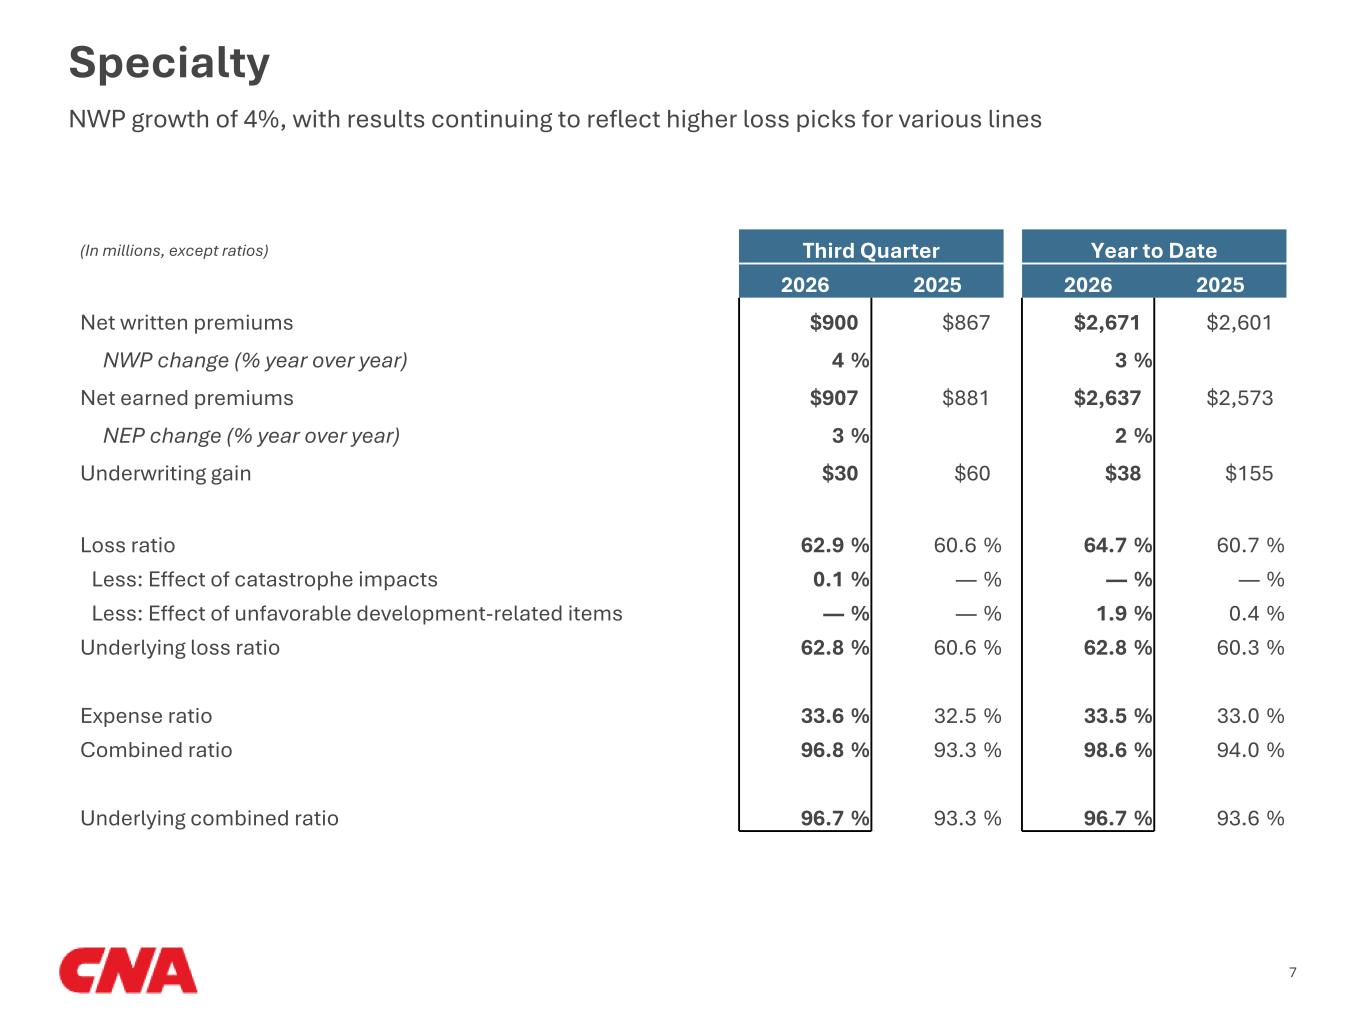
NWP growth of 4%, with results continuing to reflect higher loss picks for various lines Specialty 7 (In millions, except ratios) Third Quarter Year to Date 2026 2025 2026 2025 Net written premiums $900 $867 $2,671 $2,601 NWP change (% year over year) 4 % 3 % Net earned premiums $907 $881 $2,637 $2,573 NEP change (% year over year) 3 % 2 % Underwriting gain $30 $60 $38 $155 Loss ratio 62.9 % 60.6 % 64.7 % 60.7 % Less: Effect of catastrophe impacts 0.1 % — % — % — % Less: Effect of unfavorable development-related items — % — % 1.9 % 0.4 % Underlying loss ratio 62.8 % 60.6 % 62.8 % 60.3 % Expense ratio 33.6 % 32.5 % 33.5 % 33.0 % Combined ratio 96.8 % 93.3 % 98.6 % 94.0 % Underlying combined ratio 96.7 % 93.3 % 96.7 % 93.6 %
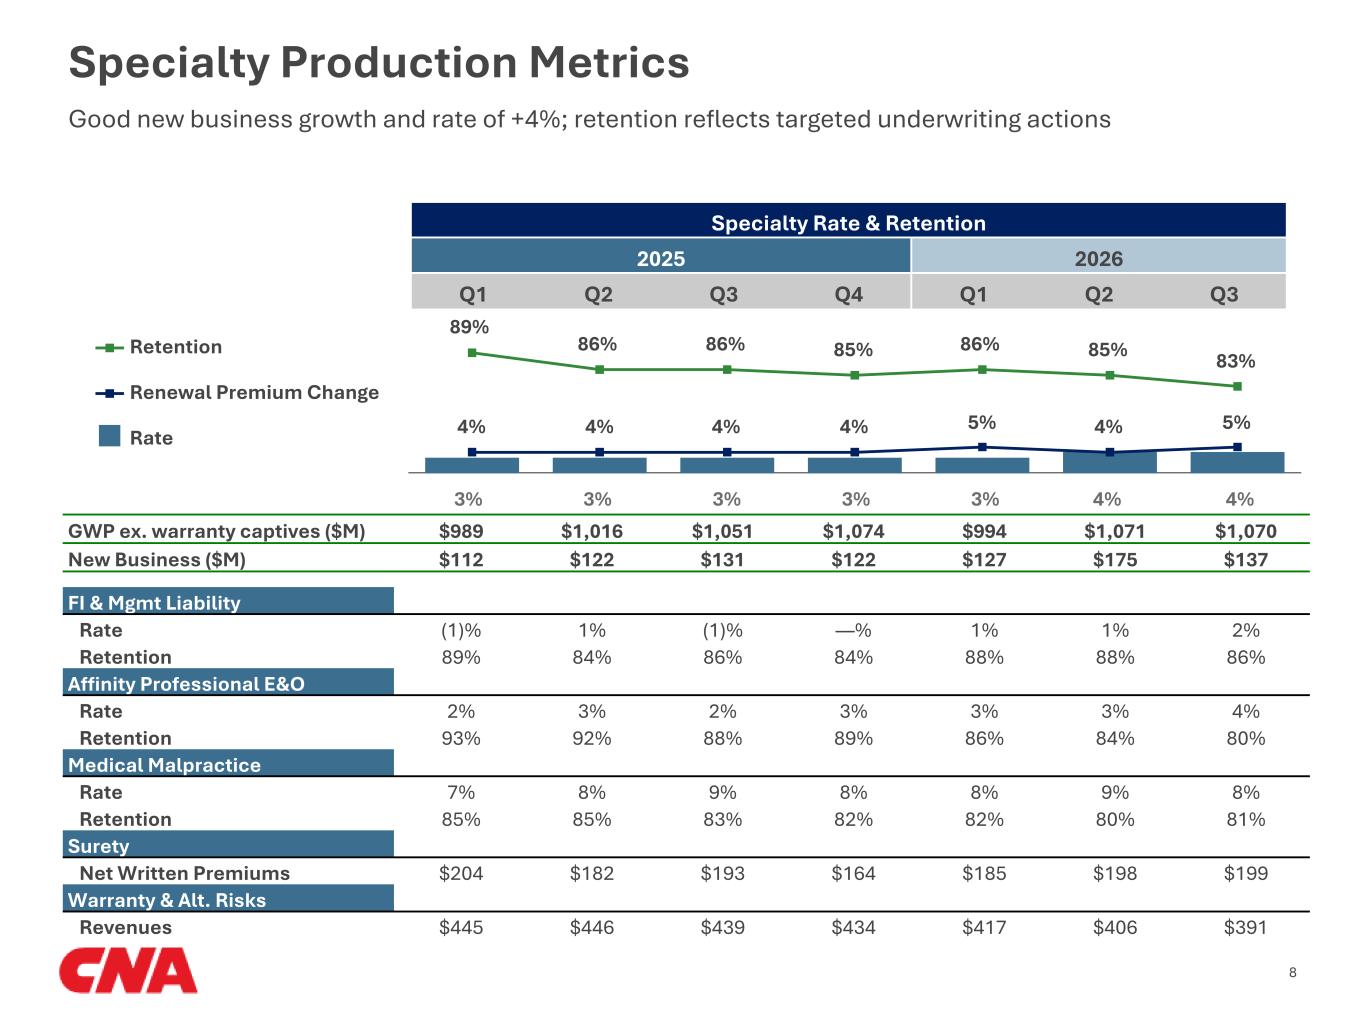
Specialty Production Metrics Good new business growth and rate of +4%; retention reflects targeted underwriting actions 8 Specialty Rate & Retention 2025 2026 Q1 Q2 Q3 Q4 Q1 Q2 Q3 4% 4% 4% 4% 5% 4% 5% 89% 86% 86% 85% 86% 85% 83% Retention Renewal Premium Change Rate GWP ex. warranty captives ($M) $989 $1,016 $1,051 $1,074 $994 $1,071 $1,070 New Business ($M) $112 $122 $131 $122 $127 $175 $137 FI & Mgmt Liability Rate (1)% 1% (1)% —% 1% 1% 2% Retention 89% 84% 86% 84% 88% 88% 86% Affinity Professional E&O Rate 2% 3% 2% 3% 3% 3% 4% Retention 93% 92% 88% 89% 86% 84% 80% Medical Malpractice Rate 7% 8% 9% 8% 8% 9% 8% Retention 85% 85% 83% 82% 82% 80% 81% Surety Net Written Premiums $204 $182 $193 $164 $185 $198 $199 Warranty & Alt. Risks Revenues $445 $446 $439 $434 $417 $406 $391 3%3% 3% 3% 3% 4% 4%
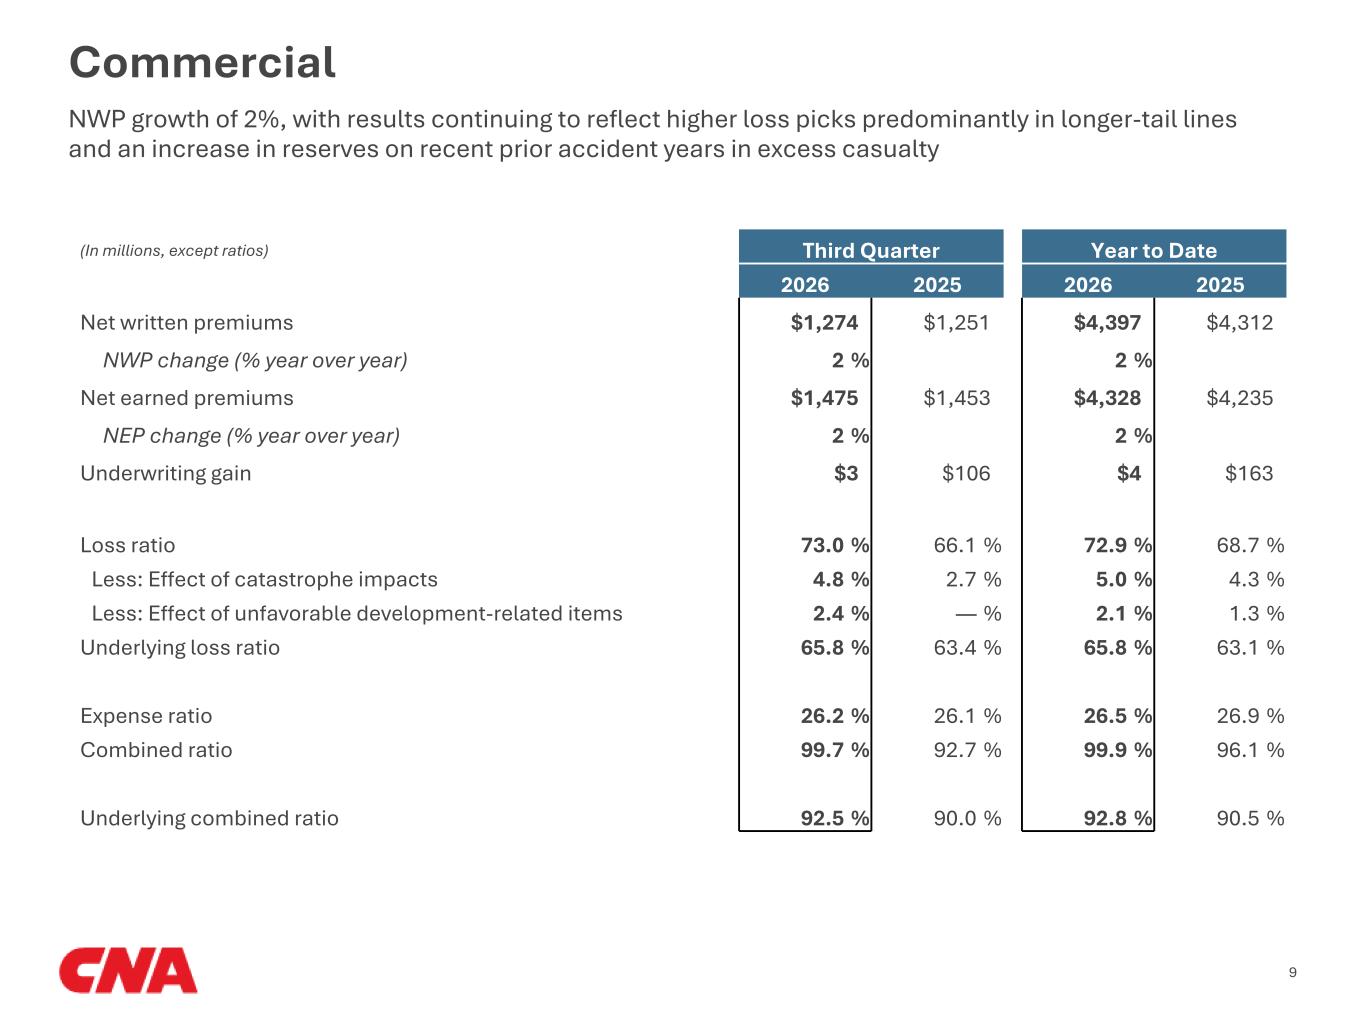
Commercial 9 (In millions, except ratios) Third Quarter Year to Date 2026 2025 2026 2025 Net written premiums $1,274 $1,251 $4,397 $4,312 NWP change (% year over year) 2 % 2 % Net earned premiums $1,475 $1,453 $4,328 $4,235 NEP change (% year over year) 2 % 2 % Underwriting gain $3 $106 $4 $163 Loss ratio 73.0 % 66.1 % 72.9 % 68.7 % Less: Effect of catastrophe impacts 4.8 % 2.7 % 5.0 % 4.3 % Less: Effect of unfavorable development-related items 2.4 % — % 2.1 % 1.3 % Underlying loss ratio 65.8 % 63.4 % 65.8 % 63.1 % Expense ratio 26.2 % 26.1 % 26.5 % 26.9 % Combined ratio 99.7 % 92.7 % 99.9 % 96.1 % Underlying combined ratio 92.5 % 90.0 % 92.8 % 90.5 % NWP growth of 2%, with results continuing to reflect higher loss picks predominantly in longer-tail lines and an increase in reserves on recent prior accident years in excess casualty
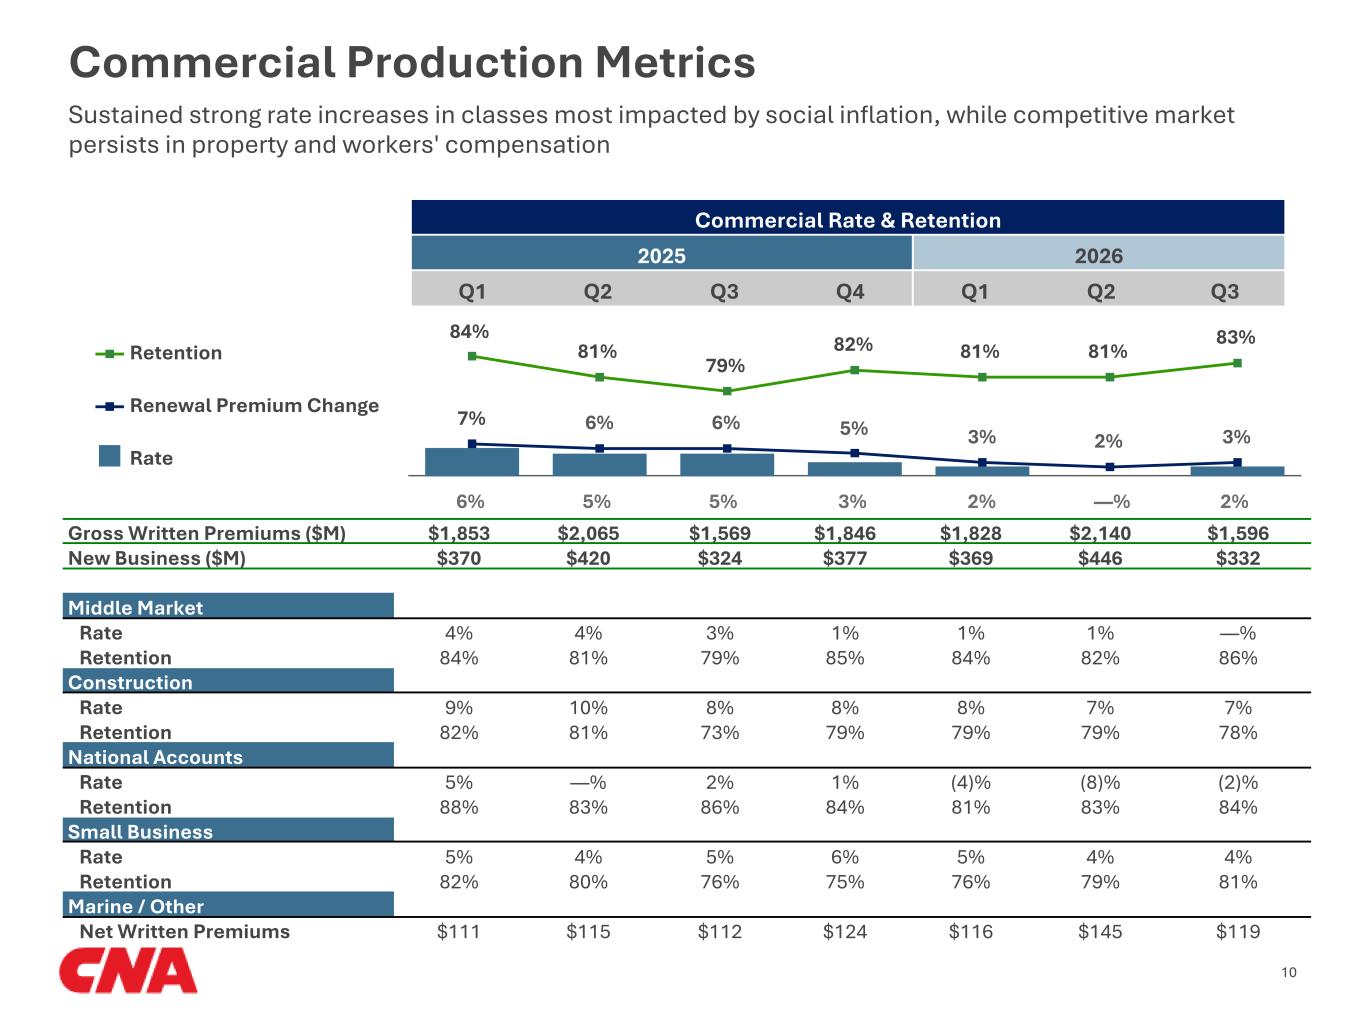
Commercial Production Metrics 10 Commercial Rate & Retention 2025 2026 Q1 Q2 Q3 Q4 Q1 Q2 Q3 7% 6% 6% 5% 3% 2% 3% 84% 81% 79% 82% 81% 81% 83% Retention Renewal Premium Change Rate Gross Written Premiums ($M) $1,853 $2,065 $1,569 $1,846 $1,828 $2,140 $1,596 New Business ($M) $370 $420 $324 $377 $369 $446 $332 Middle Market Rate 4% 4% 3% 1% 1% 1% —% Retention 84% 81% 79% 85% 84% 82% 86% Construction Rate 9% 10% 8% 8% 8% 7% 7% Retention 82% 81% 73% 79% 79% 79% 78% National Accounts Rate 5% —% 2% 1% (4)% (8)% (2)% Retention 88% 83% 86% 84% 81% 83% 84% Small Business Rate 5% 4% 5% 6% 5% 4% 4% Retention 82% 80% 76% 75% 76% 79% 81% Marine / Other Net Written Premiums $111 $115 $112 $124 $116 $145 $119 Sustained strong rate increases in classes most impacted by social inflation, while competitive market persists in property and workers' compensation 6% —%5% 5% 3% 2% 2%
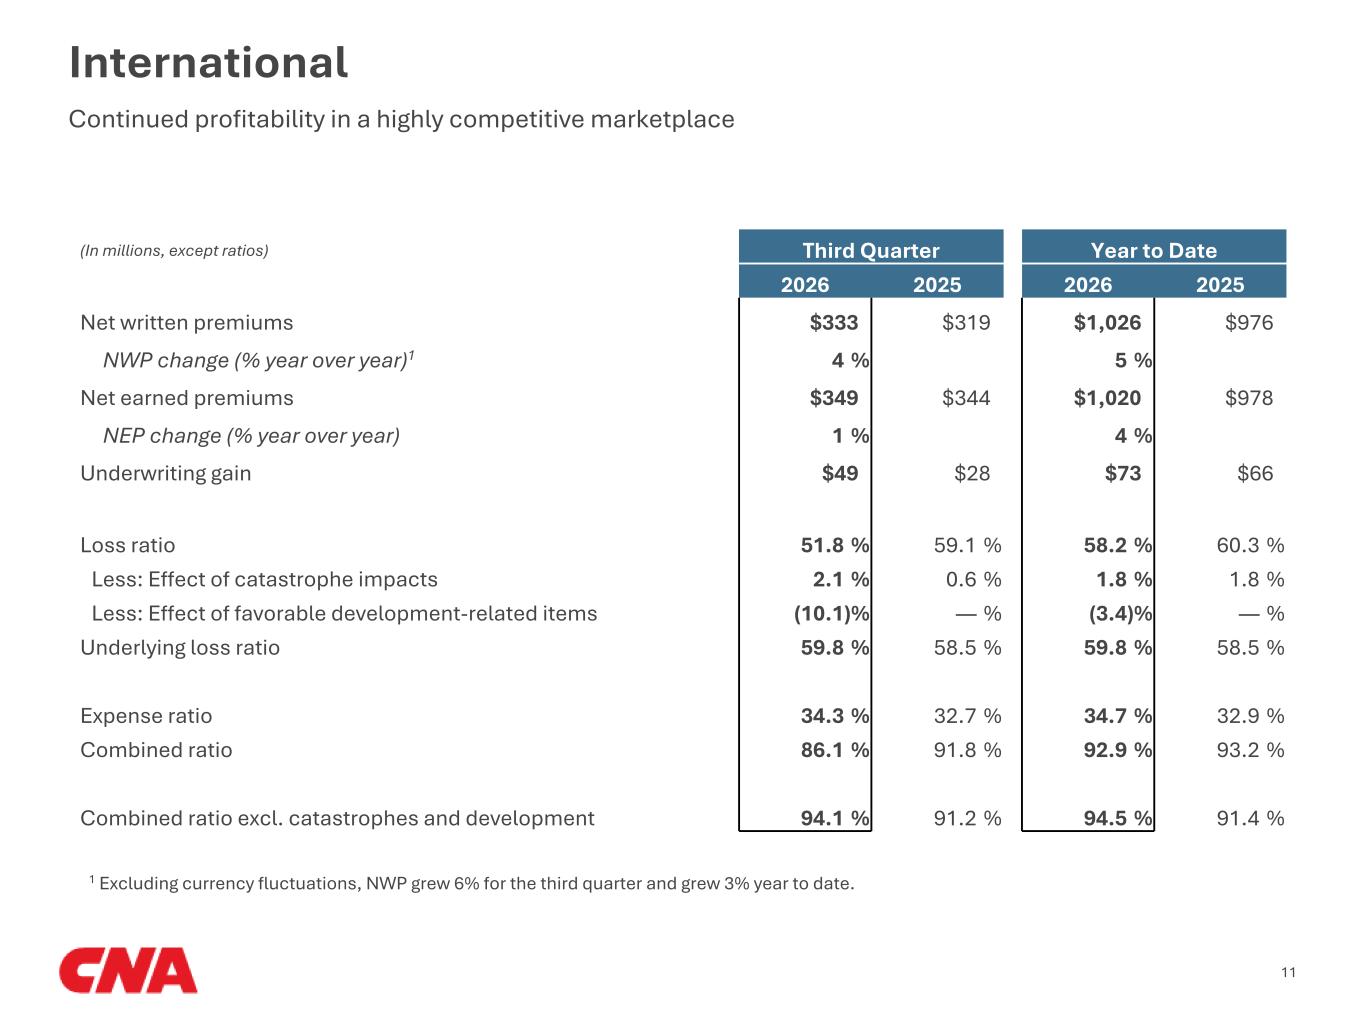
International Continued profitability in a highly competitive marketplace 11 (In millions, except ratios) Third Quarter Year to Date 2026 2025 2026 2025 Net written premiums $333 $319 $1,026 $976 NWP change (% year over year)1 4 % 5 % Net earned premiums $349 $344 $1,020 $978 NEP change (% year over year) 1 % 4 % Underwriting gain $49 $28 $73 $66 Loss ratio 51.8 % 59.1 % 58.2 % 60.3 % Less: Effect of catastrophe impacts 2.1 % 0.6 % 1.8 % 1.8 % Less: Effect of favorable development-related items (10.1) % — % (3.4) % — % Underlying loss ratio 59.8 % 58.5 % 59.8 % 58.5 % Expense ratio 34.3 % 32.7 % 34.7 % 32.9 % Combined ratio 86.1 % 91.8 % 92.9 % 93.2 % Combined ratio excl. catastrophes and development 94.1 % 91.2 % 94.5 % 91.4 % 1 Excluding currency fluctuations, NWP grew 6% for the third quarter and grew 3% year to date.
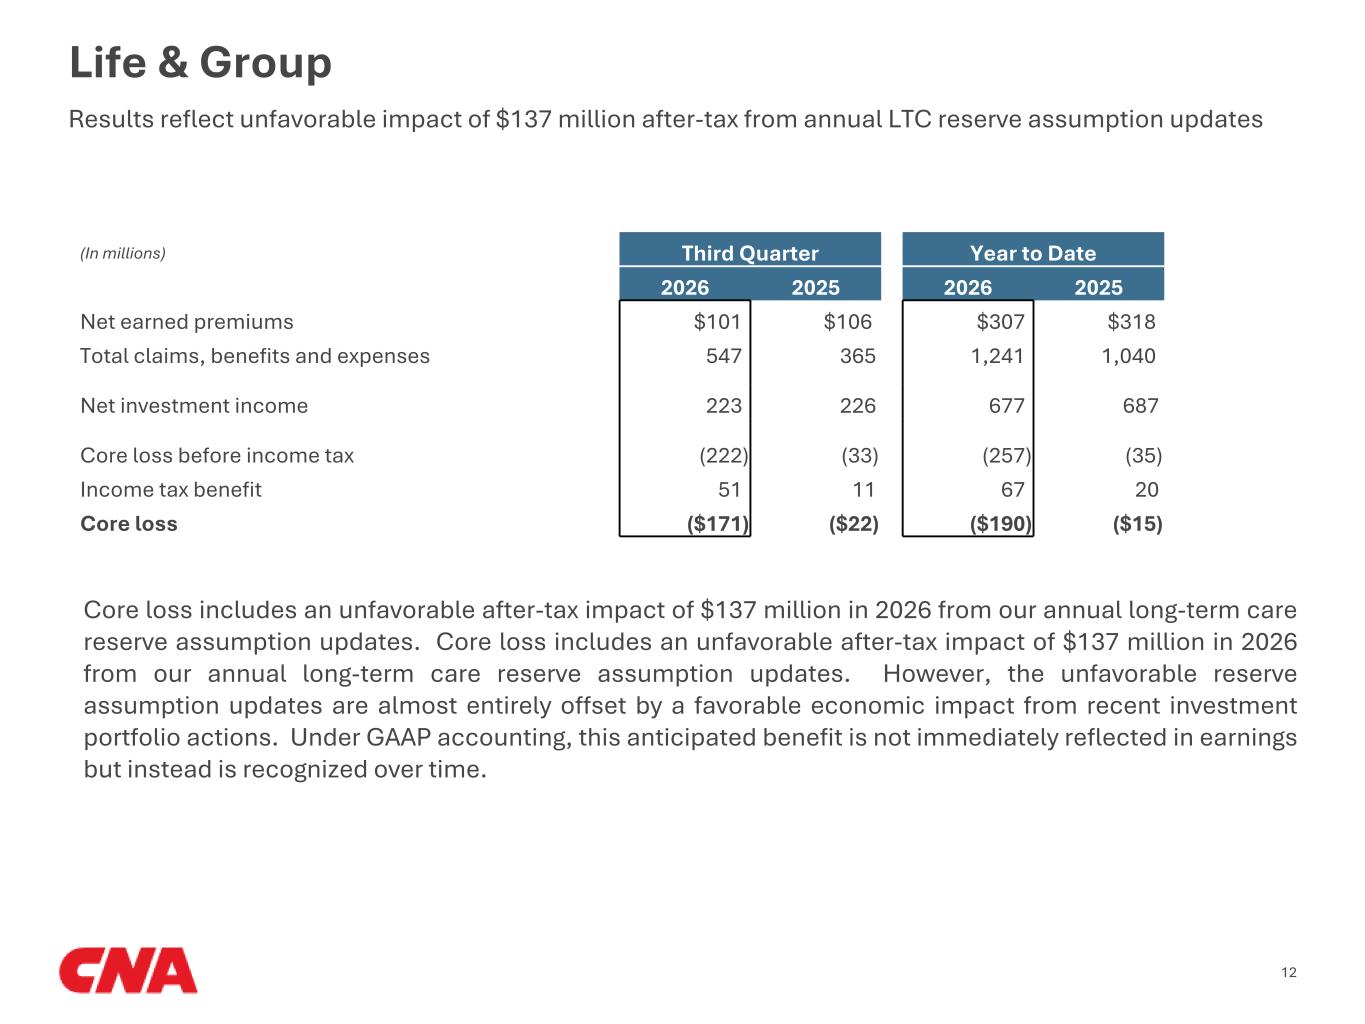
Results reflect unfavorable impact of $137 million after-tax from annual LTC reserve assumption updates Life & Group 12 (In millions) Third Quarter Year to Date 2026 2025 2026 2025 Net earned premiums $101 $106 $307 $318 Total claims, benefits and expenses 547 365 1,241 1,040 Net investment income 223 226 677 687 Core loss before income tax (222) (33) (257) (35) Income tax benefit 51 11 67 20 Core loss ($171) ($22) ($190) ($15) Core loss includes an unfavorable after-tax impact of $137 million in 2026 from our annual long-term care reserve assumption updates. Core loss includes an unfavorable after-tax impact of $137 million in 2026 from our annual long-term care reserve assumption updates. However, the unfavorable reserve assumption updates are almost entirely offset by a favorable economic impact from recent investment portfolio actions. Under GAAP accounting, this anticipated benefit is not immediately reflected in earnings but instead is recognized over time.
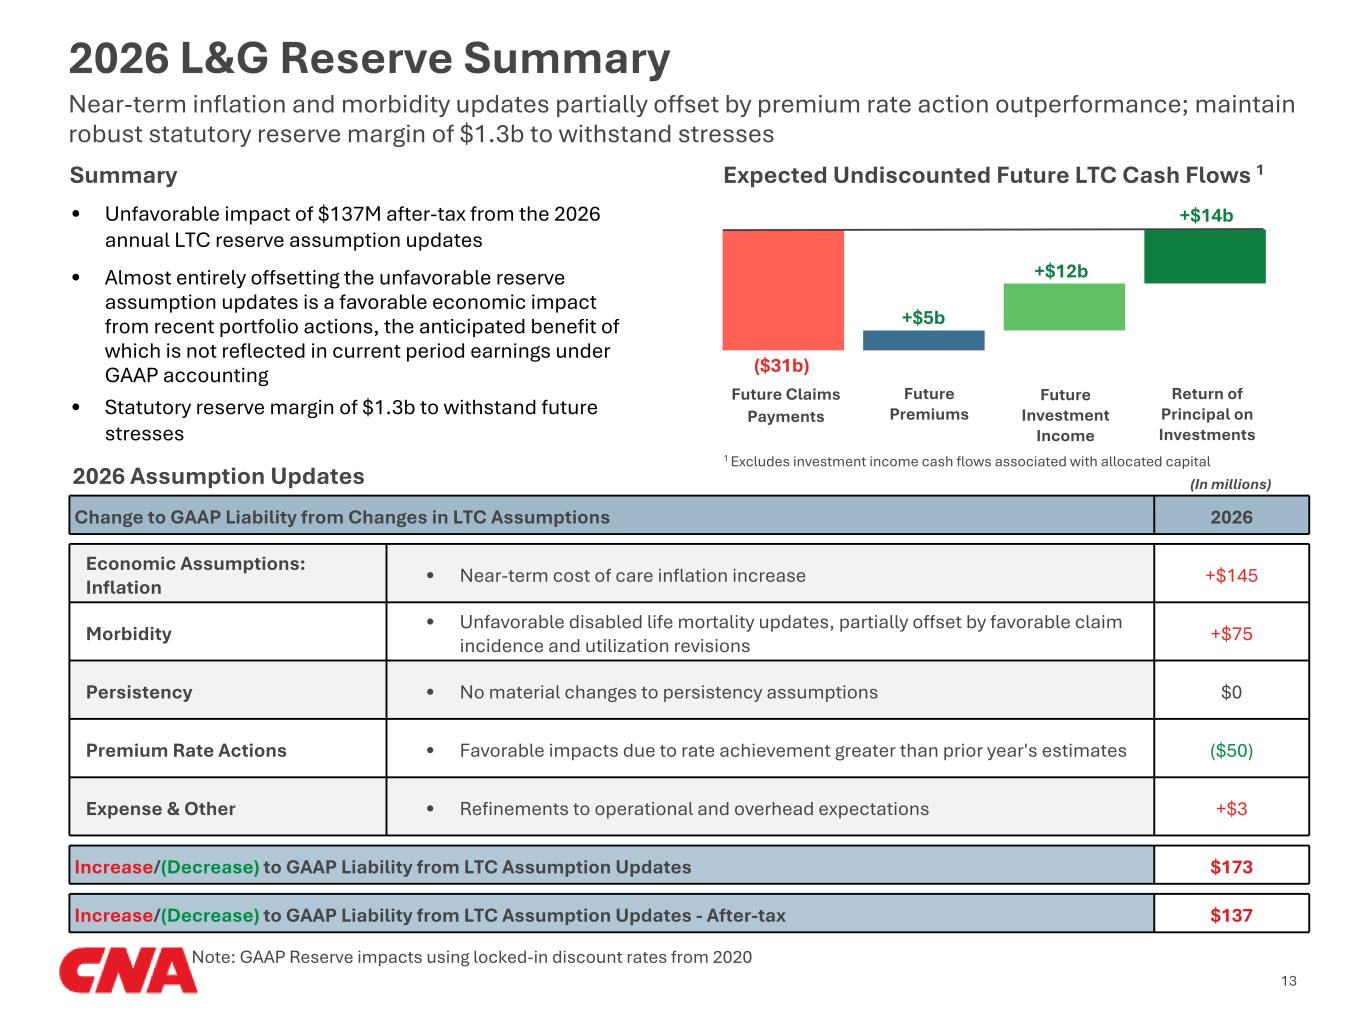
2026 L&G Reserve Summary Near-term inflation and morbidity updates partially offset by premium rate action outperformance; maintain robust statutory reserve margin of $1.3b to withstand stresses Change to GAAP Liability from Changes in LTC Assumptions 2026 Economic Assumptions: Inflation • Near-term cost of care inflation increase +$145 Morbidity • Unfavorable disabled life mortality updates, partially offset by favorable claim incidence and utilization revisions +$75 Persistency • No material changes to persistency assumptions $0 Premium Rate Actions • Favorable impacts due to rate achievement greater than prior year's estimates ($50) Expense & Other • Refinements to operational and overhead expectations +$3 Increase/(Decrease) to GAAP Liability from LTC Assumption Updates $173 Increase/(Decrease) to GAAP Liability from LTC Assumption Updates - After-tax $137 13 Summary Note: GAAP Reserve impacts using locked-in discount rates from 2020 Expected Undiscounted Future LTC Cash Flows 1 • Unfavorable impact of $137M after-tax from the 2026 annual LTC reserve assumption updates • Almost entirely offsetting the unfavorable reserve assumption updates is a favorable economic impact from recent portfolio actions, the anticipated benefit of which is not reflected in current period earnings under GAAP accounting • Statutory reserve margin of $1.3b to withstand future stresses (In millions) Future Claims Payments Future Investment Income Return of Principal on Investments ($31b) +$14b 2026 Assumption Updates 1 Excludes investment income cash flows associated with allocated capital Future Premiums +$5b +$12b
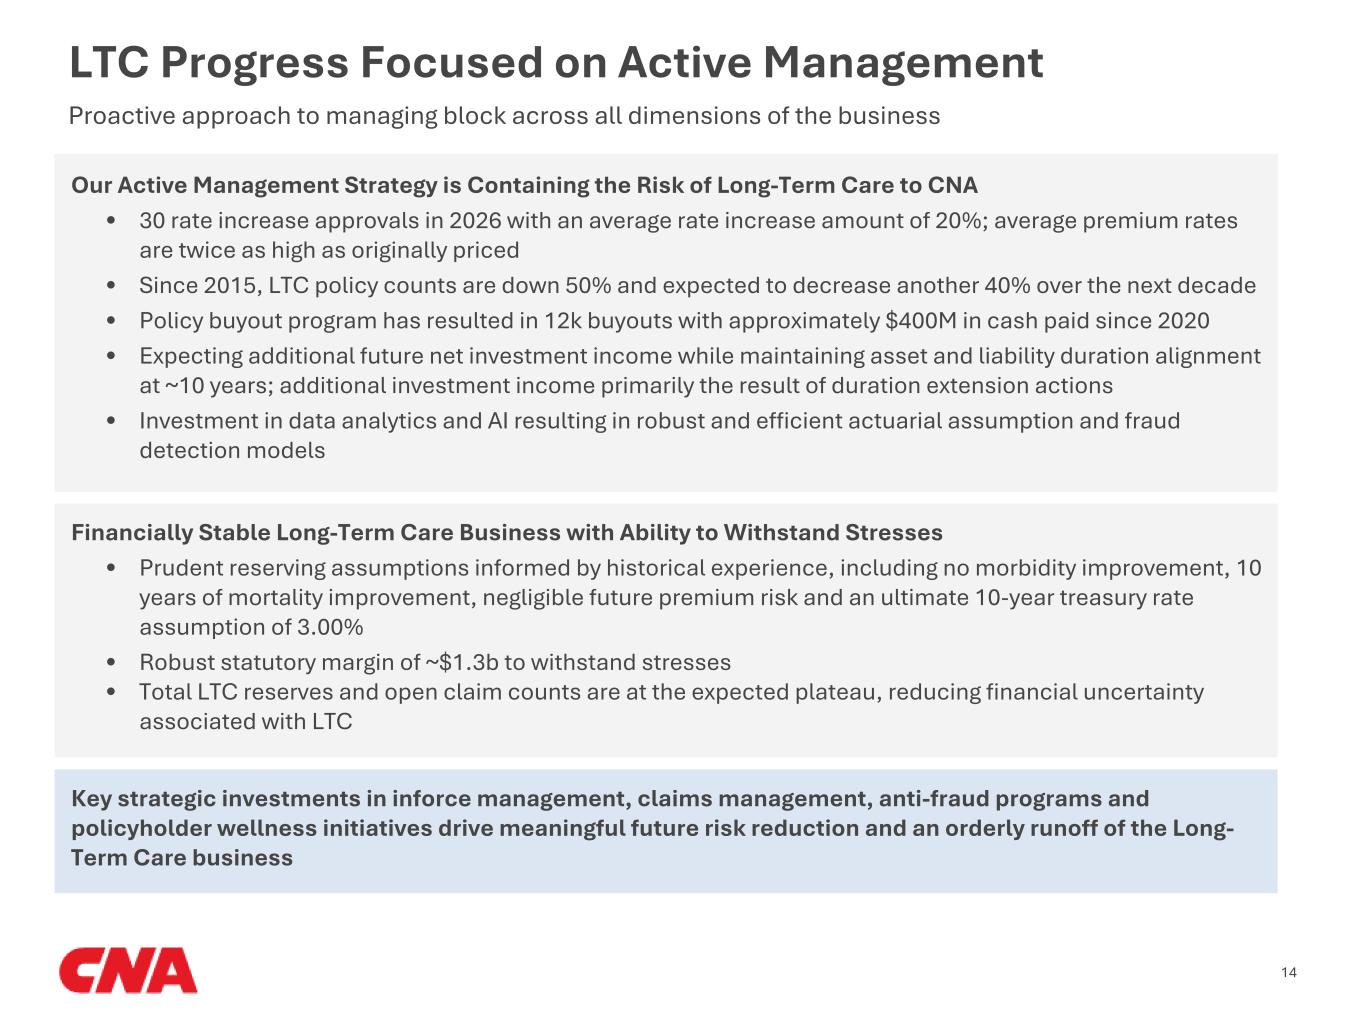
LTC Progress Focused on Active Management 14 Proactive approach to managing block across all dimensions of the business Our Active Management Strategy is Containing the Risk of Long-Term Care to CNA • 30 rate increase approvals in 2026 with an average rate increase amount of 20%; average premium rates are twice as high as originally priced • Since 2015, LTC policy counts are down 50% and expected to decrease another 40% over the next decade • Policy buyout program has resulted in 12k buyouts with approximately $400M in cash paid since 2020 • Expecting additional future net investment income while maintaining asset and liability duration alignment at ~10 years; additional investment income primarily the result of duration extension actions • Investment in data analytics and AI resulting in robust and efficient actuarial assumption and fraud detection models Financially Stable Long-Term Care Business with Ability to Withstand Stresses • Prudent reserving assumptions informed by historical experience, including no morbidity improvement, 10 years of mortality improvement, negligible future premium risk and an ultimate 10-year treasury rate assumption of 3.00% • Robust statutory margin of ~$1.3b to withstand stresses • Total LTC reserves and open claim counts are at the expected plateau, reducing financial uncertainty associated with LTC Key strategic investments in inforce management, claims management, anti-fraud programs and policyholder wellness initiatives drive meaningful future risk reduction and an orderly runoff of the Long- Term Care business
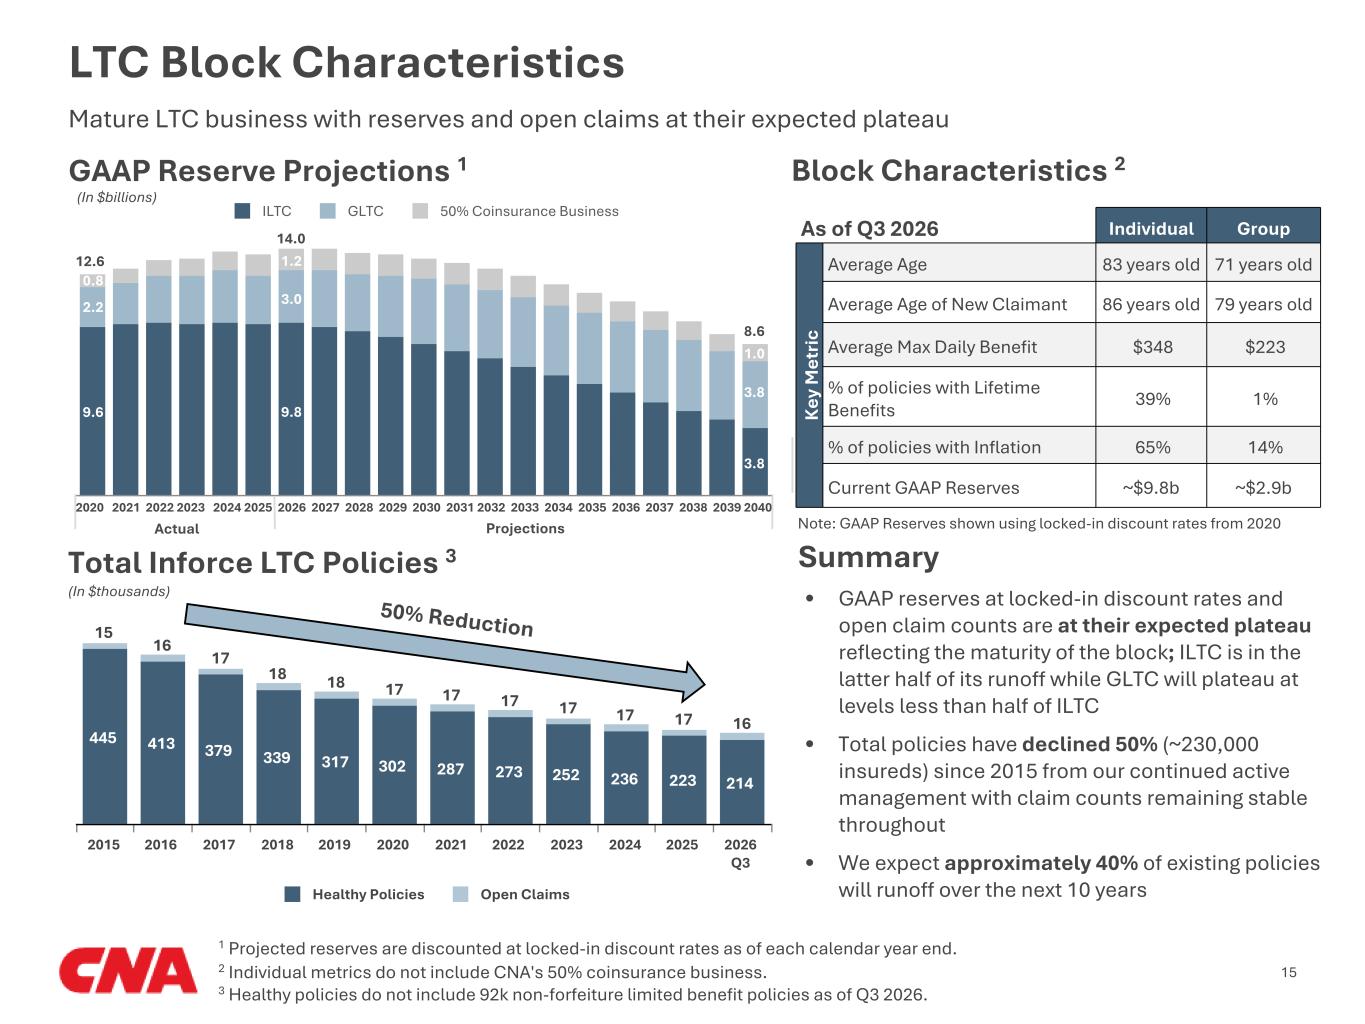
LTC Block Characteristics Mature LTC business with reserves and open claims at their expected plateau 15 Summary Block Characteristics 2 • GAAP reserves at locked-in discount rates and open claim counts are at their expected plateau reflecting the maturity of the block; ILTC is in the latter half of its runoff while GLTC will plateau at levels less than half of ILTC • Total policies have declined 50% (~230,000 insureds) since 2015 from our continued active management with claim counts remaining stable throughout • We expect approximately 40% of existing policies will runoff over the next 10 years As of Q3 2026 Individual Group Ke y M et ric Average Age 83 years old 71 years old Average Age of New Claimant 86 years old 79 years old Average Max Daily Benefit $348 $223 % of policies with Lifetime Benefits 39% 1% % of policies with Inflation 65% 14% Current GAAP Reserves ~$9.8b ~$2.9b 1 Projected reserves are discounted at locked-in discount rates as of each calendar year end. 2 Individual metrics do not include CNA's 50% coinsurance business. 3 Healthy policies do not include 92k non-forfeiture limited benefit policies as of Q3 2026. Total Inforce LTC Policies 3 GAAP Reserve Projections 1 445 413 379 339 317 302 287 273 252 236 223 214 15 16 17 18 18 17 17 17 17 17 17 16 Healthy Policies Open Claims 2015 2016 2017 2018 2019 2020 2021 2022 2023 2024 2025 2026 Q3 50% Reduction (In $thousands) Note: GAAP Reserves shown using locked-in discount rates from 2020 ILTC GLTC 50% Coinsurance Business (In $billions) 9.6 9.8 3.8 2.2 3.0 3.8 0.8 1.0 12.6 14.0 8.6 1.2 2020 2021 2022 2023 2024 2025 2026 2027 2028 2029 2030 2031 2032 2033 2034 2035 2036 2037 2038 2039 2040 Actual Projections
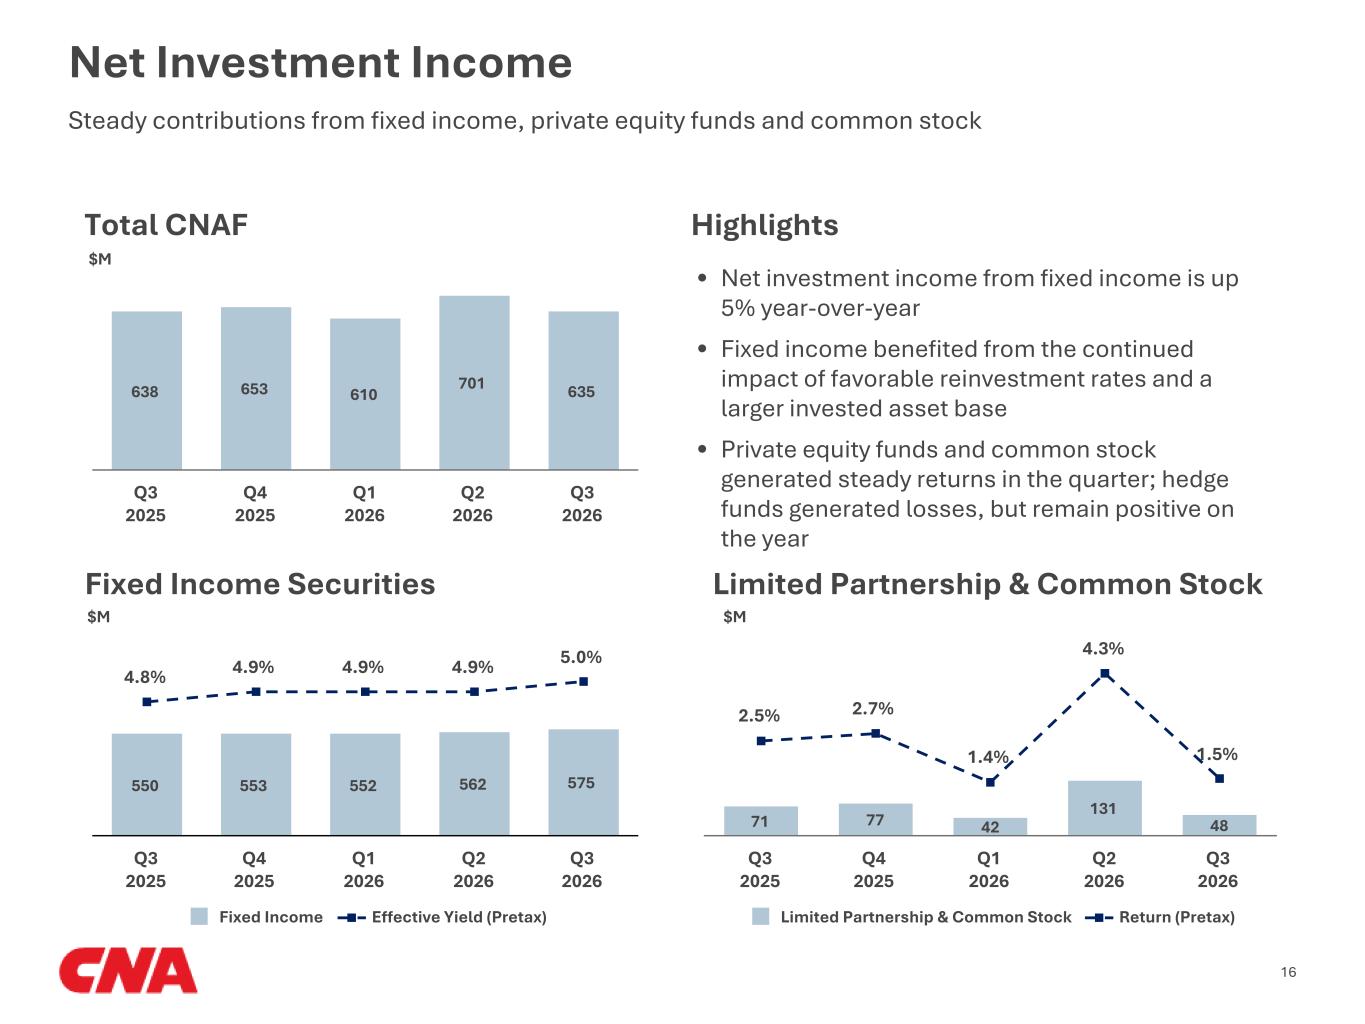
Net Investment Income Steady contributions from fixed income, private equity funds and common stock 638 653 610 701 635 Q3 2025 Q4 2025 Q1 2026 Q2 2026 Q3 2026 Total CNAF Limited Partnership & Common Stock Highlights Fixed Income Securities 550 553 552 562 575 4.8% 4.9% 4.9% 4.9% 5.0% Fixed Income Effective Yield (Pretax) Q3 2025 Q4 2025 Q1 2026 Q2 2026 Q3 2026 71 77 42 131 48 2.5% 2.7% 1.4% 4.3% 1.5% Limited Partnership & Common Stock Return (Pretax) Q3 2025 Q4 2025 Q1 2026 Q2 2026 Q3 2026 $M $M $M 16 • Net investment income from fixed income is up 5% year-over-year • Fixed income benefited from the continued impact of favorable reinvestment rates and a larger invested asset base • Private equity funds and common stock generated steady returns in the quarter; hedge funds generated losses, but remain positive on the year
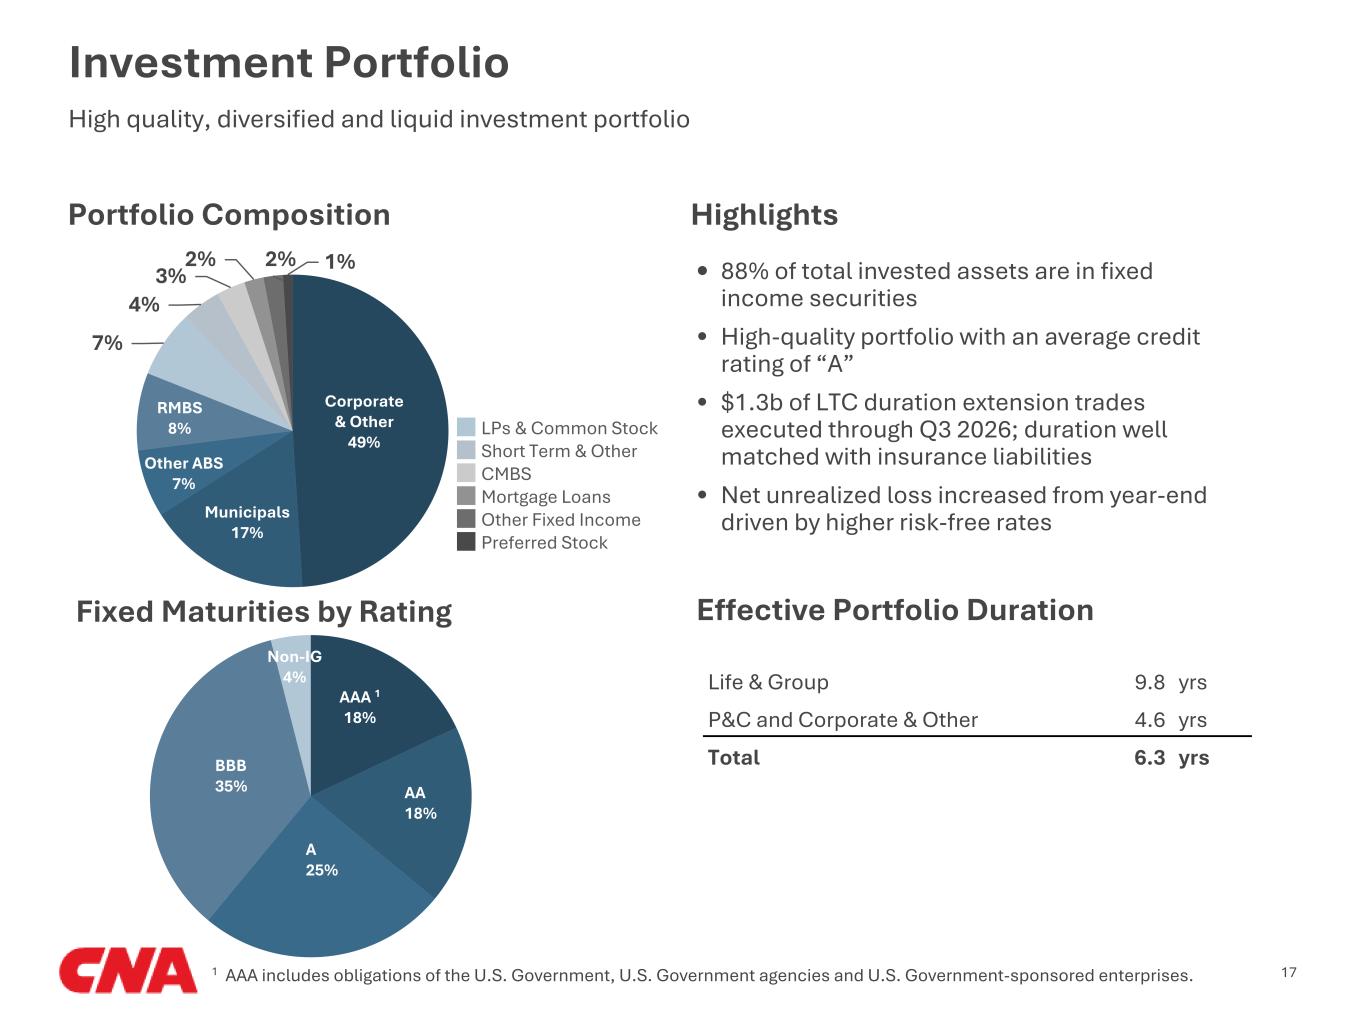
Investment Portfolio 171 AAA includes obligations of the U.S. Government, U.S. Government agencies and U.S. Government-sponsored enterprises. High quality, diversified and liquid investment portfolio • 88% of total invested assets are in fixed income securities • High-quality portfolio with an average credit rating of “A” • $1.3b of LTC duration extension trades executed through Q3 2026; duration well matched with insurance liabilities • Net unrealized loss increased from year-end driven by higher risk-free rates 7% 4% 3% 2% 2% 1% LPs & Common Stock Short Term & Other CMBS Mortgage Loans Other Fixed Income Preferred Stock Corporate & Other 49% Municipals 17% Other ABS 7% RMBS 8% Portfolio Composition Highlights Fixed Maturities by Rating AA 18% A 25% BBB 35% AAA 1 18% Non-IG 4% Effective Portfolio Duration Life & Group 9.8 yrs P&C and Corporate & Other 4.6 yrs Total 6.3 yrs
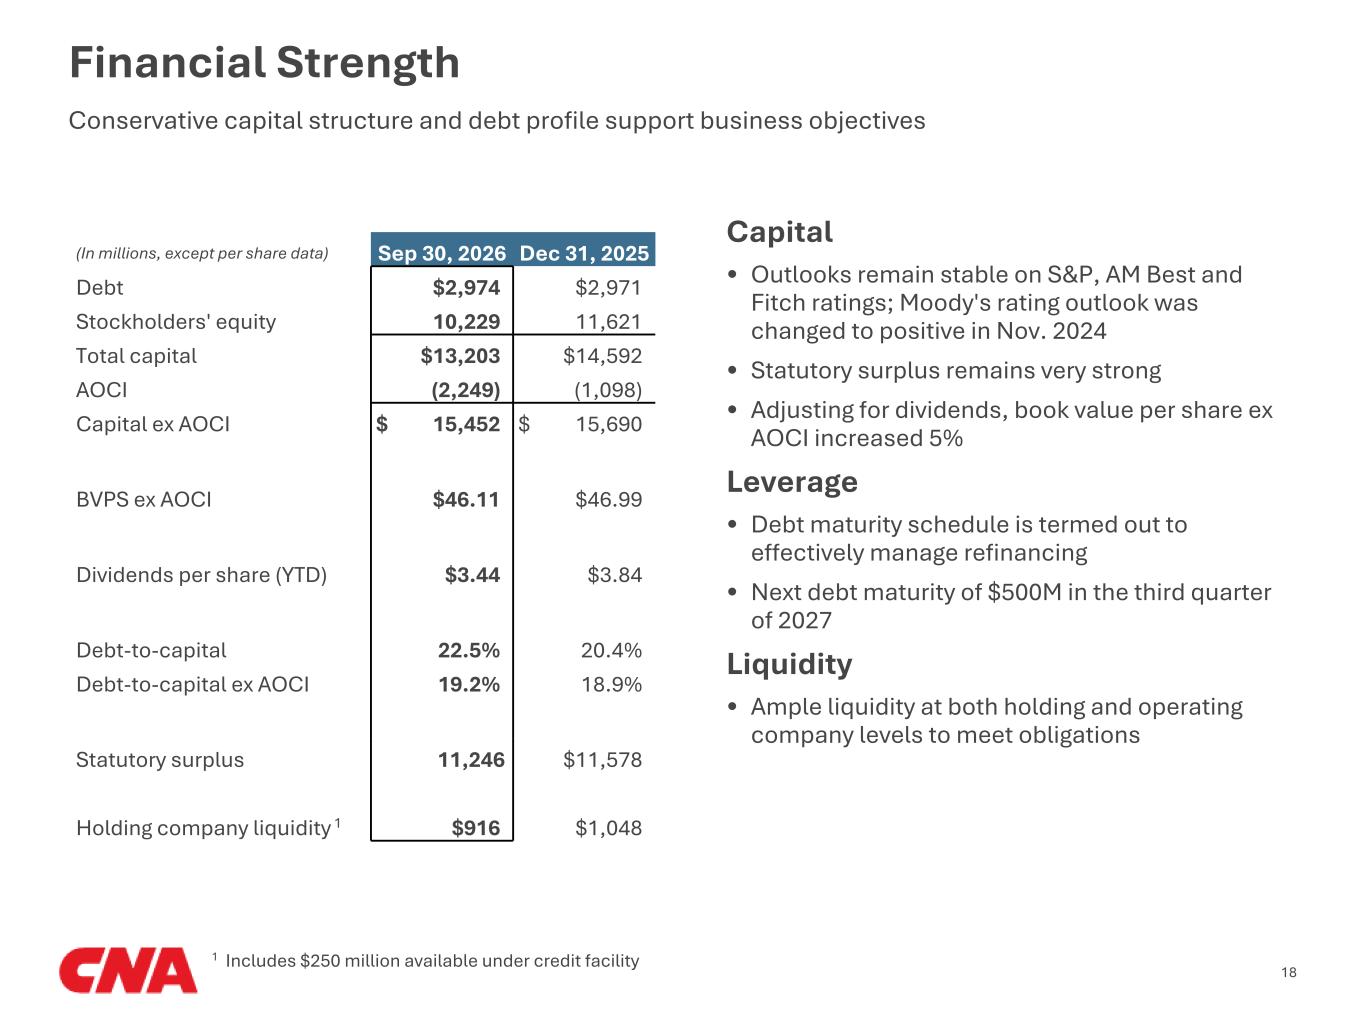
Capital • Outlooks remain stable on S&P, AM Best and Fitch ratings; Moody's rating outlook was changed to positive in Nov. 2024 • Statutory surplus remains very strong • Adjusting for dividends, book value per share ex AOCI increased 5% Leverage • Debt maturity schedule is termed out to effectively manage refinancing • Next debt maturity of $500M in the third quarter of 2027 Liquidity • Ample liquidity at both holding and operating company levels to meet obligations Financial Strength Conservative capital structure and debt profile support business objectives (In millions, except per share data) Sep 30, 2026 Dec 31, 2025 Debt $2,974 $2,971 Stockholders' equity 10,229 11,621 Total capital $13,203 $14,592 AOCI (2,249) (1,098) Capital ex AOCI $ 15,452 $ 15,690 BVPS ex AOCI $46.11 $46.99 Dividends per share (YTD) $3.44 $3.84 Debt-to-capital 22.5 % 20.4 % Debt-to-capital ex AOCI 19.2 % 18.9 % Statutory surplus 11,246 $11,578 Holding company liquidity 1 $916 $1,048 18 1 Includes $250 million available under credit facility
APPENDIX 20
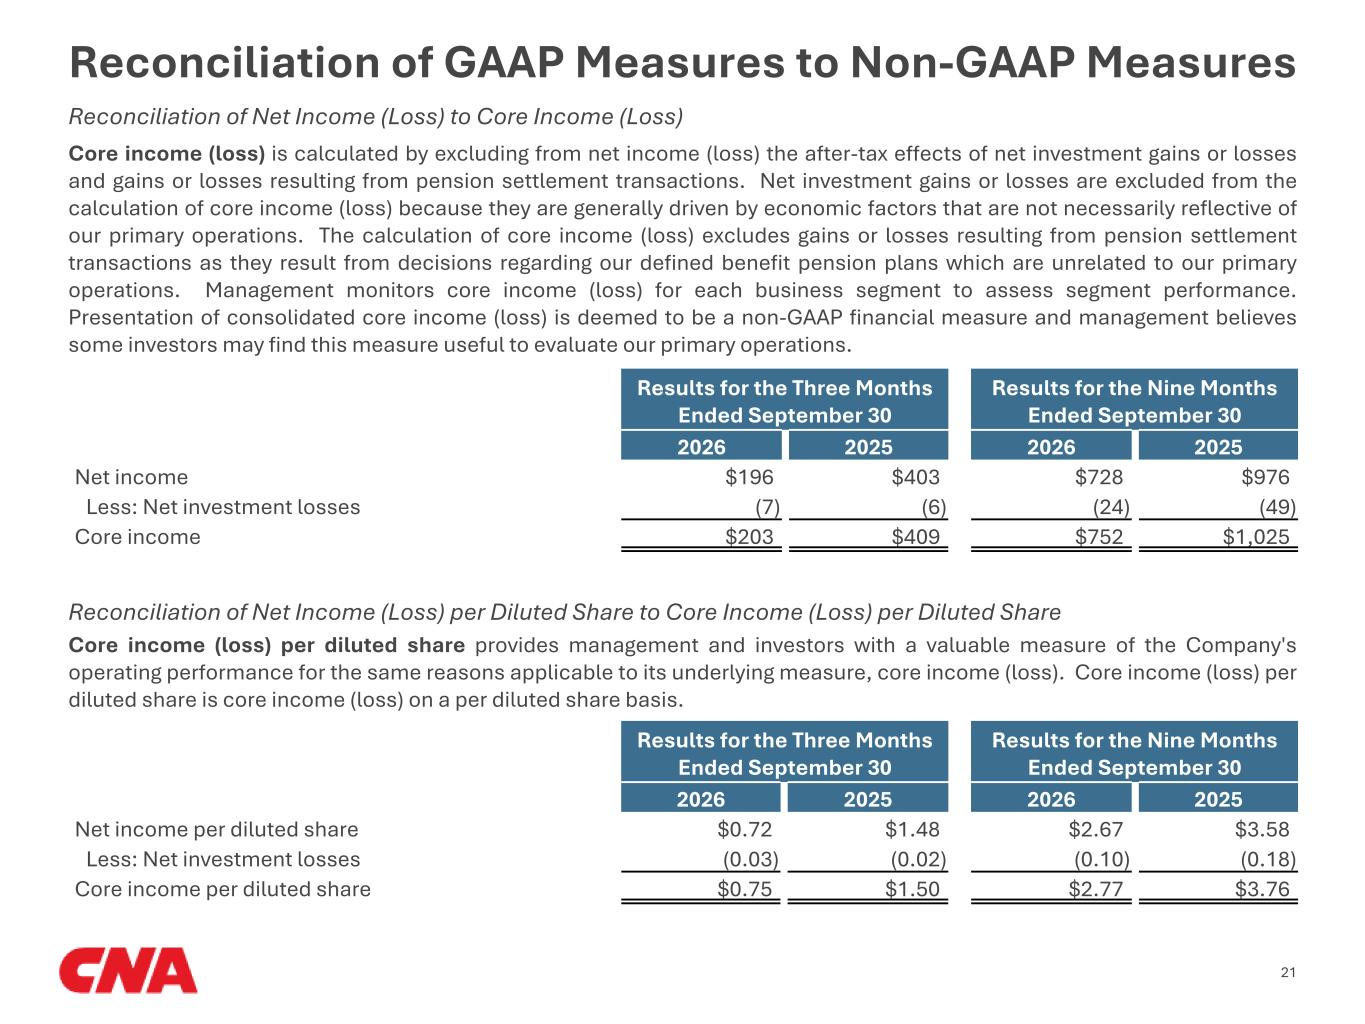
Results for the Three Months Ended September 30 Results for the Nine Months Ended September 30 2026 2025 2026 2025 Net income $196 $403 $728 $976 Less: Net investment losses (7) (6) (24) (49) Core income $203 $409 $752 $1,025 Core income (loss) is calculated by excluding from net income (loss) the after-tax effects of net investment gains or losses and gains or losses resulting from pension settlement transactions. Net investment gains or losses are excluded from the calculation of core income (loss) because they are generally driven by economic factors that are not necessarily reflective of our primary operations. The calculation of core income (loss) excludes gains or losses resulting from pension settlement transactions as they result from decisions regarding our defined benefit pension plans which are unrelated to our primary operations. Management monitors core income (loss) for each business segment to assess segment performance. Presentation of consolidated core income (loss) is deemed to be a non-GAAP financial measure and management believes some investors may find this measure useful to evaluate our primary operations. Reconciliation of Net Income (Loss) per Diluted Share to Core Income (Loss) per Diluted Share Results for the Three Months Ended September 30 Results for the Nine Months Ended September 30 2026 2025 2026 2025 Net income per diluted share $0.72 $1.48 $2.67 $3.58 Less: Net investment losses (0.03) (0.02) (0.10) (0.18) Core income per diluted share $0.75 $1.50 $2.77 $3.76 Core income (loss) per diluted share provides management and investors with a valuable measure of the Company's operating performance for the same reasons applicable to its underlying measure, core income (loss). Core income (loss) per diluted share is core income (loss) on a per diluted share basis. 21 Reconciliation of Net Income (Loss) to Core Income (Loss) Reconciliation of GAAP Measures to Non-GAAP Measures
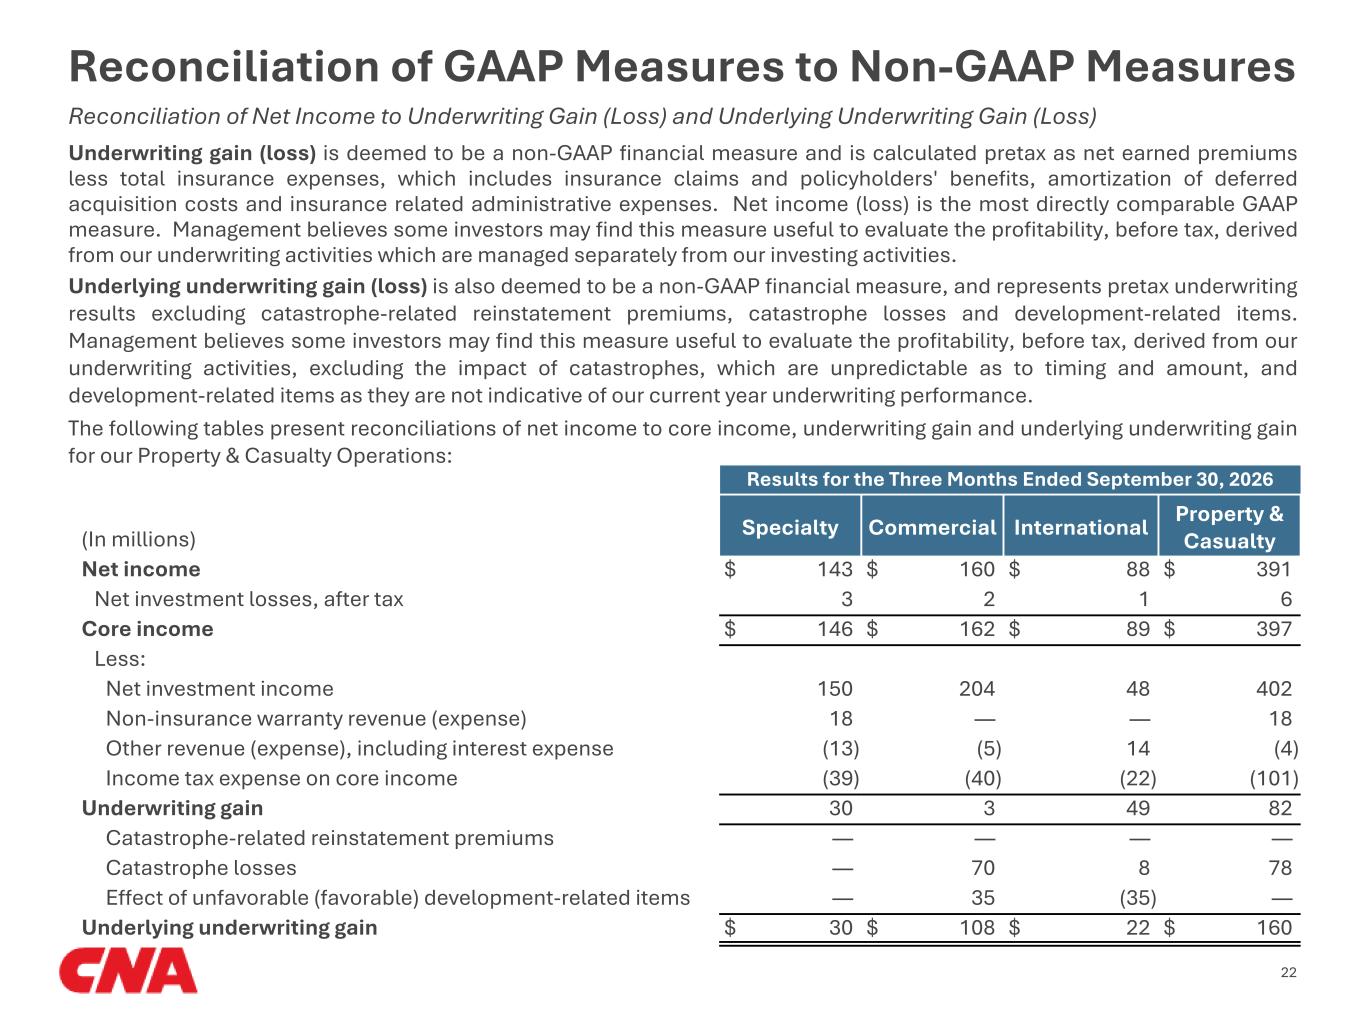
22 Underwriting gain (loss) is deemed to be a non-GAAP financial measure and is calculated pretax as net earned premiums less total insurance expenses, which includes insurance claims and policyholders' benefits, amortization of deferred acquisition costs and insurance related administrative expenses. Net income (loss) is the most directly comparable GAAP measure. Management believes some investors may find this measure useful to evaluate the profitability, before tax, derived from our underwriting activities which are managed separately from our investing activities. Underlying underwriting gain (loss) is also deemed to be a non-GAAP financial measure, and represents pretax underwriting results excluding catastrophe-related reinstatement premiums, catastrophe losses and development-related items. Management believes some investors may find this measure useful to evaluate the profitability, before tax, derived from our underwriting activities, excluding the impact of catastrophes, which are unpredictable as to timing and amount, and development-related items as they are not indicative of our current year underwriting performance. The following tables present reconciliations of net income to core income, underwriting gain and underlying underwriting gain for our Property & Casualty Operations: Results for the Three Months Ended September 30, 2026 (In millions) Specialty Commercial International Property & Casualty Net income $ 143 $ 160 $ 88 $ 391 Net investment losses, after tax 3 2 1 6 Core income $ 146 $ 162 $ 89 $ 397 Less: Net investment income 150 204 48 402 Non-insurance warranty revenue (expense) 18 — — 18 Other revenue (expense), including interest expense (13) (5) 14 (4) Income tax expense on core income (39) (40) (22) (101) Underwriting gain 30 3 49 82 Catastrophe-related reinstatement premiums — — — — Catastrophe losses — 70 8 78 Effect of unfavorable (favorable) development-related items — 35 (35) — Underlying underwriting gain $ 30 $ 108 $ 22 $ 160 Reconciliation of Net Income to Underwriting Gain (Loss) and Underlying Underwriting Gain (Loss) Reconciliation of GAAP Measures to Non-GAAP Measures
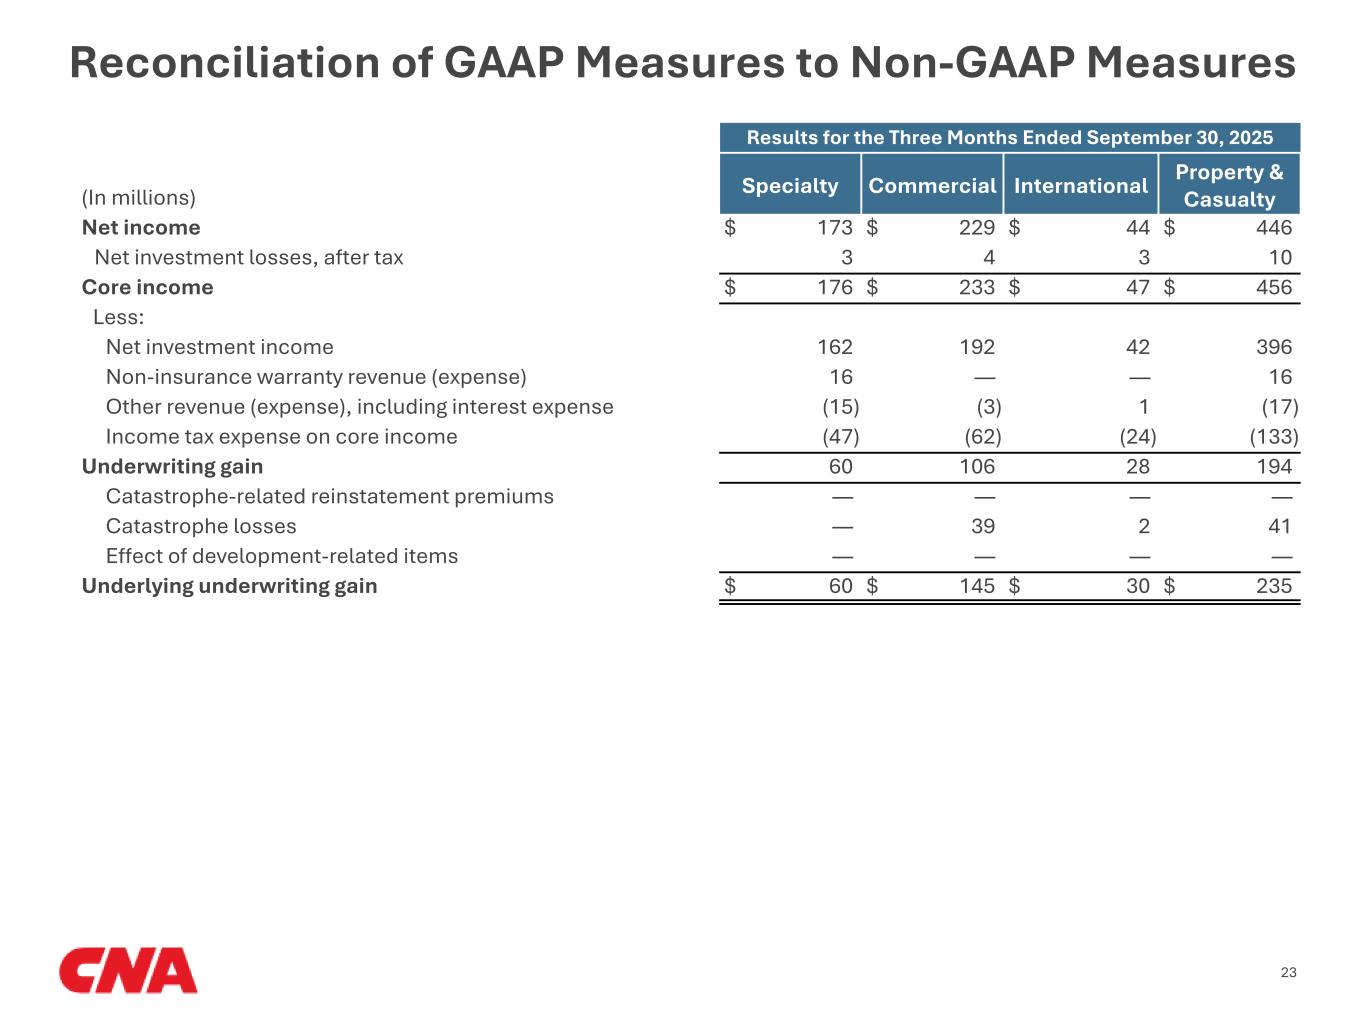
23 Results for the Three Months Ended September 30, 2025 (In millions) Specialty Commercial International Property & Casualty Net income $ 173 $ 229 $ 44 $ 446 Net investment losses, after tax 3 4 3 10 Core income $ 176 $ 233 $ 47 $ 456 Less: Net investment income 162 192 42 396 Non-insurance warranty revenue (expense) 16 — — 16 Other revenue (expense), including interest expense (15) (3) 1 (17) Income tax expense on core income (47) (62) (24) (133) Underwriting gain 60 106 28 194 Catastrophe-related reinstatement premiums — — — — Catastrophe losses — 39 2 41 Effect of development-related items — — — — Underlying underwriting gain $ 60 $ 145 $ 30 $ 235 Reconciliation of GAAP Measures to Non-GAAP Measures
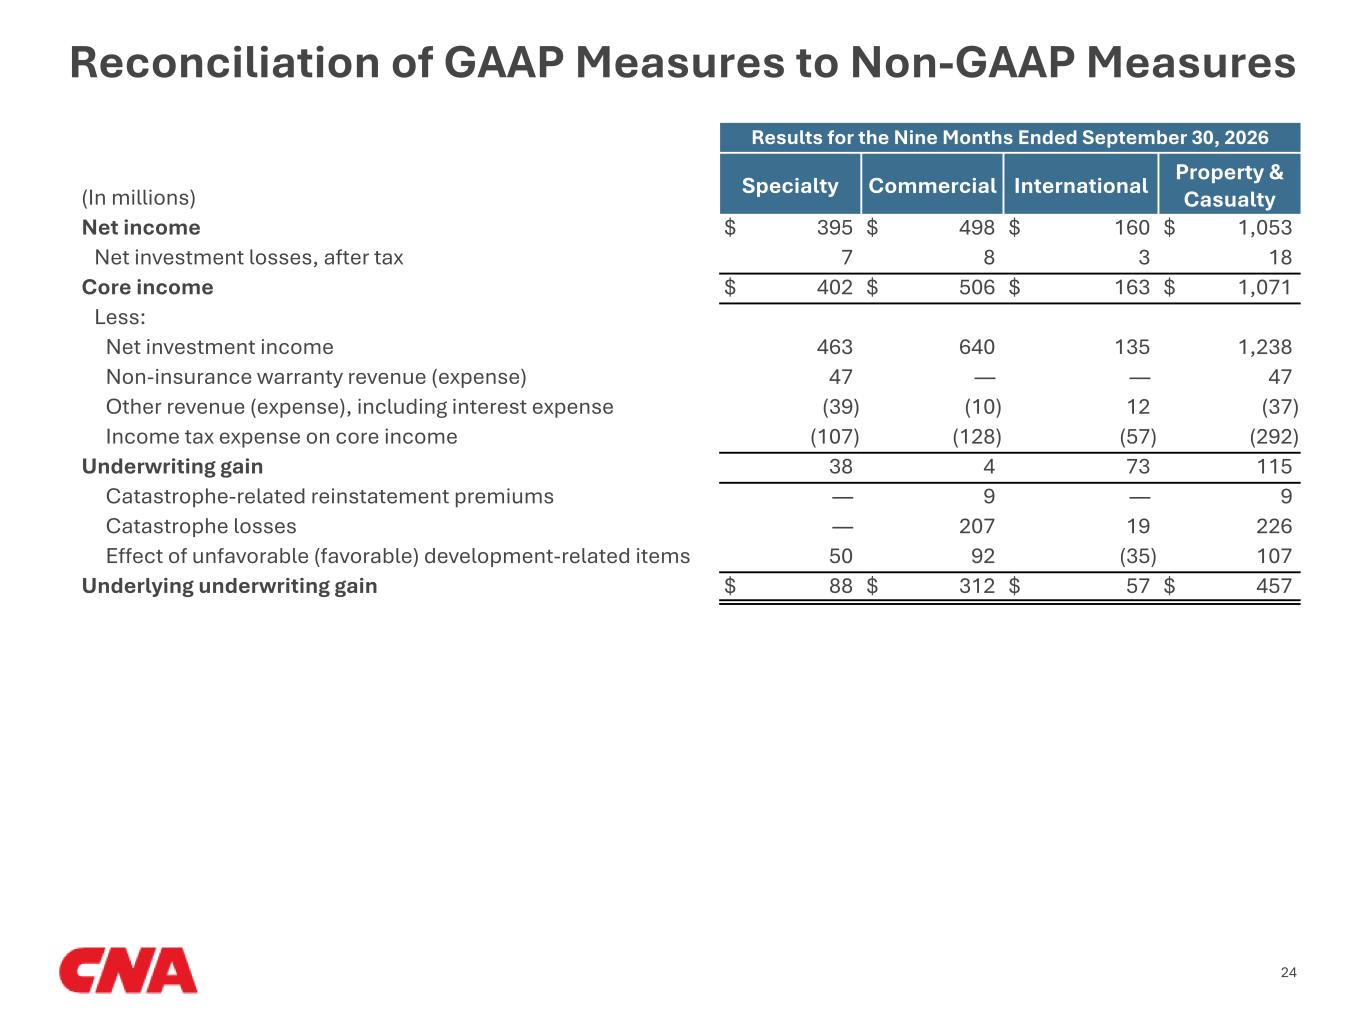
24 Results for the Nine Months Ended September 30, 2026 (In millions) Specialty Commercial International Property & Casualty Net income $ 395 $ 498 $ 160 $ 1,053 Net investment losses, after tax 7 8 3 18 Core income $ 402 $ 506 $ 163 $ 1,071 Less: Net investment income 463 640 135 1,238 Non-insurance warranty revenue (expense) 47 — — 47 Other revenue (expense), including interest expense (39) (10) 12 (37) Income tax expense on core income (107) (128) (57) (292) Underwriting gain 38 4 73 115 Catastrophe-related reinstatement premiums — 9 — 9 Catastrophe losses — 207 19 226 Effect of unfavorable (favorable) development-related items 50 92 (35) 107 Underlying underwriting gain $ 88 $ 312 $ 57 $ 457 Reconciliation of GAAP Measures to Non-GAAP Measures
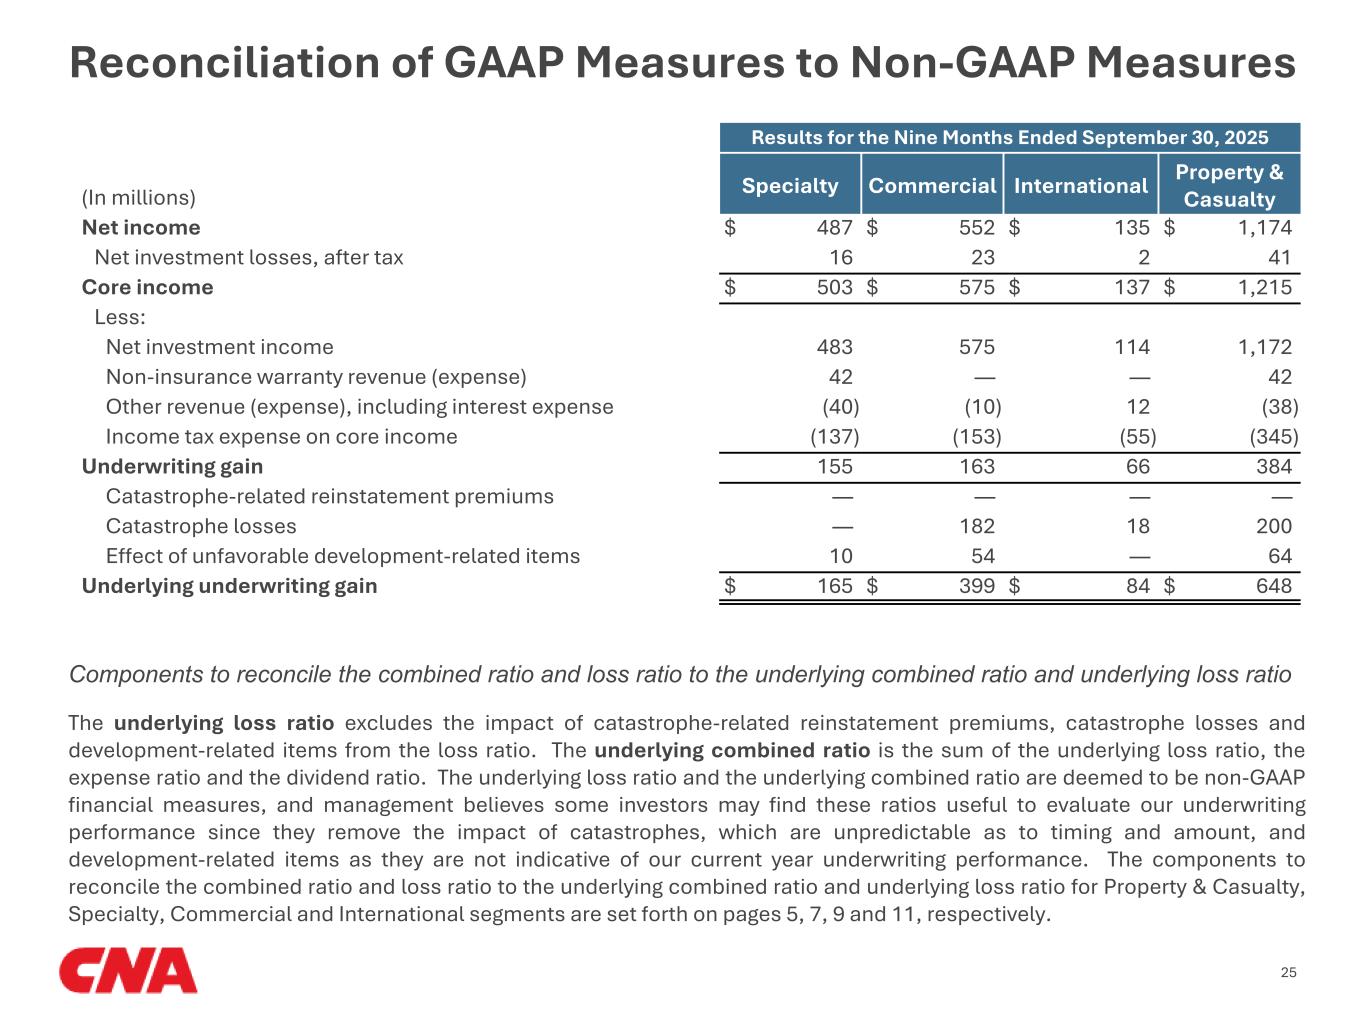
25 Results for the Nine Months Ended September 30, 2025 (In millions) Specialty Commercial International Property & Casualty Net income $ 487 $ 552 $ 135 $ 1,174 Net investment losses, after tax 16 23 2 41 Core income $ 503 $ 575 $ 137 $ 1,215 Less: Net investment income 483 575 114 1,172 Non-insurance warranty revenue (expense) 42 — — 42 Other revenue (expense), including interest expense (40) (10) 12 (38) Income tax expense on core income (137) (153) (55) (345) Underwriting gain 155 163 66 384 Catastrophe-related reinstatement premiums — — — — Catastrophe losses — 182 18 200 Effect of unfavorable development-related items 10 54 — 64 Underlying underwriting gain $ 165 $ 399 $ 84 $ 648 The underlying loss ratio excludes the impact of catastrophe-related reinstatement premiums, catastrophe losses and development-related items from the loss ratio. The underlying combined ratio is the sum of the underlying loss ratio, the expense ratio and the dividend ratio. The underlying loss ratio and the underlying combined ratio are deemed to be non-GAAP financial measures, and management believes some investors may find these ratios useful to evaluate our underwriting performance since they remove the impact of catastrophes, which are unpredictable as to timing and amount, and development-related items as they are not indicative of our current year underwriting performance. The components to reconcile the combined ratio and loss ratio to the underlying combined ratio and underlying loss ratio for Property & Casualty, Specialty, Commercial and International segments are set forth on pages 5, 7, 9 and 11, respectively. Components to reconcile the combined ratio and loss ratio to the underlying combined ratio and underlying loss ratio Reconciliation of GAAP Measures to Non-GAAP Measures
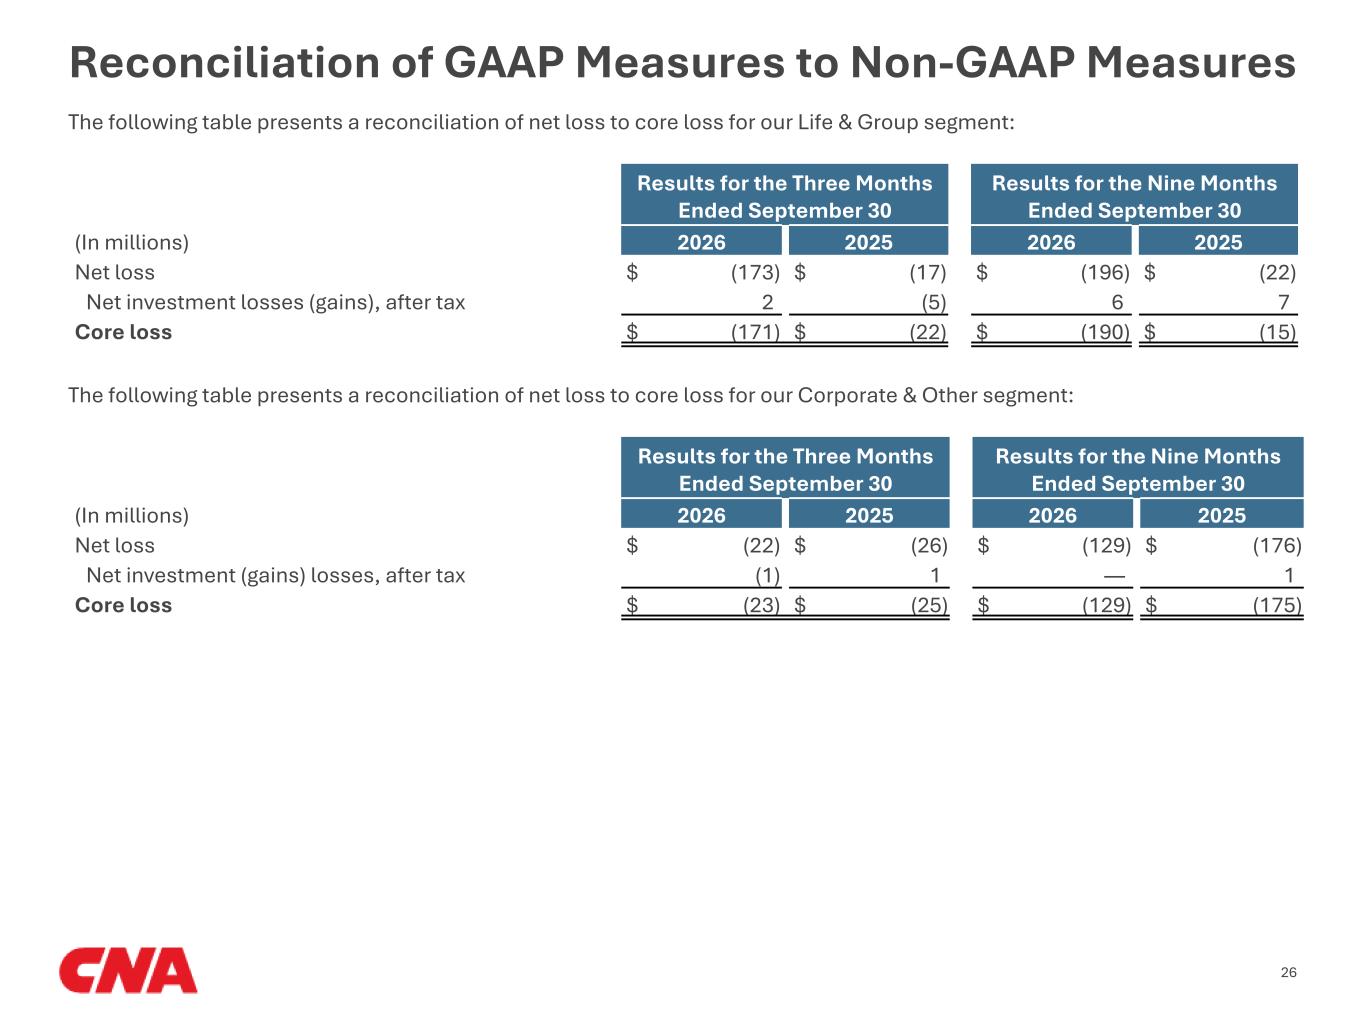
Reconciliation of GAAP Measures to Non-GAAP Measures The following table presents a reconciliation of net loss to core loss for our Life & Group segment: Results for the Three Months Ended September 30 Results for the Nine Months Ended September 30 (In millions) 2026 2025 2026 2025 Net loss $ (173) $ (17) $ (196) $ (22) Net investment losses (gains), after tax 2 (5) 6 7 Core loss $ (171) $ (22) $ (190) $ (15) The following table presents a reconciliation of net loss to core loss for our Corporate & Other segment: Results for the Three Months Ended September 30 Results for the Nine Months Ended September 30 (In millions) 2026 2025 2026 2025 Net loss $ (22) $ (26) $ (129) $ (176) Net investment (gains) losses, after tax (1) 1 — 1 Core loss $ (23) $ (25) $ (129) $ (175) 26
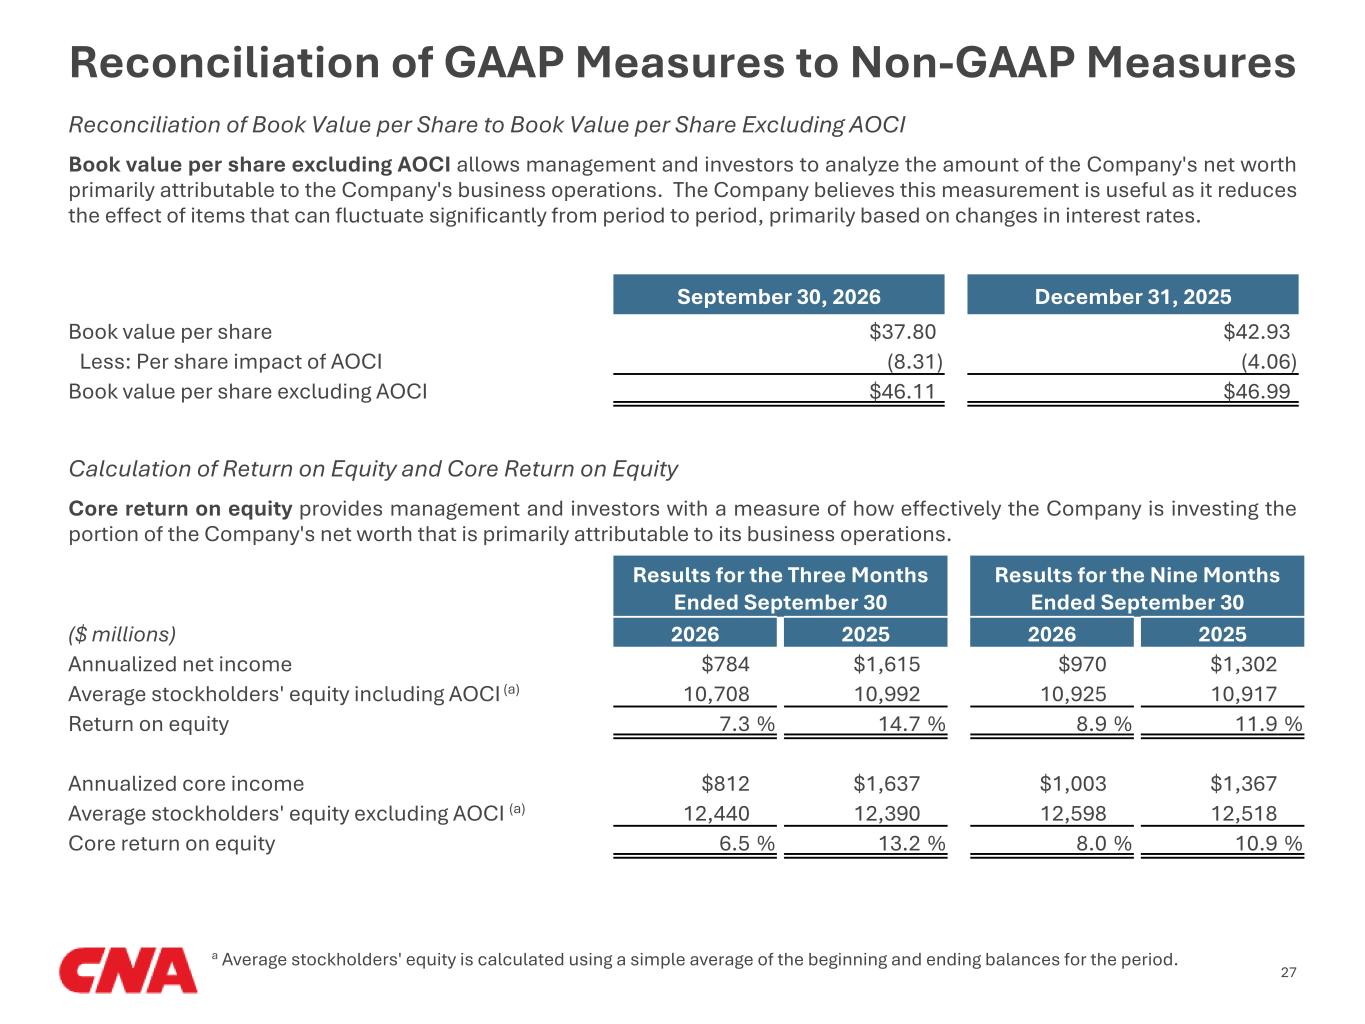
September 30, 2026 December 31, 2025 Book value per share $37.80 $42.93 Less: Per share impact of AOCI (8.31) (4.06) Book value per share excluding AOCI $46.11 $46.99 Book value per share excluding AOCI allows management and investors to analyze the amount of the Company's net worth primarily attributable to the Company's business operations. The Company believes this measurement is useful as it reduces the effect of items that can fluctuate significantly from period to period, primarily based on changes in interest rates. Calculation of Return on Equity and Core Return on Equity Results for the Three Months Ended September 30 Results for the Nine Months Ended September 30 ($ millions) 2026 2025 2026 2025 Annualized net income $784 $1,615 $970 $1,302 Average stockholders' equity including AOCI (a) 10,708 10,992 10,925 10,917 Return on equity 7.3 % 14.7 % 8.9 % 11.9 % Annualized core income $812 $1,637 $1,003 $1,367 Average stockholders' equity excluding AOCI (a) 12,440 12,390 12,598 12,518 Core return on equity 6.5 % 13.2 % 8.0 % 10.9 % Core return on equity provides management and investors with a measure of how effectively the Company is investing the portion of the Company's net worth that is primarily attributable to its business operations. a Average stockholders' equity is calculated using a simple average of the beginning and ending balances for the period. 27 Reconciliation of Book Value per Share to Book Value per Share Excluding AOCI Reconciliation of GAAP Measures to Non-GAAP Measures