Earnings Results 3rd Quarter 2026 October 16, 2026 .2
2 This presentation may contain forward-looking statements regarding M&T Bank Corporation (“M&T”) within the meaning of the Private Securities Litigation Reform Act of 1995 and the rules and regulations of the Securities and Exchange Commission (“SEC”). Any statement that does not describe historical or current facts is a forward-looking statement, including statements based on current expectations, estimates and projections about M&T's business, and management's beliefs and assumptions. Statements regarding the potential effects of events or factors specific to M&T and/or the financial industry as a whole, as well as national and global events generally, on M&T's business, financial condition, liquidity and results of operations may constitute forward-looking statements. Such statements are subject to the risk that the actual effects may differ, possibly materially, from what is reflected in those forward-looking statements due to factors and future developments that are uncertain, unpredictable and in many cases beyond M&T's control. Forward-looking statements are typically identified by words such as "believe," "expect," "anticipate," "intend," "target," "estimate," "continue," or "potential," by future conditional verbs such as "will," "would," "should," "could," or "may," or by variations of such words or by similar expressions. These statements are not guarantees of future performance and involve certain risks, uncertainties and assumptions which are difficult to predict and may cause actual outcomes to differ materially from what is expressed or forecasted. While there can be no assurance that any list of risks and uncertainties is complete, important factors that could cause actual outcomes and results to differ materially from those contemplated by forward-looking statements include the following, without limitation: economic conditions and growth rates, including inflation and market volatility; events, developments and current conditions in the financial services industry, including trust, brokerage and investment management businesses; changes in interest rates, spreads on earning assets and interest-bearing liabilities, and interest rate sensitivity; prepayment speeds, loan originations, loan concentrations by type and industry, credit losses and market values on loans, collateral securing loans, and other assets; sources of liquidity; levels of client deposits; ability to contain costs and expenses; changes in M&T's credit ratings; domestic or international political developments and other geopolitical events, including trade and tariff policies and international conflicts and hostilities; changes and trends in the securities markets; common shares outstanding and common stock price volatility; fair value of and number of stock-based compensation awards to be issued in future periods; the impact of changes in market values on trust-, brokerage-, and investment management-related revenues; federal, state or local legislation and/or regulations affecting the financial services industry, or M&T and its subsidiaries individually or collectively, including tax policy; regulatory supervision and oversight, including monetary policy and capital requirements; governmental and public policy changes; political conditions, either nationally or in the states in which M&T and its subsidiaries do business; the initiation and outcome of potential, pending and future litigation, investigations and governmental proceedings, including tax-related examinations and other matters; operational risk events, including loss resulting from fraud by employees or persons outside M&T and breaches in data and cybersecurity; changes in accounting policies or procedures as may be required by the Financial Accounting Standards Board, regulatory agencies or legislation; increasing price, product and service competition by competitors, including new entrants; technological developments and changes; the ability to continue to introduce competitive new products and services on a timely, cost-effective basis; the mix of products and services; protection and validity of intellectual property rights; reliance on large customers; technological, implementation and cost/ financial risks in large, multi-year contracts; continued availability of financing; financial resources in the amounts, at the times and on the terms required to support M&T and its subsidiaries' future businesses; and material differences in the actual financial results of merger, acquisition, divestment and investment activities compared with M&T's initial expectations, including the full realization of anticipated cost savings and revenue enhancements. These are representative of the factors that could affect the outcome of the forward-looking statements. In addition, as noted, such statements could be affected by general industry and market conditions and growth rates, general economic and political conditions, either nationally or in the states in which M&T and its subsidiaries do business, and other factors. M&T provides further detail regarding these risks and uncertainties in its Form 10-K for the year ended December 31, 2025, including in the Risk Factors section of such report, as well as in other SEC filings. Forward-looking statements speak only as of the date they are made, and M&T assumes no duty and does not undertake to update forward-looking statements. Annualized, pro forma, projected, and estimated numbers are used for illustrative purposes only, are not forecasts and may not reflect actual results. This presentation also contains financial information and performance measures determined by methods other than in accordance with accounting principles generally accepted in the United States ("GAAP"). Management believes investors may find these non-GAAP financial measures useful. These disclosures should not be viewed as a substitute for financial measures determined in accordance with GAAP, nor are they necessarily comparable to non-GAAP performance measures that may be presented by other companies. Please see the Appendix for reconciliation of GAAP with corresponding non- GAAP measures, as indicated in the presentation. Forward-Looking Statements and Non-GAAP Financial Measures
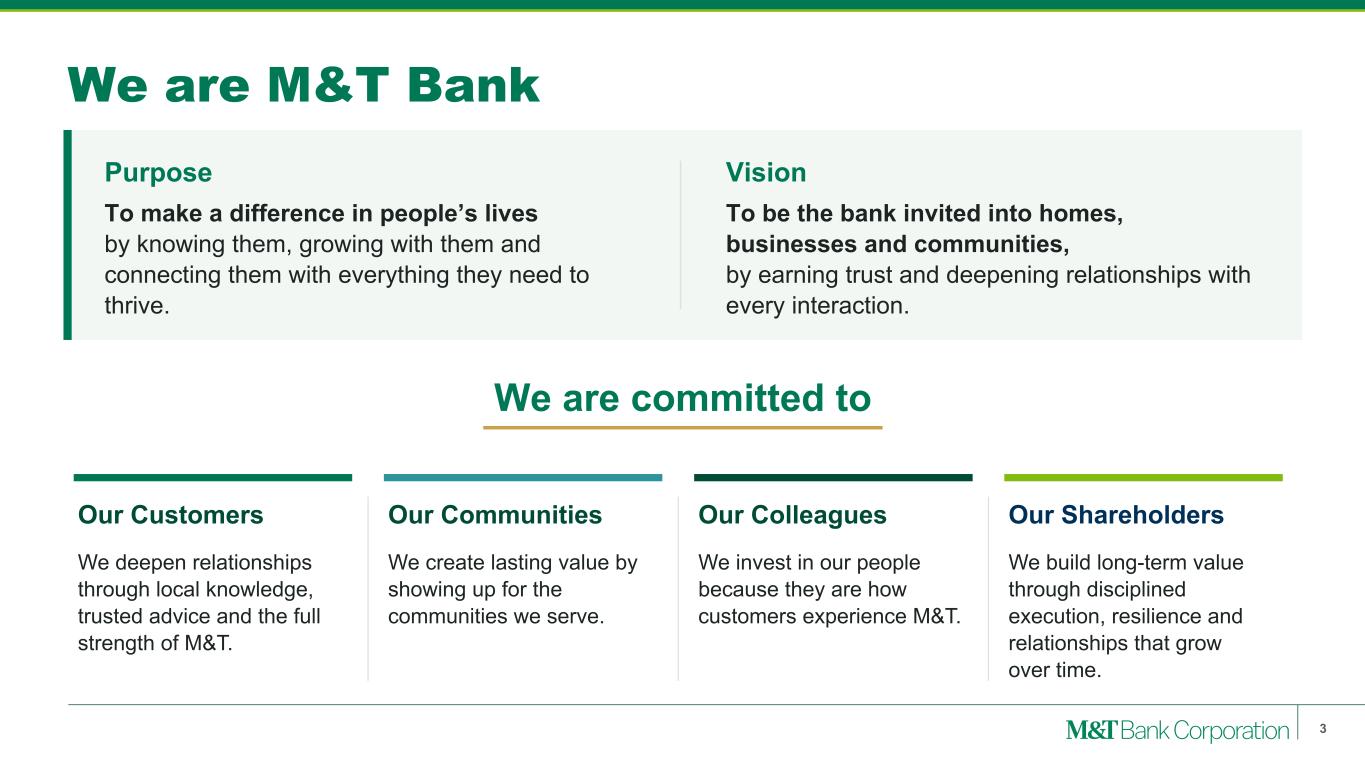
We are M&T Bank Purpose To make a difference in people’s lives by knowing them, growing with them and connecting them with everything they need to thrive. Vision To be the bank invited into homes, businesses and communities, by earning trust and deepening relationships with every interaction. We are committed to Our Customers We deepen relationships through local knowledge, trusted advice and the full strength of M&T. Our Communities We create lasting value by showing up for the communities we serve. Our Colleagues We invest in our people because they are how customers experience M&T. Our Shareholders We build long-term value through disciplined execution, resilience and relationships that grow over time. 3
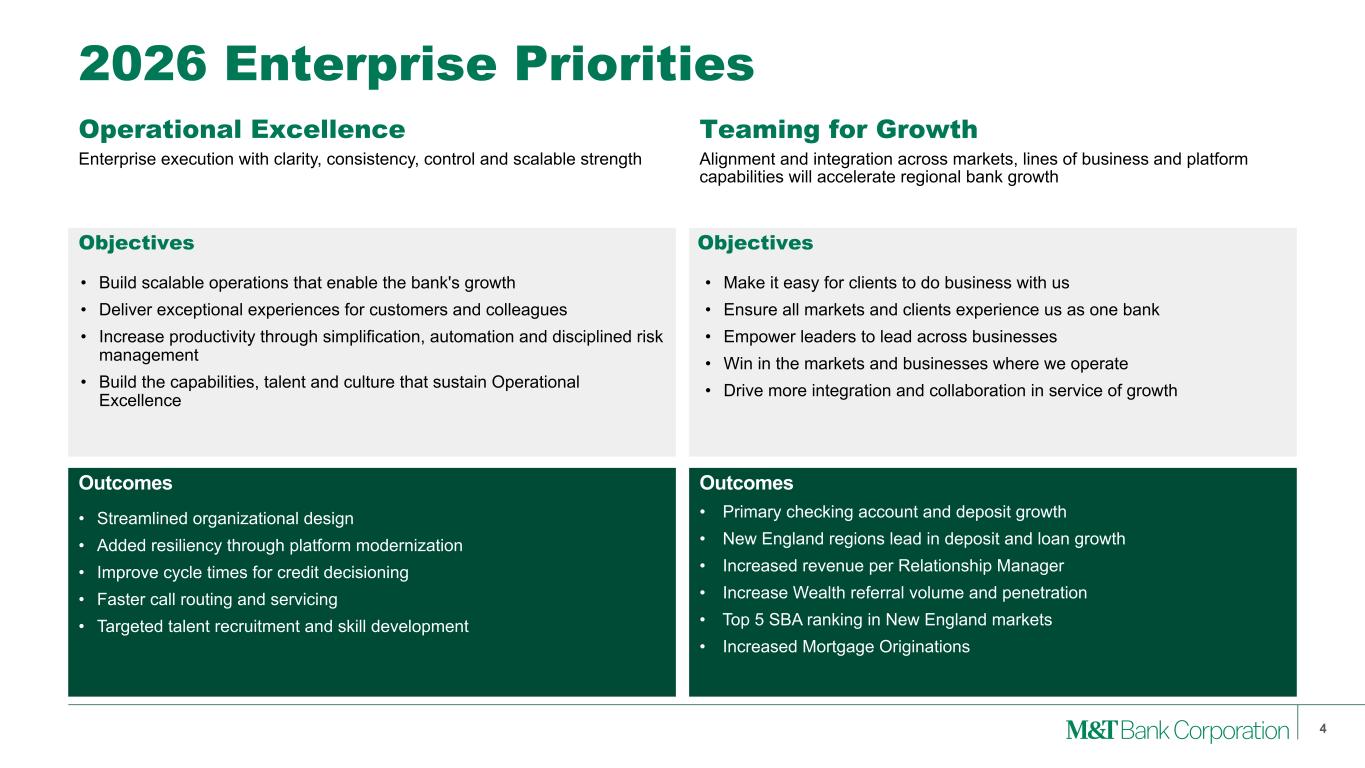
Operational Excellence Alignment and integration across markets, lines of business and platform capabilities will accelerate regional bank growth 4 2026 Enterprise Priorities Teaming for Growth • Make it easy for clients to do business with us • Ensure all markets and clients experience us as one bank • Empower leaders to lead across businesses • Win in the markets and businesses where we operate • Drive more integration and collaboration in service of growth Enterprise execution with clarity, consistency, control and scalable strength • Build scalable operations that enable the bank's growth • Deliver exceptional experiences for customers and colleagues • Increase productivity through simplification, automation and disciplined risk management • Build the capabilities, talent and culture that sustain Operational Excellence • Streamlined organizational design • Added resiliency through platform modernization • Improve cycle times for credit decisioning • Faster call routing and servicing • Targeted talent recruitment and skill development • Primary checking account and deposit growth • New England regions lead in deposit and loan growth • Increased revenue per Relationship Manager • Increase Wealth referral volume and penetration • Top 5 SBA ranking in New England markets • Increased Mortgage Originations Objectives Objectives Outcomes Outcomes
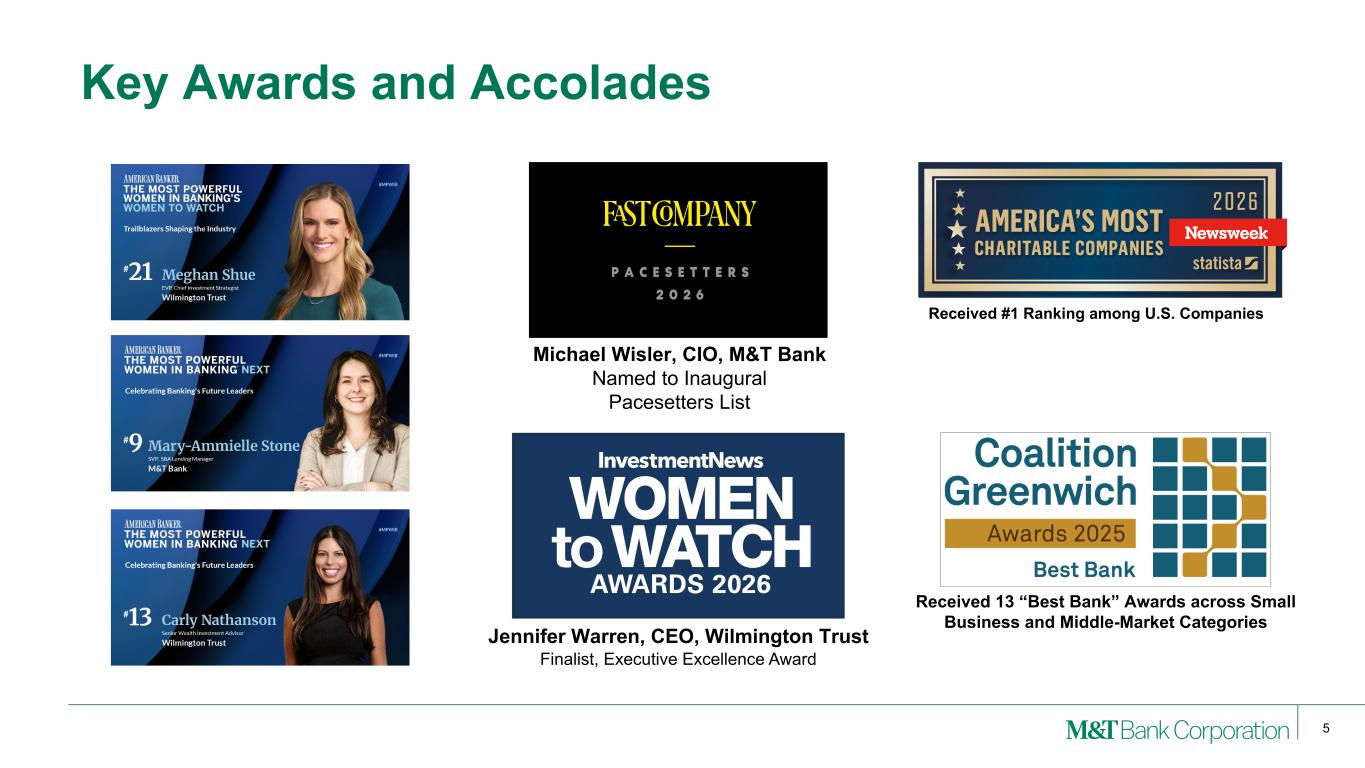
Key Awards and Accolades Received 13 “Best Bank” Awards across Small Business and Middle-Market Categories Jennifer Warren, CEO, Wilmington Trust Finalist, Executive Excellence Award Michael Wisler, CIO, M&T Bank Named to Inaugural Pacesetters List Received #1 Ranking among U.S. Companies 5
6 Financial Results
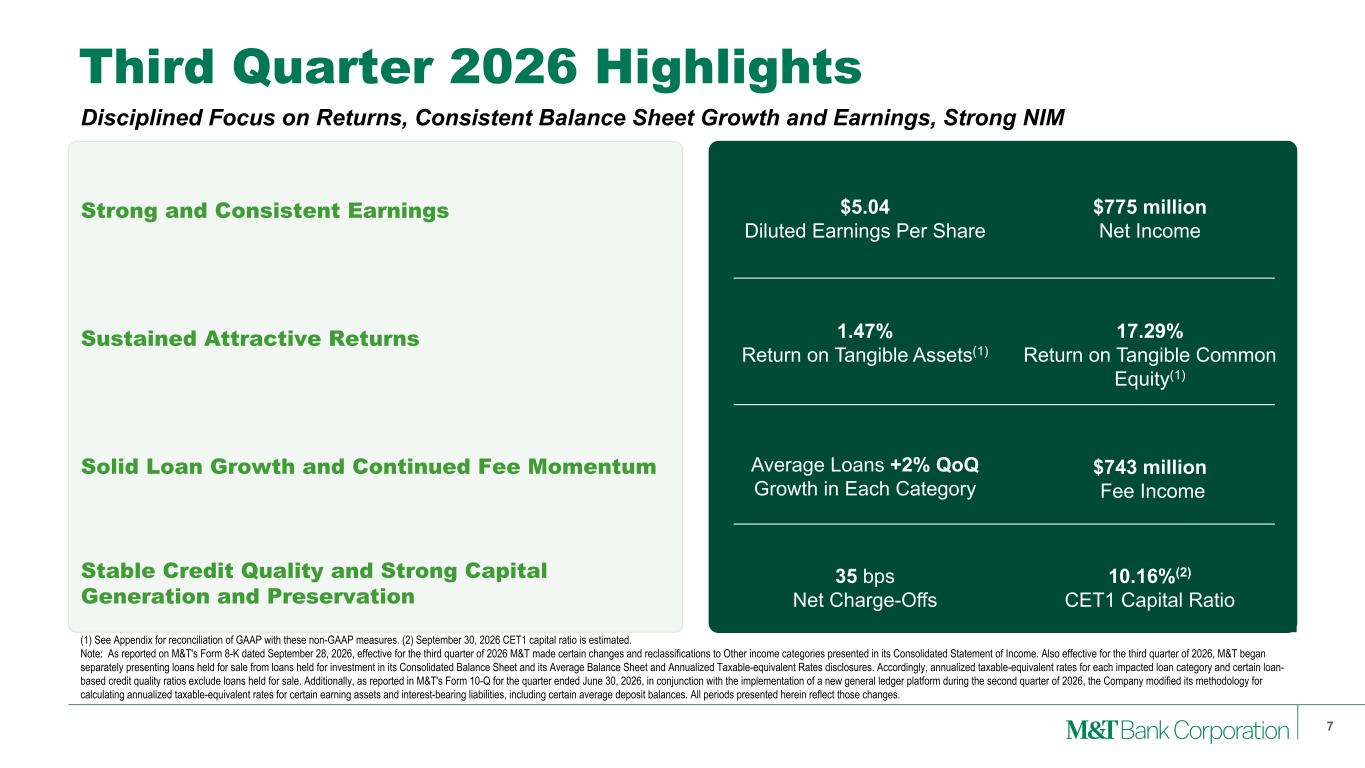
Third Quarter 2026 Highlights 7 (1) See Appendix for reconciliation of GAAP with these non-GAAP measures. (2) September 30, 2026 CET1 capital ratio is estimated. Note: As reported on M&T's Form 8-K dated September 28, 2026, effective for the third quarter of 2026 M&T made certain changes and reclassifications to Other income categories presented in its Consolidated Statement of Income. Also effective for the third quarter of 2026, M&T began separately presenting loans held for sale from loans held for investment in its Consolidated Balance Sheet and its Average Balance Sheet and Annualized Taxable-equivalent Rates disclosures. Accordingly, annualized taxable-equivalent rates for each impacted loan category and certain loan- based credit quality ratios exclude loans held for sale. Additionally, as reported in M&T's Form 10-Q for the quarter ended June 30, 2026, in conjunction with the implementation of a new general ledger platform during the second quarter of 2026, the Company modified its methodology for calculating annualized taxable-equivalent rates for certain earning assets and interest-bearing liabilities, including certain average deposit balances. All periods presented herein reflect those changes. Disciplined Focus on Returns, Consistent Balance Sheet Growth and Earnings, Strong NIM Strong and Consistent Earnings Sustained Attractive Returns Solid Loan Growth and Continued Fee Momentum Stable Credit Quality and Strong Capital Generation and Preservation $5.04 Diluted Earnings Per Share $775 million Net Income 1.47% Return on Tangible Assets(1) 17.29% Return on Tangible Common Equity(1) Average Loans +2% QoQ Growth in Each Category $743 million Fee Income 35 bps Net Charge-Offs 10.16%(2) CET1 Capital Ratio
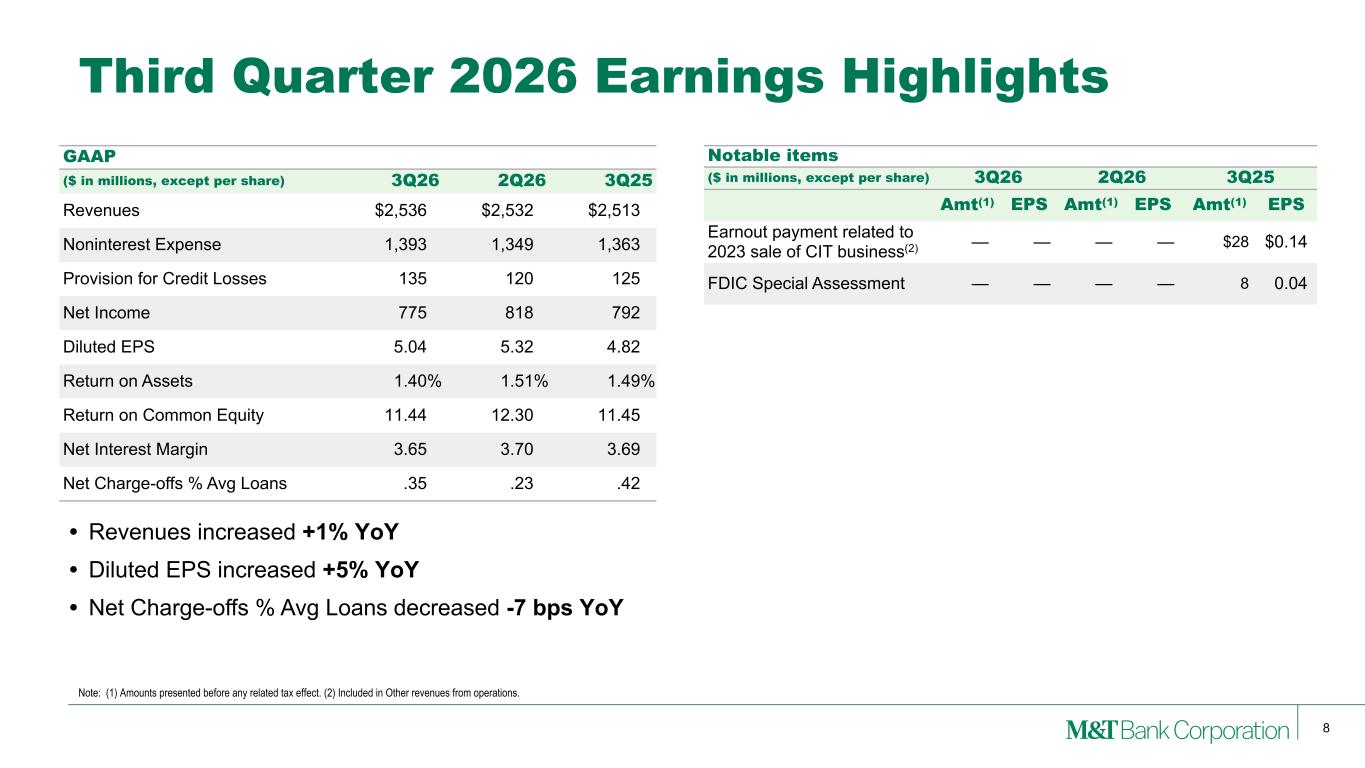
8 • Revenues increased +1% YoY • Diluted EPS increased +5% YoY • Net Charge-offs % Avg Loans decreased -7 bps YoY Notable items ($ in millions, except per share) 3Q26 2Q26 3Q25 Amt(1) EPS Amt(1) EPS Amt(1) EPS Earnout payment related to 2023 sale of CIT business(2) — — — — $28 $0.14 FDIC Special Assessment — — — — 8 0.04 Third Quarter 2026 Earnings Highlights GAAP ($ in millions, except per share) 3Q26 2Q26 3Q25 Revenues $2,536 $2,532 $2,513 Noninterest Expense 1,393 1,349 1,363 Provision for Credit Losses 135 120 125 Net Income 775 818 792 Diluted EPS 5.04 5.32 4.82 Return on Assets 1.40% 1.51% 1.49% Return on Common Equity 11.44 12.30 11.45 Net Interest Margin 3.65 3.70 3.69 Net Charge-offs % Avg Loans .35 .23 .42 Note: (1) Amounts presented before any related tax effect. (2) Included in Other revenues from operations.
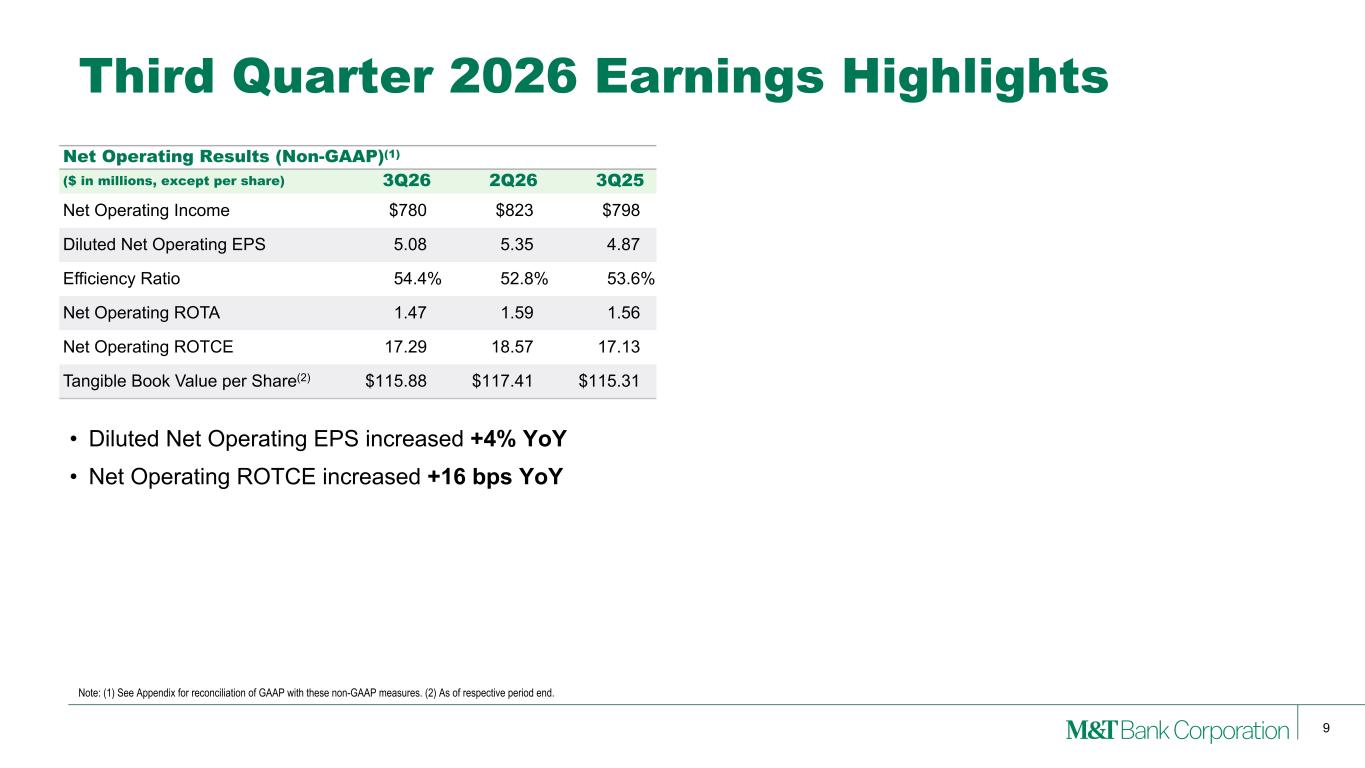
9 Note: (1) See Appendix for reconciliation of GAAP with these non-GAAP measures. (2) As of respective period end. Third Quarter 2026 Earnings Highlights Net Operating Results (Non-GAAP)(1) ($ in millions, except per share) 3Q26 2Q26 3Q25 Net Operating Income $780 $823 $798 Diluted Net Operating EPS 5.08 5.35 4.87 Efficiency Ratio 54.4% 52.8% 53.6% Net Operating ROTA 1.47 1.59 1.56 Net Operating ROTCE 17.29 18.57 17.13 Tangible Book Value per Share(2) $115.88 $117.41 $115.31 • Diluted Net Operating EPS increased +4% YoY • Net Operating ROTCE increased +16 bps YoY
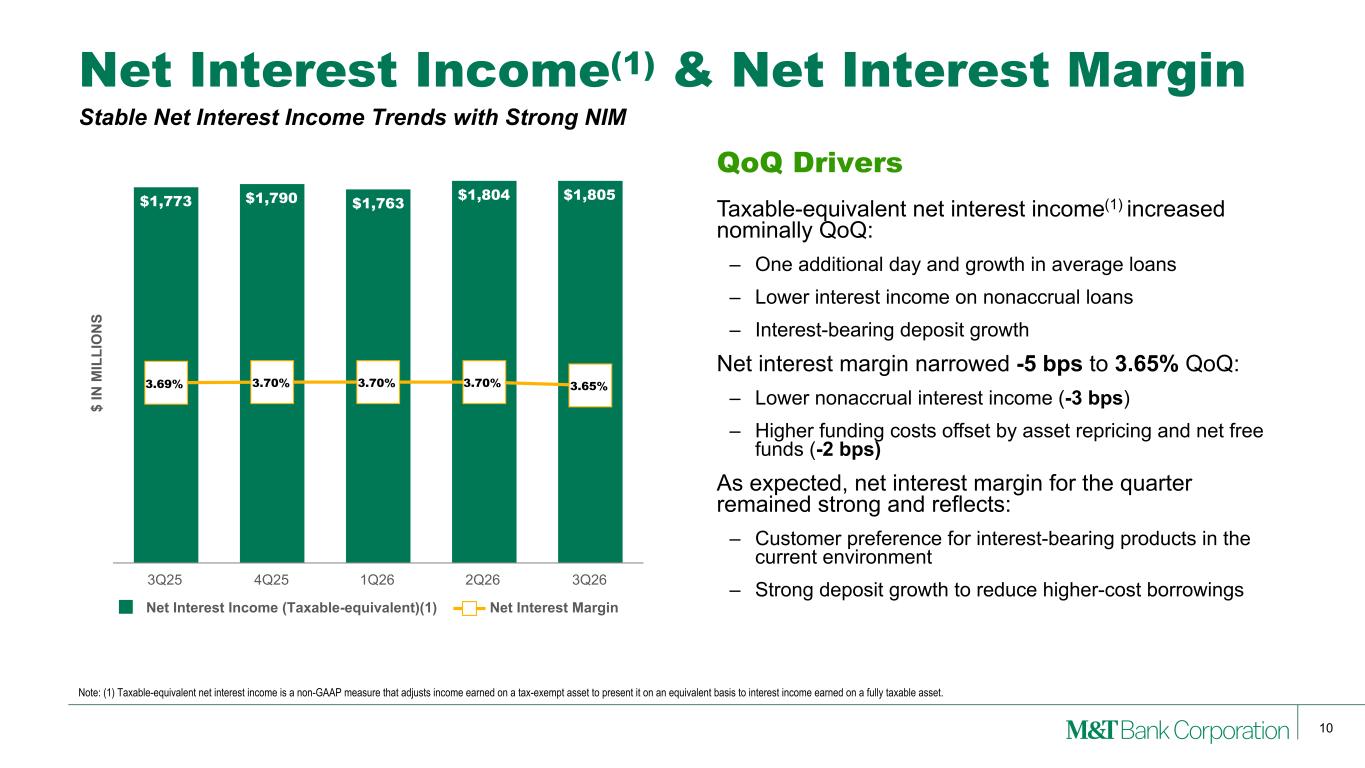
10 Net Interest Income(1) & Net Interest Margin Note: (1) Taxable-equivalent net interest income is a non-GAAP measure that adjusts income earned on a tax-exempt asset to present it on an equivalent basis to interest income earned on a fully taxable asset. Stable Net Interest Income Trends with Strong NIM $ IN M IL LI O N S $1,773 $1,790 $1,763 $1,804 $1,805 3.69% 3.70% 3.70% 3.70% 3.65% Net Interest Income (Taxable-equivalent)(1) Net Interest Margin 3Q25 4Q25 1Q26 2Q26 3Q26 QoQ Drivers Taxable-equivalent net interest income(1) increased nominally QoQ: – One additional day and growth in average loans – Lower interest income on nonaccrual loans – Interest-bearing deposit growth Net interest margin narrowed -5 bps to 3.65% QoQ: – Lower nonaccrual interest income (-3 bps) – Higher funding costs offset by asset repricing and net free funds (-2 bps) As expected, net interest margin for the quarter remained strong and reflects: – Customer preference for interest-bearing products in the current environment – Strong deposit growth to reduce higher-cost borrowings
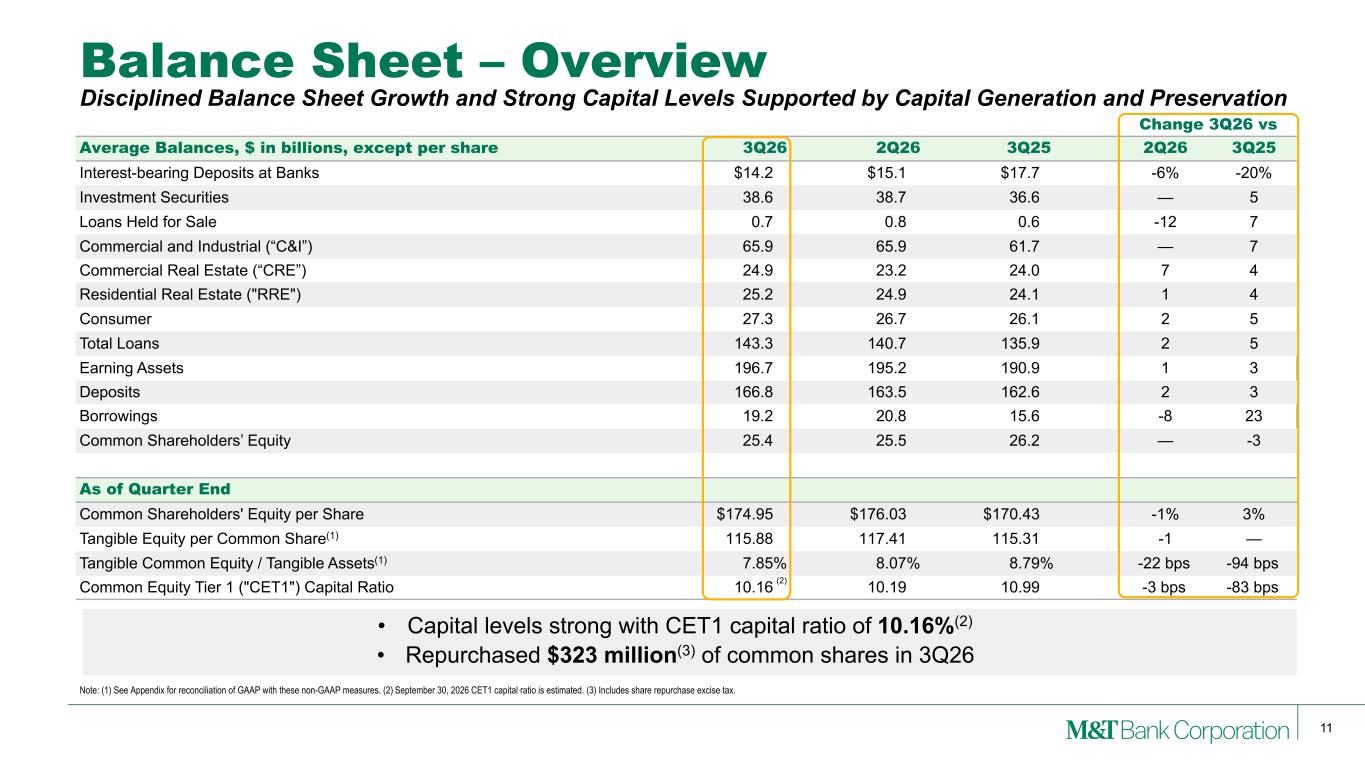
11 • Capital levels strong with CET1 capital ratio of 10.16%(2) • Repurchased $323 million(3) of common shares in 3Q26 Change 3Q26 vs Average Balances, $ in billions, except per share 3Q26 2Q26 3Q25 2Q26 3Q25 Interest-bearing Deposits at Banks $14.2 $15.1 $17.7 -6% -20% Investment Securities 38.6 38.7 36.6 — 5 Loans Held for Sale 0.7 0.8 0.6 -12 7 Commercial and Industrial (“C&I”) 65.9 65.9 61.7 — 7 Commercial Real Estate (“CRE”) 24.9 23.2 24.0 7 4 Residential Real Estate ("RRE") 25.2 24.9 24.1 1 4 Consumer 27.3 26.7 26.1 2 5 Total Loans 143.3 140.7 135.9 2 5 Earning Assets 196.7 195.2 190.9 1 3 Deposits 166.8 163.5 162.6 2 3 Borrowings 19.2 20.8 15.6 -8 23 Common Shareholders’ Equity 25.4 25.5 26.2 — -3 As of Quarter End Common Shareholders' Equity per Share $174.95 $176.03 $170.43 -1% 3% Tangible Equity per Common Share(1) 115.88 117.41 115.31 -1 — Tangible Common Equity / Tangible Assets(1) 7.85 % 8.07 % 8.79 % -22 bps -94 bps Common Equity Tier 1 ("CET1") Capital Ratio 10.16 10.19 10.99 -3 bps -83 bps Balance Sheet – Overview Note: (1) See Appendix for reconciliation of GAAP with these non-GAAP measures. (2) September 30, 2026 CET1 capital ratio is estimated. (3) Includes share repurchase excise tax. Disciplined Balance Sheet Growth and Strong Capital Levels Supported by Capital Generation and Preservation (2)
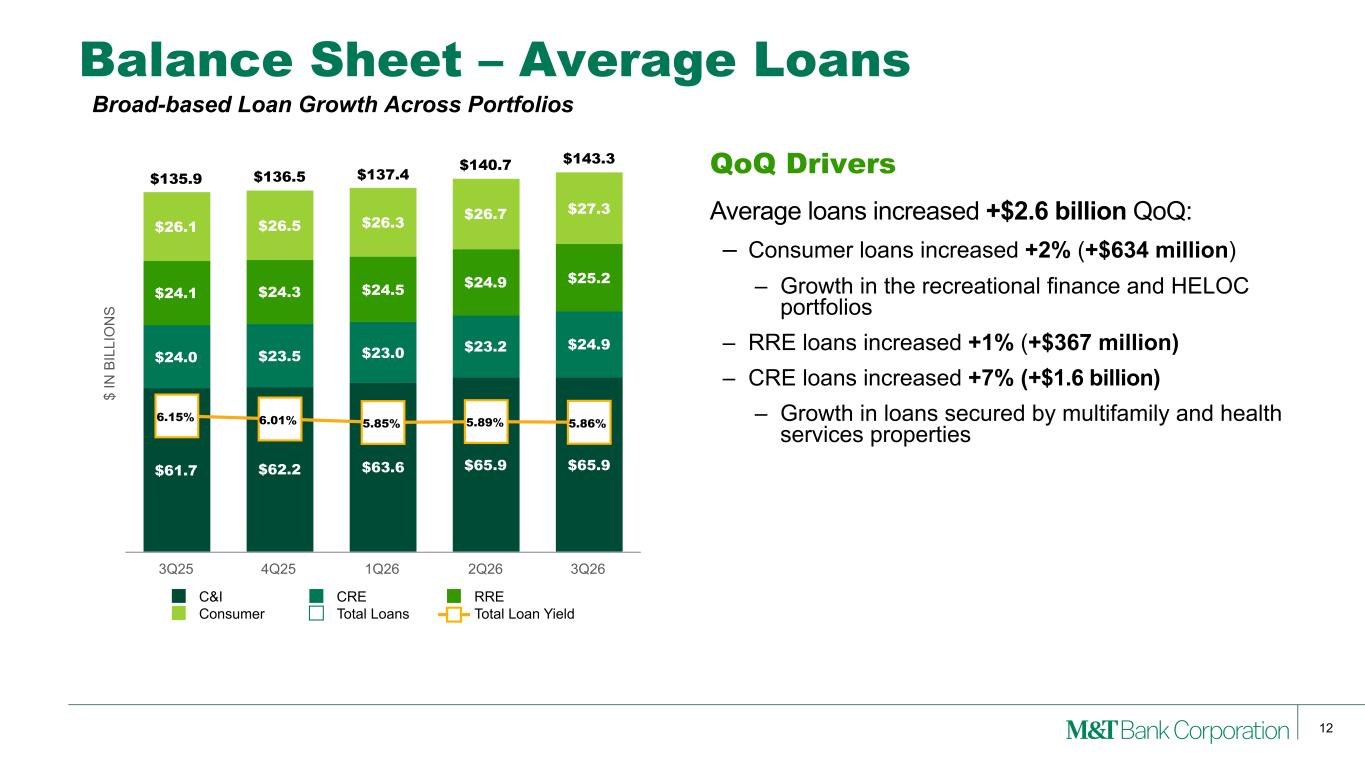
12 Balance Sheet – Average Loans QoQ Drivers Average loans increased +$2.6 billion QoQ: – Consumer loans increased +2% (+$634 million) – Growth in the recreational finance and HELOC portfolios – RRE loans increased +1% (+$367 million) – CRE loans increased +7% (+$1.6 billion) – Growth in loans secured by multifamily and health services properties $ IN B IL LI O N S $61.7 $62.2 $63.6 $65.9 $65.9 $24.0 $23.5 $23.0 $23.2 $24.9 $24.1 $24.3 $24.5 $24.9 $25.2 $26.1 $26.5 $26.3 $26.7 $27.3 $135.9 $136.5 $137.4 $140.7 $143.3 6.15% 6.01% 5.85% 5.89% 5.86% C&I CRE RRE Consumer Total Loans Total Loan Yield 3Q25 4Q25 1Q26 2Q26 3Q26 Broad-based Loan Growth Across Portfolios
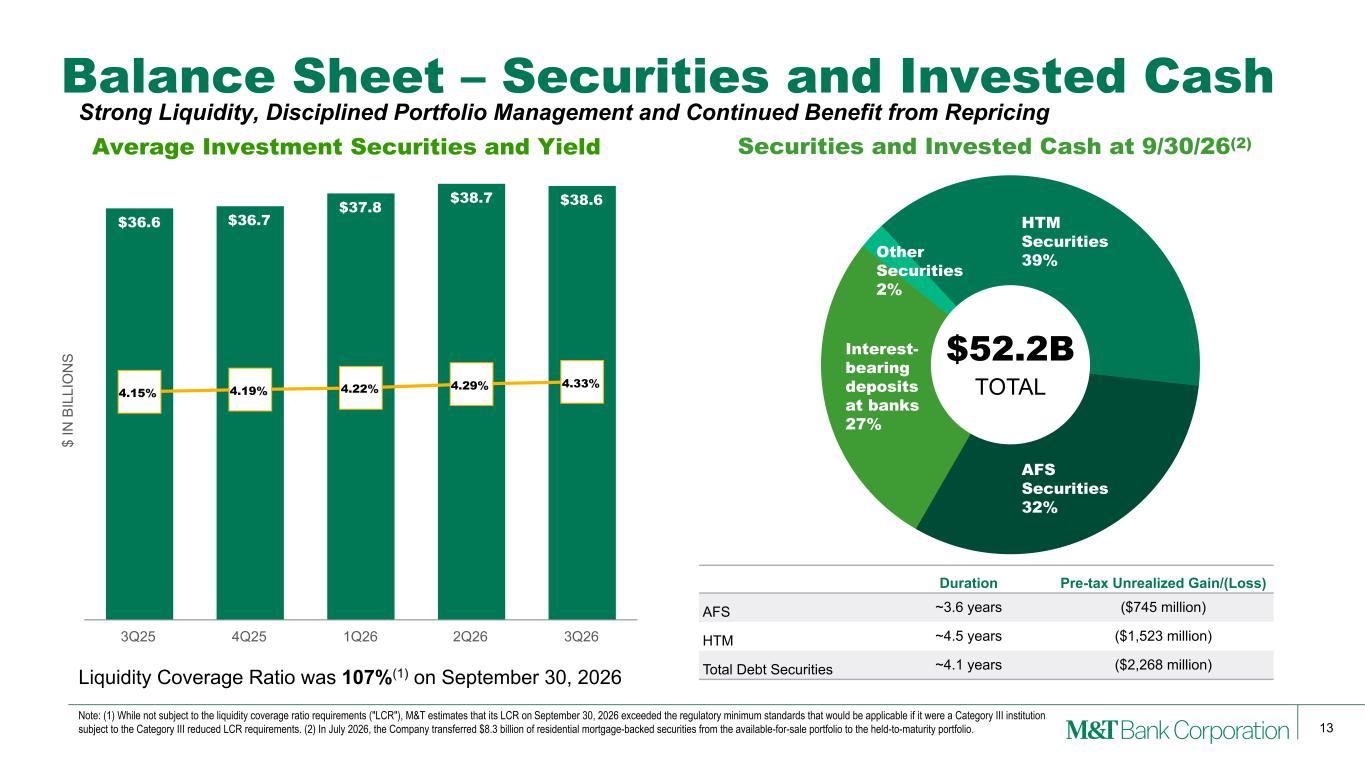
13 Balance Sheet – Securities and Invested Cash Liquidity Coverage Ratio was 107%(1) on September 30, 2026 Duration Pre-tax Unrealized Gain/(Loss) AFS ~3.6 years ($745 million) HTM ~4.5 years ($1,523 million) Total Debt Securities ~4.1 years ($2,268 million) $ IN B IL LI O N S Average Investment Securities and Yield $36.6 $36.7 $37.8 $38.7 $38.6 4.15% 4.19% 4.22% 4.29% 4.33% 3Q25 4Q25 1Q26 2Q26 3Q26 Interest- bearing deposits at banks 27% Other Securities 2% HTM Securities 39% AFS Securities 32% $52.2B TOTAL Securities and Invested Cash at 9/30/26(2) Note: (1) While not subject to the liquidity coverage ratio requirements ("LCR"), M&T estimates that its LCR on September 30, 2026 exceeded the regulatory minimum standards that would be applicable if it were a Category III institution subject to the Category III reduced LCR requirements. (2) In July 2026, the Company transferred $8.3 billion of residential mortgage-backed securities from the available-for-sale portfolio to the held-to-maturity portfolio. Strong Liquidity, Disciplined Portfolio Management and Continued Benefit from Repricing
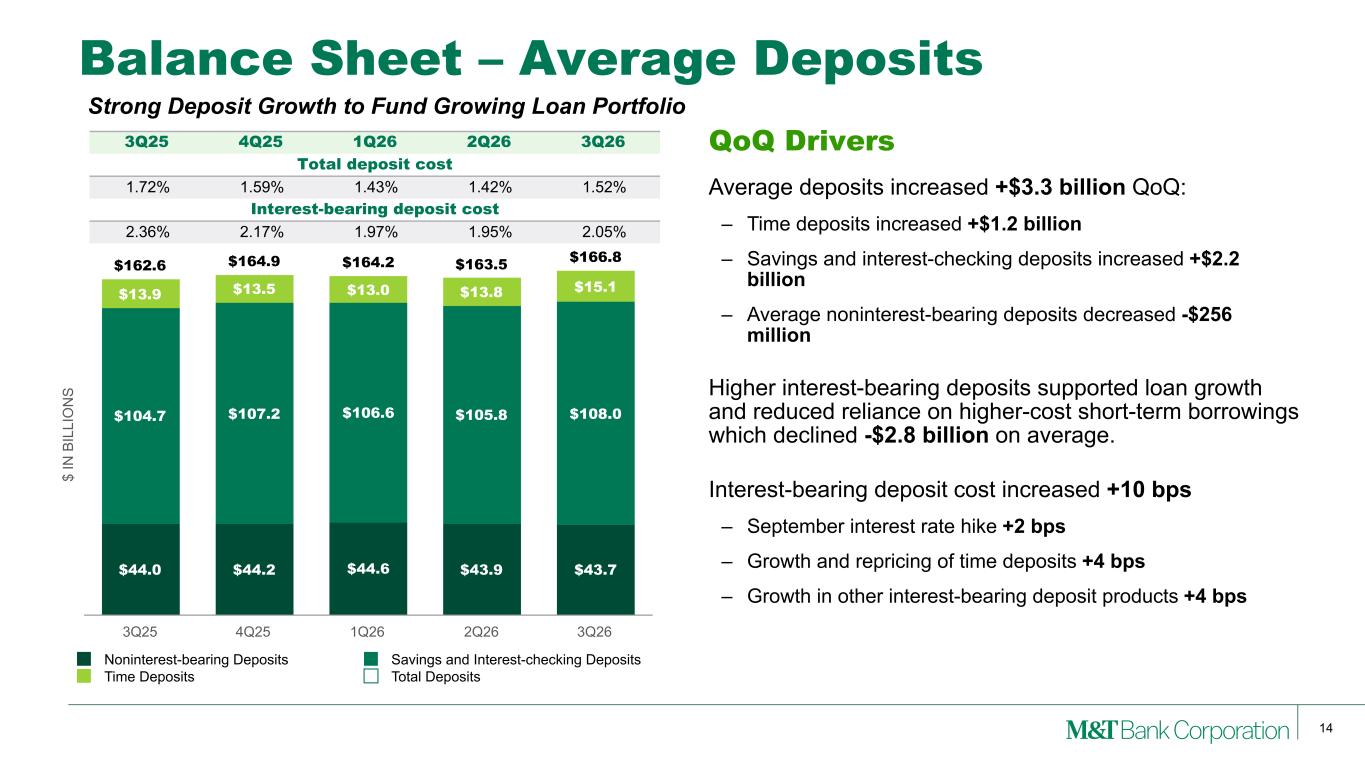
14 Balance Sheet – Average Deposits QoQ Drivers Average deposits increased +$3.3 billion QoQ: – Time deposits increased +$1.2 billion – Savings and interest-checking deposits increased +$2.2 billion – Average noninterest-bearing deposits decreased -$256 million Higher interest-bearing deposits supported loan growth and reduced reliance on higher-cost short-term borrowings which declined -$2.8 billion on average. Interest-bearing deposit cost increased +10 bps – September interest rate hike +2 bps – Growth and repricing of time deposits +4 bps – Growth in other interest-bearing deposit products +4 bps $ IN B IL LI O N S $44.0 $44.2 $44.6 $43.9 $43.7 $104.7 $107.2 $106.6 $105.8 $108.0 $13.9 $13.5 $13.0 $13.8 $15.1 $162.6 $164.9 $164.2 $163.5 $166.8 Noninterest-bearing Deposits Savings and Interest-checking Deposits Time Deposits Total Deposits 3Q25 4Q25 1Q26 2Q26 3Q26 3Q25 4Q25 1Q26 2Q26 3Q26 Total deposit cost 1.72% 1.59% 1.43% 1.42% 1.52% Interest-bearing deposit cost 2.36% 2.17% 1.97% 1.95% 2.05% Strong Deposit Growth to Fund Growing Loan Portfolio
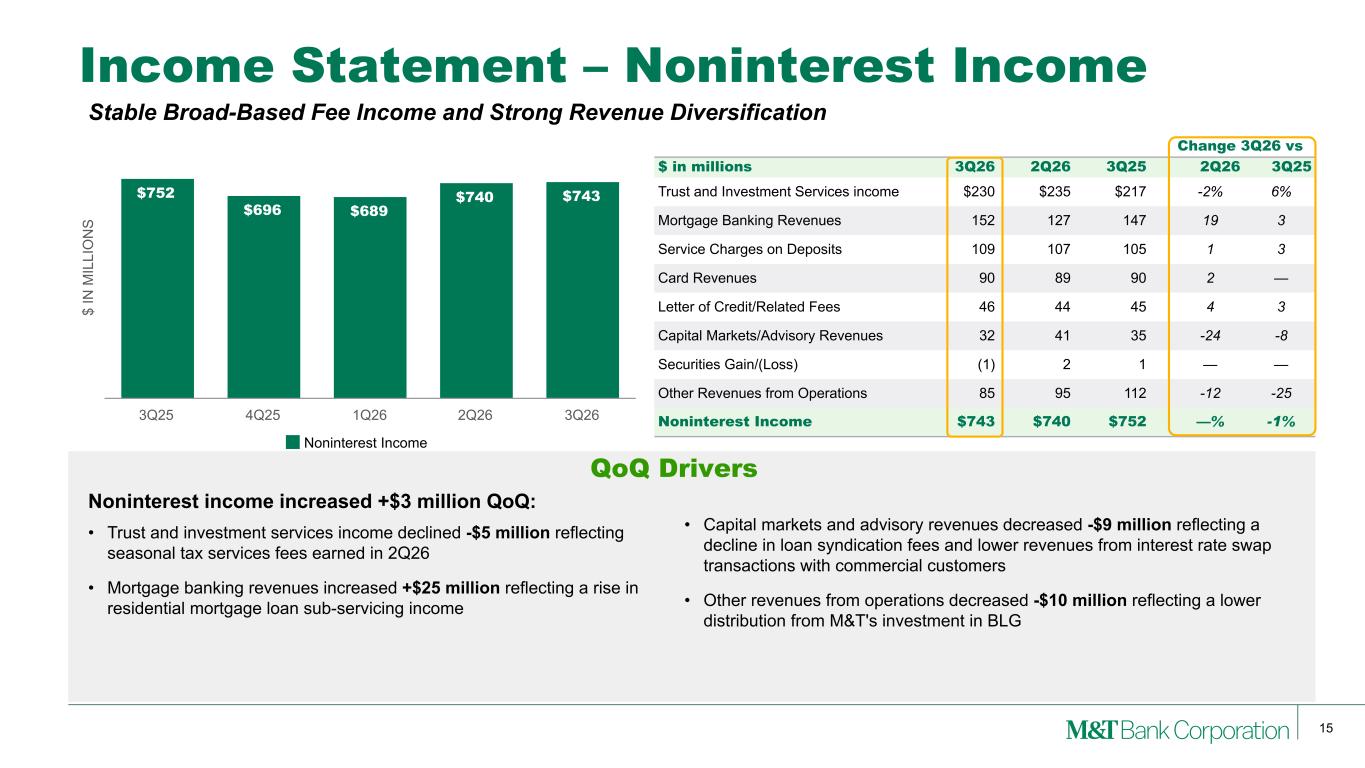
15 $ IN M IL LI O N S $752 $696 $689 $740 $743 Noninterest Income 3Q25 4Q25 1Q26 2Q26 3Q26 Change 3Q26 vs $ in millions 3Q26 2Q26 3Q25 2Q26 3Q25 Trust and Investment Services income $230 $235 $217 -2% 6% Mortgage Banking Revenues 152 127 147 19 3 Service Charges on Deposits 109 107 105 1 3 Card Revenues 90 89 90 2 — Letter of Credit/Related Fees 46 44 45 4 3 Capital Markets/Advisory Revenues 32 41 35 -24 -8 Securities Gain/(Loss) (1) 2 1 — — Other Revenues from Operations 85 95 112 -12 -25 Noninterest Income $743 $740 $752 —% -1% • Capital markets and advisory revenues decreased -$9 million reflecting a decline in loan syndication fees and lower revenues from interest rate swap transactions with commercial customers • Other revenues from operations decreased -$10 million reflecting a lower distribution from M&T's investment in BLG Income Statement – Noninterest Income Noninterest income increased +$3 million QoQ: • Trust and investment services income declined -$5 million reflecting seasonal tax services fees earned in 2Q26 • Mortgage banking revenues increased +$25 million reflecting a rise in residential mortgage loan sub-servicing income QoQ Drivers Stable Broad-Based Fee Income and Strong Revenue Diversification
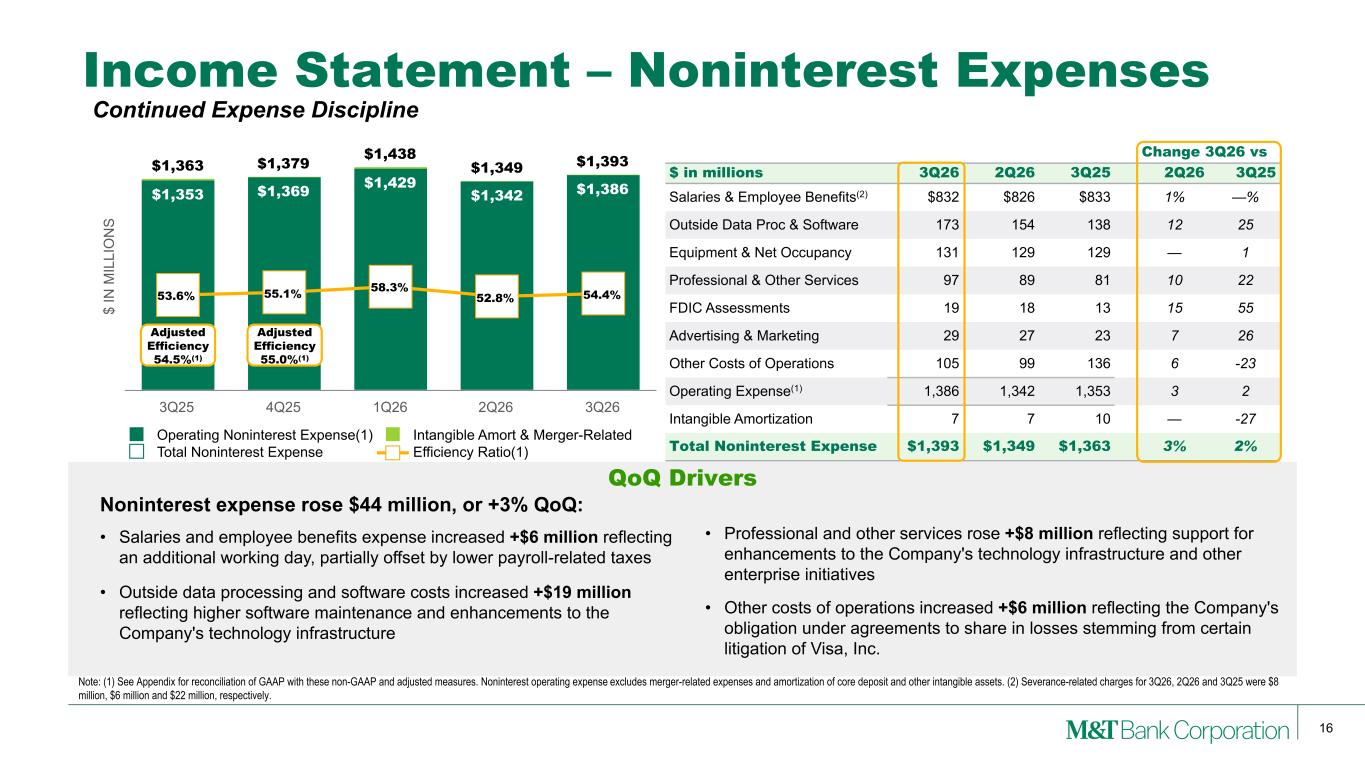
16 $ IN M IL LI O N S $1,353 $1,369 $1,429 $1,342 $1,386 $1,363 $1,379 $1,438 $1,349 $1,393 53.6% 55.1% 58.3% 52.8% 54.4% Operating Noninterest Expense(1) Intangible Amort & Merger-Related Total Noninterest Expense Efficiency Ratio(1) 3Q25 4Q25 1Q26 2Q26 3Q26 Change 3Q26 vs $ in millions 3Q26 2Q26 3Q25 2Q26 3Q25 Salaries & Employee Benefits(2) $832 $826 $833 1% —% Outside Data Proc & Software 173 154 138 12 25 Equipment & Net Occupancy 131 129 129 — 1 Professional & Other Services 97 89 81 10 22 FDIC Assessments 19 18 13 15 55 Advertising & Marketing 29 27 23 7 26 Other Costs of Operations 105 99 136 6 -23 Operating Expense(1) 1,386 1,342 1,353 3 2 Intangible Amortization 7 7 10 — -27 Total Noninterest Expense $1,393 $1,349 $1,363 3% 2% Income Statement – Noninterest Expenses Noninterest expense rose $44 million, or +3% QoQ: • Salaries and employee benefits expense increased +$6 million reflecting an additional working day, partially offset by lower payroll-related taxes • Outside data processing and software costs increased +$19 million reflecting higher software maintenance and enhancements to the Company's technology infrastructure Note: (1) See Appendix for reconciliation of GAAP with these non-GAAP and adjusted measures. Noninterest operating expense excludes merger-related expenses and amortization of core deposit and other intangible assets. (2) Severance-related charges for 3Q26, 2Q26 and 3Q25 were $8 million, $6 million and $22 million, respectively. QoQ Drivers Adjusted Efficiency 54.5%(1) Adjusted Efficiency 55.0%(1) • Professional and other services rose +$8 million reflecting support for enhancements to the Company's technology infrastructure and other enterprise initiatives • Other costs of operations increased +$6 million reflecting the Company's obligation under agreements to share in losses stemming from certain litigation of Visa, Inc. Continued Expense Discipline
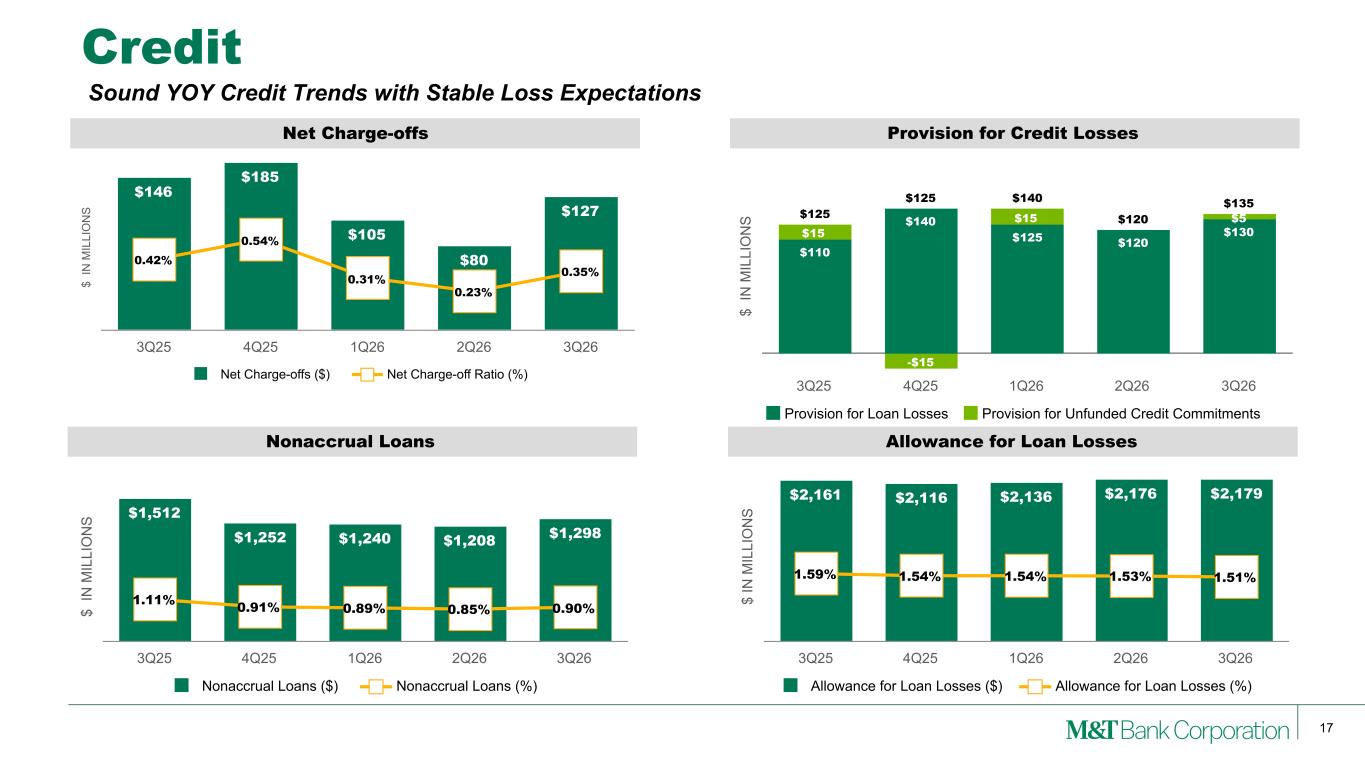
17 $ IN M IL LI O N S Nonaccrual Loans $1,512 $1,252 $1,240 $1,208 $1,298 1.11% 0.91% 0.89% 0.85% 0.90% Nonaccrual Loans ($) Nonaccrual Loans (%) 3Q25 4Q25 1Q26 2Q26 3Q26 $ IN M IL LI O N S Net Charge-offs $146 $185 $105 $80 $127 0.42% 0.54% 0.31% 0.23% 0.35% Net Charge-offs ($) Net Charge-off Ratio (%) 3Q25 4Q25 1Q26 2Q26 3Q26 Credit $ IN M IL LI O N S Allowance for Loan Losses $2,161 $2,116 $2,136 $2,176 $2,179 1.59% 1.54% 1.54% 1.53% 1.51% Allowance for Loan Losses ($) Allowance for Loan Losses (%) 3Q25 4Q25 1Q26 2Q26 3Q26 $ IN M IL LI O N S Provision for Credit Losses $125 $125 $140 $120 $135 $110 $140 $125 $120 $130$15 -$15 $15 $5 Provision for Loan Losses Provision for Unfunded Credit Commitments 3Q25 4Q25 1Q26 2Q26 3Q26 Sound YOY Credit Trends with Stable Loss Expectations
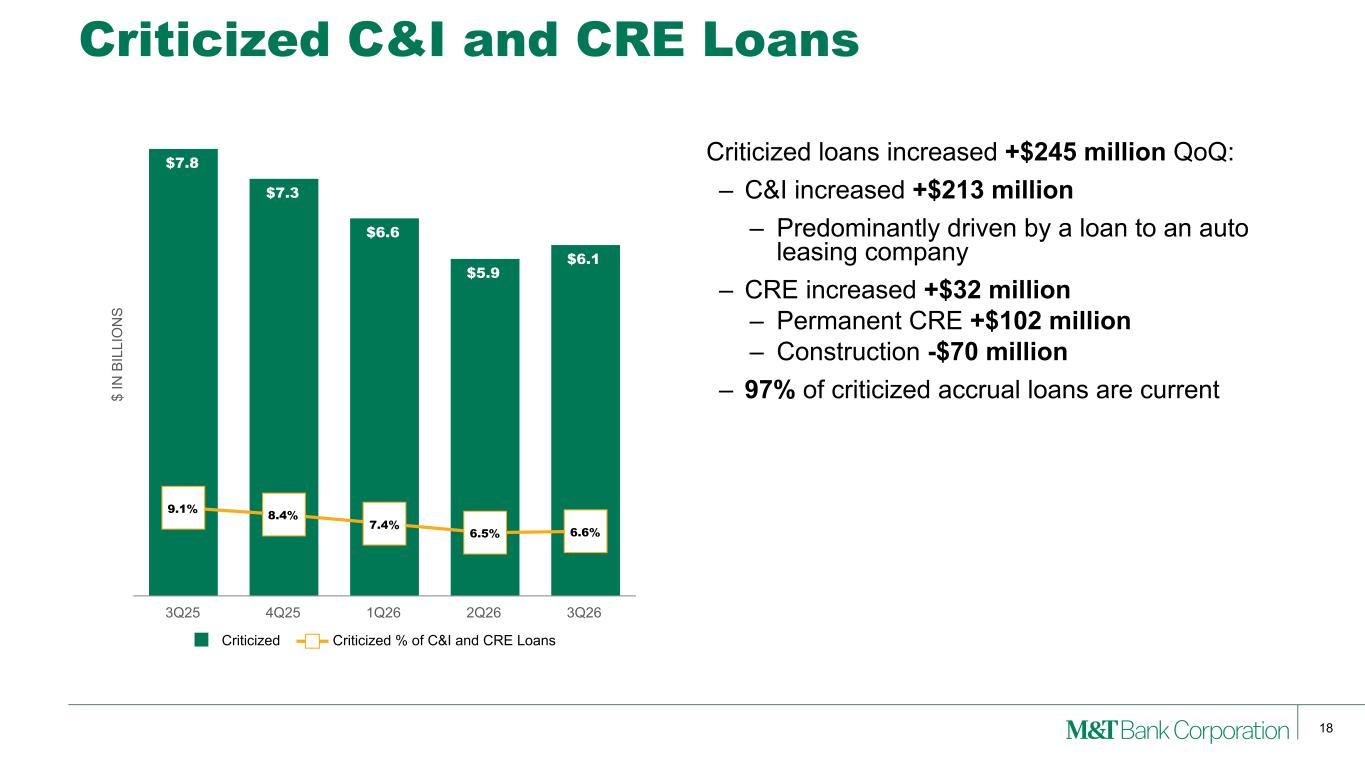
18 Criticized C&I and CRE Loans Criticized loans increased +$245 million QoQ: – C&I increased +$213 million – Predominantly driven by a loan to an auto leasing company – CRE increased +$32 million – Permanent CRE +$102 million – Construction -$70 million – 97% of criticized accrual loans are current$ IN B IL LI O N S $7.8 $7.3 $6.6 $5.9 $6.1 9.1% 8.4% 7.4% 6.5% 6.6% Criticized Criticized % of C&I and CRE Loans 3Q25 4Q25 1Q26 2Q26 3Q26
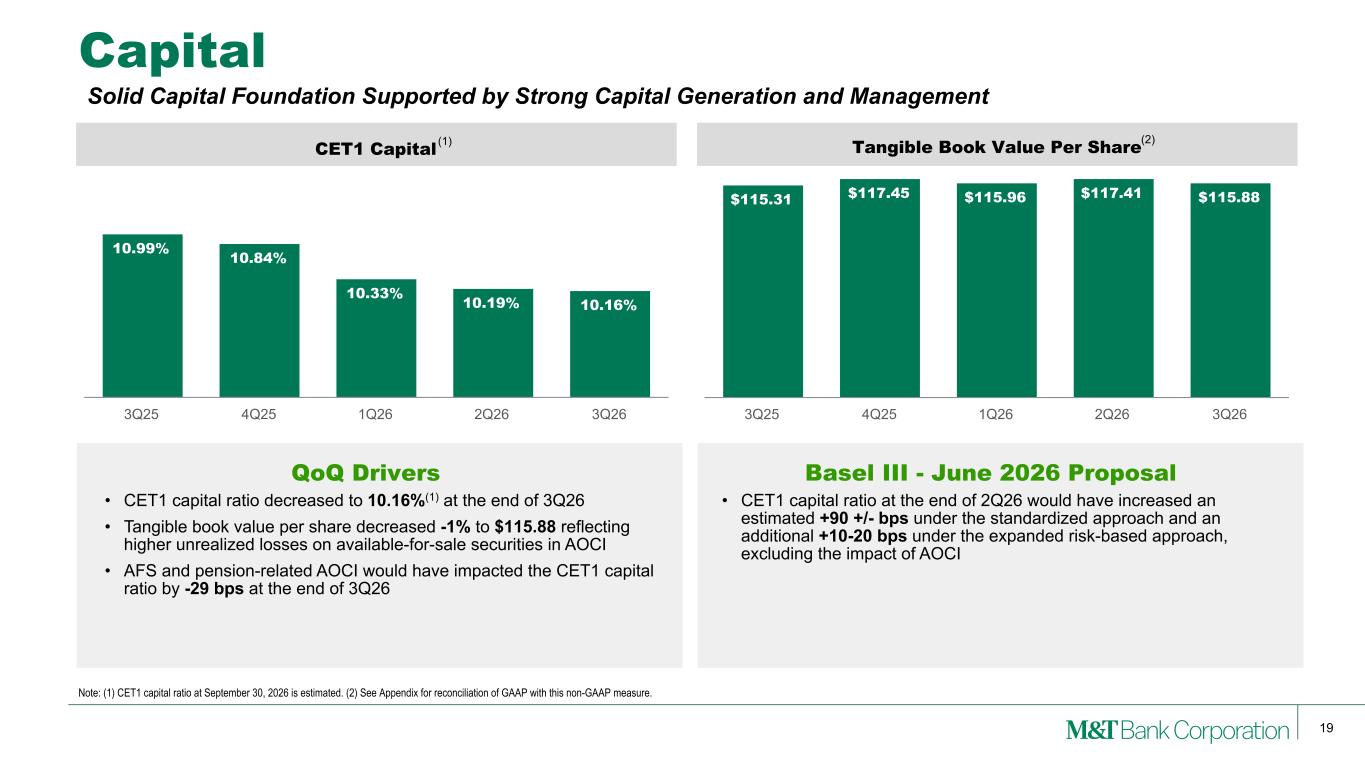
19 CET1 Capital 10.99% 10.84% 10.33% 10.19% 10.16% 3Q25 4Q25 1Q26 2Q26 3Q26 Tangible Book Value Per Share $115.31 $117.45 $115.96 $117.41 $115.88 3Q25 4Q25 1Q26 2Q26 3Q26 Capital • CET1 capital ratio decreased to 10.16%(1) at the end of 3Q26 • Tangible book value per share decreased -1% to $115.88 reflecting higher unrealized losses on available-for-sale securities in AOCI • AFS and pension-related AOCI would have impacted the CET1 capital ratio by -29 bps at the end of 3Q26 Note: (1) CET1 capital ratio at September 30, 2026 is estimated. (2) See Appendix for reconciliation of GAAP with this non-GAAP measure. QoQ Drivers (1) (2) Basel III - June 2026 Proposal • CET1 capital ratio at the end of 2Q26 would have increased an estimated +90 +/- bps under the standardized approach and an additional +10-20 bps under the expanded risk-based approach, excluding the impact of AOCI Solid Capital Foundation Supported by Strong Capital Generation and Management
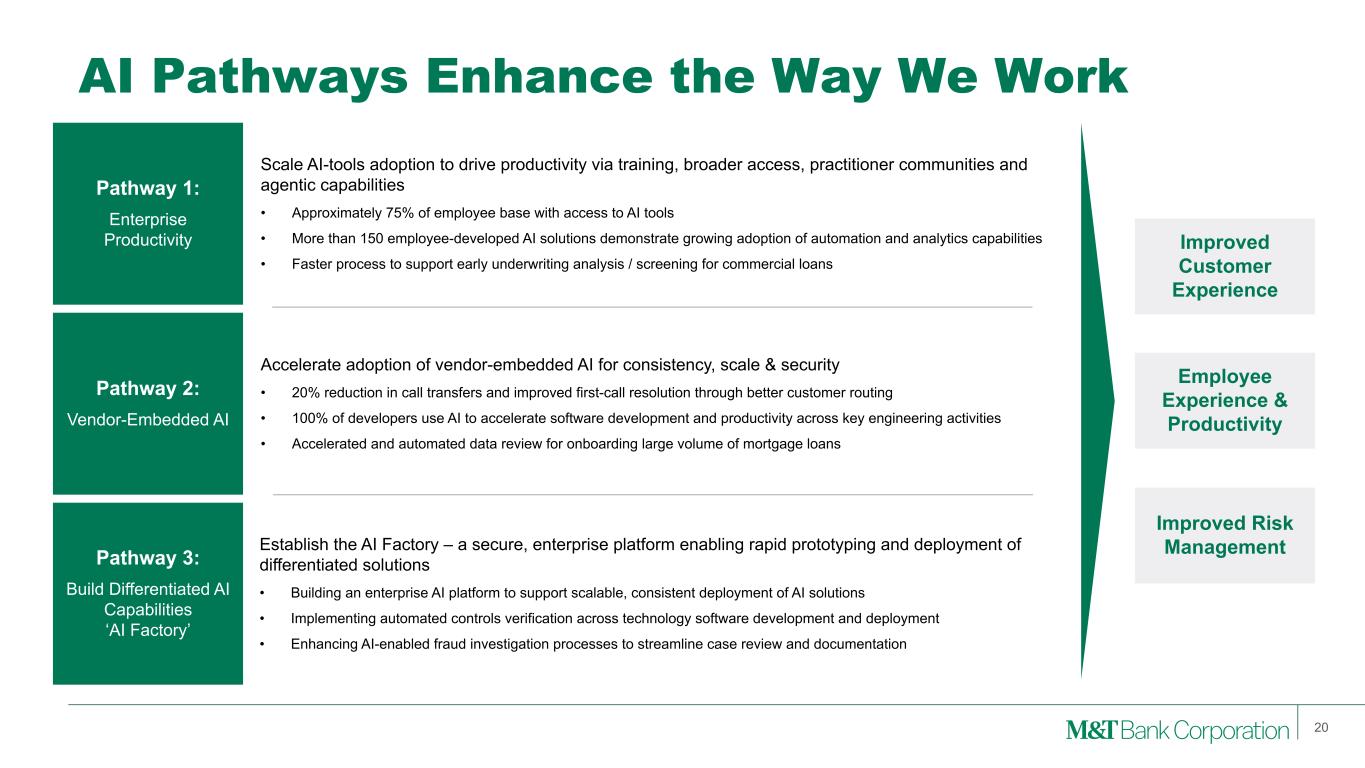
AI Pathways Enhance the Way We Work 20 Pathway 1: Enterprise Productivity Pathway 2: Vendor-Embedded AI Pathway 3: Build Differentiated AI Capabilities ‘AI Factory’ Scale AI-tools adoption to drive productivity via training, broader access, practitioner communities and agentic capabilities • Approximately 75% of employee base with access to AI tools • More than 150 employee-developed AI solutions demonstrate growing adoption of automation and analytics capabilities • Faster process to support early underwriting analysis / screening for commercial loans Accelerate adoption of vendor-embedded AI for consistency, scale & security • 20% reduction in call transfers and improved first-call resolution through better customer routing • 100% of developers use AI to accelerate software development and productivity across key engineering activities • Accelerated and automated data review for onboarding large volume of mortgage loans Establish the AI Factory – a secure, enterprise platform enabling rapid prototyping and deployment of differentiated solutions • Building an enterprise AI platform to support scalable, consistent deployment of AI solutions • Implementing automated controls verification across technology software development and deployment • Enhancing AI-enabled fraud investigation processes to streamline case review and documentation Improved Customer Experience Employee Experience & Productivity Improved Risk Management
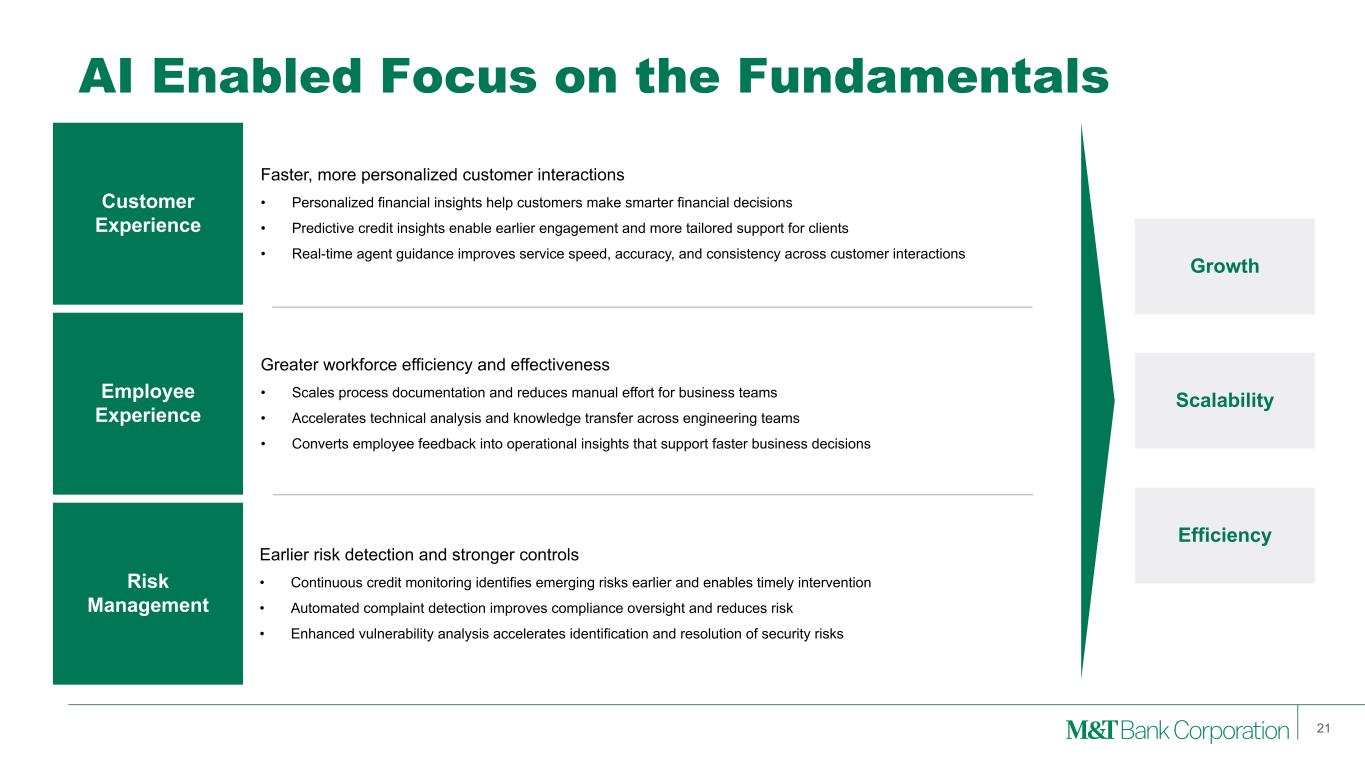
AI Enabled Focus on the Fundamentals 21 21 Customer Experience Employee Experience Risk Management Faster, more personalized customer interactions • Personalized financial insights help customers make smarter financial decisions • Predictive credit insights enable earlier engagement and more tailored support for clients • Real-time agent guidance improves service speed, accuracy, and consistency across customer interactions Greater workforce efficiency and effectiveness • Scales process documentation and reduces manual effort for business teams • Accelerates technical analysis and knowledge transfer across engineering teams • Converts employee feedback into operational insights that support faster business decisions Earlier risk detection and stronger controls • Continuous credit monitoring identifies emerging risks earlier and enables timely intervention • Automated complaint detection improves compliance oversight and reduces risk • Enhanced vulnerability analysis accelerates identification and resolution of security risks Growth Scalability Efficiency
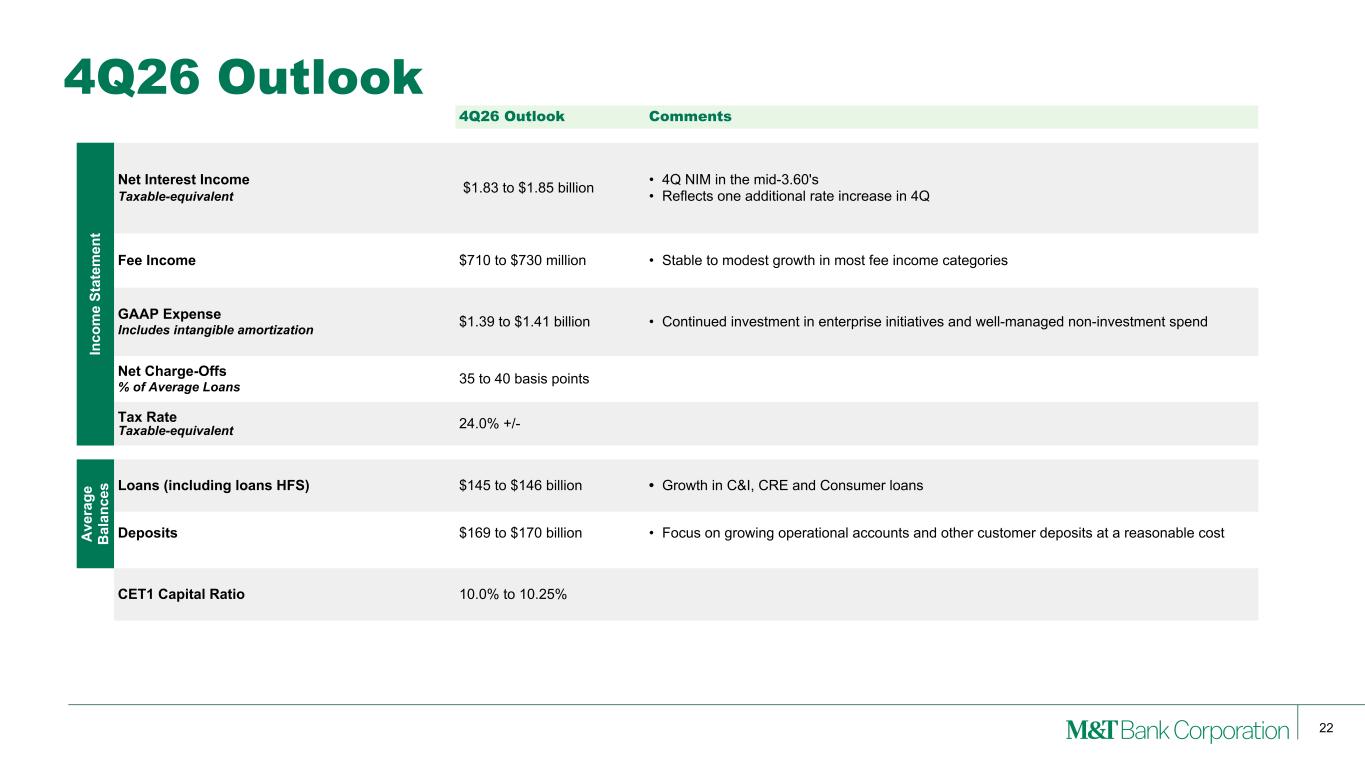
22 4Q26 Outlook 4Q26 Outlook Comments In co m e St at em en t Net Interest Income Taxable-equivalent $1.83 to $1.85 billion • 4Q NIM in the mid-3.60's • Reflects one additional rate increase in 4Q Fee Income $710 to $730 million • Stable to modest growth in most fee income categories GAAP Expense Includes intangible amortization $1.39 to $1.41 billion • Continued investment in enterprise initiatives and well-managed non-investment spend Net Charge-Offs % of Average Loans 35 to 40 basis points Tax Rate Taxable-equivalent 24.0% +/- A ve ra ge B al an ce s Loans (including loans HFS) $145 to $146 billion • Growth in C&I, CRE and Consumer loans Deposits $169 to $170 billion • Focus on growing operational accounts and other customer deposits at a reasonable cost CET1 Capital Ratio 10.0% to 10.25%
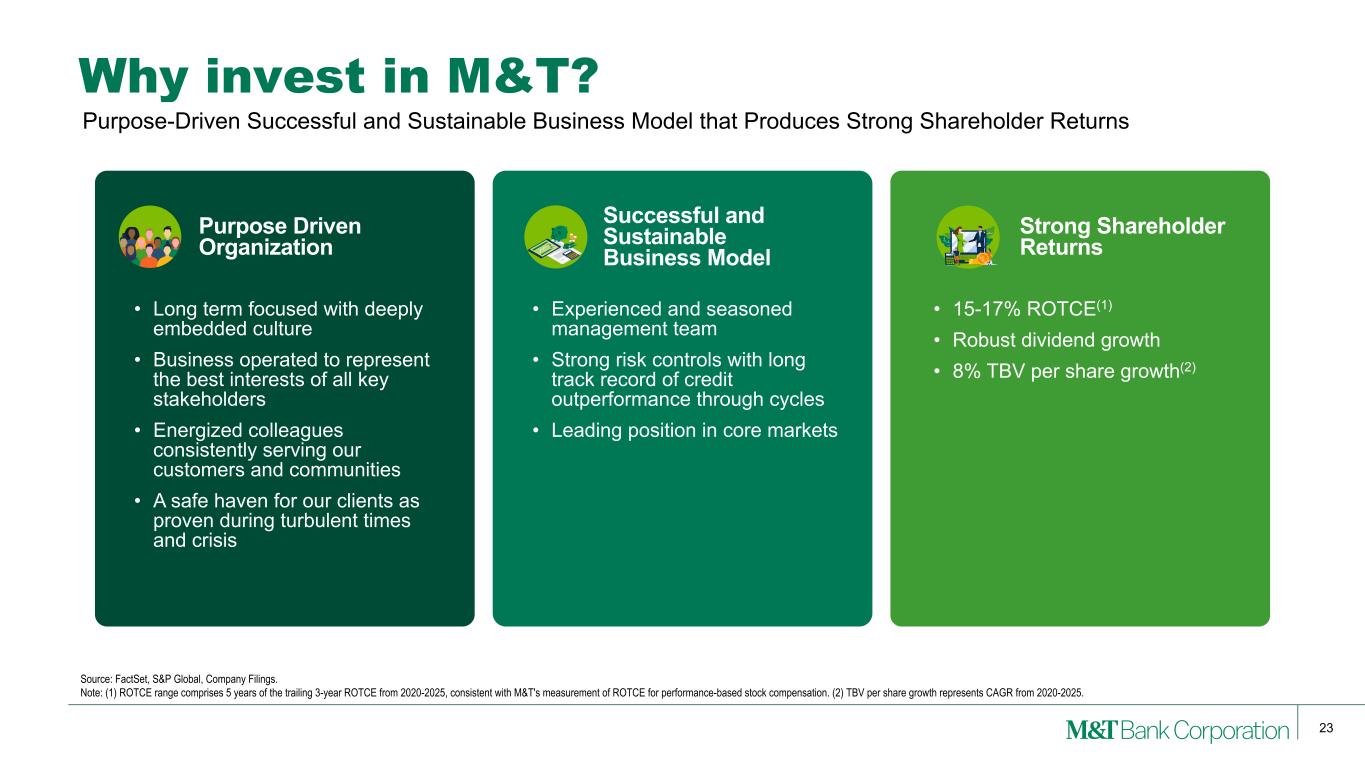
23 Why invest in M&T? • Long term focused with deeply embedded culture • Business operated to represent the best interests of all key stakeholders • Energized colleagues consistently serving our customers and communities • A safe haven for our clients as proven during turbulent times and crisis • Experienced and seasoned management team • Strong risk controls with long track record of credit outperformance through cycles • Leading position in core markets • 15-17% ROTCE(1) • Robust dividend growth • 8% TBV per share growth(2) Source: FactSet, S&P Global, Company Filings. Note: (1) ROTCE range comprises 5 years of the trailing 3-year ROTCE from 2020-2025, consistent with M&T's measurement of ROTCE for performance-based stock compensation. (2) TBV per share growth represents CAGR from 2020-2025. Purpose-Driven Successful and Sustainable Business Model that Produces Strong Shareholder Returns Purpose Driven Organization Successful and Sustainable Business Model Strong Shareholder Returns
24 Appendix
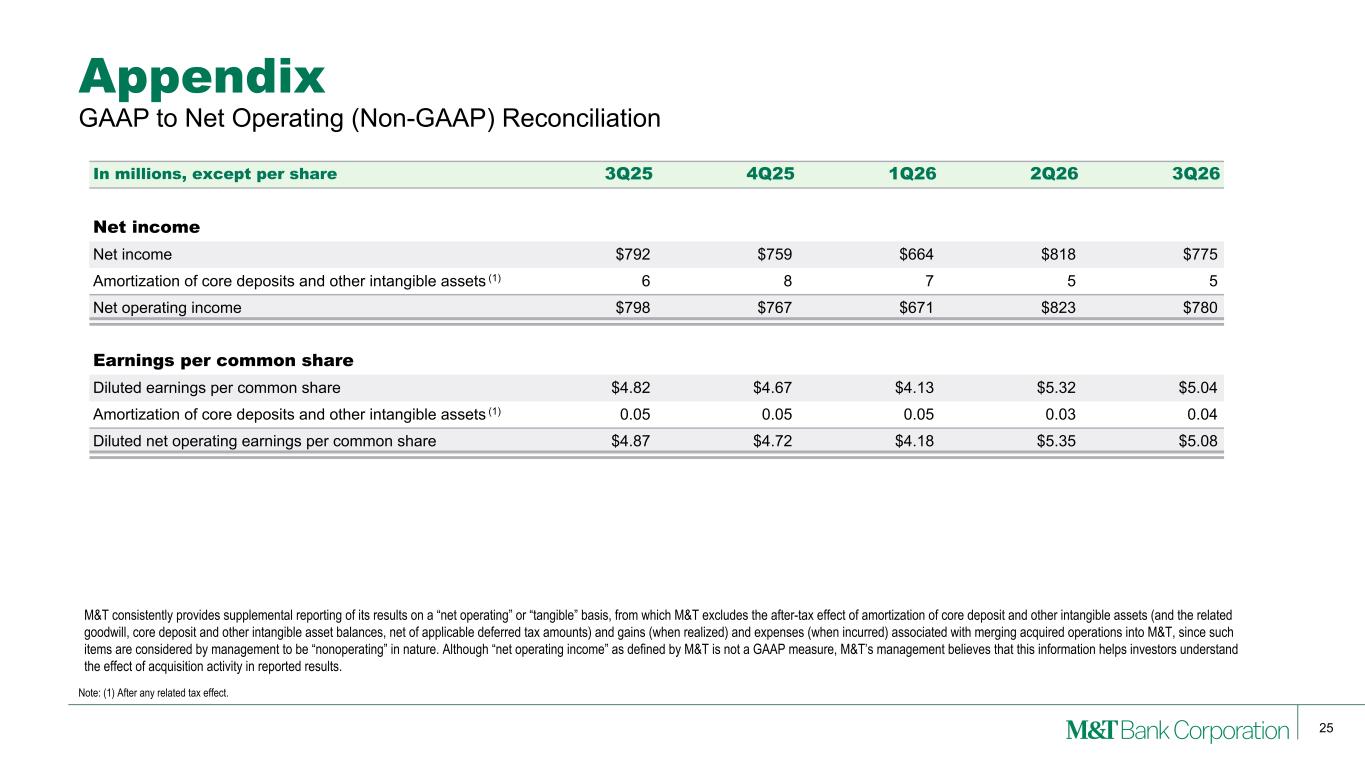
25 M&T consistently provides supplemental reporting of its results on a “net operating” or “tangible” basis, from which M&T excludes the after-tax effect of amortization of core deposit and other intangible assets (and the related goodwill, core deposit and other intangible asset balances, net of applicable deferred tax amounts) and gains (when realized) and expenses (when incurred) associated with merging acquired operations into M&T, since such items are considered by management to be “nonoperating” in nature. Although “net operating income” as defined by M&T is not a GAAP measure, M&T’s management believes that this information helps investors understand the effect of acquisition activity in reported results. Appendix Note: (1) After any related tax effect. GAAP to Net Operating (Non-GAAP) Reconciliation In millions, except per share 3Q25 4Q25 1Q26 2Q26 3Q26 Net income Net income $792 $759 $664 $818 $775 Amortization of core deposits and other intangible assets (1) 6 8 7 5 5 Net operating income $798 $767 $671 $823 $780 Earnings per common share Diluted earnings per common share $4.82 $4.67 $4.13 $5.32 $5.04 Amortization of core deposits and other intangible assets (1) 0.05 0.05 0.05 0.03 0.04 Diluted net operating earnings per common share $4.87 $4.72 $4.18 $5.35 $5.08
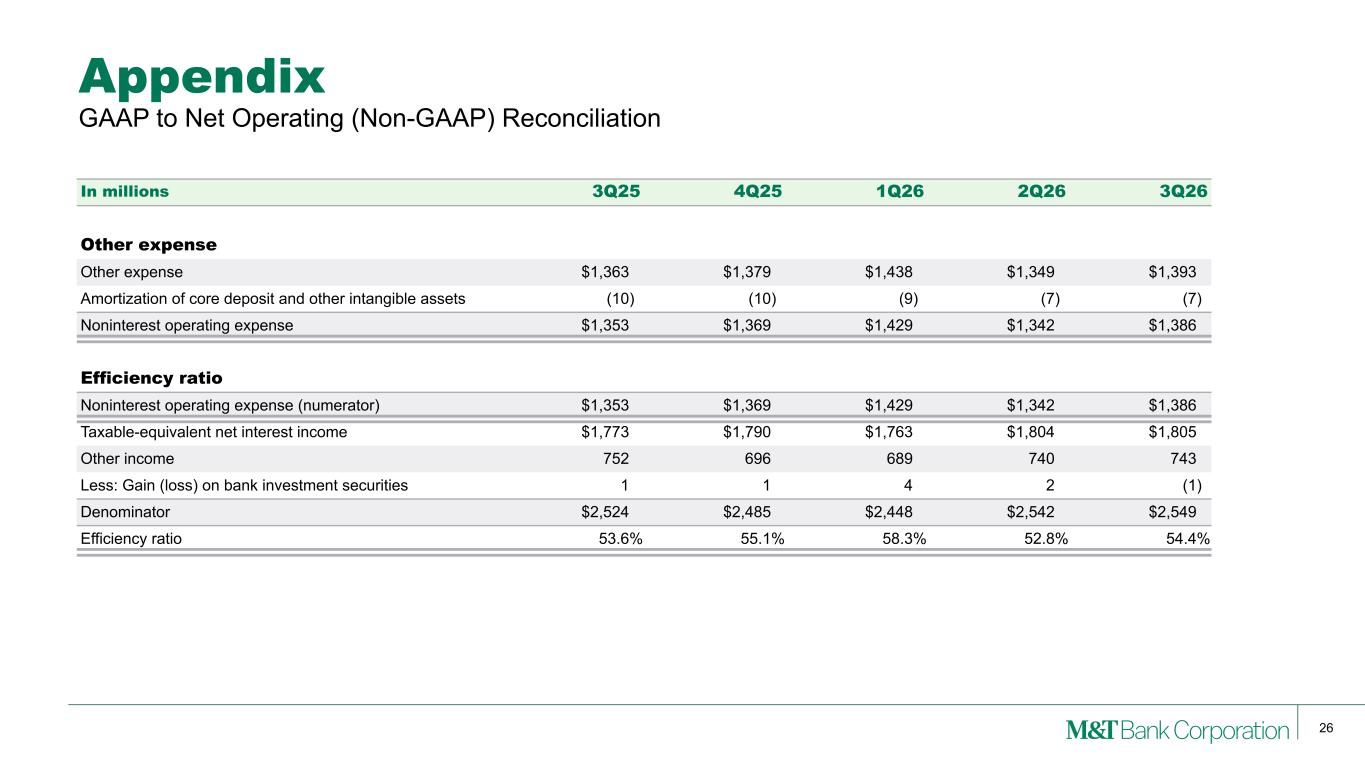
26 Appendix GAAP to Net Operating (Non-GAAP) Reconciliation In millions 3Q25 4Q25 1Q26 2Q26 3Q26 Other expense Other expense $1,363 $1,379 $1,438 $1,349 $1,393 Amortization of core deposit and other intangible assets (10) (10) (9) (7) (7) Noninterest operating expense $1,353 $1,369 $1,429 $1,342 $1,386 Efficiency ratio Noninterest operating expense (numerator) $1,353 $1,369 $1,429 $1,342 $1,386 Taxable-equivalent net interest income $1,773 $1,790 $1,763 $1,804 $1,805 Other income 752 696 689 740 743 Less: Gain (loss) on bank investment securities 1 1 4 2 (1) Denominator $2,524 $2,485 $2,448 $2,542 $2,549 Efficiency ratio 53.6 % 55.1 % 58.3 % 52.8 % 54.4 %
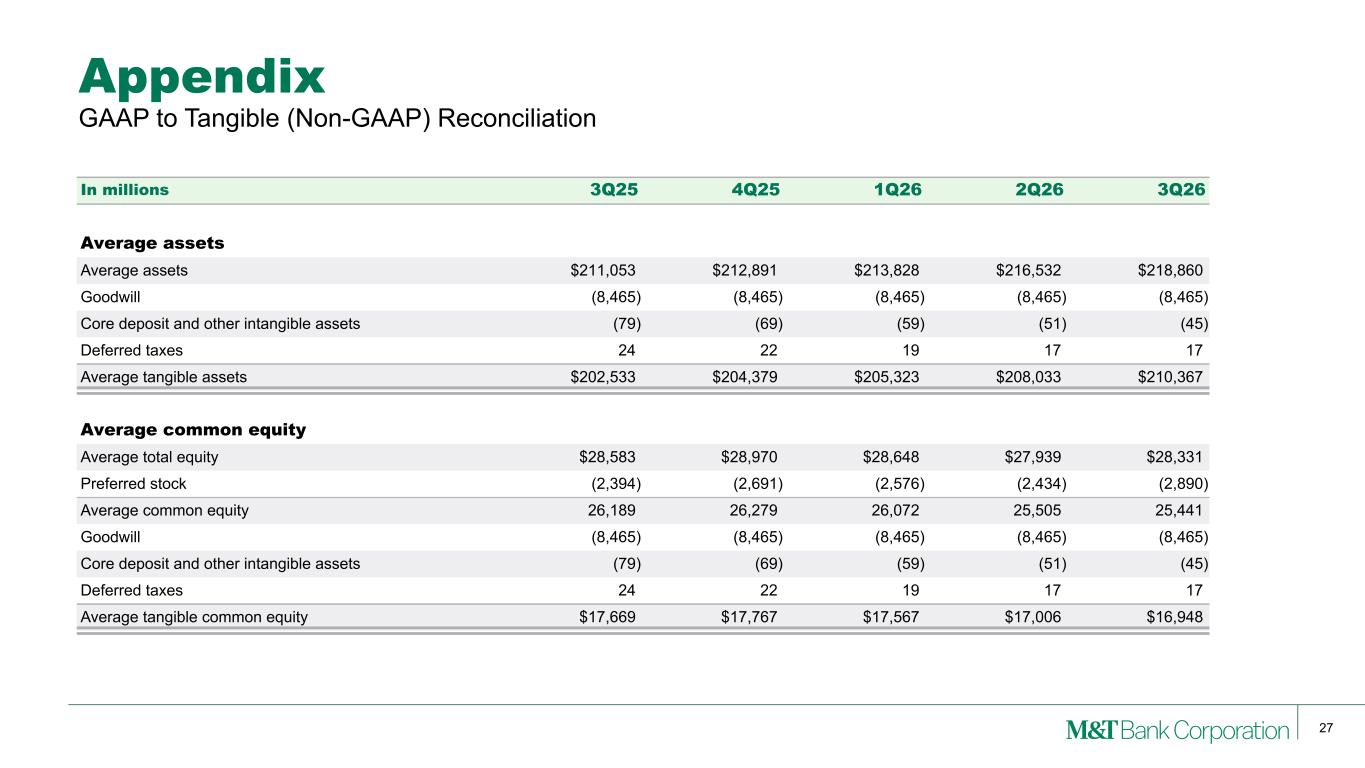
27 Appendix In millions 3Q25 4Q25 1Q26 2Q26 3Q26 Average assets Average assets $211,053 $212,891 $213,828 $216,532 $218,860 Goodwill (8,465) (8,465) (8,465) (8,465) (8,465) Core deposit and other intangible assets (79) (69) (59) (51) (45) Deferred taxes 24 22 19 17 17 Average tangible assets $202,533 $204,379 $205,323 $208,033 $210,367 Average common equity Average total equity $28,583 $28,970 $28,648 $27,939 $28,331 Preferred stock (2,394) (2,691) (2,576) (2,434) (2,890) Average common equity 26,189 26,279 26,072 25,505 25,441 Goodwill (8,465) (8,465) (8,465) (8,465) (8,465) Core deposit and other intangible assets (79) (69) (59) (51) (45) Deferred taxes 24 22 19 17 17 Average tangible common equity $17,669 $17,767 $17,567 $17,006 $16,948 GAAP to Tangible (Non-GAAP) Reconciliation
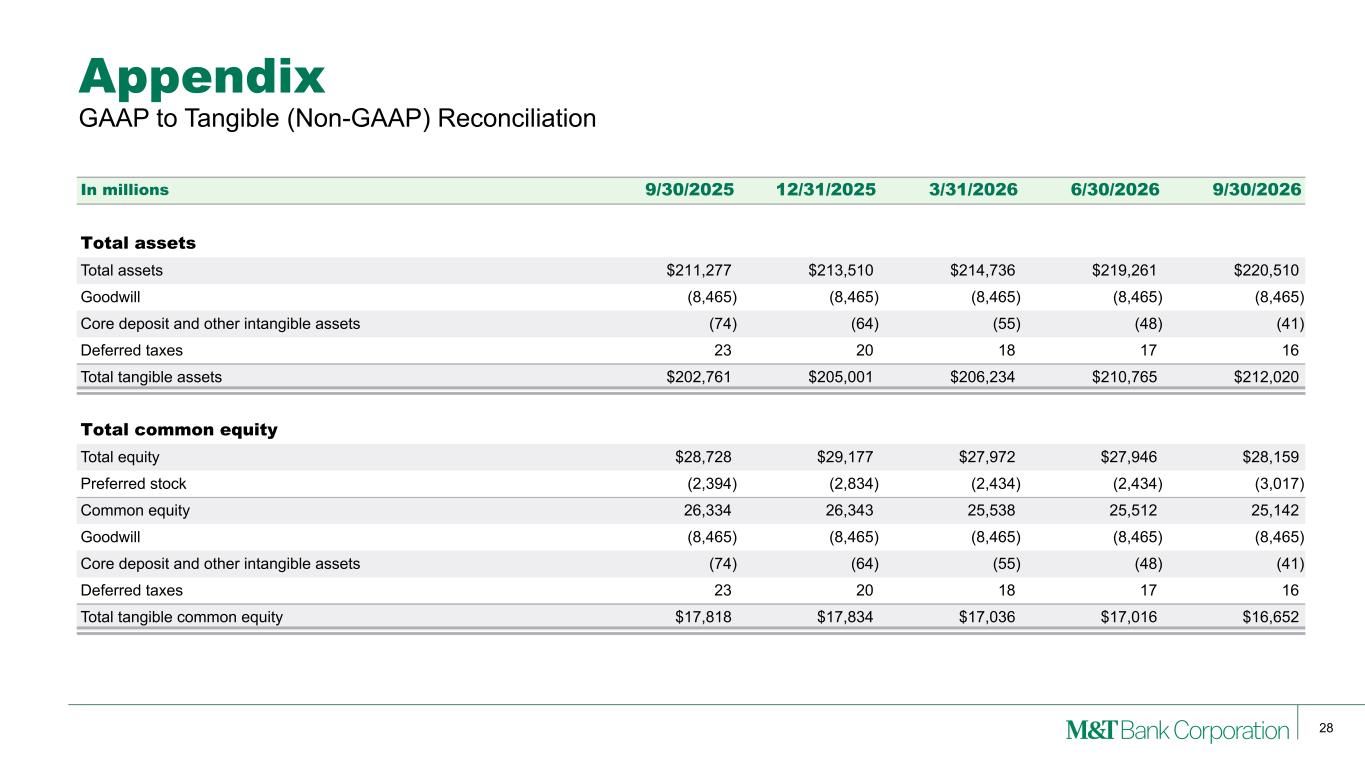
28 Appendix In millions 9/30/2025 12/31/2025 3/31/2026 6/30/2026 9/30/2026 Total assets Total assets $211,277 $213,510 $214,736 $219,261 $220,510 Goodwill (8,465) (8,465) (8,465) (8,465) (8,465) Core deposit and other intangible assets (74) (64) (55) (48) (41) Deferred taxes 23 20 18 17 16 Total tangible assets $202,761 $205,001 $206,234 $210,765 $212,020 Total common equity Total equity $28,728 $29,177 $27,972 $27,946 $28,159 Preferred stock (2,394) (2,834) (2,434) (2,434) (3,017) Common equity 26,334 26,343 25,538 25,512 25,142 Goodwill (8,465) (8,465) (8,465) (8,465) (8,465) Core deposit and other intangible assets (74) (64) (55) (48) (41) Deferred taxes 23 20 18 17 16 Total tangible common equity $17,818 $17,834 $17,036 $17,016 $16,652 GAAP to Tangible (Non-GAAP) Reconciliation
29 Appendix Reconciliation of Adjusted Metrics In millions 3Q25 4Q25 1Q26 2Q26 3Q26 Other income - Adjusted Other income $752 $696 Earnout payment related to 2023 sale of CIT business (28) — Other income - Adjusted $724 $696 Noninterest operating expense - Adjusted Noninterest operating expense $1,353 $1,369 Charitable contribution — (30) FDIC Special Assessment 8 29 Noninterest operating expense - Adjusted $1,361 $1,368 Efficiency ratio - Adjusted Noninterest operating expense (numerator) - Adjusted $1,361 $1,368 Taxable-equivalent net interest income - Adjusted 1,773 1,790 Other income - Adjusted 724 696 Less: Gain (loss) on bank investment securities — 1 Denominator $2,497 $2,485 Efficiency ratio - Adjusted 54.5% 55.0%