Filed Pursuant to Rule 433
Registration Statement No. 333-295759
Registration Statement No. 333-295759
Jefferies Financial Group Inc.
Market Linked Securities
|
Market Linked Securities—Callable with
Contingent Coupon and Contingent Downside
Principal at Risk Securities Linked to
the Lowest Performing of the S&P 500® Index, the Russell 2000® Index
and the EURO STOXX 50®
Index due March 27, 2031
Term Sheet to Preliminary Pricing Supplement dated September 18, 2026
|
Summary of Terms
|
Issuer:
|
Jefferies Financial Group Inc.
|
|||
|
Market Measures:
|
S&P 500® Index, Russell 2000® Index and EURO STOXX 50® Index (each an “Index” and collectively the “Indices”)
|
|||
|
Pricing Date*:
|
September 23, 2026
|
|||
|
Issue Date*:
|
September 28, 2026
|
|||
|
Face Amount and
Original Offering Price:
|
$1,000 per security
|
|||
|
Contingent Coupon
Payments:
|
On each contingent coupon payment date, you will receive a contingent coupon payment at a per annum rate equal to the contingent coupon rate if, and only if, the closing
level of the lowest performing Index on the related calculation day is greater than or equal to itscoupon threshold level. Each “contingent coupon payment,” if any, will be calculated per security as follows: ($1,000 × contingent coupon
rate)/4.
|
|||
|
Contingent Coupon
Payment Dates:
|
Quarterly, on the third business day following each calculation day; provided that the contingent coupon payment date with respect to the final calculation day will be the
stated maturity date.
|
|||
|
Contingent Coupon
Rate”
|
At least 10.00% per annum, to be determined on the pricing date.
|
|||
|
Optional Redemption:
|
We may, at our option, redeem the securities, in whole but not in part, on any optional redemption date. If we elect to redeem the
securities prior to the maturity date, you will be entitled to receive on the applicable optional redemption date a cash payment per Security in U.S. dollars equal to the principal amount plus any contingent coupon payment otherwise
due. If we elect to redeem the securities, we will give you notice at least 5 business days before the optional redemption date.
If the securities are redeemed, they will cease to be outstanding on the applicable optional redemption date and you will have no further rights under the securities after
that date.
|
|||
|
Calculation Days*:
|
Quarterly, on the 23rd day of each March, June, September and December, commencing December 2026 and ending December 2030, and on March 24, 2031 (the “final calculation
day”)
|
|||
|
Optional Redemption
Dates:
|
Quarterly, beginning approximately nine months after the issue date, on the contingent coupon payment dates following each calculation day scheduled to occur from June 2027
to December 2030, inclusive.
|
|||
|
Performance Factor:
|
With respect to an Index on any calculation day, its closing level on such calculation day divided by its starting level (expressed as a percentage).
|
|||
|
Maturity Payment
Amount (per security):
|
• if the ending
level of the lowest performing Index on the final calculation day is greater than or equal to its downside threshold level:
$1,000; or
• if the ending
level of the lowest performing Index on the final calculation day is less than its downside threshold level:
$1,000 × performance factor of the lowest performing Index
|
|||
|
Lowest Performing
Index:
|
For any calculation day, the lowest performing Index will be the Index with the lowest performance factor on that calculation day.
|
|||
|
Stated Maturity Date*:
|
March 27, 2031
|
|||
|
Starting Level:
|
For each Index, its closing level on the pricing date
|
|||
|
Ending Level:
|
For each Index, its closing level on the final calculation day
|
|||
|
Coupon Threshold
Level:
|
For each Index, 70% of its starting level
|
*subject to change
** In addition, selected dealers may receive a fee of up to 0.20% for marketing and other services
Summary of Terms (continued)
|
Downside
Threshold Level:
|
For each Index, 60% of its starting level
|
|||
|
Calculation
Agent:
|
Jefferies Financial Services Inc. (“JFSI”), a wholly owned subsidiary of Jefferies Financial Group Inc.
|
|||
|
Denominations:
|
$1,000 and any integral multiple of $1,000
|
|||
|
Agents
Discount**:
|
Up to 1.825%; dealers, including those using the trade name Wells Fargo Advisors (“WFA”), may receive a selling concession of up to 1.25% and WFS may pay 0.075% of
the agent’s discount to WFA as a distribution expense fee
|
|||
|
CUSIP:
|
47234KEG5
|
|||
|
Material Tax
Consequences:
|
See the preliminary pricing supplement.
|
Hypothetical Payout Profile (Maturity Payment Amount)
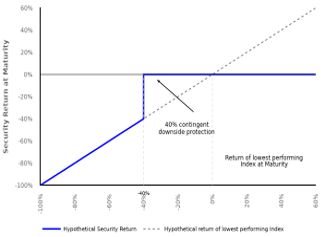
If the securities are not automatically called prior to stated maturity and the ending level of the lowest performing Index on the final calculation day is less than its
downside threshold level, you will lose more than 40%, and possibly all, of the face amount of your securities at stated maturity.
Any return on the securities will be limited to the sum of your contingent coupon payments, if any. You will not participate in any appreciation of any Index, but you will
have full downside exposure to the lowest performing Index on the final calculation day if the ending level of that Index is less than the downside threshold level.
We estimate that the value of each security on the pricing date will be approximately $974.10, or within $30.00 of that estimate. See “Estimated Value of the
Securities” in the accompanying preliminary pricing supplement for more information.
Preliminary Pricing Supplement: https://www.sec.gov/Archives/edgar/data/96223/000114036126037098/ef20082438_424b2.htm
|
The securities have complex features and investing in the securities involves risks not associated with an investment in conventional debt securities. See “Selected Risk
Considerations” in this term sheet and the accompanying preliminary pricing supplement and “Risk Factors” in the accompanying product supplement.
This introductory term sheet does not provide all of the information that an investor should consider prior to making an investment decision.
Investors should carefully review the accompanying preliminary pricing supplement, product supplement, prospectus supplement and prospectus
before making a decision to invest in the securities.
NOT A BANK DEPOSIT AND NOT INSURED OR GUARANTEED BY THE FDIC OR ANY OTHER GOVERNMENTAL AGENCY
|
Selected Risk Considerations
The risks set forth below are discussed in detail in the “Selected Risk Considerations” section in the accompanying preliminary pricing supplement and the “Risk Factors” section in the accompanying
product supplement. Please review those risk disclosures carefully.
|
•
|
If The Securities Are Not Redeemed Prior To Stated Maturity, You May Lose Some Or All Of The Face Amount Of Your Securities At Stated Maturity.
|
|
•
|
The Securities Do Not Provide For Fixed Payments Of Interest And You May Receive No Coupon Payments On One Or More Contingent Coupon Payment Dates, Or Even Throughout The Entire Term Of The
Securities.
|
|
•
|
The Securities Are Subject To The Full Risks Of Each Index And Will Be Negatively Affected If Any Index Performs Poorly, Even If The Other Indices Perform Favorably.
|
|
•
|
Your Return On The Securities Will Depend Solely On The Performance Of The Index That Is The Lowest Performing Index On Each Calculation Day, And You Will Not Benefit In Any Way From The
Performance Of The Better Performing Indices.
|
|
•
|
You Will Be Subject To Risks Resulting From The Relationship Among The Indices.
|
|
•
|
You May Be Fully Exposed To The Decline In The Lowest Performing Index On The Final Calculation Day From Its Starting Level, But Will Not Participate In Any Positive Performance Of Any
Index.
|
|
•
|
Higher Contingent Coupon Rates Are Associated With Greater Risk.
|
|
•
|
The Securities Are Subject To A Potential Early Redemption, Which Would Limit Your Ability To Receive Further Payment On The Securities.
|
|
•
|
A Contingent Coupon Payment Date, An Optional Redemption Date Or The Stated Maturity Date May Be Postponed If A Calculation Day Is Postponed.
|
|
•
|
The Tax Consequences Of An Investment In Your Securities Are Uncertain.
|
|
•
|
The Securities Are Subject To Our Credit Risk.
|
|
•
|
The Estimated Value Of The Securities On The Pricing Date, Based On Jefferies LLC Proprietary Pricing Models At That Time And Our Internal Funding Rate, Will Be Less Than The Original
Offering Price.
|
|
•
|
The Estimated Value Of The Securities Was Determined For Us By Our Subsidiary Using Proprietary Pricing Models.
|
|
•
|
The Estimated Value Of The Securities Would Be Lower If It Were Calculated Based On Our Secondary Market Rate.
|
|
•
|
The Estimated Value Of The Securities Is Not An Indication Of The Price, If Any, At Which WFS, Jefferies LLC Or Any Other Person May Be Willing To Buy The Securities From You In The
Secondary Market.
|
|
•
|
The Value Of The Securities Prior To Stated Maturity Will Be Affected By Numerous Factors, Some Of Which Are Related In Complex Ways.
|
|
•
|
The Securities Will Not Be Listed On Any Securities Exchange And The Issuer Does Not Expect A Trading Market For The Securities To Develop.
|
|
•
|
Any Payments On The Securities Will Depend Upon The Performance Of Each Index And Therefore The Securities Are Subject To The Risks Associated With The Indices, As Discussed In The
Accompanying Pricing Supplement and Product Supplement.
|
|
•
|
The Securities Are Subject To Risks Associated With Small-Size Capitalization Companies.
|
|
•
|
An Investment In The Securities Is Subject To Risks Associated With Investing In Non-U.S. Companies.
|
|
•
|
Our Economic Interests And Those Of Any Dealer Participating In The Offering Are Potentially Adverse To Your Interests.
|
|
|
The issuer has filed a registration statement (including a prospectus) with the SEC for the offering to which this communication relates. Before you invest, you should read the prospectus in that registration
statement and other documents that the issuer has filed with the SEC for more complete information about the issuer and this offering. You may get these documents for free by visiting EDGAR on the SEC website at www.sec.gov. Alternatively, the
issuer, any agent or any dealer participating in the offering will arrange to send you the prospectus if you request it by calling your financial advisor or by calling Jefferies LLC.
Wells Fargo Advisors is a trade name used by Wells Fargo Clearing Services, LLC and Wells Fargo Advisors Financial Network, LLC, members SIPC, separate registered broker-dealers and non-bank affiliates of Wells
Fargo Finance LLC and Wells Fargo & Company.
2