1 Acquisition of Capital Bancorp, Inc. (NASDAQ: CBNK) Transformational merger creating a powerful and diversified financial services franchise September 30, 2026
2 Safe Harbor Statement Forward-Looking Statements This communication includes “forward-looking statements” within the meaning of the Private Securities Litigation Reform Act of 1995, which statements involve inherent risks and uncertainties. Examples of forward-looking statements include, but are not limited to, statements regarding the outlook and expectations of Peoples and Capital, respectively, with respect to the proposed transaction, the strategic and financial benefits of the proposed transaction, including the expected impact of the proposed transactions on the combined company’s future financial performance (including anticipated accretion to earnings per share, the tangible book value earn-back period, and other operating and return metrics), the timing of the closing of the proposed transaction, and the ability to successfully integrate the combined businesses. Such statements are often characterized by the use of qualified words (and their derivatives) such as “may,” “will,” “anticipate,” “could,” “should,” “would,” “believe,” “contemplate,” “expect,” “estimate,” “continue,” “plan,” “project,” and “intend,” as well as words of similar meaning or other statements concerning opinions or judgment of Peoples or Capital or their respective management about future events. Forward-looking statements are based on assumptions as of the time they are made and are subject to risks, uncertainties, and other factors that are difficult to predict with regard to timing, extent, likelihood, and degree of occurrence, which could cause actual results to differ materially from anticipated results expressed or implied by such forward-looking statements. Such risks, uncertainties and assumptions include, among others, the following: • the occurrence of any event, change, or other circumstances that could give rise to the right of one or both of the parties to terminate the Merger Agreement; • the failure to obtain necessary regulatory approvals (and the risk that such approvals may result in the imposition of conditions that could adversely affect the combined company or the expected benefits of the proposed transaction) and the possibility that the proposed transaction does not close when expected or at all because required regulatory approvals, the failure to obtain required shareholder approvals, or other approvals and the other conditions to closing are not received or satisfied on a timely basis or at all; • the outcome of any legal proceedings that may be instituted against Peoples or Capital; • the possibility that the anticipated benefits of the proposed transaction, including anticipated cost savings and strategic gains, are not realized when expected or at all, including as a result of changes in, or problems arising from, general economic and market conditions, interest and exchange rates, monetary policy, laws and regulations and their enforcement, and the degree of competition in the geographic and business areas in which Peoples and Capital operate; • the possibility that integration of the companies may be more difficult, time-consuming, or costly than expected; • the impact of purchase accounting with respect to the proposed transaction, or any change in the assumptions used regarding the assets acquired and liabilities assumed to determine their fair value and credit marks; • the possibility that the proposed transaction may be more expensive or take longer to complete than anticipated, including as a result of unexpected factors or events; • the diversion of management’s attention from ongoing business operations and opportunities; • potential adverse reactions of Peoples’ or Capital’s customers or changes to business or employee relationships, including those resulting from the announcement or completion of the proposed transaction; • a material adverse change in the financial condition of Peoples or Capital; • changes in Peoples’ share price before closing; • risks relating to the potential dilutive effect of shares of Peoples’ common stock to be issued in the proposed transaction; • general competitive, economic, political, and market conditions; • major catastrophes such as earthquakes, floods, or other natural or human disasters, including infectious disease outbreaks; and • other factors that may affect future results of Peoples or Capital, including, among others, changes in asset quality and credit risk; the inability to sustain revenue and earnings growth; changes in interest rates; deposit flows; inflation; customer borrowing, repayment, investment, and deposit practices; the impact, extent, and timing of technological changes; capital management activities; and other actions of the Federal Reserve Board, the Office of the Comptroller of the Currency, the Consumer Financial Protection Bureau, and legislative and regulatory actions and reforms. These factors are not necessarily all of the factors that could cause Peoples, Capital, or the combined company’s actual results, performance, or achievements to differ materially from those expressed in or implied by any of the forward-looking statements. Other factors, including unknown or unpredictable factors, also could harm Peoples’, Capital’s, or the combined company’s results. Although each of Peoples and Capital believes that its expectations with respect to forward-looking statements are based upon reasonable assumptions within the bounds of its existing knowledge of its business and operations, there can be no assurance that actual results of Peoples or Capital will not differ materially from any projected future results expressed or implied by such forward-looking statements. Additional factors that could cause results to differ materially from those described above can be found in each of Peoples’ and Capital’s most recent annual report on Form 10-K for the fiscal year ended December 31, 2025, quarterly reports on Form 10-Q, and other documents subsequently filed by Peoples and Capital with the Securities and Exchange Commission. The actual results anticipated may not be realized or, even if substantially realized, they may not have the expected consequences to or effects on Peoples, Capital, or each of their respective businesses or operations. Investors are cautioned not to rely too heavily on any such forward-looking statements. Peoples and Capital urge you to consider all of these risks, uncertainties, and other factors carefully in evaluating all such forward-looking statements made by Peoples and Capital. Forward-looking statements speak only as of the date they are made, and Peoples and Capital undertake no obligation to update or clarify these forward-looking statements, whether as a result of new information, future events, or otherwise, except to the extent required by applicable law.
3 Additional Information and Where to Find It and Participants Additional Information and Where to Find It In connection with the proposed transaction, Peoples intends to file with the SEC a Registration Statement on Form S-4 to register the shares of Peoples common stock to be issued in connection with the proposed transaction. The Registration Statement will include a joint proxy statement/prospectus, and Peoples and Capital may file with the SEC other relevant documents concerning the proposed transaction. The information contained herein does not constitute an offer to sell or a solicitation of an offer to buy any securities or a solicitation of any vote or approval, nor shall there be any sale of securities in any jurisdiction in which such offer, solicitation or sale would be unlawful prior to registration or qualification under the securities laws of any such jurisdiction. BEFORE MAKING ANY VOTING OR INVESTMENT DECISION, INVESTORS AND SECURITY HOLDERS ARE URGED TO READ THE REGISTRATION STATEMENT AND JOINT PROXY STATEMENT/PROSPECTUS REGARDING THE PROPOSED TRANSACTION WHEN THEY BECOME AVAILABLE AND ANY OTHER RELEVANT DOCUMENTS FILED WITH THE SEC, AS WELL AS ANY AMENDMENTS OR SUPPLEMENTS TO THOSE DOCUMENTS, BECAUSE THEY WILL CONTAIN IMPORTANT INFORMATION ABOUT PEOPLES, CAPITAL, AND THE PROPOSED TRANSACTION AND RELATED MATTERS. Investors and security holders will be able to obtain a free copy of the registration statement, including the joint proxy statement/prospectus, as well as other relevant documents filed with the SEC containing information about Peoples and Capital, without charge, at the SEC’s website (https://www.sec.gov). Participants in Solicitation Peoples and Capital, along with their respective directors, executive officers, management, and employees may be deemed participants in the solicitation of proxies in connection with the Merger. Information concerning Peoples’ participants is set forth in the Proxy Statement, dated March 6, 2026, for Peoples’ 2026 annual meeting of stockholders as filed with the SEC on Schedule 14A. Information concerning Capital’s participants is set forth in the Proxy Statement, dated April 7, 2026, for Capital’s 2026 annual meeting of stockholders as filed with the SEC on Schedule 14A. Additional information regarding the participants in the solicitation of proxies in respect of the proposed transaction and interests of participants of Peoples and Capital in the solicitation of proxies in respect of the Merger will be included in the registration statement and joint proxy statement/prospectus to be filed with the SEC. Free copies of these documents, when available, may be obtained as described in the preceding paragraph.
4 Transaction Highlights & Merger Rationale Compelling Strategic Fit • Established, diversified business lines with demonstrated financial performance and ability to grow • Expands presence in attractive markets while adding nationwide specialty capabilities • Enhances earnings diversification and margin profile • Crosses $10 billion with meaningful scale and limited incremental Durbin- related exposure from Capital Transformational combination with Capital accelerates Peoples' strategy through greater scale, diversification and earnings power Financially Attractive(1) • ~19% fully-phased 2027E EPS accretion • TBVPS earnback of < 3 years • Well-capitalized with pro forma CET 1 ratio at close of 11.9% • Powerful pro forma profitability with fully-phased 2027E ROAA of ~1.79% and fully-phased 2027E ROATCE of ~20% Cultural Alignment • Complementary relationship-based business philosophies • Aligned principles and core values • Shared commitment to clients, employees, communities and shareholders • Meaningful addition of Capital talent and leadership to the Peoples team • Opportunistic in pursuing differentiated niche businesses with attractive return profiles (1) Fully-phased 2027E impacts assume full-year impacts and 100% phased-in cost savings, presented for illustrative purposes Note: “TBVPS” = tangible book value per share; “ROAA” = return on average assets; “ROATCE” = return on average tangible common equity; estimated financial impacts are presented for illustrative purposes only. Includes purchase accounting marks and transaction-related expenses. Pro forma data is subject to various assumptions and uncertainties. See page 2 regarding “forward-looking statements” Peoples has proven expertise to execute and deliver this compelling strategic opportunity
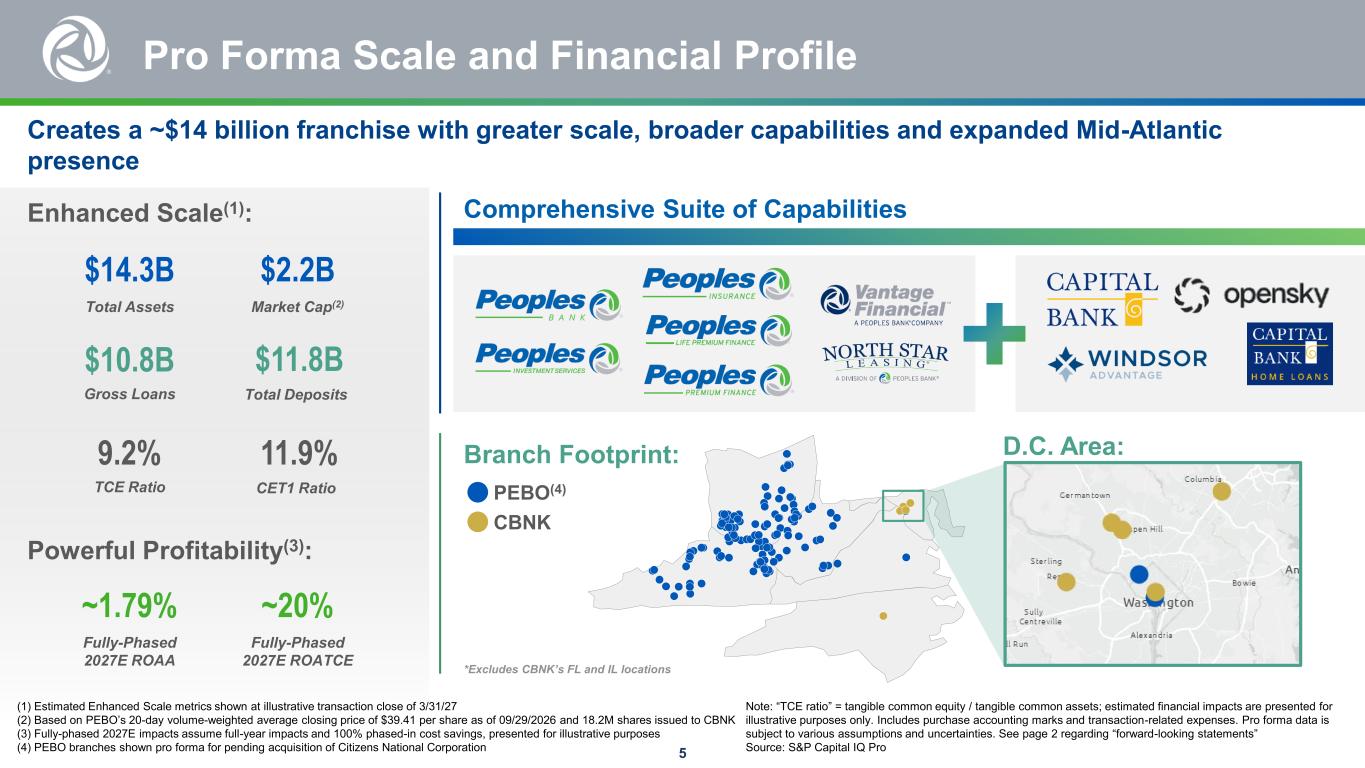
5 Pro Forma Scale and Financial Profile (1) Estimated Enhanced Scale metrics shown at illustrative transaction close of 3/31/27 (2) Based on PEBO’s 20-day volume-weighted average closing price of $39.41 per share as of 09/29/2026 and 18.2M shares issued to CBNK (3) Fully-phased 2027E impacts assume full-year impacts and 100% phased-in cost savings, presented for illustrative purposes (4) PEBO branches shown pro forma for pending acquisition of Citizens National Corporation $14.3B Total Assets Note: “TCE ratio” = tangible common equity / tangible common assets; estimated financial impacts are presented for illustrative purposes only. Includes purchase accounting marks and transaction-related expenses. Pro forma data is subject to various assumptions and uncertainties. See page 2 regarding “forward-looking statements” Source: S&P Capital IQ Pro $2.2B Market Cap(2) $10.8B Gross Loans $11.8B Total Deposits Enhanced Scale(1): Powerful Profitability(3): ~1.79% Fully-Phased 2027E ROAA ~20% Fully-Phased 2027E ROATCE Branch Footprint: D.C. Area: PEBO(4) CBNK 9.2% TCE Ratio 11.9% CET1 Ratio Comprehensive Suite of Capabilities Creates a ~$14 billion franchise with greater scale, broader capabilities and expanded Mid-Atlantic presence *Excludes CBNK’s FL and IL locations
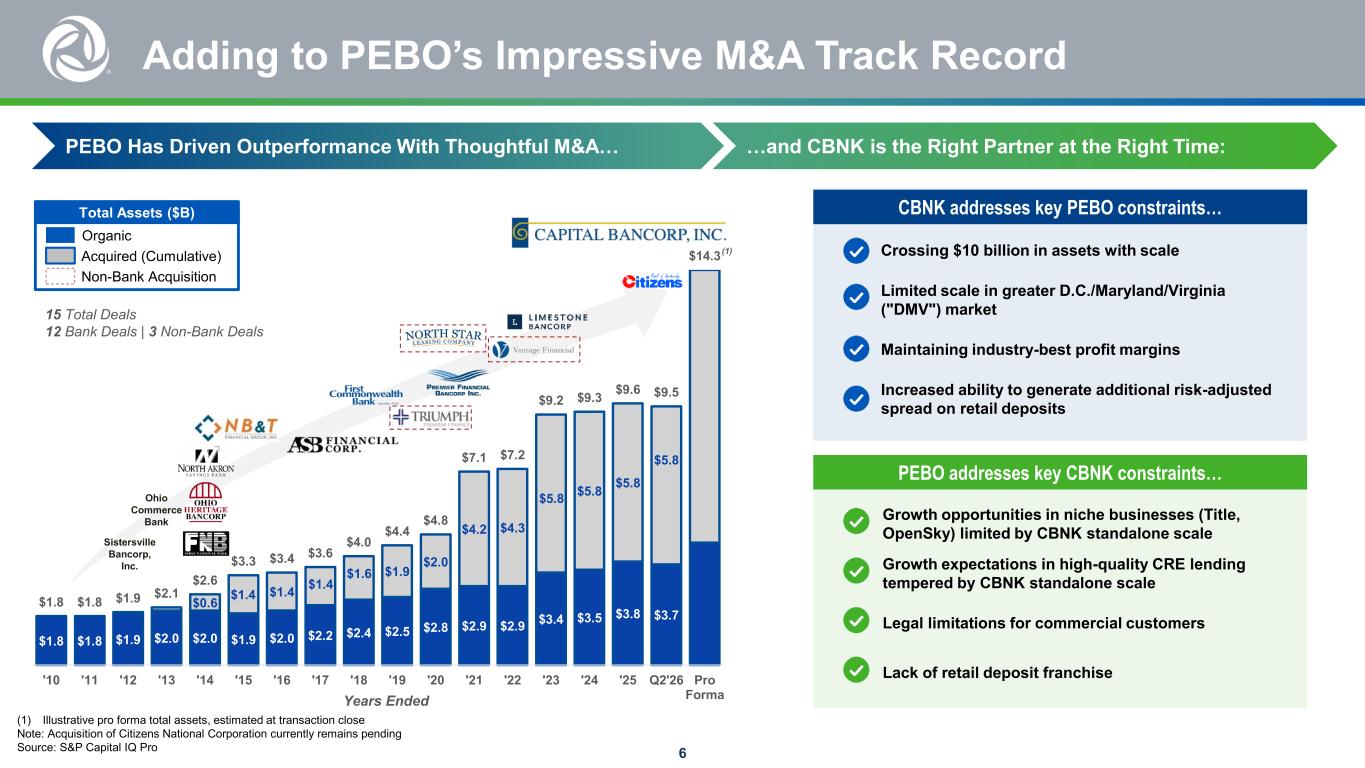
6 $1.8 $1.8 $1.9 $2.0 $2.0 $1.9 $2.0 $2.2 $2.4 $2.5 $2.8 $2.9 $2.9 $3.4 $3.5 $3.8 $3.7 $0.6 $1.4 $1.4 $1.4 $1.6 $1.9 $2.0 $4.2 $4.3 $5.8 $5.8 $5.8 $5.8 $1.8 $1.8 $1.9 $2.1 $2.6 $3.3 $3.4 $3.6 $4.0 $4.4 $4.8 $7.1 $7.2 $9.2 $9.3 $9.6 $9.5 $14.3 '10 '11 '12 '13 '14 '15 '16 '17 '18 '19 '20 '21 '22 '23 '24 '25 Q2'26 Pro Forma PEBO addresses key CBNK constraints… CBNK addresses key PEBO constraints… Adding to PEBO’s Impressive M&A Track Record Organic Acquired (Cumulative) Sistersville Bancorp, Inc. Ohio Commerce Bank Total Assets ($B) Non-Bank Acquisition 15 Total Deals 12 Bank Deals | 3 Non-Bank Deals Crossing $10 billion in assets with scale Limited scale in greater D.C./Maryland/Virginia ("DMV") market Maintaining industry-best profit margins Increased ability to generate additional risk-adjusted spread on retail deposits Growth opportunities in niche businesses (Title, OpenSky) limited by CBNK standalone scale Growth expectations in high-quality CRE lending tempered by CBNK standalone scale Legal limitations for commercial customers Lack of retail deposit franchise PEBO Has Driven Outperformance With Thoughtful M&A… …and CBNK is the Right Partner at the Right Time: Years Ended (1) Illustrative pro forma total assets, estimated at transaction close Note: Acquisition of Citizens National Corporation currently remains pending Source: S&P Capital IQ Pro (1)
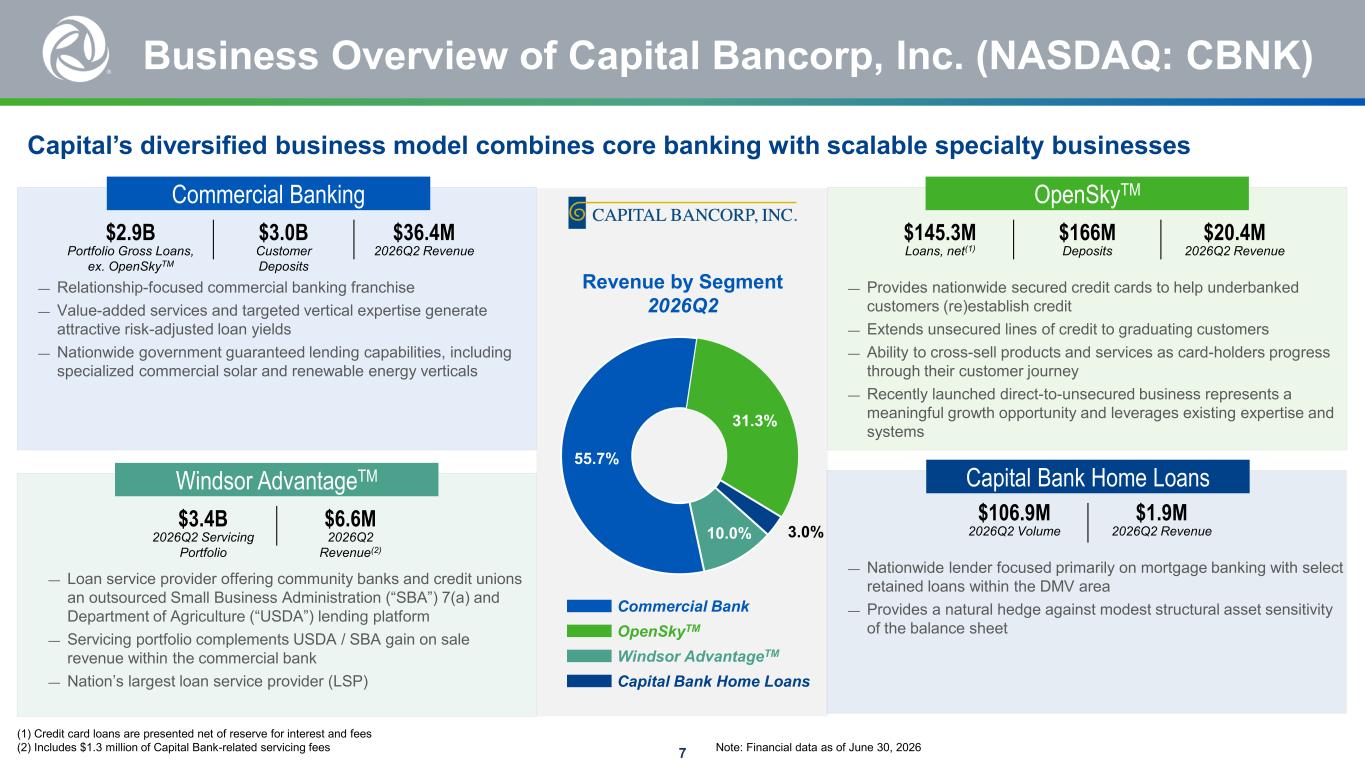
7 Capital Bank Home Loans $106.9M 2026Q2 Volume $1.9M 2026Q2 Revenue ― Nationwide lender focused primarily on mortgage banking with select retained loans within the DMV area ― Provides a natural hedge against modest structural asset sensitivity of the balance sheet Windsor AdvantageTM $3.4B 2026Q2 Servicing Portfolio $6.6M 2026Q2 Revenue(2) ― Loan service provider offering community banks and credit unions an outsourced Small Business Administration (“SBA”) 7(a) and Department of Agriculture (“USDA”) lending platform ― Servicing portfolio complements USDA / SBA gain on sale revenue within the commercial bank ― Nation’s largest loan service provider (LSP) Revenue by Segment 2026Q2 Commercial Bank OpenSkyTM Windsor AdvantageTM Capital Bank Home Loans Business Overview of Capital Bancorp, Inc. (NASDAQ: CBNK) (1) Credit card loans are presented net of reserve for interest and fees (2) Includes $1.3 million of Capital Bank-related servicing fees 55.7% 31.3% 3.0%10.0% Note: Financial data as of June 30, 2026 ― Relationship-focused commercial banking franchise ― Value-added services and targeted vertical expertise generate attractive risk-adjusted loan yields ― Nationwide government guaranteed lending capabilities, including specialized commercial solar and renewable energy verticals $2.9B Portfolio Gross Loans, ex. OpenSkyTM $3.0B Customer Deposits $36.4M 2026Q2 Revenue Commercial Banking $145.3M Loans, net(1) $166M Deposits $20.4M 2026Q2 Revenue ― Provides nationwide secured credit cards to help underbanked customers (re)establish credit ― Extends unsecured lines of credit to graduating customers ― Ability to cross-sell products and services as card-holders progress through their customer journey ― Recently launched direct-to-unsecured business represents a meaningful growth opportunity and leverages existing expertise and systems OpenSkyTM Capital’s diversified business model combines core banking with scalable specialty businesses
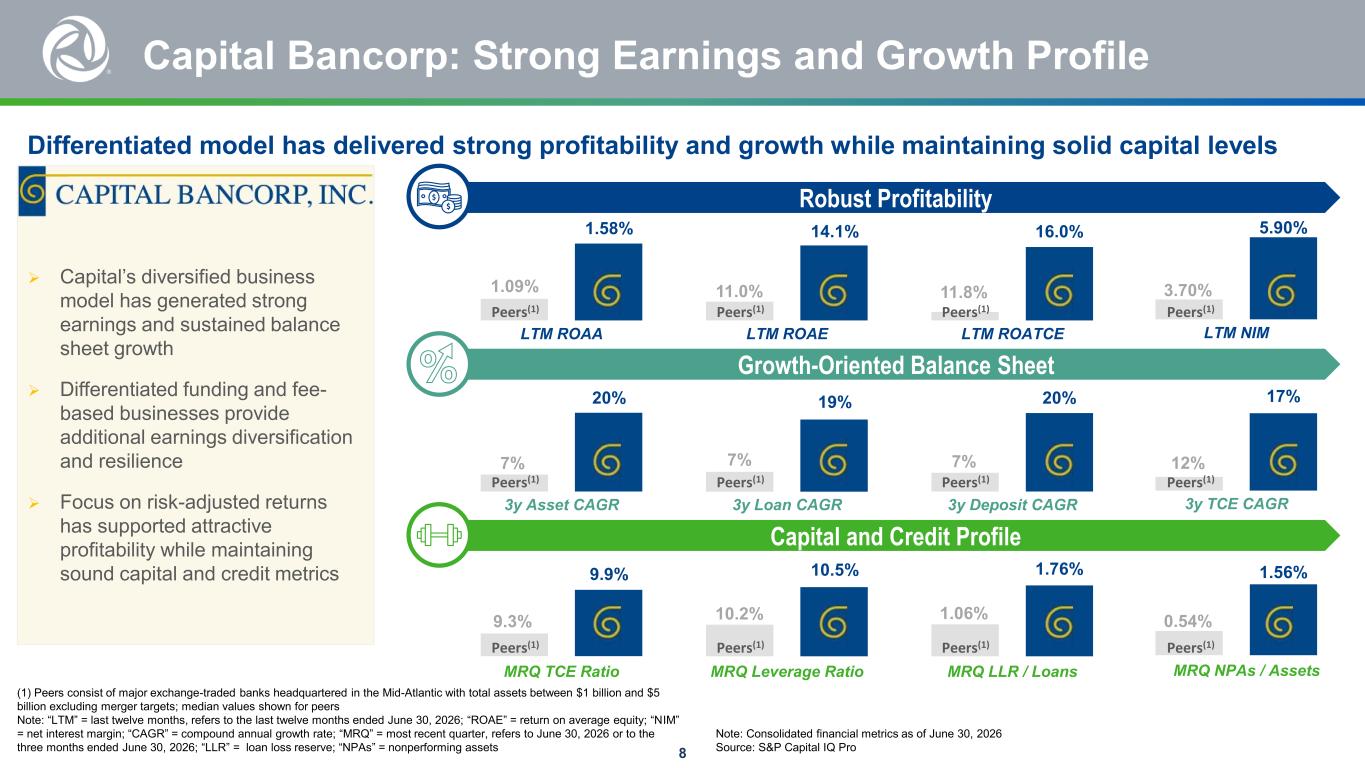
8 LTM ROAA 1.09% 1.58% LTM ROAE 11.0% 14.1% LTM ROATCE 11.8% 16.0% LTM NIM 3.70% 5.90% Peers(1) Peers(1) Peers(1) Peers(1) 3y Asset CAGR 7% 20% 3y Loan CAGR 7% 19% 3y Deposit CAGR 7% 20% 3y TCE CAGR 12% 17% Peers(1) Peers(1) Peers(1) Peers(1) MRQ NPAs / AssetsMRQ Leverage RatioMRQ TCE Ratio 9.3% 9.9% 10.2% 10.5% MRQ LLR / Loans 1.06% 1.76% 0.54% 1.56% Peers(1) Peers(1) Peers(1) Peers(1) Capital Bancorp: Strong Earnings and Growth Profile (1) Peers consist of major exchange-traded banks headquartered in the Mid-Atlantic with total assets between $1 billion and $5 billion excluding merger targets; median values shown for peers Note: “LTM” = last twelve months, refers to the last twelve months ended June 30, 2026; “ROAE” = return on average equity; “NIM” = net interest margin; “CAGR” = compound annual growth rate; “MRQ” = most recent quarter, refers to June 30, 2026 or to the three months ended June 30, 2026; “LLR” = loan loss reserve; “NPAs” = nonperforming assets Differentiated model has delivered strong profitability and growth while maintaining solid capital levels Robust Profitability Growth-Oriented Balance Sheet Capital and Credit Profile ➢ Capital’s diversified business model has generated strong earnings and sustained balance sheet growth ➢ Differentiated funding and fee- based businesses provide additional earnings diversification and resilience ➢ Focus on risk-adjusted returns has supported attractive profitability while maintaining sound capital and credit metrics Note: Consolidated financial metrics as of June 30, 2026 Source: S&P Capital IQ Pro
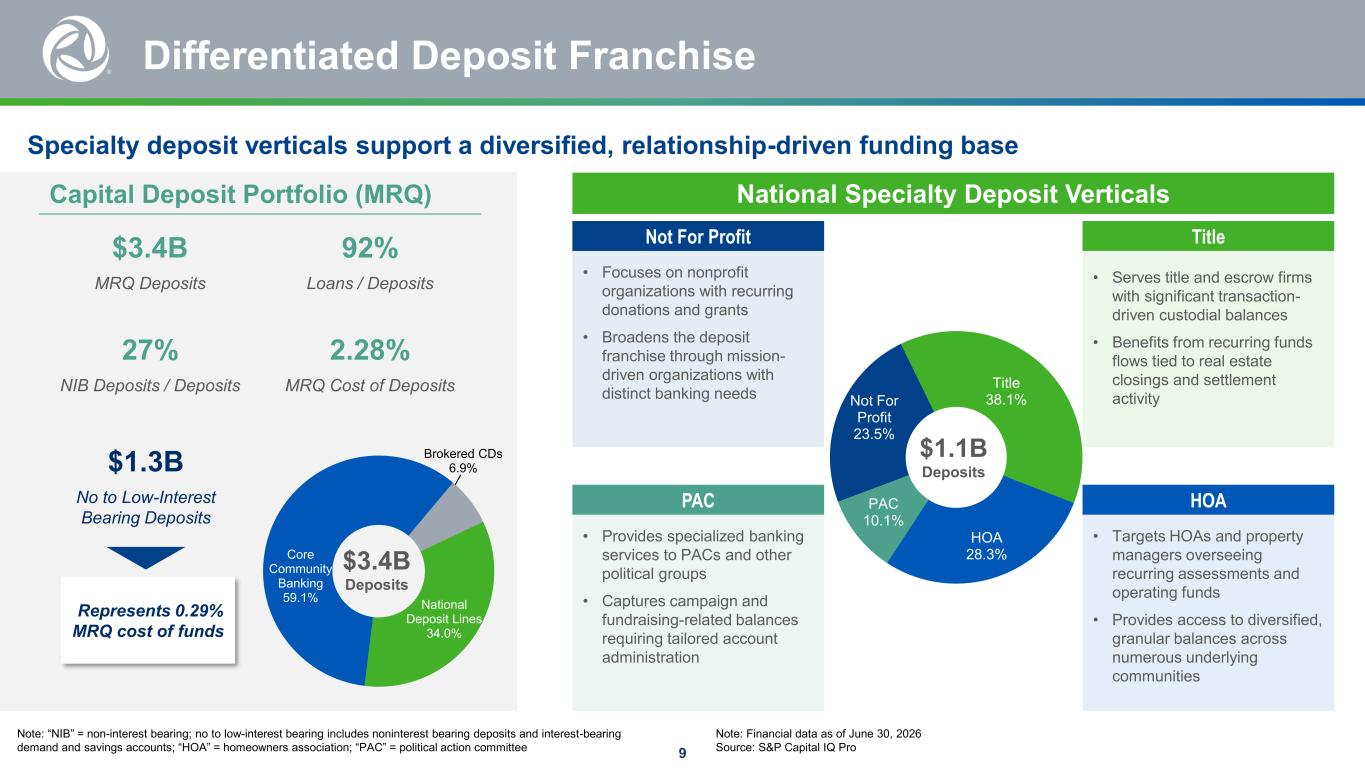
9 Differentiated Deposit Franchise Note: “NIB” = non-interest bearing; no to low-interest bearing includes noninterest bearing deposits and interest-bearing demand and savings accounts; “HOA” = homeowners association; “PAC” = political action committee 27% NIB Deposits / Deposits 2.28% MRQ Cost of Deposits 92% Loans / Deposits $3.4B MRQ Deposits Brokered CDs 6.9% National Deposit Lines 34.0% Core Community Banking 59.1% Title 38.1% HOA 28.3% PAC 10.1% Not For Profit 23.5% $1.1B Deposits Capital Deposit Portfolio (MRQ) • Serves title and escrow firms with significant transaction- driven custodial balances • Benefits from recurring funds flows tied to real estate closings and settlement activity Title • Targets HOAs and property managers overseeing recurring assessments and operating funds • Provides access to diversified, granular balances across numerous underlying communities HOA • Focuses on nonprofit organizations with recurring donations and grants • Broadens the deposit franchise through mission- driven organizations with distinct banking needs Not For Profit • Provides specialized banking services to PACs and other political groups • Captures campaign and fundraising-related balances requiring tailored account administration PAC $1.3B No to Low-Interest Bearing Deposits Represents 0.29% MRQ cost of funds Specialty deposit verticals support a diversified, relationship-driven funding base Note: Financial data as of June 30, 2026 Source: S&P Capital IQ Pro $3.4B Deposits National Specialty Deposit Verticals
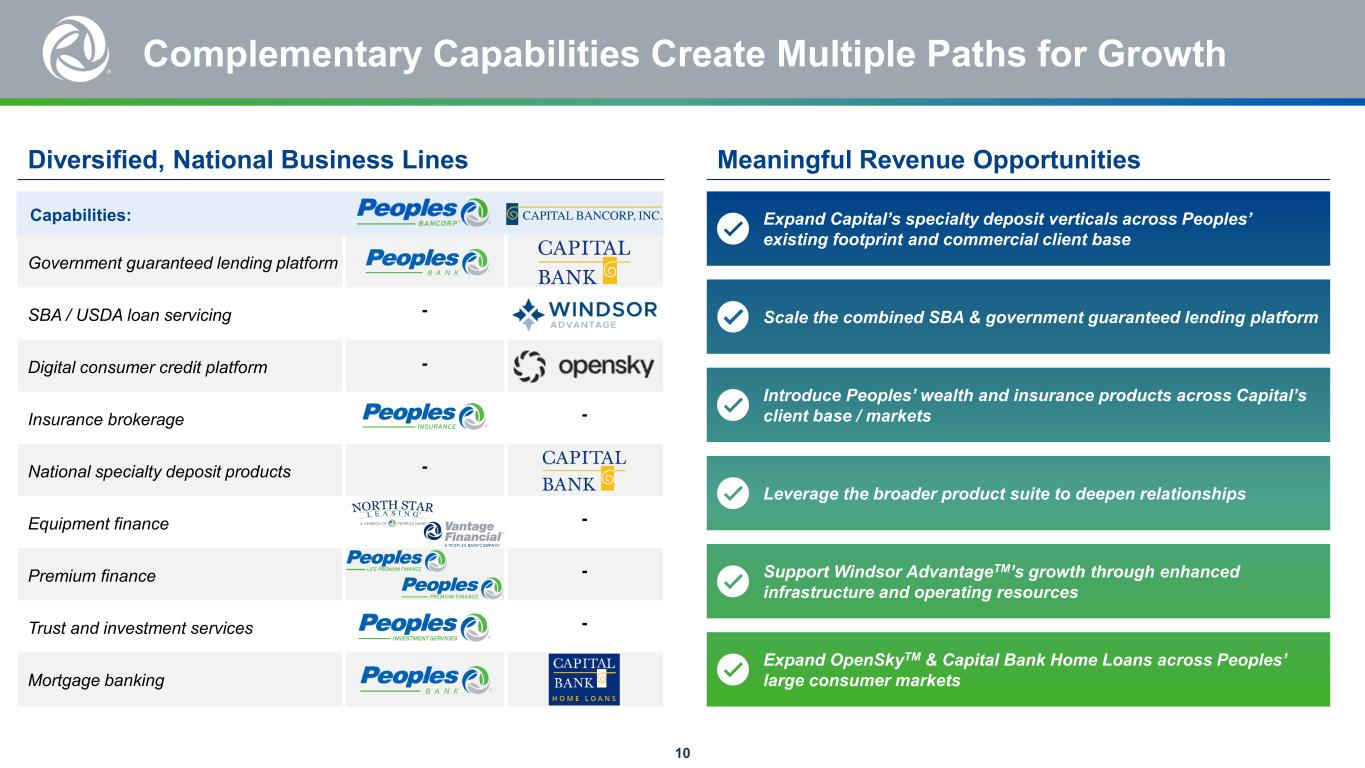
10 Expand Capital’s specialty deposit verticals across Peoples’ existing footprint and commercial client base Scale the combined SBA & government guaranteed lending platform Introduce Peoples’ wealth and insurance products across Capital’s client base / markets Leverage the broader product suite to deepen relationships Expand OpenSkyTM & Capital Bank Home Loans across Peoples’ large consumer markets Support Windsor AdvantageTM’s growth through enhanced infrastructure and operating resources Complementary Capabilities Create Multiple Paths for Growth Government guaranteed lending platform SBA / USDA loan servicing Digital consumer credit platform Insurance brokerage National specialty deposit products Equipment finance Premium finance Trust and investment services Mortgage banking Meaningful Revenue OpportunitiesDiversified, National Business Lines - - - - - - Capabilities: -
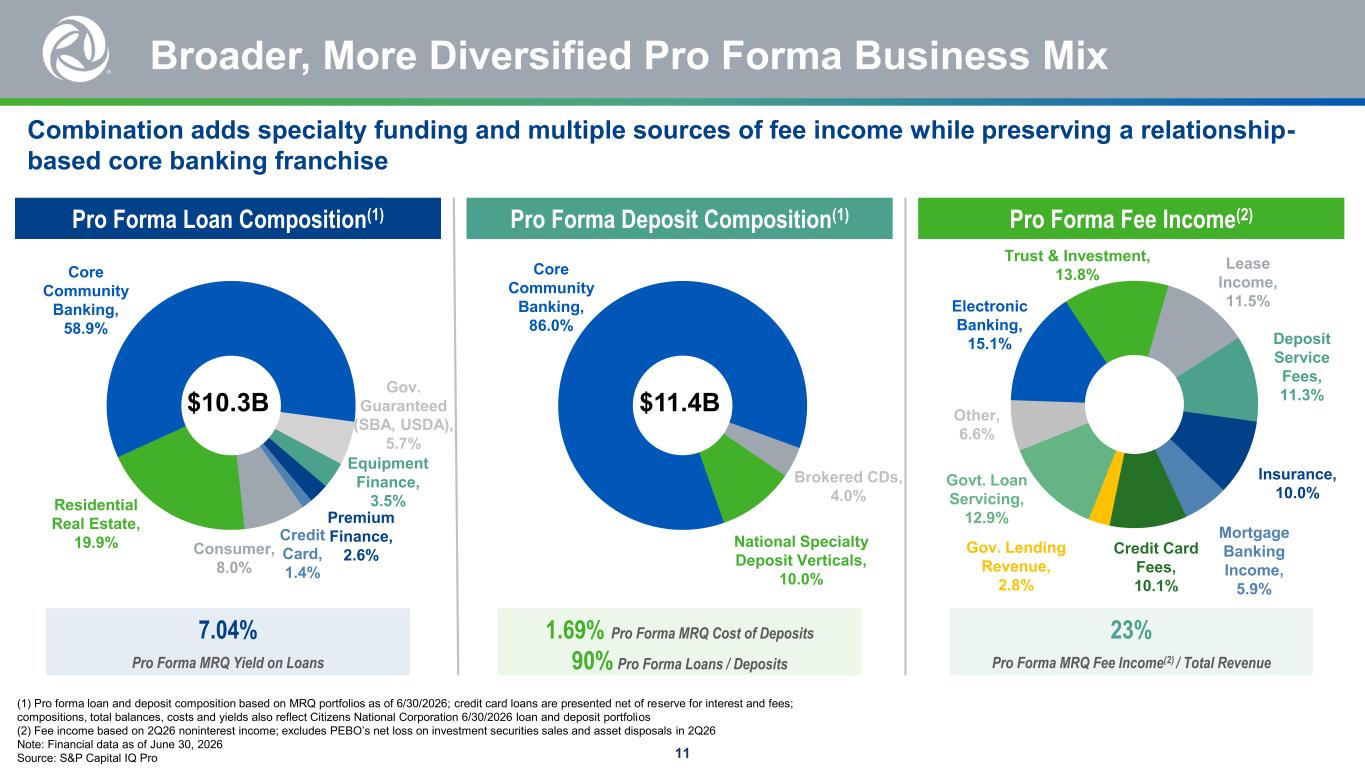
11 Broader, More Diversified Pro Forma Business Mix Brokered CDs, 4.0% Core Community Banking, 86.0% National Specialty Deposit Verticals, 10.0% Trust & Investment, 13.8% Electronic Banking, 15.1% Govt. Loan Servicing, 12.9% Deposit Service Fees, 11.3% Lease Income, 11.5% Insurance, 10.0% Mortgage Banking Income, 5.9% Credit Card Fees, 10.1% Gov. Lending Revenue, 2.8% Other, 6.6% $11.4B (1) Pro forma loan and deposit composition based on MRQ portfolios as of 6/30/2026; credit card loans are presented net of reserve for interest and fees; compositions, total balances, costs and yields also reflect Citizens National Corporation 6/30/2026 loan and deposit portfolios (2) Fee income based on 2Q26 noninterest income; excludes PEBO’s net loss on investment securities sales and asset disposals in 2Q26 Note: Financial data as of June 30, 2026 Source: S&P Capital IQ Pro Pro Forma Loan Composition(1) Pro Forma Deposit Composition(1) Pro Forma Fee Income(2) Combination adds specialty funding and multiple sources of fee income while preserving a relationship- based core banking franchise 7.04% Pro Forma MRQ Yield on Loans 1.69% Pro Forma MRQ Cost of Deposits 90% Pro Forma Loans / Deposits 23% Pro Forma MRQ Fee Income(2) / Total Revenue Core Community Banking, 58.9% Residential Real Estate, 19.9% Consumer, 8.0% Credit Card, 1.4% Equipment Finance, 3.5% Premium Finance, 2.6% $10.3B Gov. Guaranteed (SBA, USDA), 5.7%
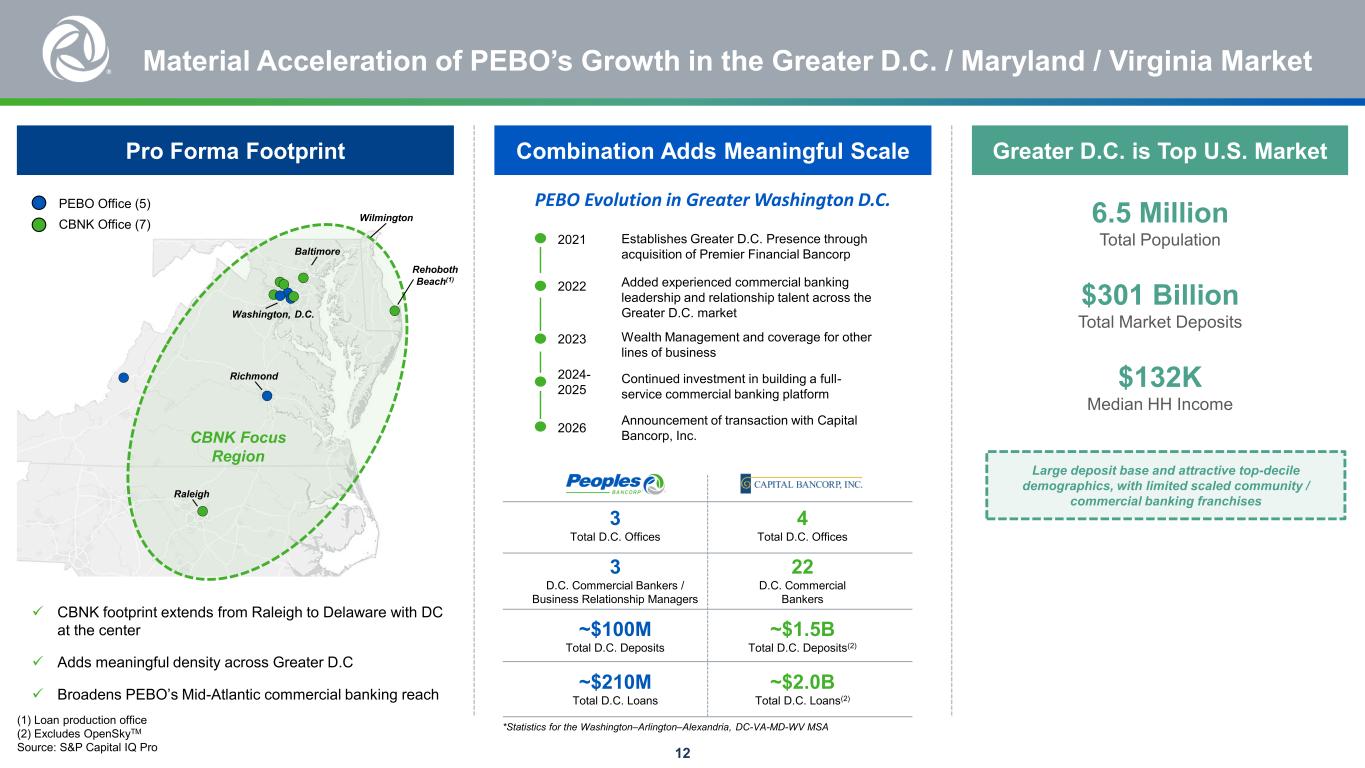
12 Greater D.C. is Top U.S. MarketPro Forma Footprint Combination Adds Meaningful Scale Richmond Raleigh Baltimore CBNK Focus Region ✓ CBNK footprint extends from Raleigh to Delaware with DC at the center ✓ Adds meaningful density across Greater D.C ✓ Broadens PEBO’s Mid-Atlantic commercial banking reach Washington, D.C. CBNK Office (7) PEBO Office (5) 2026 2024- 2025 2021 Establishes Greater D.C. Presence through acquisition of Premier Financial Bancorp Continued investment in building a full- service commercial banking platform Announcement of transaction with Capital Bancorp, Inc. Wealth Management and coverage for other lines of business 2023 2022 Added experienced commercial banking leadership and relationship talent across the Greater D.C. market PEBO Evolution in Greater Washington D.C. 22 D.C. Commercial Bankers 4 Total D.C. Offices ~$1.5B Total D.C. Deposits(2) ~$2.0B Total D.C. Loans(2) 3 D.C. Commercial Bankers / Business Relationship Managers 3 Total D.C. Offices ~$100M Total D.C. Deposits ~$210M Total D.C. Loans 6.5 Million Total Population $301 Billion Total Market Deposits $132K Median HH Income Large deposit base and attractive top-decile demographics, with limited scaled community / commercial banking franchises (1) Loan production office (2) Excludes OpenSkyTM Source: S&P Capital IQ Pro *Statistics for the Washington–Arlington–Alexandria, DC-VA-MD-WV MSA Material Acceleration of PEBO’s Growth in the Greater D.C. / Maryland / Virginia Market Rehoboth Beach(1) Wilmington
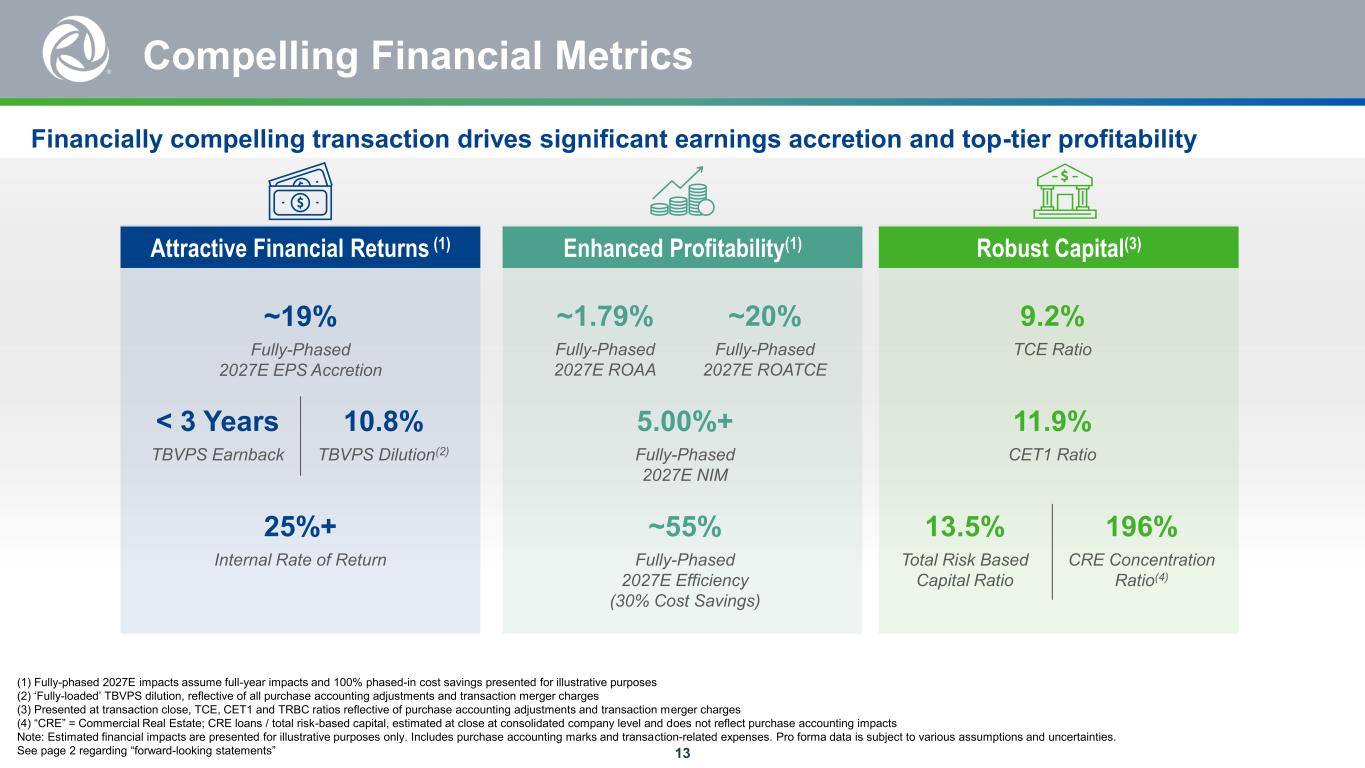
13 Compelling Financial Metrics Financially compelling transaction drives significant earnings accretion and top-tier profitability (1) Fully-phased 2027E impacts assume full-year impacts and 100% phased-in cost savings presented for illustrative purposes (2) ‘Fully-loaded’ TBVPS dilution, reflective of all purchase accounting adjustments and transaction merger charges (3) Presented at transaction close, TCE, CET1 and TRBC ratios reflective of purchase accounting adjustments and transaction merger charges (4) “CRE” = Commercial Real Estate; CRE loans / total risk-based capital, estimated at close at consolidated company level and does not reflect purchase accounting impacts Note: Estimated financial impacts are presented for illustrative purposes only. Includes purchase accounting marks and transaction-related expenses. Pro forma data is subject to various assumptions and uncertainties. See page 2 regarding “forward-looking statements” Attractive Financial Returns (1) Enhanced Profitability(1) ~19% Fully-Phased 2027E EPS Accretion 25%+ Internal Rate of Return ~1.79% Fully-Phased 2027E ROAA ~20% Fully-Phased 2027E ROATCE 5.00%+ Fully-Phased 2027E NIM ~55% Fully-Phased 2027E Efficiency (30% Cost Savings) 10.8% TBVPS Dilution(2) < 3 Years TBVPS Earnback Robust Capital(3) 11.9% CET1 Ratio 9.2% TCE Ratio 13.5% Total Risk Based Capital Ratio 196% CRE Concentration Ratio(4)
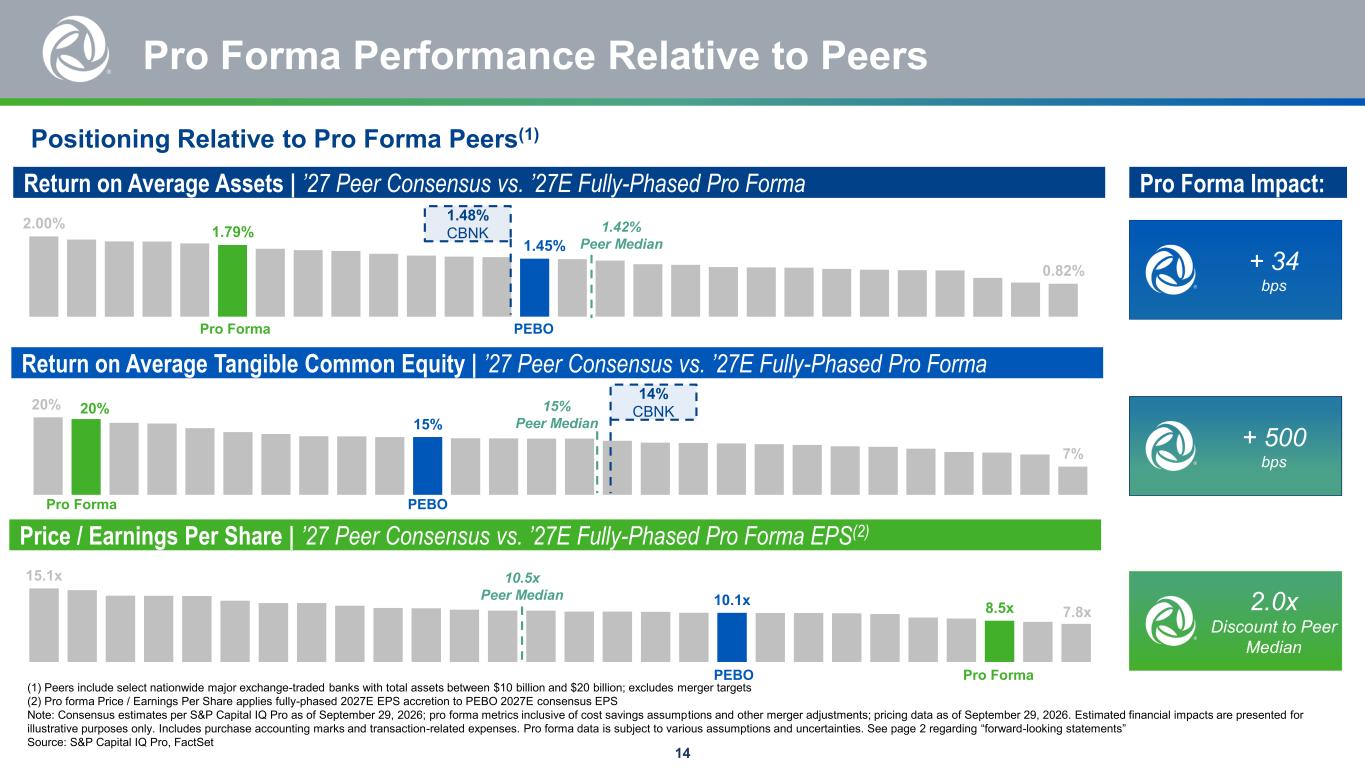
14 Pro Forma Performance Relative to Peers 2.00% 1.79% 1.45% 0.82% Return on Average Assets | ’27 Peer Consensus vs. ’27E Fully-Phased Pro Forma Return on Average Tangible Common Equity | ’27 Peer Consensus vs. ’27E Fully-Phased Pro Forma 20% 20% 15% 7% 15.1x 10.1x 8.5x 7.8x PEBOPro Forma PEBOPro Forma PEBO Pro Forma Price / Earnings Per Share | ’27 Peer Consensus vs. ’27E Fully-Phased Pro Forma EPS(2) 1.42% Peer Median 15% Peer Median 10.5x Peer Median Positioning Relative to Pro Forma Peers(1) (1) Peers include select nationwide major exchange-traded banks with total assets between $10 billion and $20 billion; excludes merger targets (2) Pro forma Price / Earnings Per Share applies fully-phased 2027E EPS accretion to PEBO 2027E consensus EPS Note: Consensus estimates per S&P Capital IQ Pro as of September 29, 2026; pro forma metrics inclusive of cost savings assumptions and other merger adjustments; pricing data as of September 29, 2026. Estimated financial impacts are presented for illustrative purposes only. Includes purchase accounting marks and transaction-related expenses. Pro forma data is subject to various assumptions and uncertainties. See page 2 regarding “forward-looking statements” Source: S&P Capital IQ Pro, FactSet Pro Forma Impact: + 34 bps + 500 bps 2.0x Discount to Peer Median 1.48% CBNK 14% CBNK
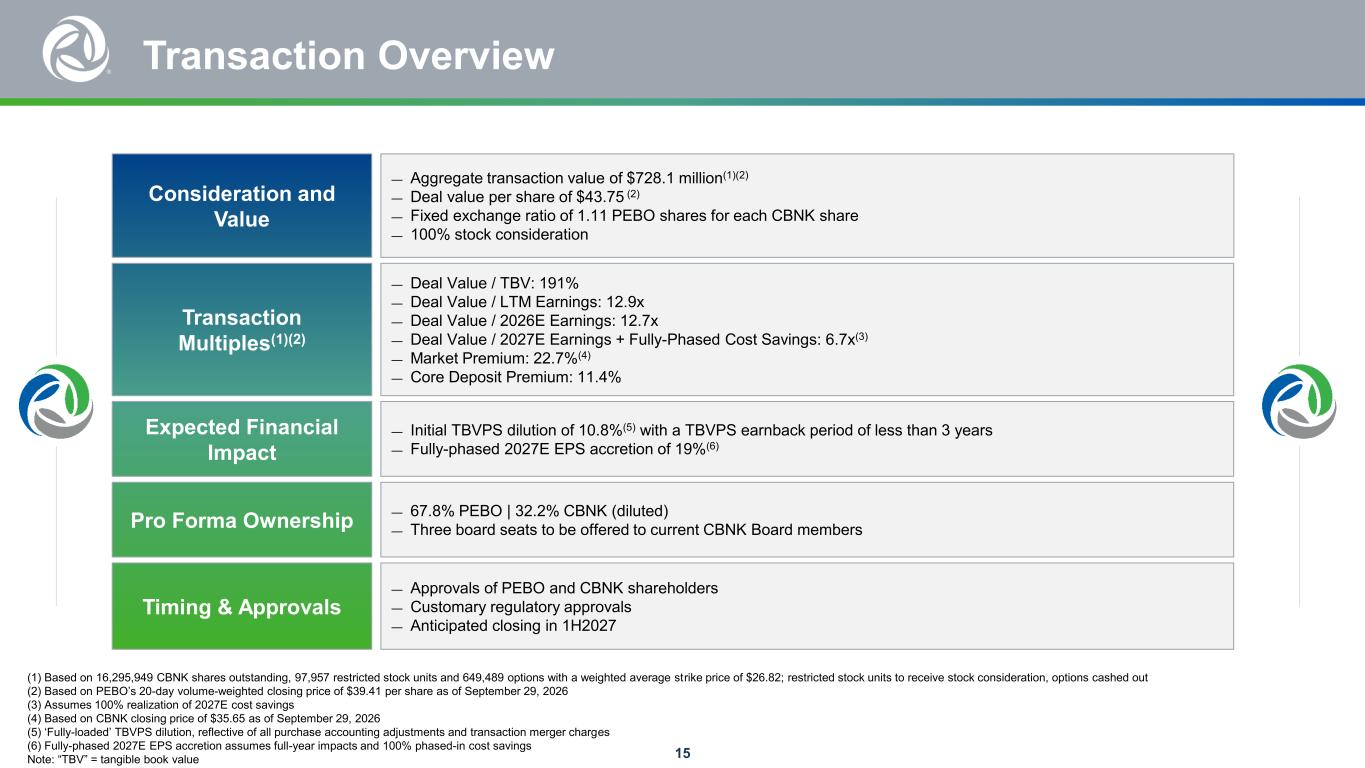
15 Transaction Overview (1) Based on 16,295,949 CBNK shares outstanding, 97,957 restricted stock units and 649,489 options with a weighted average strike price of $26.82; restricted stock units to receive stock consideration, options cashed out (2) Based on PEBO’s 20-day volume-weighted closing price of $39.41 per share as of September 29, 2026 (3) Assumes 100% realization of 2027E cost savings (4) Based on CBNK closing price of $35.65 as of September 29, 2026 (5) ‘Fully-loaded’ TBVPS dilution, reflective of all purchase accounting adjustments and transaction merger charges (6) Fully-phased 2027E EPS accretion assumes full-year impacts and 100% phased-in cost savings Note: “TBV” = tangible book value ― Aggregate transaction value of $728.1 million(1)(2) ― Deal value per share of $43.75 (2) ― Fixed exchange ratio of 1.11 PEBO shares for each CBNK share ― 100% stock consideration ― Deal Value / TBV: 191% ― Deal Value / LTM Earnings: 12.9x ― Deal Value / 2026E Earnings: 12.7x ― Deal Value / 2027E Earnings + Fully-Phased Cost Savings: 6.7x(3) ― Market Premium: 22.7%(4) ― Core Deposit Premium: 11.4% ― 67.8% PEBO | 32.2% CBNK (diluted) ― Three board seats to be offered to current CBNK Board members ― Approvals of PEBO and CBNK shareholders ― Customary regulatory approvals ― Anticipated closing in 1H2027 ― Initial TBVPS dilution of 10.8%(5) with a TBVPS earnback period of less than 3 years ― Fully-phased 2027E EPS accretion of 19%(6) Consideration and Value Transaction Multiples(1)(2) Pro Forma Ownership Timing & Approvals Expected Financial Impact
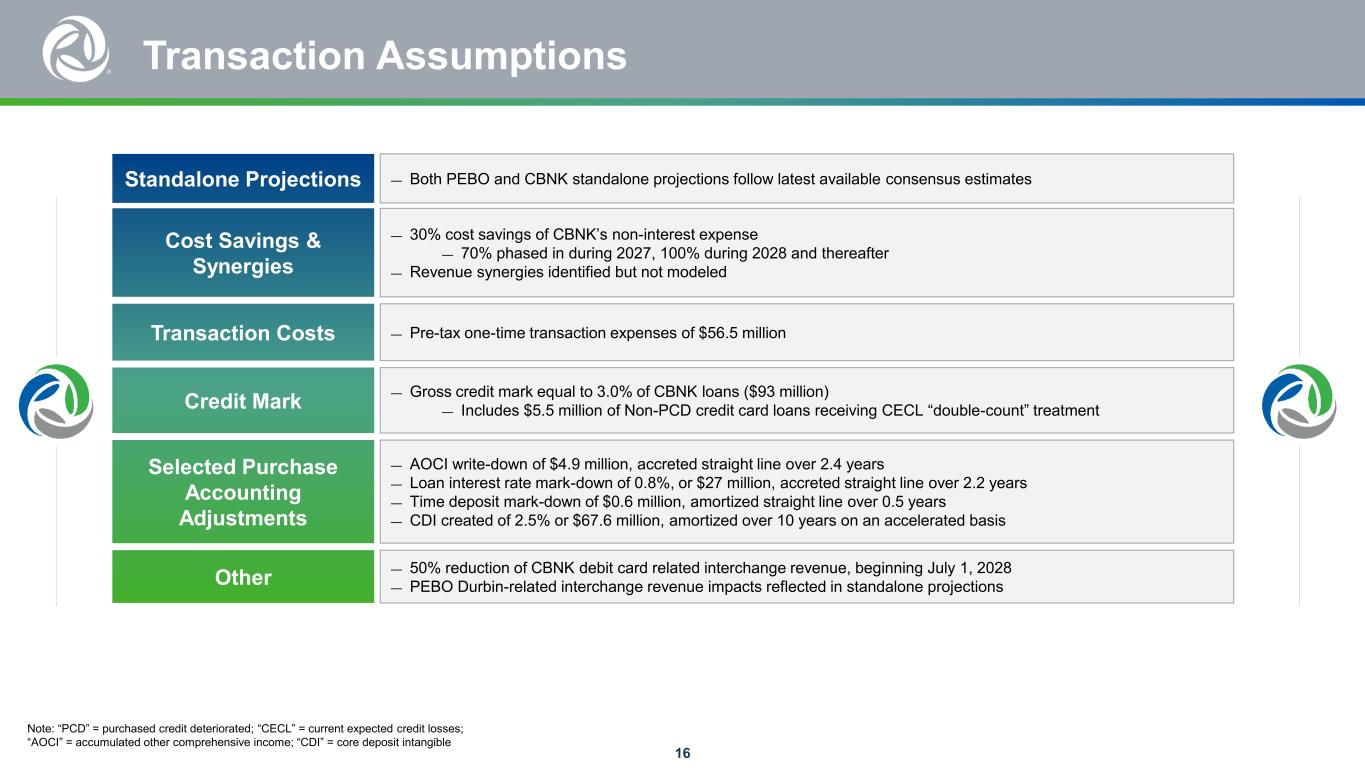
16 Transaction Assumptions Note: “PCD” = purchased credit deteriorated; “CECL” = current expected credit losses; “AOCI” = accumulated other comprehensive income; “CDI” = core deposit intangible ― 30% cost savings of CBNK’s non-interest expense ― 70% phased in during 2027, 100% during 2028 and thereafter ― Revenue synergies identified but not modeled ― Pre-tax one-time transaction expenses of $56.5 million ― Gross credit mark equal to 3.0% of CBNK loans ($93 million) ― Includes $5.5 million of Non-PCD credit card loans receiving CECL “double-count” treatment ― AOCI write-down of $4.9 million, accreted straight line over 2.4 years ― Loan interest rate mark-down of 0.8%, or $27 million, accreted straight line over 2.2 years ― Time deposit mark-down of $0.6 million, amortized straight line over 0.5 years ― CDI created of 2.5% or $67.6 million, amortized over 10 years on an accelerated basis ― 50% reduction of CBNK debit card related interchange revenue, beginning July 1, 2028 ― PEBO Durbin-related interchange revenue impacts reflected in standalone projections ― Both PEBO and CBNK standalone projections follow latest available consensus estimates Cost Savings & Synergies Transaction Costs Credit Mark Selected Purchase Accounting Adjustments Other Standalone Projections
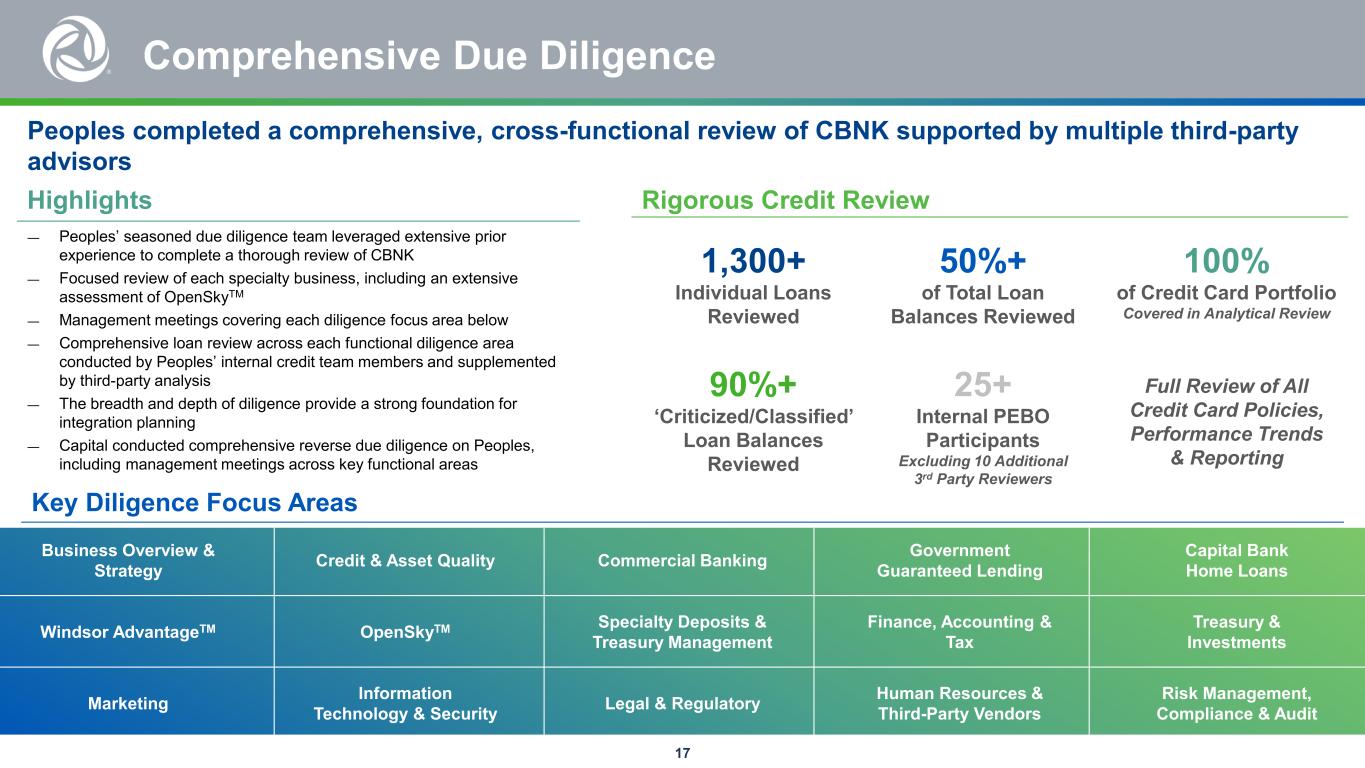
17 Comprehensive Due Diligence Highlights ― Peoples’ seasoned due diligence team leveraged extensive prior experience to complete a thorough review of CBNK ― Focused review of each specialty business, including an extensive assessment of OpenSkyTM ― Management meetings covering each diligence focus area below ― Comprehensive loan review across each functional diligence area conducted by Peoples’ internal credit team members and supplemented by third-party analysis ― The breadth and depth of diligence provide a strong foundation for integration planning ― Capital conducted comprehensive reverse due diligence on Peoples, including management meetings across key functional areas Rigorous Credit Review 50%+ of Total Loan Balances Reviewed 90%+ ‘Criticized/Classified’ Loan Balances Reviewed 25+ Internal PEBO Participants Excluding 10 Additional 3rd Party Reviewers 1,300+ Individual Loans Reviewed 100% of Credit Card Portfolio Covered in Analytical Review Full Review of All Credit Card Policies, Performance Trends & Reporting Business Overview & Strategy Credit & Asset Quality Commercial Banking Capital Bank Home Loans Windsor AdvantageTM OpenSkyTM Specialty Deposits & Treasury Management Human Resources & Third-Party Vendors Marketing Government Guaranteed Lending Risk Management, Compliance & Audit Finance, Accounting & Tax Treasury & Investments Information Technology & Security Legal & Regulatory Peoples completed a comprehensive, cross-functional review of CBNK supported by multiple third-party advisors Key Diligence Focus Areas
18 Transformational Combination Positions Peoples for Its Next Phase of Growth Combines Capital’s differentiated business lines and strong profitability with Peoples’ broad platform to enhance earnings diversification and profitability Expands Peoples’ presence in attractive markets while adding complementary nationwide specialty businesses Delivers significant earnings accretion and sufficient scale to efficiently cross $10 billion asset threshold Brings together relationship-focused franchises with aligned cultures, experienced management teams and a shared commitment to all stakeholders Creates meaningful growth opportunities by deepening relationships across the combined customer base
Appendix
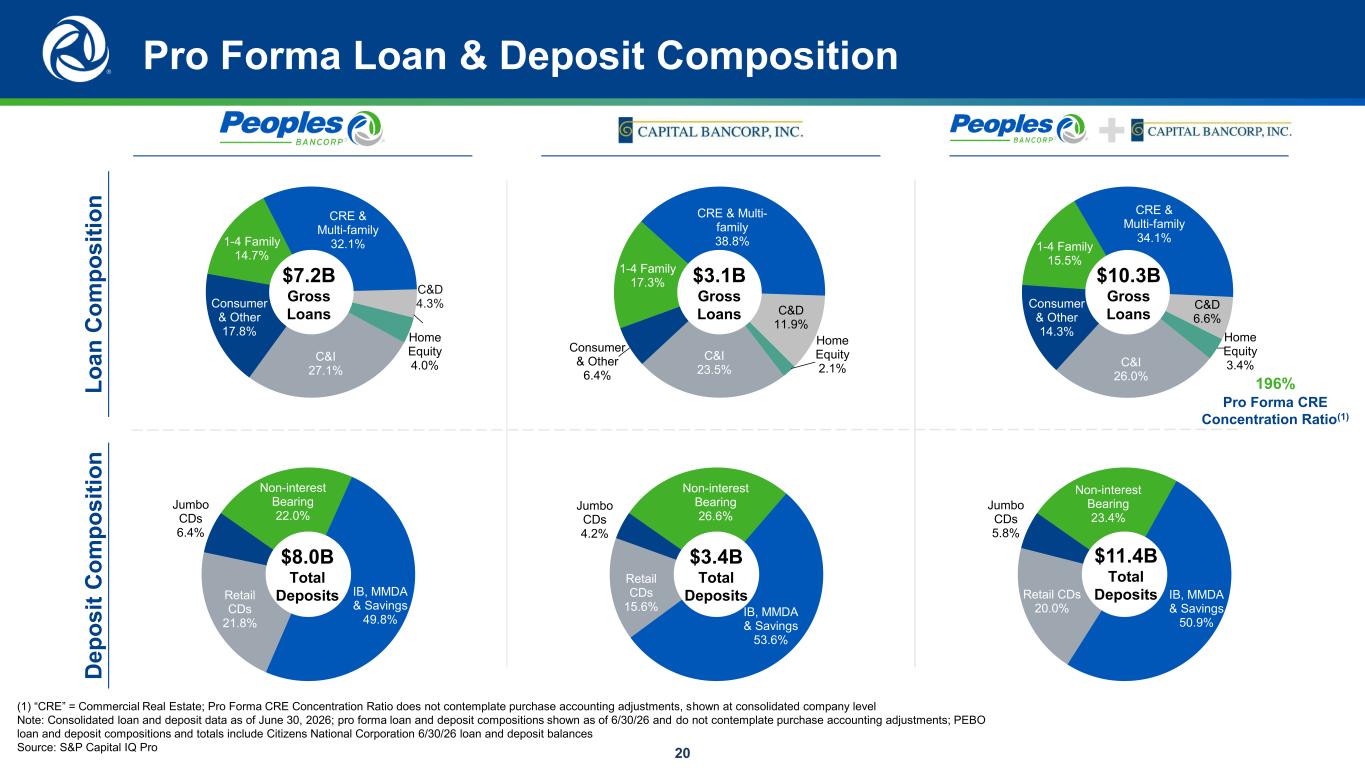
20 Pro Forma Loan & Deposit Composition Non-interest Bearing 22.0% IB, MMDA & Savings 49.8% Retail CDs 21.8% Jumbo CDs 6.4% Non-interest Bearing 26.6% IB, MMDA & Savings 53.6% Retail CDs 15.6% Jumbo CDs 4.2% Non-interest Bearing 23.4% IB, MMDA & Savings 50.9% Retail CDs 20.0% Jumbo CDs 5.8% 1-4 Family 14.7% CRE & Multi-family 32.1% C&D 4.3% Home Equity 4.0% C&I 27.1% Consumer & Other 17.8% 1-4 Family 17.3% CRE & Multi- family 38.8% C&D 11.9% Home Equity 2.1% C&I 23.5% Consumer & Other 6.4% 1-4 Family 15.5% CRE & Multi-family 34.1% C&D 6.6% Home Equity 3.4% C&I 26.0% Consumer & Other 14.3% L o a n C o m p o s it io n D e p o s it C o m p o s it io n $7.2B Gross Loans $3.1B Gross Loans $10.3B Gross Loans $8.0B Total Deposits $3.4B Total Deposits $11.4B Total Deposits (1) “CRE” = Commercial Real Estate; Pro Forma CRE Concentration Ratio does not contemplate purchase accounting adjustments, shown at consolidated company level Note: Consolidated loan and deposit data as of June 30, 2026; pro forma loan and deposit compositions shown as of 6/30/26 and do not contemplate purchase accounting adjustments; PEBO loan and deposit compositions and totals include Citizens National Corporation 6/30/26 loan and deposit balances Source: S&P Capital IQ Pro Pro Forma CRE Concentration Ratio(1) 196%
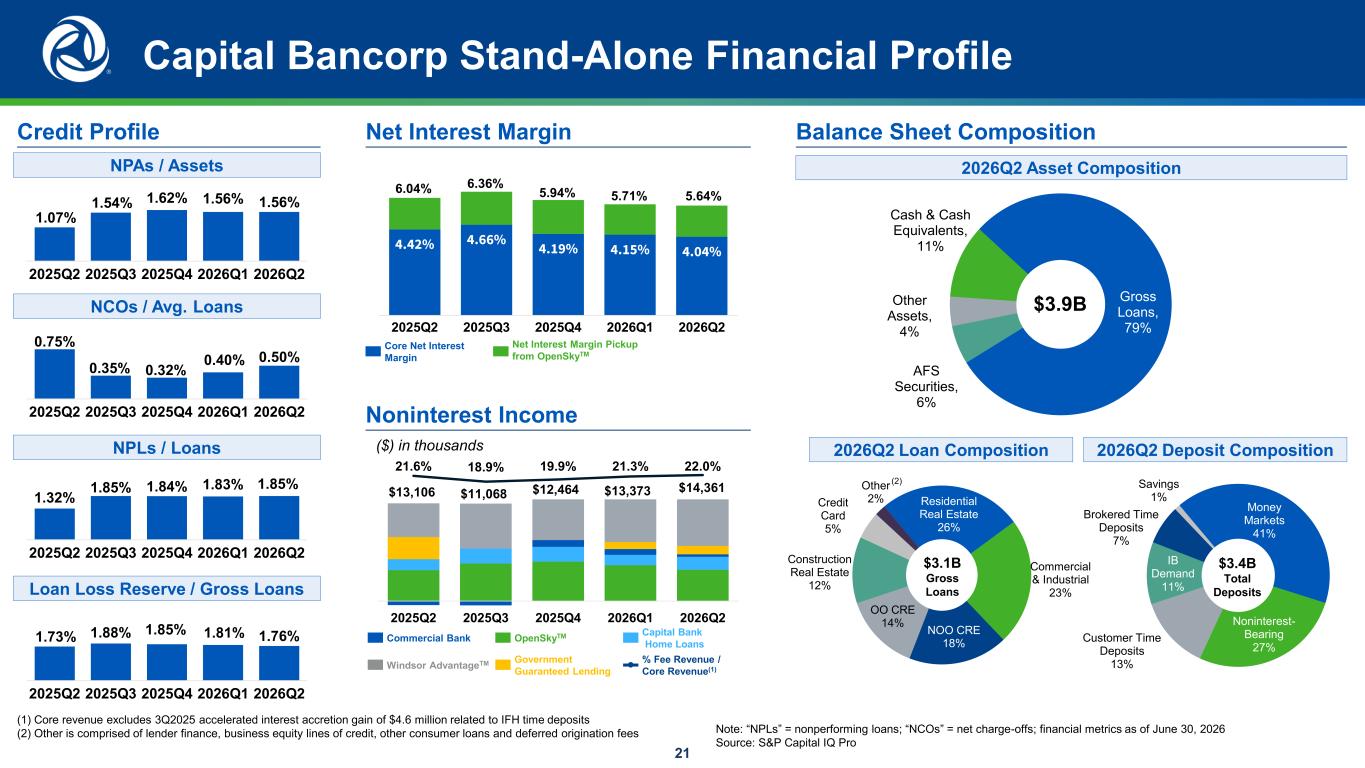
21 Capital Bancorp Stand-Alone Financial Profile Credit Profile Balance Sheet Composition NPAs / Assets 1.07% 1.54% 1.62% 1.56% 1.56% 2025Q2 2025Q3 2025Q4 2026Q1 2026Q2 NCOs / Avg. Loans 0.75% 0.35% 0.32% 0.40% 0.50% 2025Q2 2025Q3 2025Q4 2026Q1 2026Q2 NPLs / Loans 1.32% 1.85% 1.84% 1.83% 1.85% 2025Q2 2025Q3 2025Q4 2026Q1 2026Q2 Loan Loss Reserve / Gross Loans 1.73% 1.88% 1.85% 1.81% 1.76% 2025Q2 2025Q3 2025Q4 2026Q1 2026Q2 4.42% 4.66% 4.19% 4.15% 4.04% 2025Q2 2025Q3 2025Q4 2026Q1 2026Q2 21.6% 18.9% 19.9% 21.3% 22.0% 2025Q2 2025Q3 2025Q4 2026Q1 2026Q2 2026Q2 Asset Composition Cash & Cash Equivalents, 11% Gross Loans, 79% AFS Securities, 6% Other Assets, 4% 2026Q2 Loan Composition 2026Q2 Deposit Composition Residential Real Estate 26% Commercial & Industrial 23% NOO CRE 18% OO CRE 14% Construction Real Estate 12% Credit Card 5% Other 2% Money Markets 41% Noninterest- Bearing 27% Customer Time Deposits 13% IB Demand 11% Brokered Time Deposits 7% Savings 1% Core Net Interest Margin Net Interest Margin Pickup from OpenSkyTM Net Interest Margin Commercial Bank OpenSkyTM Capital Bank Home Loans Windsor AdvantageTM Government Guaranteed Lending Noninterest Income ($) in thousands (1) Core revenue excludes 3Q2025 accelerated interest accretion gain of $4.6 million related to IFH time deposits (2) Other is comprised of lender finance, business equity lines of credit, other consumer loans and deferred origination fees Note: “NPLs” = nonperforming loans; “NCOs” = net charge-offs; financial metrics as of June 30, 2026 Source: S&P Capital IQ Pro $13,106 $11,068 $12,464 $13,373 $14,361 (2) $3.9B % Fee Revenue / Core Revenue(1) 6.04% 6.36% 5.94% 5.71% 5.64% $3.1B Gross Loans $3.4B Total Deposits
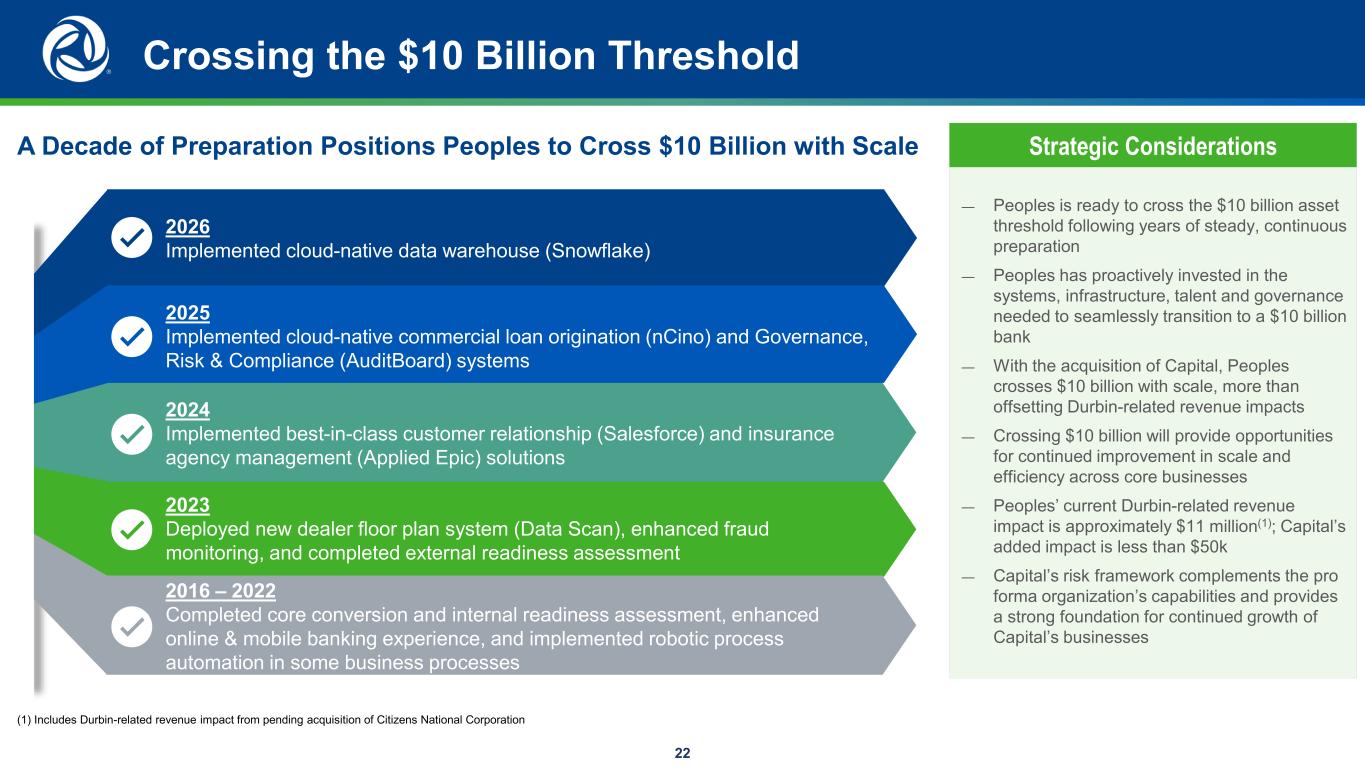
22 Crossing the $10 Billion Threshold A Decade of Preparation Positions Peoples to Cross $10 Billion with Scale 2026 Implemented cloud-native data warehouse (Snowflake) 2025 Implemented cloud-native commercial loan origination (nCino) and Governance, Risk & Compliance (AuditBoard) systems 2024 Implemented best-in-class customer relationship (Salesforce) and insurance agency management (Applied Epic) solutions 2023 Deployed new dealer floor plan system (Data Scan), enhanced fraud monitoring, and completed external readiness assessment 2016 – 2022 Completed core conversion and internal readiness assessment, enhanced online & mobile banking experience, and implemented robotic process automation in some business processes Strategic Considerations ― Peoples is ready to cross the $10 billion asset threshold following years of steady, continuous preparation ― Peoples has proactively invested in the systems, infrastructure, talent and governance needed to seamlessly transition to a $10 billion bank ― With the acquisition of Capital, Peoples crosses $10 billion with scale, more than offsetting Durbin-related revenue impacts ― Crossing $10 billion will provide opportunities for continued improvement in scale and efficiency across core businesses ― Peoples’ current Durbin-related revenue impact is approximately $11 million(1); Capital’s added impact is less than $50k ― Capital’s risk framework complements the pro forma organization’s capabilities and provides a strong foundation for continued growth of Capital’s businesses (1) Includes Durbin-related revenue impact from pending acquisition of Citizens National Corporation