Third Quarter 2026 Earnings Review United Bankshares, Inc. (UBSI) October 22, 2026 .2
This presentation and statements made by United Bankshares, Inc. (“UBSI”) and its management contain forward-looking statements within the meaning of Section 27A of the Securities Act of 1933 and Section 21E of the Securities Exchange Act of 1934. These forward-looking statements are intended to be covered by the safe harbor provisions for forward-looking statements contained in the Private Securities Litigation Reform Act of 1995. These forward-looking statements include, but are not limited to, statements about (i) projections of income, expenses, provision expense, capital structure and other financial information; (ii) UBSI’s plans, objectives, expectations and intentions and other statements contained in this presentation that are not historical facts; and (iii) other statements identified by words such as “expects,” “anticipates,” “intends,” “plans,” “believes,” “seeks,” “estimates,” “targets,” “projects,” “will,” or words of similar meaning generally intended to identify forward-looking statements. These forward-looking statements are based upon the current beliefs and expectations of the management of UBSI and are inherently subject to significant business, economic and competitive uncertainties and contingencies, many of which are beyond the control of UBSI. In addition, these forward-looking statements are subject to assumptions with respect to future business strategies and decisions that are subject to change. Actual results may differ materially from the anticipated results discussed in these forward-looking statements because of possible uncertainties. The following factors, among others, could cause actual results to differ materially from the anticipated results or other expectations expressed in the forward-looking statements: (1) the effects of and changes in trade and monetary and fiscal policies and laws, including the interest rate policies of the Federal Reserve and the trade and tariff policies; (2) general competitive, economic, political and market conditions and other factors that may affect future results of UBSI, including changes in asset quality and credit risk; the economic impact of oil and gas prices; the inability to sustain revenue and earnings growth; changes in interest rates and capital markets; inflation; customer borrowing, repayment, investment and deposit practices; the impact, extent and timing of technological changes; capital management activities; and other actions of the Federal Reserve Board and legislative and regulatory actions and reforms; (3) deposit attrition, client loss or revenue loss following completed mergers or acquisitions that may be greater than anticipated; (4) regulatory change risk resulting from new laws, rules, regulations, or accounting principles, including, without limitation, the possibility that regulatory agencies may require higher levels of capital above the current regulatory-mandated minimums and the possibility of changes in accounting standards, policies, principles and practices; (5) the cost and effects of cyber incidents or other failures, interruptions, or security breaches of UBSI’s systems and those of our customers or third-party providers; (6) competitive pressures on product pricing and services; (7) success, impact, and timing of UBSI’s business strategies, including market acceptance of any new products or services; (8) volatility and disruptions in global capital and credit markets; (9) operational, technological, cultural, regulatory, legal, credit and other risks associated with the exploration, consummation and integration of potential future acquisitions; (10) catastrophic events such as hurricanes, tornados, earthquakes, floods or other natural or human disasters, including public health crises and infectious disease outbreaks, as well as any government actions in response to such events; (11) geopolitical risk from terrorist activities and armed conflicts that may result in economic and supply disruptions, and loss of market and consumer confidence; (12) the risks of fluctuations in market prices for UBSI common stock that may or may not reflect economic condition or performance of UBSI; (13) the nature, extent, timing, and results of governmental actions, examinations, reviews, reforms, regulations, and interpretations; and (14) other factors that may affect future results of UBSI, as disclosed in UBSI’s Annual Report on Form 10-K, Quarterly Reports on Form 10-Q, and Current Reports on Form 8-K, filed by UBSI with the U.S. Securities and Exchange Commission (“SEC”) and available on the SEC’s website at http://www.sec.gov, any of which could cause actual results to differ materially from future results expressed, implied or otherwise anticipated by such forward-looking statements. UBSI cautions that the foregoing list of factors is not exclusive. UBSI does not undertake any obligation to update any forward-looking statement to reflect circumstances or events that occur after the date the forward-looking statements are made. FORWARD LOOKING STATEMENTS
Achieved Net Income of $128.7 million and Diluted Earnings Per Share of $0.94 Generated Return on Average Assets of 1.50%, Return on Average Shareholders' Equity of 9.24%, and Return on Average Tangible Common Equity* of 14.68% Returned capital through $52 million of common dividends and $99 million of share repurchases (repurchased 2.1 million shares during 3Q26) Net Interest Income (FTE) was a record $295.0 million and Net Interest Margin (FTE) increased from 3.81% to 3.86% Achieved period end annualized loan growth of ~7.5% and deposit growth of ~7.9% Announced de novo expansion into Florida with plans to establish a full-service banking office in Palm Beach Consistently ranked as one of the most trustworthy banks in America by Newsweek (ranked in the top 10 each year, including #1 in 2023) Quarterly dividend of $0.38 per share equates to a yield of ~3.3% (based upon recent prices). United has increased dividends to shareholders for 52 consecutive years Asset quality remains sound with Non-Performing Assets to Total Assets of 0.35% Strong expense control with an efficiency ratio of 48.21% Capital position remains robust and liquidity remains sound 3Q26 HIGHLIGHTS *Non-GAAP measure. Refer to appendix.
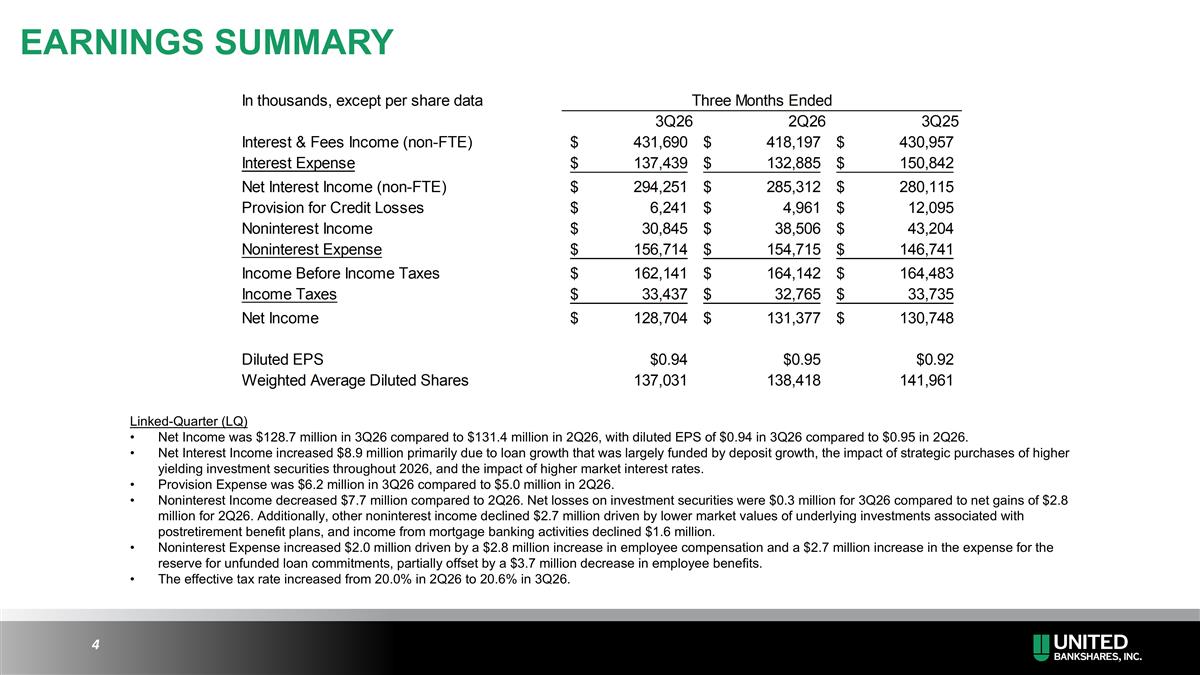
Linked-Quarter (LQ) Net Income was $128.7 million in 3Q26 compared to $131.4 million in 2Q26, with diluted EPS of $0.94 in 3Q26 compared to $0.95 in 2Q26. Net Interest Income increased $8.9 million primarily due to loan growth that was largely funded by deposit growth, the impact of strategic purchases of higher yielding investment securities throughout 2026, and the impact of higher market interest rates. Provision Expense was $6.2 million in 3Q26 compared to $5.0 million in 2Q26. Noninterest Income decreased $7.7 million compared to 2Q26. Net losses on investment securities were $0.3 million for 3Q26 compared to net gains of $2.8 million for 2Q26. Additionally, other noninterest income declined $2.7 million driven by lower market values of underlying investments associated with postretirement benefit plans, and income from mortgage banking activities declined $1.6 million. Noninterest Expense increased $2.0 million driven by a $2.8 million increase in employee compensation and a $2.7 million increase in the expense for the reserve for unfunded loan commitments, partially offset by a $3.7 million decrease in employee benefits. The effective tax rate increased from 20.0% in 2Q26 to 20.6% in 3Q26. EARNINGS SUMMARY
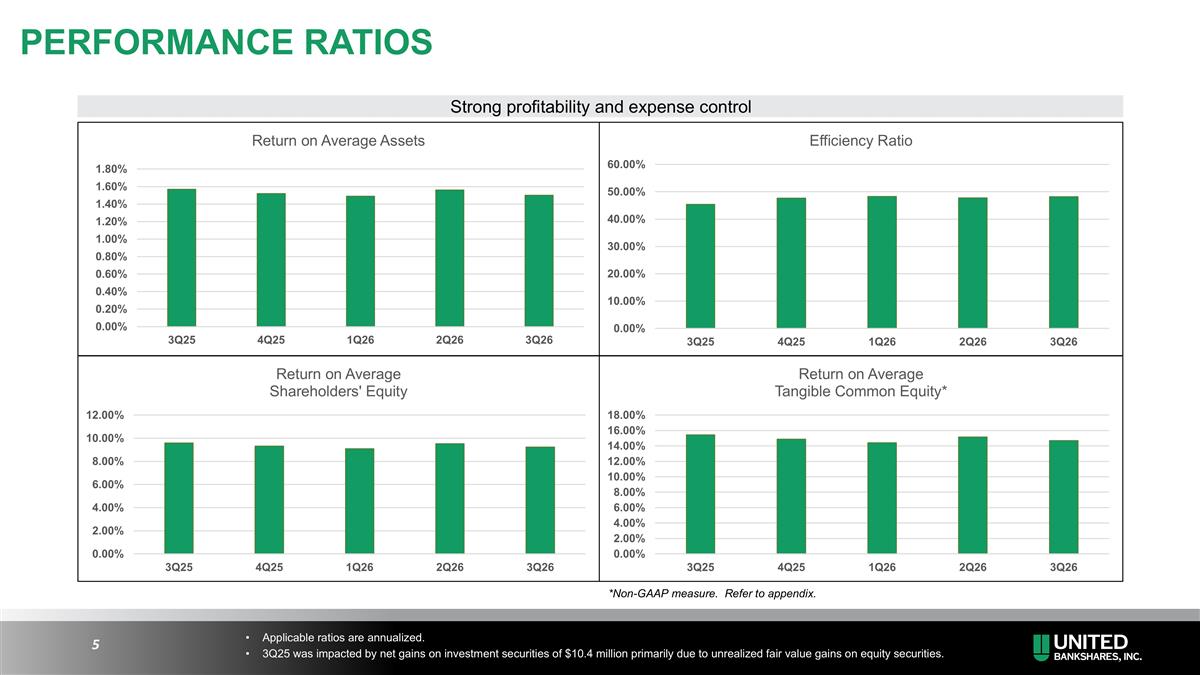
*Non-GAAP measure. Refer to appendix. Strong profitability and expense control PERFORMANCE RATIOS Applicable ratios are annualized. 3Q25 was impacted by net gains on investment securities of $10.4 million primarily due to unrealized fair value gains on equity securities.
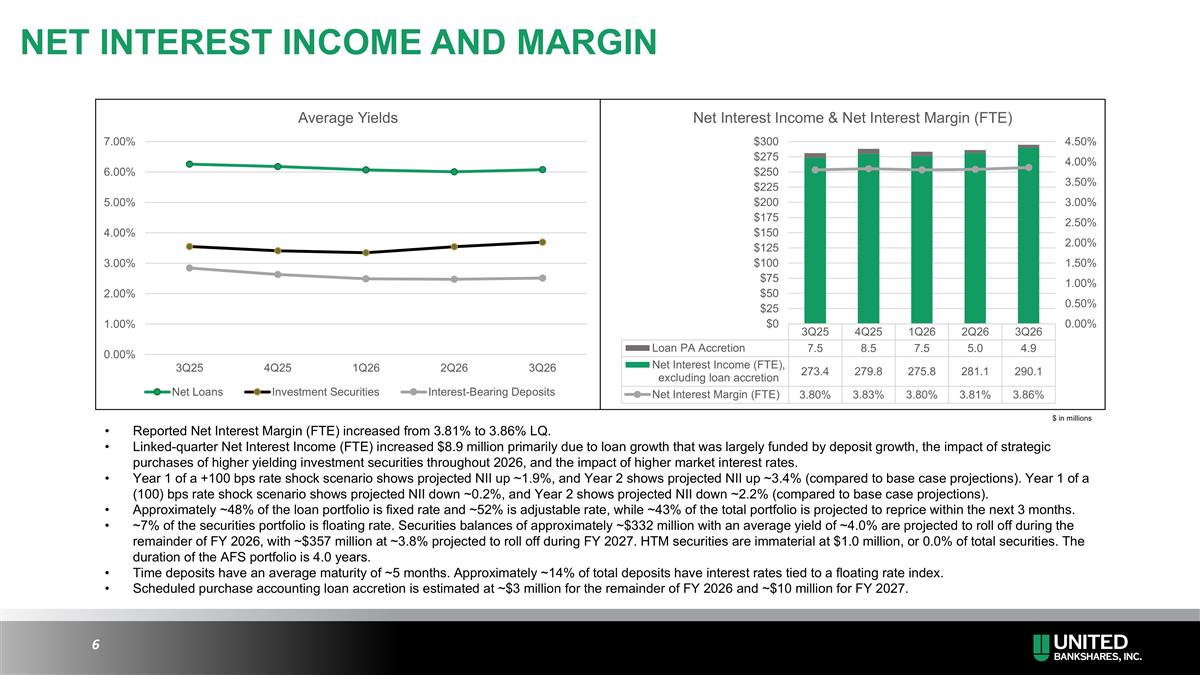
Reported Net Interest Margin (FTE) increased from 3.81% to 3.86% LQ. Linked-quarter Net Interest Income (FTE) increased $8.9 million primarily due to loan growth that was largely funded by deposit growth, the impact of strategic purchases of higher yielding investment securities throughout 2026, and the impact of higher market interest rates. Year 1 of a +100 bps rate shock scenario shows projected NII up ~1.9%, and Year 2 shows projected NII up ~3.4% (compared to base case projections). Year 1 of a (100) bps rate shock scenario shows projected NII down ~0.2%, and Year 2 shows projected NII down ~2.2% (compared to base case projections). Approximately ~48% of the loan portfolio is fixed rate and ~52% is adjustable rate, while ~43% of the total portfolio is projected to reprice within the next 3 months. ~7% of the securities portfolio is floating rate. Securities balances of approximately ~$332 million with an average yield of ~4.0% are projected to roll off during the remainder of FY 2026, with ~$357 million at ~3.8% projected to roll off during FY 2027. HTM securities are immaterial at $1.0 million, or 0.0% of total securities. The duration of the AFS portfolio is 4.0 years. Time deposits have an average maturity of ~5 months. Approximately ~14% of total deposits have interest rates tied to a floating rate index. Scheduled purchase accounting loan accretion is estimated at ~$3 million for the remainder of FY 2026 and ~$10 million for FY 2027. NET INTEREST INCOME AND MARGIN $ in millions
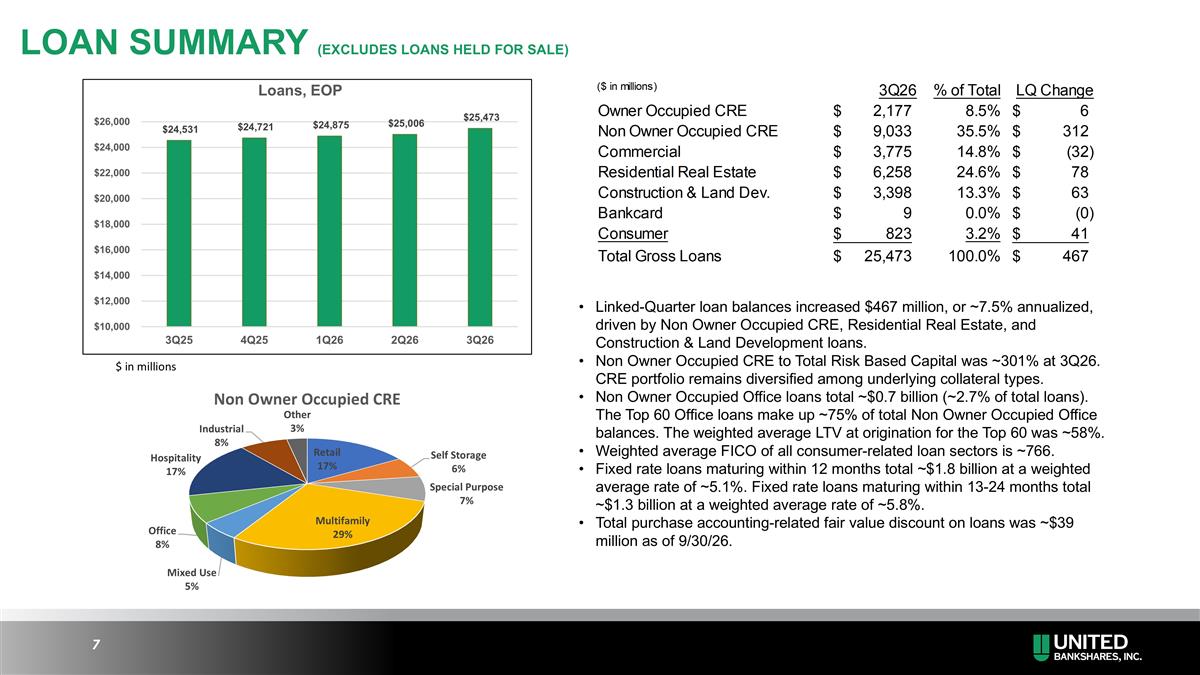
Linked-Quarter loan balances increased $467 million, or ~7.5% annualized, driven by Non Owner Occupied CRE, Residential Real Estate, and Construction & Land Development loans. Non Owner Occupied CRE to Total Risk Based Capital was ~301% at 3Q26. CRE portfolio remains diversified among underlying collateral types. Non Owner Occupied Office loans total ~$0.7 billion (~2.7% of total loans). The Top 60 Office loans make up ~75% of total Non Owner Occupied Office balances. The weighted average LTV at origination for the Top 60 was ~58%. Weighted average FICO of all consumer-related loan sectors is ~766. Fixed rate loans maturing within 12 months total ~$1.8 billion at a weighted average rate of ~5.1%. Fixed rate loans maturing within 13-24 months total ~$1.3 billion at a weighted average rate of ~5.8%. Total purchase accounting-related fair value discount on loans was ~$39 million as of 9/30/26. $ in millions LOAN SUMMARY (EXCLUDES LOANS HELD FOR SALE)
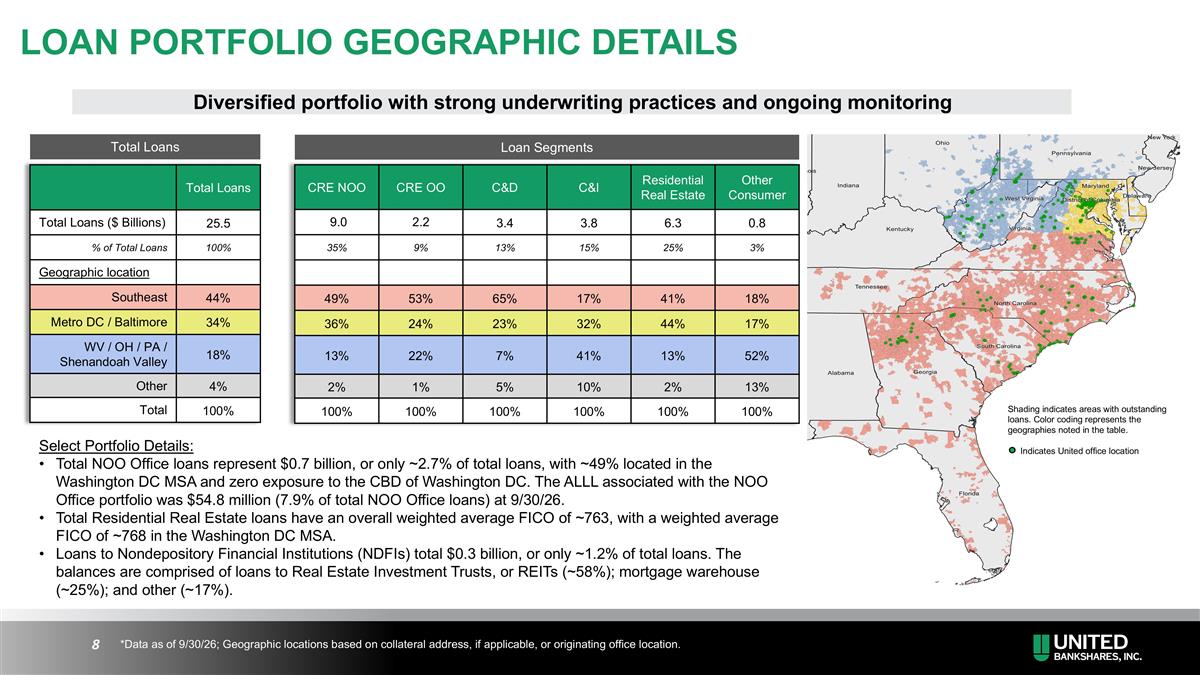
LOAN PORTFOLIO GEOGRAPHIC DETAILS Total Loans Total Loans ($ Billions) 25.5 % of Total Loans 100% Geographic location Southeast 44% Metro DC / Baltimore 34% WV / OH / PA / Shenandoah Valley 18% Other 4% Total 100% Diversified portfolio with strong underwriting practices and ongoing monitoring Select Portfolio Details: Total NOO Office loans represent $0.7 billion, or only ~2.7% of total loans, with ~49% located in the Washington DC MSA and zero exposure to the CBD of Washington DC. The ALLL associated with the NOO Office portfolio was $54.8 million (7.9% of total NOO Office loans) at 9/30/26. Total Residential Real Estate loans have an overall weighted average FICO of ~763, with a weighted average FICO of ~768 in the Washington DC MSA. Loans to Nondepository Financial Institutions (NDFIs) total $0.3 billion, or only ~1.2% of total loans. The balances are comprised of loans to Real Estate Investment Trusts, or REITs (~58%); mortgage warehouse (~25%); and other (~17%). *Data as of 9/30/26; Geographic locations based on collateral address, if applicable, or originating office location. CRE NOO CRE OO C&D C&I Residential Real Estate Other Consumer 9.0 2.2 3.4 3.8 6.3 0.8 35% 9% 13% 15% 25% 3% 49% 53% 65% 17% 41% 18% 36% 24% 23% 32% 44% 17% 13% 22% 7% 41% 13% 52% 2% 1% 5% 10% 2% 13% 100% 100% 100% 100% 100% 100% Total Loans Loan Segments Shading indicates areas with outstanding loans. Color coding represents the geographies noted in the table. Indicates United office location
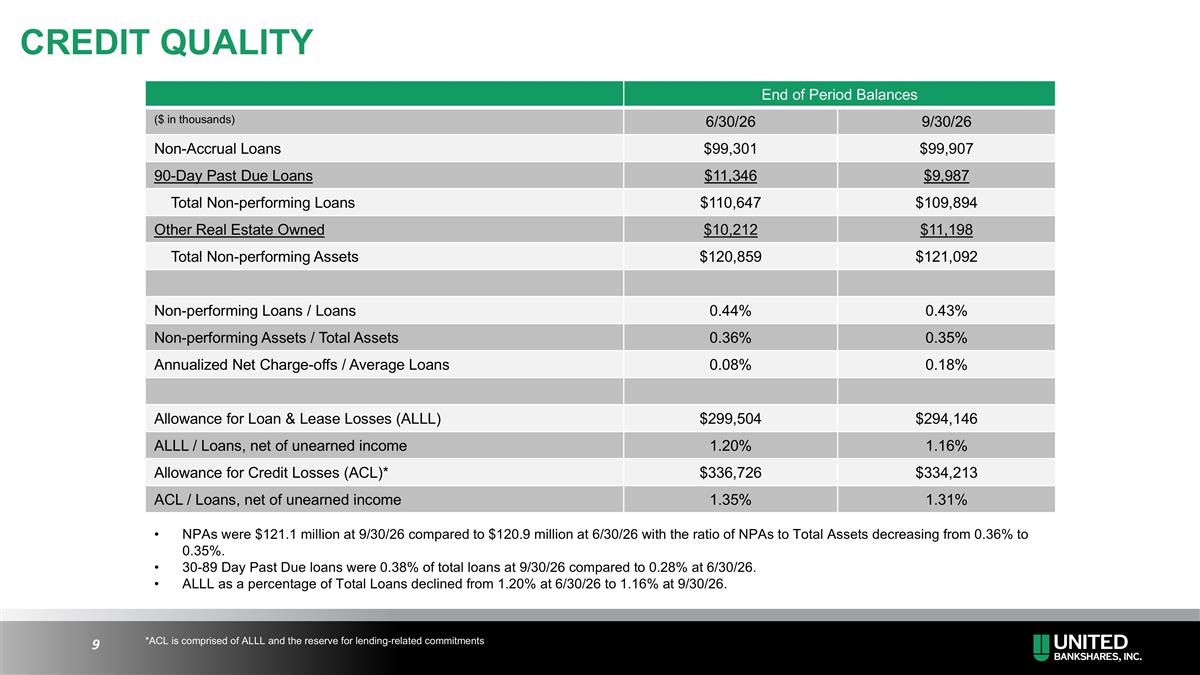
End of Period Balances ($ in thousands) 6/30/26 9/30/26 Non-Accrual Loans $99,301 $99,907 90-Day Past Due Loans $11,346 $9,987 Total Non-performing Loans $110,647 $109,894 Other Real Estate Owned $10,212 $11,198 Total Non-performing Assets $120,859 $121,092 Non-performing Loans / Loans 0.44% 0.43% Non-performing Assets / Total Assets 0.36% 0.35% Annualized Net Charge-offs / Average Loans 0.08% 0.18% Allowance for Loan & Lease Losses (ALLL) $299,504 $294,146 ALLL / Loans, net of unearned income 1.20% 1.16% Allowance for Credit Losses (ACL)* $336,726 $334,213 ACL / Loans, net of unearned income 1.35% 1.31% NPAs were $121.1 million at 9/30/26 compared to $120.9 million at 6/30/26 with the ratio of NPAs to Total Assets decreasing from 0.36% to 0.35%. 30-89 Day Past Due loans were 0.38% of total loans at 9/30/26 compared to 0.28% at 6/30/26. ALLL as a percentage of Total Loans declined from 1.20% at 6/30/26 to 1.16% at 9/30/26. *ACL is comprised of ALLL and the reserve for lending-related commitments CREDIT QUALITY
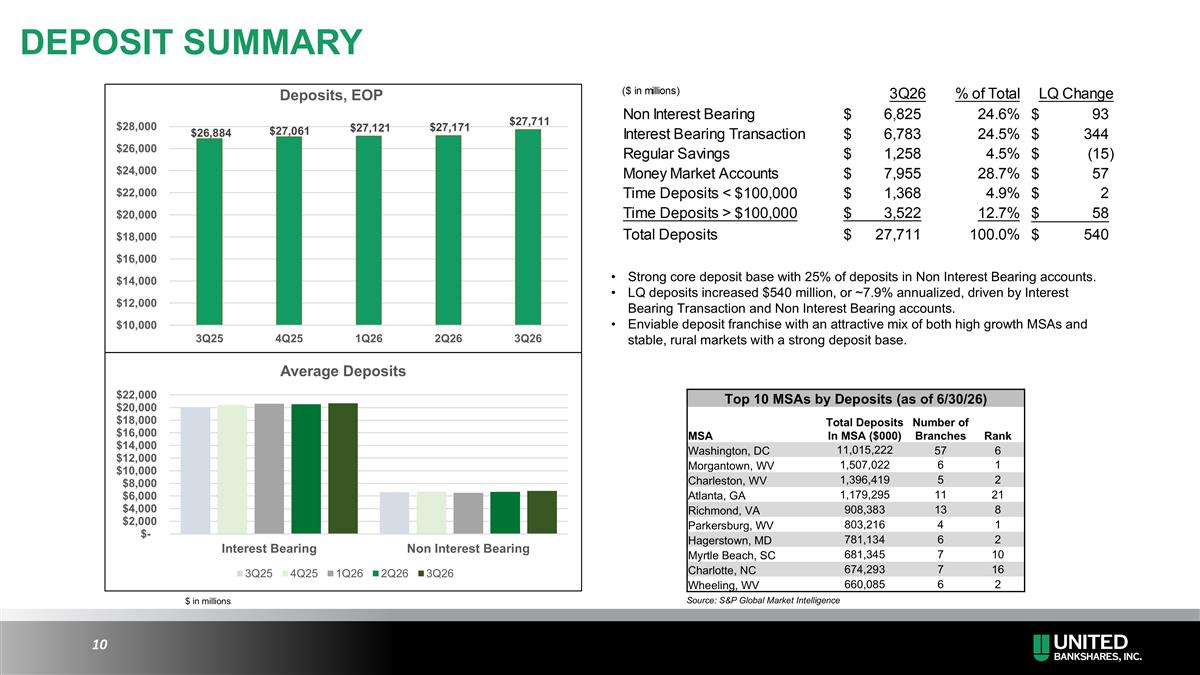
Strong core deposit base with 25% of deposits in Non Interest Bearing accounts. LQ deposits increased $540 million, or ~7.9% annualized, driven by Interest Bearing Transaction and Non Interest Bearing accounts. Enviable deposit franchise with an attractive mix of both high growth MSAs and stable, rural markets with a strong deposit base. $ in millions Source: S&P Global Market Intelligence DEPOSIT SUMMARY Top 10 MSAs by Deposits (as of 6/30/26) MSA Total Deposits In MSA ($000) Number of Branches Rank Washington, DC 11,015,222 57 6 Morgantown, WV 1,507,022 6 1 Charleston, WV 1,396,419 5 2 Atlanta, GA 1,179,295 11 21 Richmond, VA 908,383 13 8 Parkersburg, WV 803,216 4 1 Hagerstown, MD 781,134 6 2 Myrtle Beach, SC 681,345 7 10 Charlotte, NC 674,293 7 16 Wheeling, WV 660,085 6 2
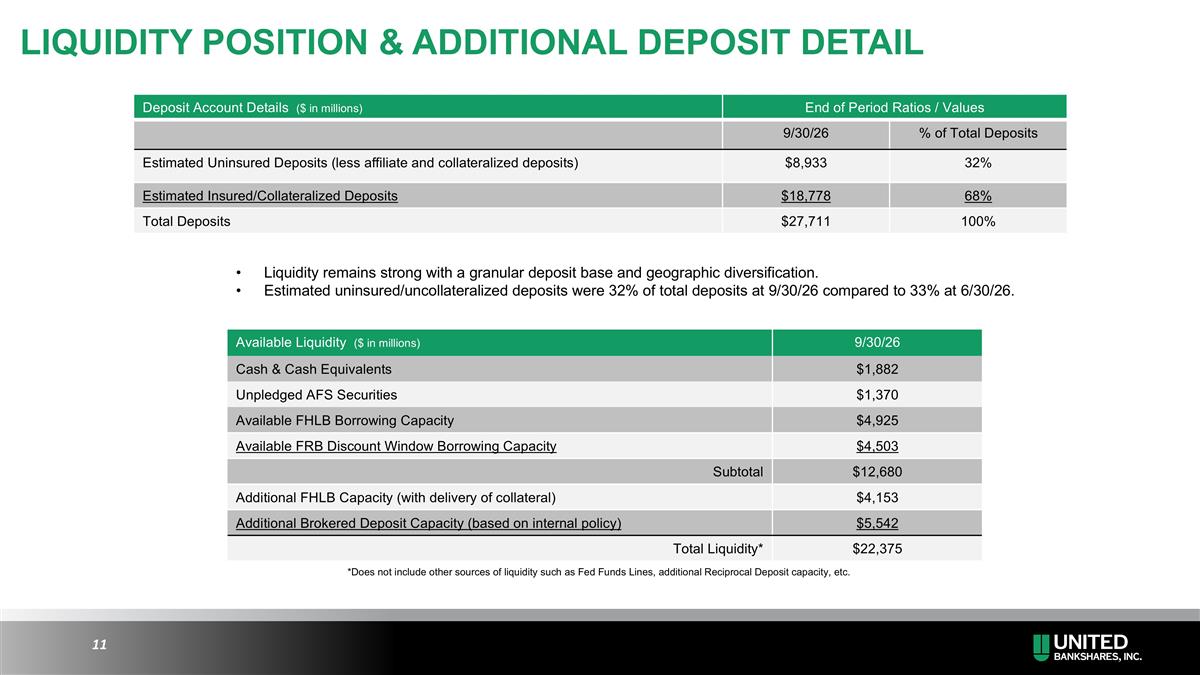
Deposit Account Details ($ in millions) End of Period Ratios / Values 9/30/26 % of Total Deposits Estimated Uninsured Deposits (less affiliate and collateralized deposits) $8,933 32% Estimated Insured/Collateralized Deposits $18,778 68% Total Deposits $27,711 100% *Does not include other sources of liquidity such as Fed Funds Lines, additional Reciprocal Deposit capacity, etc. Available Liquidity ($ in millions) 9/30/26 Cash & Cash Equivalents $1,882 Unpledged AFS Securities $1,370 Available FHLB Borrowing Capacity $4,925 Available FRB Discount Window Borrowing Capacity $4,503 Subtotal $12,680 Additional FHLB Capacity (with delivery of collateral) $4,153 Additional Brokered Deposit Capacity (based on internal policy) $5,542 Total Liquidity* $22,375 Liquidity remains strong with a granular deposit base and geographic diversification. Estimated uninsured/uncollateralized deposits were 32% of total deposits at 9/30/26 compared to 33% at 6/30/26. LIQUIDITY POSITION & ADDITIONAL DEPOSIT DETAIL
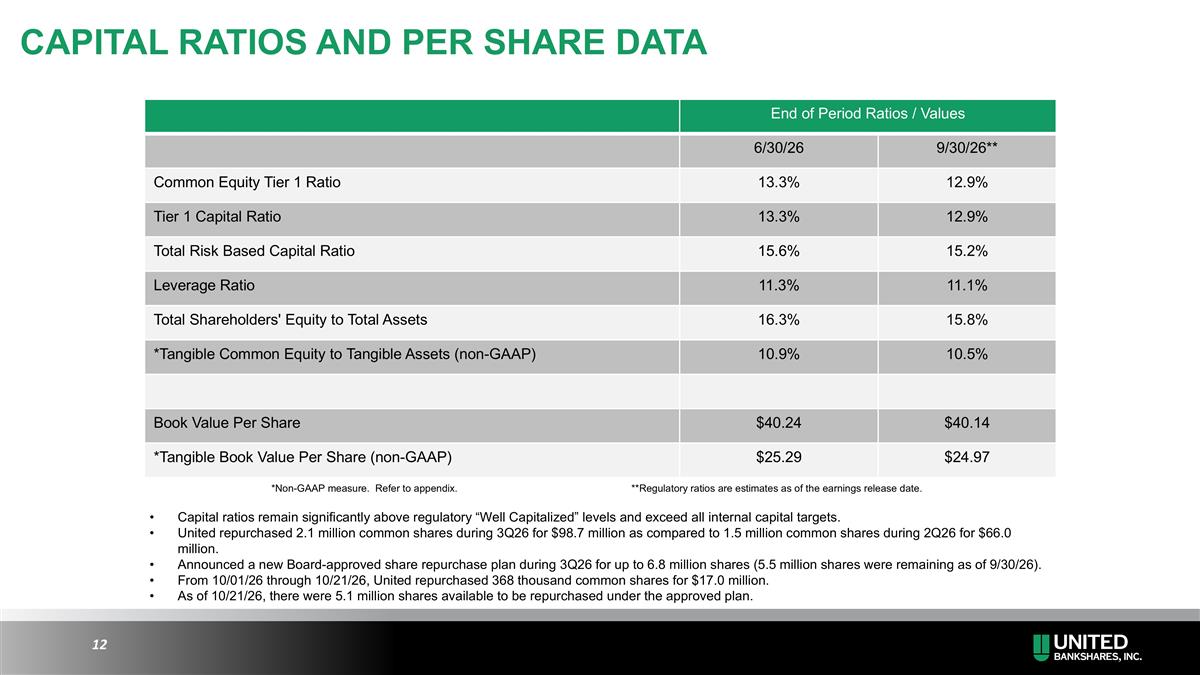
End of Period Ratios / Values 6/30/26 9/30/26** Common Equity Tier 1 Ratio 13.3% 12.9% Tier 1 Capital Ratio 13.3% 12.9% Total Risk Based Capital Ratio 15.6% 15.2% Leverage Ratio 11.3% 11.1% Total Shareholders' Equity to Total Assets 16.3% 15.8% *Tangible Common Equity to Tangible Assets (non-GAAP) 10.9% 10.5% Book Value Per Share $40.24 $40.14 *Tangible Book Value Per Share (non-GAAP) $25.29 $24.97 Capital ratios remain significantly above regulatory “Well Capitalized” levels and exceed all internal capital targets. United repurchased 2.1 million common shares during 3Q26 for $98.7 million as compared to 1.5 million common shares during 2Q26 for $66.0 million. Announced a new Board-approved share repurchase plan during 3Q26 for up to 6.8 million shares (5.5 million shares were remaining as of 9/30/26). From 10/01/26 through 10/21/26, United repurchased 368 thousand common shares for $17.0 million. As of 10/21/26, there were 5.1 million shares available to be repurchased under the approved plan. *Non-GAAP measure. Refer to appendix. **Regulatory ratios are estimates as of the earnings release date. CAPITAL RATIOS AND PER SHARE DATA
Select guidance is being provided for 2026. Our outlook may change if the expectations for these items vary from current expectations. Balance Sheet: Expect loan and deposit growth rates to be in the mid single digits for 4Q26 (annualized). Loan pipelines remain relatively strong. Expect investment portfolio balances to increase by mid single digits for 4Q26 (annualized). Net Interest Income: Net interest income (non-FTE) expected to be in the range of $296 million to $301 million for 4Q26, and $1.158 billion to $1.163 billion for 2026 (assumes one 25 bps rate increase in 4Q26). Loan purchase accounting accretion is currently estimated at $5 million for 4Q26, and $22 million for FY 2026 (includes scheduled and estimated accelerated accretion). Provision Expense: Asset quality remains sound. Provision expense will be dependent on the future economic outlook, future credit trends within United’s portfolio, and loan growth. Expect our credit performance to outperform the industry. Current planning assumption for provision expense is $8.5 million for 4Q26, and $27.5 million for FY 2026. Noninterest Income: Expect noninterest income to be in the range of $31 million to $33 million for 4Q26, and $134 million to $136 million for FY 2026. Mortgage banking revenue will be subject to industry trends. Noninterest Expense: Expect noninterest expense to be in the range of $155 million to $159 million for 4Q26 and $619 million to $623 million for FY 2026. Effective Tax Rate: Estimated at approximately ~20.5% for 4Q26. Capital: Expect to be active in the buyback in 4Q26 (market dependent). United’s capital position remains robust. 2026 OUTLOOK
Premier Mid-Atlantic and Southeast franchise with an attractive mix of high growth MSAs and smaller stable markets with a strong deposit base Consistently high-performing company with a culture of disciplined risk management and expense control 52 consecutive years of dividend increases evidences United’s strong profitability, solid asset quality, and sound capital management over a very long period of time Experienced management team with a proven track record of execution Committed to our mission of excellence in service to our employees, our customers, our shareholders and our communities Attractive valuation with a current Price-to-Earnings Ratio of ~12.6x (based upon median 2026 street consensus estimate of $3.70 per Bloomberg) INVESTMENT THESIS
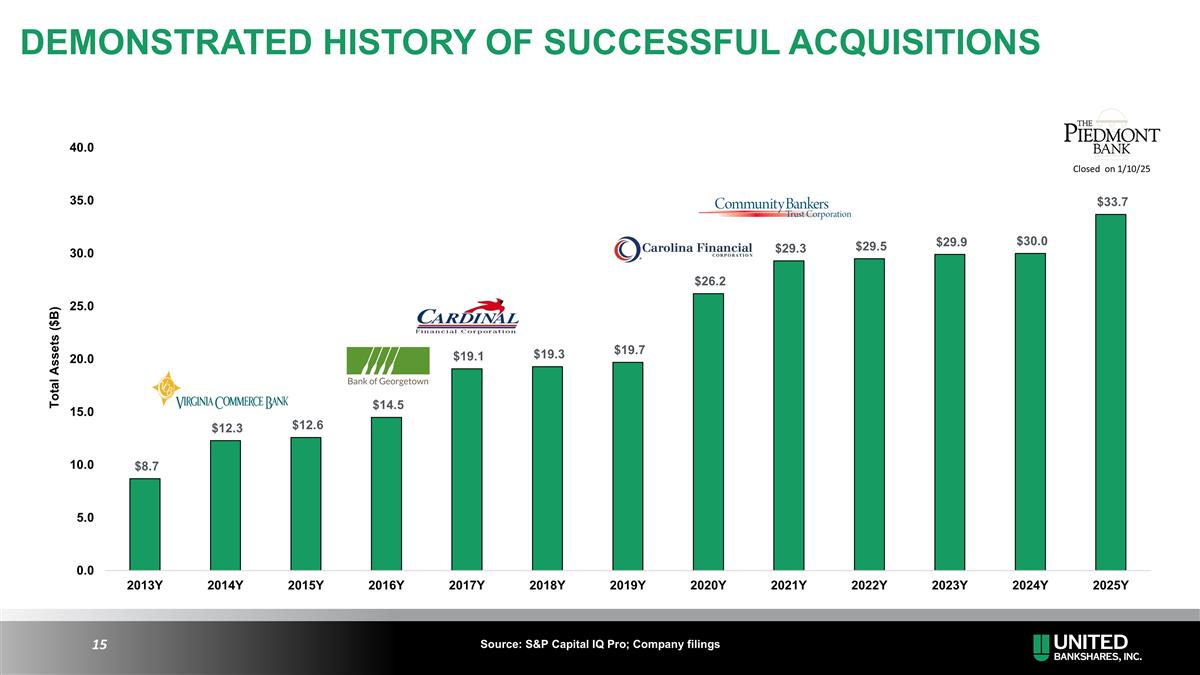
Source: S&P Capital IQ Pro; Company filings DEMONSTRATED HISTORY OF SUCCESSFUL ACQUISITIONS Closed on 1/10/25
APPENDIX
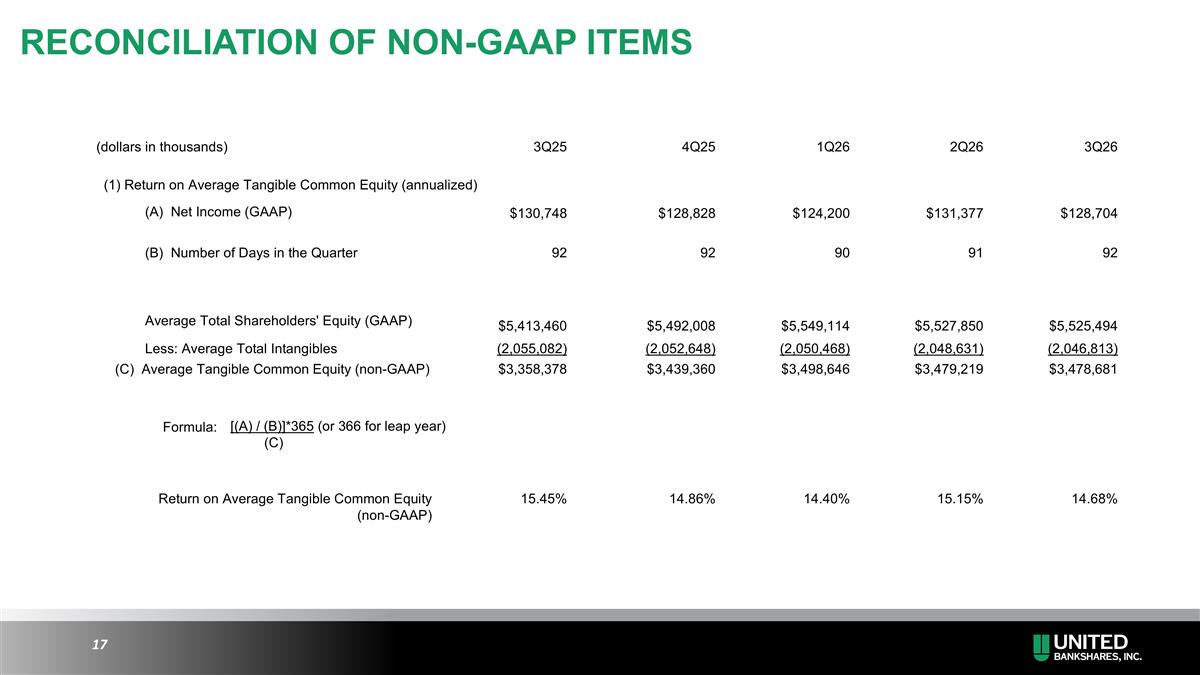
(dollars in thousands) 3Q25 4Q25 1Q26 2Q26 3Q26 (1) Return on Average Tangible Common Equity (annualized) (A) Net Income (GAAP) $130,748 $128,828 $124,200 $131,377 $128,704 (B) Number of Days in the Quarter 92 92 90 91 92 Average Total Shareholders' Equity (GAAP) $5,413,460 $5,492,008 $5,549,114 $5,527,850 $5,525,494 Less: Average Total Intangibles (2,055,082) (2,052,648) (2,050,468) (2,048,631) (2,046,813) (C) Average Tangible Common Equity (non-GAAP) $3,358,378 $3,439,360 $3,498,646 $3,479,219 $3,478,681 Formula: [(A) / (B)]*365 (or 366 for leap year) (C) Return on Average Tangible Common Equity (non-GAAP) 15.45% 14.86% 14.40% 15.15% 14.68% RECONCILIATION OF NON-GAAP ITEMS
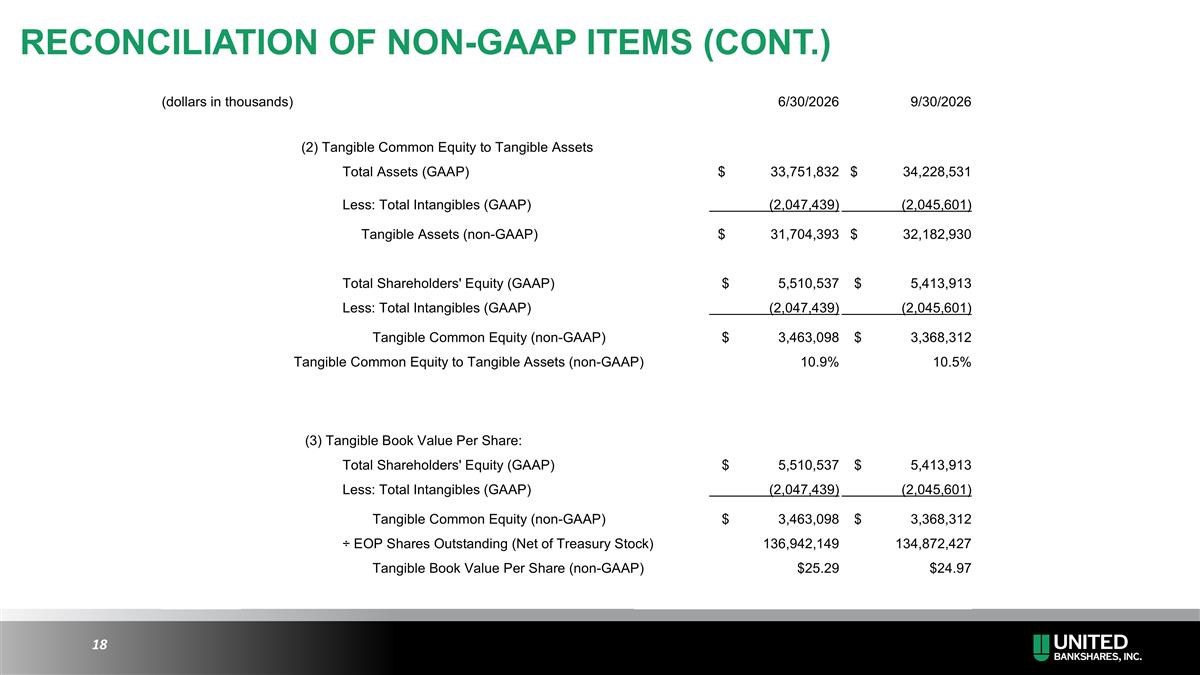
(dollars in thousands) 6/30/2026 9/30/2026 (2) Tangible Common Equity to Tangible Assets Total Assets (GAAP) $ 33,751,832 $ 34,228,531 Less: Total Intangibles (GAAP) (2,047,439) (2,045,601) Tangible Assets (non-GAAP) $ 31,704,393 $ 32,182,930 Total Shareholders' Equity (GAAP) $ 5,510,537 $ 5,413,913 Less: Total Intangibles (GAAP) (2,047,439) (2,045,601) Tangible Common Equity (non-GAAP) $ 3,463,098 $ 3,368,312 Tangible Common Equity to Tangible Assets (non-GAAP) 10.9% 10.5% (3) Tangible Book Value Per Share: Total Shareholders' Equity (GAAP) $ 5,510,537 $ 5,413,913 Less: Total Intangibles (GAAP) (2,047,439) (2,045,601) Tangible Common Equity (non-GAAP) $ 3,463,098 $ 3,368,312 ÷ EOP Shares Outstanding (Net of Treasury Stock) 136,942,149 134,872,427 Tangible Book Value Per Share (non-GAAP) $25.29 $24.97 RECONCILIATION OF NON-GAAP ITEMS (CONT.)