.2
October 30, 2026 Q3 2026 Results 1 Q3 2026 Results Webcast 30OCT26
Vice President, Investor Relations Louis Tonelli 2 Q3 2026 Results Webcast 30OCT26
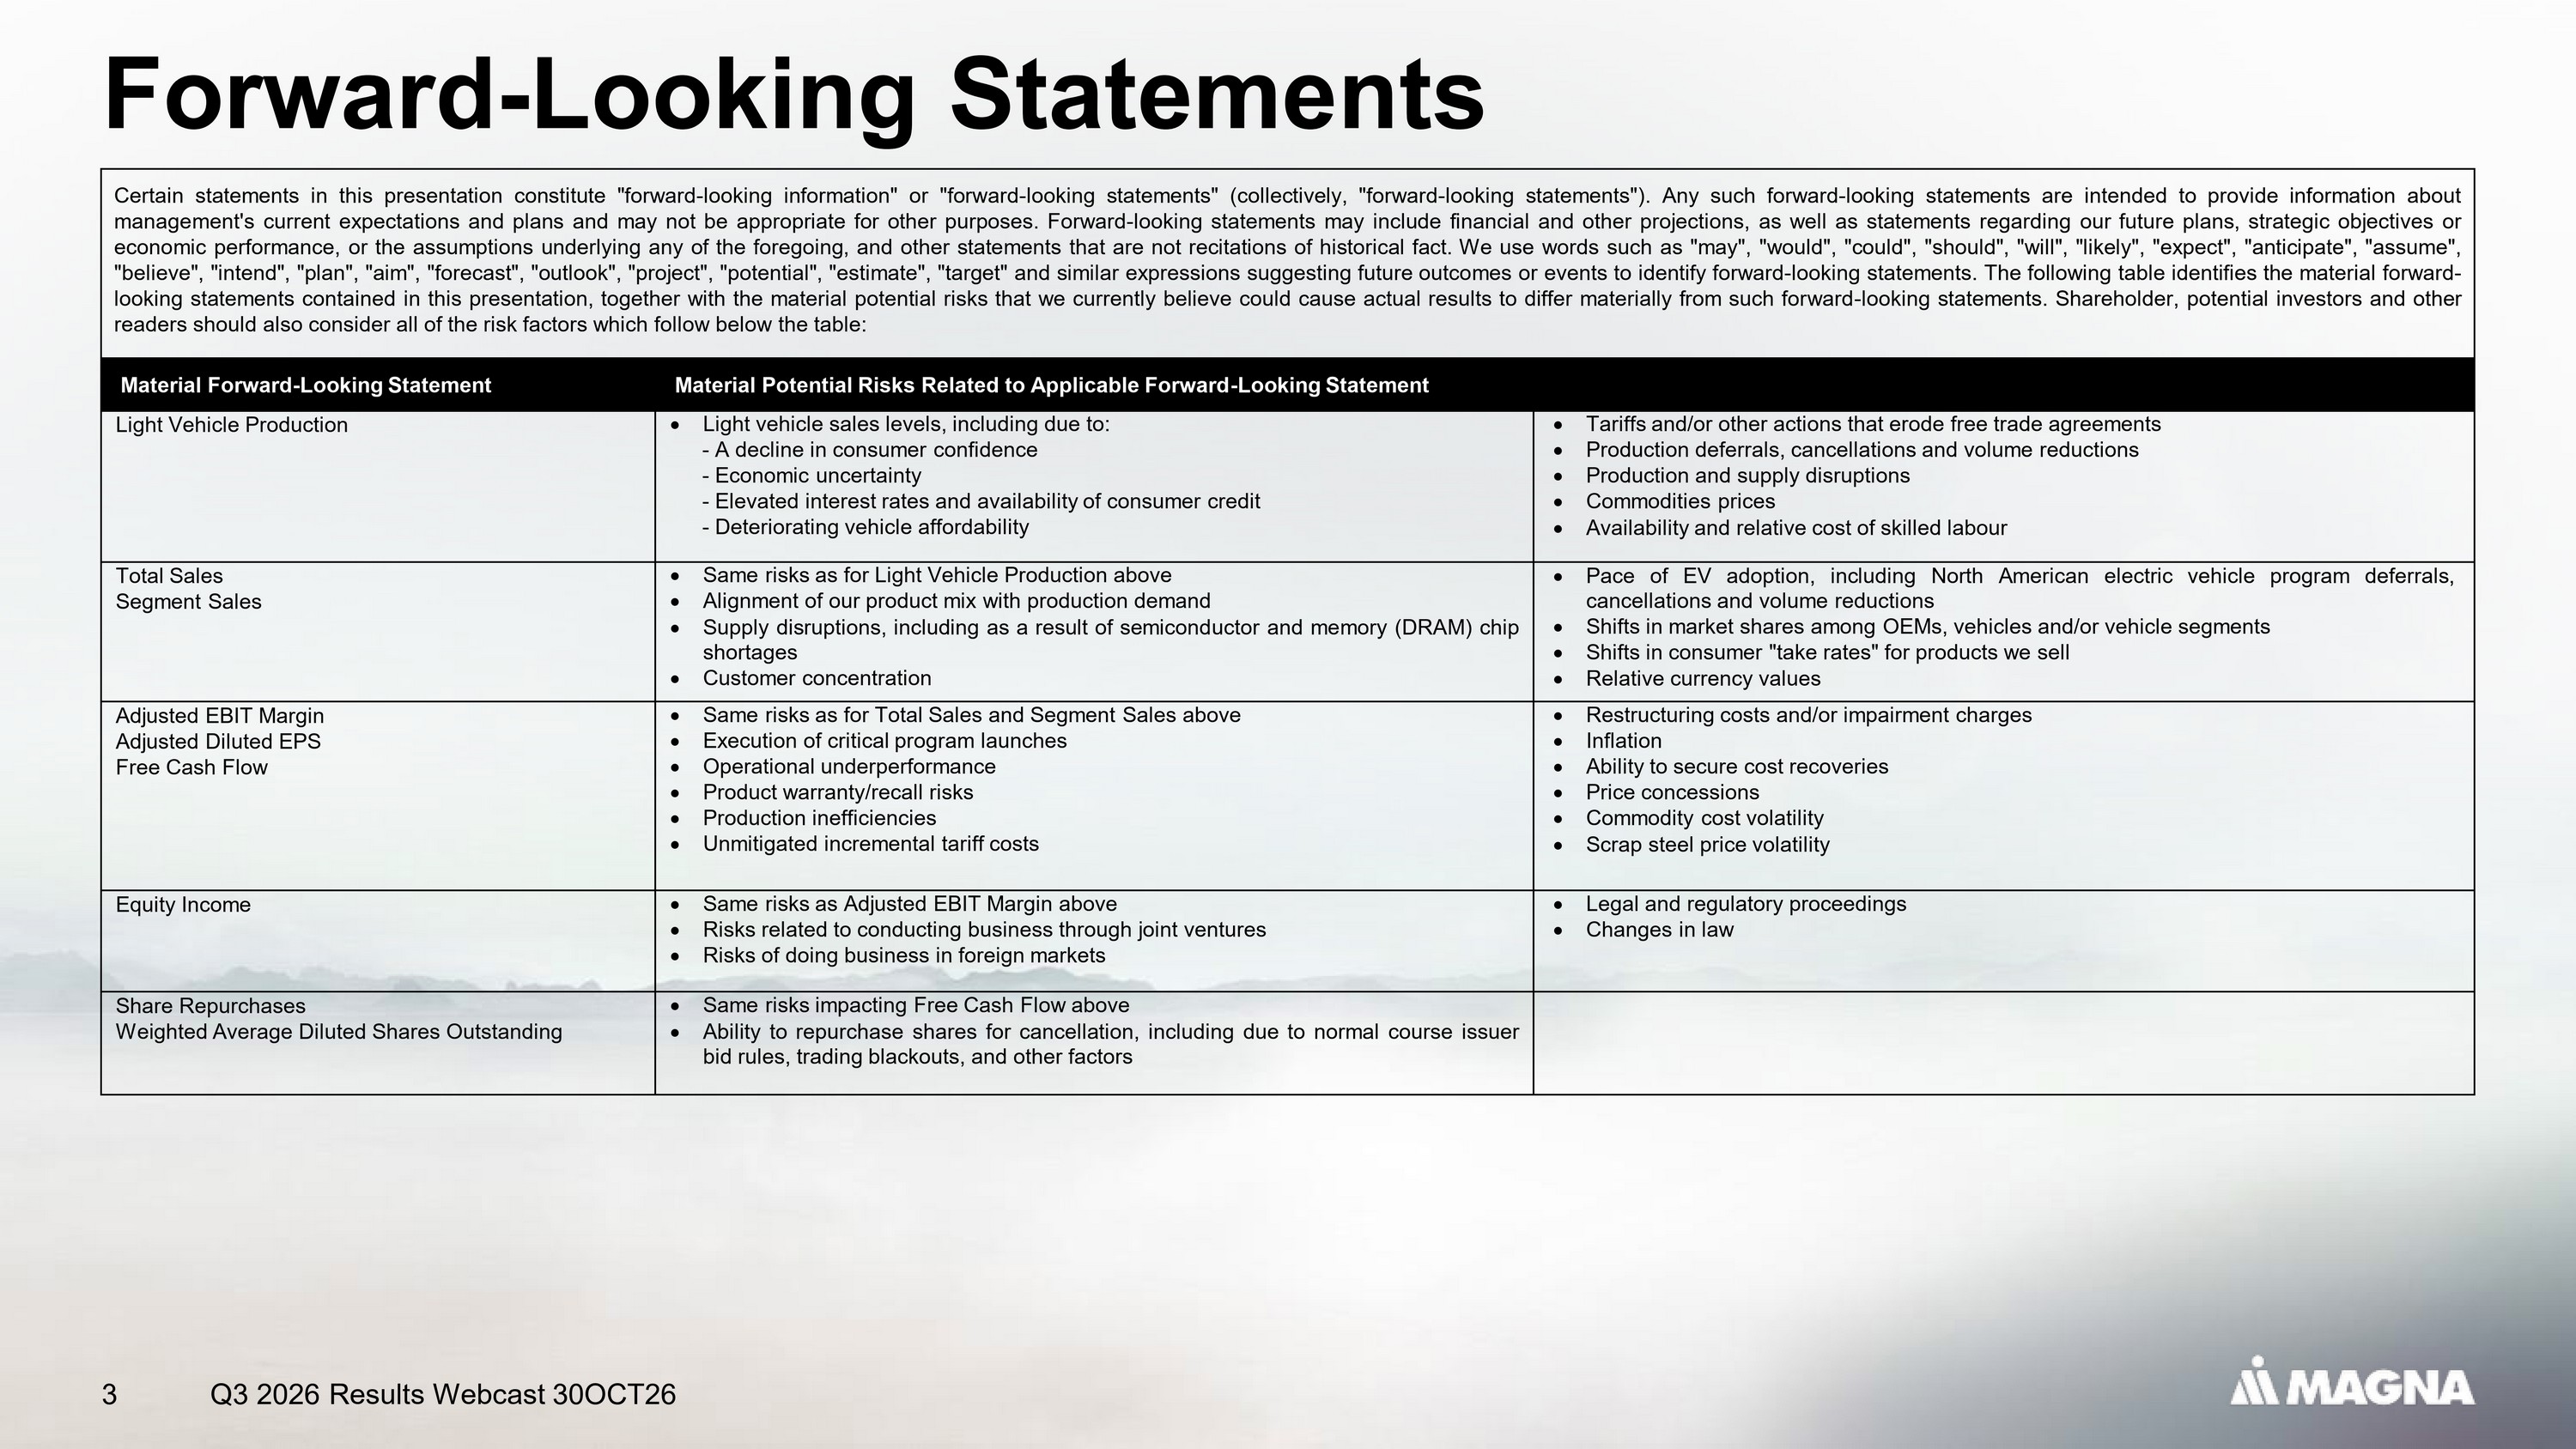
Q3 2026 Results Webcast 30OCT26 3 Forward - Looking Statements Certain statements in this presentation constitute "forward - looking information" or "forward - looking statements" (collectively, "forward - looking statements") . Any such forward - looking statements are intended to provide information about management's current expectations and plans and may not be appropriate for other purposes . Forward - looking statements may include financial and other projections, as well as statements regarding our future plans, strategic objectives or economic performance, or the assumptions underlying any of the foregoing, and other statements that are not recitations of historical fact . We use words such as "may", "would", "could", "should", "will", "likely", "expect", "anticipate", "assume", "believe", "intend", "plan", "aim", "forecast", "outlook", "project", "potential", "estimate", "target" and similar expressions suggesting future outcomes or events to identify forward - looking statements . The following table identifies the material forward - looking statements contained in this presentation, together with the material potential risks that we currently believe could cause actual results to differ materially from such forward - looking statements . Shareholder, potential investors and other readers should also consider all of the risk factors which follow below the table : Material Potential Risks Related to Applicable Forward - Looking Statement Material Forward - Looking Statement Tariffs and/or other actions that erode free trade agreements Production deferrals, cancellations and volume reductions Production and supply disruptions Commodities prices Availability and relative cost of skilled labour Light vehicle sales levels, including due to : - A decline in consumer confidence - Economic uncertainty - Elevated interest rates and availability of consumer credit - Deteriorating vehicle affordability Light Vehicle Production Pace of EV adoption, including North American electric vehicle program deferrals, cancellations and volume reductions Shifts in market shares among OEMs, vehicles and/or vehicle segments Shifts in consumer "take rates" for products we sell Relative currency values Same risks as for Light Vehicle Production above Alignment of our product mix with production demand Supply disruptions, including as a result of semiconductor and memory (DRAM) chip shortages Customer concentration Total Sales Segment Sales Restructuring costs and/or impairment charges Inflation Ability to secure cost recoveries Price concessions Commodity cost volatility Scrap steel price volatility Same risks as for Total Sales and Segment Sales above Execution of critical program launches Operational underperformance Product warranty/recall risks Production inefficiencies Unmitigated incremental tariff costs Adjusted EBIT Margin Adjusted Diluted EPS Free Cash Flow Legal and regulatory proceedings Changes in law Same risks as Adjusted EBIT Margin above Risks related to conducting business through joint ventures Risks of doing business in foreign markets Equity Income Same risks impacting Free Cash Flow above Ability to repurchase shares for cancellation, including due to normal course issuer bid rules, trading blackouts, and other factors Share Repurchases Weighted Average Diluted Shares Outstanding
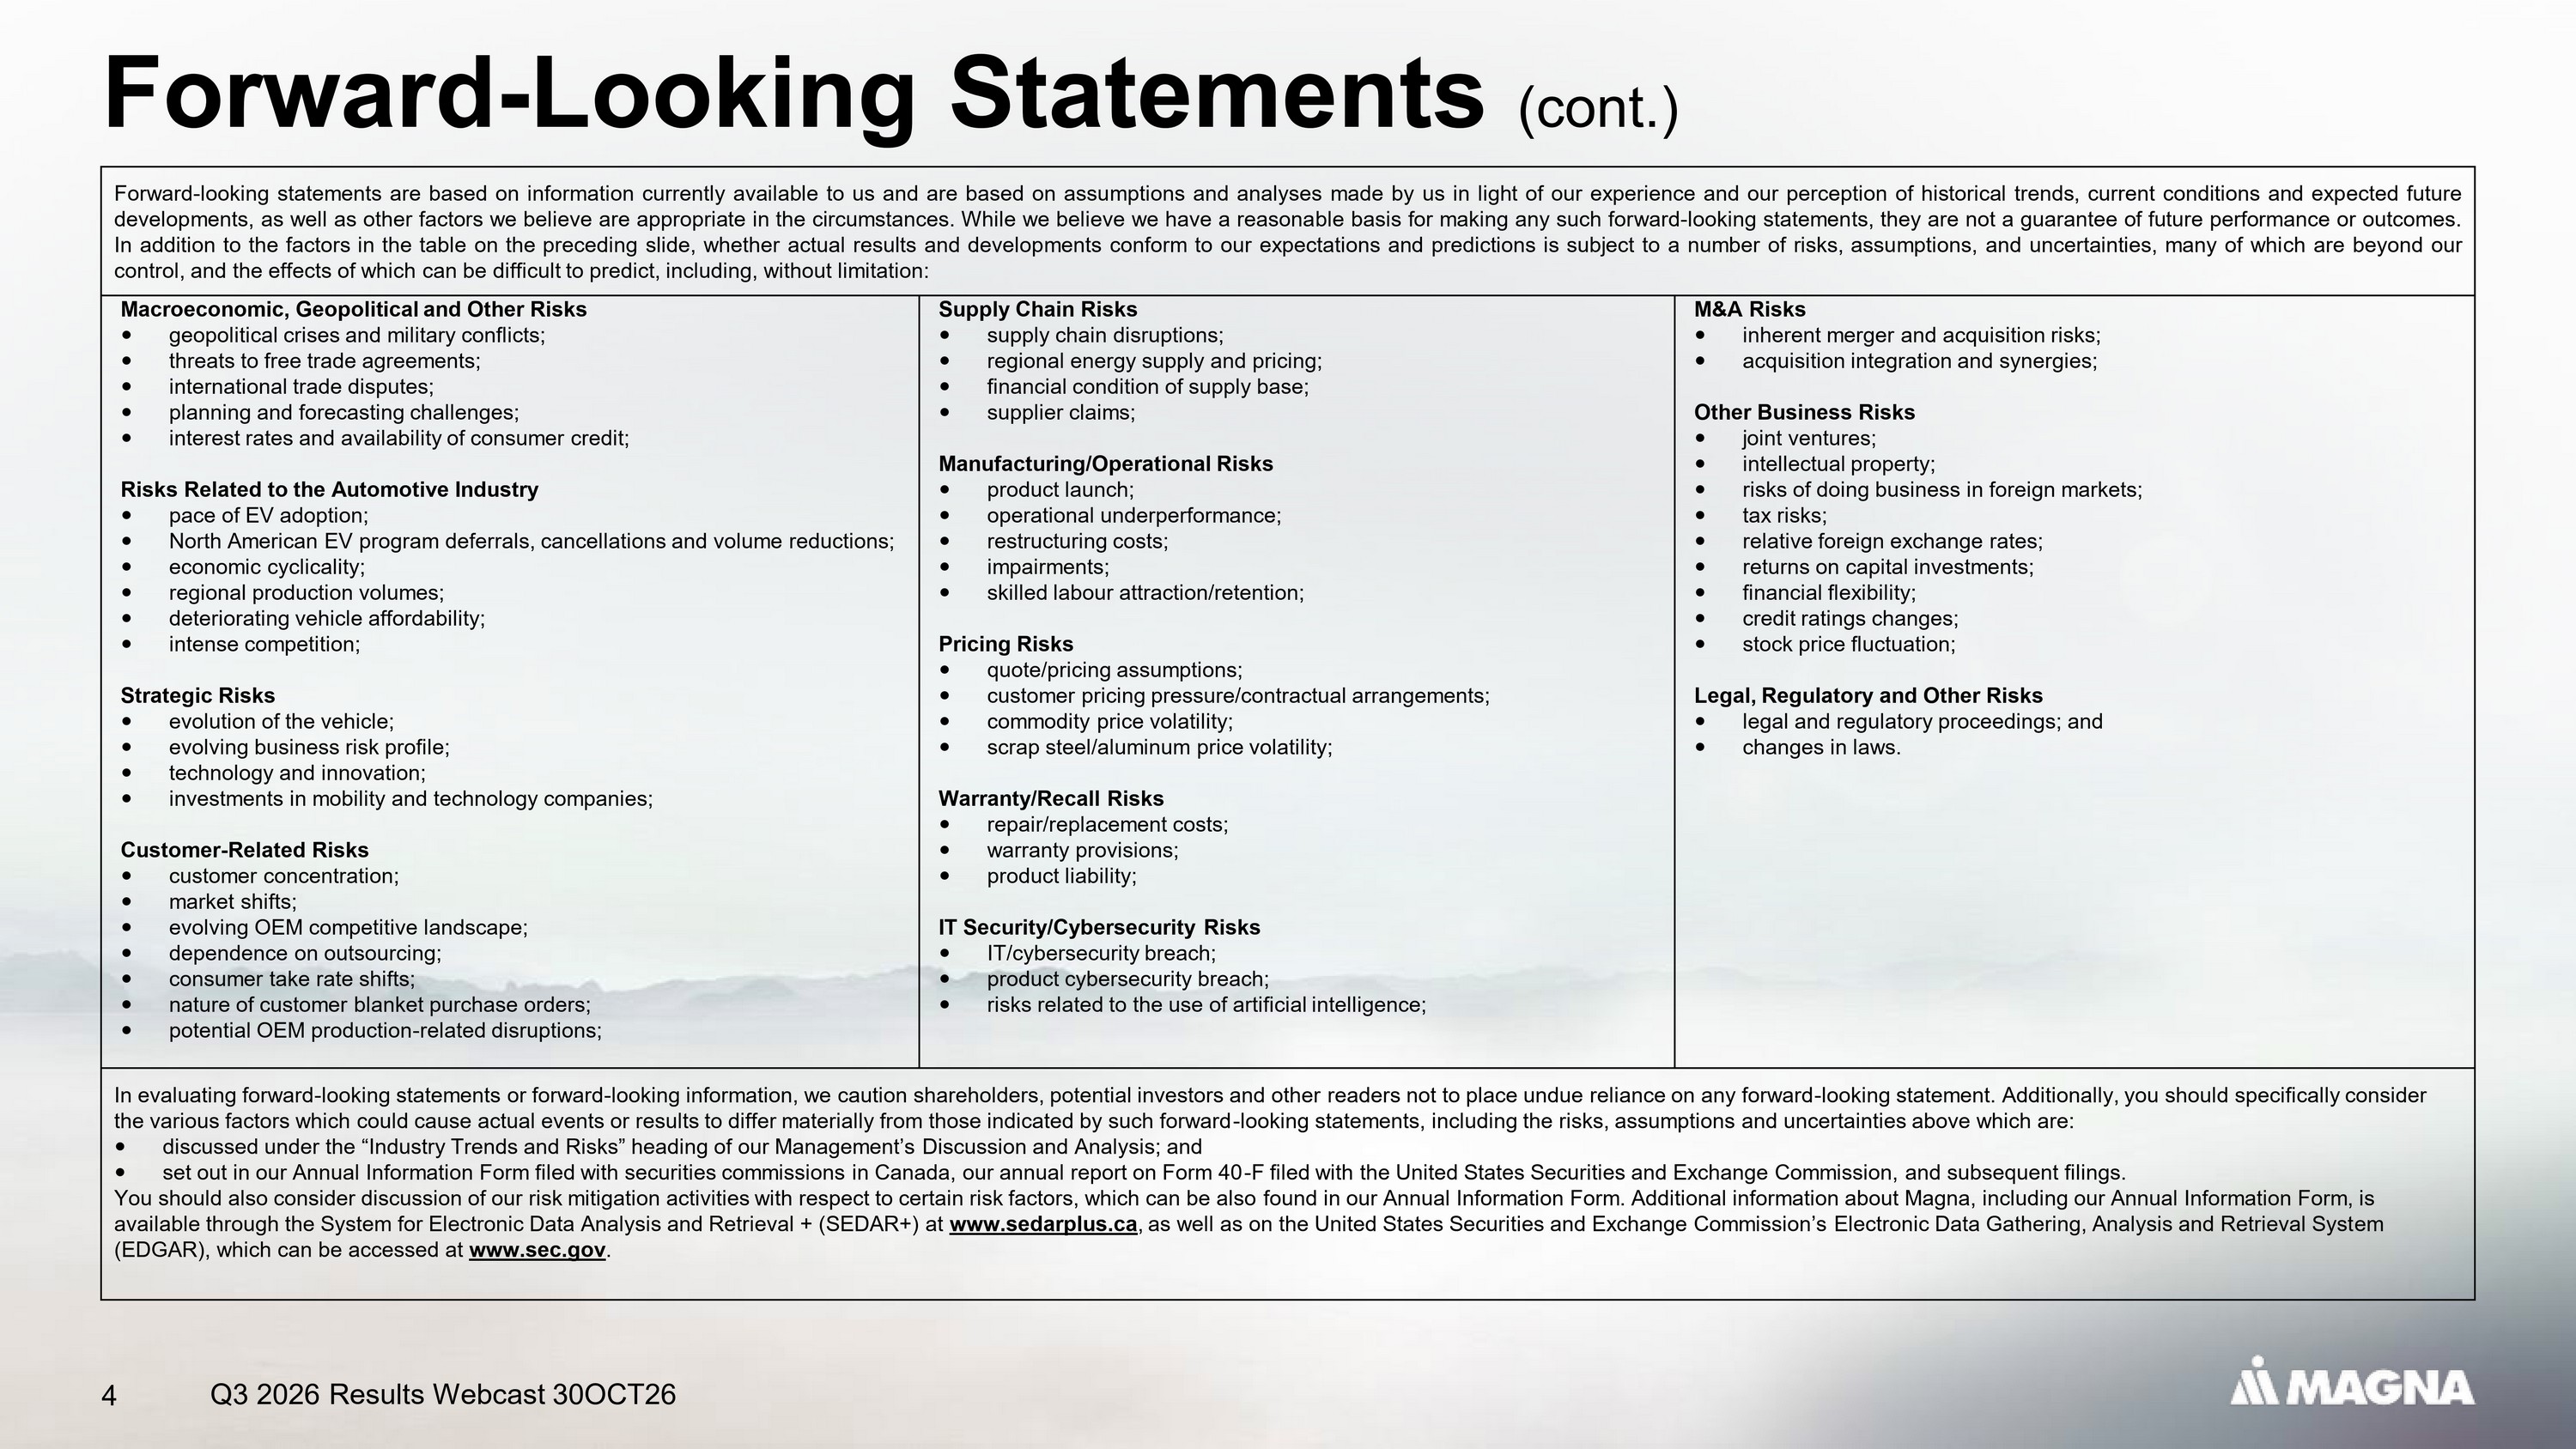
Q3 2026 Results Webcast 30OCT26 4 Forward - Looking Statements (cont.) Forward - looking statements are based on information currently available to us and are based on assumptions and analyses made by us in light of our experience and our perception of historical trends, current conditions and expected future developments, as well as other factors we believe are appropriate in the circumstances . While we believe we have a reasonable basis for making any such forward - looking statements, they are not a guarantee of future performance or outcomes . In addition to the factors in the table on the preceding slide, whether actual results and developments conform to our expectations and predictions is subject to a number of risks, assumptions, and uncertainties, many of which are beyond our control, and the effects of which can be difficult to predict, including, without limitation : M&A Risks inherent merger and acquisition risks; acquisition integration and synergies; Other Business Risks joint ventures; intellectual property; risks of doing business in foreign markets; tax risks; relative foreign exchange rates; returns on capital investments; financial flexibility; credit ratings changes; stock price fluctuation; Legal, Regulatory and Other Risks legal and regulatory proceedings; and changes in laws. Supply Chain Risks supply chain disruptions; regional energy supply and pricing; financial condition of supply base; supplier claims; Manufacturing/Operational Risks product launch; operational underperformance; restructuring costs; impairments; skilled labour attraction/retention; Pricing Risks quote/pricing assumptions; customer pricing pressure/contractual arrangements; commodity price volatility; scrap steel/aluminum price volatility; Warranty/Recall Risks repair/replacement costs; warranty provisions; product liability; IT Security/Cybersecurity Risks IT/cybersecurity breach; product cybersecurity breach; risks related to the use of artificial intelligence; Macroeconomic, Geopolitical and Other Risks geopolitical crises and military conflicts; threats to free trade agreements; international trade disputes; planning and forecasting challenges; interest rates and availability of consumer credit; Risks Related to the Automotive Industry pace of EV adoption; North American EV program deferrals, cancellations and volume reductions; economic cyclicality; regional production volumes; deteriorating vehicle affordability; intense competition; Strategic Risks evolution of the vehicle; evolving business risk profile; technology and innovation; investments in mobility and technology companies; Customer - Related Risks customer concentration; market shifts; evolving OEM competitive landscape; dependence on outsourcing; consumer take rate shifts; nature of customer blanket purchase orders; potential OEM production - related disruptions; In evaluating forward - looking statements or forward - looking information, we caution shareholders, potential investors and other readers not to place undue reliance on any forward - looking statement. Additionally, you should specifically consider the various factors which could cause actual events or results to differ materially from those indicated by such forward - looking statements, including the risks, assumptions and uncertainties above which are: discussed under the “Industry Trends and Risks” heading of our Management’s Discussion and Analysis; and set out in our Annual Information Form filed with securities commissions in Canada, our annual report on Form 40 - F filed with th e United States Securities and Exchange Commission, and subsequent filings. You should also consider discussion of our risk mitigation activities with respect to certain risk factors, which can be also fo und in our Annual Information Form. Additional information about Magna, including our Annual Information Form, is available through the System for Electronic Data Analysis and Retrieval + (SEDAR+) at www.sedarplus.ca , as well as on the United States Securities and Exchange Commission’s Electronic Data Gathering, Analysis and Retrieval Syst em (EDGAR), which can be accessed at www.sec.gov .
Today's discussion excludes the impact of other expense (income), net ("Unusual Items") and amortization of acquired intangible assets. Please refer to the reconciliation of Non - GAAP measures in our press release dated October 30, 2026 for further information. "Organic", in the context of sales movements, means "excluding the impact of foreign exchange, acquisitions and divestitures". Weighted Sales Growth over Market (GoM) compares Magna organic sales growth (%) to vehicle production change (%) after applying Magna - specific geographic sales weighting, excluding Complete Vehicles, to regional production. All amounts are in U.S. Dollars Reminders 5 Q3 2026 Results Webcast 30OCT26
President & Chief Executive Officer Swamy Kotagiri 6 Q3 2026 Results Webcast 30OCT26
Key Takeaways 7 Strong Q3 results, with continued margin expansion driven by disciplined execution 1 • Sales down 4%, weighted Growth over Market of +0.5% (+1.0% ex - CV) • Adjusted EBIT up 11% , Adjusted EBIT margin expanded 90 bps to 6.8% • Adjusted EPS rose 38% to $1.83 • Continuing operational excellence across the Company • Favourable commercial items in Q3, including some timing from Q4 Q3 2026 Results Webcast 30OCT26
Key Takeaways 8 Solid free cash flow reflects further improved operating performance 2 • Generated operating cash flow of $950 million and free cash flow of $584 million in Q3 • Ended Q3 with strong balance sheet, including $1.4 billion in cash • Strong cash generation and investment - grade balance sheet provide financial flexibility Q3 2026 Results Webcast 30OCT26
Key Takeaways 9 Updated Outlook reflects ongoing confidence in margin, EPS and cash flow trajectory 3 • Updating sales range to reflect lower expected vehicle production in China, unfavourable program mix • Narrowing FY 2026 Outlook range for Adj. EBIT margin ( 6.3% to 6.5% ) • Maintaining midpoint of FY 2026 Outlook range for Adj. EPS ( $6.85 – $7.15 ) • Raising FY 2026 Outlook range for Free Cash Flow ( $1.85B – $1.90B ) Q3 2026 Results Webcast 30OCT26
Key Takeaways 10 Executing our proven capital allocation framework 4 • Continue to invest in business to support profitable growth • Returned $658 million in capital to shareholders in Q3, through dividends and share repurchases • Completed existing buyback authorization (NCIB) in October; Board approved new NCIB • Closed Rooftop Systems and North American Lighting divestitures Q3 2026 Results Webcast 30OCT26
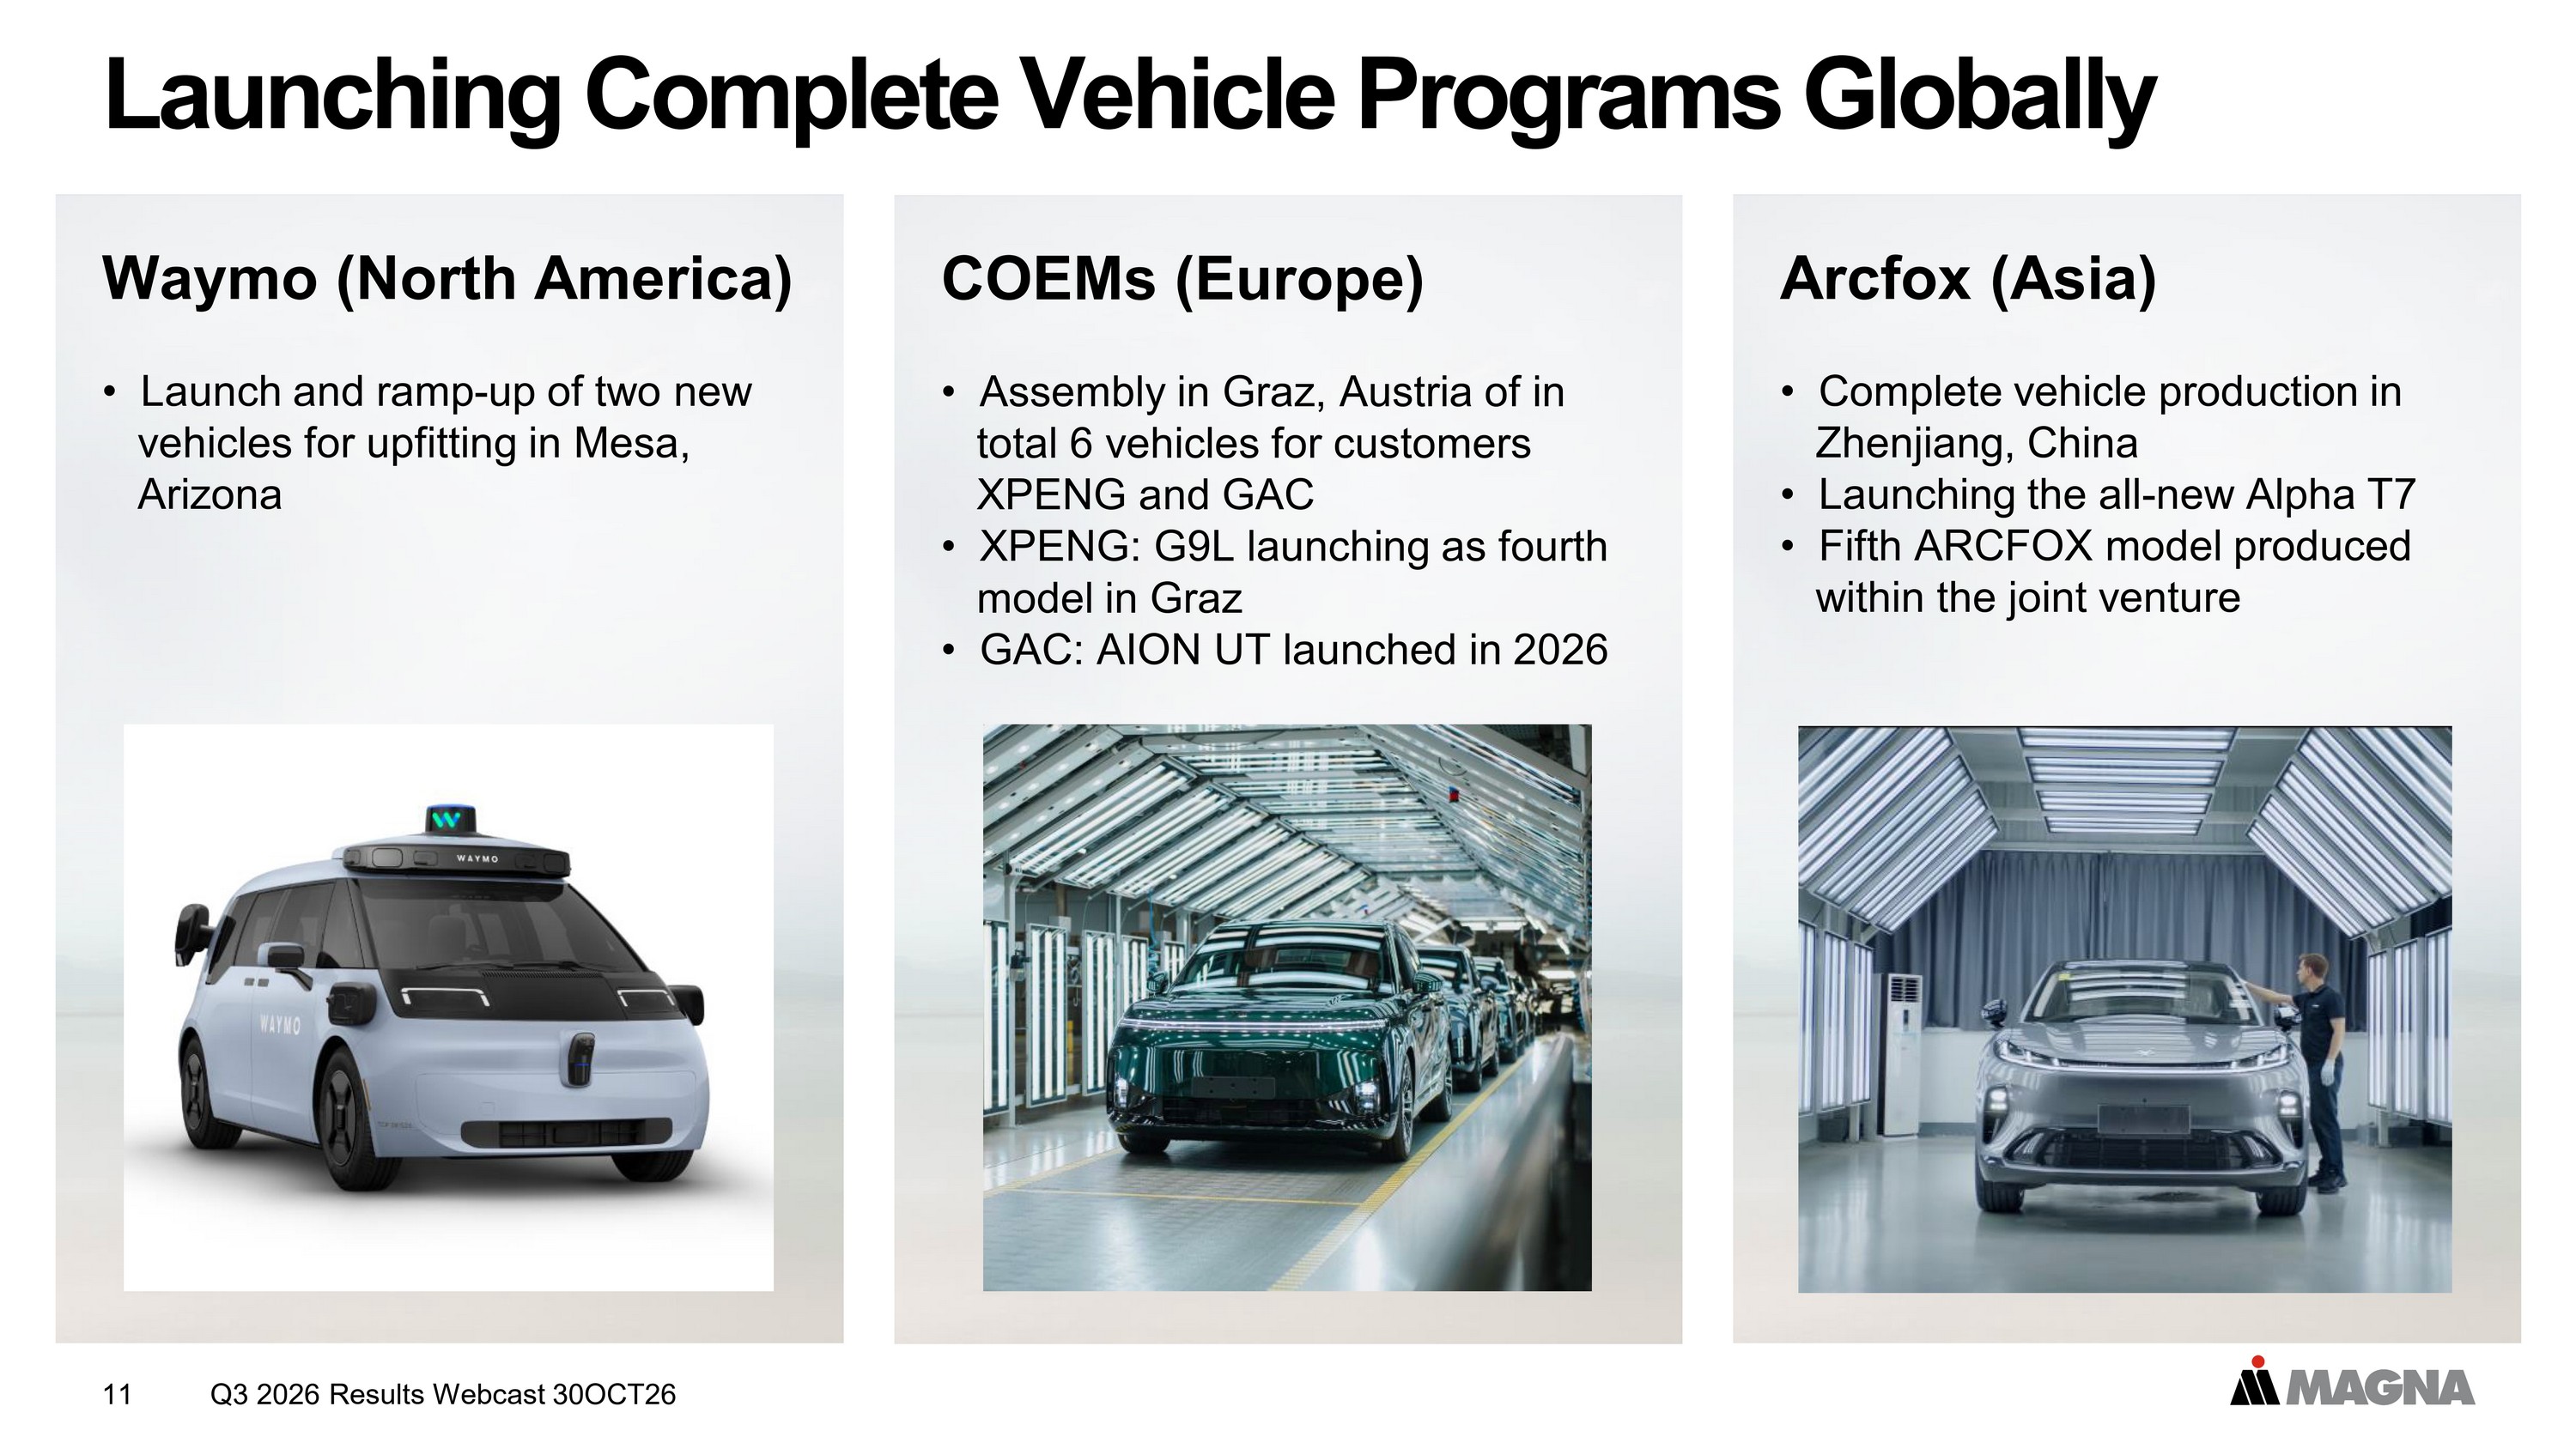
Q3 2026 Results Webcast 30OCT26 11 Launching Complete Vehicle Programs Globally Arcfox (Asia) • Complete vehicle production in Zhenjiang, China • Launching the all - new Alpha T7 • Fifth ARCFOX model produced within the joint venture COEMs (Europe) • Assembly in Graz, Austria of in total 6 vehicles for customers XPENG and GAC • XPENG: G9L launching as fourth model in Graz • GAC: AION UT launched in 2026 Waymo (North America) • Launch and ramp - up of two new vehicles for upfitting in Mesa, Arizona
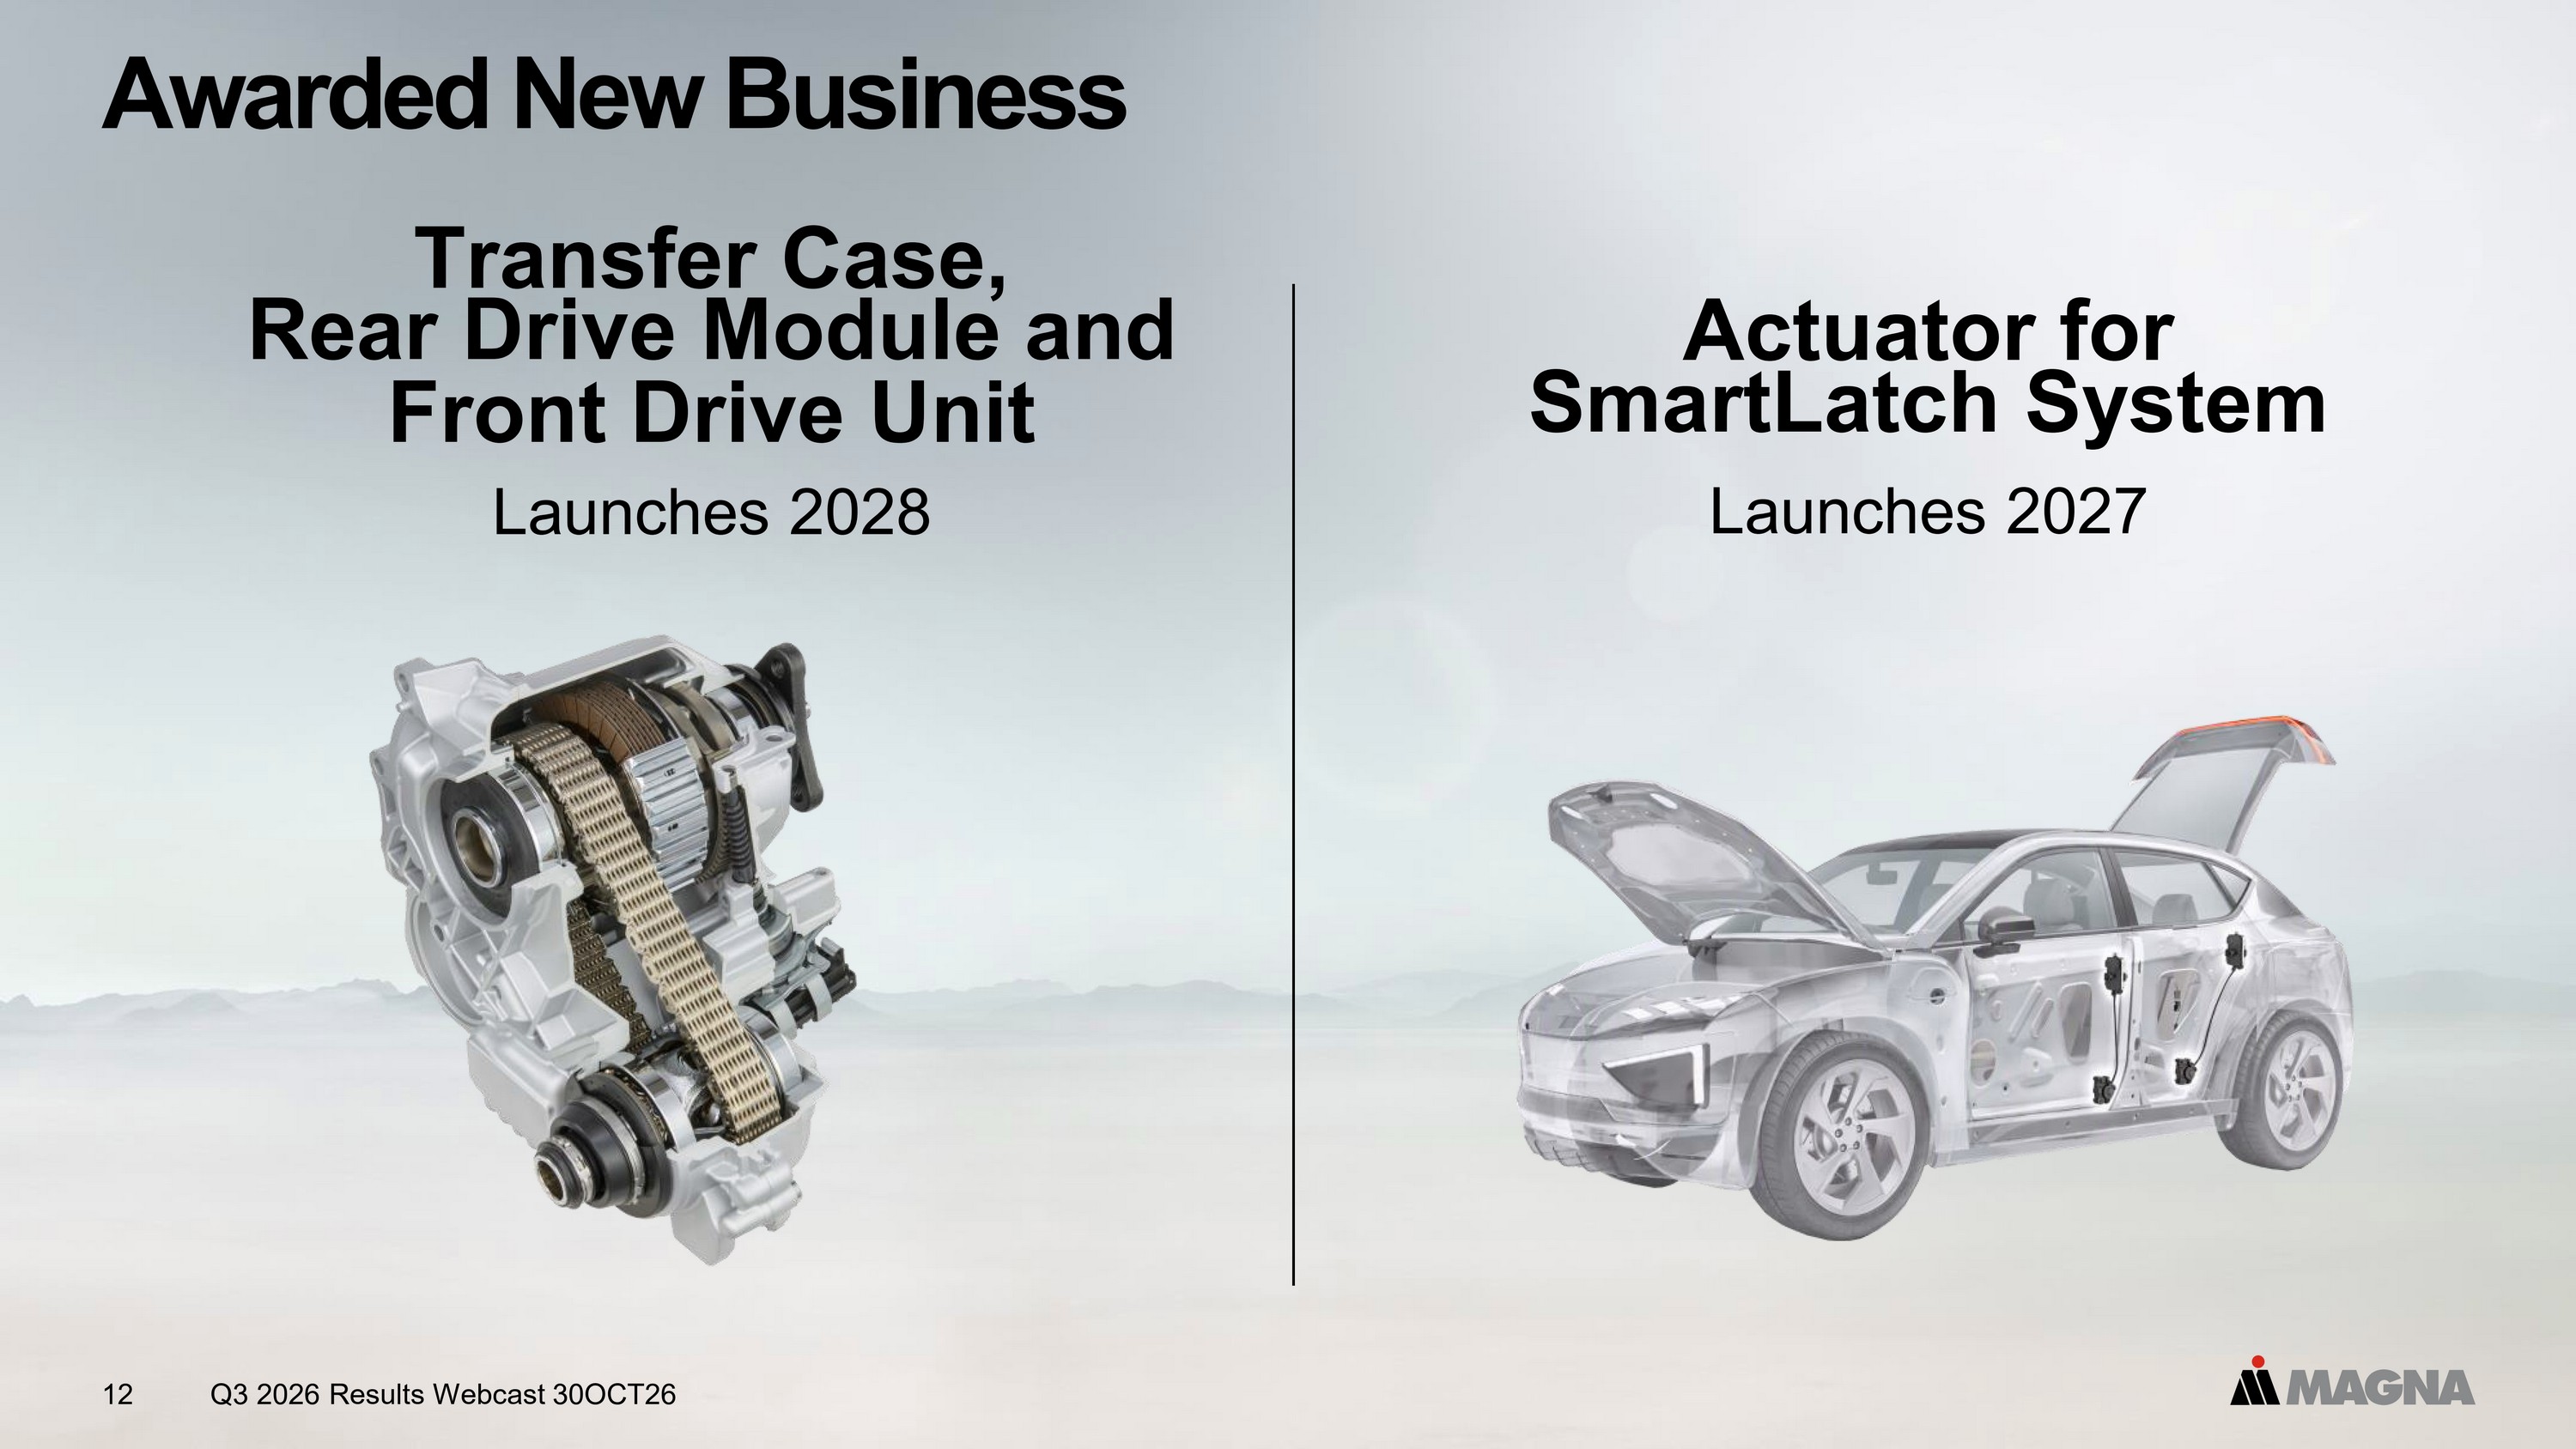
Q3 2026 Results Webcast 30OCT26 12 Awarded New Business Actuator for SmartLatch System Launches 2027 Transfer Case, Rear Drive Module and Front Drive Unit Launches 2028
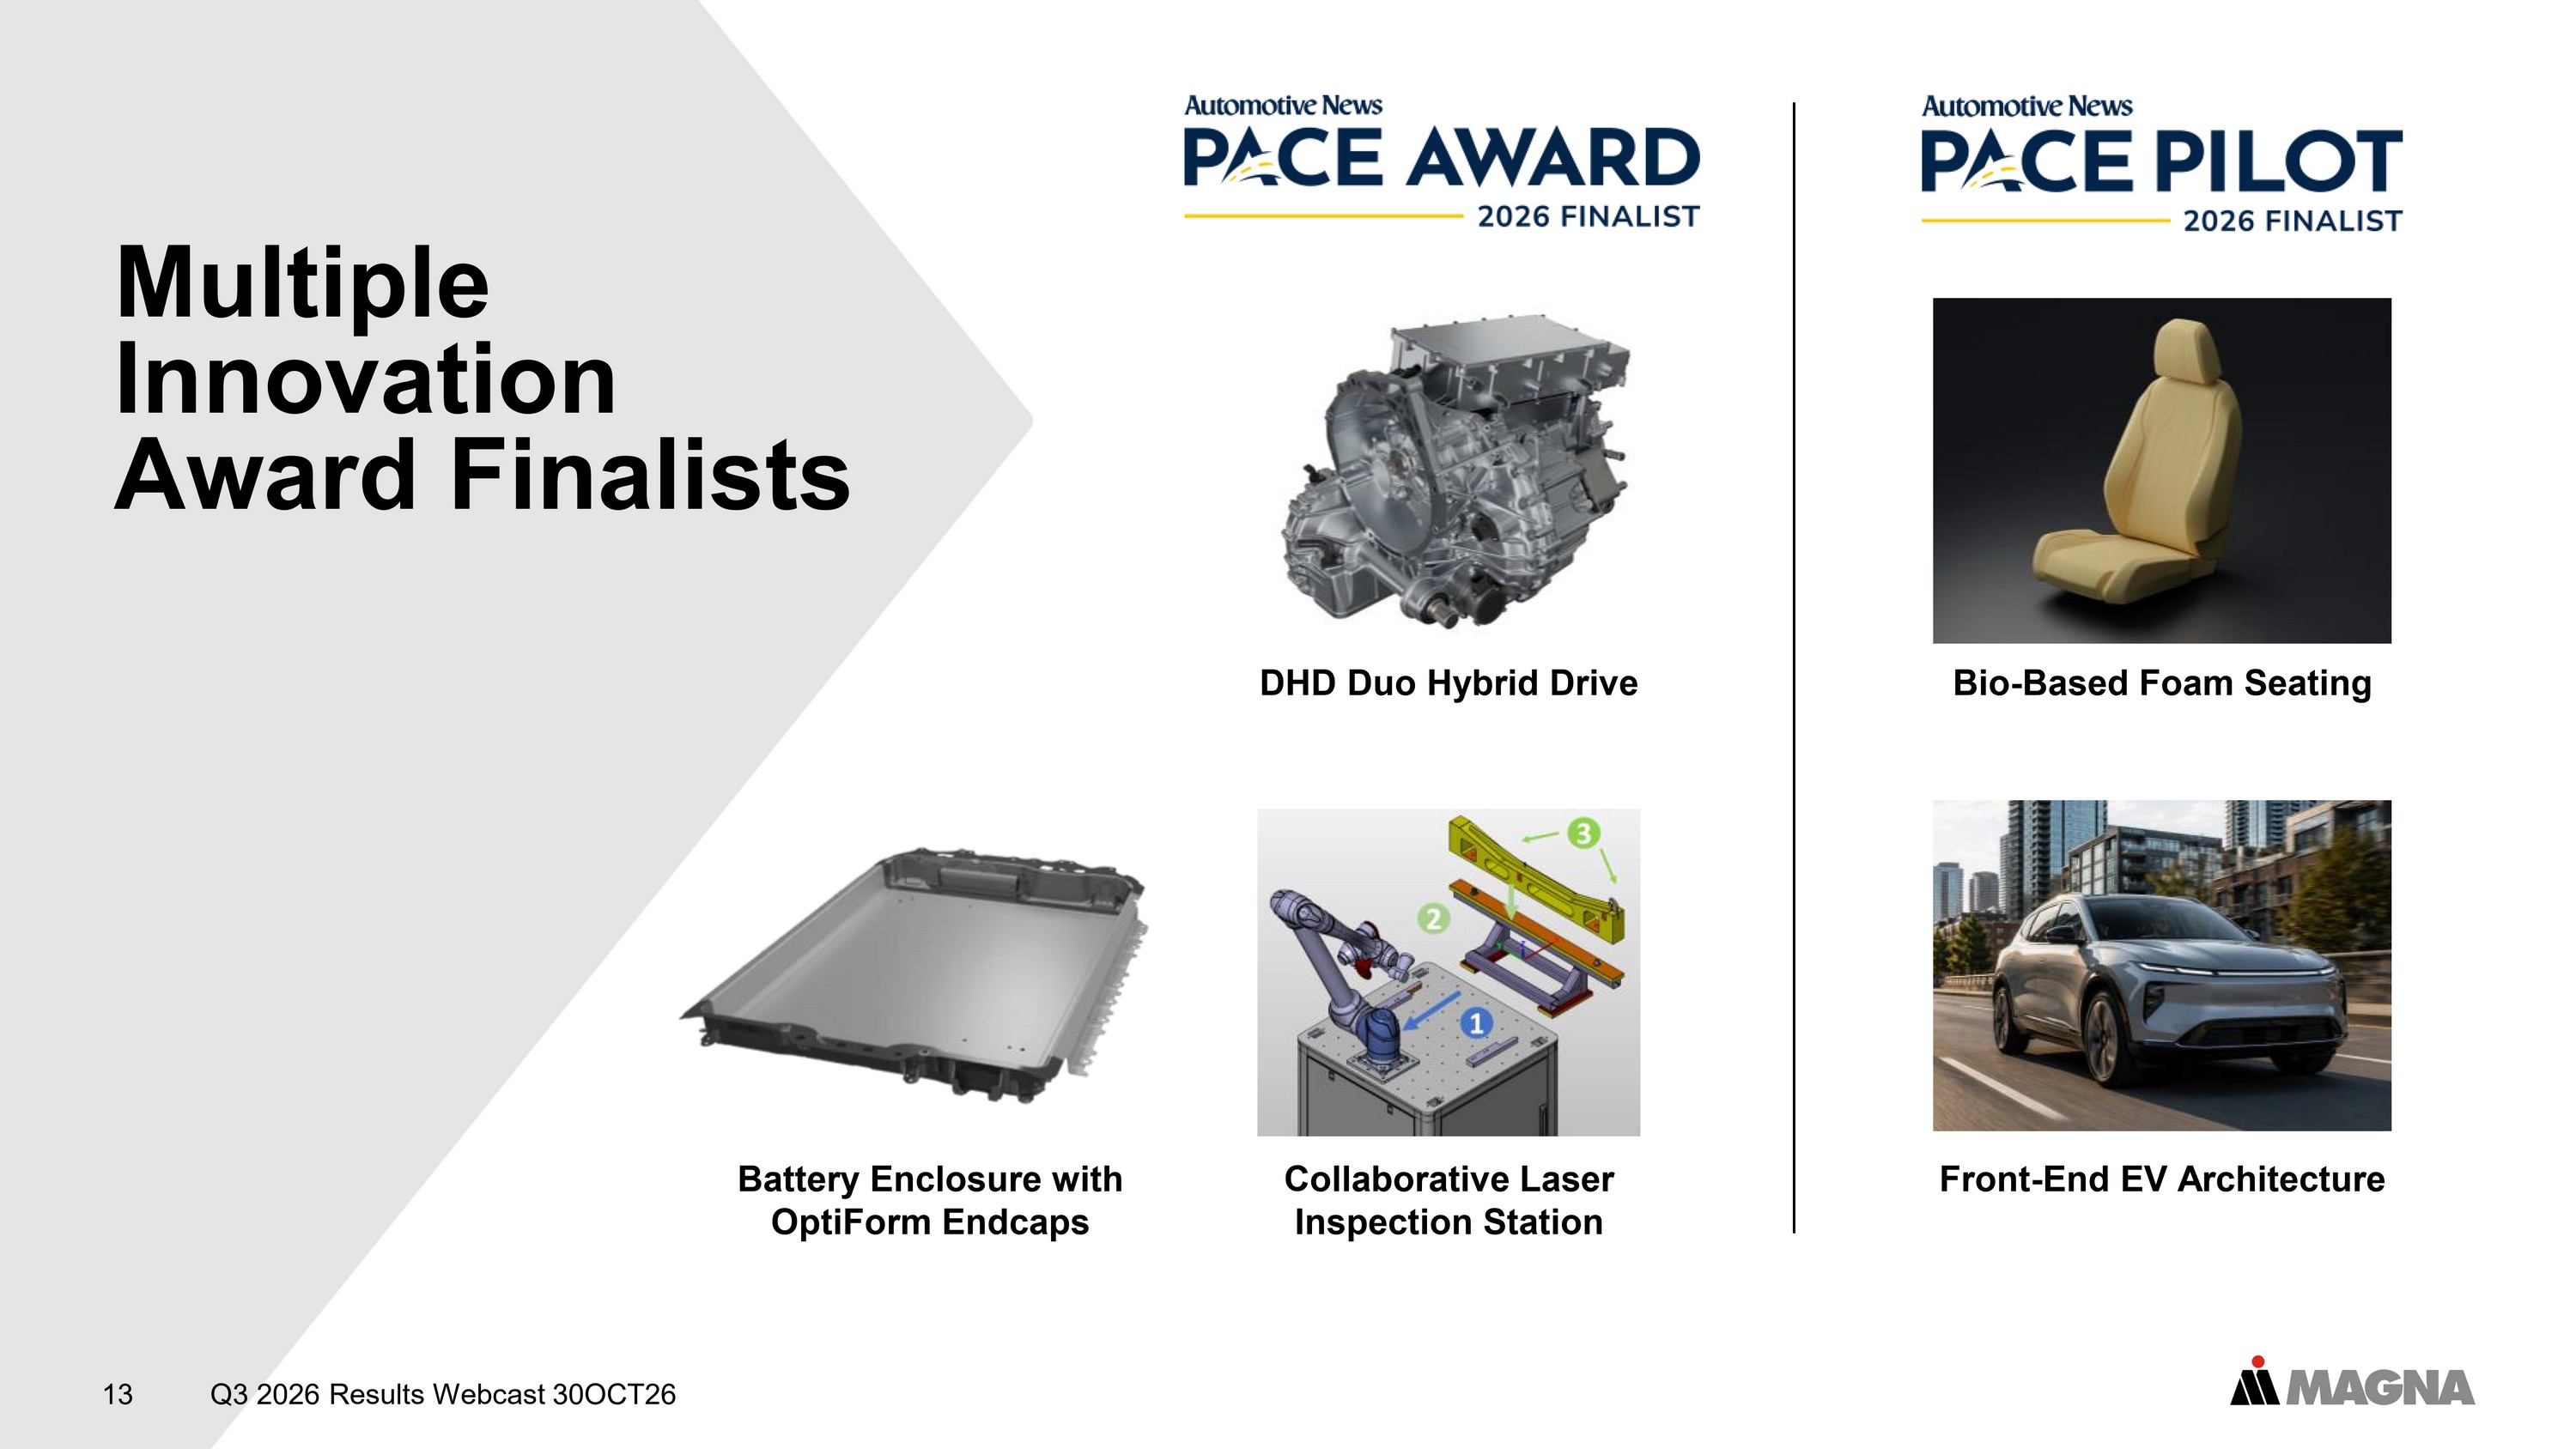
Q3 2026 Results Webcast 30OCT26 13 Multiple Innovation Award Finalists DHD Duo Hybrid Drive Battery Enclosure with OptiForm Endcaps Bio - Based Foam Seating Front - End EV Architecture Collaborative Laser Inspection Station
EVP & Chief Financial Officer Phil Fracassa 14 Q3 2026 Results Webcast 30OCT26
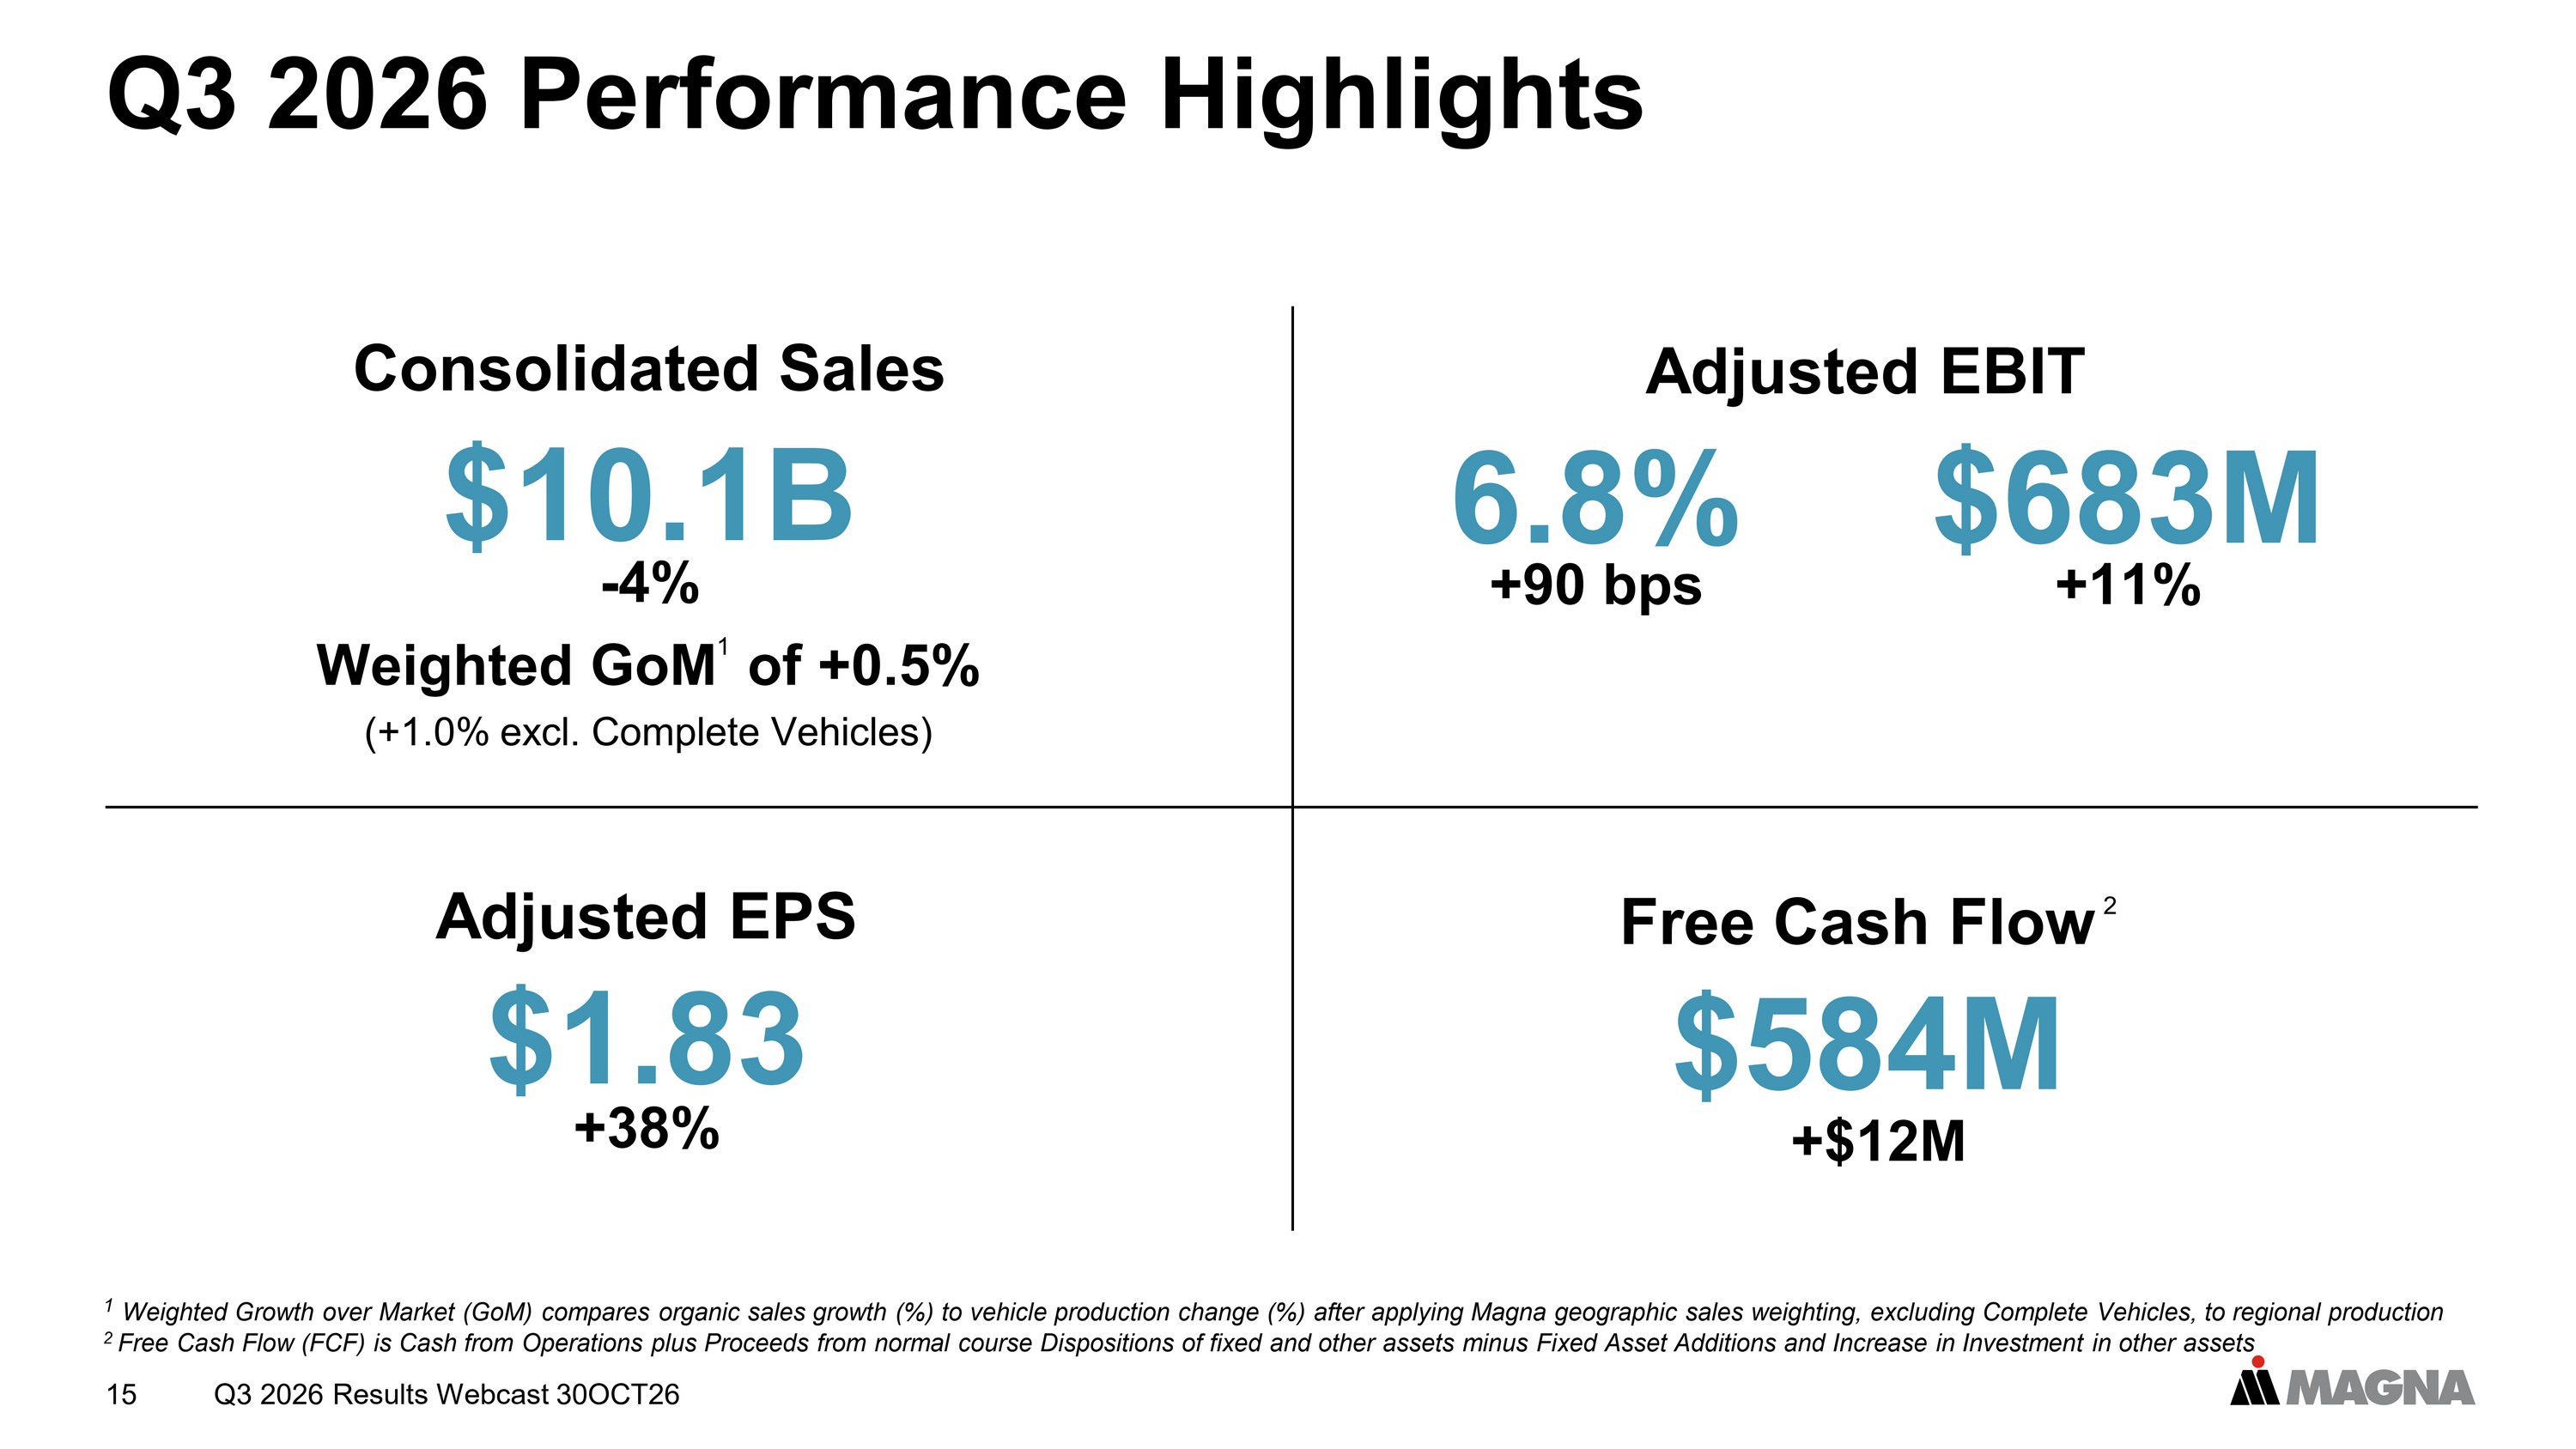
Q3 2026 Results Webcast 30OCT26 15 Q3 2026 Performance Highlights Consolidated Sales $10.1B Weighted GoM 1 of +0.5% (+1.0% excl. Complete Vehicles) - 4% Adjusted EPS $1.83 +38% 1 Weighted Growth over Market (GoM) compares organic sales growth (%) to vehicle production change (%) after applying Magna geo gra phic sales weighting, excluding Complete Vehicles, to regional production 2 Free Cash Flow (FCF) is Cash from Operations plus Proceeds from normal course Dispositions of fixed and other assets minus Fi xed Asset Additions and Increase in Investment in other assets Adjusted EBIT 6.8% +90 bps $683M +11% Free Cash Flow 2 $584M +$12M
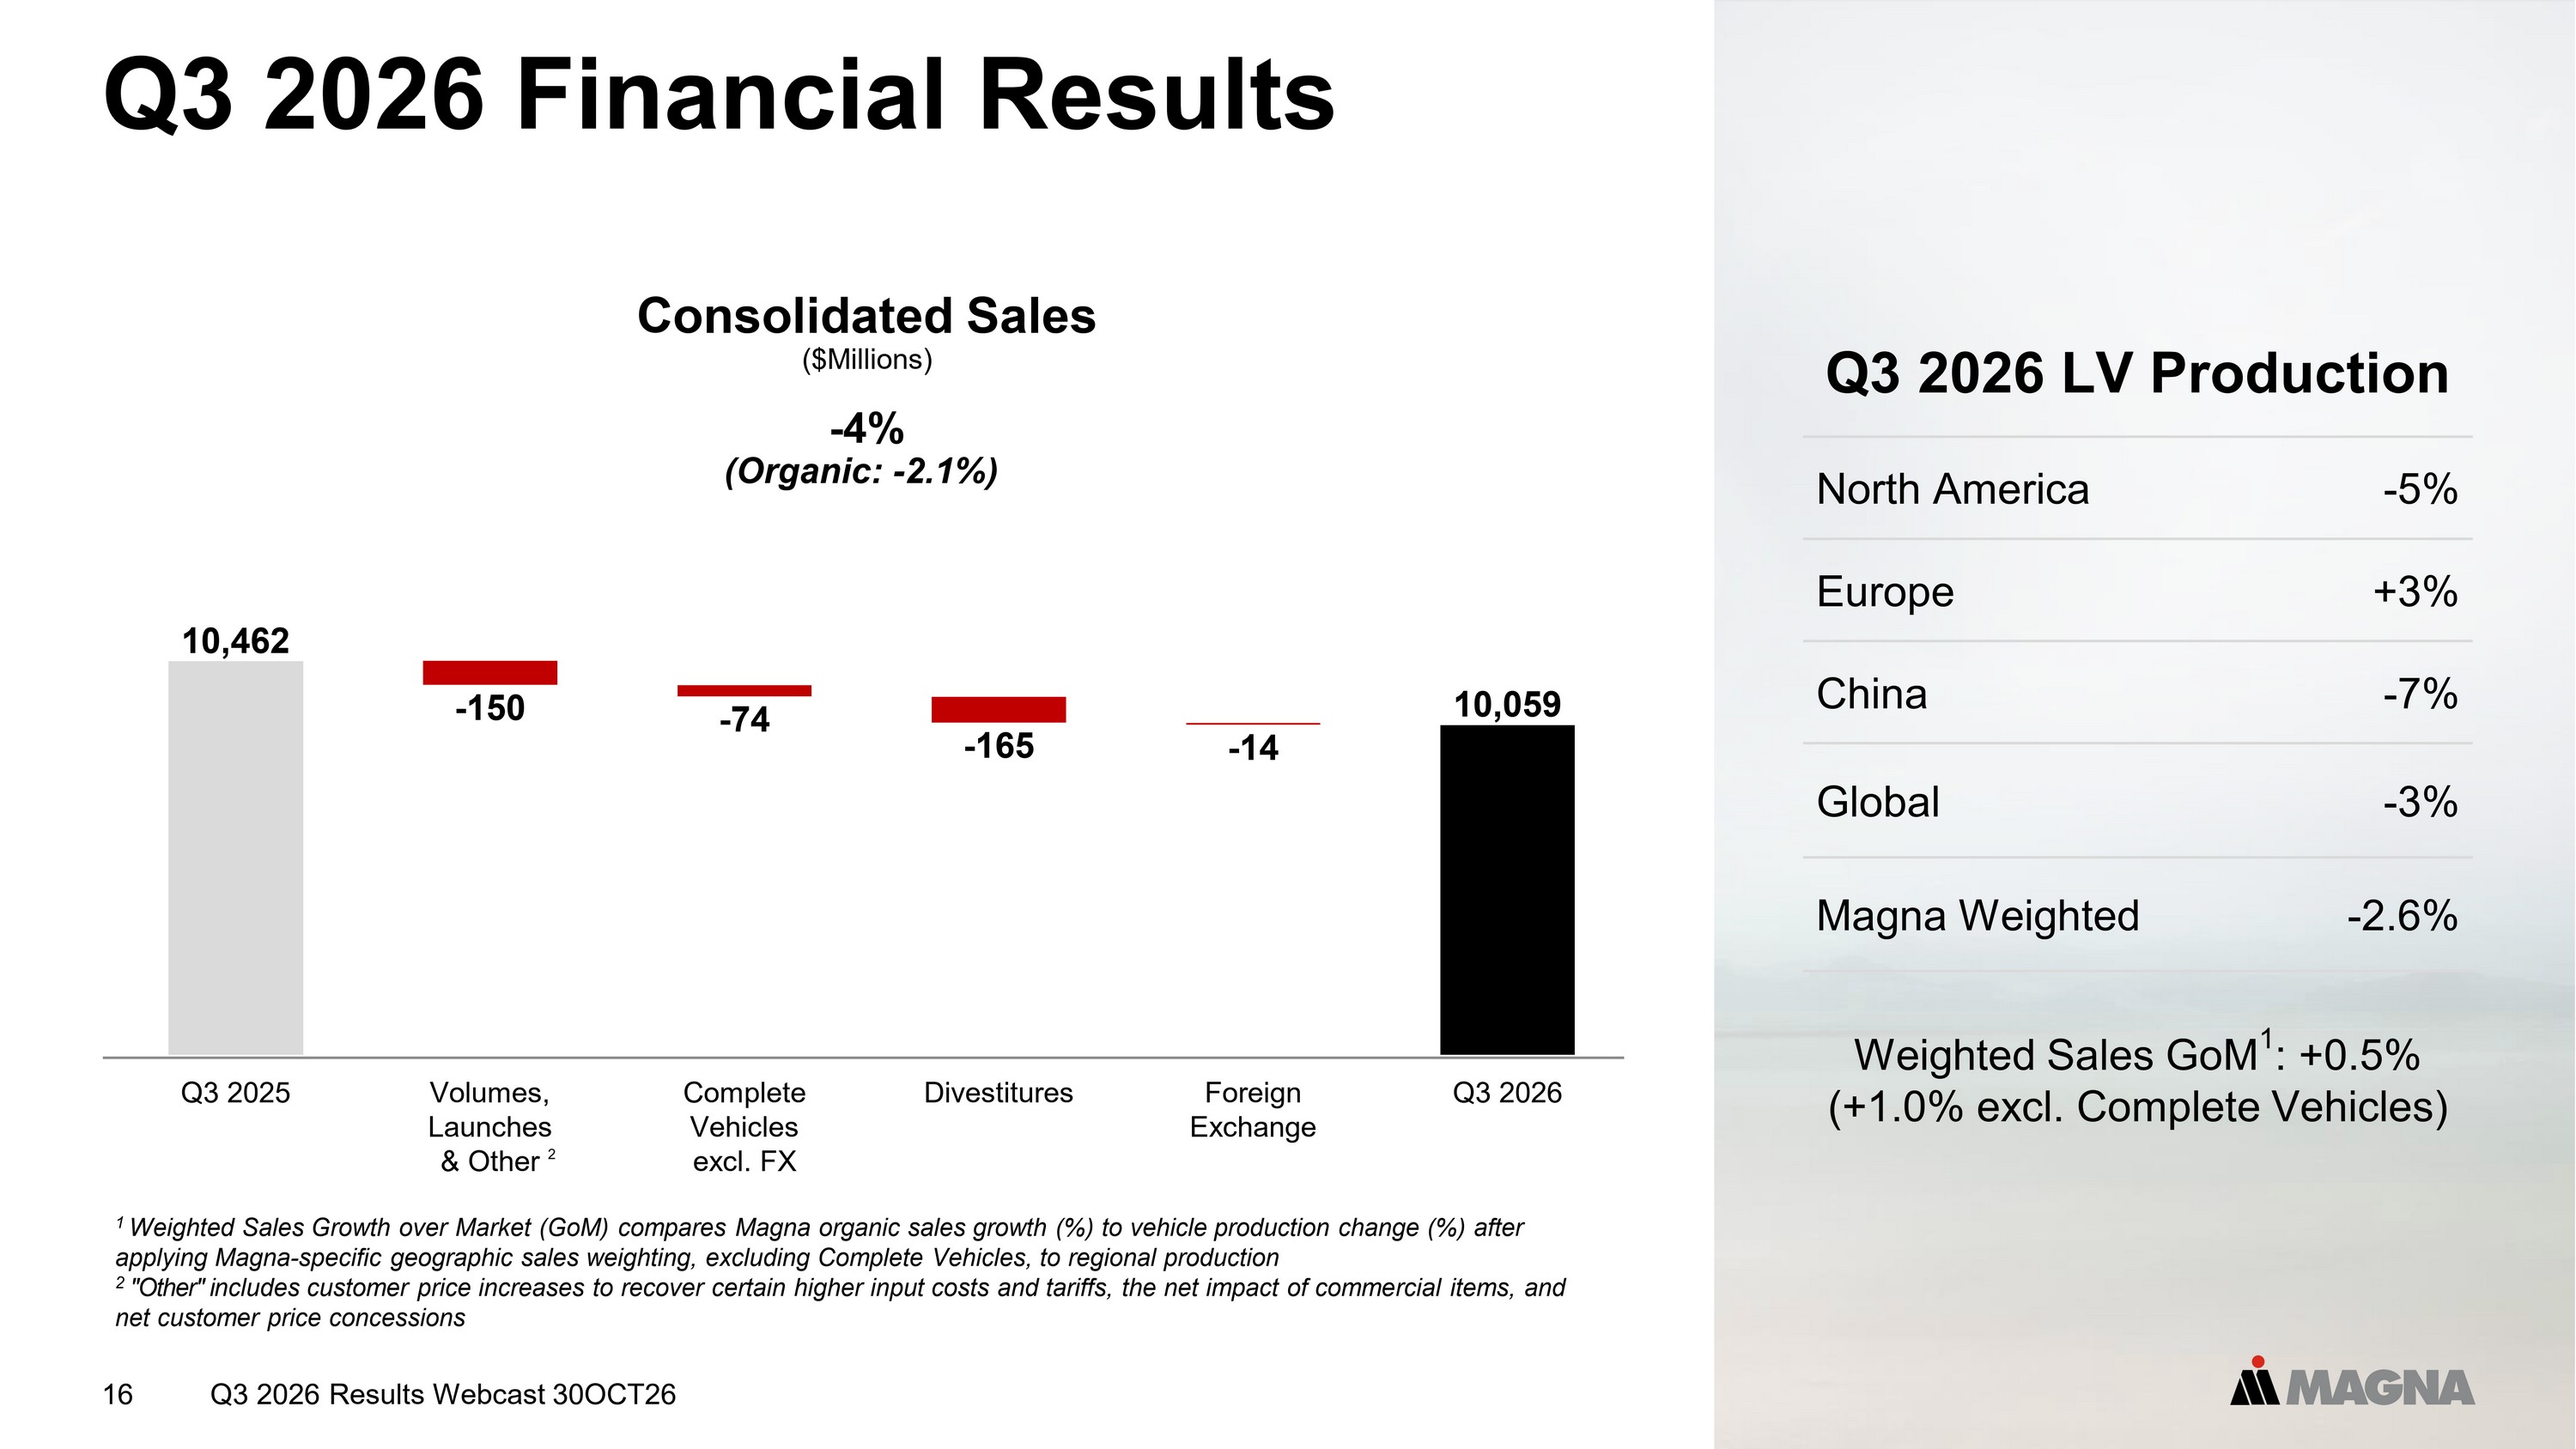
Q3 2026 Financial Results 16 1 Weighted Sales Growth over Market (GoM) compares Magna organic sales growth (%) to vehicle production change (%) after applying Magna - specific geographic sales weighting, excluding Complete Vehicles, to regional production 2 "Other" i ncludes customer price increases to recover certain higher input costs and tariffs, the net impact of commercial items, and net customer price concessions Q3 2026 LV Production - 5% North America +3% Europe - 7% China - 3% Global - 2.6% Magna Weighted Weighted Sales GoM 1 : +0.5% (+1.0% excl. Complete Vehicles) Consolidated Sales ($Millions) - 4% 10,462 - 150 - 74 - 165 - 14 10,059 Q3 2025 Volumes, Launches & Other Complete Vehicles excl. FX Divestitures Foreign Exchange Q3 2026 2 (Organic: - 2.1%) Q3 2026 Results Webcast 30OCT26
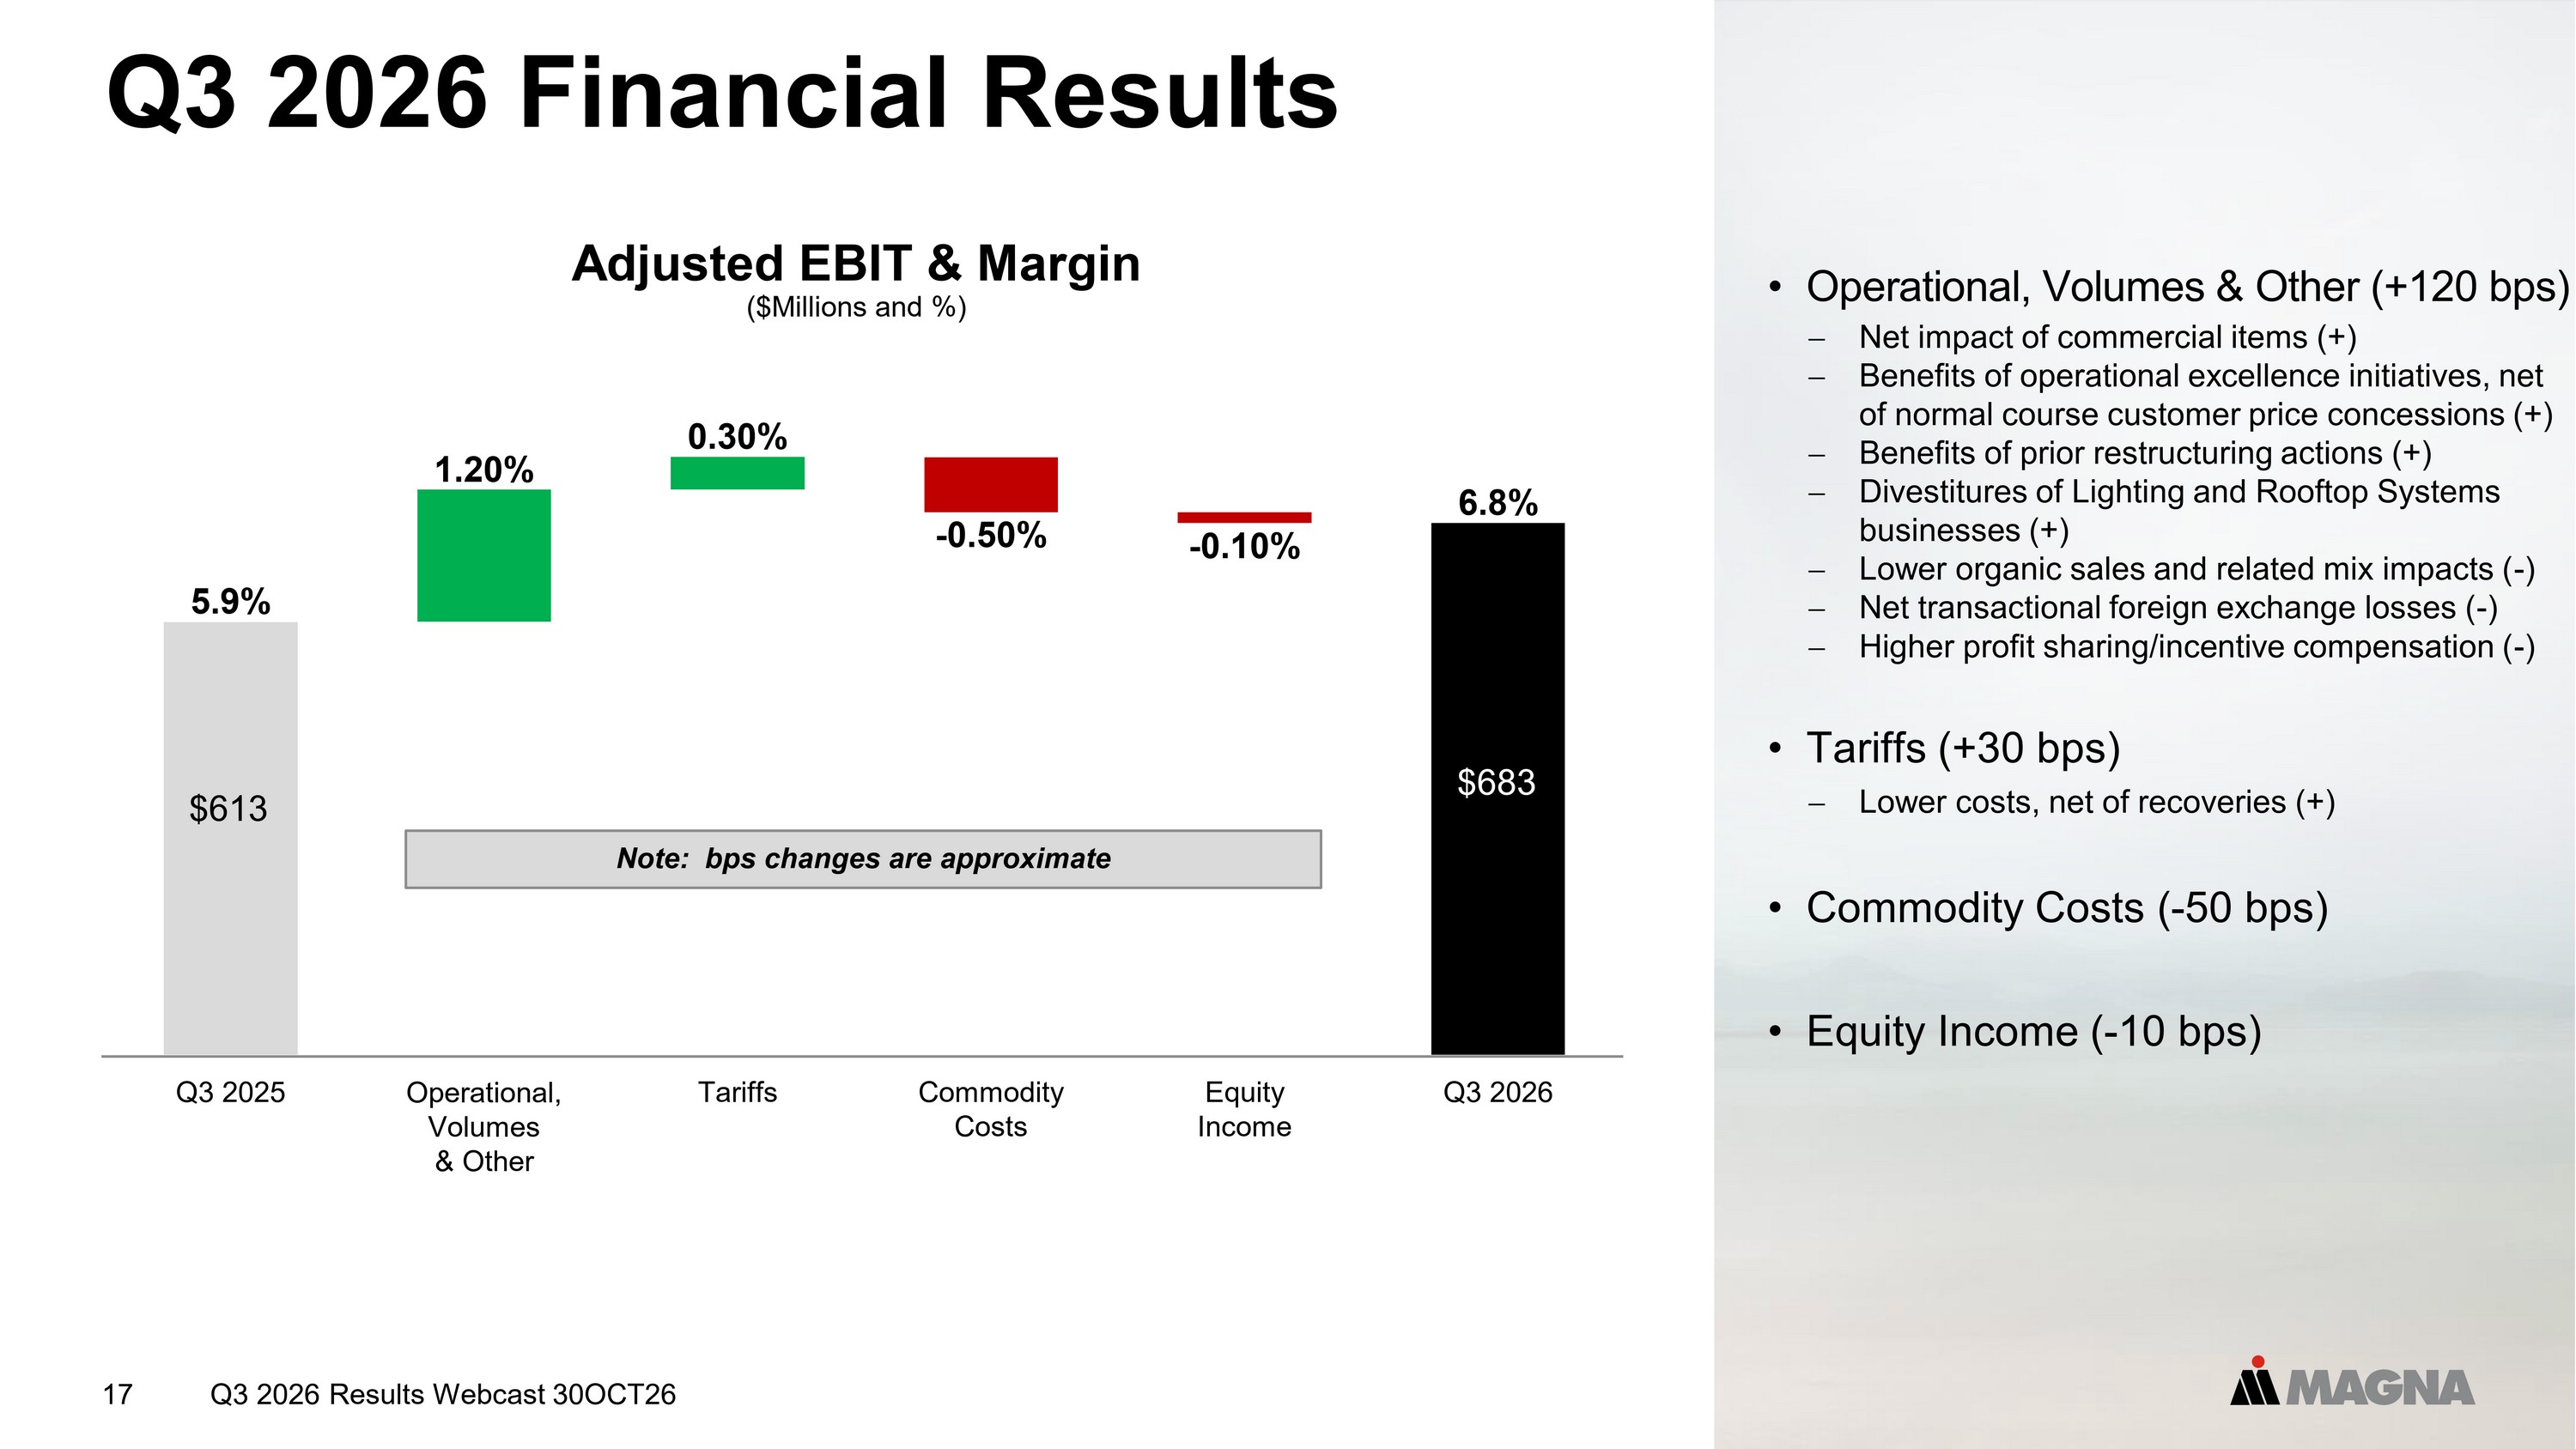
• Operational, Volumes & Other (+120 bps) Net impact of commercial items (+) Benefits of operational excellence initiatives, net of normal course customer price concessions (+) Benefits of prior restructuring actions (+) Divestitures of Lighting and Rooftop Systems businesses (+) Lower organic sales and related mix impacts ( - ) Net transactional foreign exchange losses ( - ) Higher profit sharing/incentive compensation ( - ) • Tariffs (+30 bps) Lower costs, net of recoveries (+) • Commodity Costs ( - 50 bps) • Equity Income ( - 10 bps) 17 Q3 2026 Financial Results 1.20% 0.30% - 0.50% - 0.10% 5.9% 6.8% Q3 2025 Operational, Volumes & Other Tariffs Commodity Costs Equity Income Q3 2026 $683 $613 Adjusted EBIT & Margin ($Millions and %) Note: bps changes are approximate Q3 2026 Results Webcast 30OCT26
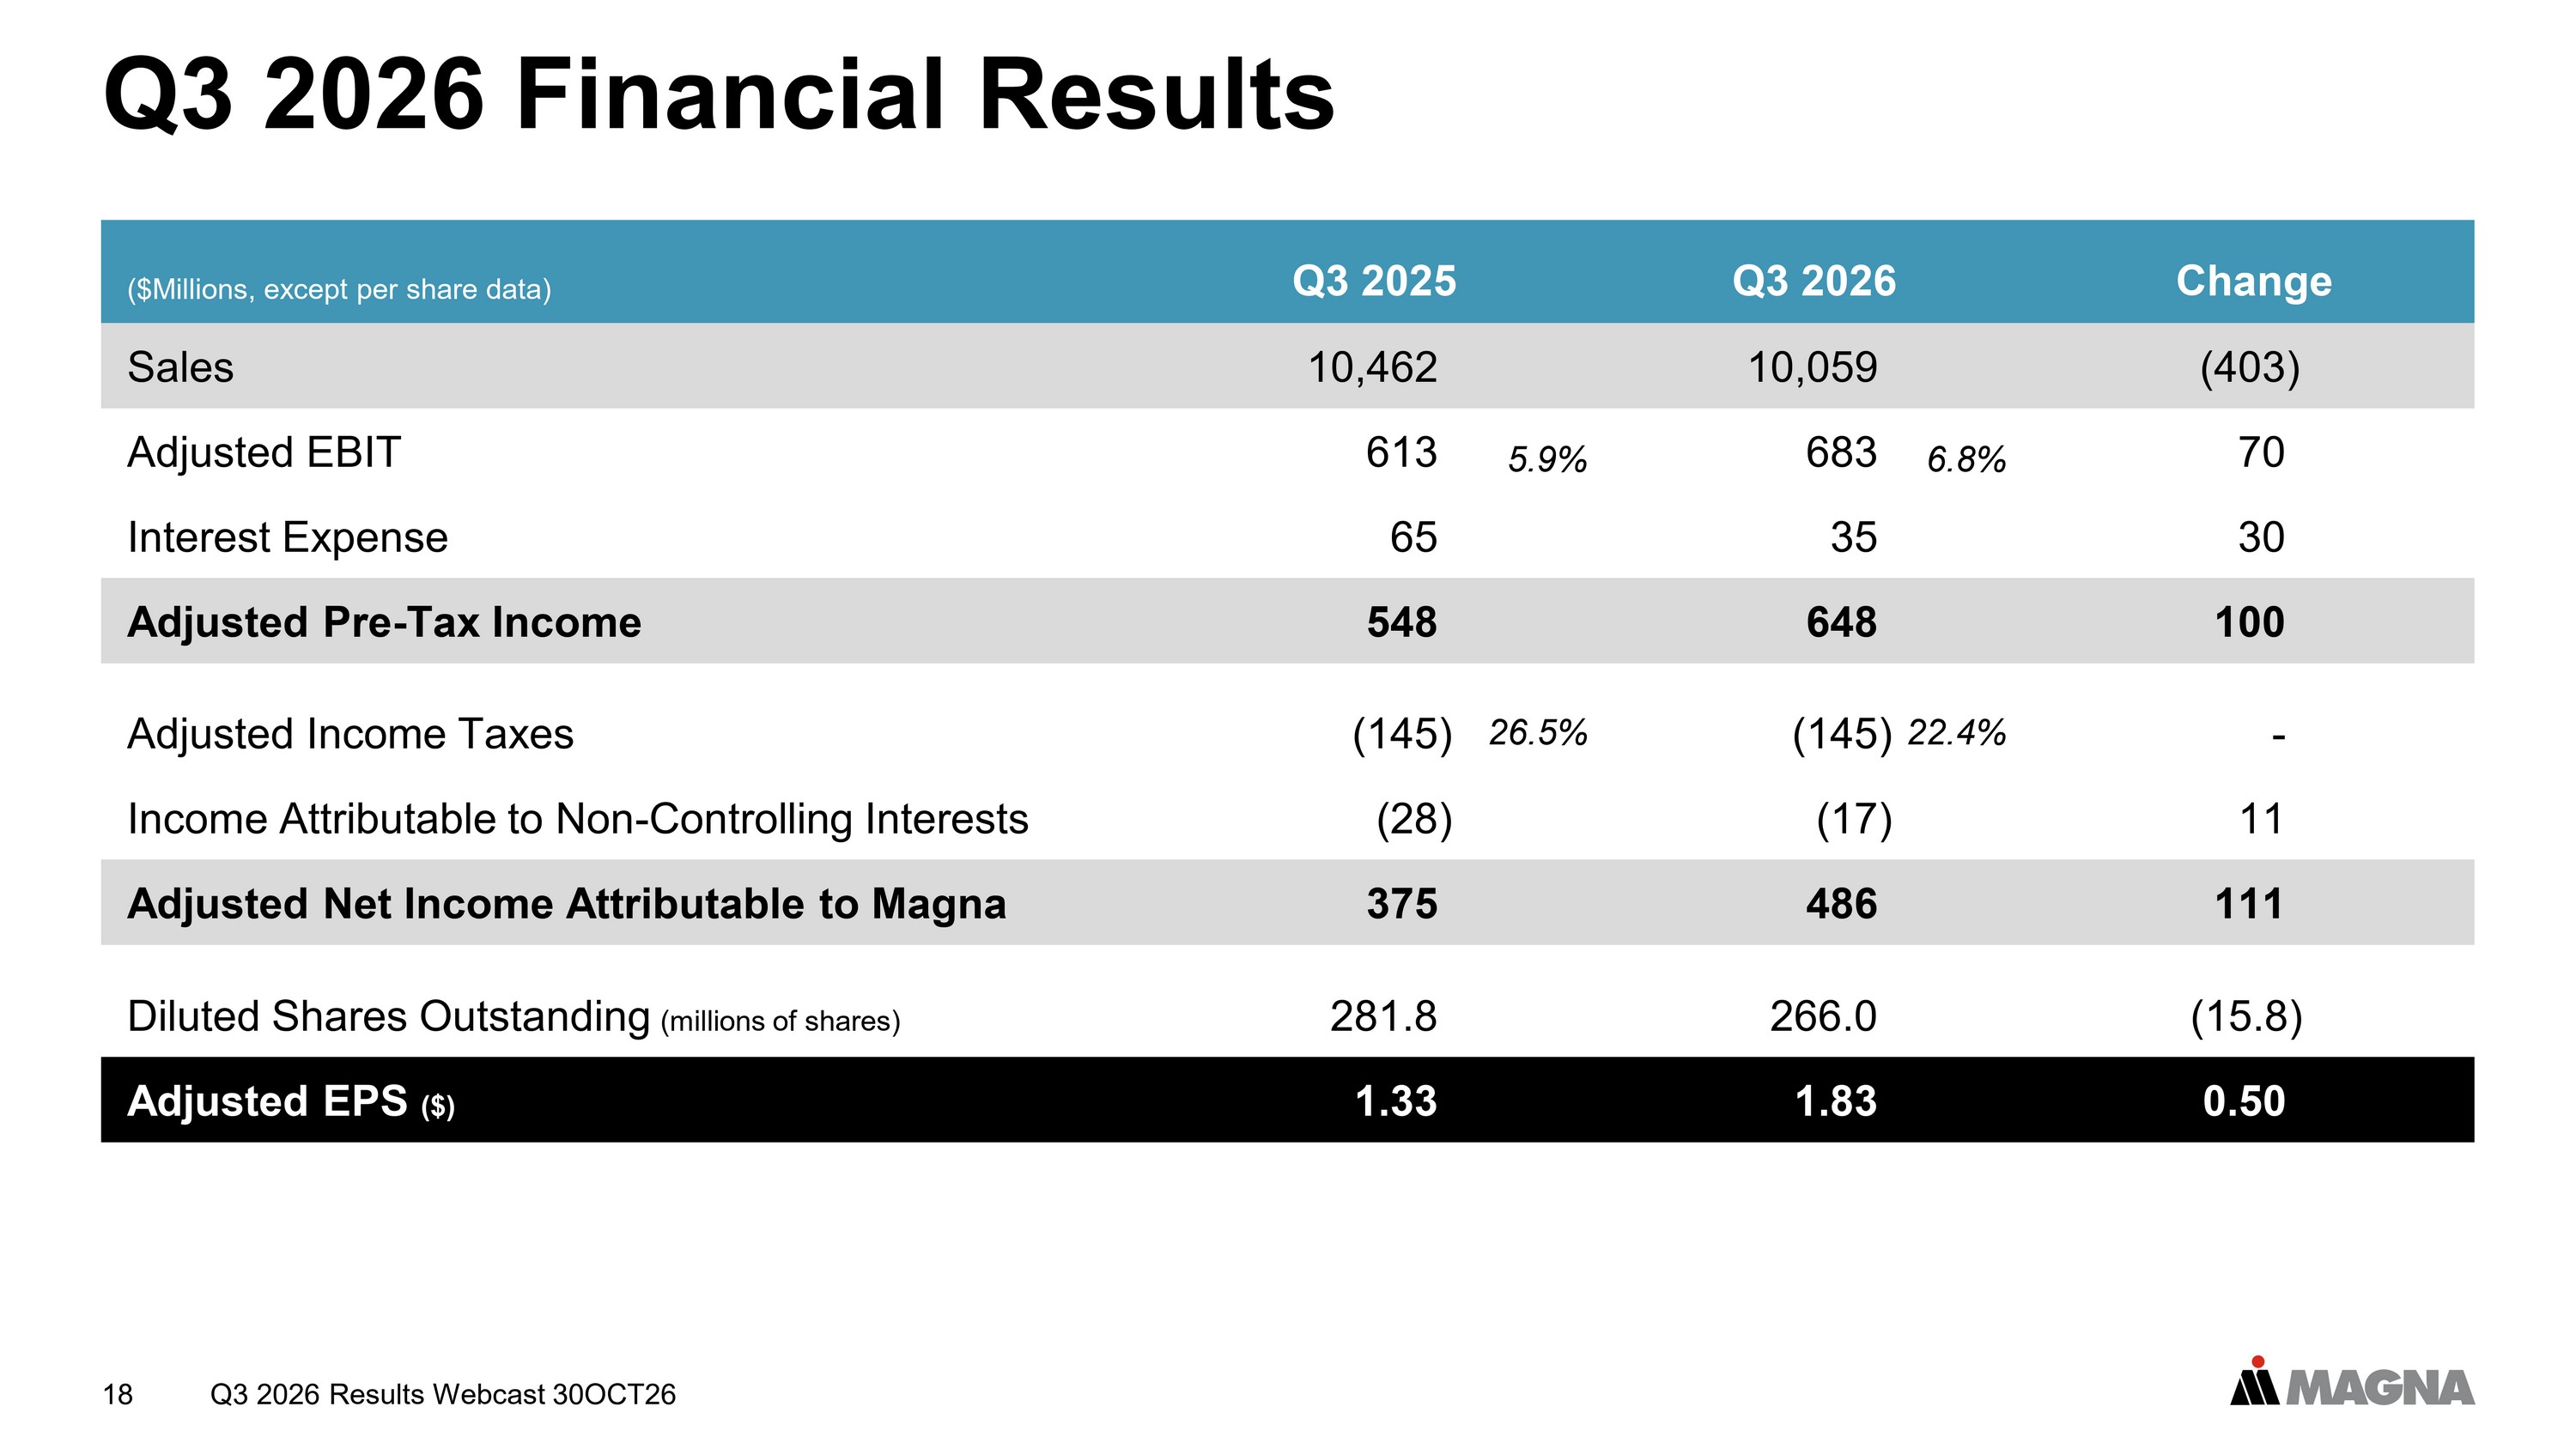
18 Q3 2026 Financial Results Change Q3 2026 Q3 2025 ($Millions, except per share data) (403) 10,059 10,462 Sales 70 683 613 Adjusted EBIT 30 35 65 Interest Expense 100 648 548 Adjusted Pre - Tax Income - (145) (145) Adjusted Income Taxes 11 (17) (28) Income Attributable to Non - Controlling Interests 111 486 375 Adjusted Net Income Attributable to Magna (15.8) 266.0 281.8 Diluted Shares Outstanding (millions of shares) 0.50 1.83 1.33 Adjusted EPS ($) 26.5% 22.4% 5.9% 6.8% Q3 2026 Results Webcast 30OCT26
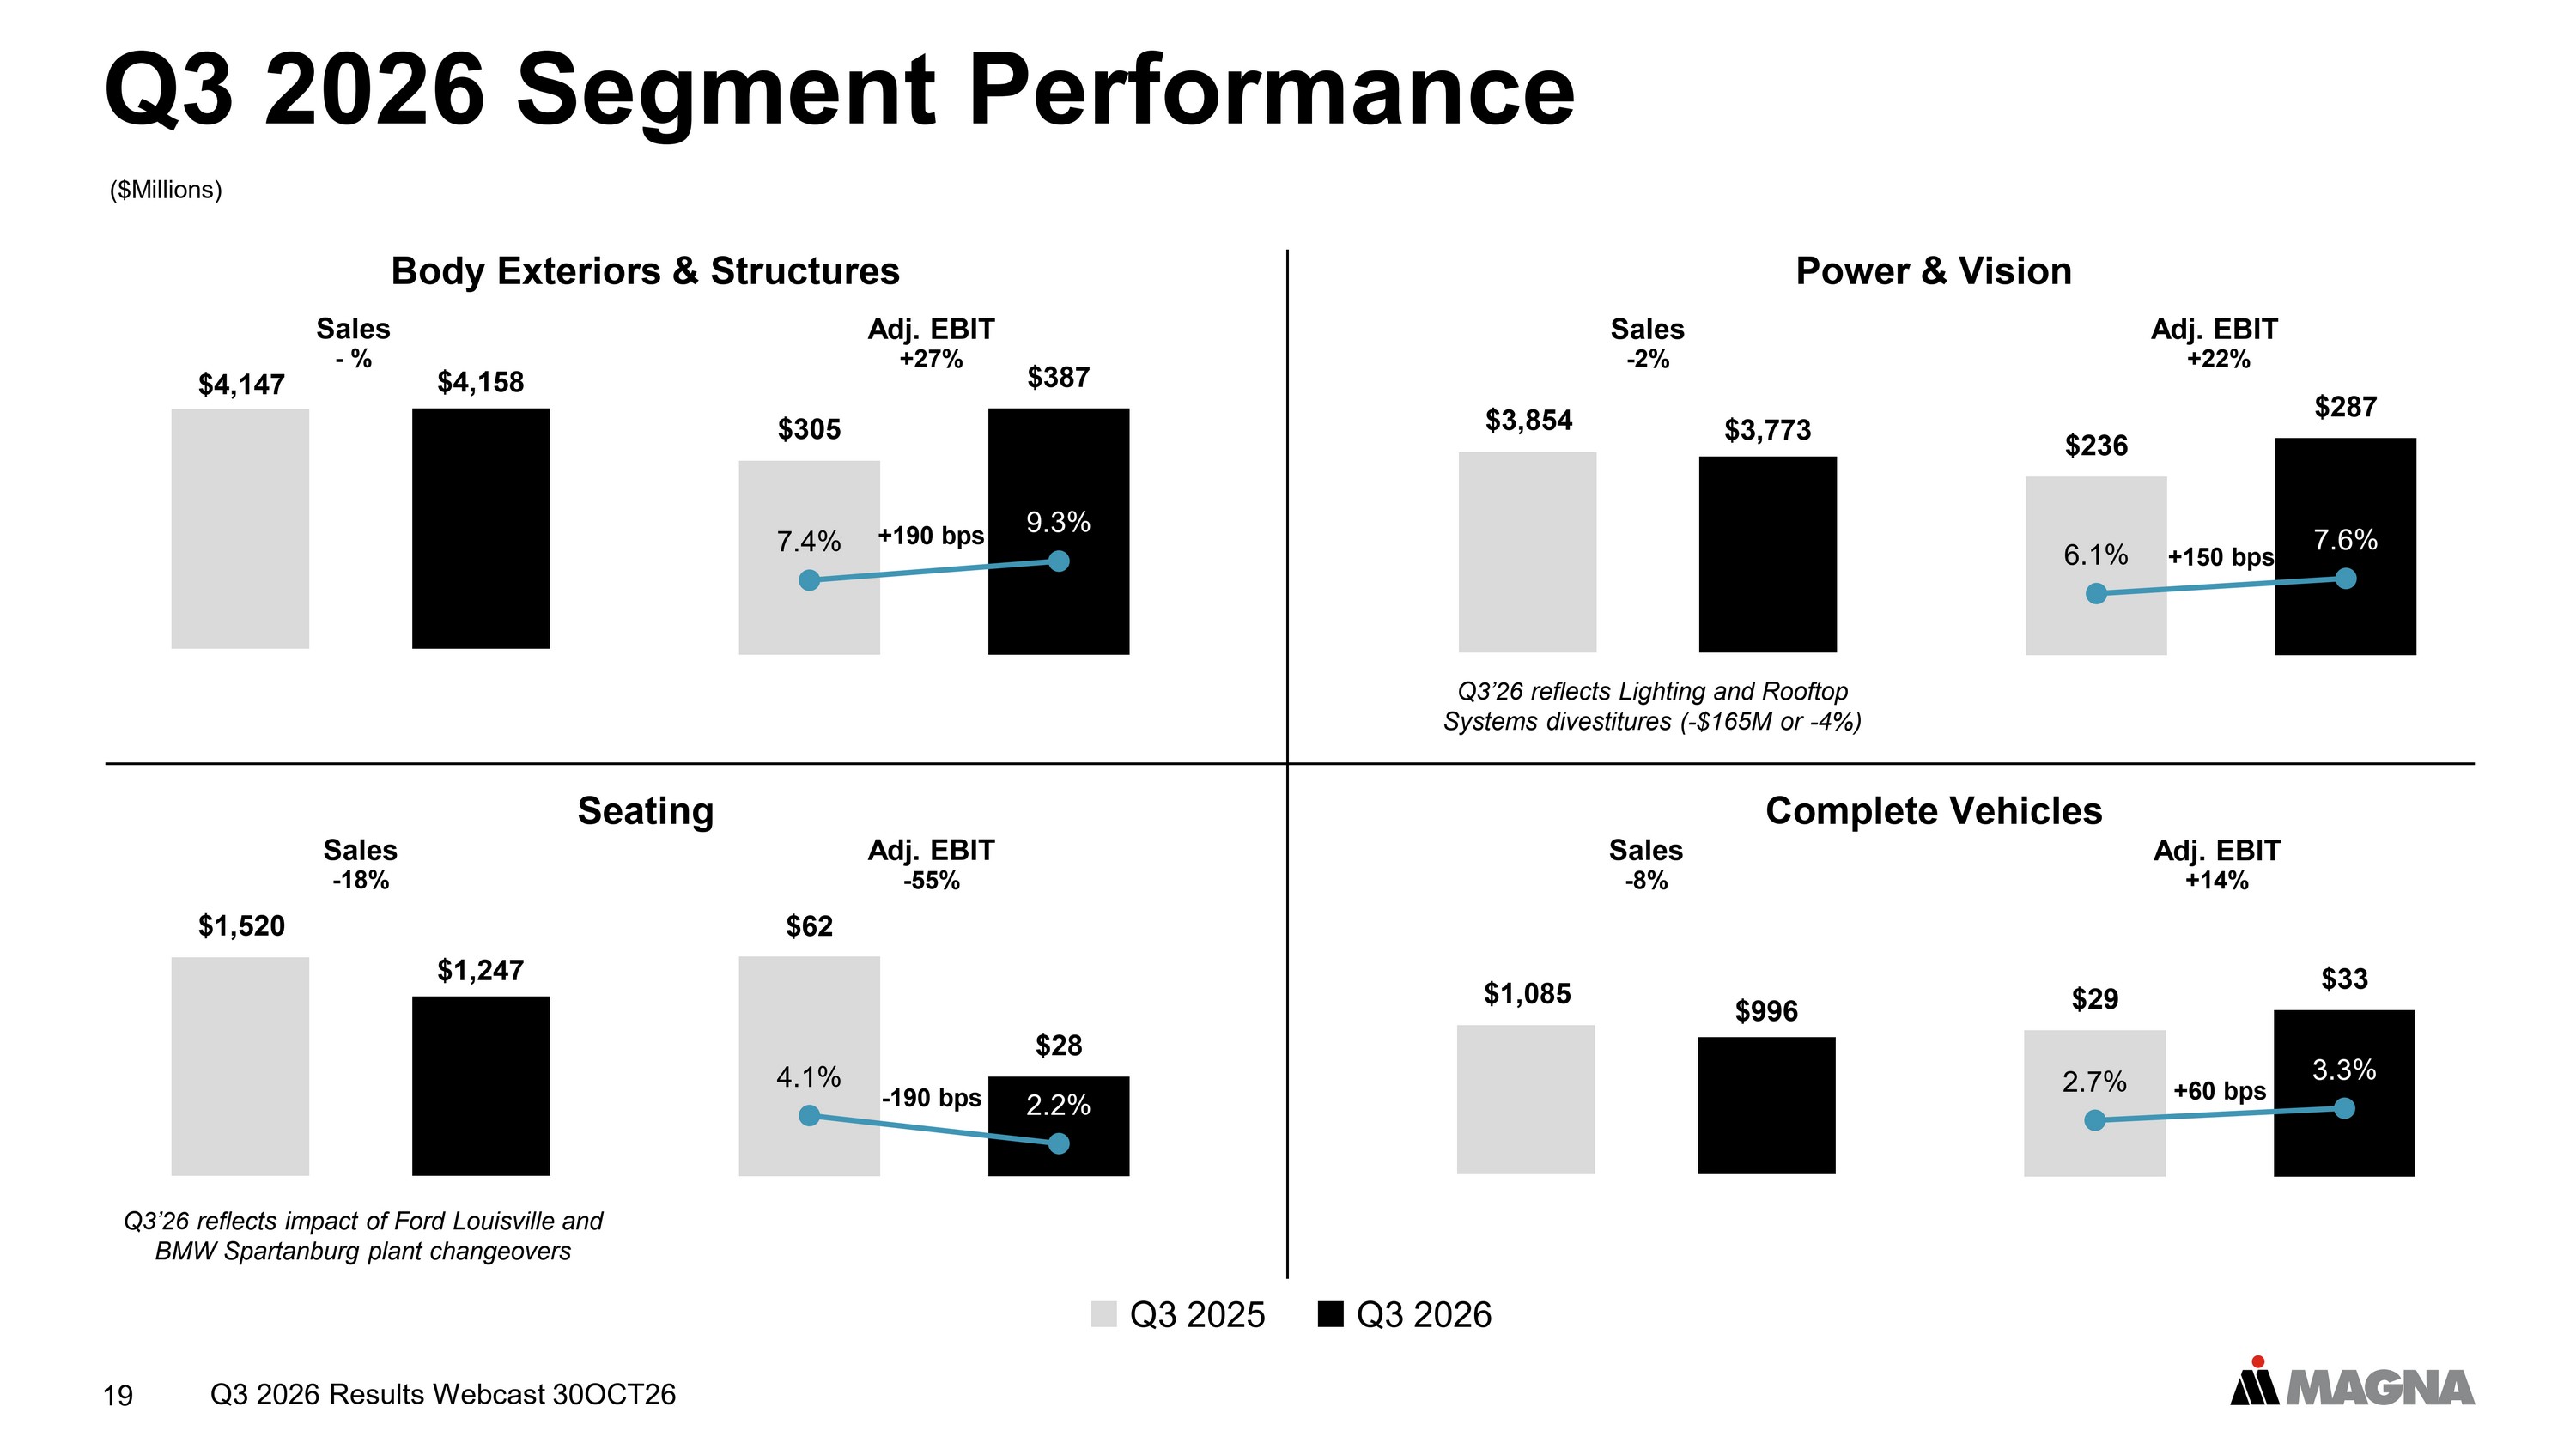
Q3 2026 Segment Performance Q3 2025 Q3 2026 Seating Power & Vision Complete Vehicles Body Exteriors & Structures $4,147 $4,158 $0,000 $0,500 $1,000 $1,500 $2,000 $2,500 $3,000 $3,500 $4,000 $4,500 $305 $387 7.4% 9.3% 0.0 0.1 0.1 0.2 0.2 0.3 0.3 $0 $50 $100 $150 $200 $250 $300 $350 $400 $450 Sales - % Adj. EBIT +27% $1,520 $1,247 $0 $200 $400 $600 $800 $1,000 $1,200 $1,400 $1,600 $1,800 $62 $28 4.1% 2.2% 0.0 0.0 0.0 0.1 0.1 0.1 0.1 0.1 0.2 0.2 $0 $10 $20 $30 $40 $50 $60 $70 Sales - 18% Adj. EBIT - 55% $3,854 $3,773 $0 $500 $1,000 $1,500 $2,000 $2,500 $3,000 $3,500 $4,000 $4,500 $5,000 $236 $287 6.1% 7.6% 0.0 0.1 0.1 0.2 0.2 0.3 0.3 $0 $50 $100 $150 $200 $250 $300 $350 $400 Sales - 2% Adj. EBIT +22% $1,085 $996 $0 $200 $400 $600 $800 $1,000 $1,200 $1,400 $1,600 $1,800 $29 $33 2.7% 3.3% 0.0 0.0 0.0 0.1 0.1 0.1 0.1 0.1 $0 $10 $20 $30 $40 $50 $60 Sales - 8% Adj. EBIT +14% +190 bps - 190 bps +150 bps ($Millions) 19 +60 bps Q3 2026 Results Webcast 30OCT26 Q3’26 reflects Lighting and Rooftop Systems divestitures ( - $165M or - 4%) Q3’26 reflects impact of Ford Louisville and BMW Spartanburg plant changeovers
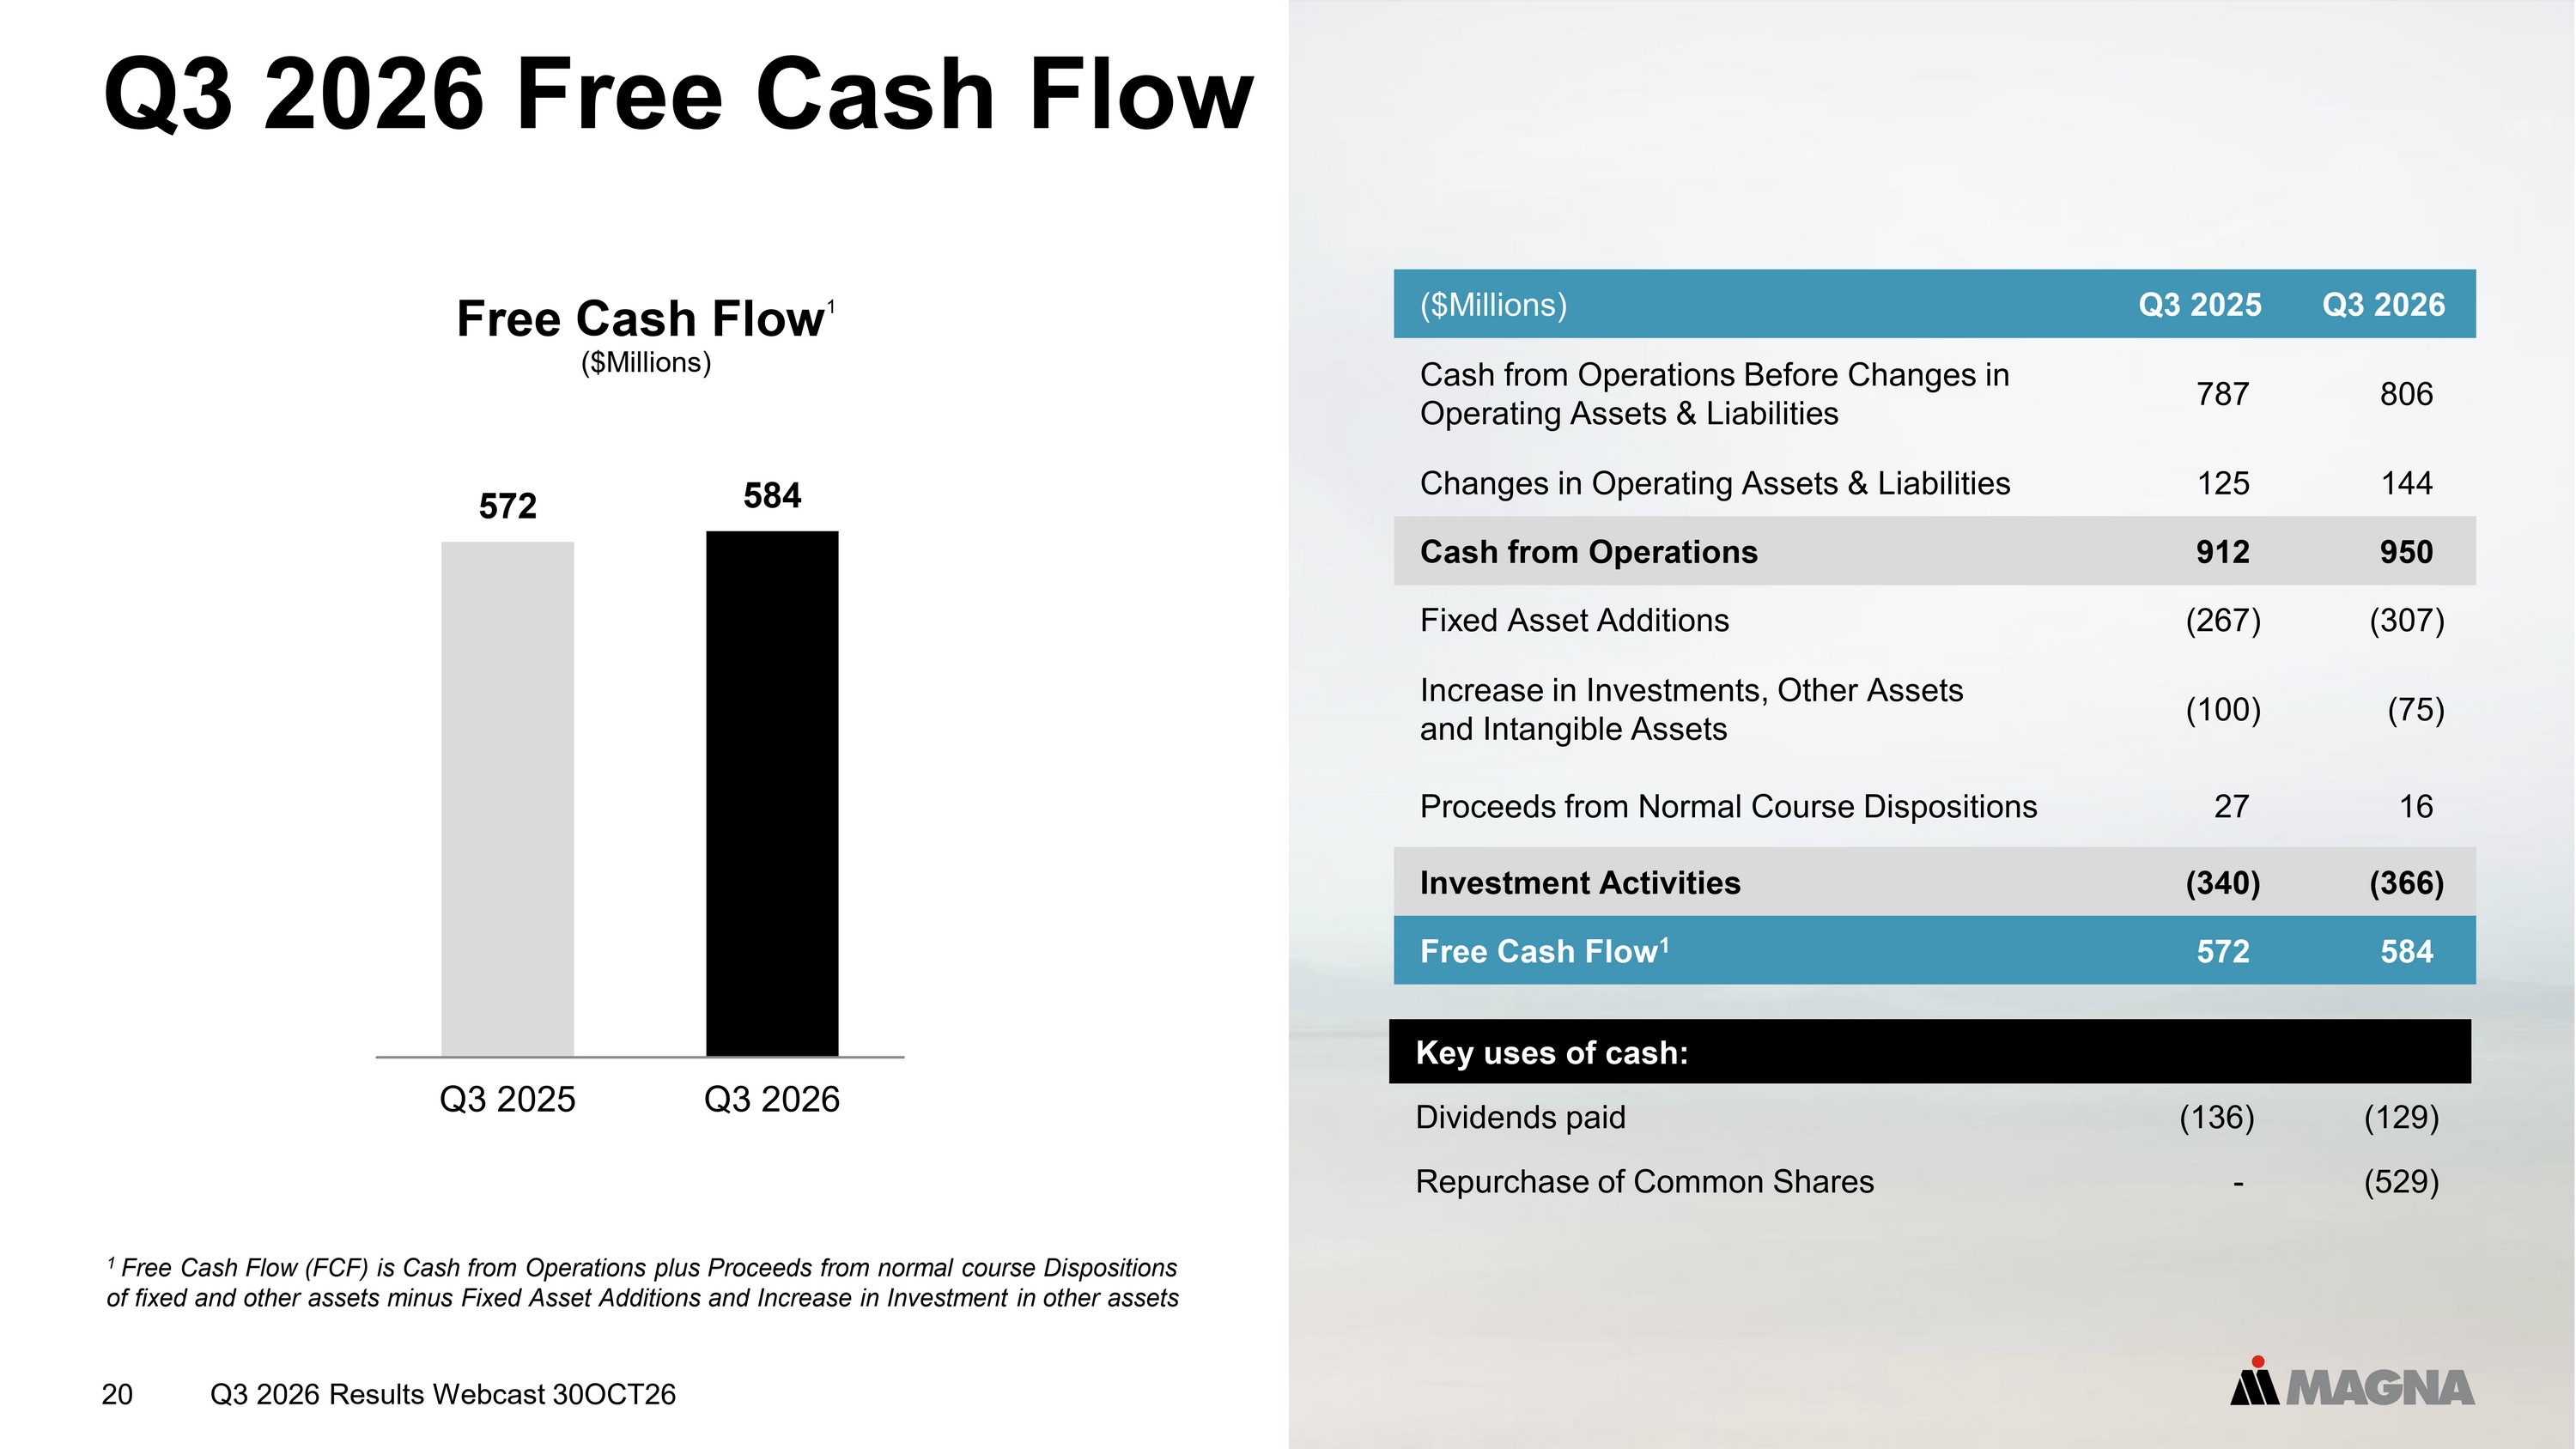
20 Q3 2026 Free Cash Flow Free Cash Flow 1 ($Millions) 572 584 0 100 200 300 400 500 600 700 Q3 2025 Q3 2026 1 Free Cash Flow (FCF) is Cash from Operations plus Proceeds from normal course Dispositions of fixed and other assets minus Fixed Asset Additions and Increase in Investment in other assets Key uses of cash: (129) (136) Dividends paid (529) - Repurchase of Common Shares Q3 2026 Q3 2025 ($Millions) 806 787 Cash from Operations Before Changes in Operating Assets & Liabilities 144 125 Changes in Operating Assets & Liabilities 950 912 Cash from Operations (307) (267) Fixed Asset Additions (75) (100) Increase in Investments, Other Assets and Intangible Assets 16 27 Proceeds from Normal Course Dispositions (366) (340) Investment Activities 584 572 Free Cash Flow 1 Q3 2026 Results Webcast 30OCT26
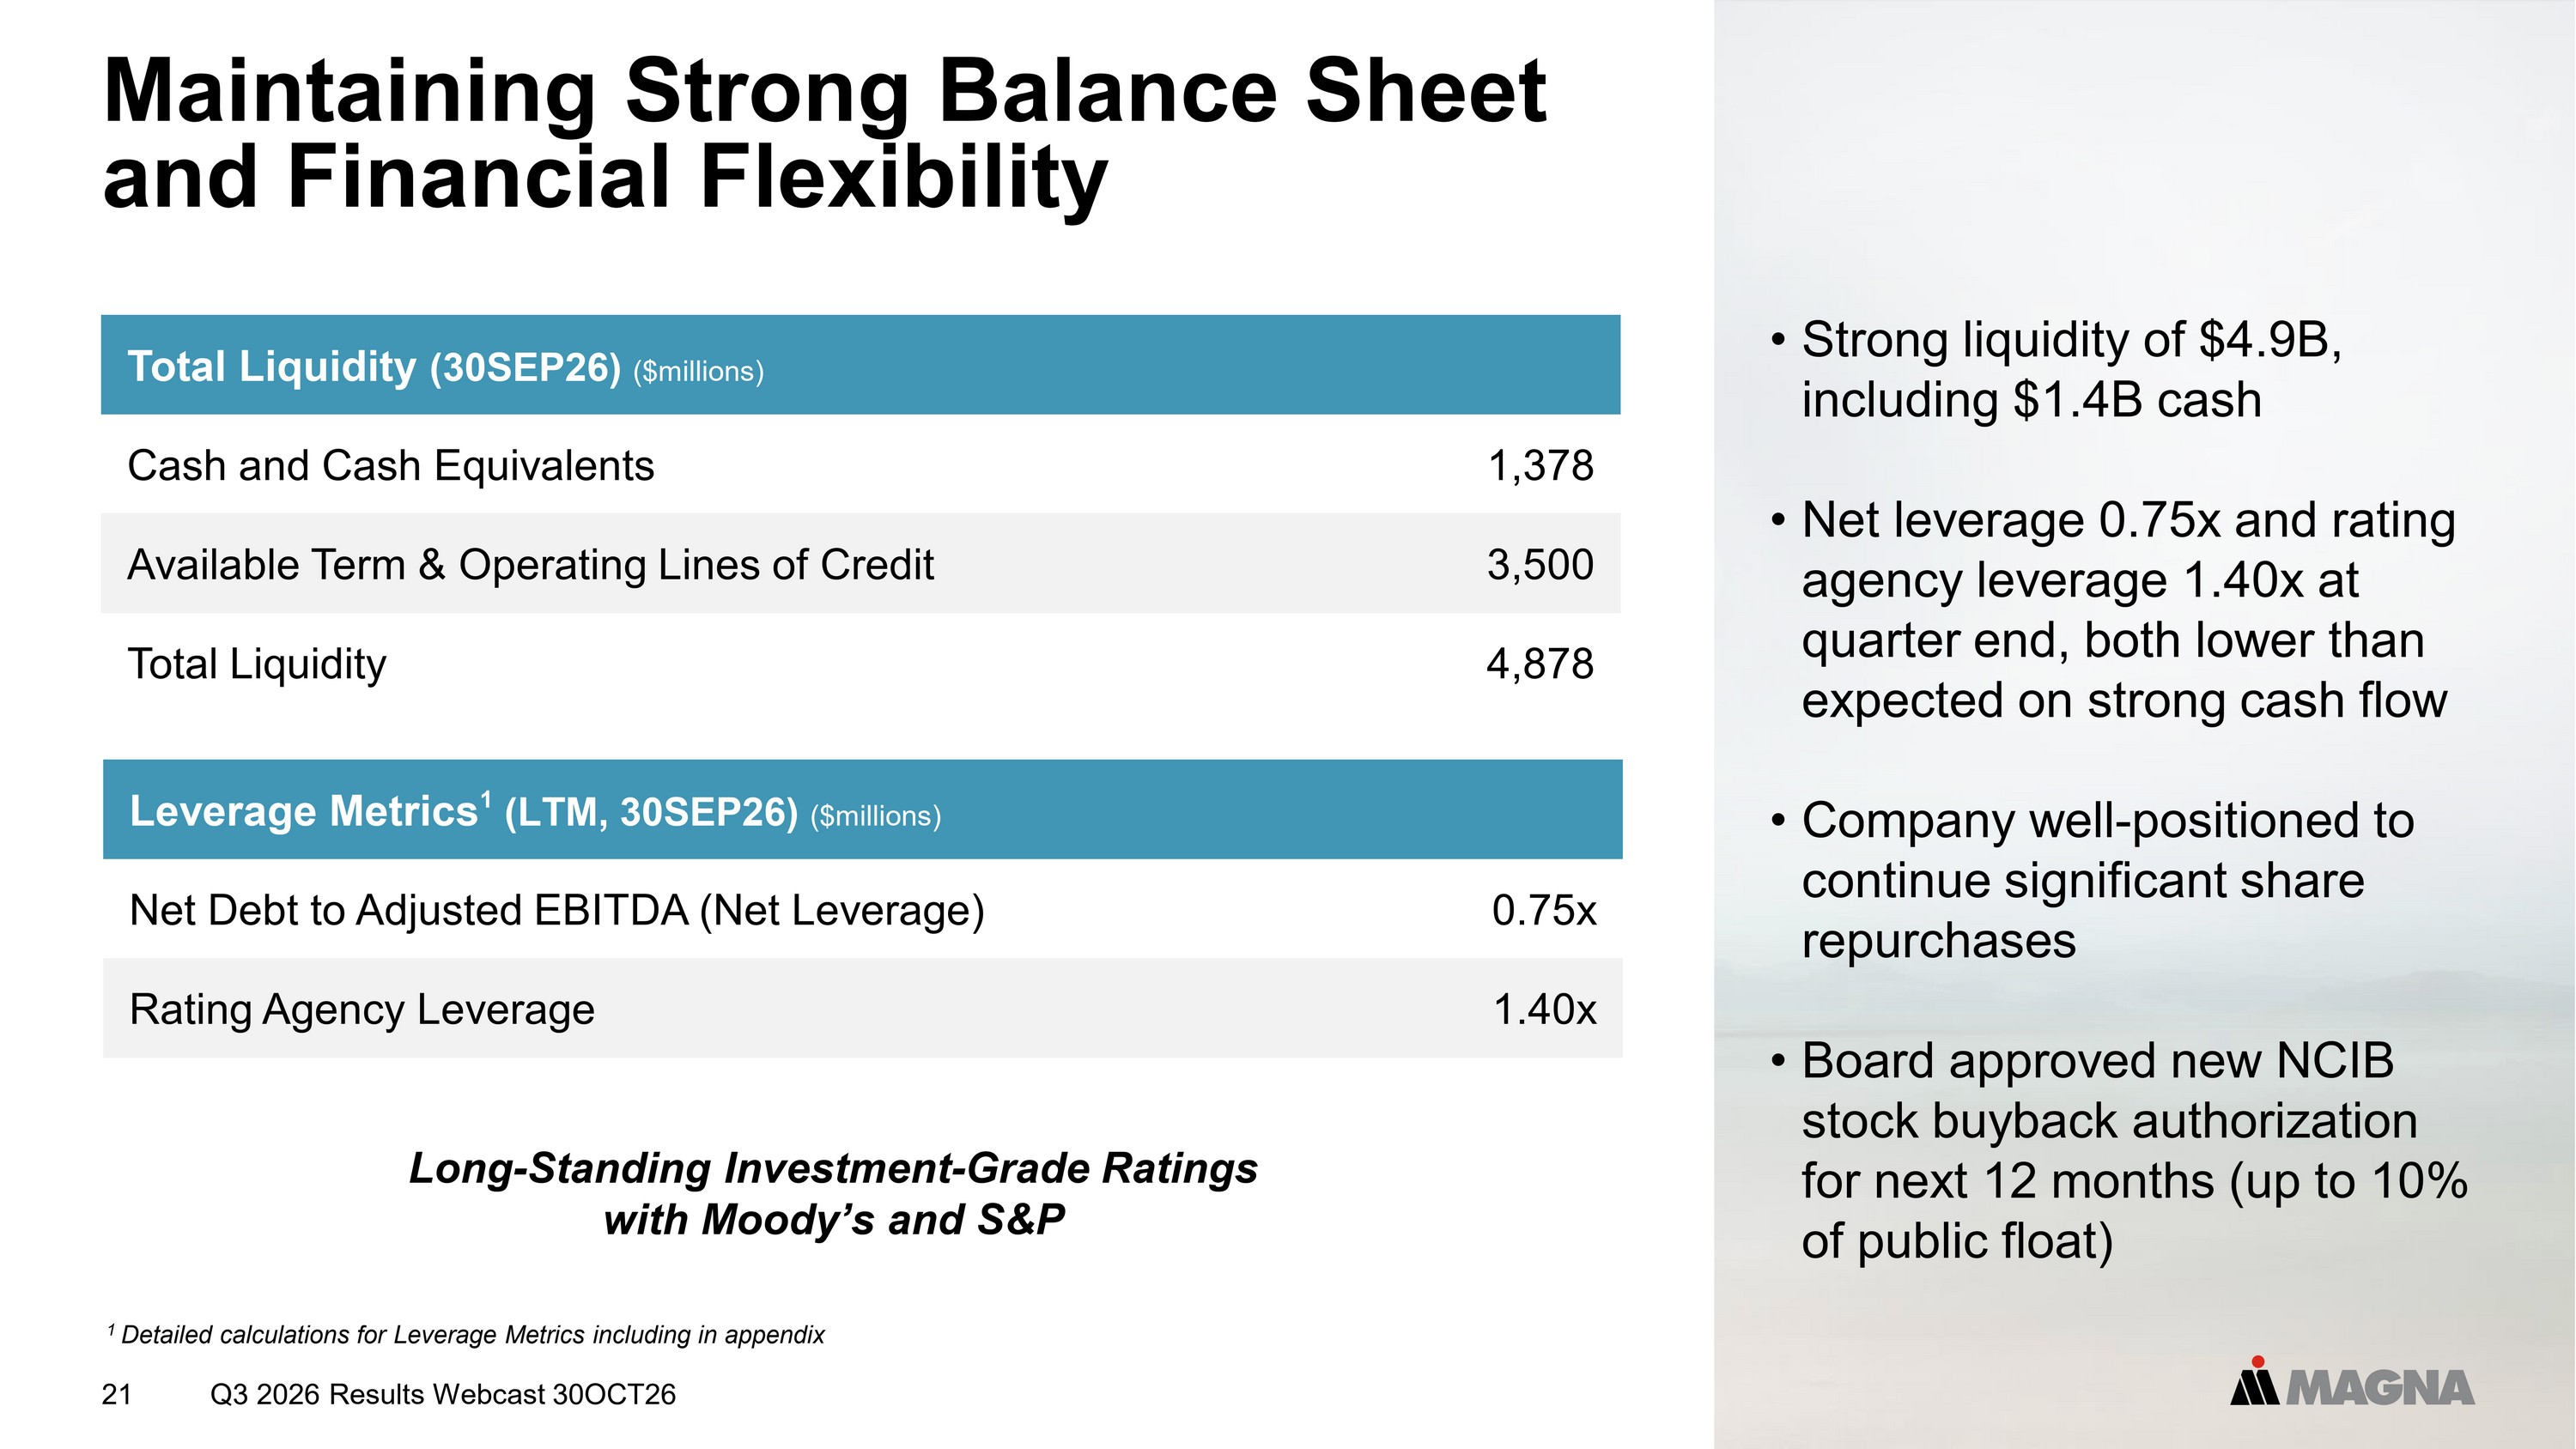
Maintaining Strong Balance Sheet and Financial Flexibility 21 Leverage Metrics 1 (LTM, 30SEP26) ($millions) 0.75x Net Debt to Adjusted EBITDA (Net Leverage) 1.40x Rating Agency Leverage Total Liquidity (30SEP26) ($millions) 1,378 Cash and Cash Equivalents 3,500 Available Term & Operating Lines of Credit 4,878 Total Liquidity Long - Standing Investment - Grade Ratings with Moody’s and S&P • Strong liquidity of $4.9B, including $1.4B cash • Net leverage 0.75x and rating agency leverage 1.40x at quarter end, both lower than expected on strong cash flow • Company well - positioned to continue significant share repurchases • Board approved new NCIB stock buyback authorization for next 12 months (up to 10% of public float) Q3 2026 Results Webcast 30OCT26 1 Detailed calculations for Leverage Metrics including in appendix
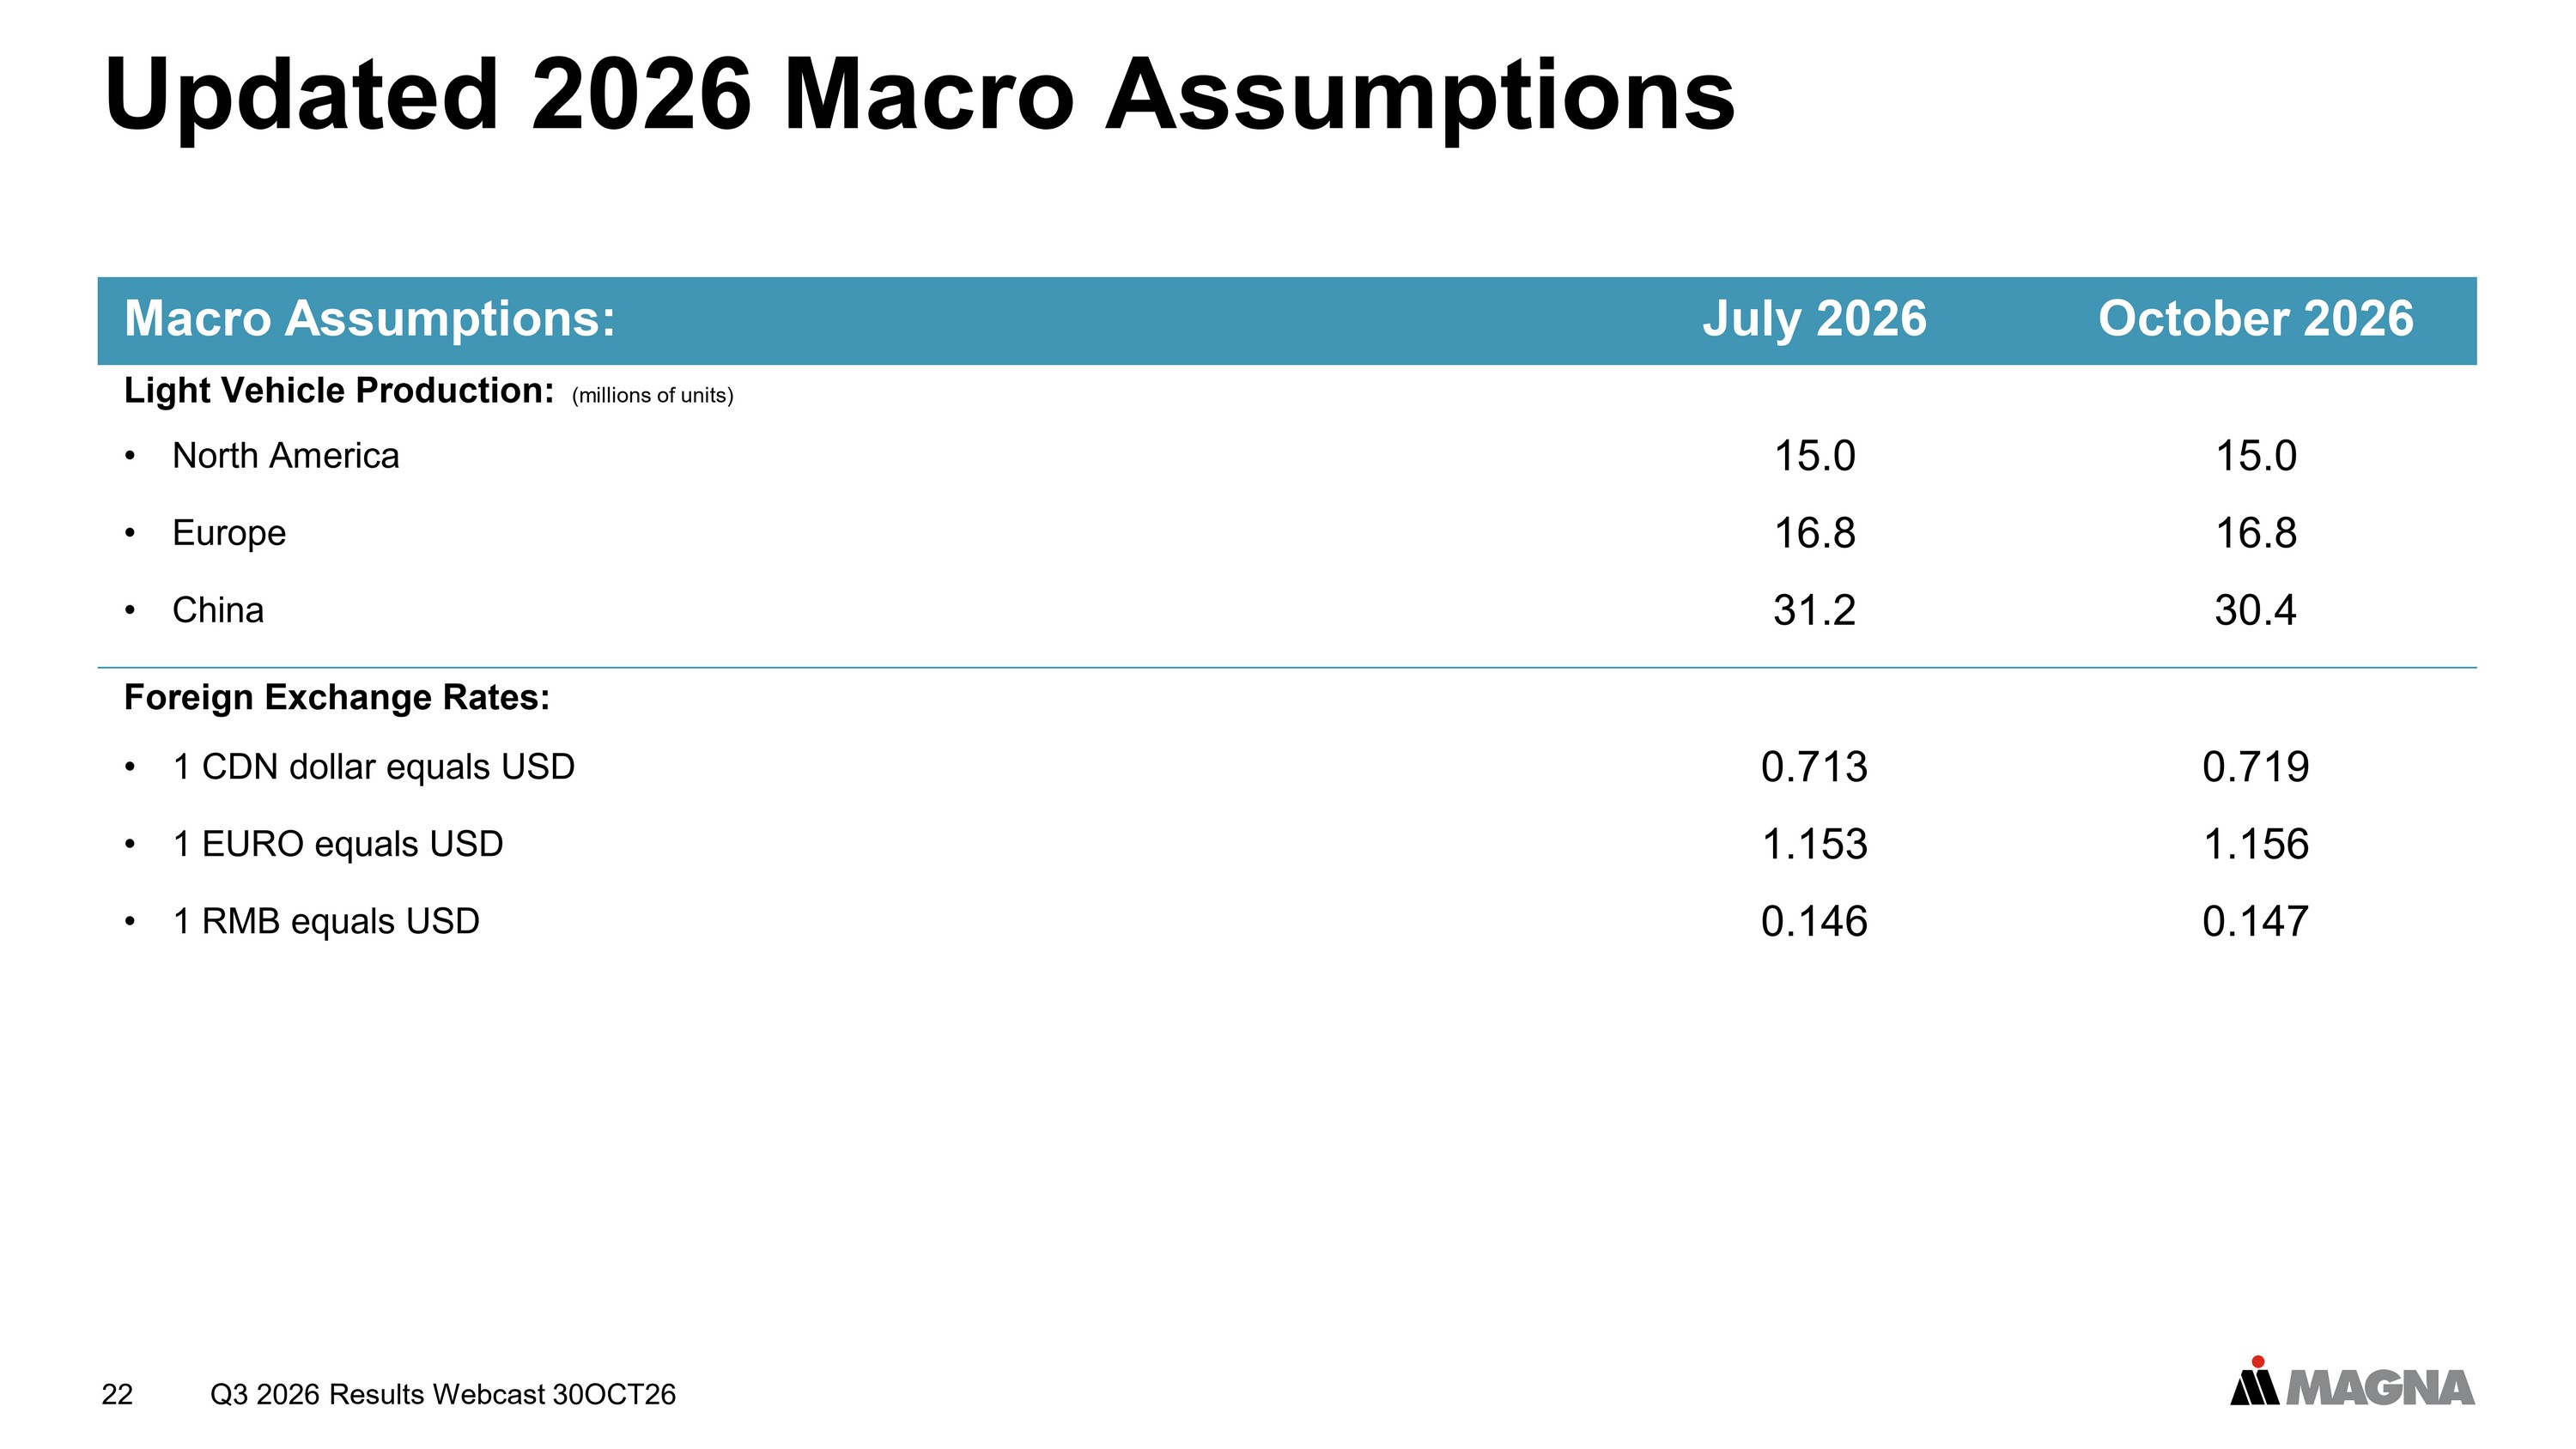
22 Updated 2026 Macro Assumptions October 2026 July 2026 Macro Assumptions: Light Vehicle Production: (millions of units) 15.0 15.0 • North America 16.8 16.8 • Europe 30.4 31.2 • China Foreign Exchange Rates: 0.719 0.713 • 1 CDN dollar equals USD 1.156 1.153 • 1 EURO equals USD 0.147 0.146 • 1 RMB equals USD Q3 2026 Results Webcast 30OCT26
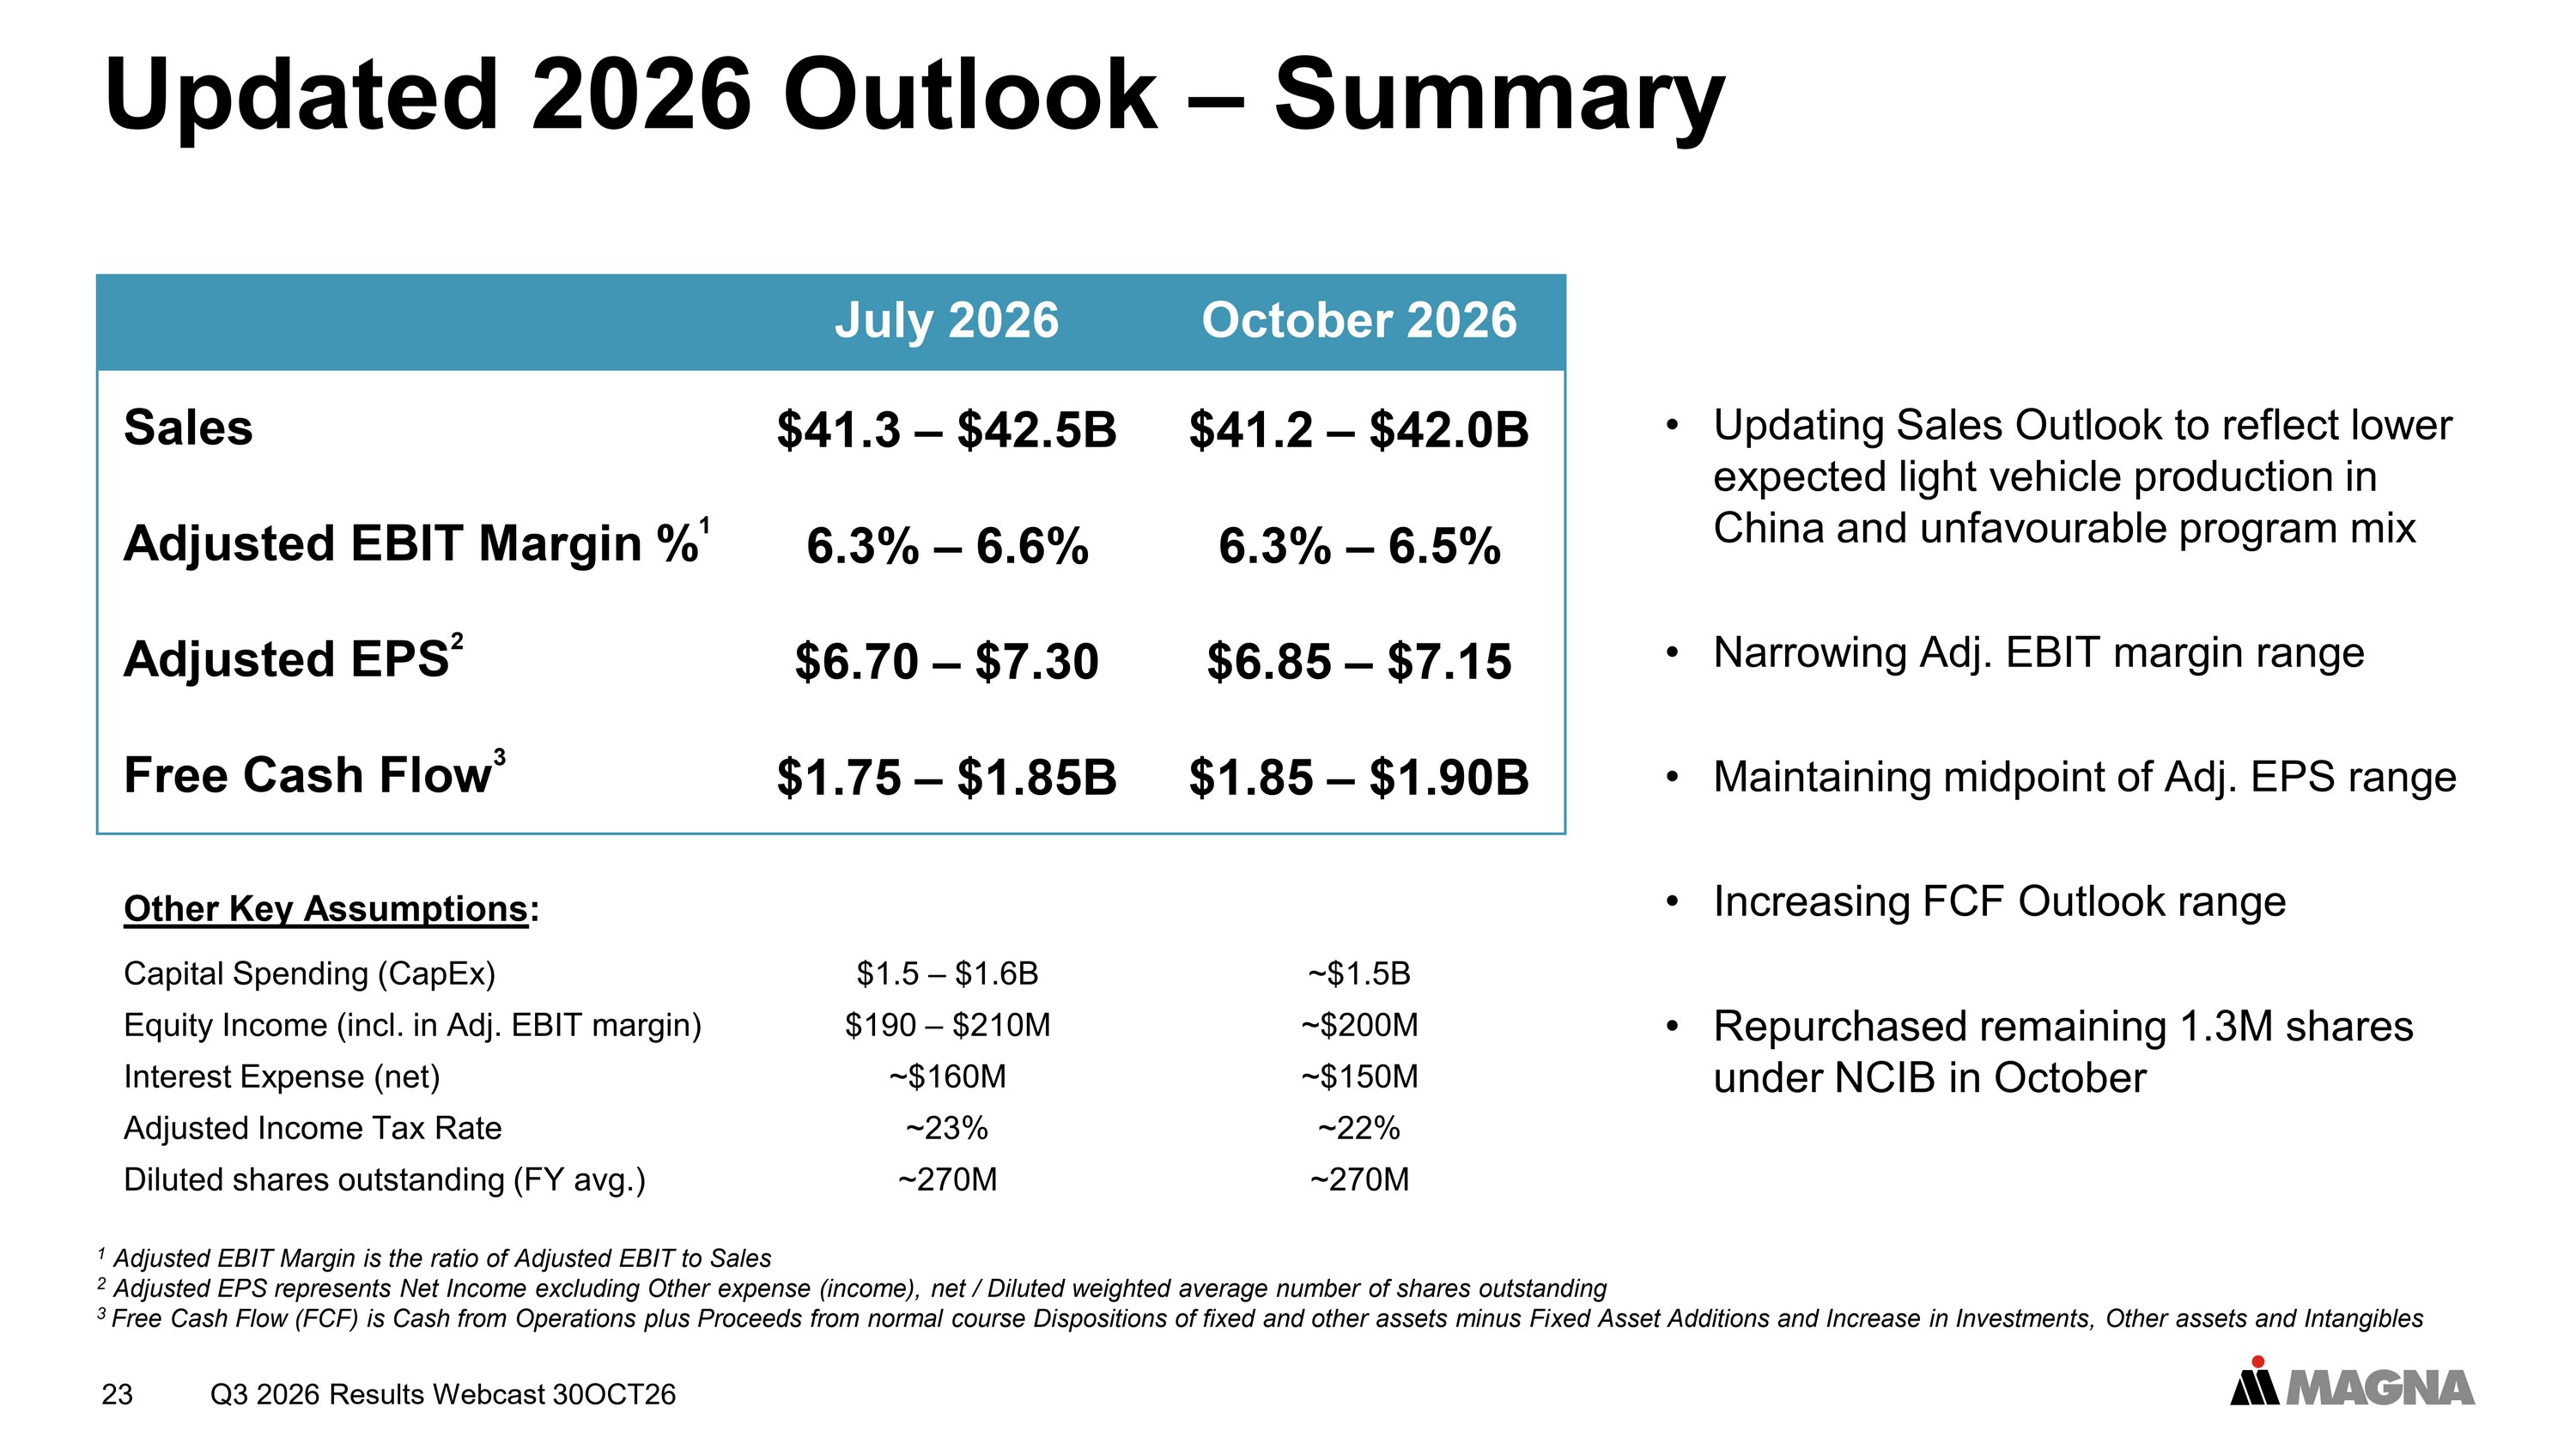
23 Updated 2026 Outlook – Summary October 2026 July 2026 $41.2 – $42.0B $41.3 – $42.5B Sales 6.3% – 6.5% 6.3% – 6.6% Adjusted EBIT Margin % 1 $6.85 – $7.15 $6.70 – $7.30 Adjusted EPS 2 $1.85 – $1.90B $1.75 – $1.85B Free Cash Flow 3 1 Adjusted EBIT Margin is the ratio of Adjusted EBIT to Sales 2 Adjusted EPS represents Net Income excluding Other expense (income), net / Diluted weighted average number of shares outstand in g 3 Free Cash Flow (FCF) is Cash from Operations plus Proceeds from normal course Dispositions of fixed and other assets minus Fi xed Asset Additions and Increase in Investments, Other assets and Intangibles • Updating Sales Outlook to reflect lower expected light vehicle production in China and unfavourable program mix • Narrowing Adj. EBIT margin range • Maintaining midpoint of Adj. EPS range • Increasing FCF Outlook range • Repurchased remaining 1.3M shares under NCIB in October Other Key Assumptions : ~$1.5B $1.5 – $1.6B Capital Spending ( CapEx ) ~$200M $190 – $210M Equity Income (incl. in Adj. EBIT margin) ~$150M ~$160M Interest Expense (net) ~22% ~23% Adjusted Income Tax Rate ~270M ~270M Diluted shares outstanding (FY avg.) Q3 2026 Results Webcast 30OCT26
President & Chief Executive Officer Swamy Kotagiri 24 Q3 2026 Results Webcast 30OCT26
• Delivered meaningful Adjusted EBIT Margin and Adjusted EPS growth • Generated solid free cash flow, reinforcing the quality and sustainability of earnings Strong Q3 2026 with margin expansion, EPS growth and cash generation In Summary Q3 2026 Results Webcast 30OCT26 25
• Updated 2026 outlook, reflecting confidence in ongoing operating performance • Continued focus on margin expansion, EPS growth and strong free cash flow • Executing a disciplined capital allocation strategy, including significant return of capital • Completed previous NCIB program, Board approved new NCIB Positioned for continued margin expansion, EPS growth and shareholder returns In Summary Q3 2026 Results Webcast 30OCT26 26
Wednesday, November 11, 2026 New York, NY Magna Investor Day 27 Q3 2026 Results Webcast 30OCT26
28 Q&A Q3 2026 Results Webcast 30OCT26
29 Q3 2026 Results Appendix Q3 2026 Results Webcast 30OCT26
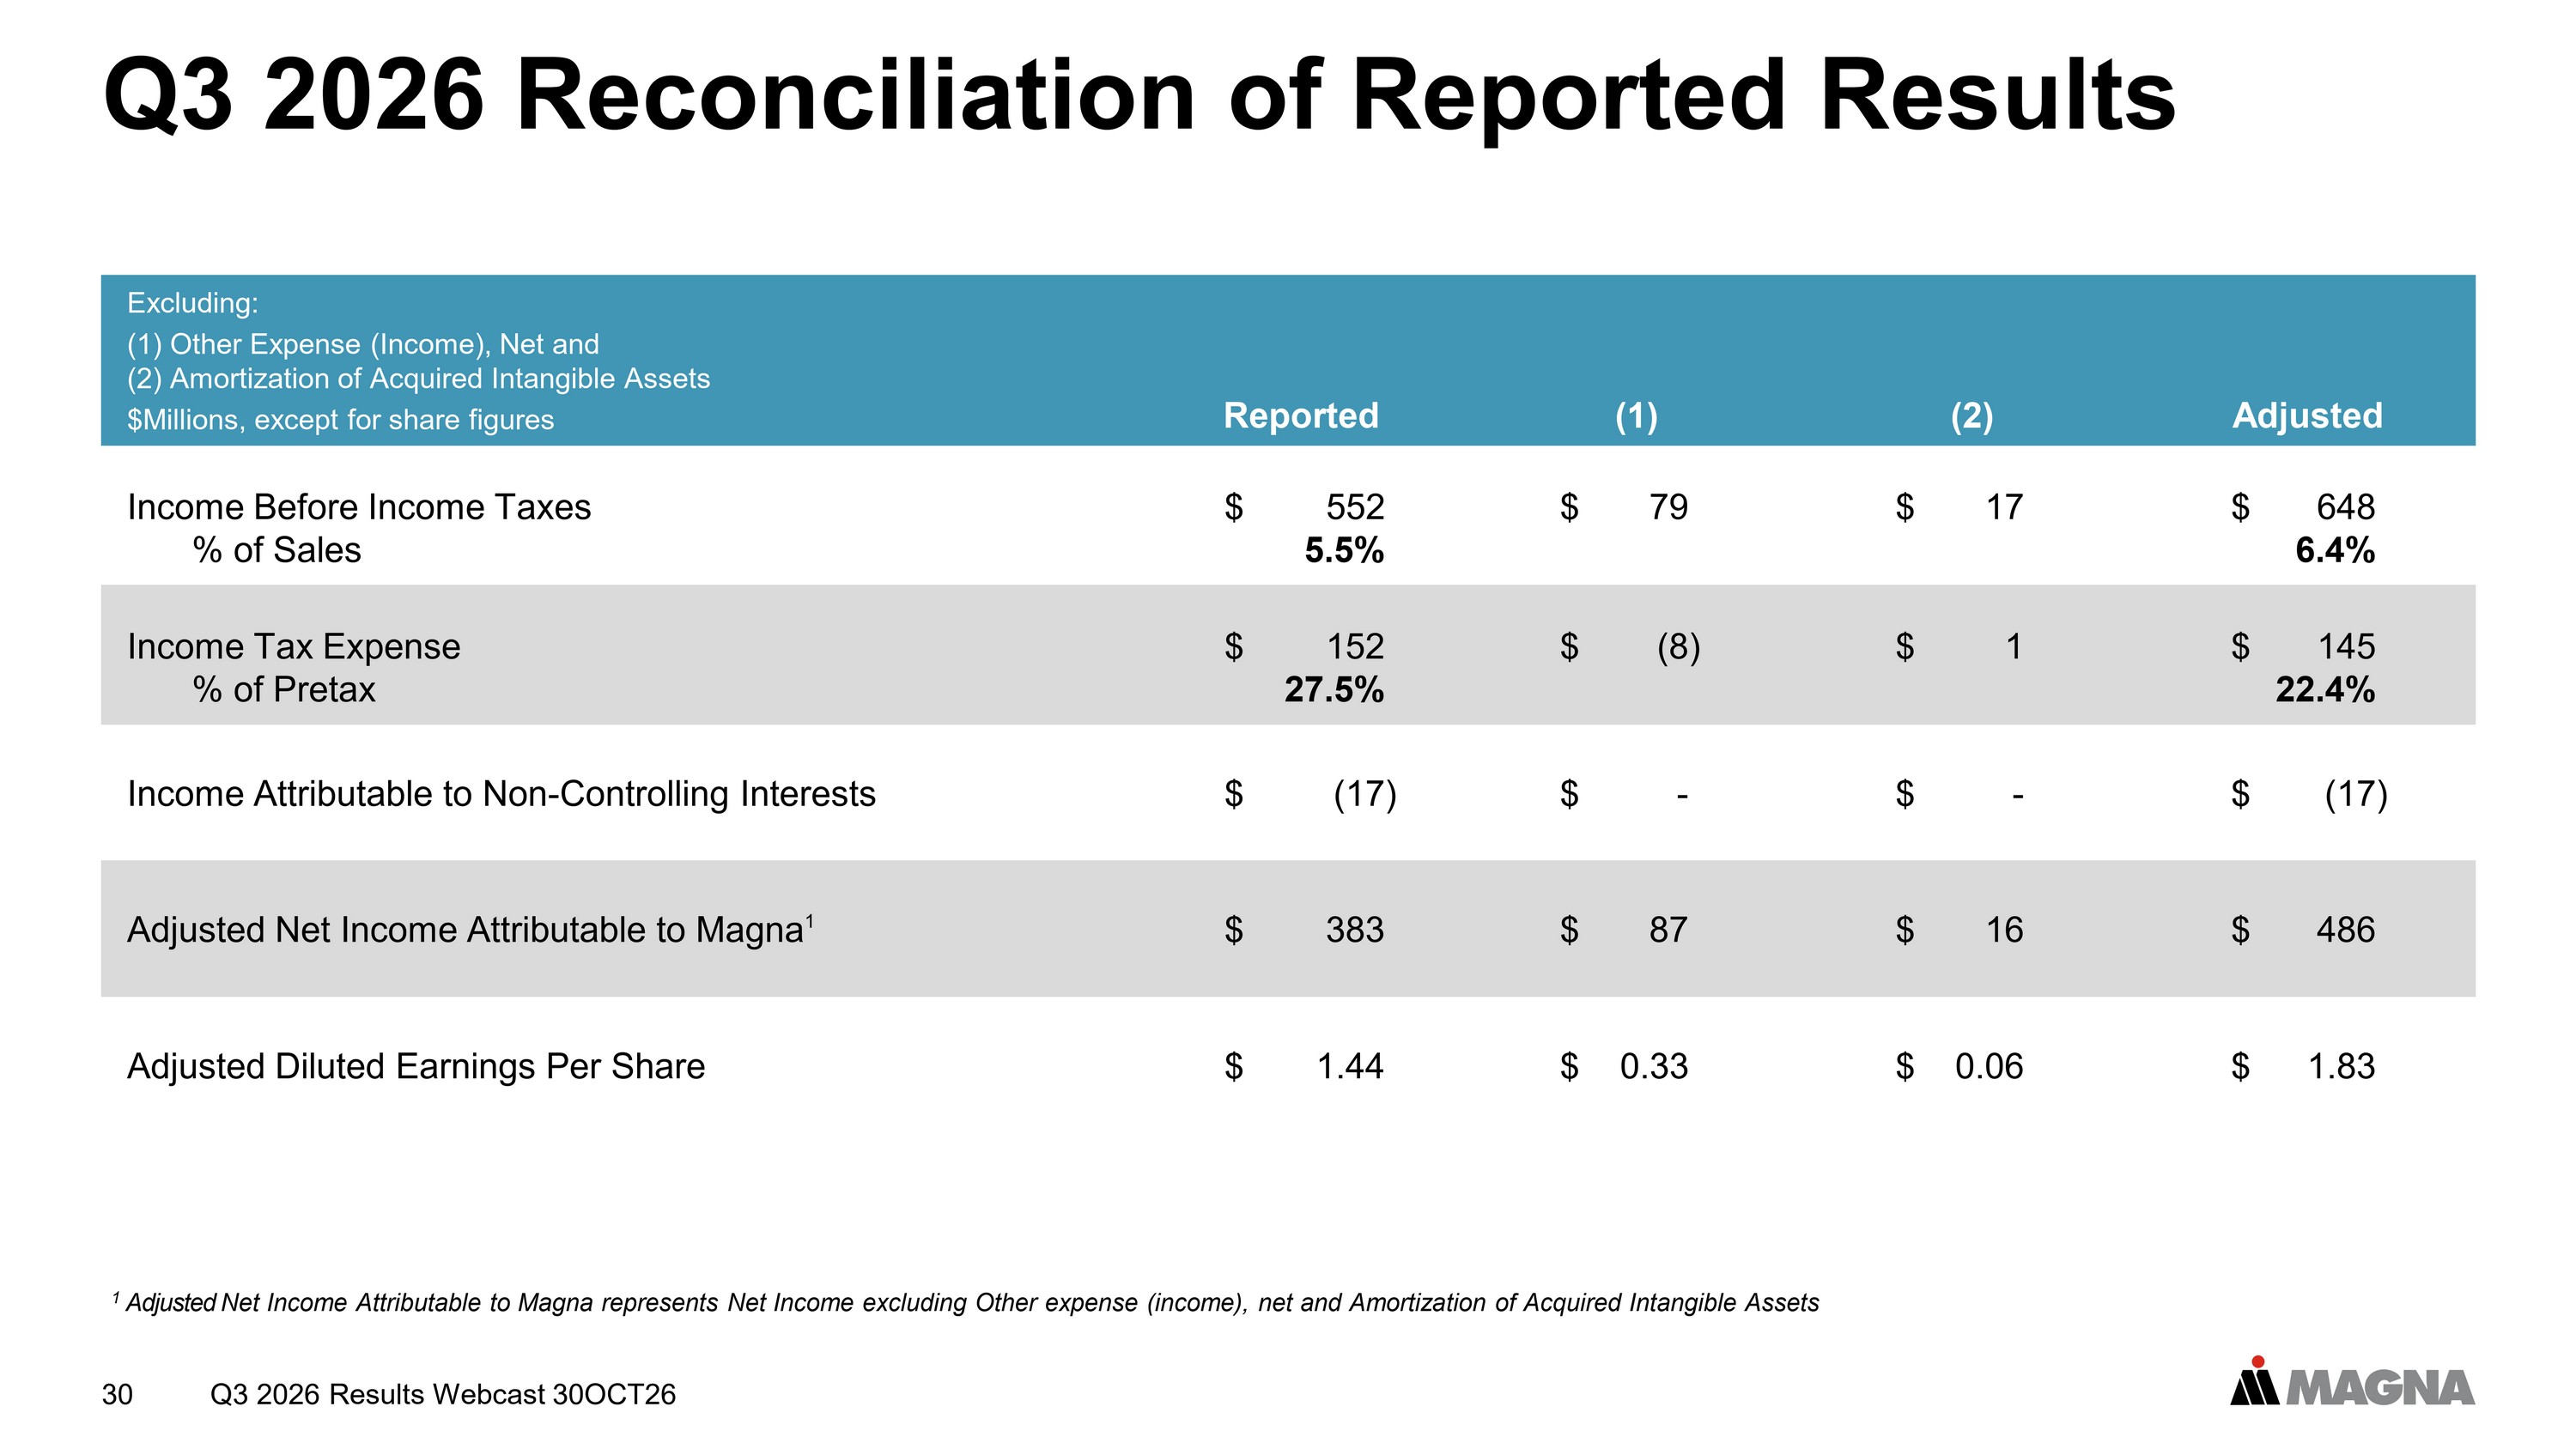
30 Q3 2026 Reconciliation of Reported Results Adjusted (2) (1) Reported Excluding: (1) Other Expense (Income), Net and (2) Amortization of Acquired Intangible Assets $Millions, except for share figures $ 648 $ 17 $ 79 $ 552 Income Before Income Taxes 6.4% 5.5% % of Sales $ 145 $ 1 $ (8) $ 152 Income Tax Expense 22.4% 27.5% % of Pretax $ (17) $ - $ - $ (17) Income Attributable to Non - Controlling Interests $ 486 $ 16 $ 87 $ 383 Adjusted Net Income Attributable to Magna 1 $ 1.83 $ 0.06 $ 0.33 $ 1.44 Adjusted Diluted Earnings Per Share 1 Adjusted Net Income Attributable to Magna represents Net Income excluding Other expense (income), net and Amortization of Acquired Int ang ible Assets Q3 2026 Results Webcast 30OCT26
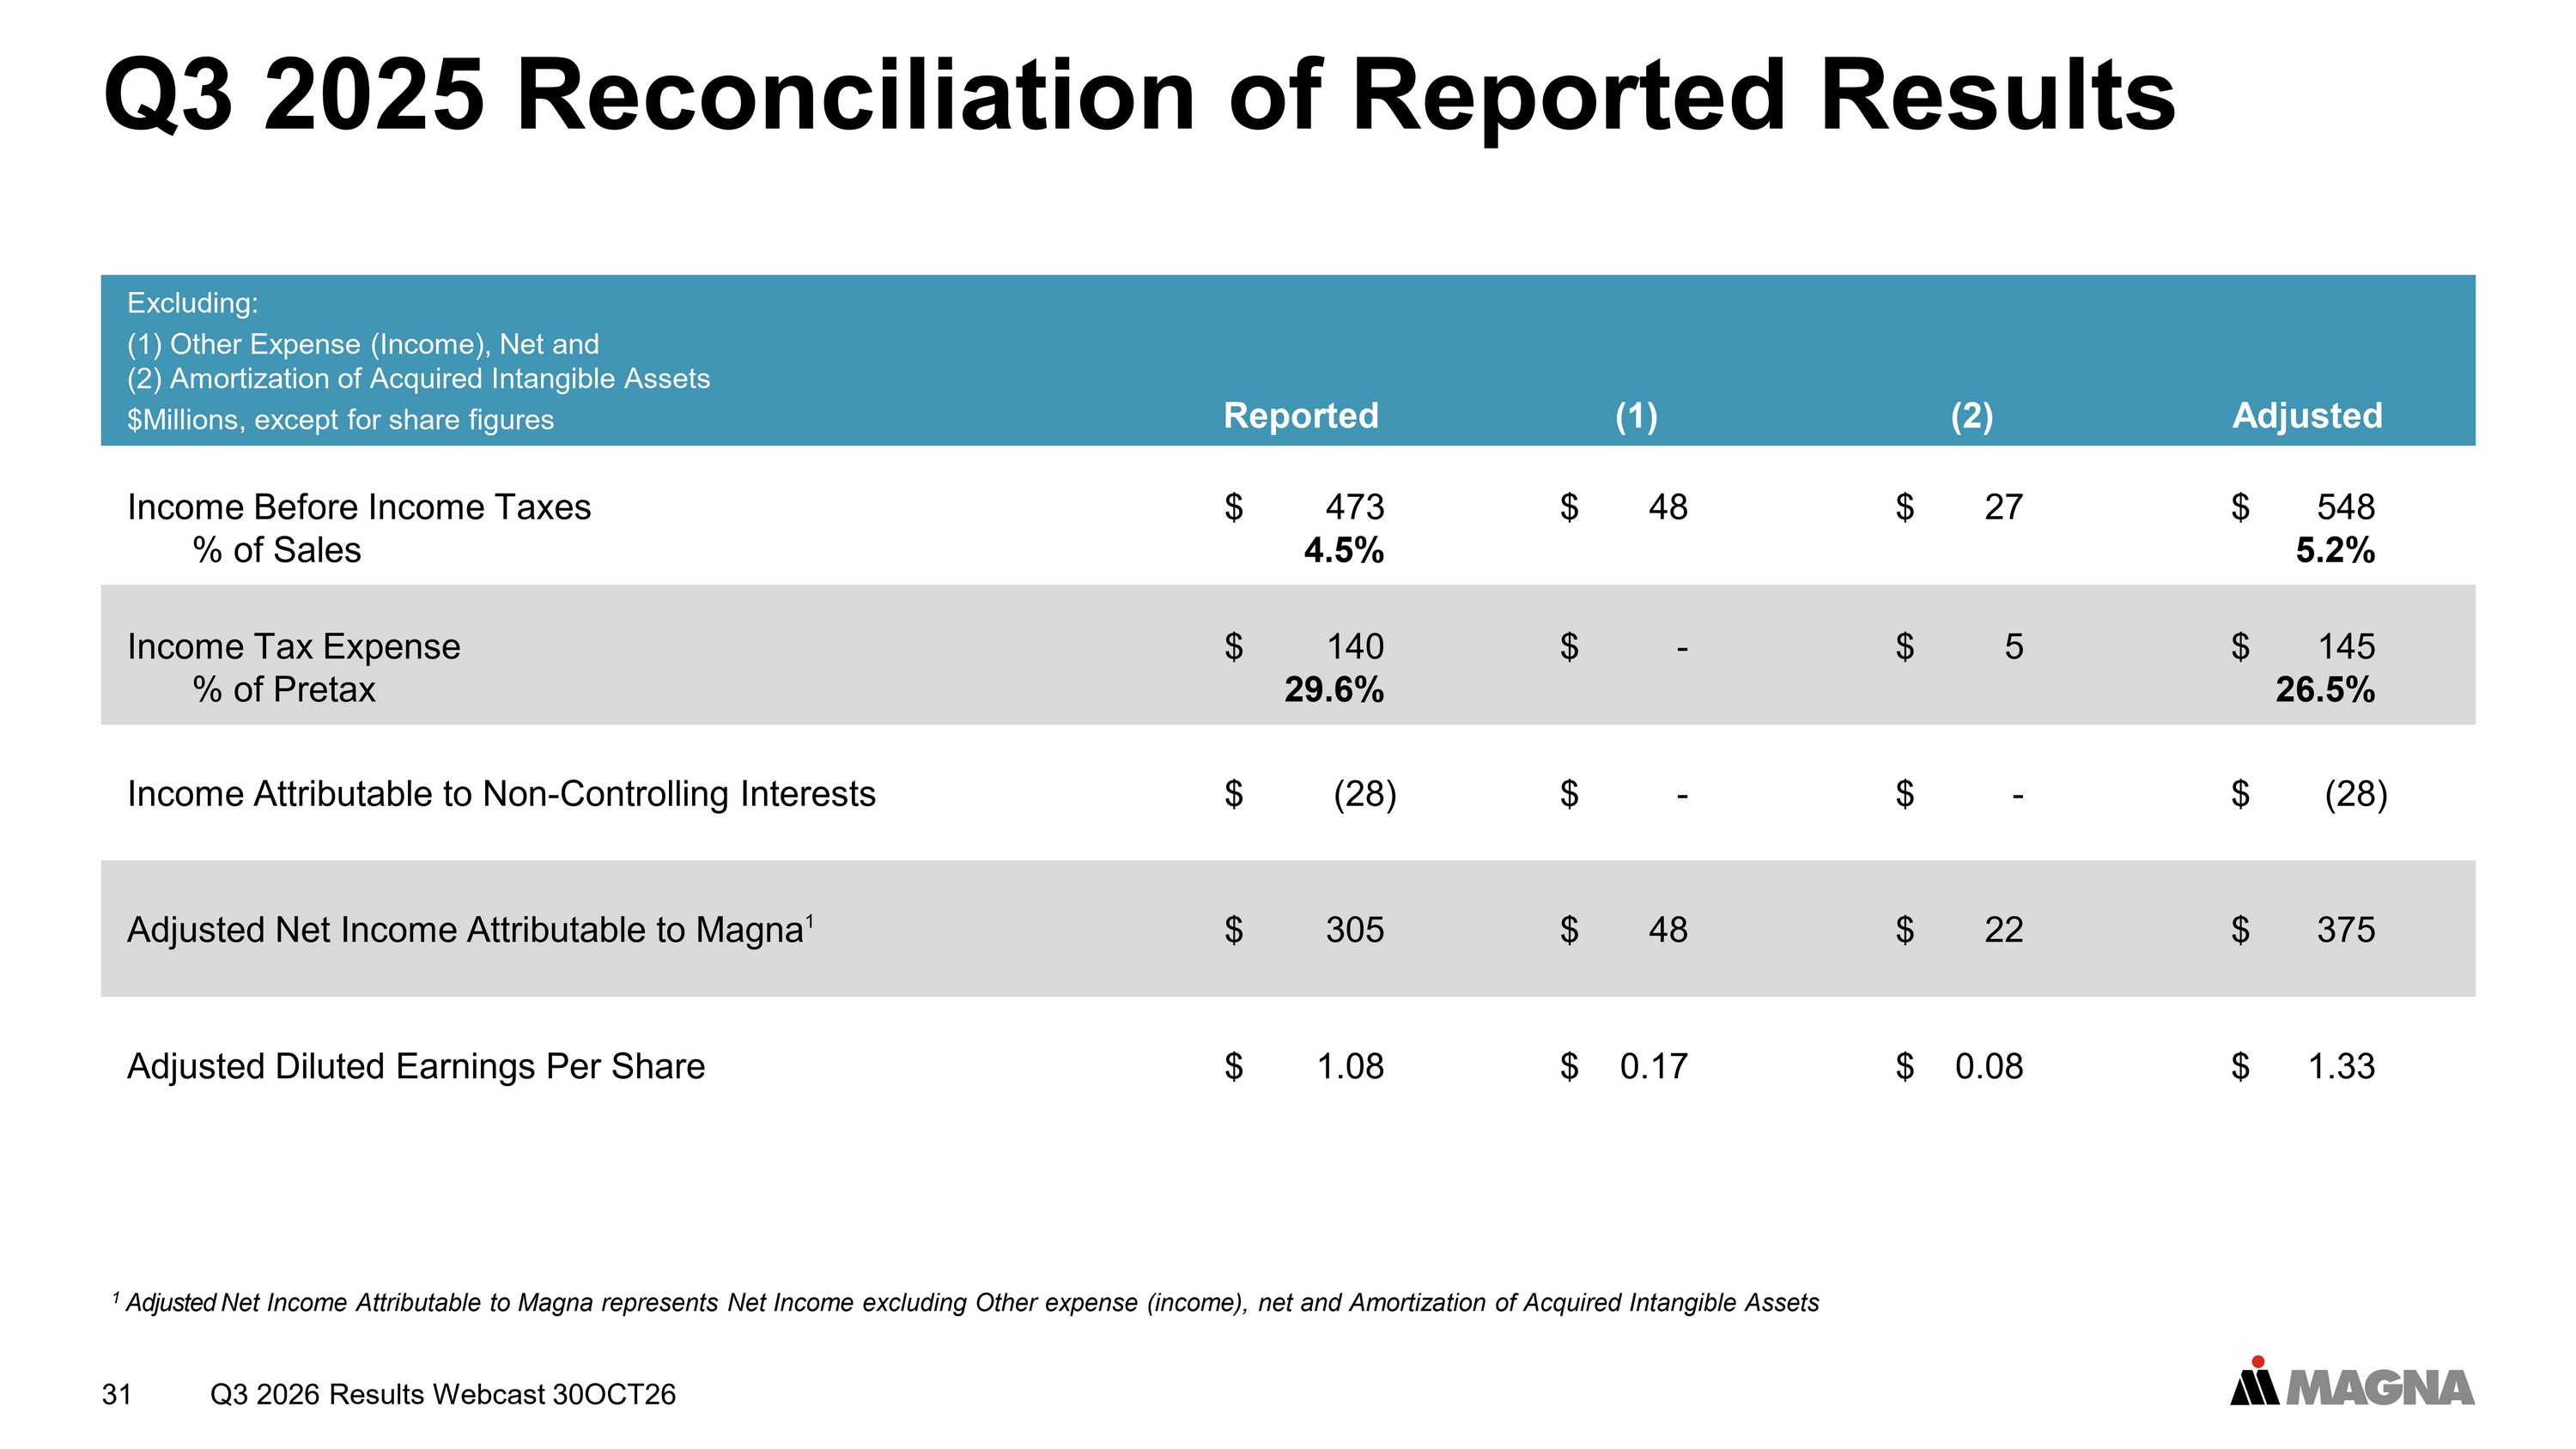
31 Q3 2025 Reconciliation of Reported Results Adjusted (2) (1) Reported Excluding: (1) Other Expense (Income), Net and (2) Amortization of Acquired Intangible Assets $Millions, except for share figures $ 548 $ 27 $ 48 $ 473 Income Before Income Taxes 5.2% 4.5% % of Sales $ 145 $ 5 $ - $ 140 Income Tax Expense 26.5% 29.6% % of Pretax $ (28) $ - $ - $ (28) Income Attributable to Non - Controlling Interests $ 375 $ 22 $ 48 $ 305 Adjusted Net Income Attributable to Magna 1 $ 1.33 $ 0.08 $ 0.17 $ 1.08 Adjusted Diluted Earnings Per Share 1 Adjusted Net Income Attributable to Magna represents Net Income excluding Other expense (income), net and Amortization of Acquired Int ang ible Assets Q3 2026 Results Webcast 30OCT26
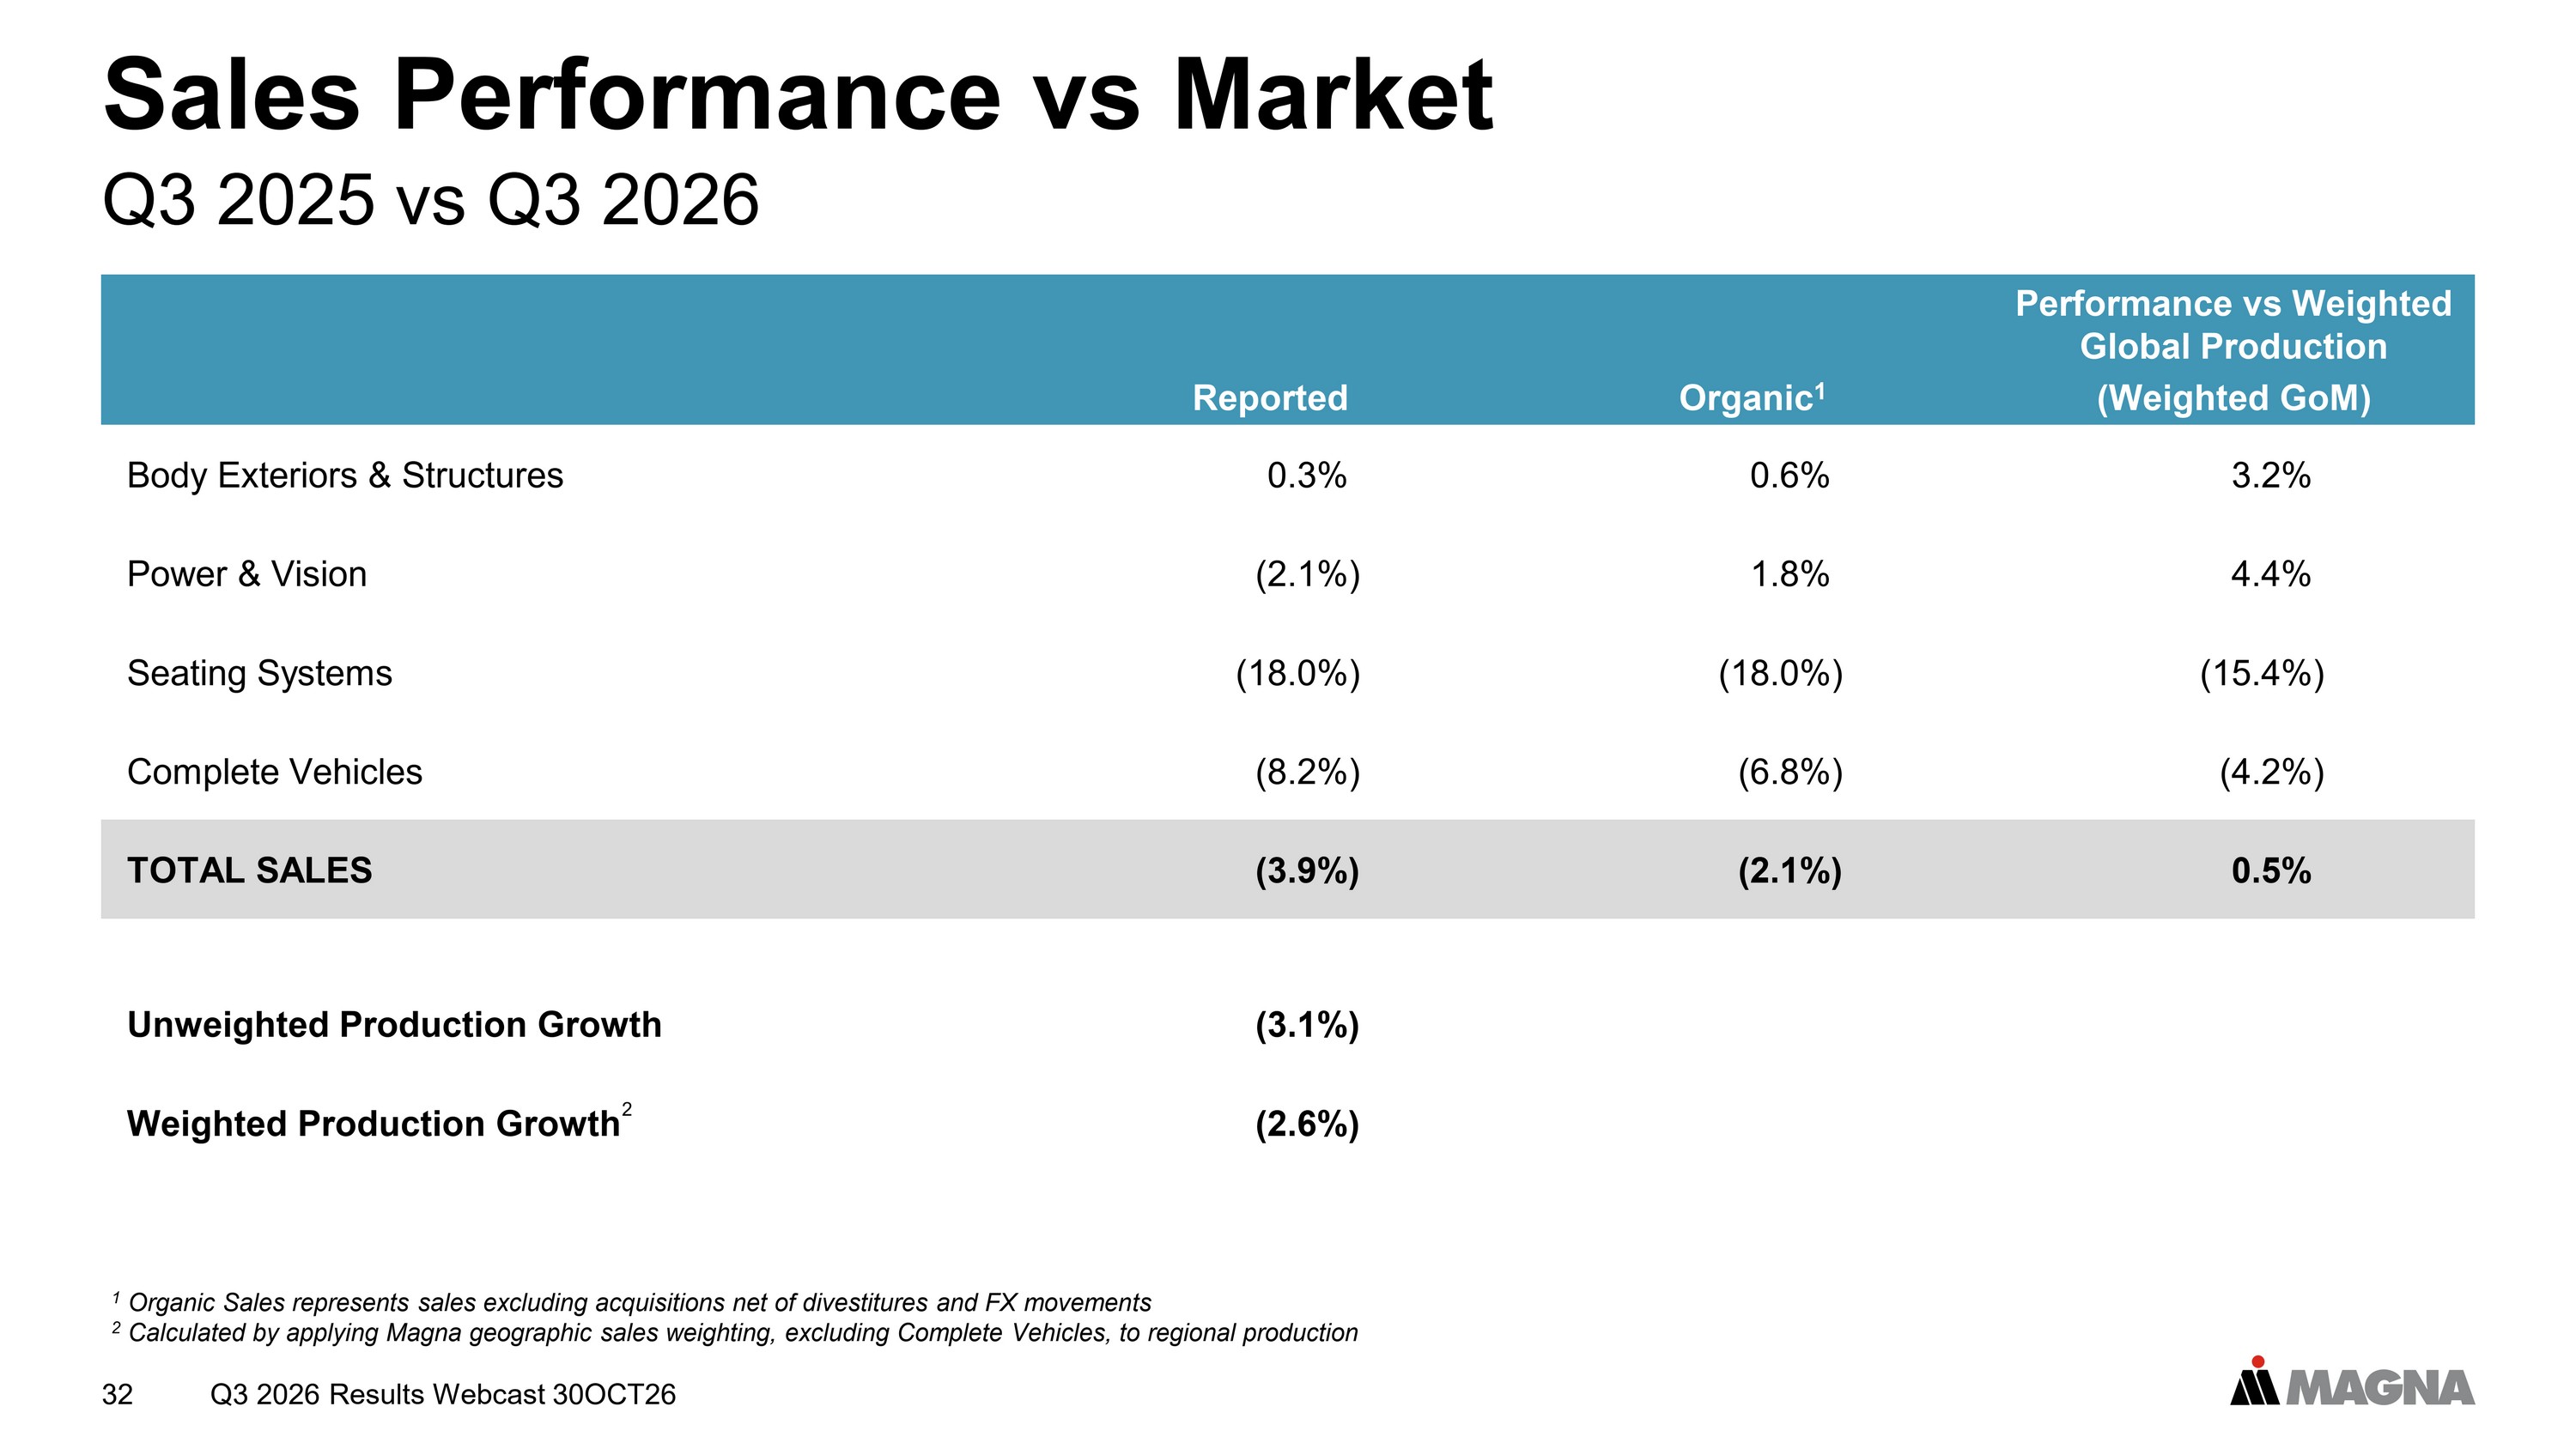
32 Q3 2025 vs Q3 2026 Sales Performance vs Market Performance vs Weighted Global Production (Weighted GoM) Organic 1 Reported 3.2% 0.6% 0.3% Body Exteriors & Structures 4.4% 1.8% (2.1%) Power & Vision (15.4%) (18.0%) (18.0%) Seating Systems (4.2%) (6.8%) (8.2%) Complete Vehicles 0.5% (2.1%) (3.9%) TOTAL SALES (3.1%) Unweighted Production Growth (2.6%) Weighted Production Growth 2 1 Organic Sales represents sales excluding acquisitions net of divestitures and FX movements 2 Calculated by applying Magna geographic sales weighting, excluding Complete Vehicles, to regional production Q3 2026 Results Webcast 30OCT26
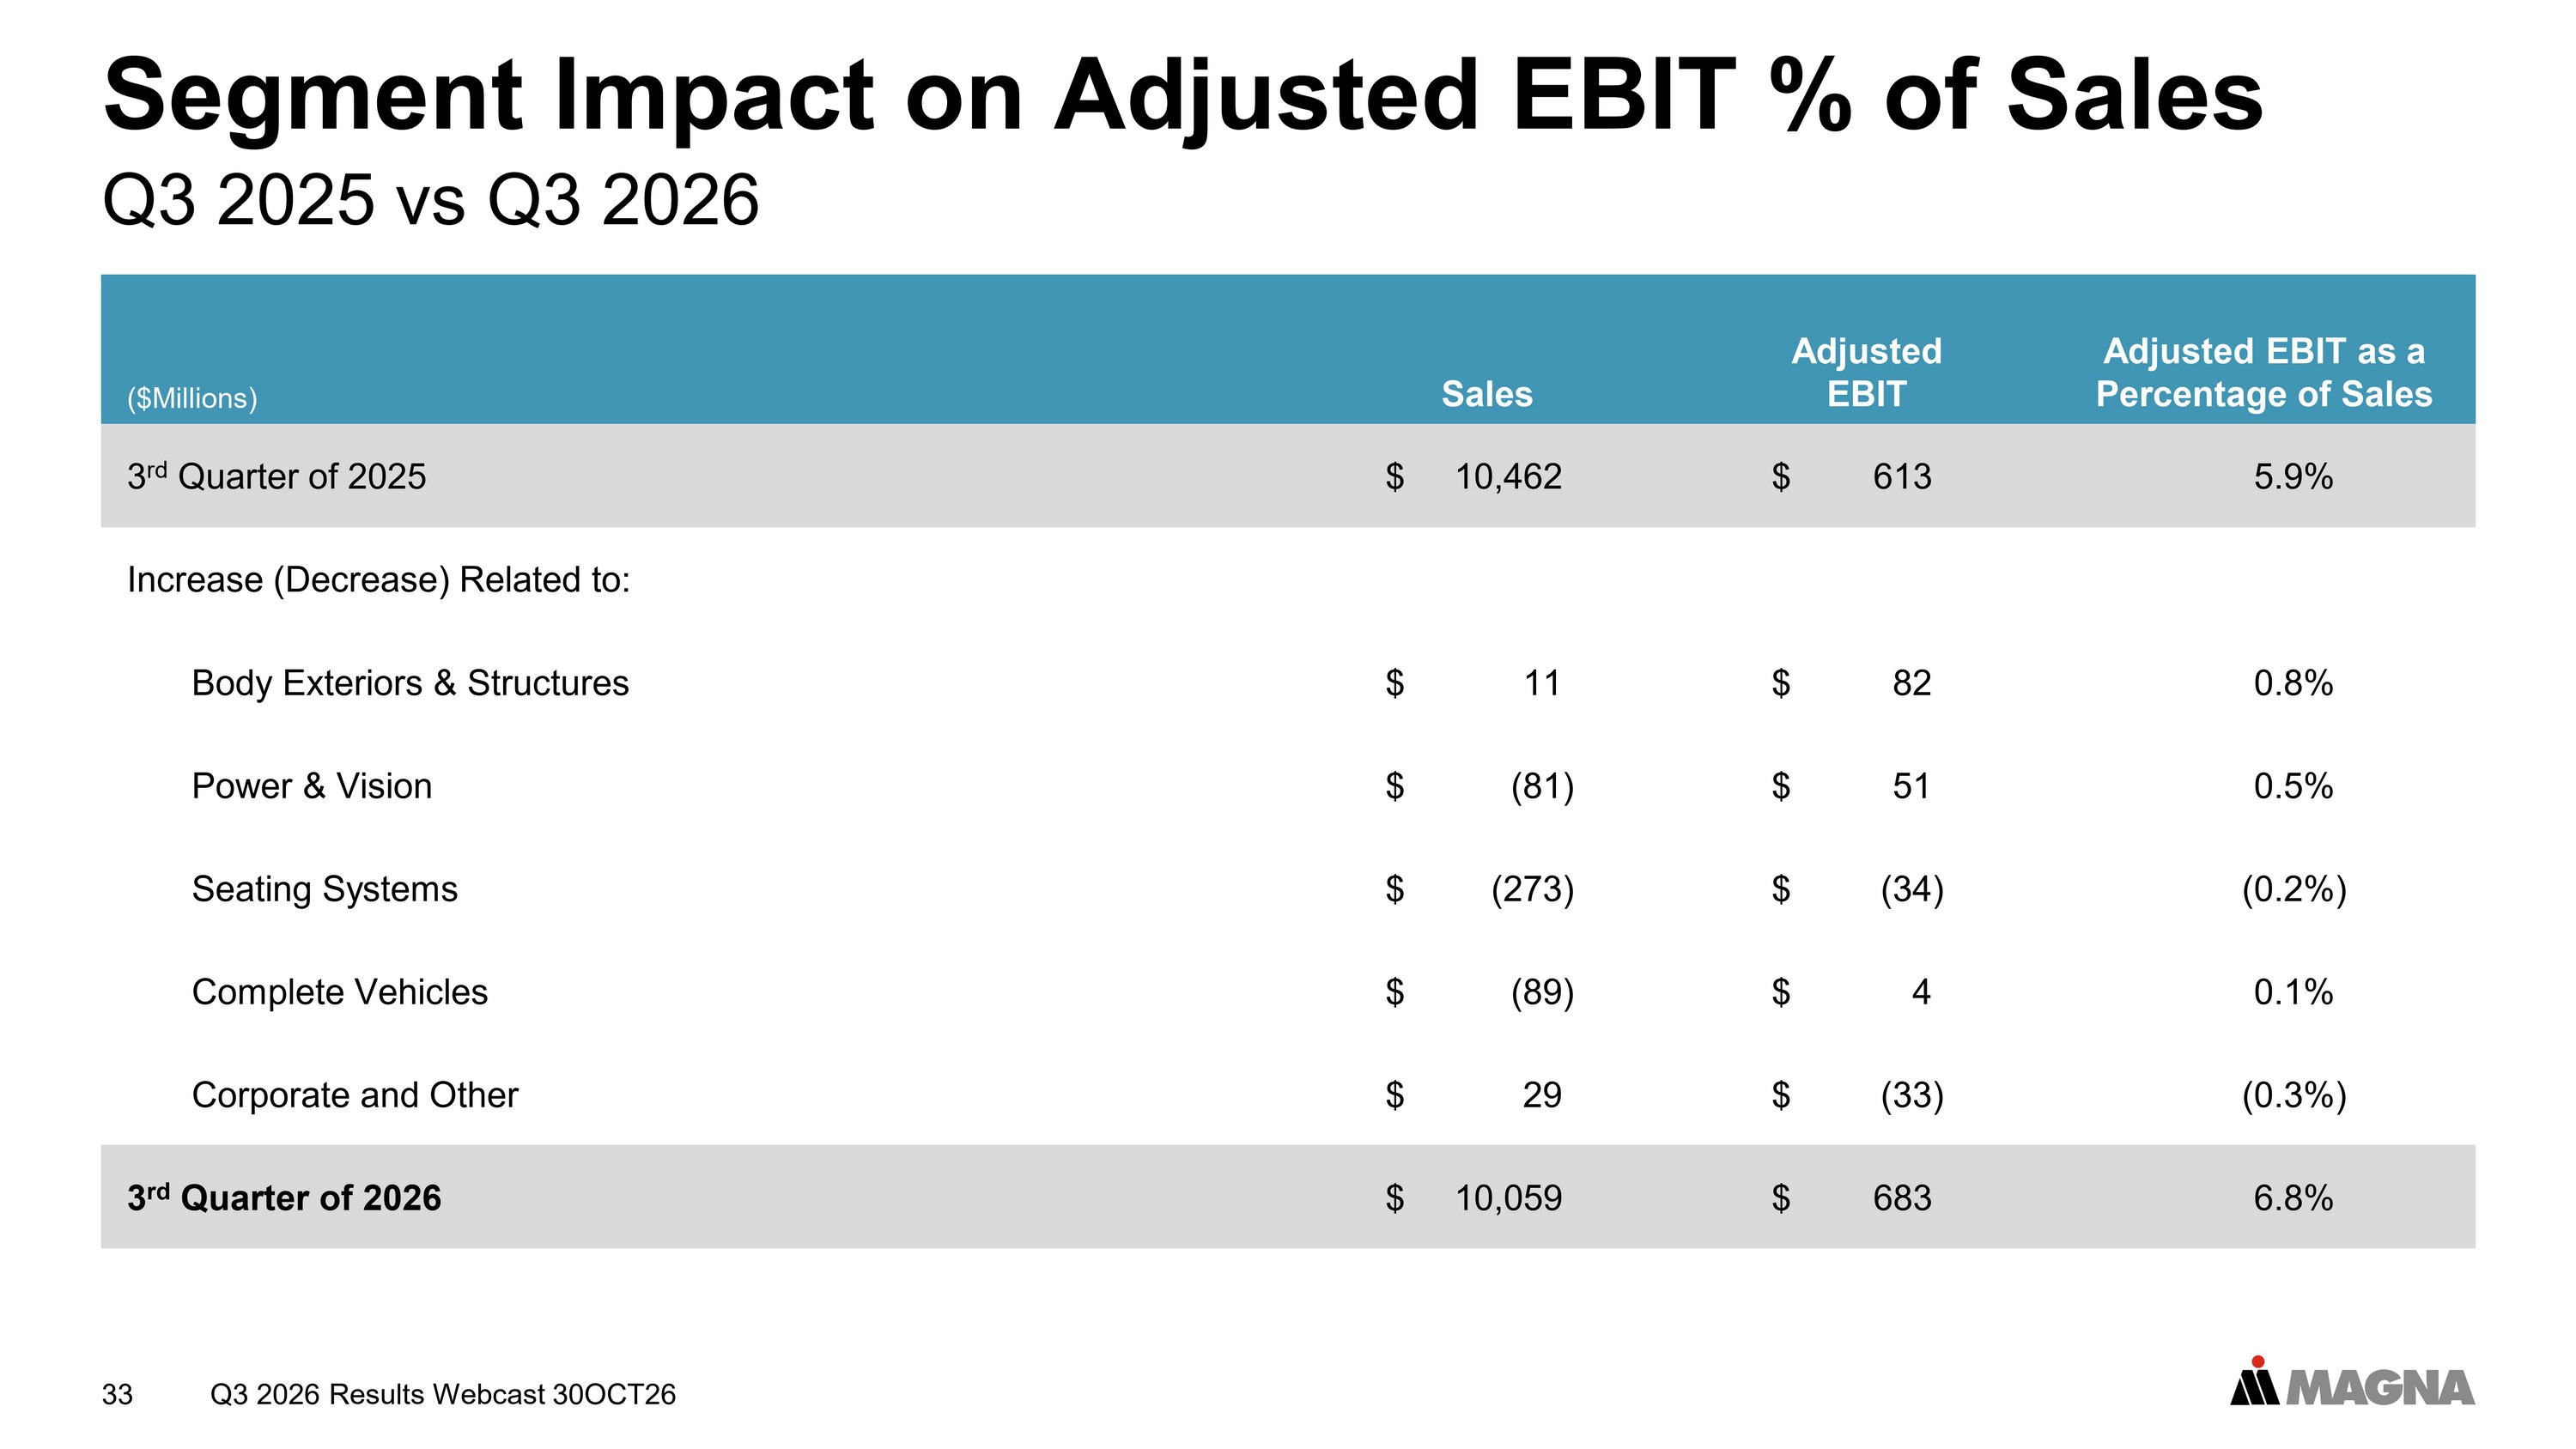
33 Q3 2025 vs Q3 2026 Segment Impact on Adjusted EBIT % of Sales Adjusted EBIT as a Percentage of Sales Adjusted EBIT Sales ($Millions) 5.9% $ 613 $ 10,462 3 rd Quarter of 2025 Increase (Decrease) Related to: 0.8% $ 82 $ 11 Body Exteriors & Structures 0.5% $ 51 $ (81) Power & Vision (0.2%) $ (34) $ (273) Seating Systems 0.1% $ 4 $ (89) Complete Vehicles (0.3%) $ (33) $ 29 Corporate and Other 6.8% $ 683 $ 10,059 3 rd Quarter of 2026 Q3 2026 Results Webcast 30OCT26
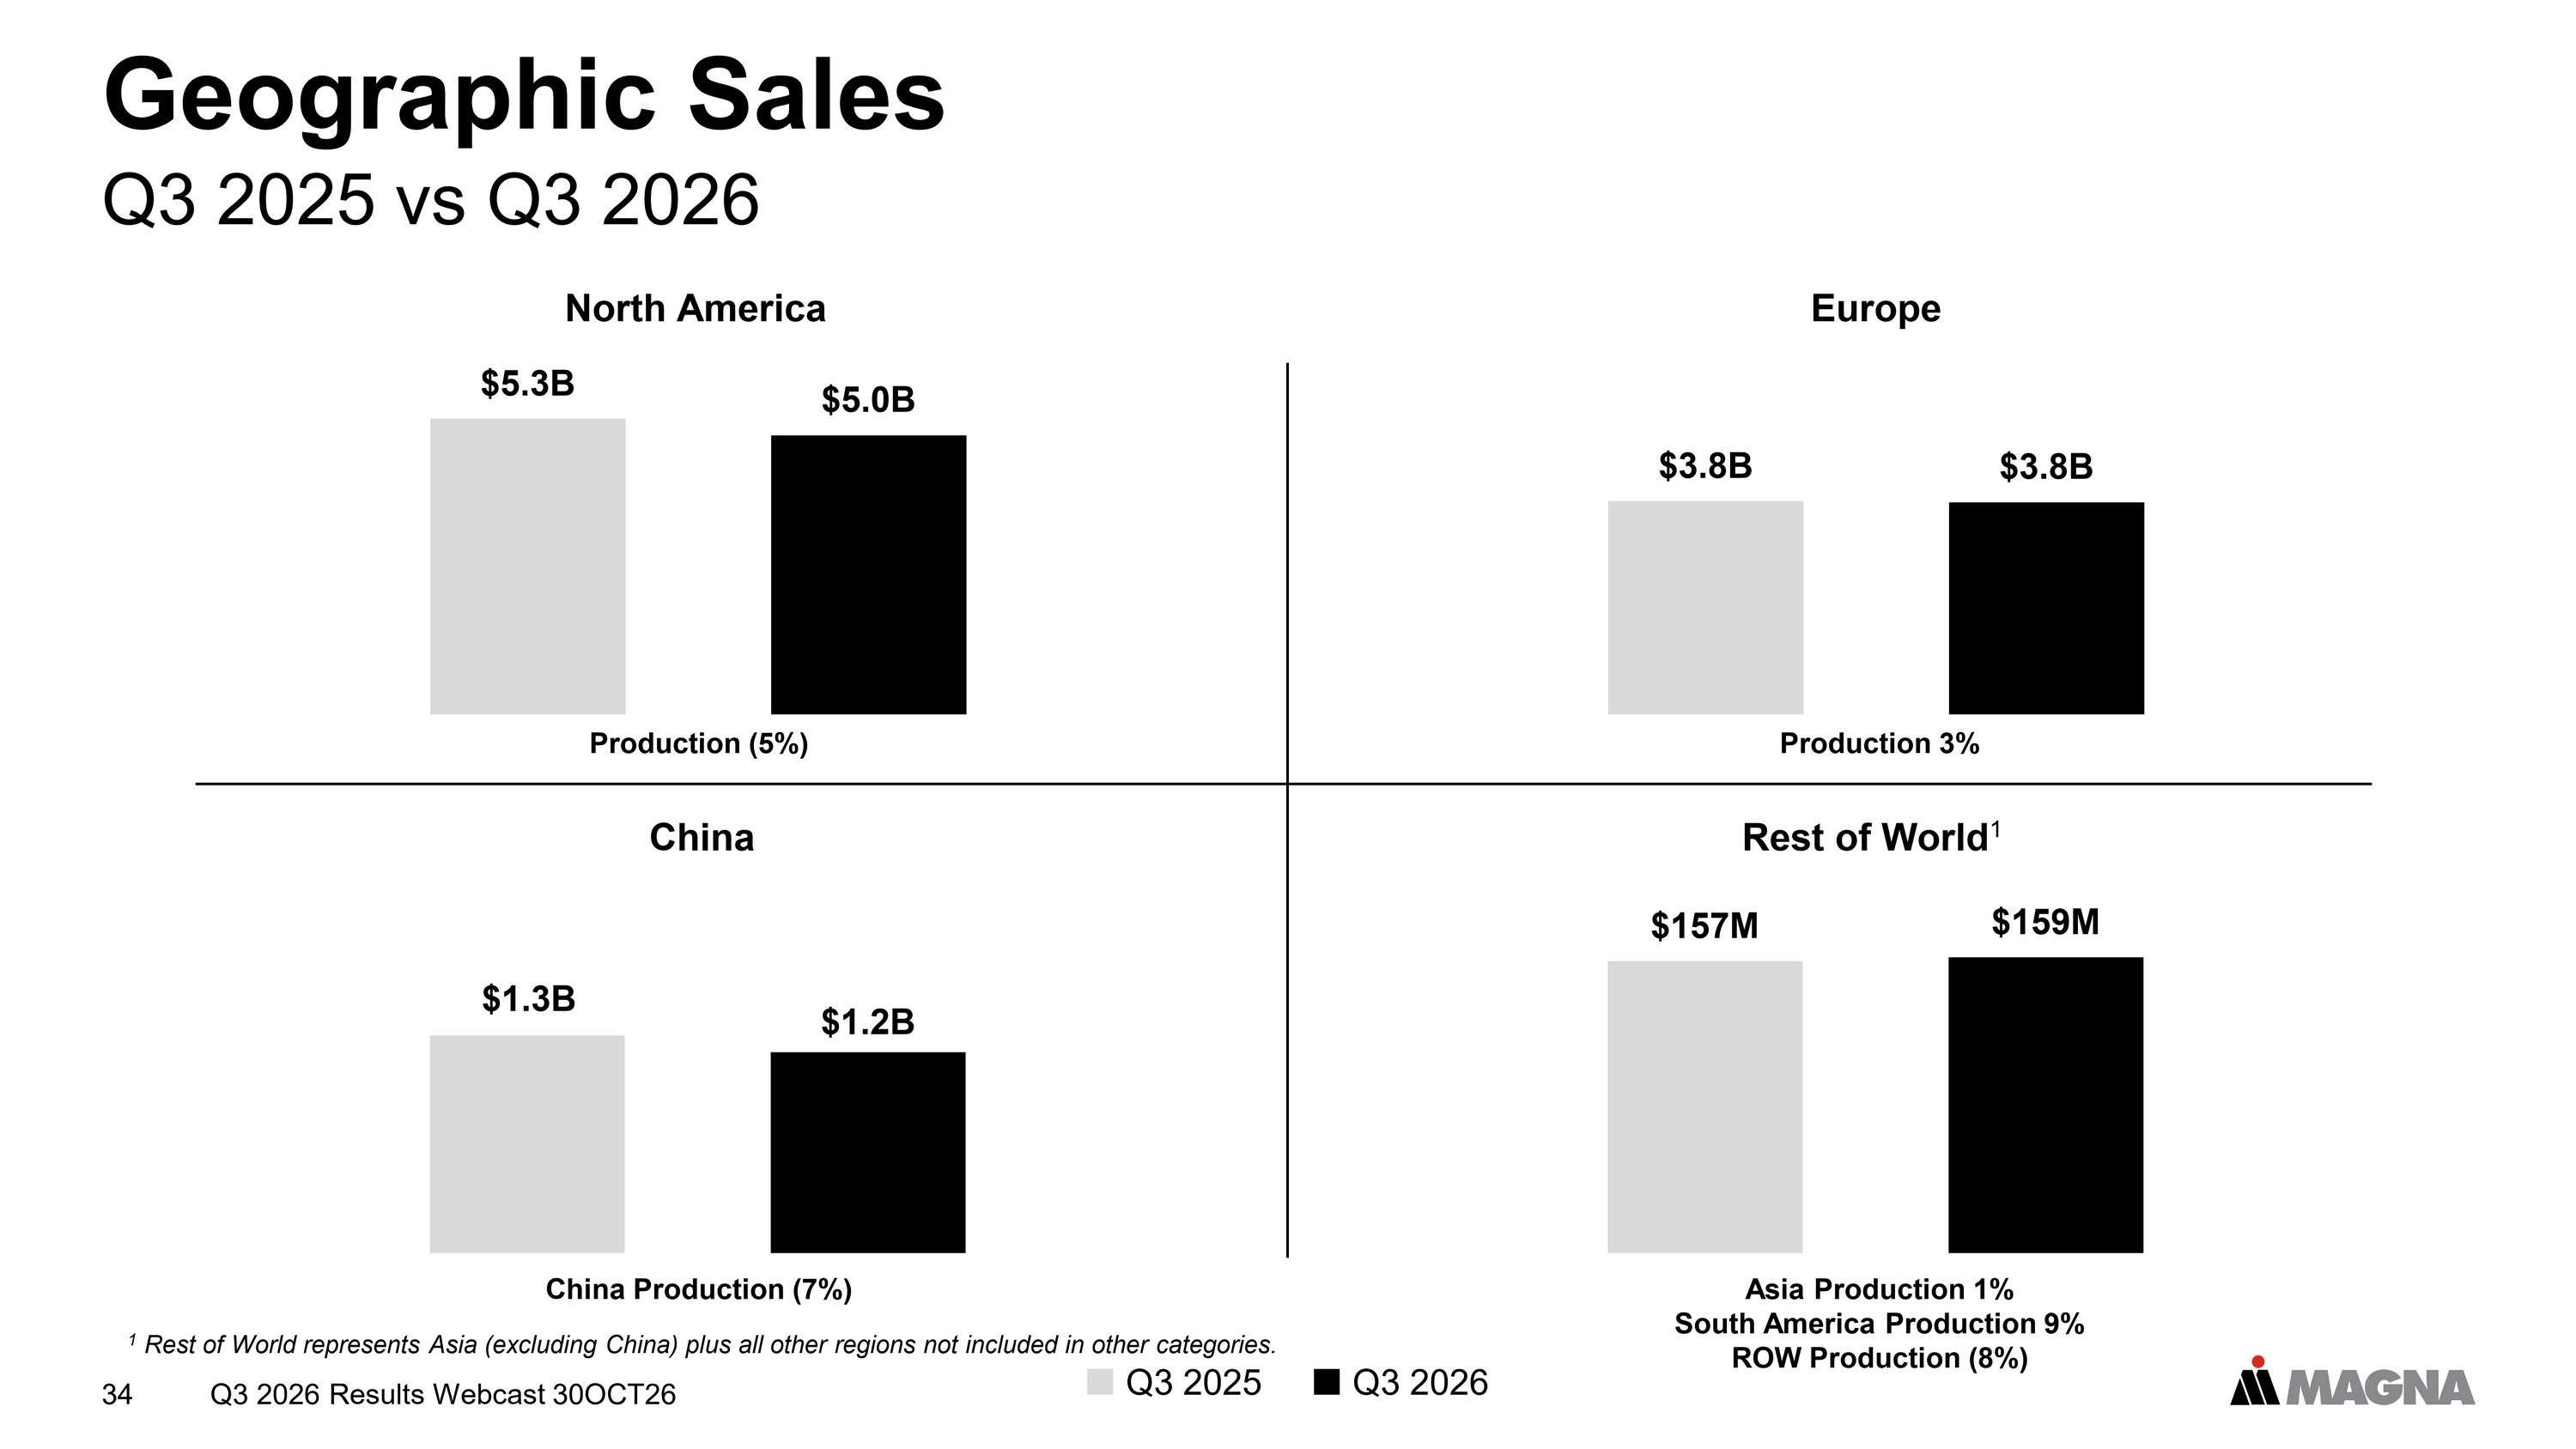
34 Q3 2025 vs Q3 2026 Geographic Sales Q3 2025 Q3 2026 China China Production (7%) $1.3B $1.2B $0.00B $0.20B $0.40B $0.60B $0.80B $1.00B $1.20B $1.40B $1.60B $1.80B $2.00B $5.3B $5.0B $0.0B $1.0B $2.0B $3.0B $4.0B $5.0B $6.0B North America Production (5%) $3.8B $3.8B $0.0B $1.0B $2.0B $3.0B $4.0B $5.0B $6.0B Europe Production 3% $157M $159M $0M $20M $40M $60M $80M $100M $120M $140M $160M $180M Asia Production 1% South America Production 9% ROW Production (8%) Rest of World 1 1 Rest of World represents Asia (excluding China) plus all other regions not included in other categories. Q3 2026 Results Webcast 30OCT26
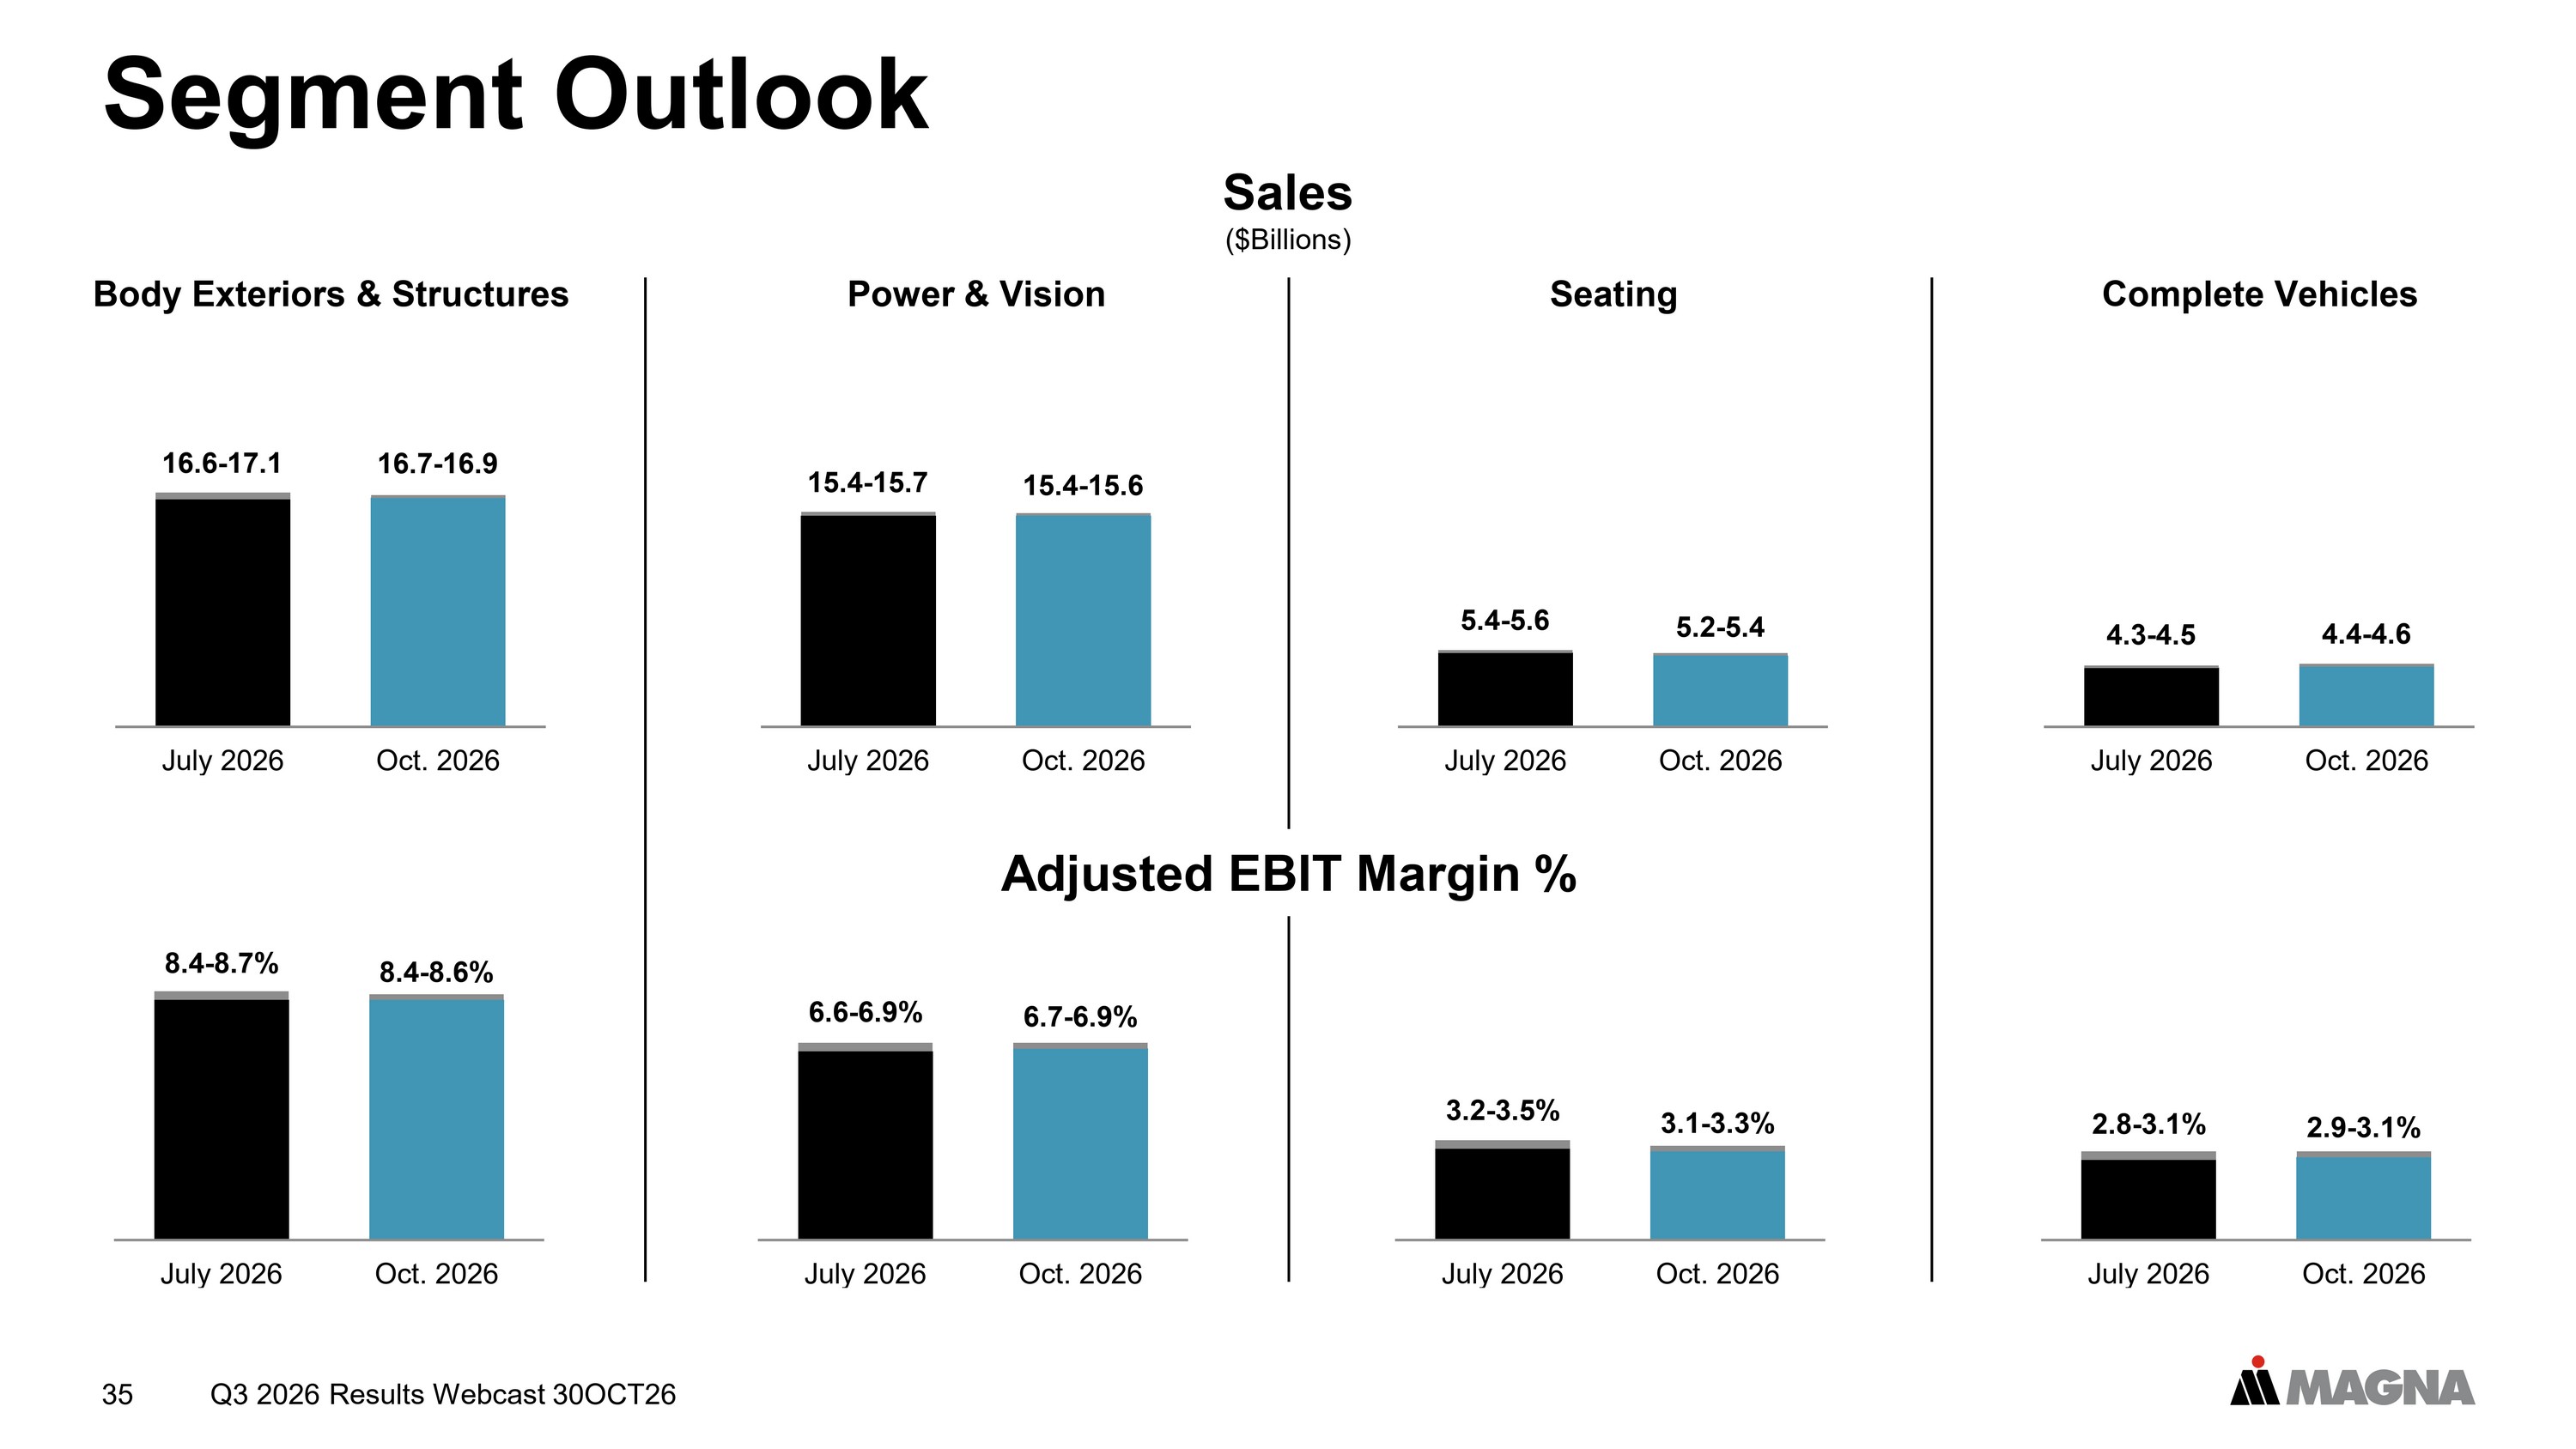
35 Segment Outlook July 2026 Oct. 2026 8.4 - 8.7% 8.4 - 8.6% Adjusted EBIT Margin % Body Exteriors & Structures July 2026 Oct. 2026 16.6 - 17.1 16.7 - 16.9 Sales ($Billions) July 2026 Oct. 2026 6.6 - 6.9% 6.7 - 6.9% Power & Vision July 2026 Oct. 2026 15.4 - 15.7 15.4 - 15.6 July 2026 Oct. 2026 3.2 - 3.5% 3.1 - 3.3% Seating July 2026 Oct. 2026 5.4 - 5.6 5.2 - 5.4 July 2026 Oct. 2026 2.8 - 3.1% 2 .9 - 3.1% Complete Vehicles July 2026 Oct. 2026 4.3 - 4.5 4.4 - 4.6 Q3 2026 Results Webcast 30OCT26
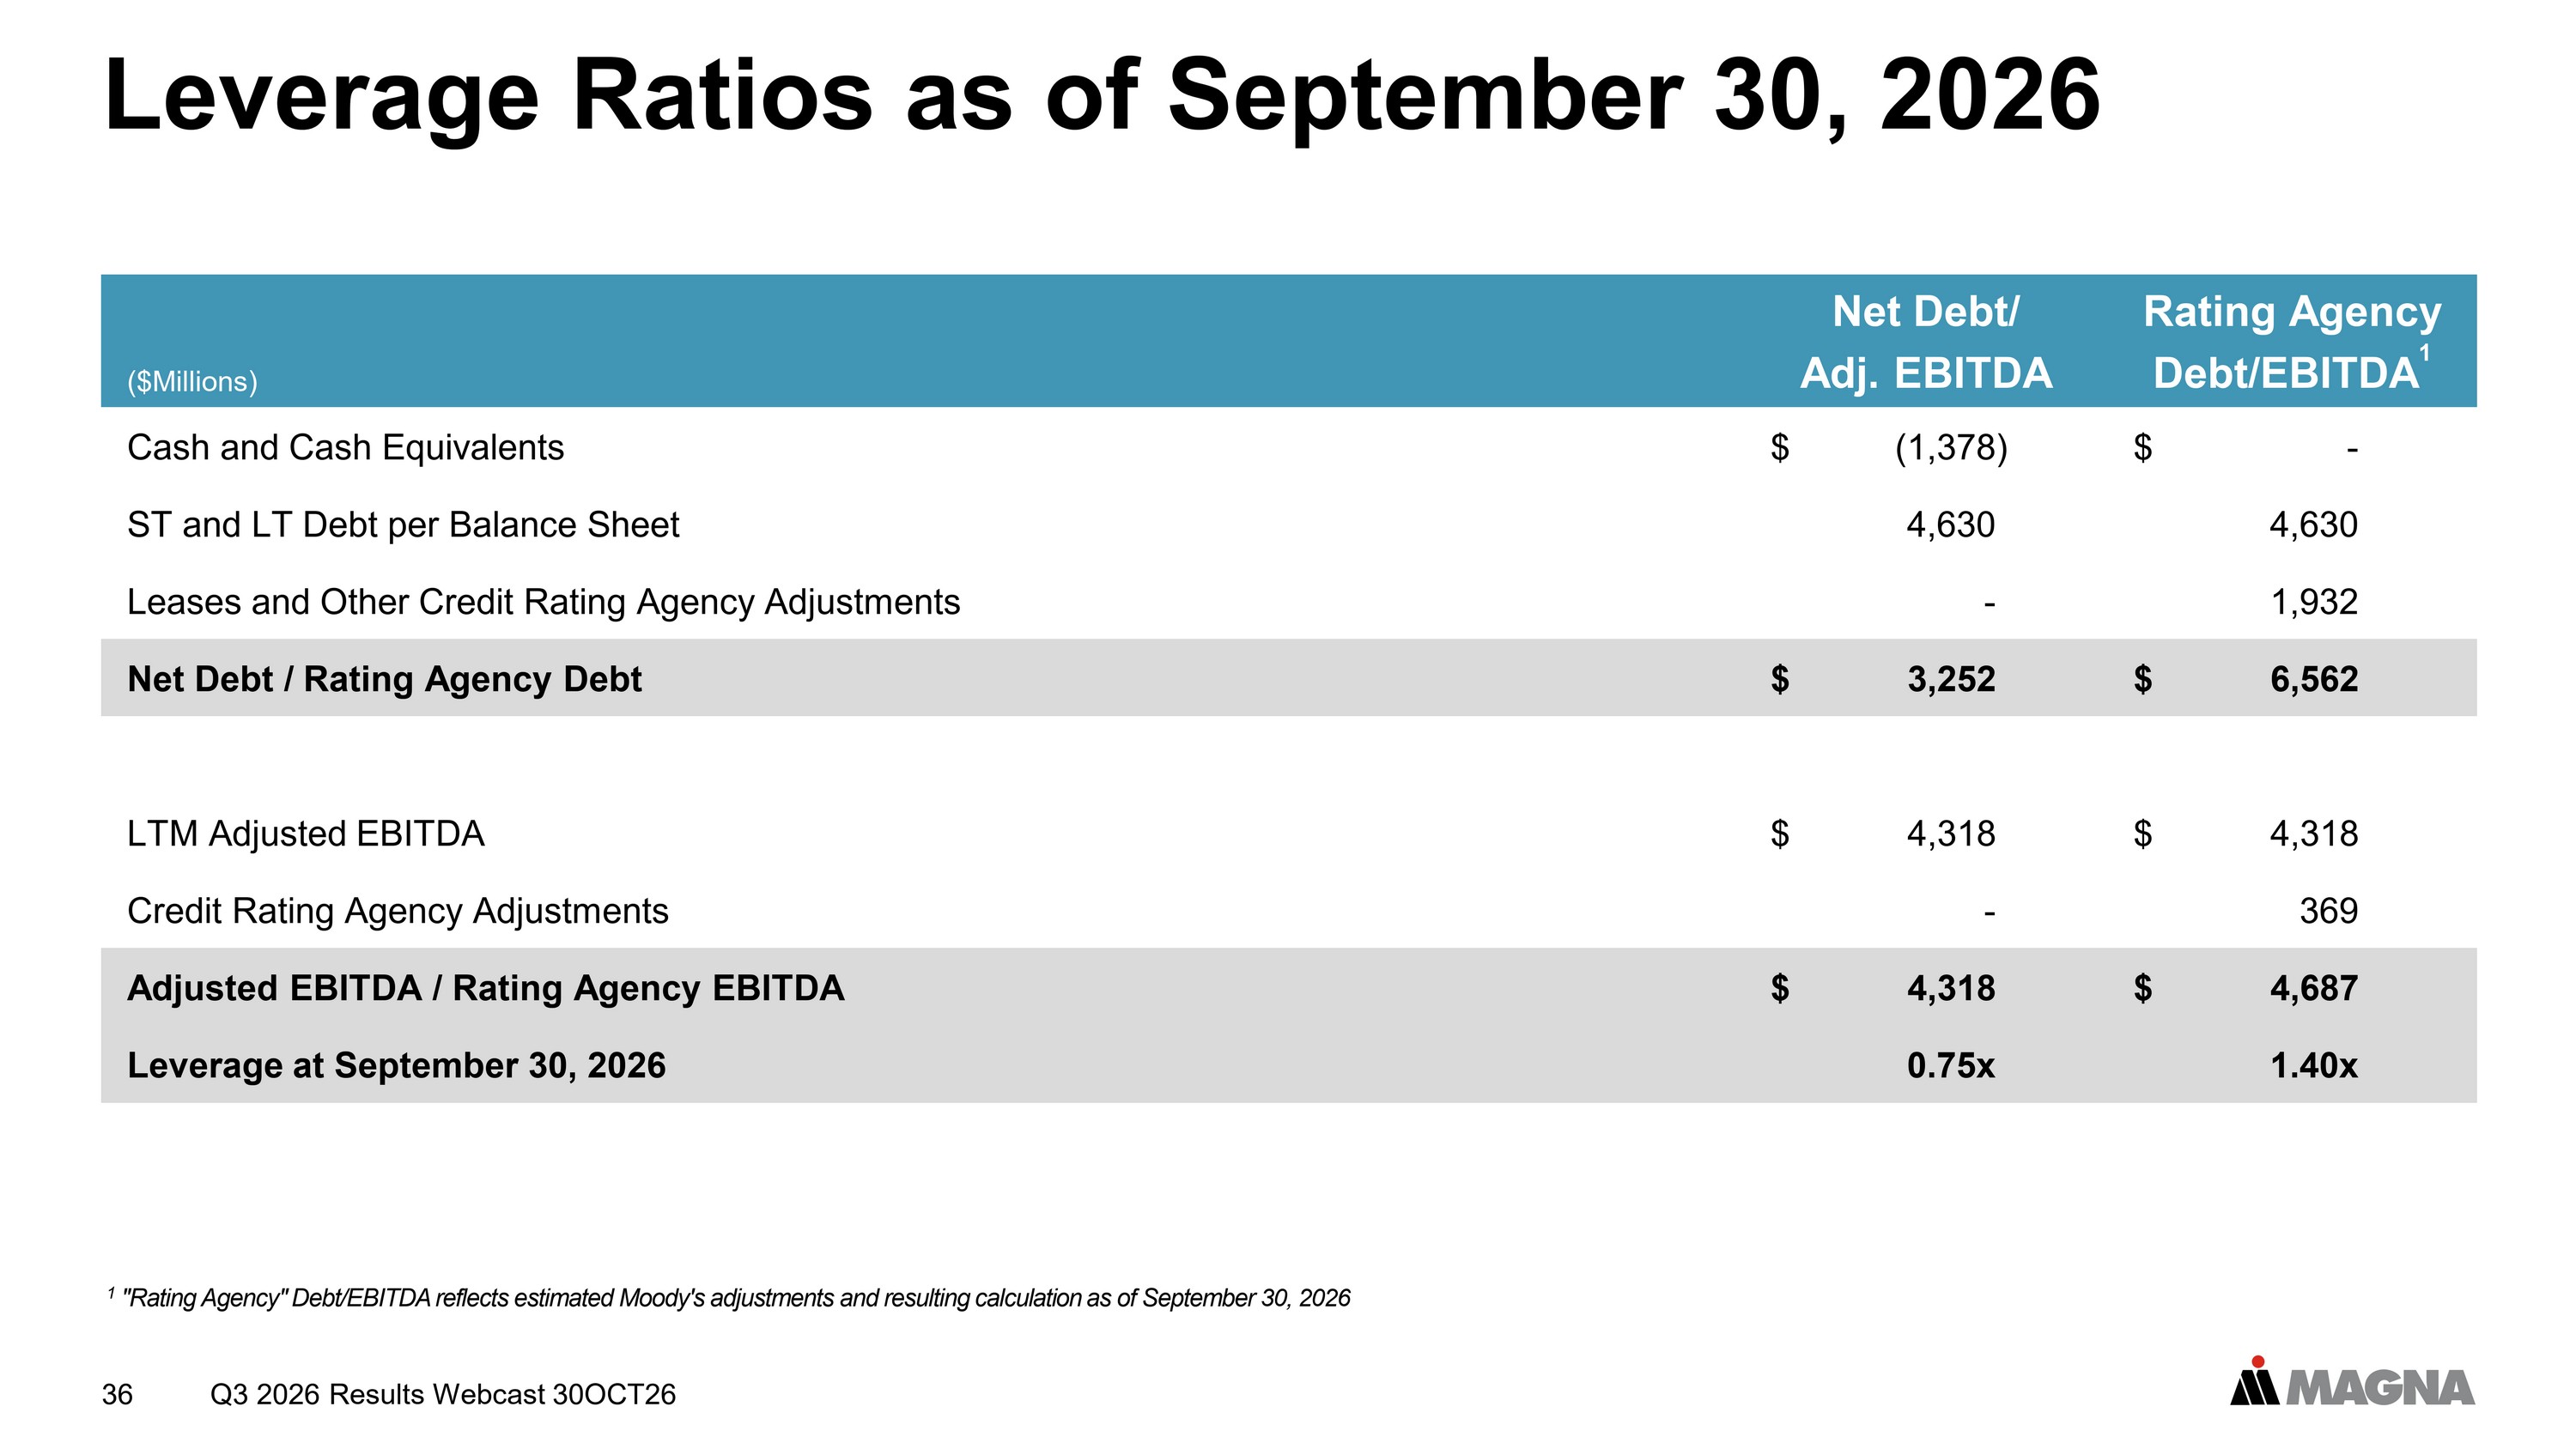
36 Leverage Ratios as of September 30, 2026 Rating Agency Debt/EBITDA 1 Net Debt/ Adj. EBITDA ($Millions) $ - $ (1,378) Cash and Cash Equivalents 4,630 4,630 ST and LT Debt per Balance Sheet 1,932 - Leases and Other Credit Rating Agency Adjustments $ 6,562 $ 3,252 Net Debt / Rating Agency Debt $ 4,318 $ 4,318 LTM Adjusted EBITDA 369 - Credit Rating Agency Adjustments $ 4,687 $ 4,318 Adjusted EBITDA / Rating Agency EBITDA 1.40x 0.75x Leverage at September 30, 2026 1 "Rating Agency" Debt/EBITDA reflects estimated Moody's adjustments and resulting calculation as of September 30, 2026 Q3 2026 Results Webcast 30OCT26
37 Q3 2026 Results Webcast 30OCT26