Third Quarter 2026 Results October 23, 2026
60 121 158 242 242 242 254 150 0 218 218 218 164 167 168 253 206 59 69 72 73 236 243 248 23rd Quarter 2026 Cautionary Statement Forward-Looking Information This earnings presentation and the associated conference call may include forward‐looking statements by us and our authorized officers pertaining to such matters as our goals, beliefs, intentions, and expectations regarding, among other things: (a) revenues, earnings, loan production, asset quality, liquidity position, capital levels, risk analysis, divestitures, acquisitions, and other material transactions, among other matters; (b) the future costs and benefits of the actions we may take; (c) our assessments of credit risk and probable losses on loans and associated allowances and reserves; (d) our assessments of interest rate and other market risks; (e) our ability to achieve profitability goals within projected timeframes and to execute on our strategic plan, including the sufficiency of our internal resources, procedures and systems; (f) our ability to execute our capital management strategies, including our ability to complete our current stock repurchase program and to implement future stock repurchase programs; (g) our ability to attract, incentivize, and retain key personnel and the roles of key personnel; (h) our ability to achieve our financial and other strategic goals, including those related to our recent holding company reorganization, which was completed in October 2025 (the "Reorganization"), our merger with Flagstar Bancorp, Inc., which was completed in December 2022, our acquisition of substantial portions of the former Signature Bank through an FDIC-assisted transaction, which was completed in March 2023, and our ability to comply with the heightened regulatory standards with respect to governance and risk management programs to which we are subject as a national bank with assets of $50 billion or more; (i) the impact of the $1.05 billion capital raise we completed in March 2024; (j) the conversion or exchange of shares of our preferred stock; (k) the payment of dividends on shares of our capital stock, including adjustments to the amount of dividends payable on shares of our preferred stock; (l) the dilution of existing equity holders associated with future equity awards and stock issuances; (m) the effects of the reverse stock split we effected in July 2024; and (n) the impact of the 2024 sale of our mortgage servicing operations, third party mortgage loan origination business, and mortgage warehouse business. Forward‐looking statements are typically identified by such words as “believe,” “expect,” “anticipate,” “intend,” “outlook,” “estimate,” “forecast,” “project,” “should,” "confident," and other similar words and expressions, and are subject to numerous assumptions, risks, and uncertainties, which change over time. Additionally, forward‐looking statements speak only as of the date they are made; we do not assume any duty, and do not undertake, to update our forward‐looking statements. Furthermore, because forward‐looking statements are subject to assumptions and uncertainties, actual results or future events could differ, possibly materially, from those anticipated in our statements, including guidance or expectations regarding our future financial or operating results and long-term strategic objectives, and our future performance could differ materially from our historical results. Our forward‐looking statements are subject to, among others, the following principal risks and uncertainties: general economic conditions and trends, either nationally or locally; conditions in the securities, credit and financial markets; changes in interest rates; changes in deposit flows, and in the demand for deposit, loan, and investment products and other financial services; changes in real estate values; changes in the quality or composition of our loan or investment portfolios, including associated allowances and reserves; changes in future allowance for credit losses, including changes required under relevant accounting and regulatory requirements; the ability to pay future dividends; the ability to implement future stock repurchase programs, which are subject to the approval of the Board of Directors and other various factors, including the Bank's liquidity, capital position, and financial performance, accounting, and regulatory considerations as well as general market conditions; changes in our capital management and balance sheet strategies and our ability to successfully implement such strategies; our ability to achieve the anticipated benefits of the Reorganization; changes in our Board of Directors and our executive management team; changes in our strategic plan, including changes in our internal resources, procedures and systems, and our ability to successfully implement such plan; changes in competitive pressures among financial institutions or from non‐financial institutions; changes in legislation, regulations, and policies; changes relating to rent regulation and housing, including recent legislative action in New York City to freeze rents effective October 1, 2026, on certain rent-regulated properties; the impacts of tariffs, sanctions and other trade policies of the United States and its global trading counterparts; the outcome of federal, state, and local elections and the resulting economic and other impact on the areas in which we conduct business; the impact of changing political conditions or federal government shutdowns; the imposition of restrictions on our operations by bank regulators; the outcome of pending or threatened litigation, or of investigations or any other matters before regulatory agencies, whether currently existing or commencing in the future; our ability to comply with heightened regulatory standards with respect to governance and risk management programs to which we are subject as a national bank with assets of $50 billion or more; the restructuring of our mortgage business; our ability to achieve anticipated cost savings and enhanced efficiencies with respect to our balance sheet and expense reduction strategies; the impact of failures or disruptions in or breaches of our operational or security systems, data or infrastructure, or those of third parties, including as a result of cyberattacks or campaigns; the impact of natural disasters, extreme weather events, civil unrest, international military conflict, terrorism or other geopolitical events; and a variety of other matters which, by their nature, are subject to significant uncertainties and/or are beyond our control. Our forward-looking statements are also subject to the following principal risks and uncertainties with respect to our merger with Flagstar Bancorp, which was completed in December 2022, and our acquisition of substantial portions of the former Signature Bank through an FDIC-assisted transaction, which was completed in March 2023: the possibility that the anticipated benefits of the transactions will not be realized when expected or at all; the possibility of increased legal and compliance costs, including with respect to any litigation or regulatory actions related to the business practices of acquired companies or the combined business; diversion of management's attention from ongoing business operations and opportunities; the possibility that we may be unable to achieve expected synergies and operating efficiencies in or as a result of the transactions within the expected timeframes or at all; and revenues following the transactions may be lower than expected. More information regarding some of these factors is provided in the Risk Factors section of our Annual Report on Form 10‐K for the year ended December 31, 2025, and in other reports we file with the Office of the Comptroller of the Currency (the “OCC”) and voluntarily file with the Securities and Exchange Commission (the “SEC”), and which are also available on our Investor Relations website. Our forward‐looking statements may also be subject to other risks and uncertainties, including those we may discuss in this news release, on our conference call, during investor presentations, or in our securities disclosure filings. All such files are accessible on our website at ir.flagstar.com, on the OCC's website at www.occ.gov, and on the SEC’s website at www.sec.gov.
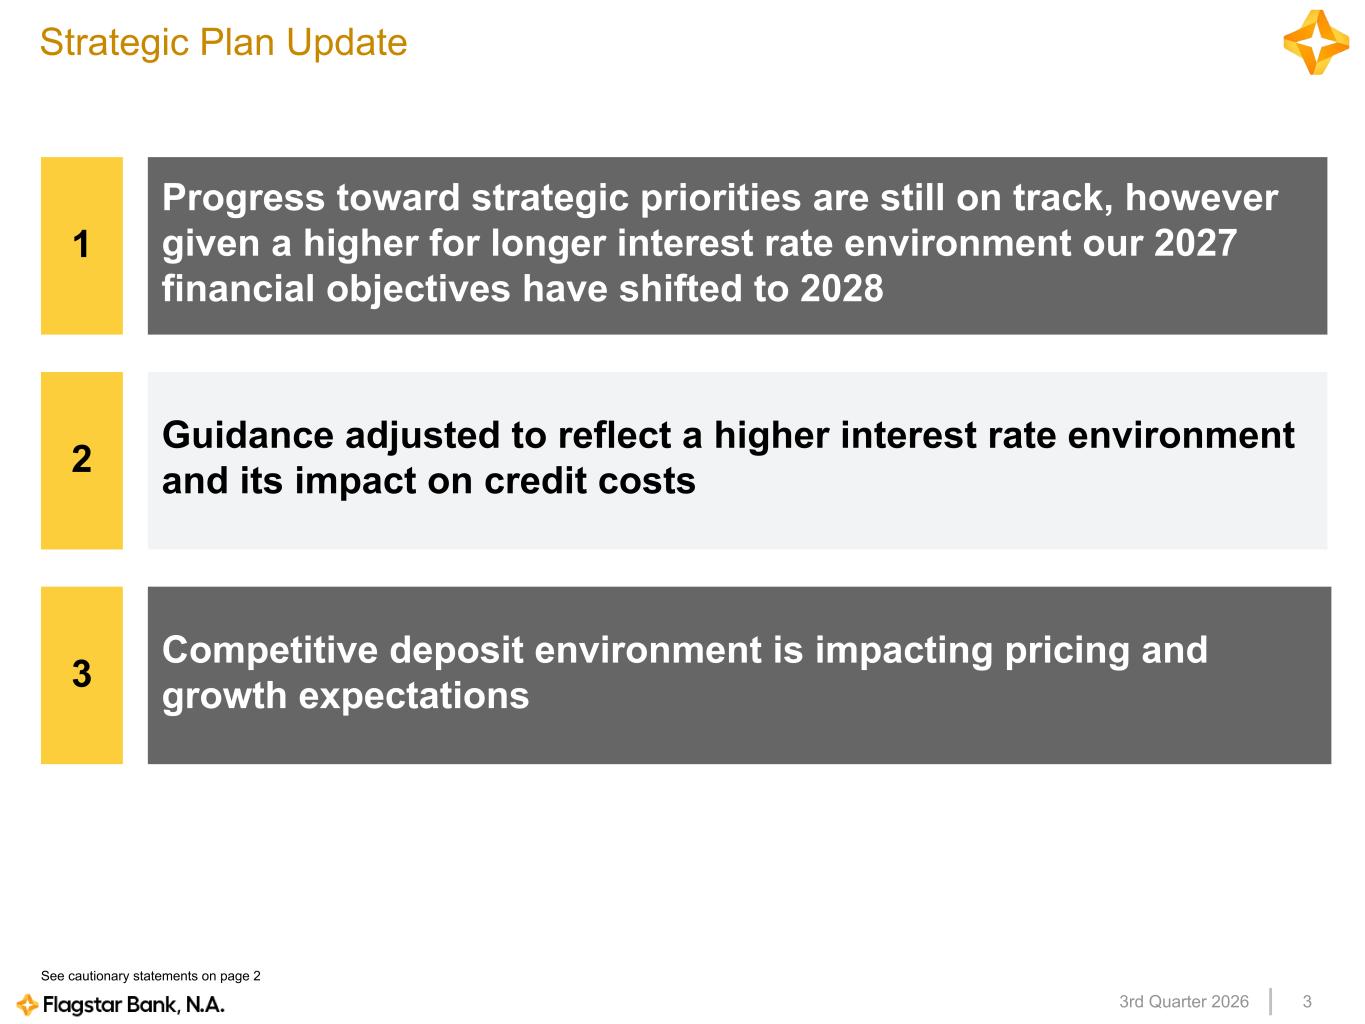
60 121 158 242 242 242 254 150 0 218 218 218 164 167 168 253 206 59 69 72 73 236 243 248 33rd Quarter 2026 Strategic Plan Update Progress toward strategic priorities are still on track, however given a higher for longer interest rate environment our 2027 financial objectives have shifted to 2028 See cautionary statements on page 2 Guidance adjusted to reflect a higher interest rate environment and its impact on credit costs 1 Competitive deposit environment is impacting pricing and growth expectations 2 3
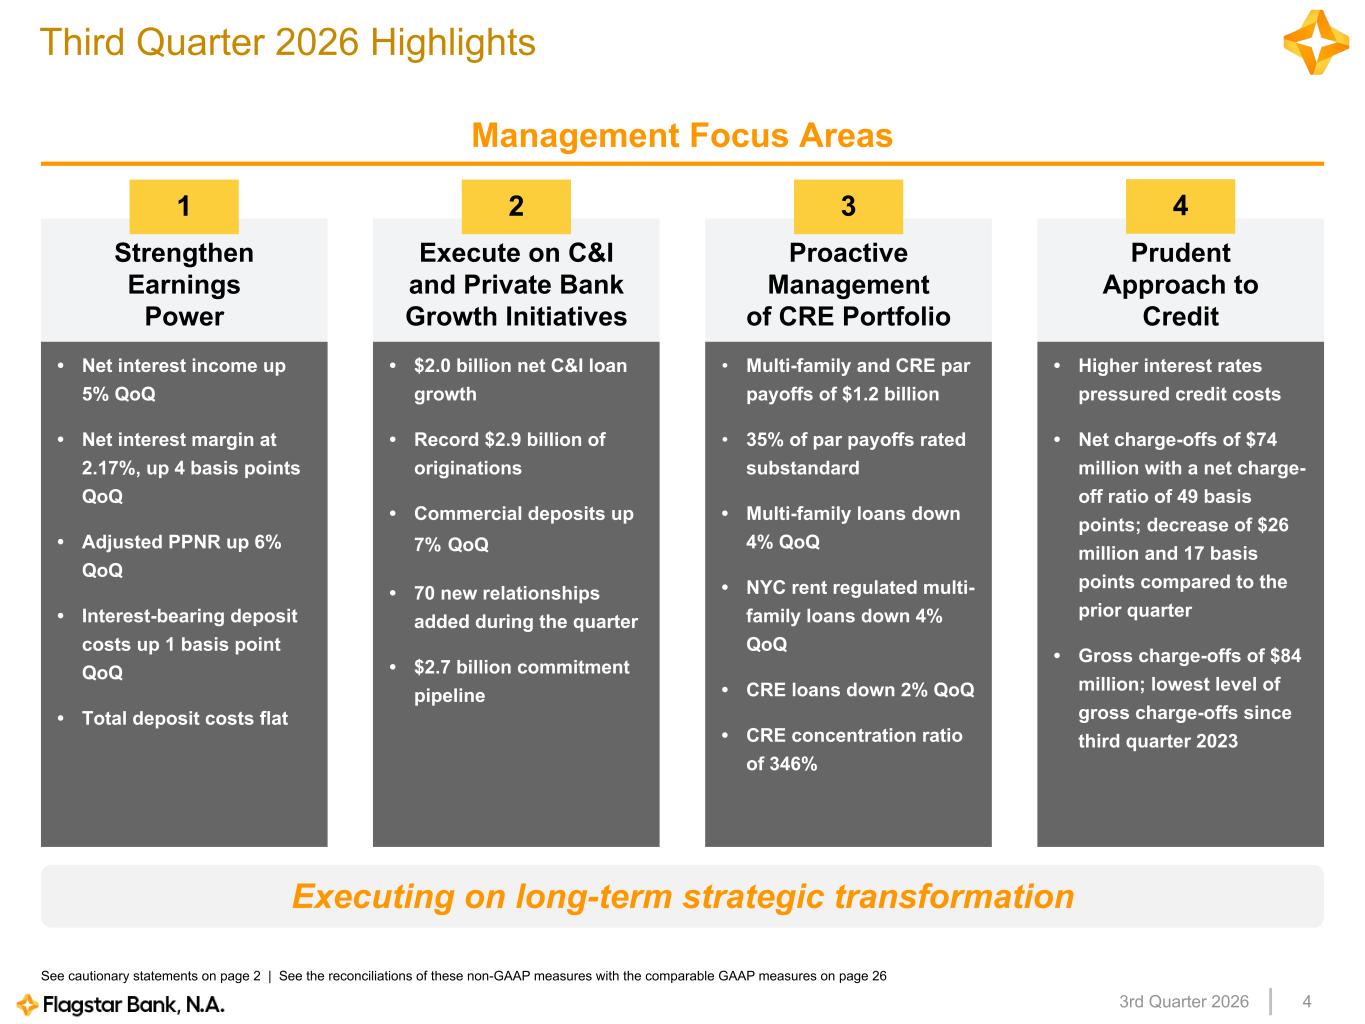
60 121 158 242 242 242 254 150 0 218 218 218 164 167 168 253 206 59 69 72 73 236 243 248 43rd Quarter 2026 Management Focus Areas Third Quarter 2026 Highlights • $2.0 billion net C&I loan growth • Record $2.9 billion of originations • Commercial deposits up 7% QoQ • 70 new relationships added during the quarter • $2.7 billion commitment pipeline Execute on C&I and Private Bank Growth Initiatives • Higher interest rates pressured credit costs • Net charge-offs of $74 million with a net charge- off ratio of 49 basis points; decrease of $26 million and 17 basis points compared to the prior quarter • Gross charge-offs of $84 million; lowest level of gross charge-offs since third quarter 2023 Proactive Management of CRE Portfolio • Multi-family and CRE par payoffs of $1.2 billion • 35% of par payoffs rated substandard • Multi-family loans down 4% QoQ • NYC rent regulated multi- family loans down 4% QoQ • CRE loans down 2% QoQ • CRE concentration ratio of 346% Prudent Approach to Credit • Net interest income up 5% QoQ • Net interest margin at 2.17%, up 4 basis points QoQ • Adjusted PPNR up 6% QoQ • Interest-bearing deposit costs up 1 basis point QoQ • Total deposit costs flat Strengthen Earnings Power 1 2 3 4 See cautionary statements on page 2 | See the reconciliations of these non-GAAP measures with the comparable GAAP measures on page 26 Executing on long-term strategic transformation
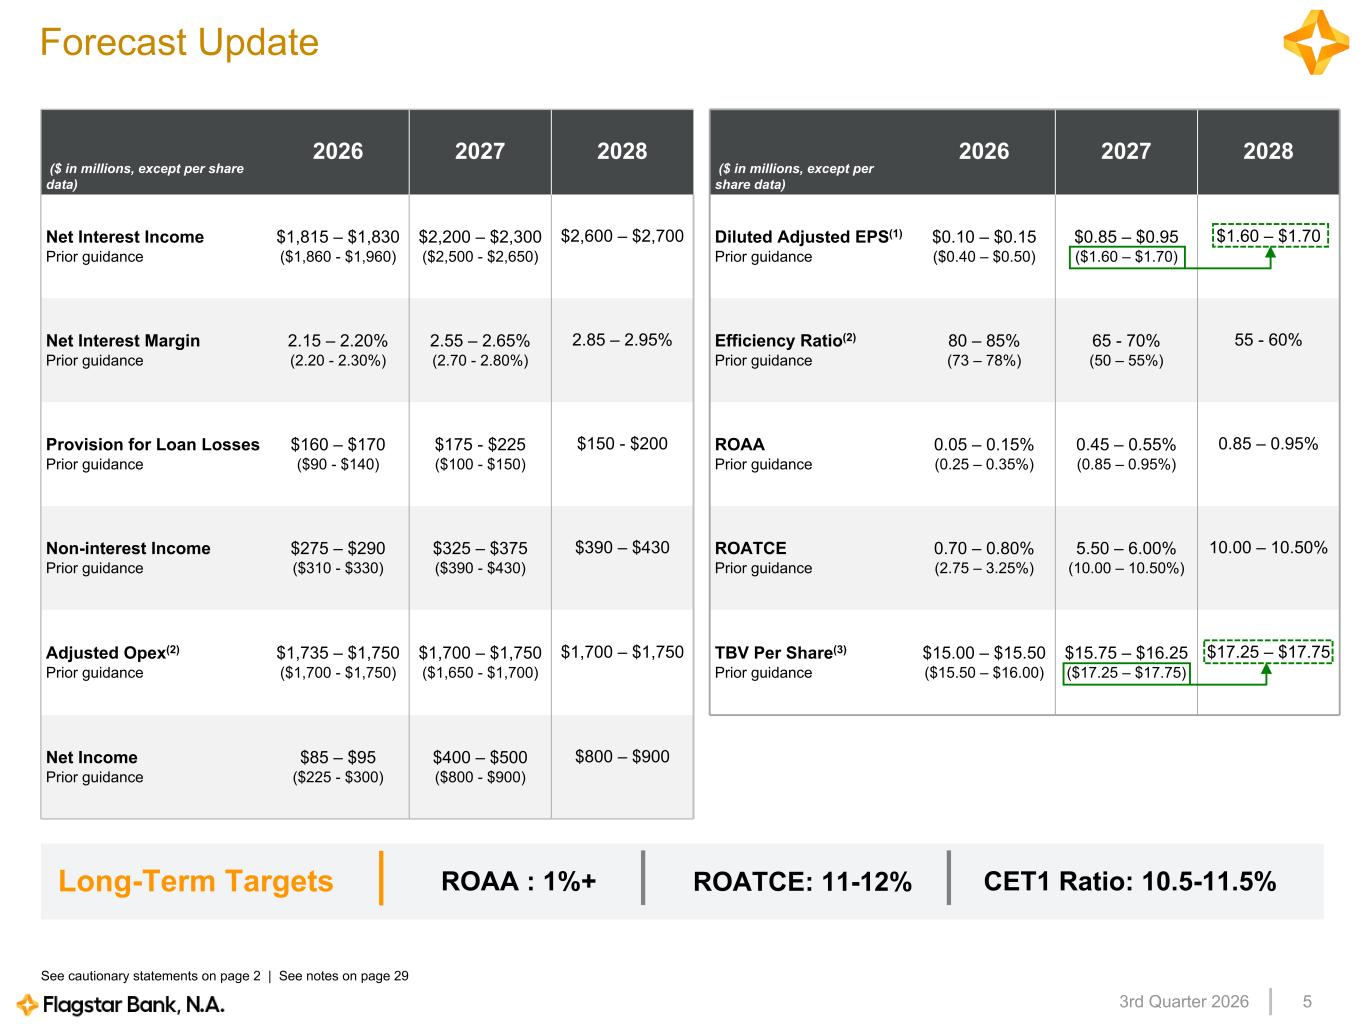
60 121 158 242 242 242 254 150 0 218 218 218 164 167 168 253 206 59 69 72 73 236 243 248 53rd Quarter 2026 Forecast Update ($ in millions, except per share data) 2026 2027 2028 Net Interest Income Prior guidance $1,815 – $1,830 ($1,860 - $1,960) $2,200 – $2,300 ($2,500 - $2,650) $2,600 – $2,700 Net Interest Margin Prior guidance 2.15 – 2.20% (2.20 - 2.30%) 2.55 – 2.65% (2.70 - 2.80%) 2.85 – 2.95% Provision for Loan Losses Prior guidance $160 – $170 ($90 - $140) $175 - $225 ($100 - $150) $150 - $200 Non-interest Income Prior guidance $275 – $290 ($310 - $330) $325 – $375 ($390 - $430) $390 – $430 Adjusted Opex(2) Prior guidance $1,735 – $1,750 ($1,700 - $1,750) $1,700 – $1,750 ($1,650 - $1,700) $1,700 – $1,750 Net Income Prior guidance $85 – $95 ($225 - $300) $400 – $500 ($800 - $900) $800 – $900 Long-Term Targets ROAA : 1%+ ROATCE: 11-12% CET1 Ratio: 10.5-11.5% See cautionary statements on page 2 | See notes on page 29 ($ in millions, except per share data) 2026 2027 2028 Diluted Adjusted EPS(1) Prior guidance $0.10 – $0.15 ($0.40 – $0.50) $0.85 – $0.95 ($1.60 – $1.70) $1.60 – $1.70 Efficiency Ratio(2) Prior guidance 80 – 85% (73 – 78%) 65 - 70% (50 – 55%) 55 - 60% ROAA Prior guidance 0.05 – 0.15% (0.25 – 0.35%) 0.45 – 0.55% (0.85 – 0.95%) 0.85 – 0.95% ROATCE Prior guidance 0.70 – 0.80% (2.75 – 3.25%) 5.50 – 6.00% (10.00 – 10.50%) 10.00 – 10.50% TBV Per Share(3) Prior guidance $15.00 – $15.50 ($15.50 – $16.00) $15.75 – $16.25 ($17.25 – $17.75) $17.25 – $17.75
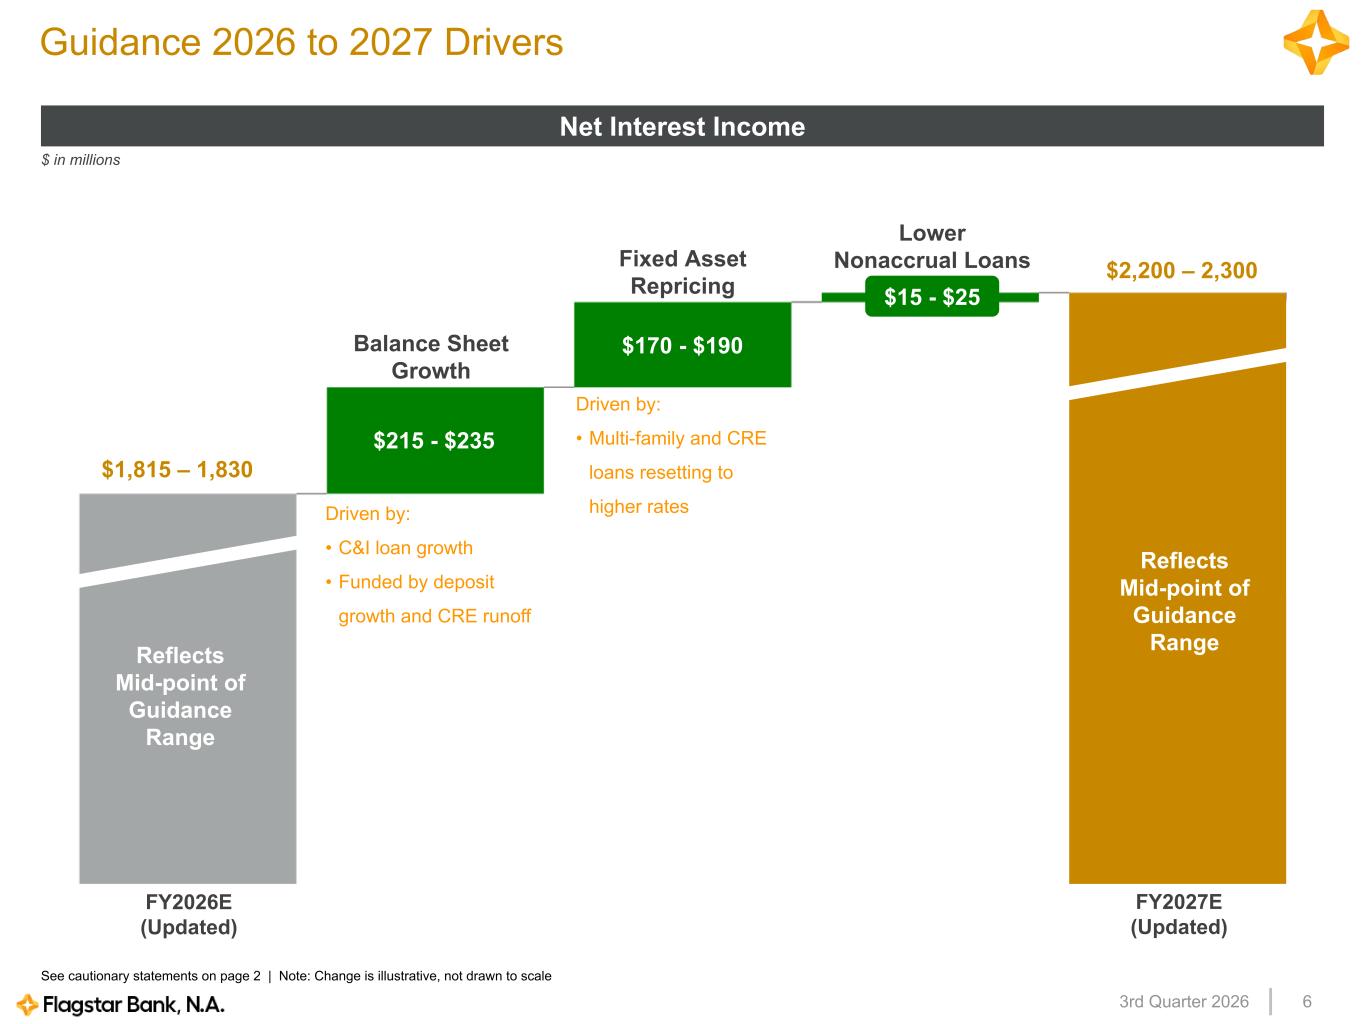
60 121 158 242 242 242 254 150 0 218 218 218 164 167 168 253 206 59 69 72 73 236 243 248 63rd Quarter 2026 Guidance 2026 to 2027 Drivers Net Interest Income $1,815 – 1,830 FY2026E (Updated) Driven by: • C&I loan growth • Funded by deposit growth and CRE runoff $ in millions $215 - $235 Driven by: • Multi-family and CRE loans resetting to higher rates Balance Sheet Growth Fixed Asset Repricing Lower Nonaccrual Loans FY2027E (Updated) See cautionary statements on page 2 | Note: Change is illustrative, not drawn to scale Reflects Mid-point of Guidance Range Reflects Mid-point of Guidance Range $2,200 – 2,300 $170 - $190 $15 - $25
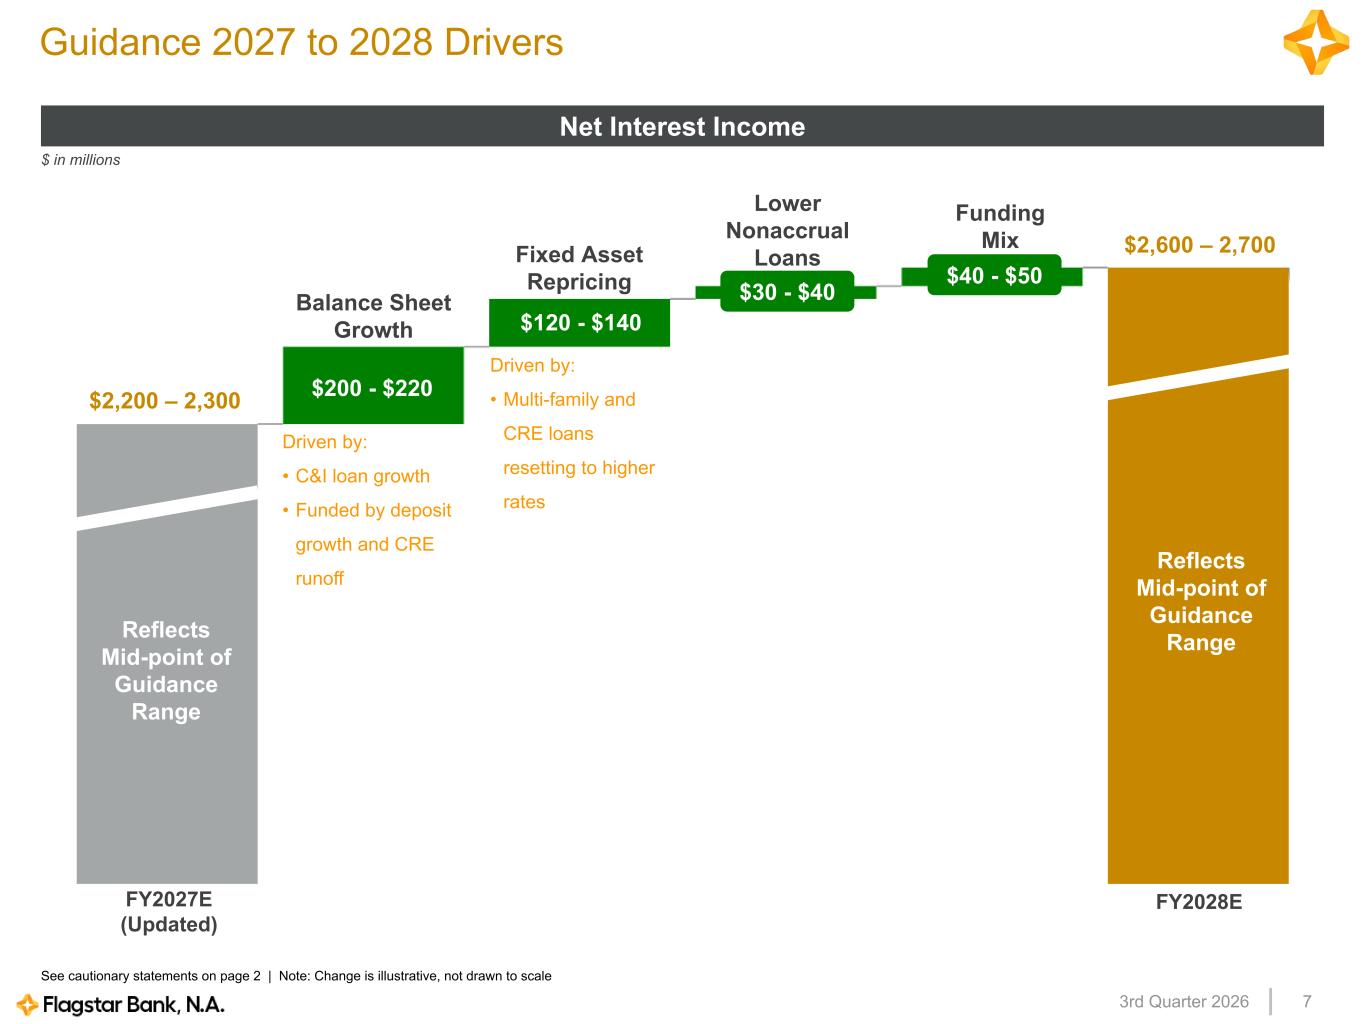
60 121 158 242 242 242 254 150 0 218 218 218 164 167 168 253 206 59 69 72 73 236 243 248 73rd Quarter 2026 Guidance 2027 to 2028 Drivers Net Interest Income $2,200 – 2,300 FY2027E (Updated) Driven by: • C&I loan growth • Funded by deposit growth and CRE runoff $ in millions $200 - $220 Driven by: • Multi-family and CRE loans resetting to higher rates Balance Sheet Growth Fixed Asset Repricing Lower Nonaccrual Loans FY2028E Reflects Mid-point of Guidance Range Reflects Mid-point of Guidance Range $2,600 – 2,700 $120 - $140 $40 - $50 $30 - $40 Funding Mix See cautionary statements on page 2 | Note: Change is illustrative, not drawn to scale
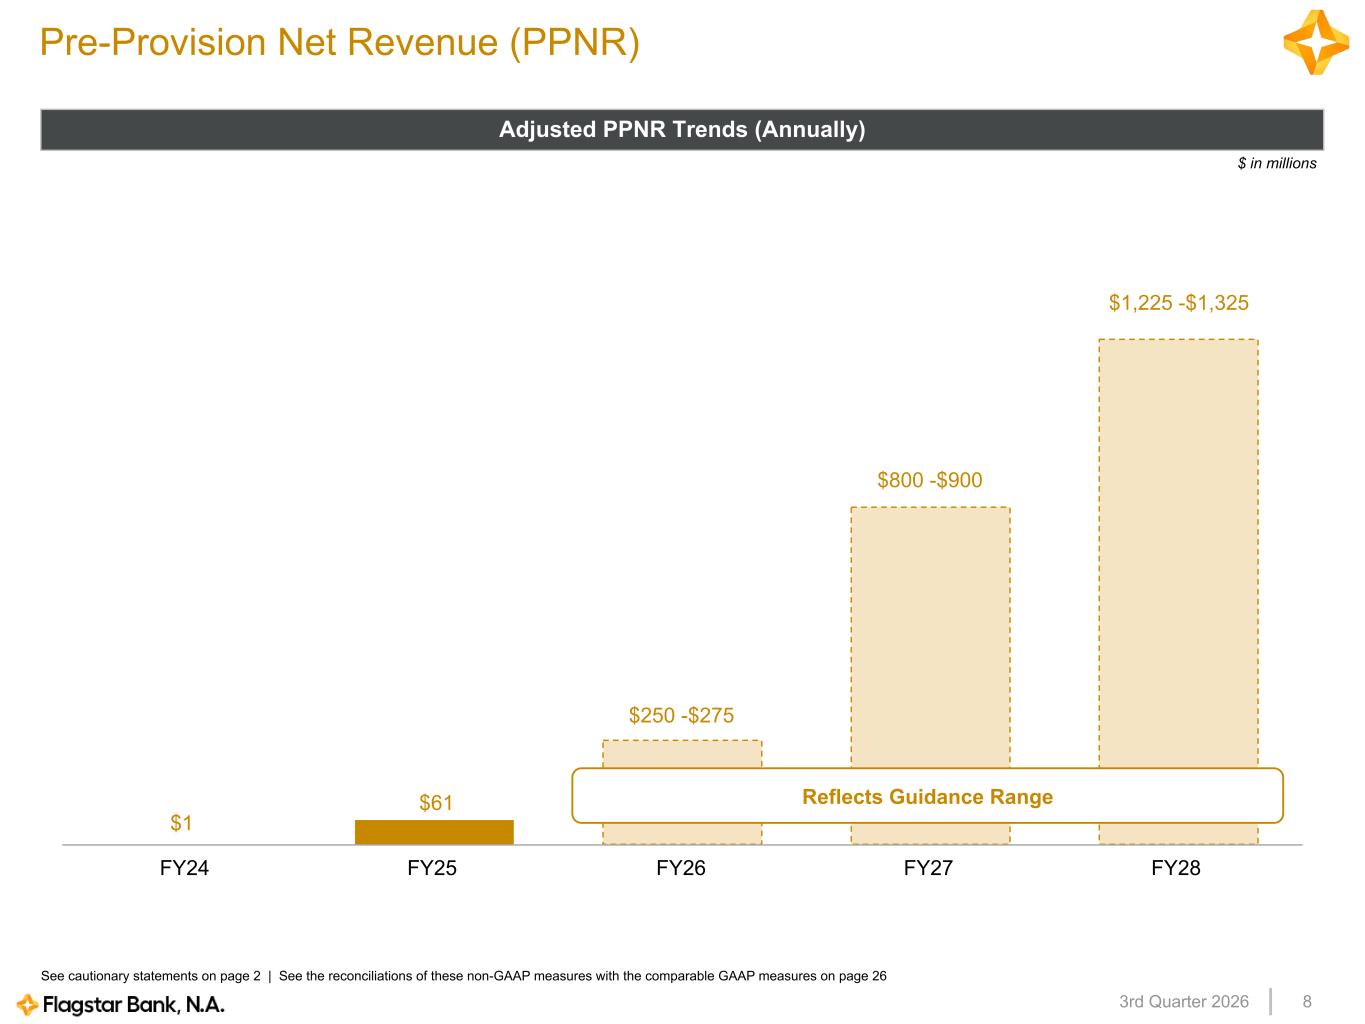
60 121 158 242 242 242 254 150 0 218 218 218 164 167 168 253 206 59 69 72 73 236 243 248 83rd Quarter 2026 Pre-Provision Net Revenue (PPNR) See cautionary statements on page 2 | See the reconciliations of these non-GAAP measures with the comparable GAAP measures on page 26 Adjusted PPNR Trends (Annually) FY24 FY25 FY26 FY27 FY28 $1 $61 $250 -$275 Reflects Guidance Range $ in millions $800 -$900 $1,225 -$1,325
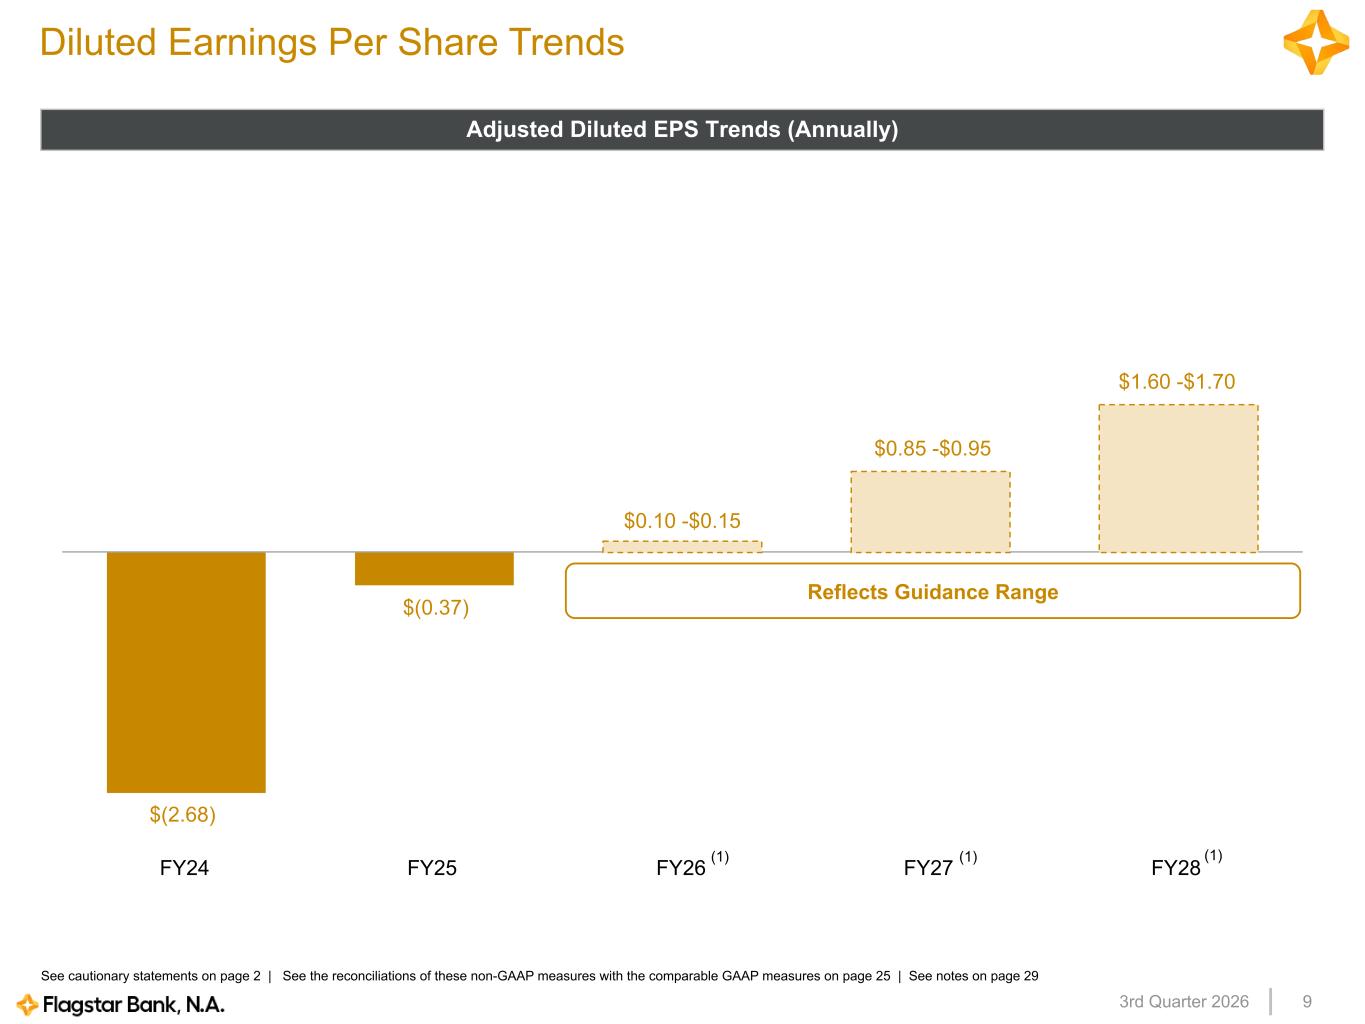
60 121 158 242 242 242 254 150 0 218 218 218 164 167 168 253 206 59 69 72 73 236 243 248 93rd Quarter 2026 Diluted Earnings Per Share Trends See cautionary statements on page 2 | See the reconciliations of these non-GAAP measures with the comparable GAAP measures on page 25 | See notes on page 29 Adjusted Diluted EPS Trends (Annually) FY24 FY25 FY26 FY27 FY28(1) (1) $(2.68) $(0.37) $0.10 -$0.15 $0.85 -$0.95 (1) $1.60 -$1.70 Reflects Guidance Range
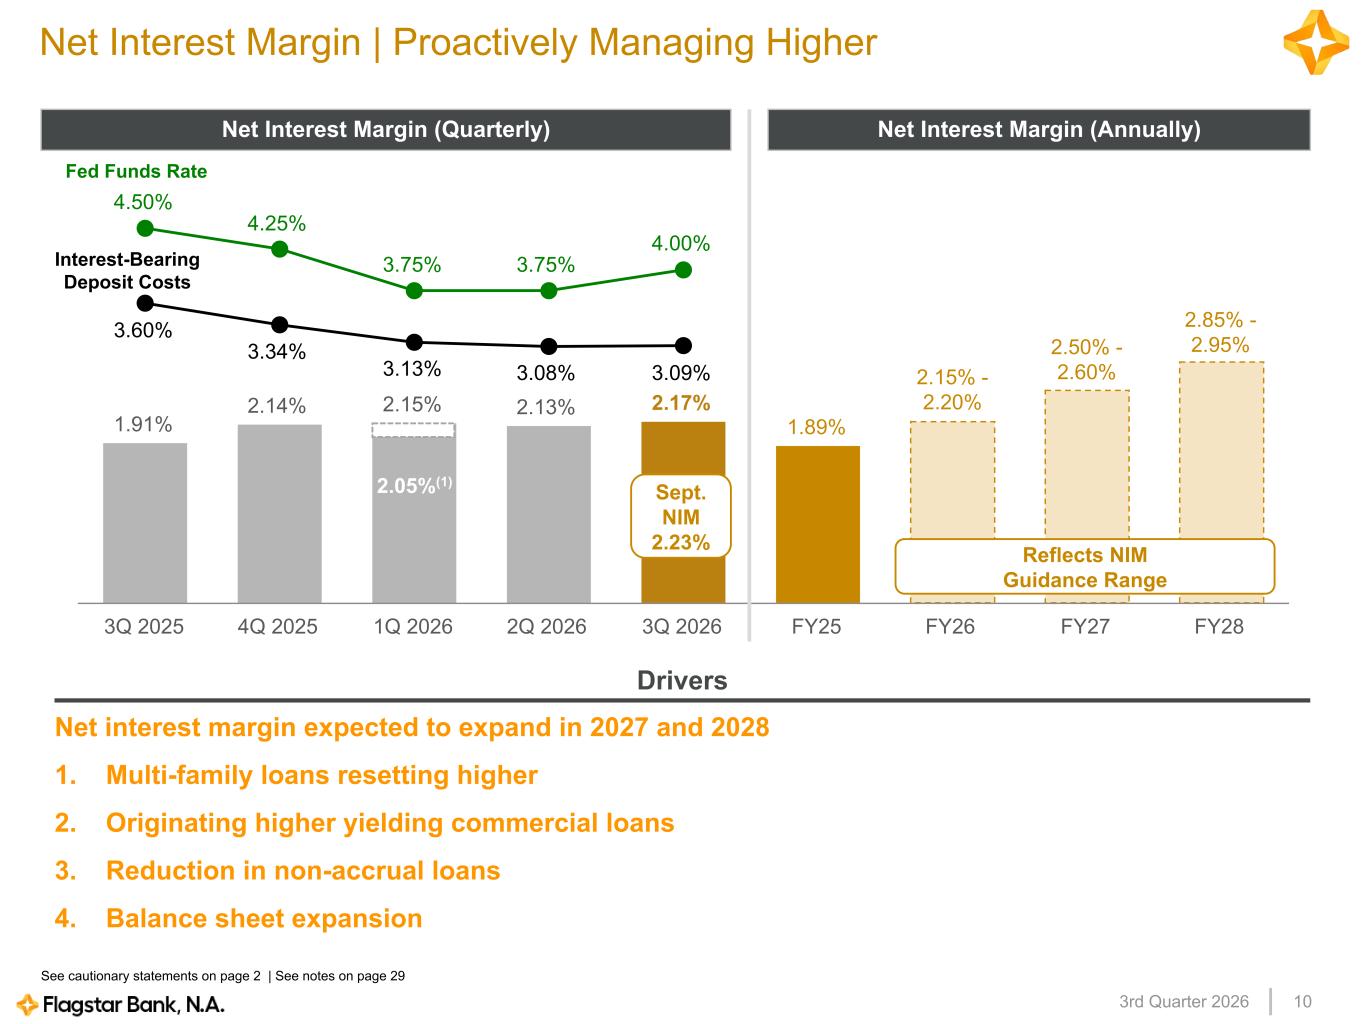
60 121 158 242 242 242 254 150 0 218 218 218 164 167 168 253 206 59 69 72 73 236 243 248 103rd Quarter 2026 1.91% 2.14% 2.15% 2.13% 2.17% 1.89% 3.60% 3.34% 3.13% 3.08% 3.09% 4.50% 4.25% 3.75% 3.75% 4.00% 3Q 2025 4Q 2025 1Q 2026 2Q 2026 3Q 2026 FY25 FY26 FY27 FY28 Net Interest Margin | Proactively Managing Higher Net Interest Margin (Quarterly) Net interest margin expected to expand in 2027 and 2028 1. Multi-family loans resetting higher 2. Originating higher yielding commercial loans 3. Reduction in non-accrual loans 4. Balance sheet expansion Drivers See cautionary statements on page 2 | See notes on page 29 Reflects NIM Guidance Range 2.05%(1) 2.15% - 2.20% 2.50% - 2.60% Fed Funds Rate Interest-Bearing Deposit Costs Net Interest Margin (Annually) Sept. NIM 2.23% 2.85% - 2.95%
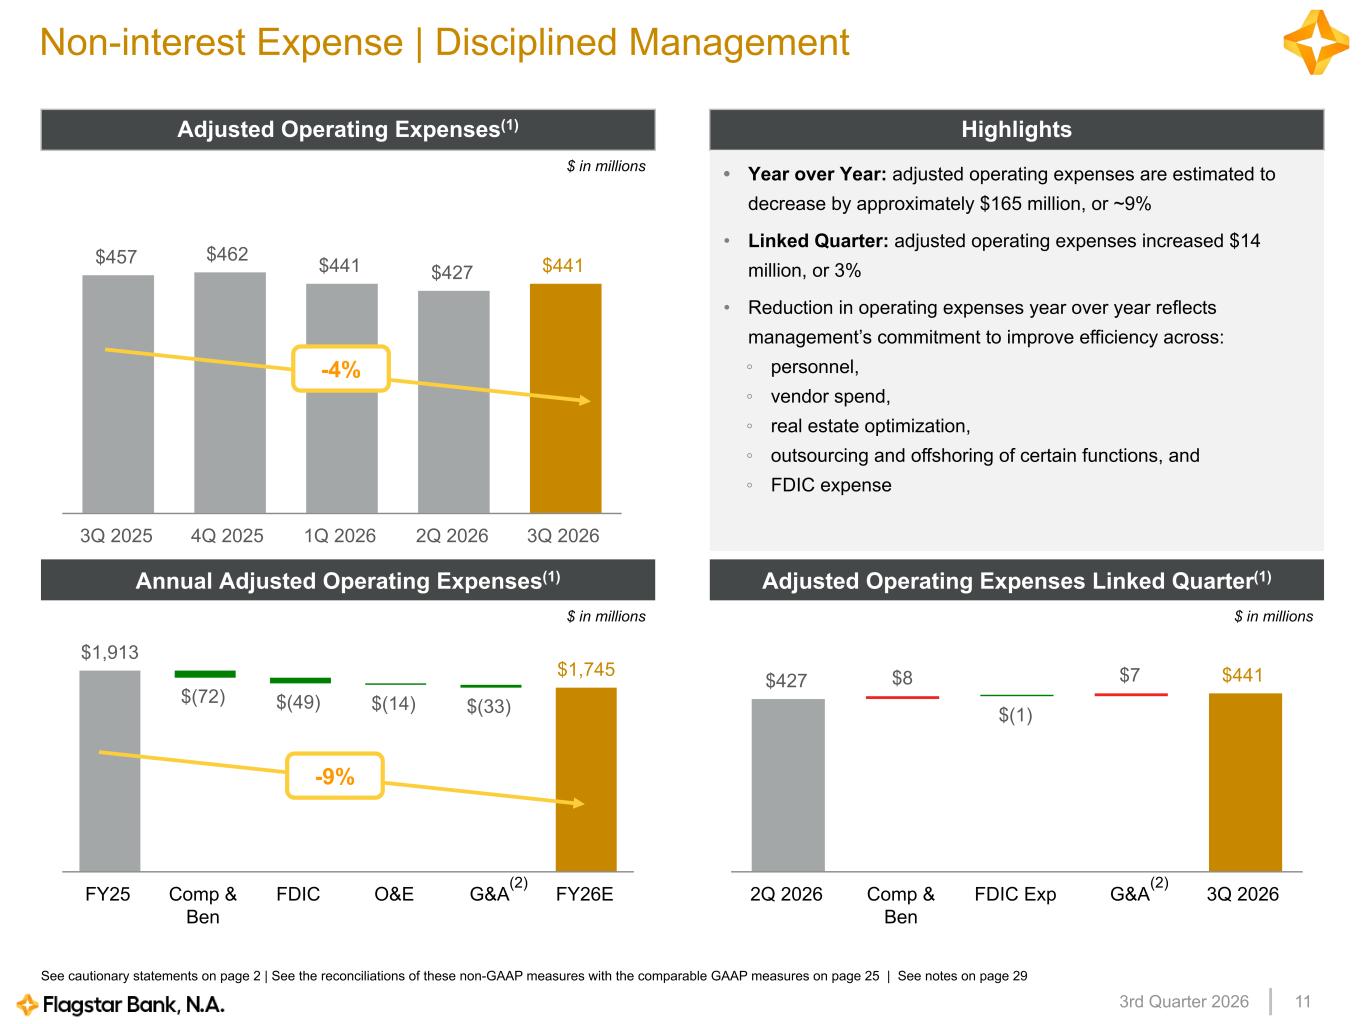
60 121 158 242 242 242 254 150 0 218 218 218 164 167 168 253 206 59 69 72 73 236 243 248 113rd Quarter 2026 $1,913 $(72) $(49) $(14) $(33) $1,745 FY25 Comp & Ben FDIC O&E G&A FY26E Non-interest Expense | Disciplined Management Highlights • Year over Year: adjusted operating expenses are estimated to decrease by approximately $165 million, or ~9% • Linked Quarter: adjusted operating expenses increased $14 million, or 3% • Reduction in operating expenses year over year reflects management’s commitment to improve efficiency across: ◦ personnel, ◦ vendor spend, ◦ real estate optimization, ◦ outsourcing and offshoring of certain functions, and ◦ FDIC expense Adjusted Operating Expenses(1) Adjusted Operating Expenses Linked Quarter(1) See cautionary statements on page 2 | See the reconciliations of these non-GAAP measures with the comparable GAAP measures on page 25 | See notes on page 29 Annual Adjusted Operating Expenses(1) $ in millions $ in millions $457 $462 $441 $427 $441 3Q 2025 4Q 2025 1Q 2026 2Q 2026 3Q 2026 $427 $8 $(1) $7 $441 2Q 2026 Comp & Ben FDIC Exp G&A 3Q 2026 $ in millions -4% (2) (2) -9%
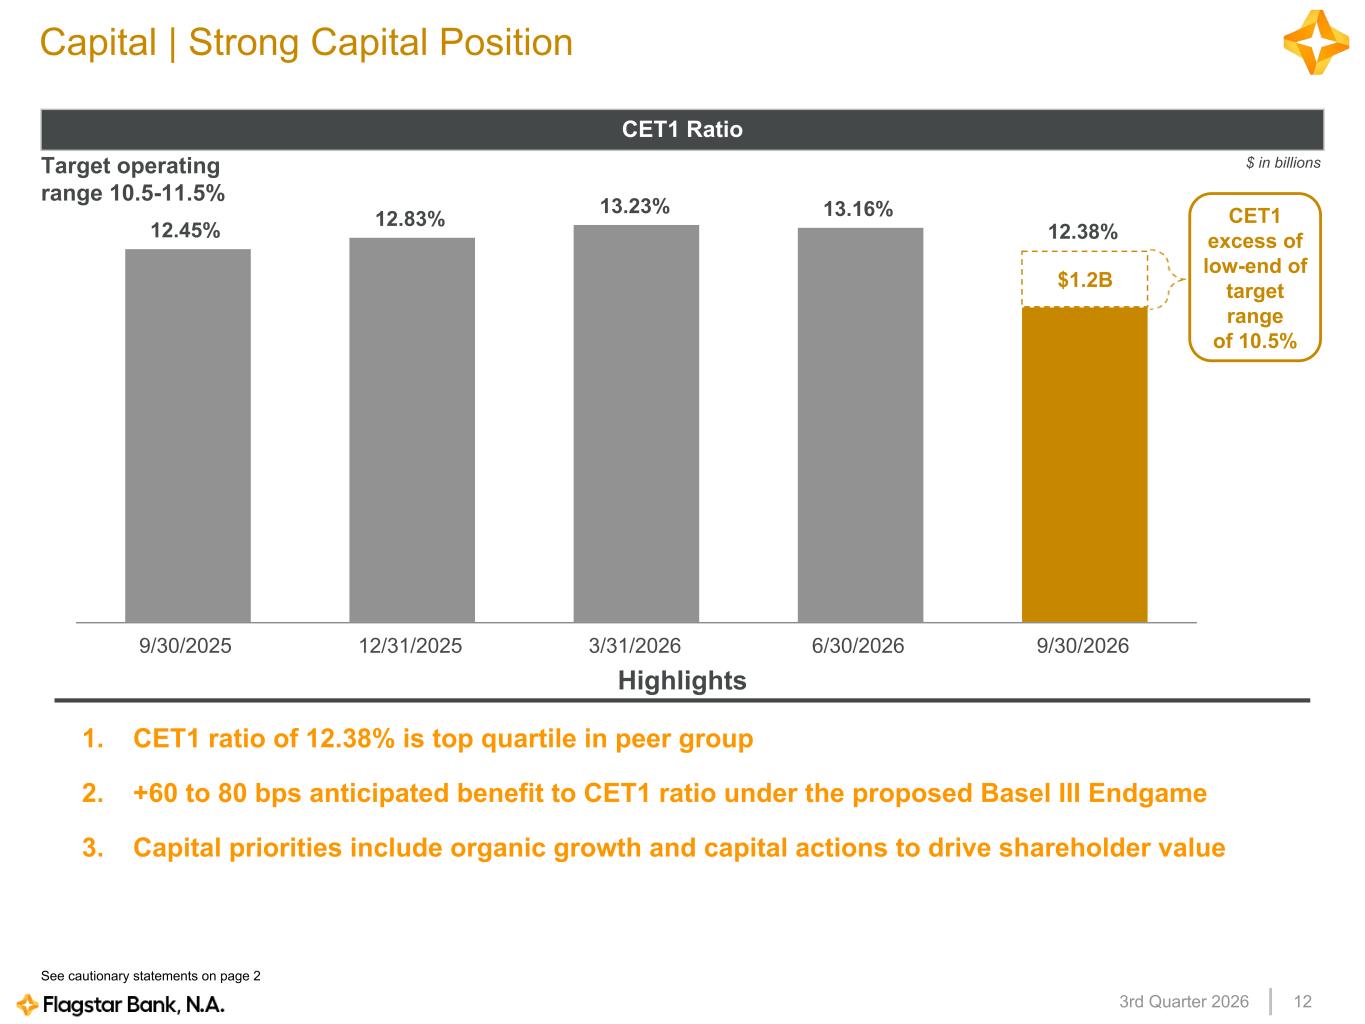
60 121 158 242 242 242 254 150 0 218 218 218 164 167 168 253 206 59 69 72 73 236 243 248 123rd Quarter 2026 Capital | Strong Capital Position CET1 Ratio Target operating range 10.5-11.5% 1. CET1 ratio of 12.38% is top quartile in peer group 2. +60 to 80 bps anticipated benefit to CET1 ratio under the proposed Basel III Endgame 3. Capital priorities include organic growth and capital actions to drive shareholder value Highlights $ in billions CET1 excess of low-end of target range of 10.5% 12.45% 12.83% 13.23% 13.16% 12.38% 9/30/2025 12/31/2025 3/31/2026 6/30/2026 9/30/2026 $1.2B See cautionary statements on page 2
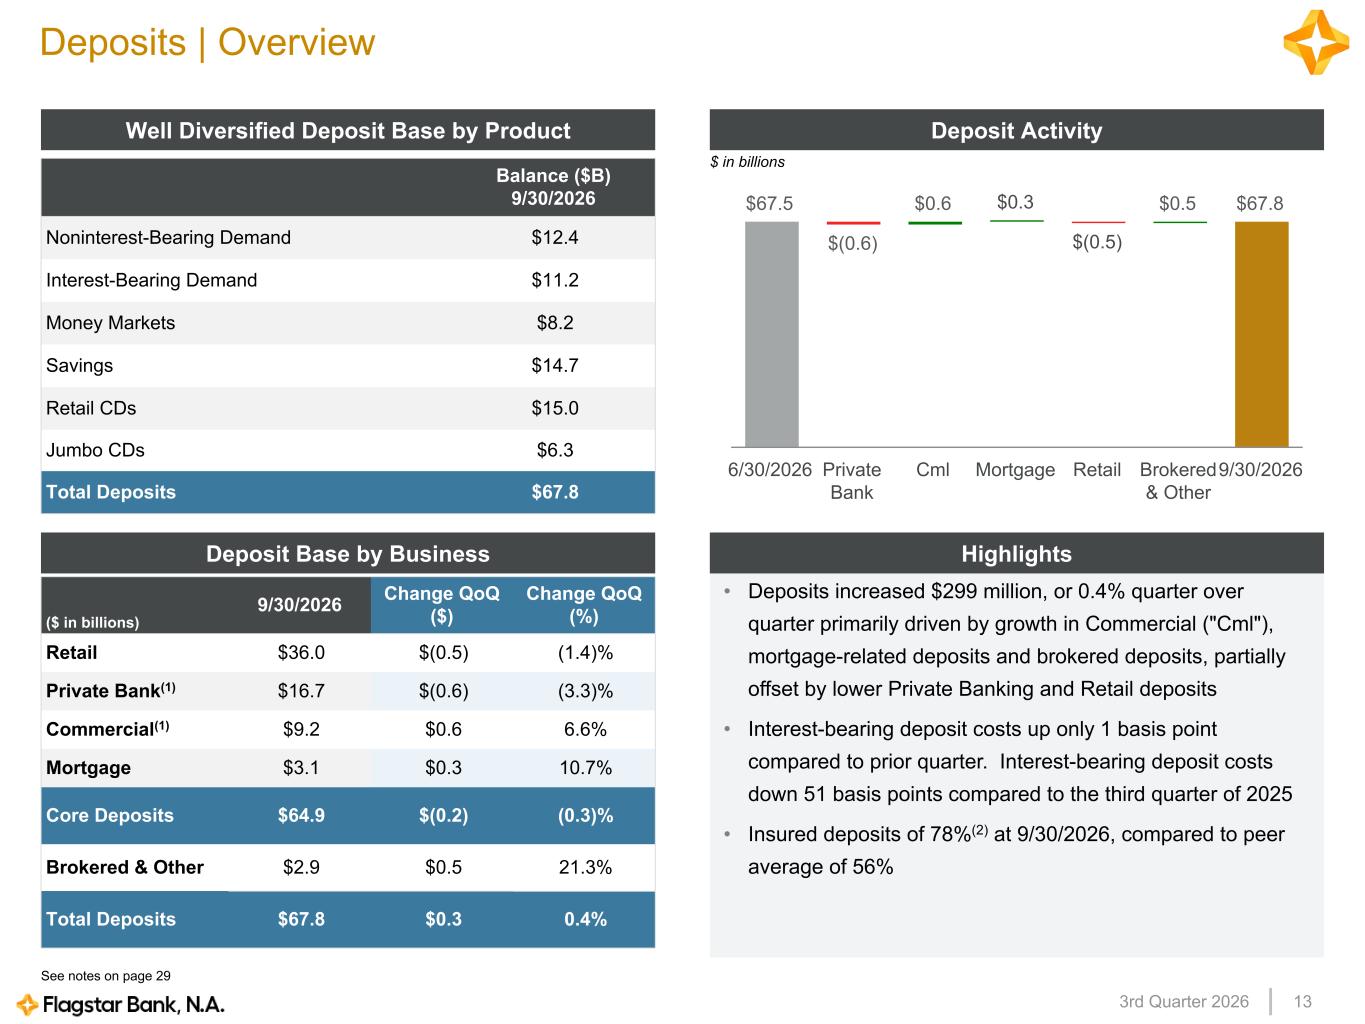
60 121 158 242 242 242 254 150 0 218 218 218 164 167 168 253 206 59 69 72 73 236 243 248 133rd Quarter 2026 Balance ($B) 9/30/2026 Noninterest-Bearing Demand $12.4 Interest-Bearing Demand $11.2 Money Markets $8.2 Savings $14.7 Retail CDs $15.0 Jumbo CDs $6.3 Total Deposits $67.8 Deposits | Overview Deposit ActivityWell Diversified Deposit Base by Product • Deposits increased $299 million, or 0.4% quarter over quarter primarily driven by growth in Commercial ("Cml"), mortgage-related deposits and brokered deposits, partially offset by lower Private Banking and Retail deposits • Interest-bearing deposit costs up only 1 basis point compared to prior quarter. Interest-bearing deposit costs down 51 basis points compared to the third quarter of 2025 • Insured deposits of 78%(2) at 9/30/2026, compared to peer average of 56% HighlightsDeposit Base by Business ($ in billions) 9/30/2026 Change QoQ ($) Change QoQ (%) Retail $36.0 $(0.5) (1.4)% Private Bank(1) $16.7 $(0.6) (3.3)% Commercial(1) $9.2 $0.6 6.6% Mortgage $3.1 $0.3 10.7% Core Deposits $64.9 $(0.2) (0.3)% Brokered & Other $2.9 $0.5 21.3% Total Deposits $67.8 $0.3 0.4% $ in billions See notes on page 29 $67.5 $(0.6) $0.6 $0.3 $(0.5) $0.5 $67.8 6/30/2026 Private Bank Cml Mortgage Retail Brokered & Other 9/30/2026
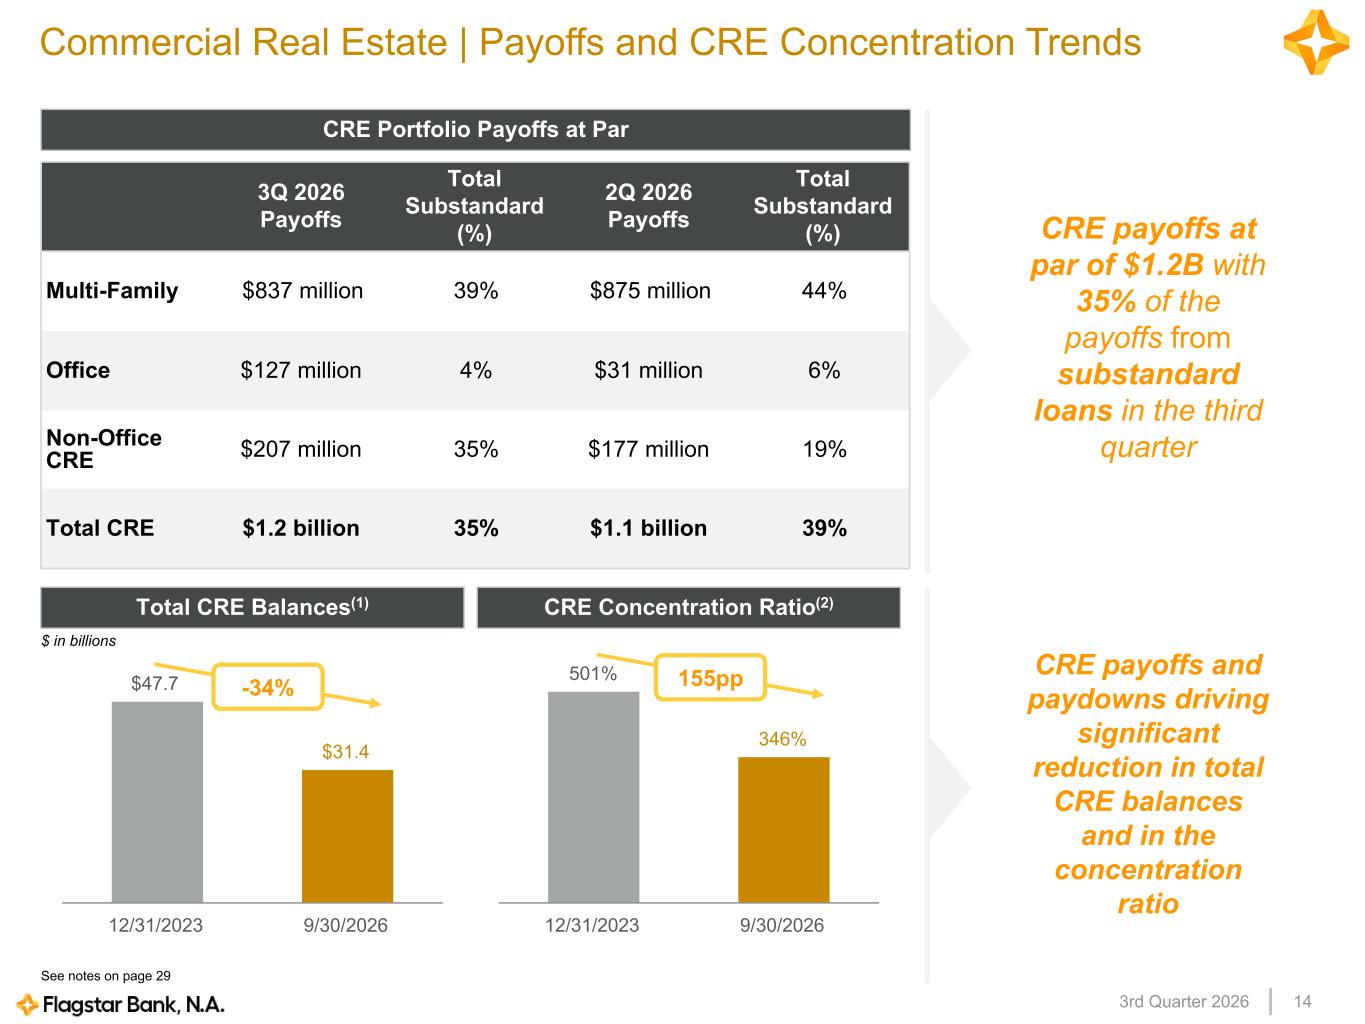
60 121 158 242 242 242 254 150 0 218 218 218 164 167 168 253 206 59 69 72 73 236 243 248 143rd Quarter 2026 501% 346% 12/31/2023 9/30/2026 Commercial Real Estate | Payoffs and CRE Concentration Trends 3Q 2026 Payoffs Total Substandard (%) 2Q 2026 Payoffs Total Substandard (%) Multi-Family $837 million 39% $875 million 44% Office $127 million 4% $31 million 6% Non-Office CRE $207 million 35% $177 million 19% Total CRE $1.2 billion 35% $1.1 billion 39% CRE payoffs at par of $1.2B with 35% of the payoffs from substandard loans in the third quarter CRE Portfolio Payoffs at Par Total CRE Balances(1) CRE payoffs and paydowns driving significant reduction in total CRE balances and in the concentration ratio 155pp CRE Concentration Ratio(2) $ in billions -34% See notes on page 29 $47.7 $31.4 12/31/2023 9/30/2026
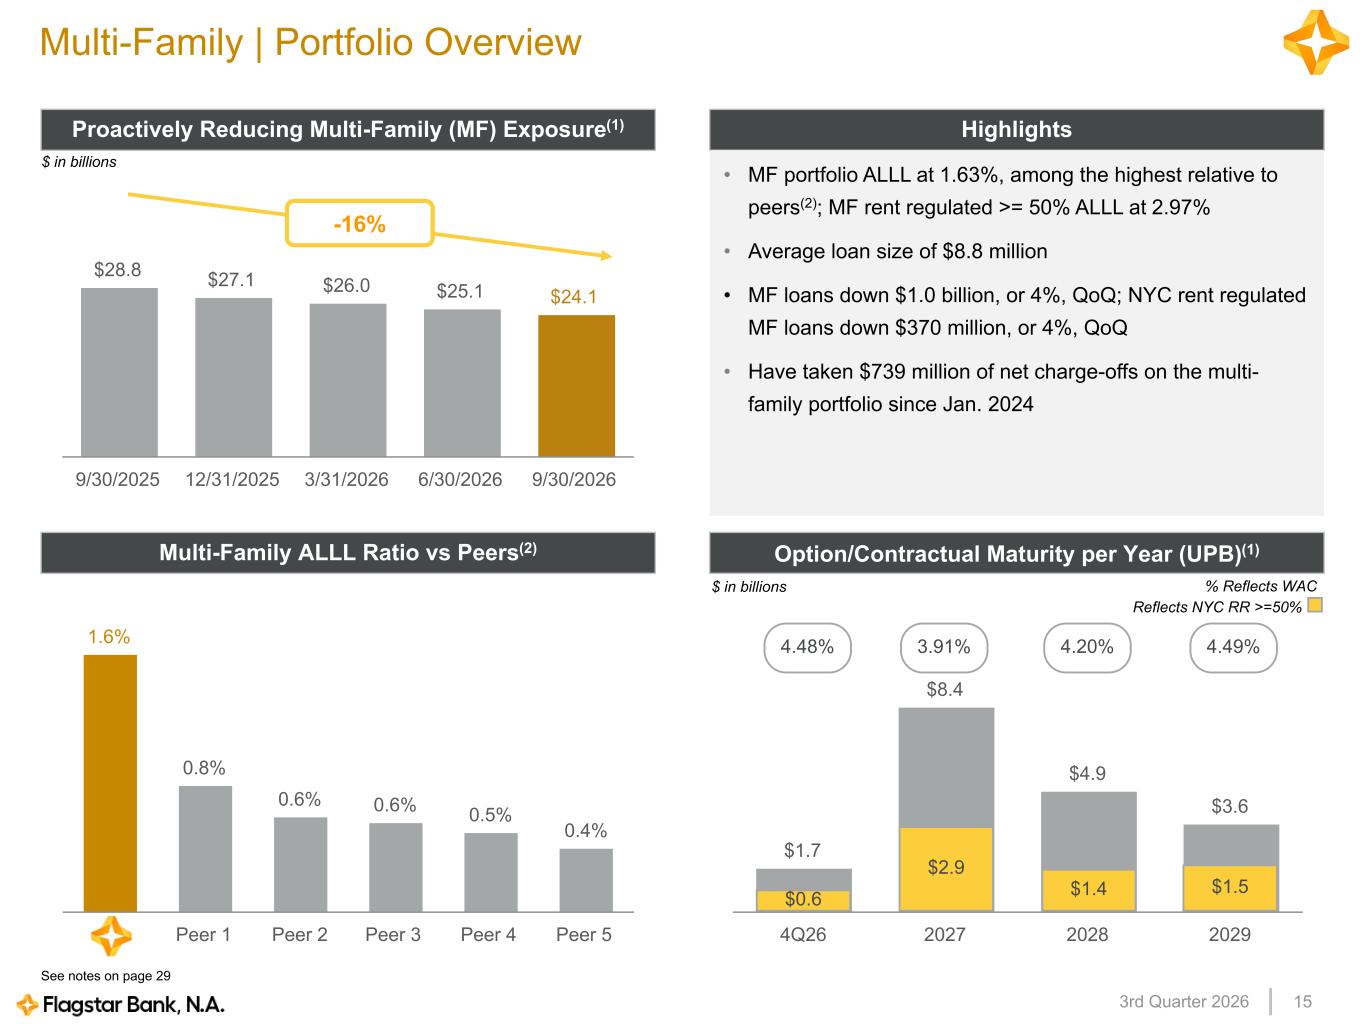
60 121 158 242 242 242 254 150 0 218 218 218 164 167 168 253 206 59 69 72 73 236 243 248 153rd Quarter 2026 Multi-Family | Portfolio Overview Highlights • MF portfolio ALLL at 1.63%, among the highest relative to peers(2); MF rent regulated >= 50% ALLL at 2.97% • Average loan size of $8.8 million • MF loans down $1.0 billion, or 4%, QoQ; NYC rent regulated MF loans down $370 million, or 4%, QoQ • Have taken $739 million of net charge-offs on the multi- family portfolio since Jan. 2024 Proactively Reducing Multi-Family (MF) Exposure(1) $ in billions Multi-Family ALLL Ratio vs Peers(2) Option/Contractual Maturity per Year (UPB)(1) $ in billions % Reflects WAC See notes on page 29 3.53% 3.73% 4.66%4.26% $28.8 $27.1 $26.0 $25.1 $24.1 9/30/2025 12/31/2025 3/31/2026 6/30/2026 9/30/2026 -16% 1.6% 0.8% 0.6% 0.6% 0.5% 0.4% FLG Peer 1 Peer 2 Peer 3 Peer 4 Peer 5 $1.7 $8.4 $4.9 $3.6 4Q26 2027 2028 2029 4.48% 3.91% 4.20% 4.49% $1.5$1.4 $2.9 $0.6 Reflects NYC RR >=50%
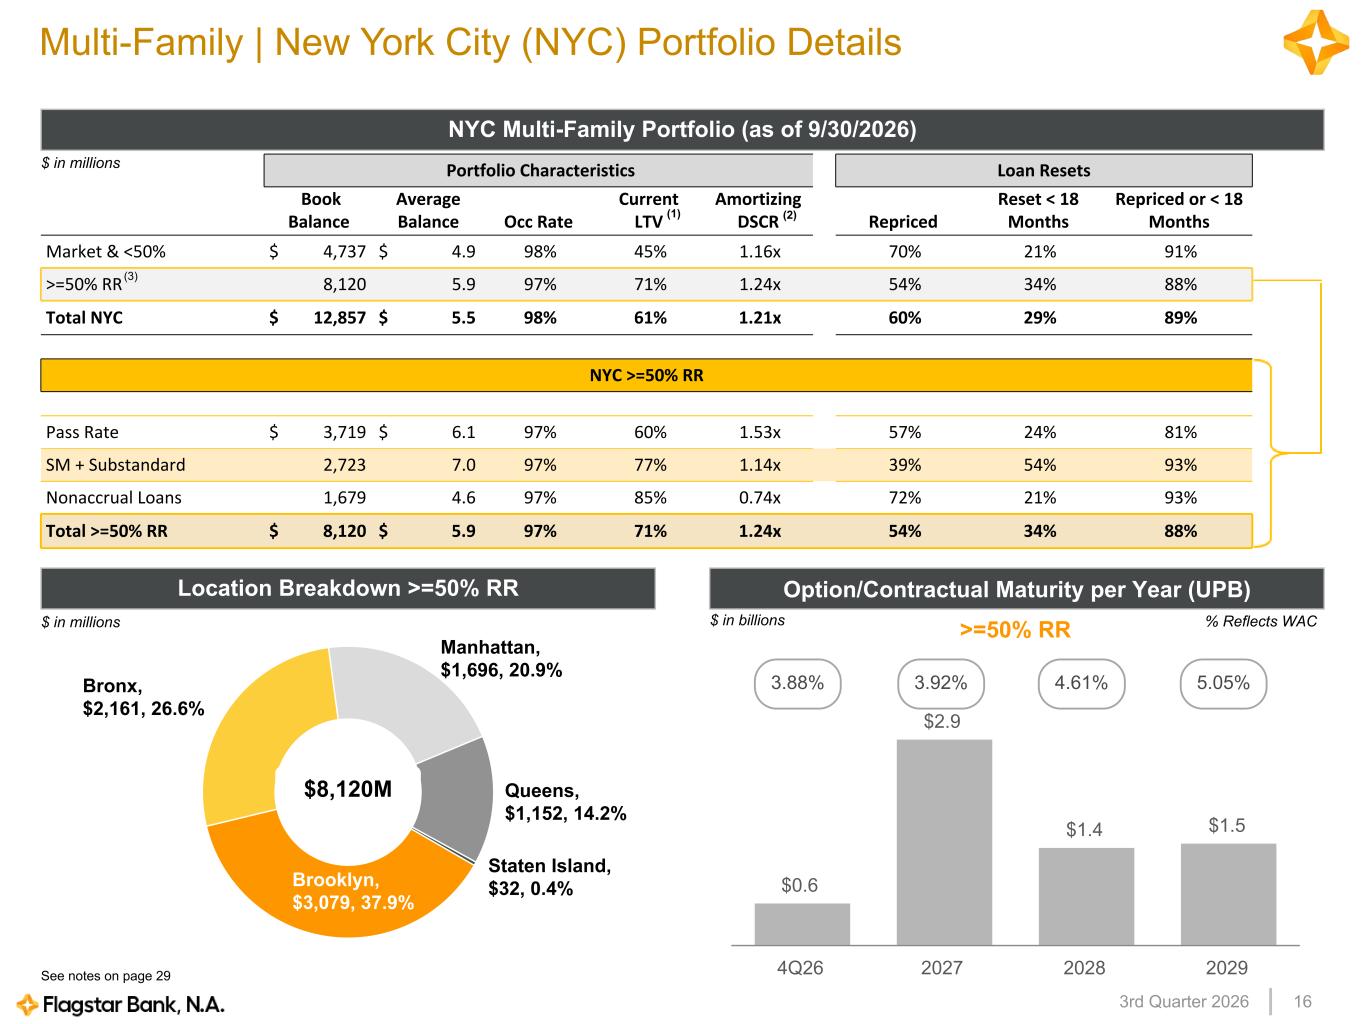
60 121 158 242 242 242 254 150 0 218 218 218 164 167 168 253 206 59 69 72 73 236 243 248 163rd Quarter 2026 $0.6 $2.9 $1.4 $1.5 4Q26 2027 2028 2029 Brooklyn, $3,079, 37.9% Bronx, $2,161, 26.6% Manhattan, $1,696, 20.9% Queens, $1,152, 14.2% Staten Island, $32, 0.4% Portfolio Characteristics Loan Resets Book Balance Average Balance Occ Rate Current LTV Amortizing DSCR Repriced Reset < 18 Months Repriced or < 18 Months Market & <50% $ 4,737 $ 4.9 98% 45% 1.16x 70% 21% 91% >=50% RR 8,120 5.9 97% 71% 1.24x 54% 34% 88% Total NYC $ 12,857 $ 5.5 98% 61% 1.21x 60% 29% 89% NYC >=50% RR Pass Rate $ 3,719 $ 6.1 97% 60% 1.53x 57% 24% 81% SM + Substandard 2,723 7.0 97% 77% 1.14x 39% 54% 93% Nonaccrual Loans 1,679 4.6 97% 85% 0.74x 72% 21% 93% Total >=50% RR $ 8,120 $ 5.9 97% 71% 1.24x 54% 34% 88% Multi-Family | New York City (NYC) Portfolio Details NYC Multi-Family Portfolio (as of 9/30/2026) $ in millions (3) (1) (2) Location Breakdown >=50% RR $ in millions Option/Contractual Maturity per Year (UPB) $ in billions % Reflects WAC>=50% RR See notes on page 29 3.92%3.88% 4.61% 5.05% $8,120M
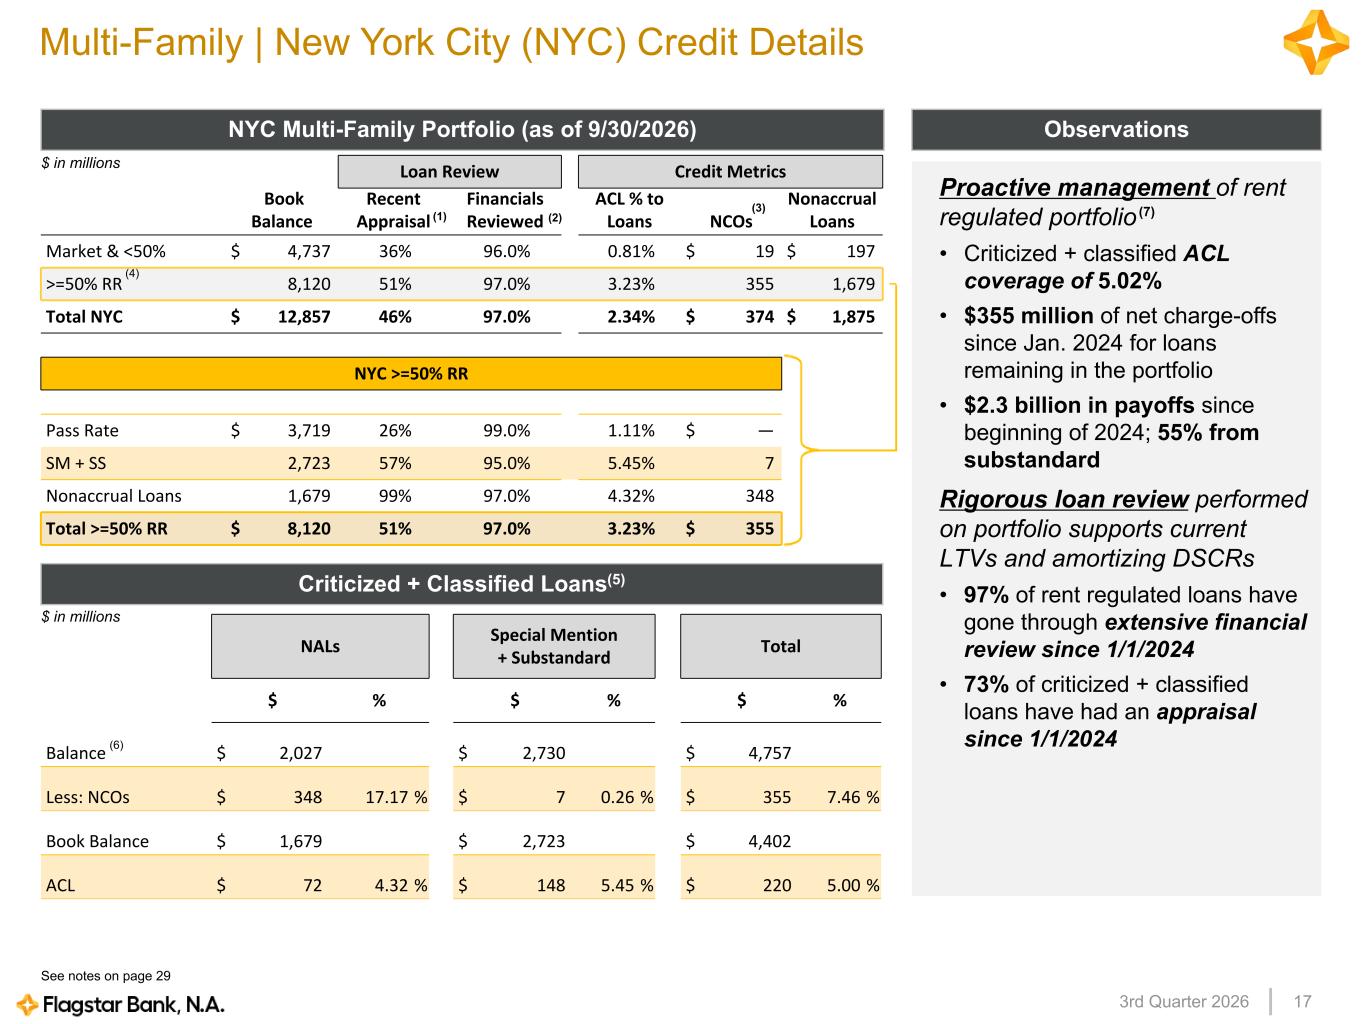
60 121 158 242 242 242 254 150 0 218 218 218 164 167 168 253 206 59 69 72 73 236 243 248 173rd Quarter 2026 NALs Special Mention + Substandard Total $ % $ % $ % Balance $ 2,027 $ 2,730 $ 4,757 Less: NCOs $ 348 17.17 % $ 7 0.26 % $ 355 7.46 % Book Balance $ 1,679 $ 2,723 $ 4,402 ACL $ 72 4.32 % $ 148 5.45 % $ 220 5.00 % Loan Review Credit Metrics Book Balance Recent Appraisal Financials Reviewed ACL % to Loans NCOs Nonaccrual Loans Market & <50% $ 4,737 36% 96.0% 0.81% $ 19 $ 197 >=50% RR 8,120 51% 97.0% 3.23% 355 1,679 Total NYC $ 12,857 46% 97.0% 2.34% $ 374 $ 1,875 NYC >=50% RR Pass Rate $ 3,719 26% 99.0% 1.11% $ — SM + SS 2,723 57% 95.0% 5.45% 7 Nonaccrual Loans 1,679 99% 97.0% 4.32% 348 Total >=50% RR $ 8,120 51% 97.0% 3.23% $ 355 Multi-Family | New York City (NYC) Credit Details NYC Multi-Family Portfolio (as of 9/30/2026) $ in millions (4) (1) (2) Proactive management of rent regulated portfolio • Criticized + classified ACL coverage of 5.02% • $355 million of net charge-offs since Jan. 2024 for loans remaining in the portfolio • $2.3 billion in payoffs since beginning of 2024; 55% from substandard Rigorous loan review performed on portfolio supports current LTVs and amortizing DSCRs • 97% of rent regulated loans have gone through extensive financial review since 1/1/2024 • 73% of criticized + classified loans have had an appraisal since 1/1/2024 Criticized + Classified Loans(5) (7) (6) Observations See notes on page 29 $ in millions (3)
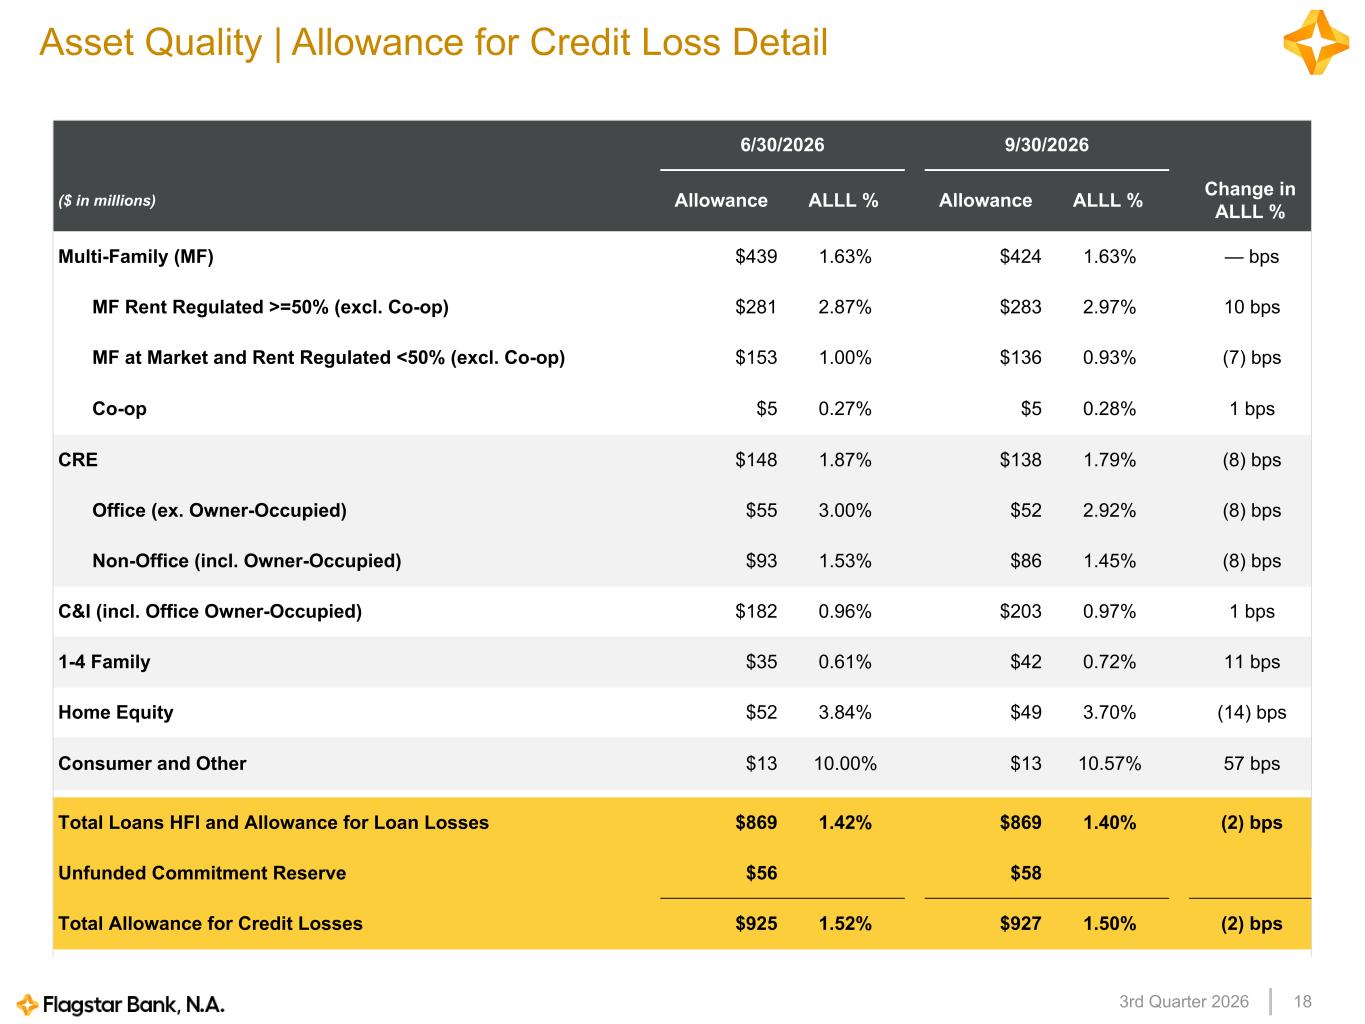
60 121 158 242 242 242 254 150 0 218 218 218 164 167 168 253 206 59 69 72 73 236 243 248 183rd Quarter 2026 6/30/2026 9/30/2026 ($ in millions) Allowance ALLL % Allowance ALLL % Change in ALLL % Multi-Family (MF) $439 1.63% $424 1.63% — bps MF Rent Regulated >=50% (excl. Co-op) $281 2.87% $283 2.97% 10 bps MF at Market and Rent Regulated <50% (excl. Co-op) $153 1.00% $136 0.93% (7) bps Co-op $5 0.27% $5 0.28% 1 bps CRE $148 1.87% $138 1.79% (8) bps Office (ex. Owner-Occupied) $55 3.00% $52 2.92% (8) bps Non-Office (incl. Owner-Occupied) $93 1.53% $86 1.45% (8) bps C&I (incl. Office Owner-Occupied) $182 0.96% $203 0.97% 1 bps 1-4 Family $35 0.61% $42 0.72% 11 bps Home Equity $52 3.84% $49 3.70% (14) bps Consumer and Other $13 10.00% $13 10.57% 57 bps Total Loans HFI and Allowance for Loan Losses $869 1.42% $869 1.40% (2) bps Unfunded Commitment Reserve $56 $58 Total Allowance for Credit Losses $925 1.52% $927 1.50% (2) bps Asset Quality | Allowance for Credit Loss Detail
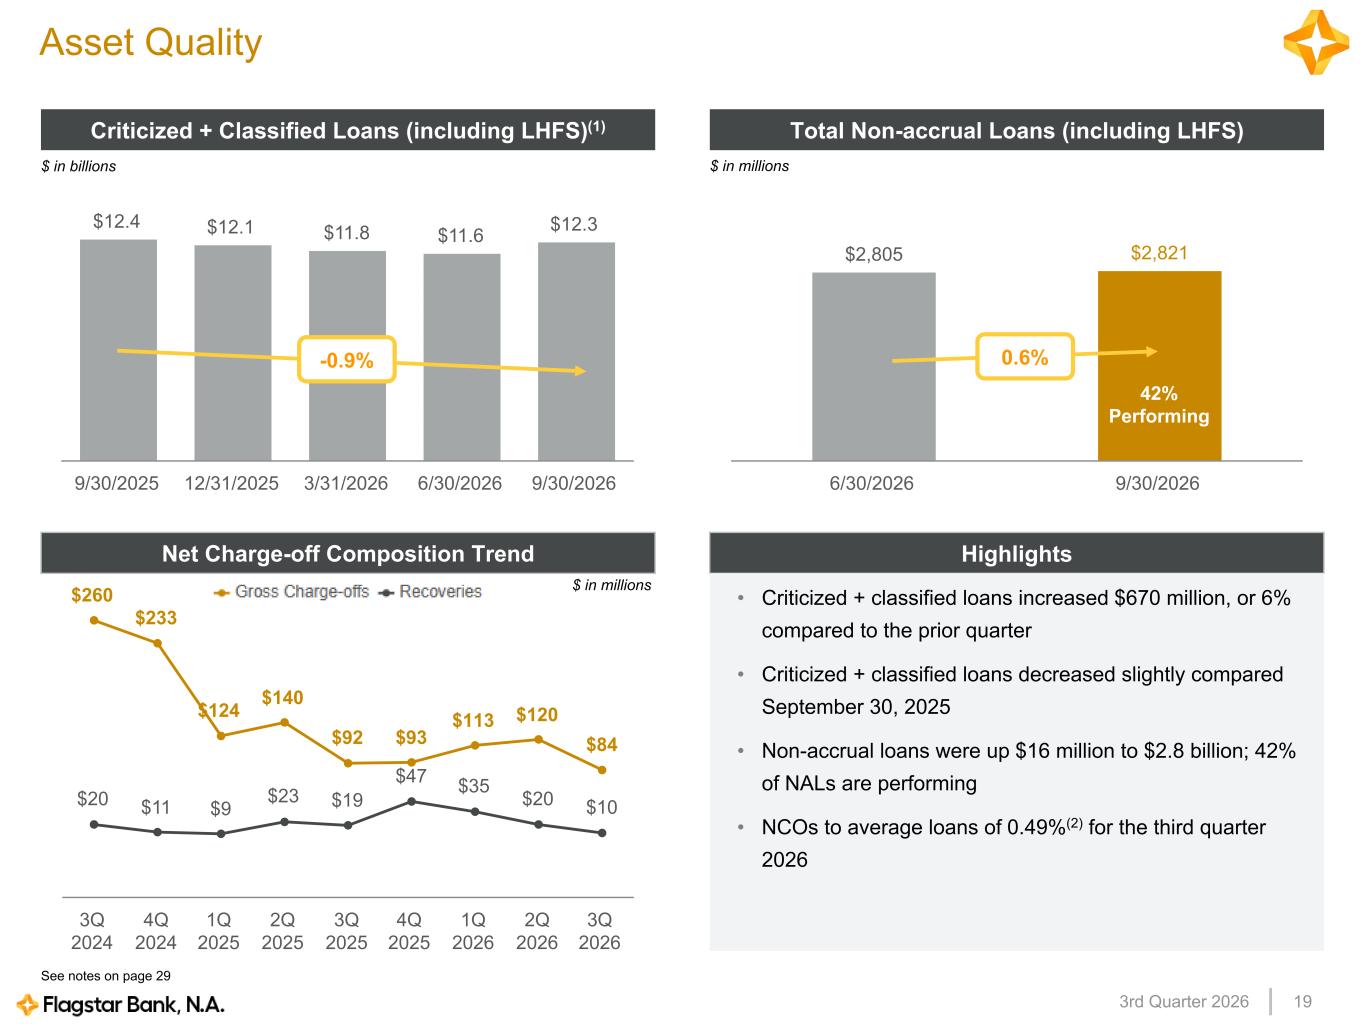
60 121 158 242 242 242 254 150 0 218 218 218 164 167 168 253 206 59 69 72 73 236 243 248 193rd Quarter 2026 Asset Quality Criticized + Classified Loans (including LHFS)(1) Total Non-accrual Loans (including LHFS) Highlights • Criticized + classified loans increased $670 million, or 6% compared to the prior quarter • Criticized + classified loans decreased slightly compared September 30, 2025 • Non-accrual loans were up $16 million to $2.8 billion; 42% of NALs are performing • NCOs to average loans of 0.49%(2) for the third quarter 2026 Net Charge-off Composition Trend $ in millions$ in billions See notes on page 29 $12.4 $12.1 $11.8 $11.6 $12.3 9/30/2025 12/31/2025 3/31/2026 6/30/2026 9/30/2026 -0.9% $2,805 $2,821 6/30/2026 9/30/2026 0.6% $260 $233 $124 $140 $92 $93 $113 $120 $84 $20 $11 $9 $23 $19 $47 $35 $20 $10 3Q 2024 4Q 2024 1Q 2025 2Q 2025 3Q 2025 4Q 2025 1Q 2026 2Q 2026 3Q 2026 $ in millions 42% Performing
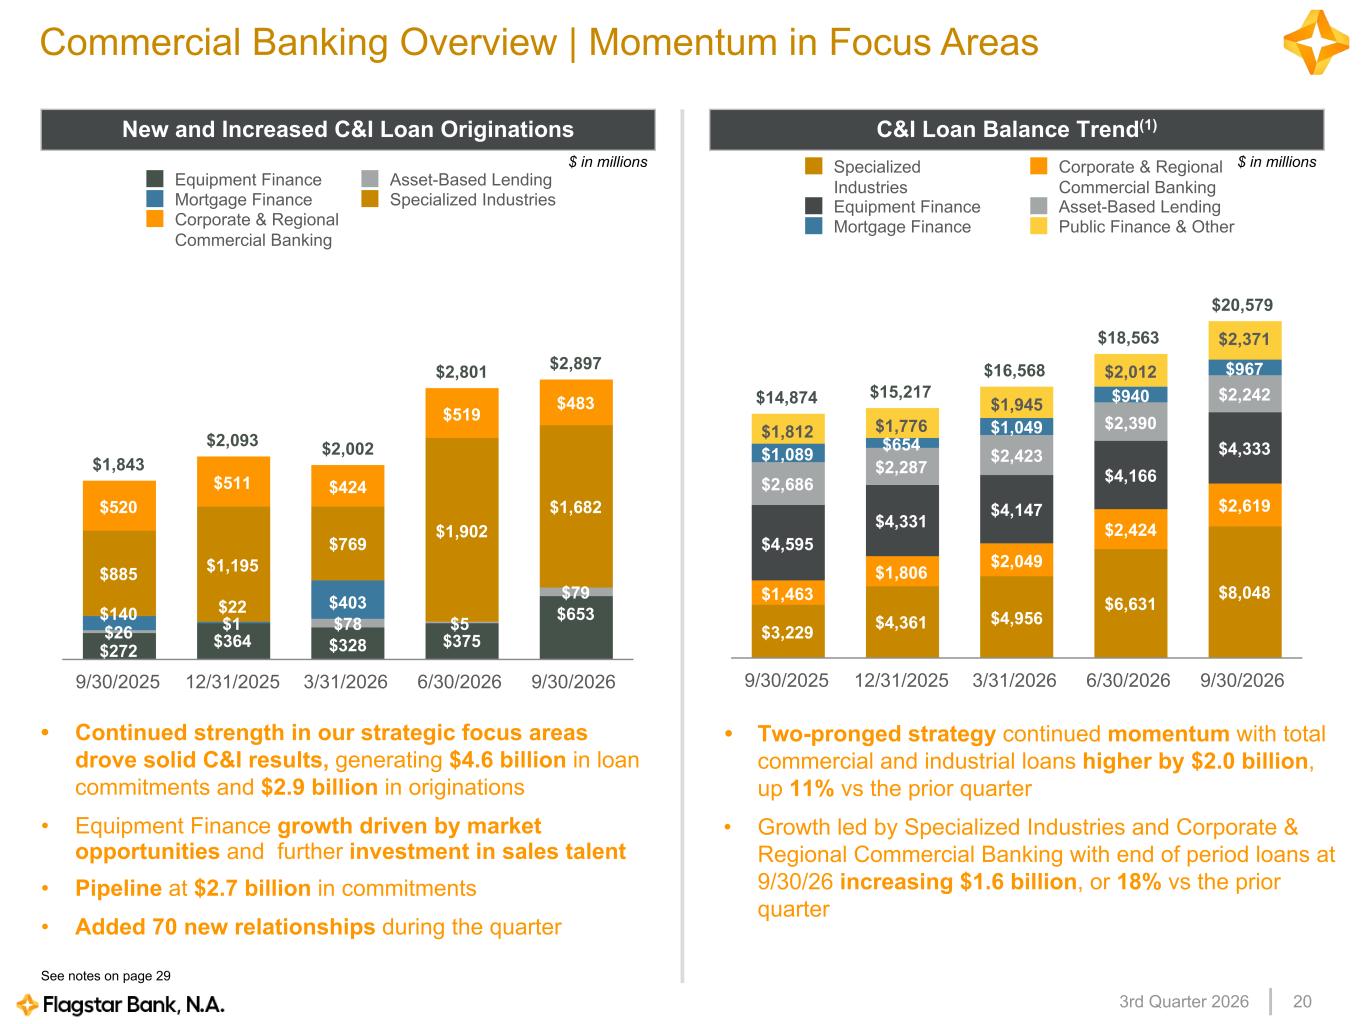
60 121 158 242 242 242 254 150 0 218 218 218 164 167 168 253 206 59 69 72 73 236 243 248 203rd Quarter 2026 Commercial Banking Overview | Momentum in Focus Areas C&I Loan Balance Trend(1) $ in millions New and Increased C&I Loan Originations $ in millions • Continued strength in our strategic focus areas drove solid C&I results, generating $4.6 billion in loan commitments and $2.9 billion in originations • Equipment Finance growth driven by market opportunities and further investment in sales talent • Pipeline at $2.7 billion in commitments • Added 70 new relationships during the quarter $1,843 $2,093 $2,002 $2,801 $2,897 $272 $364 $328 $375 $653 $26 $1 $78 $5 $79 $140 $22 $403 $885 $1,195 $769 $1,902 $1,682$520 $511 $424 $519 $483 Equipment Finance Asset-Based Lending Mortgage Finance Specialized Industries Corporate & Regional Commercial Banking 9/30/2025 12/31/2025 3/31/2026 6/30/2026 9/30/2026 $14,874 $15,217 $16,568 $18,563 $20,579 $3,229 $4,361 $4,956 $6,631 $8,048$1,463 $1,806 $2,049 $2,424 $2,619 $4,595 $4,331 $4,147 $4,166 $4,333 $2,686 $2,287 $2,423 $2,390 $2,242 $1,089 $654 $1,049 $940 $967 $1,812 $1,776 $1,945 $2,012 $2,371 Specialized Industries Corporate & Regional Commercial Banking Equipment Finance Asset-Based Lending Mortgage Finance Public Finance & Other 9/30/2025 12/31/2025 3/31/2026 6/30/2026 9/30/2026 • Two-pronged strategy continued momentum with total commercial and industrial loans higher by $2.0 billion, up 11% vs the prior quarter • Growth led by Specialized Industries and Corporate & Regional Commercial Banking with end of period loans at 9/30/26 increasing $1.6 billion, or 18% vs the prior quarter See notes on page 29
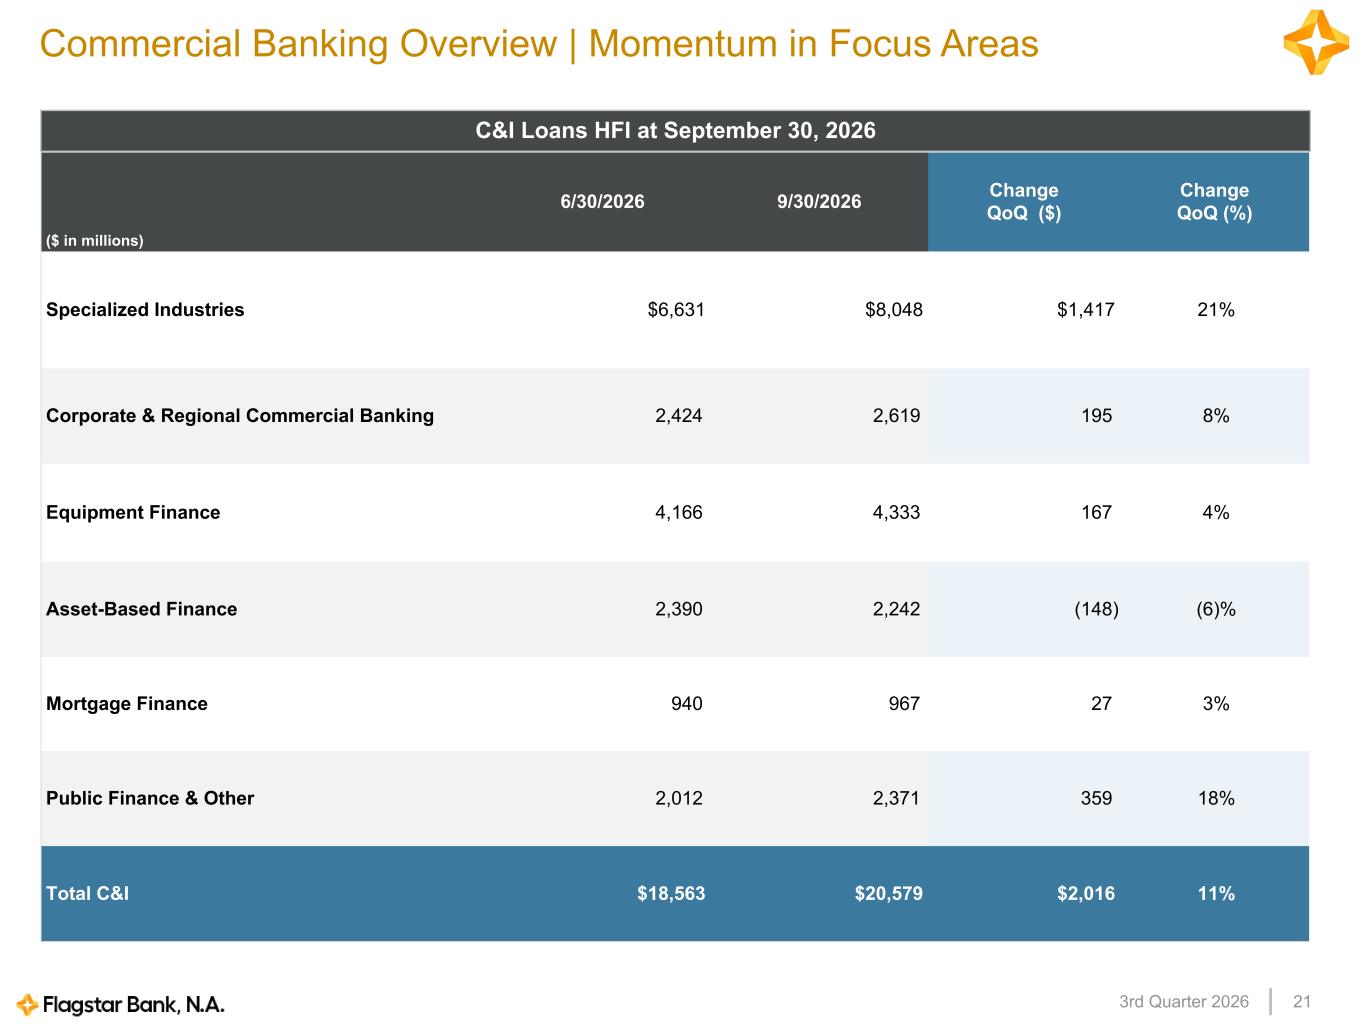
60 121 158 242 242 242 254 150 0 218 218 218 164 167 168 253 206 59 69 72 73 236 243 248 213rd Quarter 2026 Commercial Banking Overview | Momentum in Focus Areas C&I Loans HFI at September 30, 2026 ($ in millions) 6/30/2026 9/30/2026 Change QoQ ($) Change QoQ (%) Specialized Industries $6,631 $8,048 $1,417 21% Corporate & Regional Commercial Banking 2,424 2,619 195 8% Equipment Finance 4,166 4,333 167 4% Asset-Based Finance 2,390 2,242 (148) (6)% Mortgage Finance 940 967 27 3% Public Finance & Other 2,012 2,371 359 18% Total C&I $18,563 $20,579 $2,016 11%
Appendix
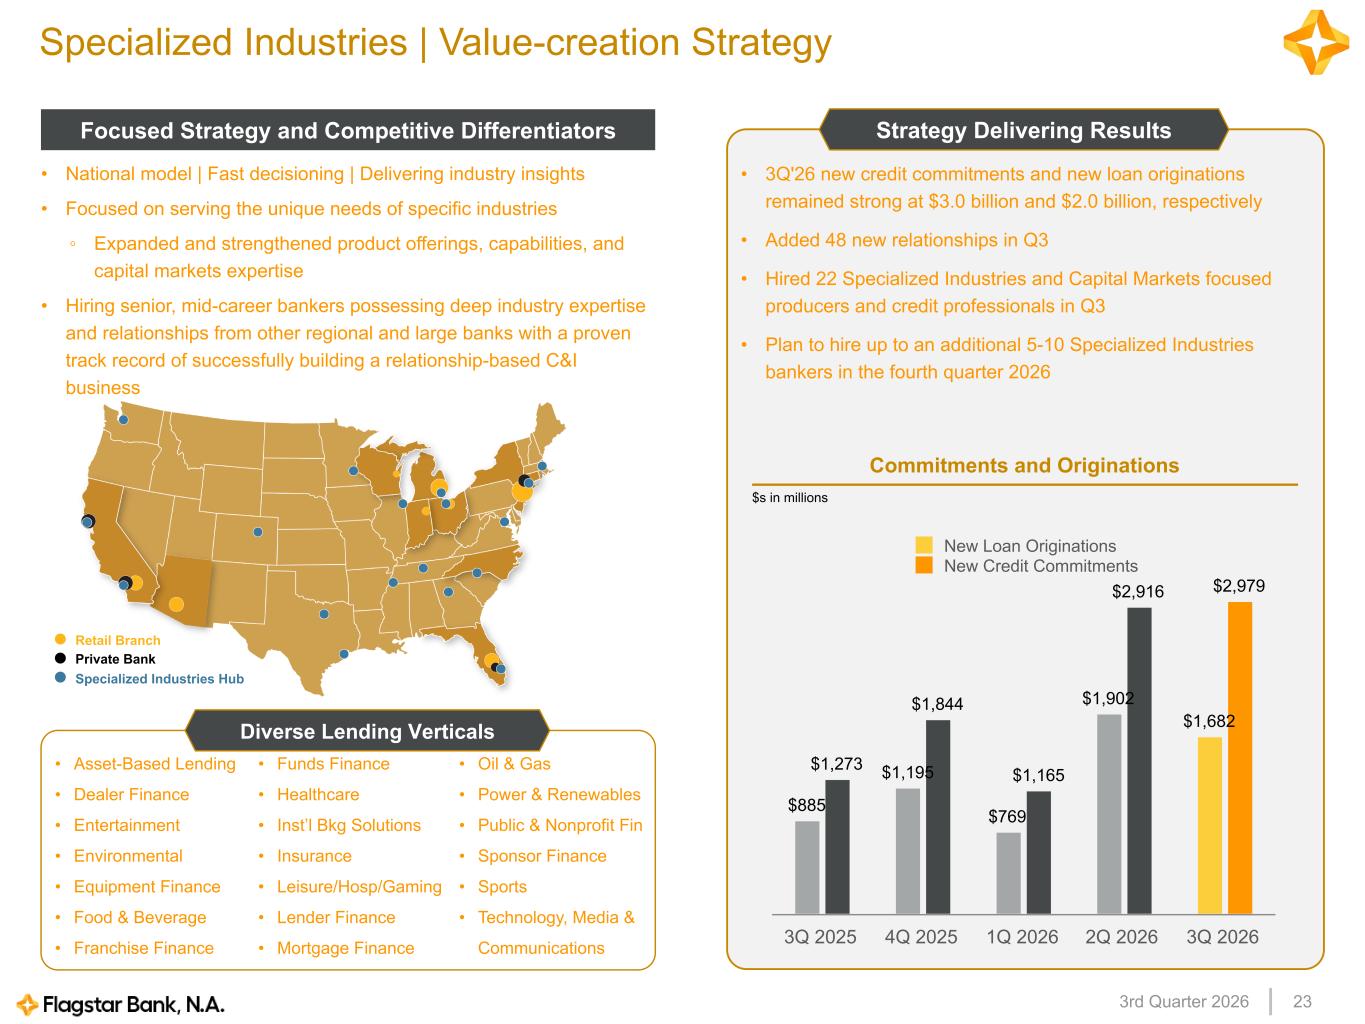
60 121 158 242 242 242 254 150 0 218 218 218 164 167 168 253 206 59 69 72 73 236 243 248 233rd Quarter 2026 Specialized Industries | Value-creation Strategy Focused Strategy and Competitive Differentiators Strategy Delivering Results • Oil & Gas • Power & Renewables • Public & Nonprofit Fin • Sponsor Finance • Sports • Technology, Media & Communications • Asset-Based Lending • Dealer Finance • Entertainment • Environmental • Equipment Finance • Food & Beverage • Franchise Finance • Funds Finance • Healthcare • Inst’l Bkg Solutions • Insurance • Leisure/Hosp/Gaming • Lender Finance • Mortgage Finance Diverse Lending Verticals • National model | Fast decisioning | Delivering industry insights • Focused on serving the unique needs of specific industries ◦ Expanded and strengthened product offerings, capabilities, and capital markets expertise • Hiring senior, mid-career bankers possessing deep industry expertise and relationships from other regional and large banks with a proven track record of successfully building a relationship-based C&I business Commitments and Originations Retail Branch Private Bank • 3Q'26 new credit commitments and new loan originations remained strong at $3.0 billion and $2.0 billion, respectively • Added 48 new relationships in Q3 • Hired 22 Specialized Industries and Capital Markets focused producers and credit professionals in Q3 • Plan to hire up to an additional 5-10 Specialized Industries bankers in the fourth quarter 2026 Specialized Industries Hub $s in millions $885 $1,195 $769 $1,902 $1,682 $1,273 $1,844 $1,165 $2,916 $2,979 New Loan Originations New Credit Commitments 3Q 2025 4Q 2025 1Q 2026 2Q 2026 3Q 2026
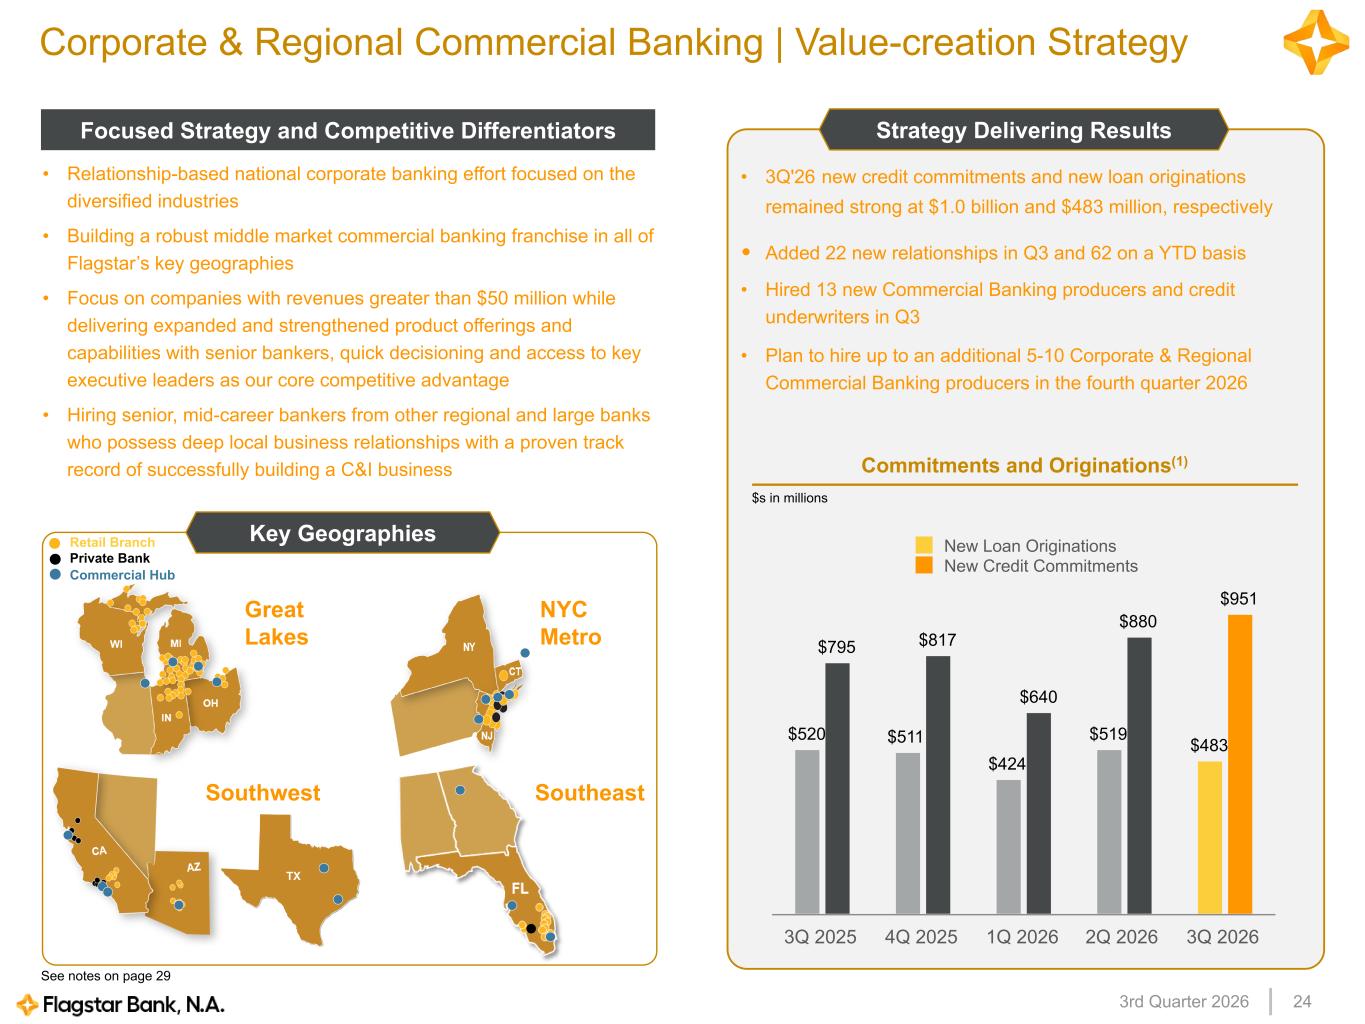
60 121 158 242 242 242 254 150 0 218 218 218 164 167 168 253 206 59 69 72 73 236 243 248 243rd Quarter 2026 Corporate & Regional Commercial Banking | Value-creation Strategy Focused Strategy and Competitive Differentiators Strategy Delivering Results • Relationship-based national corporate banking effort focused on the diversified industries • Building a robust middle market commercial banking franchise in all of Flagstar’s key geographies • Focus on companies with revenues greater than $50 million while delivering expanded and strengthened product offerings and capabilities with senior bankers, quick decisioning and access to key executive leaders as our core competitive advantage • Hiring senior, mid-career bankers from other regional and large banks who possess deep local business relationships with a proven track record of successfully building a C&I business • 3Q'26 new credit commitments and new loan originations remained strong at $1.0 billion and $483 million, respectively • Added 22 new relationships in Q3 and 62 on a YTD basis • Hired 13 new Commercial Banking producers and credit underwriters in Q3 • Plan to hire up to an additional 5-10 Corporate & Regional Commercial Banking producers in the fourth quarter 2026 Great Lakes NYC Metro Southwest Southeast Key Geographies Private Bank Commitments and Originations(1) Commercial Hub $s in millions $520 $511 $424 $519 $483 $795 $817 $640 $880 $951 New Loan Originations New Credit Commitments 3Q 2025 4Q 2025 1Q 2026 2Q 2026 3Q 2026 Retail Branch TX See notes on page 29
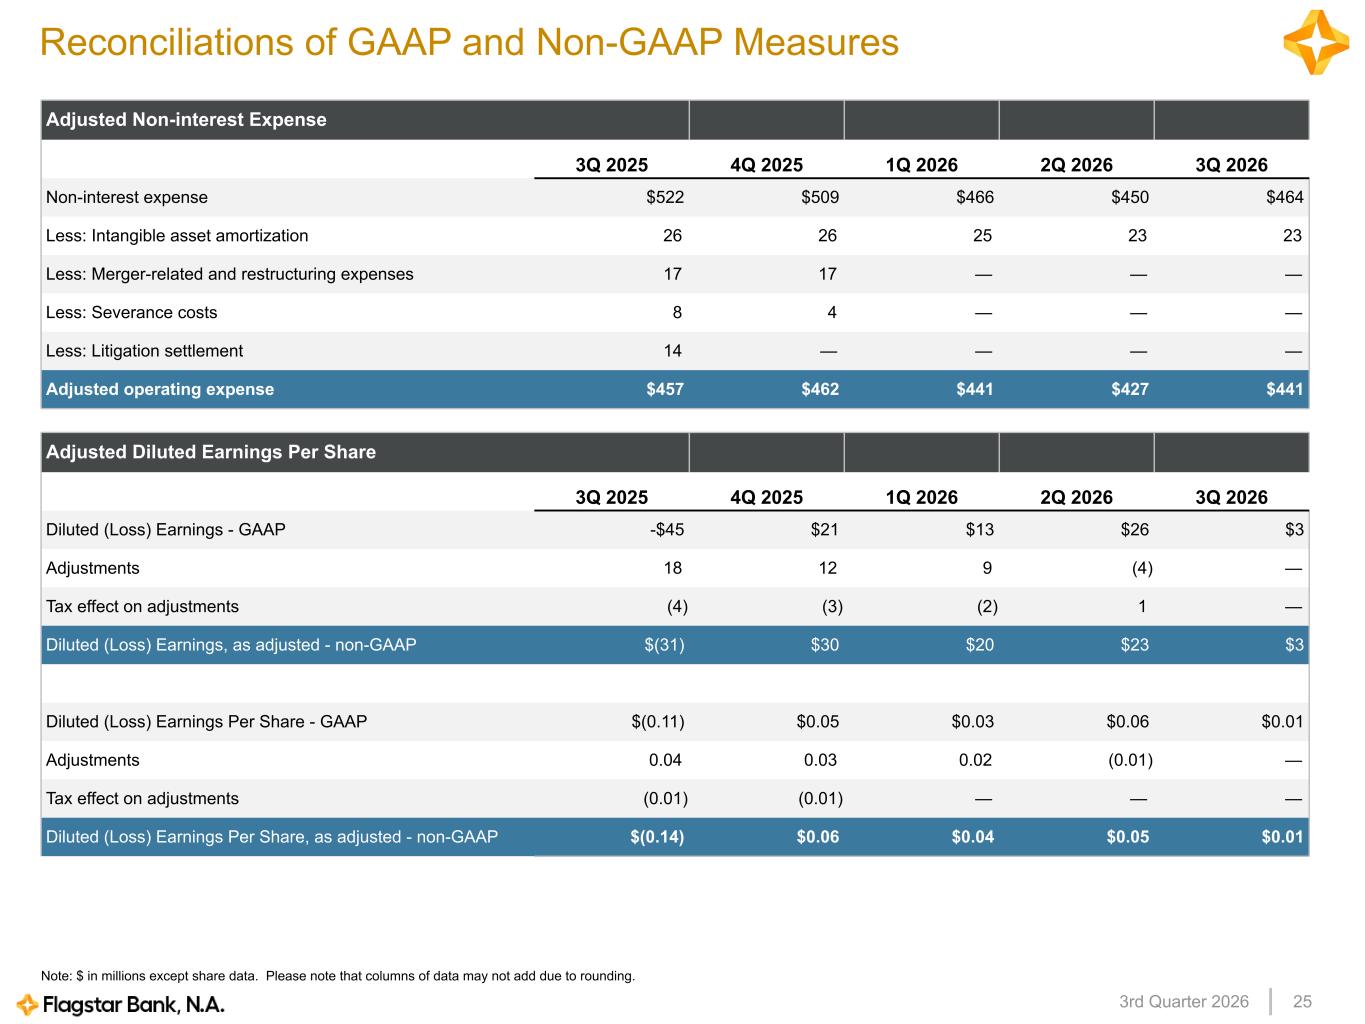
60 121 158 242 242 242 254 150 0 218 218 218 164 167 168 253 206 59 69 72 73 236 243 248 253rd Quarter 2026 Note: $ in millions except share data. Please note that columns of data may not add due to rounding. Reconciliations of GAAP and Non-GAAP Measures Adjusted Non-interest Expense 3Q 2025 4Q 2025 1Q 2026 2Q 2026 3Q 2026 Non-interest expense $522 $509 $466 $450 $464 Less: Intangible asset amortization 26 26 25 23 23 Less: Merger-related and restructuring expenses 17 17 — — — Less: Severance costs 8 4 — — — Less: Litigation settlement 14 — — — — Adjusted operating expense $457 $462 $441 $427 $441 Adjusted Diluted Earnings Per Share 3Q 2025 4Q 2025 1Q 2026 2Q 2026 3Q 2026 Diluted (Loss) Earnings - GAAP -$45 $21 $13 $26 $3 Adjustments 18 12 9 (4) — Tax effect on adjustments (4) (3) (2) 1 — Diluted (Loss) Earnings, as adjusted - non-GAAP $(31) $30 $20 $23 $3 Diluted (Loss) Earnings Per Share - GAAP $(0.11) $0.05 $0.03 $0.06 $0.01 Adjustments 0.04 0.03 0.02 (0.01) — Tax effect on adjustments (0.01) (0.01) — — — Diluted (Loss) Earnings Per Share, as adjusted - non-GAAP $(0.14) $0.06 $0.04 $0.05 $0.01
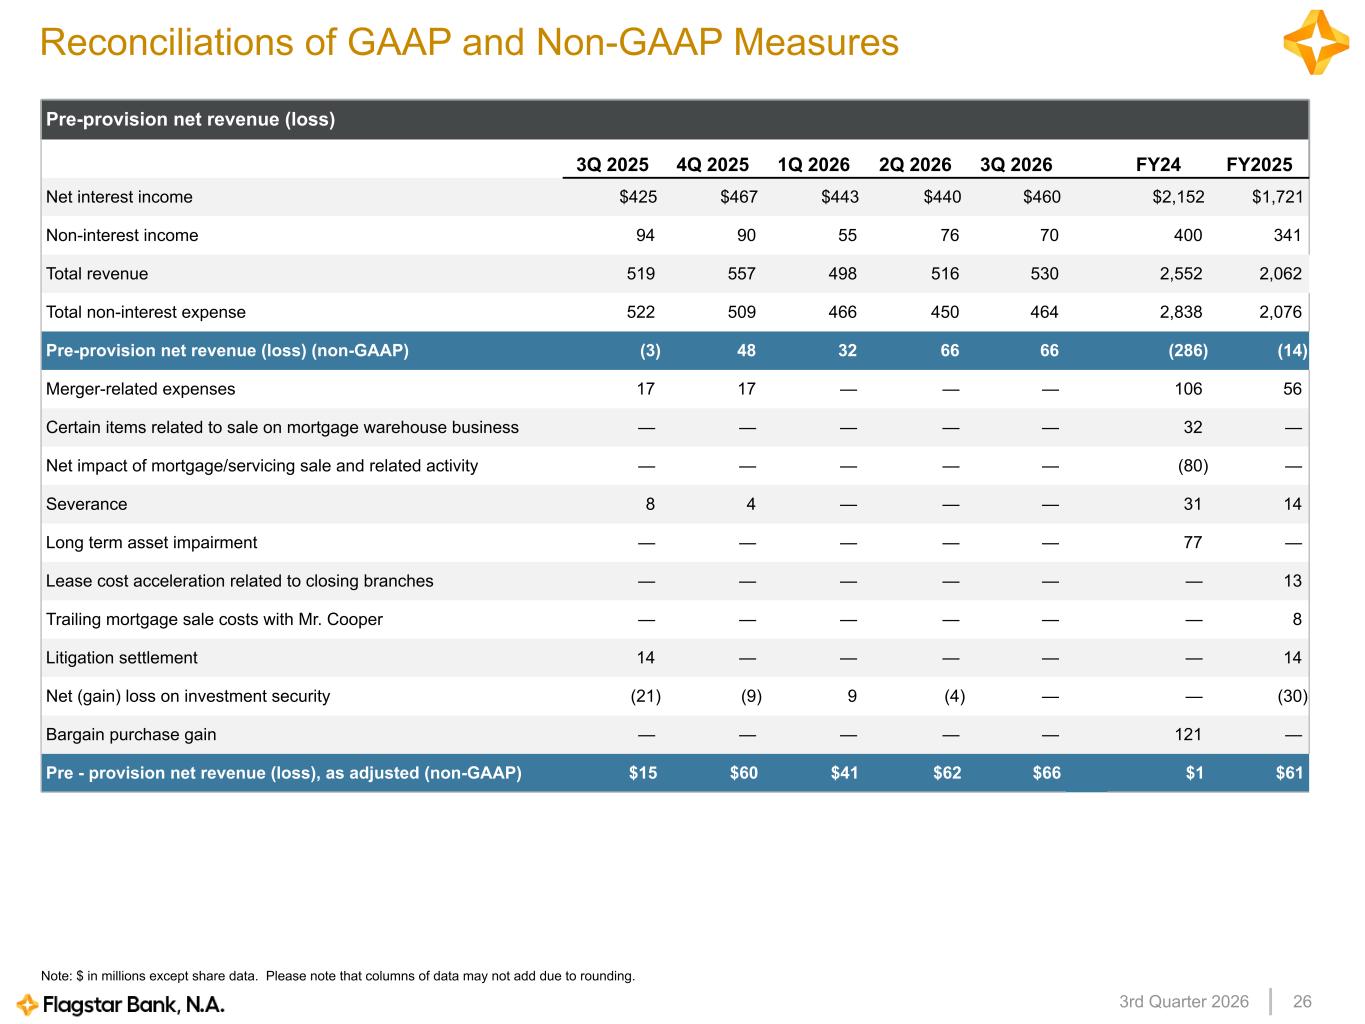
60 121 158 242 242 242 254 150 0 218 218 218 164 167 168 253 206 59 69 72 73 236 243 248 263rd Quarter 2026 Note: $ in millions except share data. Please note that columns of data may not add due to rounding. Reconciliations of GAAP and Non-GAAP Measures Pre-provision net revenue (loss) 3Q 2025 4Q 2025 1Q 2026 2Q 2026 3Q 2026 FY24 FY2025 Net interest income $425 $467 $443 $440 $460 $2,152 $1,721 Non-interest income 94 90 55 76 70 400 341 Total revenue 519 557 498 516 530 2,552 2,062 Total non-interest expense 522 509 466 450 464 2,838 2,076 Pre-provision net revenue (loss) (non-GAAP) (3) 48 32 66 66 (286) (14) Merger-related expenses 17 17 — — — 106 56 Certain items related to sale on mortgage warehouse business — — — — — 32 — Net impact of mortgage/servicing sale and related activity — — — — — (80) — Severance 8 4 — — — 31 14 Long term asset impairment — — — — — 77 — Lease cost acceleration related to closing branches — — — — — — 13 Trailing mortgage sale costs with Mr. Cooper — — — — — — 8 Litigation settlement 14 — — — — — 14 Net (gain) loss on investment security (21) (9) 9 (4) — — (30) Bargain purchase gain — — — — — 121 — Pre - provision net revenue (loss), as adjusted (non-GAAP) $15 $60 $41 $62 $66 $1 $61
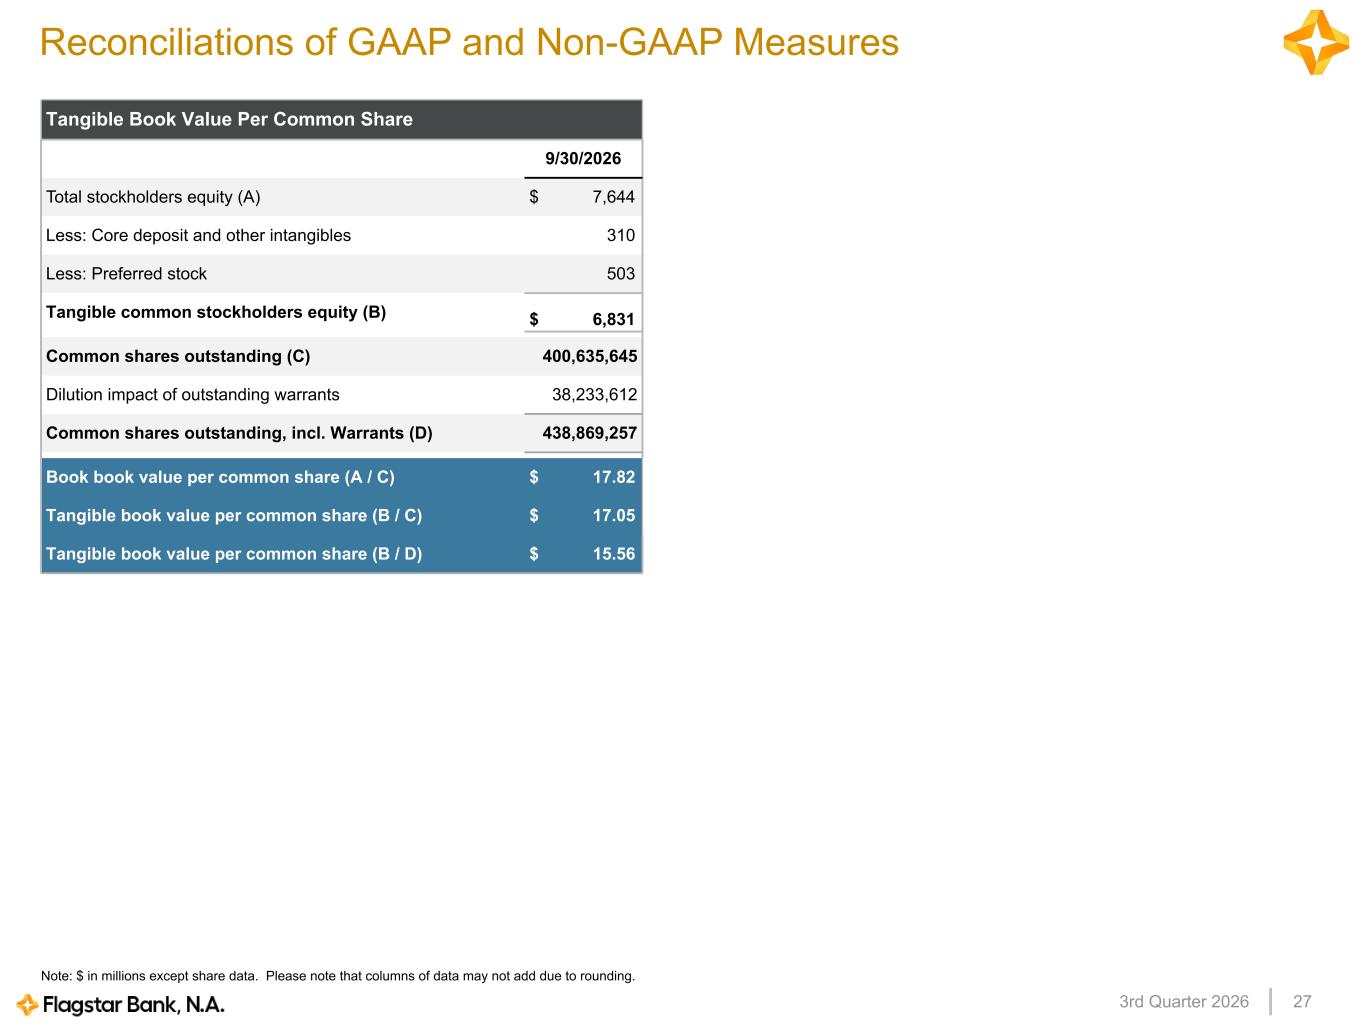
60 121 158 242 242 242 254 150 0 218 218 218 164 167 168 253 206 59 69 72 73 236 243 248 273rd Quarter 2026 Note: $ in millions except share data. Please note that columns of data may not add due to rounding. Reconciliations of GAAP and Non-GAAP Measures Tangible Book Value Per Common Share 9/30/2026 Total stockholders equity (A) $ 7,644 Less: Core deposit and other intangibles 310 Less: Preferred stock 503 Tangible common stockholders equity (B) $ 6,831 Common shares outstanding (C) 400,635,645 Dilution impact of outstanding warrants 38,233,612 Common shares outstanding, incl. Warrants (D) 438,869,257 Book book value per common share (A / C) $ 17.82 Tangible book value per common share (B / C) $ 17.05 Tangible book value per common share (B / D) $ 15.56
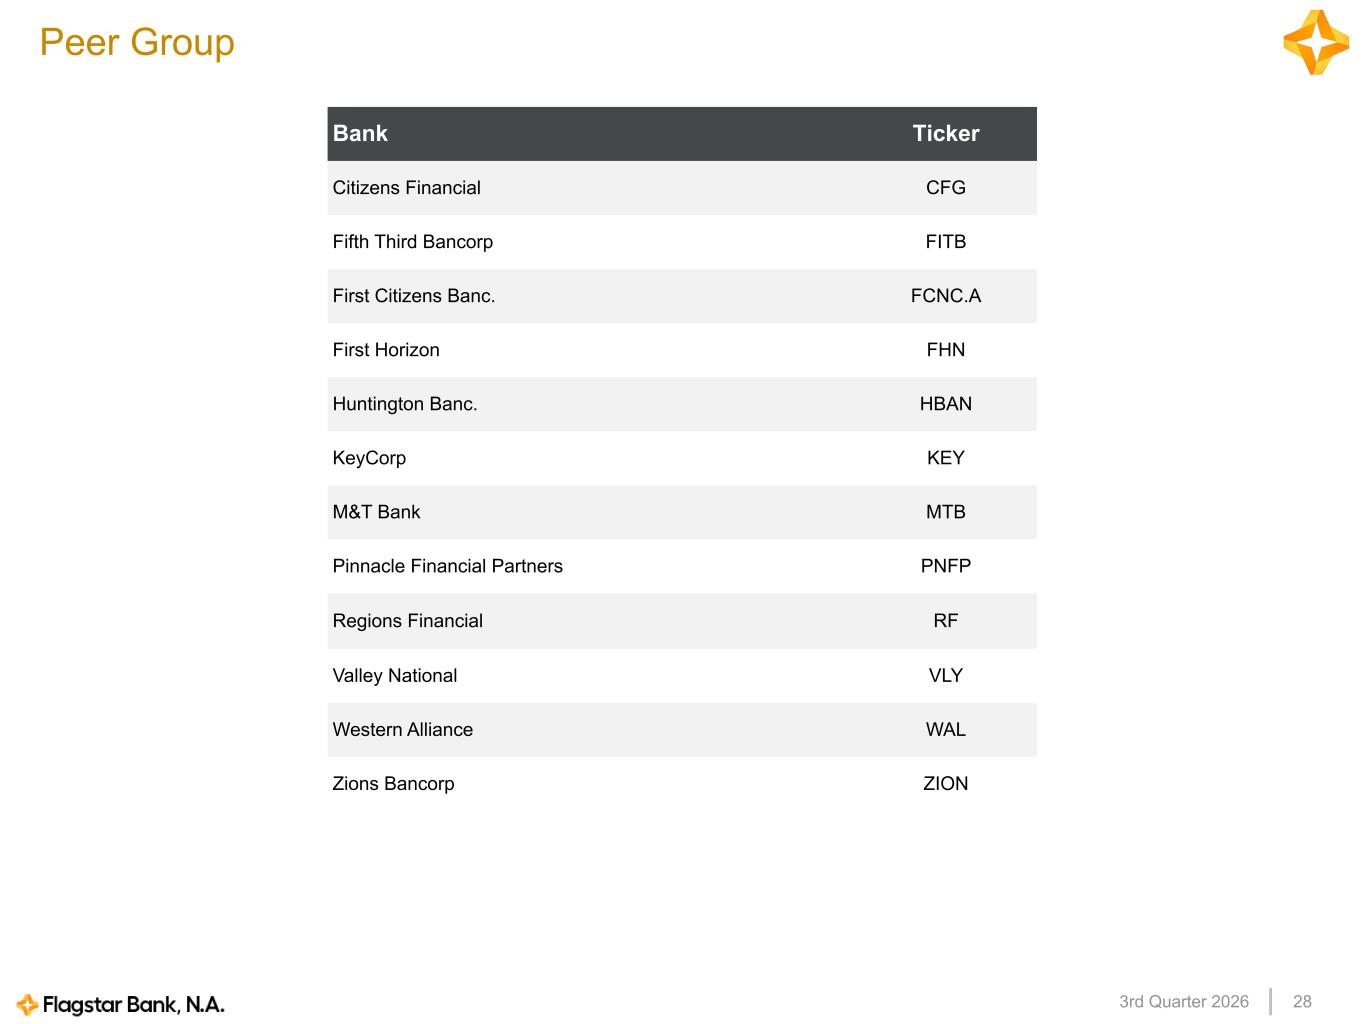
60 121 158 242 242 242 254 150 0 218 218 218 164 167 168 253 206 59 69 72 73 236 243 248 283rd Quarter 2026 Bank Ticker Citizens Financial CFG Fifth Third Bancorp FITB First Citizens Banc. FCNC.A First Horizon FHN Huntington Banc. HBAN KeyCorp KEY M&T Bank MTB Pinnacle Financial Partners PNFP Regions Financial RF Valley National VLY Western Alliance WAL Zions Bancorp ZION Peer Group
60 121 158 242 242 242 254 150 0 218 218 218 164 167 168 253 206 59 69 72 73 236 243 248 293rd Quarter 2026 Notes Slide 5 1. Includes warrants and options – warrant and options dilution calculated using the treasury stock method with projected share price based on a 1.0x tangible book value multiple 2. Excludes impact from intangible asset amortization and merger-related expenses 3. Includes warrants – warrant options dilution calculated using the treasury stock method with projected share price based on a 1.0x tangible book value multiple Slide 9 1. Includes warrants and options – warrant and options dilution calculated using the treasury stock method with projected share price based on a 1.0x tangible book value multiple Slide 10 1. Reflects net interest margin adjusted for $20.5 million hedge benefit in the fourth quarter of 2025 Slide 11 1. Excludes impact from intangible asset amortization, merger-related expenses, and other adjustments 2. Includes software and professional expenses Slide 13 1. In the current quarter, a balance transfer of approximately $275 million was reclassified from the Private Bank business line to Commercial. As of 6/30/2026, ending balances have been adjusted to reflect this transfer — Private Bank reduced by $275 million and Commercial increased by $275 million. 2. Excludes collateralized deposits and excludes internal deposits Slide 14 1. Total CRE excludes $2.6 billion of owner-occupied CRE 2. Calculated as: Total CRE balances (excluding $2.6 billion of owner occupied CRE) / (Tier 1 Capital + Allowance for Loans & Lease Losses) Slide 15 1. Reflects Multi-Family UPB excluding Co-op loans 2. Northeast Multi-Family peers include banks with disclosed Multi-Family ALLL ratios: BPOP and EWBC as of 6/30/26, DCOM as of 3/31/26, and FFIC and BBT as of 9/30/25 Slide 16 1. Current LTV is calculated by dividing the most recent appraised value by the current loan amount 2. Amortizing DSCR includes hypothetical amortization for deals in interest-only periods 3. Reflects rent regulated percent based on units at origination Slide 17 1. Reflects percent of appraisals received based on book balance since 1/1/2024 2. Reflects financials reviewed since 1/1/2024 as a percent of book balance 3. Reflects cumulative net charge-offs since 1/1/2024 for loans remaining in the portfolio 4. Reflects rent regulated percent based on units at origination 5. Reflects ACL coverage ratio at 9/30/2026 and all NCOs taken on loans in the portfolio at 9/30/2026 6. Sum of book balance plus net charge-offs 7. Defined as >=50% units are rent regulated Slide 19 1. Shown on UPB basis and excludes one-to-four family residential loans and other loans, which primarily includes HELOCs 2. Presented on an annualized basis Slide 20 1. Prior quarters were adjusted for a reclass from Asset-Based Finance to Equipment Finance category: 9/30/25 ~$956 million, and 12/31/25 $842 million Slide 24 1. Excludes ABL transactions, which are included as Specialized Industries When necessary, certain reclassifications have been made to prior-period amounts to conform to the current-period presentation.