United States
Securities and Exchange Commission
Washington, D.C. 20549
FORM 6-K
Report of Foreign Private Issuer
Pursuant to Rule 13a-16 or 15d-16
of the
Securities Exchange Act of 1934
For the month of
October 2026
Vale S.A.
Praia de Botafogo nº 186, 18º andar,
Botafogo
22250-145 Rio de Janeiro, RJ, Brazil
(Address of principal executive office)
(Indicate by check mark whether the registrant files or will file annual reports under cover of Form 20-F or Form 40-F.)
(Check One) Form 20-F x Form 40-F ¨
Rio de Janeiro, October 29th, 2026 3Q26 Quarterly Results “Our third-quarter results reflect disciplined execution of our strategy and a continued focus on operational excellence. In a dynamic market environment, our portfolio flexibility, affreightment strategy, and hedging program helped protect margins and support solid cash flow generation, further strengthening our balance sheet. In iron ore, we are building a more flexible and competitive operating platform. The start-up of the Serra Sul +20 project, together with the commissioning of the Compact Crushing project, will further enhance S11D's performance and reinforce its position as a world-class asset. Combined with solid performance across our asset base, these initiatives positions us well to finish the year strongly. Vale Base Metals continues to gain momentum, with Salobo delivering record third-quarter production and both copper and nickel on track to reach the upper half of the production guidances. With the approval of the Salobo CPF project, we take another important step in our copper growth journey, leveraging our existing assets and infrastructure to grow with capital efficiency. Together, these achievements strengthen Vale's resilience and position us to create sustainable value over the long term.", commented Gustavo Pimenta, CEO Selected financial indicators US$ million 3Q26 3Q25 Δ y/y 2Q26 Δ q/q 9M26 Net operating revenues Adjusted EBITDA Proforma EBITDA1 Free cash flow Recurring free cash flow Attributable net income Attributable proforma net income Net debt2 Expanded net debt 10,599 3,327 3,508 2,230 1,373 10,420 4,369 4,399 2,453 2% 10,498 -24% -20% 3,676 4,066 -9% 1,562 1,255 1,255 13,097 2,685 2,744 12,452 -12% -53% -54% 1,505 1,505 1,375 1,566 5% 13,173 16,413 Capital expenditures 1,250 16,640 1,250 1 Excluding expenses related to Brumadinho and non-recurring items. 2 Including leases (IFRS 16). Results Highlights-1% 0% 16,677 1,128 9M25 1% 30,355 27,343 -9% 10,833 10,870 -14% 11,469 48% -9% -9% -20% -1% -2% 11% 4,548 3,691 4,523 4,714 13,097 16,413 3,467 11,035 3,965 3,074 6,196 6,332 12,452 16,640 3,477 Δ y/y 11% 0% 4% 15% 20% -27% -26% 5% -1% 0% • Robust sales performance. Iron ore sales increased by 0.3% (0.3 Mt) y/y, despite a 6% (6 Mt) decline in production over the same period. Copper sales declined 4%, as expected, reflecting the planned Sossego SAG mill rebuild. Nickel sales increased 16.1% (6.9 kt) y/ y, supported by stronger production. All 2026 production guidances reaffirmed, with copper and nickel pointing to the upper half of the ranges. • Iron ore price realization reflecting external factors. The average realized iron ore fines price was US$ 85.1/t, down 10% q/q and y/y, due to lower reference prices and temporary adjustments related to CFR sales. • Higher realized copper price realization. Realized copper prices increased to US$ 15.314/t (+9% q/q, +56% y/y), above the LME price variation. Realized nickel prices reached US$ 16,898/t (-6% q/q, +9% y/y), with higher premiums partly offsetting lower reference prices. • Iron ore costs impacted by BRL and oil prices. C1 cash cost was US$ 23.1/t (+12% y/y), mainly reflecting the BRL appreciation and diesel costs, while all-in costs reached US$ 60.4/t (+21% y/y), further pressured by higher freight costs. • Copper costs continue to improve. Copper all-in costs at US$ -175/t (US$ -1.2k/t y/y), supported by strong by-product revenues. Nickel all-in costs increased in line with expectations, up 18% y/y to US$ 14,552/t, reflecting higher planned maintenance. • Proforma EBITDA of US$ 3.5 billion, down 20% y/y (-14% q/q), mainly driven by the decrease in iron ore fines realized prices and external cost pressures, including the BRL appreciation and higher bunker prices. • Capital expenditures of US$ 1.3 billion, flat y/y, with full-year investments expected to be at the lower end of the US$ 5.4-5.7 billion guidance range. • Recurring Free Cash Flow of US$ 1.4 billion, US$ 0.2 billion lower y/y, as successful hedging and working capital management partly offset lower Proforma EBITDA. Total Free Cash Flow reached US$ 2.2 billion. • Expanded net debt of US$ 16.4 billion, US$ 0.2 billion lower q/q, driven by cash flow generation.-1- Iron Ore Solutions Business Highlights • Iron ore production totaled 88.4 Mt (-6% y/y), mainly reflecting lower run-of-mine availability at Serra Norte. A new quarterly record at Serra Sul and incremental volumes from the Capanema and VGR1 projects partly offset the decline, demonstrating the successful ramp-up of key growth projects. Pellet production totaled 8.6 Mt (+7% y/y). • Based on year-to-date performance and expected operational improvements, Vale remains confident in delivering the lower end of its iron ore production guidance (335-345 Mt) and the midpoint of its pellet production guidance (30-34 Mt) for 2026. • The Compact Crushing project started operation in Q3. Together with the ramp-up of the Serra Sul +20 project, it is expected to enhance operational flexibility and support performance from 2027. • The operations at Fábrica mine resumed in September, following compliance with applicable safety, environmental, and licensing requirements, as well as actions established under the Commitment Agreement. Vale Base Metals • Copper production totaled 85.5 kt (-6% y/y), reflecting the planned SAG mill rebuild at Sossego, partly offset by strong performance at Salobo. Nickel output totaled 49.7 kt (6% y/y), driven mainly by the strong performance at Onça Puma's second furnace and the highest quarterly output at the Sudbury Refinery since 4Q13. • Vale is on track to achieve the upper half of its 2026 production guidance ranges for both copper (360-380 kt) and nickel (185-200 kt). Year-to-date, copper and nickel production increased by 4% and 8% y/y, respectively. • The Salobo Coarse Particle Flotation (CPF) project advanced to execution in August. Expected to add up to ~30 ktpy, the project supports VBM's ambition to reach 420-500 ktpy of copper production by 2030. Physical progress reached 17%, with start-up expected in 1H28, about one year ahead of schedule. • The Thompson Mine Complex transaction was completed in October, concluding the strategic review process and establishing Exiro Nickel as the new owner and operator, while VBM retained an 18.9% interest and a multi-year nickel concentrate offtake agreement. Other developments • As part of Vale's ongoing risk management strategy, the Brent oil hedge program, combined with forward freight agreements (FFAs) execution, generated an economic gain of US$ 97 million in the quarter, equivalent to approximately US$ 1.4/dmt of iron ore sold. Recognized in the financial results, this benefit offsets part of the higher oil prices that pressured all-in costs in the quarter. Including the Brent oil hedge effect, iron ore all-in costs would be equivalent to US$ 59/dmt in the quarter. • The B7A dam in Nova Lima (MG) had its emergency level status lifted, following Brazilian National Mining Agency approval. The decision comes after the completion of the works to decharacterize the structure. Since 2020, 29 dams have been removed from emergency level status, representing an 83% reduction. Reparation Brumadinho • The execution of the Brumadinho Integral Reparation Agreement continues to progress, with approximately 84% of the agreed-upon commitments completed by 3Q26 and in accordance with the deadlines outlined in the settlement. The "To Pay" obligations of the Reparation Agreement were completed in October, 2026. Mariana • The Samarco reparation program continues to advance, with R$ 83.8 billion disbursed as of September 30, 2026. As of October 20th, 2026, more than 649 thousand individuals were compensated, including more than 322 thousand under the Definitive Indemnification Program (PID). In August, 19 additional municipalities joined the agreement, bringing the total number of signatories to 45 of the 49 eligible municipalities, including Mariana.-2- Operational Results Production Summary 000’ metric tons 3Q26 3Q25 ∆ y/y 2Q26 ∆ q/q 9M26 9M25 Δ y/y 2026 guidance Iron ore¹ Pellets Copper Nickel 88,354 8,554 94,403 -6% 84,255 5% 242,284 245,671 7,997 85.5 49.7 1 90.8 46.8 7% -6% 6% 7,303 98.4 42.0 17% 24,026 -13% 18% 286.2 141.0 23,031 274.3 131.0 Including third-party purchases, run-of-mine and feed for pelletizing plants. 2 Iron ore agglomerates guidance, including iron ore pellets and briquettes. Sales Summary-1% 4% 4% 8% 335-345 Mt 30-34 Mt² 360-380 kt 185-200 kt 000’ metric tons Iron ore Fines¹ 3Q26 86,285 75,513 3Q25 85,997 75,020 ∆ y/y 0% 1% 2Q26 79,747 ∆ q/q 9M26 Pellets 8,720 ROM Copper Nickel 1 Including third-party purchases. Iron ore and pellets operations 8,769 2,052 86.3 49.8 2,208 90.0 42.9 • Northern System: production decreased by 6.9 Mt y/y, totaling 42.8 Mt in the quarter, driven by Serra Norte's 31% (-7.7 Mt) lower y/y output. • Serra Norte: the decline reflects lower run-of-mine availability, primarily due to operational constraints in mining areas near cave-related exclusion zones and at the bottom of the pits, as well as a one-off impact from lower fleet reliability. The quarter’s mine plan also included increased processing of contact ore and higher waste 9M25 8% 234,745 229,485 69,946 -1% -7% -4% 16% 7,748 2,053 97.6 44.4 8% 204,894 199,461 13% 0% -12% 12% 24,167 5,683 275.1 139.0 23,745 6,279 260.9 123.2 Iron ore production, Mt (3Q26 vs. 3Q25) 94.4 — (6.9) 1.5 (0.7) Δ y/y 2% 3% 2% -9% 5% 13% 88.4 3Q25 Northern System Southeastern System Southern System Third-party purchases Iron ore production-to-sales, Mt (3Q26) 88.4 stripping, which temporarily affected productivity. Importantly, these activities have increased hematite availability for the coming months and are expected to support stronger production y/y in Q4. 3.3 (0.8) (0.5) (4.1) 3Q26 86.3 • Serra Sul achieved its highest-ever quarterly output, reaching 23.8 Mt (+0.2 Mt y/y). In Q3, the Compact Crushing project started operations. Together with the Production Pelletizing mass loss Moisture change and adjustments Concentration mass loss (ex-Brazil) Inventory consumption Sales Serra Sul +20 project ramp-up, it is expected to further enhance operational flexibility and support production performance from 2027 onward. • Southeastern System: production was broadly stable y/y, totaling 22.7 Mt in the quarter. The result was supported by higher output from the Mariana Complex, reflecting improved performance at Alegria and Fazendão, as well as the continued ramp-up of Capanema, which offset planned maintenance activities in Brucutu and Itabira. • Southern System: production decreased by 0.7 Mt y/y, totaling 13.1 Mt in the quarter, mainly reflecting the stoppage of Fábrica and Viga operations since January 2026. This impact was partly offset by higher output at the Vargem Grande Complex, supported by the VGR1 plant. Operations at Fábrica resumed in September. • Pellets: production increased by 0.6 Mt y/y, totaling 8.6 Mt in the quarter, mainly driven by higher pellet feed availability from Brucutu and Itabira, as well as increased production at Vargem Grande pellet plant. • Iron ore sales totaled 86.3 Mt, 0.3 Mt higher y/y, mainly reflecting the sale of inventories built in previous periods.-3- Operational Results Copper operations • Salobo: copper production increased by 4.6 kt y/y, reaching 57.6 kt in the quarter, driven by strong mine and mill performance, resulting in its highest production for Q3. Copper production, kt (3Q26 vs. 3Q25) 90.8 (4.6) (0.7) 85.5 • Sossego: copper production decreased by 9.2 kt y/y, reaching 10.1 kt in the quarter, reflecting the ongoing planned SAG mill rebuild. The rebuild commenced in August and is expected to be completed in the second half of November. During this period, the Sossego plant continues to operate using a mobile crushing system, partly mitigating the impact of the SAG mill shutdown. 3Q25 Brazil Canada 3Q26 • Canada: copper production decreased by 0.7 kt y/y, reaching 17.7 kt in the quarter, reflecting the impact of preventive SAG mill maintenance at Voisey’s Bay brought forward to July. Ontario production remained solid, supported by additional throughput from the Clarabelle Mill expansion and the commissioning of Rod Mill #2, which started operations in September. • Payable copper sales1 totaled 86.3 kt, 3.7 kt lower y/y, mainly reflecting the production decrease. Nickel operations • Sudbury: own sourced finished nickel production increased by 2.8 kt y/y, reaching 11.3 kt in the quarter, supported by higher own sourced feed availability, solid mine performance, and the successful ramp-up of processing facilities following planned maintenance in Q2. As a result, production at Sudbury Refinery reached its highest quarterly level since 4Q13. Nickel production, kt (3Q26 vs. 3Q25) 1.0 46.8 3Q25 2.8 49.7 (0.9) Brazil Canada External feed 3Q26 • Voisey’s Bay: own sourced finished nickel production decreased by 1.1 kt y/y, reaching 9.6 kt in the quarter, as a result of Long Harbour annual maintenance, which was brought forward to September. • Thompson: own sourced finished nickel production decreased by 0.7 kt y/y, reaching 2.2 kt in the quarter, with the higher consumption of own sourced feed in Sudbury. • Onça Puma: finished nickel production increased by 2.8 kt y/y, reaching 8.7 kt in the quarter, reflecting the strong performance of the second furnace, resulting in Onça Puma’s highest Q3 production. • Nickel sales totaled 49.8 kt, 6.9 kt higher y/y, in line with production. 1 Sales volumes are lower than production volumes due to payable copper vs. contained copper: part of the copper contained in the concentrates is lost in the smelting and refining process, hence payable quantities of copper are approximately 3.5% lower than contained volumes.-4- Financial Results US$ million 3Q26 3Q25 Δ y/y 2Q26 Δ q/q 9M26 9M25 Δ y/y Proforma EBITDA Net operating revenues 10,599 10,420 2% 10,498 1% 30,355 27,343 11% COGS (7,940) (6,632) 20% (7,294) 9% (21,407) (18,168) 18% SG&A (159) (158) 1% (176) -10% (487) (434) 12% Research and development (189) (151) 25% (185) 2% (505) (433) 17% Pre-operating and stoppage expenses (86) (50) 72% (100) -14% (235) (211) 11% Brumadinho & decharacterization of dams¹ (181) (30) 503% (101) 79% (347) (165) 110% Non-recurring expenses — — n.a. (289) -100% (289) — n.a. Other operational expenses (excluding non-recurring expenses) (209) (238) -12% (214) -2% (616) (583) 6% Streaming 238 155 54% 291 -18% 786 490 60% EBITDA from Associates and JV's 328 292 12% 335 -2% 896 786 14% Adjusted EBIT 2,401 3,608 -33% 2,765 -13% 8,151 8,625 -5% Depreciation, amortization & depletion 926 761 22% 911 2% 2,682 2,245 19% Adjusted EBITDA 3,327 4,369 -24% 3,676 -9% 10,833 10,870 0% Proforma EBITDA² 3,508 4,399 -20% 4,066 -14% 11,469 11,035 4% Reconciliation of Proforma EBITDA to Net Income Proforma EBITDA² 3,508 4,399 -20% 4,066 -14% 11,469 11,035 4% Brumadinho & decharacterization of dams¹ and non recurring expenses (181) (30) 503% (390) -54% (636) (165) 285% Impairment and gains (losses) on disposal of non current assets, net (242) (370) -35% 16 n.a. (346) (755) -54% Streaming (238) (155) 54% (291) -18% (786) (490) 60% EBITDA from Associates and JV's (328) (292) 12% (335) -2% (896) (786) 14% Equity results and other results in Associates and JV´s (197) 160 n.a. 100 n.a. (61) 151 n.a. Financial results 138 (339) n.a. (473) n.a. (301) 13 n.a. Income taxes (259) 83 n.a. (368) -30% (1,132) (532) 113% Depreciation, depletion & amortization (926) (761) 22% (911) 2% (2,682) (2,245) 19% Net income 1,275 2,695 -53% 1,414 -10% 4,629 6,226 -26% Net income attributable to noncontrolling interests 20 10 100% 39 -49% 106 30 253% Net income attributable to Vale's shareholders 1,255 2,685 -53% 1,375 -9% 4,523 6,196 -27% Non-recurring items³ — 59 -100% 191 -100% 191 136 40% Proforma net income attributable to Vale’s shareholders 1,255 2,744 -54% 1,566 -20% 4,714 6,332 -26% 1 Find more information about expenses in Annex 4: Brumadinho & Decharacterization. 2 Excluding expenses related to Brumadinho and non-recurring items. 3 Includes impairments, non-recurring expenses and tax effects related to these items. Proforma EBITDA and Proforma net income attributable to Vale's shareholders – Reporting practice To enhance transparency and comparability, Vale reports: •Proforma EBITDA - a metric that provides a clearer view of operational performance across periods. It comprises: (i) Adjusted EBITDA as defined in note 3 to Vale’s Interim Financial Statements, which is a required disclosure under IFRS 8 – Operating Segments; excluding (ii) Brumadinho-related and dam decharacterization effects, and (iii) non-recurring items. This metric is disclosed consistently and in compliance with CVM Resolution 156. For the reconciliation of EBITDA Proforma to Net Income, please refer to the table above. •Proforma net income attributable to Vale's shareholders - a metric that provides a clearer view of earnings performance across periods. It excludes non-recurring items, such as asset impairments, as well as the related income tax effects. -5- Financial Results EBITDA Proforma EBITDA was US$ 3.5 billion in 3Q26, 20% lower y/y, mainly driven by (i) lower iron ore realized prices, (ii) higher costs and expenses, primarily reflecting the suspension of operations a Fábrica and Viga, higher third-party acquisition costs in Iron Ore and Nickel, and increased planned maintenance costs in the Nickel business, and (iii) exogenous effects, such as freight costs and the negative impact of the BRL appreciation. These effects were partly offset by the higher realized prices for copper, nickel, and by-products. Proforma EBITDA 3Q26 vs. 3Q25 - US$ million 4,399 (673) (532) 680 (275) 28 (119) Proforma EBITDA 3Q25¹ Iron Ore Prices Costs & Expenses Freight 1 Excluding Brumadinho expenses. 2 Including Associates and JVs EBITDA, volumes and others. Net Income FX effect VBM Prices Others² 3,508 Proforma EBITDA 3Q26¹ Proforma net income totaled US$ 1.3 billion in 3Q26, 54% lower y/y, mainly driven by (i) lower Proforma EBITDA US$ -891 million, (ii) a negative effect from Associates & JV's, mostly related to the Samarco provision adjustment (US$ -322 million), and (iii) higher income tax, mainly reflecting a variation related to foreign exchange effects on tax loss carryforwards at subsidiaries (US$ -276 million). These effects were partly offset by a US$ 610 million increase in mark to-market valuation and derivative settlements, recorded in Financial Results. Net income attributable to Vale’s shareholders also totaled US$ 1.3 billion, 53% lower y/y, driven by the decline in Proforma net income. Proforma net income 3Q26 vs. 3Q25 – US$ million 2,744 (891) (393) 477 (312) Proforma Net Income attributable 3Q25 Proforma EBITDA Associates & JVs¹ Income tax² Financial results³ 1,255 (370) Others⁴ Proforma Net Income attributable 3Q26 ¹ Including variations of (i) US$ -357 million in equity results and (ii) US$ -36 million in EBITDA from associates and JVs.2 Excluding a variation of US$ 30 million in taxes impacted by non-recurring items. 3 Including mark-to-market valuation variations of (i) US$ 426 million in other derivatives and (ii) US$ 184 million in currency and interest rate swaps. 4 Including variations of (i) US$ 39 million in gains (losses) on disposal of non-current assets, net, (ii) US$ 10 million in Net income attributable to non-controlling interests, (iii) US$ -151 million in Brumadinho and decharacterization of dams, (iv) US$ -83 million in Streaming, (v) US$ -165 million in Depreciation, depletion & amortization.-6- Capital Expenditures Total CAPEX US$ million 3Q26 3Q25 Δ y/y 2Q26 Δ q/q 9M26 9M25 Δ y/y Iron Ore Solutions 898 891 1 % 819 10% 2,555 2,561 0 % Vale Base Metals 315 322 -2 % 284 11% 825 858 -4 % Copper 138 86 60 % 118 17% 345 208 66 % Nickel 177 236 -25 % 166 7% 480 650 -26 % Energy and others 37 37 0 % 25 48% 87 58 50 % Total 1,250 1,250 0 % 1,128 11% 3,467 3,477 0 % Capital expenditures totaled US$ 1.25 billion in 3Q26, flat y/y and on track to meet the low-end of the 2026 CAPEX guidance of US$ 5.4-5.7 billion, reflecting ongoing project efficiency initiatives. Growth Projects US$ million 3Q26 3Q25 Δ y/y 2Q26 Δ q/q 9M26 9M25 Δ y/y Iron Ore Solutions 137 244 -44 % 159 -14% 454 730 -38 % Vale Base Metals 49 55 -11 % 38 29% 111 119 -7 % Copper 28 3 n.a. 13 115% 47 8 n.a. Nickel 21 52 -60 % 25 -16% 64 111 -42 % Energy and others — — n.a. — n.a. — — n.a. Total 186 299 -38 % 197 -6% 565 849 -33 % Investments in growth projects totaled US$ 186 million, down US$ 113 million (-38%) y/y, mainly reflecting lower disbursements in the Iron Ore Solutions and Nickel segments following the ramp-up of the Capanema and Onça Puma 2nd Furnace projects and the start-up of the Serra Sul +20 project in July. The Salobo Coarse Particle Flotation (Salobo CPF) project has been approved. The project will expand Salobo III plant capacity from 12 to 18 Mtpa, increasing copper production by ~30 ktpy and gold by ~15 kozpy. It is a low-capital intensity brownfield expansion with an IRR above 50%. The project reached 17% physical progress in 3Q26 and start-up is planned for 1H28. Sustaining Investments US$ million 3Q26 3Q25 Δ y/y 2Q26 Δ q/q 9M26 9M25 Δ y/y Iron Ore Solutions 761 647 18 % 660 15% 2,101 1,831 15 % Vale Base Metals 266 267 0 % 246 8% 714 739 -3 % Copper 110 83 33 % 105 5% 298 200 49 % Nickel 156 184 -15 % 141 11% 416 539 -23 % Energy and others 37 37 0 % 25 48% 87 58 50 % Total 1,064 951 12 % 931 14% 2,902 2,628 10 % Sustaining investments totaled US$1.1 billion, up US$ 113 million (12%) y/y, mainly driven by higher investments in Iron Ore. This primarily reflects the advanced stage of construction works to adapt the Oman pellet plant to receive concentrate from the Jinnan concentration facility, as well as progress on other sustaining projects. The Compact Crushing project started commissioning in July. The project is expected to improve iron ore and waste processing at Serra Sul and, together with the ramp-up of the Serra Sul +20 project, further enhance operational flexibility and support production performance. Financial Results -7- Free cash flow US$ million 3Q26 3Q25 Δ y/y 2Q26 Δ q/q 9M26 9M25 Δ y/y Proforma EBITDA¹ 3,508 4,399 -20% 4,066 -14% 11,469 11,035 4% Working capital² 250 (231) n.a. (162) n.a. (775) (491) 58% Capex (1,250) (1,250) 0% (1,128) 11% (3,467) (3,477) 0% Net financial expenses³ 45 (95) n.a. 26 73% (3) (288) -99% Income taxes and REFIS (240) (558) -57% (271) -11% (832) (1,622) -49% Associates & JV's, net of dividends received⁴ (280) (234) 20% (300) -7% (785) (648) 21% Brumadinho incurred expenses & dams⁵ (241) (183) 32% (220) 10% (598) (496) 21% Streaming (238) (155) 54% (291) -18% (786) (490) 60% Others (181) (131) 38% (215) -16% (532) (449) 18% Recurring Free Cash Flow 1,373 1,562 -12% 1,505 -9% 3,691 3,074 20% Non-recurring events 857 — n.a. — n.a. 857 — n.a. Disposal and acquisition of investments, net — 891 n.a. — n.a. — 891 n.a. Free Cash Flow⁶ 2,230 2,453 -9% 1,505 48% 4,548 3,965 15% Brumadinho (225) (306) -26% (263) -14% (595) (594) 0% Samarco (234) (970) -76% (717) -67% (1,080) (2,122) -49% Cash management and others (2,506) (935) 168% (60) n.a. (5,540) (597) n.a. Increase/(Decrease) in cash & equivalents (735) 242 n.a. 465 n.a. (2,667) 652 n.a. 1 Excluding expenses related to Brumadinho and non-recurring items. ² Includes US$ -46 million related to streaming transactions in 3Q26, US$ -44 million in 3Q25, US$ -46 million in 2Q26, US$ -126 million in 9M26 and US$ -161 million in 9M25, reflecting the difference between contractual terms and cash receipts, subject to volume and settlement dynamics. ³ Includes interest in loans and borrowings, leasing and net cash received on settlement of derivatives. ⁴ Net of US$ 48 million in dividends received in 3Q26, US$ 58 million in 3Q25, US$ 35 million in 2Q26, US$ 111 million in 9M26 and US$ 138 million in 9M25. ⁵ Includes payments related to dam decharacterization, incurred expenses related to Brumadinho, and others. Recurring Free Cash Flow totaled US$ 1.4 billion, US$ 189 million lower y/y, mainly due to lower Proforma EBITDA generation. This effect was largely offset by (i) a working capital release in the quarter, (ii) lower taxes paid, and (iii) positive results from the cash settlement of derivatives, which contributed US$ 249 million in cash in the quarter and US$ 702 million year-to-date. The working capital release in the quarter was mainly driven by (i) an increase in accounts payable, due to extended supplier payment terms, and (ii) inventory drawdown, with higher sales in Q3. These effects were partly offset by an increase in accounts receivable, reflecting higher sales volumes toward the end of the quarter. Vale Base Metals continued to positively contribute to cash generation, delivering Free Cash Flow of US$ 484 million in the quarter and US$ 1.1 billion year-to-date. Free Cash Flow totaled US$ 2.2 billion, US$ 223 million lower y/y, supported by a non-recurring cash release related to tax incentives. Vale’s cash position was impacted by US$ 1.7 billion in dividend and interest on capital payments during the quarter, along with continued liability management, resulting in a US$ 735 million decrease in cash and cash equivalents. Free Cash Flow 3Q26 - US$ million 3,508 250 (1,250) (195) (280) (241) (238) (181) 1,373 857 2,230 (459) (2,506) (735) Proforma EBITDA Working capital variation Capex Net financial expenses & income taxes¹ Associates & JV's² Brumadinho incurred expenses & dams³ Streaming Others⁴ Recurring Free Cash Flow Non recurring items Free Cash Flow Brumadinho & Samarco⁵ Cash management and others⁶ Decrease in cash & equivalents ¹ Includes income taxes and REFIS (US$ -240 million), interests on loans and borrowings (US$ -216 million), leasing (US$ -42 million), net cash received on settlement of derivatives (US$ 249 million), and other financial revenues (US$ 54 million). ² Related to Associates and Joint Ventures EBITDA that was included in the Proforma EBITDA, net of dividends received. ³ Includes incurred expenses on Brumadinho (US$ -147 million) and payments on dam decharacterization (US$ -94 million). ⁴ Includes disbursements related to railway concession contracts (US$ -197 million), and others. ⁵ Payments related to Brumadinho and Samarco. Excludes incurred expenses. ⁶ Includes US$ -1,676 in dividends and interest on capital paid and US$ -830 million in debt repayment. Financial Results -8- Financial Results Debt US$ million 3Q26 3Q25 Δ y/y 2Q26 Δ q/q Gross debt¹ 17,531 17,843 -2% 18,304 -4% Lease (IFRS 16) 602 700 -14% 634 -5% Gross debt and leases 18,133 18,543 Cash, cash equivalents and short-term investments (5,036) (6,091) Net debt 13,097 12,452 5% 13,173 -1% Currency swaps² (521) (173) 201% (367) 42% Brumadinho provisions 1,611 1,960 -18% 1,774 -2% -17% 18,938 (5,765) Samarco provisions 2,226 2,401 -7% 2,097 Expanded net debt 16,413 16,640 -1% 16,677 -2% Average debt maturity (years) 8.2 8.7 Cost of debt after hedge (% pa) 5.9 5.4 Total debt and leases / adjusted LTM EBITDA (x) 1.2 1.3 Net debt / adjusted LTM EBITDA (x) 0.8 0.8 Adjusted LTM EBITDA / LTM gross interest (x) 15.0 1Does not include leases (IFRS 16). 2 Includes interest rate swaps. 15.2 -6% 9% -8% 0% -1% 8.1 5.6 1.2 0.8 15.8 Expanded net debt decreased by US$ 264 million q/q, totaling US$ 16.4 billion, mainly reflecting solid free cash flow generation during the quarter. Vale's expanded net debt continues to move toward the midpoint of the US$ 10-20 billion target range. Gross debt and leases decreased by US$ 805 million q/q, reaching US$ 18.1 billion as of September 30th, 2026, mainly reflecting debt principal repayments. The average debt maturity was 8.2 years at the end of 3Q26, slightly above the 8.1 years at the end of 2Q26. The average annual cost of debt after currency and interest rate swaps increased to 5.9% from 5.6% at the end of 2Q26, mainly reflecting higher SOFR rates on Vale's debt. -4% -13% -9% 6% 1% 5% 0% 0% -5% -9- Segments’ Performance Adjusted EBITDA by business area: US$ million 3Q26 3Q25 Δ y/y 2Q26 Δ q/q 9M26 9M25 Δ y/y Iron Ore Solutions 2,633 3,972 -34% 3,056 -14% 8,595 9,836 -13 % Fines 2,078 3,418 -39% 2,561 -19% 7,080 8,147 -13 % Pellets 516 512 1% 416 24% 1,411 1,525 -7 % Other ferrous products and logistics services 39 42 -7% 79 -51% 104 164 -37 % Vale Base Metals 1,105 687 61% 1,289 -14% 3,591 1,962 83 % Copper 1,021 614 66% 1,026 0% 2,996 1,698 76 % Nickel 98 114 -14% 294 -67% 669 356 88 % Other (14) (41) -66% (31) -55% (74) (92) -20 % Unallocated Items¹ (230) (260) -12% (279) -18% (717) (763) -6% Proforma EBITDA 3,508 4,399 -20% 4,066 -14% 11,469 11,035 4% Brumadinho & decharacterization of dams² (181) (30) n.a. (101) 79% (347) (165) 110 % Non-recurring expenses — — n.a. (289) n.a. (289) — n.a. Adjusted EBITDA 3,327 4,369 -24% 3,676 -9% 10,833 10,870 0% 1 Includes US$ 15 million in unallocated expenses from Vale Base Metals Ltd ("VBM") in 3Q26. Considering the unallocated expenses, VBM’s EBITDA was US$ 1.1 billion in 3Q26. 2 More information about these expenses in Annex 5: Brumadinho & Decharacterization. Segment information 3Q26 US$ million Net operating revenues Cost¹ SG&A and others¹ R&D¹ Pre operating & stoppage¹ Associates and JVs EBITDA Streaming Adjusted EBITDA Iron Ore Solutions 7,767 (5,187) (90) (92) (50) 285 — 2,633 Fines 6,428 (4,295) (68) (84) (40) 137 — 2,078 Pellets 1,169 (714) 1 (1) (3) 64 — 516 Other ferrous products and logistics services 170 (178) (23) (7) (7) 84 — 39 Vale Base Metals 2,832 (1,891) (72) (45) — 43 238 1,105 Copper² 1,524 (469) (14) (20) — — — 1,021 Nickel³ 1,339 (1,225) (30) (24) — 38 — 98 Others⁴ (31) (197) (28) (1) — 5 238 (14) Brumadinho & decharacterization of dams⁵ — — (181) — — — — (181) Non-recurring expenses — — — — — — — — Unallocated Items⁶ — — (193) (35) (2) — — (230) Total 10,599 (7,078) (536) (172) (52) 328 238 3,327 ¹ Excluding depreciation, depletion, and amortization. ² Including by-products from our copper operations. ³ Including copper and by-products from our nickel operations. ⁴ Starting in 3Q25, streaming transactions at market prices, previously reported under SG&A and others, will be disclosed separately as Streaming. Prior periods were restated. ⁵ More information about these expenses in Annex 5: Brumadinho & Decharacterization. ⁶ Includes US$ 15 million in unallocated expenses from Vale Base Metals Ltd ("VBM") in 3Q26. Considering the unallocated expenses, VBM’s EBITDA was US$ 1.1 billion in 3Q26. Business Segments’ Performance -10- Iron Ore Solutions Highlights 3Q26 3Q25 Δ y/y 2Q26 Δ q/q 9M26 9M25 Δ y/y Average Prices (US$/t) Iron ore - 61% Fe price 96.7 99.4 -3% 105.0 -8% 101.7 98.1 4% Iron ore fines realized price, CFR/FOB 85.1 94.4 -10% 95.0 -10% 91.6 90.2 2% Iron ore pellets realized price, CFR/FOB 134.0 130.8 2% 137.0 -2% 134.9 135.0 0% Volume sold (‘000 metric tons) Fines 75,513 75,020 1% 69,946 8% 204,894 199,461 3% Pellets 8,720 8,769 -1% 7,748 13% 24,167 23,745 2% ROM 2,052 2,208 -7% 2,053 0% 5,683 6,279 -9% Total - Iron ore 86,285 85,997 0% 79,747 8% 234,745 229,485 2% Financials indicators (US$ million) Net Revenues 7,767 8,423 -8% 7,888 -2% 22,530 21,761 4% Costs¹ (5,187) (4,531) 14% (4,923) 5% (14,107) (12,141) 16% SG&A and Other expenses¹ (90) (54) 67% (50) 80% (212) (114) 86% R&D expenses (92) (84) 10% (86) 7% (244) (222) 10% Pre-operating and stoppage expenses¹ (50) (42) 19% (62) -19% (143) (159) -10% EBITDA Associates & JV's 285 260 10% 289 -1% 771 711 8% Adjusted EBITDA 2,633 3,972 -34% 3,056 -14% 8,595 9,836 -13% Depreciation and amortization (643) (553) 16% (667) -4% (1,868) (1,568) 19% Adjusted EBIT 1,990 3,419 -42% 2,389 -17% 6,727 8,248 -18% 1 Net of depreciation and amortization. Adjusted EBITDA per segment US$ million 3Q26 3Q25 Δ y/y 2Q26 Δ q/q 9M26 9M25 Δ y/y Fines 2,078 3,418 -39% 2,561 -19% 7,080 8,147 -13 % Pellets 516 512 1% 416 24% 1,411 1,525 -7 % Other ferrous products and logistics services 39 42 -7% 79 -51% 104 164 -37 % Adjusted EBITDA 2,633 3,972 -34% 3,056 -14% 8,595 9,836 -13 % Iron Ore Solutions EBITDA was US$ 2.6 billion, 34% lower y/y, mainly due to (i) lower realized prices, (ii) exogenous effects, such as higher freight costs and the negative impact of the BRL appreciation, and (iii) higher costs and expenses. Iron Ore Fines EBITDA was US$ 2.1 billion, 39% lower y/y, reflecting (i) lower realized prices (US$ -705 million), (ii) exogenous effects, such as higher freight costs (US$ -273 million) due to higher bunker fuel prices and the negative impact of the BRL appreciation (US$ -66 million), and (iii) higher costs and expenses (US$ -322 million). These effects were partly offset by higher sales volumes (US$ 23 million). Iron Ore Pellets EBITDA increased by 1% y/y, totaling US$ 516 million, mainly driven by higher realized prices (US$ 40 million) as a result of higher pellet premiums. This effect was partly offset by the negative impact of the BRL appreciation (US$ -17 million) and higher costs and expenses related to operational stoppages (US$ -14 million). EBITDA variation – US$ million (3Q26 vs. 3Q25) 3,972 (673) (331) (275) (91) 20 11 2,633 3Q25 Price Costs & Expenses Freight FX effect Volume Others¹ 3Q26 1 Includes Associates and JVs EBITDA and others. -11- Iron Ore Fines Product mix 000 metric tons 3Q26 3Q25 Δ y/y 2Q26 Δ q/q 9M26 9M25 Δ y/y Volume sold Fines¹ 75,513 75,020 1% 69,946 8% 204,894 199,461 3 % IOCJ 3,291 5,672 -42% 4,271 -23% 11,395 16,665 -32 % BRBF 32,223 36,133 -11% 30,295 6% 92,693 104,095 -11 % Mid-Grade Carajás 18,329 10,474 75% 13,014 41% 39,005 24,064 62 % Pellet feed - China (PFC)² 10,131 8,575 18% 11,863 -15% 31,063 18,021 72 % Lump 2,487 2,160 15% 2,244 11% 6,842 5,556 23 % High-silica products 2,779 4,267 -35% 1,038 168% 4,498 10,111 -56 % Other fines (60-62% Fe) 6,273 7,739 -19% 7,221 -13% 19,399 20,949 -7 % 1 Including third-party purchases. 2 Products concentrated in Chinese facilities. Revenues The average realized iron ore fines price was US$ 85.1/t, US$ 9.9/t lower q/q, mainly reflecting the negative impact of lower reference prices (US$ 8.3/t lower q/q) and more negative FOB sales adjustments (US$ 1.9/t lower q/q). The latter was primarily driven by higher spot freight rates at the end of the quarter, which resulted in a larger negative cut-off adjustment for CFR sales still in transit at quarter-end. Assuming lower freight rates at the end of 4Q26, the quarter on-quarter change in this adjustment is expected to positively impact realized prices. These negative effects were partly offset by the positive contribution from pricing mechanisms (US$ 0.7/t higher q/q). Price realization iron ore fines – US$/t (3Q26) 96.7 1.6 (0.5) 0.5 (0.1) (1.2) 97.0 (4.4) (7.5) 85.1 Average reference 61%Fe price 3Q26 (dmt) Quality and premiums¹ Provisional prices in prior quarter² Lagged prices Current prices Provisional prices in current quarter³ CFR reference (dmt) Adjustments for FOB sales⁴ Moisture Vale realized price (wmt)⁵ Impact of pricing system adjustments 1 Includes quality (US$ 1.7/t) and premiums/discounts and commercial conditions (US$ -0.1/t). 2 Adjustment as a result of provisional prices booked in 2Q26 at US$ 99.0/t. 3 Difference between the weighted average of the prices provisionally set at the end of 3Q26 at US$ 93.4/t based on forward curves and US$ 96.7/t from the 3Q26 average reference price. 4 Includes freight pricing mechanisms of CFR sales freight recognition. 5 Vale’s price is net of taxes. Iron ore all-in premium US$/t 3Q26 3Q25 Δ y/y 2Q26 Δ q/q 9M26 9M25 Δ y/y All-in premium - Total¹ 4.4 4.9 -10% 4.4 0% 4.9 4.7 4 % Iron ore fines quality and premiums 1.6 3.5 -54% 3.0 -47% 2.8 2.5 12 % Pellets business' weighted average contribution² 2.8 1.4 100% 1.4 100% 2.1 2.2 -5 % 1 Starting in 1Q26, the all-in premium will be disclosed in relation to the 61% Fe price index. Prior periods were restated. 2 Weighted average contribution. The all-in premium, adjusted for the 61% Fe price index, totaled US$ 4.4/t, broadly stable q/q. The contribution from iron ore fines quality premiums decreased (US$ 1.4/t lower q/q), mainly reflecting a lower premium contribution from Mid-grade Carajás products due to the operational restrictions at Serra Norte. Market premiums for low-alumina products remained strong, supporting a solid price realization. Lower overall iron ore fines realized premiums were fully offset by a higher contribution from the Pellets business (US$ 1.4/t higher q/q), driven by stronger quarterly pellet premiums and a greater share of direct reduction pellet sales. Business Segments’ Performance -12- Costs and expenses Iron ore fines and pellets all-in costs (cash cost break-even landed in China) US$/t 3Q26 3Q25 Δ y/y 2Q26 Δ q/q 9M26 9M25 Δ y/y C1 cash cost, ex-third-party purchase costs 23.1 20.7 12% 24.1 -4% 23.6 21.3 11 % Third-party purchases cost adjustments 3.7 3.6 3% 3.6 3% 3.9 3.8 3 % Freight cost¹ 22.8 18.8 21% 22.0 4% 21.2 18.6 14 % Distribution cost 4.3 3.8 13% 5.3 -19% 4.8 3.7 30 % Expenses & royalties² 7.8 5.7 37% 7.8 0% 7.7 5.8 33 % EBITDA from associates and joint ventures (1.8) (1.8) 0% (2.1) -14% (2.0) (1.8) 11 % Moisture adjustment 5.0 4.3 16% 5.3 -6% 5.1 4.5 13 % Iron ore fines quality adjustment³ (1.6) (3.5) -54% (3.0) -47% (2.8) 2.5 n.a. Iron ore fines all-in costs (US$/dmt) 63.2 51.5 23% 63.0 0% 61.5 53.4 15 % Pellet business contribution (2.8) (1.4) 100% (1.4) 100% (2.1) (2.2) -5 % Iron ore fines and pellets all-in costs (US$/dmt) 60.4 50.1 21% 61.6 -2% 59.4 51.2 16 % Sustaining investments (fines and pellets) 9.0 7.8 15% 8.5 6% 9.2 8.1 14 % Iron ore fines and pellets all-in costs⁴ (US$/dmt) 69.4 57.9 20% 70.1 -1% 68.6 59.3 16 % 1 Ex-bunker oil hedge. 2 Including stoppage costs and expenses. 3 Starting in 1Q26, the all-in premium will be disclosed in relation to the 61% Fe price index. Prior periods were restated. ⁴ Including sustaining investment. Iron ore fines C1 production costs US$ million 3Q26 3Q25 Δ y/y 2Q26 Δ q/q 9M26 9M25 Δ y/y C1 production costs, ex-third-party purchase costs 22.4 20.3 10% 24.1 -7% 23.7 21.5 10% C1 cash cost, ex-third-party purchase costs 23.1 20.7 12% 24.1 -4% 23.6 21.3 11% The C1 cash cost, excluding third-party purchases, reached US$ 23.1/t in 3Q26, 12% higher y/y. The increase mainly reflects (i) the negative impact of the BRL appreciation, (ii) an unfavorable production mix effect from the lower contribution of Serra Norte volumes, which have structurally lower production costs, (iii) higher diesel prices in the Brazilian domestic market, and (iv) costs related to the deconsolidation of Aliança Energia. These impacts were partly offset by ongoing efficiency gains, which helped mitigate external headwinds. C1 cash cost, excluding third-party purchase costs - US$/t, 3Q26 vs. 3Q25 20.7 0.8 0.6 0.5 0.3 (0.1) 0.3 23.1 3Q25 FX effect Mix and fixed cost dilution Diesel Aliança Energia deconsolidation Efficiency iniciatives¹ Others² 3Q26 1 Including maintenance, materials, personnel and services. 2 Including demurrage, inventory turnover and others. Vale's average maritime freight cost was US$ 22.8/t in 3Q26, US$ 0.8/t higher q/q, mainly due to higher bunker fuel costs (US$ 0.5/t higher q/q) and increased exposure to spot freight rates (US$ 0.3/t higher q/q), driven by seasonally higher sales in the second semester. CFR sales totaled 68.2 Mt in 3Q26, accounting for 90% of total iron ore fines sales. Vale's freight strategy continued to mitigate the impact of higher freight market volatility during the quarter. The Company's shipping requirements are predominantly covered by long-term contracts at freight-fixed rates, reducing direct exposure to spot freight rates. At the same time, fleet optimization initiatives and the use of larger, more fuel-efficient vessels support a competitive freight cost position. In 3Q26, Vale's freight costs remained US$ 14/t below the Brazil–China C3 route. As part of Vale's ongoing risk management strategy, Vale hedged approximately 70% of its forecasted bunker oil consumption for 2026 through Brent crude oil contracts. Considering the economic effect of these contracts in 3Q26, combined with forward freight agreements, the benefit on all-in cost per ton of iron ore, was approximately US$ 1.4/dmt. Adjusting for this effect, Vale’s all-in cost in 3Q26 would be equivalent to US$ 59.0/dmt, compared with the reported US$ 60.4/dmt, helping offset the impact of higher freight costs. For 2027, ~67% of the forecasted bunker oil consumption was hedged at an average of US$ 78/bbl in Brent oil-equivalent contracts. Business Segments’ Performance -13- Business Segments’ Performance Pellets 3Q26 3Q25 Δ y/y 2Q26 Δ q/q 9M26 9M25 Volume sold (‘000 metric tons) Pellets US$ million 8,720 8,769 -1% 7,748 Net revenues Cash costs¹ Pre-operational & stoppage expenses Expenses² Leased pelletizing plants EBITDA EBITDA Iron ore pellets realized price (CFR/FOB, US$/t) 1,169 (714) (4) 1 1,147 (677) (5) 2% 1,062 5% 13% 24,167 23,745 10% (680) -20% 2 64 516 134.0 45 512 130.8 -50% 42% 1% (27) 2 59 416 2% 137.0 Cash costs¹ per ton (US$/t) EBITDA per ton (US$/t) 81.9 59.2 77.2 58.4 1Including iron ore, leasing, freight, overhead, energy and others. 2 Including selling, R&D and others. 6% 1% 87.8 53.7 5% (1,981) -85% Pellets sales totaled 8.7 Mt, flat y/y and 13% higher q/q reflecting the increase in production levels. Δ y/y 2% 3,261 (34) -50% 8% 24% -2% -7% 10% 2 163 1,411 134.9 82.0 58.4 3,206 (1,813) (12) 4 140 1,525 135.0 76.4 64.2 2% 9% 183% -50% 16% -7% 0% 7% -9% The average realized iron ore pellet price was US$ 134.0/t, 2% lower q/q, driven by lower iron ore reference prices, which was partly offset by stronger pellet premiums and a higher share of direct reduction pellet sales. Pellets’ cash costs per ton were 6% higher y/y, totaling US$ 81.9/t, primarily due to the combination of the negative impact of the BRL appreciation and higher costs and expenses related to operational stoppages. FOB sales accounted for 58% of total pellets sales in the quarter.-14- Vale Base Metals Highlights US$ million Net Revenues Costs¹ SG&A and other expenses¹ ² R&D expenses Pre-operating and stoppage expenses¹ EBITDA from associates and JV's Streaming² Adjusted EBITDA 3Q26 2,832 (1,891) (72) (45) — 3Q25 1,997 (1,368) (92) (39) Δ y/y 42% 38% -22% 15% 2Q26 2,610 (1,533) (86) Δ q/q 9M26 9M25 9% 7,825 5,582 23% (4,800) (3,872) -16% (41) 2 43 238 1,105 Depreciation and amortization Adjusted EBIT (280) 825 32 155 687 (201) 486 n.a. 34% 54% 61% 39% 70% — 48 291 1,289 (232) 1,057 10% n.a. -10% -18% -14% 21% -22% (232) (112) — 125 786 3,591 (803) 2,788 (196) (107) (10) 75 490 1,962 (657) 1,304 Δ y/y 40 % 24 % 18 % 5 % n.a. 67 % 60 % 83 % 22 % 114 % 1Net of depreciation and amortization. 2 Starting in 3Q25, streaming transactions at market prices, previously reported under SG&A and others are disclosed separately as Streaming. Prior periods were restated. Adjusted EBITDA US$ million 3Q26 3Q25 Δ y/y 2Q26 Δ q/q 9M26 9M25 Δ y/y Copper 1,021 614 66% 1,026 0% 2,996 1,698 76 % Nickel 98 114 -14% 294 -67% 669 356 88 % Others (14) (41) -66% (31) -55% (74) (92) -20 % Total 1,105 687 61% 1,289 -14% 3,591 1,962 83 % Vale Base Metals EBITDA increased by 61% y/y in 3Q26, totaling US$ 1.1 billion, supported by consistent operational results and higher realized prices across all commodities in the portfolio, partly offset by maintenance and purchased feed costs. Copper EBITDA increased by 66% y/y, totaling US$ 1.0 billion in the quarter, driven by higher realized prices for copper (US$ 385 million) and by-products (US$ 80 million). These positive effects were partly offset by maintenance costs associated with the Sossego SAG mill rebuild (US$ -40 million) and the negative impact of the BRL appreciation (US$ -19 million). Nickel EBITDA decreased by 14% y/y, totaling US$ 98 million in the quarter, (i) higher own-sourced feed costs (US$ ‑109 million), reflecting the inventory turnover of higher unit production costs from 2Q26 and lower nickel grades consistent with the mine plans, (i) higher external feed prices (US$ -69 milion), and ( i) planned maintenance costs (US$ ‑33 milion). These effects were partly offset by higher realized prices for nickel (US$ 71 million) and by-products (US$ 125 million). EBITDA variation – US$ million (3Q26 vs. 3Q25) 680 687 (117) 1,105 (73) (59) 3Q25 Price¹ Costs² Maintenance costs Volume (13) Others³ 3Q26 ¹ Includes variations of (i) US$ 457 million in realized prices for copper and nickel, (ii) US$ 204 million in realized prices for by-products, and (iii) US$ 19 million in provisional price adjustments. ² Includes variations of (i) US$ 21 million in cost improvements in copper, (ii) US$ -69 million in higher external feed prices, (iii) US$ -54 million lower ore grade and (iv) US$ -16 million in cost inflation. 3 Includes variations of (i) US$ 11 million in EBITDA from Associates and JV's, (ii) US$ -13 million in exchange rate and (iii) others. -15- Copper US$ million (unless otherwise stated) 3Q26 3Q25 Δ y/y 2Q26 Δ q/q 9M26 9M25 Δ y/y LME copper price (US$/t) 14,104 9,797 44% 13,329 6% 13,434 9,556 41 % Average realized copper price (US$/t) 15,314 9,818 56% 14,062 9% 14,159 9,252 53 % Volume sold – copper (kt) 70 70 0% 78 -10% 219 197 11 % Net Revenues 1,524 1,086 40% 1,555 -2% 4,493 2,944 53 % Costs¹ (469) (437) 7% (479) -2% (1,374) (1,178) 17 % Selling and other expenses1,2 (14) (22) -36% (30) -53% (76) (34) 124 % R&D expenses3 (20) (13) 54% (20) 0% (47) (33) 42 % Pre-operating and stoppage expenses¹ — — n.a. — n.a. — (1) n.a. Adjusted EBITDA 1,021 614 66% 1,026 0% 2,996 1,698 76 % Depreciation and amortization (49) (44) 11% (49) 0% (142) (117) 21 % Adjusted EBIT 972 570 71% 977 -1% 2,854 1,581 81 % 1 Net of depreciation and amortization. 2 Includes expenses related to Hu'u (US$ -10 million), revenues related to the recovery of tax credits (US$ 11 million) and other revenues and expenses (US$ 6 million) in 3Q26. 3 Includes R&D expenses in new projects development unrelated to current operations of US$ 11 million in 3Q26. Adjusted EBITDA US$ million 3Q26 3Q25 Δ y/y 2Q26 Δ q/q 9M26 9M25 Δ y/y Salobo 938 485 93% 830 13% 2,465 1,307 89 % Sossego 138 143 -3% 291 -53% 738 321 130 % Other¹ (55) (14) 293% (95) -42% (207) 70 n.a. Total 1,021 614 66% 1,026 0% 2,996 1,698 76 % 1 Includes R&D expenses and the unrealized provisional price adjustments. Revenues Net revenues totaled US$ 1.5 billion in 3Q26, 40% higher y/y, mainly explained by higher realized copper prices (US$ 385 million), higher gold and silver prices (US$ 80 million). The average realized copper price was US$ 15,314/t, 9% higher q/q, reflecting higher LME prices, positive timing effects on pricing, and the favorable contribution of TC/RCs under current copper concentrate market conditions. The average realized copper price was 9% higher than the LME average price, primarily reflecting positive price adjustments to prior-period sales with final settlement at a higher LME price in the quarter. Average realized copper price 3Q26 – US$/t 14,104 (152) 13,952 1,310 15,262 52 15,314 Average LME copper price Current period price adjustments ¹ Copper gross realized price Prior period price adjustments ² Copper realized price before discounts TC/RCs, penalties, premiums discounts ³ Average copper realized price Note: Vale’s copper products are sold on a provisional pricing basis, with final prices determined in a future period. The average copper realized price excludes the mark-to-market of open invoices based on the copper price forward curve (unrealized provisional price adjustments) and includes the prior and current period price adjustments (realized provisional price adjustments). 1 Current-period price adjustments: Final invoices that were provisionally priced and settled within the quarter. 2 Prior-period price adjustments: Final invoices of sales provisionally priced in prior quarters. 3 TC/RCs, penalties, premiums, and discounts for intermediate products. Business Segments’ Performance -16- Business Segments’ Performance Costs & Expenses All-in costs (EBITDA break-even) US$/t 3Q26 3Q25 Δ y/y 2Q26 Δ q/q 9M26 9M25 COGS By-product revenues COGS after by-product revenues Other expenses¹ Total costs 6,721 (6,771) (50) (73) 6,221 (5,706) 515 8% 6,169 19% (6,845) 9% 6,264 5,966 -1% n.a. 343 (123) TC/RCs, penalties, premiums and discounts EBITDA break-even² ³ (52) (175) 858 136 994 n.a. n.a. n.a. n.a. (676) 319 (357) 100 (257) -93% (6,891) Δ y/y 5 % (5,164) (627) n.a. -66% n.a. -32% 184 (443) 85 (358) 802 203 1,005 210 1,215 33 % n.a.-9 % n.a.-60 % n.a. 1 Includes sales expenses, R&D associated with Salobo and Sossego, pre-operating and stoppage expenses and other expenses. 2 Considering only the cash effect of streaming transactions, copper operations EBITDA break-even would increase to US$ 3,288/t in 3Q26. 3 The realized price to be compared to the EBITDA break-even should be the copper realized price before discounts (US$ 15,262/t for 3Q26), given that TC/RCs, penalties, and other discounts are already part of the EBITDA break-even build-up. Unit COGS were US$ 6,721/t, 8% higher y/y, driven by the Sossego SAG mill rebuild costs (US$ +576/t) and the BRL appreciation (US$ +258/t). These effects were partly offset by higher fixed-cost dilution at Salobo (US$ -295/t), reflecting its strong operational performance. All-in costs totaled US$ -175/t in the quarter, US$ 1,169/t lower y/y and largely in-line q/q. The year-on-year improvement was mainly driven by higher unit by-product revenues (US$ -1,065/t) and the effect of the recovery of tax credits related to Salobo (US$ -143/t), included in other expenses, which offset the unit COGS effect mentioned above. Unit COGS, net of by-products, by operation US$/t 3Q26 3Q25 Δ y/y 2Q26 Δ q/q 9M26 9M25 Δ y/y Salobo (799) (156) n.a. (1,605) -50% (1,473) 40 n.a. Sossego 3,620 2,260 60% 1,415 156% 1,557 2,979 -48 %-17- Nickel US$ million (unless otherwise stated) 3Q26 3Q25 Δ y/y 2Q26 Δ q/q 9M26 9M25 Δ y/y LME nickel price 16,573 15,015 10% 18,131 -9% 17,337 15,251 14% Average realized nickel price 16,898 15,445 9% 18,061 -6% 17,307 15,773 10% Volume sold - nickel (kt) 50 43 16% 44 14% 139 123 13% Volume sold - copper (kt) 17 20 -15% 20 -15% 56 64 -13% Net Revenues 1,339 1,010 33% 1,241 8% 3,764 2,991 26% Costs¹ (1,225) (871) 41% (946) 29% (3,081) (2,559) 20% Selling and other expenses¹ ² (30) (31) -3% (24) 25% (61) (60) 2% R&D expenses² (24) (25) -4% (20) 20% (63) (72) -13% Pre-operating and stoppage expenses¹ — 2 n.a. — n.a. — (9) n.a. EBITDA from associates and JV's 38 29 31% 43 -12% 111 65 71% Adjusted EBITDA 98 114 -14% 294 -67% 669 356 88% Depreciation and amortization (223) (150) 49% (181) 23% (640) (519) 23% Adjusted EBIT (125) (36) 247% 113 n.a. 29 (162) n.a. 1 Net of depreciation and amortization. ² Includes R&D and other expenses not related to current operations of US$ 35 million in 3Q26. Adjusted EBITDA US$ million 3Q26 3Q25 Δ y/y 2Q26 Δ q/q 9M26 9M25 Δ y/y Sudbury¹ 6 44 -86% 118 -95% 351 118 197 % Voisey’s Bay & Long Harbour 54 46 17% 118 -54% 238 13 n.a. Standalone Refineries² (9) 2 n.a. 45 n.a. 60 32 88 % Onça Puma 19 9 111% 41 -54% 111 37 200 % Others³ 28 13 115% (28) n.a. (91) 156 n.a. Total 98 114 -14% 294 -67% 669 356 88 % 1 Includes the Thompson operations. 2 Comprises the sales results for Clydach and Matsusaka refineries. 3 Includes intercompany eliminations, provisional price adjustments and inventories adjustments. Includes proportionate EBITDA from PTVI. Revenues Net revenues totaled US$ 1.3 billion in 3Q26, increasing by 33% y/y, driven by stronger nickel sales volumes (US$ 107 million), higher realized nickel prices (US$ 71 million), and higher by-products revenues (US$ 119 million). The average realized nickel price was US$ 16,898/t, 6% lower q/q, explained by a 9% decrease in the LME nickel average price, partly offset by higher average aggregate premiums. The average realized nickel price was 2% higher than the LME average, mainly due to the positive impact of premiums and fixed price sales. Average realized nickel price 3Q26 – US$/t 16,573 277 16,850 (1) 50 16,898 Average LME nickel price Nickel average aggregate premium Average realized price before timing and other adjustments Quotational period Fixed price sales Average nickel realized price Business Segments’ Performance -18- Business Segments’ Performance Costs & Expenses All-in costs (EBITDA break-even) US$/t COGS ex-external feed COGS¹ By-product revenues¹ COGS after by-product revenues Other expenses² EBITDA from associates & JV's Total Costs Nickel average aggregate (premium) discount 3Q26 25,796 24,603 (9,391) 15,212 380 3Q25 22,835 20,310 (8,166) 12,144 Δ y/y 2Q26 13% 23,652 21% 21,345 15% (10,311) Δ q/q 9M26 9M25 9% 24,002 24,033 15% 22,170 21,394 -9% (10,432) (8,034) 25% 11,034 1,324 (763) 14,829 (277) EBITDA break-even³ 14,552 (677) 12,791 (444) 12,347 -71% 13% 354 (970) 16% 10,418 -38% (78) 18% 10,340 38% 11,738 13,360 7% -21% 336 (799) 1,065 (528) 42% 11,275 13,897 255% (122) (467) 41% 11,153 13,430 Δ y/y — % 4 % 30 %-12 %-68 % 51 %-19 %-74 %-17 % 1Excluding marketing activities. 2 Includes R&D associated with current nickel operations, sales expenses and pre-operating & stoppage. 3 Considering only the cash effect of streaming transactions, nickel operations EBITDA break-even would increase to US$ 15,397/t in 3Q26. Unit COGS, excluding external feed purchases, were US$ 25,796/t, 13% higher y/y, mainly driven by (i) the inventory turnover effect of higher unit production costs from 2Q26 (US$994/t), (ii) planned maintenance costs (US$663/t), (iii) lower nickel grades consistent with the mine plans (US$441/t), and (iv) cost inflation, mainly related to energy and fuel costs, (US$321/t). Unit COGS totaled US$ 24,603/t, up 21% y/y and 15% q/q. All-in costs totaled US$ 14,552/t in the quarter, 18% higher y/y and 41% higher q/q. The year-on-year increase was driven by higher own-source feed costs, along with higher external feed prices (US$ 1,376/t), partly offset by unit by-product revenues (US$ 1,225/t). The q/q increase reflected lower by-product revenues (US$ 920/t). Unit COGS, net of by-products, by operation US$/t 3Q26 3Q25 Δ y/y 2Q26 Δ q/q 9M26 9M25 Δ y/y Sudbury¹ ² 16,340 10,768 52% 10,238 60% 9,766 12,153 -20 % Voisey’s Bay & Long Harbour² 13,368 10,955 Standalone refineries² ³ 18,209 15,813 22% 15% 6,727 15,109 99% 11,180 14,713 -24 % 10 % Onça Puma 11,541 10,721 8% 10,384 11% 10,518 10,484 0 % 21% 16,474 14,998 ¹ Sudbury costs include Thompson costs. ² A large portion of Sudbury, Clydach, Matsusaka and Long Harbour finished nickel production is derived from intercompany transfers, as well as from the purchase of ore or nickel intermediates from third parties. These transactions are valued at fair market value. ³ Comprises the unit COGS for Clydach and Matsusaka refineries.-19- Webcast information Investor Relations Vale will host a webcast on vale.RI@vale.com Friday 30thOctober, 2026 10:00 a.m. (New York) Thiago Lofiego11:00 a.m. (Brasília) thiago.lofiego@vale.com 2:00 p.m. (London) Luciana Oliveti luciana.oliveti@vale.com Internet access to the webcast and presentation materials will be available on Vale website at www.vale.com/investors Pedro Terra pedro.terra@vale.com A webcast replay will be accessible shortly after the completion of the call. Patricia Tinoco patricia.tinoco@vale.com Further information on Vale can be found at: vale.comExcept where otherwise indicated, the operational and financial information in this release is based on the consolidated figures in accordance with IFRS. Our quarterly financial statements are reviewed by the company’s independent auditors. The main subsidiaries that are consolidated are the following: Companhia Portuária da Baía de Sepetiba, Vale Manganês S.A., Minerações Brasileiras Reunidas S.A., Vale Base Metals Ltd, Salobo Metais S.A, Tecnored Desenvolvimento Tecnológico S.A., Vale Holdings B.V, Vale Canada Limited, Vale International S.A., Vale Malaysia Minerals Sdn. Bhd. and Vale Oman Pelletizing Company LLC. This press release may include statements about Vale’s current expectations about future events or results (forward-looking statements). Many of those forward-looking statements can be identified by the use of forward-looking words such as ”anticipate,” ”believe,” ”could,” ”expect,” ”should,” ”plan,” ”intend,” ”estimate” “will” and ”potential,” among others. All forward-looking statements involve various risks and uncertainties. Vale cannot guarantee that these statements will prove correct. These risks and uncertainties include, among others, factors related to: (a) the countries where Vale operates, especially Brazil and Canada; (b) the global economy; (c) the capital markets; (d) the mining and metals prices and their dependence on global industrial production, which is cyclical by nature; and (e) global competition in the markets in which Vale operates. Vale cautions you that actual results may differ materially from the plans, objectives, expectations, estimates and intentions expressed in this presentation. Vale undertakes no obligation to publicly update or revise any forward-looking statement, whether as a result of new information or future events or for any other reason. To obtain further information on factors that may lead to results different from those forecast by Vale, please consult the reports that Vale files with the U.S. Securities and Exchange Commission (SEC), the Brazilian Comissão de Valores Mobiliários (CVM) and, in particular, the factors discussed under “Forward-Looking Statements” and “Risk Factors” in Vale’s annual report on Form 20-F. The information contained in this press release includes financial measures that are not prepared in accordance with IFRS. These non-IFRS measures differ from the most directly comparable measures determined under IFRS, but we have not presented a reconciliation to the most directly comparable IFRS measures, because the non-IFRS measures are forward-looking and a reconciliation cannot be prepared without unreasonable effort. -20- Annex 1: Production and sales summary Iron ore 000’ metric tons 3Q26 3Q25 ∆ y/y 2Q26 ∆ q/q 9M26 9M25 Δ y/y Northern System 42,802 49,737 -14% 39,560 8% 115,535 125,379 -8% Serra Norte and Serra Leste 18,997 26,172 -27% 16,134 18% 48,450 61,504 -21% Serra Sul (S11D) 23,805 23,564 1% 23,426 2% 67,085 63,875 5% Southeastern System 22,737 22,721 0% 24,336 -7% 66,267 59,885 11% Itabira (Cauê, Conceição and others) 5,883 7,247 -19% 6,034 -3% 17,340 18,156 -4% Minas Centrais (Brucutu and others) 6,329 7,979 -21% 8,376 -24% 21,516 21,366 1% Mariana (Capanema, Timbopeba and others) 10,525 7,494 40% 9,925 6% 27,410 20,363 35% Southern System 13,126 13,783 -5% 12,075 9% 35,579 37,463 -5% Paraopeba (Mutuca, Fábrica and others) 2,057 4,376 -53% 1,806 14% 5,506 11,165 -51% Vargem Grande (VGR, Pico and others) 11,069 9,407 18% 10,269 8% 30,073 26,296 14% Own production 78,665 86,240 -9% 75,971 4% 217,380 222,726 -2% Third-party purchases 9,689 8,162 19% 8,284 17% 24,903 22,945 9% Iron Ore Production¹ 88,354 94,403 -6% 84,255 5% 242,284 245,671 -1% Pelletizing mass loss (816) (710) 15% (877) -7% (2,446) (2,181) 12% Moisture change and adjustments (455) (1,049) -57% (1,095) -58% (4,212) (2,881) 46% Concentration mass loss (ex-Brazil) (4,146) (2,190) 89% (3,185) 30% (10,329) (6,295) 64% Inventory (build-up)/ consumption 3,348 (4,457) n.a. 648 417% 9,447 (4,831) n.a. Iron Ore Sales² 86,285 85,997 0% 79,747 8% 234,745 229,485 2% Fines Sales³ 75,513 75,020 1% 69,946 8% 204,894 199,461 3% IOCJ 3,291 5,672 -42% 4,271 -23% 11,395 16,665 -32% BRBF 32,223 36,133 -11% 30,295 6% 92,693 104,095 -11% Mid-Grade Carajás 18,329 10,474 75% 13,014 41% 39,005 24,064 62% Pellet feed – China⁴ 10,131 8,575 18% 11,863 -15% 31,063 18,021 72% Lump 2,487 2,160 15% 2,244 11% 6,842 5,556 23% High-silica products 2,779 4,267 -35% 1,038 168% 4,498 10,111 -56% Other fines (60-62% Fe) 6,273 7,739 -19% 7,221 -13% 19,399 20,949 -7% Pellet Sales 8,720 8,769 -1% 7,748 13% 24,167 23,745 2% ROM Sales 2,052 2,208 -7% 2,053 0% 5,683 6,279 -9% Sales from 3rd party purchase 9,216 8,201 12% 7,418 24% 23,415 22,561 4% 1 Including third party purchases, run-of-mine and feed for pelletizing plants. 2 Vale’s Fe content reached 62.5%, alumina 1.3% and silica 5.6% in 3Q26 sales portfolio. 3 Including third-party purchases. 4 Products concentrated in Chinese facilities. Pellets ‘000 metric tons 3Q26 3Q25 ∆ y/y 2Q26 ∆ q/q 9M26 9M25 Δ y/y Northern System — 10 -100% 145 -100% 217 669 -68% São Luis¹ — 10 -100% 145 -100% 217 669 -68% Southeastern System 5,354 4,575 17% 5,759 -7% 16,142 13,001 24% Itabrasco (Tubarão 3) 917 349 163% 978 -6% 2,741 1,974 39% Hispanobras (Tubarão 4) 1,028 755 36% 909 13% 2,588 1,547 67% Nibrasco (Tubarão 5 and 6) 1,087 1,028 6% 1,127 -4% 3,336 2,433 37% Kobrasco (Tubarão 7) 753 903 -17% 1,112 -32% 2,744 2,592 6% Tubarão 8 1,569 1,540 2% 1,632 -4% 4,732 4,455 6% Southern System 1,109 888 25% 1,199 -8% 3,497 3,119 12% Vargem Grande 1,109 888 25% 1,199 -8% 3,497 3,119 12% Oman 2,091 2,524 -17% 200 946% 4,170 6,242 -33% Pellet Production 8,554 7,997 7% 7,303 17% 24,026 23,031 4% Pellet Sales 8,720 8,769 -1% 7,748 13% 24,167 23,745 2% 1 Starting in 1Q26, the São Luís plant will operate in line with demand scenarios, and Vale will evaluate the timing of a potential full resumption based on market conditions. Annexes -21- Copper - Finished production by source 000’ metric tons 3Q26 3Q25 ∆ y/y 2Q26 ∆ q/q 9M26 9M25 Δ y/y Brazil 67.7 72.3 -6% 78.3 -14% 227.8 211.6 8% Salobo 57.6 53.0 9% 52.4 10% 162.8 155.8 4% Sossego 10.1 19.3 -48% 25.9 -61% 65.0 55.8 16% Canada 17.7 18.4 -4% 20.1 -12% 58.2 62.6 -7% Sudbury 12.6 12.6 0% 12.5 1% 38.4 43.6 -12% Thompson 0.1 0.2 -50% 0.2 -50% 0.4 1.4 -71% Voisey's Bay 3.1 4.3 -28% 6.0 -48% 14.5 13.9 4% Feed from third parties1 1.9 1.3 46% 1.4 36% 4.9 3.7 32% Copper Production 85.5 90.8 -6% 98.4 -13% 286.2 274.3 4% Copper Sales 86.3 90.0 -4% 97.6 -12% 275.1 260.9 5% Copper Sales Brazil 69.7 70.2 -1% 77.8 -10% 219.4 197.4 11% Copper Sales Canada 16.6 19.8 -16% 19.8 -16% 55.8 63.5 -12% 1 External feed purchased from third parties and processed into copper in our Canadian operation. Nickel ‘000 metric tons 3Q26 3Q25 ∆ y/y 2Q26 ∆ q/q 9M26 9M25 Δ y/y Finished Production by Source Canada 23.1 22.1 5% 19.4 19% 64.8 63.4 2% Sudbury 11.3 8.5 33% 6.7 69% 28.6 27.0 6% Thompson 2.2 2.9 -24% 2.2 0% 5.6 10.6 -47% Voisey's Bay 9.6 10.7 -10% 10.4 -8% 30.5 25.8 18% Brazil 8.7 5.9 47% 9.4 -7% 27.0 16.1 68% External feed 17.8 18.7 -5% 13.3 34% 49.2 51.5 -4% Feed from third-parties1 4.7 3.8 24% 1.8 161% 10.1 11.8 -14% PTVI offtake2 13.1 14.9 -12% 11.4 15% 39.0 39.7 -2% Finished Production by Site Sudbury 17.7 15.0 18% 9.7 82% 42.8 45.0 -5% Voisey’s Bay & Long Harbour 11.0 11.7 -6% 12.2 -10% 34.4 32.7 5% Onça Puma 8.7 5.9 47% 9.4 -7% 27.0 16.1 68% Clydach 6.9 8.6 -20% 5.2 33% 22.4 22.5 0% Matsusaka 5.5 5.2 6% 5.6 -2% 14.6 13.2 11% Others3 — 0.3 -100% — n.a. — 1.3 -100% Nickel Production 49.7 46.8 6% 42.0 18% 141.0 131.0 8% Nickel Sales 49.8 42.9 16% 44.4 12% 139.0 123.2 13% 1 External feed purchased from third parties and processed into finished nickel in our Canadian operations. It does not include feed purchased from PTVI. 2 Starting from 3Q24, PTVI sourced production is reported as “External feed” and reflects solely the 80%-offtake attributable to Vale Base Metals processed at downstream facilities. Before, PTVI production was 100% consolidated by Vale. 3 Includes intermediates produced in Thompson and PTVI, tolling and others. Vale Base Metals by-products - Finished production 3Q26 3Q25 ∆ y/y 2Q26 ∆ q/q 9M26 9M25 Δ y/y Cobalt (metric tons) 990 964 3% 772 28% 2,650 2518 5% Platinum (000’ oz troy) 28 21 33% 18 56% 67 73 -8% Palladium (000’ oz troy) 33 25 32% 23 43% 79 89 -11% Gold (000’ oz troy)1 106 112 -5% 108 -2% 336 348 -3% Total by-Products (000’ metric tons Cu eq.)2 3 49 49 0% 50 -2% 157 148 6% 1 Includes Gold from Copper and Nickel operations. 2 Includes Iridium, Rhodium, Ruthenium and Silver. 3 Copper equivalent tons calculated using average market metal prices for each quarter. Market reference prices: for copper and cobalt: LME spot; for Gold, Silver, Platinum, and Palladium: Bloomberg; for other PGMs: Johnson Matthey. Annexes -22- Vale Base Metals: Maintenance scheduled in 2026 Q1 Q2 Q3 Q4 Copper operations Salobo Salobo I & II 2 weeks Salobo III 2 weeks Sossego Sossego 2 weeks 2 weeks 3 weeks 2 weeks Sossego SAG rebuild 9 weeks 7 weeks Nickel operations Sudbury Coleman Creighton 6 weeks Copper Cliff 3 weeks Garson 4 weeks Totten 1 week Stobie 1 week Clarabelle mill 4 weeks Sudbury Smelter 4 weeks Sudbury Refinery 4 weeks Port Colborne (Ni, Co & PGMs) 4 weeks Thompson Thompson mine 4 weeks Thompson mill 4 weeks Voisey’s Bay & Long Harbour Voisey’s Bay 2 weeks Long Harbour Refinery 1 week 1 week Standalone Refineries Clydach 4 weeks 3 weeks Matsusaka 5 weeks Brazil Onça Puma 1 week 3 weeks Note: The maintenance schedule may be deliberately adjusted if it proves beneficial for operations and the overall business. The number of weeks is rounded to 0.0 or 0.5 and may involve more than one maintenance activity within the quarter. Annexes -23- Annex 2: Detailed Financial Information Simplified financial statements Income Statement US$ million 3Q26 3Q25 Δ y/y 2Q26 Δ q/q 9M26 9M25 Δ y/y Net operating revenue 10,599 10,420 2% 10,498 1% 30,355 27,343 11% Cost of goods sold and services rendered (7,940) (6,632) 20% (7,294) 9% (21,407) (18,168) 18% Gross profit 2,659 3,788 -30% 3,204 -17% 8,948 9,175 -2% Gross margin (%) 25% 36% -11 p.p. 31% -6 p.p. 29% 34% -5 p.p. Selling and administrative expenses (159) (158) 1% (176) -10% (487) (434) 12% Research and development (189) (151) 25% (185) 2% (505) (433) 17% Pre-operating and operational stoppage (86) (50) 72% (100) -14% (235) (211) 11% Other operational expenses, net (390) (268) 46% (604) -35% (1,252) (748) 67% Impairment and gains (losses) on disposal of non current assets, net (242) (370) -35% 16 n.a. (346) (755) -54% Operating income 1,593 2,791 -43% 2,155 -26% 6,123 6,594 -7% Financial income 110 148 -26% 122 -10% 360 376 -4% Financial expenses (434) (396) 10% (409) 6% (1,261) (1,182) 7% Other financial items, net 462 (91) n.a. (186) n.a. 600 819 -27% Equity results and other results in associates and joint ventures (197) 160 n.a. 100 n.a. (61) 151 n.a. Income before income taxes 1,534 2,612 -41% 1,782 -14% 5,761 6,758 -15% Current tax (153) 294 n.a. (400) -62% (795) (177) 349% Deferred tax (106) (211) -50% 32 n.a. (337) (355) -5% Net income 1,275 2,695 -53% 1,414 -10% 4,629 6,226 -26% Net income attributable to noncontrolling interests 20 10 100% 39 -49% 106 30 253% Net income attributable to Vale's shareholders 1,255 2,685 -53% 1,375 -9% 4,523 6,196 -27% Basic earnings per share (attributable to the Company's shareholders - US$): Basic and diluted earnings per share (attributable to the Company's shareholders - US$) 0.29 0.63 -54% 0.32 -9% 1.06 1.45 -27% Equity income (loss) by business segment US$ million 3Q26 % 3Q25 %Δ y/y 2Q26 %Δ q/q 9M26 % 9M25 %Δ y/y Iron Ore Solutions 123 98% 149 103% -17% 113 92% 9% 267 88% 320 106% -17% Vale Base Metals¹ 3 2% (3) -2% n.a. 10 8% -70% 38 12% (20) -6% n.a. Unallocated items — 0% (1) -1% n.a. — 0% n.a. — 0% 1 0% n.a. Total 126 100% 145 100% -13% 123 100% 2% 305 100% 301 100% 1% ¹ Restated from historical figures. Annexes -24- Balance sheet US$ million 09/30/2026 09/30/2025 Δ y/y 06/30/2026 Δ q/q Assets Current assets 16,946 16,486 3% 17,659 -4% Cash and cash equivalents 4,841 5,902 -18% 5,577 -13% Short term investments 195 189 3% 188 4% Accounts receivable 2,955 2,506 18% 2,614 13% Other financial assets 798 626 27% 576 39% Inventories 6,058 5,567 9% 6,264 -3% Recoverable taxes 1,509 1,232 22% 1,717 -12% Other 565 464 22% 696 -19% Non-current assets held for sale 25 — n.a. 27 -7% Non-current assets 10,039 13,306 -25% 10,535 -5% Judicial deposits 573 638 -10% 577 -1% Other financial assets 1,135 416 173% 796 43% Recoverable taxes 1,757 1,771 -1% 1,743 1% Deferred income taxes 6,010 8,891 -32% 6,016 0% Other 564 1,590 -65% 1,403 -60% Fixed assets 61,455 61,398 0% 61,085 1% Total assets 88,440 91,190 -3% 89,279 -1% Liabilities Current liabilities 15,370 13,324 15% 14,818 4% Suppliers and other payables 6,814 5,651 21% 6,203 10% Loans and borrowings 1,190 470 153% 1,093 9% Leases 161 175 -8% 169 -5% Railway concession 529 484 9% 629 -16% Other financial liabilities 638 512 25% 649 -2% Taxes payable 765 576 33% 890 -14% Settlement program ("REFIS") 471 430 10% 464 2% Provisions for litigation 164 148 11% 161 2% Employee benefits 1,055 1,012 4% 886 19% Liabilities related to associates and joint ventures 745 1,188 -37% 662 13% Liabilities related to Brumadinho 706 814 -13% 807 -13% Decharacterization of dams and asset retirement obligations 1,043 938 11% 1,119 -7% Dividends payable 22 — n.a. 21 5% Other 868 926 -6% 884 -2% Liabilities associated with non-current assets held for sale 199 — n.a. 181 10% Non-current liabilities 34,493 35,585 -3% 35,515 -3% Loans and borrowings 16,341 17,373 -6% 17,211 -5% Leases 441 525 -16% 465 -5% Railway concession 1,765 2,081 -15% 1,790 -1% Other financial liabilities 3,240 2,756 18% 3,247 0% Settlement program (REFIS) 519 905 -43% 627 -17% Deferred income taxes 171 66 159% 54 217% Provisions for litigation 1,021 912 12% 997 2% Employee benefits 1,142 1,212 -6% 1,185 -4% Liabilities related to associates and joint ventures 1,481 1,213 22% 1,435 3% Liabilities related to Brumadinho 905 1,146 -21% 967 -6% Decharacterization of dams and asset retirement obligations 4,998 5,134 -3% 5,032 -1% Streaming transactions 1,932 1,988 -3% 1,944 -1% Others 537 274 96% 561 -4% Total liabilities 49,863 48,909 2% 50,333 -1% Shareholders' equity 38,577 42,281 -9% 38,946 -1% Total liabilities and shareholders' equity 88,440 91,190 -3% 89,279 -1% Annexes -25- Cash flow US$ million 3Q26 3Q25Δ y/y 2Q26Δ q/q 9M26 9M25 Δ y/y Cash flow generated from operations 3,045 3,643 -16% 3,129 -3% 8,642 9,039 -4% Payment of interest on loans, financing and other financial liabilities (216) (185) 17% (310) -30% (740) (694) 7% Receipts from the settlement of derivatives, net 249 93 168% 337 -26% 702 376 87% Payments related to Brumadinho (225) (306) -26% (263) -14% (595) (594) 0% Payments related to de-characterization of dams (94) (110) -15% (71) 32% (228) (272) -16% Payments related to participative shareholder's debentures remuneration — — n.a. (139) n.a. (139) (131) 6% Payments of income taxes (including refinancing programs) (240) (558) -57% (271) -11% (832) (1,622) -49% Net cash generated by operating activities 2,519 2,577 -2% 2,412 4% 6,810 6,102 12% Cash flow from investing activities Short-term investment 70 61 15% 59 19% 187 194 -4% Acquisition of property, plant and equipment and intangible assets (1,447) (1,394) 4% (1,244) 16% (3,876) (3,817) 2% Payments related to Samarco dam failure (234) (970) -76% (717) -67% (1,080) (2,122) -49% Dividends received from joint ventures and associates 48 58 -17% 35 37% 111 138 -20% Cash received from disposal and acquisition of investments, net — 1,006 n.a. — n.a. — 1,006 n.a. Other investment activities, net 853 (1) n.a. 39 n.a. 852 (9) n.a. Net cash used in investing activities (710) (1,240) -43% (1,828) -61% (3,806) (4,610) -17% Cash flow from financing activities Loans and financing: Loans and borrowings from third parties — 1,011 n.a. 161 n.a. 1,123 4,298 -74% Payments of loans and borrowings from third parties (830) (461) 80% (81) n.a. (2,028) (1,431) 42% Payments of leasing (42) (42) 0% (49) -14% (125) (105) 19% Payments to shareholders: Dividends and interest on capital paid to Vale's shareholders (1,676) (1,485) 13% — n.a. (4,421) (3,464) 28% Share buyback program — — n.a. (140) n.a. (214) — n.a. Net cash used in financing activities (2,548) (977) 161% (109) n.a. (5,665) (702) n.a. Net increase (decrease) in cash and cash equivalents (739) 360 n.a. 475 n.a. (2,661) 790 n.a. Cash and cash equivalents in the beginning of the period 5,577 5,514 1% 5,085 10% 7,372 4,953 49% Effect of exchange rate changes on cash and cash equivalents 3 28 -89% 17 -82% 130 274 -53% Cash from subsidiaries classified as non‑current assets held for sale — — n.a. — n.a. — (115) n.a. Cash and cash equivalents at the end of period 4,841 5,902 -18% 5,577 -13% 4,841 5,902 -18% Non-cash transactions: Additions to property, plant and equipment - capitalized loans and borrowing costs 18 5 260% 5 260% 28 17 65% Cash flow from operating activities Income before income taxes 1,534 2,612 -41% 1,782 -14% 5,761 6,758 -15% Adjusted for: Changes in estimates related to the provision of Brumadinho 8 5 60% 5 60% 7 54 -87% Changes in estimates related to the provision of de characterization of dams 26 (53) n.a. (53) n.a. (30) (118) -75% Equity results and other results in associates and joint ventures 197 (160) n.a. (100) n.a. 61 (151) n.a. Impairment and other results related to non-current assets, net 242 370 -35% (16) n.a. 346 755 -54% Depreciation, depletion and amortization 926 761 22% 911 2% 2,682 2,245 19% Financial results, net (138) 339 n.a. 473 n.a. 301 (13) n.a. Change in assets and liabilities Accounts receivable (390) (207) 88% (259) 51% (768) (50) n.a. Inventories 137 (344) n.a. (255) n.a. (332) (727) -54% Suppliers and contractors 621 105 n.a. 726 -14% 1,085 827 31% Other assets and liabilities, net (118) 215 n.a. (85) 39% (471) (541) -13% Cash generated from operations 3,045 3,643 -16% 3,129 -3% 8,642 9,039 -4% Annexes -26- Reconciliation of IFRS and “non-GAAP” information (a) Adjusted EBIT US$ million 3Q26 3Q25 Δ y/y 2Q26 Δ q/q 9M26 9M25 Δ y/y Net operating revenues 10,599 10,420 2% 10,498 1% 30,355 27,343 11% COGS (7,940) (6,632) 20% (7,294) 9% (21,407) (18,168) 18% Sales and administrative expenses (159) (158) 1% (176) -10% (487) (434) 12% Research and development expenses (189) (151) 25% (185) 2% (505) (433) 17% Pre-operating and stoppage expenses (86) (50) 72% (100) -14% (235) (211) 11% Brumadinho event and dam decharacterization of dams (181) (30) n.a. (101) 79% (347) (165) 110% Other operational expenses, net¹ (209) (238) -12% (503) -58% (905) (583) 55% EBITDA from associates and JV's 328 292 12% 335 -2% 896 786 14% Streaming¹ 238 155 54% 291 -18% 786 490 60% Adjusted EBIT 2,401 3,608 -33% 2,765 -13% 8,151 8,625 -5% ¹ Starting in 3Q25, streaming transactions at market prices, previously reported under "Other operational expenses, net", will be disclosed separately as Streaming. Prior periods were restated. (b) Adjusted EBITDA EBITDA defines profit or loss before interest, tax, depreciation, depletion and amortization. The definition of Adjusted EBITDA for the Company is the operating income or loss plus EBITDA associates and joint ventures, and excluding the amounts charged as (i) depreciation, depletion and amortization and (ii) impairment and gains (losses) on disposal of non-current assets. However, our adjusted EBITDA is not the measure defined as EBITDA under IFRS and may possibly not be comparable with indicators with the same name reported by other companies. Adjusted EBITDA should not be considered as a substitute for operational profit or as a better measure of liquidity than operational cash flow, which are calculated in accordance with IFRS. Vale provides its adjusted EBITDA to give additional information about its capacity to pay debt, carry out investments and cover working capital needs. The following tables shows the reconciliation between adjusted EBITDA and operational cash flow and adjusted EBITDA and net income, in accordance with its statement of changes in financial position. The definition of Adjusted EBIT is Adjusted EBITDA plus depreciation, depletion and amortization. Reconciliation between adjusted EBITDA and operational cash flow US$ million 3Q26 3Q25 Δ y/y 2Q26 Δ q/q 9M26 9M25 Δ y/y Adjusted EBITDA 3,327 4,369 -24% 3,676 -9% 10,833 10,870 0% Working capital: Accounts receivable (390) (207) 88% (259) 51% (768) (50) n.a. Inventories 137 (344) n.a. (255) n.a. (332) (727) -54% Suppliers and contractors 621 105 n.a. 726 -14% 1,085 827 31% Changes in estimates related to the provision of Brumadinho 8 5 60% 5 60% 7 54 -87% Changes in estimates related to the provision of de-characterization of dams 26 (53) n.a. (53) n.a. (30) (118) -75% Others (684) (232) 195% (711) -4% (2,153) (1,817) 18% Cash flow 3,045 3,643 -16% 3,129 -3% 8,642 9,039 -4% Payments of income taxes (including refinancing programs) (240) (558) -57% (271) -11% (832) (1,622) -49% Payment of interest on loans, financing and other financial liabilities (216) (185) 17% (310) -30% (740) (694) 7% Payments related to Brumadinho event (225) (306) -26% (263) -14% (595) (594) 0% Payments related to de-characterization of dams (94) (110) -15% (71) 32% (228) (272) -16% Payments related to participative shareholder's debentures remuneration — — n.a. (139) n.a. (139) (131) 6% Receipts from the settlement of derivatives, net 249 93 168% 337 -26% 702 376 87% Net cash generated by operating activities 2,519 2,577 -2% 2,412 4% 6,810 6,102 12% Annexes -27- Reconciliation between adjusted EBITDA and net income US$ million 3Q26 3Q25 Δ y/y 2Q26 Δ q/q 9M26 9M25 Δ y/y Adjusted EBITDA 3,327 4,369 -24 % 3,676 -9% 10,833 10,870 — % Depreciation, depletion and amortization (926) (761) 22 % (911) 2% (2,682) (2,245) 19 % EBITDA from associates and joint ventures (328) (292) 12 % (335) -2% (896) (786) 14 % Impairment and gains (losses) on disposal of non current assets, net¹ (242) (370) -35 % 16 n.a. (346) (755) -54 % Streaming¹ (238) (155) 54 % (291) -18% (786) (490) 60 % Operating income 1,593 2,791 -43 % 2,155 -26% 6,123 6,594 -7 % Financial results 138 (339) n.a. (473) n.a. (301) 13 n.a. Equity results and other results in associates and joint ventures (197) 160 n.a. 100 n.a. (61) 151 n.a. Income taxes (259) 83 n.a. (368) -30% (1,132) (532) 113 % Net income 1,275 2,695 -53 % 1,414 -10% 4,629 6,226 -26 % Net income attributable to noncontrolling interests 20 10 100 % 39 -49% 106 30 253 % Net income attributable to Vale's shareholders 1,255 2,685 -53 % 1,375 -9% 4,523 6,196 -27 % ¹ Starting in 3Q25, streaming transactions at market prices, previously reported under "Impairment and gains (losses) on disposal of non-current assets, net", are disclosed separately as Streaming. Prior periods were restated. (c) Net debt US$ million 3Q26 3Q25 Δ y/y 2Q26 Δ q/q Gross debt 17,531 17,843 -2% 18,304 -4% Leases 602 700 -14% 634 -5% Cash and cash equivalents (5,036) (6,091) -17% (5,765) -13% Net debt 13,097 12,452 5% 13,173 -1% (d) Gross debt / LTM Adjusted EBITDA US$ million 3Q26 3Q25 Δ y/y 2Q26 Δ q/q Total debt and leases / LTM Adjusted EBITDA (x) 1.2 1.3 -8% 1.2 0% Total debt and leases / LTM operational cash flow (x) 0.8 0.9 -11% 0.8 0% (e) LTM Adjusted EBITDA / LTM interest payments US$ million 3Q26 3Q25 Δ y/y 2Q26 Δ q/q Adjusted LTM EBITDA / LTM gross interest (x) 15.0 15.2 -1% 15.8 -5% LTM adjusted EBITDA / LTM interest payments (x) 14.7 16.0 -8% 16.2 -9% (f) US dollar exchange rates R$/US$ 3Q26 3Q25 Δ y/y 2Q26 Δ q/q Average 5.1366 5.4488 -6% 5.0494 2% End of period 5.1809 5.3186 -3% 5.1766 0% Annexes -28- Revenues and volumes Net operating revenue by business area US$ million 3Q26 % 3Q25 % Δ y/y 2Q26 % Δ q/q 9M26 % 9M25 % Δ y/y Iron Ore Solutions 7,767 73% 8,423 81% -8% 7,888 75% -2% 22,530 74% 21,761 80% 4% Fines 6,428 61% 7,078 68% -9% 6,641 63% -3% 18,761 62% 17,994 66% 4% ROM 27 0% 30 0% -10% 34 0% -21% 81 0% 86 0% -6% Pellets 1,169 11% 1,147 11% 2% 1,062 10% 10% 3,261 11% 3,206 12% 2% Other ferrous products and logistics services 143 1% 168 2% -15% 151 1% -5% 427 1% 475 2% -10% Vale Base Metals 2,832 27% 1,997 19% 42% 2,610 25% 9% 7,825 26% 5,582 20% 40% Copper 1,323 12% 869 8% 52% 1,376 13% -4% 3,911 13% 2,371 9% 65% Nickel 842 8% 662 6% 27% 801 8% 5% 2,406 8% 1,942 7% 24% Gold as by-product¹ 264 2% 270 3% -2% 270 3% -2% 817 3% 604 2% 35% Silver as by-product 30 0% 24 0% 25% 46 0% -35% 122 0% 61 0% 100% PGMs 102 1% 79 1% 29% 53 1% 92% 291 1% 205 1% 42% Cobalt¹ 31 0% 30 0% 3% 37 0% -16% 98 0% 68 0% 44% Others² 240 2% 63 1% 281% 27 0% n.a. 180 1% 331 1% -46% Total 10,599 100% 10,420 100% 2% 10,498 100% 1% 30,355 100% 27,343 100% 11% ¹ Excludes adjustment of US$ 238 million in 3Q26, US$ 291 million in 2Q26, US$ 786 million in 9M26, US$ 155 million in 3Q25 and US$ 490 million in 9M25 to reflect the performance of the streaming transactions at market price. ² Includes marketing activities. Net operating revenue by destination 3Q26 % 3Q25 % Δ y/y 2Q26 % Δ q/q 9M26 % 9M25 % Δ y/y North America 495 5% 404 4% 23% 458 4% 8% 1,425 5% 1,247 5% 14 % USA 363 3% 275 3% 32% 332 3% 9% 999 3% 844 3% 18 % Canada 132 1% 129 1% 2% 126 1% 5% 426 1% 403 1% 6 % South America 839 8% 834 8% 1% 869 8% -3% 2,577 8% 2,517 9% 2 % Brazil 758 7% 782 8% -3% 811 8% -7% 2,352 8% 2,371 9% -1 % Others 81 1% 52 0% 56% 58 1% 40% 225 1% 146 1% 54 % Asia 6,966 66% 7,406 71% -6% 7,016 67% -1% 19,940 66% 18,401 67% 8 % China 4,980 47% 5,695 55% -13% 5,283 50% -6% 14,632 48% 13,910 51% 5 % Japan 592 6% 620 6% -5% 639 6% -7% 1,850 6% 1,785 7% 4 % South Korea 380 4% 219 2% 74% 197 2% 93% 845 3% 705 3% 20 % Others 1,014 10% 872 8% 16% 897 9% 13% 2,613 9% 2,001 7% 31 % Europe 1,829 17% 1,246 12% 47% 1,757 17% 4% 5,194 17% 3,768 14% 38 % Germany 486 5% 307 3% 58% 523 5% -7% 1,480 5% 1,223 4% 21 % Italy 46 0% 50 0% -8% 86 1% -47% 235 1% 214 1% 10 % Others 1,297 12% 889 9% 46% 1,148 11% 13% 3,479 11% 2,331 9% 49 % Middle East 189 2% 268 3% -29% 122 1% 55% 503 2% 692 3% -27 % Rest of the World 281 3% 262 3% 7% 276 3% 2% 716 2% 718 3% 0% Total 10,599 100% 10,420 100% 2% 10,498 100% 1% 30,355 100% 27,343 100% 11% Annexes -29- Operating Expenses US$ million 3Q26 3Q25 Δ y/y 2Q26 Δ q/q 9M26 9M25 Δ y/y SG&A 159 158 1% 176 -10% 487 434 12 % Administrative 138 133 4% 154 -10% 420 369 14 % Personnel 53 55 -4% 51 4% 160 156 3 % Services 47 33 42% 53 -11% 135 85 59 % Depreciation 11 16 -31% 17 -35% 38 47 -19 % Others 27 29 -7% 33 -18% 87 81 7 % Selling 21 25 -16% 22 -5% 67 65 3 % R&D 189 151 25% 185 2% 505 433 17 % Pre-operating and stoppage expenses 86 50 72% 100 -14% 235 211 11 % Expenses related to Brumadinho event and decharacterization of dams 181 30 n.a. 101 79% 347 165 110 % Other operating expenses 209 238 -12% 503 -58% 905 583 55 % Total operating expenses 824 627 31% 1,065 -23% 2,479 1,826 36 % Depreciation 63 28 125% 73 -14% 181 91 99 % Operating expenses, ex-depreciation 761 599 27% 992 -23% 2,298 1,735 32 % Other operating expenses – breakdown by segment US$ million 3Q26 3Q25 Δ y/y 2Q26 Δ q/q 9M26 9M25 Δ y/y Iron Ore Solutions 62 21 195% 17 265% 121 17 n.a. Fines 55 7 n.a. 16 244% 102 (9) n.a. Pellets (1) (2) -50% (2) -50% (1) (3) -67 % Other ferrous products and logistics services 8 16 -50% 3 167% 20 29 -31 % Vale Base Metals 35 56 -38% 43 -19% 112 99 13 % Copper 13 21 -38% 30 -57% 75 33 127 % Nickel 22 21 5% 18 22% 38 38 0% Others — 14 n.a. (5) n.a. (1) 28 n.a. Unallocated items 112 161 -30% 443 -75% 672 467 44 % TOTAL - Other operating expenses 209 238 -12% 503 -58% 905 583 55 % Annexes -30- Financial results US$ million 3Q26 3Q25 Δ y/y 2Q26 Δ q/q 9M26 9M25 Δ y/y Financial expenses, of which: (434) (396) 10% (409) 6% (1,261) (1,182) 7% Gross interest (250) (263) -5% (254) -2% (768) (725) 6 % Capitalization of interest 18 5 260% 5 260% 28 17 65 % Others (186) (115) 62% (142) 31% (467) (409) 14 % Financial expenses (REFIS) (16) (23) -30% (18) -11% (54) (65) -17 % Financial income 110 148 -26% 122 -10% 360 376 -4 % Participative shareholders' debentures (34) (149) -77% 198 n.a. (72) (228) -68 % Derivatives¹ 863 253 241% (62) n.a. 1,526 1,566 -3 % Currency and interest rate swaps 410 226 81% 192 114% 964 1,547 -38 % Others (commodities, etc) 453 27 n.a. (254) n.a. 562 19 n.a. Foreign exchange (24) 148 n.a. (18) 33% 53 351 -85 % Monetary variation (343) (343) 0% (304) 13% (907) (870) 4 % Foreign exchange and monetary variation (367) (195) 88% (322) 14% (854) (519) 65 % Financial result, net 138 (339) n.a. (473) n.a. (301) 13 n.a. ¹ The cash effect of the derivatives was a gain of US$ 249 million in 3Q26. Sustaining Investments by type US$ million Iron Ore Solutions Vale Base Metals Energy and others Total Enhancement of operations 473 166 8 648 Replacement projects 20 24 — 45 Filtration and dry stacking projects 18 — — 18 Dam management 30 23 — 52 Other investments in dams and waste dumps 90 28 — 119 Health and safety 51 15 13 79 Social investments and environmental protection 32 2 — 35 Administrative & others 45 8 16 68 Total 761 266 37 1,064 Annexes -31- Annex 3: Segment information Segment information 3Q26US$ million Net operating revenues Cost¹ SG&A and others¹ R&D¹ Pre operating & stoppage¹ Associates and JVs EBITDA Streaming Adjusted EBITDA Iron Ore Solutions 7,767 (5,187) (90) (92) (50) 285 — 2,633 Fines 6,428 (4,295) (68) (84) (40) 137 — 2,078 Pellets 1,169 (714) 1 (1) (3) 64 — 516 Other ferrous products and logistics services 170 (178) (23) (7) (7) 84 — 39 Vale Base Metals 2,832 (1,891) (72) (45) — 43 238 1,105 Copper² 1,524 (469) (14) (20) — — — 1,021 Salobo 1,304 (379) 15 (2) — — — 938 Sossego 237 (90) (3) (6) — — — 138 Other (17) — (26) (12) — — — (55) Nickel³ 1,339 (1,225) (30) (24) — 38 — 98 Sudbury 681 (667) (5) (3) — — — 6 Voisey’s Bay & Long Harbour 324 (269) — (1) — — — 54 Standalone Refineries 209 (218) — — — — — (9) Onça Puma 118 (96) (3) — — — — 19 Other 7 25 (22) (20) — 38 — 28 Others⁴ (31) (197) (28) (1) — 5 238 (14) Brumadinho and decharacterization of dams — — (181) — — — — (181) Non-recurring expenses — — — — — — — — Unallocated items⁵ — — (193) (35) (2) — — (230) Total 10,599 (7,078) (536) (172) (52) 328 238 3,327 ¹ Excluding depreciation, depletion and amortization. ² Including by-products from our copper operations. ³ Including copper and by-products from our nickel operations. ⁴ Starting in 3Q25, streaming transactions at market prices, previously reported under SG&A and others, are disclosed separately as Streaming. Prior periods were restated. ⁵ Includes US$ 15 million in unallocated expenses from Vale Base Metals Ltd ("VBM") in 3Q26. Considering the unallocated expenses, VBM’s EBITDA was US$ 1.1 billion in 3Q26. Segment information 3Q25 US$ million Net operating revenues Cost¹ SG&A and others¹ R&D¹ Pre operating & stoppage¹ Associates and JVs EBITDA Streaming Adjusted EBITDA Iron Ore Solutions 8,423 (4,531) (54) (84) (42) 260 — 3,972 Fines 7,078 (3,673) (20) (70) (31) 134 — 3,418 Pellets 1,147 (677) 2 (3) (2) 45 — 512 Other ferrous products and logistics services 198 (181) (36) (11) (9) 81 — 42 Vale Base Metals 1,997 (1,368) (92) (39) 2 32 155 687 Copper² 1,086 (437) (22) (13) — — — 614 Salobo 833 (331) (17) — — — — 485 Sossego 255 (106) (2) (4) — — — 143 Other (2) — (3) (9) — — — (14) Nickel³ 1,010 (871) (31) (25) 2 29 — 114 Sudbury 510 (436) (11) (19) — — — 44 Voisey’s Bay & Long Harbour 250 (194) — (10) — — — 46 Standalone Refineries 215 (213) — — — — — 2 Onça Puma 76 (62) (3) — (2) — — 9 Other (41) 34 (17) 4 4 29 — 13 Others⁴ (99) (60) (39) (1) — 3 155 (41) Brumadinho and decharacterization of dams — — (30) — — — — (30) Non-recurring expenses — — — — — — — — Unallocated items⁵ — — (233) (27) — — — (260) Total 10,420 (5,899) (409) (150) (40) 292 155 4,369 ¹ Excluding depreciation, depletion and amortization. ² Including by-products from our copper operations. ³ Including copper and by-products from our nickel operations. ⁴ Starting in 3Q25, streaming transactions at market prices, previously reported under SG&A and others, will be disclosed separately as Streaming. Prior periods were restated. ⁵ Includes US$ 16 million in unallocated expenses from Vale Base Metals Ltd ("VBM") in 3Q25. Considering the unallocated expenses, VBM’s EBITDA was US$ 671 million in 3Q25. Annexes -32- Segment information 2Q26 US$ million Net operating revenues Cost¹ SG&A and others¹ R&D¹ Pre operating & stoppage¹ Associates and JVs EBITDA Streaming Adjusted EBITDA Iron Ore Solutions 7,888 (4,923) (50) (86) (62) 289 — 3,056 Fines 6,641 (4,088) (31) (82) (29) 150 — 2,561 Pellets 1,062 (680) 2 — (27) 59 — 416 Other ferrous products and logistics services 185 (155) (21) (4) (6) 80 — 79 Vale Base Metals 2,610 (1,533) (86) (41) — 48 291 1,289 Copper² 1,555 (479) (30) (20) — — — 1,026 Salobo 1,202 (361) (8) (3) — — — 830 Sossego 423 (118) (8) (6) — — — 291 Other (70) — (14) (11) — — — (95) Nickel³ 1,241 (946) (24) (20) — 43 — 294 Sudbury 610 (483) (8) (1) — — — 118 Voisey’s Bay & Long Harbour 309 (195) — 4 — — — 118 Standalone Refineries 224 (179) — — — — — 45 Onça Puma 138 (93) (4) — — — — 41 Other (40) 4 (11) (23) — 43 — (27) Others⁴ (186) (108) (32) (1) — 5 291 (31) Brumadinho and decharacterization of dams — — (101) — — — — (101) Non-recurring expenses — — (289) — — — — (289) Unallocated items⁵ — — (238) (40) 1 (2) — (279) Total 10,498 (6,456) (764) (167) (61) 335 291 3,676 ¹ Excluding depreciation, depletion and amortization. ² Including by-products from our copper operations. ³ Including copper and by-products from our nickel operations. ⁴ Starting in 3Q25, streaming transactions at market prices, previously reported under SG&A and others, are disclosed separately as Streaming. Prior periods were restated. ⁵ Includes US$ 39 million in unallocated expenses from Vale Base Metals Ltd ("VBM") in 2Q26. Considering the unallocated expenses, VBM’s EBITDA was US$ 1.3 billion in 2Q26. Segment information 9M26 US$ million Net operating revenues Cost¹ SG&A and others¹ R&D¹ Pre operating & stoppage¹ Associates and JVs EBITDA Streaming Adjusted EBITDA Iron Ore Solutions 22,530 (14,107) (212) (244) (143) 771 — 8,595 Fines 18,761 (11,628) (145) (223) (91) 406 — 7,080 Pellets 3,261 (1,981) 2 (2) (32) 163 — 1,411 Other ferrous products and logistics services 508 (498) (69) (19) (20) 202 — 104 Vale Base Metals 7,825 (4,800) (232) (112) — 125 786 3,591 Copper² 4,493 (1,374) (76) (47) — — — 2,996 Salobo 3,523 (1,048) (4) (6) — — — 2,465 Sossego 1,095 (326) (16) (15) — — — 738 Other (125) — (56) (26) — — — (207) Nickel³ 3,764 (3,081) (61) (63) — 111 — 669 Sudbury 1,966 (1,594) (15) (6) — — — 351 Voisey’s Bay & Long Harbour 944 (712) 8 (2) — — — 238 Standalone Refineries 655 (595) — — — — — 60 Onça Puma 414 (292) (10) — — — — 111 Other (215) 112 (44) (55) — 111 — (91) Others⁴ (432) (345) (95) (1) — 14 786 (74) Brumadinho and decharacterization of dams — — (347) — — — — (347) Non-recurring expenses — — (289) — — — — (289) Unallocated items⁵ — — (620) (95) (2) — — (717) Total 30,355 (18,907) (1,700) (451) (145) 896 786 10,833 ¹ Excluding depreciation, depletion and amortization. ² Including by-products from our copper operations. ³ Including copper and by-products from our nickel operations. ⁴ Starting in 3Q25, streaming transactions at market prices, previously reported under SG&A and others, will be disclosed separately as Streaming. Prior periods were restated. ⁵ Includes US$ 71 million in unallocated expenses from Vale Base Metals Ltd ("VBM") in 9M26. Considering the unallocated expenses, VBM’s EBITDA was US$ 3.5 billion in 9M26. Annexes -33- Segment information 9M25 US$ million Net operating revenues Cost¹ SG&A and others¹ R&D¹ Pre operating & stoppage¹ Associates and JVs EBITDA Streaming Adjusted EBITDA Iron Ore Solutions 21,761 (12,141) (114) (222) (159) 711 — 9,836 Fines 17,994 (9,870) (31) (181) (124) 359 — 8,147 Pellets 3,206 (1,813) 4 (6) (6) 140 — 1,525 Other ferrous products and logistics services 561 (458) (87) (35) (29) 212 — 164 Vale Base Metals 5,582 (3,872) (196) (107) (10) 75 490 1,962 Copper² 2,944 (1,178) (34) (33) (1) — — 1,698 Salobo 2,228 (893) (26) (1) (1) — — 1,307 Sossego 617 (285) (3) (8) — — — 321 Other 99 — (5) (24) — — — 70 Nickel³ 2,991 (2,559) (60) (72) (9) 65 — 356 Sudbury 1,538 (1,365) (16) (39) — — — 118 Voisey’s Bay & Long Harbour 684 (647) — (24) — — — 13 Standalone Refineries 607 (575) — — — — — 32 Onça Puma 222 (170) (10) — (5) — — 37 Other (60) 198 (34) (9) (4) 65 — 156 Others⁴ (353) (135) (102) (2) — 10 490 (92) Brumadinho and decharacterization of dams — — (165) — — — — (165) Non-recurring expenses — — — — — — — — Unallocated items⁵ — — (660) (103) — — — (763) Total 27,343 (16,013) (1,135) (432) (169) 786 490 10,870 ¹ Excluding depreciation, depletion and amortization. ² Including by-products from our copper operations. ³ Including copper and by-products from our nickel operations. ⁴ Starting in 3Q25, streaming transactions at market prices, previously reported under SG&A and others, will be disclosed separately as Streaming. Prior periods were restated. Includes US$ 94 million in unallocated expenses from Vale Base Metals Ltd ("VBM") in 9M25. Considering the unallocated expenses, VBM’s EBITDA was US$ 1.9 billion in 9M25. Annexes -34- Annex 4: Additional information by business segment Iron Ore Solutions: Financial results detailed Prices and revenues breakdown 3Q26 3Q25 Δ y/y 2Q26 Δ q/q 9M26 9M25 Δ y/y Average prices (US$/t) Iron ore - 61% Fe price index 96.7 99.4 -3% 105.0 -8% 101.7 98.1 4 % Iron ore - 62% Fe low alumina index 102.2 104.2 -2% 110.3 -7% 106.8 101.6 5 % Iron ore - 65% Fe index 112.7 118.3 -5% 122.1 -8% 118.5 114.8 3 % Provisional price at the end of the quarter 93.4 100.8 -7% 99.0 -6% 93.4 100.8 -7 % Iron ore fines Vale's CFR reference (dmt) 97.0 104.4 -7% 106.0 -8% 103.0 100.6 2 % Iron ore fines realized price, CFR/FOB (wmt) 85.1 94.4 -10% 95.0 -10% 91.6 90.2 2 % Iron ore pellets realized price, CFR/FOB (wmt) 134.0 130.8 2% 137.0 -2% 134.9 135.0 0 % Net operating revenue by product (US$ million) Fines 6,428 7,078 -9% 6,641 -3% 18,761 17,994 4 % ROM 27 30 -10% 34 -21% 81 86 -6 % Pellets 1,169 1,147 2% 1,062 10% 3,261 3,206 2 % Other ferrous products and logistics services 143 168 -15% 151 -5% 427 475 -10 % Total 7,767 8,423 -8% 7,888 -2% 22,530 21,761 4 % Volume sold by destination – Fines, pellets and ROM ‘000 metric tons 3Q26 3Q25 Δ y/y 2Q26 Δ q/q 9M26 9M25 Δ y/y Americas 9,258 9,249 0% 8,901 4% 26,893 27,129 -1 % Brazil 8,116 8,588 -5% 8,094 0% 23,925 24,914 -4 % Others 1,142 661 73% 807 42% 2,968 2,215 34 % Asia 70,475 69,950 1% 64,238 10% 188,610 182,583 3 % China 54,821 55,926 -2% 51,187 7% 146,863 144,464 2 % Japan 5,507 6,010 -8% 5,847 -6% 17,284 17,130 1 % Others 10,147 8,014 27% 7,204 41% 24,463 20,989 17 % Europe 3,624 3,157 15% 3,903 -7% 11,251 10,577 6 % Germany 1,350 898 50% 1,257 7% 3,696 3,117 19 % France 287 — n.a. 366 -22% 750 559 34 % Others 1,987 2,259 -12% 2,280 -13% 6,805 6,901 -1 % Middle East 1,229 1,791 -31% 800 54% 3,260 4,480 -27 % Rest of the World 1,699 1,850 -8% 1,905 -11% 4,731 4,716 0 % Total 86,285 85,997 0% 79,747 8% 234,745 229,485 2 % Annexes -35- Iron ore fines pricing Pricing system breakdown (%) 3Q26 3Q25 Δ y/y 2Q26 Δ q/q Lagged 12 11 9% 12 0% Current 51 58 -12% 58 -12% Provisional 37 31 19% 30 23% Total 100 100 0% 100 0% Price realization US$/t 3Q26 3Q25 Δ y/y 2Q26 Δ q/q Average reference 61% Fe price (dmt) 96.7 99.4 -3% 105.0 -8% Quality and premiums¹ 1.6 3.5 -54% 3.0 -47% Impact of pricing system adjustments (1.3) 1.6 n.a. (2.0) -35% Provisional prices in prior quarter² (0.5) 1.6 n.a. — n.a. Lagged prices 0.5 (0.6) n.a. (0.4) n.a. Current prices (0.1) — n.a. 0.1 n.a. Provisional prices in current quarter³ (1.2) 0.4 n.a. (1.8) -33% CFR reference (dmt) 97.0 104.4 -7% 106.0 -8% Adjustments for FOB sales⁴ (4.4) (2.1) 110% (2.5) 76% Moisture (7.5) (8.0) -6% (8.5) -12% Vale realized price (wmt)⁵ 85.1 94.4 -10% 95.0 -10% 1 Includes quality (US$ 1.7/t) and premiums/discounts and commercial conditions (US$ -0.1/t). 2 Adjustment as a result of provisional prices booked in 2Q26 at US$ 99.0/t. 3 Difference between the weighted average of the prices provisionally set at the end of 3Q26 at US$ 93.4/t based on forward curves and US$ 96.7/t from the 3Q26 average reference price. 4 Includes freight pricing mechanisms of CFR sales freight recognition. 5 Vale’s price is net of taxes. Previous periods were restated. Iron ore fines costs & expenses COGS - 3Q26 vs. 3Q25 US$ million 3Q25 Volume Exchange rate Others Total variation 3Q26 C1 cash costs 1,821 13 60 127 200 2,021 Freight 1,265 16 — 273 289 1,554 Distribution costs 282 2 — 40 42 324 Royalties & others¹ 305 1 — 90 91 396 Total costs before depreciation and amortization 3,673 32 60 530 622 4,295 Depreciation 388 3 12 41 56 444 Total 4,061 35 72 571 678 4,739 ¹ Includes stoppage costs (USD 72MM in 3Q26). Annexes -36- Cash cost and freight 3Q26 3Q25 Δ y/y 2Q26 Δ q/q 9M26 9M25 Δ y/y C1 cash cost (US$ million) C1 cash cost, including third-party purchase costs (A) 2,021 1,821 11% 1,938 4% 5,632 5,003 13% Third-party purchase cost adjustment¹ (B) 493 438 13% 430 15% 1,355 1,236 10% C1 cash cost, ex-third-party purchase costs (C = A – B) 1,528 1,384 10% 1,508 1% 4,278 3,768 14% Sales volumes (Mt) Volume sold² (D) 75.5 75.0 1% 69.9 8% 204.9 199.5 3% Volume sold from third-party purchases (E) 9.2 8.2 12% 7.4 24% 23.4 22.6 4% Volume sold from own operations (F = D – E) 66.3 66.8 -1% 62.5 6% 181.5 176.9 3% C1 cash cost², FOB (US$/t) C1 cash cost, ex-third-party purchase costs (C/F) 23.1 20.7 12% 24.1-4% 23.6 21.3 11% Average third-party purchase C1 cash cost (B/E) 53.5 53.4 0% 58.0-8% 57.9 54.8 6% Iron ore cash cost (A/D) 26.8 24.3 10% 27.7-3% 27.5 25.1 10% Freight Maritime freight costs (G) 1,554 1,265 23% 1,376 13% 3,884 3,307 17% CFR sales (%) (H) 90% 90% — p.p. 89% 1 p.p. 90% 89 1 p.p. Volume CFR (Mt) (I = D x H) 68.2 67.3 1% 62.5 9% 183.5 170.0 8% Freight unit cost (US$/t) (G/I) 22.8 18.8 21% 22.0 4% 21.2 18.6 14% 1 Includes logistics costs related to third-party purchases. 2 Excludes ROM, royalties and distribution costs. Expenses US$ million 3Q26 3Q25 Δ y/y 2Q26 Δ q/q 9M26 9M25 Δ y/y SG&A 10 12 -17% 13 -23% 35 37 -5 % R&D 84 70 20% 82 2% 223 181 23 % Pre-operating and stoppage expenses 40 31 29% 29 38% 91 124 -27 % Other expenses 58 8 n.a. 18 222% 110 (6) n.a. Total expenses 192 121 59% 142 35% 459 336 37% Annexes -37- Iron Ore Solutions: Project Details Growth projects Capex 3Q26 Financial Progress¹ Physical Progress Comments Serra Sul +20 Capacity: 20 Mtpy Start-up: 2H26 Capex: US$ 2,844 million 83 74% 90% Commissioning of the Long-Distance Conveyor Belt began in July 2026. At the plant, no-load commissioning of equipment in the Secondary Crushing building has commenced. In the Classification building, equipment installation is progressing according to plan. Sustaining Projects Capex 3Q26 Financial Progress¹ Physical Progress Comments Compact Crushing S11D Capacity: 50 Mtpy Start-up: 4Q26 Capex: US$ 755 million 28 82% 99% Start-up in 3Q26. 1 CAPEX disbursement until end of 3Q26 vs. CAPEX expected. Projects under evaluation Apolo Capacity: 14 Mtpy Stage: FEL2 Southeastern System (Brazil) Growth project Vale’s ownership: 100% Open pit mine Briquette plants Capacity: Under evaluation Stage: 1 plant under construction, 1 plant at FEL2; 2 plants at different stages of FEL Brazil and other regions Growth project Investment decision: 2027-2030 Vale’s ownership: N/A Cold agglomeration plant Itabira mines Capacity: 25 Mtpy Stage: projects at different phases of FEL1 and FEL2 Southeastern System (Brazil) Replacement project Vale’s ownership: 100% Open pit mine Diverse pits, tailing and waste stockpile projects aimed at maintaining Itabira´s long-term production volumes. Mega Hubs Capacity: Under evaluation Stage: Pre-feasibility Study Middle East Growth project Vale’s ownership: N/A Industrial complexes for iron ore concentration and agglomeration and production of direct reduction metallics Vale continues to advance in negotiations with world class players and jointly study the development of Mega Hubs S11C Capacity: Under evaluation Stage: FEL2 Northern System (Brazil) Replacement project Vale’s ownership: 100% Open pit mine Serra Norte N1/N2¹ Capacity: 10 Mtpy Stage: FEL2 Northern System (Brazil) Replacement project Vale’s ownership: 100% Open pit mine Serra Leste expansion Capacity: 10 Mtpy (+4 Mtpy) Stage: Engineering Northern System (Brazil) Growth Project Vale’s ownership: 100% Open pit mine expansion. The project will be implemented in stages until it reaches full capacity Part of the expansion capacity is already under construction, including the upgrading of Plants II and III and the construction of the Tunnel. 1 Project scope is under review given permitting constraints. Annexes -38- Vale Base Metals: Copper Revenues & price realization 3Q26 3Q25 Δ y/y 2Q26 Δ q/q 9M26 9M25 Δ y/y Volume sold Copper ('000 metric tons) 70 70 —% 78 -10% 219 197 11 % Gold as by-product (‘000 oz) 102 104 -2% 101 1% 301 297 1 % Silver as by-product (‘000 oz) 317 342 -7% 330 -4% 891 907 -2 % Average prices Average LME copper price (US$/t) 14,104 9,797 44% 13,329 6% 13,434 9,556 41 % Average copper realized price (US$/t) 15,314 9,818 56% 14,062 9% 14,159 9,252 53 % Gold (US$/oz)¹ 4,400 3,706 19% 4,977 -12% 4,781 3,316 44 % Silver (US$/oz) 71 39 82% 84 -15% 80 35 129 % Net revenue (US$ million) Copper 1,068 688 55% 1,093 -2% 3,106 1,826 70 % Gold as by-product¹ 450 387 16% 505 -11% 1,440 988 46 % Silver as by-product 22 13 69% 28 -21% 71 31 129 % Total 1,540 1,088 42% 1,626 -5% 4,617 2,844 62% Provisional price adjustments2 (16) (2) n.a. (71) -77% (124) 100 n.a. Net revenue after provisional price adjustments 1,524 1,086 40% 1,555 -2% 4,493 2,944 53% 1 Revenues presented were adjusted to reflect the market prices of products delivered related to the streaming transactions. 2 On September 30, 2026, Vale had provisionally priced copper sales from Sossego and Salobo totaling 79,016 tons valued at weighted average LME forward price of US$ 14,445/t, subject to final pricing over the following months. Breakdown of copper realized prices US$/t 3Q26 3Q25 Δ y/y 2Q26 Δ q/q 9M26 9M25 Δ y/y Average LME copper price 14,104 9,797 44% 13,329 6% 13,434 9,556 41 % Current period price adjustments¹ (152) (63) 141% (179) -15% (332) (66) n.a. Copper gross realized price 13,952 9,733 43% 13,150 6% 13,103 9,491 38 % Prior period price adjustments² 1,310 221 n.a. 1,012 29% 1,142 (29) n.a. Copper realized price before discounts 15,262 9,954 53% 14,162 8% 14,244 9,462 51 % TC/RCs, penalties, premiums and discounts³ 52 (136) n.a. (100) n.a. (85) (210) -60 % Average copper realized price 15,314 9,818 56% 14,062 9% 14,159 9,252 53 % Note: Vale's copper products are sold on a provisional pricing basis, with final prices determined in a future period. The average copper realized price excludes the mark-to-market of open invoices based on the copper price forward curve (unrealized provisional price adjustments) and includes the prior and current period price adjustments (realized provisional price adjustments). 1 Current period price adjustments: Final invoices that were provisionally priced and settled within the quarter. 2 Prior-period price adjustment: Final invoices of sales provisionally priced in prior quarters. 3 TC/RCs, penalties, premiums, and discounts for intermediate products. Annexes -39- Vale Base Metals: Nickel Revenues & price realization 3Q26 3Q25 Δ y/y 2Q26 Δ q/q 9M26 9M25 Δ y/y Volume sold ('000 metric tons) Nickel 50 43 16% 44 14% 139 123 13 % Copper 17 20 -15% 20 -15% 56 64 -13 % Gold as by-product ('000 oz) 9 9 0% 8 13% 26 29 -10 % Silver as by-product ('000 oz) 164 245 -33% 191 -14% 600 825 -27 % PGMs ('000 oz) 62 43 44% 39 59% 145 156 -7 % Cobalt (metric ton) 779 908 -14% 920 -15% 2,364 2,256 5 % Average realized prices (US$/t) Nickel 16,898 15,445 9% 18,061 -6% 17,307 15,773 10 % Copper 15,322 9,114 68% 14,260 7% 14,449 8,588 68 % Gold (US$/oz) 4,153 3,488 19% 4,554 -9% 4,597 3,329 38 % Silver (US$/oz) 46 42 10% 97 -53% 85 36 136 % Cobalt 60,768 39,572 54% 62,046 -2% 60,081 34,756 73 % Net revenue by product (US$ million) Nickel 842 663 27% 801 5% 2,406 1,943 24 % Copper 254 180 41% 283 -10% 805 545 48 % Gold as by-product¹ 38 32 19% 36 6% 120 97 24 % Silver as by-product 8 10 -20% 18 -56% 51 29 76 % PGMs 102 79 29% 53 92% 291 206 41 % Cobalt¹ 47 36 31% 57 -18% 142 78 82 % Others 18 12 50% 10 80% 41 33 24 % Total 1,309 1,012 29% 1,259 4% 3,856 2,931 32 % Provisional price adjustments 30 (2) n.a. (17) n.a. (92) 60 n.a. Net revenue after provisional price adjustments 1,339 1,010 33% 1,241 8% 3,764 2,991 26 % 1 Revenues presented above were adjusted to reflect the market prices of products delivered related to the streaming transactions. Breakdown of nickel volumes sold, realized price and premium 3Q26 3Q25 Δ y/y 2Q26 Δ q/q 9M26 9M25 Δ y/y Volumes (kt) Class I nickel 33.7 30.7 10% 29.5 14% 94.2 90.9 4 % Class II nickel 15.8 11.7 35% 14.4 10% 43.4 31.0 40 % Intermediates 0.3 0.5 -40% 0.4 -25% 1.3 1.3 0 % Total 49.8 42.9 16% 44.4 12% 139.0 123.2 13 % Nickel realized price (US$/t) LME average nickel price 16,573 15,015 10% 18,131 -9% 17,337 15,251 14 % Average nickel realized price 16,898 15,445 9% 18,061 -6% 17,307 15,773 10 % Contribution to the nickel realized price by category: Nickel average aggregate premium/(discount) 277 444 -38% 78 255% 122 467 -74 % Other timing and pricing adjustments contributions¹ 49 (14) n.a. (148) n.a. (152) 56 n.a. 1 Comprises (i) the realized quotational period effects (based on sales distribution in the prior three months, as well as the differences between the LME price at the moment of sale and the LME average price), with a negative impact of US$ 1/t and (ii) fixed-price sales, with a positive impact of US$ 50/t. Product type by operation % of sales North Atlantic¹ Matsusaka Onça Puma Class I nickel 97.1 — — Class II nickel 2.9 96.7 97.7 Intermediates — 3.3 2.3 1 Comprises Sudbury, Clydach and Long Harbour refineries. Annexes -40- Vale Base Metals: Project Details Growth projects Capex 3Q26 Financial progress¹ Physical progress Comments Salobo CPF - Copper Capacity: 30 ktpy Start-up: 1H28 Capex: US$ 215 million 12 5% 17% Project sanction announced in August 2026. Critical equipment contracts awarded and mobilized. Clarabelle Mill Expansion Phase 1 & 2 (Sudbury Fill the Mill) - Nickel Capacity: 7.2 Mtpy (+2 Mtpy) Start-up: 1Q27 Capex: US$ 110 million 11 69% 88% Production related equipment online. Completing scope on support equipment and punch list items. Sustaining projects Capex 3Q26 Financial progress¹ Physical progress Comments Bacaba - Copper Capacity: 50 ktpy Start-up: 3Q27 Capex: US$ 290 million 29 29% 62% Pre-stripping bridge and infrastructure activities are progressing ahead of schedule with construction ongoing. 1 CAPEX disbursement until end of 3Q26 vs. Capex expected. 2 VBM Capex of US$ 175 million with US$ 40 million in funding from Wheaton Precious Metals. Projects under evaluation Copper Alemão Capacity: ~80 ktpy Stage: FEL3 Carajás, Brazil Growth project Investment decision: 2027 Vale Base Metals ownership: 100% Underground mine and processing plant 140 kozpy Au as by-product South Hub extension (118 / Cristalino) Capacity: 60-80 ktpy Stage: FEL2-FEL3 Carajás, Brazil Replacement project Vale Base Metals ownership: 100% Open pit mines NRSE1 Capacity: ~25 ktpy Stage: FEL3 Ontario, Canada Growth project Investment decision: 2027 Vale Base Metals ownership: 50% Underground mine and processing plant 5 ktpy Ni as co-product; JV partnership under discussion Hu’u Capacity: 300-350 ktpy Stage: FEL2 Dompu, Indonesia Growth project 200 kozpy Au as by-product Vale Base Metals ownership: 80% Underground mine (block cave) and processing plant Paulo Afonso (North Hub) Capacity: 70-100 ktpy Stage: FEL2 Carajás, Brazil Growth project Vale Base Metals ownership: 100% Open pit mine and Processing plant Nickel CCM Pit Capacity: 12-15 ktpy Stage: FEL3 Ontario, Canada Replacement project Investment decision: 2026-2027 Vale Base Metals ownership: 100% Open pit mine 7-9 ktpy Cu as by-product 1 Nickel Rim South Extension - this was project Victor in previous reports. Figures reflect expected 50% equity basis in JV partnership under discussion. Annexes -41- Annex 5: Brumadinho, Samarco & Dam Decharacterization Brumadinho & Dam decharacterization US$ million Provisions balance 30Jun26 EBITDA impact² Payments FX and other adjustments³ Provisions balance 30Sep26 Decharacterization 2,124 26 (94) 37 2,093 Agreements & donations¹ 1,774 8 (225) 54 1,611 Total Provisions 3,898 34 (319) 91 3,704 Incurred Expenses — 147 (147) — — Total 3,898 181 (466) 91 3,704 1 Includes Integral Reparation Agreement, individual, labor and emergency indemnifications, tailing removal and containment works. 2 Includes the revision of estimates for provisions and incurred expenses, including discount rate effect. 3 Includes foreign exchange, present value and other adjustments. Impact of Brumadinho and Decharacterization from 2019 to 3Q26 US$ million EBITDA impact Payments FX and other adjustments² Provisions balance 30Sep26 Decharacterization 4,770 (2,735) 58 2,093 Agreements & donations¹ 9,539 (8,710) 782 1,611 Total Provisions 14,309 (11,445) 840 3,704 Incurred expenses 4,015 (4,015) — — Others 180 (178) (2) — Total 18,504 (15,638) 838 3,704 ¹ Includes Integral Reparation Agreement, individual, labor and emergency indemnifications, tailing removal and containment works. ² Includes foreign exchange, present value and other adjustments. Cash outflow related to Brumadinho commitments (included in the expanded net debt)1 2 US$ billion Disbursed from 2019 to 3Q26 4Q26 2027 2028 Yearly average 2029-2031 Integral Reparation Agreement & other reparation provisions (8.7) 0.3 0.7 0.4 0.1 1 Estimate cash outflow given BRL-USD exchange final rate of September, 30th of 5.1809. 2 Amounts stated without discount to present value, net of judicial deposits and inflation adjustments. Cash outflow related to Samarco commitments (included in the expanded net debt)1 2 3 Already disbursed 4Q26 2027 2028 2029 2030 2031 Yearly average 2032-2043 Mariana reparation and others – 100% 84.5 1.6 8.7 6.7 9.7 9.9 7.3 5.5 Vale’s contribution (R$ billion) 0.8 4.3 2.6 3.9 3.5 — — Vale’s contribution (US$ billion)³ 0.1 0.8 0.5 0.8 0.7 — — 1 Amounts stated in real terms. 2 Estimate cash outflow given BRL-USD exchange final rate of September, 30th of 5.1809. 3 Including other Samarco commitments and UK claim provisions. Cash outflow of decharacterization and incurred expenses (not included in the expanded net debt)1 2 US$ billion Disbursed from 2019 to 3Q26 4Q26 2027 2028 Yearly average 2029-2035 Decharacterization (2.7) 0.1 0.4 0.5 0.2 Incurred expenses (4.0) 0.1 0.3 0.3 0.2 Total (6.7) 0.2 0.7 0.8 — 1 Estimate cash outflow for 2026-2035 period, given BRL-USD exchange final rate of September, 30th of 5.1809. ² Amounts stated without discount to present value, net of judicial deposits and inflation adjustments. ³ Estimate annual average cash flow for Decharacterization provisions in the 2029-2035 period is US$ 248 million per year. ⁴ Disbursements related to incurred expenses ending in 2030. Annexes -42-
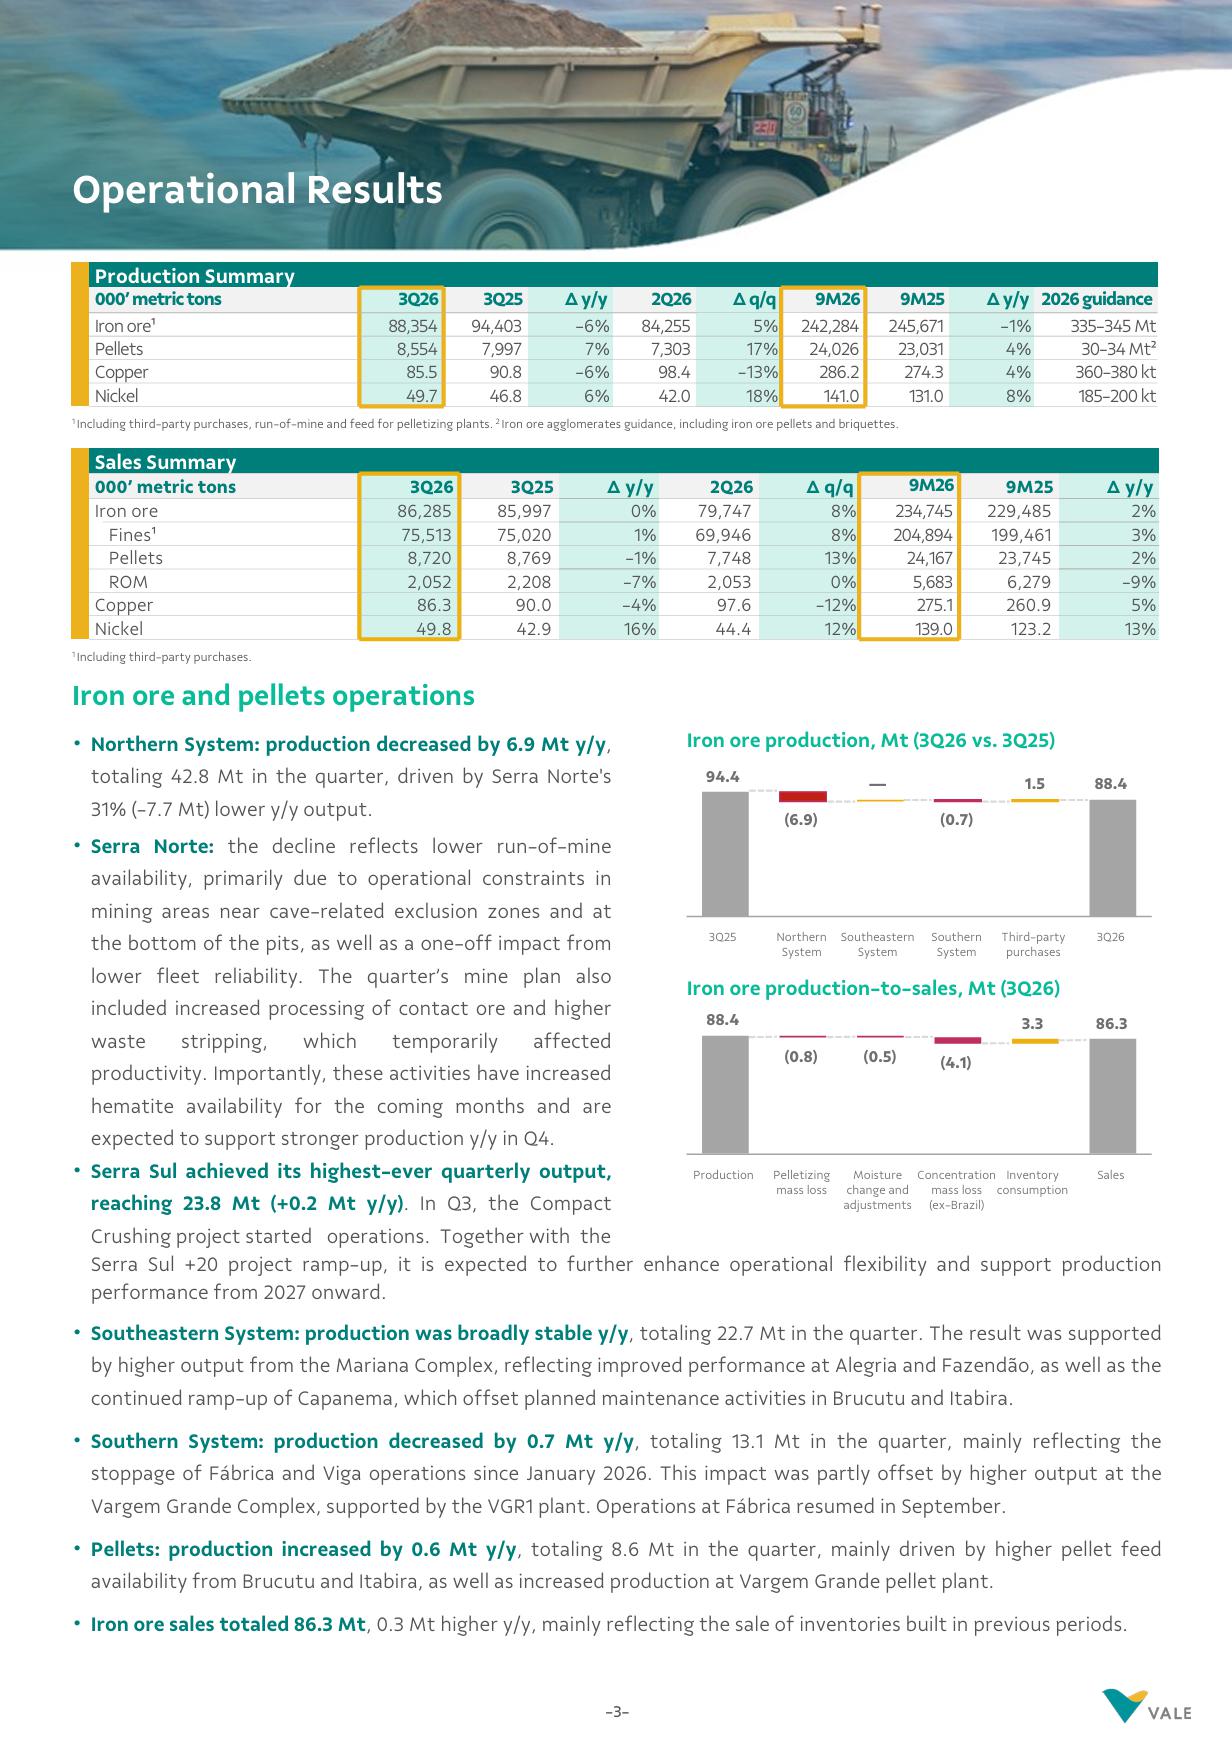
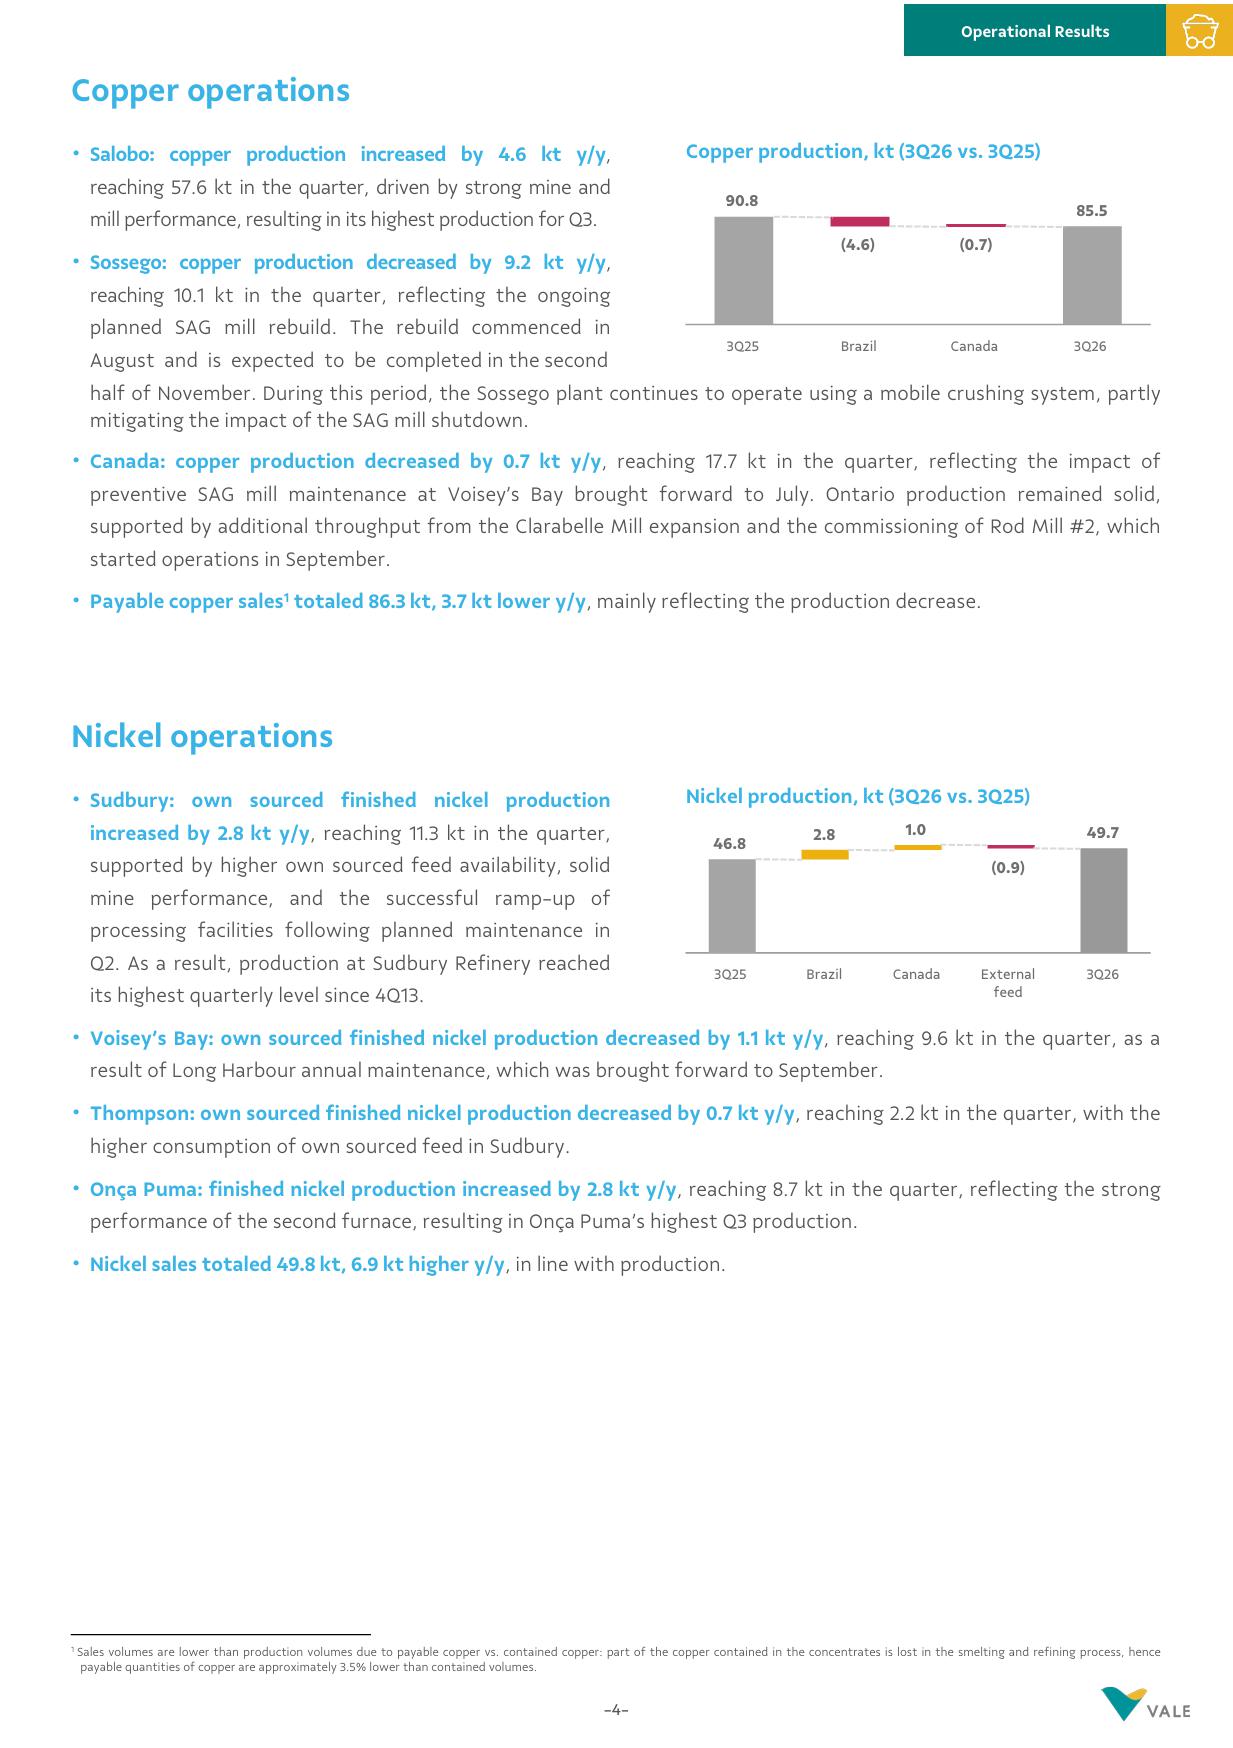
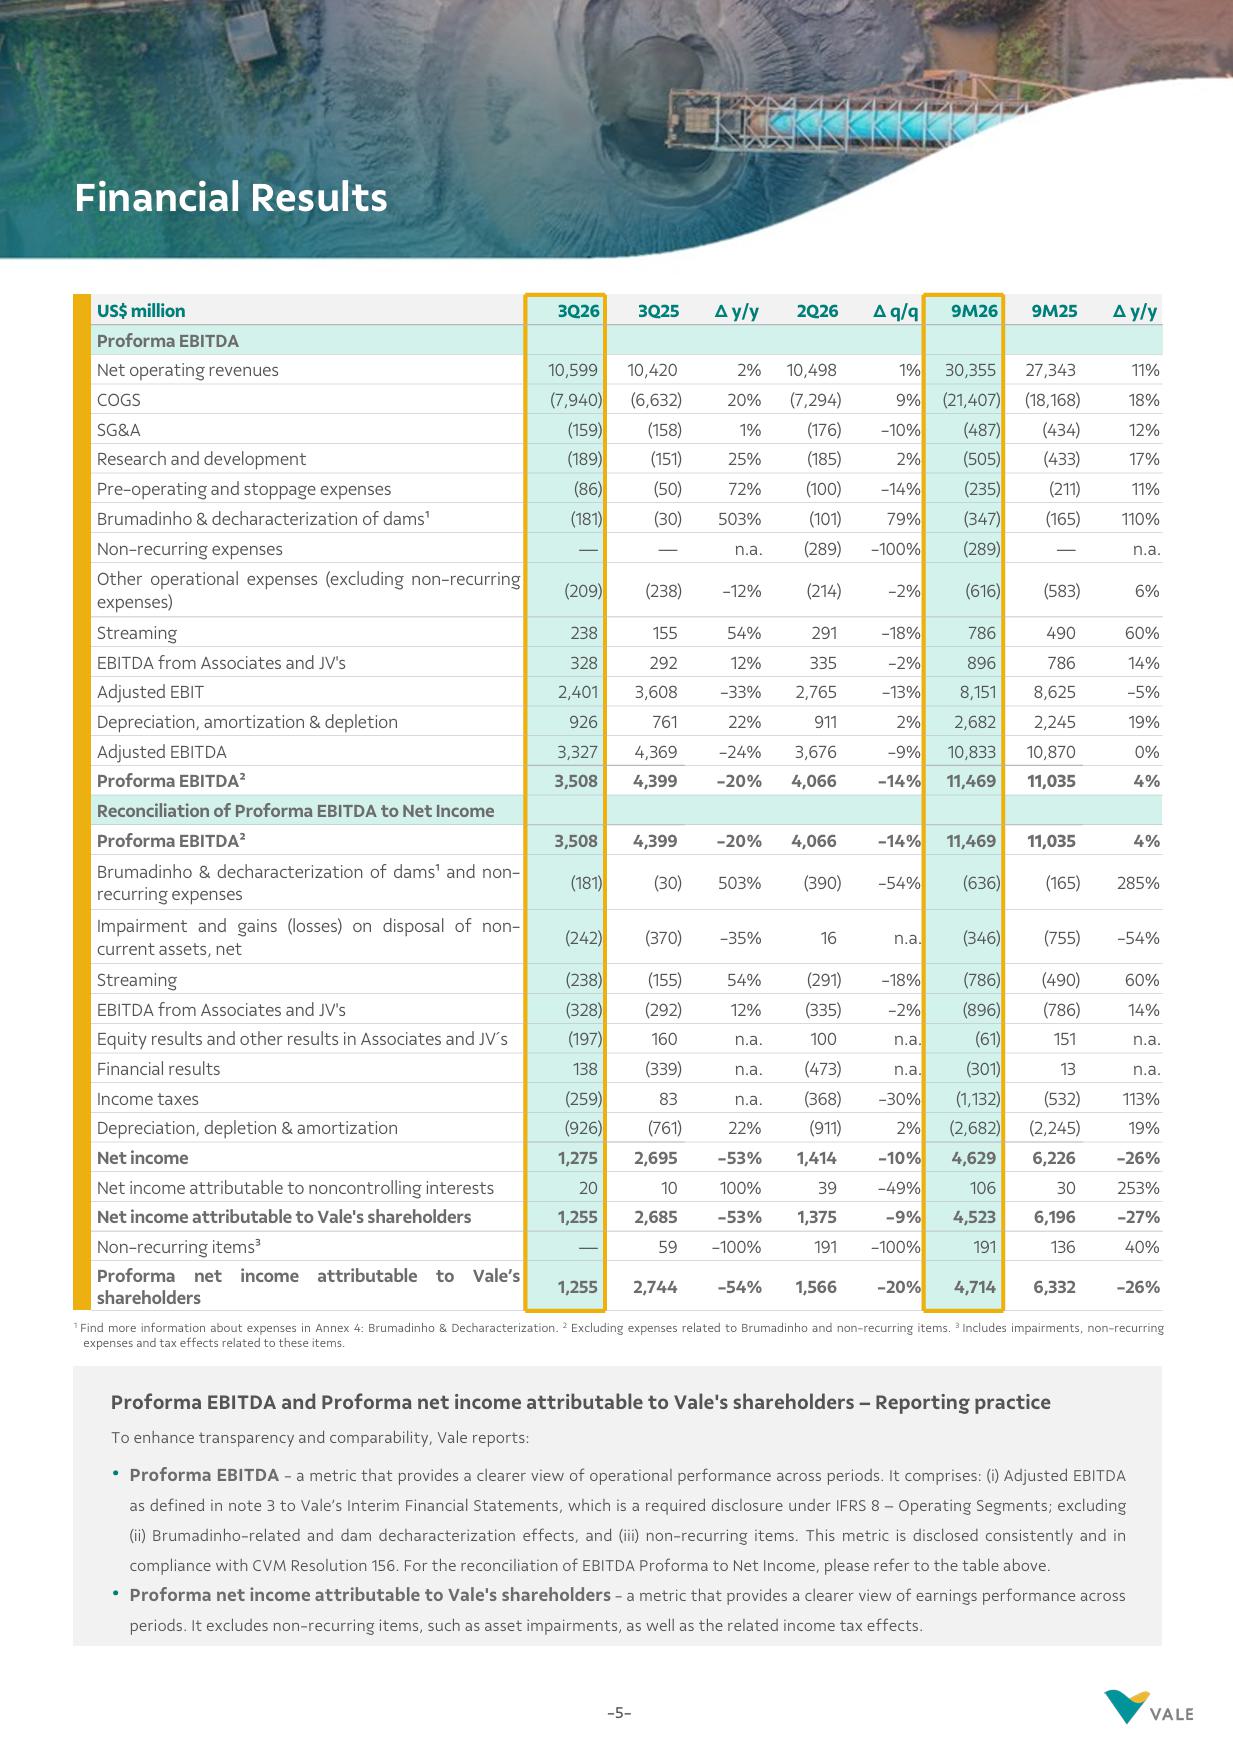
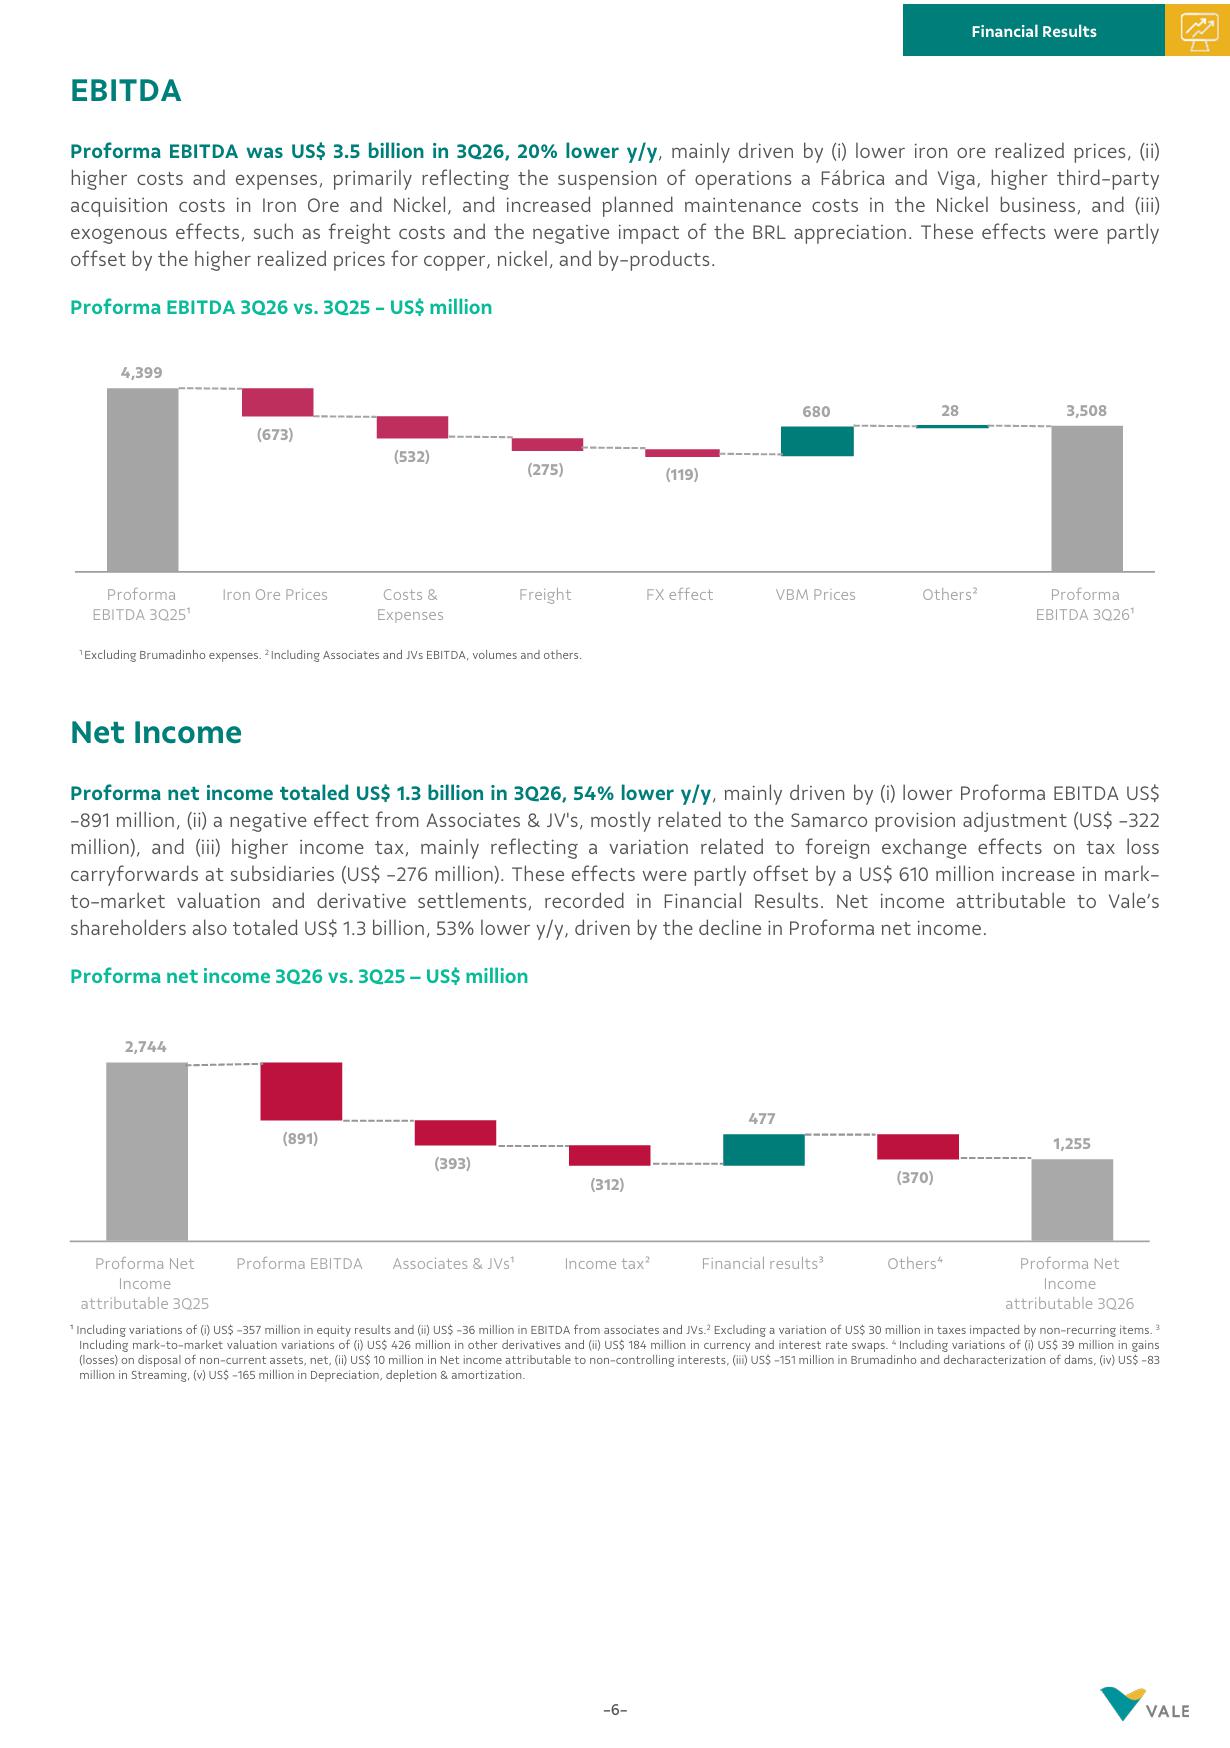
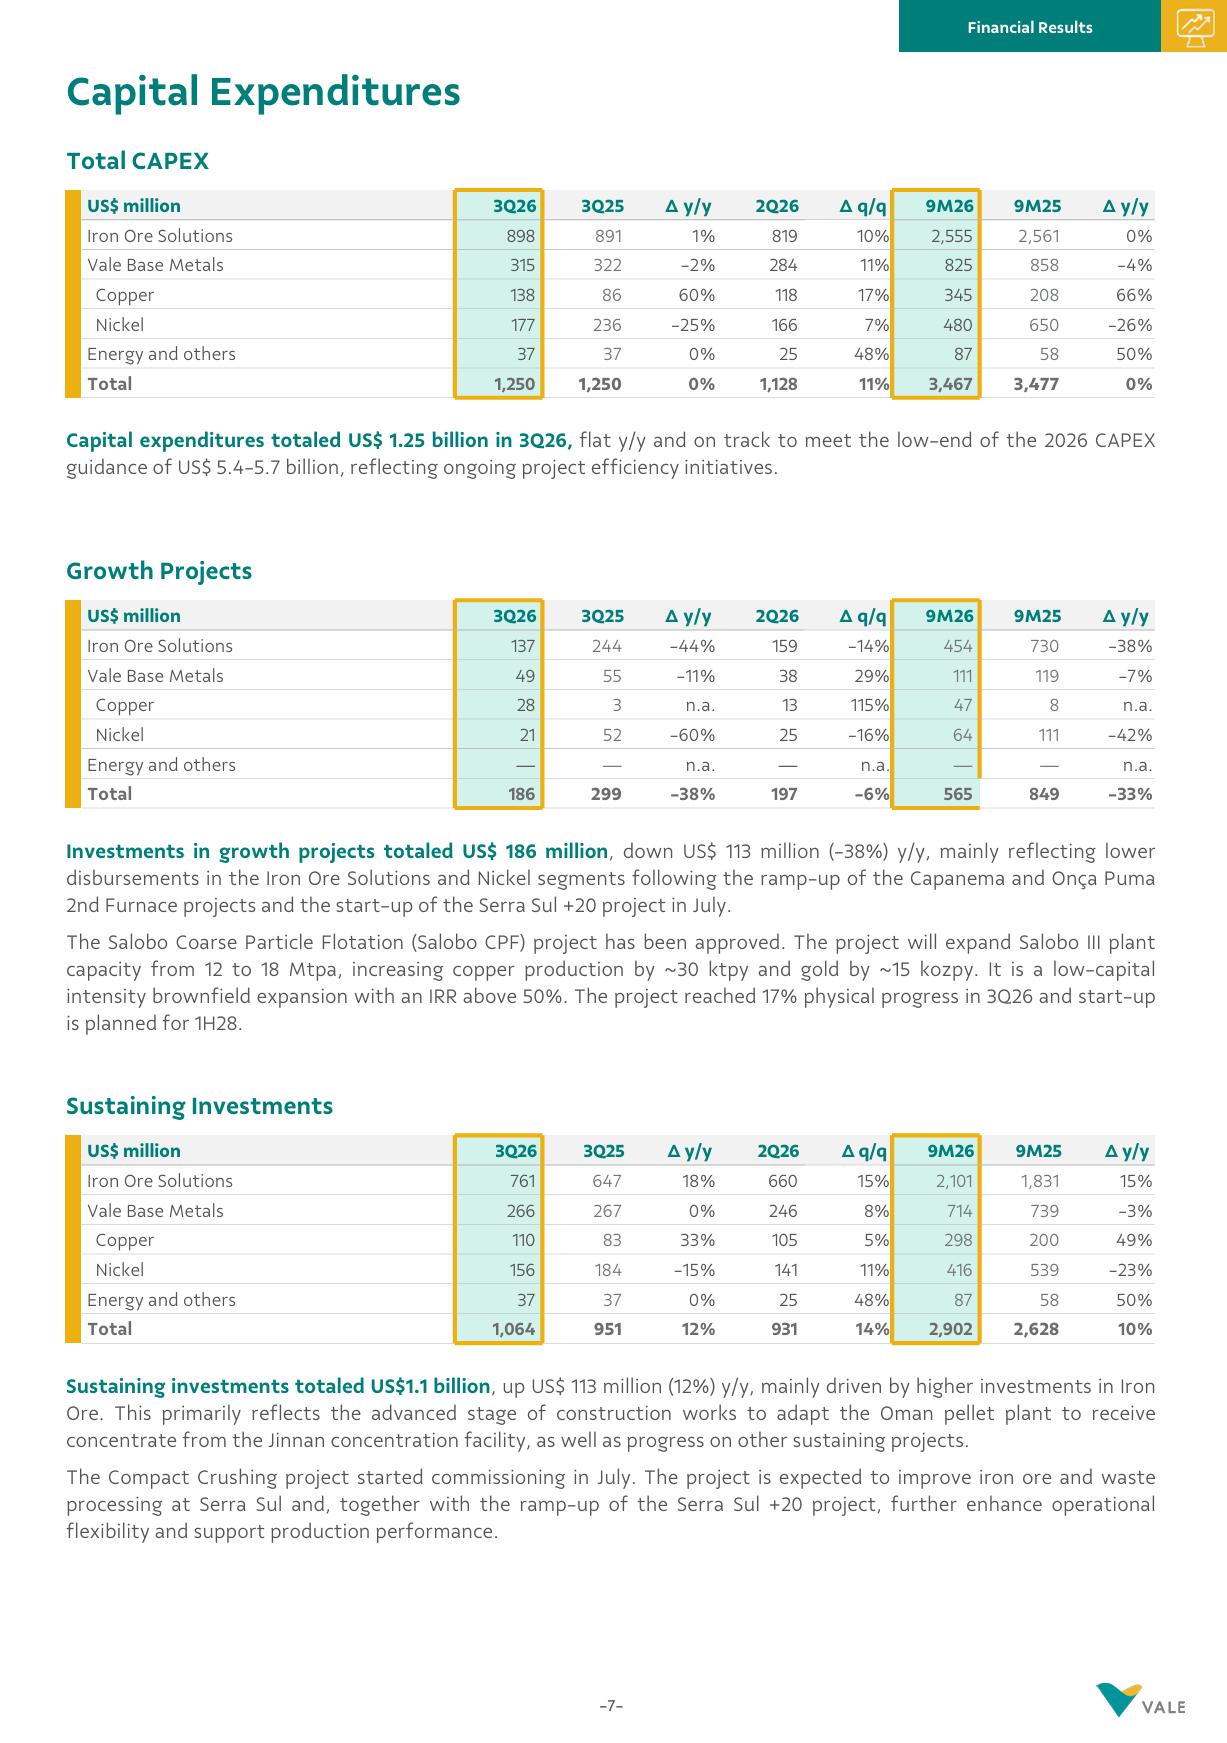
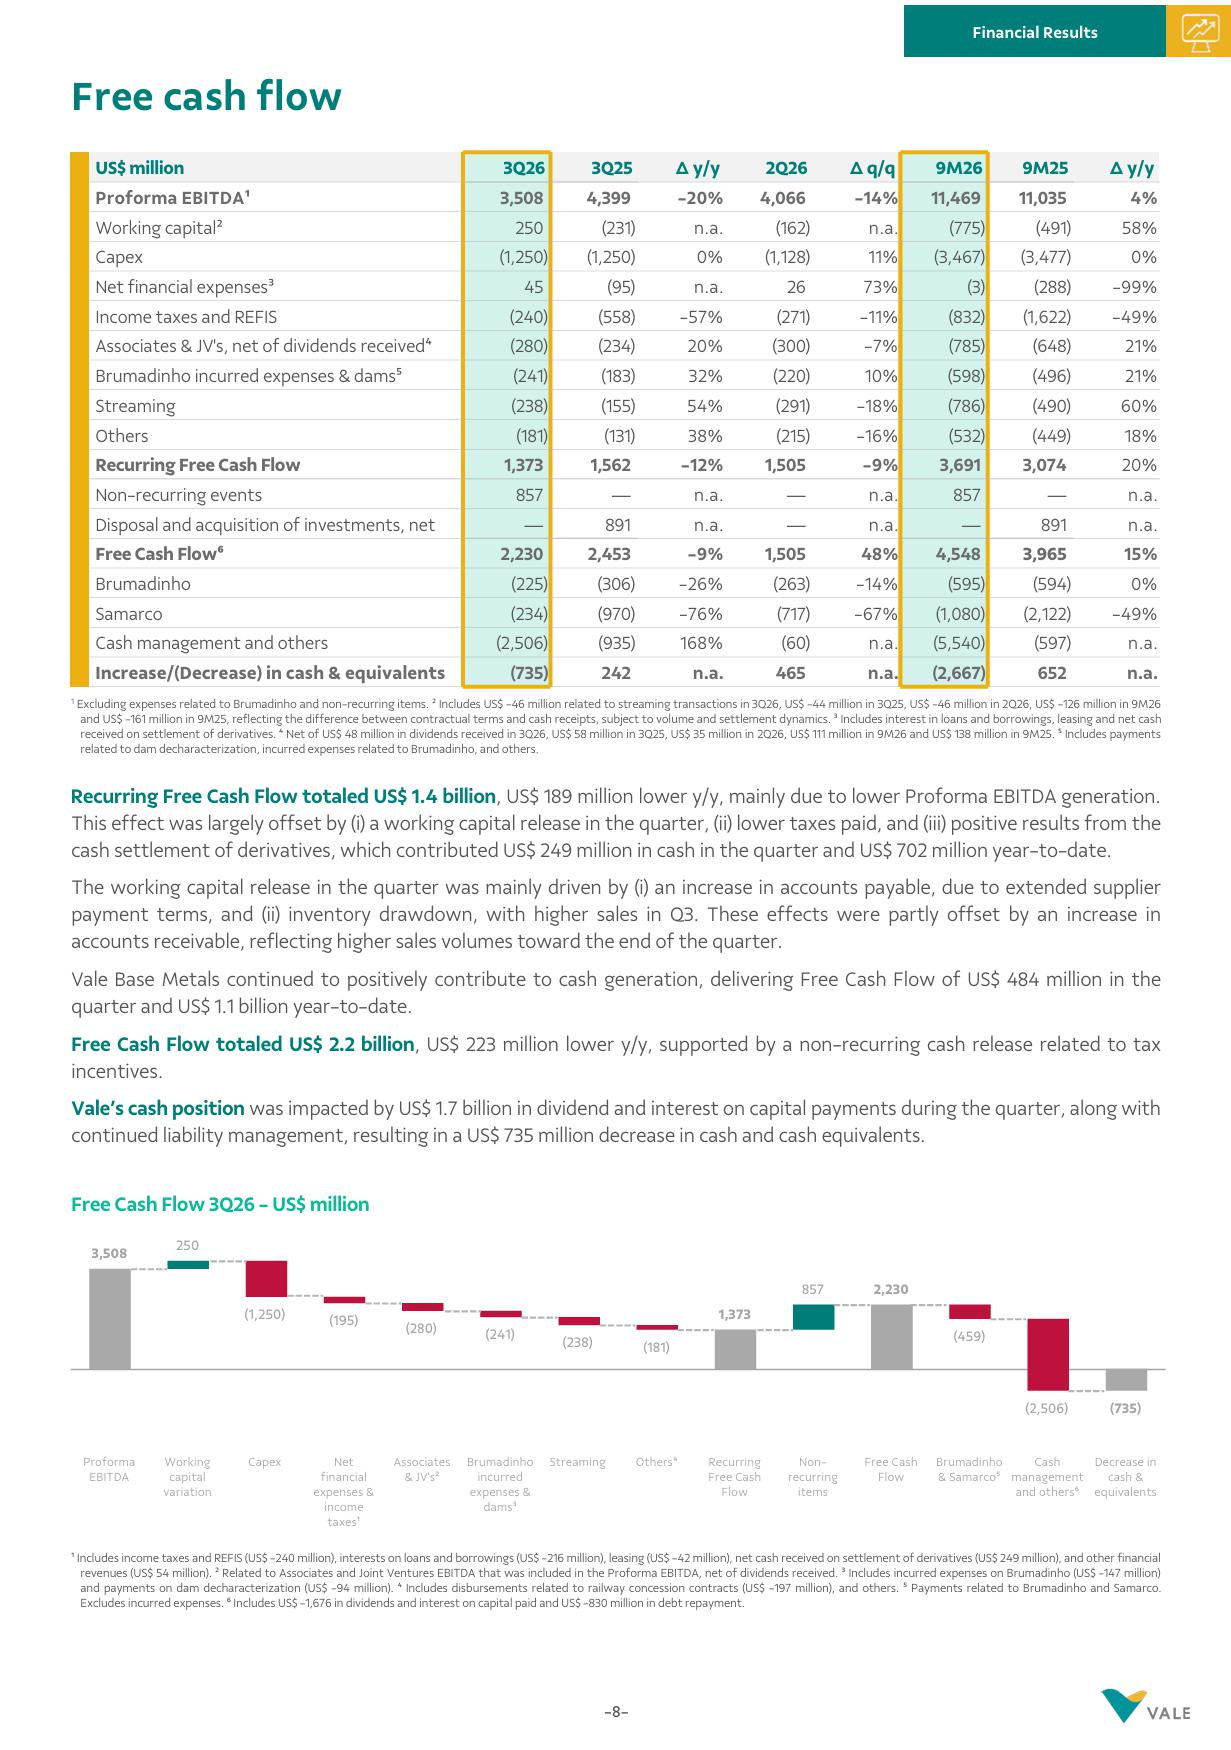
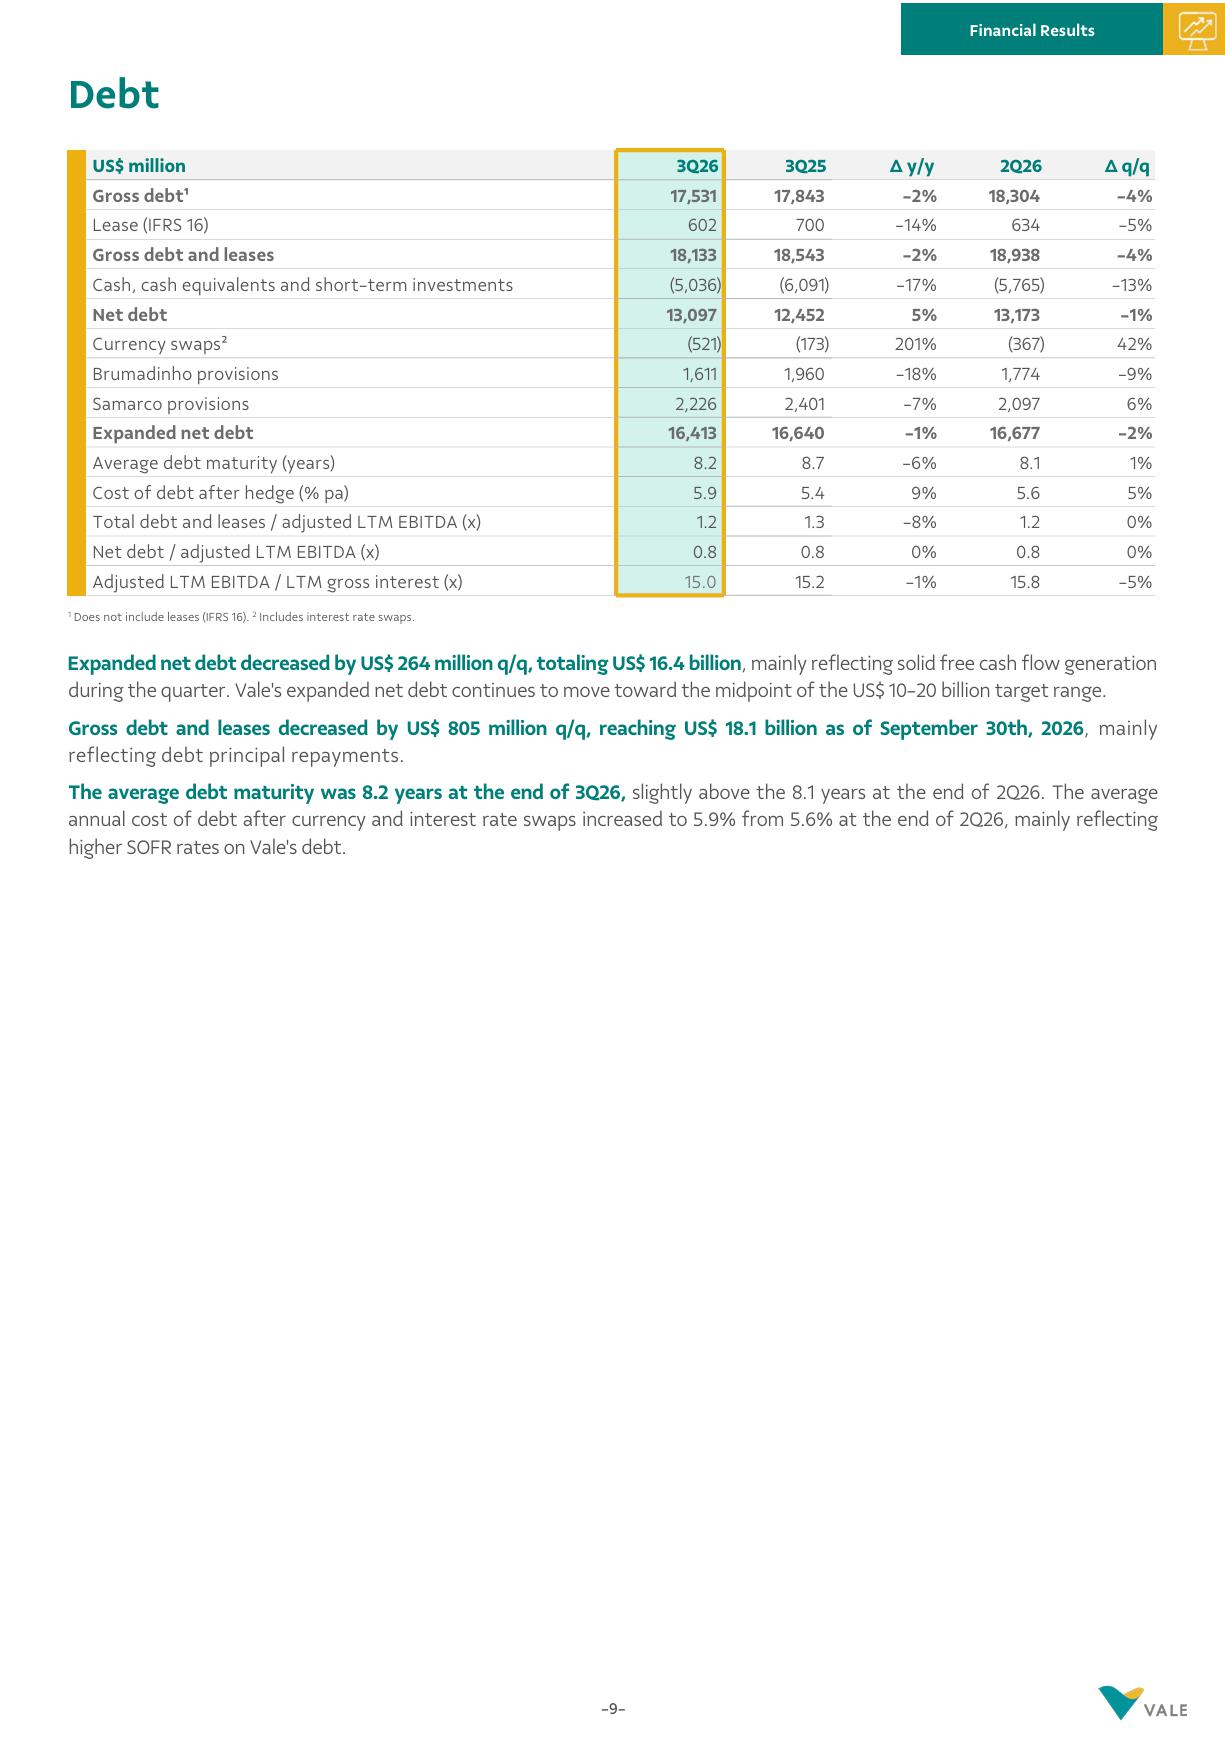
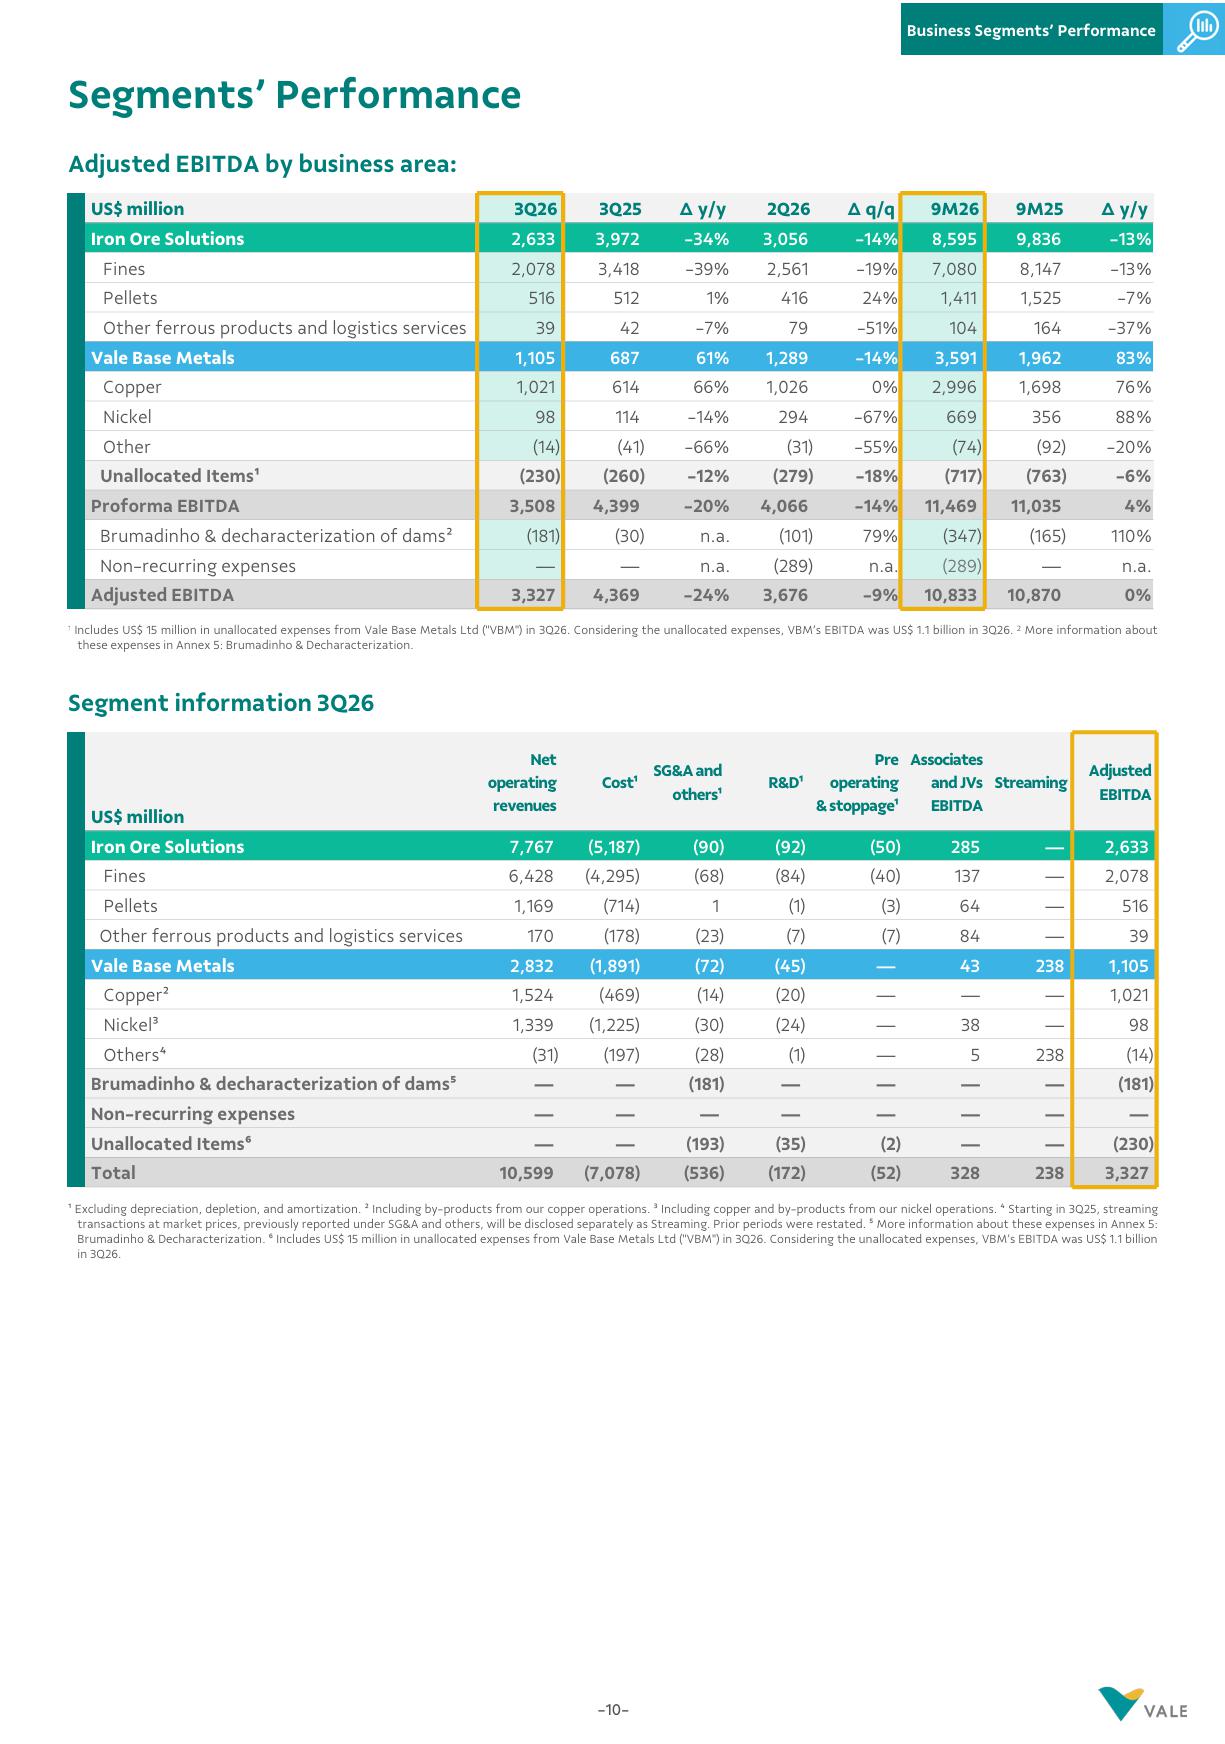
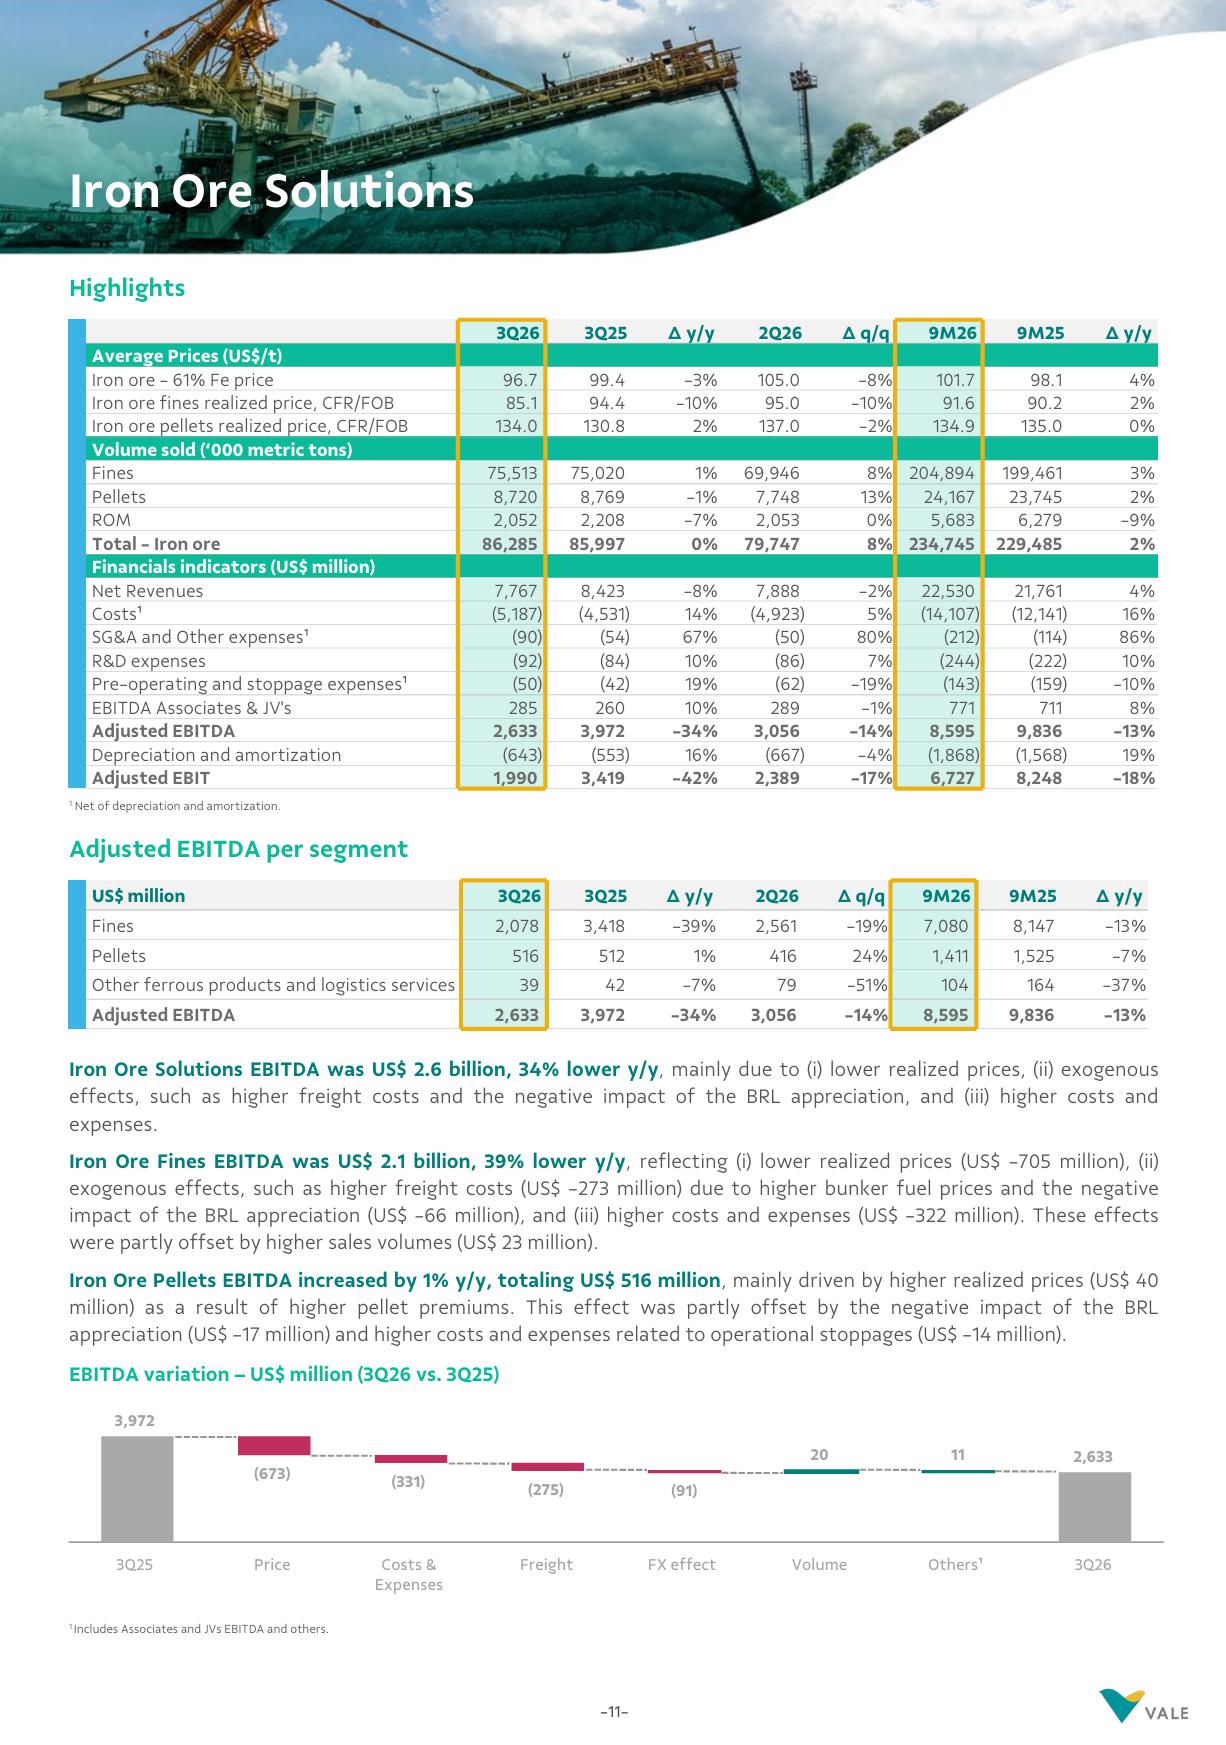
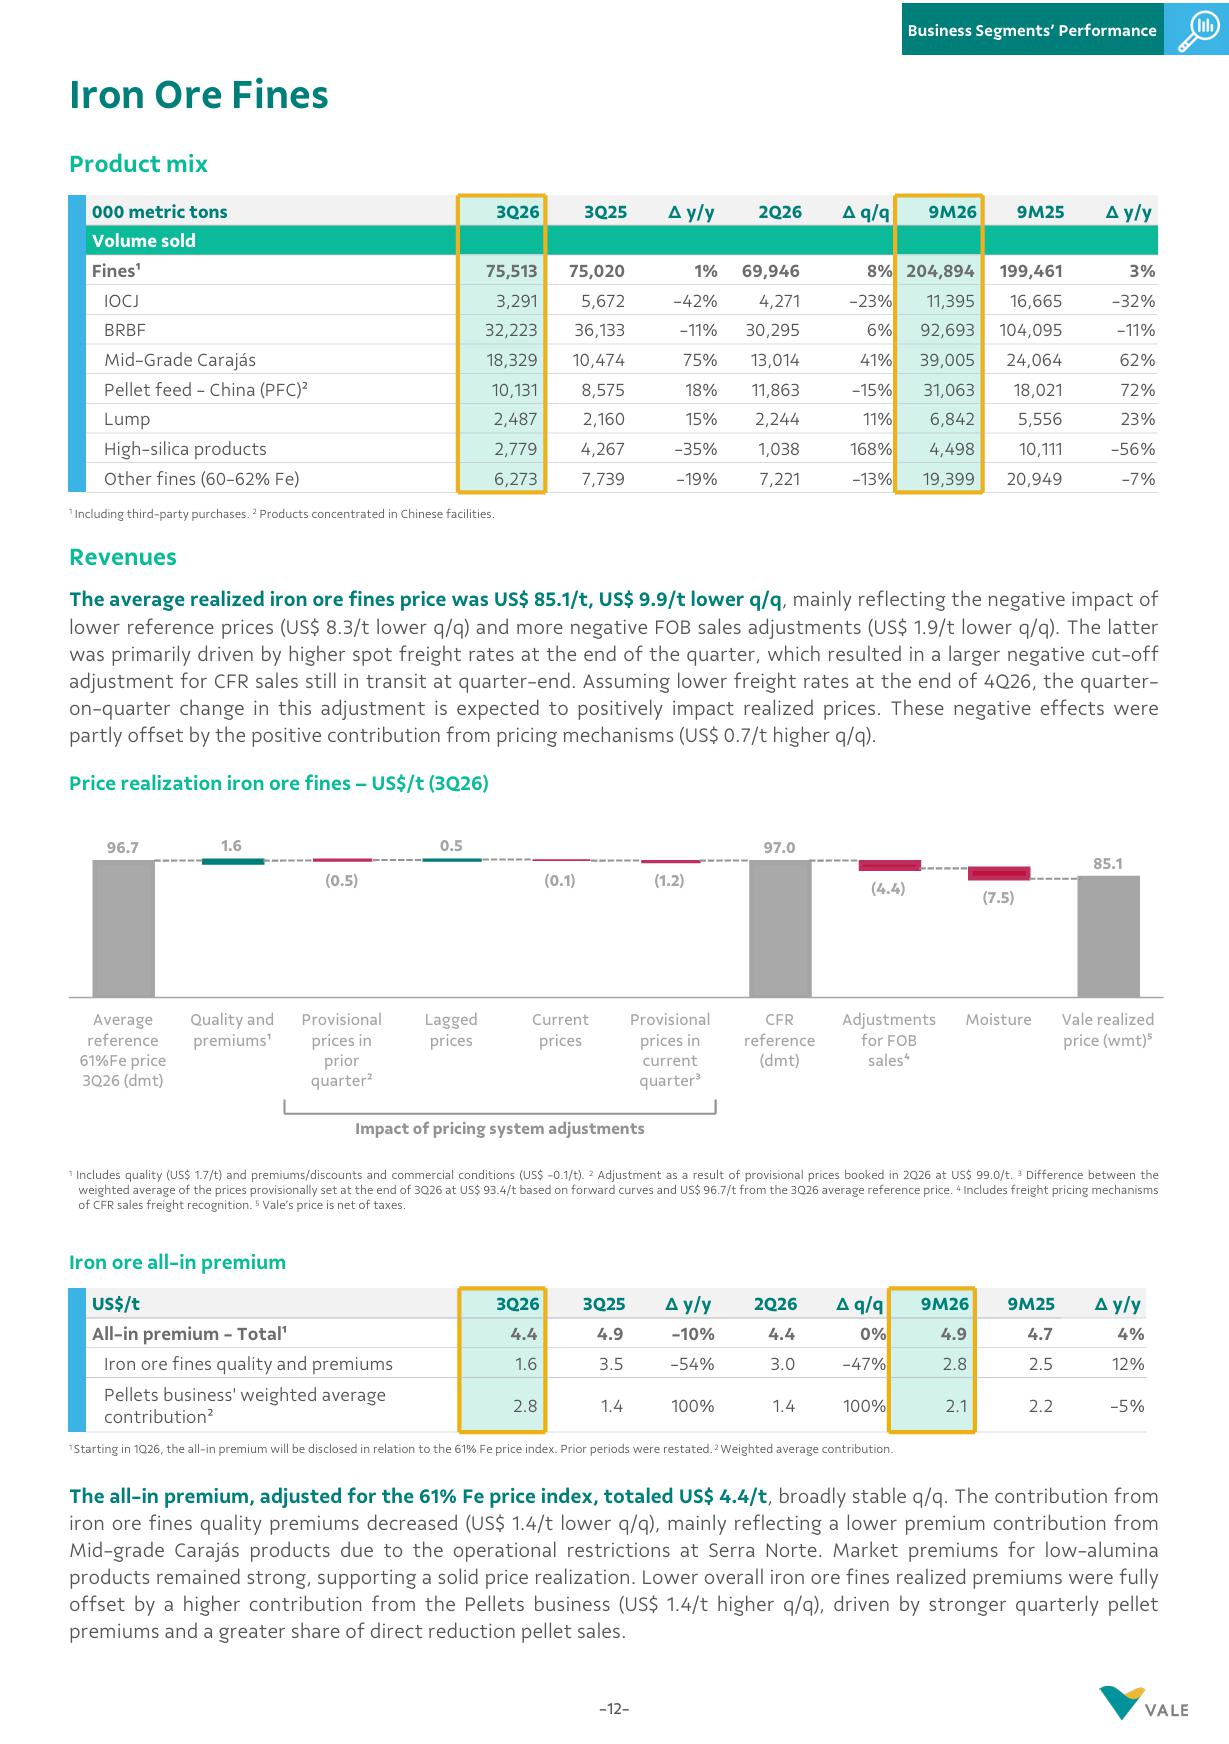
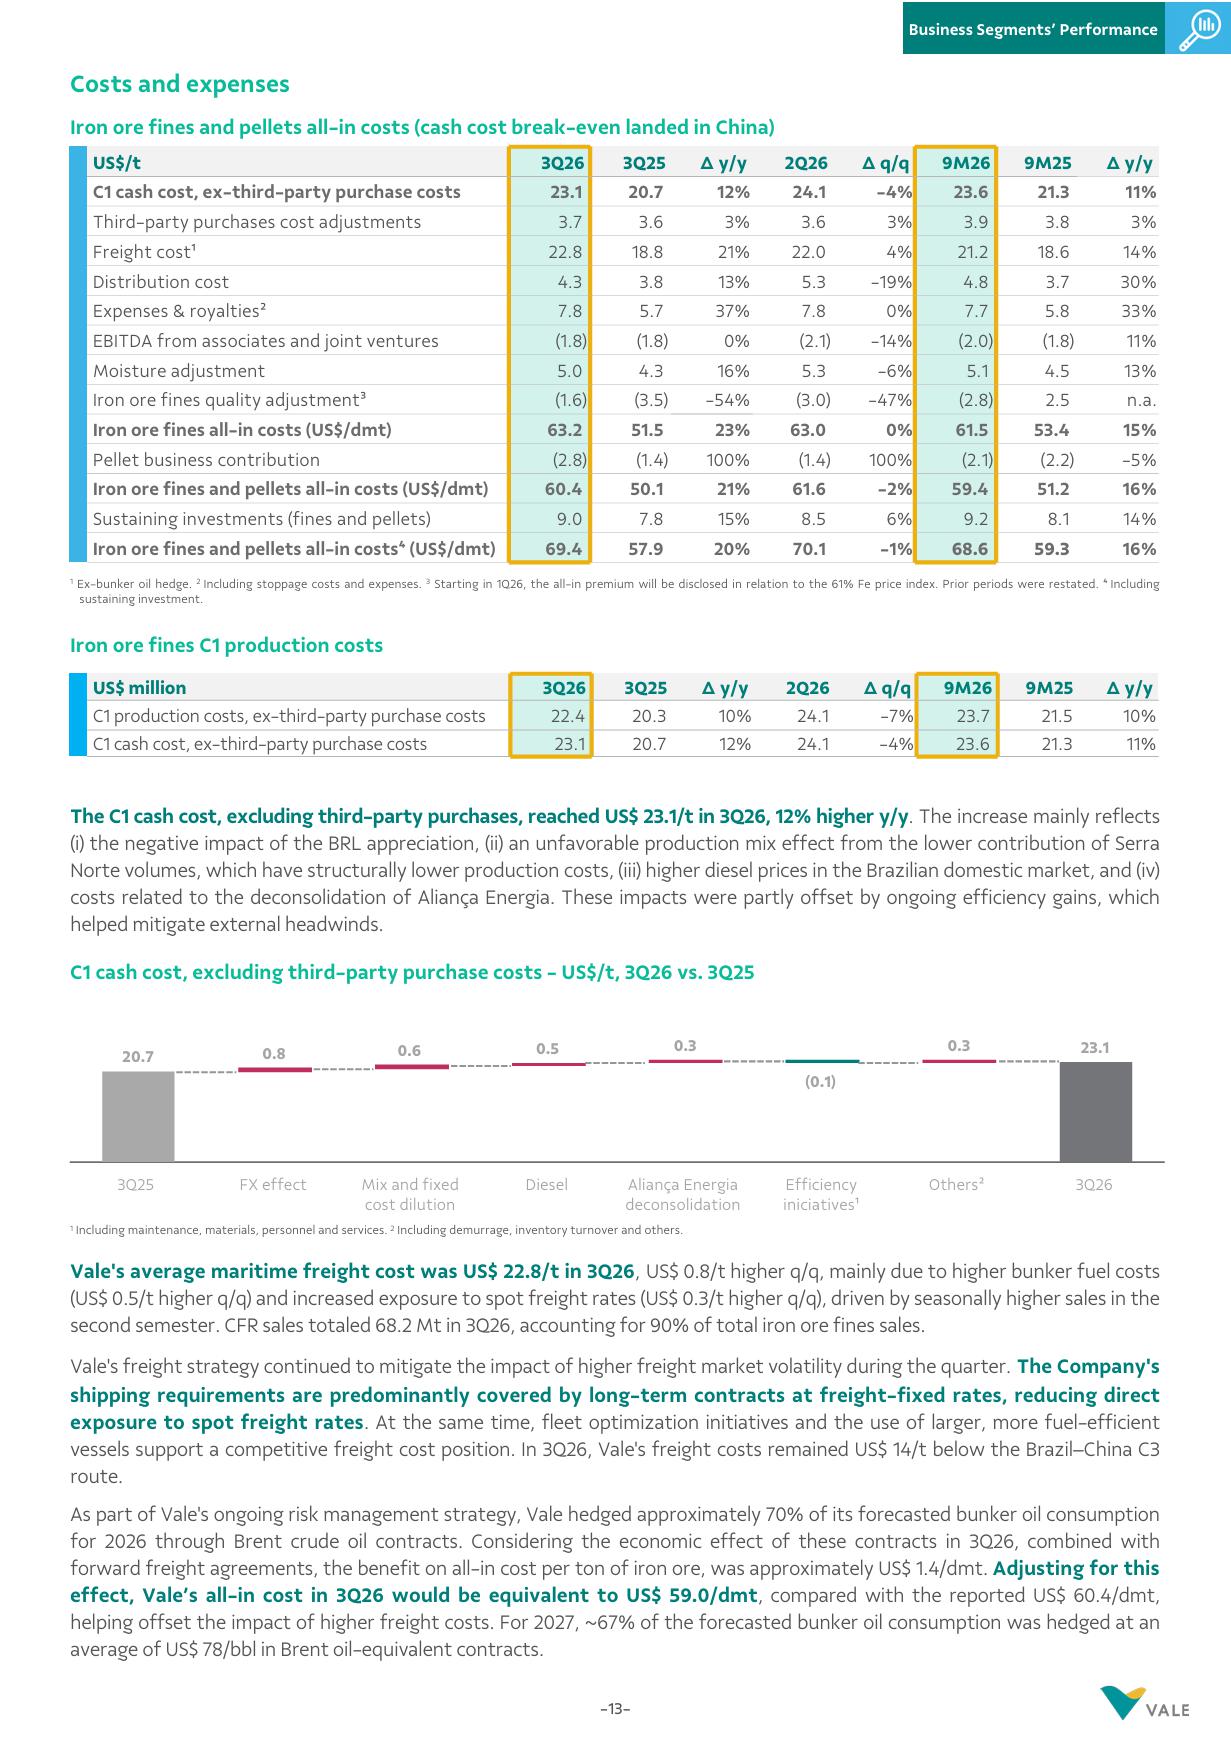
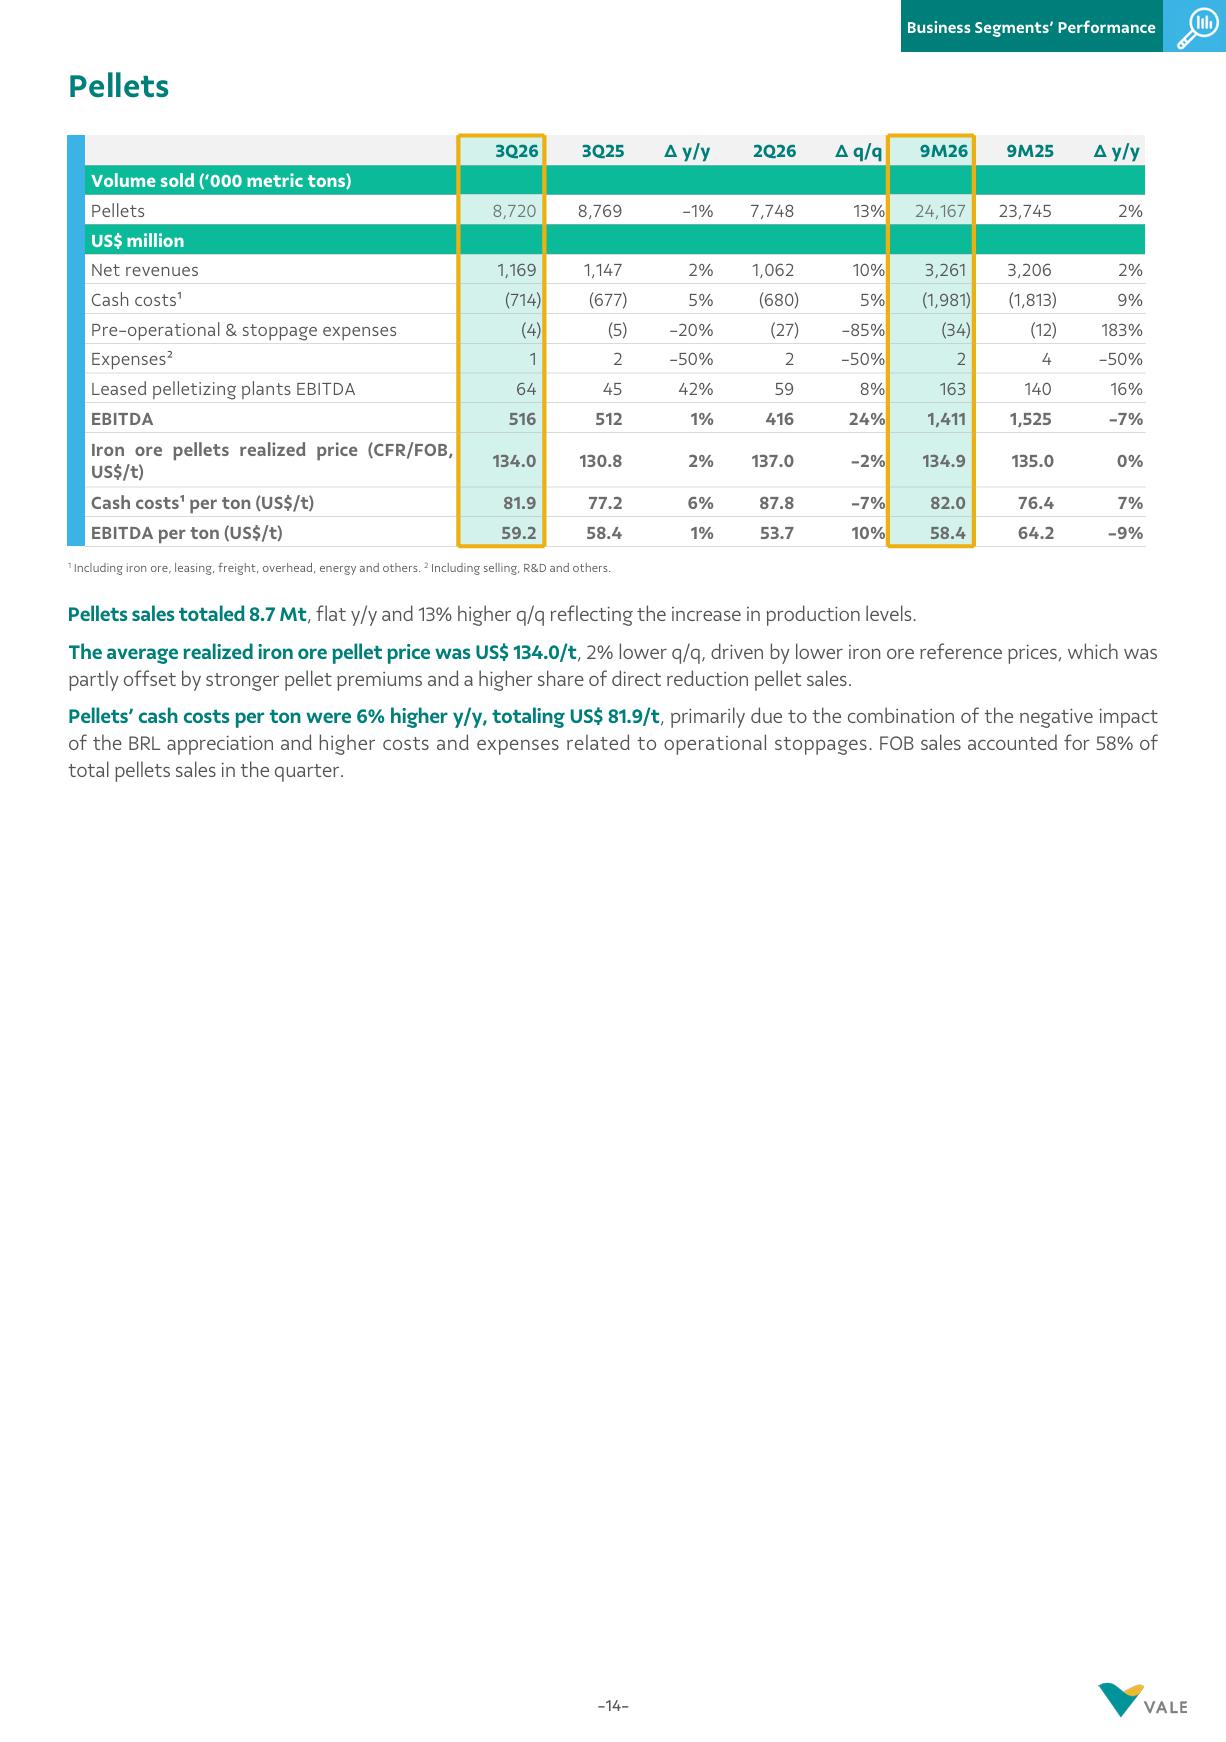
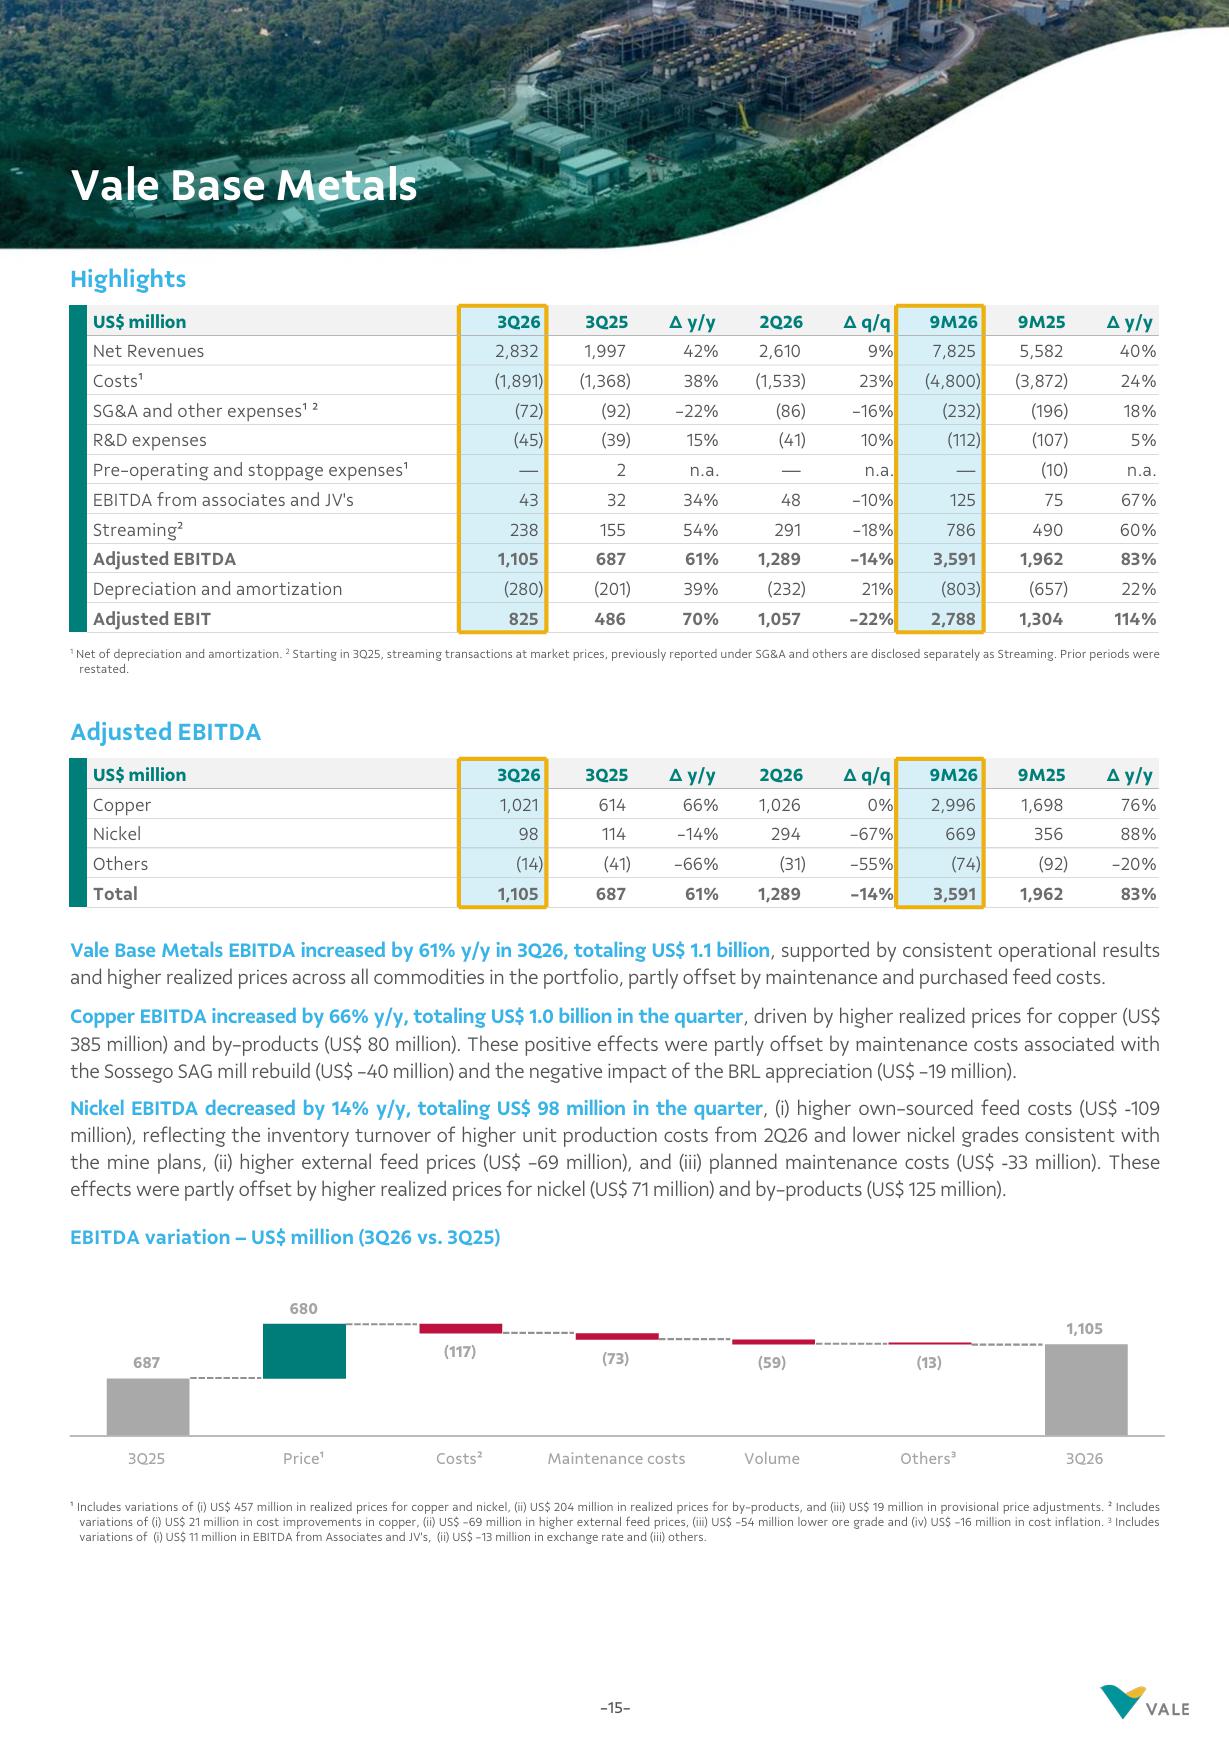
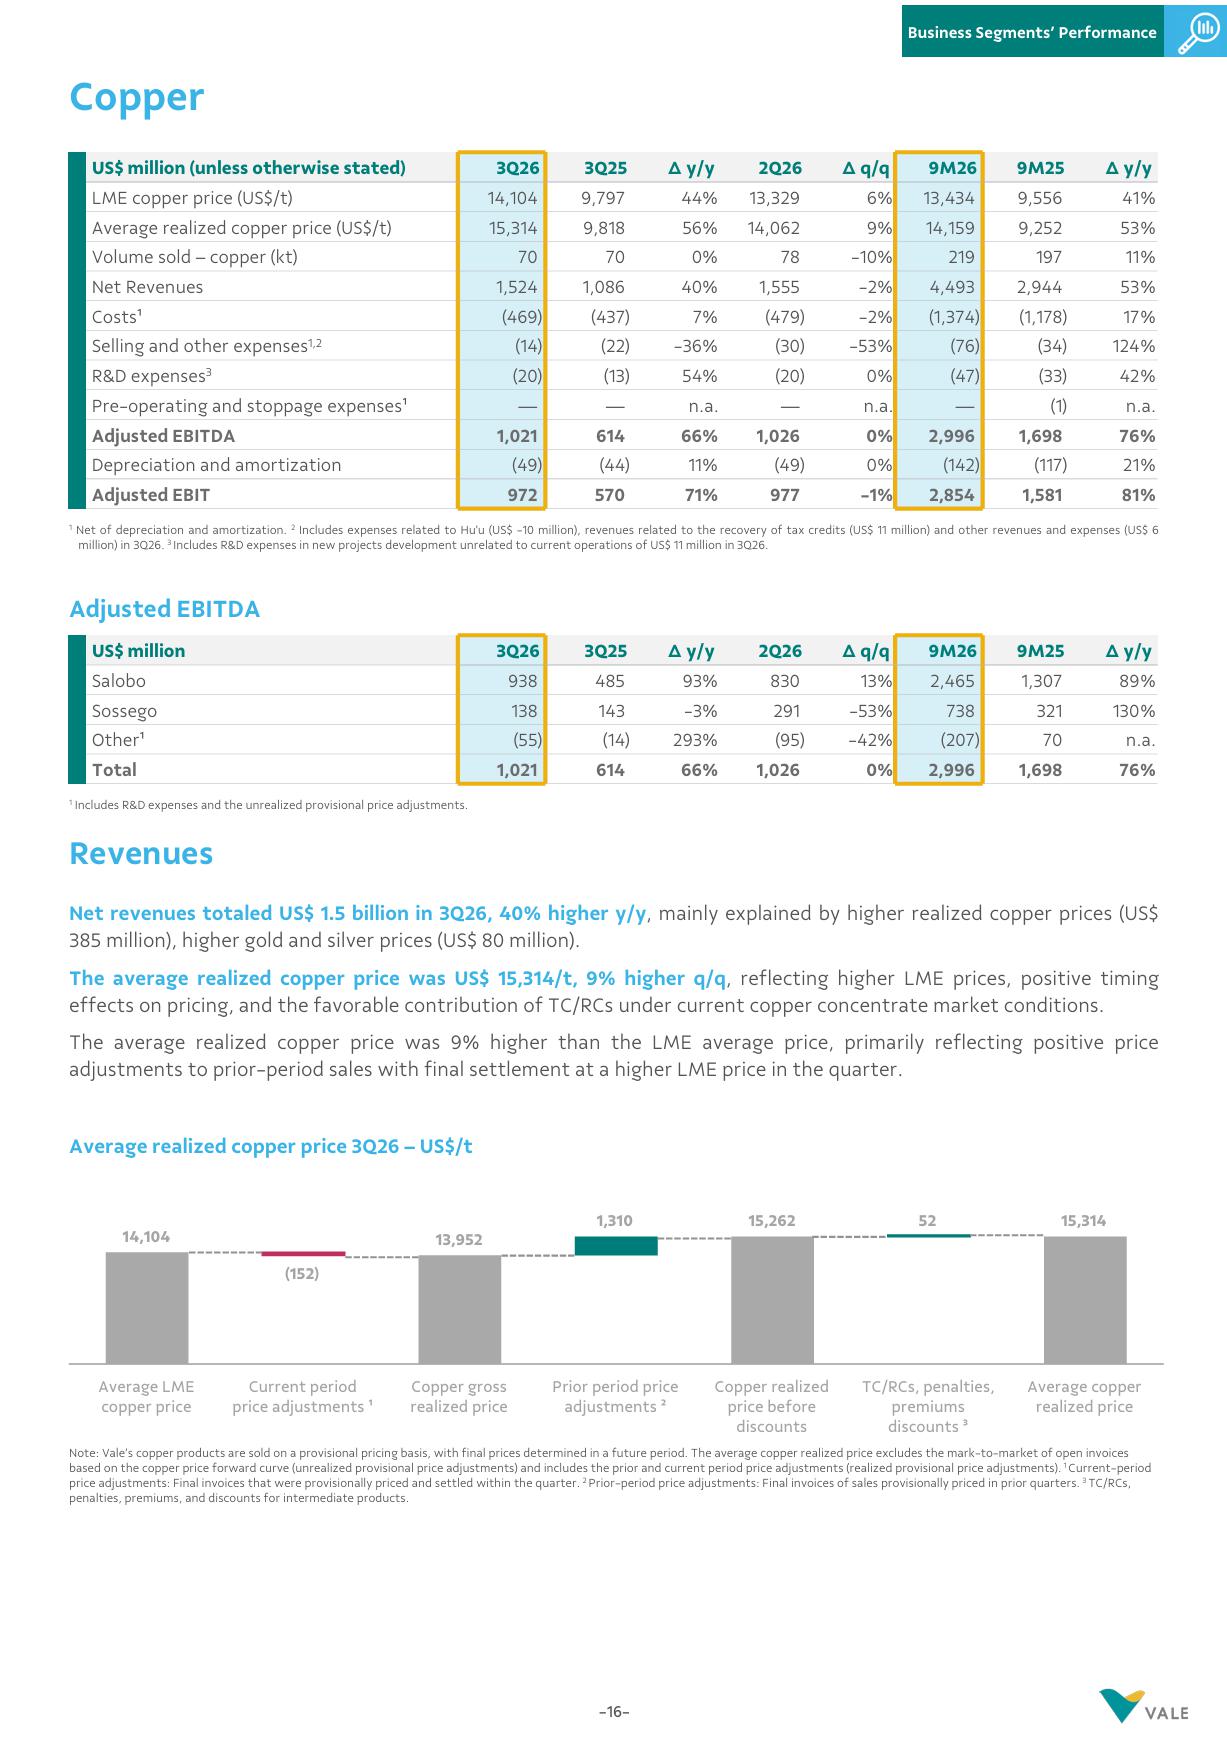
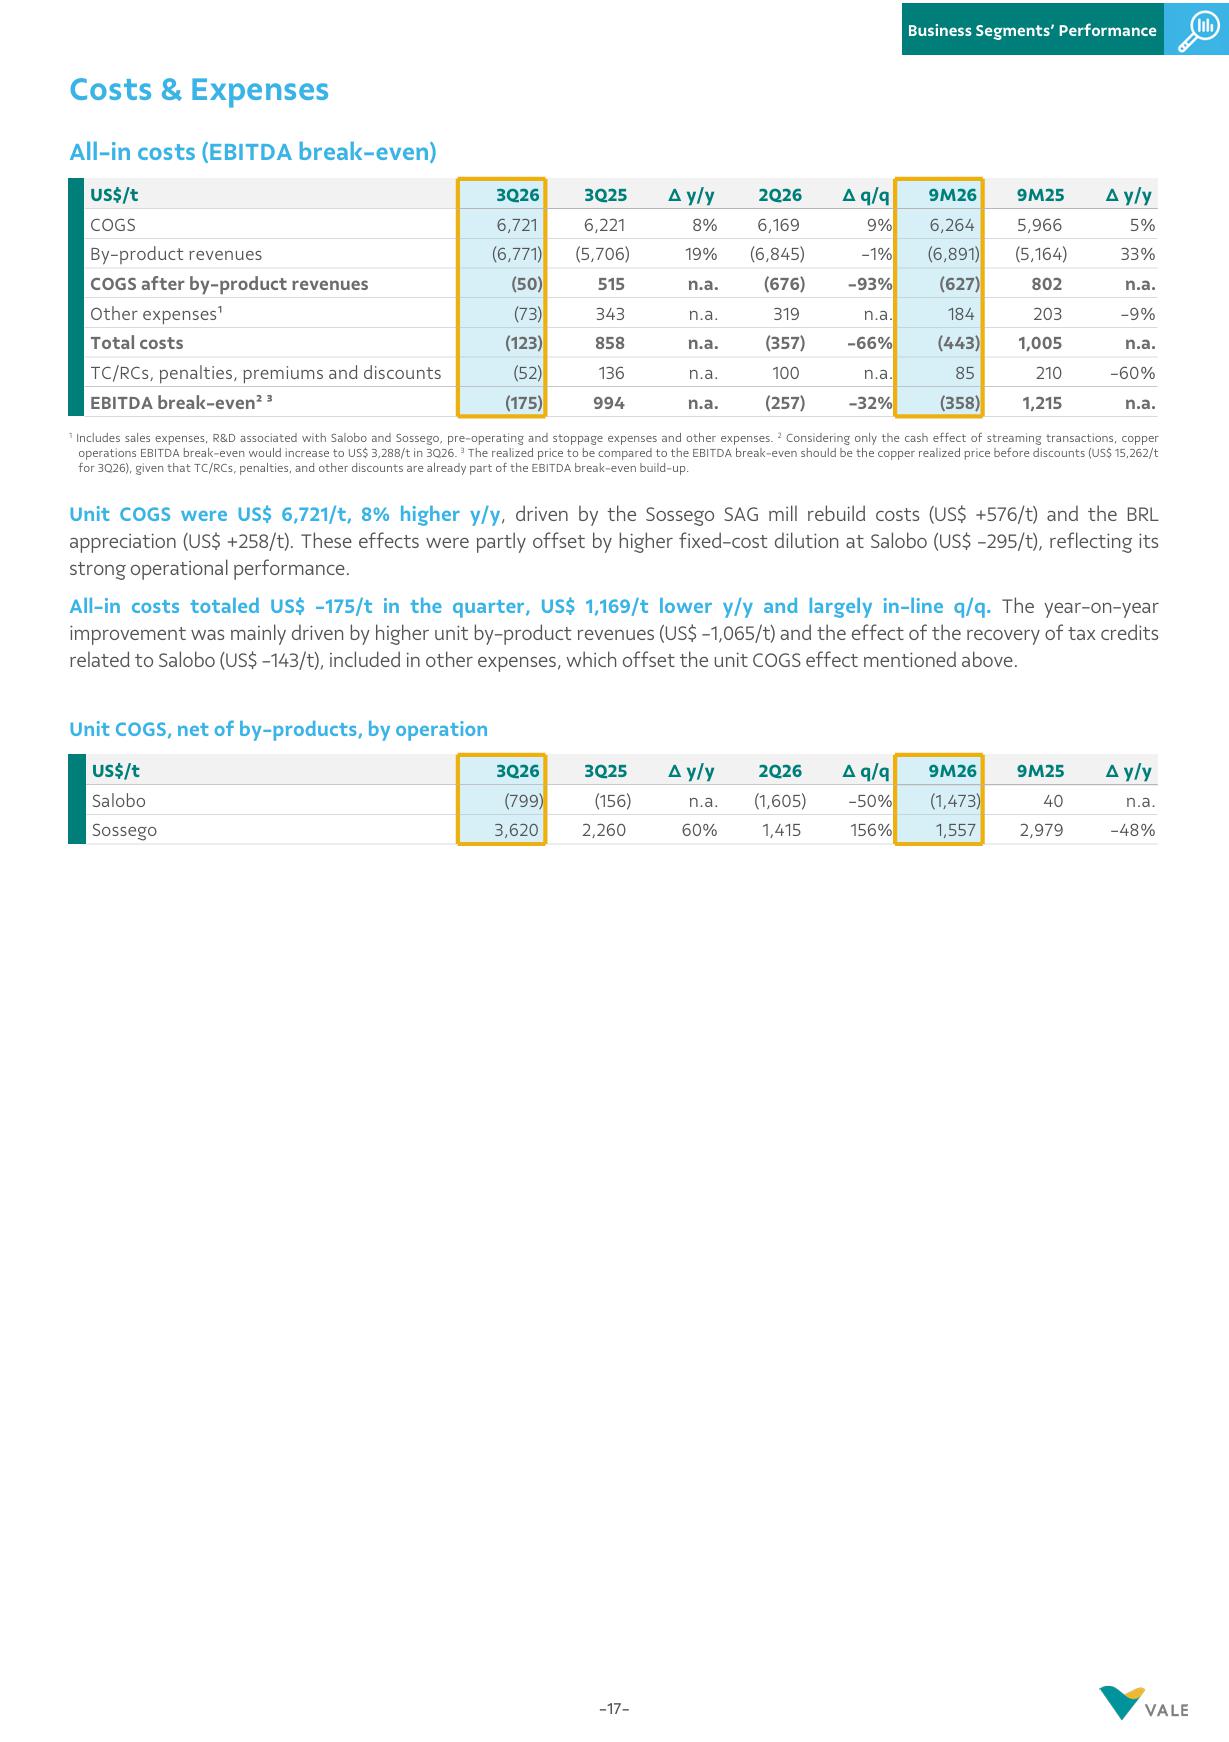
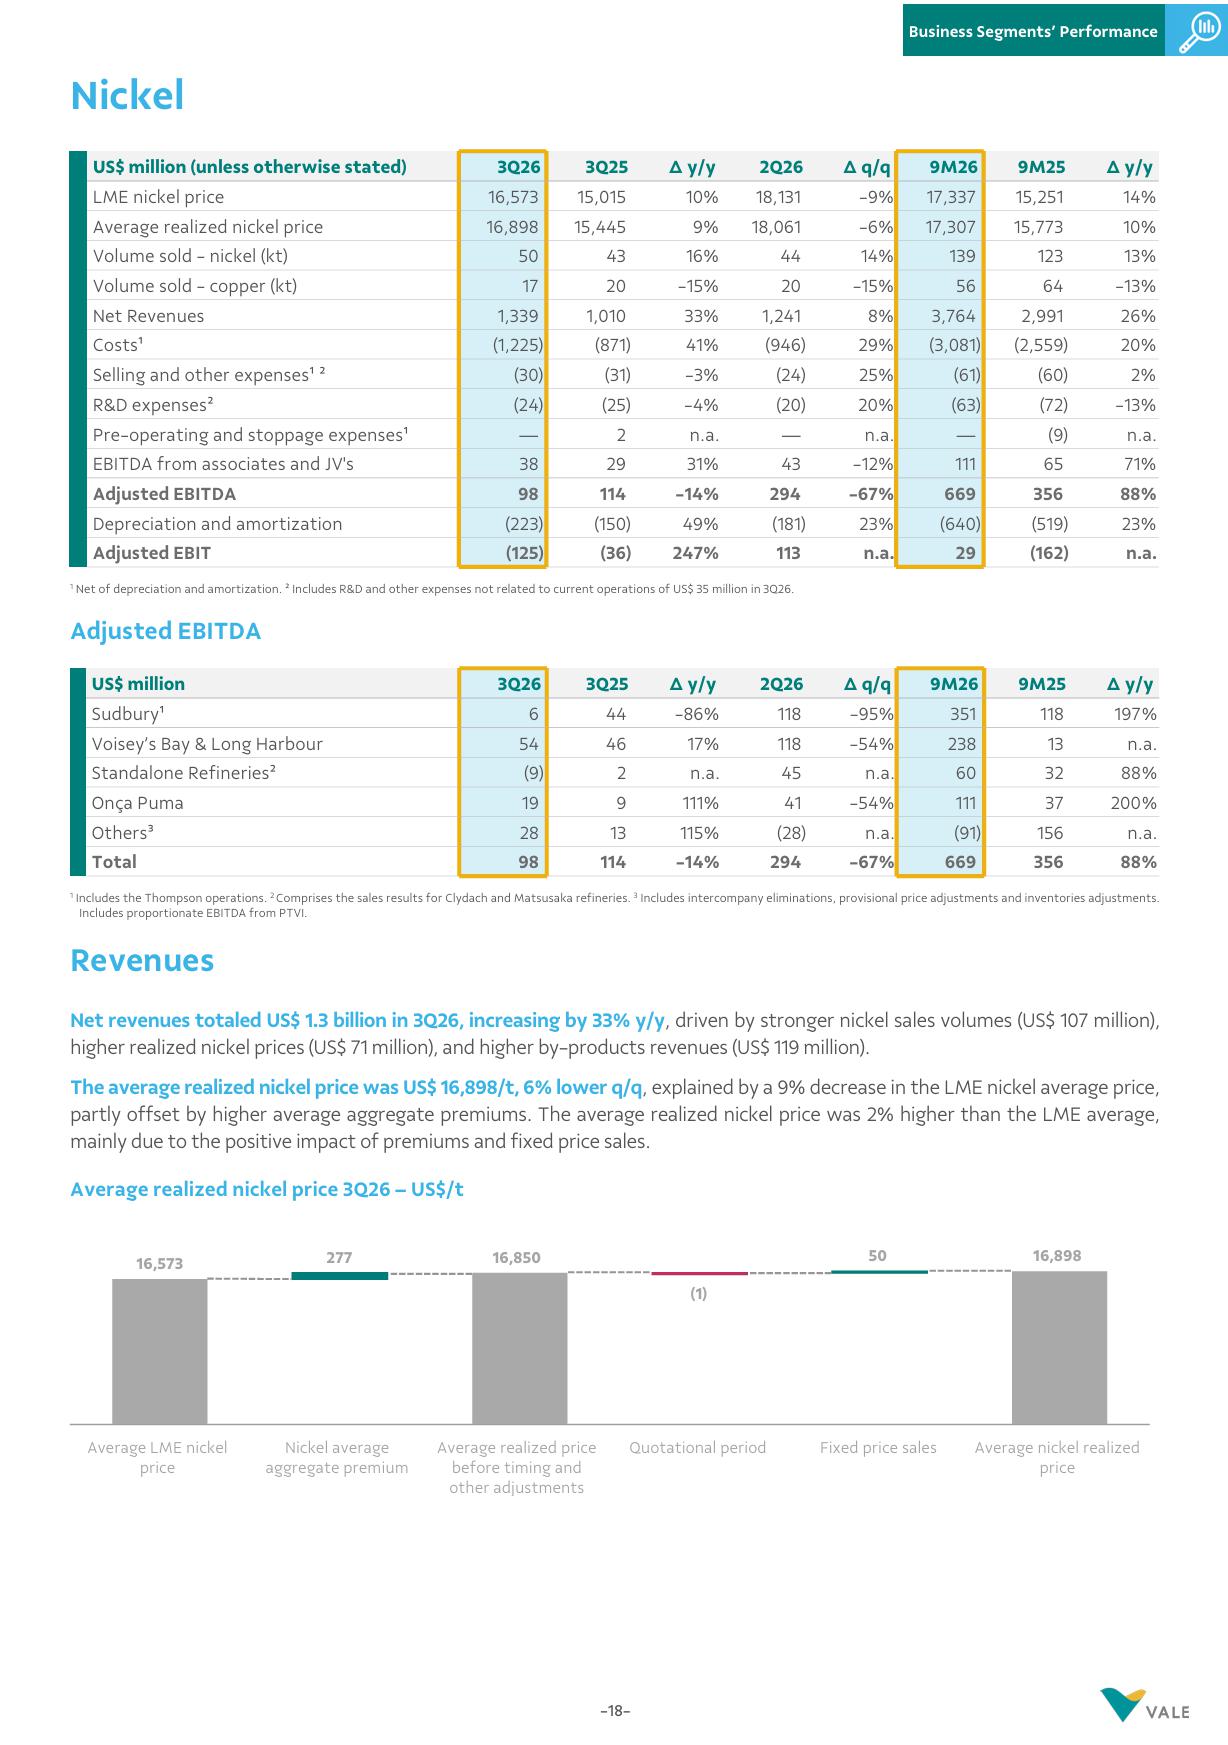
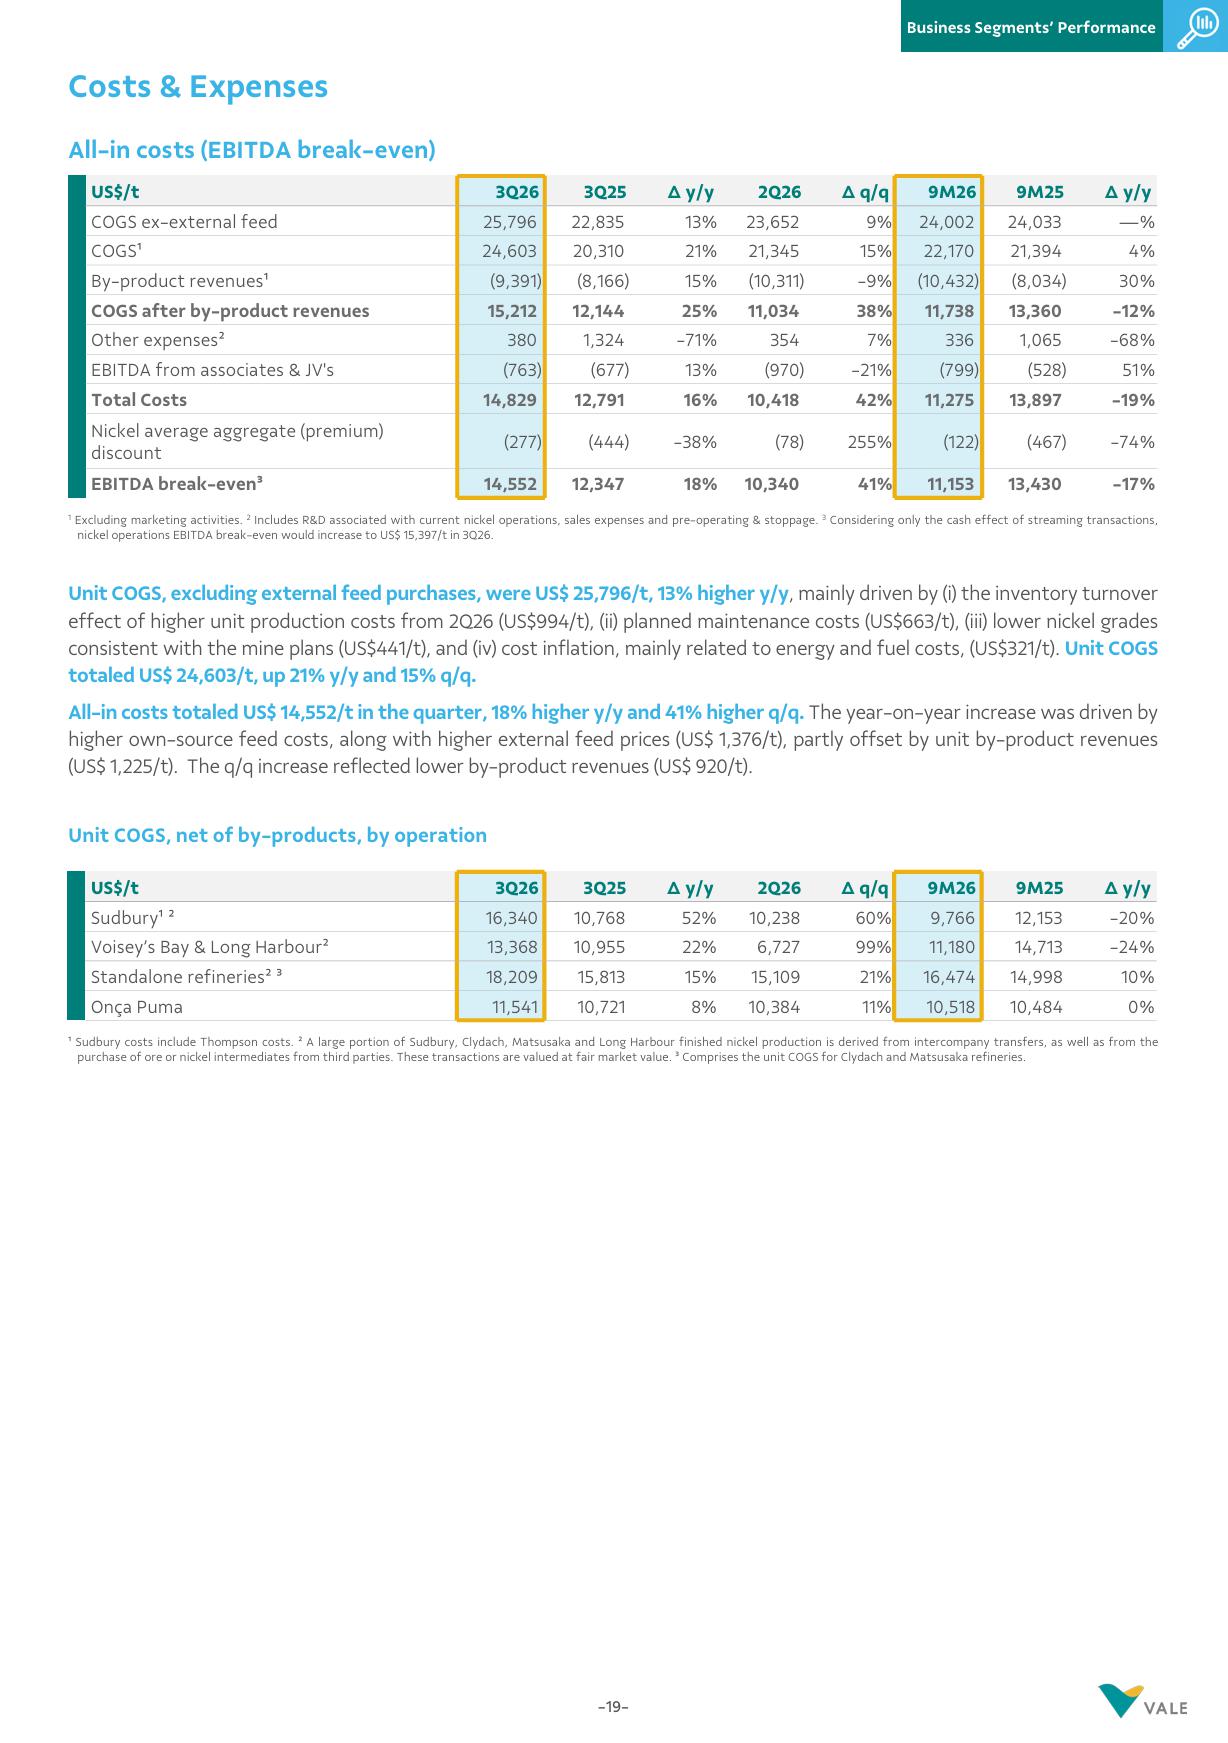
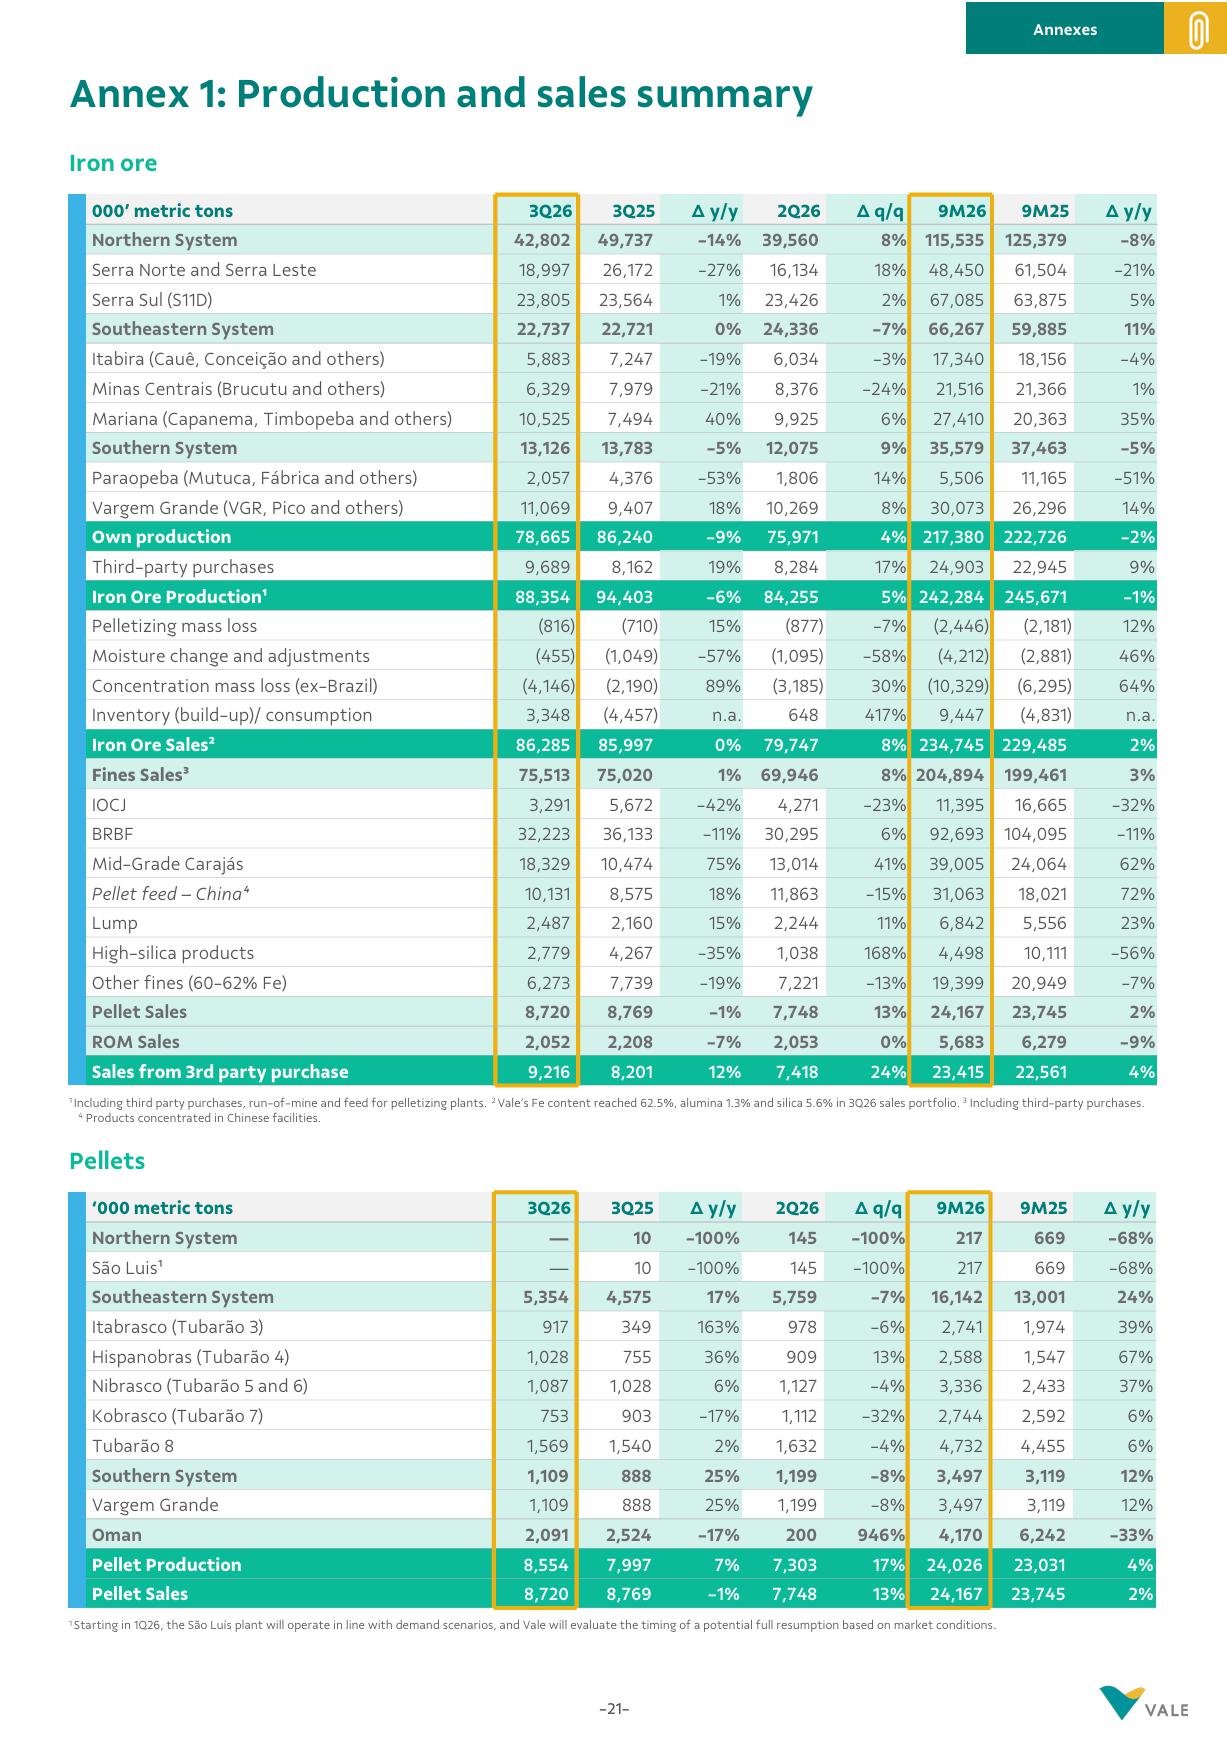
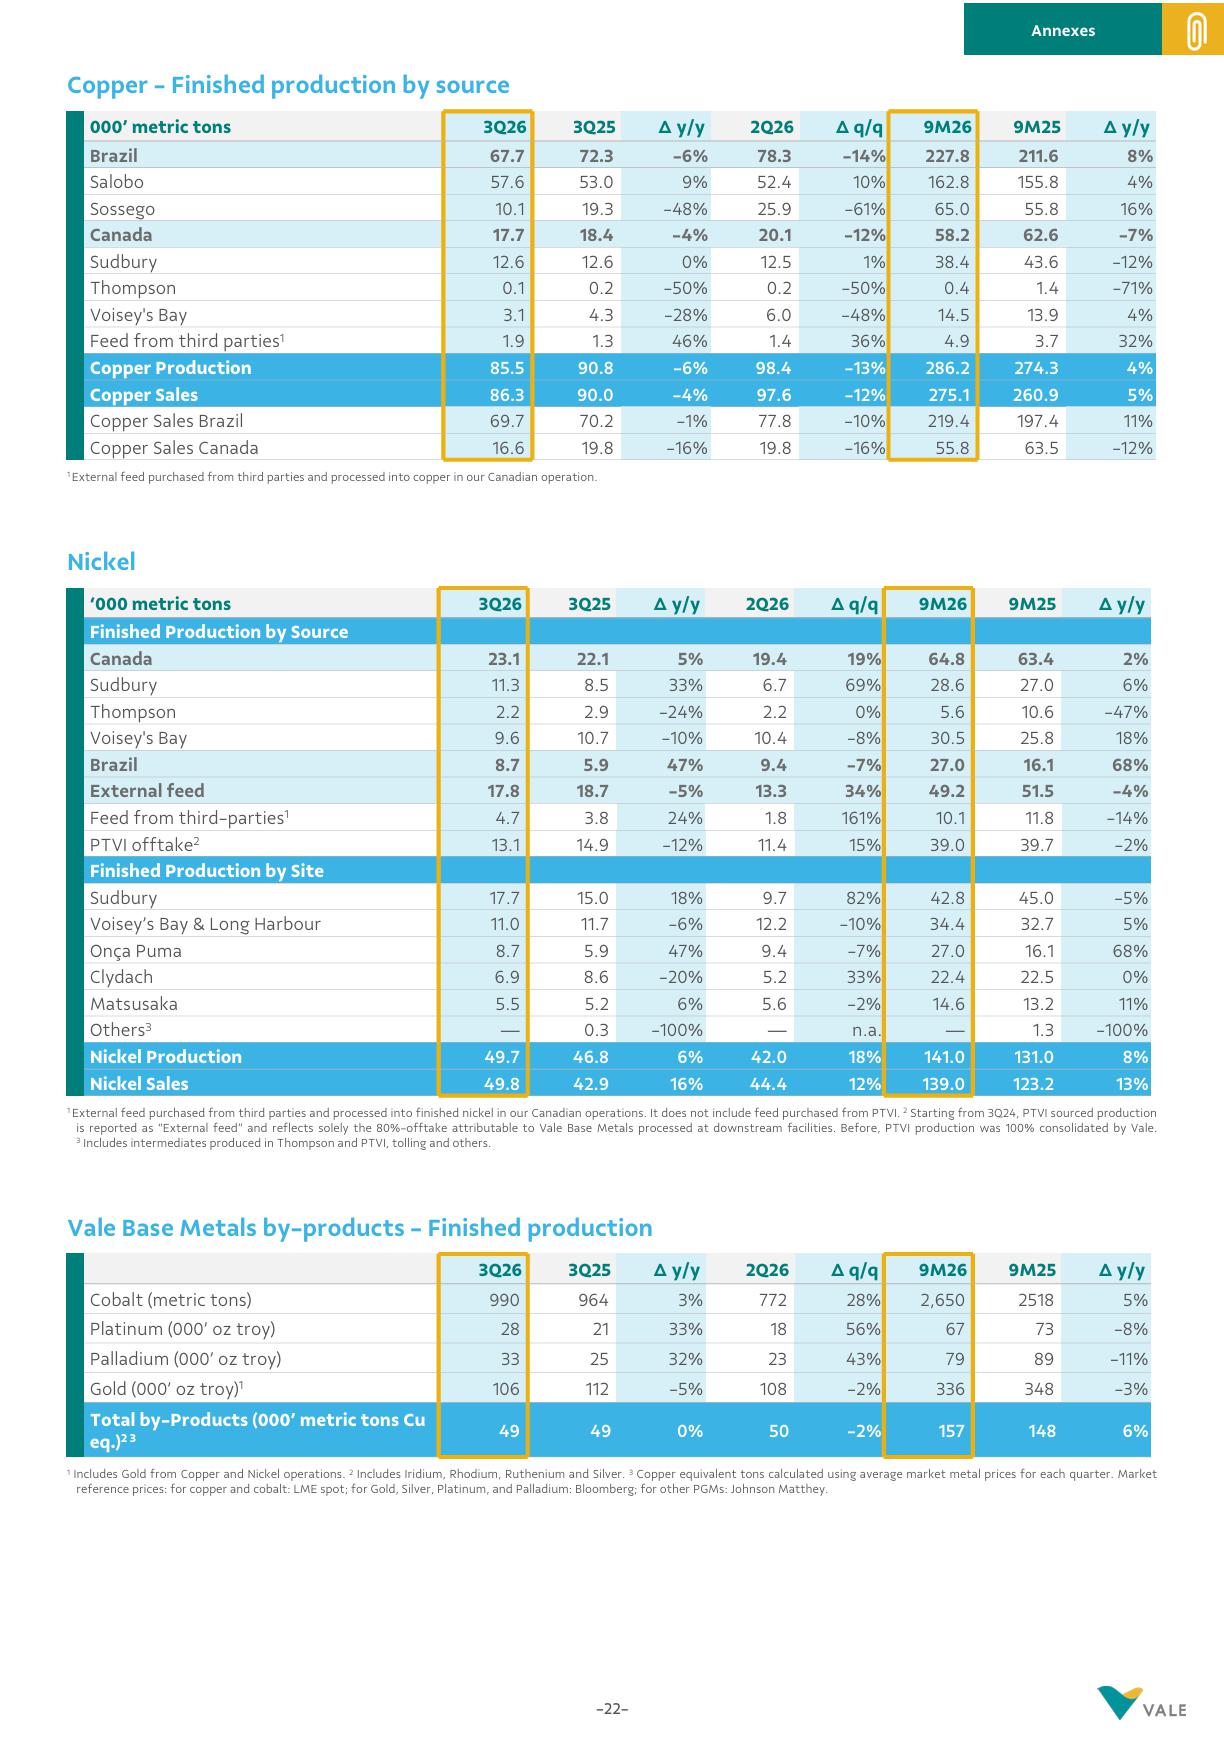
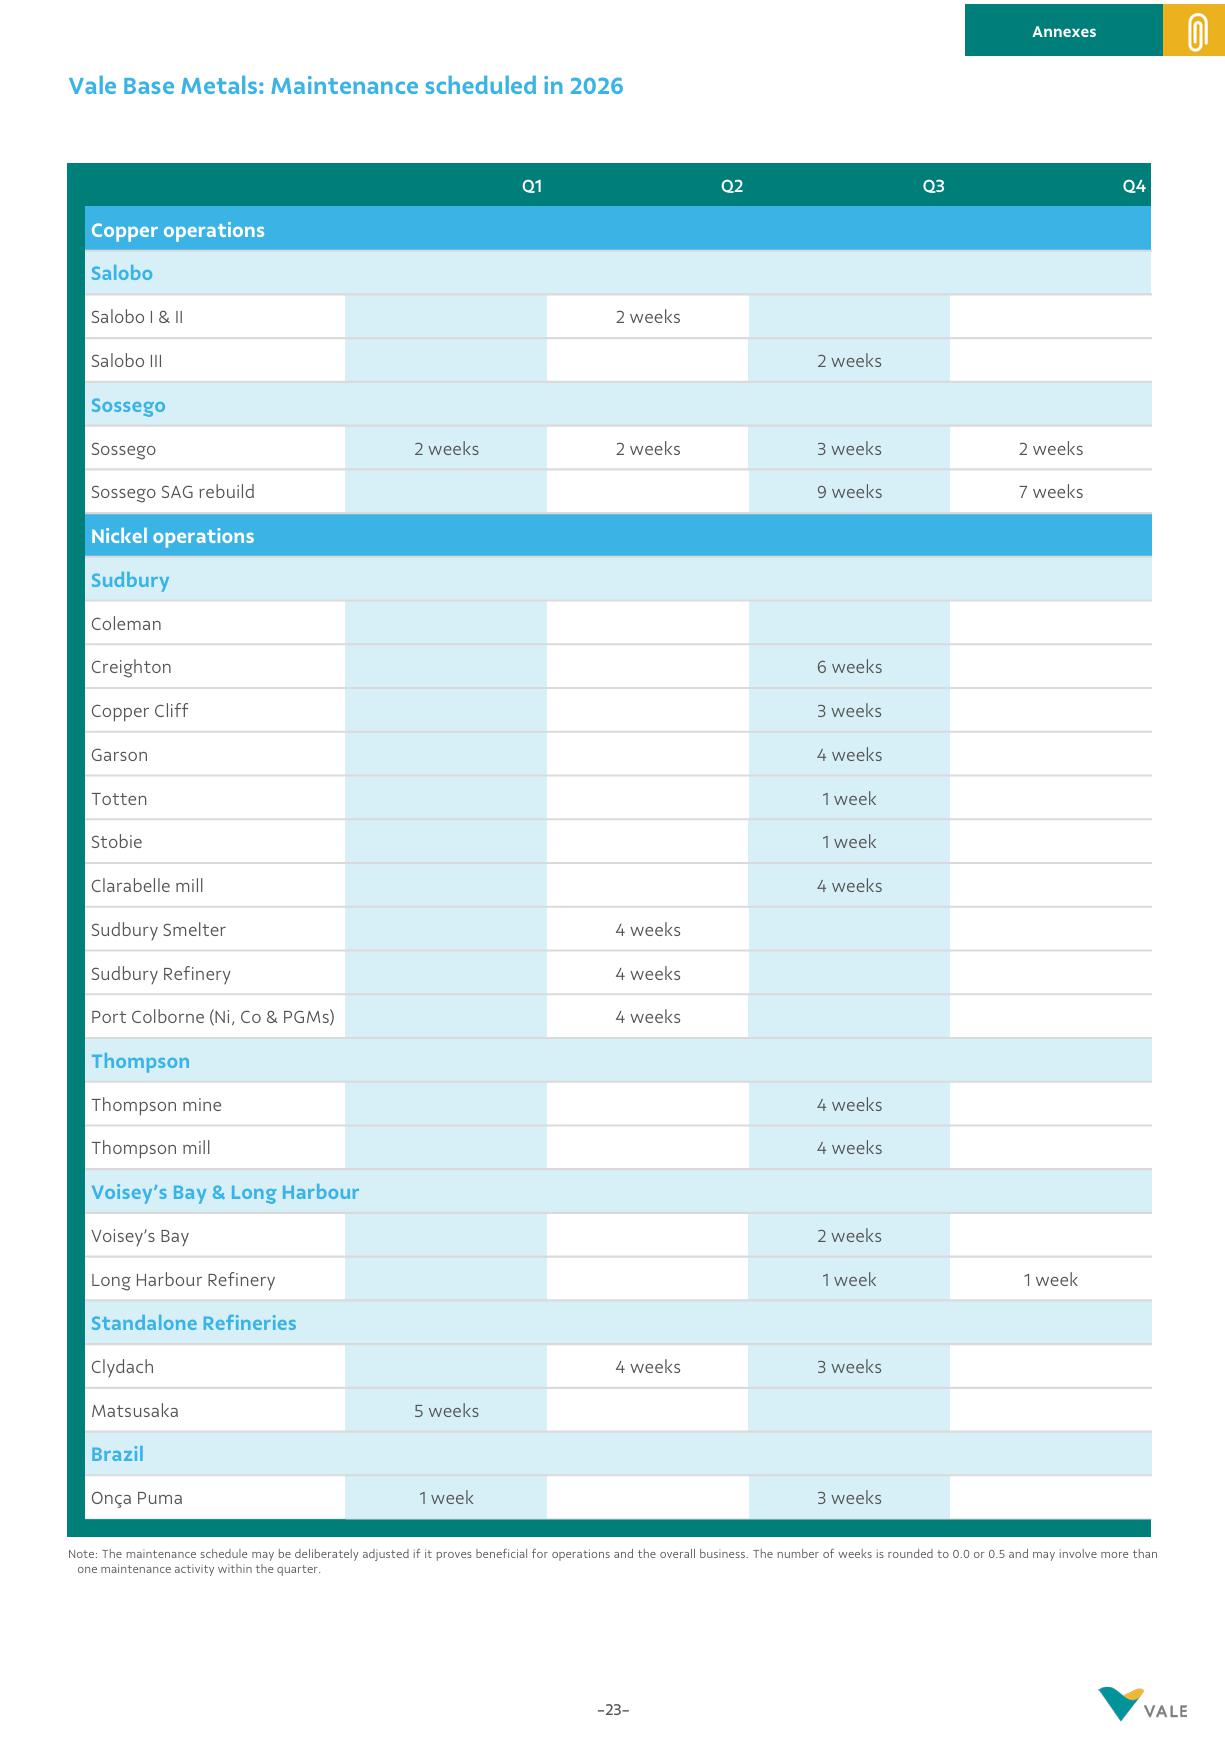
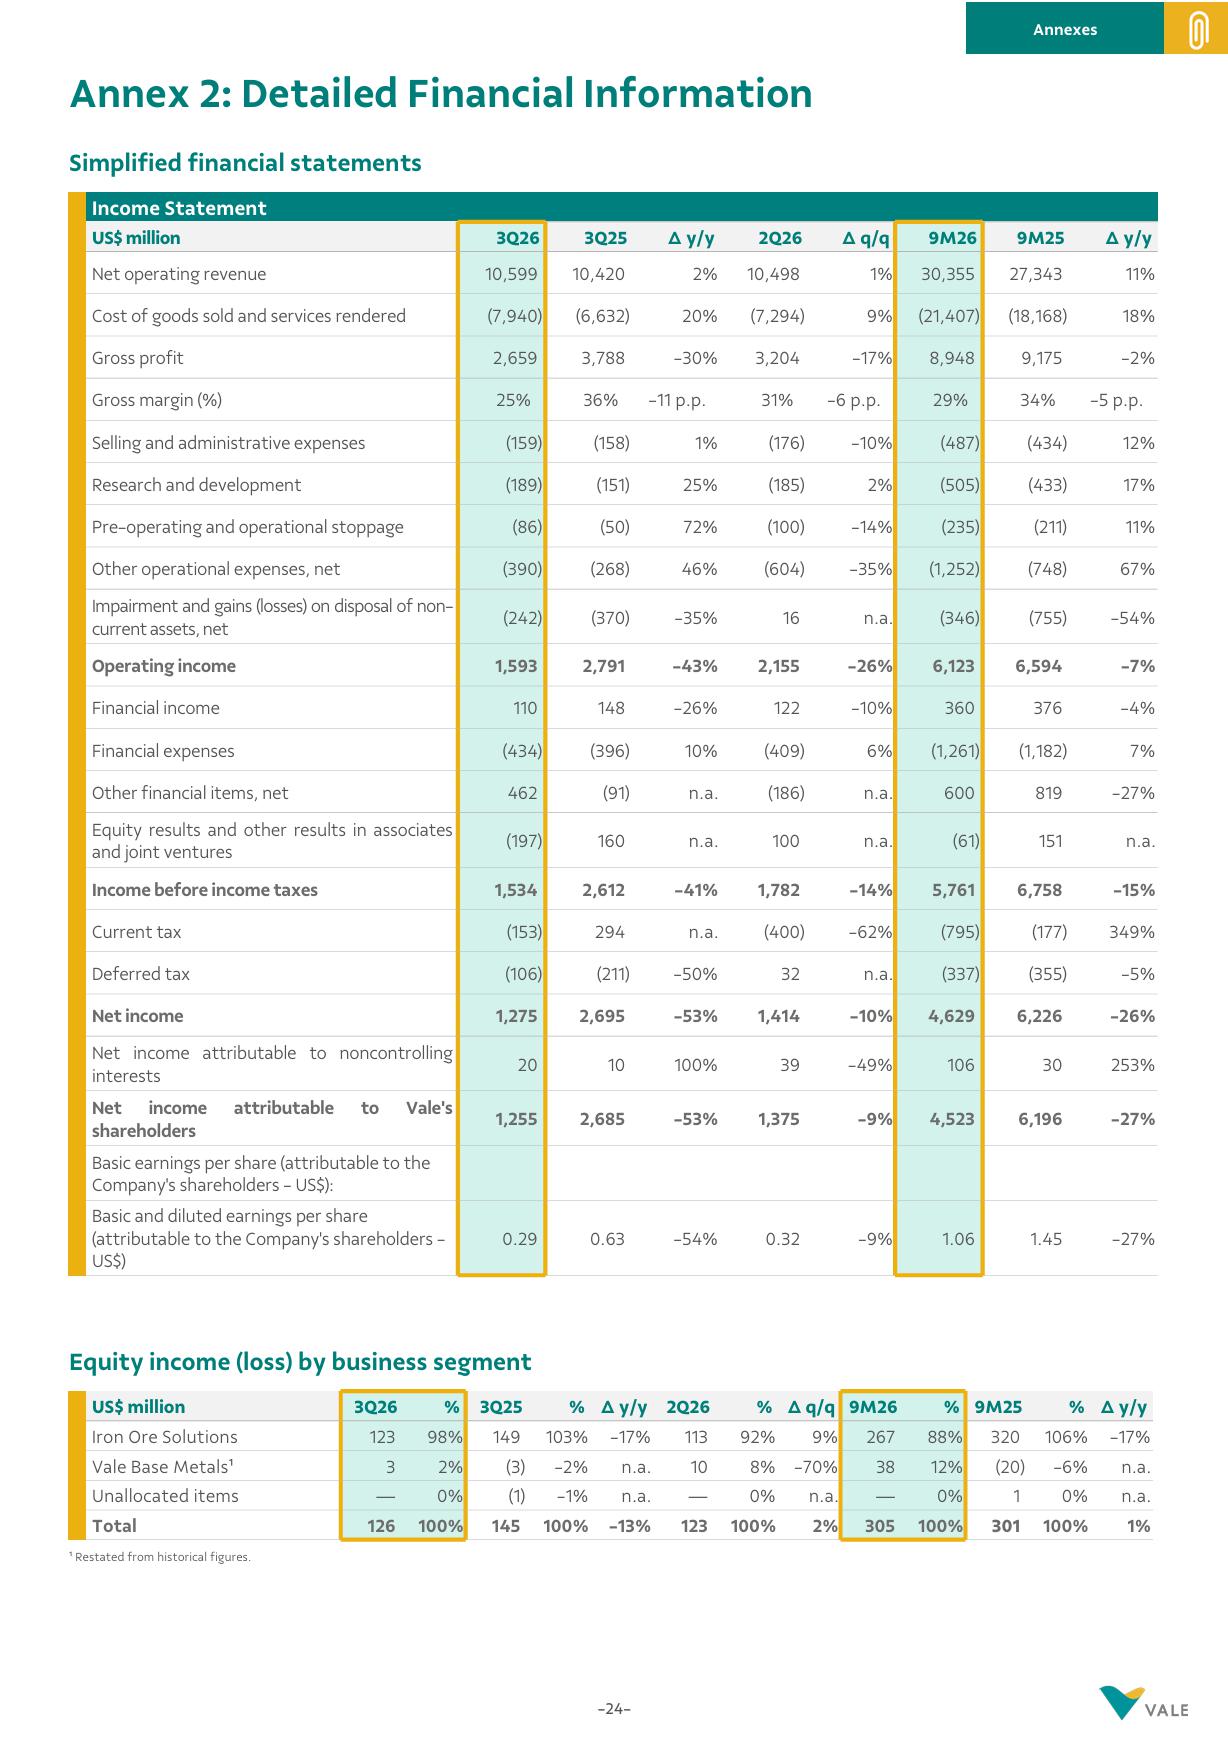
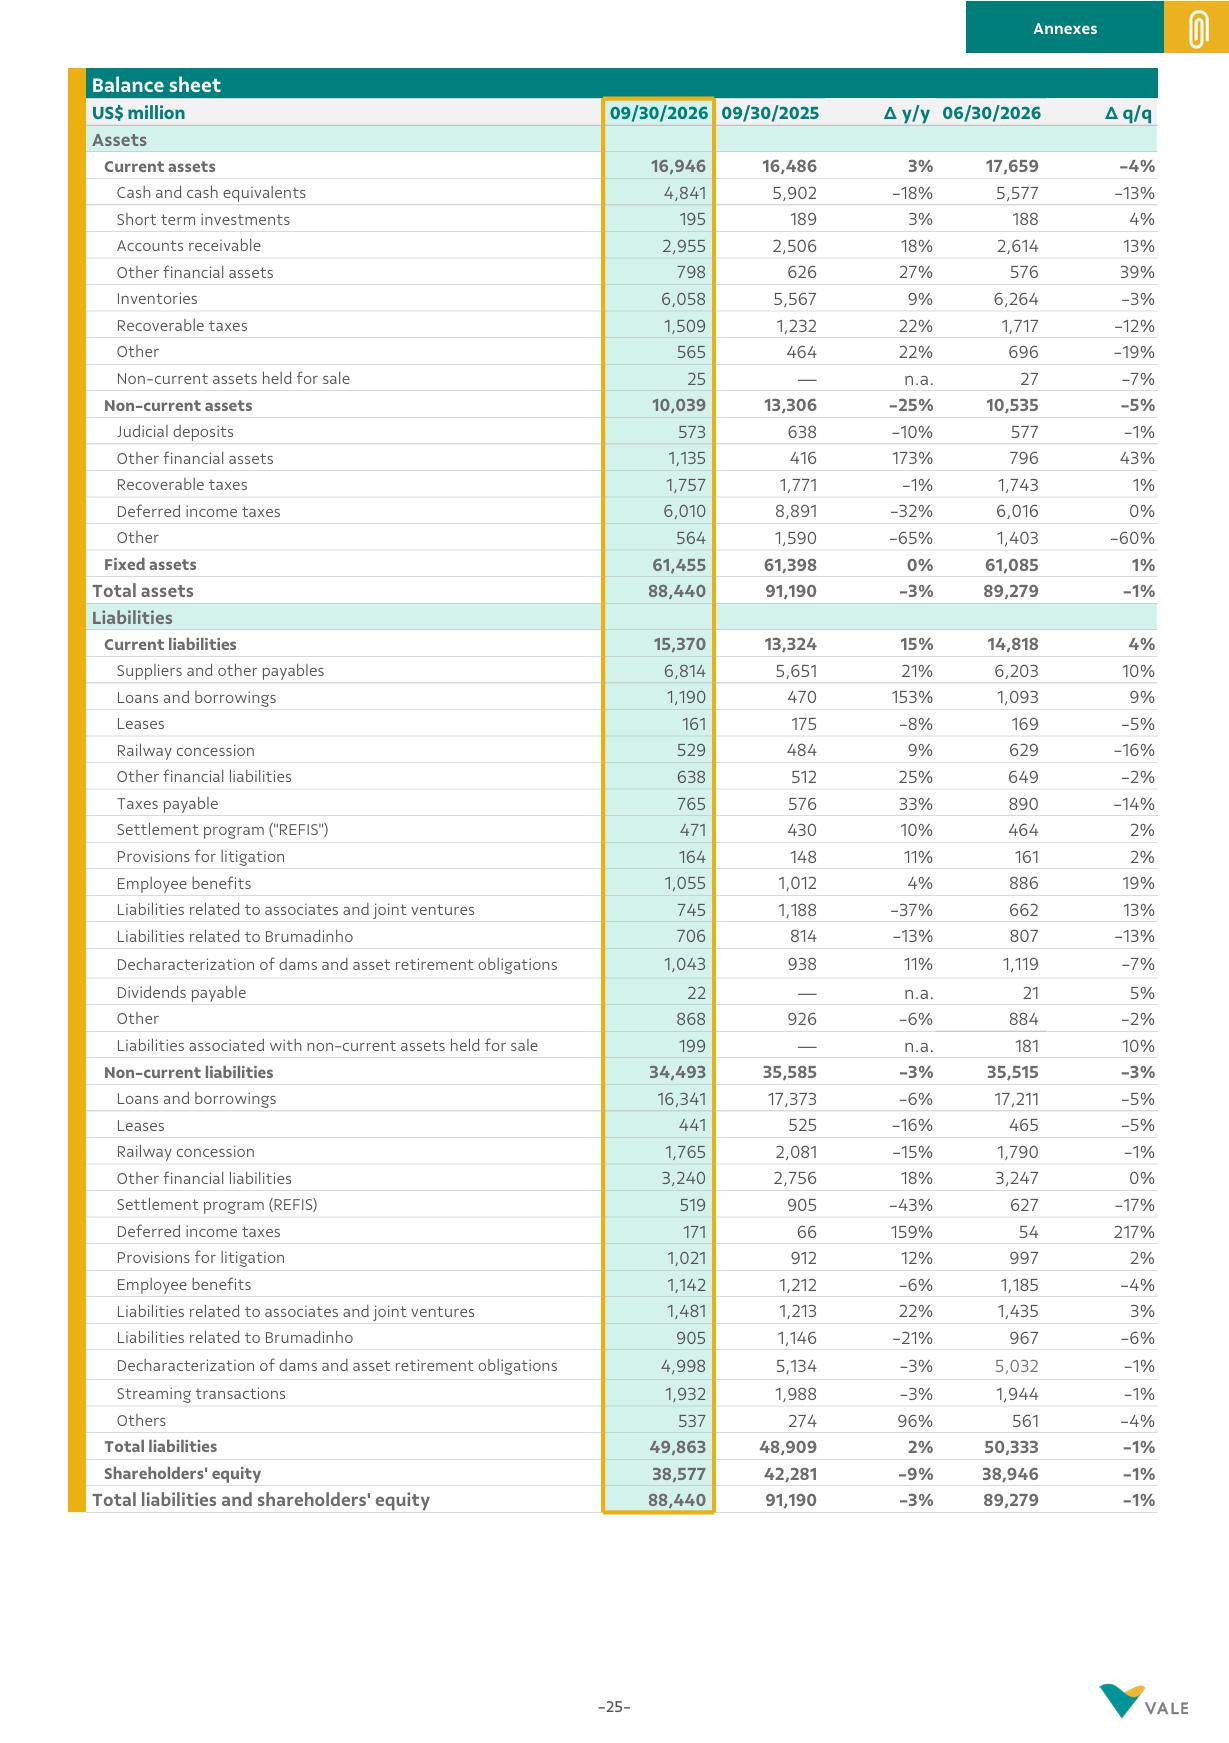
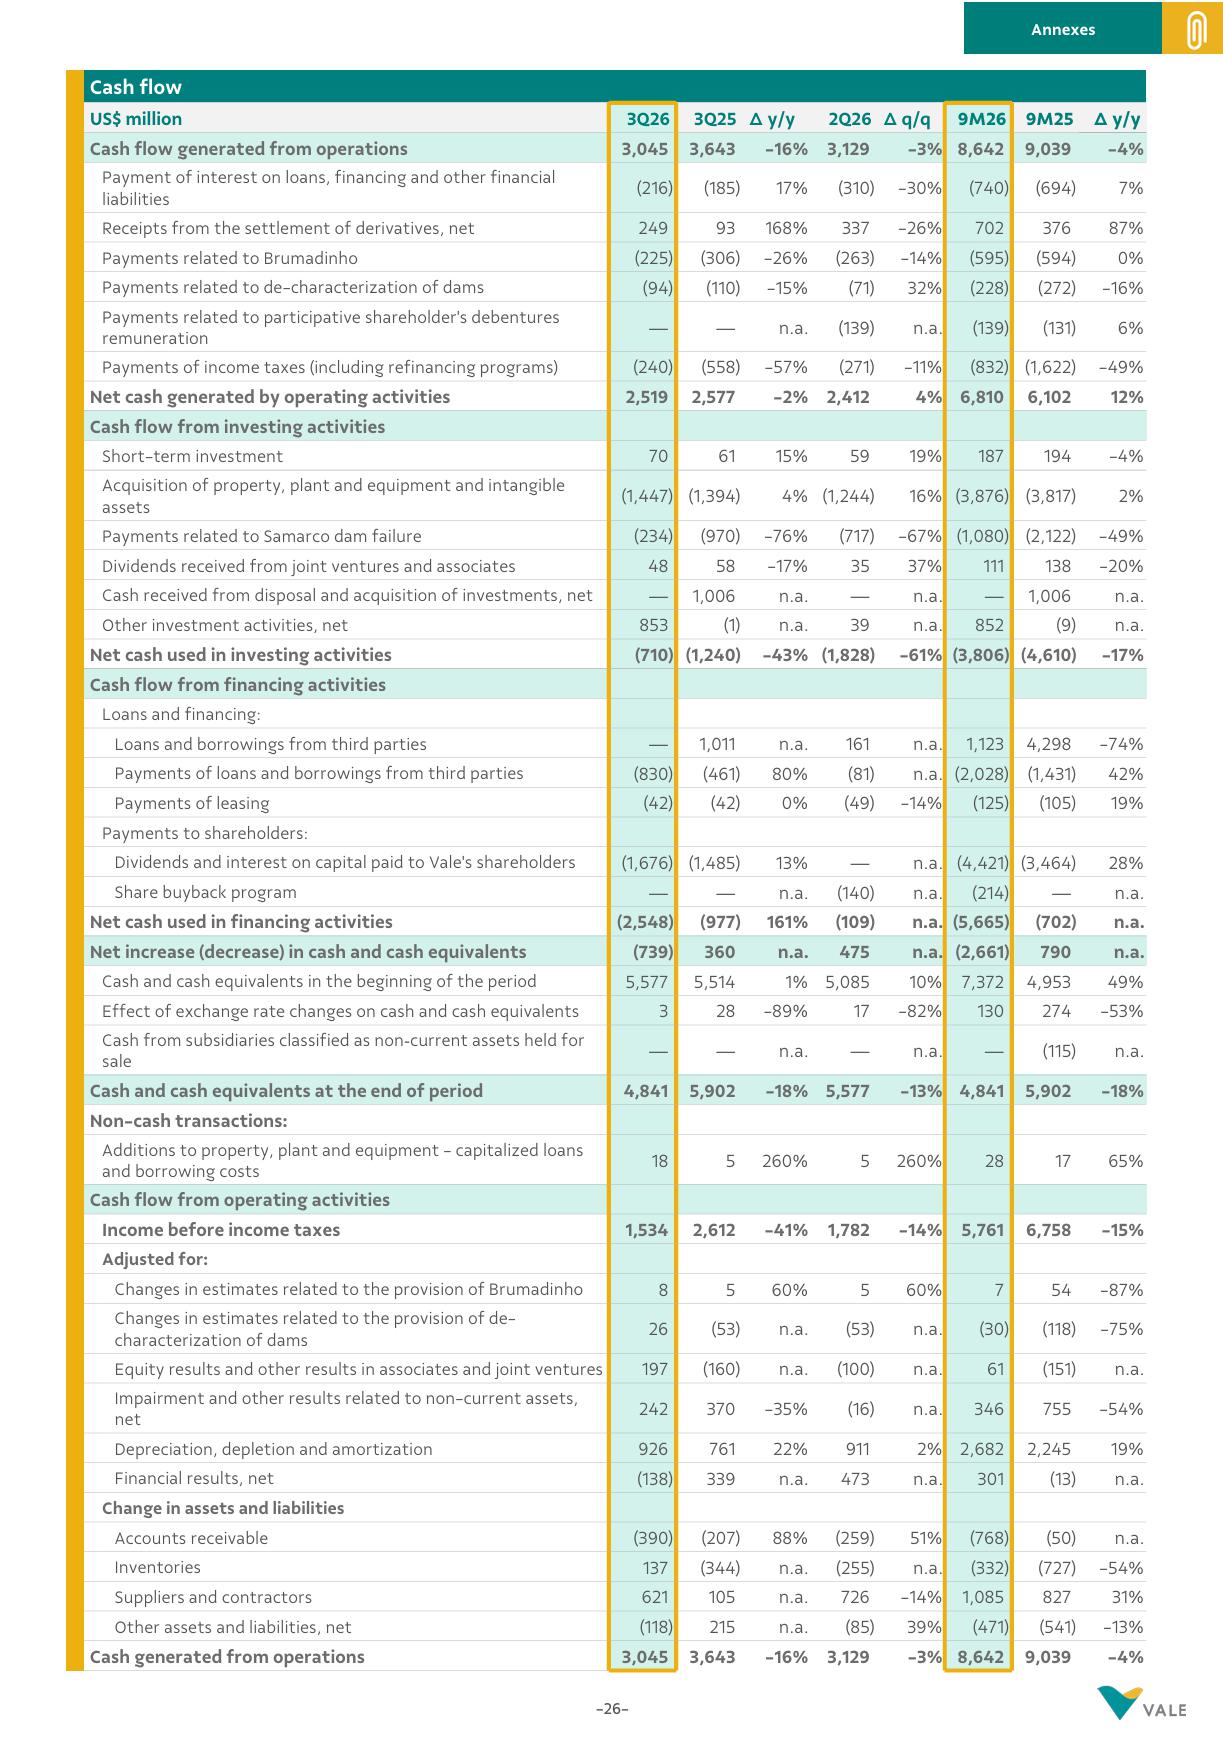
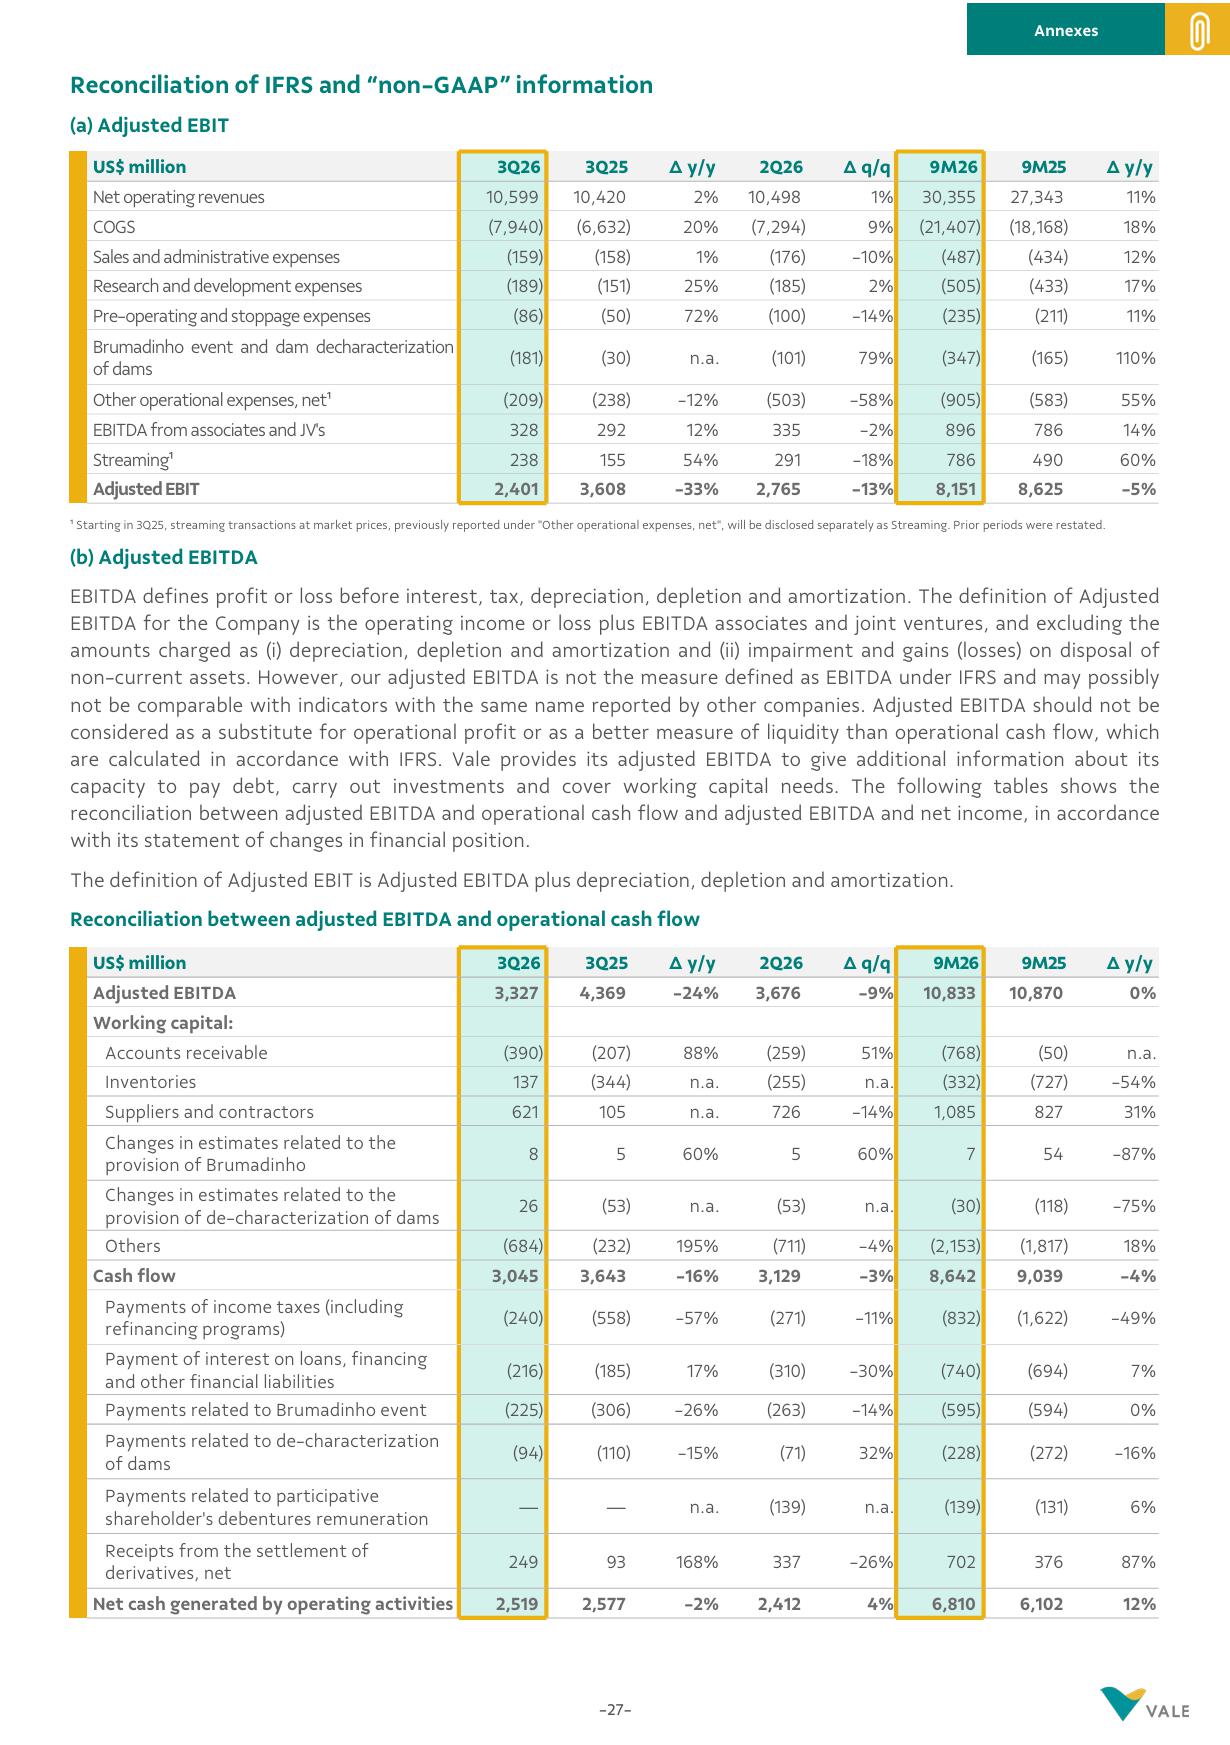
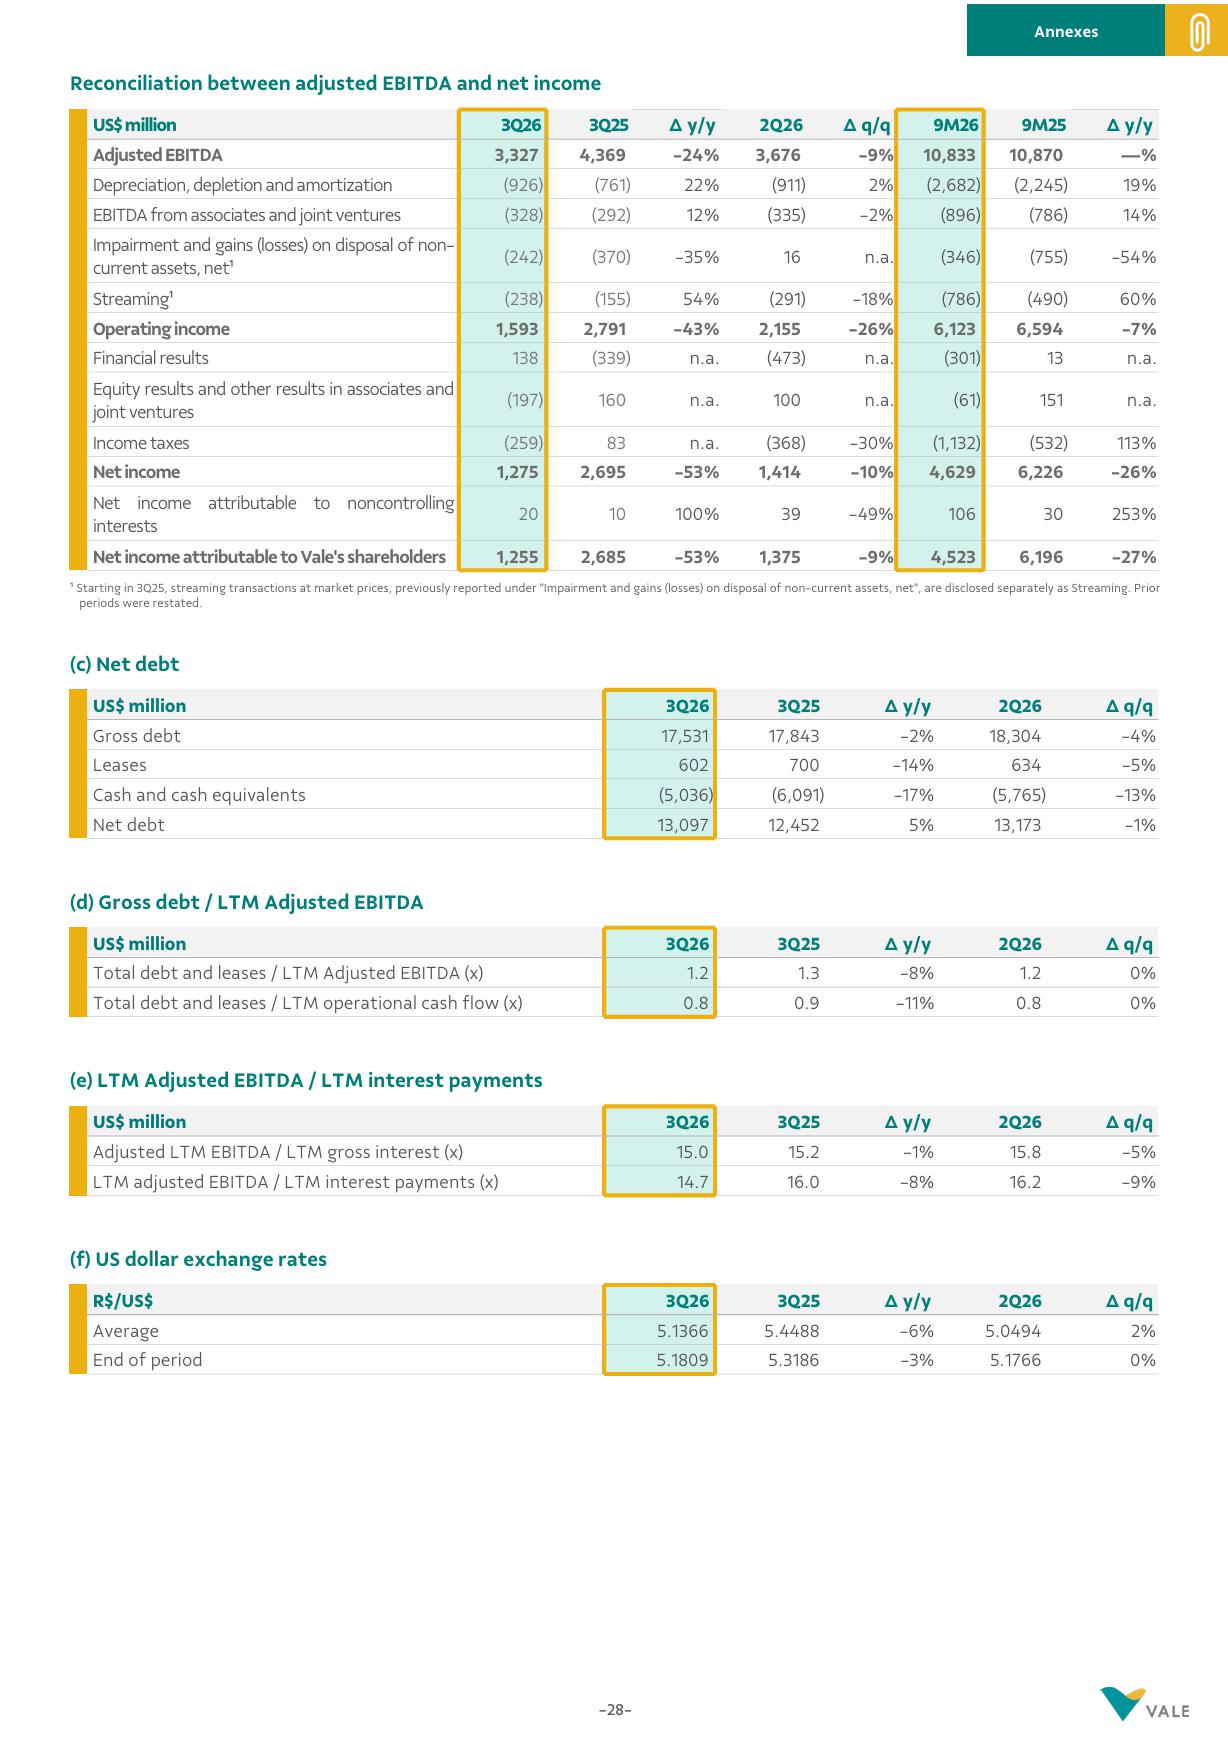
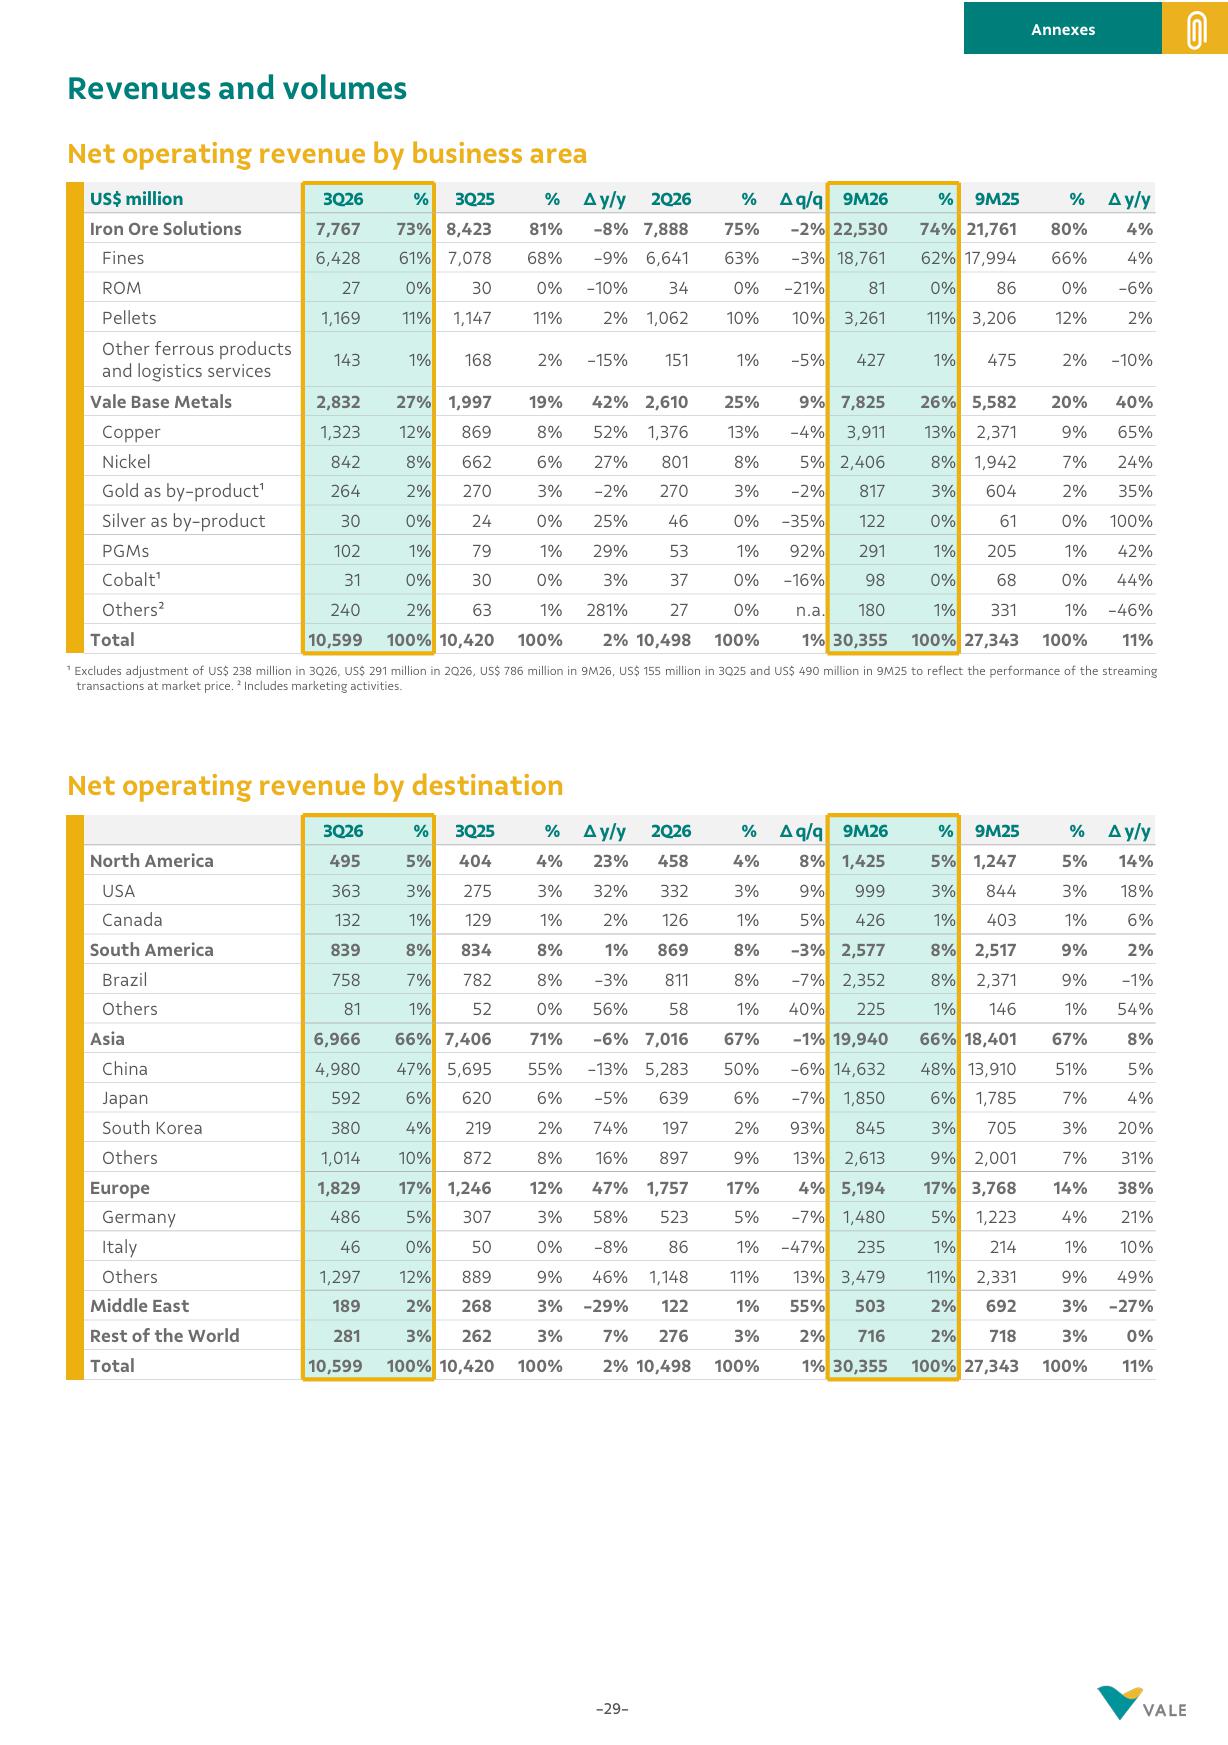
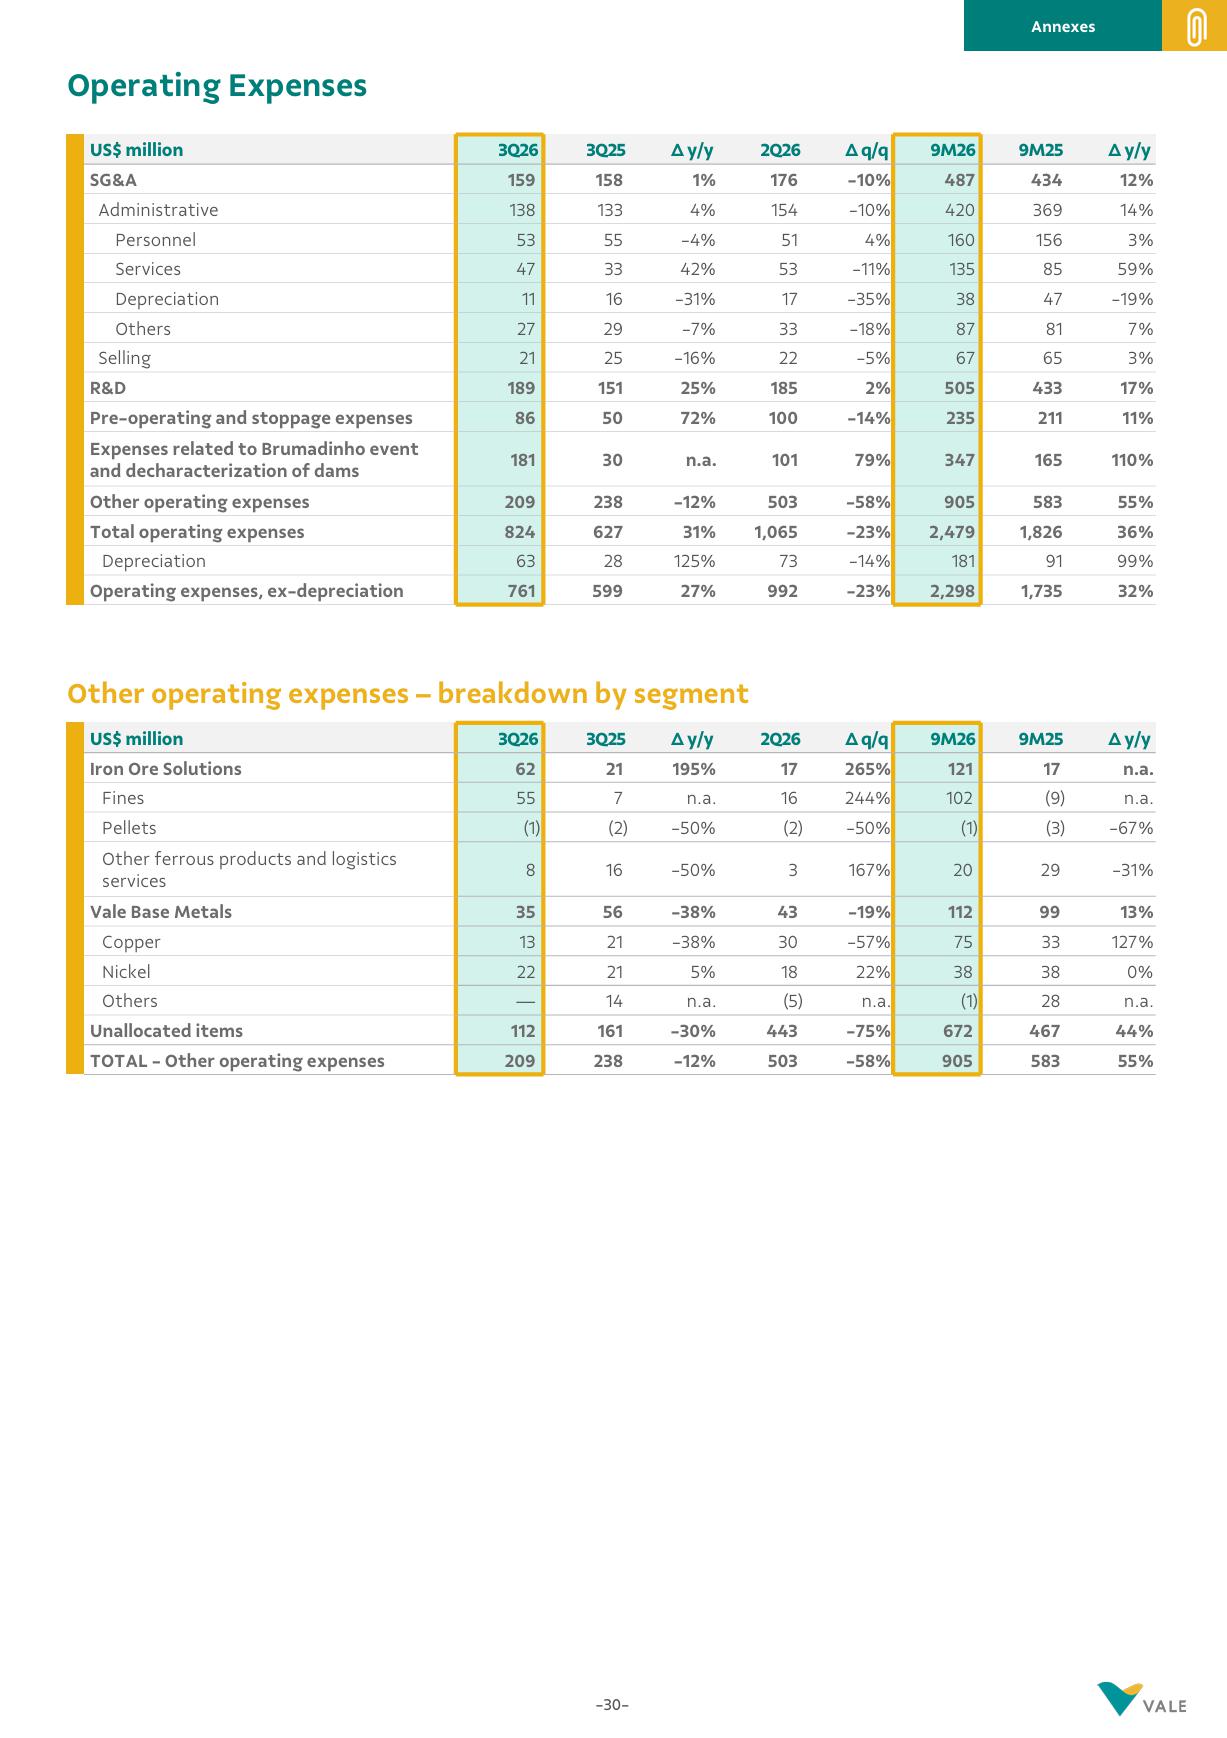
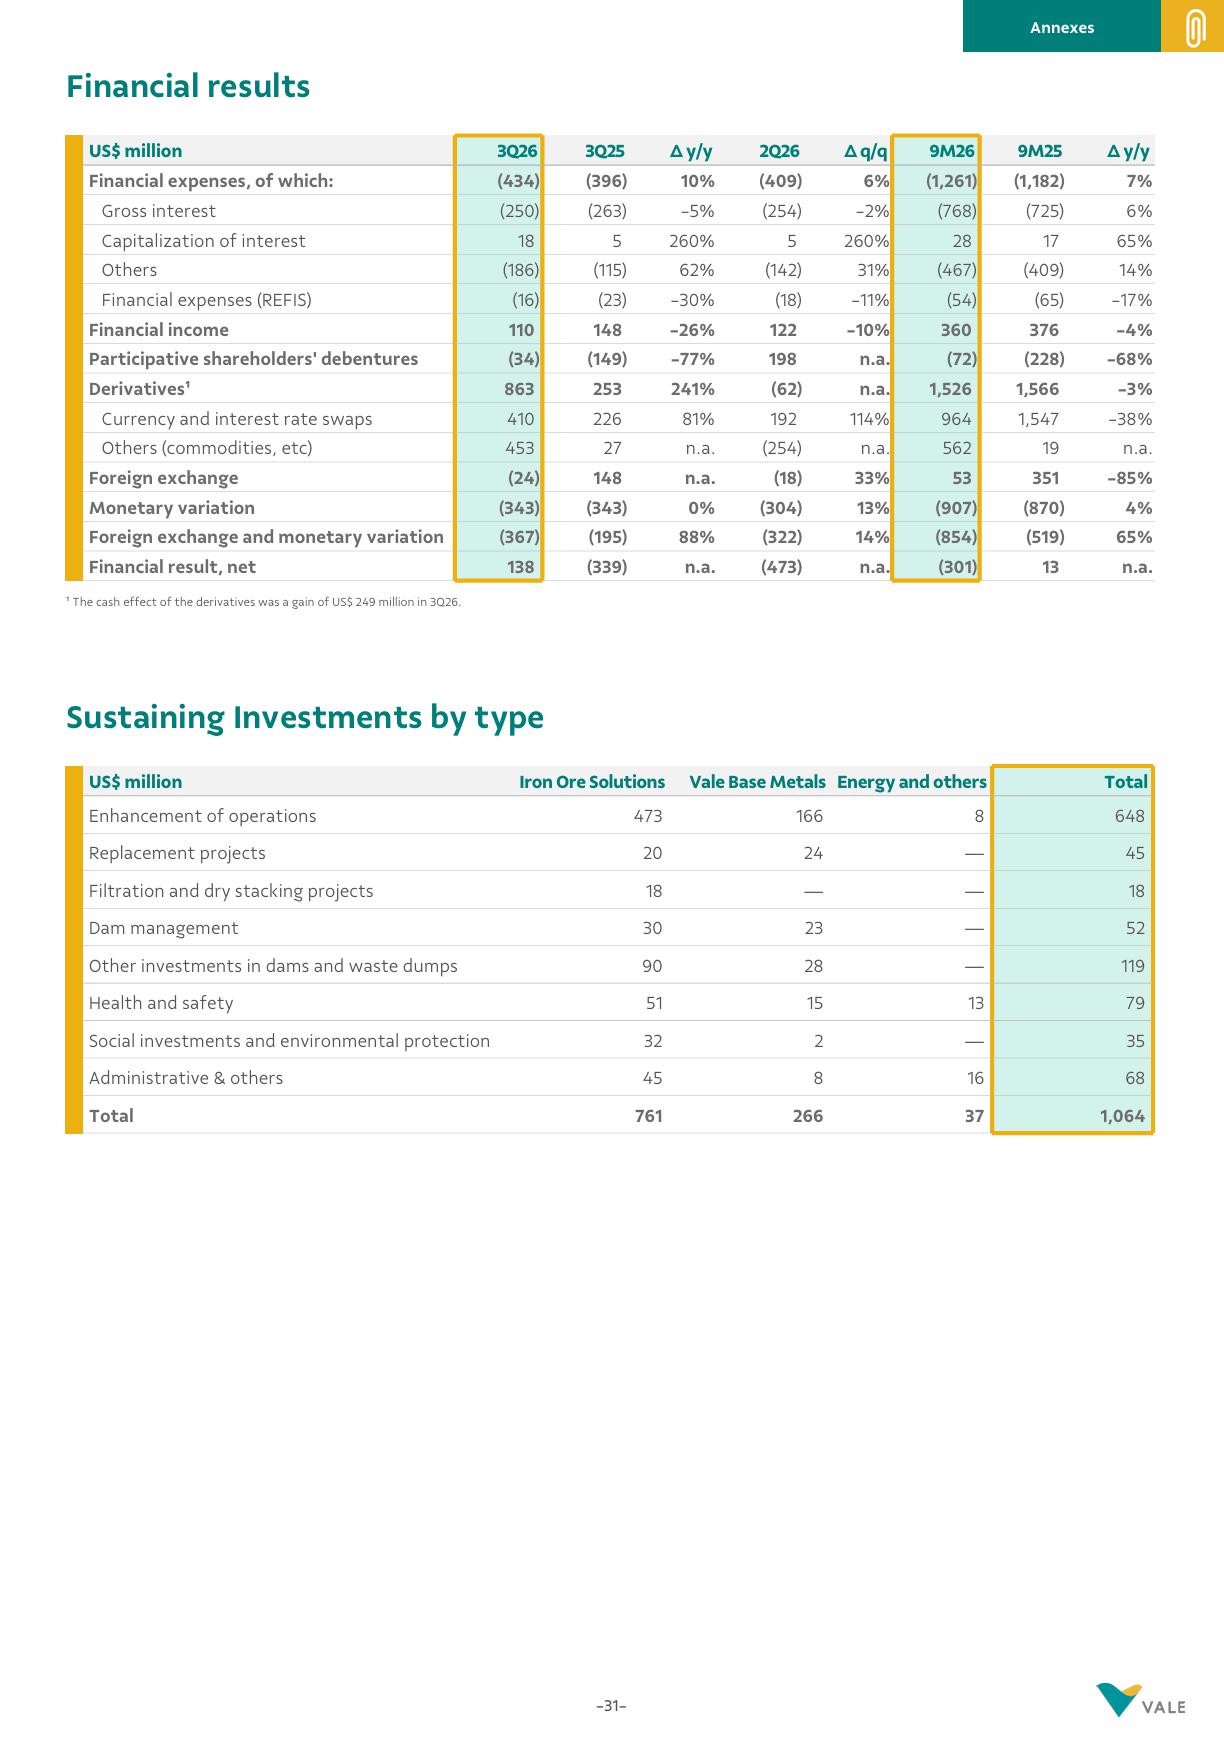
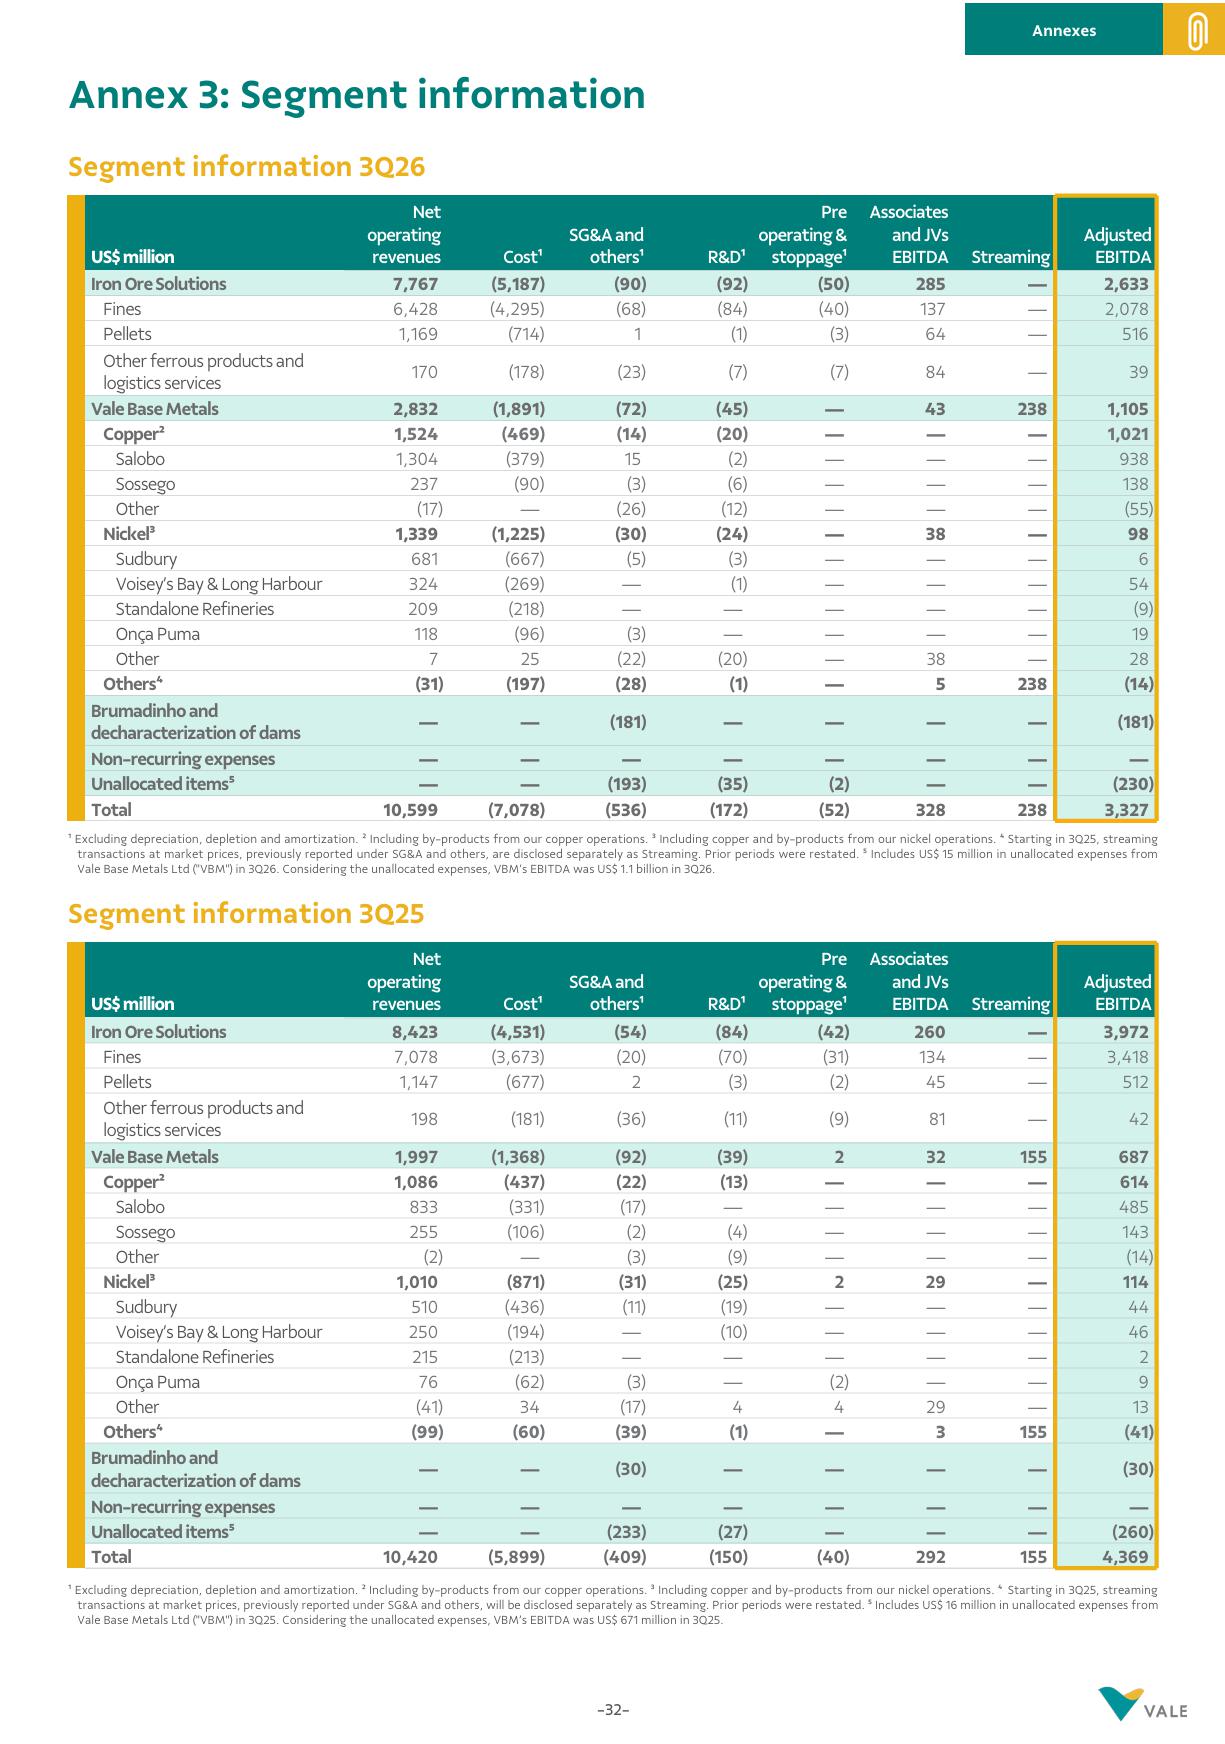
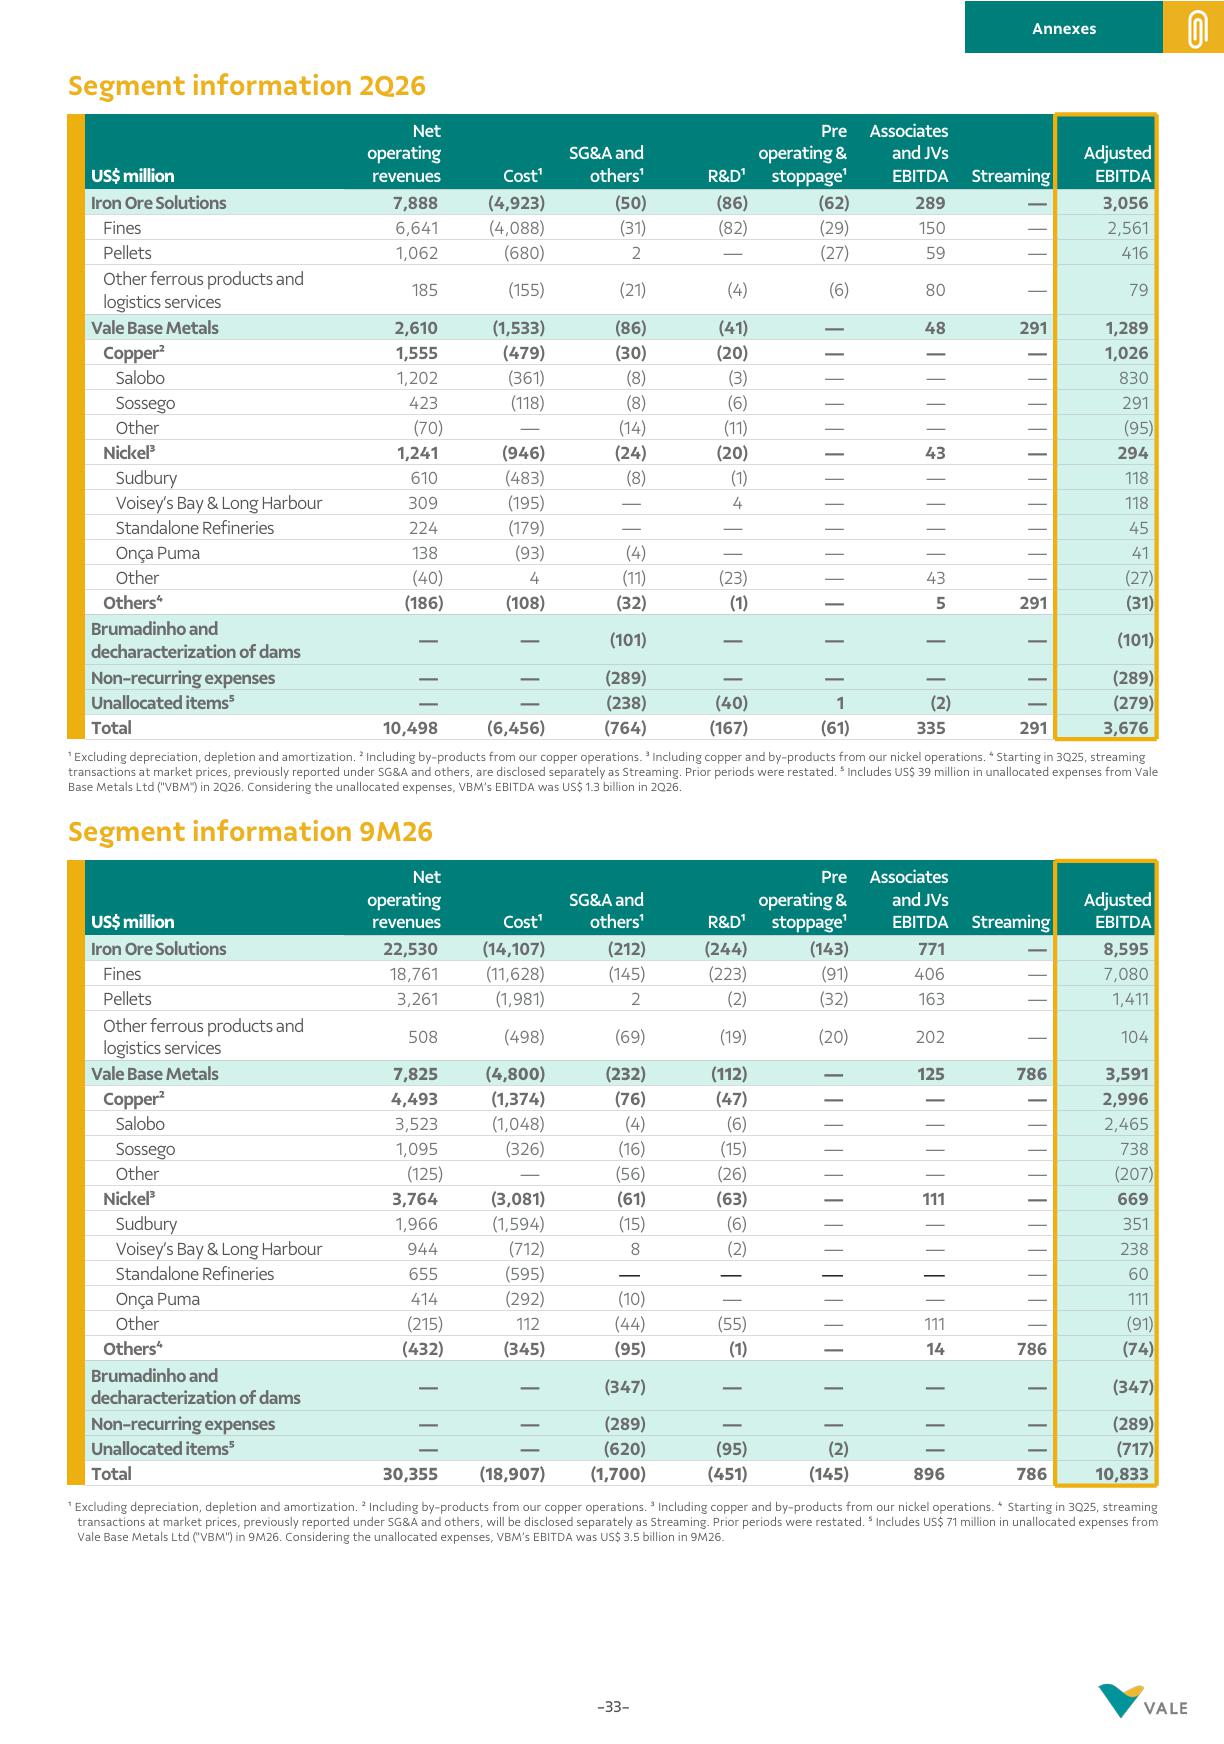
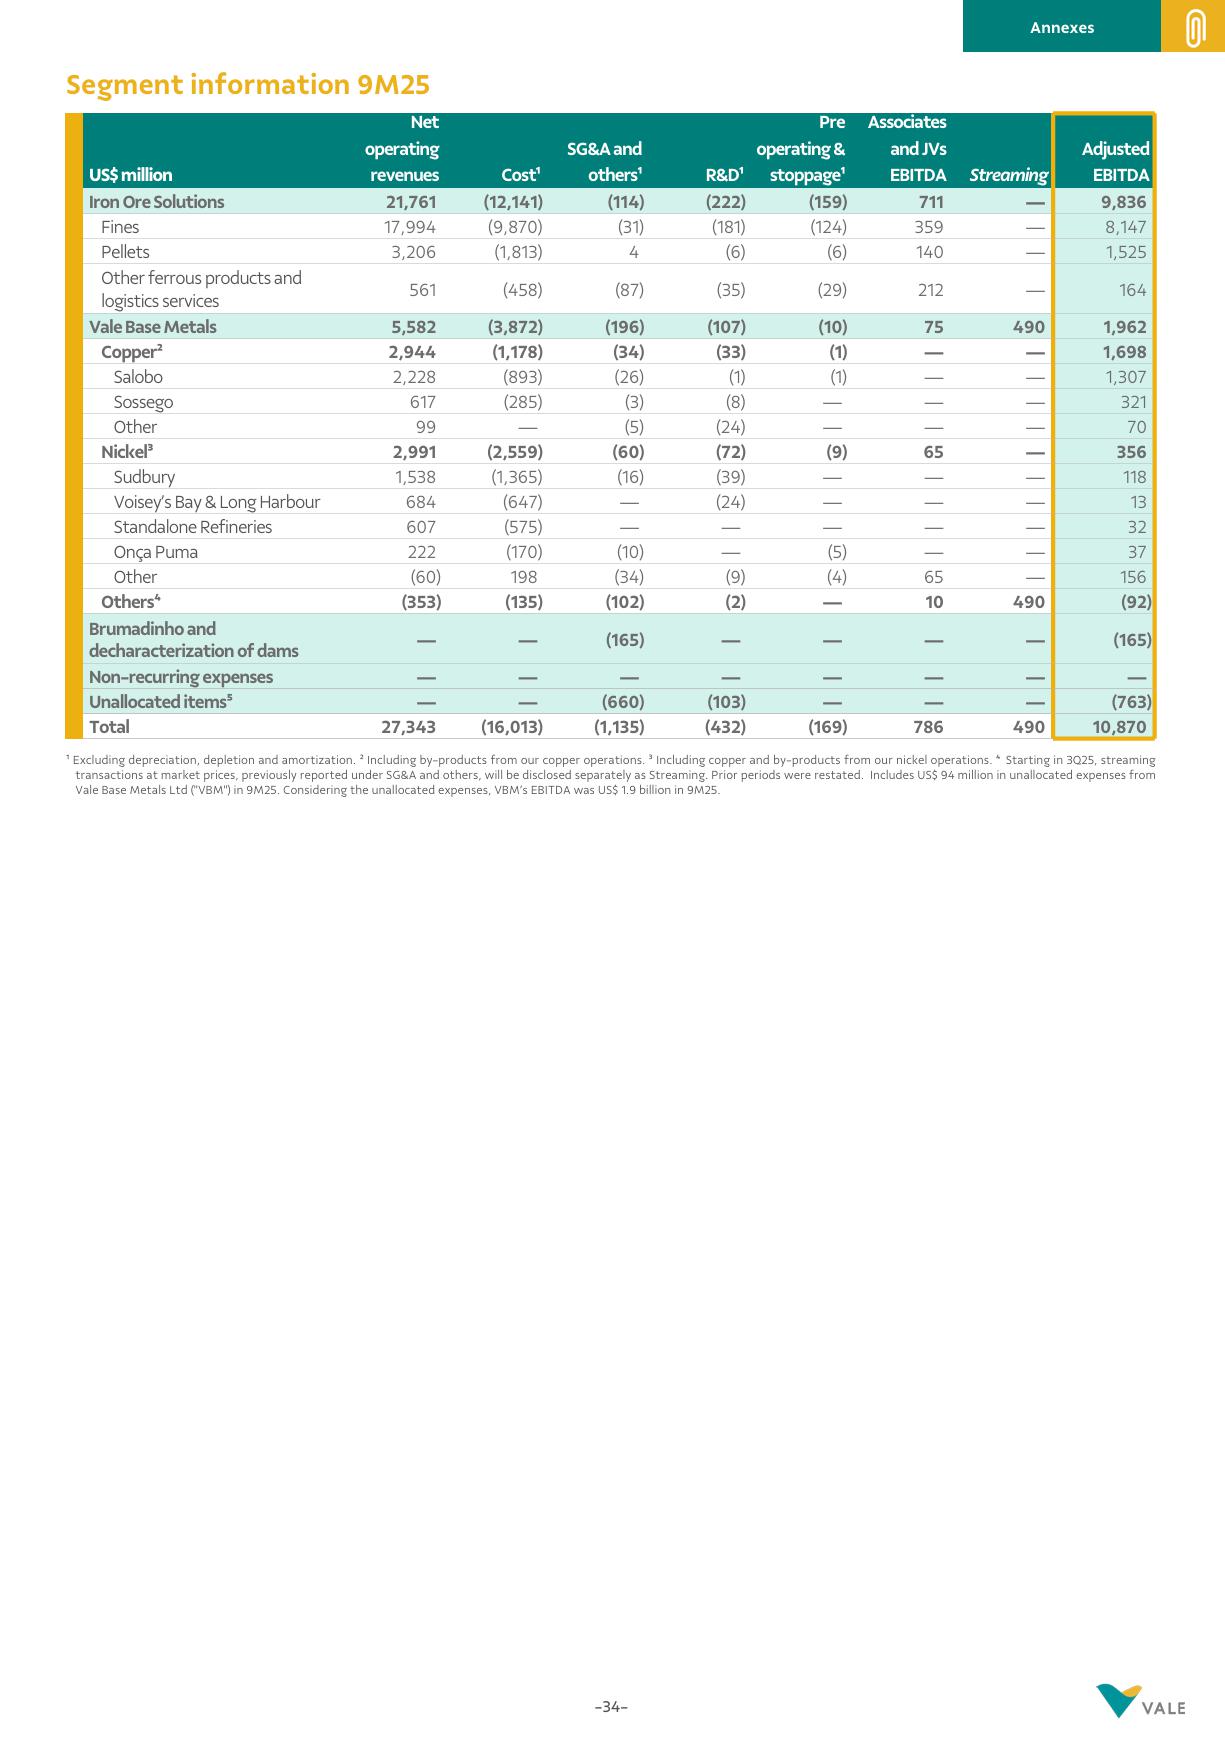
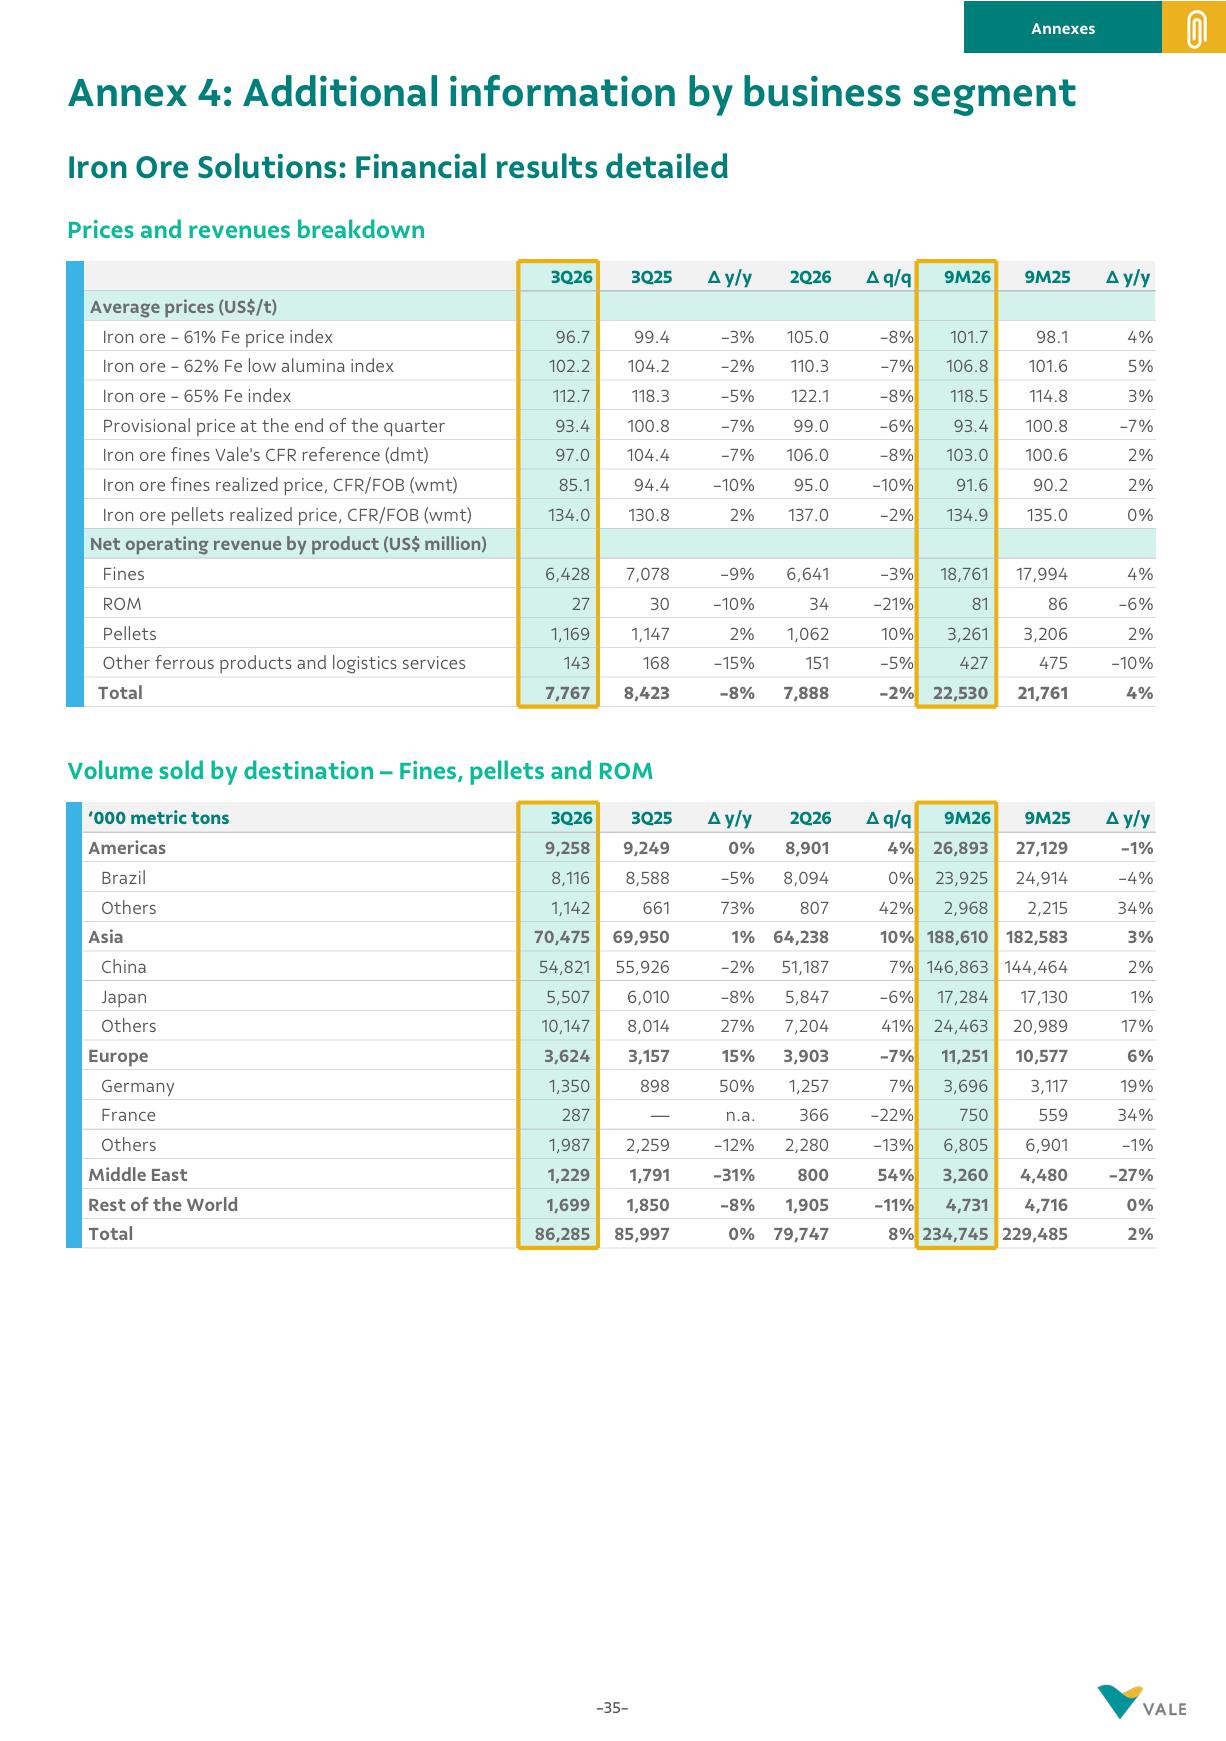
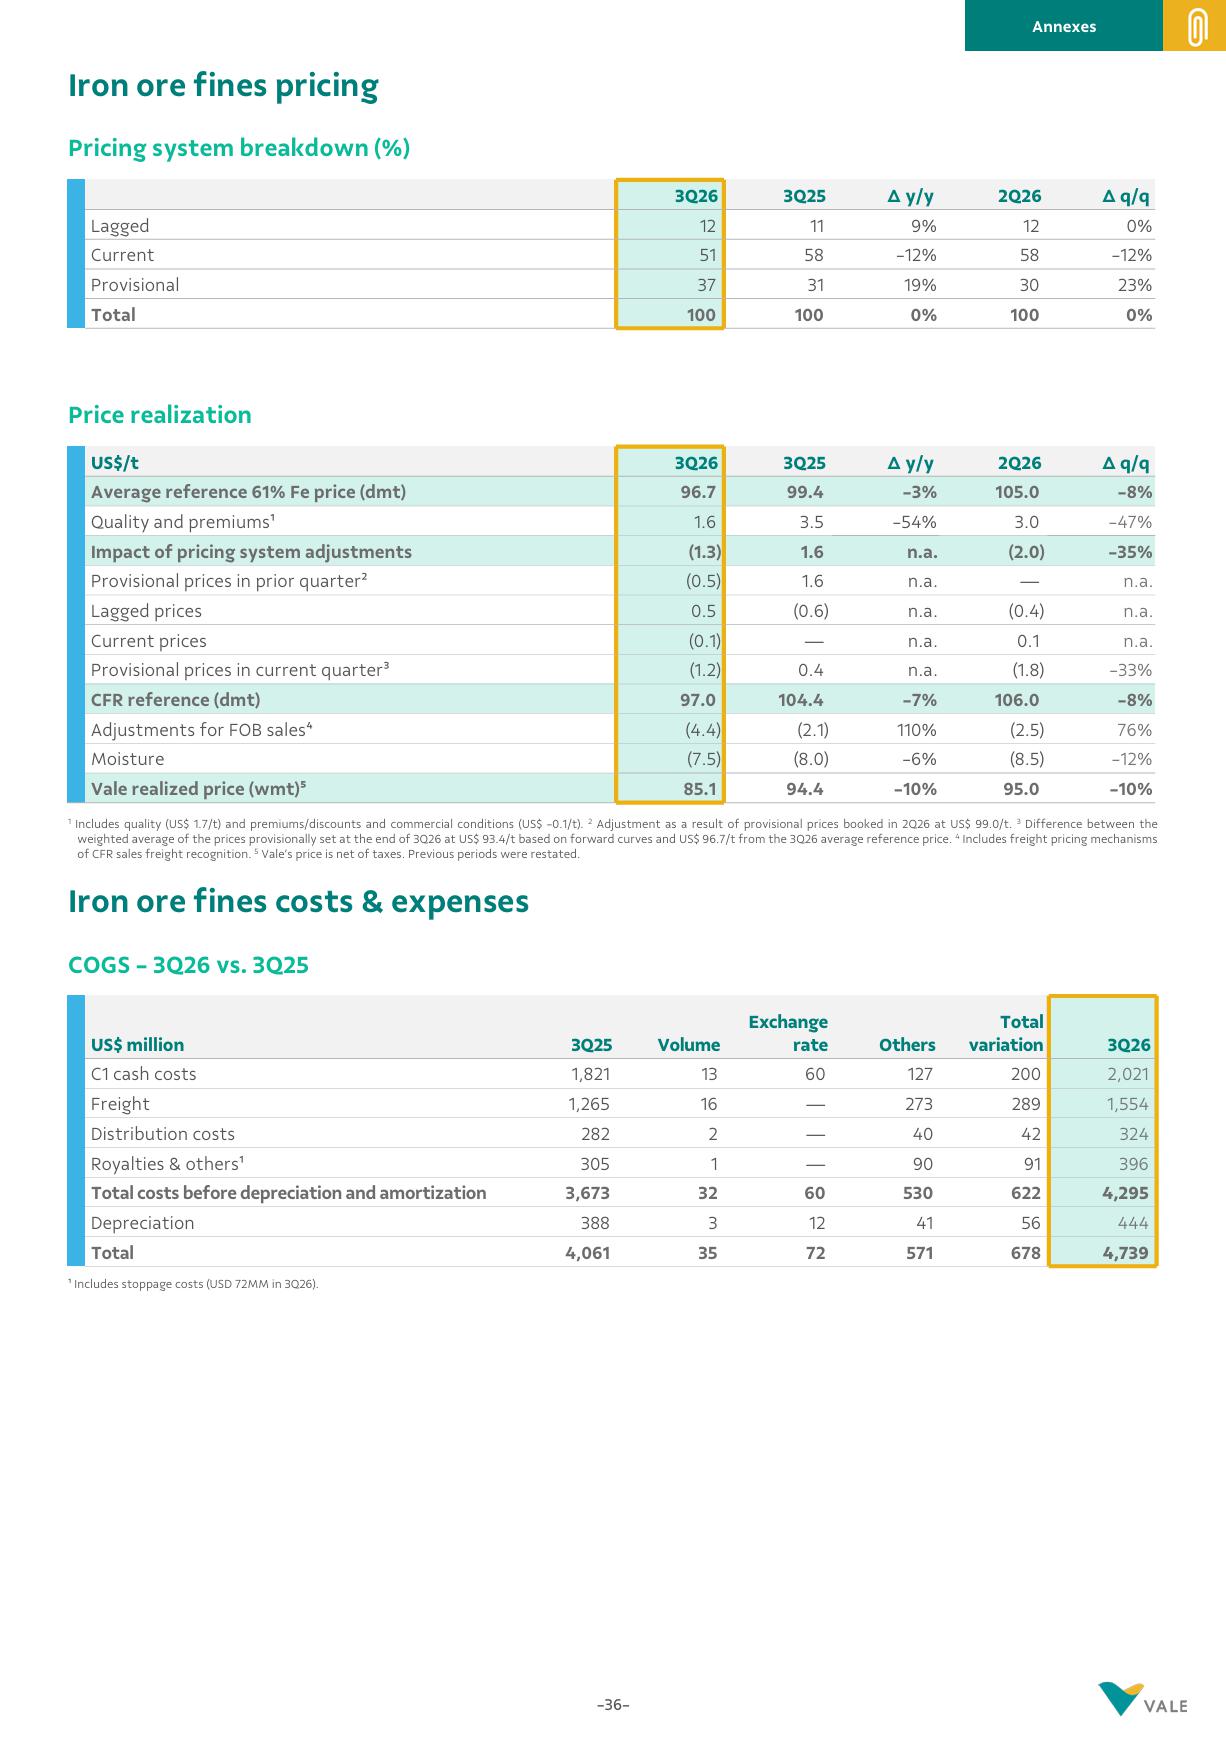
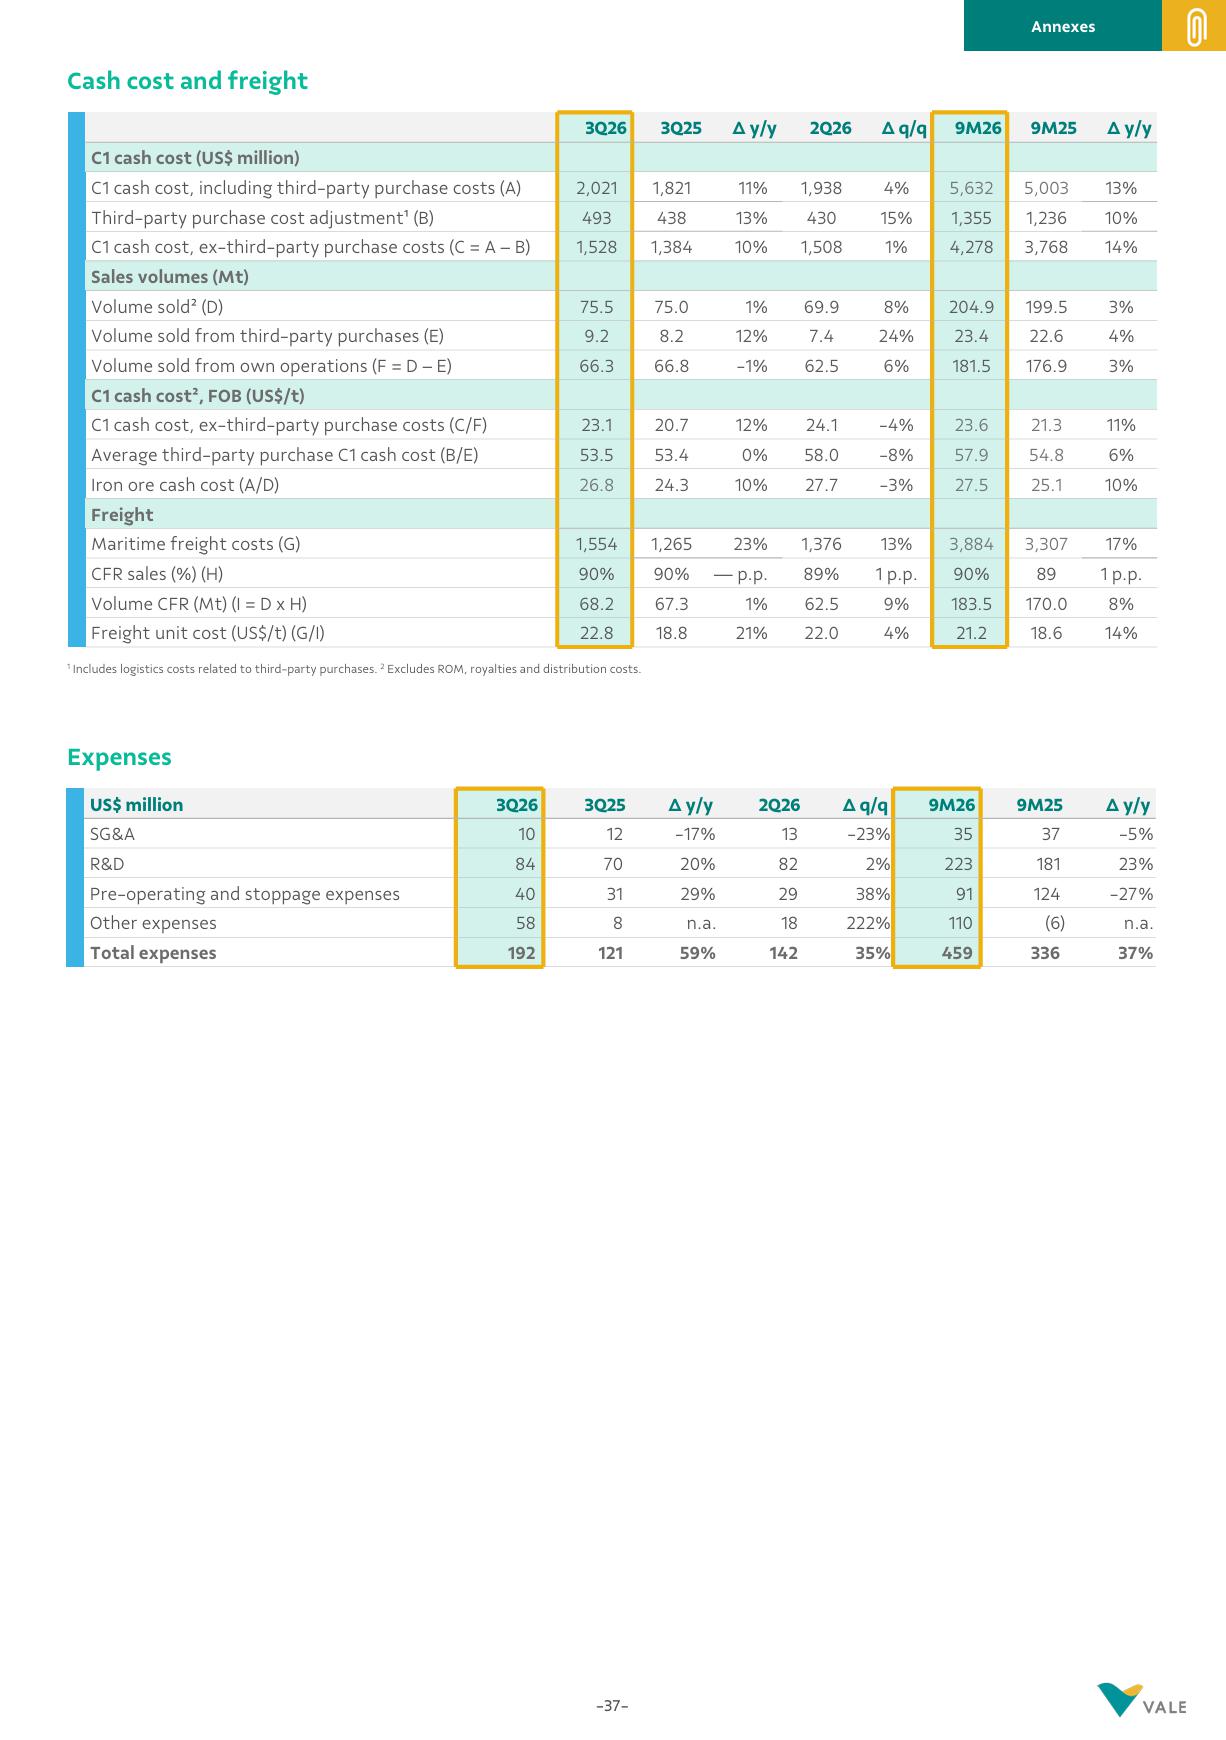
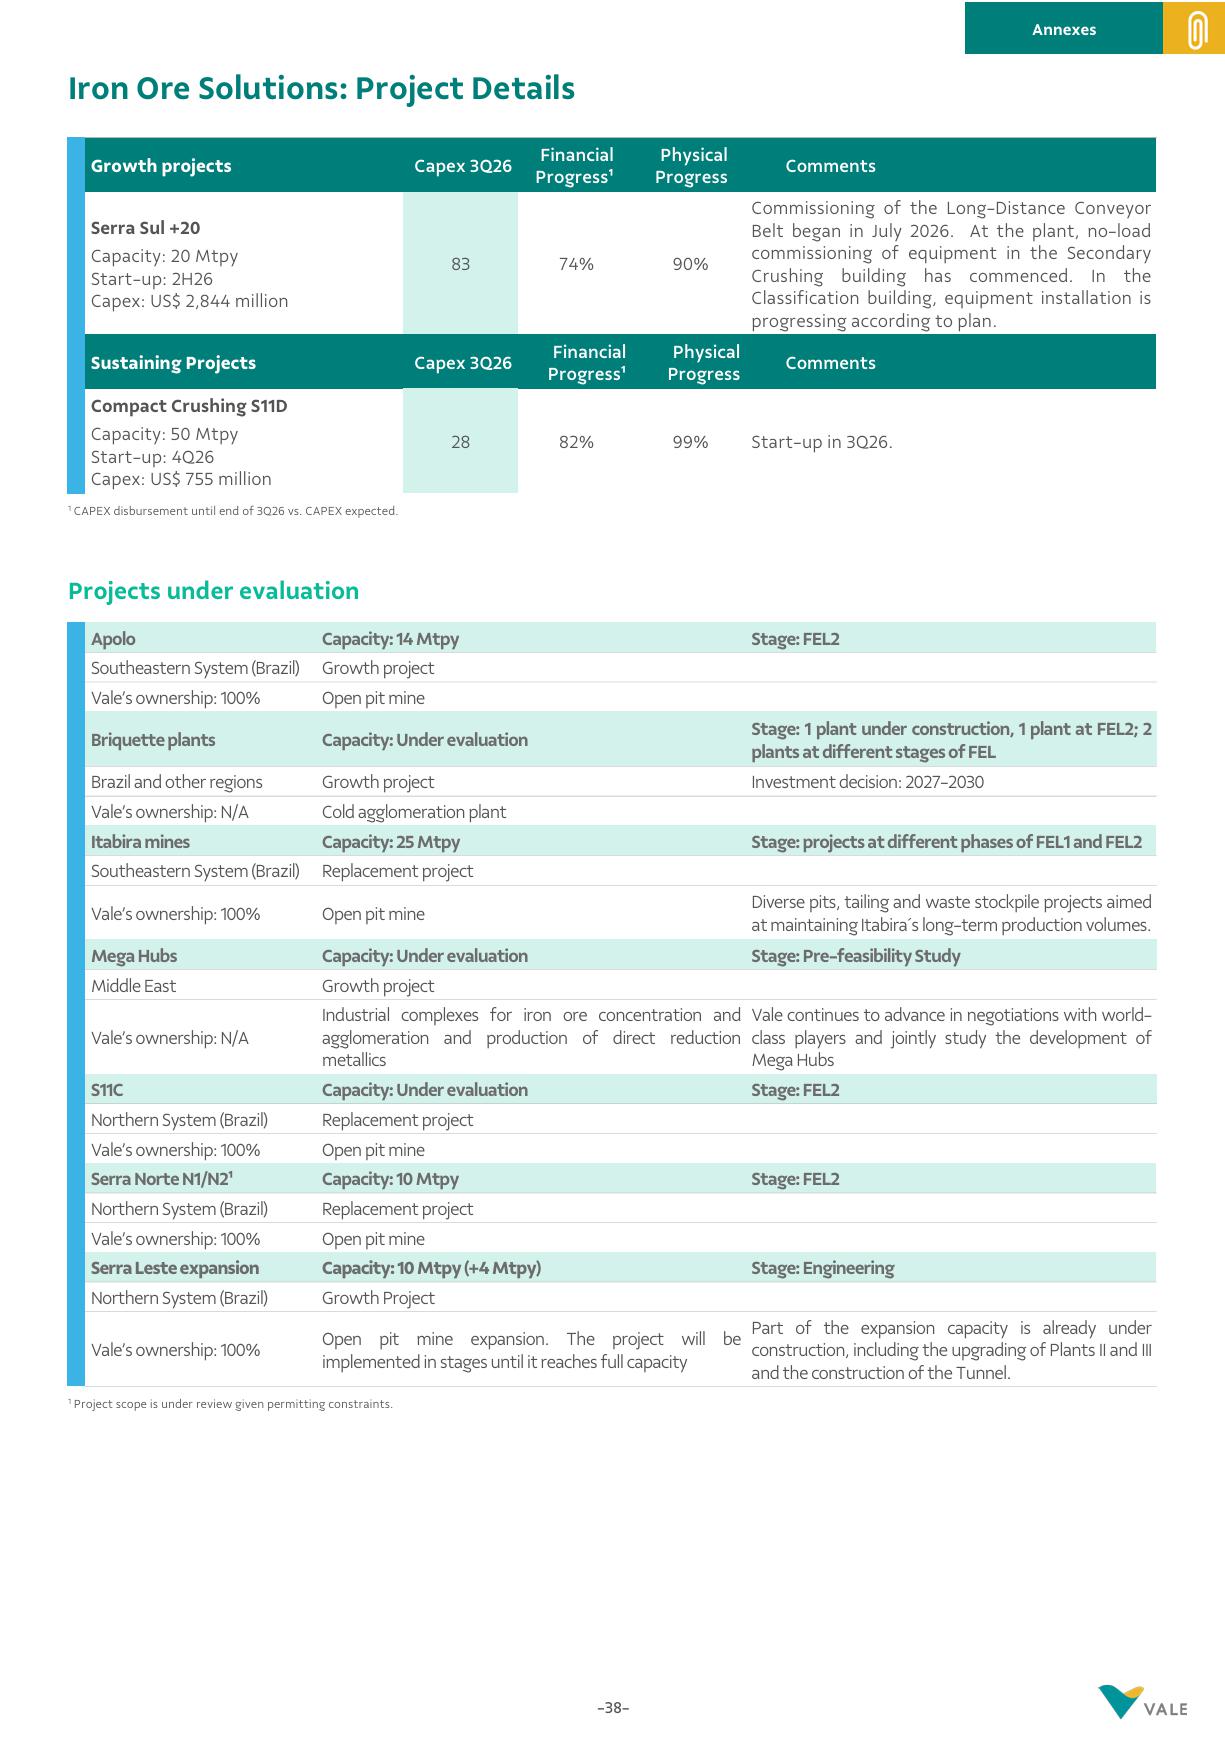
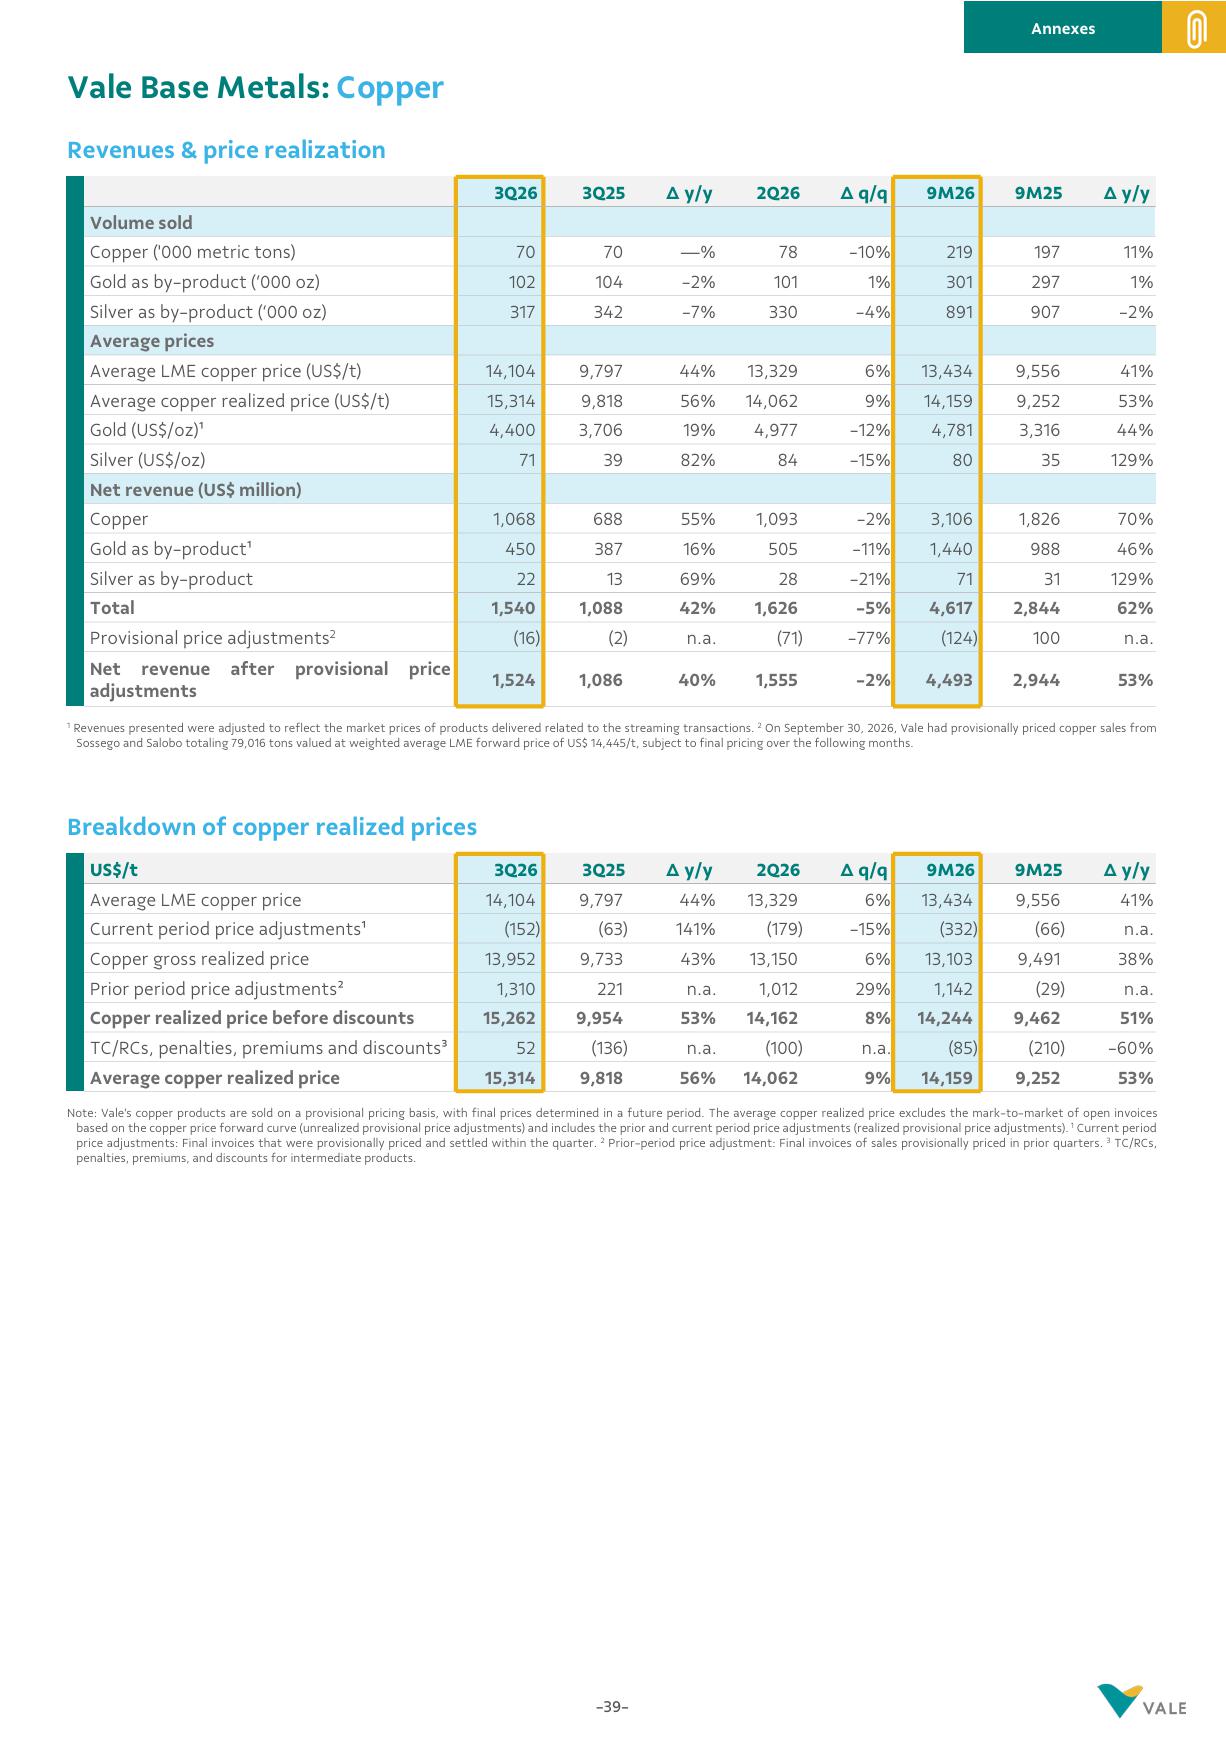
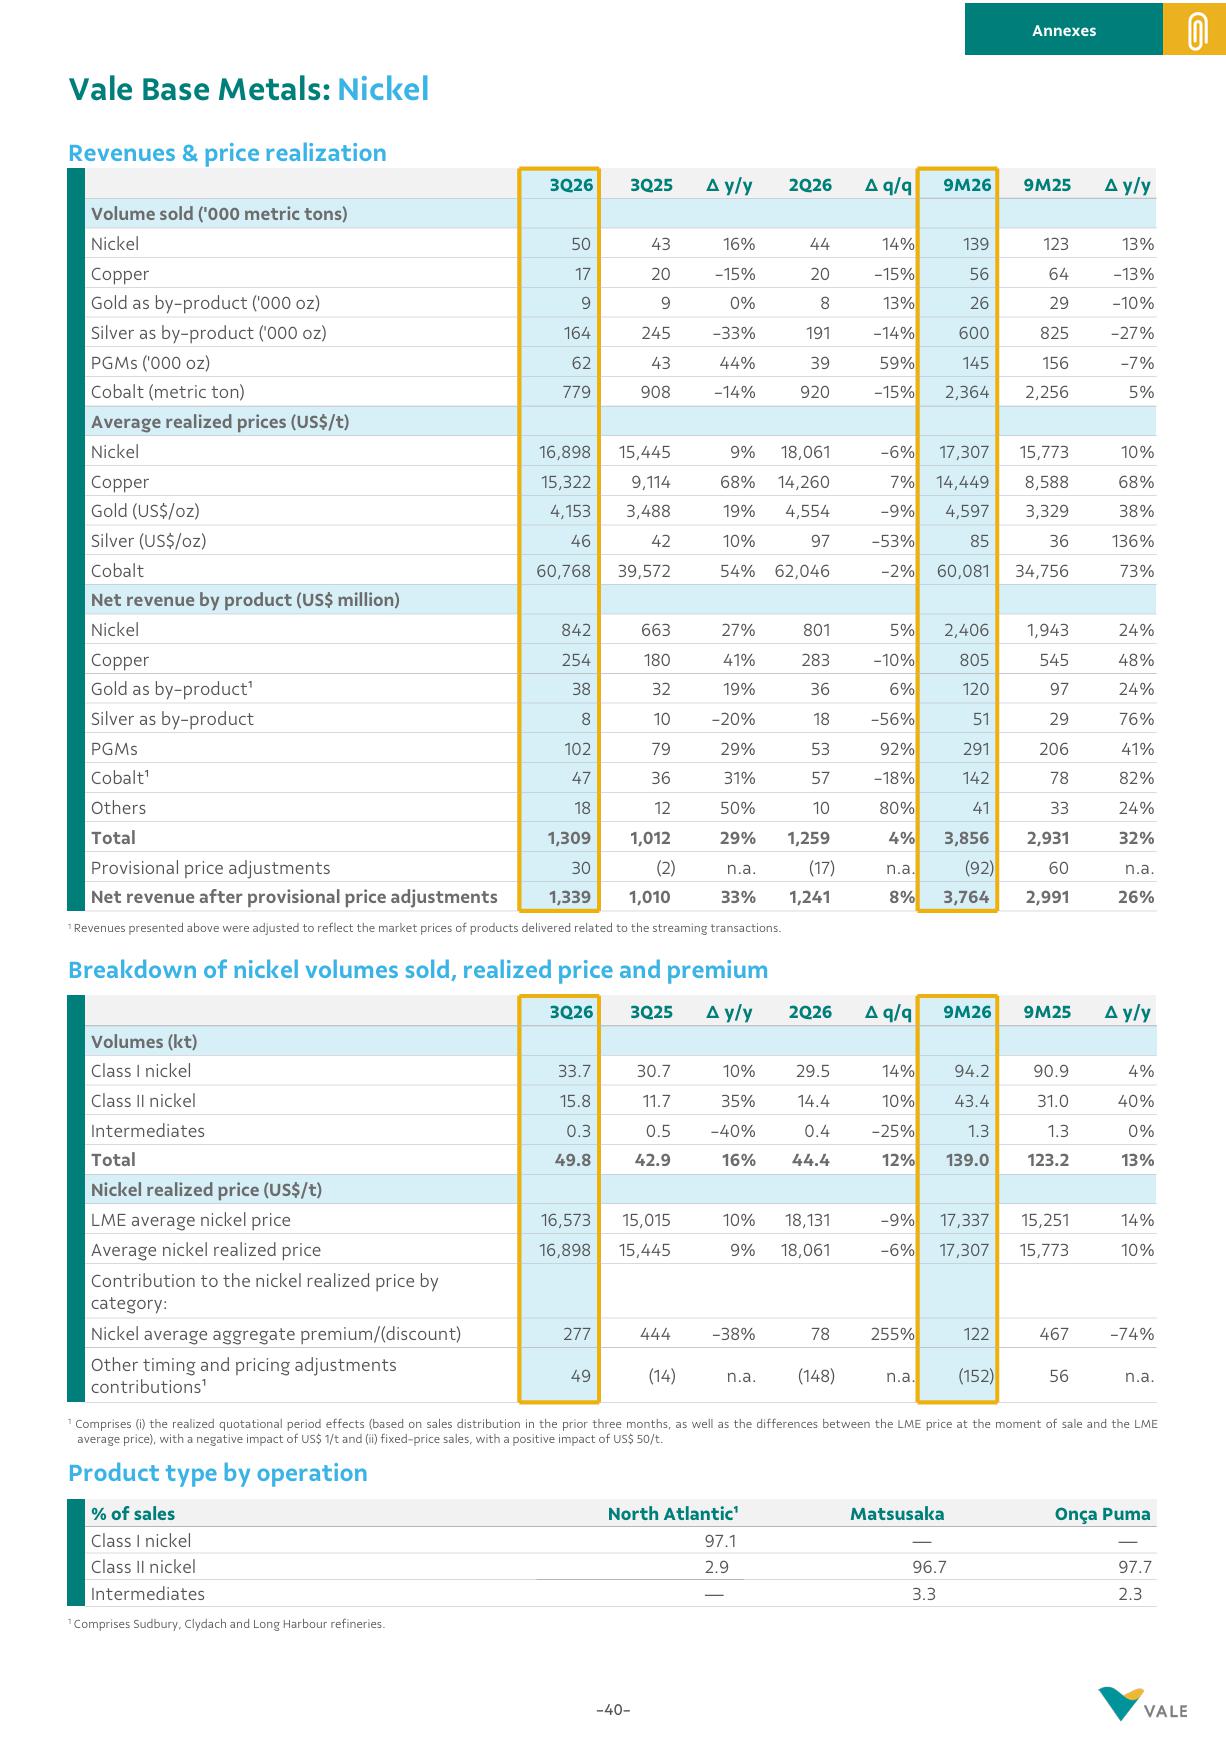
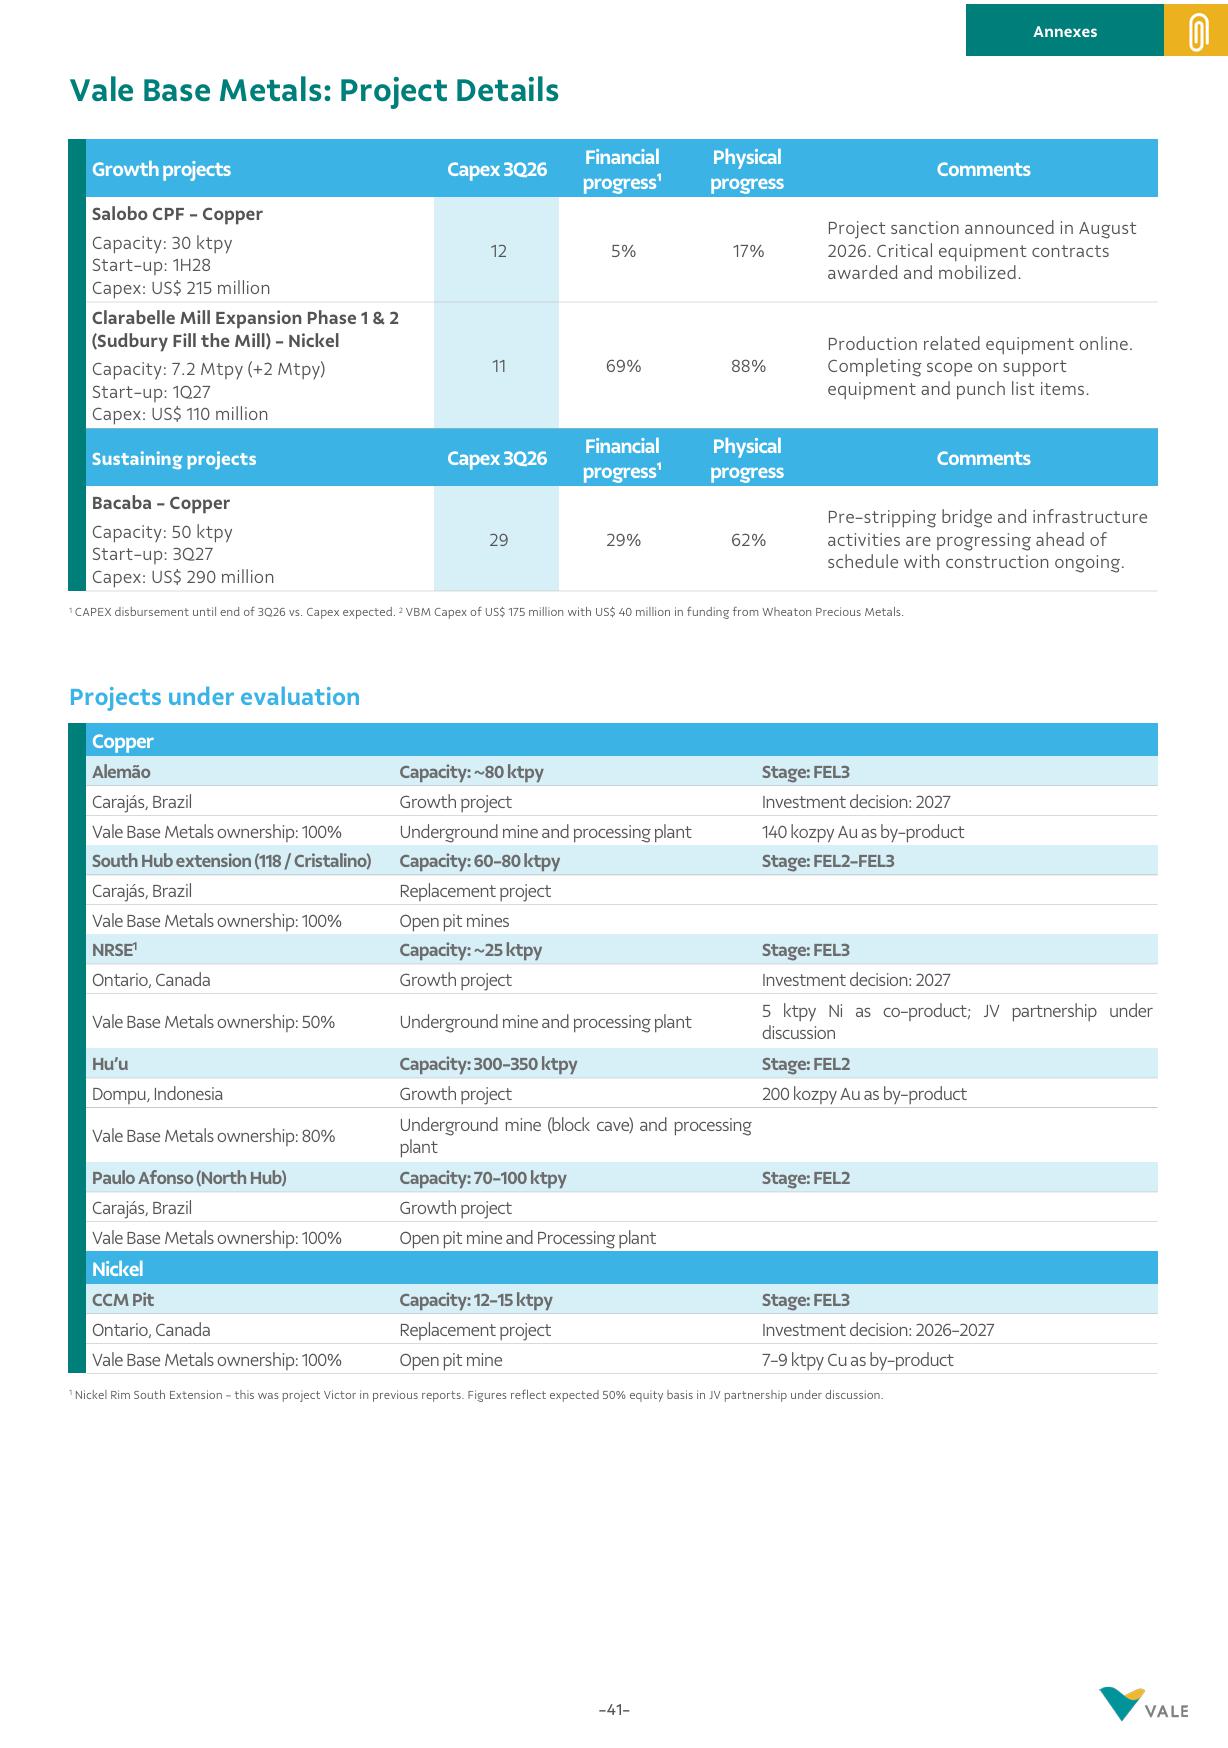
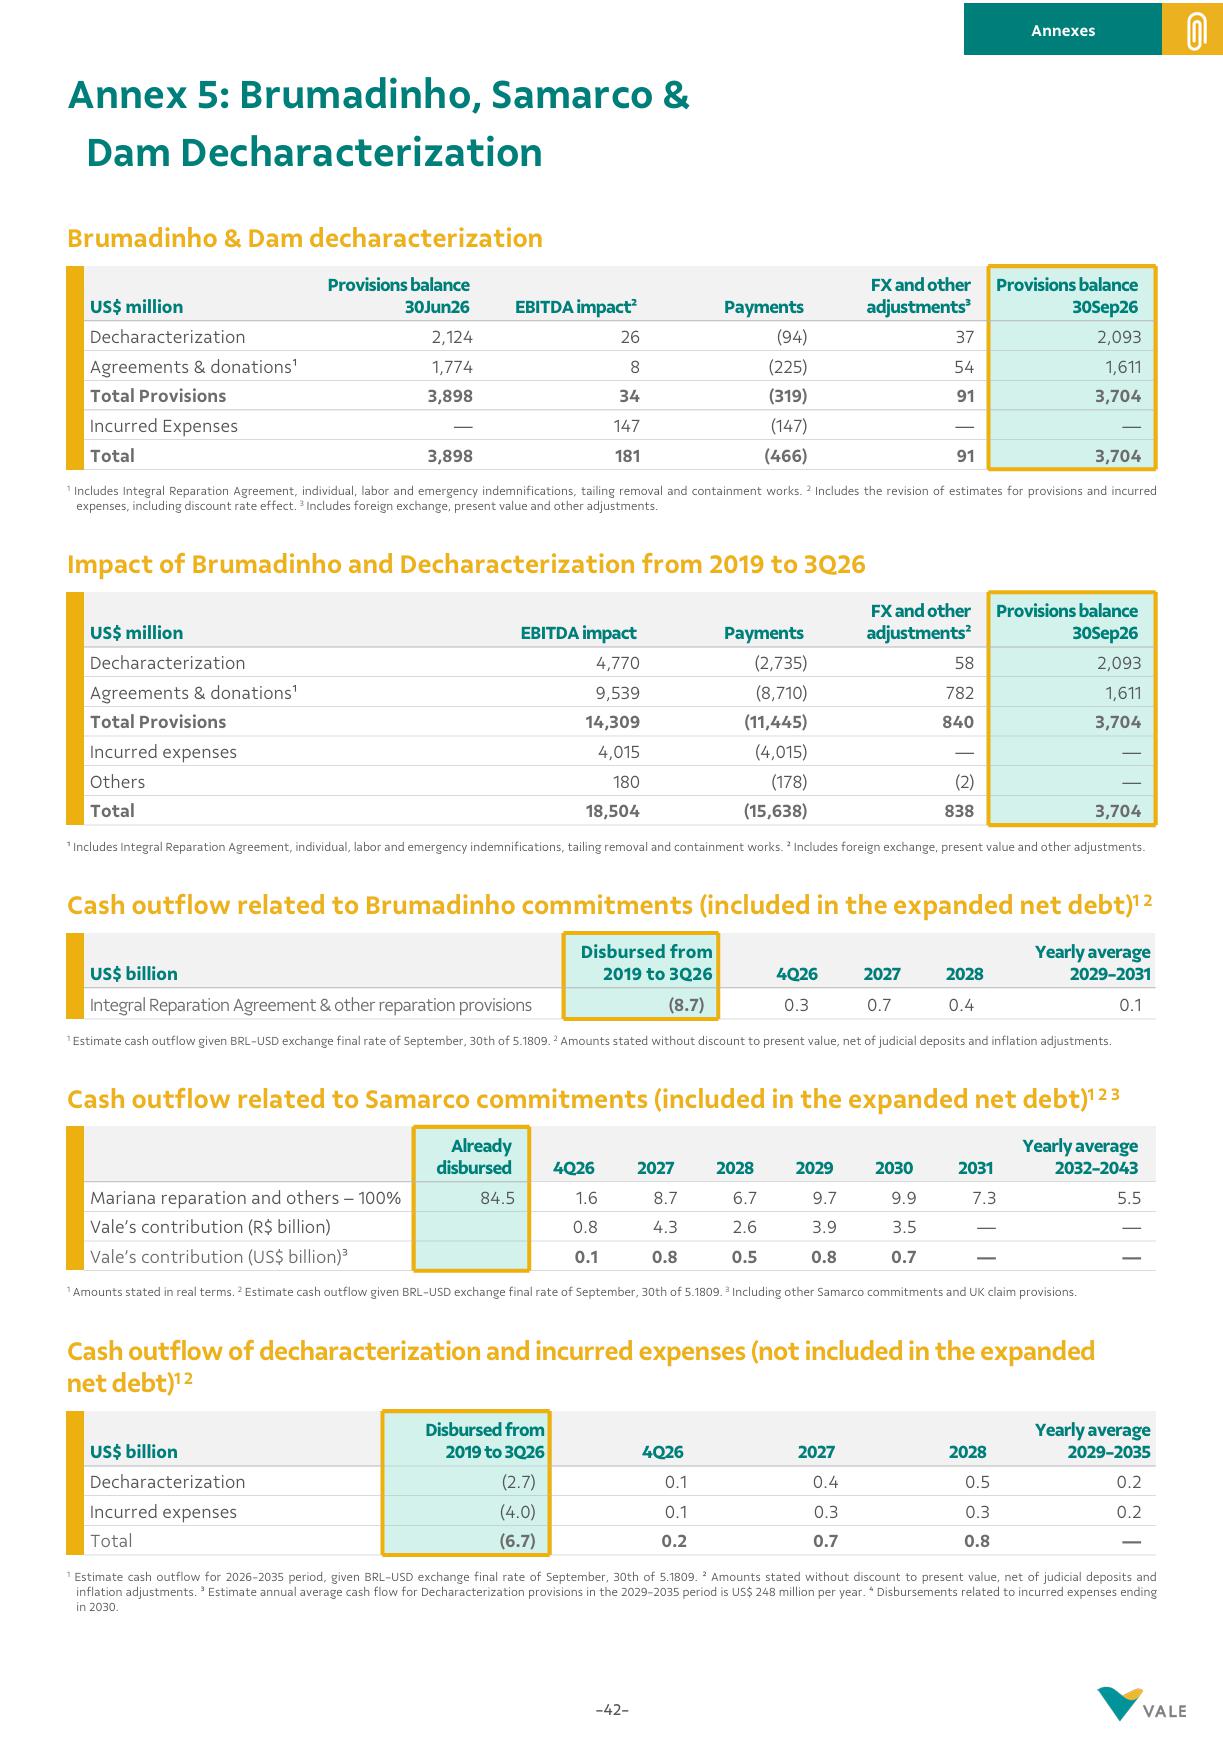
Signatures
Pursuant to the requirements of the Securities Exchange Act of 1934, the registrant has duly caused this report to be signed on its behalf by the undersigned, thereunto duly authorized.
| Vale S.A. (Registrant) | ||
| By: | /s/ Thiago Lofiego | |
| Date: October 29, 2026 | Director of Investor Relations | |