Please wait

Exhibit 2


LOGO

Third Quarter Results 2026


LOGO

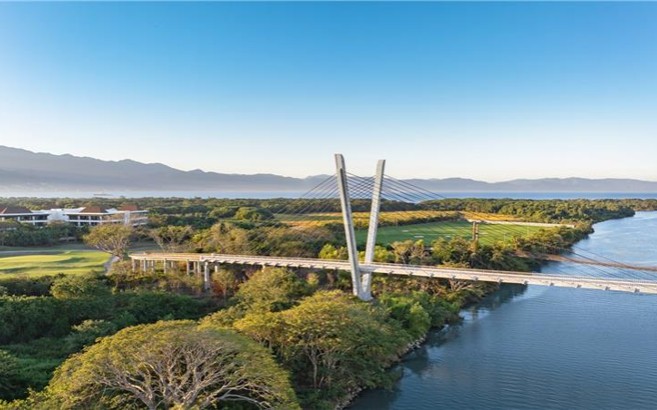
Cable-Stayed Bridge, Nayarit, Mexico


  Stock Listing Information    Investor Relations   
  NYSE (ADS)    In the United States:   
  Ticker: CX    + 1 877 7CX NYSE   
  Mexican Stock Exchange (CPO)    In Mexico:   
  Ticker: CEMEX.CPO    + 52 (81) 8888 4327   
  Ratio of CEMEXCPO to CX = 10:1    E-Mail: ir@cemex.com   


   LOGO
Operating and financial highlights     


     January - September     Third Quarter  
     2026     2025     % var     l-t-l
% var
    2026     2025     % var     l-t-l
% var
 

Consolidated volumes


Domestic gray cement

     32,984       32,456       2 %        11,492       11,145       3 %   

Ready-mix

     31,989       32,506       (2 %)        11,043       11,314       (2 %)   

Aggregates

     97,319       98,650       (1 %)        34,179       35,084       (3 %)   


Sales

     13,203       11,952       10 %      5 %      4,590       4,245       8 %      5 % 

Gross profit

     4,567       3,948       16 %      9 %      1,628       1,426       14 %      10 % 

as % of Sales

     34.6 %      33.0 %      1.6 pp        35.5 %      33.6 %      1.9 pp   

Operating earnings before other income and expenses, net

     1,785       1,332       34 %      26 %      652       547       19 %      15 % 

as % of Sales

     13.5 %      11.1 %      2.4 pp        14.2 %      12.9 %      1.3 pp   

SG&A expenses as a % of Sales

     8.8 %      9.6 %      (0.8 pp)        8.1 %      8.7 %      (0.6 pp)   

Controlling interest net income (loss)

     982       1,316       (25 %)        407       264       55 %   

Operating EBITDA

     2,802       2,299       22 %      16 %      990       882       12 %      9 % 

as % of Sales

     21.2 %      19.2 %      2.0 pp        21.6 %      20.8 %      0.8 pp   


Free cash flow from operations

     1,389       473       194 %        723       540       34 %   


Total debt

     6,075       6,789       (11 %)        6,075       6,789       (11 %)   

Earnings (loss) of continuing operations per ADS

     0.68       0.47       43 %        0.28       0.16       76 %   

Fully diluted earnings (loss) of continuing operations per ADS

     0.67       0.47       44 %        0.28       0.16       77 %   

Average diluted ADSs outstanding (1) (2)

     1,460       1,470       (1 %)        1,458       1,471       (1 %)   


Average ADSs outstanding (1)

     1,443       1,448       (0 %)        1,441       1,449       (1 %)   


Employees

     38,023       40,244       (6 %)        38,023       40,244       (6 %)   


Cement and aggregates volumes in thousands of metric tons. Ready-mix volumes in thousands of cubic meters. In millions of U.S. dollars, except volumes, percentages, employees, and per-ADS amounts. Average ADSs outstanding are presented in millions.


(1) 

Average ADSs outstanding equals the total number of Series A shares and Series B shares outstanding as if they were all held in ADS form.

(2) 

The calculation of Average diluted ADSs outstanding also includes the restricted ADSs allocated to eligible employees as variable compensation.


Consolidated Net Sales reached US$4.6 billion in 3Q26, an 8% increase from 3Q25, supported by higher consolidated prices and improving gray cement volume trends in most markets.

Cost of sales, as a percentage of Net Sales, decreased by 1.9pp to 64.5% in 3Q26 and by 1.6pp to 65.4% on a year-to-date basis, compared with the corresponding periods last year, driven by operational efficiencies under Project Cutting Edge.

Operating expenses, as a percentage of Net Sales, increased by 0.6pp to 21.3% in 3Q26 and decreased by 0.8pp to 21.1% on a year-to-date basis, compared with the corresponding periods last year. The year-to-date improvement was driven by savings under Project Cutting Edge.

Operating EBITDA reached US$990 million in 3Q26, increasing 12% from 3Q25, reflecting the combined benefits of our transformation, higher pricing, growing gray cement volumes, and favorable FX movements. This marks the fifth consecutive quarter with double-digit Operating EBITDA growth.

Operating EBITDA margin in 3Q26 increased 0.8pp year-over-year to 21.6%. Expansion is largely explained by pricing increases, lower energy prices in our cement operations, and improved profitability in our Urbanization Solutions business.

Controlling interest net income reached US$407 million in 3Q26, a 55% increase year-over-year driven mainly by higher Operating earnings.


2026 Third Quarter Results


Page 2


   LOGO
Operating results     


Mexico


     January - September     Third Quarter  
     2026     2025     % var     l-t-l % var     2026     2025     % var     l-t-l % var  

Sales

     3,866       3,158       22 %      10 %      1,299       1,117       16 %      9 % 

Operating EBITDA

     1,425       1,025       39 %      24 %      480       369       30 %      22 % 

Operating EBITDA margin

     36.9 %      32.4 %      4.5 pp        37.0 %      33.1 %      3.9 pp   

In millions of U.S. dollars; except percentages.


     Domestic gray cement     Ready-mix     Aggregates  
Year-over-year percentage variation    January -
September
    Third Quarter     January -
September
    Third Quarter     January -
September
    Third Quarter  

Volume

     7 %      7 %      (3 %)      (2 %)      2 %      (2 %) 

Price (USD)

     17 %      12 %      15 %      11 %      16 %      11 % 

Price (local currency)

     6 %      5 %      3 %      4 %      4 %      4 % 

All price variations are based on FOB prices. Price (local currency) for EMEA, Europe, MEA, and SCAC calculated on a volume-weighted-average basis at constant foreign-exchange rates.

Mexico delivered another strong quarter supported by growing cement demand and cost efficiencies, leading to a double-digit increase in Operating EBITDA year-over-year for the quarter.

Sequentially, cement pricing remained stable after adjusting for mix effect, while ready-mix prices increased 2%.

Year-over-year cement volume growth was supported by a healthy residential sector and government-backed social programs, including housing and Rural Roads. Industry demand is expected to remain constructive, reflecting higher infrastructure spending and continued momentum in residential construction in 2027. In ready-mix, the orderbook continues to expand sequentially, especially on infrastructure projects.

United States


     January - September     Third Quarter  
     2026     2025     % var     l-t-l % var     2026     2025     % var     l-t-l % var  

Sales

     3,884       3,806       2 %      2 %      1,373       1,310       5 %      5 % 

Operating EBITDA

     697       738       (5 %)      (5 %)      259       269       (4 %)      (4 %) 

Operating EBITDA margin

     18.0 %      19.4 %      (1.4 pp)        18.9 %      20.6 %      (1.7 pp)   

In millions of U.S. dollars; except percentages.


     Domestic gray cement     Ready-mix     Aggregates  
Year-over-year percentage variation    January -
September
    Third Quarter     January -
September
    Third Quarter     January -
September
    Third Quarter  

Volume

     1 %      4 %      (0 %)      (1 %)      5 %      4 % 

Price (USD)

     (3 %)      (4 %)      (0 %)      1 %      1 %      (1 %) 

Price (local currency)

     (3 %)      (4 %)      (0 %)      1 %      1 %      (1 %) 

All price variations are based on FOB prices. Price (local currency) for EMEA, Europe, MEA, and SCAC calculated on a volume-weighted-average basis at constant foreign-exchange rates.

The United States posted positive volume performance with cement and aggregates increasing 4% during the quarter. Growth was mainly driven by favorable dynamics across most of our markets as well as the contribution from our new mortars platform in the U.S., Omega. Operating EBITDA and Operating EBITDA margin in the quarter were impacted by an unplanned outage, higher raw material cost inflation in ready-mix and cement, and lower cement prices.

Compared to 4Q25, ready-mix and aggregates prices are up mid-single digits, with some erosion in cement prices in select markets.

Demand continues to be led primarily by infrastructure, while industrial-sector demand, particularly related to the AI ecosystem and energy sector, continues to grow. Residential construction remains challenged by affordability constraints and elevated housing inventories.


2026 Third Quarter Results


Page 3


   LOGO
Operating results     


Europe, Middle East and Africa


     January - September     Third Quarter  
     2026     2025     % var     l-t-l % var     2026     2025     % var     l-t-l % var  

Sales

     4,115       3,790       9 %      4 %      1,435       1,379       4 %      3 % 

Operating EBITDA

     702       593       18 %      15 %      257       247       4 %      4 % 

Operating EBITDA margin

     17.0 %      15.7 %      1.3 pp        17.9 %      17.9 %      0.0 pp   

In millions of U.S. dollars; except percentages.


     Domestic gray cement     Ready-mix     Aggregates  
Year-over-year percentage variation    January -
September
    Third Quarter     January -
September
    Third Quarter     January -
September
    Third Quarter  

Volume

     (3 %)      (1 %)      (1 %)      (3 %)      (6 %)      (8 %) 

Price (USD)

     3 %      (3 %)      11 %      8 %      10 %      7 % 

Price (local currency)

     1 %      (1 %)      4 %      5 %      5 %      5 % 

All price variations are based on FOB prices. Price (local currency) for EMEA, Europe, MEA, and SCAC calculated on a volume-weighted-average basis at constant foreign-exchange rates.

The EMEA region delivered favorable results, with Operating EBITDA growth distributed across both subregions, supported by strong pricing and efficiencies from Project Cutting Edge, which partially mitigated rising energy costs in the region.

Sequential pricing was broadly stable in Europe across our three products. Importantly, prices are up low to mid-single digits on a cumulative basis since 4Q25, reflecting successful first-half pricing increases in markets affected by the introduction of the Carbon Border Adjustment Mechanism (CBAM) this year. Across Europe, fuel surcharges and price increases covering the majority of our ready-mix volumes are helping mitigate higher diesel costs.

In Europe, Germany posted cement volume growth for the first time this year and, together with Spain, helped offset softer volumes elsewhere amid persistent heatwaves, project delays, and a fragile recovery in construction activity across several markets.

For Middle East and Africa, double-digit cement volume growth was driven by a demand recovery in Egypt, while our operations in Israel and the UAE remained resilient amid geopolitical tensions.


2026 Third Quarter Results


Page 4


   LOGO
Operating results     


South, Central America and the Caribbean


     January - September     Third Quarter  
     2026     2025     % var     l-t-l % var     2026     2025     % var     l-t-l % var  

Sales

     935       864       8 %      (1 %)      333       297       12 %      (0 %) 

Operating EBITDA

     195       170       15 %      6 %      62       65       (5 %)      (14 %) 

Operating EBITDA margin

     20.8 %      19.7 %      1.1 pp        18.6 %      21.9 %      (3.3 pp)   

In millions of U.S. dollars; except percentages.


     Domestic gray cement     Ready-mix     Aggregates  
Year-over-year percentage variation    January -
September
    Third Quarter     January -
September
    Third Quarter     January -
September
    Third Quarter  

Volume

     2 %      3 %      (6 %)      (2 %)      (25 %)      (19 %) 

Price (USD)

     7 %      9 %      16 %      22 %      19 %      30 % 

Price (local currency)

     0 %      (0 %)      (1 %)      (2 %)      1 %      4 % 

All price variations are based on FOB prices. Price (local currency) for EMEA, Europe, MEA, and SCAC calculated on a volume-weighted-average basis at constant foreign-exchange rates.

In South, Central America and the Caribbean, our results were impacted by higher cement purchases in Jamaica, reflecting annual maintenance works and stronger-than-expected demand, along with higher energy costs in the region.

Cement demand in the region remained solid, supported by robust performance in Colombia and Jamaica, with the informal sector driving activity in both markets. In Jamaica, demand also benefited from increased reconstruction activity related to last year’s Hurricane Melissa and continued investment in tourism-related projects.

We remain optimistic on the fundamentals of our portfolio in the region, supported by resilient informal construction.


2026 Third Quarter Results


Page 5


   LOGO
Operating results     


Operating EBITDA and Free cash flow from operations


     January - September     Third Quarter  
     2026     2025     % var     2026     2025     % var  

Operating earnings before other income and expenses, net

     1,785       1,332       34 %      652       547       19 % 

Depreciation and amortization of assets

     1,017       967         338       335    


Operating EBITDA

     2,802       2,299       22 %      990       882       12 % 

Net Interest Paid

     (226 )      (314 )        (69 )      (104 )   

Maintenance capital expenditures & lease payments (1)

     (495 )      (605 )        (183 )      (224 )   

Change in working capital

     (505 )      (545 )        (3 )      132    

Net Taxes Paid

     (234 )      (223 )        (90 )      (87 )   

Other cash expenditures

     (112 )      (219 )        (21 )      (67 )   

Proceeds from sales of fixed assets

     159       88         99       8    

Free Cash Flows from discontinued operations

     —        (8 )        —        (2 )   


Free cash flow from operations

     1,389       473       194 %      723       540       34 % 


In millions of U.S. dollars; except percentages.


(1) 

Including lease payments of US$64 million in 3Q26 and US$70 million in 3Q25.

Net debt variation


     YTD variation      Quarterly variation  

Net debt

     4Q25:        4,958        2Q26:        6,225  


Free cash flow from operations (effect on Net debt)

        (1,389 )          (723 ) 


Growth capital expenditures

        208           52  

Acquisitions and divestments

        281           22  

Investments in intangible assets

        100           30  

Coupons on subordinated notes

        113           36  

Dividends

        120           44  

Share buybacks

        100           —   

Redemption of 5.125% subordinated notes

        1,000           —   

Others, net (1)

        (67 )          (263 ) 


Net debt variation

        466           (802 ) 


Net debt

     3Q26:        5,423        3Q26:        5,423  


In millions of U.S. dollars; except percentages.


(1) 

“Others, net” primarily reflects the EUR 200 million grant received from the Spanish government in 3Q26 for a proposed carbon capture project. Year-to-date, this benefit was partially offset by pension plan payments and a reduction in the balance of securitization programs.

Information on debt

     Third Quarter     Second
Quarter
 
     2026     2025     % var     2026  

Total debt (1)

     6,075       6,789       (11 %)      6,879  

Short-term

     7 %      11 %        6 % 

Long-term

     93 %      89 %        94 % 

Cash and cash equivalents

     652       1,198       (46 %)      654  

Net debt

     5,423       5,592       (3 %)      6,225  


Leverage ratio (2)

     1.80       2.52         2.08  


     Third Quarter  

CURRENCY DENOMINATION (3)

   2026     2025  

U.S. dollar

     79 %      68 % 

Euro

     16 %      21 % 

Mexican peso

     2 %      7 % 

Other

     3 %      3 % 

INTEREST RATE (3)


Fixed

     87 %      67 % 

Variable

     13 %      33 % 


In millions of U.S. dollars; except percentages and ratios.


(1) 

Includes leases, in accordance with International Financial Reporting Standards (IFRS).

(2) 

Calculated based on Net debt plus subordinated notes. Although subordinated notes are not considered debt, they are included in this calculation for ease of review by financial analysts.

(3) 

Includes the effect of our interest rate and cross-currency derivatives, as applicable.


2026 Third Quarter Results


Page 6


   LOGO
Operating results     


Consolidated Statement of Operations & Statement of Financial Position

Cemex, S.A.B. de C.V. and Subsidiaries

In thousands of U.S. dollars, except per ADS amounts


     January - September     Third Quarter  

STATEMENT OF OPERATIONS

   2026     2025     % var     l-t-l
% var
    2026     2025     % var     l-t-l
% var
 

Sales

     13,202,902       11,952,175       10 %      5 %      4,590,392       4,245,421       8 %      5 % 

Cost of sales

     (8,636,286 )      (8,004,350 )      (8 %)        (2,961,978 )      (2,819,782 )      (5 %)   


Gross profit

     4,566,616       3,947,825       16 %      9 %      1,628,414       1,425,639       14 %      10 % 

Operating expenses

     (2,781,300 )      (2,615,743 )      (6 %)        (976,430 )      (878,310 )      (11 %)   


Operating earnings before other income and expenses, net

     1,785,315       1,332,081       34 %      26 %      651,984       547,329       19 %      15 % 

Other expenses, net

     (66,779 )      (208,634 )      68 %        25,883       (95,090 )      N/A    


Operating earnings

     1,718,536       1,123,447       53 %        677,867       452,239       50 %   

Financial expense

     (307,361 )      (345,721 )      11 %        (102,913 )      (110,148 )      7 %   

Other financial income (expense), net

     (55,641 )      138,086       N/A         (14,795 )      (11,938 )      (24 %)   

Financial income

     37,281       31,342       19 %        9,359       12,196       (23 %)   

Results from financial instruments, net

     11,886       (40,066 )      N/A         8,791       (7,133 )      N/A    

Foreign exchange results

     (28,599 )      213,902       N/A         (7,419 )      5,968       N/A    

Effects on net present value on assets and liabilities and others, net

     (76,210 )      (67,091 )      (14 %)        (25,526 )      (22,969 )      (11 %)   

Equity in gain (loss) of associates

     45,554       55,883       (18 %)        20,186       30,624       (34 %)   


Income (loss) before income tax

     1,401,088       971,696       44 %        580,345       360,777       61 %   

Income tax

     (404,578 )      (272,535 )      (48 %)        (170,920 )      (120,868 )      (41 %)   


Profit (loss) of continuing operations

     996,510       699,161       43 %        409,425       239,909       71 %   

Discontinued operations

     4,005       631,711       (99 %)        1,516       32,140       (95 %)   


Consolidated net income (loss)

     1,000,515       1,330,872       (25 %)        410,941       272,049       51 %   

Non-controlling interest net income (loss)

     18,769       15,196       24 %        3,490       8,349       (58 %)   


Controlling interest net income (loss)

     981,746       1,315,676       (25 %)        407,451       263,699       55 %   


Operating EBITDA

     2,802,168       2,299,039       22 %      16 %      990,206       882,264       12 %      9 % 

Earnings (loss) of continuing operations per ADS

     0.68       0.47       43 %        0.28       0.16       76 %   


     As of September 30  

STATEMENT OF FINANCIAL POSITION

   2026      2025      % var  

Total assets

     27,968,733        29,007,657        (4 %) 

Cash and cash equivalents

     651,975        1,197,717        (46 %) 

Trade receivables less allowance for doubtful accounts

     2,040,120        1,960,041        4 % 

Other accounts receivable

     959,085        781,700        23 % 

Inventories, net

     1,498,934        1,559,293        (4 %) 

Assets held for sale

     753,970        306,185        146 % 

Other current assets

     126,069        151,585        (17 %) 

Current assets

     6,030,153        5,956,521        1 % 

Property, machinery, and equipment, net

     11,507,560        11,908,751        (3 %) 

Other assets

     10,431,021        11,142,385        (6 %) 


Total liabilities

     14,762,425        15,090,221        (2 %) 

Current liabilities

     6,372,500        6,526,442        (2 %) 

Long-term liabilities

     4,897,320        5,142,095        (5 %) 

Other liabilities

     3,492,605        3,421,685        2 % 


Total stockholders’ equity

     13,206,308        13,917,436        (5 %) 

Common stock and additional paid-in capital

     7,699,108        7,699,108        0 % 

Other equity reserves

     (2,651,337 )       (2,502,420 )       (6 %) 

Subordinated notes

     974,000        1,974,000        (51 %) 

Retained earnings

     6,878,780        6,432,432        7 % 

Non-controlling interest

     305,757        314,316        (3 %) 


2026 Third Quarter Results


Page 7


   LOGO
Operating results     


Operating summary per country

In thousands of U.S. dollars


     January - September     Third Quarter  

SALES

   2026     2025     % var     l-t-l
% var
    2026     2025     % var     l-t-l
% var
 

Mexico

     3,866,185       3,158,145       22 %      10 %      1,299,267       1,117,220       16 %      9 % 

U.S.A.

     3,883,535       3,806,159       2 %      2 %      1,372,811       1,309,885       5 %      5 % 

Europe, Middle East and Africa

     4,115,269       3,789,670       9 %      4 %      1,434,717       1,378,733       4 %      3 % 

Europe

     2,950,114       2,849,253       4 %      1 %      1,022,235       1,026,428       (0 %)      1 % 

Middle East and Africa

     1,165,155       940,417       24 %      13 %      412,482       352,306       17 %      11 % 

South, Central America and the Caribbean

     935,300       863,555       8 %      (1 %)      333,152       297,492       12 %      (0 %) 

Others and intercompany eliminations

     402,613       334,645       20 %      23 %      150,446       142,090       6 %      7 % 


TOTAL

     13,202,902       11,952,175       10 %      5 %      4,590,392       4,245,421       8 %      5 % 


GROSS PROFIT


Mexico

     2,062,236       1,587,411       30 %      17 %      688,612       558,833       23 %      16 % 

U.S.A.

     1,052,552       1,079,590       (3 %)      (3 %)      395,123       385,135       3 %      3 % 

Europe, Middle East and Africa

     1,125,364       1,006,311       12 %      9 %      408,460       389,920       5 %      4 % 

Europe

     875,638       801,331       9 %      7 %      317,531       311,878       2 %      3 % 

Middle East and Africa

     249,726       204,980       22 %      14 %      90,928       78,042       17 %      11 % 

South, Central America and the Caribbean

     289,367       271,232       7 %      (3 %)      97,477       97,936       (0 %)      (17 %) 

Others and intercompany eliminations

     37,097       3,281       N/A       N/A       38,743       (6,185 )      N/A       N/A  


TOTAL

     4,566,616       3,947,825       16 %      9 %      1,628,414       1,425,639       14 %      10 % 


OPERATING EARNINGS BEFORE OTHER INCOME AND EXPENSES, NET


Mexico

     1,255,164       867,780       45 %      29 %      423,410       314,626       35 %      26 % 

U.S.A.

     301,422       349,883       (14 %)      (14 %)      125,939       137,596       (8 %)      (8 %) 

Europe, Middle East and Africa

     447,406       343,452       30 %      28 %      174,981       160,587       9 %      9 % 

Europe

     307,401       231,059       33 %      32 %      125,158       116,543       7 %      8 % 

Middle East and Africa

     140,005       112,393       25 %      19 %      49,822       44,044       13 %      10 % 

South, Central America and the Caribbean

     126,483       118,217       7 %      1 %      38,016       45,475       (16 %)      (24 %) 

Others and intercompany eliminations

     (345,159 )      (347,250 )      1 %      12 %      (110,363 )      (110,956 )      1 %      8 % 


TOTAL

     1,785,315       1,332,081       34 %      26 %      651,984       547,329       19 %      15 % 


2026 Third Quarter Results


Page 8


   LOGO
Operating results     


Operating summary per country

Operating EBITDA in thousands of U.S. dollars

Operating EBITDA margin as a percentage of sales


     January - September     Third Quarter  

OPERATING EBITDA

   2026     2025     %
var
    l-t-l
% var
    2026     2025     %
var
    l-t-l
% var
 

Mexico

     1,424,963       1,024,509       39 %      24 %      480,403       369,400       30 %      22 % 

U.S.A.

     697,431       737,588       (5 %)      (5 %)      259,307       269,307       (4 %)      (4 %) 

Europe, Middle East and Africa

     701,604       593,119       18 %      15 %      257,318       247,059       4 %      4 % 

Europe

     503,288       430,497       17 %      15 %      189,110       183,908       3 %      4 % 

Middle East and Africa

     198,316       162,622       22 %      14 %      68,208       63,151       8 %      3 % 

South, Central America and the Caribbean

     194,726       169,753       15 %      6 %      61,970       65,033       (5 %)      (14 %) 

Others and intercompany eliminations

     (216,556 )      (225,929 )      4 %      22 %      (68,791 )      (68,534 )      (0 %)      12 % 


TOTAL

     2,802,168       2,299,039       22 %      16 %      990,206       882,264       12 %      9 % 


OPERATING EBITDA MARGIN


Mexico

     36.9 %      32.4 %      4.5 pp        37.0 %      33.1 %      3.9 pp   

U.S.A.

     18.0 %      19.4 %      (1.4 pp)        18.9 %      20.6 %      (1.7 pp)   

Europe, Middle East and Africa

     17.0 %      15.7 %      1.3 pp        17.9 %      17.9 %      0.0 pp   

Europe

     17.1 %      15.1 %      2.0 pp        18.5 %      17.9 %      0.6 pp   

Middle East and Africa

     17.0 %      17.3 %      (0.3 pp)        16.5 %      17.9 %      (1.4 pp)   

South, Central America and the Caribbean

     20.8 %      19.7 %      1.1 pp        18.6 %      21.9 %      (3.3 pp)   


TOTAL

     21.2 %      19.2 %      2.0 pp        21.6 %      20.8 %      0.8 pp   


2026 Third Quarter Results


Page 9


   LOGO
Operating results     


Volume summary

Cement and aggregates: Thousands of metric tons

Ready-mix: Thousands of cubic meters


     January - September     Third Quarter  
     2026      2025      % var     2026      2025      % var  

Consolidated cement volume (1)

     38,817        39,319        (1 %)      13,408        13,938        (4 %) 

Consolidated ready-mix volume

     31,989        32,506        (2 %)      11,043        11,314        (2 %) 

Consolidated aggregates volume (2)

     97,319        98,650        (1 %)      34,179        35,084        (3 %) 

Per-country volume summary


     January - September     Third Quarter     Third Quarter 2026  

DOMESTIC GRAY CEMENT

   2026 vs. 2025     2026 vs. 2025     vs. Second Quarter 2026  

Mexico

     7 %      7 %      0 % 

U.S.A.

     1 %      4 %      3 % 

Europe, Middle East and Africa

     (3 %)      (1 %)      0 % 

Europe

     (5 %)      (5 %)      (3 %) 

Middle East and Africa

     2 %      12 %      8 % 

South, Central America and the Caribbean

     2 %      3 %      5 % 


     January - September     Third Quarter     Third Quarter 2026  

READY-MIX

   2026 vs. 2025     2026 vs. 2025     vs. Second Quarter 2026  

Mexico

     (3 %)      (2 %)      2 % 

U.S.A.

     (0 %)      (1 %)      3 % 

Europe, Middle East and Africa

     (1 %)      (3 %)      0 % 

Europe

     (6 %)      (7 %)      (2 %) 

Middle East and Africa

     5 %      1 %      4 % 

South, Central America and the Caribbean

     (6 %)      (2 %)      10 % 


     January - September     Third Quarter     Third Quarter 2026  

AGGREGATES

   2026 vs. 2025     2026 vs. 2025     vs. Second Quarter 2026  

Mexico

     2 %      (2 %)      1 % 

U.S.A.

     5 %      4 %      9 % 

Europe, Middle East and Africa

     (6 %)      (8 %)      (0 %) 

Europe

     (7 %)      (8 %)      (1 %) 

Middle East and Africa

     (3 %)      (7 %)      2 % 

South, Central America and the Caribbean

     (25 %)      (19 %)      14 % 


(1)

Consolidated cement volumes include domestic and export volume of gray cement, white cement, special cement, mortar, and clinker.

(2)

Consolidated aggregates volumes include aggregates from our marine business in the United Kingdom.


2026 Third Quarter Results


Page 10


   LOGO
Operating results     


Price summary

Variation in U.S. dollars


     January - September     Third Quarter     Third Quarter 2026  

DOMESTIC GRAY CEMENT

   2026 vs. 2025     2026 vs. 2025     vs. Second Quarter 2026  

Mexico

     17 %      12 %      (1 %) 

U.S.A.

     (3 %)      (4 %)      (3 %) 

Europe, Middle East and Africa

     3 %      (3 %)      (4 %) 

Europe

     3 %      0 %      (2 %) 

Middle East and Africa

     8 %      (5 %)      (2 %) 

South, Central America and the Caribbean

     7 %      9 %      2 % 


     January - September     Third Quarter     Third Quarter 2026  

READY-MIX

   2026 vs. 2025     2026 vs. 2025     vs. Second Quarter 2026  

Mexico

     15 %      11 %      2 % 

U.S.A.

     (0 %)      1 %      1 % 

Europe, Middle East and Africa

     11 %      8 %      (2 %) 

Europe

     5 %      1 %      (1 %) 

Middle East and Africa

     24 %      21 %      (3 %) 

South, Central America and the Caribbean

     16 %      22 %      9 % 


     January - September     Third Quarter     Third Quarter 2026  

AGGREGATES

   2026 vs. 2025     2026 vs. 2025     vs. Second Quarter 2026  

Mexico

     16 %      11 %      (3 %) 

U.S.A.

     1 %      (1 %)      (2 %) 

Europe, Middle East and Africa

     10 %      7 %      (3 %) 

Europe

     7 %      4 %      (3 %) 

Middle East and Africa

     24 %      19 %      (4 %) 

South, Central America and the Caribbean

     19 %      30 %      12 % 

All price variations are based on FOB prices. Price (local currency) for EMEA, Europe, MEA, and SCAC calculated on a volume-weighted-average basis at constant foreign-exchange rates.


2026 Third Quarter Results


Page 11


   LOGO
Operating results     


Price summary

Variation in Local Currency


     January - September     Third Quarter     Third Quarter 2026  

DOMESTIC GRAY CEMENT

   2026 vs. 2025     2026 vs. 2025     vs. Second Quarter 2026  

Mexico

     6 %      5 %      (1 %) 

U.S.A.

     (3 %)      (4 %)      (3 %) 

Europe, Middle East and Africa

     1 %      (1 %)      (3 %) 

Europe

     1 %      1 %      (1 %) 

Middle East and Africa

     10 %      (0 %)      (3 %) 

South, Central America and the Caribbean

     0 %      (0 %)      (2 %) 


     January - September     Third Quarter     Third Quarter 2026  

READY-MIX

   2026 vs. 2025     2026 vs. 2025     vs. Second Quarter 2026  

Mexico

     3 %      4 %      2 % 

U.S.A.

     (0 %)      1 %      1 % 

Europe, Middle East and Africa

     4 %      5 %      (0 %) 

Europe

     2 %      2 %      (0 %) 

Middle East and Africa

     10 %      12 %      0 % 

South, Central America and the Caribbean

     (1 %)      (2 %)      (2 %) 


     January - September     Third Quarter     Third Quarter 2026  

AGGREGATES

   2026 vs. 2025     2026 vs. 2025     vs. Second Quarter 2026  

Mexico

     4 %      4 %      (3 %) 

U.S.A.

     1 %      (1 %)      (2 %) 

Europe, Middle East and Africa

     5 %      5 %      (2 %) 

Europe

     4 %      5 %      (2 %) 

Middle East and Africa

     8 %      8 %      0 % 

South, Central America and the Caribbean

     1 %      4 %      1 % 

All price variations are based on FOB prices. Price (local currency) for EMEA, Europe, MEA, and SCAC calculated on a volume-weighted-average basis at constant foreign-exchange rates.


2026 Third Quarter Results


Page 12


   LOGO
Other information     


Operating expenses

The following table shows the breakdown of operating expenses for the period presented.


    January - September     Third Quarter  

(Thousands of U.S. dollars)

  2026     2025     % var     2026     2025     % var  

General and administrative expenses

    891,830       880,240       1 %      281,916       283,334       (1 %) 

Selling expenses

    268,821       269,857       (0 %)      90,753       87,771       3 % 

Distribution and logistics expenses

    1,410,271       1,286,289       10 %      530,583       445,396       19 % 


Operating expenses before depreciation

    2,570,922       2,436,386       6 %      903,251       816,501       11 % 


Depreciation in operating expenses

    210,378       179,357       17 %      73,179       61,809       18 % 


Operating expenses

    2,781,300       2,615,743       6 %      976,430       878,310       11 % 


As % of Net Sales


General and administrative expenses

     6.8 %       7.4 %       6.1 %       6.7 % 

SG&A expenses

     8.8 %       9.6 %       8.1 %       8.7 % 

Equity-related information

As of December 31, 2025, the number of outstanding CPO-equivalents was 14,508,328,248. See Cemex’s reports furnished to or filed with the U.S. Securities and Exchange Commission for information, if any, regarding repurchases of securities and other developments that may have caused a change in the number of CPO-equivalents outstanding after December 31, 2025. For the three-month period ended March 31, 2026, 78,803,711 CPOs were repurchased by Cemex under its share repurchase program approved at Cemex, S.A.B. de C.V.’s ordinary annual shareholders meeting held on March 25, 2025. On March 26, 2026, Cemex, S.A.B. de C.V.’s ordinary annual shareholders meeting approved a new repurchase program that will be in effect until the next annual shareholders meeting to be held in 2027. No CPOs were repurchased by Cemex under such program from March 26, 2026 to September 30, 2026.

One Cemex ADS represents ten Cemex CPOs. One Cemex CPO represents two Series A shares and one Series B share.

For purposes of this report, outstanding CPO-equivalents equal the total number of Series A and B shares outstanding as if they were all held in CPO form, less CPOs held by Cemex and its subsidiaries, which as of December 31, 2025, were 20,541,277. Starting 2024, employees receive restricted ADRs instead of restricted CPOs. Restricted ADRs allocated to eligible employees as variable compensation are not included in the outstanding CPO-equivalents.

Derivative instruments

The following table shows the notional amount for each type of derivative instrument and the aggregate fair market value for all of Cemex’s derivative instruments as of the last day of each quarter presented.


     Third Quarter     Second Quarter  

(Millions of U.S. dollars)

   2026     2025     2026  
     Notional
amount
     Fair
value
    Notional
amount
     Fair
value
    Notional
amount
     Fair
value
 

Exchange rate derivatives (1)

     1,045        (37 )      1,313        (63 )      1,225        (80 ) 

Interest rate swaps (2)

     1,723        (11 )      1,640        (26 )      1,733        7  

Fuel derivatives (3)

     203        84       244        7       264        31  


     2,971        36       3,197        (82 )      3,222        (42 ) 


(1) 

The exchange rate derivatives are used to manage currency exposures arising from net investments in foreign operations.

(2) 

As of September 30, 2026, these instruments are associated with bank loans, including interest rate and exchange rate swap derivatives.

(3) 

Cemex’s derivative financial instruments portfolio includes swaps and financial options. These derivative instruments are mainly used to hedge the market price risk of certain fuels associated with certain Cemex operations, such as transportation and production. In addition, there are call spreads on Brent oil and derivatives thereof, designed to mitigate the exposure related to the implicit cost of fuel in distribution expenses.

Under IFRS, companies are required to recognize the fair value of all derivative financial instruments on the balance sheet as financial assets or liabilities, with changes in such fair market values recorded in the income statement, except when transactions are entered into for hedging purposes. In cash-flow hedging cases, changes in the fair market value of the related derivative instruments are recognized temporarily in equity and subsequently reclassified into earnings as the effects of the underlying are recognized in the income statement. Moreover, in transactions related to net investment hedges, changes in fair market value are recorded directly in equity as part of the currency translation effect and are reclassified to the income statement only in the case of disposal of the net investment. As of September 30, 2026, in connection with the derivatives portfolio’s fair market value, Cemex recognized changes in fair market value resulting in a financial asset of US$36 million.


2026 Third Quarter Results


Page 13


   LOGO
Other information     


Discontinued operations

On October 6, 2025, Cemex concluded the sale of substantially all its operations and the majority of its assets in Panama to Grupo Estrella, primarily comprising one cement plant and related cement assets, ready-mix concrete, and aggregates, for a total consideration of US$200 million. Cemex retained its admixtures business in Panama. The sale resulted in a loss on disposal of US$63 million and a goodwill write-off of US$24 million. For the nine-month period ended September 30, 2025, Cemex’s operations in Panama are reported in Cemex’s income statements, net of income tax, in the single line item “Discontinued operations.”

On January 30, 2025, Cemex completed the sale of its operations in the Dominican Republic to Cementos Progreso Holdings, S.L., and its strategic partners for a total consideration of US$928 million, after adjustments for final cash, debt, and working capital balances. The divested assets consisted of one cement plant in the Dominican Republic with two integrated production lines, along with related cement, ready-mix concrete, aggregates, and marine terminal assets. For the nine-month period ended September 30, 2025, Cemex’s operations in the Dominican Republic are reported in Cemex’s income statements, net of income tax, in the single line item “Discontinued operations,” including a gain on sale of US$551 million, net of the reclassification of foreign currency translation effects accrued in equity until the date of sale and goodwill write-off of US$13 million.

The table below summarizes the income statements for the nine-month period ended September 30, 2025. It includes Cemex’s discontinued operations related to Panama and the Dominican Republic.


INCOME STATEMENTS    Jan - Sep     Third Quarter  

(Millions of U.S. dollars)

   2026      2025     2026      2025  

Sales

        130          36  

Cost of sales, operating expenses, other expenses, and gain on sale, net

     4        512       2        (1 ) 

Interest expense, net, and others

        (6 )         (2 ) 


Income (loss) before income tax

     4        636       2        33  


Income tax

        (4 )         (1 ) 


Net result from discontinued operations

     4        632       2        32  


Assets held for sale and related liabilities

As of September 30, 2026, Cemex presents “Assets held for sale” and “Liabilities directly related to assets held for sale”, respectively, in connection with the agreement to divest several assets in Colombia, including cement operations and a portfolio of ready-mix concrete, aggregates, mortars, and admixtures, for total proceeds of approximately US$485 million. This transaction is expected to close by year-end. We will continue to consolidate these operations in Cemex’s income statements until the transaction closes.

Cemex entered into exclusive negotiations with Vicat for the proposed sale of certain ready-mix concrete and aggregates operations in South-Eastern France. The proposed transaction remains subject to employee consultation, the execution of definitive agreements and regulatory approvals. The operations will continue to be consolidated in Cemex’s income statements until closing. As of September 30, 2026, the related assets and liabilities are presented as “Assets held for sale” and “Liabilities directly related to assets held for sale”, respectively.

The following table presents condensed combined information of the statement of financial position for the assets held for sale in Colombia and France as of September 30, 2026:


(Millions of U.S. dollars)

   2026  

Current assets

     223  

Non-current assets

     492  


Total assets

     715  

Current liabilities

     113  

Non-current liabilities

     133  


Total liabilities

     246  


Net assets sold or held for sale

     469  


2026 Third Quarter Results


Page 14


   LOGO
Definitions of terms and disclosures     


Methodology for translation, consolidation, and presentation of results

Under IFRS, Cemex translates the financial statements of foreign subsidiaries using exchange rates at the reporting date for the balance sheet and the exchange rates at the end of each month for the income statement.

Breakdown of regions and subregions

The South, Central America and the Caribbean region includes Cemex’s operations in Colombia, Puerto Rico, Nicaragua, Jamaica, Trinidad and Tobago, Guyana, Barbados, Peru, and Bahamas.

The EMEA region includes Europe, Middle East and Africa.

Europe subregion includes operations in Spain, Croatia, the Czech Republic, France, Germany, Poland, and the United Kingdom.

Middle East and Africa subregion includes operations in United Arab Emirates, Egypt, and Israel.

Definition of terms

Free cash flow from operations Cemex defines it as Operating EBITDA minus net interest paid, maintenance capital expenditures, maintenance lease payments, fixed asset sales, change in working capital, net taxes paid, and other cash expenditures.

l-t-l (like to like) on a like-to-like basis adjusting for currency fluctuations.

Maintenance capital expenditures equal investments incurred for the purpose of ensuring the company’s operational continuity. These include capital expenditures on projects required to replace obsolete assets or maintain current operational levels, and mandatory capital expenditures, which are projects required to comply with governmental regulations or company policies.

Net debt equals total debt (debt plus financial leases) minus cash and cash equivalents.

Sales, when referring to reportable segment sales, revenues are presented before eliminations of intragroup transactions. When referring to Consolidated Sales, these represent the total revenues (Net Sales) of the company as reported in the financial statements.

Operating EBITDA, or EBITDA equals operating earnings before other income and expenses, net, plus depreciation and amortization.

Operating EBITDA margin, or EBITDA margin, is calculated by dividing our “Operating EBITDA” by our sales.

pp equals percentage points.

Prices all reference to pricing initiatives, price increases or decreases, refer to our prices for our products and services.

SG&A expenses equal selling and administrative expenses

Growth capital expenditures equal investments incurred with the purpose of increasing the company’s profitability. These include capital expenditures on projects designed to increase profitability by expanding capacity, and margin improvement capital expenditures, which are projects designed to increase profitability by reducing costs.

Investment in intangible assets equals investments and expenses incurred in the development of internal-use software, industrial property, and trademarks, and aggregates mining rights.

Working capital equals operating accounts receivable (including other current assets received as payment in kind) plus historical inventories minus operating payables.

% var percentage variation.

Earnings per ADS

Please refer to page 2 for the number of average ADSs outstanding used for the calculation of earnings per ADS.

According to the IAS 33 Earnings per share, the weighted-average number of common shares outstanding is determined considering the number of days during the accounting period in which the shares have been outstanding, including shares derived from corporate events that have modified the stockholder’s equity structure during the period, such as increases in the number of shares by a public offering and the distribution of shares from stock dividends or recapitalizations of retained earnings and the potential diluted shares (Stock options, Restricted Stock Options and Mandatory Convertible Shares). The shares issued because of share dividends, recapitalizations and potential diluted shares are considered as issued at the beginning of the period.


Exchange rates    January - September      Third Quarter      Third Quarter  
     2026      2025      2026      2025      2026      2025  
   Average      Average      Average      Average      End of period      End of period  

Mexican peso

     17.48        19.49        17.47        18.62        18.08        18.32  

Euro

     0.8612        0.8934        0.8702        0.8614        0.8827        0.8521  

British pound

     0.7438        0.7588        0.7444        0.7465        0.7539        0.7439  

Amounts provided in units of local currency per U.S. dollar.


2026 Third Quarter Results


Page 15


   LOGO
Disclaimer     


Except as the context otherwise may require, references in this report to “we,” “us,” “our,” or similar expressions refer to Cemex, S.A.B. de C.V. (“Cemex”) (NYSE: CX; BMV: CEMEX.CPO) and its consolidated entities. The information disclosed in this report and the current or future events referenced therein may contain forward-looking statements within the meaning of applicable securities laws and regulations, including but not limited to Section 27A of the Securities Act of 1933, as amended, and Section 21E of the Securities Exchange Act of 1934, as amended. We intend these forward-looking statements to be covered by the “safe harbor” provisions for forward-looking statements within the meaning of applicable securities laws and regulations in all jurisdictions where such provisions exist, including but not limited to the US Private Securities Litigation Reform Act of 1995. These forward-looking statements and information are necessarily subject to risks, uncertainties, and assumptions. Forward-looking statements include, without limitation, statements related to our plans, objectives, and expectations (financial or otherwise), and typically can be identified by the use of words such as, but not limited to, “will”, “may,” “assume,” “might,” “should,” “could,” “continue,” “would,” “can,” “consider,” “anticipate,” “estimate,” “expect,” “envision,” “plan,” “believe,” “foresee,” “predict,” “potential,” “target,” “goal,” “strategy,” “intend,” “aimed”, or other forward-looking words. Although we believe that our expectations are reasonable, we can give no assurance that these expectations will prove to be correct, and actual results, performance and/or achievements may vary, including materially, from historical results, performance and/or achievements or those anticipated by forward-looking statements due to various factors. Unless otherwise indicated, these forward-looking statements reflect our current expectations and projections about the future based on certain assumptions and on our knowledge of facts and circumstances as of the date such forward-looking statements are made. These forward-looking statements necessarily involve risks, uncertainties, assumptions and other important factors that could cause results and any estimate, projection and/or guidance presented in this report to differ materially from historical results, performance and/or achievements or those anticipated by forward-looking statements due to various factors. Among others, such risks, uncertainties, assumptions, and other important factors that could cause results and any estimate, projection and/or guidance presented in this report to differ or fail to materialize, or that otherwise could have an impact on us, include those discussed in our most recent annual report and those detailed from time to time in our other filings with the U.S. Securities and Exchange Commission (“SEC”), Mexican National Banking and Securities Commission (Comisión Nacional Bancaria y de Valores, the “CNBV”) and the Mexican Stock Exchange (Bolsa Mexicana de Valores, the “BMV”), which factors are incorporated herein by reference, including, but not limited to: changes in general economic, political and social conditions, including government shutdowns, new governments or regimes and decisions implemented by such new governments or regimes, changes in laws or regulations in the countries in which we do business, elections, changes in inflation, interest and foreign exchange rates, employment levels, population growth, any slowdown in the flow of remittances into countries where we operate, consumer confidence and the liquidity of the financial and capital markets in Mexico, the United States of America, the European Union (“EU”), the United Kingdom or other countries in which we operate; the cyclical activity of the construction sector and reduced construction activity in our end markets or reduced use in our end markets for our products; our exposure to sectors that impact our and our clients’ businesses, particularly those operating in the commercial and residential construction sectors, and the public and private infrastructure and energy sectors; volatility in pension plan asset values and liabilities, which may require cash or other contributions to the pension plans; changes in spending levels for residential and commercial construction and general infrastructure projects; the availability of short-term credit lines or working capital facilities, which can assist us in connection with market cycles; any impact of not maintaining investment grade debt rating or not obtaining investment grade debt ratings from additional rating agencies on our cost of capital and on the cost of the products and services we purchase; availability of raw materials and related fluctuating prices of raw materials, as well as of goods and services in general, in particular increases in prices of raw materials, goods and services, as a result of inflation, trade barriers, measures imposed by governments or as a result of conflicts between countries that disrupt supply chains; changes in the cost and availability of energy, fuel and electricity, and the effectiveness of our hedging and other derivative instruments; the timing, scale and execution of government-sponsored housing and social programs; our ability to maintain and expand our distribution network and maintain favorable relationships with third parties who supply us with equipment, services and essential supplies; competition in the markets in which we offer our products and services; the impact of environmental cleanup costs and other remedial actions, and other environmental, climate and related liabilities relating to existing and/or divested businesses, assets and/or operations; our ability to secure and permit aggregates reserves in strategically located areas in amounts that our operations require to operate or operate in a cost-efficient manner; the timing and amount of federal, state, and local funding for infrastructure; changes in our effective tax rate; our ability to comply with regulations and implement technologies and other initiatives that aim to reduce and/or capture CO2 emissions and comply with related carbon emissions regulations in place in the jurisdictions where we have operations; the legal and regulatory environment, including environmental, climate, trade, energy, tax, antitrust, sanctions, import and export controls, construction, human rights and labor welfare, and acquisition-related rules and regulations in the countries and regions in which we have operations; the effects of currency fluctuations on our results of operations and financial condition; our ability to satisfy our obligations under our debt agreements, the indentures that govern our outstanding notes, and our other debt instruments and financial obligations, and also regarding our subordinated notes with no fixed maturity and other financial obligations; adverse legal or regulatory proceedings or disputes, such as class actions or enforcement or other proceedings brought by third parties, government and regulatory agencies, including antitrust investigations and claims; our ability to protect our reputation and intellectual property; our ability to consummate asset sales or consummate asset sales in terms favorable to us, fully integrate newly acquired businesses, achieve cost-savings from our cost-reduction initiatives, implement our pricing and commercial initiatives for our products and services, and generally meet our business strategy’s goals; the increasing reliance on information technology infrastructure for our sales, invoicing, procurement, financial statements, and other processes that can adversely affect our sales and operations in the event that the infrastructure does not work as intended, experiences technical difficulties, or is subjected to invasion, disruption, or damage caused by circumstances beyond our control, including cyber-attacks, catastrophic events, power outages, natural disasters, computer system or network failures, or other security breaches; the effects of climate change, in particular reflected in weather conditions, including but not limited to excessive rain and snow, shortage of usable water, wildfires and natural disasters, such as earthquakes, hurricanes, tornadoes and floods, that could affect our facilities or the markets in which we offer our products and services or from where we source our raw materials; trade barriers, including but not limited to tariffs or import taxes, including those imposed by the United States of America to key markets in which we operate, in particular, Mexico, China and the EU, and changes in existing trade policies or changes to, or withdrawals from, free trade agreements, including the United States-Mexico-Canada Agreement (the “USMCA”), and the overall impact that the imposition or threat of trade barriers may cause on the overall economy of the countries in which we do business or that are part of our global supply chain; availability and cost of trucks, railcars, barges, and ships, terminals, warehouses, as well as their licensed operators, drivers, staff and workers for transport, loading and unloading of our materials or that are otherwise a part of our supply chain; labor shortages and constraints; our ability to hire, effectively compensate and retain our key personnel and maintain satisfactory labor relations; our ability to detect and prevent money laundering, terrorism financing and corruption, as well as other illegal activities, and how any measures implemented by governments to detect and prevent money laundering, terrorism financing and corruption, and other illegal activities, affect our customers, suppliers and countries in which we do business in general; defaults, losses or disruptions in agreements, financial transactions or operations resulting from sanctions or restrictions imposed on any financial institution, including but not limited to banks, common representatives, trustees, payment processors, paying agents or other financial intermediaries, or any related parties; terrorist and organized criminal activities, social unrest, as well as geopolitical events, such as global, regional or national instability, hostilities, war, and armed conflicts, including the current war between Russia and Ukraine, the ongoing war among Israel, the United States and Iran, conflicts in the Middle East and any insecurity and hostilities in Mexico related to illegal activities or organized crime and any actions any government takes to prevent these illegal activities and organized crime; the impact of pandemics, epidemics, or outbreaks of infectious diseases and the response of governments and other third parties, which could adversely affect, among other matters, the ability of our operating facilities to operate at full or any capacity, supply chains, international operations, availability of liquidity, investor confidence and consumer spending, as well as the availability of, and demand for, our products and services; changes in the economy that affect demand for consumer goods, consequently affecting demand for our products and services; the depth and duration of an economic slowdown or recession, instability in the business landscape and lack of availability of credit; declarations of insolvency or bankruptcy, or becoming subject to similar proceedings; natural disasters and other unforeseen events (including global health hazards such as, for example, COVID-19); and our ability to implement our climate action program in effect at any given time, if any, including our current “Future in Action” climate action and nature


2026 Third Quarter Results


Page 16


   LOGO
Disclaimer     


program, and to achieve our sustainability goals and objectives in effect at any given time, if any, including under our current “Future in Action” climate action and nature program. Many factors could cause our expectations, expected results, and/or projections expressed in this report and in the events referenced herein not being reached and/or not producing the expected benefits and/or results, as any such benefits or results are subject to uncertainties, costs, performance, and also rate of success and/or implementation of technologies, some of which are not yet proven, among other factors. Should one or more of these risks or uncertainties materialize, or should underlying assumptions prove incorrect, actual results, performance and/or achievements may vary materially from historical results, performance, and/or achievements and/or results; performance and/or achievements expressly or implicitly anticipated by the forward-looking statements; or otherwise, could have an impact on us. Forward-looking statements should not be considered guarantees of future performance, and past results or developments are not indicative of results or developments in subsequent periods. Actual results, performance and/or achievements of our operations and the development of market conditions in which we operate, or other circumstances that may materialize, may differ materially from those described in, or suggested by, the forward-looking statements contained in this report, and events referenced therein. Any or all of our forward-looking statements may turn out to be inaccurate, and the factors identified above are not exhaustive. Accordingly, undue reliance on forward-looking statements should not be placed, as such forward-looking statements speak only as of the dates on which they are made. The forward-looking statements and the information disclosed in this report are made and stated as of the dates specified in this report and are subject to change without notice; and, except to the extent legally required, we expressly disclaim any obligation or undertaking to update or correct the information contained in this report, or revise any forward-looking statements in this report, whether to reflect new information, the occurrence of anticipated or unanticipated future events or circumstances, any change in our expectations regarding those forward-looking statements, any change in events, conditions or circumstances on which any such statement is based, or otherwise. Readers should review future reports filed or furnished by us with the SEC, the CNBV and the BMV. Market data used in this report and events referenced herein not attributed to a specific source are our estimates and have not been independently verified. Certain financial and statistical information contained in this report is subject to rounding adjustments; accordingly, any discrepancies between the totals and the sums of the amounts listed are due to rounding. Unless otherwise specified, all references to records are our internal records. This report includes certain non-International Financial Reporting Standards (“IFRS”) financial measures that differ from financial information presented by us in accordance with IFRS in our financial statements and reports containing financial information. The aforementioned non-IFRS financial measures include “Operating EBITDA” or “EBITDA” (operating earnings before other expenses, net plus depreciation and amortization), “Operating EBITDA Margin” or “EBITDA Margin” (Operating EBITDA for the period divided by revenues reported for the same period), “Operating EBIT” or “EBIT” (operating earnings before other expenses, net), “Free Cash Flow from Operations” (Operating EBITDA minus net interest paid, maintenance capital expenditures, maintenance lease payments, fixed asset sales, change in working capital, net taxes paid, and other cash expenditures), and “Adjusted Free Cash Flow from Operations Conversion Rate” (measures how much of the company’s operating earnings turn into actual cash). The closest IFRS financial measure to Operating EBITDA is “Operating earnings before other expenses, net,” as Operating EBITDA adds depreciation and amortization to the IFRS financial measure. We believe there is no close IFRS financial measure to compare to Operating EBITDA Margin. The closest IFRS financial measure to Operating EBIT is “Operating earnings before other expenses, net.” We believe there is no close IFRS financial measure to compare to Free Cash Flow from Operations. We believe there is no close IFRS financial measure to compare to Adjusted Free Cash Flow from Operations Conversion Rate. These non-IFRS financial measures are designed to complement and should not be considered superior to financial measures calculated in accordance with IFRS. Although Operating EBITDA, Operating EBITDA Margin, Operating EBIT and Free Cash Flow from Operations are not measures of operating performance, an alternative to cash flows or a measure of financial position under IFRS, Operating EBITDA is the financial measure used by our management to review operating performance and profitability, for decision-making purposes and to allocate resources. Moreover, our Operating EBITDA is a measure used by our creditors to review our ability to internally fund capital expenditures, service or incur debt and comply with financial covenants under our financing agreements. Furthermore, our management regularly reviews our Operating EBITDA Margin by reportable segment and on a consolidated basis as a measure of performance and profitability. These non-IFRS financial measures do not have any standardized meaning and are therefore unlikely to be comparable to similarly titled measures presented by other companies. The financial measures presented in this report are being provided for informative purposes only and shall not be construed as investment, financial, or other advice. Also, this report includes statistical data regarding production, distribution, marketing and sale of cement, ready-mix concrete, clinker, aggregates, and Urbanization Solutions. We generated some of this data internally, and some was obtained from independent industry publications and reports that we believe to be reliable sources. We have not independently verified this data nor sought the consent of any organizations to refer to their reports in this report. We act in strict compliance with antitrust laws and as such, among other measures, maintain an independent pricing policy that has been independently developed and its core element is to price our products and services based upon their quality and characteristics as well as their value to our customers. We do not accept any communications or agreements of any type with competitors regarding the determination of our prices for our products and services. Unless the context indicates otherwise, all references to pricing initiatives, price increases or decreases, refer to our prices for our products. The information, statements, and opinions contained in this report are for informational purposes only and do not constitute a public offer under any applicable legislation, an offer to sell, or solicitation of any offer to buy any securities or financial instruments, or any advice or recommendation with respect to such securities or other financial instruments. You should not construe any such information or other material as legal, tax, investment, financial, or other advice. We are not responsible for any third-party information referenced in this report. Cautionary Statement Regarding Environmental, Social, and Governance (“ESG”) and Sustainability-Related Data, Metrics, and Methodologies. This report includes non-financial metrics, estimates, or other information related to ESG and sustainability matters that are subject to significant uncertainties, which may include the methodology, collection, and verification of data, various estimates, and assumptions, and/or underlying data that is obtained from third parties, some of which cannot be independently verified. The preparation of certain information on ESG and sustainability matters contained in this report requires the application of a number of key judgments, assumptions, and estimates. The reported measures reflect good faith estimates, assumptions, and judgments at the given point in time. There is a risk that these judgments, estimates, or assumptions may subsequently prove to be incorrect and/or, to the extent legally required, may need to be restated, or changed. The disclosure of information on sustainability-related matters is not yet subject to the same recognized or accepted reporting or accounting principles and rules as traditional financial information. Consequently, there are no commonly accepted reporting practices for us to follow, and ESG metrics among organizations in our industry may not be comparable. In addition, the underlying data, systems, and controls that support non-financial reporting are generally considerably less sophisticated than the systems and internal control for financial reporting and rely on manual processes. This may result in non-comparable information between organizations and/or between reporting periods within organizations as methodologies continue to develop and/or be socialized. The further development of or changes to accounting and/or reporting standards could materially impact the performance metrics, data points, and targets contained in this report, and the reader may not be able to compare non-financial information performance metrics, data points, or targets between reporting periods on a direct like-for-like basis. Additionally, the information disclosed in this report contains references to “green,” “social,” “sustainable,” or equivalent-labelled activities, products, assets, or projects. There is currently no single globally recognized or accepted, consistent, and comparable set of definitions or standards (legal, regulatory, or otherwise) of, nor widespread cross-market consensus i) as to what constitutes, a ‘green’, ‘social,’ or ‘sustainable’ or having equivalent-labelled activity, product, or asset; or ii) as to what precise attributes are required for a particular activity, product, or asset to be defined as ‘green’, ‘social,’ or ‘sustainable’ or such other equivalent label; or iii) as to climate and sustainable funding and financing activities and their classification and reporting. Therefore, there is little certainty, and no assurance or representation is given that such activities, products, assets or projects and/or reporting of those activities, products, assets or projects will meet any present or future expectations or requirements for describing or classifying such activities, products, assets or projects as ‘green,’ ‘social,’ or ‘sustainable,’ or attributing similar labels. We expect policies, regulatory requirements, standards, and definitions to be developed and continuously evolve over time. Cautionary Statement Regarding Forward-Looking ESG or Sustainability Statements. Certain sections in this report contain ESG- or sustainability-related forward-looking statements, such as aims, ambitions, estimates, forecasts, plans, projections, targets, goals and other metrics, including but not limited to: climate and emissions, business and human rights, corporate governance, research and development and partnerships, development of products and services that intend to address sustainability-related concerns and sustainability related targets/ ambitions when finalized,


2026 Third Quarter Results


Page 17


   LOGO
Disclaimer     


including the implementation of technologies and other initiatives that aim to reduce and/or capture CO2 emissions. These forward-looking statements also include references to specific programs, such as our current “Future in Action” climate action and nature program, as well as various ESG-related indicators, objectives or metrics disclosed previously or that may be disclosed in the future, none of which are guarantees and any and all of which may ultimately not be achieved or may be abandoned at any time, whether in part, in full, or within any specific timeframe. There are many significant uncertainties, assumptions, judgements, opinions, estimates, forecasts and statements made of future expectations underlying these forward-looking statements which could cause actual results, performance, outcomes or events to differ materially from those expressed or implied in these forward-looking statements, which include, but are not limited to: the extent and pace of climate change, including the timing and manifestation of physical and transition risks; the macroeconomic environment; uncertainty around future climate-related policy and regulations, including the timely implementation and integration of adequate government policies; the effectiveness of actions of governments, legislators, regulators, businesses, investors, customers, and other stakeholders to mitigate the impact of climate and sustainability-related risks; changes in customer behavior and demand, changes in the available technology for mitigation and the effectiveness of any such technologies, as some of these new technologies may be unproven; excessive costs and expenses related to acquire and/or develop technology for mitigation; the roll-out of low carbon infrastructure; the availability and adoption of renewable energy in our value chain; the development of carbon capture, circular utilization, and sequestration technologies, including the adoption of cost-effective carbon-related technologies such as carbon capture, utilization, and storage; the availability of accurate, verifiable, reliable, consistent, and comparable climate-related data; lack of transparency and comparability of climate-related forward-looking methodologies; variation in approaches and outcomes, as variations in methodologies may lead to under or overestimates and consequently present exaggerated indication of climate-related risk; and reliance on assumptions and future uncertainty. Calculations of forward-looking metrics are complex and require many methodological choices and assumptions. Accordingly, undue reliance should not be placed on these forward-looking statements. Furthermore, changing national and international standards, industry and scientific practices, regulatory requirements, and market expectations regarding climate change, which remain under continuous development, are subject to different interpretations. There can be no assurance that these standards, practices, requirements, and expectations will not be interpreted differently than our understanding when defining sustainability-related ambitions and targets or change in a manner that substantially increases the cost or effort for us to achieve such ambitions and targets.

UNLESS OTHERWISE NOTED, ALL MONETARY FIGURES ARE PRESENTED IN DOLLARS, BASED ON INTERNATIONAL FINANCIAL REPORTING STANDARDS, AS APPLICABLE

Copyright Cemex, S.A.B. de C.V. and subsidiaries.


2026 Third Quarter Results


Page 18