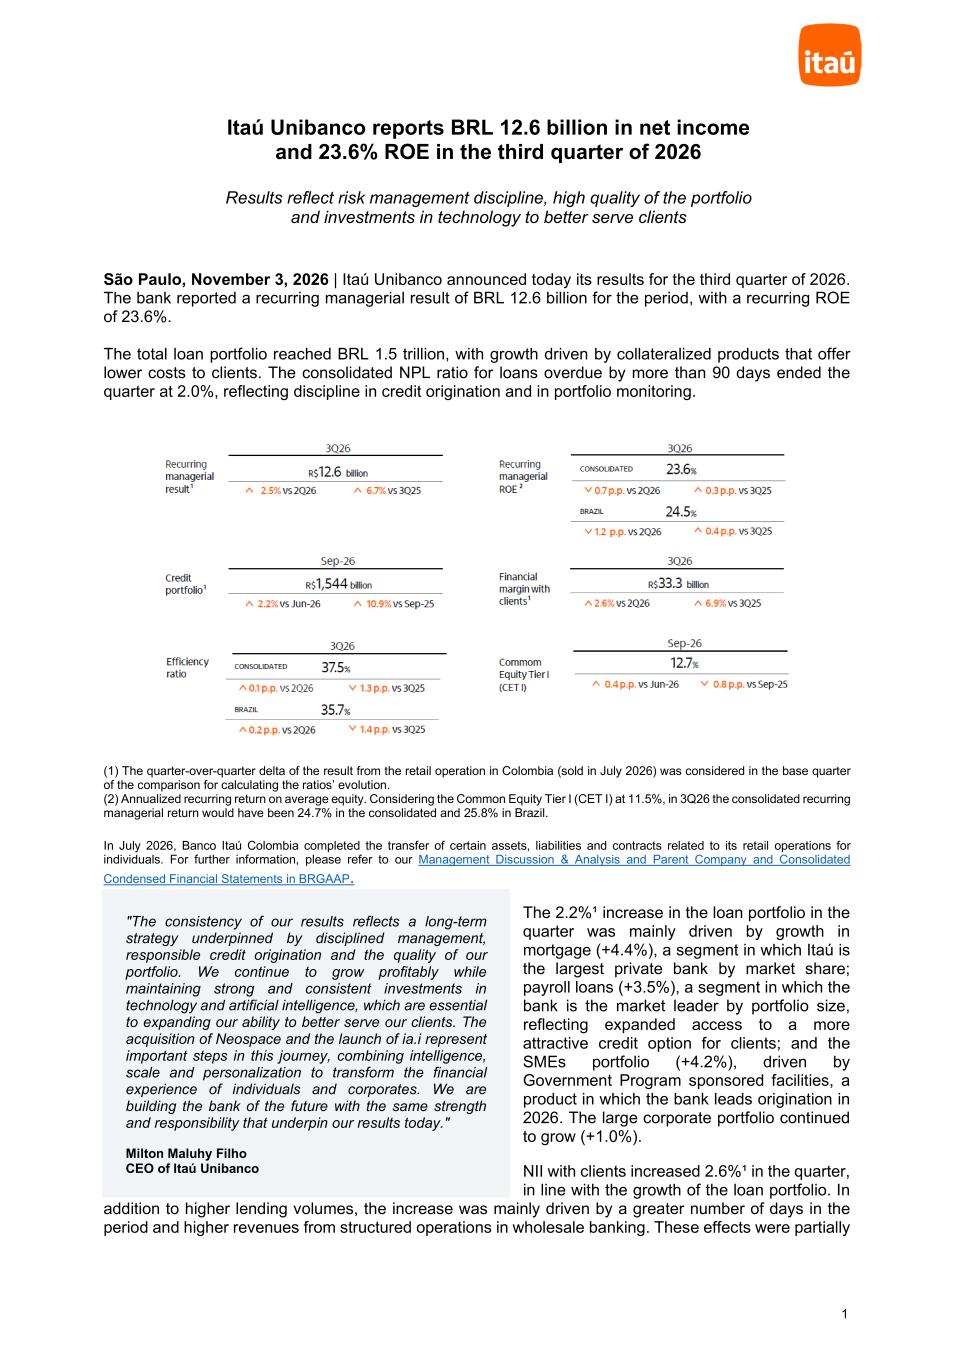
Itaú Unibanco reports BRL 12.6 billion in net income and 23.6% ROE in the third quarter of 2026 Results reflect risk management discipline, high quality of the portfolio and investments in technology to better serve clients São Paulo, November 3, 2026 | Itaú Unibanco announced today its results for the third quarter of 2026. The bank reported a recurring managerial result of BRL 12.6 billion for the period, with a recurring ROE of 23.6%. The total loan portfolio reached BRL 1.5 trillion, with growth driven by collateralized products that offer lower costs to clients. The consolidated NPL ratio for loans overdue by more than 90 days ended the quarter at 2.0%, reflecting discipline in credit origination and in portfolio monitoring. (1) The quarter-over-quarter delta of the result from the retail operation in Colombia (sold in July 2026) was considered in the base quarter of the comparison for calculating the ratios’ evolution. (2) Annualized recurring return on average equity. Considering the Common Equity Tier I (CET I) at 11.5%, in 3Q26 the consolidated recurring managerial return would have been 24.7% in the consolidated and 25.8% in Brazil. In July 2026, Banco Itaú Colombia completed the transfer of certain assets, liabilities and contracts related to its retail operations for individuals. For further information, please refer to our Management Discussion & Analysis and Parent Company and Consolidated Condensed Financial Statements in BRGAAP. The 2.2%¹ increase in the loan portfolio in the quarter was mainly driven by growth in mortgage (+4.4%), a segment in which Itaú is the largest private bank by market share; payroll loans (+3.5%), a segment in which the bank is the market leader by portfolio size, reflecting expanded access to a more attractive credit option for clients; and the SMEs portfolio (+4.2%), driven by Government Program sponsored facilities, a product in which the bank leads origination in 2026. The large corporate portfolio continued to grow (+1.0%). NII with clients increased 2.6%¹ in the quarter, in line with the growth of the loan portfolio. In addition to higher lending volumes, the increase was mainly driven by a greater number of days in the period and higher revenues from structured operations in wholesale banking. These effects were partially "The consistency of our results reflects a long-term strategy underpinned by disciplined management, responsible credit origination and the quality of our portfolio. We continue to grow profitably while maintaining strong and consistent investments in technology and artificial intelligence, which are essential to expanding our ability to better serve our clients. The acquisition of Neospace and the launch of ia.i represent important steps in this journey, combining intelligence, scale and personalization to transform the financial experience of individuals and corporates. We are building the bank of the future with the same strength and responsibility that underpin our results today." Milton Maluhy Filho CEO of Itaú Unibanco 1
offset by the product mix, reflecting growth in secured portfolios, including mortgages, payroll loans and Government Program sponsored facilities, as well as by asset spread compression, mitigated by higher volumes in the liability margin. Cost of credit totaled BRL 10.4 billion, with the annualized cost of credit ratio remaining stable compared with the previous quarter, at 2.7%. The NPL ratio for loans overdue between 15 and 90 days ended the quarter at 1.7% and the NPL ratio for loans overdue by more 90 days reached 2.0%. It is worth highlighting that Itaú continues to report delinquency indicators that are significantly better than market levels. In September, the delinquency rate over 15 days was 6.7% for individuals, 6.4 p.p. below the market rate excluding Itaú, and 2.9% for Corporates, approximately half the market level, also excluding Itaú. This difference reflects the consistency of Itaú’s strategy and disciplined risk management. Fee income increased 0.5%¹ in the quarter. Asset management revenues rose 7.8%, across both investment funds and consortium products, while card issuance revenues increased 7.1%. Conversely, investment banking revenues declined, mainly due to lower fixed-income securities issuance. Non-interest expenses totaled BRL 17.1 billion, up 2.4% in the quarter, mainly reflecting the 4.6% wage adjustment due to the collective bargaining agreement. Brazil's efficiency ratio reached 35.7% in the third quarter of 2026, 1.4 p.p. better than the ratio recorded in the same period last year (37.1%). Itaú ended the quarter with comfortable capitalization and liquidity levels. The Common Equity Tier 1 (CET I) ratio reached 12.7%, supported by organic capital generation. The strength of the balance sheet is also reflected in liquidity indicators: the Liquidity Coverage Ratio (LCR) ended September at 205.8%, compared with the minimum regulatory requirement of 100%, while the Net Stable Funding Ratio (NSFR) reached 123.7%, also compared with a minimum regulatory requirement of 100%. The loan-to-funding ratio was 78.6%. Together, these indicators reinforce the strength of the bank’s balance sheet, providing capacity to continue growing or navigate more challenging economic cycles. Itaú revised its 2026 guidance for the effective income and social contribution tax rate to between 28.0% and 29.0%, reflecting the change in the Long-Term Interest Rate (TJLP) trajectory. Guidance for all other lines remained unchanged. Itaú continues to advance its efforts to deliver an increasingly integrated and digital experience for its clients. During the quarter, “Pontos Itaú” were integrated into the Pix payment journey, enabling clients to use their reward program points directly for PIX transactions. Another highlight is the launch of Itaú Pay, a solution that connects clients and digital businesses through a simpler, safer and more personalized payment experience. Market Consensus Itaú Unibanco's results for the third quarter of 2026 were in line with Market Consensus³. ³ Market Consensus considers the average of estimates from the following institutions: Autonomous, Bank of America Merrill Lynch, Bradesco, BTG Pactual, Citi, Goldman Sachs, HSBC, J.P. Morgan, Morgan Stanley, Safra, Santander, UBS and XP Investimentos In BRL million Itaú Unibanco Market Consensus³ % Managerial Result 12,617 12,584 0.3% “The consistency of our results is supported by the strength of our balance sheet and the discipline with which we manage risk and allocate capital. This foundation enables us to grow responsibly, providing credit that is appropriate to our clients’ needs and repayment capacity. We continue to invest in technology to make the bank more efficient and improve the client experience, earning their preference and building long-lasting relationships. In doing so, our focus remains on sustaining profitability over time” Gabriel Amado de Moura CFO of Itaú Unibanco 2
For further information on Itaú Unibanco's results, please visit the Itaú Unibanco Investor Relations website: https://www.itau.com.br/investor-relations Corporate Communications – Itaú Unibanco imprensa@itau-unibanco.com.br 3