.2
|
| 2 Disclaimer Forward-Looking Statements This presentation contains “forward-looking statements” within the meanings of Section 27A of the Securities Act of 1933, as amended, and Section 21E of the Securities Exchange Act of 1934, as amended. The Company intends such forward-looking statements to be covered by the safe harbor provisions for forward-looking statements contained in the Private Securities Litigation Reform Act of 1995. Forward-looking statements include, without limitation, statements concerning plans, estimates, calculations, forecasts and projections with respect to the anticipated future performance of the Company. These statements are often, but not always, identified by words such as “may”, “might”, “should”, “could”, “predict”, “potential”, “believe”, “expect”, “continue”, “will”, “anticipate”, “seek”, “estimate”, “intend”, “plan”, “projection”, “would”, “annualized”, “target” and “outlook”, or the negative version of those words or other comparable words of a future or forward-looking nature. Forward-looking statements are neither historical facts nor assurances of future performance. Instead, they are based only on our current beliefs, expectations and assumptions regarding our business, future plans and strategies, projections, anticipated events and trends, the economy and other future conditions. Because forward-looking statements relate to the future, they are subject to inherent known and unknown uncertainties, risks, changes in circumstances and other factors that are difficult to predict and many of which are outside of our control. Our actual results and financial condition may differ materially from those indicated in the forward-looking statements. Therefore, you should not rely on any of these forward-looking statements. Important factors that could cause our actual results and financial condition to differ materially from those indicated in the forward-looking statements include, among others, the following: interest rate risk, including the effects of the recent increase in the benchmark federal funds rate by the Federal Reserve; effects on the U.S. economy resulting from actions taken by the federal government, including the threat or implementation of tariffs, immigration enforcement, executive orders, and changes in foreign policy; fluctuations in the values of the securities held in our securities portfolio, including as the result of changes in interest rates; business and economic conditions generally and in the financial services industry, nationally and within our market area, including the level and impact of inflation, and future monetary policies of the Federal Reserve and executive orders in response thereto, and possible recession; credit risk and risks from concentrations (including by type of borrower, geographic area, collateral and industry) within the Company’s loan portfolio or large loans to certain borrowers (including commercial real estate (“CRE”) loans); the overall health of the local and national real estate market; our ability to successfully manage credit risk; our ability to maintain an adequate level of allowance for credit losses on loans; new or revised accounting standards as may be adopted by state and federal regulatory agencies, the Financial Accounting Standards Board, Securities and Exchange Commission (the “SEC”) or Public Company Accounting Oversight Board; the concentration of large deposits from certain clients, including those who have balances above current Federal Deposit Insurance Corporation insurance limits; our ability to successfully manage liquidity risk, which may increase our dependence on non-core funding sources such as brokered deposits, and negatively impact our cost of funds; our ability to raise additional capital to implement our business plan; our ability to implement our growth strategy and manage costs effectively; the composition of our senior leadership team and our ability to attract and retain key personnel; talent and labor shortages and employee turnover; the occurrence of fraudulent activity, breaches or failures of our or our third-party vendors’ information security controls or cybersecurity-related incidents, including as a result of sophisticated attacks using artificial intelligence and similar tools or as a result of insider fraud; interruptions involving our information technology and telecommunications systems or third-party servicers; competition in the financial services industry, including from nonbank competitors such as credit unions, “fintech” companies and digital asset service providers; the effectiveness of our risk management framework; rapid technological changes implemented by us and other parties in the financial services industry, including third-party vendors, which may be more difficult to implement or more expensive than anticipated or which may have unforeseen consequence to us and our customers, including the development and implementation of tools incorporating artificial intelligence; emerging issues related to the development and use of artificial intelligence that could give rise to legal or regulatory action, damage our reputation, or otherwise materially harm our business or customers; the commencement, cost and outcome of litigation and other legal proceedings and regulatory actions against us; the impact of recent and future legislative and regulatory changes, domestic or foreign; risks related to climate change and the negative impact it may have on our customers and their businesses; the imposition of tariffs or other governmental policies impacting the global supply chain and the value of products produced by our commercial borrowers; severe weather, natural disasters, wide spread disease or pandemics, acts of war, military conflicts, or terrorism, changes in foreign relations, or other adverse external events, including the wars in Iran and Ukraine, ongoing conflicts in the Middle East and other international military conflicts that can increase levels of political and economic unpredictability, contribute to rising energy and commodity prices, affect global supply chains, increase the volatility of financial markets, and other matters beyond our control; potential impairment to the goodwill the Company recorded in connection with acquisitions; the availability of future equity and debt issuances and other capital raising opportunities on favorable terms; changes to U.S. or state tax laws, regulations and governmental policies concerning the Company’s general business, including changes in interpretation or prioritization of such rules and regulations; the impact of bank failures or adverse developments at other banks and related negative publicity about the banking industry in general on investor and depositor sentiment regarding the stability and liquidity of banks; and any other risks described in the “Risk Factors” sections of reports filed by the Company with the SEC. Any forward-looking statement made by us in this presentation is based only on information currently available to us and speaks only as of the date on which it is made. The Company undertakes no obligation to publicly update any forward-looking statement, whether written or oral, that may be made from time to time, whether as a result of new information, future developments or otherwise. Certain of the information contained in this presentation is derived from information provided by industry sources. Although the Company believes that such information is accurate and that the sources from which it has been obtained are reliable, the Company cannot guarantee the accuracy of, and has not independently verified, such information. Use of Non-GAAP financial measures In addition to the results presented in accordance with U.S. Generally Accepted Accounting Principles (“GAAP”), the Company routinely supplements its evaluation with an analysis of certain non-GAAP financial measures. The Company believes these non-GAAP financial measures, in addition to the related GAAP measures, provide meaningful information to investors to help them understand the Company’s operating performance and trends, and to facilitate comparisons with the performance of peers. These disclosures should not be viewed as a substitute for operating results determined in accordance with GAAP, nor are they necessarily comparable to non-GAAP performance measures that may be presented by other companies. Reconciliations of non-GAAP disclosures to the comparable GAAP measures are provided in this presentation. |
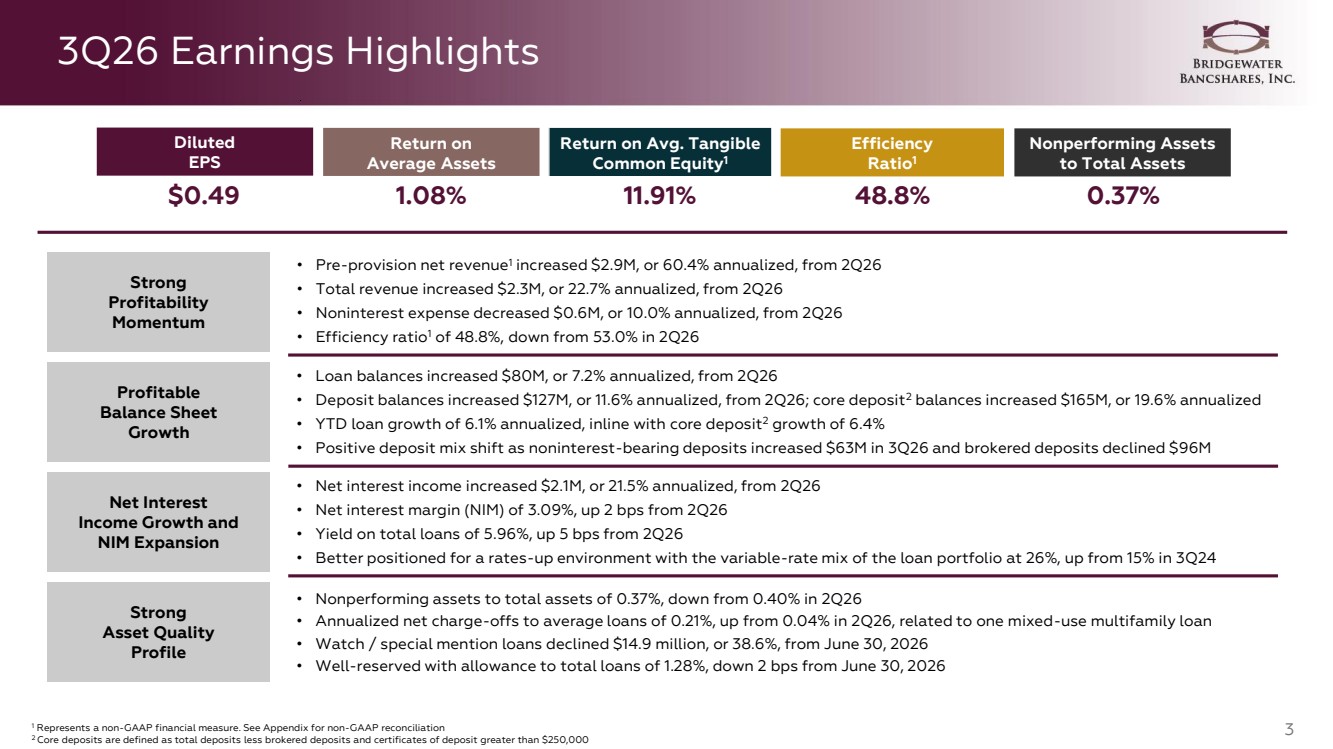
| 3 3Q26 Earnings Highlights • Pre-provision net revenue1 increased $2.9M, or 60.4% annualized, from 2Q26 • Total revenue increased $2.3M, or 22.7% annualized, from 2Q26 • Noninterest expense decreased $0.6M, or 10.0% annualized, from 2Q26 • Efficiency ratio1 of 48.8%, down from 53.0% in 2Q26 0.37% • Loan balances increased $80M, or 7.2% annualized, from 2Q26 • Deposit balances increased $127M, or 11.6% annualized, from 2Q26; core deposit2 balances increased $165M, or 19.6% annualized • YTD loan growth of 6.1% annualized, inline with core deposit2 growth of 6.4% • Positive deposit mix shift as noninterest-bearing deposits increased $63M in 3Q26 and brokered deposits declined $96M • Net interest income increased $2.1M, or 21.5% annualized, from 2Q26 • Net interest margin (NIM) of 3.09%, up 2 bps from 2Q26 • Yield on total loans of 5.96%, up 5 bps from 2Q26 • Better positioned for a rates-up environment with the variable-rate mix of the loan portfolio at 26%, up from 15% in 3Q24 Profitable Balance Sheet Growth Net Interest Income Growth and NIM Expansion $0.49 Diluted EPS Nonperforming Assets to Total Assets Efficiency Ratio1 Return on Average Assets Return on Avg. Tangible Common Equity1 1.08% 11.91% 48.8% 1 Represents a non-GAAP financial measure. See Appendix for non-GAAP reconciliation 2 Core deposits are defined as total deposits less brokered deposits and certificates of deposit greater than $250,000 • Nonperforming assets to total assets of 0.37%, down from 0.40% in 2Q26 • Annualized net charge-offs to average loans of 0.21%, up from 0.04% in 2Q26, related to one mixed-use multifamily loan • Watch / special mention loans declined $14.9 million, or 38.6%, from June 30, 2026 • Well-reserved with allowance to total loans of 1.28%, down 2 bps from June 30, 2026 Strong Asset Quality Profile Strong Profitability Momentum |
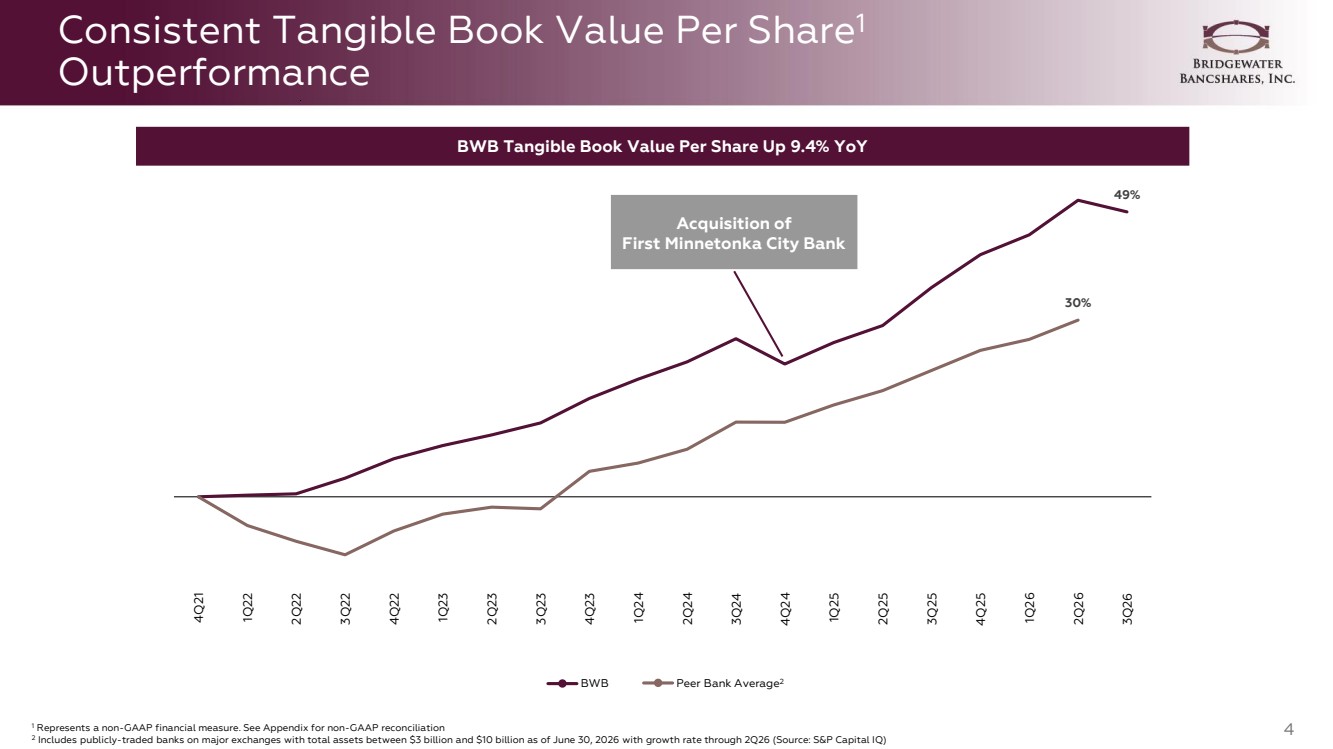
| 4 Consistent Tangible Book Value Per Share1 Outperformance 49% 30% 4Q21 1Q22 2Q22 3Q22 4Q22 1Q23 2Q23 3Q23 4Q23 1Q24 2Q24 3Q24 4Q24 1Q25 2Q25 3Q25 4Q25 1Q26 2Q26 3Q26 BWB Peer Bank Average2 Acquisition of First Minnetonka City Bank 1 Represents a non-GAAP financial measure. See Appendix for non-GAAP reconciliation 2 Includes publicly-traded banks on major exchanges with total assets between $3 billion and $10 billion as of June 30, 2026 with growth rate through 2Q26 (Source: S&P Capital IQ) BWB Tangible Book Value Per Share Up 9.4% YoY |
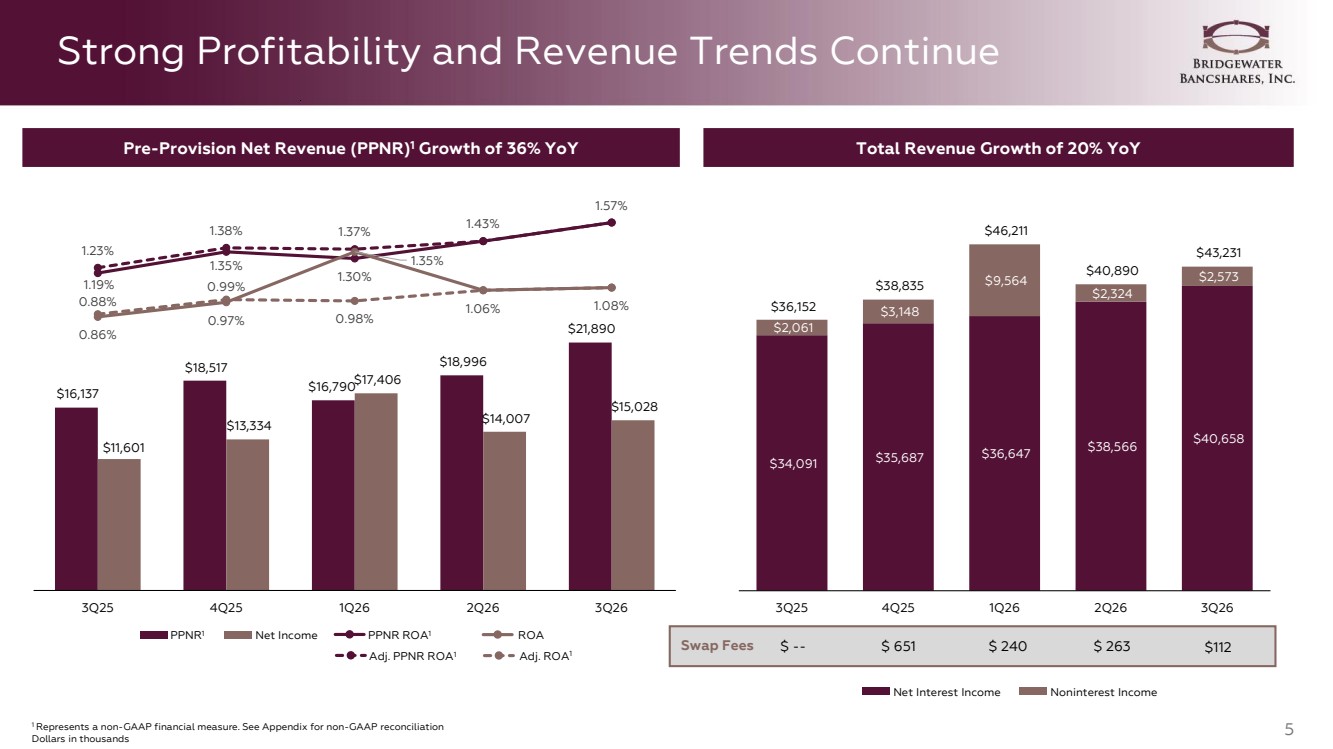
| 5 Strong Profitability and Revenue Trends Continue PPNR ROA1 $34,091 $35,687 $36,647 $38,566 $40,658 $2,061 $3,148 $9,564 $2,324 $2,573 $36,152 $38,835 $46,211 $40,890 $43,231 3Q25 4Q25 1Q26 2Q26 3Q26 $16,137 $18,517 $16,790 $18,996 $21,890 $11,601 $13,334 $17,406 $14,007 $15,028 1.19% 1.35% 1.30% 1.43% 1.57% 1.23% 1.38% 1.37% 0.86% 0.97% 1.35% 0.88% 1.06% 1.08% 0.99% 0.98% 3Q25 4Q25 1Q26 2Q26 3Q26 PPNR Net Income 1 ROA 1 Represents a non-GAAP financial measure. See Appendix for non-GAAP reconciliation Dollars in thousands Adj. PPNR ROA1 Adj. ROA1 Pre-Provision Net Revenue (PPNR)1 Growth of 36% YoY Total Revenue Growth of 20% YoY Net Interest Income Noninterest Income Swap Fees $ -- $ 651 $ 240 $ 263 $112 |
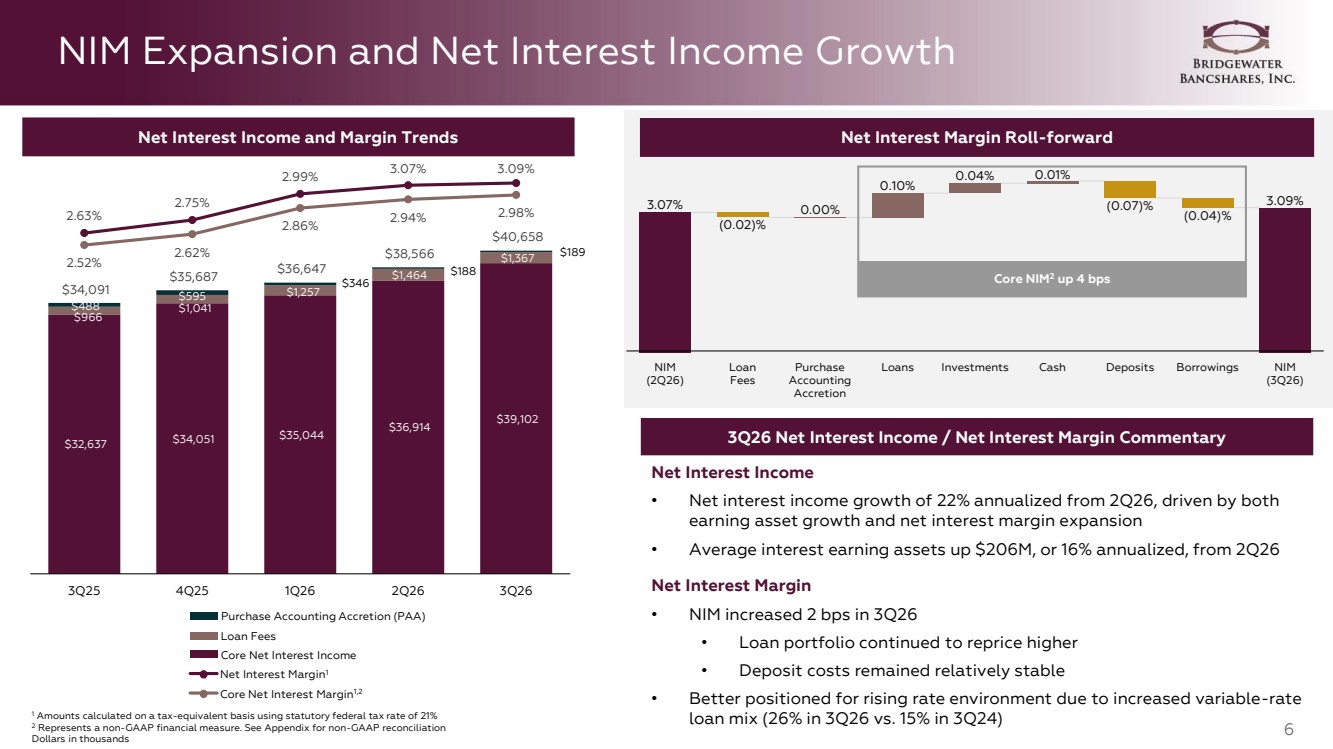
| 6 NIM Expansion and Net Interest Income Growth $32,637 $34,051 $35,044 $36,914 $39,102 $966 $1,041 $1,257 $1,464 $1,367 $488 $595 $346 $188 $189 $34,091 $35,687 $36,647 $38,566 $40,658 2.63% 2.75% 2.99% 3.07% 3.09% 2.52% 2.62% 2.86% 2.94% 2.98% 3Q25 4Q25 1Q26 2Q26 3Q26 Net Interest Margin1 Core Net Interest Income Loan Fees Net Interest Income and Margin Trends 3.07% 0.10% 0.04% 0.01% (0.07)% (0.04)% (0.02)% 0.00% 3.09% NIM (2Q26) Loan Fees Purchase Accounting Accretion Loans Investments Cash Deposits Borrowings NIM (3Q26) Net Interest Margin Roll-forward 3Q26 Net Interest Income / Net Interest Margin Commentary 1 Amounts calculated on a tax-equivalent basis using statutory federal tax rate of 21% 2 Represents a non-GAAP financial measure. See Appendix for non-GAAP reconciliation Dollars in thousands Net Interest Income • Net interest income growth of 22% annualized from 2Q26, driven by both earning asset growth and net interest margin expansion • Average interest earning assets up $206M, or 16% annualized, from 2Q26 Net Interest Margin • NIM increased 2 bps in 3Q26 • Loan portfolio continued to reprice higher • Deposit costs remained relatively stable • Better positioned for rising rate environment due to increased variable-rate loan mix (26% in 3Q26 vs. 15% in 3Q24) Core NIM2 up 4 bps Core Net Interest Margin1,2 Purchase Accounting Accretion (PAA) |
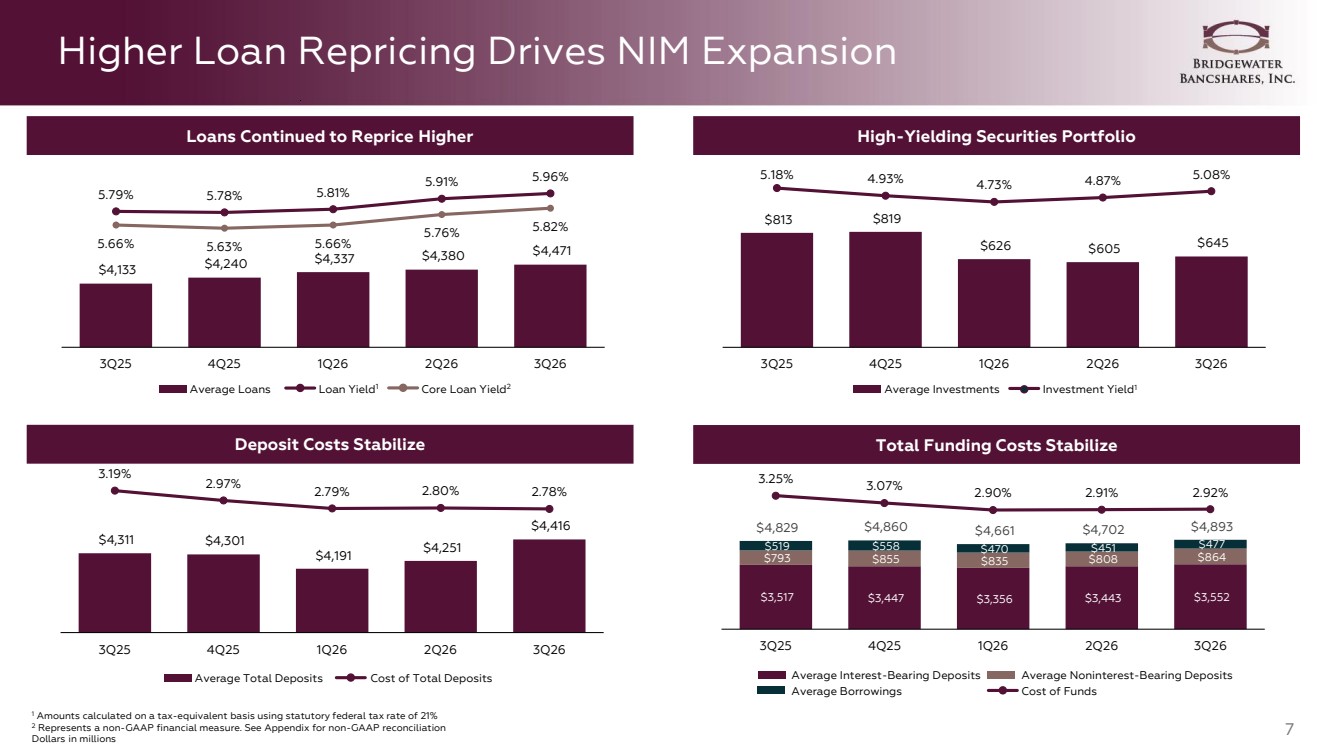
| 7 Higher Loan Repricing Drives NIM Expansion $3,517 $3,447 $3,356 $3,443 $3,552 $793 $855 $835 $808 $864 $519 $558 $470 $451 $477 $4,829 $4,860 $4,661 $4,702 $4,893 3.25% 3.07% 2.90% 2.91% 2.92% 3Q25 4Q25 1Q26 2Q26 3Q26 $4,133 $4,240 $4,337 $4,380 $4,471 5.79% 5.78% 5.81% 5.91% 5.96% 5.66% 5.63% 5.66% 5.76% 5.82% 3Q25 4Q25 1Q26 2Q26 3Q26 $4,311 $4,301 $4,191 $4,251 $4,416 3.19% 2.97% 2.79% 2.80% 2.78% 3Q25 4Q25 1Q26 2Q26 3Q26 Core Loan Yield2 $813 $819 $626 $605 $645 5.18% 4.93% 4.73% 4.87% 5.08% 3Q25 4Q25 1Q26 2Q26 3Q26 Average Interest-Bearing Deposits Average Noninterest-Bearing Deposits Average Borrowings Cost of Funds Average Loans Loan Yield1 Average Investments Investment Yield1 Average Total Deposits Cost of Total Deposits 1 Amounts calculated on a tax-equivalent basis using statutory federal tax rate of 21% 2 Represents a non-GAAP financial measure. See Appendix for non-GAAP reconciliation Dollars in millions Loans Continued to Reprice Higher Deposit Costs Stabilize High-Yielding Securities Portfolio Total Funding Costs Stabilize |
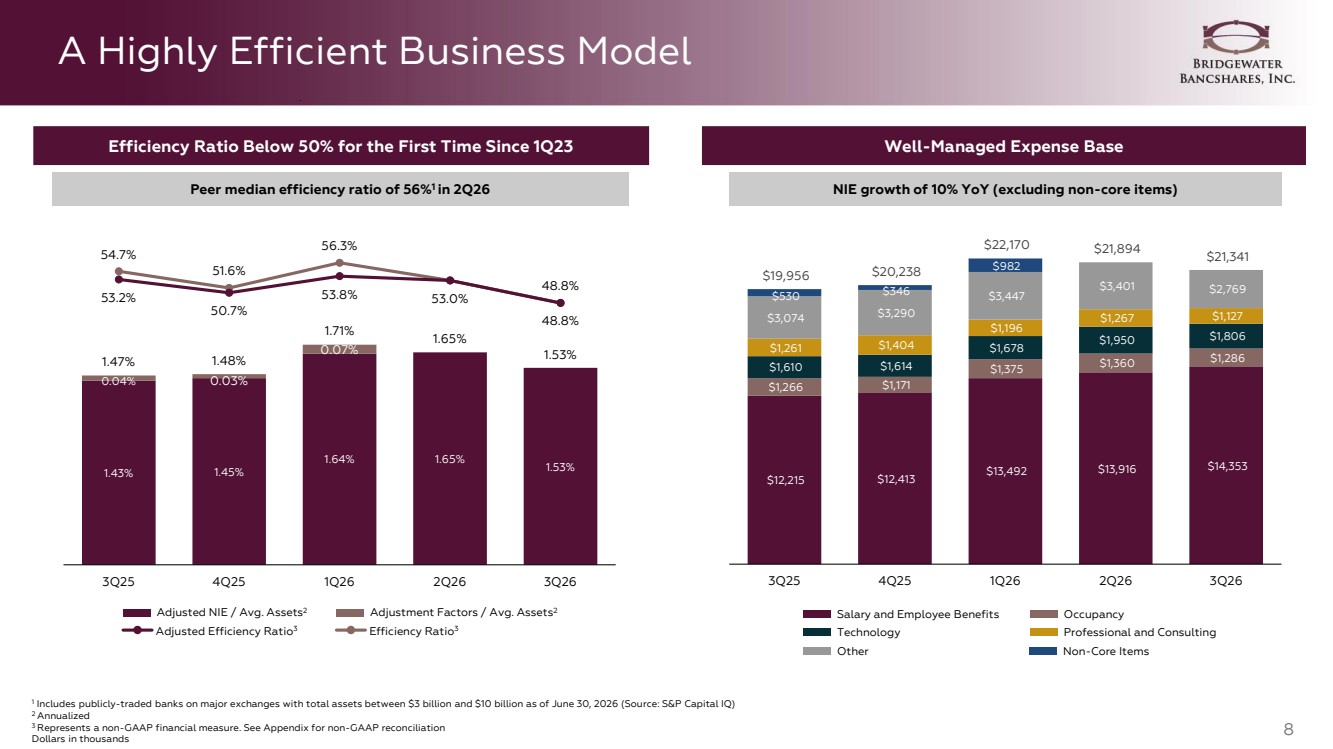
| $12,215 $12,413 $13,492 $13,916 $14,353 $1,266 $1,171 $1,375 $1,360 $1,286 $1,610 $1,614 $1,678 $1,950 $1,806 $1,261 $1,404 $1,196 $3,074 $3,290 $1,267 $1,127 $3,447 $3,401 $2,769 $530 $346 $982 $19,956 $20,238 $22,170 $21,894 $21,341 3Q25 4Q25 1Q26 2Q26 3Q26 8 A Highly Efficient Business Model 1.43% 1.45% 1.64% 1.65% 1.53% 0.04% 0.03% 0.07% 1.47% 1.48% 1.71% 1.65% 1.53% 54.7% 51.6% 56.3% 48.8% 53.2% 50.7% 53.8% 53.0% 48.8% 3Q25 4Q25 1Q26 2Q26 3Q26 Adjusted NIE / Avg. Assets2 Adjusted Efficiency Ratio3 Peer median efficiency ratio of 56%1 in 2Q26 NIE growth of 10% YoY (excluding non-core items) Salary and Employee Benefits Occupancy Technology Professional and Consulting 1 Includes publicly-traded banks on major exchanges with total assets between $3 billion and $10 billion as of June 30, 2026 (Source: S&P Capital IQ) 2 Annualized 3 Represents a non-GAAP financial measure. See Appendix for non-GAAP reconciliation Dollars in thousands Other Adjustment Factors / Avg. Assets2 Efficiency Ratio3 Non-Core Items Efficiency Ratio Below 50% for the First Time Since 1Q23 Well-Managed Expense Base |
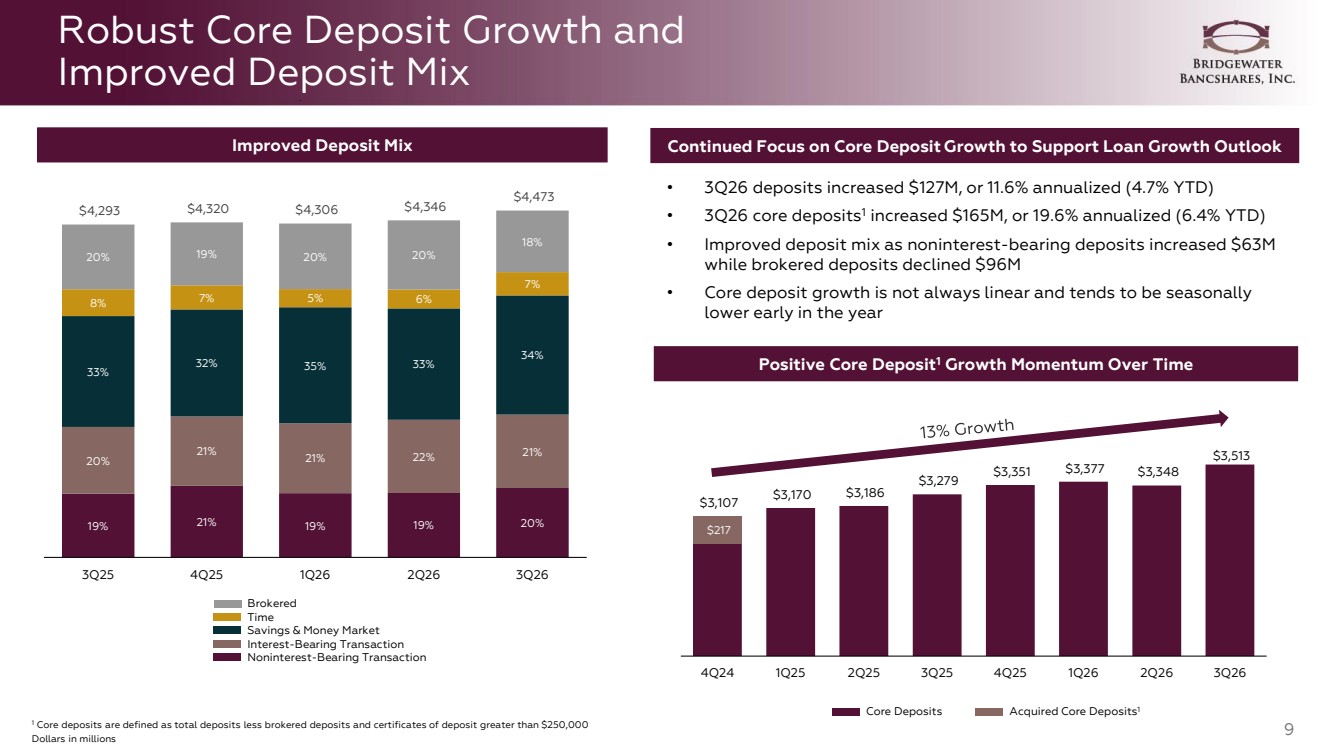
| 9 Robust Core Deposit Growth and Improved Deposit Mix 19% 21% 19% 19% 20% 20% 21% 21% 22% 21% 33% 32% 35% 33% 34% 8% 7% 5% 6% 7% 20% 19% 20% 20% 18% $4,293 $4,320 $4,306 $4,346 $4,473 3Q25 4Q25 1Q26 2Q26 3Q26 Interest-Bearing Transaction Noninterest-Bearing Transaction Time Savings & Money Market Brokered • 3Q26 deposits increased $127M, or 11.6% annualized (4.7% YTD) • 3Q26 core deposits1 increased $165M, or 19.6% annualized (6.4% YTD) • Improved deposit mix as noninterest-bearing deposits increased $63M while brokered deposits declined $96M • Core deposit growth is not always linear and tends to be seasonally lower early in the year Continued Focus on Core Deposit Growth to Support Loan Growth Outlook 1 Core deposits are defined as total deposits less brokered deposits and certificates of deposit greater than $250,000 Dollars in millions Positive Core Deposit1 Growth Momentum Over Time $217 $3,107 $3,170 $3,186 $3,279 $3,351 $3,377 $3,348 $3,513 4Q24 1Q25 2Q25 3Q25 4Q25 1Q26 2Q26 3Q26 Improved Deposit Mix Core Deposits Acquired Core Deposits1 |
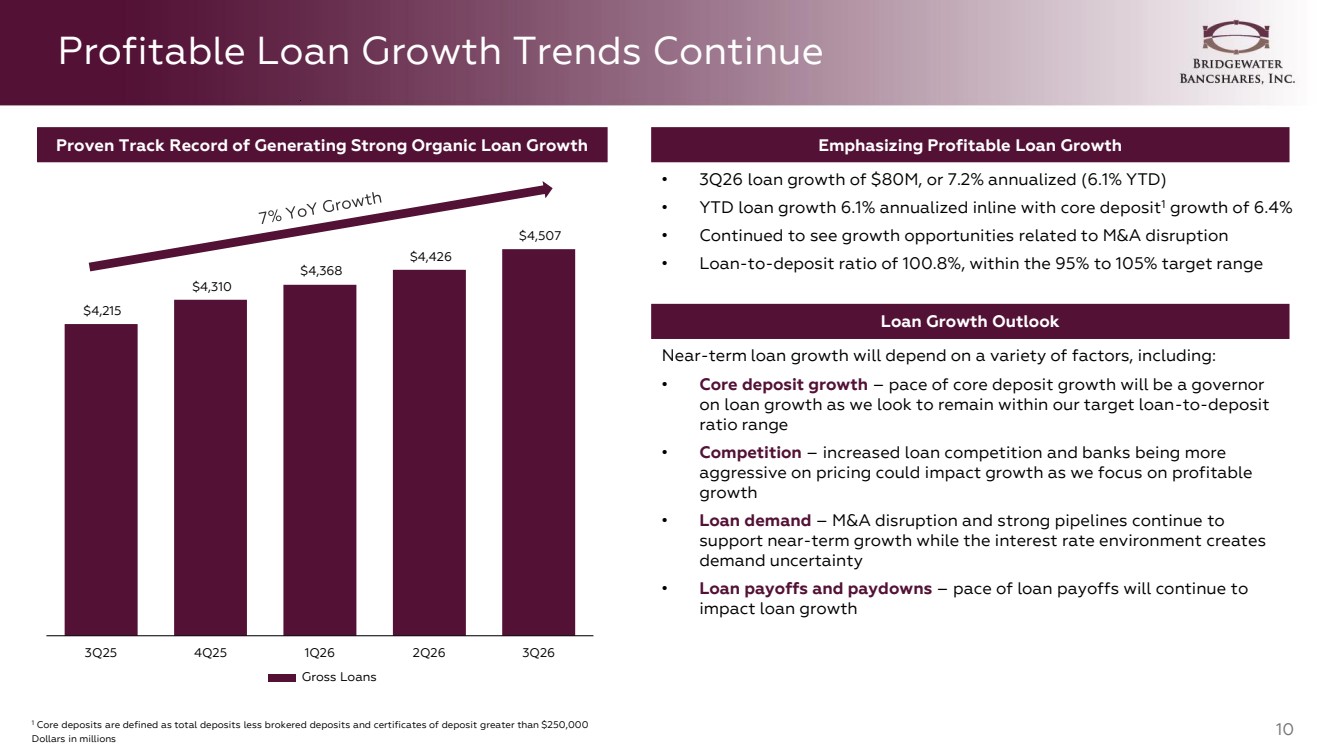
| 10 Profitable Loan Growth Trends Continue $4,215 $4,310 $4,368 $4,426 $4,507 3Q25 4Q25 1Q26 2Q26 3Q26 Gross Loans 1 Core deposits are defined as total deposits less brokered deposits and certificates of deposit greater than $250,000 Dollars in millions • 3Q26 loan growth of $80M, or 7.2% annualized (6.1% YTD) • YTD loan growth 6.1% annualized inline with core deposit1 growth of 6.4% • Continued to see growth opportunities related to M&A disruption • Loan-to-deposit ratio of 100.8%, within the 95% to 105% target range Emphasizing Profitable Loan Growth Near-term loan growth will depend on a variety of factors, including: • Core deposit growth – pace of core deposit growth will be a governor on loan growth as we look to remain within our target loan-to-deposit ratio range • Competition – increased loan competition and banks being more aggressive on pricing could impact growth as we focus on profitable growth • Loan demand – M&A disruption and strong pipelines continue to support near-term growth while the interest rate environment creates demand uncertainty • Loan payoffs and paydowns – pace of loan payoffs will continue to impact loan growth Loan Growth Outlook Proven Track Record of Generating Strong Organic Loan Growth |
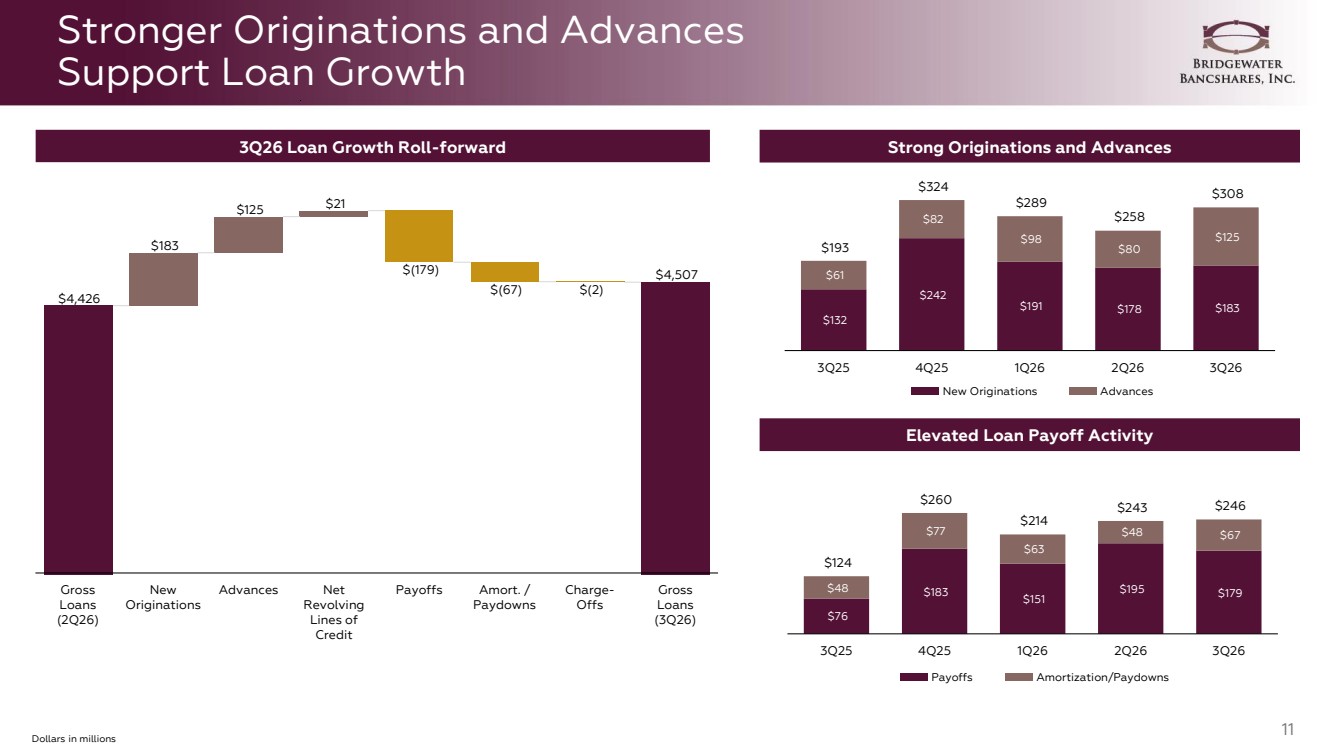
| 11 Stronger Originations and Advances Support Loan Growth Strong Originations and Advances $132 $242 $191 $178 $183 $61 $82 $98 $80 $125 $193 $324 $289 $258 $308 3Q25 4Q25 1Q26 2Q26 3Q26 New Originations Advances Elevated Loan Payoff Activity $76 $183 $151 $195 $179 $48 $77 $63 $48 $67 $124 $260 $214 $243 $246 3Q25 4Q25 1Q26 2Q26 3Q26 Payoffs Amortization/Paydowns Dollars in millions $4,426 $21 $4,507 $183 $125 $(179) $(67) $(2) Gross Loans (2Q26) New Originations Advances Net Revolving Lines of Credit Payoffs Amort. / Paydowns Charge-Offs Gross Loans (3Q26) 3Q26 Loan Growth Roll-forward |
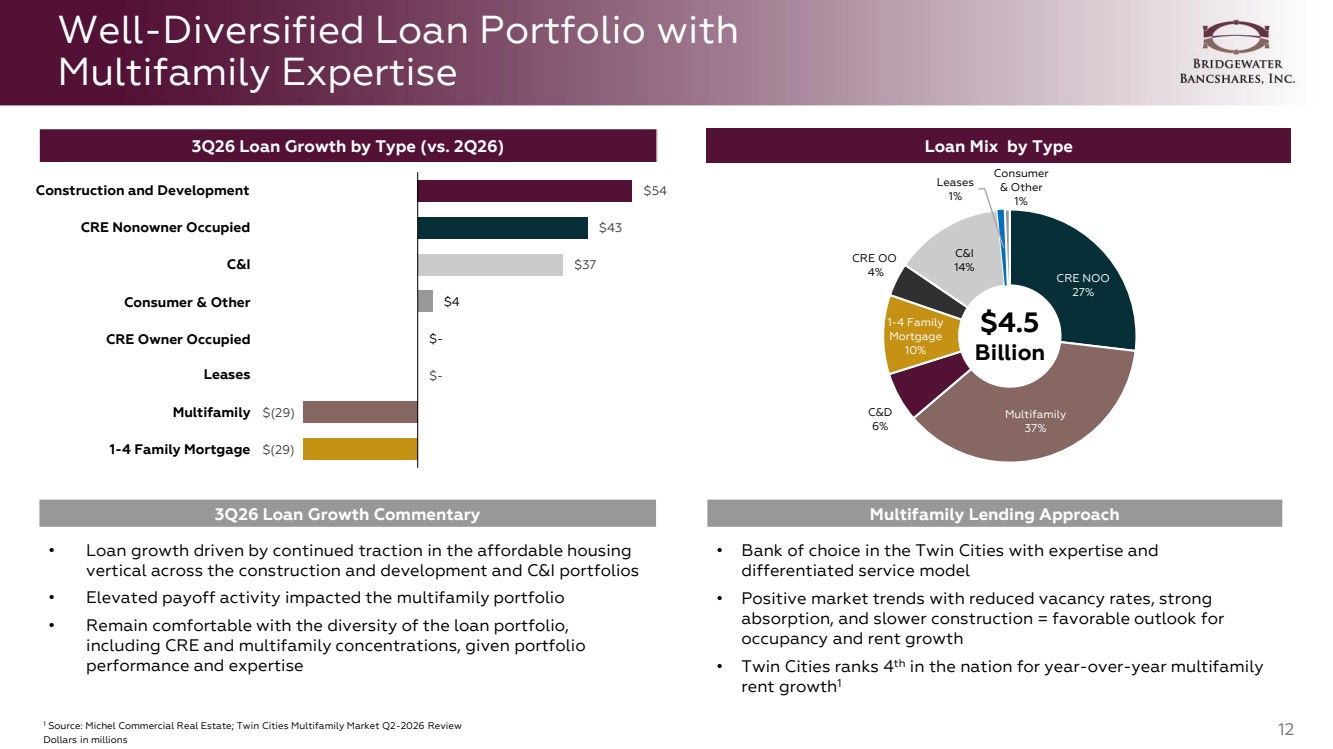
| 12 Well-Diversified Loan Portfolio with Multifamily Expertise $(29) $(29) $- $- $4 $37 $43 $54 1 Source: Michel Commercial Real Estate; Twin Cities Multifamily Market Q2-2026 Review Dollars in millions CRE NOO 27% Multifamily 37% C&D 6% 1-4 Family Mortgage 10% CRE OO 4% C&I 14% Leases 1% Consumer & Other 1% Loan Mix by Type $4.5 Billion • Loan growth driven by continued traction in the affordable housing vertical across the construction and development and C&I portfolios • Elevated payoff activity impacted the multifamily portfolio • Remain comfortable with the diversity of the loan portfolio, including CRE and multifamily concentrations, given portfolio performance and expertise 3Q26 Loan Growth by Type (vs. 2Q26) Multifamily 1-4 Family Mortgage Construction and Development C&I CRE Nonowner Occupied CRE Owner Occupied Consumer & Other Leases 3Q26 Loan Growth Commentary • Bank of choice in the Twin Cities with expertise and differentiated service model • Positive market trends with reduced vacancy rates, strong absorption, and slower construction = favorable outlook for occupancy and rent growth • Twin Cities ranks 4th in the nation for year-over-year multifamily rent growth1 Multifamily Lending Approach |
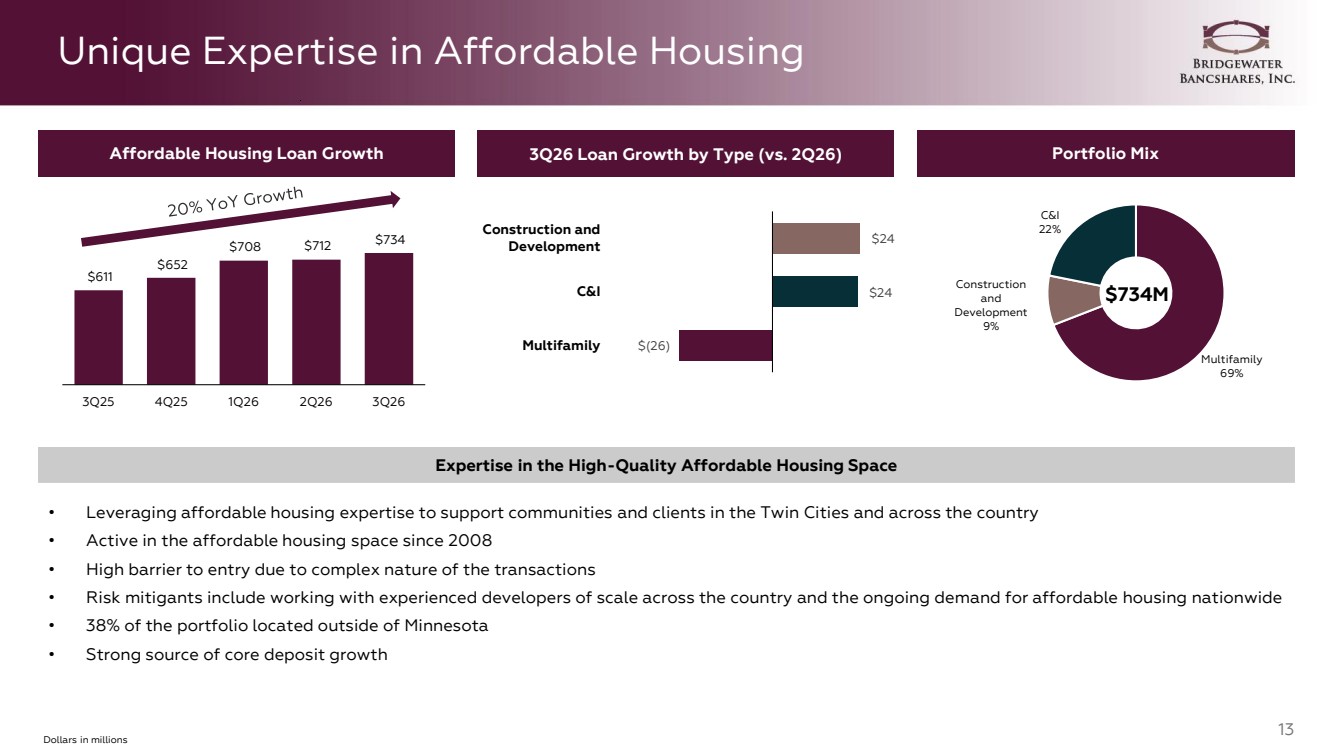
| 13 Unique Expertise in Affordable Housing Dollars in millions Expertise in the High-Quality Affordable Housing Space • Leveraging affordable housing expertise to support communities and clients in the Twin Cities and across the country • Active in the affordable housing space since 2008 • High barrier to entry due to complex nature of the transactions • Risk mitigants include working with experienced developers of scale across the country and the ongoing demand for affordable housing nationwide • 38% of the portfolio located outside of Minnesota • Strong source of core deposit growth Multifamily 69% Construction and Development 9% C&I 22% $734M $611 $652 $708 $712 $734 3Q25 4Q25 1Q26 2Q26 3Q26 $(26) $24 $24 Construction and Development C&I Multifamily Affordable Housing Loan Growth 3Q26 Loan Growth by Type (vs. 2Q26) Portfolio Mix |
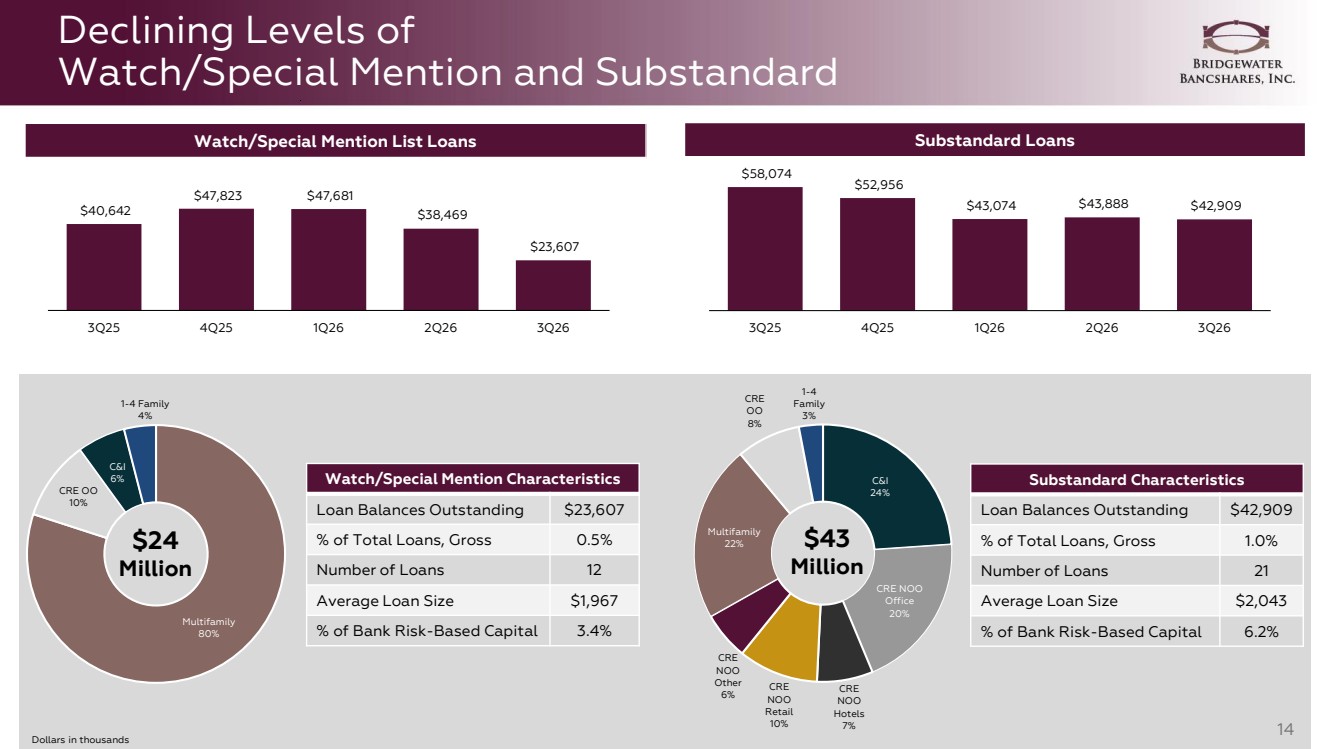
| 14 Declining Levels of Watch/Special Mention and Substandard Multifamily 80% CRE OO 10% C&I 6% 1-4 Family 4% $24 Million Watch/Special Mention List Loans Substandard Loans C&I 24% CRE NOO Office 20% CRE NOO Hotels 7% CRE NOO Retail 10% CRE NOO Other 6% Multifamily 22% CRE OO 8% 1-4 Family 3% $43 Million Watch/Special Mention Characteristics Loan Balances Outstanding $23,607 % of Total Loans, Gross 0.5% Number of Loans 12 Average Loan Size $1,967 % of Bank Risk-Based Capital 3.4% Substandard Characteristics Loan Balances Outstanding $42,909 % of Total Loans, Gross 1.0% Number of Loans 21 Average Loan Size $2,043 % of Bank Risk-Based Capital 6.2% $40,642 $47,823 $47,681 $38,469 $23,607 3Q25 4Q25 1Q26 2Q26 3Q26 $58,074 $52,956 $43,074 $43,888 $42,909 3Q25 4Q25 1Q26 2Q26 3Q26 Dollars in thousands |
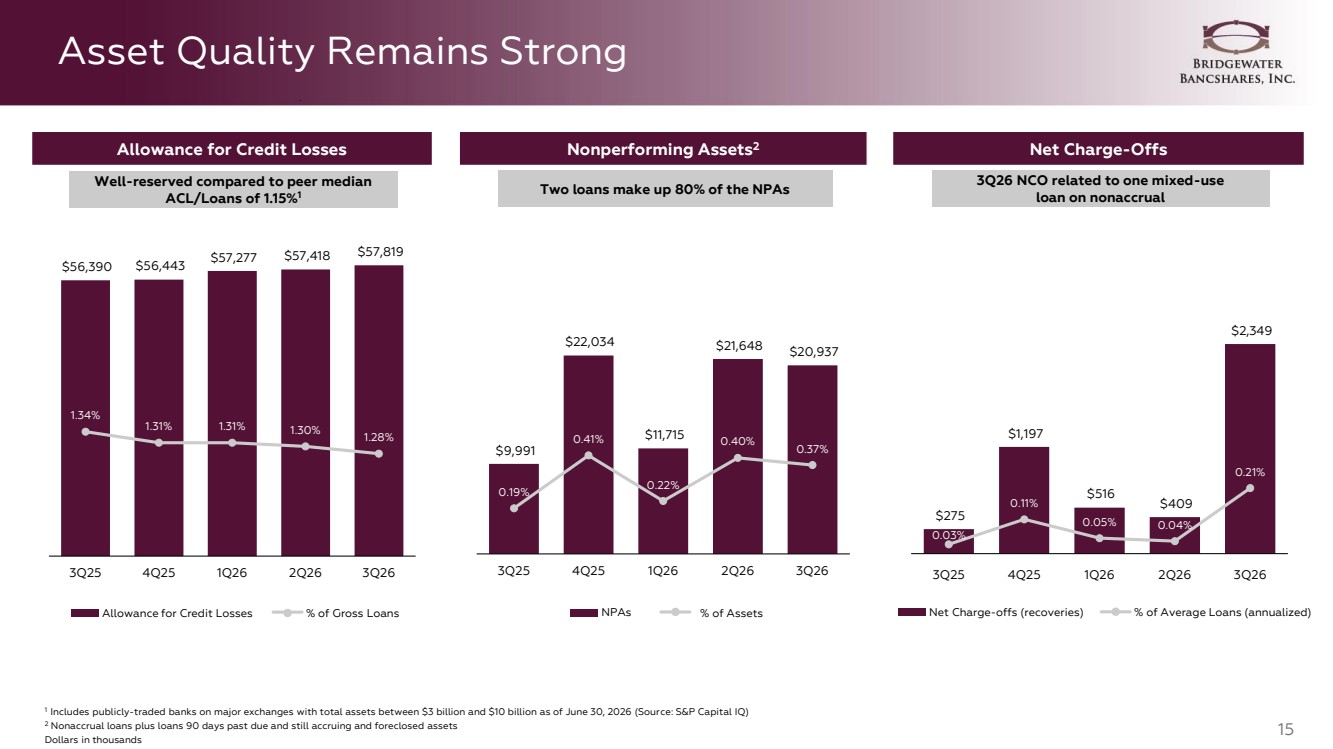
| 15 Asset Quality Remains Strong 1 Includes publicly-traded banks on major exchanges with total assets between $3 billion and $10 billion as of June 30, 2026 (Source: S&P Capital IQ) 2 Nonaccrual loans plus loans 90 days past due and still accruing and foreclosed assets Dollars in thousands $275 $1,197 $516 $409 $2,349 0.03% 0.11% 0.05% 0.04% 0.21% 3Q25 4Q25 1Q26 2Q26 3Q26 Net Charge-Offs 3Q26 NCO related to one mixed-use loan on nonaccrual Net Charge-offs (recoveries) % of Average Loans (annualized) $56,390 $56,443 $57,277 $57,418 $57,819 1.34% 1.31% 1.31% 1.30% 1.28% 3Q25 4Q25 1Q26 2Q26 3Q26 Allowance for Credit Losses Well-reserved compared to peer median ACL/Loans of 1.15%1 Allowance for Credit Losses % of Gross Loans $9,991 $22,034 $11,715 $21,648 $20,937 0.19% 0.41% 0.22% 0.40% 0.37% 3Q25 4Q25 1Q26 2Q26 3Q26 Nonperforming Assets2 Two loans make up 80% of the NPAs NPAs % of Assets |
| 16 Strong Capital Position to Support Growth Total Risk-Based Capital Ratio Common Equity Tier 1 Capital Ratio Tier 1 Leverage Ratio Stable Capital Ratios Tangible Common Equity Ratio1 1 Represents a non-GAAP financial measure. See Appendix for non-GAAP reconciliation Recent Capital Actions • $12.4M remaining under current share repurchase authorization as of September 30, 2026; no shares repurchased in 3Q26 • No shares sold in 3Q26 as part of the at-the-market (ATM) offering launched in February 2026 Capital Allocation Priorities 1 3 2 Organic Growth Share Repurchases M&A 4 Dividends Drive profitability by supporting a proven organic loan growth engine Opportunistically return capital to shareholders by buying back stock based on valuation, capital levels, and other uses of capital Review and evaluate M&A opportunities that complement BWB’s business model Have not historically paid a common stock dividend given organic growth opportunities 9.02% 9.20% 9.89% 10.02% 9.94% 9.08% 9.17% 9.53% 9.61% 9.63% 14.12% 14.12% 14.48% 14.48% 14.24% 7.71% 8.01% 8.34% 8.62% 8.16% 3Q25 4Q25 1Q26 2Q26 3Q26 |
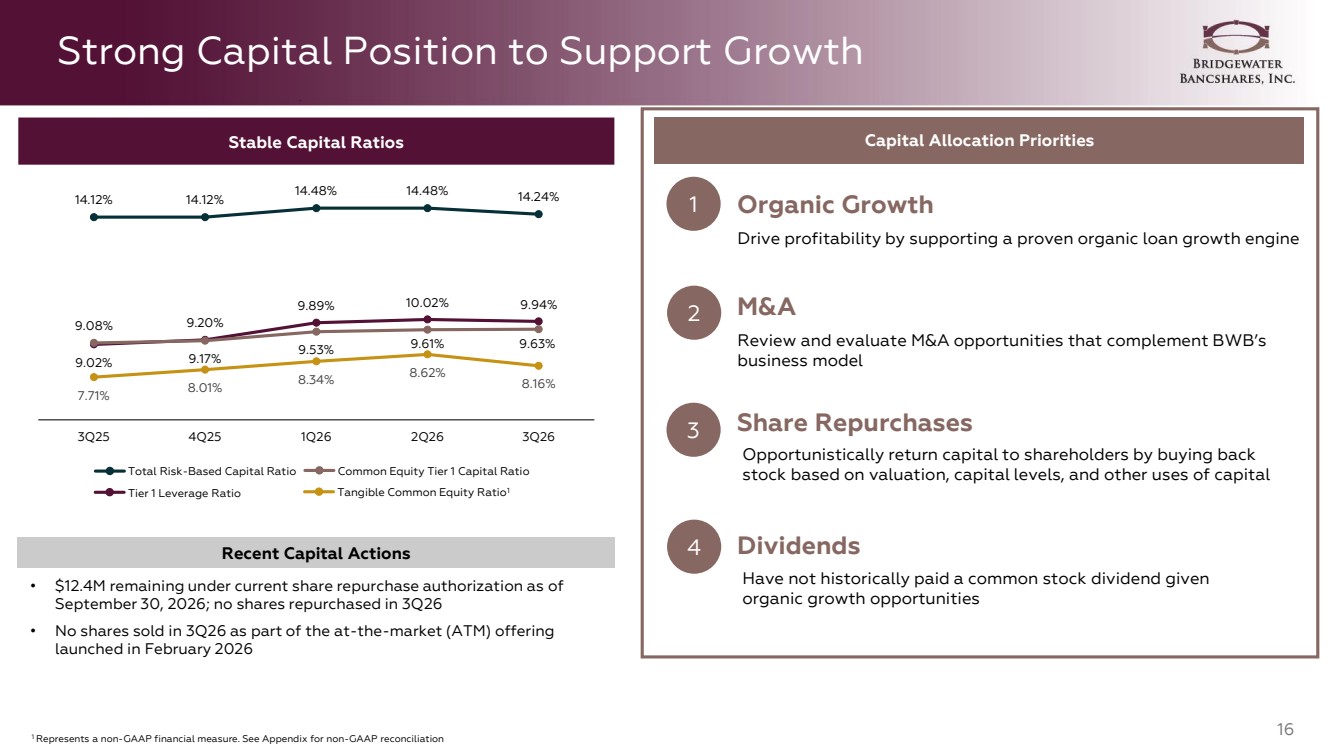
| 17 Near-Term Expectations • Mid-single digit loan growth, dependent on the pace of core deposit growth • Focus on profitable growth while aligning loan growth with core deposit growth over time • Target loan-to-deposit ratio between 95% and 105% Balance Sheet Growth • Net interest margin stability over the near-term (assumes three additional rate hikes through the first half of 2027) • Higher loan repricing offsetting higher deposit costs • Dependent on changes in interest rates and shape of the yield curve • Continued net interest income growth due to NIM stabilization and loan growth outlook Net Interest Margin • Noninterest expense to return to 2Q26 levels in 4Q26 • Continued investments in people and technology initiatives Expenses • Maintain stable capital levels in the current environment given the growth outlook • Opportunistic and nimble approach to capital, focused on enhancing shareholder value and supporting the balance sheet, whether as a purchaser or issuer Capital Levels |
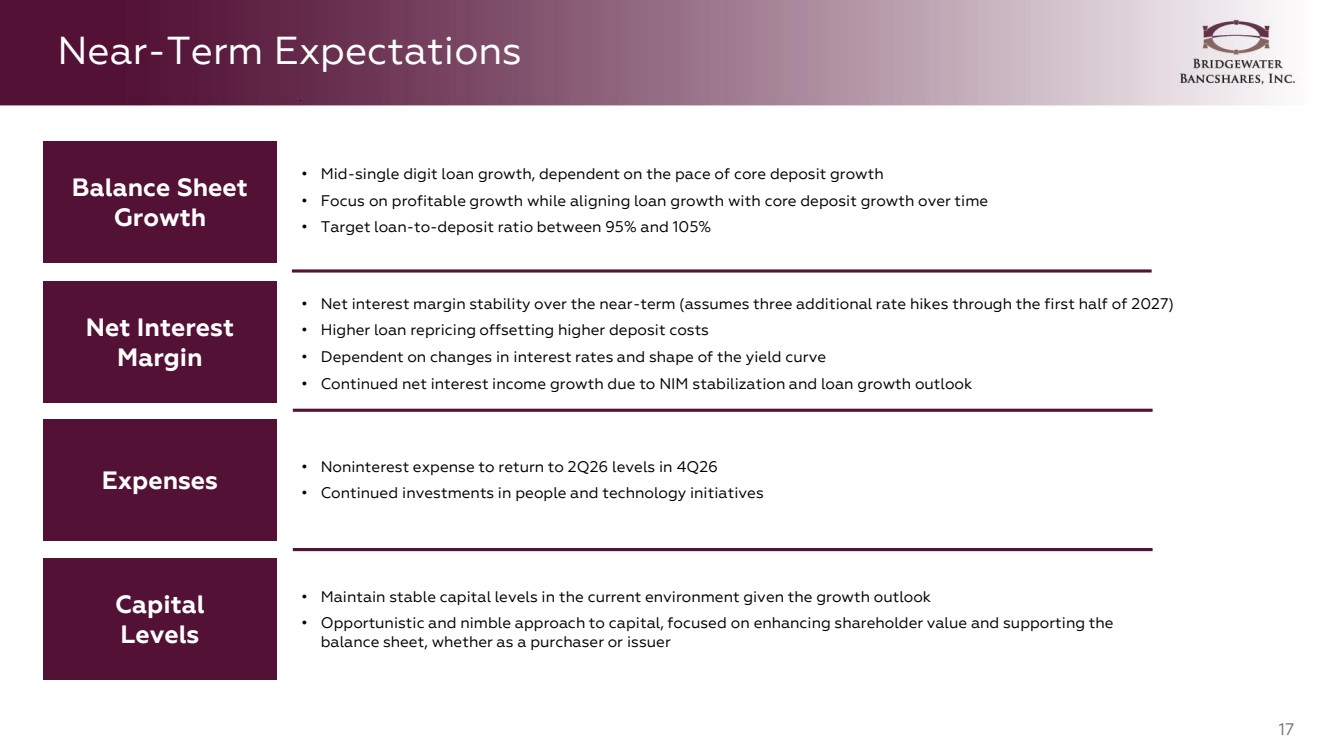
| 18 2026 Strategic Priorities Optimize Levels of Profitable Growth Continue to Gain Loan and Deposit Market Share Expand Reach of the Affordable Housing Vertical Leverage Technology to Support Business Growth • Leverage elevated loan demand and pipelines to drive organic loan growth • Continue to align loan growth with core deposit growth over time • Drive NIM expansion in the lower interest rate environment • Maintain strong credit quality through consistent underwriting standards and active credit oversight • Take local deposit and loan market share by being the bank-of-choice for clients wanting to bank local in the Twin Cities • Expand expertise and capacity across targeted verticals, such as affordable housing, women business leaders, nonprofits, and SBA • Leverage marketplace disruption in the Twin Cities to attract new clients and top talent • Evaluate M&A opportunities that support our business model and growth outlook • Leverage affordable housing expertise to grow client base across the Twin Cities and nationally • Enhance our national presence as an affordable housing lender while building infrastructure for long-term growth • Expand and enhance perm product offering to drive additional loan and swap fee income • Continue to earn strong core deposits through affordable housing transactions • Leverage recent technology investments to support growth and enhance workflow efficiencies • Develop AI strategies to enhance operational efficiencies, strengthen client relationships, and empower team members • Modernize core banking for scalable growth with open architecture and easy access to third party services • Expand investment in digital products to improve the client experience Year-to-Date Progress (3Q26) • Aligning loan growth (6.1%) with core deposit1 growth (6.4%) • NIM expansion of 34 bps • Hired 17 team members as a result of the local M&A disruption • Affordable housing balances up $82M, or 17% annualized • Advanced AI from strategy to execution through enterprise governance, workforce enablement and governed automation pilots 1 Core deposits are defined as total deposits less brokered deposits and certificates of deposit greater than $250,000 |
| 19 APPENDIX |
| 20 Loan Portfolio Positioned to Reprice Higher 21% 19% 19% 8% 18% 15% $105 $94 $94 $38 $88 $72 Less Than 1 Year 1 to 2 Years 2 to 3 Years 3 to 4 Years 4 to 5 Years 5+ Years 25% 19% 17% 14% 13% 12% $697 $527 $467 $408 $382 $348 Less Than 1 Year 1 to 2 Years 2 to 3 Years 3 to 4 Years 4 to 5 Years 5+ Years Fixed, 63% Variable, 26% Adjustable, 11% Loan Portfolio Mix Fixed-Rate Portfolio ($2.8B) Variable-Rate Portfolio ($1.2B) Adjustable-Rate Portfolio ($490M) Years to Maturity • $697M of fixed-rate loans maturing over the next year, with a weighted average yield of 5.70% • Larger fixed-rate portfolio provides support to total loan yields in a rates-down environment Variable-Rate Loan Floors • Intentional focus on growing the variable-rate loans to make the loan portfolio more rate-neutral • $1.2B of variable-rate loans offset much of the $1.6B of immediately adjustable deposits tied to short-term rates • 68% of variable-rate portfolio have rate floors, with 83% of the floors at or above 5% • 97% of variable-rate loans are currently tied to SOFR or Prime Adjustable-Rate Repricing/Maturity Schedule • $105M of adjustable-rate loans repricing or maturing over the next year, with a weighted average yield of 4.23% • Adjustable-rate loans positioned to continue repricing higher Dollars in millions Data as of September 30, 2026 WA Yield 5.70% 5.57% 5.55% 6.16% 5.56% 4.52% WA Yield 4.23% 4.44% 5.68% 6.56% 6.63% 4.65% 5% 12% 36% 43% 4% $44 $98 $295 $346 $30 Below 4% 4%-5% 5%-6% 6%-7% Above 7% Increasing Variable-Rate Mix Fixed Variable Adjustable 67% 65% 65% 64% 63% 19% 22% 23% 25% 26% 14% 13% 12% 11% 11% 3Q25 4Q25 1Q26 2Q26 3Q26 |
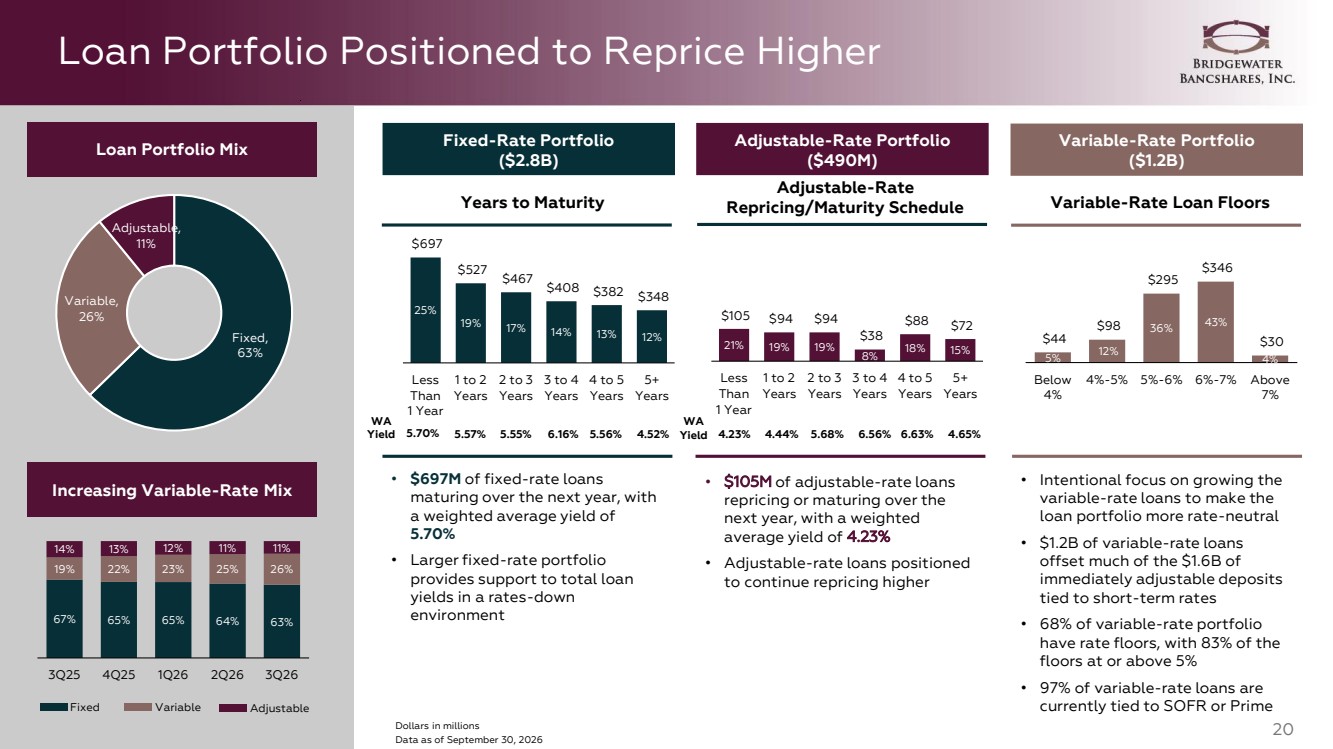
| Interest Rate Sensitivity Estimated Change in NII From Immediate Interest Rate Shocks +100 bps -100 bps Loan Portfolio Considerations • Loan portfolio most sensitive to changes in the 3- to 5-year portion of the yield curve • Increased mix of variable-rate loans to support loan yield repricing in a rates-up environment • $802M of fixed- and adjustable-rate loans scheduled to reprice over the next year • Leveraged prepayment penalties on new loan originations to help maintain benefit of higher rates over time Funding Considerations • Deposit base is more sensitive to changing interest rates • Strong momentum in core deposit growth since March 2023 • Continue to supplement core deposits with wholesale funding to support loan growth over time • $2.0B of funding tied to short-term rates, including $1.6B of immediately-adjustable deposits and $0.4B of derivative hedging • $592M of other repricing opportunities, including time deposit maturities over the next 12 months and callable brokered deposits with rates over 4.00% -200 bps (1.1)% +4.3% 2Q26 +13.3% (1.0)% +2.4% 3Q26 +8.1% (2.7)% +4.4% 3Q25 +10.5% (1.1)% +4.6% 1Q26 +12.2% (1.4)% +3.7% 4Q25 +9.4% +200 bps (4.9)% (2.8)% (2.2)% (2.4)% (2.5)% 21 More neutral balance sheet with rate-sensitive portions of the loan and deposit portfolios better aligned – $1.2B of variable-rate loans and $1.6B of deposits tied to short-term rates |
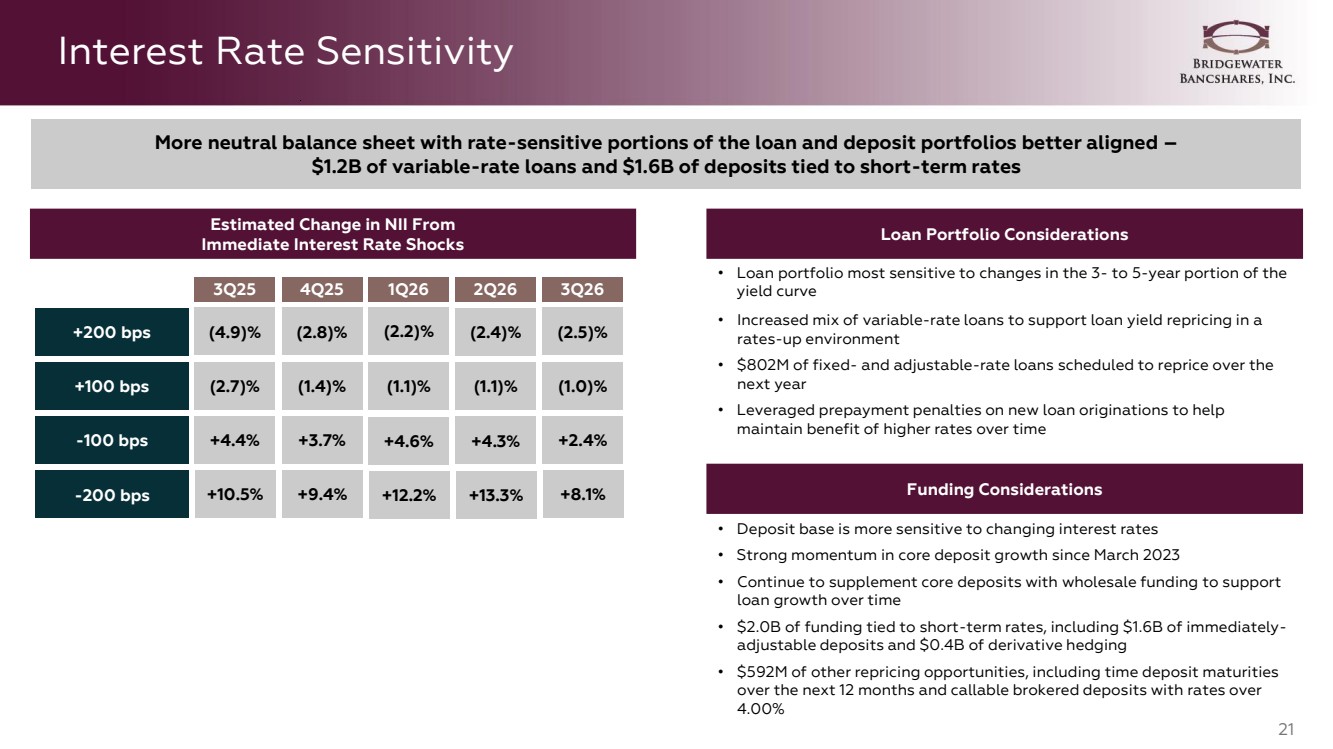
| 22 Managing Multifamily and Office-Related Risk 1 Excludes NOO medical office of $45 million Data as of September 30, 2026 Strong Multifamily Track Record Well-Managed CRE NOO Office Portfolio1 With Limited CBD Exposure Percent of Total Loans Average Loan Size 4.9% $2.2M CRE NOO Office by Geography Twin Cities Suburban 68% Minneapolis-St. Paul (CBD) 13% Minneapolis -St. Paul (non-CBD) 17% Out-of-State (non-CBD) 1% Greater MN 1% $220M • Majority of CRE NOO office exposure in the Twin Cities suburbs • Only 4 loans totaling $28M located in Minnesota CBDs • Only 4 loans totaling $2M outside of Minnesota (non-CBD), consisting of projects for existing local clients Loan Balances Average Loan Size NCOs (since 2005) $1.7B $2.9M $3M Multifamily Lending Focus in Stable Twin Cities Market • Bank of choice in the Twin Cities with expertise and differentiated service model • Greater tenant diversification compared to other asset classes • Positive market trends with reduced vacancy rates, strong absorption, and slower construction = favorable outlook for occupancy and rent growth • Market catalysts include relative affordability, steady population growth, low unemployment, strong wages, and shortage of single-family housing Weighted Average LTV 67% Weighted Average LTV 68% |
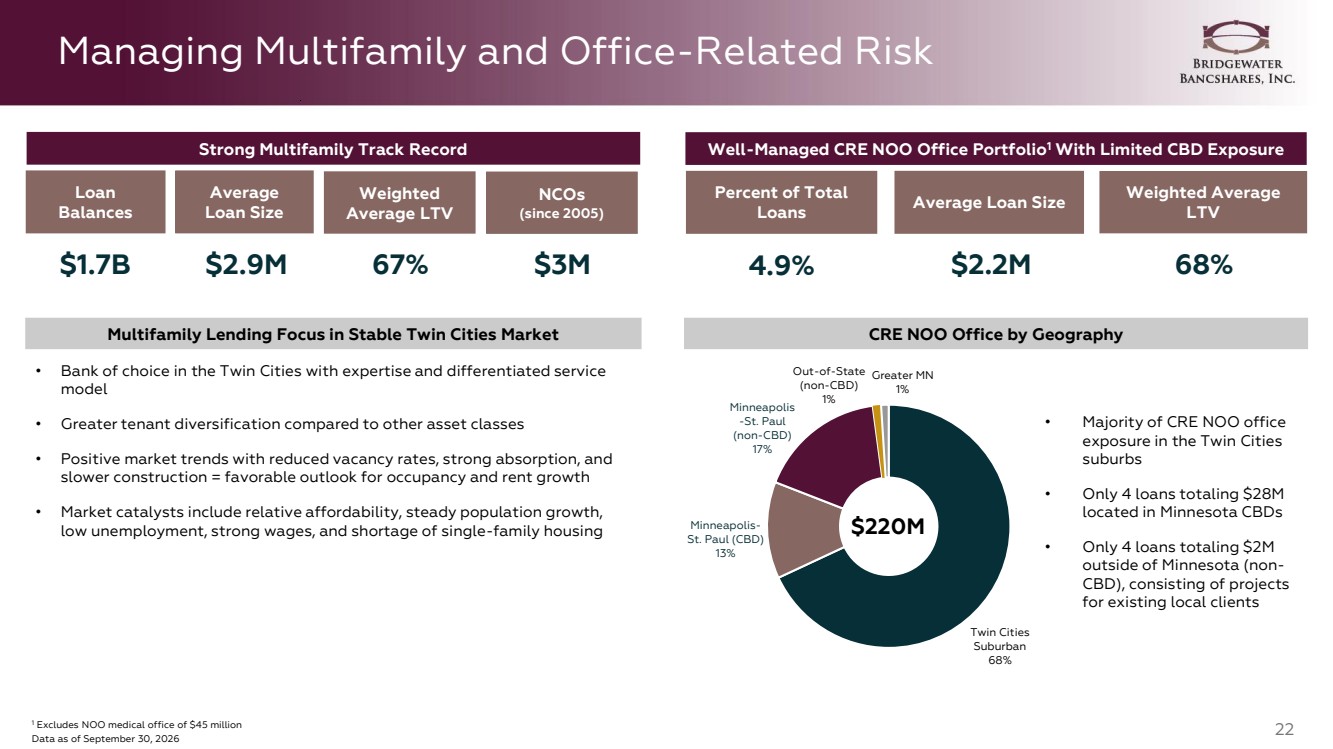
| 23 High Quality Securities Portfolio See Quarterly Peer Bank Financial Review AAA 35% AA 41% A 5% BBB 6% NR 13% Rating Mix Derivatives Portfolio Offsetting AOCI Impact (dollars in thousands) $(25,175) $(61,070) $14,278 $27,431 $(5,563) $(22,863) 3Q25 3Q26 MTM Securities MTM Derivatives Net Impact on AOCI1 • No held-to-maturity securities • Securities portfolio average duration of 7.4 years • Average securities portfolio yield of 5.08% 1 Includes the tax-effected impact of $2,244 in 3Q25 and $9,220 in 3Q26 31% 31% 40% 37% 35% 29% 31% 35% 42% 46% 13% 12% 17% 15% 14% 18% 19% 9% 7% 8% 6% 5% $826 $776 $567 $605 $599 3Q25 4Q25 1Q26 2Q26 3Q26 Mortgage-Backed Securities Municipal Bonds U.S. Treasuries Corporate Securities Securities Available for Sale Portfolio (dollars in millions) Other |
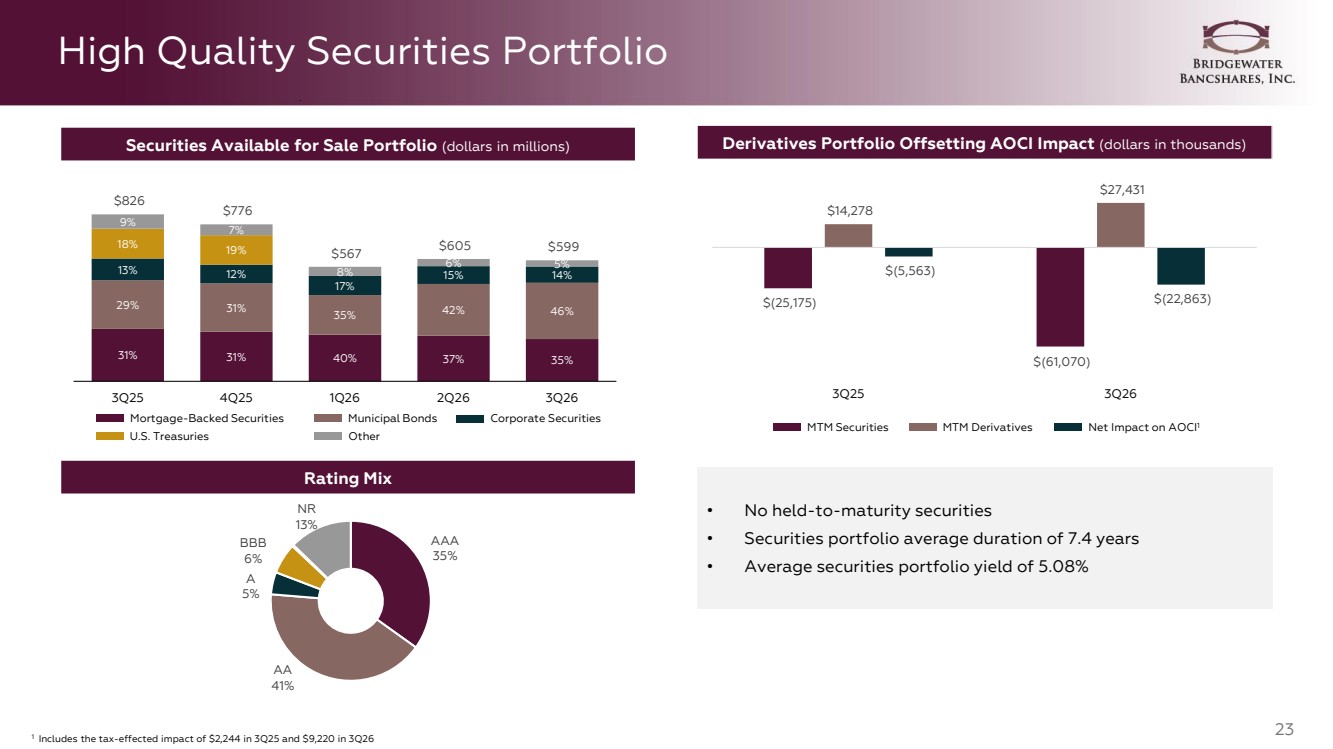
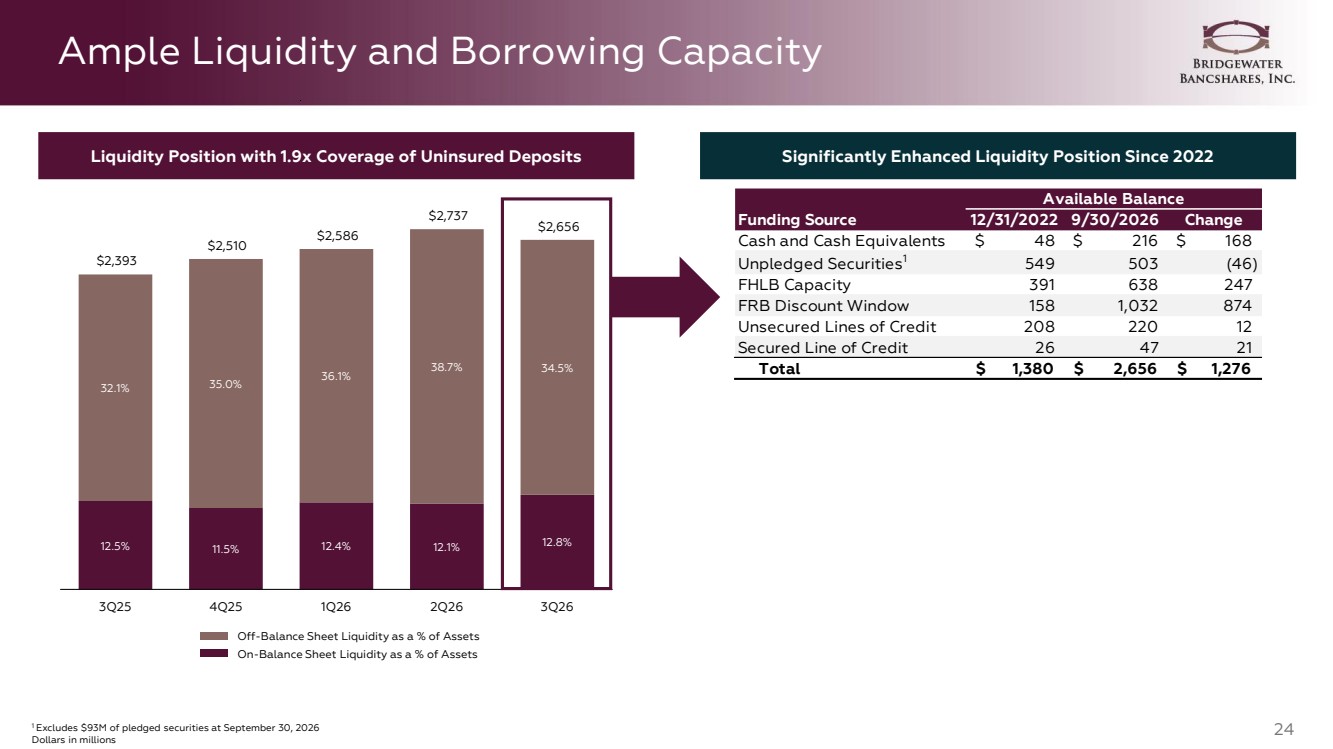
| 24 Ample Liquidity and Borrowing Capacity 12.5% 11.5% 12.4% 12.1% 12.8% 32.1% 35.0% 36.1% 38.7% 34.5% $2,393 $2,510 $2,586 $2,737 $2,656 3Q25 4Q25 1Q26 2Q26 3Q26 1 Excludes $93M of pledged securities at September 30, 2026 Dollars in millions Off-Balance Sheet Liquidity as a % of Assets On-Balance Sheet Liquidity as a % of Assets Liquidity Position with 1.9x Coverage of Uninsured Deposits Significantly Enhanced Liquidity Position Since 2022 Funding Source 12/31/2022 9/30/2026 Change Cash and Cash Equivalents $ 4 8 $ 216 $ 168 Unpledged Securities1 549 503 (46) FHLB Capacity 391 638 247 FRB Discount Window 158 1,032 874 Unsecured Lines of Credit 208 220 12 Secured Line of Credit 26 4 7 21 Total $ 1,380 $ 2,656 $ 1,276 Available Balance |
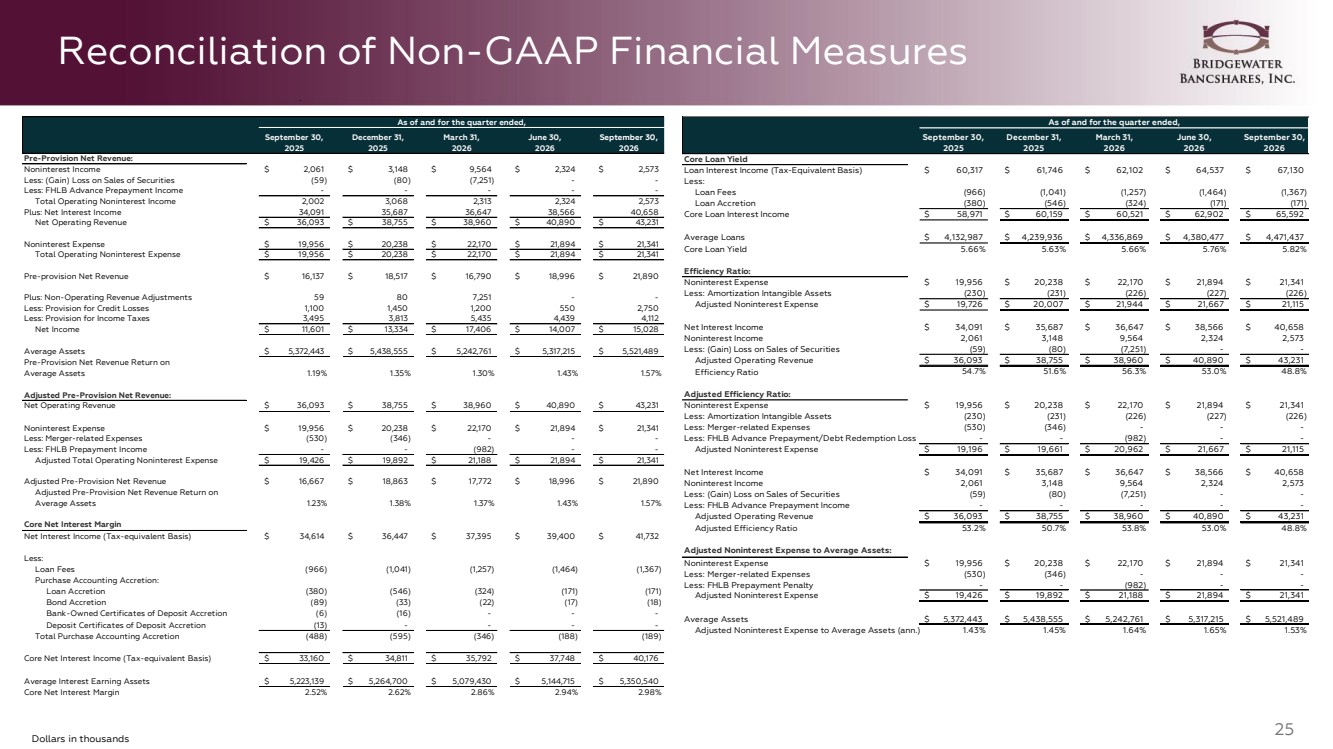
| 25 Reconciliation of Non-GAAP Financial Measures Dollars in thousands September 30, 2025 December 31, 2025 March 31, 2026 June 30, 2026 September 30, 2026 Core Loan Yield Loan Interest Income (Tax-Equivalent Basis) $ 60,317 $ 61,746 $ 62,102 $ 64,537 $ 67,130 Less: Loan Fees (966) (1,041) (1,257) (1,464) (1,367) Loan Accretion (380) (546) (324) (171) (171) Core Loan Interest Income $ 58,971 $ 60,159 $ 60,521 $ 62,902 $ 65,592 Average Loans $ 4,132,987 $ 4,239,936 $ 4,336,869 $ 4,380,477 $ 4,471,437 Core Loan Yield 5.66% 5.63% 5.66% 5.76% 5.82% Efficiency Ratio: Noninterest Expense $ 19,956 $ 20,238 $ 22,170 $ 21,894 $ 21,341 Less: Amortization Intangible Assets (230) (231) (226) (227) (226) Adjusted Noninterest Expense $ 19,726 $ 20,007 $ 21,944 $ 21,667 $ 21,115 Net Interest Income $ 34,091 $ 35,687 $ 36,647 $ 38,566 $ 40,658 Noninterest Income 2,061 3,148 9,564 2,324 2,573 Less: (Gain) Loss on Sales of Securities (59) (80) (7,251) - - Adjusted Operating Revenue $ 36,093 $ 38,755 $ 38,960 $ 40,890 $ 43,231 Efficiency Ratio 54.7% 51.6% 56.3% 53.0% 48.8% Adjusted Efficiency Ratio: Noninterest Expense $ 19,956 $ 20,238 $ 22,170 $ 21,894 $ 21,341 Less: Amortization Intangible Assets (230) (231) (226) (227) (226) Less: Merger-related Expenses (530) (346) - - - Less: FHLB Advance Prepayment/Debt Redemption Loss - - (982) - - Adjusted Noninterest Expense $ 19,196 $ 19,661 $ 20,962 $ 21,667 $ 21,115 Net Interest Income $ 34,091 $ 35,687 $ 36,647 $ 38,566 $ 40,658 Noninterest Income 2,061 3,148 9,564 2,324 2,573 Less: (Gain) Loss on Sales of Securities (59) (80) (7,251) - - Less: FHLB Advance Prepayment Income - - - - - Adjusted Operating Revenue $ 36,093 $ 38,755 $ 38,960 $ 40,890 $ 43,231 Adjusted Efficiency Ratio 53.2% 50.7% 53.8% 53.0% 48.8% Adjusted Noninterest Expense to Average Assets: Noninterest Expense $ 19,956 $ 20,238 $ 22,170 $ 21,894 $ 21,341 Less: Merger-related Expenses (530) (346) - - - Less: FHLB Prepayment Penalty - - (982) - - Adjusted Noninterest Expense $ 19,426 $ 19,892 $ 21,188 $ 21,894 $ 21,341 Average Assets $ 5,372,443 $ 5,438,555 $ 5,242,761 $ 5,317,215 $ 5,521,489 Adjusted Noninterest Expense to Average Assets (ann.) 1.43% 1.45% 1.64% 1.65% 1.53% As of and for the quarter ended, September 30, 2025 December 31, 2025 March 31, 2026 June 30, 2026 September 30, 2026 Pre-Provision Net Revenue: Noninterest Income $ 2,061 $ 3,148 $ 9,564 $ 2,324 $ 2,573 Less: (Gain) Loss on Sales of Securities (59) (80) (7,251) - - Less: FHLB Advance Prepayment Income - - - - - Total Operating Noninterest Income 2,002 3,068 2,313 2,324 2,573 Plus: Net Interest Income 34,091 35,687 36,647 38,566 40,658 Net Operating Revenue $ 36,093 $ 38,755 $ 38,960 $ 40,890 $ 43,231 Noninterest Expense $ 19,956 $ 20,238 $ 22,170 $ 21,894 $ 21,341 Total Operating Noninterest Expense $ 19,956 $ 20,238 $ 22,170 $ 21,894 $ 21,341 Pre-provision Net Revenue $ 16,137 $ 18,517 $ 16,790 $ 18,996 $ 21,890 Plus: Non-Operating Revenue Adjustments 59 8 0 7,251 - - Less: Provision for Credit Losses 1,100 1,450 1,200 550 2,750 Less: Provision for Income Taxes 3,495 3,813 5,435 4,439 4,112 Net Income $ 11,601 $ 13,334 $ 17,406 $ 14,007 $ 15,028 Average Assets $ 5,372,443 $ 5,438,555 $ 5,242,761 $ 5,317,215 $ 5,521,489 Pre-Provision Net Revenue Return on Average Assets 1.19% 1.35% 1.30% 1.43% 1.57% Adjusted Pre-Provision Net Revenue: Net Operating Revenue $ 36,093 $ 38,755 $ 38,960 $ 40,890 $ 43,231 Noninterest Expense $ 19,956 $ 20,238 $ 22,170 $ 21,894 $ 21,341 Less: Merger-related Expenses (530) (346) - - - Less: FHLB Prepayment Income - - (982) - - Adjusted Total Operating Noninterest Expense $ 19,426 $ 19,892 $ 21,188 $ 21,894 $ 21,341 Adjusted Pre-Provision Net Revenue $ 16,667 $ 18,863 $ 17,772 $ 18,996 $ 21,890 Adjusted Pre-Provision Net Revenue Return on Average Assets 1.23% 1.38% 1.37% 1.43% 1.57% Core Net Interest Margin Net Interest Income (Tax-equivalent Basis) $ 34,614 $ 36,447 $ 37,395 $ 39,400 $ 41,732 Less: Loan Fees (966) (1,041) (1,257) (1,464) (1,367) Purchase Accounting Accretion: Loan Accretion (380) (546) (324) (171) (171) Bond Accretion (89) (33) (22) (17) (18) Bank-Owned Certificates of Deposit Accretion (6) (16) - - - Deposit Certificates of Deposit Accretion (13) - - - - Total Purchase Accounting Accretion (488) (595) (346) (188) (189) Core Net Interest Income (Tax-equivalent Basis) $ 33,160 $ 34,811 $ 35,792 $ 37,748 $ 40,176 Average Interest Earning Assets $ 5,223,139 $ 5,264,700 $ 5,079,430 $ 5,144,715 $ 5,350,540 Core Net Interest Margin 2.52% 2.62% 2.86% 2.94% 2.98% As of and for the quarter ended, |
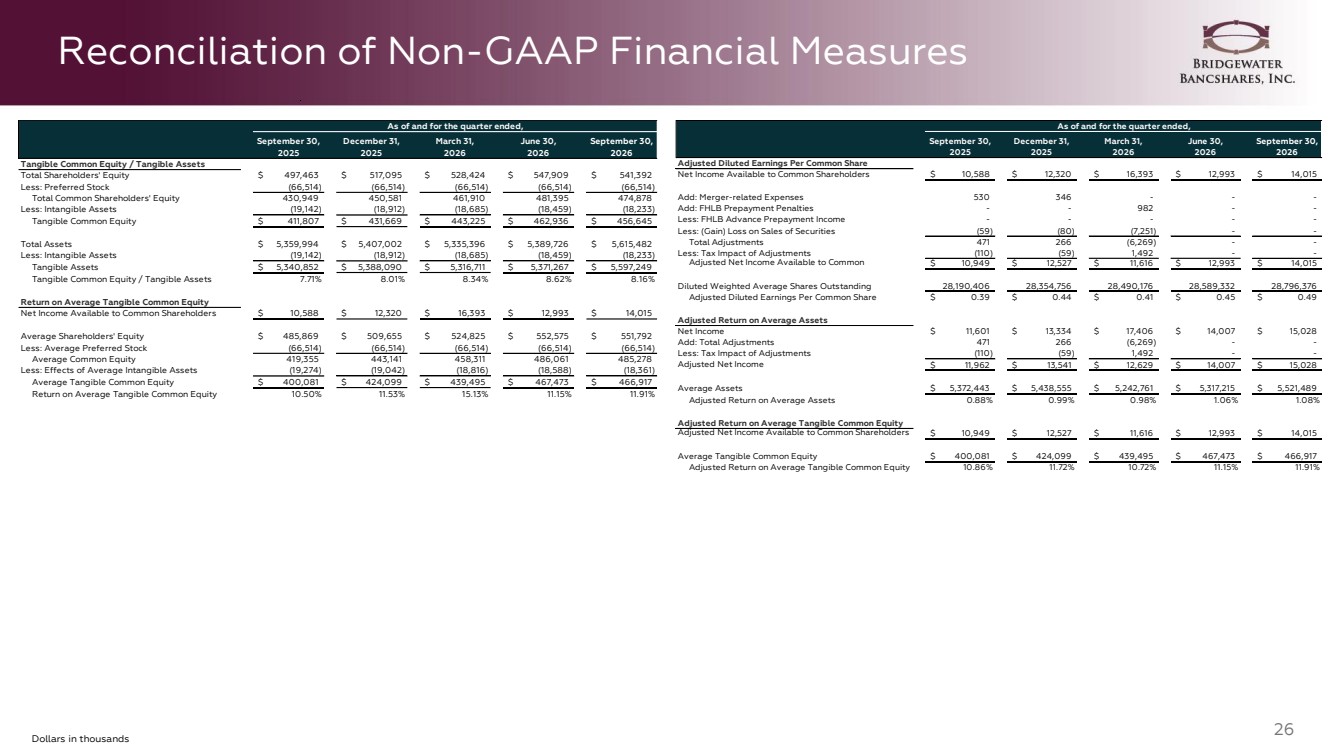
| 26 Reconciliation of Non-GAAP Financial Measures Dollars in thousands September 30, 2025 December 31, 2025 March 31, 2026 June 30, 2026 September 30, 2026 Tangible Common Equity / Tangible Assets Total Shareholders' Equity $ 497,463 $ 517,095 $ 528,424 $ 547,909 $ 541,392 Less: Preferred Stock (66,514) (66,514) (66,514) (66,514) (66,514) Total Common Shareholders' Equity 430,949 450,581 461,910 481,395 474,878 Less: Intangible Assets (19,142) (18,912) (18,685) (18,459) (18,233) Tangible Common Equity $ 411,807 $ 431,669 $ 443,225 $ 462,936 $ 456,645 Total Assets $ 5,359,994 $ 5,407,002 $ 5,335,396 $ 5,389,726 $ 5,615,482 Less: Intangible Assets (19,142) (18,912) (18,685) (18,459) (18,233) Tangible Assets $ 5,340,852 $ 5,388,090 $ 5,316,711 $ 5,371,267 $ 5,597,249 Tangible Common Equity / Tangible Assets 7.71% 8.01% 8.34% 8.62% 8.16% Return on Average Tangible Common Equity Net Income Available to Common Shareholders $ 10,588 $ 12,320 $ 16,393 $ 12,993 $ 14,015 Average Shareholders' Equity $ 485,869 $ 509,655 $ 524,825 $ 552,575 $ 551,792 Less: Average Preferred Stock (66,514) (66,514) (66,514) (66,514) (66,514) Average Common Equity 419,355 443,141 458,311 486,061 485,278 Less: Effects of Average Intangible Assets (19,274) (19,042) (18,816) (18,588) (18,361) Average Tangible Common Equity $ 400,081 $ 424,099 $ 439,495 $ 467,473 $ 466,917 Return on Average Tangible Common Equity 10.50% 11.53% 15.13% 11.15% 11.91% As of and for the quarter ended, September 30, 2025 December 31, 2025 March 31, 2026 June 30, 2026 September 30, 2026 Adjusted Diluted Earnings Per Common Share Net Income Available to Common Shareholders $ 10,588 $ 12,320 $ 16,393 $ 12,993 $ 14,015 Add: Merger-related Expenses 530 346 - - - Add: FHLB Prepayment Penalties - - 982 - - Less: FHLB Advance Prepayment Income - - - - - Less: (Gain) Loss on Sales of Securities (59) (80) (7,251) - - Total Adjustments 471 266 (6,269) - - Less: Tax Impact of Adjustments (110) (59) 1,492 - - Adjusted Net Income Available to Common $ 10,949 $ 12,527 $ 11,616 $ 12,993 $ 14,015 Diluted Weighted Average Shares Outstanding 28,190,406 28,354,756 28,490,176 28,589,332 28,796,376 Adjusted Diluted Earnings Per Common Share $ 0.39 $ 0.44 $ 0.41 $ 0.45 $ 0.49 Adjusted Return on Average Assets Net Income $ 11,601 $ 13,334 $ 17,406 $ 14,007 $ 15,028 Add: Total Adjustments 471 266 (6,269) - - Less: Tax Impact of Adjustments (110) (59) 1,492 - - Adjusted Net Income $ 11,962 $ 13,541 $ 12,629 $ 14,007 $ 15,028 Average Assets $ 5,372,443 $ 5,438,555 $ 5,242,761 $ 5,317,215 $ 5,521,489 Adjusted Return on Average Assets 0.88% 0.99% 0.98% 1.06% 1.08% Adjusted Return on Average Tangible Common Equity Adjusted Net Income Available to Common Shareholders $ 10,949 $ 12,527 $ 11,616 $ 12,993 $ 14,015 Average Tangible Common Equity $ 400,081 $ 424,099 $ 439,495 $ 467,473 $ 466,917 Adjusted Return on Average Tangible Common Equity 10.86% 11.72% 10.72% 11.15% 11.91% As of and for the quarter ended, |
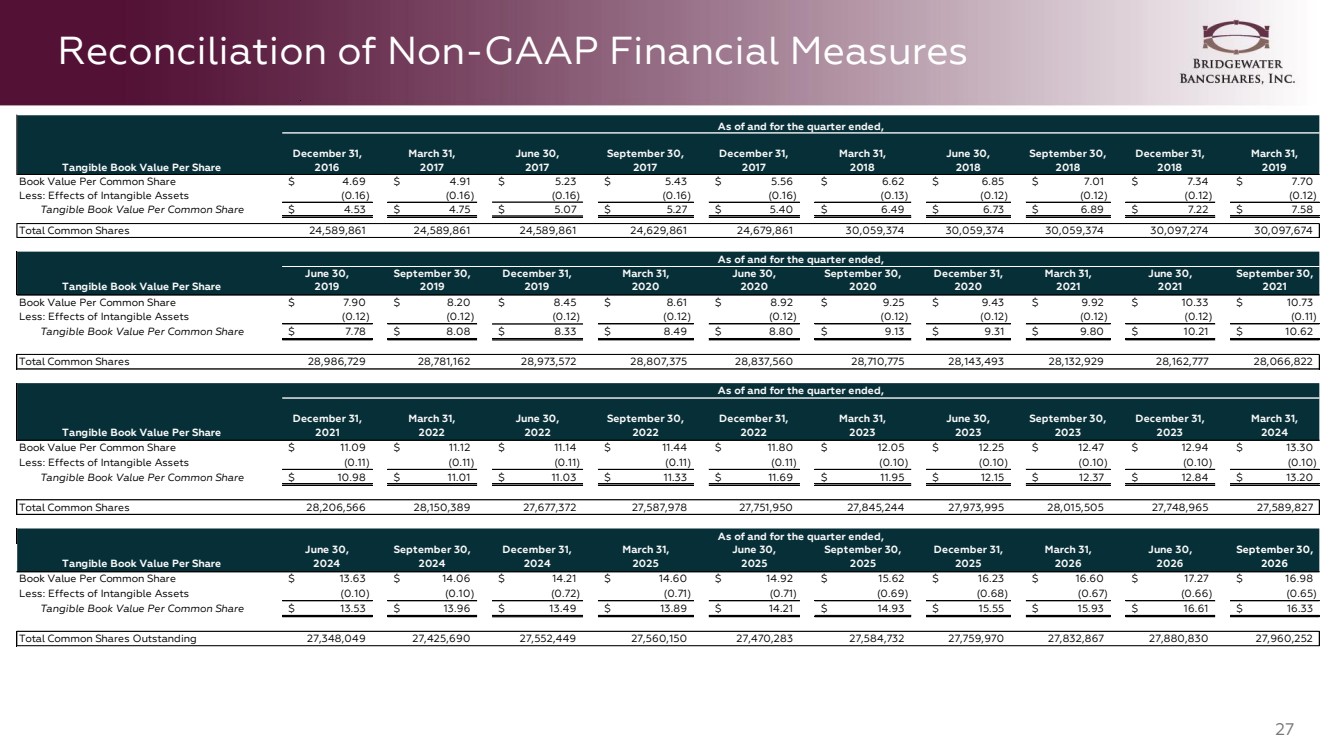
| 27 Reconciliation of Non-GAAP Financial Measures Tangible Book Value Per Share December 31, 2016 March 31, 2017 June 30, 2017 September 30, 2017 December 31, 2017 March 31, 2018 June 30, 2018 September 30, 2018 December 31, 2018 March 31, 2019 Book Value Per Common Share $ 4.69 $ 4.91 $ 5.23 $ 5.43 $ 5.56 $ 6.62 $ 6.85 $ 7.01 $ 7.34 $ 7.70 Less: Effects of Intangible Assets (0.16) (0.16) (0.16) (0.16) (0.16) (0.13) (0.12) (0.12) (0.12) (0.12) Tangible Book Value Per Common Share $ 4.53 $ 4.75 $ 5.07 $ 5.27 $ 5.40 $ 6.49 $ 6.73 $ 6.89 $ 7.22 $ 7.58 Total Common Shares 24,589,861 24,589,861 24,589,861 24,629,861 24,679,861 30,059,374 30,059,374 30,059,374 30,097,274 30,097,674 Tangible Book Value Per Share June 30, 2019 September 30, 2019 December 31, 2019 March 31, 2020 June 30, 2020 September 30, 2020 December 31, 2020 March 31, 2021 June 30, 2021 September 30, 2021 Book Value Per Common Share $ 7.90 $ 8.20 $ 8.45 $ 8.61 $ 8.92 $ 9.25 $ 9.43 $ 9.92 $ 10.33 $ 10.73 Less: Effects of Intangible Assets (0.12) (0.12) (0.12) (0.12) (0.12) (0.12) (0.12) (0.12) (0.12) (0.11) Tangible Book Value Per Common Share $ 7.78 $ 8.08 $ 8.33 $ 8.49 $ 8.80 $ 9.13 $ 9.31 $ 9.80 $ 10.21 $ 10.62 Total Common Shares 28,986,729 28,781,162 28,973,572 28,807,375 28,837,560 28,710,775 28,143,493 28,132,929 28,162,777 28,066,822 Tangible Book Value Per Share December 31, 2021 March 31, 2022 June 30, 2022 September 30, 2022 December 31, 2022 March 31, 2023 June 30, 2023 September 30, 2023 December 31, 2023 March 31, 2024 Book Value Per Common Share $ 11.09 $ 11.12 $ 11.14 $ 11.44 $ 11.80 $ 12.05 $ 12.25 $ 12.47 $ 12.94 $ 13.30 Less: Effects of Intangible Assets (0.11) (0.11) (0.11) (0.11) (0.11) (0.10) (0.10) (0.10) (0.10) (0.10) Tangible Book Value Per Common Share $ 10.98 $ 11.01 $ 11.03 $ 11.33 $ 11.69 $ 11.95 $ 12.15 $ 12.37 $ 12.84 $ 13.20 Total Common Shares 28,206,566 28,150,389 27,677,372 27,587,978 27,751,950 27,845,244 27,973,995 28,015,505 27,748,965 27,589,827 Tangible Book Value Per Share June 30, 2024 September 30, 2024 December 31, 2024 March 31, 2025 June 30, 2025 September 30, 2025 December 31, 2025 March 31, 2026 June 30, 2026 September 30, 2026 Book Value Per Common Share $ 13.63 $ 14.06 $ 14.21 $ 14.60 $ 14.92 $ 15.62 $ 16.23 $ 16.60 $ 17.27 $ 16.98 Less: Effects of Intangible Assets (0.10) (0.10) (0.72) (0.71) (0.71) (0.69) (0.68) (0.67) (0.66) (0.65) Tangible Book Value Per Common Share $ 13.53 $ 13.96 $ 13.49 $ 13.89 $ 14.21 $ 14.93 $ 15.55 $ 15.93 $ 16.61 $ 16.33 Total Common Shares Outstanding 27,348,049 27,425,690 27,552,449 27,560,150 27,470,283 27,584,732 27,759,970 27,832,867 27,880,830 27,960,252 As of and for the quarter ended, As of and for the quarter ended, As of and for the quarter ended, As of and for the quarter ended, |