Earnings & Financial Performance .2 Q3 2026 Financial Results October 21, 2026
Forward-Looking Statements 2 This presentation contains forward-looking statements within the meaning of the Private Securities Litigation Reform Act of 1995 that reflect the current views of BankUnited, Inc. (“BankUnited”, “BKU”, or the “Company”) with respect to, among other things, future events and financial performance, dividend payments and stock repurchases. The Company generally identifies forward-looking statements by terminology such as “outlook,” “believes,” “expects,” “potential,” “continues,” “may,” “will,” “could,” “should,” “seeks,” “approximately,” “predicts,” “intends,” “plans,” “estimates,” “anticipates,” "forecasts" or the negative version of those words or other comparable words. Any forward-looking statements contained in this presentation are based on the historical performance of the Company and its subsidiaries or on the Company’s current plans, estimates and expectations. The inclusion of this forward-looking information should not be regarded as a representation by the Company that the future plans, estimates or expectations contemplated by the Company will be achieved. Such forward-looking statements are subject to various risks and uncertainties and assumptions, including (without limitation) those relating to the Company’s operations, financial results, financial condition, business prospects, growth strategy and liquidity, including as impacted by external circumstances outside the Company's direct control, such as (1) an inability to successfully execute our core business strategy; (2) adverse events or conditions impacting the financial services industry, (3) our ability to access capital, including the impact of our credit rating; (4) credit risk inherent in the business of making loans and embedded in our securities portfolio, including inadequate allowance for credit losses and real estate market conditions and valuations; (5) interest rate risk, (6) liquidity risks, (7) risks related to the regulation of our industry, (8) operational risk, including dependence on information technology and third party service providers and the risk of systems failures, interruptions or breaches of security or inability to keep pace with technological change; (9) reputational risk, (10) the impact of conditions in the financial markets and economic conditions generally; (11) ineffective risk management or internal controls; and (12) the selection and application of accounting policies and methods and related assumptions and estimates. If one or more of these or other risks or uncertainties materialize, or if the Company’s underlying assumptions prove to be incorrect, the Company’s actual results may vary materially from those indicated in these statements. These factors should not be construed as exhaustive. The Company does not undertake any obligation to publicly update or review any forward-looking statement, whether as a result of new information, future developments or otherwise. A number of important factors could cause actual results to differ materially from those indicated by the forward-looking statements. Information on these factors can be found in the Company’s Annual Report on Form 10-K for the year ended December 31, 2025 and any subsequent Quarterly Report on Form 10-Q or Current Report on Form 8-K, which are available at the SEC’s website (www.sec.gov).
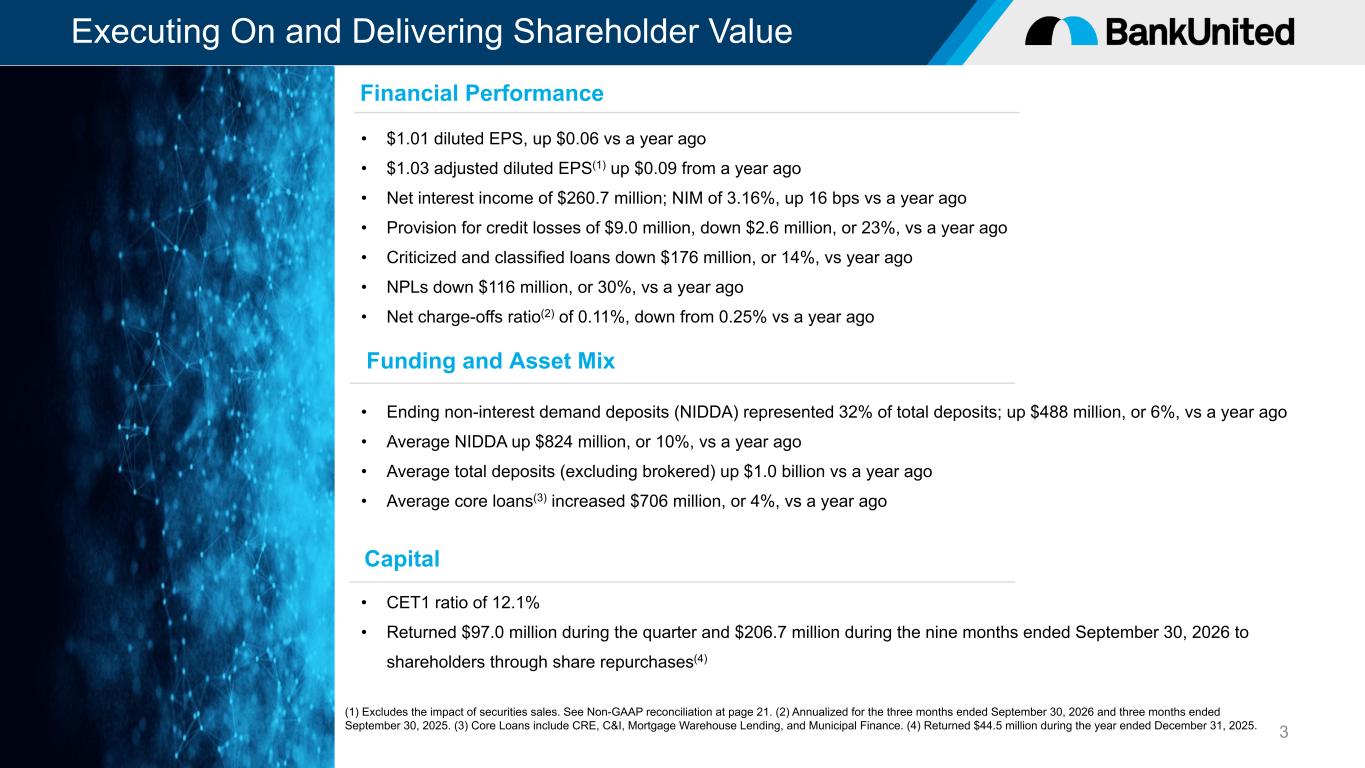
Executing On and Delivering Shareholder Value 3 • $1.01 diluted EPS, up $0.06 vs a year ago • $1.03 adjusted diluted EPS(1) up $0.09 from a year ago • Net interest income of $260.7 million; NIM of 3.16%, up 16 bps vs a year ago • Provision for credit losses of $9.0 million, down $2.6 million, or 23%, vs a year ago • Criticized and classified loans down $176 million, or 14%, vs year ago • NPLs down $116 million, or 30%, vs a year ago • Net charge-offs ratio(2) of 0.11%, down from 0.25% vs a year ago • Ending non-interest demand deposits (NIDDA) represented 32% of total deposits; up $488 million, or 6%, vs a year ago • Average NIDDA up $824 million, or 10%, vs a year ago • Average total deposits (excluding brokered) up $1.0 billion vs a year ago • Average core loans(3) increased $706 million, or 4%, vs a year ago Financial Performance Funding and Asset Mix (1) Excludes the impact of securities sales. See Non-GAAP reconciliation at page 21. (2) Annualized for the three months ended September 30, 2026 and three months ended September 30, 2025. (3) Core Loans include CRE, C&I, Mortgage Warehouse Lending, and Municipal Finance. (4) Returned $44.5 million during the year ended December 31, 2025. Capital • CET1 ratio of 12.1% • Returned $97.0 million during the quarter and $206.7 million during the nine months ended September 30, 2026 to shareholders through share repurchases(4)
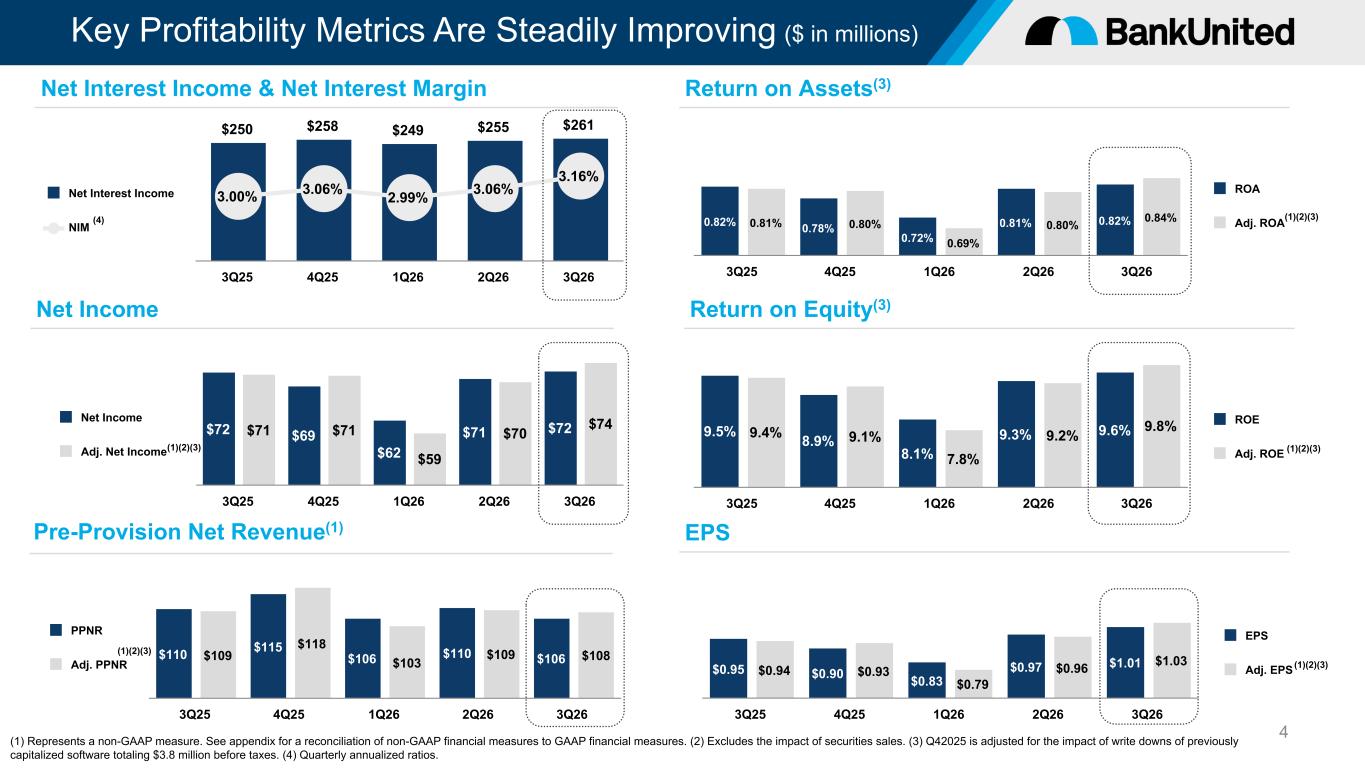
Key Profitability Metrics Are Steadily Improving ($ in millions) 4 $72 $69 $62 $71 $72$71 $71 $59 $70 $74Net Income Adj. Net Income 3Q25 4Q25 1Q26 2Q26 3Q26 9.5% 8.9% 8.1% 9.3% 9.6%9.4% 9.1% 7.8% 9.2% 9.8% ROE Adj. ROE 3Q25 4Q25 1Q26 2Q26 3Q26 $250 $258 $249 $255 $261 3.00% 3.06% 2.99% 3.06% 3.16% Net Interest Income NIM 3Q25 4Q25 1Q26 2Q26 3Q26 0.82% 0.78% 0.72% 0.81% 0.82%0.81% 0.80% 0.69% 0.80% 0.84% ROA Adj. ROA 3Q25 4Q25 1Q26 2Q26 3Q26 Net Interest Income & Net Interest Margin Net Income Return on Assets(3) Return on Equity(3) $110 $115 $106 $110 $106$109 $118 $103 $109 $108 PPNR Adj. PPNR 3Q25 4Q25 1Q26 2Q26 3Q26 Pre-Provision Net Revenue(1) $0.95 $0.90 $0.83 $0.97 $1.01$0.94 $0.93 $0.79 $0.96 $1.03 EPS Adj. EPS 3Q25 4Q25 1Q26 2Q26 3Q26 EPS (1) Represents a non-GAAP measure. See appendix for a reconciliation of non-GAAP financial measures to GAAP financial measures. (2) Excludes the impact of securities sales. (3) Q42025 is adjusted for the impact of write downs of previously capitalized software totaling $3.8 million before taxes. (4) Quarterly annualized ratios. (1)(2)(3) (1)(2)(3) (1)(2)(3) (1)(2)(3) (4) (1)(2)(3)
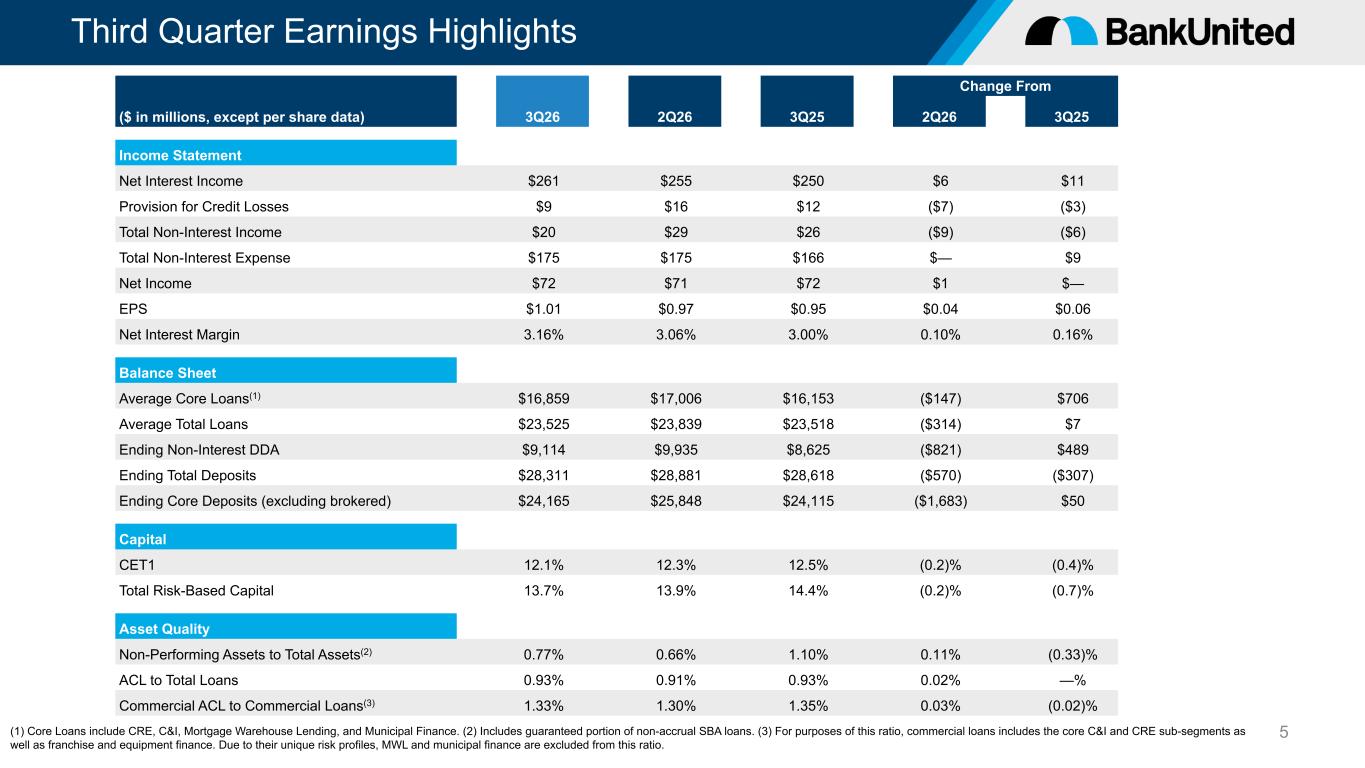
Third Quarter Earnings Highlights 5 Change From ($ in millions, except per share data) 3Q26 2Q26 3Q25 2Q26 3Q25 Income Statement Net Interest Income $261 $255 $250 $6 $11 Provision for Credit Losses $9 $16 $12 ($7) ($3) Total Non-Interest Income $20 $29 $26 ($9) ($6) Total Non-Interest Expense $175 $175 $166 $— $9 Net Income $72 $71 $72 $1 $— EPS $1.01 $0.97 $0.95 $0.04 $0.06 Net Interest Margin 3.16% 3.06% 3.00% 0.10% 0.16% Balance Sheet Average Core Loans(1) $16,859 $17,006 $16,153 ($147) $706 Average Total Loans $23,525 $23,839 $23,518 ($314) $7 Ending Non-Interest DDA $9,114 $9,935 $8,625 ($821) $489 Ending Total Deposits $28,311 $28,881 $28,618 ($570) ($307) Ending Core Deposits (excluding brokered) $24,165 $25,848 $24,115 ($1,683) $50 Capital CET1 12.1% 12.3% 12.5% (0.2)% (0.4)% Total Risk-Based Capital 13.7% 13.9% 14.4% (0.2)% (0.7)% Asset Quality Non-Performing Assets to Total Assets(2) 0.77% 0.66% 1.10% 0.11% (0.33)% ACL to Total Loans 0.93% 0.91% 0.93% 0.02% —% Commercial ACL to Commercial Loans(3) 1.33% 1.30% 1.35% 0.03% (0.02)% (1) Core Loans include CRE, C&I, Mortgage Warehouse Lending, and Municipal Finance. (2) Includes guaranteed portion of non-accrual SBA loans. (3) For purposes of this ratio, commercial loans includes the core C&I and CRE sub-segments as well as franchise and equipment finance. Due to their unique risk profiles, MWL and municipal finance are excluded from this ratio.
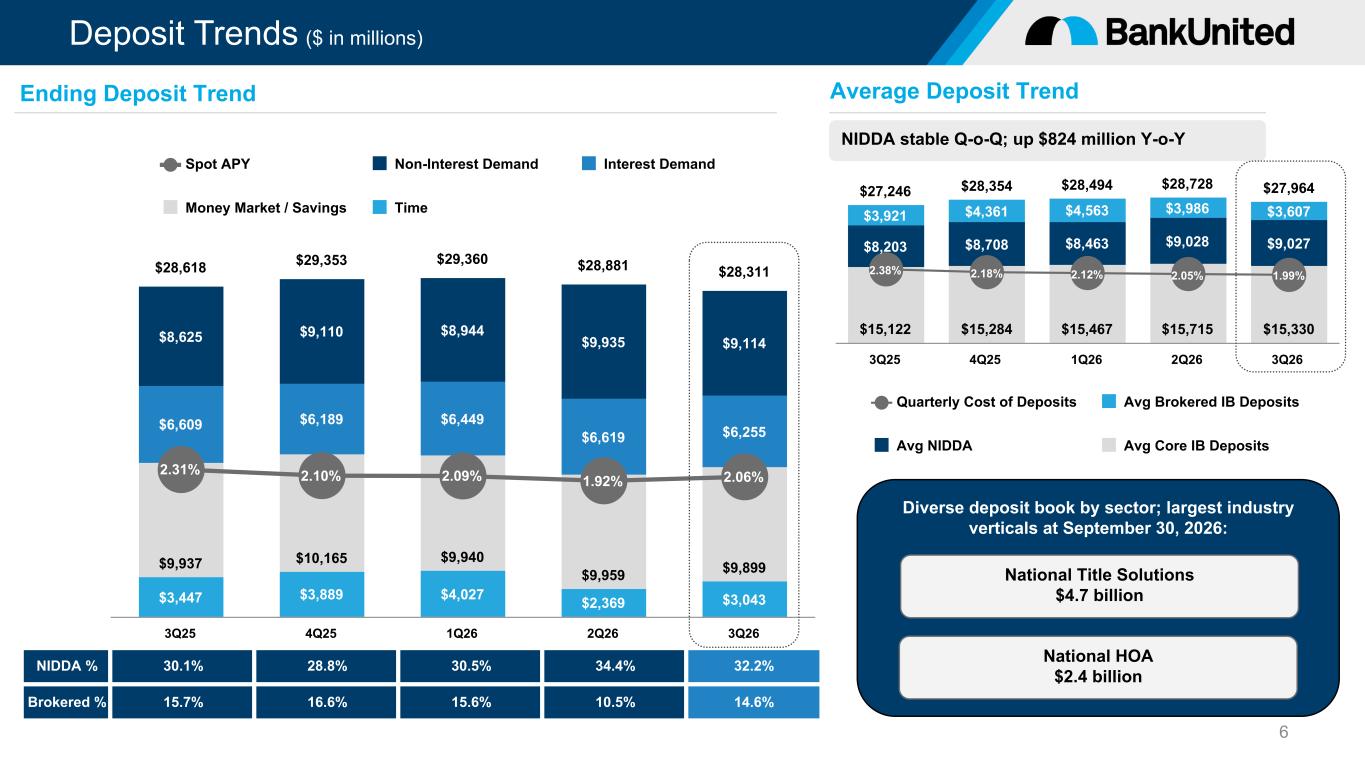
Deposit Trends ($ in millions) $3,447 $3,889 $4,027 $2,369 $3,043 $9,937 $10,165 $9,940 $9,959 $9,899 $6,609 $6,189 $6,449 $6,619 $6,255 $8,625 $9,110 $8,944 $9,935 $9,114 $28,618 $29,353 $29,360 $28,881 $28,311 2.31% 2.10% 2.09% 1.92% 2.06% Spot APY Non-Interest Demand Interest Demand Money Market / Savings Time 3Q25 4Q25 1Q26 2Q26 3Q26 6 NIDDA % 30.1% 28.8% 30.5% 34.4% 32.2% Brokered % 15.7% 16.6% 15.6% 10.5% 14.6% Diverse deposit book by sector; largest industry verticals at September 30, 2026: Ending Deposit Trend Average Deposit Trend NIDDA stable Q-o-Q; up $824 million Y-o-Y $27,246 $28,354 $28,494 $28,728 $27,964 $15,122 $15,284 $15,467 $15,715 $15,330 $8,203 $8,708 $8,463 $9,028 $9,027 $3,921 $4,361 $4,563 $3,986 $3,607 2.38% 2.18% 2.12% 2.05% 1.99% Quarterly Cost of Deposits Avg Brokered IB Deposits Avg NIDDA Avg Core IB Deposits 3Q25 4Q25 1Q26 2Q26 3Q26 National Title Solutions $4.7 billion National HOA $2.4 billion
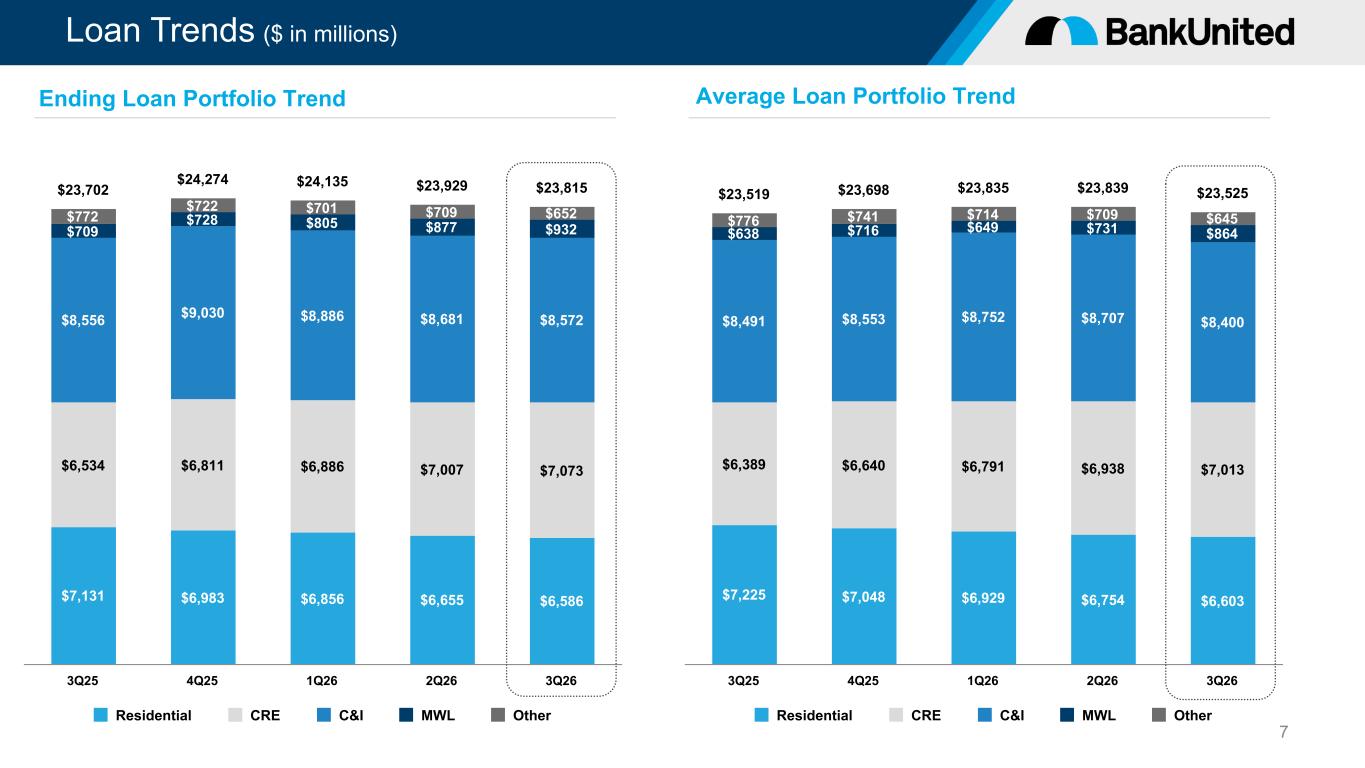
Loan Trends ($ in millions) $7,131 $6,983 $6,856 $6,655 $6,586 $6,534 $6,811 $6,886 $7,007 $7,073 $8,556 $9,030 $8,886 $8,681 $8,572 $709 $728 $805 $877 $932 $772 $722 $701 $709 $652 $23,702 $24,274 $24,135 $23,929 $23,815 Residential CRE C&I MWL Other 3Q25 4Q25 1Q26 2Q26 3Q26 7 Ending Loan Portfolio Trend Average Loan Portfolio Trend $7,225 $7,048 $6,929 $6,754 $6,603 $6,389 $6,640 $6,791 $6,938 $7,013 $8,491 $8,553 $8,752 $8,707 $8,400 $638 $716 $649 $731 $864 $776 $741 $714 $709 $645 $23,519 $23,698 $23,835 $23,839 $23,525 Residential CRE C&I MWL Other 3Q25 4Q25 1Q26 2Q26 3Q26
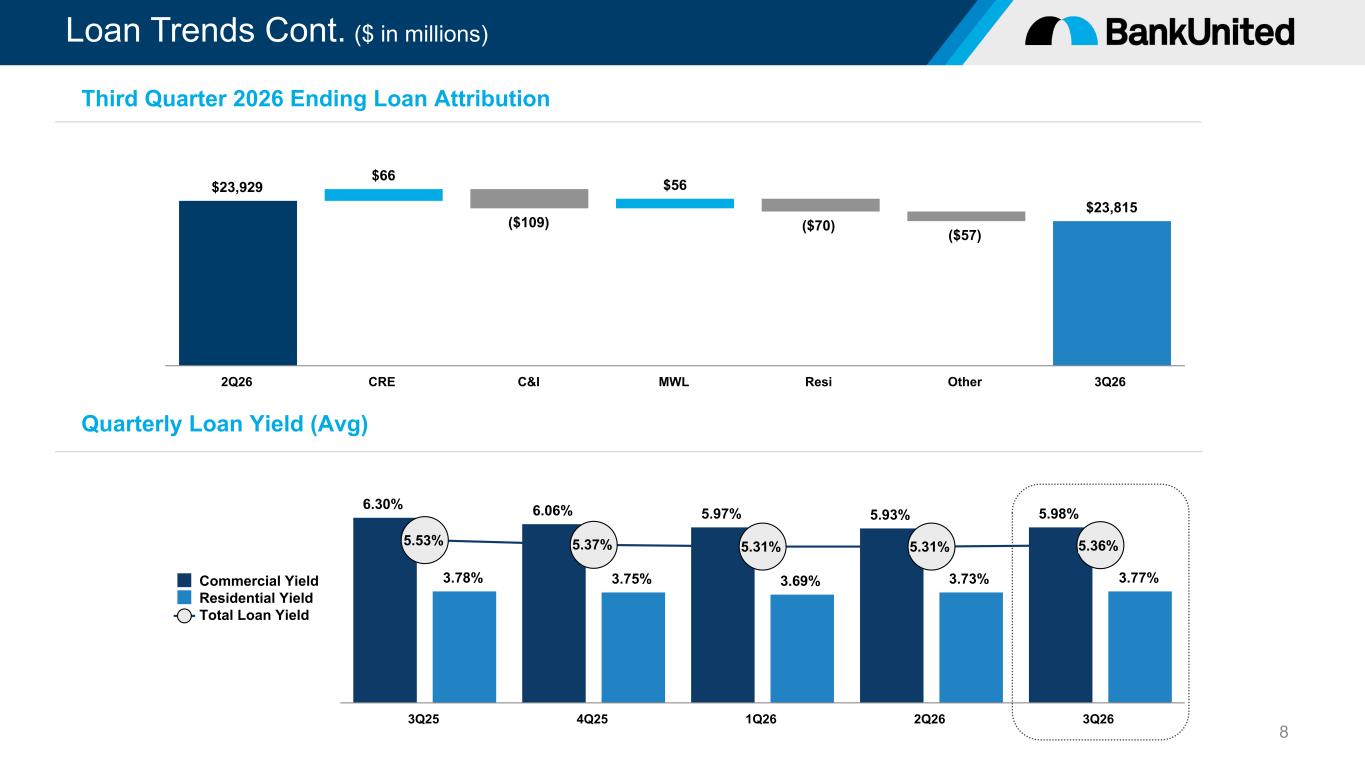
Loan Trends Cont. ($ in millions) 8 $23,929 $66 ($109) $56 ($70) ($57) $23,815 2Q26 CRE C&I MWL Resi Other 3Q26 Third Quarter 2026 Ending Loan Attribution 6.30% 6.06% 5.97% 5.93% 5.98% 3.78% 3.75% 3.69% 3.73% 3.77% 5.53% 5.37% 5.31% 5.31% 5.36% Commercial Yield Residential Yield Total Loan Yield 3Q25 4Q25 1Q26 2Q26 3Q26 Quarterly Loan Yield (Avg)
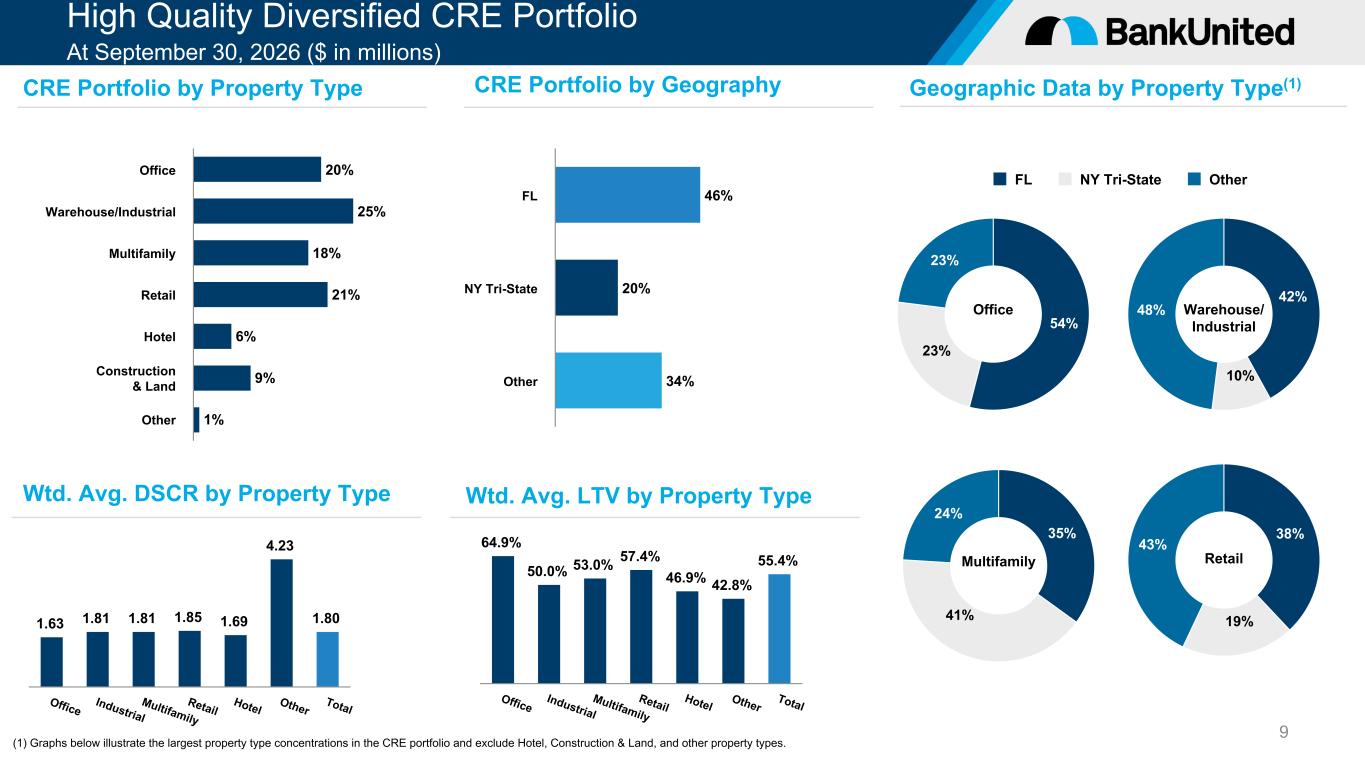
High Quality Diversified CRE Portfolio At September 30, 2026 ($ in millions) 9 20% 25% 18% 21% 6% 9% 1% Office Warehouse/Industrial Multifamily Retail Hotel Construction & Land Other 1.63 1.81 1.81 1.85 1.69 4.23 1.80 Office Industrial Multifamily Retail Hotel Other Total 64.9% 50.0% 53.0% 57.4% 46.9% 42.8% 55.4% Office Industrial Multifamily Retail Hotel Other Total CRE Portfolio by Property Type Wtd. Avg. DSCR by Property Type CRE Portfolio by Geography Geographic Data by Property Type(1) Wtd. Avg. LTV by Property Type 46% 20% 34% FL NY Tri-State Other 54% 23% 23% 42% 10% 48% 35% 41% 24% 38% 19% 43% Multifamily Retail Warehouse/ Industrial Office FL NY Tri-State Other (1) Graphs below illustrate the largest property type concentrations in the CRE portfolio and exclude Hotel, Construction & Land, and other property types.
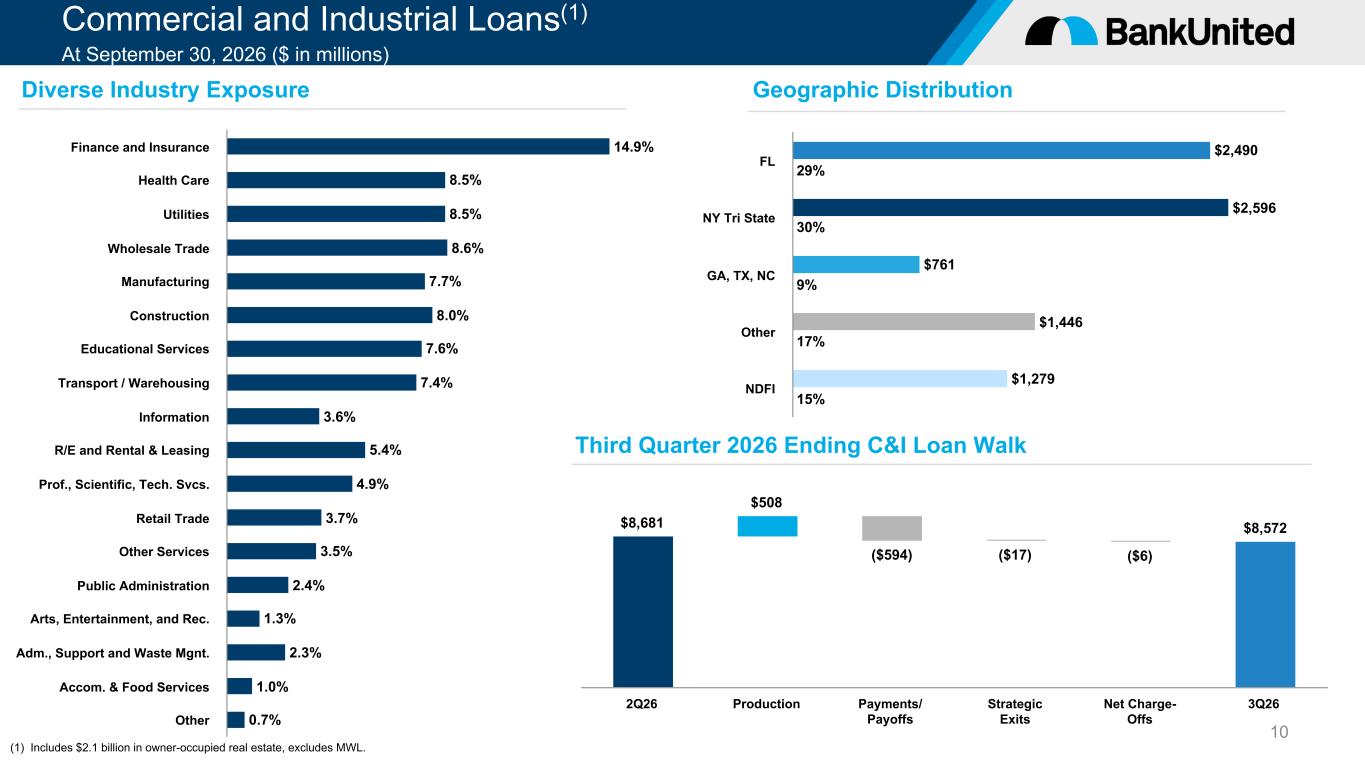
Commercial and Industrial Loans(1) At September 30, 2026 ($ in millions) 10 14.9% 8.5% 8.5% 8.6% 7.7% 8.0% 7.6% 7.4% 3.6% 5.4% 4.9% 3.7% 3.5% 2.4% 1.3% 2.3% 1.0% 0.7% Finance and Insurance Health Care Utilities Wholesale Trade Manufacturing Construction Educational Services Transport / Warehousing Information R/E and Rental & Leasing Prof., Scientific, Tech. Svcs. Retail Trade Other Services Public Administration Arts, Entertainment, and Rec. Adm., Support and Waste Mgnt. Accom. & Food Services Other $8,681 $508 ($594) ($17) ($6) $8,572 2Q26 Production Payments/ Payoffs Strategic Exits Net Charge- Offs 3Q26 Diverse Industry Exposure Geographic Distribution Third Quarter 2026 Ending C&I Loan Walk (1) Includes $2.1 billion in owner-occupied real estate, excludes MWL. $2,490 $2,596 $761 $1,446 $1,279 29% 30% 9% 17% 15% FL NY Tri State GA, TX, NC Other NDFI
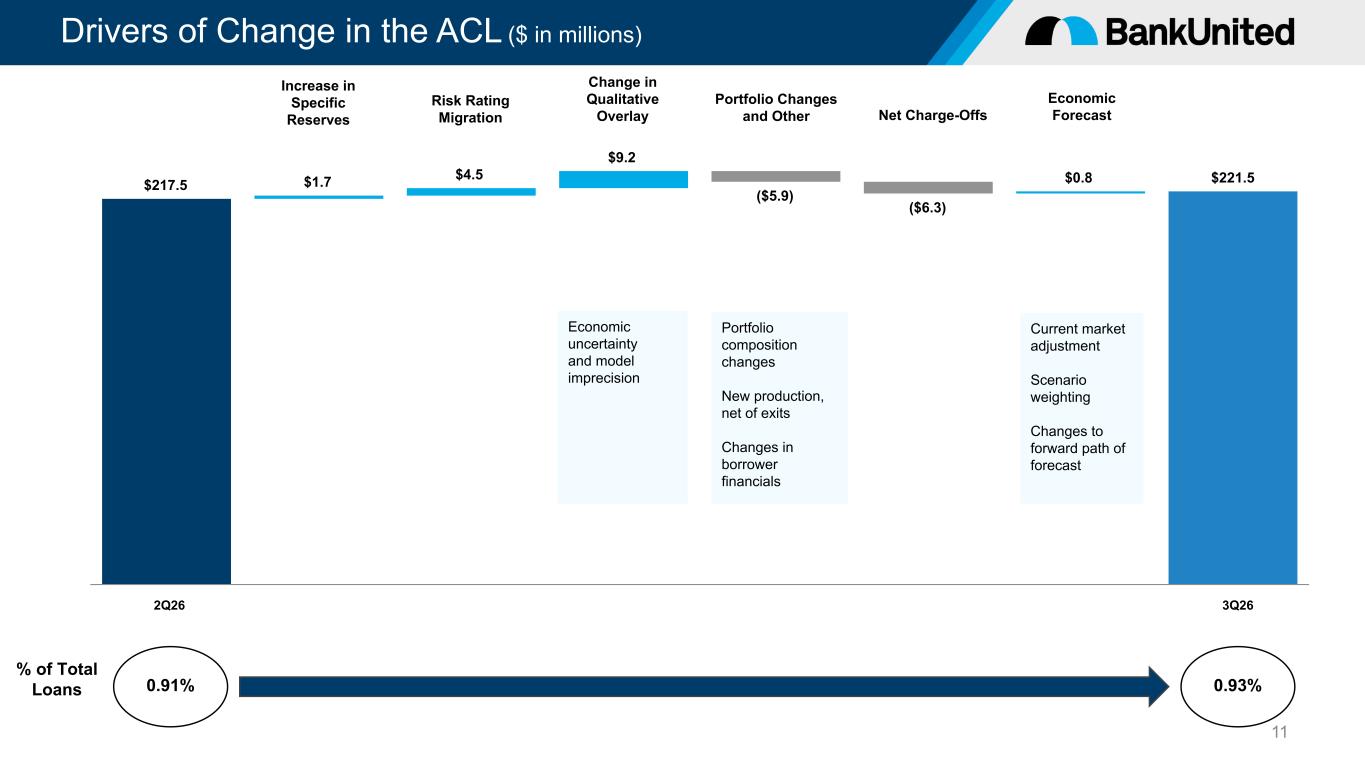
Drivers of Change in the ACL ($ in millions) 11 $217.5 $1.7 $4.5 $9.2 ($5.9) ($6.3) $0.8 $221.5 2Q26 3Q26 % of Total Loans 0.91% 0.93% Increase in Specific Reserves Risk Rating Migration Change in Qualitative Overlay Portfolio Changes and Other Net Charge-Offs Economic Forecast Current market adjustment Scenario weighting Changes to forward path of forecast Portfolio composition changes New production, net of exits Changes in borrower financials Economic uncertainty and model imprecision
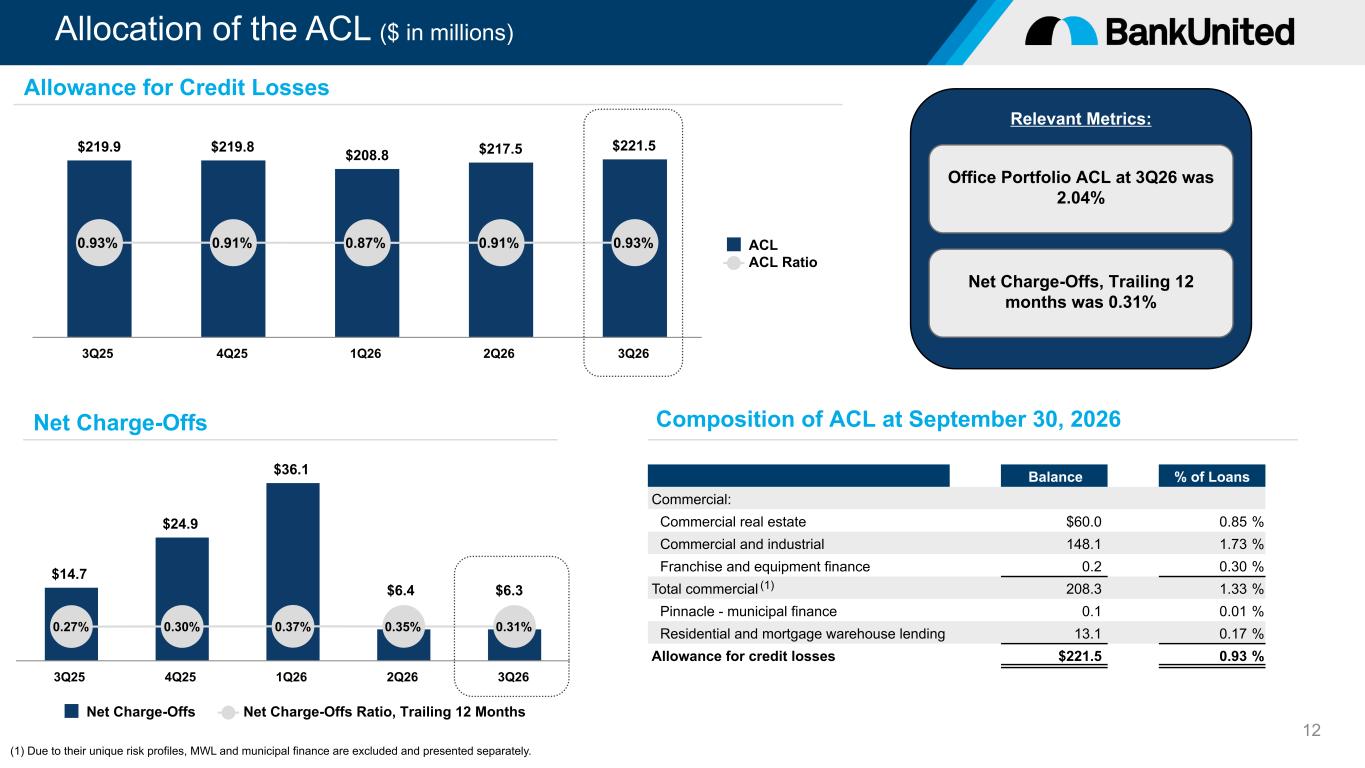
Relevant Metrics: Allocation of the ACL ($ in millions) 12 Office Portfolio ACL at 3Q26 was 2.04% $219.9 $219.8 $208.8 $217.5 $221.5 0.93% 0.91% 0.87% 0.91% 0.93% ACL ACL Ratio 3Q25 4Q25 1Q26 2Q26 3Q26 $14.7 $24.9 $36.1 0.27% 0.30% 0.37% 0.35% 0.31% Net Charge-Offs Net Charge-Offs Ratio, Trailing 12 Months 3Q25 4Q25 1Q26 2Q26 3Q26 Allowance for Credit Losses Net Charge-Offs Composition of ACL at September 30, 2026 Balance % of Loans Commercial: Commercial real estate $60.0 0.85 % Commercial and industrial 148.1 1.73 % Franchise and equipment finance 0.2 0.30 % Total commercial 208.3 1.33 % Pinnacle - municipal finance 0.1 0.01 % Residential and mortgage warehouse lending 13.1 0.17 % Allowance for credit losses $221.5 0.93 % Net Charge-Offs, Trailing 12 months was 0.31% $6.3$6.4 (1) (1) Due to their unique risk profiles, MWL and municipal finance are excluded and presented separately.
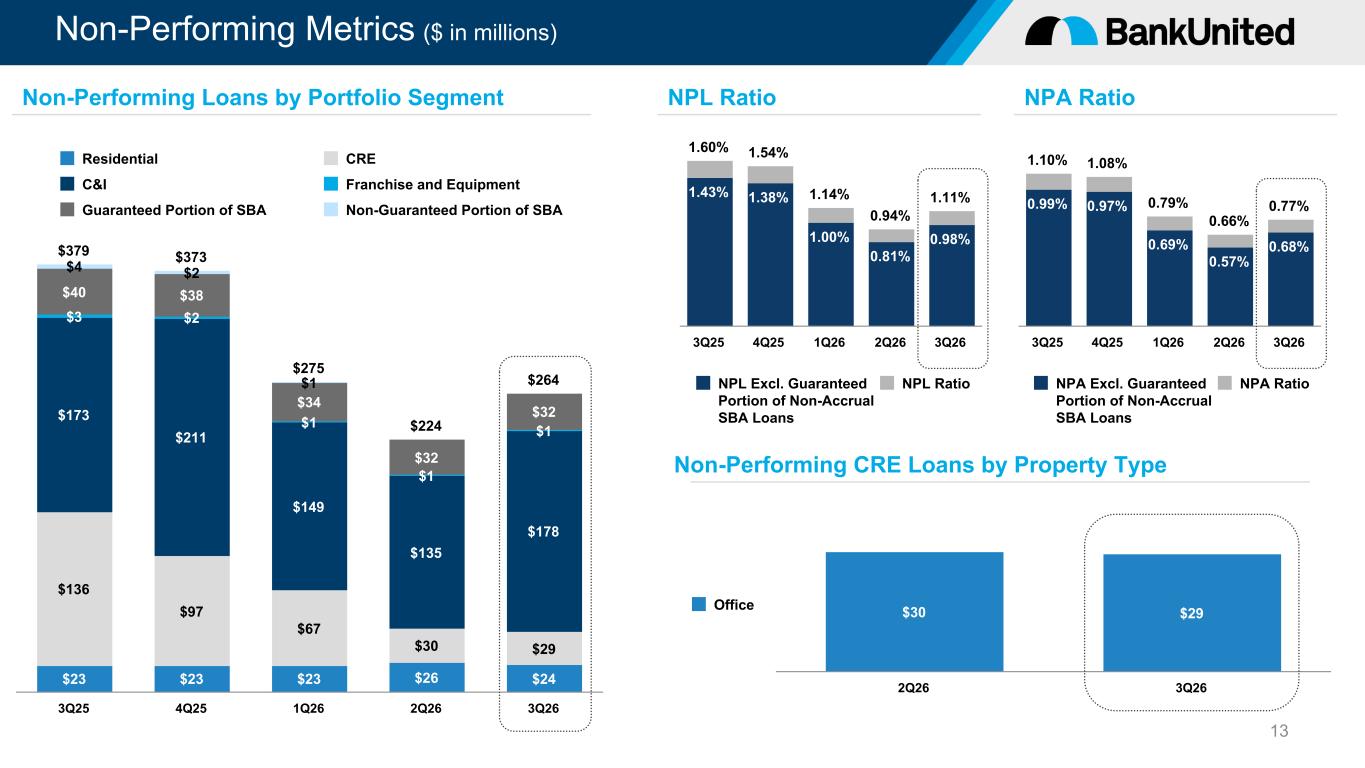
Non-Performing Metrics ($ in millions) 13 1.60% 1.54% 1.14% 0.94% 1.11%1.43% 1.38% 1.00% 0.81% 0.98% NPL Excl. Guaranteed Portion of Non-Accrual SBA Loans NPL Ratio 3Q25 4Q25 1Q26 2Q26 3Q26 NPL RatioNon-Performing Loans by Portfolio Segment $379 $373 $275 $224 $264 $23 $23 $23 $26 $24 $136 $97 $67 $30 $29 $173 $211 $149 $135 $178 $3 $2 $1 $1 $1 $40 $38 $34 $32 $32 $4 $2 $1 Residential CRE C&I Franchise and Equipment Guaranteed Portion of SBA Non-Guaranteed Portion of SBA 3Q25 4Q25 1Q26 2Q26 3Q26 1.10% 1.08% 0.79% 0.66% 0.77%0.99% 0.97% 0.69% 0.57% 0.68% NPA Excl. Guaranteed Portion of Non-Accrual SBA Loans NPA Ratio 3Q25 4Q25 1Q26 2Q26 3Q26 NPA Ratio Non-Performing CRE Loans by Property Type $30 $29Office 2Q26 3Q26
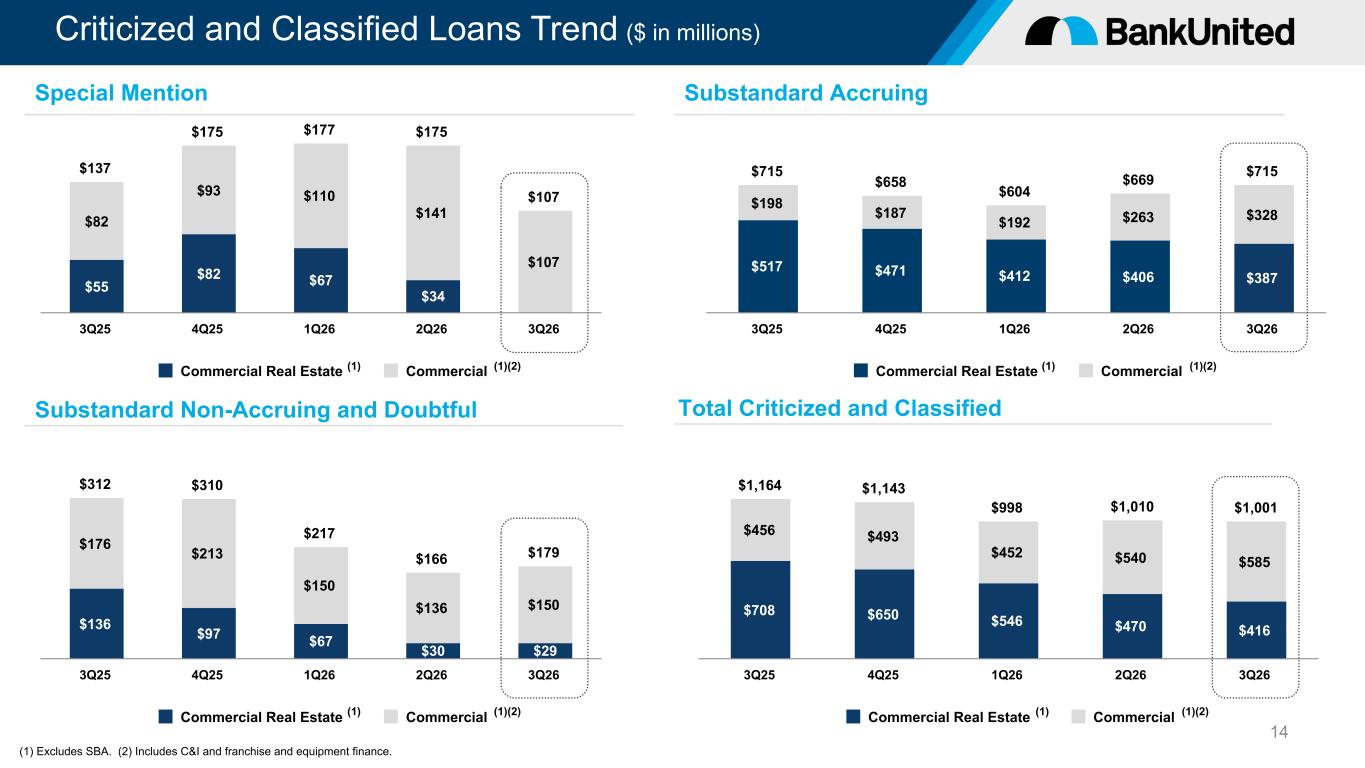
Criticized and Classified Loans Trend ($ in millions) 14 $137 $175 $177 $175 $107 $55 $82 $67 $34 $82 $93 $110 $141 $107 Commercial Real Estate Commercial 3Q25 4Q25 1Q26 2Q26 3Q26 $312 $310 $217 $166 $179 $136 $97 $67 $30 $29 $176 $213 $150 $136 $150 Commercial Real Estate Commercial 3Q25 4Q25 1Q26 2Q26 3Q26 (1) Excludes SBA. (2) Includes C&I and franchise and equipment finance. Special Mention Substandard Non-Accruing and Doubtful $715 $658 $604 $669 $715 $517 $471 $412 $406 $387 $198 $187 $192 $263 $328 Commercial Real Estate Commercial 3Q25 4Q25 1Q26 2Q26 3Q26 $1,164 $1,143 $998 $1,010 $1,001 $708 $650 $546 $470 $416 $456 $493 $452 $540 $585 Commercial Real Estate Commercial 3Q25 4Q25 1Q26 2Q26 3Q26 Total Criticized and Classified Substandard Accruing (1) (1)(2) (1) (1)(2) (1) (1)(2) (1) (1)(2)
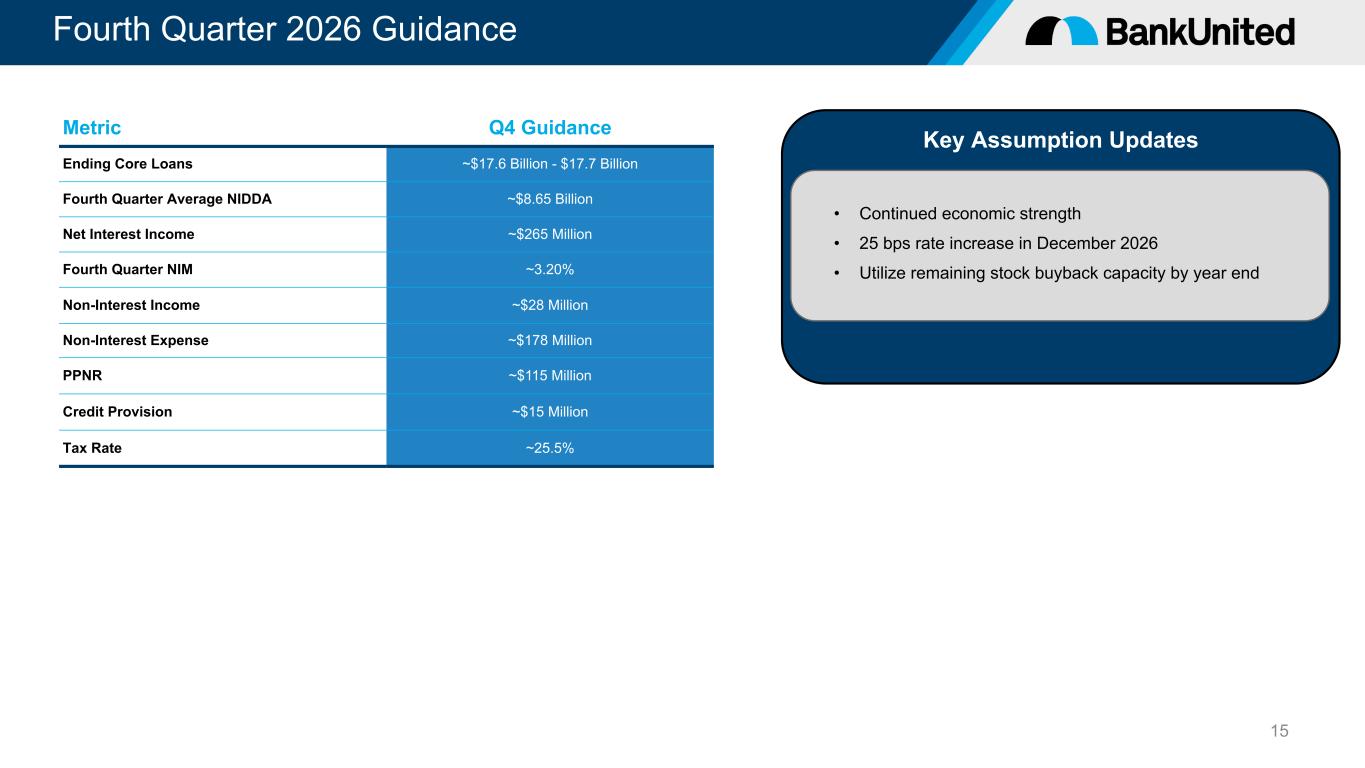
Fourth Quarter 2026 Guidance 15 Key Assumption Updates • Continued economic strength • 25 bps rate increase in December 2026 • Utilize remaining stock buyback capacity by year end Metric Q4 Guidance Ending Core Loans ~$17.6 Billion - $17.7 Billion Fourth Quarter Average NIDDA ~$8.65 Billion Net Interest Income ~$265 Million Fourth Quarter NIM ~3.20% Non-Interest Income ~$28 Million Non-Interest Expense ~$178 Million PPNR ~$115 Million Credit Provision ~$15 Million Tax Rate ~25.5%
Appendix
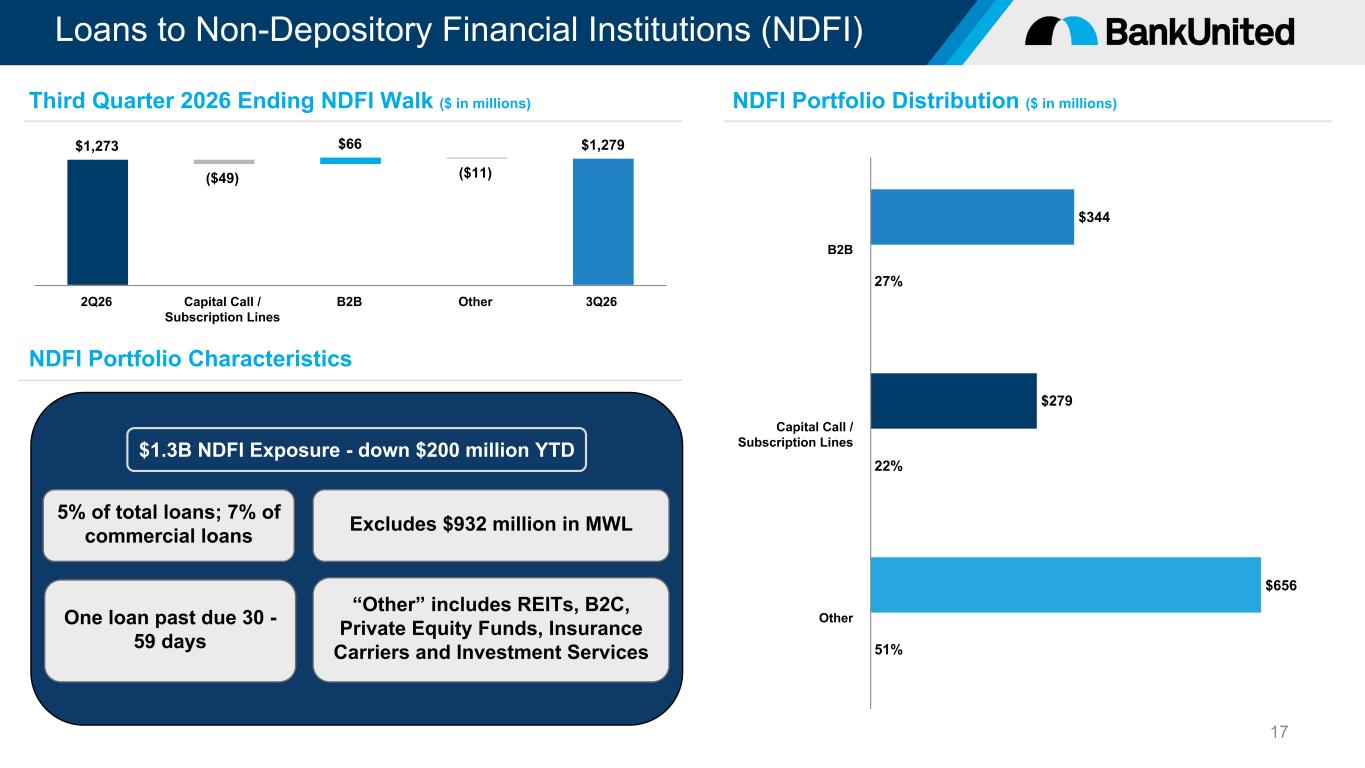
$1.3B NDFI Exposure - down $200 million YTD Loans to Non-Depository Financial Institutions (NDFI) 17 “Other” includes REITs, B2C, Private Equity Funds, Insurance Carriers and Investment Services NDFI Portfolio Characteristics 5% of total loans; 7% of commercial loans One loan past due 30 - 59 days Excludes $932 million in MWL $1,273 ($49) $66 ($11) $1,279 2Q26 Capital Call / Subscription Lines B2B Other 3Q26 Third Quarter 2026 Ending NDFI Walk ($ in millions) NDFI Portfolio Distribution ($ in millions) $344 $279 $656 27% 22% 51% B2B Capital Call / Subscription Lines Other
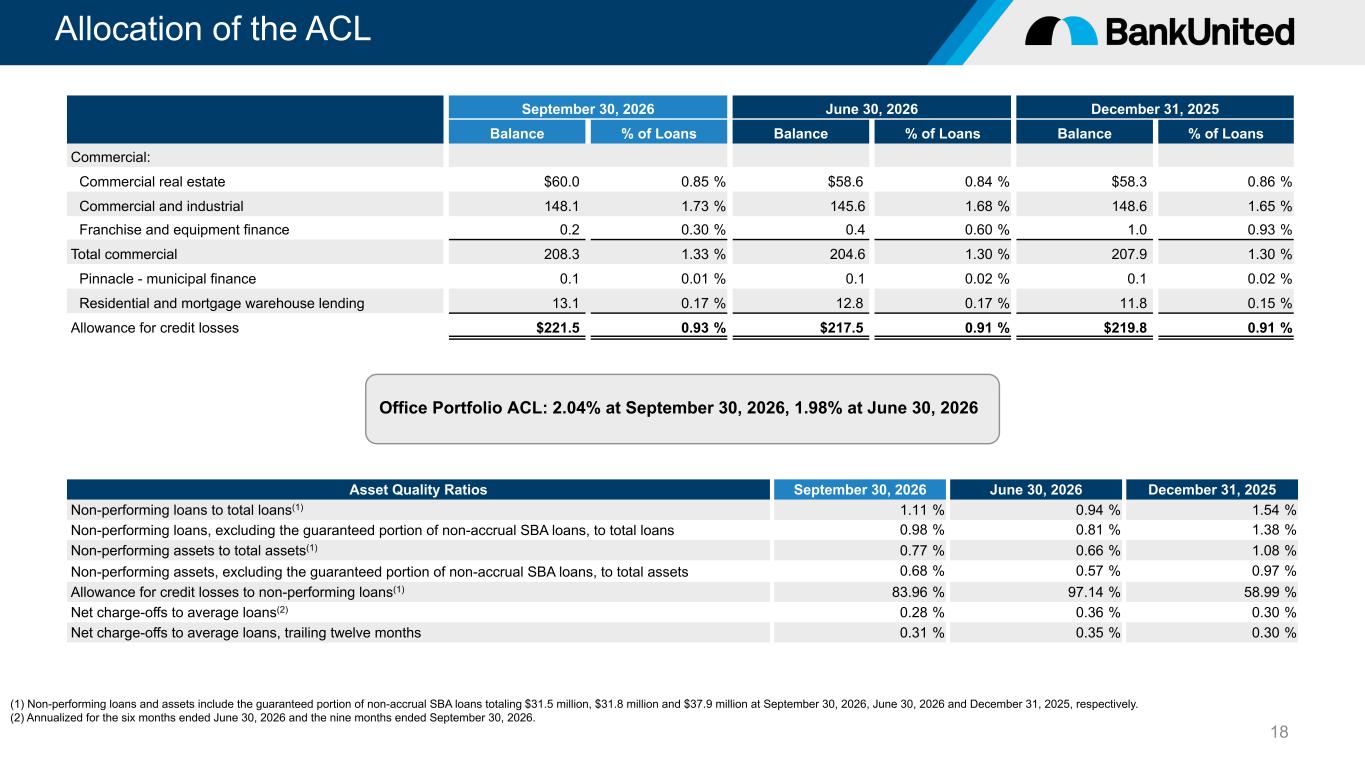
Allocation of the ACL 18 September 30, 2026 June 30, 2026 December 31, 2025 Balance % of Loans Balance % of Loans Balance % of Loans Commercial: Commercial real estate $60.0 0.85 % $58.6 0.84 % $58.3 0.86 % Commercial and industrial 148.1 1.73 % 145.6 1.68 % 148.6 1.65 % Franchise and equipment finance 0.2 0.30 % 0.4 0.60 % 1.0 0.93 % Total commercial 208.3 1.33 % 204.6 1.30 % 207.9 1.30 % Pinnacle - municipal finance 0.1 0.01 % 0.1 0.02 % 0.1 0.02 % Residential and mortgage warehouse lending 13.1 0.17 % 12.8 0.17 % 11.8 0.15 % Allowance for credit losses $221.5 0.93 % $217.5 0.91 % $219.8 0.91 % Office Portfolio ACL: 2.04% at September 30, 2026, 1.98% at June 30, 2026 Asset Quality Ratios September 30, 2026 June 30, 2026 December 31, 2025 Non-performing loans to total loans(1) 1.11 % 0.94 % 1.54 % Non-performing loans, excluding the guaranteed portion of non-accrual SBA loans, to total loans 0.98 % 0.81 % 1.38 % Non-performing assets to total assets(1) 0.77 % 0.66 % 1.08 % Non-performing assets, excluding the guaranteed portion of non-accrual SBA loans, to total assets 0.68 % 0.57 % 0.97 % Allowance for credit losses to non-performing loans(1) 83.96 % 97.14 % 58.99 % Net charge-offs to average loans(2) 0.28 % 0.36 % 0.30 % Net charge-offs to average loans, trailing twelve months 0.31 % 0.35 % 0.30 % (1) Non-performing loans and assets include the guaranteed portion of non-accrual SBA loans totaling $31.5 million, $31.8 million and $37.9 million at September 30, 2026, June 30, 2026 and December 31, 2025, respectively. (2) Annualized for the six months ended June 30, 2026 and the nine months ended September 30, 2026.
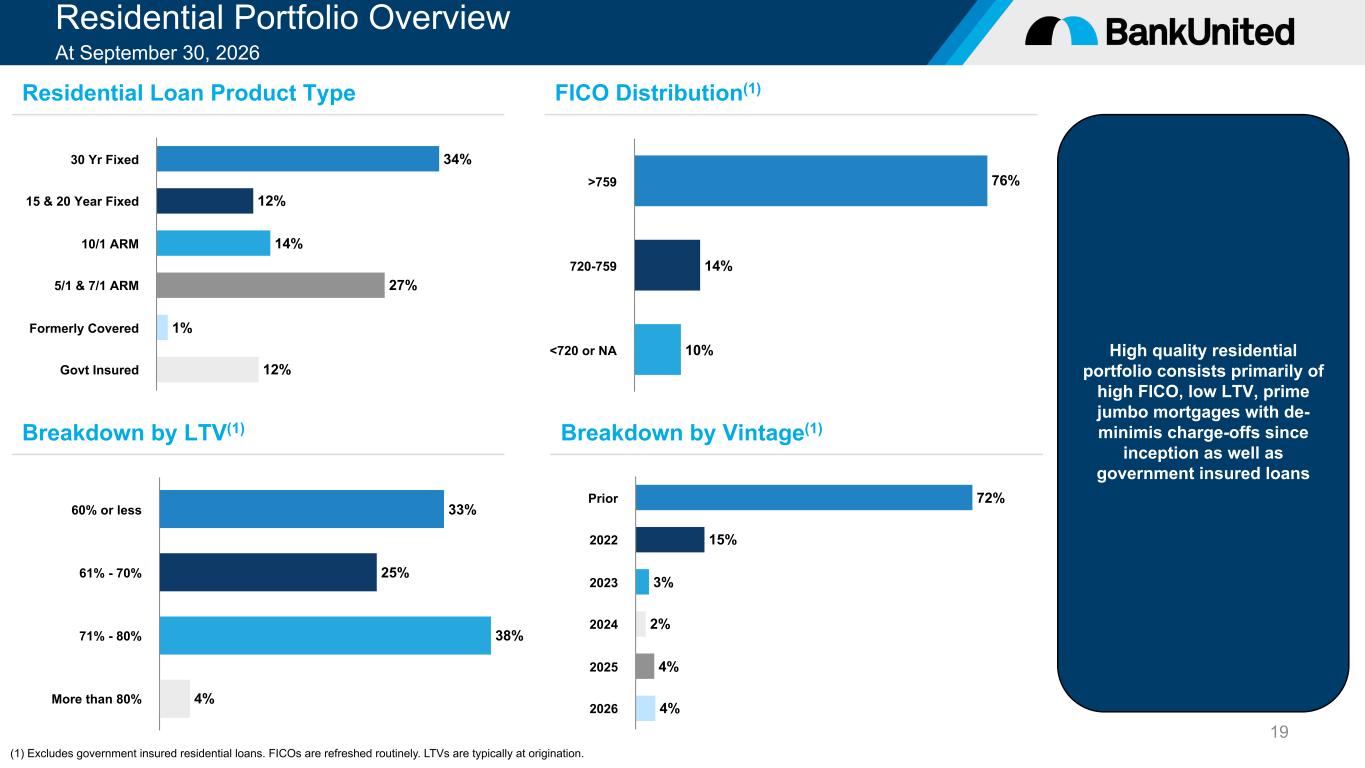
Residential Portfolio Overview At September 30, 2026 19 High quality residential portfolio consists primarily of high FICO, low LTV, prime jumbo mortgages with de- minimis charge-offs since inception as well as government insured loans (1) Excludes government insured residential loans. FICOs are refreshed routinely. LTVs are typically at origination. Residential Loan Product Type Breakdown by LTV(1) FICO Distribution(1) Breakdown by Vintage(1) 34% 12% 14% 27% 1% 12% 30 Yr Fixed 15 & 20 Year Fixed 10/1 ARM 5/1 & 7/1 ARM Formerly Covered Govt Insured 76% 14% 10% >759 720-759 <720 or NA 33% 25% 38% 4% 60% or less 61% - 70% 71% - 80% More than 80% 72% 15% 3% 2% 4% 4% Prior 2022 2023 2024 2025 2026
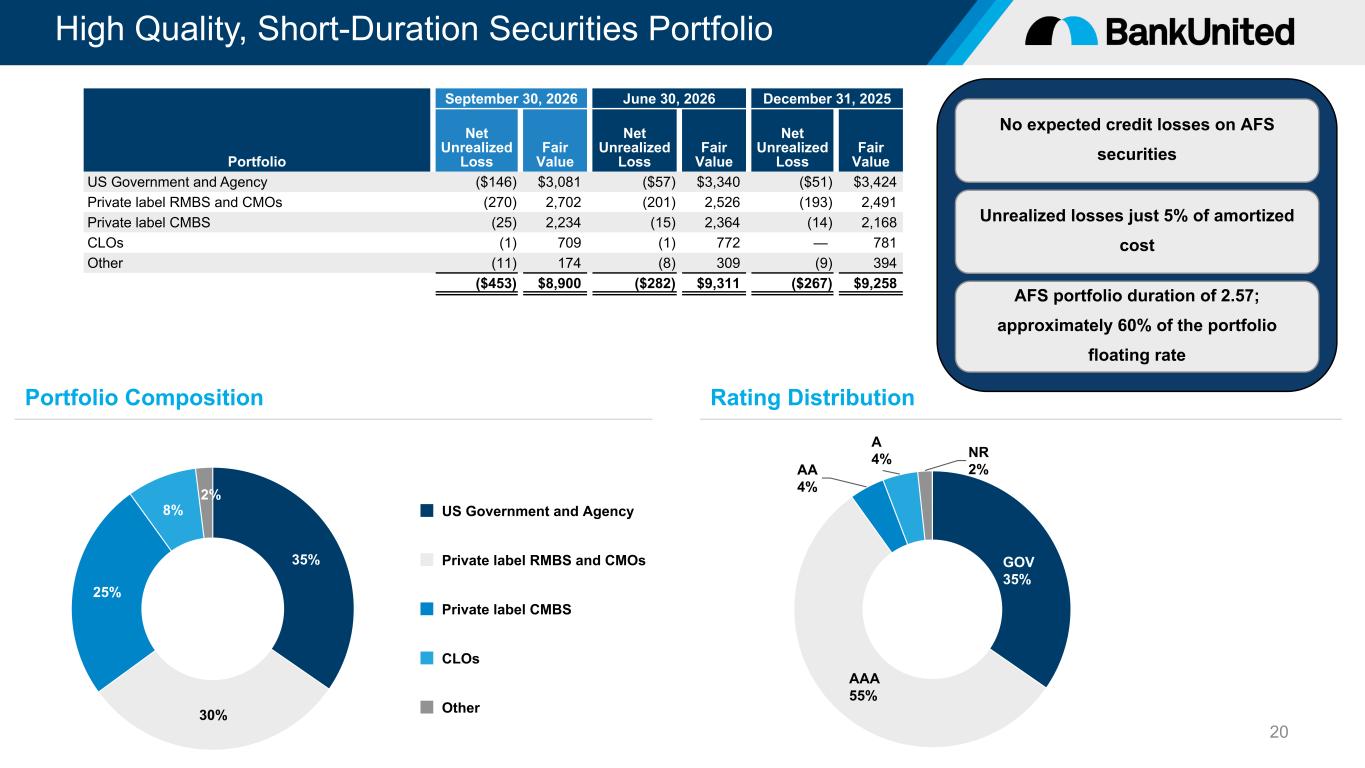
Unrealized losses just 5% of amortized cost No expected credit losses on AFS securities High Quality, Short-Duration Securities Portfolio 20 35% 30% 25% 8% 2% US Government and Agency Private label RMBS and CMOs Private label CMBS CLOs Other GOV 35% AAA 55% AA 4% A 4% NR 2% September 30, 2026 June 30, 2026 December 31, 2025 Portfolio Net Unrealized Loss Fair Value Net Unrealized Loss Fair Value Net Unrealized Loss Fair Value US Government and Agency ($146) $3,081 ($57) $3,340 ($51) $3,424 Private label RMBS and CMOs (270) 2,702 (201) 2,526 (193) 2,491 Private label CMBS (25) 2,234 (15) 2,364 (14) 2,168 CLOs (1) 709 (1) 772 — 781 Other (11) 174 (8) 309 (9) 394 ($453) $8,900 ($282) $9,311 ($267) $9,258 Portfolio Composition Rating Distribution AFS portfolio duration of 2.57; approximately 60% of the portfolio floating rate
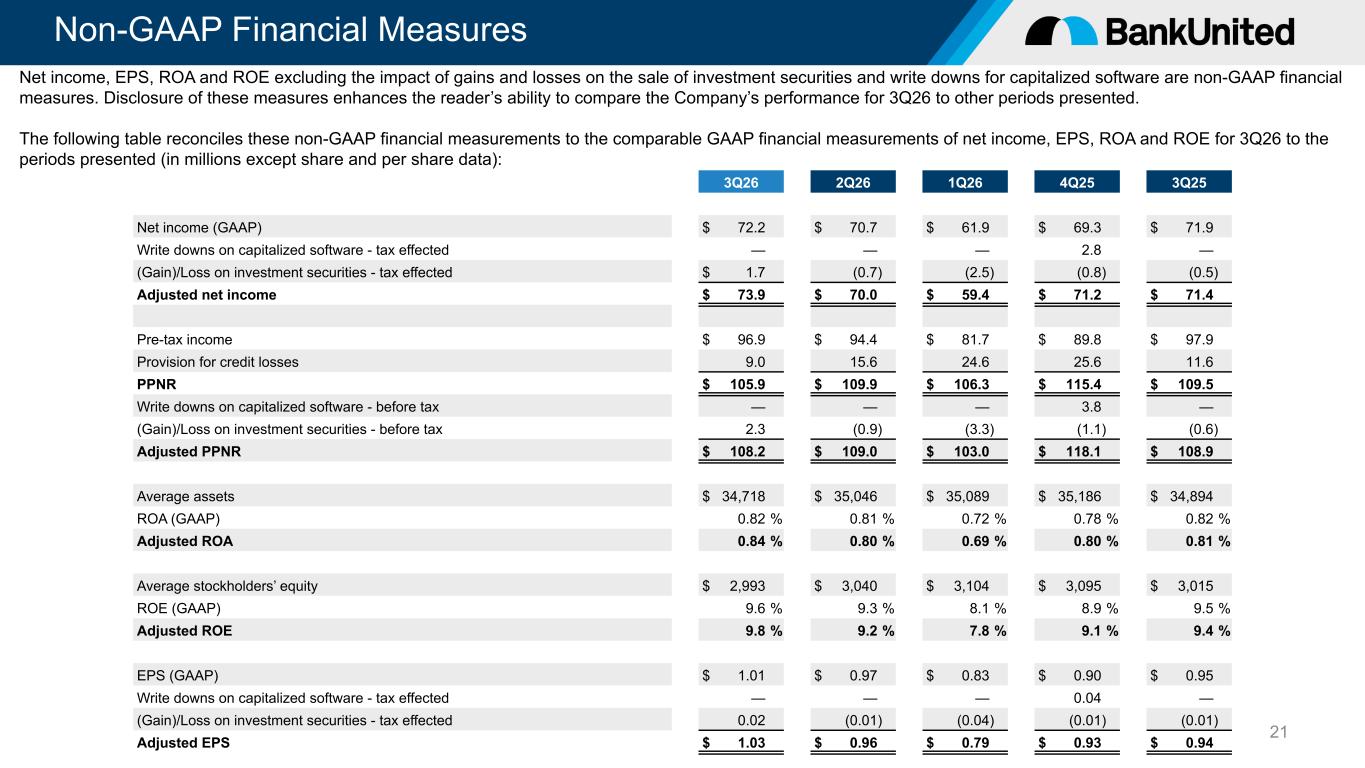
Non-GAAP Financial Measures 21 3Q26 2Q26 1Q26 4Q25 3Q25 Net income (GAAP) $ 72.2 $ 70.7 $ 61.9 $ 69.3 $ 71.9 Write downs on capitalized software - tax effected — — — 2.8 — (Gain)/Loss on investment securities - tax effected $ 1.7 (0.7) (2.5) (0.8) (0.5) Adjusted net income $ 73.9 $ 70.0 $ 59.4 $ 71.2 $ 71.4 Pre-tax income $ 96.9 $ 94.4 $ 81.7 $ 89.8 $ 97.9 Provision for credit losses 9.0 15.6 24.6 25.6 11.6 PPNR $ 105.9 $ 109.9 $ 106.3 $ 115.4 $ 109.5 Write downs on capitalized software - before tax — — — 3.8 — (Gain)/Loss on investment securities - before tax 2.3 (0.9) (3.3) (1.1) (0.6) Adjusted PPNR $ 108.2 $ 109.0 $ 103.0 $ 118.1 $ 108.9 Average assets $ 34,718 $ 35,046 $ 35,089 $ 35,186 $ 34,894 ROA (GAAP) 0.82 % 0.81 % 0.72 % 0.78 % 0.82 % Adjusted ROA 0.84 % 0.80 % 0.69 % 0.80 % 0.81 % Average stockholders’ equity $ 2,993 $ 3,040 $ 3,104 $ 3,095 $ 3,015 ROE (GAAP) 9.6 % 9.3 % 8.1 % 8.9 % 9.5 % Adjusted ROE 9.8 % 9.2 % 7.8 % 9.1 % 9.4 % EPS (GAAP) $ 1.01 $ 0.97 $ 0.83 $ 0.90 $ 0.95 Write downs on capitalized software - tax effected — — — 0.04 — (Gain)/Loss on investment securities - tax effected 0.02 (0.01) (0.04) (0.01) (0.01) Adjusted EPS $ 1.03 $ 0.96 $ 0.79 $ 0.93 $ 0.94 Net income, EPS, ROA and ROE excluding the impact of gains and losses on the sale of investment securities and write downs for capitalized software are non-GAAP financial measures. Disclosure of these measures enhances the reader’s ability to compare the Company’s performance for 3Q26 to other periods presented. The following table reconciles these non-GAAP financial measurements to the comparable GAAP financial measurements of net income, EPS, ROA and ROE for 3Q26 to the periods presented (in millions except share and per share data):
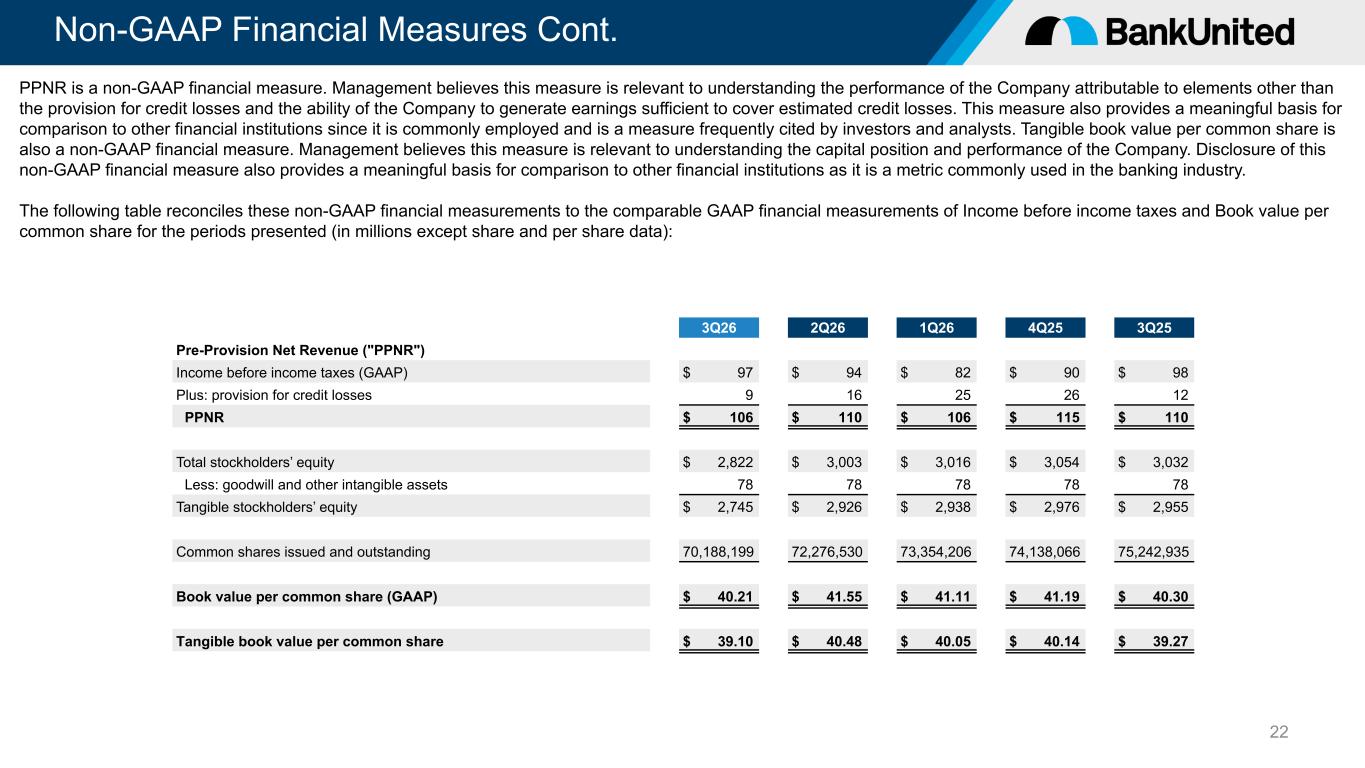
Non-GAAP Financial Measures Cont. 22 PPNR is a non-GAAP financial measure. Management believes this measure is relevant to understanding the performance of the Company attributable to elements other than the provision for credit losses and the ability of the Company to generate earnings sufficient to cover estimated credit losses. This measure also provides a meaningful basis for comparison to other financial institutions since it is commonly employed and is a measure frequently cited by investors and analysts. Tangible book value per common share is also a non-GAAP financial measure. Management believes this measure is relevant to understanding the capital position and performance of the Company. Disclosure of this non-GAAP financial measure also provides a meaningful basis for comparison to other financial institutions as it is a metric commonly used in the banking industry. The following table reconciles these non-GAAP financial measurements to the comparable GAAP financial measurements of Income before income taxes and Book value per common share for the periods presented (in millions except share and per share data): 3Q26 2Q26 1Q26 4Q25 3Q25 Pre-Provision Net Revenue ("PPNR") Income before income taxes (GAAP) $ 97 $ 94 $ 82 $ 90 $ 98 Plus: provision for credit losses 9 16 25 26 12 PPNR $ 106 $ 110 $ 106 $ 115 $ 110 Total stockholders’ equity $ 2,822 $ 3,003 $ 3,016 $ 3,054 $ 3,032 Less: goodwill and other intangible assets 78 78 78 78 78 Tangible stockholders’ equity $ 2,745 $ 2,926 $ 2,938 $ 2,976 $ 2,955 Common shares issued and outstanding 70,188,199 72,276,530 73,354,206 74,138,066 75,242,935 Book value per common share (GAAP) $ 40.21 $ 41.55 $ 41.11 $ 41.19 $ 40.30 Tangible book value per common share $ 39.10 $ 40.48 $ 40.05 $ 40.14 $ 39.27