Please wait
| | |
| 2026 Third Quarter Report |
Contrarian. Innovative. Aligned.
Table of Contents
Letter to shareholders 2
Management's Discussion and Analysis 6
Consolidated Financial Statements 25
Notes to the Consolidated Financial Statements 30
Dear fellow shareholders,
Q3 2026 and YTD Review
Sprott’s Assets Under Management (“AUM”) were $57.3 billion as at September 30, 2026, up 3% from $55.6 billion as at June 30, 2026 and down 4% from $59.6 billion as of December 31, 2025. On a three-month ended basis, our AUM was positively impacted by market value appreciation across a majority of our fund products. Conversely, for the nine months ended September 30, 2026, our AUM was negatively impacted by market value depreciation and net outflows from our precious metals products, partially offset by positive net inflows to our critical materials products. During the third quarter, we reported $207 million in net redemptions. On a year-to-date basis, net inflows were $1.1 billion as of September 30, 2026. Average AUM was $58.8 billion for the quarter, up $16.5 billion or 39% from $42.3 billion for the quarter ended September 30, 2025, and $64 billion on a year-to-date basis, up $26.3 billion or 70% from $37.7 billion for the nine months ended September 30, 2025. Subsequent to quarter-end, as at October 30, 2026, AUM was $52.1 billion.
Net income for the quarter was $22 million ($0.86 per share), up $8.8 million or 67% from $13.2 million ($0.51 per share) for the quarter ended September 30, 2025 and $85.5 million ($3.32 per share) on a year-to-date basis, up $46.9 million from $38.6 million ($1.50 per share) for the nine months ended September 30, 2025. Our net income performance was primarily due to higher average AUM in our exchange listed products and managed equities segments, as well as carried interest crystallization in our private strategies segment in the first quarter.
Adjusted EBITDA was $46 million ($1.79 per share) for the quarter, up $14.1 million or 44% from $31.9 million ($1.24 per share) for the quarter ended September 30, 2025 and $154.7 million ($6.01 per share) on a year-to-date basis, up $75.4 million or 95% from $79.3 million ($3.07 per share) for the nine months ended September 30, 2025. Our Adjusted EBITDA increased in the quarter and on a nine months ended basis due to higher average AUM, attributable to a combination of net inflows and market value appreciation across a majority of our fund products since the third quarter of last year, which more than offset the impact of year-to-date pullbacks in precious metals valuations.
Precious Metals
Precious metals recovered modestly during the third quarter of 2026, although significant volatility persisted. Spot gold rose 3.7% during the quarter to close September at US$4,157/oz, while silver gained 3.1% to US$60/oz. These quarterly gains masked a sharp September reversal, when gold declined 6.3% and silver fell 9.2% as rising real yields and a stronger U.S. dollar weighed on non-interest-bearing assets. The U.S. 10-year inflation-protected Treasury yield increased 49 basis points in September, highlighting the pressure from tighter financial conditions. Nevertheless, gold and silver finished the quarter above their June lows, while reported gold ETF holdings increased in September and silver ETF holdings rose for a third consecutive month. In our view, the quarter underscored the tension between near-term monetary headwinds and longer-term structural support. Rising sovereign debt burdens, persistent fiscal deficits and central bank reserve diversification continue to underpin gold’s role as a strategic monetary asset. Silver remains exposed to interest rate and currency volatility, but resilient Chinese demand and silver’s industrial applications provide additional support.
In recent weeks we have seen a long-overdue liquidity event begin to play out. Gold and silver are increasingly being caught in a broader liquidity-driven deleveraging cycle. As volatility rises, leveraged investors, systematic strategies and risk managers are forced to cut exposure, often selling liquid winners regardless of fundamentals. Gold may initially hold up better as falling bond yields support safe-haven demand, while silver’s higher volatility and industrial sensitivity leave it more exposed to forced liquidation. The result is a temporary disconnect from supportive fundamentals, with downside pressure likely to persist until positioning is sufficiently reduced and liquidity conditions stabilize.
Critical Materials
Uranium markets experienced a sharp contrast between improving fuel-market conditions and volatile mining equities during the third quarter of 2026. The uranium spot price increased during the quarter, and the long-term price reached an all-time high of US$96/lb, while uranium mining equities endured considerable volatility. In August, stronger pricing supported a rally in mining shares, with uranium miners up 17.2% before subsequent weakness erased those gains by quarter-end. In our view, the quarter’s central distinction was between the conditions underpinning uranium contracting and the financial-market pressures affecting mining shares. Utilities were accepting higher prices and more favorable producer terms to secure future supply, improving revenue visibility and mine economics even as equity markets remained volatile.
We remain constructive on the long-term outlook for critical materials. Discussions surrounding September’s World Nuclear Symposium reinforced the growing focus on financing, building and fueling additional nuclear capacity, supported by rising electricity demand, energy security priorities and the expansion of AI infrastructure. For uranium, declining utility contract coverage beyond 2030 and constrained mine supply strengthen the case for sustained investment in new production. Copper faces a similar challenge as grid expansion and electrification increase demand while declining ore grades and lengthy development timelines constrain supply growth. Copper prices also reached multiple all-time highs in the quarter, while copper miners were the standout critical materials subsector during both the quarter and year-to-date, reflecting growing recognition of these structural supply constraints. Efforts to diversify rare earth supply chains outside China add another important dimension to the opportunity. These structural drivers support our diversified critical materials platform and reinforce our constructive long-term outlook, even as commodity prices, financing conditions and investor flows are likely to remain volatile.
Physical Trusts
Our physical trust AUM increased by $1.2 billion during the quarter driven by somewhat higher gold and silver prices, offset by $416 million in redemptions from our precious metals trusts.
ETFs
We continued to see the benefits of our growing critical materials franchise during the third quarter with our critical materials ETFs delivering $236 million in net sales despite the volatile environment. On a nine-month basis, these strategies have accounted for $1.6 billion in net flows and we are actively exploring new ideas to expand this product suite.
Managed Equities
Precious metals equities rebounded during the third quarter, although September’s selloff underscored the sector’s continued volatility. Our flagship Sprott Gold Equity Fund returned 15.7% for the three months ended September 30, 2026. Our active ETFs continue to scale, with the combined AUM of the Sprott Active Gold & Silver Miners ETF (GBUG) and the Sprott Active Metals & Miners ETF (METL) exceeding $250 million.
Mining equities remain attractive with valuations that don’t currently reflect their stronger balance sheets and growing free cash flows.
Private Strategies
Our Private Strategies business continues to be well positioned, supported by favorable market tailwinds and a strong track record. This has driven increased demand on both sides of the platform, with borrowers and investees increasingly seeking our financing solutions and institutional investors looking to allocate additional capital to our strategies. The market continues to evolve toward less-dilutive financing solutions that preserve shareholder value and reduce long-term impacts on capital structures. This shift aligns closely with the products offered by Sprott’s Private Strategies team and is expected to support higher capital deployment in 2027 and beyond.
Outlook
Geopolitical conditions have worsened since our last letter. The war in Iran has re-escalated and is now a broader Middle East conflict with attacks on Saudi Arabia and many other Gulf states. Energy and other commodity prices are rising again with reserve stockpiles nearly depleted. The resultant inflationary expectations drove fixed income markets to their worst quarterly performance in decades. U.S. 10-year Treasuries declined by nearly 8% in the quarter with yields at levels not seen in two decades. This despite the best efforts of the U.S. Treasury Department and Federal Reserve to convince markets that they could control inflation and force rates back down. Federal Reserve chairman Kevin Warsh delivered a hawkish speech in August. Then in September, the Federal Reserve raised rates 25 basis points more to preserve credibility than to have an economic impact. For his part, Treasury Secretary Bessent directed an intervention in the currency markets to prevent Japan from selling U.S. Treasuries to defend its currency. Next, Bessent raised the Treasury's commitment to buy back long dated issues. And finally, he declared “I am the house” in an effort to scare short-term traders into covering their short positions. None of these moves had more than a momentary impact on halting the rise in rates. Further, describing the Department of the Treasury as some kind of casino can hardly inspire confidence. We are reminded of the famous quote from the 1975 movie Jaws, “You are going to need a bigger boat.” Perhaps that’s why Secretary Bessent recently hired sound money advocate Judy Shelton as a Counselor to the Treasury Department. Shelton’s responsibilities are said to include “advising Bessent on currency policy, with a particular focus on evaluating financial conditions in China.” While Shelton was widely ridiculed by the Senate when President Trump nominated her for a Federal Reserve position during his first term, her views about backing long-term Treasuries with some linkage to gold may not be so far fetched today. A quick study of China will reveal its continued gold purchases and the lowest 10-year interest rates of any major economy other than Switzerland.
On the surface, equity markets seemed more resilient with major U.S. indices hitting all-time highs and the S&P 500 index itself closing the third quarter just 2% off its all-time high. But once again this was driven by a handful of mega-cap technology companies benefiting from the perceived limitless growth in artificial intelligence. The mean performance of all stocks in the S&P 500 was negative 21%. In the broader Russell 3000 index, 57% of the stocks were down more than 20%. It appears to us that the generals have gotten too far ahead of their troops.
As the U.S. enters midterm elections, it seems that confidence in our leadership has deteriorated from an already low level. Nothing has been accomplished on the leading issues about the cost of living. In fact, the most recent news on inflation is heading in the wrong direction. The only tangible progress has been the renaming of some national monuments and bodies of water. The Gulf of Mexico is now the Gulf of America and Lake Ontario has become Lake America. We have heard that some Canadians prefer the name “The Strait of our Moose.” To be fair, there have also been some modest positives. We have made peace with Greenland and Maine Senator Susan Collins, who is locked in a tight Senate race, successfully lobbied the administration to lower trade tensions by reducing the 50% tariffs on some Canadian goods used by her state’s agricultural industry, including seaweed, rock salt and edible algae. Unfortunately for her constituents, these reductions will be offset by higher tariffs on shampoo, caskets, carpets and other household items.
The news flow from the White House has become exhausting. Reports of trade deals and peace negotiations now seem confined to within the White House walls with outside participants lacking knowledge of their existence. While we don't expect any of this to change in the near term, we remain confident that our products in physical commodities and the miners that produce them are well positioned to help investors diversify their portfolios.
Amid all the noise, we continue to do all we can to create value for our clients and shareholders. Our marketing team continues to generate best-in-class thought leadership materials and our client-facing teams are seeing increased activity from institutions and family offices. Our key accounts team’s efforts to forge relationships and gain shelf space for our products on increasingly larger platforms are paying off. We are beginning to see the impacts of our technology investments on productivity and we continue to explore new ways to become more efficient through thoughtful use of AI. And our efforts are being recognized. In October, Sprott was named as one of Fortune Magazine’s 100 Fastest Growing companies.
We remain confident that the investment thesis for both precious metals and critical materials continues to improve. Our financial position remains strong and our free cash-flow generation is accelerating. We continue to exercise a disciplined capital allocation framework and on November 3, 2026 our board of directors approved a 25% increase to our regular quarterly dividend. During the year and through October we have bought back more than $20 million of our shares through our normal course issuer bid. And we have ample capacity to continue buying if market conditions cause the stock to trade below what we believe to be its long-term value.
As always, we thank you, our fellow shareholders, for your continued support. We look forward to reporting to you on our progress in the quarters ahead. We remain contrarian, innovative and aligned.
Sincerely,
Whitney George
Chief Executive Officer
Management's Discussion and Analysis
Three and nine months ended September 30, 2026
Forward looking statements
Certain statements in this Management's Discussion and Analysis ("MD&A"), and in particular the "Outlook" section, contain forward-looking information and forward-looking statements (collectively referred to herein as the "Forward-Looking Statements") within the meaning of applicable Canadian and U.S. securities laws. The use of any of the words "expect", "anticipate", "continue", "estimate", "may", "will", "project", "should", "believe", "plans", "intends" and similar expressions are intended to identify Forward-Looking Statements. In particular, but without limiting the foregoing, this MD&A contains Forward-Looking Statements pertaining to: (i) our positioning will benefit from a highly compelling environment for precious metals, critical materials and their related equities; (ii) our expectation for higher capital deployment and investor support in private strategies; (iii) our strong financial position and accelerating free cash-flow generation; (iv) our ability to repurchase our shares; and (v) the declaration, payment and designation of dividends and confidence that our business will support the dividend level without impacting our ability to fund future growth initiatives.
Although Sprott Inc. (the "Company") believes that the Forward-Looking Statements are reasonable, they are not guarantees of future results, performance or achievements. A number of factors or assumptions have been used to develop the Forward-Looking Statements, including: (i) the impact of increasing competition in each business in which the Company operates will not be material; (ii) quality management will be available; (iii) the effects of regulation and tax laws of governmental agencies will be consistent with the current environment; (iv) the impact of public health outbreaks; and (v) those assumptions disclosed herein under the heading "Critical Accounting Estimates and significant judgments". Actual results, performance or achievements could vary materially from those expressed or implied by the Forward-Looking Statements should assumptions underlying the Forward-Looking Statements prove incorrect or should one or more risks or other factors materialize, including: (i) difficult market conditions; (ii) poor investment performance; (iii) failure to continue to retain and attract quality staff; (iv) employee errors or misconduct resulting in regulatory sanctions or reputational harm; (v) performance fee fluctuations; (vi) a business segment or another counterparty failing to pay its financial obligation; (vii) failure of the Company to meet its demand for cash or fund obligations as they come due; (viii) changes in the investment management industry; (ix) failure to implement effective information security policies, procedures and capabilities; (x) lack of investment opportunities; (xi) risks related to regulatory compliance; (xii) failure to manage risks appropriately; (xiii) failure to deal appropriately with conflicts of interest; (xiv) competitive pressures; (xv) corporate growth which may be difficult to sustain and may place significant demands on existing administrative, operational and financial resources; (xvi) failure to comply with privacy laws; (xvii) failure to successfully implement succession planning; (xviii) foreign exchange ("FX") risk relating to the relative value of the U.S. dollar; (xix) litigation risk; (xx) failure to develop effective business resiliency plans; (xxi) failure to obtain or maintain sufficient insurance coverage on favorable economic terms; (xxii) historical financial information being not necessarily indicative of future performance; (xxiii) the market price of common shares of the Company may fluctuate widely and rapidly; (xxiv) risks relating to the Company’s investment products; (xxv) risks relating to the Company's proprietary investments; (xxvi) risks relating to the Company's private strategies business; (xxvii) those risks described under the heading "Risk Factors" in the Company’s annual information form dated February 18, 2026; and (xxviii) those risks described under the headings "Managing Financial Risk" and "Managing Non-Financial Risk" in this MD&A. In addition, the payment of dividends is not guaranteed and the amount and timing of any dividends payable by the Company will be at the discretion of the board of directors of the Company and will be established on the basis of the Company’s earnings, the satisfaction of solvency tests imposed by applicable corporate law for the declaration and payment of dividends, and other relevant factors. The Forward-Looking Statements speak only as of the date hereof, unless otherwise specifically noted, and the Company does not assume any obligation to publicly update any Forward-Looking Statements, whether as a result of new information, future events or otherwise, except as may be expressly required by applicable securities laws.
Management's discussion and analysis
This MD&A of financial condition and results of operations, dated November 3, 2026, presents an analysis of the consolidated financial condition of the Company and its subsidiaries as at September 30, 2026, compared with December 31, 2025, and the consolidated results of operations for the three and nine months ended September 30, 2026, compared with the three and nine months ended September 30, 2025. The board of directors of the Company approved this MD&A on November 3, 2026. All note references in this MD&A are to the notes to the Company's September 30, 2026 interim condensed consolidated financial statements ("interim financial statements"), unless otherwise noted. The Company was incorporated under the Business Corporations Act (Ontario) on February 13, 2008.
Presentation of financial information
The interim financial statements, including the required comparative information, have been prepared in accordance with International Financial Reporting Standards ("IFRS"), as issued by the International Accounting Standards Board ("IASB") in effect as at September 30, 2026, specifically, IAS 34 Interim Financial Reporting. Financial results, including related historical comparatives contained in this MD&A, unless otherwise specified herein, are based on the interim financial statements. While the Company's primary transactional currency and presentation currency is the U.S. dollar, IFRS requires that the Company measure its foreign exchange gains and losses through its consolidated statements of operations and comprehensive income using the Canadian dollar as its functional currency. All dollar references in this MD&A are in U.S. dollars. The use of the term "prior period" refers to the three and nine months ended September 30, 2025.
Key performance indicators and non-IFRS and other financial measures
The Company measures the success of its business using a number of key performance indicators that are not measurements in accordance with IFRS and should not be considered an alternative to net income (loss) or any other measure of performance under IFRS. Non-IFRS financial measures do not have a standardized meaning prescribed by IFRS and are therefore unlikely to be comparable to similar measures presented by other issuers. Our key performance indicators and non-IFRS and other financial measures are discussed below. For quantitative reconciliations of non-IFRS financial measures to their most directly comparable IFRS financial measures, please see page 12 of this MD&A.
Assets under management
Assets under management ("AUM") refers to the total net assets managed by the Company through its various investment product offerings and managed accounts.
Net inflows
Net inflows result in changes to AUM, and as such, have a direct impact on the revenues and earnings of the Company. They are described individually below:
Trust unit issuances and exchange traded funds ("ETF") unit ’creations’
The primary way in which inflows arise in our exchange listed products segment is through: (1) units of our physical trusts being issued through at-the-market (“ATM”) transactions, secondary public and private offerings; and (2) new 'creations' of ETF units.
Net sales
Fund sales (net of redemptions) are the primary manner in which net inflows arise in our managed equities segment.
Net capital calls
Capital calls, net of capital distributions ("net capital calls") are the primary manner in which net inflows arise in our private strategies segment.
Other net inflows
Other net inflows primarily include fund acquisitions. It is possible for committed capital in our private strategies to earn a commitment fee despite being uncalled, in which case, it will also be included in this category as AUM.
Net fees
Net fees are calculated as: (1) total management fees net of fund expenses and direct payouts; and (2) carried interest and performance fees, net of their related payouts. Net fees is a key revenue indicator as it represents revenue contributions after directly associated costs in managing our AUM.
Net commissions
Net commissions are calculated as total commissions, net of commission expenses. Net commissions primarily arise from the purchase and sale of critical materials in our exchange listed products segment.
Net revenues
Net revenues are calculated as the total of: (1) net fees, excluding carried interest and performance fees, net of their related payouts; (2) net commissions; (3) finance income; and (4) co-investment income.
Net compensation & net compensation ratio
Net compensation is calculated as total compensation expense before: (1) commission expenses paid to employees; (2) direct payouts to employees; (3) carried interest and performance fee payouts to employees; (4) severance and new hire accruals; and (5) impact of stock price changes and graded vesting amortization on cash-settled equity plans. Net compensation ratio is calculated as net compensation divided by net revenues.
Total shareholder return
Total shareholder return is the financial gain (loss) that results from a change in the Company's share price, plus any dividends paid over the period.
Liquid co-investments
Liquid co-investments are the Company's co-investments that can be monetized in less than 90 days.
EBITDA, adjusted EBITDA and adjusted EBITDA margin
EBITDA in its most basic form is defined as earnings before interest expense, income taxes, depreciation and amortization. Adjusted EBITDA further adjusts for items noted in the below reconciliation table. Adjusted EBITDA margin is calculated as adjusted EBITDA divided by net revenues.
EBITDA, adjusted EBITDA and adjusted EBITDA margin are measures commonly used in the investment industry by management, investors and investment analysts in understanding and comparing results by factoring out the impact of different financing methods, capital structures, amortization techniques and income tax rates between companies in the same industry. While other companies, investors or investment analysts may not utilize the same method of calculating EBITDA (or adjustments thereto), the Company believes its adjusted EBITDA metric results in a better comparison of the Company's underlying operations against its peers and a better indicator of recurring results from operations as compared to other non-IFRS financial measures. Adjusted EBITDA margin is a key indicator of the Company’s profitability on a per dollar of revenue basis, and as such, is commonly used in the financial services sector by analysts, investors and management.
Neither EBITDA, adjusted EBITDA or adjusted EBITDA margin have a standardized meaning under IFRS. Consequently, they should not be considered in isolation, nor should they be used in substitute for measures of performance prepared in accordance with IFRS.
The following table outlines how our EBITDA, adjusted EBITDA and adjusted EBITDA margin measures are determined:
| | | | | | | | | | | | | | |
| 3 months ended | 9 months ended |
| | | | |
| (In thousands $) | Sep. 30, 2026 | Sep. 30, 2025 | Sep. 30, 2026 | Sep. 30, 2025 |
| Net income for the period | 22,004 | | 13,159 | | 85,479 | | 38,617 | |
Net income margin (1) | 29 | % | 20 | % | 29 | % | 22 | % |
| Adjustments: | | | | |
| Interest expense | 388 | | 261 | | 980 | | 827 | |
| Provision for income taxes | 7,705 | | 4,109 | | 32,399 | | 13,263 | |
| Depreciation and amortization | 799 | | 647 | | 2,161 | | 1,825 | |
| EBITDA | 30,896 | | 18,176 | | 121,019 | | 54,532 | |
| Adjustments: | | | | |
(Gain) loss on investments (2) | (1,711) | | (7,012) | | (3,199) | | (11,249) | |
Stock-based compensation (3) | 16,528 | | 22,374 | | 56,272 | | 47,217 | |
| Foreign exchange (gain) loss | 124 | | (666) | | (1,257) | | 3,151 | |
Severance, new hire accruals and other | 235 | | 111 | | 557 | | 195 | |
| Carried interest and performance fees | (82) | | (1,757) | | (52,115) | | (16,564) | |
| Carried interest and performance fee payouts - internal | 33 | | 690 | | 31,154 | | 1,988 | |
| Carried interest and performance fee payouts - external | — | | — | | 2,247 | | — | |
| Adjusted EBITDA | 46,023 | | 31,916 | | 154,678 | | 79,270 | |
Adjusted EBITDA margin | 69 | % | 65 | % | 71 | % | 62 | % |
(1) Calculated as IFRS net income divided by IFRS total revenue.
(2) This adjustment removes the income effects of gains or losses on short-term investments, co-investments, and private holdings to ensure the reporting objectives of our adjusted EBITDA metric are met.
(3) The movement in the quarter and on a year-to-date basis was primarily due to the Company's "cash-settled" stock-based compensation plan which requires mark-to-market accounting under IFRS 2.
Business overview
Our reportable operating segments are as follows:
For a detailed account of the underlying principal subsidiaries within our reportable operating segments, refer to the Company's Annual Information Form and Note 2 of the annual audited financial statements.
For the nine months ended September 30, 2026
•The Company launched a new critical materials ETF, Sprott Rare Earths Ex-China ETF ("REXC"), an ETF providing focused exposure to rare earths companies outside of China.
•The Sprott Physical Copper Trust began trading on the New York Stock Exchange under the symbol ("SCOP"). Concurrent with the new listing, the trust enhanced its redemption feature which allows for monthly physical redemptions. We expect both developments to broaden the trust's appeal to a wider range of investors.
Results of operations
Summary financial information
| | | | | | | | | | | | | | | | | | | | | | | | | | | |
| (In thousands $) | Q3
2026 | Q2
2026 | Q1
2026 | Q4
2025 | Q3
2025 | Q2
2025 | Q1
2025 | Q4
2024 | |
| | | | | | | | | |
| Management fees | 70,797 | | 76,388 | | 81,538 | | 63,818 | | 50,710 | | 44,446 | | 39,989 | | 41,441 | | |
| Fund expenses | (3,534) | | (4,107) | | (3,452) | | (3,304) | | (2,778) | | (2,699) | | (2,464) | | (2,708) | | |
| Direct payouts | (2,778) | | (3,007) | | (2,987) | | (2,247) | | (1,871) | | (1,709) | | (1,602) | | (1,561) | | |
| Carried interest and performance fees | 82 | | — | | 52,033 | | 38,104 | | 1,757 | | 14,807 | | — | | 2,511 | | |
| Carried interest and performance fee payouts - internal | (33) | | — | | (31,121) | | (15,465) | | (690) | | (1,298) | | — | | (830) | | |
| Carried interest and performance fee payouts - external | — | | — | | (2,247) | | — | | — | | — | | — | | — | | |
| Net fees | 64,534 | | 69,274 | | 93,764 | | 80,906 | | 47,128 | | 53,547 | | 35,923 | | 38,853 | | |
| | | | | | | | | |
| Commissions | 470 | | 1,456 | | 5,822 | | 2,655 | | 3,816 | | 1,725 | | 286 | | 819 | | |
| Commission expense - internal | (31) | | (65) | | (71) | | (275) | | (329) | | (180) | | (52) | | (146) | | |
Commission expense - external | (108) | | (652) | | (2,791) | | (1,143) | | (1,801) | | (779) | | (47) | | (290) | | |
| Net commissions | 331 | | 739 | | 2,960 | | 1,237 | | 1,686 | | 766 | | 187 | | 383 | | |
| | | | | | | | | |
| Finance income | 1,902 | | 1,634 | | 2,481 | | 2,464 | | 1,583 | | 1,213 | | 1,402 | | 1,441 | | |
| Co-investment income | 160 | | 129 | | 205 | | 198 | | 234 | | 280 | | 151 | | 296 | | |
| Less: Carried interest and performance fees (net of payouts) | (49) | | — | | (18,665) | | (22,639) | | (1,067) | | (13,509) | | — | | (1,681) | | |
Total net revenues (1) | 66,878 | | 71,776 | | 80,745 | | 62,166 | | 49,564 | | 42,297 | | 37,663 | | 39,292 | | |
| Add: Carried interest and performance fees | 82 | | — | | 52,033 | | 38,104 | | 1,757 | | 14,807 | | — | | 2,511 | | |
| Gain (loss) on investments | 1,711 | | 615 | | 873 | | 4,195 | | 7,012 | | 2,703 | | 1,534 | | (3,889) | | |
| Fund expenses | 3,534 | | 4,107 | | 3,452 | | 3,304 | | 2,778 | | 2,699 | | 2,464 | | 2,708 | | |
| Direct payouts | 2,778 | | 3,007 | | 2,987 | | 2,247 | | 1,871 | | 1,709 | | 1,602 | | 1,561 | | |
| Commission expense - internal/external | 139 | | 717 | | 2,862 | | 1,418 | | 2,130 | | 959 | | 99 | | 436 | | |
| Total revenues | 75,122 | | 80,222 | | 142,952 | | 111,434 | | 65,112 | | 65,174 | | 43,362 | | 42,619 | | |
| | | | | | | | | |
| Compensation | 34,784 | | 24,157 | | 86,071 | | 61,329 | | 38,550 | | 33,825 | | 19,597 | | 19,672 | | |
| Direct payouts | (2,778) | | (3,007) | | (2,987) | | (2,247) | | (1,871) | | (1,709) | | (1,602) | | (1,561) | | |
| Carried interest and performance fee payouts - internal | (33) | | — | | (31,121) | | (15,465) | | (690) | | (1,298) | | — | | (830) | | |
| Commission expense - internal | (31) | | (65) | | (71) | | (275) | | (329) | | (180) | | (52) | | (146) | | |
| Severance, new hire accruals and other | (235) | | (153) | | (169) | | (125) | | (111) | | (32) | | (52) | | (166) | | |
Impact of stock price changes and graded vesting amortization on cash-settled equity plans (2) | (9,656) | | 1,756 | | (27,988) | | (22,351) | | (16,598) | | (12,758) | | (412) | | 71 | | |
| Net compensation | 22,051 | | 22,688 | | 23,735 | | 20,866 | | 18,951 | | 17,848 | | 17,479 | | 17,040 | | |
| Net compensation ratio | 33 | % | 32 | % | 29 | % | 34 | % | 39 | % | 43 | % | 47 | % | 44 | % | |
| | | | | | | | | |
| Direct payouts | 2,778 | | 3,007 | | 2,987 | | 2,247 | | 1,871 | | 1,709 | | 1,602 | | 1,561 | | |
| Carried interest and performance fee payouts - internal | 33 | | — | | 31,121 | | 15,465 | | 690 | | 1,298 | | — | | 830 | | |
| Commission expense - internal | 31 | | 65 | | 71 | | 275 | | 329 | | 180 | | 52 | | 146 | | |
Severance, new hire accruals and other | 235 | | 153 | | 169 | | 125 | | 111 | | 32 | | 52 | | 166 | | |
Impact of stock price changes and graded vesting amortization on cash-settled equity plans (2) | 9,656 | | (1,756) | | 27,988 | | 22,351 | | 16,598 | | 12,758 | | 412 | | (71) | | |
Fund expenses (3) | 3,534 | | 4,107 | | 3,452 | | 3,304 | | 2,778 | | 2,699 | | 2,464 | | 2,708 | | |
Carried interest and performance fee payouts - external (3) | — | | — | | 2,247 | | — | | — | | — | | — | | — | | |
Commission expense - external (3) | 108 | | 652 | | 2,791 | | 1,143 | | 1,801 | | 779 | | 47 | | 290 | | |
| Selling, general, and administrative ("SG&A") | 5,676 | | 5,093 | | 5,862 | | 5,053 | | 4,473 | | 4,825 | | 4,127 | | 4,949 | | |
| Interest expense | 388 | | 291 | | 301 | | 395 | | 261 | | 286 | | 280 | | 613 | | |
| Depreciation and amortization | 799 | | 673 | | 689 | | 652 | | 647 | | 637 | | 541 | | 600 | | |
| Foreign exchange (gain) loss | 124 | | (980) | | (401) | | 1,080 | | (666) | | 3,263 | | 554 | | (2,706) | | |
| | | | | | | | | |
| Total expenses | 45,413 | | 33,993 | | 101,012 | | 72,956 | | 47,844 | | 46,314 | | 27,610 | | 26,126 | | |
| Net income | 22,004 | | 34,257 | | 29,218 | | 28,728 | | 13,159 | | 13,501 | | 11,957 | | 11,680 | | |
| Net income per share | 0.86 | | 1.33 | | 1.13 | | 1.11 | | 0.51 | | 0.52 | | 0.46 | | 0.46 | | |
| Adjusted EBITDA | 46,023 | | 50,765 | | 57,890 | | 42,130 | | 31,916 | | 25,453 | | 21,901 | | 22,362 | | |
| Adjusted EBITDA per share | 1.79 | | 1.97 | | 2.25 | | 1.63 | | 1.24 | | 0.99 | | 0.85 | | 0.88 | | |
| Total assets | 551,712 | | 515,758 | | 504,271 | | 525,779 | | 466,169 | | 439,429 | | 386,131 | | 388,798 | | |
| Total liabilities | 151,084 | | 123,575 | | 124,225 | | 158,534 | | 121,441 | | 93,955 | | 59,986 | | 65,150 | | |
| | | | | | | | | |
| Total AUM | 57,320,822 | | 55,562,022 | | 65,071,077 | | 59,605,519 | | 49,088,162 | | 40,040,822 | | 35,076,761 | | 31,535,062 | | |
| Average AUM | 58,805,685 | | 63,896,900 | | 69,316,718 | | 53,216,229 | | 42,346,242 | | 37,580,867 | | 33,265,327 | | 33,401,157 | | |
| | | | | | | | | |
| | | | | | | | | |
| | | | | | | | | |
| | | | | | | | | |
| | | | | | | | | |
| | | | | | | | | |
| | | | | | | | | |
| | | | | | | | | |
(1) Prior period net revenues include revenues from non-reportable segments: Q4 2024 - $406 and fund expense recoveries: Q4 2025 - $469; Q3 2025 - $386; Q2 2025 - $327; Q1 2025 - $279; and Q4 2024 - $280.
(2) The movement in the quarter and on a year-to-date basis was primarily due to the Company's "cash-settled" stock-based compensation plan which requires mark-to-market accounting under IFRS 2.
(3) Together, fund expenses, carried interest and performance fee payouts - external and commission expense - external are included in "Fund expenses" on the income statement.
AUM summary
AUM was $57.3 billion as at September 30, 2026, up 3% from $55.6 billion as at June 30, 2026 and down 4% from $59.6 billion as at December 31, 2025. On a three months ended basis, our AUM was positively impacted by market value appreciation across a majority of our fund products. On a nine months ended basis, our AUM was negatively impacted by market value depreciation and net outflows from our precious metals products, partially offset by positive net inflows to our critical materials products. Average AUM was $58.8 billion for the quarter, up $16.5 billion or 39% from $42.3 billion for the quarter ended September 30, 2025, and $64 billion on a year-to-date basis, up $26.3 billion or 70% from $37.7 billion for the nine months ended September 30, 2025. On a three and nine months ended basis, our average AUM was positively impacted by a combination of net inflows and market value appreciation across a majority of our fund products since the third quarter of last year, which more than offset the impact of year-to-date pullbacks in precious metals valuations. Subsequent to quarter-end, as at October 30, 2026, AUM was $52.1 billion, down 9% from $57.3 billion as at September 30, 2026.
| | | | | | | | | | | | | | | | | | | | | | | |
| 3 months results | | | | | | | |
| | | | | | | |
| (In millions $) | AUM
Jun. 30, 2026 | Net
inflows | Market
value changes | Other net inflows | AUM Sep. 30, 2026 | | Net management fee rate (1) |
| | | | | | | |
| Exchange listed products | | | | | | | |
| - Precious metals physical trusts and ETFs | | | | | | |
| - Physical Gold Trust | 14,749 | 381 | 506 | — | 15,636 | | 0.35% |
| - Physical Silver Trust | 12,642 | (542) | 426 | — | 12,526 | | 0.45% |
| - Physical Gold and Silver Trust | 7,332 | (208) | 245 | — | 7,369 | | 0.40% |
| - Precious Metals ETFs | 1,473 | 17 | 202 | — | 1,692 | | 0.39% |
| - Physical Platinum & Palladium Trust | 543 | (47) | 35 | — | 531 | | 0.50% |
| 36,739 | (399) | 1,414 | — | 37,754 | | 0.40% |
| | | | | | | |
| - Critical materials physical trusts and ETFs | | | | | | |
| - Physical Uranium Trust | 7,044 | — | 360 | — | 7,404 | | 0.31% |
| - Critical Materials ETFs | 3,960 | 236 | (299) | — | 3,897 | | 0.57% |
| - Physical Copper Trust | 203 | (4) | 16 | — | 215 | | 0.33% |
| 11,207 | 232 | 77 | — | 11,516 | | 0.41% |
| | | | | | | |
| Total exchange listed products | 47,946 | (167) | 1,491 | — | 49,270 | | 0.40% |
| | | | | | | |
Managed equities (2) | 5,619 | (37) | 460 | — | 6,042 | | 0.80% |
| | | | | | | |
| Private strategies | 1,997 | (3) | 15 | — | 2,009 | | 0.75% |
| | | | | | | |
Total AUM | 55,562 | (207) | 1,966 | — | 57,321 | | 0.45% |
| | | | | | | |
| | | | | | | |
9 months results | | | | | | | |
| | | | | | | |
| (In millions $) | AUM
Dec. 31, 2025 | Net
inflows | Market
value changes | Other
net inflows | AUM Sep. 30, 2026 | | Net management fee rate (1) |
| | | | | | | |
| Exchange listed products | | | | | | | |
| - Precious metals physical trusts and ETFs | | | | | | |
| - Physical Gold Trust | 15,976 | 295 | (635) | — | 15,636 | | 0.35% |
| - Physical Silver Trust | 15,109 | (51) | (2,532) | — | 12,526 | | 0.45% |
| - Physical Gold and Silver Trust | 9,065 | (1,008) | (688) | — | 7,369 | | 0.40% |
| - Precious Metals ETFs | 1,654 | 45 | (7) | — | 1,692 | | 0.39% |
| - Physical Platinum & Palladium Trust | 773 | (86) | (156) | — | 531 | | 0.50% |
| 42,577 | (805) | (4,018) | — | 37,754 | | 0.40% |
| | | | | | | |
| - Critical materials physical trusts and ETFs | | | | | | |
| - Physical Uranium Trust | 6,158 | 703 | 543 | — | 7,404 | | 0.31% |
| - Critical Materials ETFs | 2,950 | 1,572 | (625) | — | 3,897 | | 0.57% |
| - Physical Copper Trust | 131 | 60 | 24 | — | 215 | | 0.33% |
| 9,239 | 2,335 | (58) | — | 11,516 | | 0.41% |
| | | | | | | |
| Total exchange listed products | 51,816 | 1,530 | (4,076) | — | 49,270 | | 0.40% |
| | | | | | | |
Managed equities (2) | 5,656 | (212) | 598 | — | 6,042 | | 0.80% |
| | | | | | | |
| Private strategies | 2,134 | (188) | 63 | — | 2,009 | | 0.75% |
| | | | | | | |
Total AUM | 59,606 | 1,130 | (3,415) | — | 57,321 | | 0.45% |
(1) Net management fee rate represents the weighted average fees for all funds in the category, net of fund expenses. |
(2) Managed equities is made up of funds and high net worth managed accounts invested primarily in precious metals strategies (95%) and U.S. value strategies (5%). |
Key revenue lines Key expense lines
Management, carried interest and performance fees
Management fees were $70.8 million for the quarter, up $20.1 million or 40% from $50.7 million for the quarter ended September 30, 2025, and $228.7 million on a year-to-date basis, up $93.6 million or 69% from $135.1 million for the nine months ended September 30, 2025. Carried interest and performance fees were $0.1 million for the quarter, down $1.7 million or 95% from $1.8 million for the quarter ended September 30, 2025, and $52.1 million on a year-to-date basis, up $35.6 million from $16.6 million for the nine months ended September 30, 2025. Net fees were $64.5 million for the quarter, up $17.4 million or 37% from $47.1 million for the quarter ended September 30, 2025, and $227.6 million on a year-to-date basis, up $91 million or 67% from $136.6 million for the nine months ended September 30, 2025. Our revenue performance in the quarter and on a nine months ended basis was primarily due to an increase in average AUM attributable to a combination of net inflows and market value appreciation across a majority of our fund products since the end of the third quarter of last year, which more than offset the impact of year-to-date pullbacks in precious metals valuations that commenced in the second quarter of this year. Additionally, we benefited from carried interest crystallization in our private strategies segment in the first quarter.
Commission revenues
Commission revenues were $0.5 million for the quarter, down $3.3 million or 88% from $3.8 million for the quarter ended September 30, 2025 and $7.7 million on a year-to-date basis, up $1.9 million or 33% from $5.8 million for the nine months ended September 30, 2025. Net commissions were $0.3 million for the quarter, down $1.4 million or 80% from $1.7 million for the quarter ended September 30, 2025 and $4 million on a year-to-date basis, up $1.4 million or 53% from $2.6 million for the nine months ended September 30, 2025. The decrease in the quarter was due to lower ATM activity in our physical uranium trust and the increase on a nine months ended basis was due to higher ATM activity, primarily in our physical uranium trust, and to a lesser extent, in our physical copper trust.
Finance income
Finance income was $1.9 million for the quarter, up $0.3 million or 20% from $1.6 million for the quarter ended September 30, 2025 and $6 million on a year-to-date basis, up $1.8 million or 43% from $4.2 million for the nine months ended September 30, 2025. The increase in the quarter and on a nine months ended basis was primarily due to increased interest income on higher cash balances.
Compensation
Net compensation expense was $22.1 million for the quarter, up $3.1 million or 16% from $19 million for the quarter ended September 30, 2025 and $68.5 million on a year-to-date basis, up $14.2 million or 26% from $54.3 million for the nine months ended September 30, 2025. The increase in the quarter and on a nine months ended basis was primarily due to higher incentive compensation on increased net fee generation. Our net compensation ratio was 33% in the quarter (September 30, 2025 - 39%) and 31% on a year-to-date basis (September 30, 2025 - 42%).
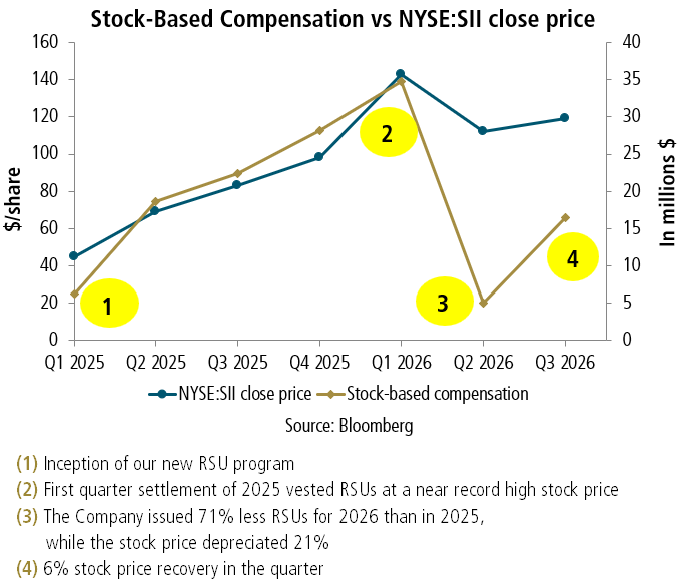
Stock-based compensation expense was $16.5 million for the quarter, down $5.8 million or 26% from $22.4 million for the quarter ended September 30, 2025 and $56.3 million on a year-to-date basis, up $9.1 million or 19% from $47.2 million for the nine months ended September 30, 2025. The decrease in the quarter was due to a lower mark-to-market taken on our cash-settled restricted stock units ("RSUs"), as our stock price appreciated 6% during the quarter, whereas this same time last year the mark appreciated 20%. On a year-to-date basis, the increase was primarily due to the settlement of a portion of the 2025 stock grant in the first quarter of 2026, at a time when the stock price reached near record highs ($142.90/share). Since inception of our RSU program in 2025, stock-based compensation expense has moved in line with the Company's stock price, while the magnitude of the expense has dropped significantly since Q2, 2026 due to the Company issuing 71% less RSUs this year than in 2025. See the illustration below:
SG&A
SG&A expense was $5.7 million for the quarter, up $1.2 million or 27% from $4.5 million for the quarter ended September 30, 2025 and $16.6 million on a year-to-date basis, up $3.2 million or 24% from $13.4 million for the nine months ended September 30, 2025. The increase in the quarter and on a nine months ended basis was due to higher marketing and professional services costs.
Earnings
Net income for the quarter was $22 million ($0.86 per share), up $8.8 million or 67% from $13.2 million ($0.51 per share) for the quarter ended September 30, 2025 and $85.5 million ($3.32 per share) on a year-to-date basis, up $46.9 million from $38.6 million ($1.50 per share) for the nine months ended September 30, 2025. Our net income performance was primarily due to higher average AUM in our exchange listed products and managed equities segments, as well as carried interest crystallization in our private strategies segment in the first quarter.
Adjusted EBITDA was $46 million ($1.79 per share) for the quarter, up $14.1 million or 44% from $31.9 million ($1.24 per share) for the quarter ended September 30, 2025 and $154.7 million ($6.01 per share) on a year-to-date basis, up $75.4 million or 95% from $79.3 million ($3.07 per share) for the nine months ended September 30, 2025. Our Adjusted EBITDA increased in the quarter and on a nine months ended basis due to higher average AUM, attributable to a combination of net inflows and market value appreciation across a majority of our fund products since the third quarter of last year, which more than offset the impact of year-to-date pullbacks in precious metals valuations.
Additional revenues and expenses
Investment gains were $1.7 million for the quarter, down $5.3 million or 76% from investment gains of $7 million for the quarter ended September 30, 2025 and $3.2 million on a year-to-date basis, down $8.1 million or 72% from $11.2 million for the nine months ended September 30, 2025. Investment gains in the quarter and on a nine months ended basis were mainly driven by market value appreciation of our co-investments.
Depreciation of property and equipment was $0.8 million for the quarter, up $0.2 million or 23% from $0.6 million for the quarter ended September 30, 2025 and $2.2 million on a year-to-date basis, up $0.3 million or 18% from $1.8 million for the nine months ended September 30, 2025. The increase in the quarter and on a nine months ended basis was due to depreciation of leasehold improvements.
Balance sheet
Total assets were $551.7 million, up $25.9 million or 5% from $525.8 million as at December 31, 2025. The increase was primarily from higher cash balances from increased earnings. Total liabilities were $151.1 million, down $7.5 million or 5% from $158.5 million as at December 31, 2025. The decrease was primarily due to lower compensation payable. Total shareholders' equity was $400.6 million, up $33.4 million or 9% from $367.2 million as at December 31, 2025.
Reportable operating segments
Exchange listed products
| | | | | | | | | | | | | | |
| | | | |
| 3 months ended | 9 months ended |
| | | | |
| (In thousands $) | Sep. 30, 2026 | Sep. 30, 2025 | Sep. 30, 2026 | Sep. 30, 2025 |
| | | | |
| Management fees | 54,241 | | 37,248 | | 176,731 | | 97,634 | |
| Fund expenses | (2,700) | | (2,066) | | (8,433) | | (5,937) | |
| Net fees | 51,541 | | 35,182 | | 168,298 | | 91,697 | |
| | | | |
| Commissions | 216 | | 3,476 | | 6,997 | | 4,895 | |
| Commission expense - internal | — | | (231) | | — | | (336) | |
| Commission expense - external | (108) | | (1,735) | | (3,483) | | (2,456) | |
| Net commissions | 108 | | 1,510 | | 3,514 | | 2,103 | |
| | | | |
| | | | |
| Total net revenues | 51,649 | | 36,692 | | 171,812 | | 93,800 | |
| Gain (loss) on investments | 721 | | 1,997 | | 563 | | 3,101 | |
| Fund expenses | 2,700 | | 2,066 | | 8,433 | | 5,937 | |
| Commission expense - internal | — | | 231 | | — | | 336 | |
| Commission expense - external | 108 | | 1,735 | | 3,483 | | 2,456 | |
| Total revenues | 55,178 | | 42,721 | | 184,291 | | 105,630 | |
| | | | |
| Net compensation | 7,375 | | 5,806 | | 23,096 | | 15,869 | |
| Commission expense - internal | — | | 231 | | — | | 336 | |
| | | | |
| Impact of stock price changes and graded vesting amortization on cash-settled equity plans | 2,617 | | 4,254 | | 9,316 | | 7,399 | |
| Fund expenses | 2,700 | | 2,066 | | 8,433 | | 5,937 | |
| Commission expense - external | 108 | | 1,735 | | 3,483 | | 2,456 | |
| SG&A | 2,690 | | 1,865 | | 7,649 | | 5,442 | |
| Interest expense | 64 | | — | | 158 | | 92 | |
| Depreciation and amortization | 142 | | 36 | | 215 | | 105 | |
| Foreign exchange (gain) loss | 72 | | (695) | | (2,576) | | 2,086 | |
| | | | |
| Total expenses | 15,768 | | 15,298 | | 49,774 | | 39,722 | |
| | | | |
| | | | |
| Income before income taxes | 39,410 | | 27,423 | | 134,517 | | 65,908 | |
| Adjusted EBITDA | 43,524 | | 30,549 | | 146,746 | | 77,085 | |
Adjusted EBITDA margin | 84 | % | 83 | % | 85 | % | 82 | % |
| | | | |
| Total AUM | 49,270,394 | | 41,778,504 | | 49,270,394 | | 41,778,504 | |
| Average AUM | 50,811,626 | | 35,875,523 | | 55,803,406 | | 31,817,453 | |
| | | | |
3 and 9 months ended
Income before income taxes was $39.4 million for the quarter, up $12 million or 44% from $27.4 million for the quarter ended September 30, 2025, and was $134.5 million on a year-to-date basis, up $68.6 million from $65.9 million for the nine months ended September 30, 2025. Adjusted EBITDA was $43.5 million for the quarter, up $13 million or 42% from $30.5 million for the quarter ended September 30, 2025, and was $146.7 million on a year-to-date basis, up $69.7 million or 90% from $77.1 million for the nine months ended September 30, 2025. Our three and nine months ended results benefited from higher average AUM in our physical trusts and ETFs.
| | | | | | | | | | | | | | |
| | | | |
| 3 months ended | 9 months ended |
| | | | |
| (In thousands $) | Sep. 30, 2026 | Sep. 30, 2025 | Sep. 30, 2026 | Sep. 30, 2025 |
| | | | |
| Management fees | 13,030 | | 9,373 | | 40,784 | | 24,860 | |
| Fund expenses | (766) | | (625) | | (2,449) | | (1,741) | |
| Direct payouts | (2,447) | | (1,504) | | (7,644) | | (3,984) | |
| Carried interest and performance fees | 82 | | 1,757 | | 337 | | 16,556 | |
| Carried interest and performance fee payouts - internal | (33) | | (690) | | (153) | | (1,986) | |
| Net fees | 9,866 | | 8,311 | | 30,875 | | 33,705 | |
| | | | |
| Finance income | 86 | | 58 | | 498 | | 161 | |
| | | | |
| Less: Carried interest and performance fees (net of payouts) | (49) | | (1,067) | | (184) | | (14,570) | |
Total net revenues (1) | 9,903 | | 7,302 | | 31,189 | | 19,296 | |
| Add: Carried interest and performance fees | 82 | | 1,757 | | 337 | | 16,556 | |
| Gain (loss) on investments | 1,149 | | 4,173 | | 1,799 | | 7,782 | |
| Fund expenses | 766 | | 625 | | 2,449 | | 1,741 | |
| Direct payouts | 2,447 | | 1,504 | | 7,644 | | 3,984 | |
| Total revenues | 14,347 | | 15,361 | | 43,418 | | 49,359 | |
| | | | |
| Net compensation | 4,051 | | 4,064 | | 12,552 | | 11,459 | |
| Direct payouts | 2,447 | | 1,504 | | 7,644 | | 3,984 | |
| Carried interest and performance fee payouts - internal | 33 | | 690 | | 153 | | 1,986 | |
| Severance, new hire accruals and other | 156 | | 111 | | 478 | | 193 | |
| Impact of stock price changes and graded vesting amortization on cash-settled equity plans | 730 | | 2,191 | | 3,299 | | 3,820 | |
| Fund expenses | 766 | | 625 | | 2,449 | | 1,741 | |
| SG&A | 1,226 | | 1,139 | | 3,910 | | 3,085 | |
| Interest expense | 64 | | 16 | | 187 | | 145 | |
| Depreciation and amortization | 139 | | 99 | | 346 | | 295 | |
| Foreign exchange (gain) loss | 83 | | (464) | | (2,165) | | 1,536 | |
| Total expenses | 9,695 | | 9,975 | | 28,853 | | 28,244 | |
| | | | |
| Income before income taxes | 4,652 | | 5,386 | | 14,565 | | 21,115 | |
| Adjusted EBITDA | 5,128 | | 2,911 | | 16,279 | | 7,186 | |
Adjusted EBITDA margin | 52 | % | 42 | % | 52 | % | 39 | % |
| | | | |
| Total AUM | 6,041,880 | | 5,171,187 | | 6,041,880 | | 5,171,187 | |
| Average AUM | 5,994,219 | | 4,335,539 | | 6,172,253 | | 3,725,598 | |
| | | | |
(1) Prior period net revenues include fund expense recoveries of $386 in the quarter and $992 on a year-to-date basis.
3 and 9 months ended
Income before income taxes was $4.7 million for the quarter, down $0.7 million or 14% from $5.4 million for the quarter ended September 30, 2025 and was $14.6 million on a year-to-date basis, down $6.6 million or 31% from $21.1 million for the nine months ended September 30, 2025. Our earnings were lower in the quarter and on a nine months ended basis due to lower carried interest crystallization.
Adjusted EBITDA was $5.1 million for the quarter, up $2.2 million or 76% from $2.9 million for the quarter ended September 30, 2025 and was $16.3 million on a year-to-date basis, up $9.1 million from $7.2 million for the nine months ended September 30, 2025. Our three and nine months ended results benefited from higher average AUM on market value appreciation across the majority of our fund products.
Private strategies
| | | | | | | | | | | | | | |
| | | | |
| 3 months ended | 9 months ended |
| | | | |
| (In thousands $) | Sep. 30, 2026 | Sep. 30, 2025 | Sep. 30, 2026 | Sep. 30, 2025 |
| | | | |
| Management fees | 3,688 | | 4,323 | | 11,704 | | 13,316 | |
| Fund expenses | (68) | | (87) | | (211) | | (263) | |
| Direct payouts | (331) | | (367) | | (1,128) | | (1,198) | |
| Carried interest and performance fees | — | | — | | 51,778 | | 8 | |
| Carried interest and performance fee payouts - internal | — | | — | | (31,001) | | (2) | |
| Carried interest and performance fee payouts - external | — | | — | | (2,247) | | — | |
| Net fees | 3,289 | | 3,869 | | 28,895 | | 11,861 | |
| | | | |
| Finance income | 672 | | 921 | | 2,846 | | 2,679 | |
| Less: Carried interest and performance fees (net of payouts) | — | | — | | (18,530) | | (6) | |
| Total net revenues | 3,961 | | 4,790 | | 13,211 | | 14,534 | |
| Add: Carried interest and performance fees | — | | — | | 51,778 | | 8 | |
| Gain (loss) on investments | (219) | | 1,001 | | 1,042 | | 1,408 | |
| Fund expenses | 68 | | 87 | | 211 | | 263 | |
| Direct payouts | 331 | | 367 | | 1,128 | | 1,198 | |
| Total revenues | 4,141 | | 6,245 | | 67,370 | | 17,411 | |
| | | | |
| Net compensation | 1,888 | | 2,068 | | 6,341 | | 6,450 | |
| Direct payouts | 331 | | 367 | | 1,128 | | 1,198 | |
| Carried interest and performance fee payouts - internal | — | | — | | 31,001 | | 2 | |
| | | | |
| Impact of stock price changes and graded vesting amortization on cash-settled equity plans | 361 | | — | | 385 | | — | |
| Fund expenses | 68 | | 87 | | 211 | | 263 | |
| Carried interest and performance fee payouts - external | — | | — | | 2,247 | | — | |
| SG&A | 404 | | 490 | | 1,203 | | 1,322 | |
| Interest expense | 1 | | 1 | | 3 | | 4 | |
| Depreciation and amortization | 14 | | 13 | | 41 | | 38 | |
| Foreign exchange (gain) loss | 336 | | (995) | | (1,082) | | 1,734 | |
| Total expenses | 3,403 | | 2,031 | | 41,478 | | 11,011 | |
| | | | |
| | | | |
| Income before income taxes | 738 | | 4,214 | | 25,892 | | 6,400 | |
| Adjusted EBITDA | 1,945 | | 2,232 | | 6,436 | | 6,776 | |
Adjusted EBITDA margin | 49 | % | 47 | % | 49 | % | 47 | % |
| | | | |
| Total AUM | 2,008,548 | | 2,138,471 | | 2,008,548 | | 2,138,471 | |
| Average AUM | 1,999,840 | | 2,135,180 | | 2,044,466 | | 2,206,421 | |
3 and 9 months ended
Income before income taxes was $0.7 million for the quarter, down $3.5 million or 82% from $4.2 million for the quarter ended September 30, 2025 and was $25.9 million on a year-to-date basis, up $19.5 million from $6.4 million for the nine months ended September 30, 2025. Our three months ended results were impacted by lower management fees, foreign exchange losses and market value depreciation of our co-investments. Our nine months ended results benefited from carried interest crystallization in our lending fund during the first quarter.
Adjusted EBITDA was $1.9 million for the quarter, down $0.3 million or 13% from $2.2 million for the quarter ended September 30, 2025 and was $6.4 million on a year-to-date basis, down $0.3 million or 5% from $6.8 million for the nine months ended September 30, 2025. Our three and nine months ended results were impacted by lower management fees due to lower average AUM.
This segment is a cost center that provides capital, balance sheet management and shared services to the Company's subsidiaries.
| | | | | | | | | | | | | | |
| | | | |
| 3 months ended | 9 months ended |
| | | | |
| (In thousands $) | Sep. 30, 2026 | Sep. 30, 2025 | Sep. 30, 2026 | Sep. 30, 2025 |
| | | | |
| Gain (loss) on investments | 17 | | 13 | | 29 | | 22 | |
| Finance income | 1,100 | | 516 | | 2,498 | | 1,106 | |
| Total revenues | 1,117 | | 529 | | 2,527 | | 1,128 | |
| | | | |
| Net compensation | 8,737 | | 6,873 | | 26,485 | | 19,871 | |
| Impact of stock price changes and graded vesting amortization on cash-settled equity plans | 5,948 | | 10,153 | | 22,888 | | 18,549 | |
| Severance, new hire accruals and other | 79 | | — | | 79 | | — | |
| SG&A | 1,257 | | 887 | | 3,568 | | 3,148 | |
| Interest expense | 259 | | 244 | | 632 | | 586 | |
| Depreciation and amortization | 500 | | 497 | | 1,551 | | 1,379 | |
| Foreign exchange (gain) loss | (473) | | 1,415 | | 4,733 | | (2,242) | |
| Total expenses | 16,307 | | 20,069 | | 59,936 | | 41,291 | |
| | | | |
| | | | |
| Income (loss) before income taxes | (15,190) | | (19,540) | | (57,409) | | (40,163) | |
| Adjusted EBITDA | (4,740) | | (3,808) | | (15,171) | | (11,502) | |
3 and 9 months ended
•Net compensation increased primarily due to higher incentive compensation on increased net fee generation.
•Market value of stock-based compensation expense was lower in the quarter and higher on a nine months ended basis. The decrease in the quarter was due to a lower mark-to-market taken on our RSUs, as our stock price appreciated 6% during the quarter, whereas this same time last year the mark appreciated 20%. On a year-to-date basis, the increase was primarily due to the settlement of a portion of the 2025 stock grant in the first quarter of 2026, at a time when the stock price reached near record highs ($142.90/share). Since inception of our RSU program in 2025, stock-based compensation expense has moved in line with the Company's stock price, while the magnitude of the expense has dropped significantly since Q2, 2026 due to the Company issuing 71% less RSUs this year than in 2025.
•SG&A was up for the quarter and on a year-to-date basis, primarily due to an increase in professional services and marketing costs.
Dividends
The following dividends were declared by the Company during the nine months ended September 30, 2026:
| | | | | | | | | | | | |
| Record date | Payment date | Cash dividend
per share | Total dividend amount (in thousands $) | |
| | | | |
| August 17, 2026 - Regular dividend Q2 2026 | September 1, 2026 | $0.40 | 10,282 | | |
| May 19, 2026 - Regular dividend Q1 2026 | June 3, 2026 | $0.40 | 10,310 | | |
| March 2, 2026 - Regular dividend Q4 2025 | March 17, 2026 | $0.40 | 10,315 | | |
Dividends declared in 2026 (1) | | | 30,907 | | |
| | | | |
| | | | |
| | | | |
| | | | |
| | | | |
| | | | |
| | | | |
| | | | |
| | | | |
| | | | |
| | | | |
| | | | |
| | | | |
| | | | |
| | | | |
| | | | |
| | | | |
| | | | |
| | | | |
| | | | |
| | | | |
| | | | |
| | | | |
| | | | |
| | | | |
| | | | |
| | | | |
| | | | |
| | | | |
| | | | |
(1) Subsequent to quarter-end, on November 3, 2026, a regular dividend of $0.50 per common share was declared for the quarter ended September 30, 2026. This dividend is payable on December 1, 2026 to shareholders of record at the close of business on November 16, 2026.
Capital stock
Total capital stock issued and outstanding was 25.7 million (December 31, 2025 - 25.8 million). The decrease on a year-to-date basis was due to the Company's repurchase and cancellation of 84,056 shares under its normal course issuer bid.
Earnings per share for the current and prior period have been calculated using the weighted average number of shares outstanding during the respective periods. Basic earnings per share was $0.86 for the quarter and $3.32 on a year-to-date basis compared to $0.51 and $1.50 in the prior periods, respectively. Diluted earnings per share was $0.86 for the quarter and $3.32 on a year-to-date basis compared to $0.51 and $1.50 in the prior periods, respectively.
As at September 30, 2026, no stock options are outstanding (December 31, 2025 - 12,500).
Liquidity and capital resources
As at September 30, 2026, the Company had $202.1 million (December 31, 2025 - $123.4 million) of cash and cash equivalents. In addition, the Company had $78.5 million of co-investments (December 31, 2025 - $76.7 million) of which $29.1 million (December 31, 2025 - $35.5 million) can be monetized in less than 90 days (liquid co-investments).
As at September 30, 2026, the Company had $nil (December 31, 2025 - $nil) outstanding on its credit facility, which matures on August 8, 2028. As at September 30, 2026, the Company was in compliance with all covenants, terms and conditions under the credit facility.
The Company has access to a credit facility of $75 million with a major Canadian schedule I chartered bank. Amounts under the facility may be borrowed in U.S. dollars through SOFR or base rate loans. Amounts may also be borrowed in Canadian dollars through prime rate loans or CORRA loans.
Key terms under the current credit facility are noted below:
Structure
•5-year, $75 million revolver with "bullet maturity" on August 8, 2028
Interest rate
•SOFR + 2.36%
Covenant terms
•Minimum AUM: $11.7 billion;
•Debt to EBITDA less than or equal to 2.5:1; and
•EBITDA to interest expense more than or equal to 2.5:1
Commitments
The Company has commitments to make co-investments in private strategies LPs or commitments to make co-investments in fund strategies in the Company's other segments. As at September 30, 2026, the Company had $1.5 million in co-investment commitments in private strategies LPs due within one year (December 31, 2025 - $3 million) and $2.9 million due after 12 months (December 31, 2025 - $nil).
Critical accounting estimates and significant judgments
The key assumptions concerning the future and other key sources of estimation uncertainty at the reporting date that have a significant risk of causing a material adjustment to the carrying amounts of assets and liabilities are described below. The Company based its assumptions and estimates on parameters available when the financial statements were prepared. Existing circumstances and assumptions about future developments may change due to market changes or circumstances arising beyond the control of the Company. Such changes are reflected in the assumptions and estimates as they occur. The Company’s material accounting policy information is described in Note 2 of the December 31, 2025 annual audited financial statements. Certain of these accounting policies require management to make key assumptions concerning the future and consider other sources of estimation uncertainty at the reporting date. These accounting estimates are considered critical because they require subjective and/or complex judgments that may have a material impact on the value of our assets, liabilities, revenues and expenses.
Critical accounting estimates
Impairment of goodwill and intangible assets
All indefinite life intangible assets and goodwill are reviewed for impairment quarterly and tested for impairment annually. Values associated with goodwill and intangibles involve estimates and assumptions, including those with respect to future cash inflows and outflows, discount rates, AUM and asset lives. These estimates require significant judgment regarding market growth rates and fund flow assumptions, which could affect the Company's future results if estimates of future performance and fair value change.
Significant judgments
Investments in other entities
IFRS 10 Consolidated Financial Statements ("IFRS 10") and IAS 28 Investments in Associates and Joint Ventures ("IAS 28") provide for the use of judgment in determining whether an investee should be included within the consolidated financial statements of the Company and on what basis (subsidiary, joint venture, financial instrument or associate). Significant judgment is applied in evaluating facts and circumstances relevant to the Company and investee, including: (1) the extent of the Company's direct and indirect interest in the investee; (2) the level of compensation to be received from the investee for management and other services provided to it; (3) "kick out rights" available to other investors in the investee; and (4) other indicators of the extent of power that the Company has over the investee.
Fair value of financial instruments
When the fair value of financial assets and financial liabilities recorded in the consolidated balance sheets cannot be derived from active markets, they are determined using valuation techniques and models. Model inputs are taken from observable markets where possible, but where this is not feasible, unobservable inputs may be used. These unobservable inputs include, but are not limited to, projected cash flows, discount rates, comparable recent transactions and volatility of underlying securities in warrant valuations. The use of unobservable inputs can involve significant judgment and materially affect the reported fair value of financial instruments.
Managing financial risks
Market risk
The Company separates market risk into three categories: price risk, interest rate risk and foreign currency risk.
Price risk
Price risk arises from the possibility that changes in the price of the Company's on and off-balance sheet assets and liabilities will result in changes in carrying value or recoverable amounts. The Company's revenues are also exposed to price risk since management fees, carried interest and performance fees are correlated with AUM, which fluctuates with changes in the market values of the assets in the funds and managed accounts managed by the Company.
Interest rate risk
Interest rate risk arises from the possibility that changes in interest rates will adversely affect the value of, or cash flows from, financial assets and liabilities. The Company’s earnings, particularly through its private strategies segment, are exposed to volatility as a result of sudden changes in interest rates. Management takes into account a number of factors and is committed to several processes to ensure that this risk is appropriately managed.
Foreign currency risk
The Company enters into transactions that are denominated primarily in U.S. dollars. Foreign currency risk arises from foreign exchange rate movements that could negatively impact the liquidity of the Company in instances where there is a translation from U.S. dollars to a different currency.
Credit risk
Credit risk is the risk that a borrower will not honor its commitments and a loss to the Company may result. Credit risk generally arises in the Company's investment portfolio.
Investments
The Company incurs credit risk when entering into, settling and financing transactions with counterparties. Management takes into account a number of factors and is committed to several processes to ensure that this risk is appropriately managed.
Other
The majority of receivables relate to management fees, carried interest and performance fees receivable from the funds and managed accounts managed by the Company. These receivables are short-term in nature and any credit risk associated with them is managed by dealing with counterparties that the Company believes to be creditworthy and by actively monitoring credit exposure and the financial health of the counterparties.
Liquidity risk
Liquidity risk is the risk that the Company cannot meet a demand for cash or fund its obligations as they come due. The Company's exposure to liquidity risk is minimal, as it maintains sufficient levels of liquid assets to meet its obligations as they come due. The Company has $202.1 million (December 31, 2025 - $123.4 million) of cash and cash equivalents. In addition, the Company has $78.5 million of co-investments (December 31, 2025 - $76.7 million) of which $29.1 million (December 31, 2025 - $35.5 million) can be monetized in less than 90 days (liquid co-investments). The Company also has access to a credit facility of $75 million with a major Canadian schedule I chartered bank.
The Company's exposure to liquidity risk as it relates to its co-investments in private strategies LPs arises from fluctuations in cash flows from making capital calls and receiving capital distributions. The Company manages its co-investment liquidity risk through the ongoing monitoring of scheduled capital calls and distributions ("match funding") and through its broader treasury risk management program and enterprise capital budgeting.
Financial liabilities, including accounts payable and accrued liabilities and compensation payable, are generally short-term in nature and due within a year.
The Company's management team is responsible for reviewing resources to ensure funds are readily available to meet its financial obligations as they come due and ensuring adequate funds exist to support business strategies and operations growth. The Company manages liquidity risk by monitoring cash balances on a daily basis and through its broader treasury risk management program. To meet any liquidity shortfalls, actions taken by the Company could include, but are not limited to: drawing on the line of credit; slowing its co-investment activities; liquidating investments; and adjusting or otherwise temporarily suspending Annual Incentive Plan ("AIP") payments.
Concentration risk
As a natural consequence of our business strategy, a significant portion of the Company's AUM is focused on the precious metals and critical materials sectors. If such AUM declines, either because of declining market values or net outflows from the funds, our revenues would be adversely affected.
In addition, certain investments may be concentrated to a material degree, in a single position or group of positions, in precious metals and critical materials. Management takes into account a number of factors and is committed to several processes to ensure that the investment risk is appropriately managed, but the investments may decline due to declines in such sectors.
Disclosure controls and procedures ("DC&P") and internal control over financial reporting ("ICFR")
Management is responsible for the design and operational effectiveness of DC&P and ICFR in order to provide reasonable assurance regarding the disclosure of material information relating to the Company. This includes information required to be disclosed in the Company's annual filings, interim filings and other reports filed under securities legislation, as well as the reliability of financial reporting and the preparation of financial statements for external purposes in accordance with IFRS.
Our chief executive officer and chief financial officer, after evaluating the effectiveness of our DC&P and ICFR (as defined in the applicable U.S. and Canadian securities laws), concluded that the Company's DC&P and ICFR were properly designed and were operating effectively as at September 30, 2026. In addition, there were no material changes to ICFR during the quarter.
Managing non-financial risks
For details around other risks managed by the Company (e.g. confidentiality of information, conflicts of interest, etc.) refer to the
Company's annual report as well as the Annual Information Form available on EDGAR at www.sec.gov and SEDAR+ at
www.sedarplus.com.
Additional information relating to the Company, including the Company's Annual Information Form is available on EDGAR at www.sec.gov and SEDAR+ at www.sedarplus.com.
Consolidated Financial Statements
Three and nine months ended September 30, 2026
Interim condensed consolidated balance sheets (unaudited)
| | | | | | | | | | | |
| | | |
| As at | | Sep. 30 | Dec. 31 |
| (In thousands of U.S. dollars) | | 2026 | 2025 |
| | | |
| Assets | | | |
| Current | | | |
| Cash and cash equivalents | | 202,144 | | 123,444 | |
| Fees receivable | | 7,971 | | 46,038 | |
| Short-term investments | (Notes 3 & 9) | 708 | | 640 | |
| Other assets | (Note 5) | 9,343 | | 14,261 | |
| Income taxes recoverable | | 3,551 | | 3,357 | |
| Total current assets | | 223,717 | | 187,740 | |
| | | |
| Co-investments | (Notes 4 & 9) | 78,489 | | 76,697 | |
| Other assets | (Notes 5 & 9) | 24,636 | | 34,469 | |
| Property and equipment, net | | 25,327 | | 21,280 | |
| Intangible assets | (Note 7) | 176,640 | | 183,116 | |
| Goodwill | (Note 7) | 19,149 | | 19,149 | |
| Deferred income taxes | | 3,754 | | 3,328 | |
| | 327,995 | | 338,039 | |
| Total assets | | 551,712 | | 525,779 | |
| | | |
| Liabilities and shareholders' equity | | | |
| Current | | | |
| Accounts payable and accrued liabilities | | 8,183 | | 13,552 | |
| Compensation payable | | 61,139 | | 81,318 | |
| Income taxes payable | | 14,191 | | 2,668 | |
| Total current liabilities | | 83,513 | | 97,538 | |
| | | |
| Other accrued liabilities | | 53,393 | | 47,738 | |
| | | |
| Deferred income taxes | | 14,178 | | 13,258 | |
| Total liabilities | | 151,084 | | 158,534 | |
| | | |
| Shareholders' equity | | | |
| Capital stock | (Note 8) | 438,570 | | 448,575 | |
| Contributed surplus | (Note 8) | 34,515 | | 35,057 | |
| Retained earnings (deficit) | | 21,123 | | (33,449) | |
| Accumulated other comprehensive loss | | (93,580) | | (82,938) | |
| Total shareholders' equity | | 400,628 | | 367,245 | |
| Total liabilities and shareholders' equity | | 551,712 | | 525,779 | |
| | | |
| Commitments and contingencies | (Note 13) | | |
| | | |
| | | |
| The accompanying notes form part of the unaudited interim condensed consolidated financial statements | | |
| | | |
| | | |
| | | |
"Ronald Dewhurst" "Graham Birch"
Director Director
Interim condensed consolidated statements of operations and comprehensive
income (unaudited)
| | | | | | | | | | | | | | | | | |
| | For the three months ended | For the nine months ended |
| | | | | |
| | Sep. 30 | Sep. 30 | Sep. 30 | Sep. 30 |
| (In thousands of U.S. dollars, except for per share amounts) | 2026 | 2025 | 2026 | 2025 |
| | | | | |
| Revenues | | | | | |
| Management fees | | 70,797 | | 50,710 | | 228,723 | | 135,145 | |
| Carried interest and performance fees | | 82 | | 1,757 | | 52,115 | | 16,564 | |
| Commissions | | 470 | | 3,816 | | 7,748 | | 5,827 | |
| Finance income | | 1,902 | | 1,583 | | 6,017 | | 4,198 | |
| Gain (loss) on investments | (Notes 3, 4 and 5) | 1,711 | | 7,012 | | 3,199 | | 11,249 | |
| Co-investment income | (Note 6) | 160 | | 234 | | 494 | | 665 | |
| Total revenues | | 75,122 | | 65,112 | | 298,296 | | 173,648 | |
| | | | | |
| Expenses | | | | | |
| Compensation | (Note 8) | 34,784 | | 38,550 | | 145,012 | | 91,972 | |
Fund expenses | | 3,642 | | 4,579 | | 16,891 | | 10,568 | |
| Selling, general and administrative | | 5,676 | | 4,473 | | 16,631 | | 13,425 | |
| Interest expense | | 388 | | 261 | | 980 | | 827 | |
| Depreciation of property and equipment | | 799 | | 647 | | 2,161 | | 1,825 | |
| Foreign exchange (gain) loss | | 124 | | (666) | | (1,257) | | 3,151 | |
| | | | | |
| Total expenses | | 45,413 | | 47,844 | | 180,418 | | 121,768 | |
| | | | | |
| Income before income taxes | 29,709 | | 17,268 | | 117,878 | | 51,880 | |
| Provision for income taxes | | 7,705 | | 4,109 | | 32,399 | | 13,263 | |
| Net income for the period | | 22,004 | | 13,159 | | 85,479 | | 38,617 | |
| | | | | |
| Net income per share: | | | | | |
| Basic | (Note 8) | 0.86 | | 0.51 | | 3.32 | | 1.50 | |
| Diluted | (Note 8) | 0.86 | | 0.51 | | 3.32 | | 1.50 | |
| | | | | |
| Net income for the period | | 22,004 | | 13,159 | | 85,479 | | 38,617 | |
| | | | | |
| Other comprehensive income (loss) | | | | | |
| Items that may be reclassified subsequently to profit or loss | | | | |
Foreign currency translation gain (loss) (taxes of $Nil) | 228 | | (5,184) | | (10,642) | | 8,467 | |
| Total other comprehensive income (loss) | 228 | | (5,184) | | (10,642) | | 8,467 | |
| Comprehensive income | | 22,232 | | 7,975 | | 74,837 | | 47,084 | |
| | | | | |
| The accompanying notes form part of the unaudited interim condensed consolidated financial statements |
Interim condensed consolidated statements of changes in shareholders' equity (unaudited)
| | | | | | | | | | | | | | | | | | | | | | | |
| | | | | | | |
| (In thousands of U.S. dollars, except for number of shares) | | Number of shares
outstanding | Capital stock | Contributed surplus | Retained earnings (deficit) | Accumulated other comprehensive income (loss) | Total
equity |
| | | | | | | |
| At Dec. 31, 2025 | | 25,786,258 | | 448,575 | | 35,057 | | (33,449) | | (82,938) | | 367,245 | |
| | | | | | | |
| Shares released on equity incentive plans | (Note 8) | — | | — | | (542) | | — | | — | | (542) | |
| Shares acquired and canceled under normal course issuer bid | (Note 8) | (84,056) | | (10,005) | | — | | — | | — | | (10,005) | |
| Foreign currency translation gain (loss) | | — | | — | | — | | — | | (10,642) | | (10,642) | |
| Dividends declared | (Note 10) | — | | — | | — | | (30,907) | | — | | (30,907) | |
| Net income | | — | | — | | — | | 85,479 | | — | | 85,479 | |
Balance, Sep. 30, 2026 | | 25,702,202 | | 438,570 | | 34,515 | | 21,123 | | (93,580) | | 400,628 | |
| | | | | | | |
| At Dec. 31, 2024 | | 25,814,859 | | 450,127 | | 36,267 | | (67,255) | | (95,491) | | 323,648 | |
| | | | | | | |
| | | | | | | |
| Shares released on equity incentive plans | (Note 8) | — | | — | | (1,283) | | — | | — | | (1,283) | |
| Shares acquired and canceled under normal course issuer bid | (Note 8) | (28,601) | | (1,552) | | — | | — | | — | | (1,552) | |
| Foreign currency translation gain (loss) | | — | | — | | — | | — | | 8,467 | | 8,467 | |
| Stock-based compensation | (Note 8) | — | | — | | 55 | | — | | — | | 55 | |
| | | | | | | |
| Dividends declared | | — | | — | | — | | (23,224) | | — | | (23,224) | |
| Net income | | — | | — | | — | | 38,617 | | — | | 38,617 | |
Balance, Sep. 30, 2025 | | 25,786,258 | | 448,575 | | 35,039 | | (51,862) | | (87,024) | | 344,728 | |
| | | | | | | |
| The accompanying notes form part of the unaudited interim condensed consolidated financial statements | | | |
Interim condensed consolidated statements of cash flows (unaudited)
| | | | | | | | | | | |
| | | |
| | For the nine months ended |
| | | |
| | Sep. 30 | Sep. 30 |
| (In thousands of U.S. dollars) | | 2026 | 2025 |
| | | |
| Operating activities | | | |
| Net income for the period | | 85,479 | | 38,617 | |
| Add (deduct) non-cash items: | | | |
| (Gain) loss on investments | | (3,199) | | (11,249) | |
| Stock-based compensation | | — | | 55 | |
| Depreciation of property and equipment | | 2,161 | | 1,825 | |
| Deferred income tax expense | | 829 | | 1,399 | |
| Current income tax expense | | 31,570 | | 11,864 | |
| Other items | | (18) | | (469) | |
| Income taxes paid | | (19,916) | | (22,947) | |
| Changes in: | | | |
| Fees receivable | | 38,067 | | (8,175) | |
| Other assets | | 16,990 | | (2,674) | |
| Accounts payable, accrued liabilities and compensation payable | | (28,056) | | 37,524 | |
| Cash provided by (used in) operating activities | | 123,907 | | 45,770 | |
| | | |
| Investing activities | | | |
| Purchase of investments | | (17,660) | | (7,942) | |
| Sale of investments | | 18,768 | | 12,440 | |
| Purchase of property and equipment | | (1,400) | | (1,529) | |
| | | |
| Cash provided by (used in) investing activities | | (292) | | 2,969 | |
| | | |
| Financing activities | | | |
| Acquisition of common shares under normal course issuer bid | | (10,005) | | (1,552) | |
| Repayment of lease liabilities | | (1,068) | | (793) | |
| Contributions from non-controlling interest | | 1,870 | | 8,178 | |
| | | |
| | | |
| Dividends paid | | (30,907) | | (23,224) | |
| Cash provided by (used in) financing activities | | (40,110) | | (17,391) | |
| Effect of foreign exchange on cash balances | | (4,805) | | 1,716 | |
| Net increase (decrease) in cash and cash equivalents during the period | | 78,700 | | 33,064 | |
| Cash and cash equivalents, beginning of the period | | 123,444 | | 46,834 | |
| Cash and cash equivalents, end of the period | | 202,144 | | 79,898 | |
| Cash and cash equivalents: | | | |
| Cash | | 196,364 | | 74,864 | |
| Short-term deposits | | 5,780 | | 5,034 | |
| | 202,144 | | 79,898 | |
| | | |
| | | |
| | | |
| | | |
| The accompanying notes form part of the unaudited interim condensed consolidated financial statements | |
| | | |
SPROTT INC.
Notes to the interim condensed consolidated financial statements (unaudited)
For the three and nine months ended September 30, 2026 and 2025
1 Corporate information
Sprott Inc. (the "Company") was incorporated under the Business Corporations Act (Ontario) on February 13, 2008. Its registered office is at Royal Bank Plaza, South Tower, 200 Bay Street, Suite 2600, Toronto, Ontario M5J 2J1.
2 Summary of material accounting policy information
Statement of compliance
These unaudited interim condensed consolidated financial statements ("interim financial statements") have been prepared in accordance with International Financial Reporting Standards ("IFRS") in effect as at September 30, 2026 as issued by the International Accounting Standards Board ("IASB").
Compliance with IFRS requires the Company to exercise judgment and make estimates and assumptions that affect the reported amount of assets and liabilities and disclosure of contingent assets and liabilities at the date of the financial statements and the reported amounts of revenues and expenses during the reporting period. Actual results may vary. Except as otherwise noted, significant accounting judgments and estimates are described in Note 2 of the December 31, 2025 annual audited consolidated financial statements and have been applied consistently to the interim financial statements as at and for the three and nine months ended September 30, 2026.
The interim financial statements have been authorized for issue by a resolution of the board of directors of the Company on November 3, 2026.
Basis of presentation
These interim financial statements have been prepared on a going concern basis and on a historical cost basis, except for certain financial instruments classified as fair value through profit or loss ("FVTPL") and which are measured at fair value to the extent required or permitted under IFRS and as set out in the relevant accounting policies. The interim financial statements are presented in U.S. dollars and all values are rounded to the nearest thousand ($000), except when indicated otherwise.
Principles of consolidation
These interim financial statements of the Company are prepared on a consolidated basis so as to include the accounts of all limited partnerships and corporations the Company is deemed to control under IFRS. Controlled limited partnerships and corporations ("subsidiaries") are consolidated from the date the Company obtains control. All intercompany balances with subsidiaries are eliminated upon consolidation. Subsidiary financial statements are prepared for the same reporting period as the Company and are based on accounting policies consistent with that of the Company.
The Company consolidates interest in its funds or subsidiaries if the Company has control over the entity. Control exists if the Company has power over the entity, exposure or rights to variable returns from its involvement with the entity and the ability to use its power over the entity to affect the amount of returns the Company receives. In many, but not all instances, control will exist when the Company owns more than one half of the voting rights of a corporation, or is the sole limited and general partner of a limited partnership.
The Company records third-party interest in the funds which do not qualify to be equity due to redeemable or limited life features, as non-controlling interest liabilities. Such interests are initially recognized at fair value, with any changes recorded in the co-investment income line of the consolidated statements of operations and comprehensive income.
SPROTT INC.
Notes to the interim condensed consolidated financial statements (unaudited)
For the three and nine months ended September 30, 2026 and 2025
The Company currently controls the following principal subsidiaries:
•Sprott Asset Management LP ("SAM");
•Sprott U.S. Holdings Inc. ("SUSHI"), parent of: (1) SGRIL Holdings Inc. ("SGRIL Holdings"); (2) Sprott Global Resource Investments Ltd. ("SGRIL"); (3) Sprott Asset Management USA Inc. ("SAM US"); and (4) Resource Capital Investment Corporation ("RCIC"). Collectively, the interests of SUSHI are referred to as "US entities" in these financial statements;
•Sprott Resource Streaming and Royalty Corporation and Sprott Private Resource Streaming and Royalty (Management) Corp. ("SRSR"); and
•Sprott Resource Lending Corp. ("SRLC")
Other accounting policies
All other accounting policies, judgments, and estimates described in the December 31, 2025 annual audited consolidated financial statements have been applied consistently to the interim financial statements unless otherwise noted.
Future changes in accounting policies
IFRS 18 Presentation and disclosure in financial statements ("IFRS 18")
In April 2024, the International Accounting Standards Board (IASB) issued IFRS 18, which replaces IAS 1 Presentation of Financial Statements. IFRS 18 introduces changes with how an entity presents its consolidated statement of operations, including mandatory totals and subtotals, as well as classification of income and expenses into five categories: operating, investing, financing, income taxes and discontinued operations. IFRS 18 also requires additional disclosure around management-defined performance measures.
IFRS 18 is effective for the Company’s fiscal year beginning on January 1, 2027 and will be applied retrospectively. The Company is currently assessing the impacts of the conversion to IFRS 18.
SPROTT INC.
Notes to the interim condensed consolidated financial statements (unaudited)
For the three and nine months ended September 30, 2026 and 2025
3 Short-term investments
Primarily consist of equity investments in public entities the Company receives as consideration during private strategies, managed equities and broker-dealer activities (in thousands $):
| | | | | | | | | | | |
| | |
| | | |
| Classification and measurement criteria | Sep. 30, 2026 | Dec. 31, 2025 |
| | | |
| Public equities and share purchase warrants | FVTPL | 708 | | 640 | |
| | | |
| Total short-term investments | | 708 | | 640 | |
| | | |
| | | |
Gains (losses) on financial assets and liabilities classified at FVTPL of $nil for the three and nine months ended September 30, 2026 (three and nine months ended September 30, 2025 - $0.2 million) are included in the gain (loss) on investments line in the consolidated statements of operations and comprehensive income.
4 Co-investments
Consists of the following (in thousands $):
| | | | | | | | | | | |
| | | |
| Classification and measurement criteria | Sep. 30, 2026 | Dec. 31, 2025 |
| | | |
| Co-investments in funds | FVTPL | 78,489 | | 76,697 | |
| | | |
| | | |
| Total co-investments | | 78,489 | | 76,697 | |
Gains (losses) on co-investments of $1.7 million for the three months ended September 30, 2026 (three months ended September 30, 2025 - $6.8 million) and $3.2 million for the nine months ended September 30, 2026 (nine months ended September 30, 2025 - $11 million) are included in the gain (loss) on investments line in the consolidated statements of operations and comprehensive income.
SPROTT INC.
Notes to the interim condensed consolidated financial statements (unaudited)
For the three and nine months ended September 30, 2026 and 2025
5 Other assets and non-controlling interest
Other assets
Consist of the following (in thousands $):
| | | | | | | | |
| Sep. 30, 2026 | Dec. 31, 2025 |
| | |
| Assets attributable to non-controlling interest | 18,804 | | 16,918 | |
| Fund recoveries and investment receivables | 5,775 | | 10,312 | |
Private holdings (1) | 4,161 | | 4,311 | |
| Prepaid expenses | 3,454 | | 4,145 | |
Other (2) | 1,785 | | 1,232 | |
| Advance on unrealized carried interest | — | | 11,812 | |
| Total other assets | 33,979 | | 48,730 | |
(1) Private holdings are financial instruments classified at FVTPL. Gains and losses are included in the gain (loss) on investments line in the consolidated statements of operations and comprehensive income.
(2) Includes miscellaneous third-party receivables.
Non-controlling interest assets and liabilities
Non-controlling interest consists of third-party interest in the Company's co-investments that are consolidated. Assets attributable to non-controlling interest represent the underlying investments in the funds. The following table provides a summary of amounts attributable to this non-controlling interest (in thousands $):
| | | | | | | | |
| Sep. 30, 2026 | Dec. 31, 2025 |
| | |
| Assets | 18,804 | 16,918 |
Liabilities - current (1) | (45) | (29) |
Liabilities - long-term (1) | (18,759) | (16,889) |
(1) Current and long-term liabilities attributable to non-controlling interest are included in accounts payable and accrued liabilities and other accrued liabilities, respectively.
SPROTT INC.
Notes to the interim condensed consolidated financial statements (unaudited)
For the three and nine months ended September 30, 2026 and 2025
6 Co-investment income
| | | | | | | | | | | | | | |
| For the three months ended | For the nine months ended |
| Sep. 30, 2026 | Sep. 30, 2025 | Sep. 30, 2026 | Sep. 30, 2025 |
| | | | |
| Co-investment income | 160 | | 234 | | 494 | | 665 | |
| Income attributable to non-controlling interest | (216) | | 1,801 | | 2,180 | | 3,607 | |
| Expense attributable to non-controlling interest | 216 | | (1,801) | | (2,180) | | (3,607) | |
| Total co-investment income | 160 | | 234 | 494 | 665 |
SPROTT INC.
Notes to the interim condensed consolidated financial statements (unaudited)
For the three and nine months ended September 30, 2026 and 2025
7 Goodwill and intangible assets
Consist of the following (in thousands $):
| | | | | | | | | | | | | | |
| Goodwill | Fund
management
contracts
(indefinite life) | Total | |
| Cost | | | | |
| At Dec. 31, 2024 | 132,251 | | 168,254 | | 300,505 | | |
Additions (1) | — | | 6,468 | | 6,468 | | |
| Net exchange differences | — | | 8,394 | | 8,394 | | |
| At Dec. 31, 2025 | 132,251 | | 183,116 | | 315,367 | | |
| | | | |
| Net exchange differences | — | | (6,476) | | (6,476) | | |
| At Sep. 30, 2026 | 132,251 | | 176,640 | | 308,891 | | |
| | | | |
| Impairment | | | | |
| At Dec. 31, 2024 | (113,102) | | — | | (113,102) | | |
| Impairment charge for the year | — | | — | | — | | |
| At Dec. 31, 2025 | (113,102) | | — | | (113,102) | | |
| Impairment charge for the period | — | | — | | — | | |
| | | | |
| | | | |
| At Sep. 30, 2026 | (113,102) | | — | | (113,102) | | |
| | | | |
| Net book value at: | | | | |
| At Dec. 31, 2025 | 19,149 | | 183,116 | | 202,265 | | |
| At Sep. 30, 2026 | 19,149 | | 176,640 | | 195,789 | | |
(1) See "Indefinite life fund management contracts" on the following page for more details.
SPROTT INC.
Notes to the interim condensed consolidated financial statements (unaudited)
For the three and nine months ended September 30, 2026 and 2025
Goodwill
The Company has identified 4 cash generating units ("CGU") as follows:
•Exchange listed products
•Managed equities
•Private strategies
•Corporate
As at September 30, 2026, the Company had allocated $19.1 million (December 31, 2025 - $19.1 million) of goodwill between the exchange listed products CGU ($17.9 million) and the managed equities CGU ($1.2 million). Goodwill was allocated on a relative value approach basis.
Indefinite life fund management contracts
As at September 30, 2026, the Company had indefinite life intangibles related to fund management contracts of $176.6 million (December 31, 2025 - $183.1 million). These contracts are held within the exchange listed products and managed equities CGUs. The addition of $6.5 million in the second quarter of the previous year was related to the remeasurement of a provision related to a historical acquisition.
Impairment assessment of goodwill and indefinite life fund management contracts
In the normal course, goodwill and indefinite life fund management contracts are tested for impairment once per annum, which for the Company is during the fourth quarter of each year or earlier if there are indicators of impairment. There were no indicators of impairment in either the exchange listed products or the managed equities CGUs as at September 30, 2026.
SPROTT INC.
Notes to the interim condensed consolidated financial statements (unaudited)
For the three and nine months ended September 30, 2026 and 2025
8 Shareholders' equity
Capital stock and contributed surplus
The authorized and issued share capital of the Company consists of an unlimited number of common shares, without par value.
| | | | | | | | |
| Number
of shares | Stated value
(in thousands $) |
| | |
| At Dec. 31, 2024 | 25,814,859 | | 450,127 | |
| | |
| | |
| | |
| Shares acquired and canceled under normal course issuer bid | (28,601) | | (1,552) | |
| | |
| | |
| At Dec. 31, 2025 | 25,786,258 | | 448,575 | |
| | |
| | |
| Shares acquired and canceled under normal course issuer bid | (84,056) | | (10,005) | |
| | |
| | |
| At Sep. 30, 2026 | 25,702,202 | | 438,570 | |
Contributed surplus consists of stock option expense, earn-out shares expense, equity incentive plans' expense, and additional purchase consideration.
| | | | | |
| Stated value
(in thousands $) |
| |
| At Dec. 31, 2024 | 36,267 | |
| |
| Released on equity incentive plans | (1,283) | |
| Stock-based compensation | 73 | |
| |
| At Dec. 31, 2025 | 35,057 | |
| Released on equity incentive plans | (542) | |
| |
| At Sep. 30, 2026 | 34,515 | |
SPROTT INC.
Notes to the interim condensed consolidated financial statements (unaudited)
For the three and nine months ended September 30, 2026 and 2025
Equity incentive plans
The Company granted 1,690 cash-settled restricted stock units ("RSUs") during the three months ended September 30, 2026 (three months ended September 30, 2025 - nil) and 281,541 cash-settled RSUs during the nine months ended September 30, 2026 (nine months ended September 30, 2025 - 976,550) that will vest over a period of up to three years assuming the vesting criteria is met.
As at September 30, 2026, there are nil options outstanding (December 31, 2025 - 12,500).
The Company recorded stock-based compensation of $16.5 million during the three months ended September 30, 2026 (three months ended September 30, 2025 - $22.4 million) and $56.3 million during the nine months ended September 30, 2026 (nine months ended September 30, 2025 - $47.2 million).
Basic and diluted earnings per share
The following table presents the calculation of basic and diluted earnings per common share:
| | | | | | | | | | | | | | | | |
| | For the three months ended | For the nine months ended |
| | | Sep. 30, 2026 | Sep. 30, 2025 | Sep. 30, 2026 | Sep. 30, 2025 |
| | | | | | |
| Numerator (in thousands $): | | | | | | |
| Net income - basic and diluted | | | 22,004 | | 13,159 | | 85,479 | | 38,617 | |
| | | | | | |
| Denominator (number of shares in thousands): | | | | | | |
| Weighted average number of common shares | | | 25,716 | | 25,796 | | 25,756 | | 25,804 | |
| Weighted average number of common shares - basic | | | 25,716 | | 25,796 | | 25,756 | | 25,804 | |
| Weighted average number of dilutive stock options | | | — | | 13 | | — | | 13 | |
| Weighted average number of unvested shares under equity incentive plan | | | — | | 5 | | — | | 5 | |
| Weighted average number of common shares - diluted | | | 25,716 | | 25,814 | | 25,756 | | 25,822 | |
| | | | | | |
| Net income per common share | | | | | | |
| Basic | | | 0.86 | | 0.51 | | 3.32 | | 1.50 | |
| Diluted | | | 0.86 | | 0.51 | | 3.32 | | 1.50 | |
SPROTT INC.
Notes to the interim condensed consolidated financial statements (unaudited)
For the three and nine months ended September 30, 2026 and 2025
Capital management
The Company's objectives when managing capital are:
•to meet regulatory requirements and other contractual obligations;
•to safeguard the Company's ability to continue as a going concern so that it can continue to provide returns to shareholders;
•to provide financial flexibility to fund possible acquisitions;
•to provide adequate seed capital for the Company's new product offerings; and
•to provide an adequate return to shareholders through growth in assets under management, growth in management fees, carried interest and performance fees and return on the Company's invested capital that will result in dividend payments to shareholders.
The Company's capital is comprised of equity, including capital stock, contributed surplus, retained earnings (deficit) and accumulated other comprehensive income (loss). SAM is a registrant of the Ontario Securities Commission ("OSC") and SGRIL is a member of the Financial Industry Regulatory Authority ("FINRA"). As a result, all of these entities are required to maintain a minimum level of regulatory capital. To ensure compliance, management monitors regulatory and working capital on a regular basis. SAM US and RCIC are registered with the U.S. Securities and Exchange Commission ("SEC"). As at September 30, 2026 and 2025, all entities were in compliance with their respective capital requirements.
SPROTT INC.
Notes to the interim condensed consolidated financial statements (unaudited)
For the three and nine months ended September 30, 2026 and 2025
9 Fair value measurements
The following tables present the Company's recurring fair value measurements within the fair value hierarchy. The Company did not have non-recurring fair value measurements as at September 30, 2026 and December 31, 2025 (in thousands $).
Short-term investments
| | | | | | | | | | | | | | |
| |
| Sep. 30, 2026 | Level 1 | Level 2 | Level 3 | Total |
| | | | |
| | | | |
| | | | |
| | | | |
| | | | |
| Public equities and share purchase warrants | 658 | 46 | 4 | 708 |
| | | | |
| | | | |
| Total recurring fair value measurements | 658 | | 46 | | 4 | | 708 | |
| | | | |
| | | | |
| | | | |
| | | | |
| | | | |
| |
| Dec. 31, 2025 | Level 1 | Level 2 | Level 3 | Total |
| | | | |
| | | | |
| | | | |
| | | | |
| Public equities and share purchase warrants | 578 | 62 | | — | | 640 | |
| | | | |
| | | | |
| | | | |
| Total recurring fair value measurements | 578 | | 62 | | — | | 640 | |
| | | | |
| | | | |
| | | | |
| | | | |
Co-investments
| | | | | | | | | | | | | | |
| Sep. 30, 2026 | Level 1 | Level 2 | Level 3 | Total |
| | | | |
Co-investments (1) | 15,298 | 63,191 | — | 78,489 |
| Total recurring fair value measurements | 15,298 | | 63,191 | | — | | 78,489 | |
| |
| Dec. 31, 2025 | Level 1 | Level 2 | Level 3 | Total |
| | | | |
Co-investments (1) | 14,735 | 61,962 | — | 76,697 |
| Total recurring fair value measurements | 14,735 | 61,962 | — | 76,697 |
(1) Co-investments also include investments made in funds which the Company consolidates that directly hold publicly traded equities, precious metals or critical materials.
SPROTT INC.
Notes to the interim condensed consolidated financial statements (unaudited)
For the three and nine months ended September 30, 2026 and 2025
Other assets
| | | | | | | | | | | | | | |
| Sep. 30, 2026 | Level 1 | Level 2 | Level 3 | Total |
| | | | |
| Private holdings | — | | — | | 4,161 | | 4,161 | |
| Assets attributable to non-controlling interest | — | | 18,804 | | — | | 18,804 | |
| Total recurring fair value measurements | — | | 18,804 | | 4,161 | | 22,965 | |
| |
| Dec. 31, 2025 | Level 1 | Level 2 | Level 3 | Total |
| | | | |
| Private holdings | — | | — | | 4,311 | | 4,311 | |
| Assets attributable to non-controlling interest | — | | 16,918 | | — | | 16,918 | |
| Total recurring fair value measurements | — | | 16,918 | | 4,311 | | 21,229 | |
The following tables provide a summary of changes in the fair value of level 3 financial assets (in thousands $):
Short-term investments
| | | | | | | | | | | | | | | | | |
| Changes in the fair value of Level 3 measurements - Sep. 30, 2026 |
| Dec. 31, 2025 | Purchases and reclassifications | Sales | Net unrealized gains (losses) included in net income | Sep. 30, 2026 |
| | | | | |
| Share purchase warrants | — | 4 | — | — | 4 |
| | | | | |
| Total | — | 4 | — | — | 4 |
| | | | | | | | | | | | | | | | | |
| Changes in the fair value of Level 3 measurements - Dec. 31, 2025 |
| Dec. 31, 2024 | Purchases and reclassifications | Sales | Net unrealized gains (losses) included in net income | Dec. 31, 2025 |
| Share purchase warrants | 6 | — | — | (6) | — |
| Total | 6 | — | — | (6) | — |
SPROTT INC.
Notes to the interim condensed consolidated financial statements (unaudited)
For the three and nine months ended September 30, 2026 and 2025
Other assets
| | | | | | | | | | | | | | | | | |
| Changes in the fair value of Level 3 measurements - Sep. 30, 2026 |
| Dec. 31, 2025 | Purchases and reclassifications | Sales | Net unrealized gains (losses) included in net income | Sep. 30, 2026 |
| | | | | |
| Private holdings | 4,311 | — | — | (150) | 4,161 |
| Total | 4,311 | — | — | (150) | 4,161 |
| | | | | | | | | | | | | | | | | |
| Changes in the fair value of Level 3 measurements - Dec. 31, 2025 |
| Dec. 31, 2024 | Purchases and reclassifications | Sales | Net unrealized gains (losses) included in net income | Dec. 31, 2025 |
| Private holdings | 4,371 | — | — | (60) | 4,311 |
| Total | 4,371 | — | — | (60) | 4,311 |
During the nine months ended September 30, 2026, the Company transferred public equities of $nil (December 31, 2025 - $nil) from level 2 to level 1 within the fair value hierarchy.
The following table presents the valuation techniques used by the Company in measuring fair values:
| | | | | |
| Type | Valuation technique |
| Public equities, precious metals and share purchase warrants | Fair values are determined using publicly available prices or pricing models which incorporate all available market-observable inputs. |
| Co-investments | Fair values are based on the last available net asset value. |
| Fixed income securities | Fair values are based on independent market data providers or third-party broker quotes. |
| Private holdings | Fair values are based on a variety of valuation techniques, including discounted cash flows, comparable recent transactions and other techniques used by market participants. |
The Company’s level 3 securities consist of private holdings and share purchase warrants. The significant unobservable inputs used in these valuation techniques can vary considerably over time, and include gray market financing prices, volatility and discount rates. The potential impact of a 5% change in the significant unobservable inputs on profit or loss would be approximately $0.2 million (December 31, 2025 - $0.2 million).
Included in compensation payable and other accrued liabilities are liabilities related to stock-based compensation of $71.6 million (December 31, 2025 - $76.2 million) which are carried at fair value based on the underlying stock price of Sprott Inc. shares.
Financial instruments not carried at fair value
The carrying amounts of fees receivable, other assets, accounts payable and accrued liabilities, other accrued liabilities and compensation payable excluding the above mentioned stock-based compensation payable represent a reasonable approximation of fair value as they are short-term in nature.
SPROTT INC.
Notes to the interim condensed consolidated financial statements (unaudited)
For the three and nine months ended September 30, 2026 and 2025
10 Dividends
The following dividends were declared by the Company during the nine months ended September 30, 2026:
| | | | | | | | | | | |
| Record date | Payment date | Cash dividend
per share | Total dividend amount (in thousands $) |
| | | |
| August 17, 2026 - Regular dividend Q2 2026 | September 1, 2026 | $0.40 | 10,282 | |
| May 19, 2026 - Regular dividend Q1 2026 | June 3, 2026 | $0.40 | 10,310 | |
| March 2, 2026 - Regular dividend Q4 2025 | March 17, 2026 | $0.40 | 10,315 | |
Dividends declared in 2026 (1) | | | 30,907 | |
(1) Subsequent to quarter-end, on November 3, 2026, a regular dividend of $0.50 per common share was declared for the quarter ended September 30, 2026. This dividend is payable on December 1, 2026 to shareholders of record at the close of business on November 16, 2026.
11 Segmented information
For management purposes, the Company is organized into business units based on its products, services and geographical locations and has four reportable segments as follows:
•Exchange listed products (reportable), which provides management services to the Company's closed-end physical trusts and exchange traded equity investment strategies;
•Managed equities (reportable), which provides management services to the Company's active equity investment strategies;
•Private strategies (reportable), which provides management services to the Company's lending and streaming investment strategies;
•Corporate (reportable), which provides capital, balance sheet management and enterprise shared services to the Company's subsidiaries; and
•All other segments (non-reportable), which do not meet the definition of reportable segments per IFRS 8.
Management monitors the operating results of its business units separately for the purpose of making decisions about resource allocation and performance assessment. Segment performance is evaluated based on earnings before interest expense, income taxes, amortization and impairment of intangible assets and goodwill, gains and losses on investments (as if such gains and losses had not occurred), stock-based compensation, severance, new hire accruals and other, foreign exchange (gain) loss, carried interest and performance fees and carried interest and performance fee payouts (adjusted EBITDA).
Adjusted EBITDA is not a measurement in accordance with IFRS and should not be considered as an alternative to net income or any other measure of performance under IFRS.
Transfer pricing between operating segments is performed on an arm's length basis in a manner similar to transactions with third parties.
SPROTT INC.
Notes to the interim condensed consolidated financial statements (unaudited)
For the three and nine months ended September 30, 2026 and 2025
The following tables present the operations of the Company's segments (in thousands $):
For the three months ended September 30, 2026
| | | | | | | | | | | | | | | | | | | | | | | |
| Exchange listed products | Managed
equities | Private strategies | Corporate | Consolidation, elimination and all other segments | Consolidated | |
| Total revenue | 55,178 | 14,347 | 4,141 | 1,117 | 339 | 75,122 | |
| Total expenses | 15,768 | 9,695 | 3,403 | 16,307 | 240 | 45,413 | |
| Income (loss) before income taxes | 39,410 | 4,652 | 738 | (15,190) | 99 | 29,709 | |
| Adjusted EBITDA | 43,524 | 5,128 | 1,945 | (4,740) | 166 | 46,023 | |
For the three months ended September 30, 2025
| | | | | | | | | | | | | | | | | | | | |
| Exchange listed products | Managed
equities | Private strategies | Corporate | Consolidation, elimination and all other segments | Consolidated |
| Total revenue | 42,721 | 15,361 | 6,245 | 529 | 256 | 65,112 |
| Total expenses | 15,298 | 9,975 | 2,031 | 20,069 | 471 | 47,844 |
| Income (loss) before income taxes | 27,423 | 5,386 | 4,214 | (19,540) | (215) | 17,268 |
| Adjusted EBITDA | 30,549 | 2,911 | 2,232 | (3,808) | 32 | 31,916 |
For the nine months ended September 30, 2026
| | | | | | | | | | | | | | | | | | | | |
| Exchange listed products | Managed
equities | Private strategies | Corporate | Consolidation, elimination and all other segments | Consolidated |
| Total revenue | 184,291 | 43,418 | 67,370 | 2,527 | 690 | 298,296 |
| Total expenses | 49,774 | 28,853 | 41,478 | 59,936 | 377 | 180,418 |
| Income (loss) before income taxes | 134,517 | 14,565 | 25,892 | (57,409) | 313 | 117,878 |
| Adjusted EBITDA | 146,746 | 16,279 | 6,436 | (15,171) | 388 | 154,678 |
For the nine months ended September 30, 2025
| | | | | | | | | | | | | | | | | | | | |
| Exchange listed products | Managed
equities | Private strategies | Corporate | Consolidation, elimination and all other segments | Consolidated |
| Total revenue | 105,630 | 49,359 | 17,411 | 1,128 | 120 | 173,648 |
| Total expenses | 39,722 | 28,244 | 11,011 | 41,291 | 1,500 | 121,768 |
| Income (loss) before income taxes | 65,908 | 21,115 | 6,400 | (40,163) | (1,380) | 51,880 |
| Adjusted EBITDA | 77,085 | 7,186 | 6,776 | (11,502) | (275) | 79,270 |
SPROTT INC.
Notes to the interim condensed consolidated financial statements (unaudited)
For the three and nine months ended September 30, 2026 and 2025
For geographic reporting purposes, transactions are primarily recorded in the location that corresponds with the underlying subsidiary's country of domicile that generates the revenue. The following table presents the revenue of the Company by geographic location (in thousands $):
| | | | | | | | | | | | | | |
| For the three months ended | For the nine months ended |
| Sep. 30, 2026 | Sep. 30, 2025 | Sep. 30, 2026 | Sep. 30, 2025 |
| Canada | 66,169 | | 55,004 | | 271,927 | | 134,985 | |
| United States | 8,953 | | 10,108 | | 26,369 | | 38,663 | |
| 75,122 | | 65,112 | | 298,296 | | 173,648 | |
12 Loan facility
As at September 30, 2026, the Company had $nil (December 31, 2025 - $nil) outstanding on its credit facility, which matures on August 8, 2028. As at September 30, 2026, the Company was in compliance with all covenants, terms and conditions under the credit facility.
The Company has access to a credit facility of $75 million with a major Canadian schedule I chartered bank. Amounts under the facility may be borrowed in U.S. dollars through SOFR or base rate loans. Amounts may also be borrowed in Canadian dollars through prime rate loans or CORRA loans.
Key terms under the current credit facility are noted below:
Structure
•5-year, $75 million revolver with "bullet maturity" on August 8, 2028
Interest rate
•SOFR + 2.36%
Covenant terms
•Minimum AUM: $11.7 billion;
•Debt to EBITDA less than or equal to 2.5:1; and
•EBITDA to interest expense more than or equal to 2.5:1
13 Commitments and contingencies
The Company has commitments to make co-investments in private strategies LPs or commitments to make co-investments in fund strategies in the Company's other segments. As at September 30, 2026, the Company had $1.5 million in co-investment commitments in private strategies LPs due within one year (December 31, 2025 - $3 million) and $2.9 million due after 12 months (December 31, 2025 - $nil).
Corporate Information
Head Office
Sprott Inc.
Royal Bank Plaza, South Tower
200 Bay Street, Suite 2600
Toronto, Ontario M5J 2J1, Canada
416.943.8099
1.855.943.8099
Directors & Officers
Ronald Dewhurst, Chairman
Graham Birch, Director
Barbara Connolly Keady, Director
Judith W. O’Connell, Director
Catherine Raw, Director
Dinaz Dadyburjor, Director
Whitney George, Chief Executive Officer & Director
Ryan McIntyre, President
Kevin Hibbert, Co-Chief Operating Officer & CFO
Arthur Einav, Co-Chief Operating Officer & General Counsel
US Transfer Agent and Registrar
Continental Stock Transfer & Trust Company
1 State Street 30th Floor
New York, NY 10004-1561
212.509.4000
www.continentalstock.com
Canadian Transfer Agent and Registrar
TSX Trust Company
301 - 100 Adelaide St. West
Toronto, Ontario, Canada M5H 4H1
Toll Free: 866.600.5869
www.tsxtrust.com
Legal Counsel
Stikeman Elliott LLP
5300 Commerce Court West
199 Bay Street
Toronto, Ontario M5L 1B9
Auditors
KPMG LLP
Bay Adelaide Centre
333 Bay Street, Suite 4600
Toronto, Ontario M5H 2S5
Investor Relations
Shareholder requests may be directed to
Investor Relations by e-mail at ir@sprott.com
or via telephone at 416.943.8099
or toll free at 1.855.943.8099
Stock Information
Sprott Inc. common shares are traded on the New York Stock Exchange and Toronto Stock Exchange under the symbol “SII”