Exhibit (c)(18) Polaris Financial Forecast Project Polaris July 18, 2026
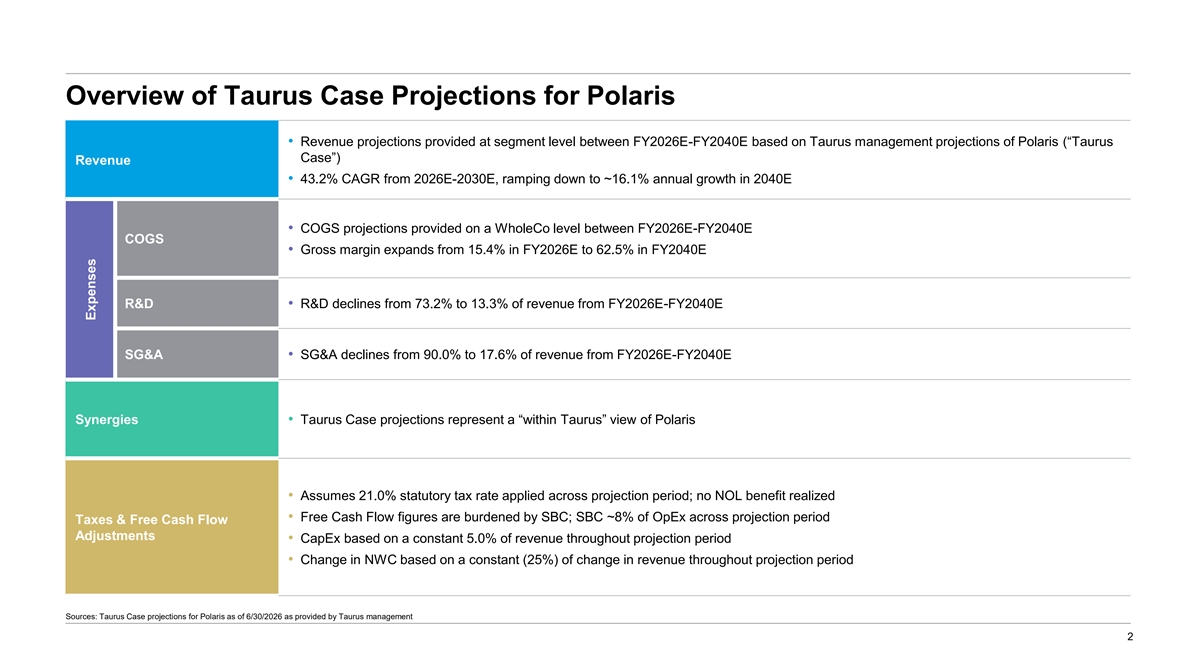
Overview of Taurus Case Projections for Polaris • Revenue projections provided at segment level between FY2026E-FY2040E based on Taurus management projections of Polaris (“Taurus Case”) Revenue • 43.2% CAGR from 2026E-2030E, ramping down to ~16.1% annual growth in 2040E • COGS projections provided on a WholeCo level between FY2026E-FY2040E COGS • Gross margin expands from 15.4% in FY2026E to 62.5% in FY2040E R&D • R&D declines from 73.2% to 13.3% of revenue from FY2026E-FY2040E SG&A • SG&A declines from 90.0% to 17.6% of revenue from FY2026E-FY2040E Synergies • Taurus Case projections represent a “within Taurus” view of Polaris • Assumes 21.0% statutory tax rate applied across projection period; no NOL benefit realized • Free Cash Flow figures are burdened by SBC; SBC ~8% of OpEx across projection period Taxes & Free Cash Flow Adjustments • CapEx based on a constant 5.0% of revenue throughout projection period • Change in NWC based on a constant (25%) of change in revenue throughout projection period Sources: Taurus Case projections for Polaris as of 6/30/2026 as provided by Taurus management 2 Expenses
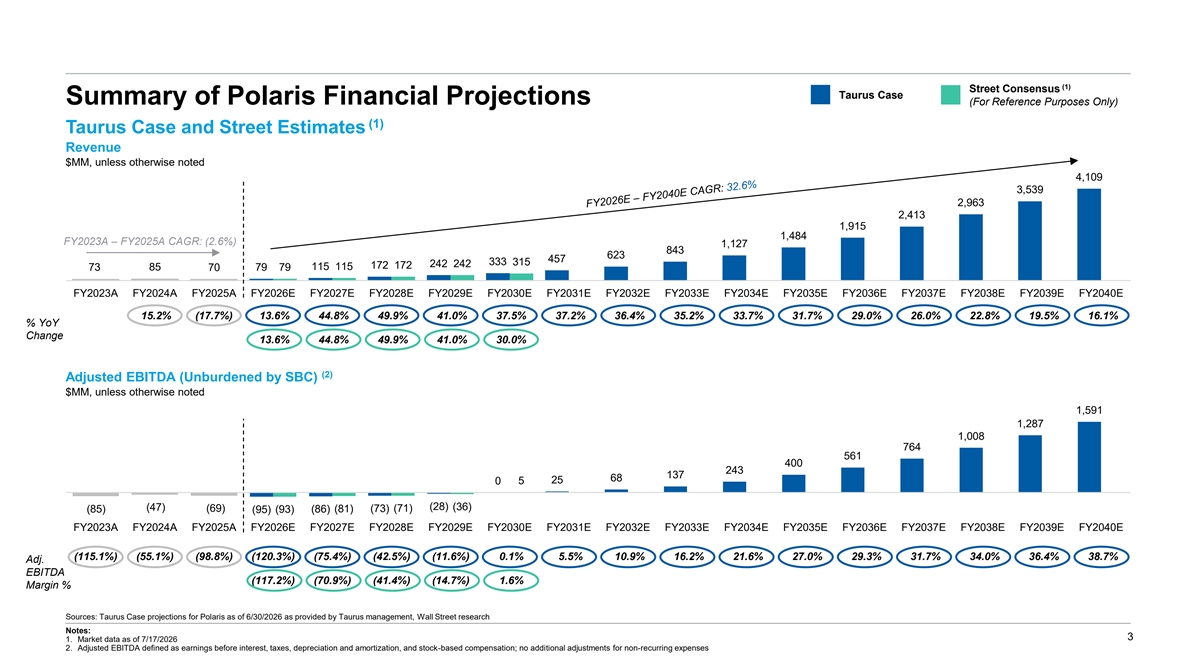
(1) Street Consensus Taurus Case Summary of Polaris Financial Projections (For Reference Purposes Only) (1) Taurus Case and Street Estimates Revenue $MM, unless otherwise noted 4,109 3,539 2,963 2,413 1,915 1,484 FY2023A – FY2025A CAGR: (2.6%) 1,127 843 623 457 333 315 242 242 172 172 73 85 70 79 79 115 115 FY2023A FY2024A FY2025A FY2026E FY2027E FY2028E FY2029E FY2030E FY2031E FY2032E FY2033E FY2034E FY2035E FY2036E FY2037E FY2038E FY2039E FY2040E 15.2% (17.7%) 13.6% 44.8% 49.9% 41.0% 37.5% 37.2% 36.4% 35.2% 33.7% 31.7% 29.0% 26.0% 22.8% 19.5% 16.1% % YoY Change 13.6% 44.8% 49.9% 41.0% 30.0% (2) Adjusted EBITDA (Unburdened by SBC) $MM, unless otherwise noted 1,591 1,287 1,008 764 561 400 243 137 68 5 25 0 (47) (28) (36) (69) (81) (73) (71) (85) (95) (93) (86) FY2023A FY2024A FY2025A FY2026E FY2027E FY2028E FY2029E FY2030E FY2031E FY2032E FY2033E FY2034E FY2035E FY2036E FY2037E FY2038E FY2039E FY2040E (115.1%) (55.1%) (98.8%) (120.3%) (75.4%) (42.5%) (11.6%) 0.1% 5.5% 10.9% 16.2% 21.6% 27.0% 29.3% 31.7% 34.0% 36.4% 38.7% Adj. EBITDA (117.2%) (70.9%) (41.4%) (14.7%) 1.6% Margin % Sources: Taurus Case projections for Polaris as of 6/30/2026 as provided by Taurus management, Wall Street research Notes: 3 1. Market data as of 7/17/2026 2. Adjusted EBITDA defined as earnings before interest, taxes, depreciation and amortization, and stock-based compensation; no additional adjustments for non-recurring expenses
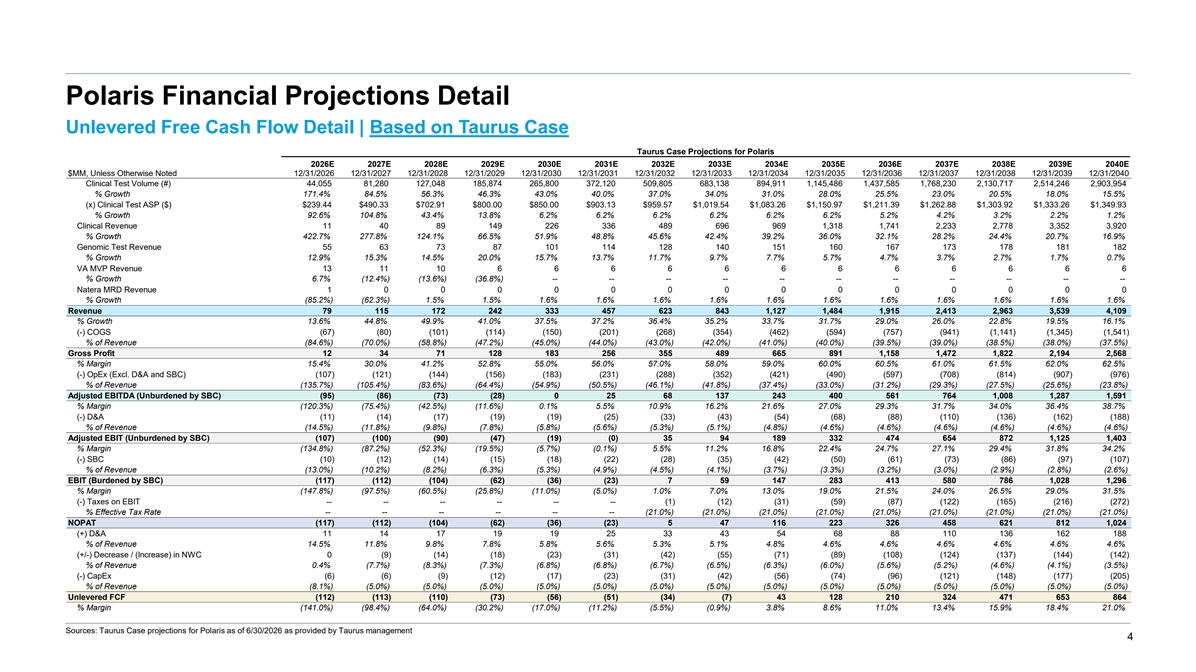
Polaris Financial Projections Detail Unlevered Free Cash Flow Detail | Based on Taurus Case Taurus Case Projections for Polaris 2026E 2027E 2028E 2029E 2030E 2031E 2032E 2033E 2034E 2035E 2036E 2037E 2038E 2039E 2040E $MM, Unless Otherwise Noted 12/31/2026 12/31/2027 12/31/2028 12/31/2029 12/31/2030 12/31/2031 12/31/2032 12/31/2033 12/31/2034 12/31/2035 12/31/2036 12/31/2037 12/31/2038 12/31/2039 12/31/2040 Clinical Test Volume (#) 44,055 81,280 127,048 185,874 265,800 372,120 509,805 683,138 894,911 1,145,486 1,437,585 1,768,230 2,130,717 2,514,246 2,903,954 % Growth 171.4% 84.5% 56.3% 46.3% 43.0% 40.0% 37.0% 34.0% 31.0% 28.0% 25.5% 23.0% 20.5% 18.0% 15.5% (x) Clinical Test ASP ($) $239.44 $490.33 $702.91 $800.00 $850.00 $903.13 $959.57 $1,019.54 $1,083.26 $1,150.97 $1,211.39 $1,262.88 $1,303.92 $1,333.26 $1,349.93 % Growth 92.6% 104.8% 43.4% 13.8% 6.2% 6.2% 6.2% 6.2% 6.2% 6.2% 5.2% 4.2% 3.2% 2.2% 1.2% Clinical Revenue 11 40 89 149 226 336 489 696 969 1,318 1,741 2,233 2,778 3,352 3,920 % Growth 422.7% 277.8% 124.1% 66.5% 51.9% 48.8% 45.6% 42.4% 39.2% 36.0% 32.1% 28.2% 24.4% 20.7% 16.9% Genomic Test Revenue 55 63 73 87 101 114 128 140 151 160 167 173 178 181 182 % Growth 12.9% 15.3% 14.5% 20.0% 15.7% 13.7% 11.7% 9.7% 7.7% 5.7% 4.7% 3.7% 2.7% 1.7% 0.7% VA MVP Revenue 13 11 10 6 6 6 6 6 6 6 6 6 6 6 6 % Growth 6.7% (12.4%) (13.6%) (36.8%) -- -- -- -- -- -- -- -- -- -- -- Natera MRD Revenue 1 0 0 0 0 0 0 0 0 0 0 0 0 0 0 % Growth (85.2%) (62.3%) 1.5% 1.5% 1.6% 1.6% 1.6% 1.6% 1.6% 1.6% 1.6% 1.6% 1.6% 1.6% 1.6% Revenue 79 115 172 242 333 457 623 843 1,127 1,484 1,915 2,413 2,963 3,539 4,109 % Growth 13.6% 44.8% 49.9% 41.0% 37.5% 37.2% 36.4% 35.2% 33.7% 31.7% 29.0% 26.0% 22.8% 19.5% 16.1% (-) COGS (67) (80) (101) (114) (150) (201) (268) (354) (462) (594) (757) (941) (1,141) (1,345) (1,541) % of Revenue (84.6%) (70.0%) (58.8%) (47.2%) (45.0%) (44.0%) (43.0%) (42.0%) (41.0%) (40.0%) (39.5%) (39.0%) (38.5%) (38.0%) (37.5%) Gross Profit 12 34 71 128 183 256 355 489 665 891 1,158 1,472 1,822 2,194 2,568 % Margin 15.4% 30.0% 41.2% 52.8% 55.0% 56.0% 57.0% 58.0% 59.0% 60.0% 60.5% 61.0% 61.5% 62.0% 62.5% (-) OpEx (Excl. D&A and SBC) (107) (121) (144) (156) (183) (231) (288) (352) (421) (490) (597) (708) (814) (907) (976) % of Revenue (135.7%) (105.4%) (83.6%) (64.4%) (54.9%) (50.5%) (46.1%) (41.8%) (37.4%) (33.0%) (31.2%) (29.3%) (27.5%) (25.6%) (23.8%) Adjusted EBITDA (Unburdened by SBC) (95) (86) (73) (28) 0 25 68 137 243 400 561 764 1,008 1,287 1,591 % Margin (120.3%) (75.4%) (42.5%) (11.6%) 0.1% 5.5% 10.9% 16.2% 21.6% 27.0% 29.3% 31.7% 34.0% 36.4% 38.7% (-) D&A (11) (14) (17) (19) (19) (25) (33) (43) (54) (68) (88) (110) (136) (162) (188) % of Revenue (14.5%) (11.8%) (9.8%) (7.8%) (5.8%) (5.6%) (5.3%) (5.1%) (4.8%) (4.6%) (4.6%) (4.6%) (4.6%) (4.6%) (4.6%) Adjusted EBIT (Unburdened by SBC) (107) (100) (90) (47) (19) (0) 35 94 189 332 474 654 872 1,125 1,403 % Margin (134.8%) (87.2%) (52.3%) (19.5%) (5.7%) (0.1%) 5.5% 11.2% 16.8% 22.4% 24.7% 27.1% 29.4% 31.8% 34.2% (-) SBC (10) (12) (14) (15) (18) (22) (28) (35) (42) (50) (61) (73) (86) (97) (107) % of Revenue (13.0%) (10.2%) (8.2%) (6.3%) (5.3%) (4.9%) (4.5%) (4.1%) (3.7%) (3.3%) (3.2%) (3.0%) (2.9%) (2.8%) (2.6%) EBIT (Burdened by SBC) (117) (112) (104) (62) (36) (23) 7 59 147 283 413 580 786 1,028 1,296 % Margin (147.8%) (97.5%) (60.5%) (25.8%) (11.0%) (5.0%) 1.0% 7.0% 13.0% 19.0% 21.5% 24.0% 26.5% 29.0% 31.5% (-) Taxes on EBIT -- -- -- -- -- -- (1) (12) (31) (59) (87) (122) (165) (216) (272) % Effective Tax Rate -- -- -- -- -- -- (21.0%) (21.0%) (21.0%) (21.0%) (21.0%) (21.0%) (21.0%) (21.0%) (21.0%) NOPAT (117) (112) (104) (62) (36) (23) 5 47 116 223 326 458 621 812 1,024 (+) D&A 11 14 17 19 19 25 33 43 54 68 88 110 136 162 188 % of Revenue 14.5% 11.8% 9.8% 7.8% 5.8% 5.6% 5.3% 5.1% 4.8% 4.6% 4.6% 4.6% 4.6% 4.6% 4.6% (+/-) Decrease / (Increase) in NWC 0 (9) (14) (18) (23) (31) (42) (55) (71) (89) (108) (124) (137) (144) (142) % of Revenue 0.4% (7.7%) (8.3%) (7.3%) (6.8%) (6.8%) (6.7%) (6.5%) (6.3%) (6.0%) (5.6%) (5.2%) (4.6%) (4.1%) (3.5%) (-) CapEx (6) (6) (9) (12) (17) (23) (31) (42) (56) (74) (96) (121) (148) (177) (205) % of Revenue (8.1%) (5.0%) (5.0%) (5.0%) (5.0%) (5.0%) (5.0%) (5.0%) (5.0%) (5.0%) (5.0%) (5.0%) (5.0%) (5.0%) (5.0%) Unlevered FCF (112) (113) (110) (73) (56) (51) (34) (7) 43 128 210 324 471 653 864 % Margin (141.0%) (98.4%) (64.0%) (30.2%) (17.0%) (11.2%) (5.5%) (0.9%) 3.8% 8.6% 11.0% 13.4% 15.9% 18.4% 21.0% Sources: Taurus Case projections for Polaris as of 6/30/2026 as provided by Taurus management 4