Exhibit (c)(19) Fairness Opinion Discussion Materials Project Polaris July 19, 2026
Legal Disclaimer We have prepared this document solely for informational purposes. You should not definitively rely upon it or use it to form the definitive basis for any decision, contract, commitment or action whatsoever, with respect to any proposed transaction or otherwise. You and your directors, officers, employees, agents and affiliates must hold this document and any oral information provided in connection with this document in strict confidence and may not communicate, reproduce, distribute or disclose it to any other person, or refer to it publicly, in whole or in part at any time except with our prior written consent. If you are not the intended recipient of this document, please delete and destroy all copies immediately. We have prepared this document and the analyses contained in it based, in part, on certain assumptions and information obtained by us from the recipient, its directors, officers, employees, agents, affiliates and/or from other sources. Our use of such assumptions and information does not imply that we have independently verified or necessarily agree with any of such assumptions or information, and we have assumed and relied upon the accuracy and completeness of such assumptions and information for purposes of this document. Neither we nor any of our affiliates, or our or their respective officers, employees or agents, make any representation or warranty, express or implied, in relation to the accuracy or completeness of the information contained in this document or any oral information provided in connection herewith, or any data it generates and accept no responsibility, obligation or liability (whether direct or indirect, in contract, tort or otherwise) in relation to any of such information. We and our affiliates and our and their respective officers, employees and agents expressly disclaim any and all liability which may be based on this document and any errors therein or omissions therefrom. Neither we nor any of our affiliates, or our or their respective officers, employees or agents, make any representation or warranty, express or implied, that any transaction has been or may be effected on the terms or in the manner stated in this document, or as to the achievement or reasonableness of future projections, management targets, estimates, prospects or returns, if any. Any views or terms contained herein are based on financial, economic, market and other conditions prevailing as of the date of this document and are therefore subject to change. We undertake no obligation or responsibility to update any of the information contained in this document. Past performance does not guarantee or predict future performance. We have (i) assumed that any forecasted financial information contained herein reflects the best available estimates of future financial performance, and (ii) not made any independent valuation or appraisal of the assets or liabilities of any company involved in any proposed transaction, nor have we been furnished with any such valuations or appraisals. The purpose of this document is to provide the recipient with an explanation of the basis upon which Morgan Stanley is issuing a financial opinion letter in relation to the proposed transaction. This document should be read in conjunction with and is subject to the terms of such financial opinion. This document supersedes any previous documents or presentations delivered by Morgan Stanley to the recipient in connection with the proposed transaction. This document and the information contained herein do not constitute an offer to sell or the solicitation of an offer to buy any security, commodity or instrument or related derivative, nor do they constitute an offer or commitment to lend, syndicate or arrange a financing, underwrite or purchase or act as an agent or advisor or in any other capacity with respect to any transaction, or commit capital, or to participate in any trading strategies, and do not constitute legal, regulatory, accounting or tax advice to the recipient. We recommend that the recipient seek independent third party legal, regulatory, accounting and tax advice regarding the contents of this document. This document is not a research report and was not prepared by the research department of Morgan Stanley or any of its affiliates. Notwithstanding anything herein to the contrary, each recipient hereof (and their employees, representatives, and other agents) may disclose to any and all persons, without limitation of any kind from the commencement of discussions, the U.S. federal and state income tax treatment and tax structure of the proposed transaction and all materials of any kind (including opinions or other tax analyses) that are provided relating to the tax treatment and tax structure. For this purpose, tax structure is limited to facts relevant to the U.S. federal and state income tax treatment of the proposed transaction and does not include information relating to the identity of the parties, their affiliates, agents or advisors. This document is provided by Morgan Stanley & Co. LLC and/or certain of its affiliates, which may include Morgan Stanley Realty Incorporated, Morgan Stanley Senior Funding, Inc., Morgan Stanley Bank, N.A., Morgan Stanley & Co. International plc, Morgan Stanley & Co. Limited, Morgan Stanley Bank International (Milan Branch), Morgan Stanley Saudi Arabia, Morgan Stanley South Africa (PTY) Limited, Morgan Stanley Securities Limited, Morgan Stanley Bank AG, Morgan Stanley MUFG Securities Co., Ltd, Mitsubishi UFJ Morgan Stanley Securities Co., Ltd, Morgan Stanley India Company Private Limited, Morgan Stanley Asia Limited, Morgan Stanley Australia Limited, Morgan Stanley Asia (Singapore) Pte., Morgan Stanley Services Limited, Morgan Stanley & Co. International plc, Seoul Branch, Morgan Stanley Canada Limited and/or Morgan Stanley, SV, SAU. Unless governing law permits otherwise, you must contact an authorized Morgan Stanley entity in your jurisdiction regarding this document or any of the information contained herein. © Morgan Stanley and/or certain of its affiliates. All rights reserved. 2
Table of Contents Section 1 Transaction Overview 4 Section 2 Valuation Analysis 6 Appendix Supplemental Materials 11 3
SECTION 1 Transaction Overview 4
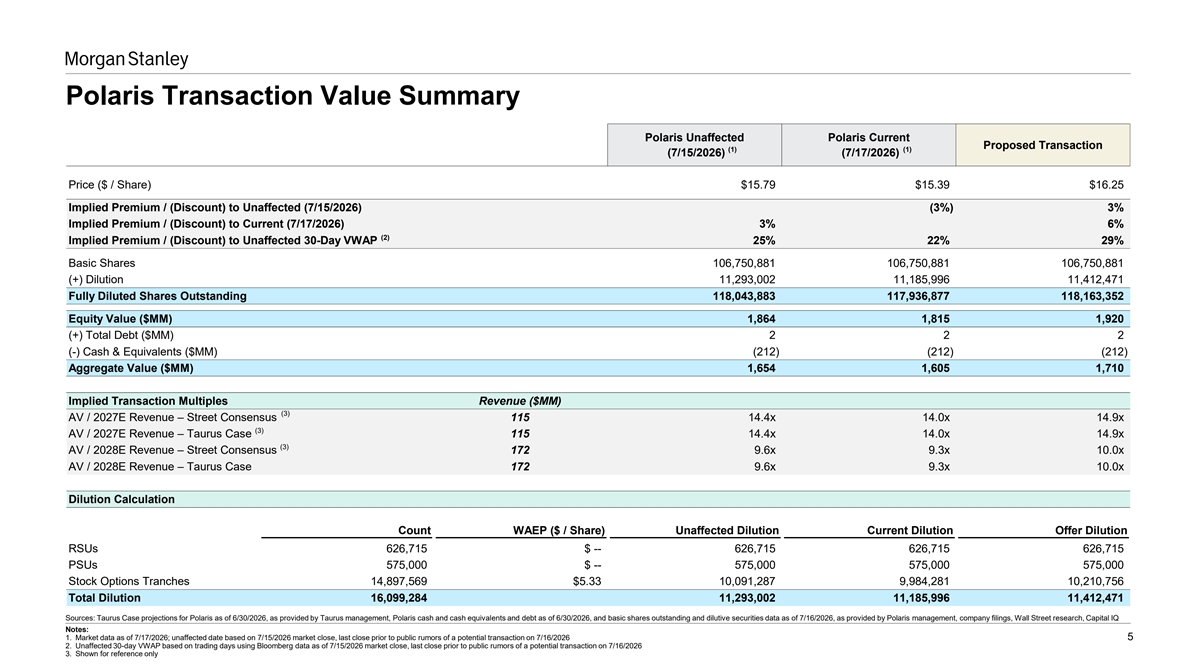
Polaris Transaction Value Summary Polaris Unaffected Polaris Current Proposed Transaction (1) (1) (7/15/2026) (7/17/2026) Price ($ / Share) $15.79 $15.39 $16.25 Implied Premium / (Discount) to Unaffected (7/15/2026) (3%) 3% Implied Premium / (Discount) to Current (7/17/2026) 3% 6% (2) Implied Premium / (Discount) to Unaffected 30-Day VWAP 25% 22% 29% Basic Shares 106,750,881 106,750,881 106,750,881 (+) Dilution 11,293,002 11,185,996 11,412,471 Fully Diluted Shares Outstanding 118,043,883 117,936,877 118,163,352 Equity Value ($MM) 1,864 1,815 1,920 (+) Total Debt ($MM) 2 2 2 (-) Cash & Equivalents ($MM) (212) (212) (212) Aggregate Value ($MM) 1,654 1,605 1,710 Implied Transaction Multiples Revenue ($MM) (3) AV / 2027E Revenue – Street Consensus 115 14.4x 14.0x 14.9x (3) AV / 2027E Revenue – Taurus Case 115 14.4x 14.0x 14.9x (3) AV / 2028E Revenue – Street Consensus 172 9.6x 9.3x 10.0x AV / 2028E Revenue – Taurus Case 172 9.6x 9.3x 10.0x Dilution Calculation Count WAEP ($ / Share) Unaffected Dilution Current Dilution Offer Dilution RSUs 626,715 $ -- 626,715 626,715 626,715 PSUs 575,000 $ -- 575,000 575,000 575,000 Stock Options Tranches 14,897,569 $5.33 10,091,287 9,984,281 10,210,756 Total Dilution 16,099,284 11,293,002 11,185,996 11,412,471 Sources: Taurus Case projections for Polaris as of 6/30/2026, as provided by Taurus management, Polaris cash and cash equivalents and debt as of 6/30/2026, and basic shares outstanding and dilutive securities data as of 7/16/2026, as provided by Polaris management, company filings, Wall Street research, Capital IQ Notes: 1. Market data as of 7/17/2026; unaffected date based on 7/15/2026 market close, last close prior to public rumors of a potential transaction on 7/16/2026 5 2. Unaffected 30-day VWAP based on trading days using Bloomberg data as of 7/15/2026 market close, last close prior to public rumors of a potential transaction on 7/16/2026 3. Shown for reference only
SECTION 2 Valuation Analysis 6
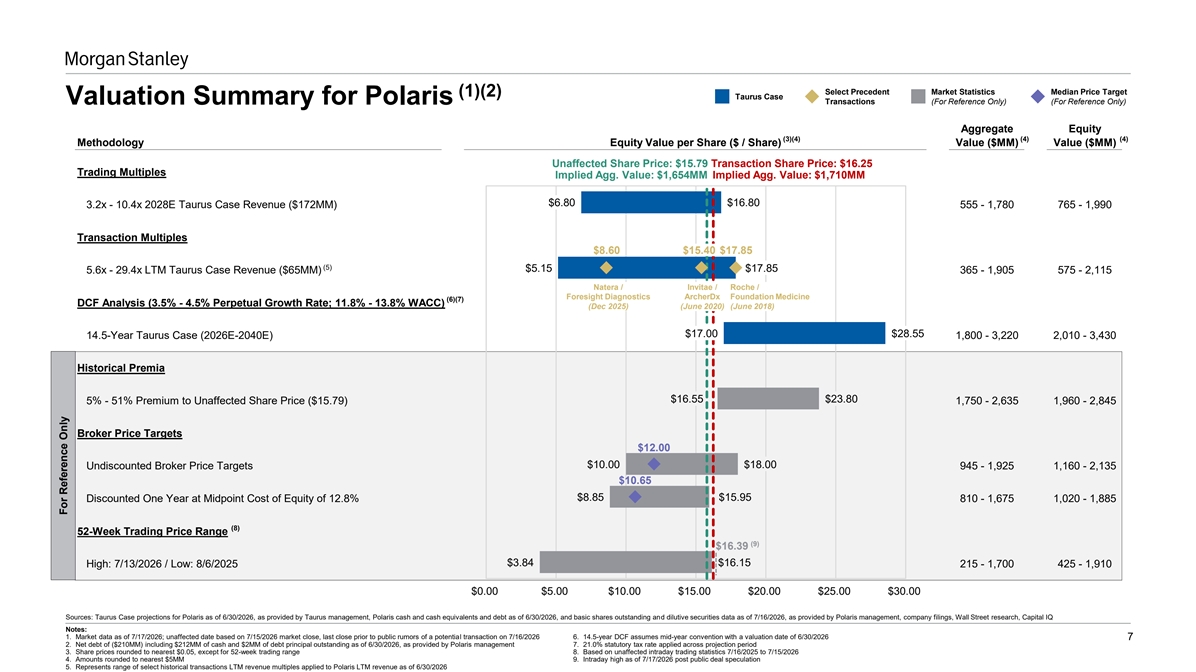
Select Precedent Market Statistics Median Price Target (1)(2) Taurus Case Transactions (For Reference Only) (For Reference Only) Valuation Summary for Polaris Aggregate Equity (3)(4) (4) (4) Methodology Equity Value per Share ($ / Share) Value ($MM) Value ($MM) Unaffected Share Price: $15.79 Transaction Share Price: $16.25 Trading Multiples Implied Agg. Value: $1,654MM Implied Agg. Value: $1,710MM $6.80 $16.80 3.2x - 10.4x 2028E Taurus Case Revenue ($172MM) 555 - 1,780 765 - 1,990 Transaction Multiples $8.60 $15.40 $17.85 (5) $5.15 $17.85 5.6x - 29.4x LTM Taurus Case Revenue ($65MM) 365 - 1,905 575 - 2,115 Natera / Invitae / Roche / Foresight Diagnostics ArcherDx Foundation Medicine (6)(7) DCF Analysis (3.5% - 4.5% Perpetual Growth Rate; 11.8% - 13.8% WACC) (Dec 2025) (June 2020) (June 2018) $17.00 $28.55 14.5-Year Taurus Case (2026E-2040E) 1,800 - 3,220 2,010 - 3,430 Historical Premia $16.55 $23.80 5% - 51% Premium to Unaffected Share Price ($15.79) 1,750 - 2,635 1,960 - 2,845 Broker Price Targets $12.00 $10.00 $18.00 Undiscounted Broker Price Targets 945 - 1,925 1,160 - 2,135 $10.65 $8.85 $15.95 Discounted One Year at Midpoint Cost of Equity of 12.8% 810 - 1,675 1,020 - 1,885 (8) 52-Week Trading Price Range (9) $16.39 $3.84 $16.15 High: 7/13/2026 / Low: 8/6/2025 215 - 1,700 425 - 1,910 $0.00 $5.00 $10.00 $15.00 $20.00 $25.00 $30.00 Sources: Taurus Case projections for Polaris as of 6/30/2026, as provided by Taurus management, Polaris cash and cash equivalents and debt as of 6/30/2026, and basic shares outstanding and dilutive securities data as of 7/16/2026, as provided by Polaris management, company filings, Wall Street research, Capital IQ Notes: 1. Market data as of 7/17/2026; unaffected date based on 7/15/2026 market close, last close prior to public rumors of a potential transaction on 7/16/2026 6. 14.5-year DCF assumes mid-year convention with a valuation date of 6/30/2026 7 2. Net debt of ($210MM) including $212MM of cash and $2MM of debt principal outstanding as of 6/30/2026, as provided by Polaris management 7. 21.0% statutory tax rate applied across projection period 3. Share prices rounded to nearest $0.05, except for 52-week trading range 8. Based on unaffected intraday trading statistics 7/16/2025 to 7/15/2026 4. Amounts rounded to nearest $5MM 9. Intraday high as of 7/17/2026 post public deal speculation 5. Represents range of select historical transactions LTM revenue multiples applied to Polaris LTM revenue as of 6/30/2026 For Reference Only
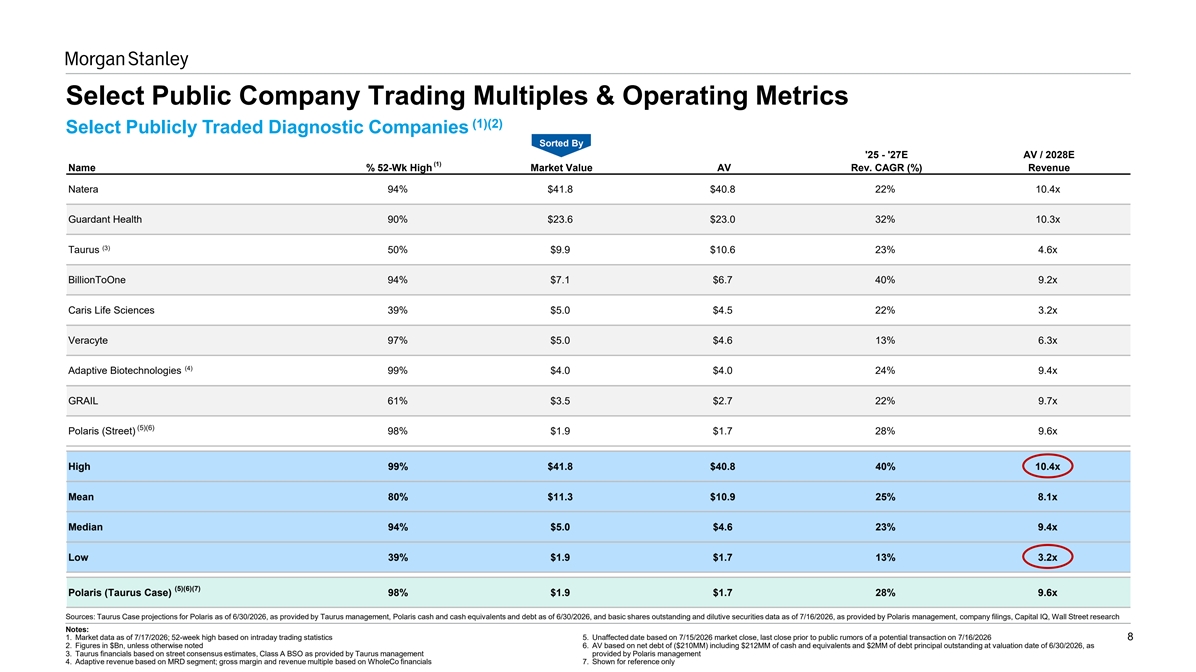
Select Public Company Trading Multiples & Operating Metrics (1)(2) Select Publicly Traded Diagnostic Companies Sorted By '25 - '27E AV / 2028E (1) Name % 52-Wk High Market Value AV Rev. CAGR (%) Revenue Natera 94% $41.8 $40.8 22% 10.4x Guardant Health 90% $23.6 $23.0 32% 10.3x (3) Taurus 50% $9.9 $10.6 23% 4.6x BillionToOne 94% $7.1 $6.7 40% 9.2x Caris Life Sciences 39% $5.0 $4.5 22% 3.2x Veracyte 97% $5.0 $4.6 13% 6.3x (4) Adaptive Biotechnologies 99% $4.0 $4.0 24% 9.4x GRAIL 61% $3.5 $2.7 22% 9.7x (5)(6) Polaris (Street) 98% $1.9 $1.7 28% 9.6x High 99% $41.8 $40.8 40% 10.4x Mean 80% $11.3 $10.9 25% 8.1x Median 94% $5.0 $4.6 23% 9.4x Low 39% $1.9 $1.7 13% 3.2x (5)(6)(7) Polaris (Taurus Case) 98% $1.9 $1.7 28% 9.6x Sources: Taurus Case projections for Polaris as of 6/30/2026, as provided by Taurus management, Polaris cash and cash equivalents and debt as of 6/30/2026, and basic shares outstanding and dilutive securities data as of 7/16/2026, as provided by Polaris management, company filings, Capital IQ, Wall Street research Notes: 1. Market data as of 7/17/2026; 52-week high based on intraday trading statistics 5. Unaffected date based on 7/15/2026 market close, last close prior to public rumors of a potential transaction on 7/16/2026 8 2. Figures in $Bn, unless otherwise noted 6. AV based on net debt of ($210MM) including $212MM of cash and equivalents and $2MM of debt principal outstanding at valuation date of 6/30/2026, as 3. Taurus financials based on street consensus estimates, Class A BSO as provided by Taurus management provided by Polaris management 4. Adaptive revenue based on MRD segment; gross margin and revenue multiple based on WholeCo financials 7. Shown for reference only
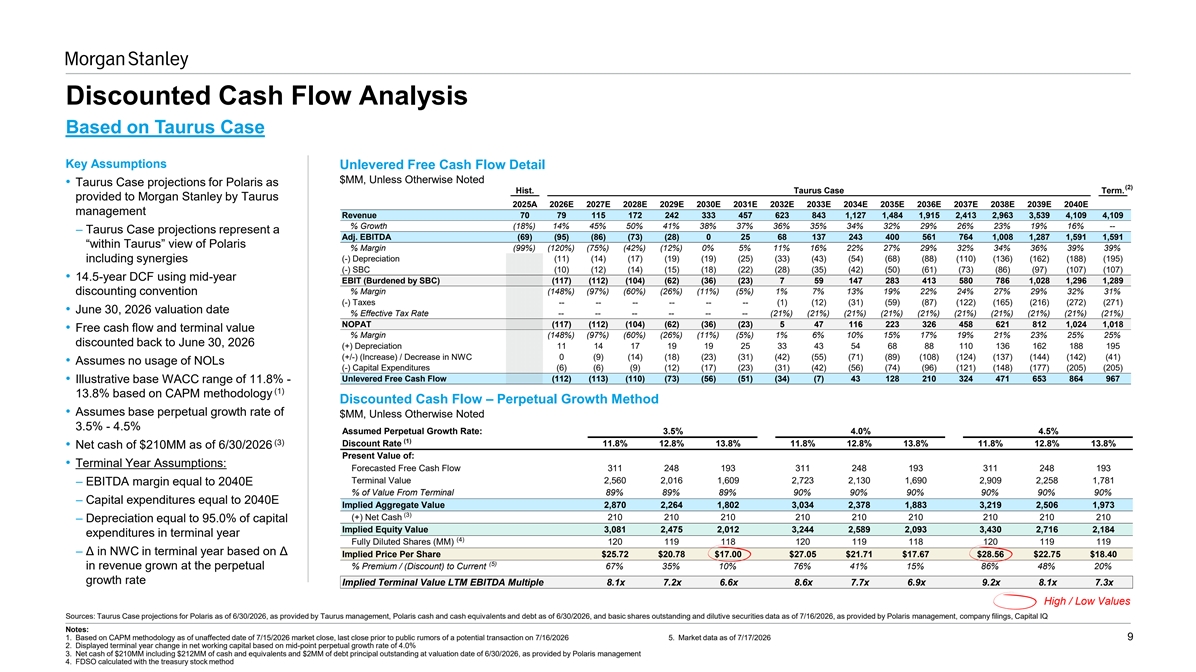
Discounted Cash Flow Analysis Based on Taurus Case Key Assumptions Unlevered Free Cash Flow Detail $MM, Unless Otherwise Noted • Taurus Case projections for Polaris as (2) Hist. Taurus Case Term. provided to Morgan Stanley by Taurus 2025A 2026E 2027E 2028E 2029E 2030E 2031E 2032E 2033E 2034E 2035E 2036E 2037E 2038E 2039E 2040E management Revenue 70 79 115 172 242 333 457 623 843 1,127 1,484 1,915 2,413 2,963 3,539 4,109 4,109 % Growth (18%) 14% 45% 50% 41% 38% 37% 36% 35% 34% 32% 29% 26% 23% 19% 16% -- – Taurus Case projections represent a Adj. EBITDA (69) (95) (86) (73) (28) 0 25 68 137 243 400 561 764 1,008 1,287 1,591 1,591 “within Taurus” view of Polaris % Margin (99%) (120%) (75%) (42%) (12%) 0% 5% 11% 16% 22% 27% 29% 32% 34% 36% 39% 39% (-) Depreciation (11) (14) (17) (19) (19) (25) (33) (43) (54) (68) (88) (110) (136) (162) (188) (195) including synergies (-) SBC (10) (12) (14) (15) (18) (22) (28) (35) (42) (50) (61) (73) (86) (97) (107) (107) • 14.5-year DCF using mid-year EBIT (Burdened by SBC) (117) (112) (104) (62) (36) (23) 7 59 147 283 413 580 786 1,028 1,296 1,289 % Margin (148%) (97%) (60%) (26%) (11%) (5%) 1% 7% 13% 19% 22% 24% 27% 29% 32% 31% discounting convention (-) Taxes -- -- -- -- -- -- (1) (12) (31) (59) (87) (122) (165) (216) (272) (271) • June 30, 2026 valuation date % Effective Tax Rate -- -- -- -- -- -- (21%) (21%) (21%) (21%) (21%) (21%) (21%) (21%) (21%) (21%) NOPAT (117) (112) (104) (62) (36) (23) 5 47 116 223 326 458 621 812 1,024 1,018 • Free cash flow and terminal value % Margin (148%) (97%) (60%) (26%) (11%) (5%) 1% 6% 10% 15% 17% 19% 21% 23% 25% 25% discounted back to June 30, 2026 (+) Depreciation 11 14 17 19 19 25 33 43 54 68 88 110 136 162 188 195 (+/-) (Increase) / Decrease in NWC 0 (9) (14) (18) (23) (31) (42) (55) (71) (89) (108) (124) (137) (144) (142) (41) • Assumes no usage of NOLs (-) Capital Expenditures (6) (6) (9) (12) (17) (23) (31) (42) (56) (74) (96) (121) (148) (177) (205) (205) Unlevered Free Cash Flow (112) (113) (110) (73) (56) (51) (34) (7) 43 128 210 324 471 653 864 967 • Illustrative base WACC range of 11.8% - (1) 13.8% based on CAPM methodology Discounted Cash Flow – Perpetual Growth Method • Assumes base perpetual growth rate of $MM, Unless Otherwise Noted 3.5% - 4.5% Assumed Perpetual Growth Rate: 3.5% 4.0% 4.5% (1) (3) Discount Rate 11.8% 12.8% 13.8% 11.8% 12.8% 13.8% 11.8% 12.8% 13.8% • Net cash of $210MM as of 6/30/2026 Present Value of: • Terminal Year Assumptions: Forecasted Free Cash Flow 311 248 193 311 248 193 311 248 193 Terminal Value 2,560 2,016 1,609 2,723 2,130 1,690 2,909 2,258 1,781 – EBITDA margin equal to 2040E % of Value From Terminal 89% 89% 89% 90% 90% 90% 90% 90% 90% – Capital expenditures equal to 2040E Implied Aggregate Value 2,870 2,264 1,802 3,034 2,378 1,883 3,219 2,506 1,973 (3) (+) Net Cash 210 210 210 210 210 210 210 210 210 – Depreciation equal to 95.0% of capital Implied Equity Value 3,081 2,475 2,012 3,244 2,589 2,093 3,430 2,716 2,184 expenditures in terminal year (4) Fully Diluted Shares (MM) 120 119 118 120 119 118 120 119 119 – Δ in NWC in terminal year based on Δ Implied Price Per Share $25.72 $20.78 $17.00 $27.05 $21.71 $17.67 $28.56 $22.75 $18.40 (5) in revenue grown at the perpetual % Premium / (Discount) to Current 67% 35% 10% 76% 41% 15% 86% 48% 20% growth rate Implied Terminal Value LTM EBITDA Multiple 8.1x 7.2x 6.6x 8.6x 7.7x 6.9x 9.2x 8.1x 7.3x High / Low Values Sources: Taurus Case projections for Polaris as of 6/30/2026, as provided by Taurus management, Polaris cash and cash equivalents and debt as of 6/30/2026, and basic shares outstanding and dilutive securities data as of 7/16/2026, as provided by Polaris management, company filings, Capital IQ Notes: 1. Based on CAPM methodology as of unaffected date of 7/15/2026 market close, last close prior to public rumors of a potential transaction on 7/16/2026 5. Market data as of 7/17/2026 9 2. Displayed terminal year change in net working capital based on mid-point perpetual growth rate of 4.0% 3. Net cash of $210MM including $212MM of cash and equivalents and $2MM of debt principal outstanding at valuation date of 6/30/2026, as provided by Polaris management 4. FDSO calculated with the treasury stock method
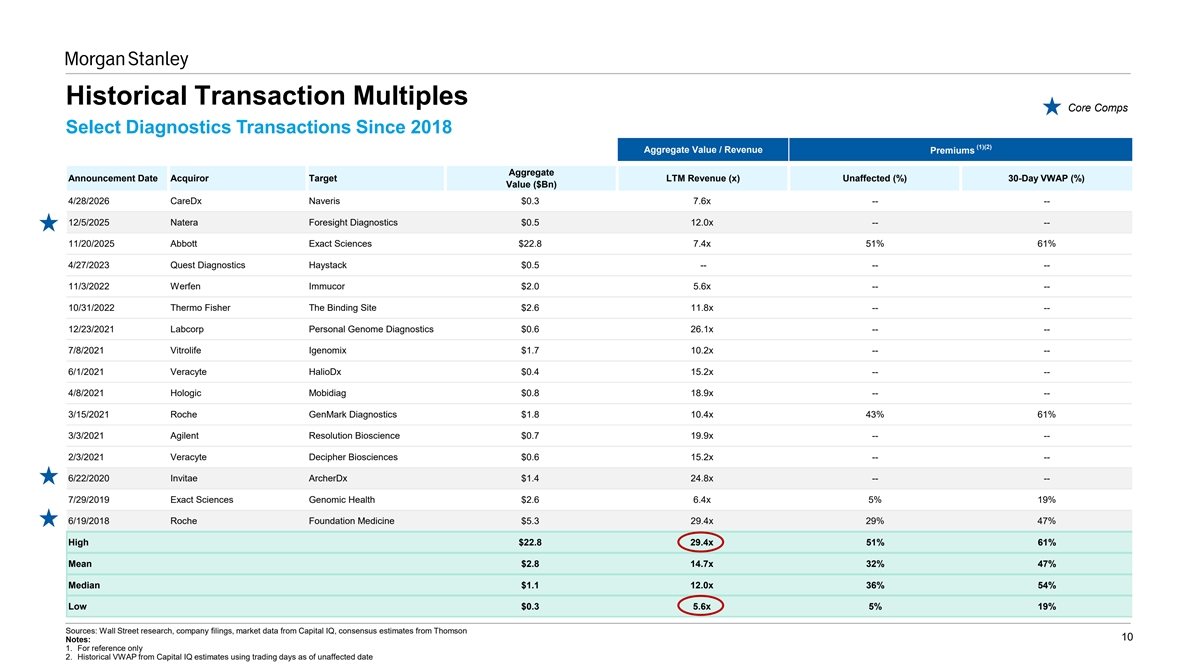
Historical Transaction Multiples Core Comps Select Diagnostics Transactions Since 2018 (1)(2) Aggregate Value / Revenue Premiums Aggregate Announcement Date Acquiror Target LTM Revenue (x) Unaffected (%) 30-Day VWAP (%) Value ($Bn) 4/28/2026 CareDx Naveris $0.3 7.6x -- -- 12/5/2025 Natera Foresight Diagnostics $0.5 12.0x -- -- 11/20/2025 Abbott Exact Sciences $22.8 7.4x 51% 61% 4/27/2023 Quest Diagnostics Haystack $0.5 -- -- -- 11/3/2022 Werfen Immucor $2.0 5.6x -- -- 10/31/2022 Thermo Fisher The Binding Site $2.6 11.8x -- -- 12/23/2021 Labcorp Personal Genome Diagnostics $0.6 26.1x -- -- 7/8/2021 Vitrolife Igenomix $1.7 10.2x -- -- 6/1/2021 Veracyte HalioDx $0.4 15.2x -- -- 4/8/2021 Hologic Mobidiag $0.8 18.9x -- -- 3/15/2021 Roche GenMark Diagnostics $1.8 10.4x 43% 61% 3/3/2021 Agilent Resolution Bioscience $0.7 19.9x -- -- 2/3/2021 Veracyte Decipher Biosciences $0.6 15.2x -- -- 6/22/2020 Invitae ArcherDx $1.4 24.8x -- -- 7/29/2019 Exact Sciences Genomic Health $2.6 6.4x 5% 19% 6/19/2018 Roche Foundation Medicine $5.3 29.4x 29% 47% High $22.8 29.4x 51% 61% Mean $2.8 14.7x 32% 47% Median $1.1 12.0x 36% 54% Low $0.3 5.6x 5% 19% Sources: Wall Street research, company filings, market data from Capital IQ, consensus estimates from Thomson 10 Notes: 1. For reference only 2. Historical VWAP from Capital IQ estimates using trading days as of unaffected date
APPENDIX Supplemental Materials 11
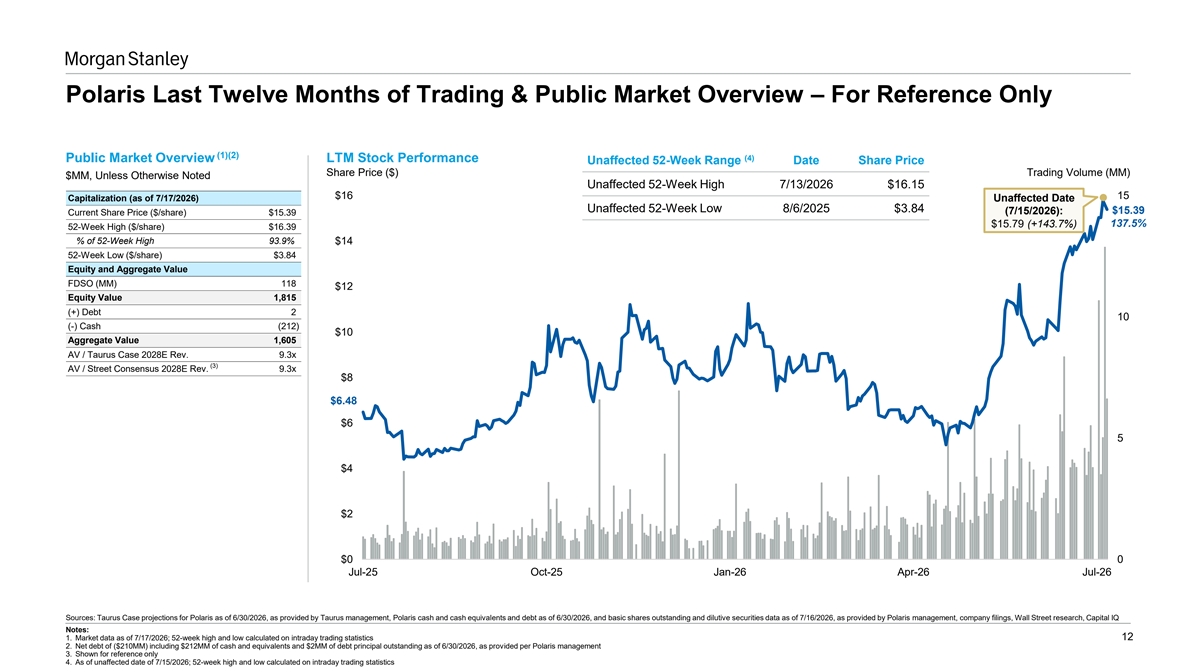
Polaris Last Twelve Months of Trading & Public Market Overview – For Reference Only (1)(2) (4) Public Market Overview LTM Stock Performance Unaffected 52-Week Range Date Share Price Share Price ($) Trading Volume (MM) $MM, Unless Otherwise Noted Unaffected 52-Week High 7/13/2026 $16.15 $16 15 Capitalization (as of 7/17/2026) Unaffected Date Unaffected 52-Week Low 8/6/2025 $3.84 (7/15/2026): $15.39 Current Share Price ($/share) $15.39 137.5% $15.79 (+143.7%) 52-Week High ($/share) $16.39 % of 52-Week High 93.9% $14 52-Week Low ($/share) $3.84 Equity and Aggregate Value FDSO (MM) 118 $12 Equity Value 1,815 (+) Debt 2 10 (-) Cash (212) $10 Aggregate Value 1,605 AV / Taurus Case 2028E Rev. 9.3x (3) AV / Street Consensus 2028E Rev. 9.3x $8 $6.48 $6 5 $4 $2 $0 0 Jul-25 Oct-25 Jan-26 Apr-26 Jul-26 Sources: Taurus Case projections for Polaris as of 6/30/2026, as provided by Taurus management, Polaris cash and cash equivalents and debt as of 6/30/2026, and basic shares outstanding and dilutive securities data as of 7/16/2026, as provided by Polaris management, company filings, Wall Street research, Capital IQ Notes: 12 1. Market data as of 7/17/2026; 52-week high and low calculated on intraday trading statistics 2. Net debt of ($210MM) including $212MM of cash and equivalents and $2MM of debt principal outstanding as of 6/30/2026, as provided per Polaris management 3. Shown for reference only 4. As of unaffected date of 7/15/2026; 52-week high and low calculated on intraday trading statistics
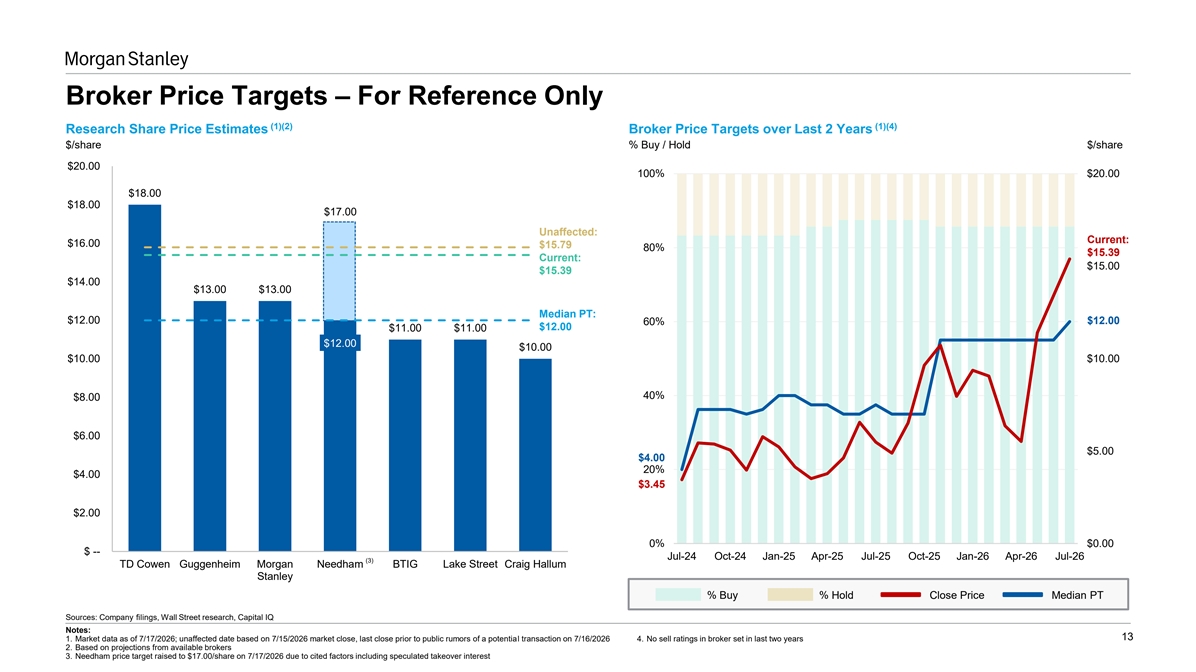
Broker Price Targets – For Reference Only (1)(2) (1)(4) Research Share Price Estimates Broker Price Targets over Last 2 Years $/share % Buy / Hold $/share $20.00 100% $20.00 $18.00 $18.00 $17.00 Unaffected: Current: $16.00 $15.79 80% $15.39 Current: $15.00 $15.39 $14.00 $13.00 $13.00 Median PT: $12.00 $12.00 60% $12.00 $11.00 $11.00 $12.00 $10.00 $10.00 $10.00 40% $8.00 $6.00 $5.00 $4.00 20% $4.00 $3.45 $2.00 0% $0.00 $ -- Jul-24 Oct-24 Jan-25 Apr-25 Jul-25 Oct-25 Jan-26 Apr-26 Jul-26 (3) TD Cowen Guggenheim Morgan Needham BTIG Lake Street Craig Hallum Stanley % Buy % Hold Close Price Median PT Sources: Company filings, Wall Street research, Capital IQ Notes: 13 1. Market data as of 7/17/2026; unaffected date based on 7/15/2026 market close, last close prior to public rumors of a potential transaction on 7/16/2026 4. No sell ratings in broker set in last two years 2. Based on projections from available brokers 3. Needham price target raised to $17.00/share on 7/17/2026 due to cited factors including speculated takeover interest
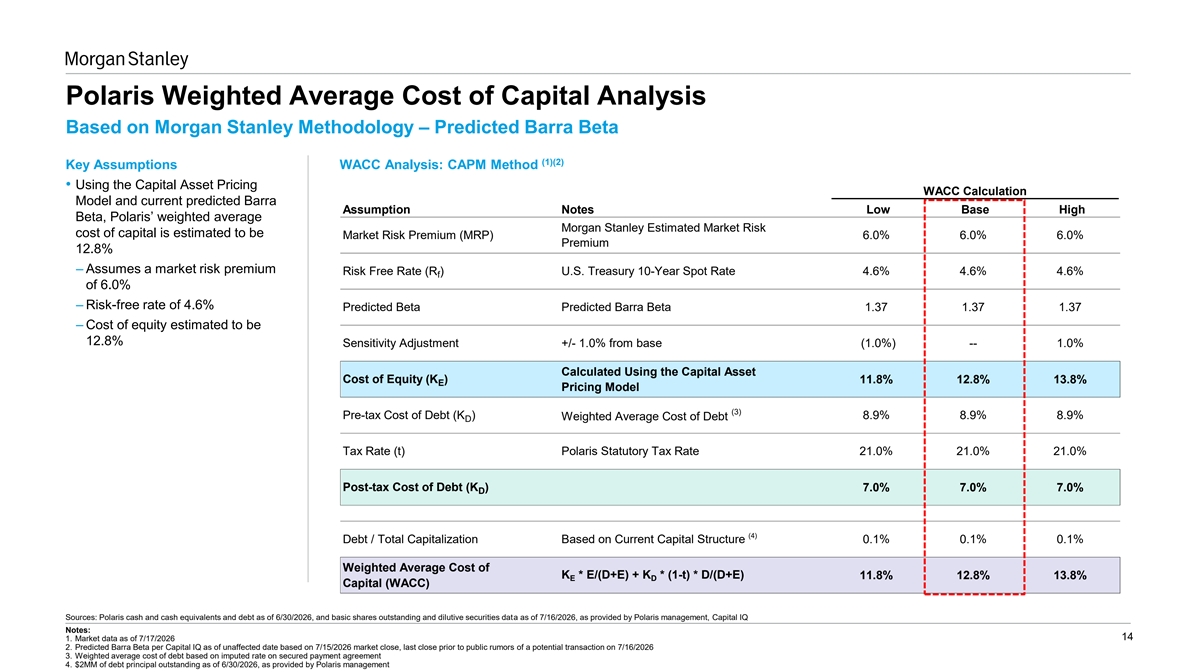
Polaris Weighted Average Cost of Capital Analysis Based on Morgan Stanley Methodology – Predicted Barra Beta (1)(2) Key Assumptions WACC Analysis: CAPM Method • Using the Capital Asset Pricing WACC Calculation Model and current predicted Barra Assumption Notes Low Base High Beta, Polaris’ weighted average Morgan Stanley Estimated Market Risk cost of capital is estimated to be Market Risk Premium (MRP) 6.0% 6.0% 6.0% Premium 12.8% – Assumes a market risk premium Risk Free Rate (R ) U.S. Treasury 10-Year Spot Rate 4.6% 4.6% 4.6% f of 6.0% – Risk-free rate of 4.6% Predicted Beta Predicted Barra Beta 1.37 1.37 1.37 – Cost of equity estimated to be 12.8% Sensitivity Adjustment +/- 1.0% from base (1.0%) -- 1.0% Calculated Using the Capital Asset Cost of Equity (K ) 11.8% 12.8% 13.8% E Pricing Model (3) Pre-tax Cost of Debt (K ) 8.9% 8.9% 8.9% Weighted Average Cost of Debt D Tax Rate (t) Polaris Statutory Tax Rate 21.0% 21.0% 21.0% Post-tax Cost of Debt (K ) 7.0% 7.0% 7.0% D (4) Debt / Total Capitalization Based on Current Capital Structure 0.1% 0.1% 0.1% Weighted Average Cost of K * E/(D+E) + K * (1-t) * D/(D+E) 11.8% 12.8% 13.8% E D Capital (WACC) Sources: Polaris cash and cash equivalents and debt as of 6/30/2026, and basic shares outstanding and dilutive securities data as of 7/16/2026, as provided by Polaris management, Capital IQ Notes: 14 1. Market data as of 7/17/2026 2. Predicted Barra Beta per Capital IQ as of unaffected date based on 7/15/2026 market close, last close prior to public rumors of a potential transaction on 7/16/2026 3. Weighted average cost of debt based on imputed rate on secured payment agreement 4. $2MM of debt principal outstanding as of 6/30/2026, as provided by Polaris management
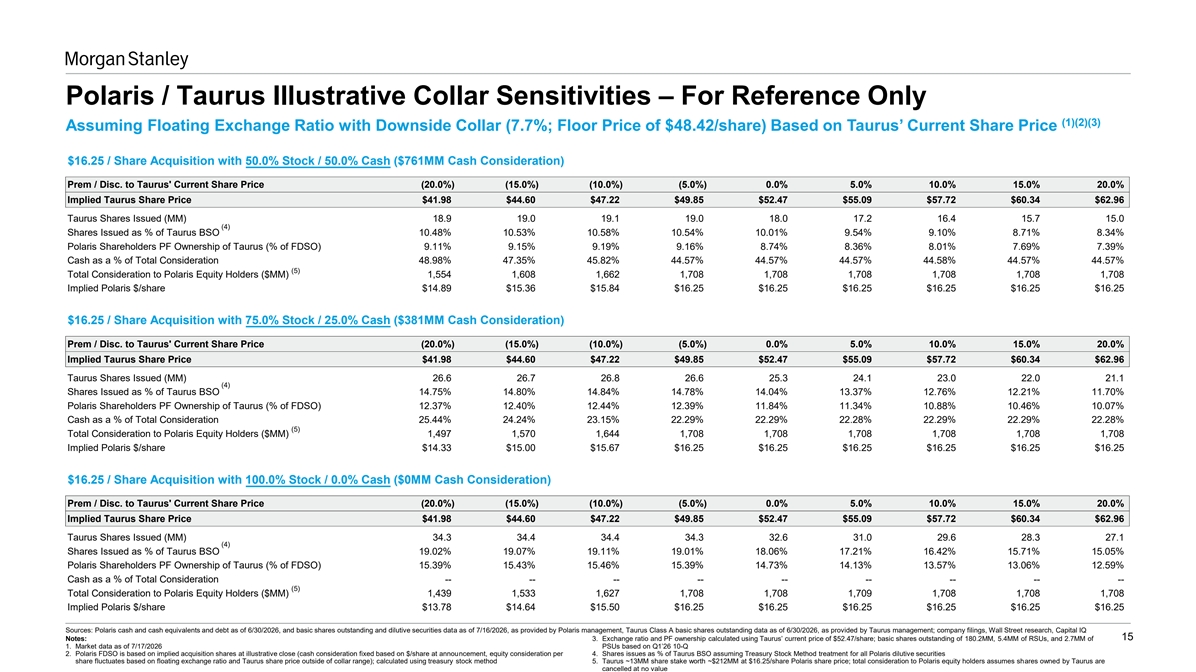
Polaris / Taurus Illustrative Collar Sensitivities – For Reference Only (1)(2)(3) Assuming Floating Exchange Ratio with Downside Collar (7.7%; Floor Price of $48.42/share) Based on Taurus’ Current Share Price $16.25 / Share Acquisition with 50.0% Stock / 50.0% Cash ($761MM Cash Consideration) Prem / Disc. to Taurus' Current Share Price (20.0%) (15.0%) (10.0%) (5.0%) 0.0% 5.0% 10.0% 15.0% 20.0% Implied Taurus Share Price $41.98 $44.60 $47.22 $49.85 $52.47 $55.09 $57.72 $60.34 $62.96 Taurus Shares Issued (MM) 18.9 19.0 19.1 19.0 18.0 17.2 16.4 15.7 15.0 (4) Shares Issued as % of Taurus BSO 10.48% 10.53% 10.58% 10.54% 10.01% 9.54% 9.10% 8.71% 8.34% Polaris Shareholders PF Ownership of Taurus (% of FDSO) 9.11% 9.15% 9.19% 9.16% 8.74% 8.36% 8.01% 7.69% 7.39% Cash as a % of Total Consideration 48.98% 47.35% 45.82% 44.57% 44.57% 44.57% 44.58% 44.57% 44.57% (5) Total Consideration to Polaris Equity Holders ($MM) 1,554 1,608 1,662 1,708 1,708 1,708 1,708 1,708 1,708 Implied Polaris $/share $14.89 $15.36 $15.84 $16.25 $16.25 $16.25 $16.25 $16.25 $16.25 $16.25 / Share Acquisition with 75.0% Stock / 25.0% Cash ($381MM Cash Consideration) Prem / Disc. to Taurus' Current Share Price (20.0%) (15.0%) (10.0%) (5.0%) 0.0% 5.0% 10.0% 15.0% 20.0% Implied Taurus Share Price $41.98 $44.60 $47.22 $49.85 $52.47 $55.09 $57.72 $60.34 $62.96 Taurus Shares Issued (MM) 26.6 26.7 26.8 26.6 25.3 24.1 23.0 22.0 21.1 (4) Shares Issued as % of Taurus BSO 14.75% 14.80% 14.84% 14.78% 14.04% 13.37% 12.76% 12.21% 11.70% Polaris Shareholders PF Ownership of Taurus (% of FDSO) 12.37% 12.40% 12.44% 12.39% 11.84% 11.34% 10.88% 10.46% 10.07% Cash as a % of Total Consideration 25.44% 24.24% 23.15% 22.29% 22.29% 22.28% 22.29% 22.29% 22.28% (5) Total Consideration to Polaris Equity Holders ($MM) 1,497 1,570 1,644 1,708 1,708 1,708 1,708 1,708 1,708 Implied Polaris $/share $14.33 $15.00 $15.67 $16.25 $16.25 $16.25 $16.25 $16.25 $16.25 $16.25 / Share Acquisition with 100.0% Stock / 0.0% Cash ($0MM Cash Consideration) Prem / Disc. to Taurus' Current Share Price (20.0%) (15.0%) (10.0%) (5.0%) 0.0% 5.0% 10.0% 15.0% 20.0% Implied Taurus Share Price $41.98 $44.60 $47.22 $49.85 $52.47 $55.09 $57.72 $60.34 $62.96 Taurus Shares Issued (MM) 34.3 34.4 34.4 34.3 32.6 31.0 29.6 28.3 27.1 (4) Shares Issued as % of Taurus BSO 19.02% 19.07% 19.11% 19.01% 18.06% 17.21% 16.42% 15.71% 15.05% Polaris Shareholders PF Ownership of Taurus (% of FDSO) 15.39% 15.43% 15.46% 15.39% 14.73% 14.13% 13.57% 13.06% 12.59% Cash as a % of Total Consideration -- -- -- -- -- -- -- -- -- (5) Total Consideration to Polaris Equity Holders ($MM) 1,439 1,533 1,627 1,708 1,708 1,709 1,708 1,708 1,708 Implied Polaris $/share $13.78 $14.64 $15.50 $16.25 $16.25 $16.25 $16.25 $16.25 $16.25 Sources: Polaris cash and cash equivalents and debt as of 6/30/2026, and basic shares outstanding and dilutive securities data as of 7/16/2026, as provided by Polaris management, Taurus Class A basic shares outstanding data as of 6/30/2026, as provided by Taurus management; company filings, Wall Street research, Capital IQ 15 Notes: 3. Exchange ratio and PF ownership calculated using Taurus’ current price of $52.47/share; basic shares outstanding of 180.2MM, 5.4MM of RSUs, and 2.7MM of 1. Market data as of 7/17/2026 PSUs based on Q1’26 10-Q 2. Polaris FDSO is based on implied acquisition shares at illustrative close (cash consideration fixed based on $/share at announcement, equity consideration per 4. Shares issues as % of Taurus BSO assuming Treasury Stock Method treatment for all Polaris dilutive securities share fluctuates based on floating exchange ratio and Taurus share price outside of collar range); calculated using treasury stock method 5. Taurus ~13MM share stake worth ~$212MM at $16.25/share Polaris share price; total consideration to Polaris equity holders assumes shares owned by Taurus are cancelled at no value