Forward-Looking Statements: This supplemental package contains “forward-looking statements” within the meaning of the Private Securities Litigation Reform Act of 1995. We caution investors that any forward-looking statements presented herein are based on management’s beliefs and assumptions and information currently available to management. Such statements are subject to risks, uncertainties and assumptions and may be affected by known and unknown risks, trends, uncertainties and factors that are beyond our control. Should one or more of these risks or uncertainties materialize, or should underlying assumptions prove incorrect, actual results may vary materially from those anticipated, estimated or projected. These risks and uncertainties include, without limitation: general risks affecting the real estate industry (including, without limitation, the market value of our properties, the inability to enter into or renew leases at favorable rates, portfolio occupancy varying from our expectations, dependence on tenants’ financial condition, and competition from other developers, owners and operators of real estate); risks associated with the disruption of credit markets or a global economic slowdown; risks associated with the potential loss of key personnel (most importantly, members of senior management); risks associated with our failure to maintain our status as a Real Estate Investment Trust under the Internal Revenue Code of 1986, as amended; possible adverse changes in tax and environmental laws; an epidemic or pandemic (such as the outbreak and worldwide spread of novel coronavirus (COVID-19), and the measures that international, federal, state and local governments, agencies, law enforcement and/or health authorities may implement to address it, which may (as with COVID-19) precipitate or exacerbate one or more of the above-mentioned factors and/or other risks, and significantly disrupt or prevent us from operating our business in the ordinary course for an extended period; litigation, including costs associated with prosecuting or defending pending or threatened claims and any adverse outcomes, and potential liability for uninsured losses and environmental contamination.
For a further discussion of these and other factors that could cause our future results to differ materially from any forward-looking statements, see Item 1A. Risk Factors in our 2025 Annual Report on Form 10-K, which was filed with the Securities and Exchange Commission (“SEC”) on February 10, 2026, and other risks described in documents we subsequently file from time to time with the SEC. We disclaim any obligation to publicly update or revise any forward-looking statement to reflect changes in underlying assumptions or factors, of new information, data or methods, future events or other changes.
Our credit ratings, which are disclosed on page 4, may not reflect the potential impact of risks relating to the structure or trading of the Company's securities and are provided solely for informational purposes. Credit ratings are not recommendations to buy, sell or hold any security, and may be revised or withdrawn at any time by the issuing organization in its sole discretion. The Company does not undertake any obligation to maintain the ratings or to advise of any change in ratings. Each agency's rating should be evaluated independently of any other agency's rating. An explanation of the significance of the ratings may be obtained from each of the rating agencies.
Second Quarter 2026
Supplemental Financial Reporting Package
Page 2
Investor Company Summary.
Executive Management Team
Laura Clark
Chief Executive Officer, Director
John Nahas
Chief Operating Officer
Michael Fitzmaurice
Chief Financial Officer
David E. Lanzer
General Counsel and Corporate Secretary
Board of Directors
Tyler H. Rose
Chairman
Laura Clark
Chief Executive Officer, Director
Robert L. Antin
Director
Diana J. Ingram
Director
Angela L. Kleiman
Director
Debra L. Morris
Director
David P. Stockert
Director
Investor Relations Information
Doug Bettisworth
SVP, Investor Relations and Capital Markets
dbettisworth@rexfordindustrial.com
Equity Research Coverage
BofA Securities
Samir Khanal
(646) 855-1497
J.P. Morgan Securities
Michael Mueller
(212) 622-6689
Barclays
Brendan Lynch
(212) 526-9428
Jefferies LLC
Jonathan Petersen
(212) 284-1705
BMO Capital Markets
John Kim
(212) 885-4115
Mizuho Securities USA
Vikram Malhotra
(212) 282-3827
BNP Paribas Exane
Nate Crossett
(646) 342-1588
Raymond James & Associates
David Rodgers
(727) 590-6578
Cantor Fitzgerald
Richard Anderson
(929) 441-6927
Robert W. Baird & Co.
Nicholas Thillman
(414) 298-5053
Citigroup Investment Research
Craig Mailman
(212) 816-4471
Scotiabank
Greg McGinniss
(212) 225-6906
Colliers Securities
Barry Oxford
(203) 961-6573
Truist Securities
Anthony Hau
(212) 303-4176
Deutsche Bank
Omotayo Okusanya
(212) 250-9284
Wells Fargo Securities
Blaine Heck
(443) 263-6529
Evercore ISI
Michael Griffin
(212) 446-9462
Wolfe Research
Andrew Rosivach
(646) 582-9250
Green Street Advisors
Vince Tibone
(949) 640-8780
Disclaimer: This list may not be complete and is subject to change as firms add or delete coverage of our company. Please note that any opinions, estimates, forecasts or predictions regarding our historical or predicted performance made by these analysts are theirs alone and do not represent opinions, estimates, forecasts or predictions of Rexford Industrial Realty, Inc. or its management. We are providing this listing as a service to our stockholders and do not by listing these firms imply our endorsement of, or concurrence with, such information, conclusions or recommendations. Interested persons may obtain copies of analysts’ reports on their own; we do not distribute these reports.
Second Quarter 2026
Supplemental Financial Reporting Package
Page 3
Company Overview.
For the Quarter Ended June 30, 2026
Second Quarter 2026
Supplemental Financial Reporting Package
Page 4
Highlights - Consolidated Financial Results.
Quarterly Results
(in millions)
Second Quarter 2026
Supplemental Financial Reporting Package
Page 5
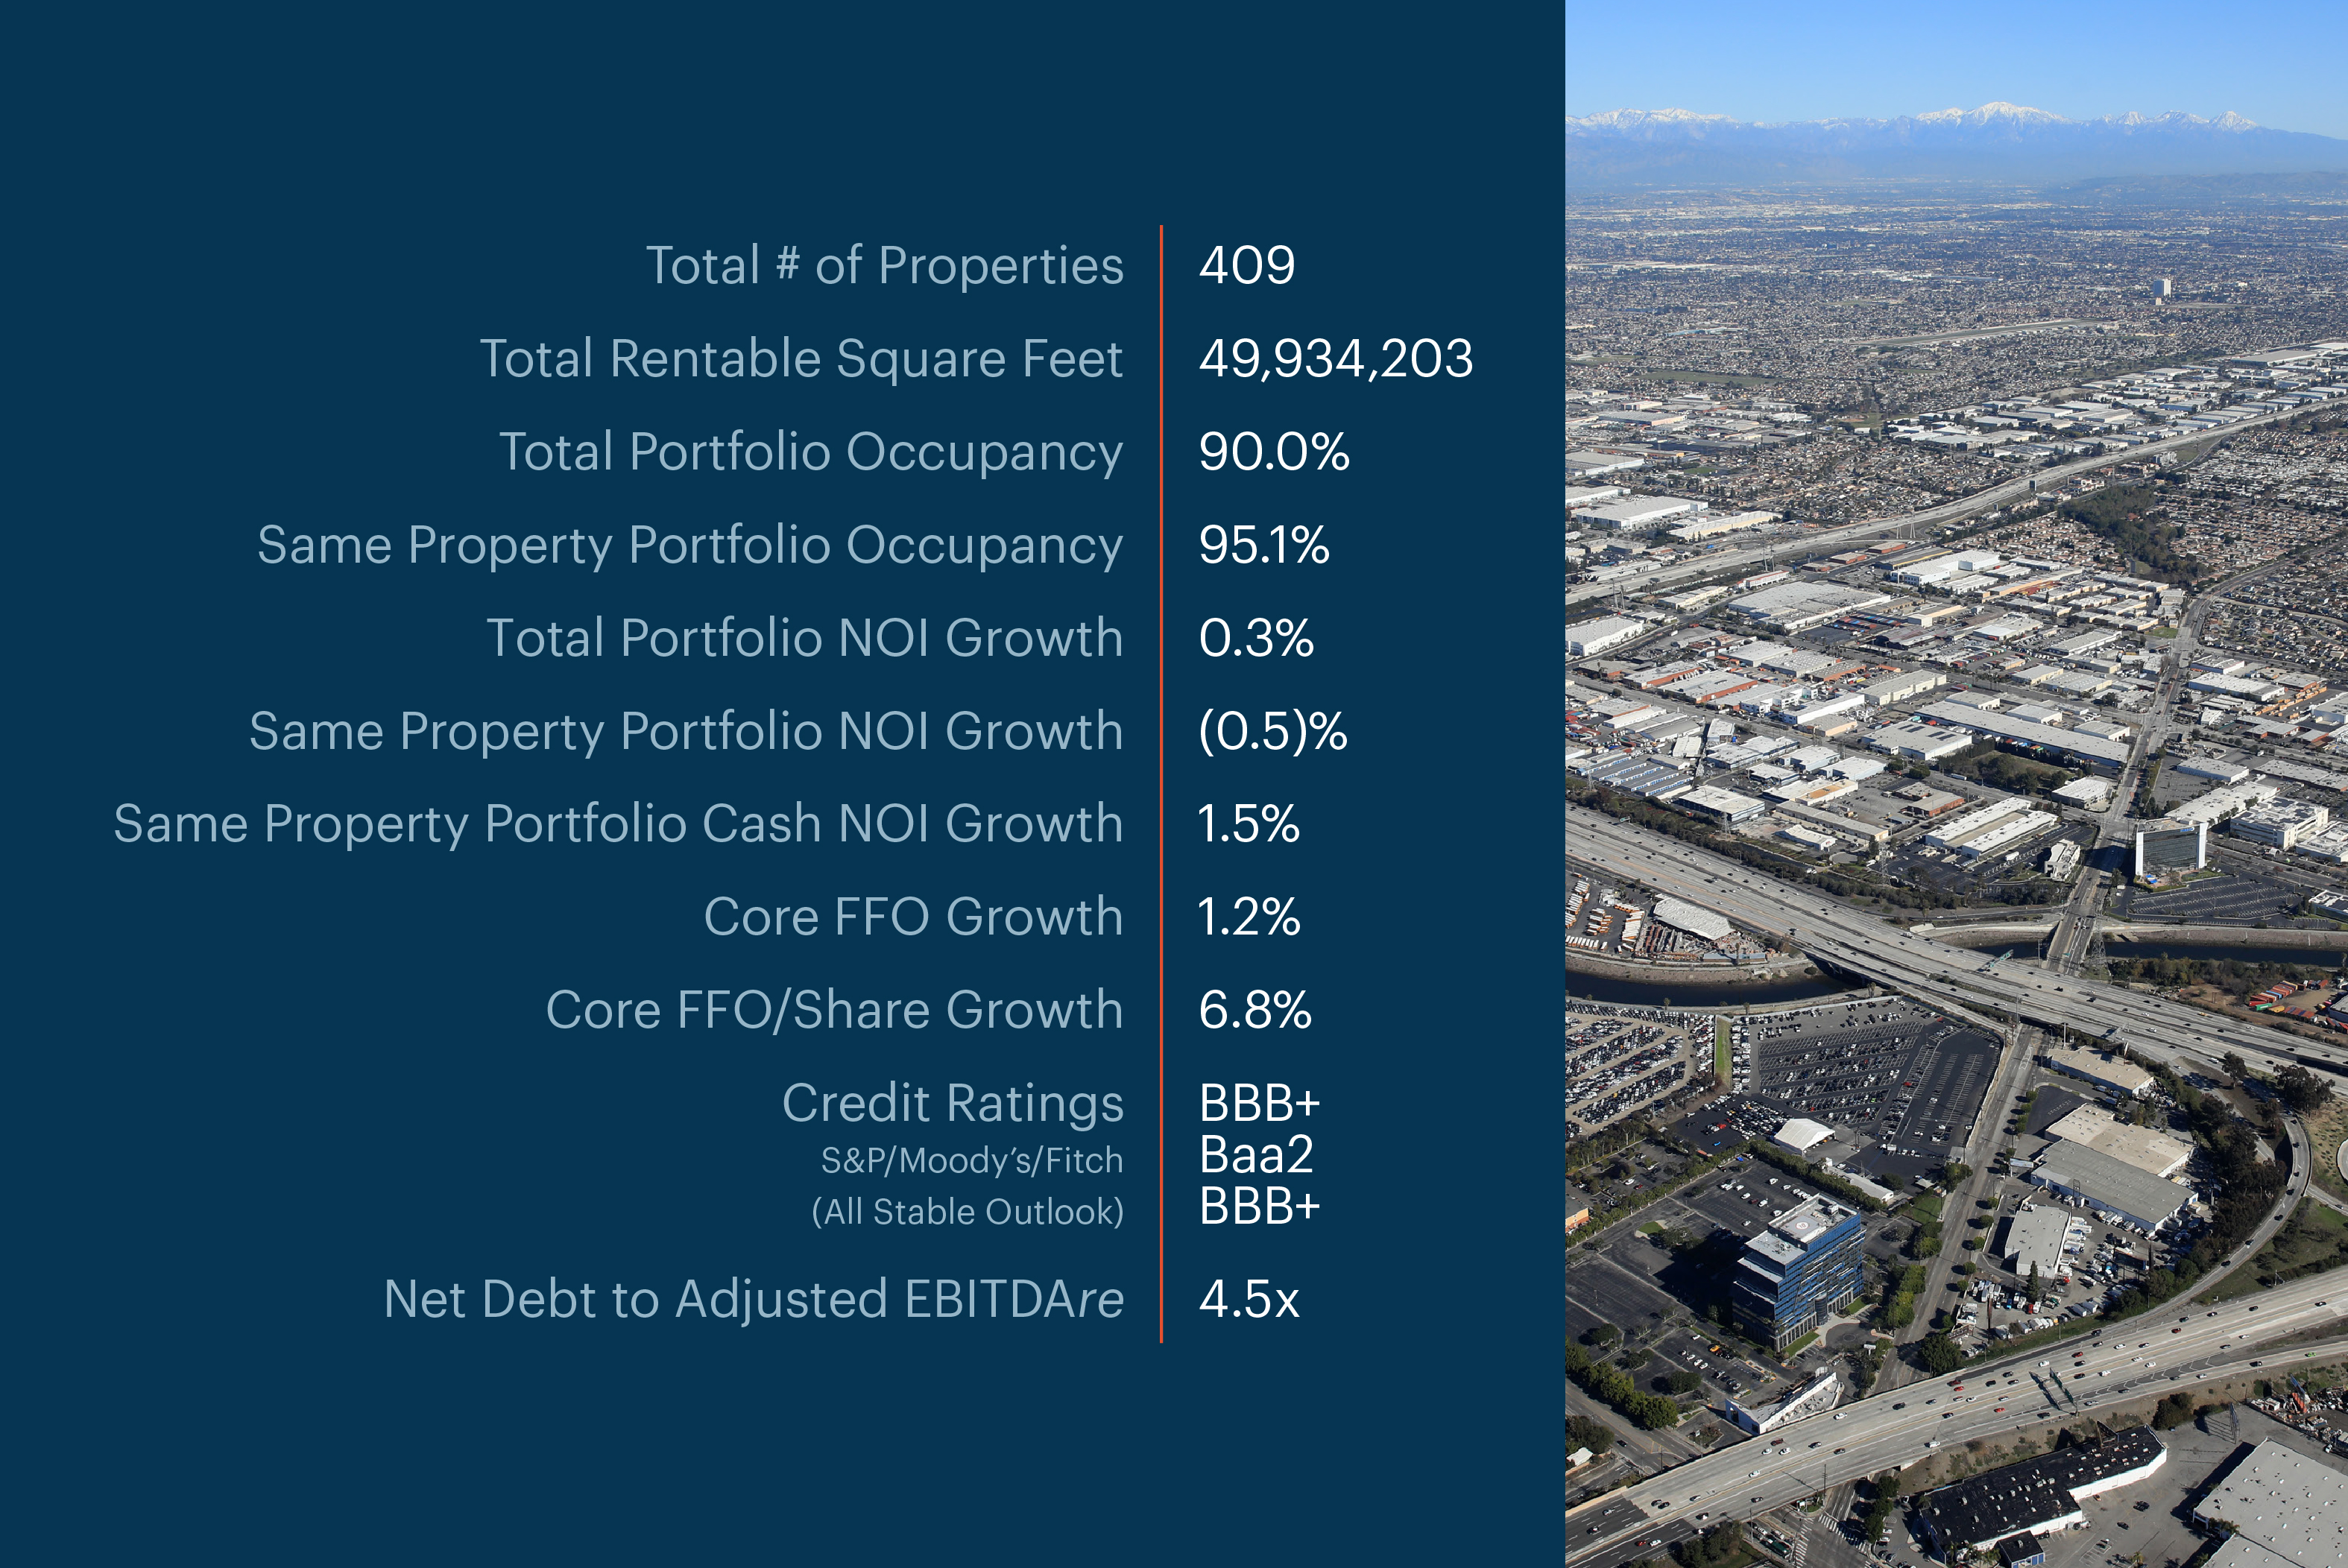
Financial and Portfolio Highlights and Capitalization Data.(1)
(in thousands except share and per share data and portfolio statistics)
Three Months Ended
June 30, 2026
March 31, 2026
December 31, 2025
September 30, 2025
June 30, 2025
Financial Results:
Total rental income
$
242,996
$
242,141
$
243,230
$
246,757
$
241,568
Net (loss) income
$
(523,811)
$
94,562
$
(67,735)
$
93,056
$
120,394
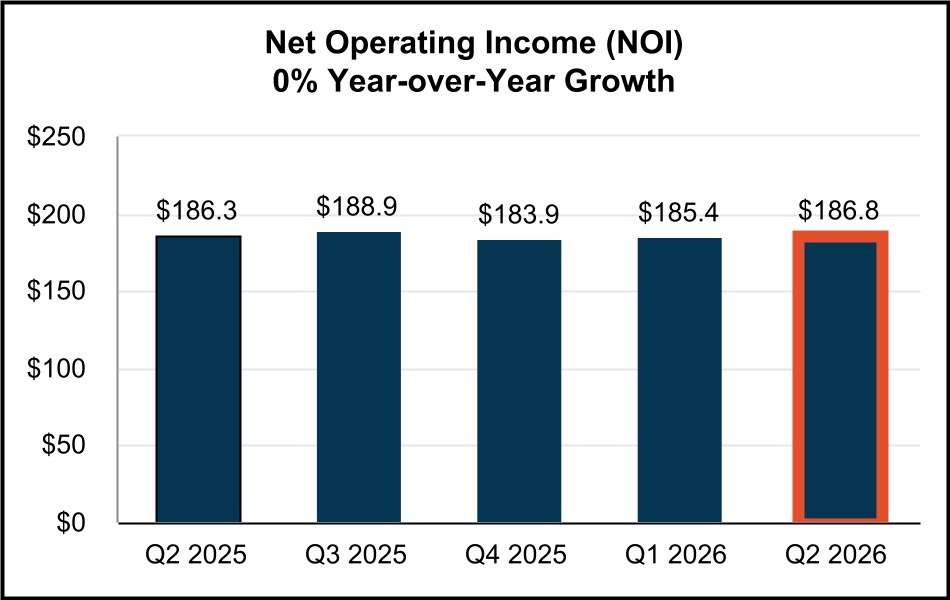
Net Operating Income (NOI)
$
186,782
$
185,378
$
183,943
$
188,878
$
186,270
Company share of Core FFO
$
141,402
$
139,758
$
136,182
$
141,700
$
139,709
Company share of Core FFO per common share - diluted
Total shares and units issued and outstanding at period end(6)
231,077,181
233,127,293
238,245,286
240,452,878
244,334,274
Series B and C Preferred Stock and Series 3 CPOP Units
$
173,250
$
173,250
$
173,250
$
173,250
$
173,250
Total equity market capitalization
$
7,914,336
$
7,803,506
$
9,398,107
$
10,058,268
$
8,864,220
Total consolidated debt
$
3,285,503
$
3,271,720
$
3,278,649
$
3,278,896
$
3,379,141
Total combined market capitalization (net debt plus equity)
$
11,167,613
$
11,023,512
$
12,510,978
$
13,088,208
$
11,812,244
Ratios:
Net debt to total combined market capitalization
29.1%
29.2%
24.9%
23.2%
25.0%
Net debt to Adjusted EBITDAre (quarterly results annualized)
4.5x
4.5x
4.4x
4.1x
4.0x
(1)For definition/discussion of non-GAAP financial measures & reconciliations to their nearest GAAP equivalents, see definitions section & reconciliation section beginning on page 33 and page 12 of this report, respectively.
(2)Rent Change for three months ended March 31, 2026, includes 1.1 million square foot lease extension with Tireco, Inc. at 10545 Production Avenue. Excluding this lease, the Net Effective Rent Change for Q1-2026 was 5.5% and the Cash Rent Change for Q1-2026 was (1.8)%.
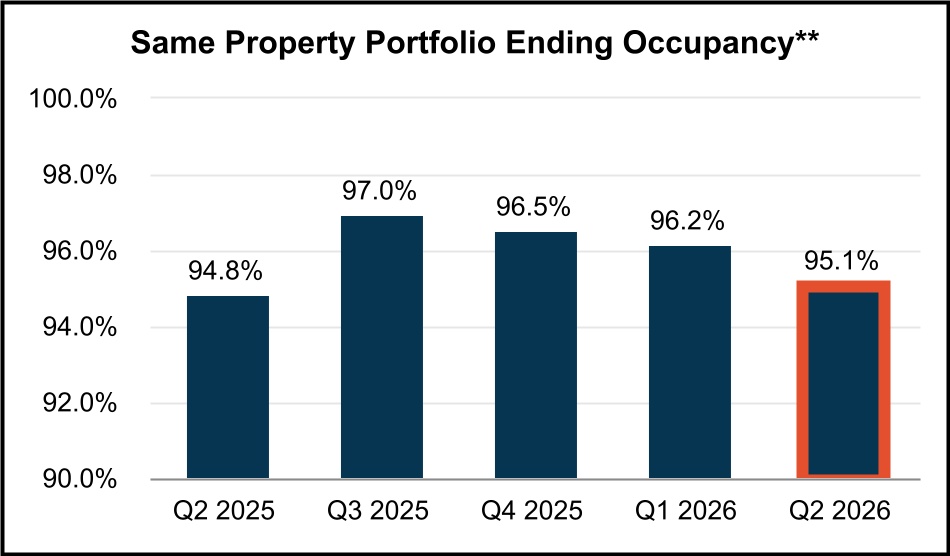
(3)Reflects the ending occupancy for the 2026 Same Property Portfolio for each period presented. For historical ending occupancy as reported in prior Supplemental packages, see “SPP Historical Information” on page 36.
(4)For comparability, Same Property Portfolio ending occupancy, NOI growth and Cash NOI growth for all comparable periods have been restated to remove the results of properties sold during Q2-2026. See page 31 for details related to dispositions.
(5)Represents the year over year percentage change in NOI and Cash NOI for the Same Property Portfolio.
(6)Includes the following # of OP Units/vested LTIP units held by noncontrolling interests: 8,716,332 (Jun 30, 2026), 8,605,741 (Mar 31, 2026), 8,288,228 (Dec 31, 2025), 8,155,706 (Sep 30, 2025) and 8,182,445 (Jun 30, 2025). Excludes the following # of shares of unvested restricted stock: 628,208 (Jun 30, 2026), 1,764,934 (Mar 31, 2026), 1,623,077 (Dec 31, 2025), 513,234 (Sep 30, 2025) and 542,922 (Jun 30, 2025). Excludes unvested LTIP units and unvested performance units.
Second Quarter 2026
Supplemental Financial Reporting Package
Page 6
Guidance.
As of June 30, 2026
2026 OUTLOOK*
Q2 2026
Updated Guidance
Q1 2026 Guidance
YTD Results as of June 30, 2026
Earnings
Net (Loss) Income Attributable to Common Stockholders per diluted share(1)(2)
($1.32) - ($1.27)
$1.22 - $1.27
$(1.86)
Company share of Core FFO per diluted share(1)(2)
$2.38 - $2.43
$2.37 - $2.42
$1.24
Same Property Portfolio(3)
Same Property Portfolio NOI Growth - Net Effective
(1.25)% - (0.25)%
(2.0)% - (1.0)%
0.3%
Same Property Portfolio NOI Growth - Cash
(0.75)% - 0.25%
(1.5)% - (0.5)%
0.6%
Average Same Property Portfolio Occupancy (Full Year)
(1)2026 Net Loss and Core FFO Guidance reflects the Company's in-place portfolio as of July 23, 2026, as well as guidance expectations related to investment activity.
(2)See page 37 for a reconciliation of the Company’s 2026 guidance range of net loss attributable to common stockholders per diluted share, the most directly comparable forward-looking GAAP financial measure, to Company share of Core FFO per diluted share.
(3)2026 Same Property Portfolio is a subset of our consolidated portfolio and includes properties that were wholly owned for the period from January 1, 2025 through July 23, 2026, and excludes properties that were or will be classified as repositioning or development (current and future) or lease-up during 2025 and 2026 (as separately listed on pages 26-30) and select buildings in other repositioning and properties included in the 2026 disposition guidance.
(4)Represents estimated annualized Cash NOI for repositioning and development projects expected to stabilize in 2026, including 1315 Storm Parkway and 12118 Bloomfield Avenue, which stabilized in the first quarter, and 3211-3233 Mission Oaks Blvd and 19900 Plummer Street, which stabilized in the second quarter.
* A number of factors could impact the Company’s ability to deliver results in line with its guidance, including, but not limited to, interest rates, inflation, the economy, tariffs, geopolitical risks including impacts from the war in the Middle East, the supply and demand of industrial real estate, the availability and terms of financing to the Company or to potential acquirers of real estate and the timing and yields for divestment and investment. There can be no assurance that the Company can achieve such results.
Second Quarter 2026
Supplemental Financial Reporting Package
Page 7
Guidance (Continued).
As of June 30, 2026
2026 Guidance Rollforward(1)
Earnings Components
Range ($ per share)
Notes
Q1 2026 Core FFO Per Diluted Share Guidance
$2.37
$2.42
Same Property Portfolio NOI Growth - Net Effective
0.01
0.01
Increased 75 bps at the midpoint to (1.25%) - (0.25%), primarily reflecting the removal of lower-growth assets tied to our 2026 planned dispositions, along with continued leasing momentum driving higher occupancy
General & Administrative Expenses
0.01
0.01
Guidance updated to +/-$57M due to corporate expense efficiencies
Other Income
0.02
0.02
Settlement and other miscellaneous income recognized in the second quarter 2026
Dispositions, Net
(0.03)
(0.03)
2H 2026 planned dispositions, with proceeds allocated to debt repayment, share repurchases and cash investment; temporary 2026 dilution reflects the timing lag in redeploying proceeds
Current 2026 Core FFO Per Diluted Share Guidance
$2.38
$2.43
Core FFO Per Diluted Share Annual Growth
(0.8)%
1.3%
(1)2026 Guidance and Guidance Rollforward represent the in-place portfolio as of July 23, 2026, as well as guidance expectations related to investment activity.
Second Quarter 2026
Supplemental Financial Reporting Package
Page 8
Consolidated Balance Sheets.
(unaudited and in thousands)
June 30, 2026
March 31, 2026
December 31, 2025
September 30, 2025
June 30, 2025
ASSETS
Land
$
7,104,413
$
7,562,694
$
7,689,921
$
7,774,737
$
7,787,021
Buildings and improvements
4,541,066
4,821,492
4,677,318
4,607,202
4,594,494
Tenant improvements
206,540
205,656
198,161
194,405
186,429
Furniture, fixtures, and equipment
132
132
132
132
132
Construction in progress
324,365
327,029
451,109
475,072
431,807
Total real estate held for investment
12,176,516
12,917,003
13,016,641
13,051,548
12,999,883
Accumulated depreciation
(1,163,226)
(1,219,932)
(1,165,792)
(1,119,746)
(1,070,684)
Investments in real estate, net
11,013,290
11,697,071
11,850,849
11,931,802
11,929,199
Cash and cash equivalents
32,226
51,714
165,778
248,956
431,117
Restricted cash
—
—
—
65,464
130,071
Loan receivable, net
123,934
123,819
123,704
123,589
123,474
Rents and other receivables, net
12,132
11,962
13,958
15,727
12,861
Deferred rent receivable, net
210,474
205,398
190,376
181,439
173,691
Deferred leasing costs, net
90,864
92,022
87,745
82,227
71,482
Deferred loan costs, net
5,877
6,382
6,886
7,391
7,892
Acquired lease intangible assets, net(1)
114,489
130,045
140,627
154,931
169,036
Acquired indefinite-lived intangible asset
5,156
5,156
5,156
5,156
5,156
Interest rate swap assets
9,247
4,562
2,025
2,804
3,586
Other assets
16,987
20,500
25,609
31,522
15,765
Assets associated with real estate held for sale, net
—
48,761
—
—
6,282
Total Assets
$
11,634,676
$
12,397,392
$
12,612,713
$
12,851,008
$
13,079,612
LIABILITIES & EQUITY
Liabilities
Notes payable
$
3,263,724
$
3,247,451
$
3,251,909
$
3,249,733
$
3,347,575
Interest rate swap liability
3
9
829
1,626
667
Accounts payable, accrued expenses and other liabilities
99,101
125,007
120,849
153,558
124,814
Dividends and distributions payable
100,960
102,418
103,399
103,913
105,594
Acquired lease intangible liabilities, net(2)
105,856
110,914
116,487
122,870
129,683
Tenant security deposits
92,386
95,219
92,444
91,835
90,757
Tenant prepaid rents
79,518
82,186
88,777
85,114
85,494
Liabilities associated with real estate held for sale
—
482
—
—
4
Total Liabilities
3,741,548
3,763,686
3,774,694
3,808,649
3,884,588
Equity
Series B preferred stock, net ($75,000 liquidation preference)
72,443
72,443
72,443
72,443
72,443
Series C preferred stock, net ($86,250 liquidation preference)
83,233
83,233
83,233
83,233
83,233
Preferred stock
155,676
155,676
155,676
155,676
155,676
Common stock
2,230
2,263
2,316
2,328
2,367
Additional paid in capital
8,631,341
8,745,875
8,945,123
8,993,439
9,140,264
Cumulative distributions in excess of earnings
(1,255,153)
(651,692)
(642,130)
(474,813)
(462,309)
Accumulated other comprehensive income (loss)
7,473
2,887
(422)
(515)
1,092
Total stockholders’ equity
7,541,567
8,255,009
8,460,563
8,676,115
8,837,090
Noncontrolling interests
351,561
378,697
377,456
366,244
357,934
Total Equity
7,893,128
8,633,706
8,838,019
9,042,359
9,195,024
Total Liabilities and Equity
$
11,634,676
$
12,397,392
$
12,612,713
$
12,851,008
$
13,079,612
(1)Includes net above-market tenant lease intangibles of $14,559 (Jun 30, 2026), $17,674 (Mar 31, 2026), $19,460 (Dec 31, 2025), $22,574 (Sep 30, 2025) and $24,994 (Jun 30, 2025), and a net below-market ground lease intangible of $12,271 (Jun 30, 2026), $12,312 (Mar 31, 2026), $12,354 (Dec 31, 2025), $12,395 (Sep 30, 2025) and $12,436 (Jun 30, 2025).
(2)Represents net below-market tenant lease intangibles as of the balance sheet date.
Second Quarter 2026
Supplemental Financial Reporting Package
Page 9
Consolidated Statements of Operations.
Quarterly Results
(unaudited and in thousands, except share and per share data)
Three Months Ended
Jun 30, 2026
Mar 31, 2026
Dec 31, 2025
Sep 30, 2025
Jun 30, 2025
Revenues
Rental income(1)
$
242,996
$
242,141
$
243,230
$
246,757
$
241,568
Management and leasing services
—
—
197
118
132
Interest income
2,510
2,937
4,670
6,367
7,807
Total Revenues
245,506
245,078
248,097
253,242
249,507
Operating Expenses
Property expenses
56,214
56,763
59,287
57,879
55,298
General and administrative
13,693
14,925
19,199
20,037
19,752
Depreciation and amortization
73,479
72,933
76,819
81,172
71,188
Total Operating Expenses
143,386
144,621
155,305
159,088
146,238
Other (Expenses) Income
Other income
3,500
1,350
—
—
—
Other expenses, net
2,001
(102)
(65,910)
(4,218)
(244)
Interest expense
(28,571)
(26,600)
(25,451)
(25,463)
(26,701)
Impairment of real estate
(624,754)
(6,824)
(89,097)
—
—
Debt extinguishment and modification expenses
—
—
—
—
(291)
Gains on sale of real estate
21,893
26,281
19,931
28,583
44,361
Total Other (Expenses) Income
(625,931)
(5,895)
(160,527)
(1,098)
17,125
Net (Loss) Income
(523,811)
94,562
(67,735)
93,056
120,394
Less: net loss (income) attributable to noncontrolling interests
19,665
(3,375)
2,312
(3,137)
(4,060)
Net (loss) income attributable to Rexford Industrial Realty, Inc.
(504,146)
91,187
(65,423)
89,919
116,334
Less: preferred stock dividends
(2,315)
(2,314)
(2,315)
(2,314)
(2,315)
Less: earnings allocated to participating securities
(441)
(1,008)
(952)
(519)
(592)
Net (loss) income attributable to common stockholders
$
(506,902)
$
87,865
$
(68,690)
$
87,086
$
113,427
Earnings per Common Share
Net (loss) income attributable to common stockholders per share - basic
$
(2.26)
$
0.38
$
(0.30)
$
0.37
$
0.48
Net (loss) income attributable to common stockholders per share - diluted
$
(2.26)
$
0.38
$
(0.30)
$
0.37
$
0.48
Weighted average shares outstanding - basic
223,812,383
228,312,419
231,758,110
234,586,980
236,098,831
Weighted average shares outstanding - diluted
223,812,383
228,312,419
232,050,966
234,586,980
236,098,831
(1)We elected the “non-separation practical expedient” in ASC 842, which allows us to avoid separating lease and non-lease rental income. As a result of this election, all rental income earned pursuant to tenant leases, including tenant reimbursements, is reflected as one line, “Rental income,” in the consolidated statements of operations. Under the section “Rental Income” on page 36 in the definitions section of this report, we include a presentation of rental revenues, tenant reimbursements and other income for all periods because we believe this information is frequently used by management, investors, securities analysts and other interested parties to evaluate our performance.
Second Quarter 2026
Supplemental Financial Reporting Package
Page 10
Consolidated Statements of Operations.
Quarterly Results (continued)
(unaudited and in thousands, except share and per share data)
Three Months Ended June 30,
Six Months Ended June 30,
2026
2025
2026
2025
Revenues
Rental income
$
242,996
$
241,568
$
485,137
$
490,389
Management and leasing services
—
132
—
274
Interest income
2,510
7,807
5,447
11,131
Total Revenues
245,506
249,507
490,584
501,794
Operating Expenses
Property expenses
56,214
55,298
112,977
110,559
General and administrative
13,693
19,752
28,618
39,620
Depreciation and amortization
73,479
71,188
146,412
157,928
Total Operating Expenses
143,386
146,238
288,007
308,107
Other (Expenses) Income
Other income
3,500
—
4,850
—
Other expenses, net
2,001
(244)
1,899
(2,483)
Interest expense
(28,571)
(26,701)
(55,171)
(53,989)
Impairment of real estate
(624,754)
—
(631,578)
—
Debt extinguishment and modification expenses
—
(291)
—
(291)
Gains on sale of real estate
21,893
44,361
48,174
57,518
Total Other (Expenses) Income
(625,931)
17,125
(631,826)
755
Net (Loss) Income
(523,811)
120,394
(429,249)
194,442
Less: net loss (income) attributable to noncontrolling interests
19,665
(4,060)
16,290
(6,909)
Net (loss) income attributable to Rexford Industrial Realty, Inc.
(504,146)
116,334
(412,959)
187,533
Less: preferred stock dividends
(2,315)
(2,315)
(4,629)
(4,629)
Less: earnings allocated to participating securities
(441)
(592)
(1,449)
(1,131)
Net (loss) income attributable to common stockholders
$
(506,902)
$
113,427
$
(419,037)
$
181,773
Net (loss) income attributable to common stockholders per share – basic
$
(2.26)
$
0.48
$
(1.85)
$
0.78
Net (loss) income attributable to common stockholders per share – diluted
$
(2.26)
$
0.48
$
(1.86)
$
0.78
Weighted-average shares of common stock outstanding – basic
223,812,383
236,098,831
226,049,970
231,771,448
Weighted-average shares of common stock outstanding – diluted
223,812,383
236,098,831
234,635,603
231,771,448
Second Quarter 2026
Supplemental Financial Reporting Package
Page 11
Non-GAAP FFO and Core FFO Reconciliations.(1)
(unaudited and in thousands, except share and per share data)
Three Months Ended
June 30, 2026
March 31, 2026
December 31, 2025
September 30, 2025
June 30, 2025
Net (Loss) Income
$
(523,811)
$
94,562
$
(67,735)
$
93,056
$
120,394
Adjustments:
Depreciation and amortization
73,479
72,933
76,819
81,172
71,188
Impairment of real estate(2)
624,754
6,824
89,097
—
—
Deduct:
Gains on sale of real estate
(21,893)
(26,281)
(19,931)
(28,583)
(44,361)
NAREIT Defined Funds From Operations (FFO)
152,529
148,038
78,250
145,645
147,221
Less: preferred stock dividends
(2,315)
(2,314)
(2,315)
(2,314)
(2,315)
Less: FFO attributable to noncontrolling interests(3)
(5,726)
(5,282)
(2,688)
(4,906)
(4,962)
Less: FFO attributable to participating securities(4)
(680)
(1,434)
(953)
(713)
(728)
Company share of FFO
$
143,808
$
139,008
$
72,294
$
137,712
$
139,216
Company share of FFO per common share‐basic
$
0.64
$
0.61
$
0.31
$
0.59
$
0.59
Company share of FFO per common share‐diluted
$
0.64
$
0.61
$
0.31
$
0.59
$
0.59
FFO
$
152,529
$
148,038
$
78,250
$
145,645
$
147,221
Adjustments:
Acquisition expenses(5)
—
—
10
161
23
Debt extinguishment and modification expenses
—
—
—
—
291
Co-CEO transition costs(5)(6)
(2,330)
—
60,223
—
—
Severance costs(5)(7)
269
—
—
2,728
199
Other nonrecurring expenses(5)(8)
45
62
5,605
1,259
—
Write-offs of below-market lease intangibles related to unexercised renewal options(9)
(497)
—
—
—
—
Core FFO
150,016
148,100
144,088
149,793
147,734
Less: preferred stock dividends
(2,315)
(2,314)
(2,315)
(2,314)
(2,315)
Less: Core FFO attributable to noncontrolling interests(3)
(5,631)
(5,284)
(4,943)
(5,045)
(4,979)
Less: Core FFO attributable to participating securities(4)(10)
(668)
(744)
(648)
(734)
(731)
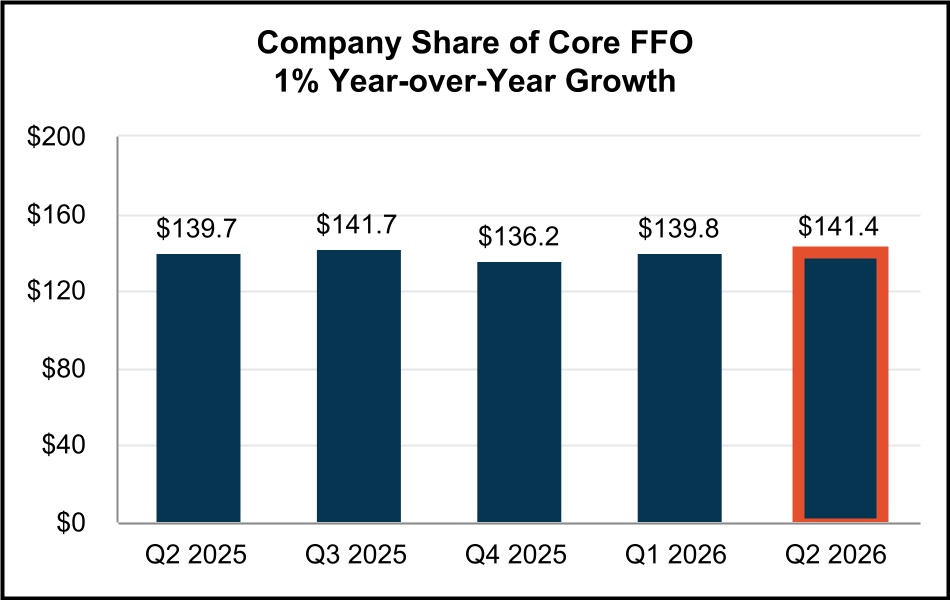
Company share of Core FFO
$
141,402
$
139,758
$
136,182
$
141,700
$
139,709
Company share of Core FFO per common share‐basic
$
0.63
$
0.61
$
0.59
$
0.60
$
0.59
Company share of Core FFO per common share‐diluted
$
0.63
$
0.61
$
0.59
$
0.60
$
0.59
Weighted-average shares outstanding-basic
223,812,383
228,312,419
231,758,110
234,586,980
236,098,831
Weighted-average shares outstanding-diluted
223,812,383
228,312,419
232,050,966
234,586,980
236,098,831
(1)For a definition and discussion of non-GAAP financial measures, see the definitions section beginning on page 33 of this report.
(2)Primarily reflects non-cash impairment charges to reduce the carrying amount of certain properties designated for disposition to their estimated fair value resulting from shortened expected holding periods associated with our increased disposition guidance.
(3)Noncontrolling interests relate to interests in the Company’s operating partnership (“OP”), represented by common & preferred units of partnership interests in the OP that are owned by unit holders other than the Company.
(4)Participating securities include unvested shares of restricted stock, unvested LTIP units and unvested performance units.
(5)Amounts are included in the line item “Other expenses, net” in the consolidated statements of operations.
(6)For the three months ended December 31, 2025, reflects accelerated share-based compensation expense in connection with the 2025 Co-CEO transition, including transition-related restricted stock granted on November 17, 2025 and pre-existing awards. For the three months ended June 30, 2026, reflects a decrease in share-based compensation expense related to updated estimates of Core FFO growth achievement for certain performance awards held by former Co-CEOs and employer payroll taxes associated with the vesting of transition-related restricted stock awards in April 2026.
(7)Includes costs associated with workforce reduction and workforce reorganization.
(8)Reflects nonrecurring advisory service costs.
(9)Reflects the write-off of the portion of a below-market lease intangible attributable to below-market fixed rate renewal options that were not exercised upon expiration of the initial lease term.
(10)For the three months ended March 31, 2026 and December 31, 2025, Core FFO attributable to participating securities was adjusted to exclude $691 and $569, respectively, of otherwise allocable Core FFO related solely to the transition‑related restricted stock awards noted above, consistent with the exclusion of the related accelerated share‑based compensation from Core FFO.
Second Quarter 2026
Supplemental Financial Reporting Package
Page 12
Non-GAAP FFO and Core FFO Reconciliations.(1)
(unaudited and in thousands, except share and per share data)
Three Months Ended June 30,
Six Months Ended June 30,
2026
2025
2026
2025
Net (Loss) Income
$
(523,811)
$
120,394
$
(429,249)
$
194,442
Adjustments:
Depreciation and amortization
73,479
71,188
146,412
157,928
Impairment of real estate(2)
624,754
—
631,578
—
Gains on sale of real estate
(21,893)
(44,361)
(48,174)
(57,518)
Funds From Operations (FFO)
152,529
147,221
300,567
294,852
Less: preferred stock dividends
(2,315)
(2,315)
(4,629)
(4,629)
Less: FFO attributable to noncontrolling interests
(5,726)
(4,962)
(11,008)
(10,356)
Less: FFO attributable to participating securities
(680)
(728)
(2,114)
(1,478)
Company share of FFO
$
143,808
$
139,216
$
282,816
$
278,389
Company share of FFO per common share‐basic
$
0.64
$
0.59
$
1.25
$
1.20
Company share of FFO per common share‐diluted
$
0.64
$
0.59
$
1.25
$
1.20
FFO
$
152,529
$
147,221
$
300,567
$
294,852
Adjustments:
Acquisition expenses(3)
—
23
—
102
Debt extinguishment and modification expenses
—
291
—
291
Non-capitalizable demolition costs(3)
—
—
—
365
Co-CEO transition costs(3)(4)
(2,330)
—
(2,330)
—
Severance costs(3)(5)
269
199
269
1,682
Other nonrecurring expenses(3)(6)
45
—
107
—
Write-offs of below-market lease intangibles related to unexercised renewal options(7)
(497)
—
(497)
—
Core FFO
150,016
147,734
298,116
297,292
Less: preferred stock dividends
(2,315)
(2,315)
(4,629)
(4,629)
Less: Core FFO attributable to noncontrolling interests
(5,631)
(4,979)
(10,915)
(10,440)
Less: Core FFO attributable to participating securities
(668)
(731)
(1,412)
(1,491)
Company share of Core FFO
$
141,402
$
139,709
$
281,160
$
280,732
Company share of Core FFO per common share‐basic
$
0.63
$
0.59
$
1.24
$
1.21
Company share of Core FFO per common share‐diluted
$
0.63
$
0.59
$
1.24
$
1.21
Weighted-average shares outstanding-basic
223,812,383
236,098,831
226,049,970
231,771,448
Weighted-average shares outstanding-diluted
223,812,383
236,098,831
226,049,970
231,771,448
(1)For a definition and discussion of non-GAAP financial measures, see the definitions section beginning on page 33 of this report.
(2)Primarily reflects non-cash impairment charges to reduce the carrying amount of certain properties designated for disposition to their estimated fair value resulting from shortened expected holding periods associated with our increased disposition guidance.
(3)Amounts are included in the line item “Other expenses, net” in the consolidated statements of operations.
(4)Reflects a decrease in share-based compensation expense related to updated estimates of Core FFO growth achievement for certain performance awards held by former Co-CEOs and employer payroll taxes associated with the vesting of transition-related restricted stock awards in April 2026.
(5)Includes costs associated with workforce reduction and workforce reorganization.
(6)Reflects nonrecurring advisory service costs.
(7)Reflects the write-off of the portion of a below-market lease intangible attributable to below-market fixed rate renewal options that were not exercised upon expiration of the initial lease term.
Second Quarter 2026
Supplemental Financial Reporting Package
Page 13
Non-GAAP AFFO Reconciliation.(1)
(unaudited and in thousands, except share and per share data)
Three Months Ended
June 30, 2026
March 31, 2026
December 31, 2025
September 30, 2025
June 30, 2025
Funds From Operations(2)
$
152,529
$
148,038
$
78,250
$
145,645
$
147,221
Adjustments:
Amortization of deferred financing costs
1,333
1,334
1,333
1,340
1,255
Non-cash stock compensation
3,666
4,063
8,537
10,485
10,091
Debt extinguishment and modification expenses
—
—
—
—
291
Amortization related to termination/settlement of interest rate derivatives
77
77
78
78
76
Note payable (discount) premium amortization, net
1,662
1,641
1,616
1,597
1,579
Co-CEO transition costs(3)
(2,330)
—
60,223
—
—
Severance costs
269
—
—
2,728
199
Other nonrecurring expenses
45
62
5,605
1,259
—
Deduct:
Preferred stock dividends
(2,315)
(2,314)
(2,315)
(2,314)
(2,315)
Straight line rental revenue adjustment(4)
(9,967)
(15,136)
(9,073)
(8,164)
(6,918)
Above/(below) market lease revenue adjustments
(3,805)
(4,647)
(4,129)
(5,254)
(5,788)
Capitalized payments(5)
(10,612)
(13,203)
(14,814)
(15,756)
(14,368)
Accretion of net loan origination fees
(115)
(115)
(115)
(115)
(115)
Recurring capital expenditures(6)
(4,750)
(2,314)
(2,566)
(3,563)
(5,887)
2nd generation tenant improvements(7)
(242)
(185)
(179)
(460)
(663)
2nd generation leasing commissions(8)
(4,942)
(8,193)
(6,324)
(8,007)
(4,162)
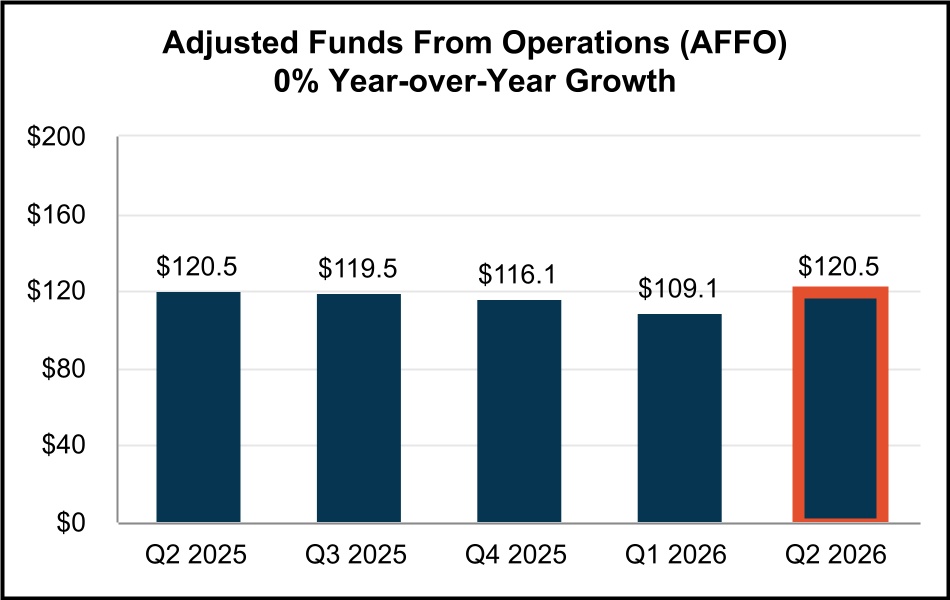
Adjusted Funds From Operations (AFFO)
$
120,503
$
109,108
$
116,127
$
119,499
$
120,496
(1)For a definition and discussion of non-GAAP financial measures, see the definitions section beginning on page 33 of this report.
(2)A quarterly reconciliation of net income or loss to Funds From Operations is set forth on page 12 of this report.
(3)For the three months ended December 31, 2025, reflects accelerated share-based compensation expense in connection with the 2025 Co-CEO transition, including transition-related restricted stock granted on November 17, 2025 and pre-existing awards. For the three months ended June 30, 2026, reflects a decrease in share-based compensation expense related to updated estimates of Core FFO growth achievement for certain performance awards held by former Co-CEOs and employer payroll taxes associated with the vesting of transition-related restricted stock awards in April 2026.
(4)Changes in straight line rental revenue adjustments from quarter to quarter are largely influenced by tenant base rent concessions recognized during each respective quarter, which increase the non‑cash component of rental revenue. For the three months ended June 30, 2026, March 31, 2026, December 31, 2025, September 30, 2025 and June 30, 2025, the adjustment reflects the impact of base rent concessions granted during those periods totaling $12,795, $18,027 (including $3,337 related to the current Tireco, Inc. lease), $11,244, $7,433 and $5,844, respectively.
(5)Includes capitalized interest, taxes, insurance and construction-related compensation costs.
(6)Excludes nonrecurring capital expenditures of $32,307, $39,867, $57,730, $62,309 and $65,376 for the three months ended June 30, 2026, March 31, 2026, December 31, 2025, September 30, 2025 and June 30, 2025, respectively.
(7)Excludes 1st generation tenant improvements of $0, $148, $67, $328 and $292 for the three months ended June 30, 2026, March 31, 2026, December 31, 2025, September 30, 2025 and June 30, 2025, respectively.
(8)Excludes 1st generation leasing commissions of $2,214, $2,174, $5,057, $7,984 and $1,879 for the three months ended June 30, 2026, March 31, 2026, December 31, 2025, September 30, 2025 and June 30, 2025, respectively.
Second Quarter 2026
Supplemental Financial Reporting Package
Page 14
Statement of Operations Reconciliations - NOI, Cash NOI, EBITDAre and Adjusted EBITDAre.(1)
(unaudited and in thousands)
NOI and Cash NOI
Three Months Ended
Jun 30, 2026
Mar 31, 2026
Dec 31, 2025
Sep 30, 2025
Jun 30, 2025
Rental income(2)(3)(4)(5)
$
242,996
$
242,141
$
243,230
$
246,757
$
241,568
Less: Property expenses
56,214
56,763
59,287
57,879
55,298
Net Operating Income (NOI)
$
186,782
$
185,378
$
183,943
$
188,878
$
186,270
Above/(below) market lease revenue adjustments(3)
(3,805)
(4,647)
(4,129)
(5,254)
(5,788)
Straight line rental revenue adjustment
(9,967)
(15,136)
(9,073)
(8,164)
(6,918)
Cash NOI
$
173,010
$
165,595
$
170,741
$
175,460
$
173,564
EBITDAre and Adjusted EBITDAre
Three Months Ended
Jun 30, 2026
Mar 31, 2026
Dec 31, 2025
Sep 30, 2025
Jun 30, 2025
Net (loss) income
$
(523,811)
$
94,562
$
(67,735)
$
93,056
$
120,394
Interest expense
28,571
26,600
25,451
25,463
26,701
Depreciation and amortization
73,479
72,933
76,819
81,172
71,188
Impairment of real estate
624,754
6,824
89,097
—
—
Gains on sale of real estate
(21,893)
(26,281)
(19,931)
(28,583)
(44,361)
EBITDAre
$
181,100
$
174,638
$
103,701
$
171,108
$
173,922
Stock-based compensation amortization
3,666
4,063
8,537
10,485
10,091
Debt extinguishment and modification expenses
—
—
—
—
291
Acquisition expenses
—
—
10
161
23
Co-CEO transition costs
(2,330)
—
60,223
—
—
Other nonrecurring expenses
45
62
5,605
1,259
—
Write-offs of below-market lease intangibles related to unexercised renewal options
(497)
—
—
—
—
Pro forma effect of dispositions(6)
68
(206)
(268)
(389)
(216)
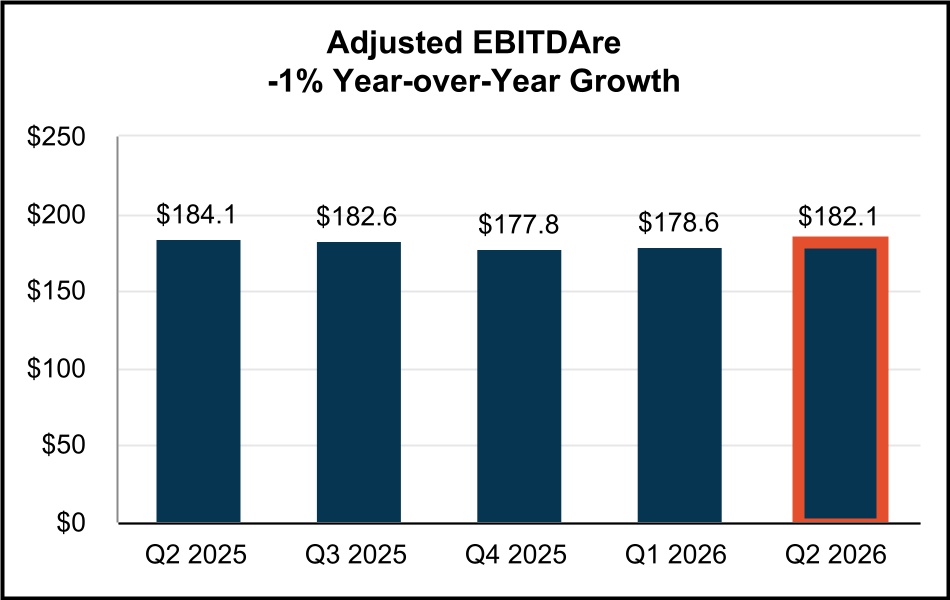
Adjusted EBITDAre
$
182,052
$
178,557
$
177,808
$
182,624
$
184,111
(1)For a definition and discussion of non-GAAP financial measures, see the definitions section beginning on page 33 of this report.
(2)See footnote (1) on page 10 for details related to our presentation of “Rental income” in the consolidated statements of operations for all periods presented.
(3)Rental income and above/(below) market lease revenue adjustments for the three months ended June 30, 2026 include $497 of income recognized from the write-off of a below-market lease intangible attributable to below-market fixed-rate renewal options that were not exercised upon expiration of the initial lease term. This amount has been excluded from Same Property Portfolio NOI and above/(below) market lease revenue adjustments on the following page.
(4)Reflects (decrease) increase to rental income due to changes in the Company’s assessment of lease payment collectability as follows (in thousands): $(1,414), $(2,731), $(2,615), $13 and $(141) for the three months ended June 30, 2026, March 31, 2026, December 31, 2025, September 30, 2025 and June 30, 2025, respectively.
(5)Rental income includes net lease termination income (in thousands) of $18, $24, $0, $458 and $0 for the three months ended June 30, 2026, March 31, 2026, December 31, 2025, September 30, 2025 and June 30, 2025, respectively. Amounts include lease termination fees and write-offs of straight-line rent and above/(below) market lease intangibles associated with lease terminations.
(6)Reflects EBITDAre generated by properties sold during the respective period prior to their disposition.
Second Quarter 2026
Supplemental Financial Reporting Package
Page 15
Same Property Portfolio Performance.(1)
(unaudited and dollars in thousands)
Same Property Portfolio:
Number of properties
341
Square Feet
41,633,904
Same Property Portfolio NOI and Cash NOI:
Three Months Ended June 30,
Six Months Ended June 30,
2026
2025
$ Change
% Change
2026
2025
$ Change
% Change
Rental income(2)(3)(4)(5)
$
210,974
$
210,887
$
87
0.0%
$
422,543
$
418,561
$
3,982
1.0%
Property expenses
46,811
45,893
918
2.0%
94,045
91,171
2,874
3.2%
Same Property Portfolio NOI
$
164,163
$
164,994
$
(831)
(0.5)%
(4)
$
328,498
$
327,390
$
1,108
0.3%
(4)
Straight-line rental revenue adjustment
(4,938)
(6,328)
1,390
(22.0)%
(15,235)
(13,835)
(1,400)
10.1%
Above/(below) market lease revenue adjustments(5)
(3,093)
(4,829)
1,736
(35.9)%
(7,263)
(9,401)
2,138
(22.7)%
Same Property Portfolio Cash NOI
$
156,132
$
153,837
$
2,295
1.5%
(4)
$
306,000
$
304,154
$
1,846
0.6%
(4)
Same Property Portfolio Occupancy:
Three Months Ended June 30,
Year-over-Year Change (basis points)
Sequential Change (basis points)
2026
2025
Three Months Ended March 31, 2026
Quarterly Weighted Average Occupancy:(6)
Los Angeles County
96.5%
93.2%
330 bps
96.9%
(40) bps
Orange County
95.9%
97.6%
(170) bps
96.4%
(50) bps
Riverside / San Bernardino County
93.3%
97.0%
(370) bps
95.0%
(170) bps
San Diego County
97.5%
98.0%
(50) bps
97.7%
(20) bps
Ventura County
94.6%
91.4%
320 bps
94.3%
30 bps
Quarterly Weighted Average Occupancy
95.7%
94.7%
100 bps
96.3%
(60) bps
Ending Occupancy:
95.1%
94.8%
30 bps
96.2%
(110) bps
(1)For a definition and discussion of non-GAAP financial measures, see the definitions section beginning on page 33 of this report.
(2)See “Same Property Portfolio Rental Income” on page 36 of the definitions section of this report for a breakdown of rental income into rental revenues, tenant reimbursements and other income for the three months and year ended June 30, 2026 and 2025.
(3)Reflects (decrease) increase to rental income due to changes in the Company’s assessment of lease payment collectability as follows: $(971) and $(30) for the three months ended June 30, 2026 and 2025, respectively, and $(3,503) and $(2,211) for the six months ended June 30, 2026 and 2025, respectively.
(4)Rental income includes lease termination fees of $18 and $0 for the three months ended June 30, 2026 and 2025, respectively, and $205 and $20 for the six months ended June 30, 2026 and 2025, respectively. Excluding these lease termination fees, Same Property Portfolio NOI decreased by 0.5% and increased by 0.3% and Same Property Portfolio Cash NOI increased by 1.5% and 0.5% during the three and six months ended June 30, 2026, compared to the three and six months ended June 30, 2025, respectively.
(5)Same Property rental income and above/(below) market lease revenue adjustments for the three months ended June 30, 2026 exclude $497 of income recognized from the write-off of a below-market lease intangibles attributable to below-market fixed rate renewal options that were not exercised upon expiration of the initial lease term, as described on the preceding page.
(6)Calculated by averaging the occupancy rate at the end of each month in 2Q-2026 and March 2026 (for 2Q-2026), the end of each month in 2Q-2025 and March 2025 (for 2Q-2025) and the end of each month in 1Q-2026 and December 2025 (for 1Q-2026).
Second Quarter 2026
Supplemental Financial Reporting Package
Page 16
Capitalization Summary.
(unaudited and in thousands, except share and per share data)
Capitalization as of June 30, 2026
Description
June 30, 2026
March 31, 2026
December 31, 2025
September 30, 2025
June 30, 2025
Common shares outstanding(1)
222,360,849
224,521,552
229,957,058
232,297,172
236,151,829
Operating partnership units outstanding(2)
8,716,332
8,605,741
8,288,228
8,155,706
8,182,445
Total shares and units outstanding at period end
231,077,181
233,127,293
238,245,286
240,452,878
244,334,274
Share price at end of quarter
$
33.50
$
32.73
$
38.72
$
41.11
$
35.57
Common Stock and Operating Partnership Units - Capitalization
$
7,741,086
$
7,630,256
$
9,224,857
$
9,885,018
$
8,690,970
Series B and C Cumulative Redeemable Preferred Stock(3)
$
161,250
$
161,250
$
161,250
$
161,250
$
161,250
3.00% Series 3 Cumulative Redeemable Convertible Preferred Units(4)
12,000
12,000
12,000
12,000
12,000
Preferred Equity
$
173,250
$
173,250
$
173,250
$
173,250
$
173,250
Total Equity Market Capitalization
$
7,914,336
$
7,803,506
$
9,398,107
$
10,058,268
$
8,864,220
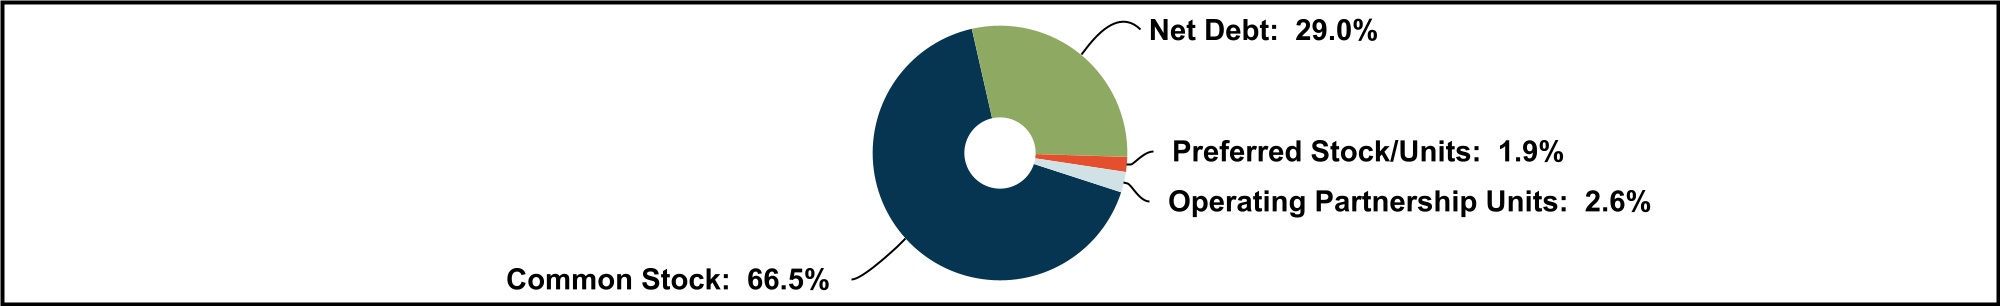
Total Debt
$
3,285,503
$
3,271,720
$
3,278,649
$
3,278,896
$
3,379,141
Less: Cash and cash equivalents
(32,226)
(51,714)
(165,778)
(248,956)
(431,117)
Net Debt
$
3,253,277
$
3,220,006
$
3,112,871
$
3,029,940
$
2,948,024
Total Combined Market Capitalization (Net Debt plus Equity)
$
11,167,613
$
11,023,512
$
12,510,978
$
13,088,208
$
11,812,244
Net debt to Adjusted EBITDAre (quarterly results annualized)(5)
4.5x
4.5x
4.4x
4.1x
4.0x
Net debt & preferred equity to Adjusted EBITDAre (quarterly results annualized)(5)
4.7x
4.8x
4.6x
4.4x
4.2x
(1)Excludes the following number of shares of unvested restricted stock: 628,208 (Jun 30, 2026), 1,764,934 (Mar 31, 2026), 1,623,077 (Dec 31, 2025), 513,234 (Sep 30, 2025) and 542,922 (Jun 30, 2025). During the three months ended June 30, 2026, March 31, 2026, December 31, 2025 and September 30, 2025, the Company repurchased 2,801,307, 5,534,357, 2,443,438 and 3,883,845 shares common stock under its stock repurchase programs at a weighted average price of $35.70, $36.14, $40.93 and $38.62 per share for a total of $100.1 million, $200.1 million, $100.0 million and $150.1 million, respectively.
(2)Represents outstanding common units of the Company’s operating partnership (“OP”), Rexford Industrial Realty, LP, that are owned by unitholders other than Rexford Industrial Realty, Inc. Represents the noncontrolling interest in our OP. As of June 30, 2026, includes 1,765,430 vested LTIP Units and 1,325,969 vested performance units and excludes 185,285 unvested LTIP Units and 2,011,382 unvested performance units.
(3)Values based on liquidation preference of $25 per share and the following number of outstanding shares of preferred stock: 5.875% Series B (3,000,000); 5.625% Series C (3,450,000).
(4)Value based on 164,998 outstanding Series 3 preferred units at a liquidation preference of $72.72825 per unit.
(5)For definition/discussion of non-GAAP financial measures and reconciliations to their nearest GAAP equivalents, see the definitions section & reconciliation section beginning on page 33 and page 12 of this report, respectively.
Second Quarter 2026
Supplemental Financial Reporting Package
Page 17
Debt Summary.
(unaudited and dollars in thousands)
Debt Detail:
As of June 30, 2026
Debt Description
Maturity Date
Stated Interest Rate
Effective
Interest Rate(1)
Principal
Balance(2)
Unsecured Debt:
$1.25 Billion Revolving Credit Facility(3)
5/30/2029(4)
SOFR+0.685%(5)
4.365%
$
14,000
$575M Exchangeable 2027 Senior Notes(6)
3/15/2027
4.375%
4.375%
575,000
$300M Term Loan Facility
5/26/2027
SOFR+0.76%(5)
3.577%(7)
300,000
$125M Senior Notes
7/13/2027
3.930%
3.930%
125,000
$300M Senior Notes
6/15/2028
5.000%
5.000%
300,000
$575M Exchangeable 2029 Senior Notes(6)
3/15/2029
4.125%
4.125%
575,000
$25M Series 2019A Senior Notes
7/16/2029
3.880%
3.880%
25,000
$400M Senior Notes
12/1/2030
2.125%
2.125%
400,000
$400M Term Loan Facility
5/30/2030
SOFR+0.76%(5)
4.174%(8)
400,000
$400M Senior Notes - Green Bond
9/1/2031
2.150%
2.150%
400,000
$75M Series 2019B Senior Notes
7/16/2034
4.030%
4.030%
75,000
Secured Debt:
$60M Term Loan Facility
10/27/2026(9)
SOFR+1.250%(9)
5.060%(10)
60,000
13943-13955 Balboa Boulevard
7/1/2027
3.930%
3.930%
13,608
2205 126th Street
12/1/2027
3.910%
3.910%
5,200
2410-2420 Santa Fe Avenue
1/1/2028
3.700%
3.700%
10,300
11832-11954 La Cienega Boulevard
7/1/2028
4.260%
4.260%
3,646
1100-1170 Gilbert Street (Gilbert/La Palma)
3/1/2031
5.125%
5.125%
1,212
7817 Woodley Avenue
8/1/2039
4.140%
4.140%
2,537
Total Debt
3.725%
$
3,285,503
Debt Composition:
Category
Weighted Average Term Remaining (yrs)
Stated Interest Rate
Effective Interest Rate
Balance
% of Total
Fixed
2.8
3.723% (See Table Above)
3.723%
$
3,271,503
99.6%
Variable
2.9
SOFR + Margin (See Table Above)
4.365%
$
14,000
0.4%
Secured
1.1
4.640%
$
96,503
3.0%
Unsecured
2.8
3.698%
$
3,189,000
97.0%
*See footnotes on the following page*
Second Quarter 2026
Supplemental Financial Reporting Package
Page 18
Debt Summary (Continued).
(unaudited and dollars in thousands)
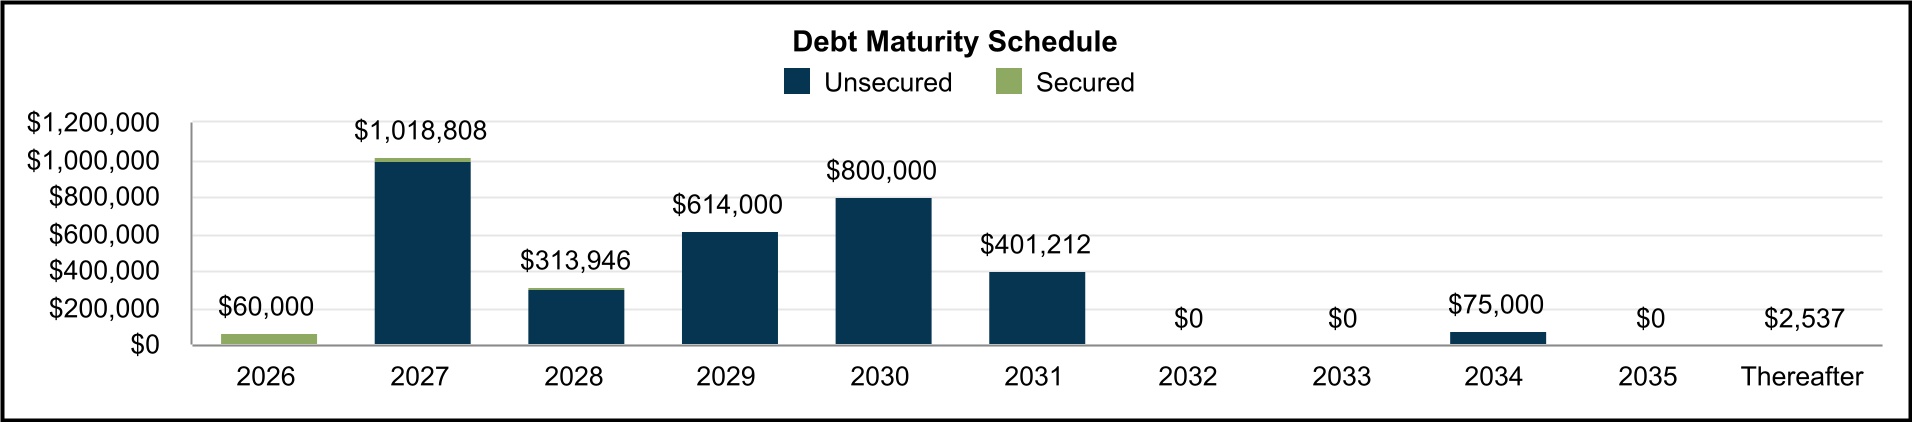
Debt Maturity Schedule(11):
Year
Secured
Unsecured
Total
% Total
Effective Interest Rate(1)
2026
$
60,000
$
—
$
60,000
2
%
5.060
%
2027
18,808
1,000,000
1,018,808
31
%
4.077
%
2028
13,946
300,000
313,946
10
%
4.949
%
2029
—
614,000
614,000
19
%
4.120
%
2030
—
800,000
800,000
24
%
3.149
%
2031
1,212
400,000
401,212
12
%
2.159
%
2032
—
—
—
—
%
—
%
2033
—
—
—
—
%
—
%
2034
—
75,000
75,000
2
%
4.030
%
2035
—
—
—
—
%
—
%
Thereafter
2,537
—
2,537
—
%
4.140
%
Total
$
96,503
$
3,189,000
$
3,285,503
100
%
3.725
%
(1)Includes the effect of interest rate swaps effective as of Jun 30, 2026. See notes (7), (8) and (10). Excludes the effect of premiums/discounts, deferred loan costs and the credit facility fee.
(2)Excludes unamortized debt issuance costs, premiums and discounts aggregating $21.8 million as of June 30, 2026.
(3)The $1.25B revolving credit facility (“Revolver”) is subject to a facility fee which is calculated as a percentage of the total commitment amount, regardless of usage. The facility fee ranges from 0.125% to 0.300% depending on our credit ratings. There are also two sustainability-linked pricing components that can periodically change the facility fee by -/+ 0.01% (or zero) depending on our achievement of the annual sustainability performance metrics. In January 2026, the facility fee decreased by 0.01% to 0.115% after certifying that our sustainability performance targets for 2025 were met.
(4)The Revolver has two six-month extensions, subject to certain terms and conditions.
(5)The interest rates on these loans are comprised of Daily SOFR for the Revolver and $400M term loan facility (“TL”) and 1-month SOFR for the $300M TL and an applicable margin ranging from 0.725% to 1.40% for the Revolver and 0.80% to 1.60% for the $300M TL and $400M TL depending on our credit ratings and leverage ratio. There is also a sustainability-linked pricing component that can periodically change the margin by -/+ 0.04% (or zero) depending on our achievement of the annual sustainability performance metric. In January 2026, the applicable margin decreased by 0.04% to 0.685% for the Revolver and to 0.76% for the $300M TL and $400M TL after certifying that our sustainability performance targets were met for 2025.
(6)Noteholders have the right to exchange their notes upon the occurrence of certain events. Exchanges will be settled in cash or in a combination of cash and shares of our common stock, at our option.
(7)Interest rate swaps effectively fix 1M SOFR on the $300M TL at 2.81725% from July 27, 2022 through May 26, 2027, resulting in an all‑in fixed rate of 3.577% after applicable margin and sustainability‑related adjustments.
(8)Interest rate swaps effectively fix Daily SOFR on the $400M TL at 3.41375% from July 1, 2025 through May 30, 2030, resulting in an all‑in fixed rate of 4.174% after applicable margin and sustainability‑related adjustments.
(9)The $60M TL has interest-only payment terms (1M SOFR + 0.10% SOFR adjustment + margin of 1.250%) and three one-year extensions remaining, subject to certain terms and conditions.
(10)Interest rate swaps effectively fix 1M SOFR on the $60M TL at 3.710% from April 3, 2023 through July 30, 2026, resulting in an all‑in fixed rate of 5.060% after applicable margin and SOFR adjustments.
(11)Excludes potential exercise of extension options and excludes the effect of scheduled monthly principal payments on amortizing secured loans.
Second Quarter 2026
Supplemental Financial Reporting Package
Page 19
Operations.
Quarterly Results
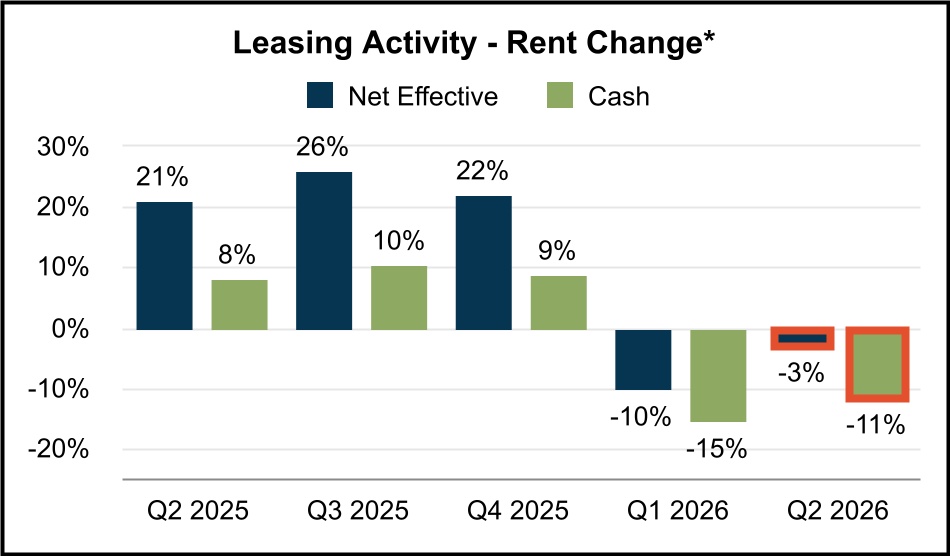
*Leasing Activity - Rent Change for Q1-2026 includes a 1.1 million square foot lease extension with Tireco, Inc. at 10545 Production Avenue. Excluding this lease, the Net Effective Rent Change for Q1-2026 is 5.5% and the Cash Rent Change is (1.8)%. See page 22 for additional details related to this lease.
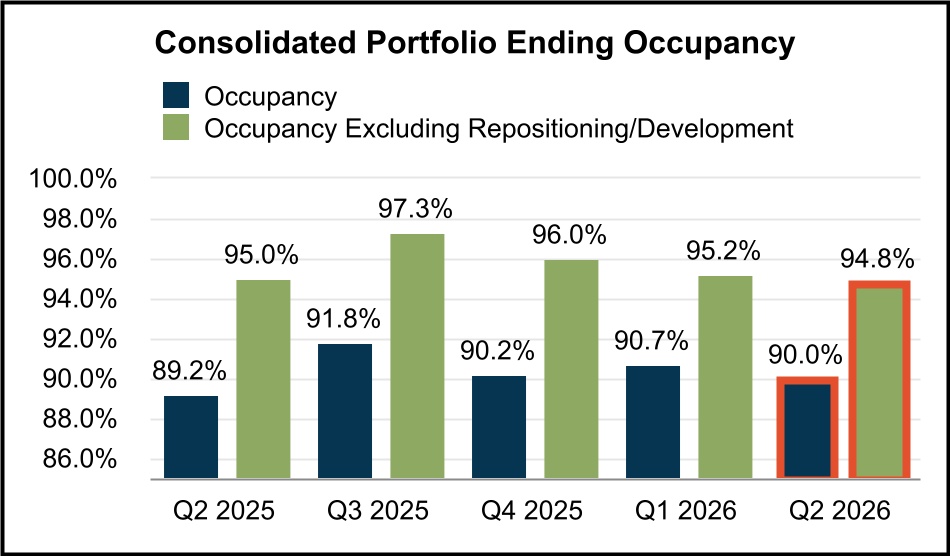
**Reflects the ending occupancy for the 2026 Same Property Portfolio for each period presented.
Second Quarter 2026
Supplemental Financial Reporting Package
Page 20
Portfolio Overview.
At June 30, 2026
(unaudited results)
Consolidated Portfolio:
Rentable Square Feet
Ending Occupancy %
In-Place ABR(3)
Market
# of Properties
Same Property Portfolio
Non-Same Property Portfolio
Total Portfolio
Same Property Portfolio
Non-Same Property Portfolio
Total
Portfolio(1)
Total Portfolio
Excluding
Repo/Redev(2)
Total (in 000’s)
Per Square Foot
Central LA
20
2,834,219
384,764
3,218,983
98.8
%
85.7
%
97.2
%
98.9
%
$
43,432
$13.88
Greater San Fernando Valley
73
5,694,646
1,333,061
7,027,707
97.0
%
61.4
%
90.3
%
92.6
%
112,683
$17.77
Mid-Counties
38
3,211,786
1,566,055
4,777,841
99.8
%
75.4
%
91.8
%
99.8
%
78,221
$17.84
San Gabriel Valley
44
4,939,663
1,140,872
6,080,535
92.7
%
36.7
%
82.2
%
93.2
%
67,827
$13.57
South Bay
78
6,503,318
951,268
7,454,586
94.1
%
78.9
%
92.2
%
94.1
%
158,062
$23.01
Los Angeles County
253
23,183,632
5,376,020
28,559,652
95.9
%
65.1
%
90.1
%
95.0
%
460,225
$17.89
North Orange County
24
1,919,265
641,893
2,561,158
92.9
%
59.9
%
84.6
%
94.1
%
41,423
$19.12
OC Airport
8
958,510
—
958,510
100.0
%
—
%
100.0
%
100.0
%
20,350
$21.23
South Orange County
9
482,919
46,642
529,561
100.0
%
100.0
%
100.0
%
100.0
%
9,410
$17.77
West Orange County
10
1,288,838
—
1,288,838
96.7
%
—
%
96.7
%
96.7
%
21,695
$17.42
Orange County
51
4,649,532
688,535
5,338,067
96.1
%
62.6
%
91.8
%
96.5
%
92,878
$18.95
Inland Empire East
1
33,258
—
33,258
100.0
%
—
%
100.0
%
100.0
%
682
$20.52
Inland Empire West
52
8,798,078
726,308
9,524,386
92.0
%
24.0
%
86.8
%
91.7
%
132,464
$16.02
Riverside / San Bernardino County
53
8,831,336
726,308
9,557,644
92.1
%
24.0
%
86.9
%
91.7
%
133,146
$16.03
Central San Diego
21
1,417,150
511,105
1,928,255
98.0
%
53.3
%
86.2
%
98.4
%
41,130
$24.75
North County San Diego
13
1,042,142
282,231
1,324,373
97.6
%
92.4
%
96.5
%
98.1
%
19,826
$15.52
San Diego County
34
2,459,292
793,336
3,252,628
97.8
%
67.2
%
90.4
%
98.2
%
60,956
$20.74
Ventura
18
2,510,112
716,100
3,226,212
94.0
%
100.0
%
95.3
%
95.5
%
44,075
$14.34
Ventura County
18
2,510,112
716,100
3,226,212
94.0
%
100.0
%
95.3
%
95.5
%
44,075
$14.34
CONSOLIDATED TOTAL / WTD AVG
409
41,633,904
8,300,299
49,934,203
95.1
%
64.5
%
90.0
%
94.8
%
$
791,280
$17.61
(4)
(1)See page 37 for historical occupancy by County.
(2)Excludes space aggregating 2,520,758 square feet at our properties that were in various stages of repositioning, development or lease-up as of June 30, 2026.
(3)See page 33 for definitions and details on how these amounts are calculated.
(4)Excluding in-place ABR associated with Land/IOS properties ($41.6M ABR) and cellular tower, solar and parking lot leases ($3.0M ABR), in-place building ABR per building SF was $16.69.
Second Quarter 2026
Supplemental Financial Reporting Package
Page 21
Executed Leasing Statistics and Trends.
(unaudited results)
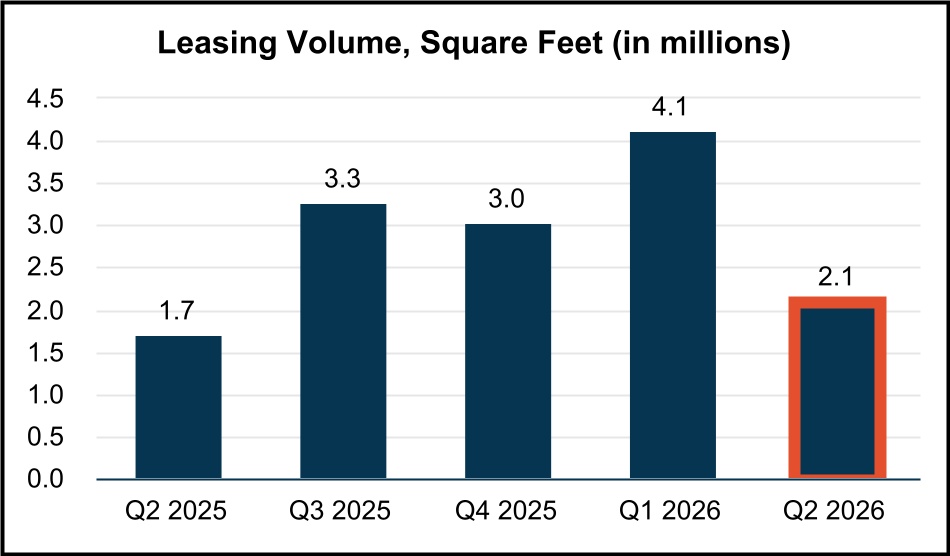
Executed Leasing Activity and Weighted Average New / Renewal Leasing Spreads:
Three Months Ended
Jun 30, 2026
Mar 31, 2026
Dec 31, 2025
Sep 30, 2025
Jun 30, 2025
Leasing Spreads:
Net Effective Rent Change(1)
(2.8)
%
(10.0)
%
22.0
%
26.1
%
20.9
%
Cash Rent Change(1)
(11.3)
%
(15.4)
%
9.0
%
10.3
%
8.1
%
Leasing Activity (Building SF):(2)
New leases
840,344
1,296,230
1,574,816
2,361,131
678,727
Renewal leases
1,261,446
2,829,822
1,464,751
904,014
1,020,266
Total leasing activity
2,101,790
4,126,052
3,039,567
3,265,145
1,698,993
Total expiring leases
(2,788,275)
(4,638,894)
(3,551,170)
(1,734,790)
(1,786,814)
Expiring leases - placed into repositioning/development
599,680
152,417
957,493
418,878
304,776
Net absorption(3)
(86,805)
(360,425)
445,890
1,949,233
216,955
Retention rate(4)
60
%
64
%
61
%
72
%
69
%
Retention + Backfill rate(5)
69
%
79
%
70
%
77
%
74
%
Executed Leasing Activity and Change in Annual Rental Rates and Turnover Costs for Current Quarter Leases:(6)
Net Effective Rent
Cash Rent
Turnover Costs(7)
Second Quarter 2026
# Leases Signed
SF of Leasing
Wtd. Avg. Lease Term (Years)
Current Lease
Prior Lease
Rent Change
Current Lease
Prior Lease
Rent Change
Wtd. Avg. Abatement (Months)
Tenant Improvements per SF
Leasing Commissions per SF
New
53
840,344
4.8
$14.03
$16.28
(13.8)%
$14.19
$17.62
(19.5)%
3.2
$1.56
$3.03
Renewal
64
1,261,446
4.6
$16.65
$16.41
1.4%
$16.50
$17.96
(8.1)%
3.4
$1.57
$2.69
Total / Wtd. Average
117
2,101,790
4.7
$15.92
$16.37
(2.8)%
$15.86
$17.87
(11.3)%
3.3
$1.57
$2.78
(1)Net Effective and Cash Rent Changes reported for Q1-26 include the 1.1 million square foot lease extension with Tireco, Inc. at 10545 Production Avenue. The lease, which was originally set to expire in January 2027, was extended through April 2030, commencing on February 1, 2027. The above-market in-place lease rate resulted in net effective and cash releasing spreads of (31.0)% and (33.5)%, respectively, for the executed lease extension. Excluding the Tireco, Inc. lease, Net Effective and Cash Rent Change for Q1-26 was 5.5% and (1.8)%, respectively. This lease extension is not indicative of the Company’s projected portfolio releasing spreads given the unique size, adjacent competitive supply and lease structure. The lease includes annual contractual rental rate increases of 2.75%, three months of rent abatement in 2027, and a conversion to a gross lease from a triple net lease, which enables the Company to capture the benefit from any potential reduction in real estate property taxes.
(2)Represents all executed leases, excluding leases with terms less than 12 months and month-to-month tenant leases.
(3)Net absorption represents total leasing activity, less expiring leases adjusted for square footage placed into repositioning/development.
(4)Retention rate is calculated as renewal lease SF plus relocation/expansion SF, divided by expiring lease SF. Retention excludes SF related to the following: (i) expiring leases associated with space that is placed into repositioning/development after the tenant vacates, (ii) early terminations with prenegotiated replacement leases and (iii) move outs where space is directly leased by subtenants.
(5)Retention + Backfill rate represents SF retained (per Retention rate definition in footnote (4)) plus the SF of move outs in the quarter which were re-leased prior to or during the same quarter, divided by expiring lease SF.
(6)Net effective and cash rent statistics and turnover costs exclude 19 new leases aggregating 469,443 RSF for which there was no comparable lease data. Comparable leases generally exclude: (i) space that has never been occupied under our ownership, (ii) repositioned/developed space, including space in pre-development/entitlement process, (iii) space that has been vacant for greater than 1 year or (iv) lease terms less than 12 months.
(7)Turnover costs include estimated tenant improvement and leasing costs associated with leases executed during the current period. Excludes costs for 1st generation leases.
Second Quarter 2026
Supplemental Financial Reporting Package
Page 22
Leasing Statistics (Continued).
(unaudited results)
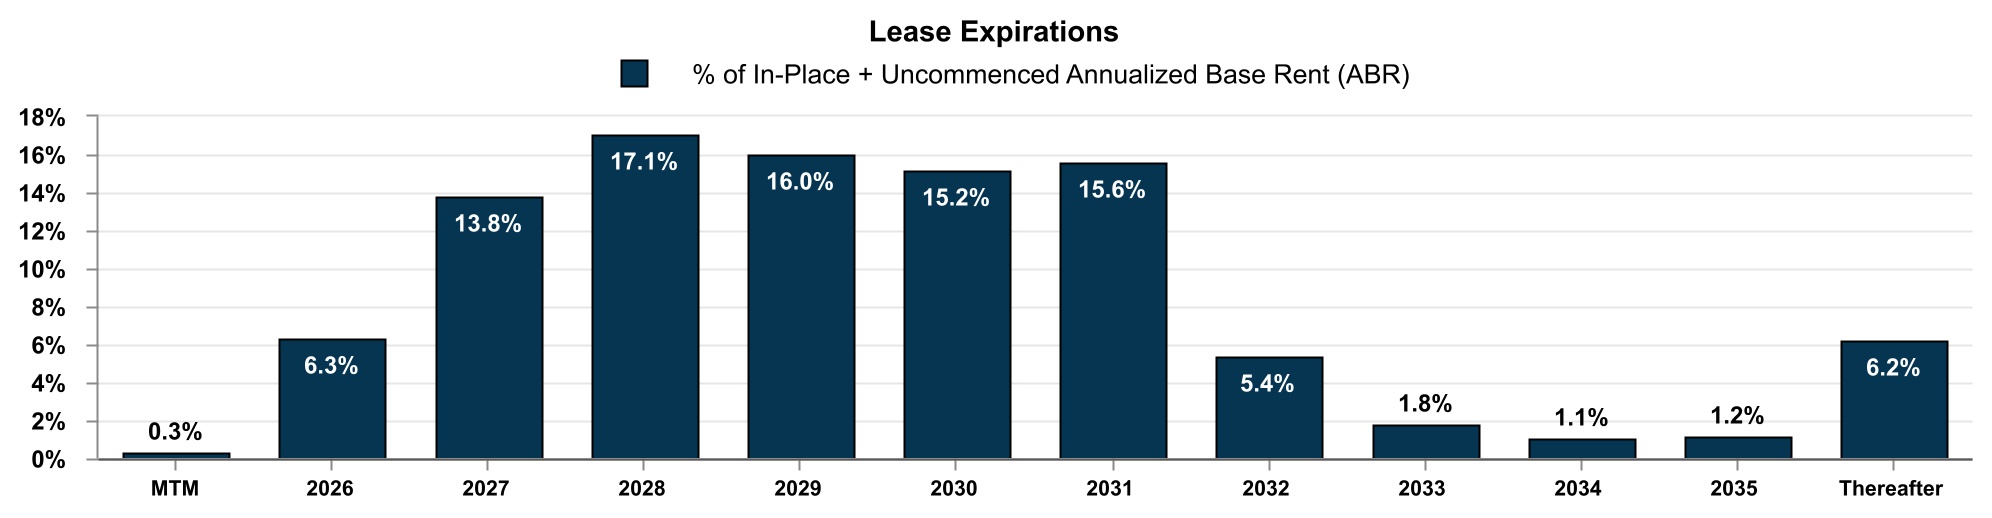
Lease Expiration Schedule as of June 30, 2026:
Year of Lease Expiration
# of Leases Expiring
Total Rentable Square Feet
In-Place + Uncommenced ABR (in thousands)
In-Place + Uncommenced ABR per SF
Available
—
2,384,291
$
—
$—
Repositioning/Development(1)
—
2,474,105
—
$—
MTM Tenants
14
158,274
2,257
$14.26
2026
169
2,556,164
49,811
$19.49
2027
369
6,506,130
109,262
$16.79
2028
307
7,092,998
135,763
$19.14
2029
298
7,032,016
126,972
$18.06
2030
144
7,089,774
120,416
$16.98
2031
133
8,291,669
123,868
$14.94
2032
41
2,314,372
42,911
$18.54
2033
16
785,478
14,195
$18.07
2034
10
493,497
8,828
$17.89
2035
8
462,072
9,659
$20.90
Thereafter
35
2,293,363
49,384
$21.53
Total Portfolio
1,544
49,934,203
$
793,326
$17.60(2)
(1)Represents vacant space at properties that were classified as repositioning, development or lease-up as of June 30, 2026.
(2)Excluding in-place + uncommenced ABR associated with Land/IOS properties ($41.55M ABR) and cellular tower, solar and parking lot leases ($2.98M ABR), in-place + uncommenced building ABR per building SF was $16.69.
Second Quarter 2026
Supplemental Financial Reporting Package
Page 23
Top Tenants and Lease Segmentation.
(unaudited results)
Top 20 Tenants as of June 30, 2026
Tenant
Submarket
Leased Rentable SF
In-Place + Uncommenced
ABR (in 000’s)(1)
% of In-Place +
Uncommenced ABR(1)
In-Place + Uncommenced
ABR per SF(1)
Lease Expiration
Tireco, Inc.(2)
Inland Empire West
1,101,840
$20,021
2.5%
$18.17
4/30/2030(2)
Zenith Energy West Coast Terminals LLC
South Bay
—(3)
$11,909
1.5%
$3.41(3)
9/29/2041
Cubic Corporation
Central San Diego
315,227
$11,786
1.5%
$37.39
3/31/2038
IBY, LLC
San Gabriel Valley
1,178,021
$11,694
1.5%
$9.93
4/5/2031(4)
Federal Express Corporation
Multiple Submarkets(5)
527,861
$10,986
1.4%
$20.81
11/30/2032(5)
L3 Technologies, Inc.
South Bay
461,431
$9,537
1.2%
$20.67
9/30/2031
GXO Logistics Supply Chain, Inc.
Mid-Counties
411,034
$9,421
1.2%
$22.92
11/30/2028
Best Buy Stores, L.P.
Inland Empire West
501,649
$9,225
1.2%
$18.39
6/30/2029
The Hertz Corporation
South Bay
38,680(6)
$8,922
1.1%
$11.14(6)
10/31/2026
Orora Packaging Solutions
Multiple Submarkets(7)
476,065
$8,175
1.0%
$17.17
9/30/2028(7)
Top 10 Tenants
5,011,808
$111,676
14.1%
Top 11 - 20 Tenants
3,804,158
$52,453
6.6%
Total Top 20 Tenants
8,815,966
$164,129
20.7%
(1)See page 33 for further details on how these amounts are calculated.
(2)Represents current in-place ABR. In Jan 2026, we executed an amendment with Tireco, Inc. to extend the lease term to Apr 30, 2030, with annualized base rent of approximately $17.0 million commencing Feb 1, 2027.
(3)The tenant is leasing an 80.2 acre industrial outdoor storage site with ABR of $11.9 million or $3.41 per land square foot.
(4)Includes (i) 184,879 RSF expiring Apr 30, 2028 and (ii) 993,142 RSF expiring Apr 5, 2031.
(5)Includes (i) one land lease in LA-Mid-Counties expiring Jun 30, 2029, (ii) one land lease in North Orange County expiring Oct 31, 2031, (iii) 30,160 RSF in Ventura expiring Sep 30, 2027, (iv) an additional land lease in LA-Mid-Counties expiring Jun 30, 2029, (v) 42,270 RSF in LA-South Bay expiring Oct 31, 2030, (vi) 311,995 RSF in North County San Diego expiring Feb 28, 2031, & (vii) 143,436 RSF in LA-South Bay expiring Nov 30, 2032.
(6)The tenant is leasing 18.4 acres of land with ABR of $8.9 million or $11.14 per land square foot.
(7)Includes (i) 100,500 RSF in LA-Greater SF Valley expiring Sep 30, 2027, (ii) 48,997 RSF in North County San Diego expiring Sep 30, 2028 and (ii) 326,568 RSF in North Orange County expiring Sep 30, 2028.
Lease Segmentation by Size:
Square Feet
Number of Leases
Leased Building/Land Rentable SF
Building/Land Rentable SF
Leased %
Leased % Excl. Repo/Redev
In-Place +
Uncommenced ABR
(in 000’s)(1)
% of In-Place +
Uncommenced
ABR(1)
In-Place +
Uncommenced
ABR per SF(1)
Building:
<4,999
522
1,290,103
1,401,678
92.0%
92.0%
$
26,079
3.3%
$20.21
5,000 - 9,999
222
1,586,618
1,730,752
91.7%
92.9%
31,161
3.9%
$19.64
10,000 - 24,999
316
5,178,278
5,736,201
90.3%
92.3%
98,076
12.4%
$18.94
25,000 - 49,999
182
6,595,050
7,143,616
92.3%
95.2%
121,152
15.3%
$18.37
50,000 - 99,999
115
8,219,885
9,198,452
89.4%
96.0%
145,549
18.3%
$17.71
>100,000
116
22,007,654
24,510,542
89.8%
95.5%
326,770
41.2%
$14.85
Building Subtotal / Wtd. Avg.
1,473
44,877,588
(2)
49,721,241
(2)
90.3%
(2)
95.0%
(2)
$
748,787
94.4%
$16.69
Land/IOS(3)
22
7,664,817
(4)
8,263,593
(4)
92.8%
(4)
41,555
5.2%
$5.42
(4)
Other(3)
49
2,984
0.4%
Total
1,544
$
793,326
100.0%
(1)See page 33 for further details on how these amounts are calculated.
(2)Excludes 198,219 leased building RSF and 212,962 building RSF that are associated with “Land/IOS.” Including this RSF, total portfolio is 90.3% leased and 95.0% occupied.
(3)“Land/IOS” includes leases for improved land sites and industrial outdoor storage (IOS) sites. “Other” includes amounts related to cellular tower, solar and parking lot leases.
(4)Represents leased land square feet, available land square feet, land leased percentage and ABR per land square foot associated with Land/IOS leases.
Second Quarter 2026
Supplemental Financial Reporting Package
Page 24
Capital Expenditure Summary.
(unaudited results, in thousands, except square feet and per square foot data)
Six months ended June 30, 2026
Year to Date
Q2-2026
Q1-2026
Total
SF(1)
PSF
Tenant Improvements:
New Leases – 1st Generation
$
—
$
148
$
148
44,052
$
3.36
New Leases – 2nd Generation
127
50
177
342,432
$
0.52
Renewals
115
135
250
483,116
$
0.52
Total Tenant Improvements
$
242
$
333
$
575
Leasing Commissions & Lease Costs:
New Leases – 1st Generation
$
2,214
$
2,174
$
4,388
950,924
$
4.61
New Leases – 2nd Generation
1,679
3,931
5,610
1,433,954
$
3.91
Renewals
3,263
4,262
7,525
4,232,953
$
1.78
Total Leasing Commissions & Lease Costs
$
7,156
$
10,367
$
17,523
Total Recurring Capex
$
4,750
$
2,314
$
7,064
50,348,153
$
0.14
Recurring Capex % of NOI
2.5
%
1.2
%
1.9
%
Recurring Capex % of Rental Income
2.0
%
1.0
%
1.5
%
Nonrecurring Capex:
Repositioning and Development in Process(2)
$
19,597
$
29,483
$
49,080
Unit Renovation(3)
7,914
7,933
15,847
Other(4)
4,796
2,451
7,247
Total Nonrecurring Capex
$
32,307
$
39,867
$
72,174
35,695,785
$
2.02
Other Capitalized Costs(5)
$
11,090
$
13,858
$
24,948
(1)For tenant improvements and leasing commissions, reflects the aggregate square footage of the leases in which we incurred such costs, excluding new/renewal leases in which there were no tenant improvements and/or leasing commissions. For recurring capex, reflects the weighted average square footage of our consolidated portfolio for the period (including properties that were sold during the period). For nonrecurring capex, reflects the aggregate square footage of the properties in which we incurred such capital expenditures.
(2)Includes capital expenditures related to repositioning or development properties.
(3)Includes non-tenant-specific capital expenditures.
(4)Includes other nonrecurring capital expenditures including, but not limited to, seismic and fire sprinkler upgrades, replacements of either roof or parking lots, solar installation, ADA related construction and capital expenditures for deferred maintenance existing at the time such property was acquired.
(5)Includes the following capitalized costs: (i) compensation costs of personnel directly responsible for and who spend their time on development, renovation and rehabilitation activity and (ii) interest, property taxes and insurance costs incurred during the pre-development and construction periods of repositioning or development projects.
Second Quarter 2026
Supplemental Financial Reporting Package
Page 25
Properties and Space Under Repositioning/Development.(1)
Properties and Space Under Repositioning/Development (Continued).(1)
As of June 30, 2026
(unaudited results, $ in millions)
Near-Term Potential Future Repositioning and Development
Property
Submarket
Repositioning/ Development
Projected
RSF(2)
Estimated Construction Start
Purchase Price ($M)
Lease Expiration Date
Project Description
9400-9500 Santa Fe Springs Road(10)
Mid-Counties
Repositioning
184,270
3Q-26
$210.0
Vacant
Functionality and quality upgrades including new office, additional power capacity and sprinkler upgrade.
3100 Fujita Street
South Bay
Repositioning
91,516
3Q-26
$14.2
Vacant
Repositioning of an existing 1970s vintage, functionally-limited industrial building acquired in 2018 through a sale leaseback.
9000 Airport Boulevard
South Bay
Development
395,684
4Q-26
$144.3
10/31/26
18 acres of industrially-zoned land acquired through a sale leaseback for planned development. Following lease expiration, the project will deliver a rare, Class-A industrial campus.
4181 Ruffin Road
Central San Diego
Development
220,943
1Q-27
$36.0
10/31/26
Development of a modern Class A industrial building with highly competitive functionality in a premier location.
3550 Tyburn Street
SF Valley
Repositioning
85,537
1Q-27
$10.5
01/31/27
Repositioning to reduce office space and upgrade warehouse infrastructure to convert from manufacturing to more modern distribution use.
Properties and Space Under Repositioning/Development (Continued).(1)
As of June 30, 2026
(unaudited results, in thousands, except square feet)
Current Year Stabilized Repositioning/Development
Property (Submarket)
RSF(2)
Stabilized Period
Stabilized Return on Cost
12118 Bloomfield Avenue
107,045
1Q-26
5.2%
1315 Storm Parkway(11)
37,844
1Q-26
5.9%
3211-3233 Mission Oaks Blvd.(3)
116,852
2Q-26
9.6%
19900 Plummer Street(4)
79,539
2Q-26
4.4%
(1)For definitions of “Properties and Space Under Repositioning/Development,” “Estimated Construction Period,” “Purchase Price,” “Estimated Project Costs,” “Estimated Total Investment,” “Estimated Remaining Costs,” “Annualized Stabilized Cash NOI,” “Actual Cash NOI,” “Estimated Stabilized Return on Cost” and other definitions related to our repositioning/development portfolio, see pages 35-36 in the Notes and Definitions section of this report.
(2)RSF is the actual rentable square footage that is subject to repositioning at the property/building, and may be less than the total RSF of the entire property or particular building(s) under repositioning. For developments, RSF represents the estimated rentable square footage of the project upon completion of the development.
(3)As of June 30, 2026, the entire project includes 526,069 RSF, comprised of: (i) 3211 Mission Oaks Blvd., a newly constructed building totaling 116,852 RSF, and (ii) 3233 Mission Oaks Blvd., with 409,217 RSF that was not redeveloped. Site improvements were completed across the entire project. Costs and yield shown reflect the entire project, while RSF and property leased percentage apply only to 3211 Mission Oaks Blvd. 3211 Mission Oaks Blvd was considered stabilized in Q1-26, as one year had passed since construction completion. In 2Q-26 this project achieved 100% occupancy and for presentation purposes is reflected as stabilized in 2Q-26.
(4)19900 Plummer Street was considered stabilized in 1Q-26, as one year had passed since construction completion. In 2Q-26 this project achieved 100% occupancy and for presentation purposes is reflected as stabilized in 2Q-26.
(5)As of 2Q-26, 4416 Azusa Canyon Road is considered stabilized, as one year had passed since construction completion. However, this project is presented in Lease-Up because it has not yet reached 90% occupancy.
(6)As of 1Q-26, 12772 San Fernando Road and 1500 Raymond Avenue are considered stabilized, as one year had passed since construction completion. However, these properties are presented in Lease-Up because they have not yet reached 90% occupancy.
(7)During 2Q-26, a 46,653 RSF lease was executed at 14955 Salt Lake Avenue, bringing the property to 100% leased. The lease is expected to commence in 3Q-26.
(8)Subsequent to quarter-end a 66,130 RSF lease was executed at 24935-24955 Avenue Kearny, bringing the property to 100% leased. The lease is expected to commence in 4Q-26.
(9)Subsequent to quarter-end a 35,895 RSF lease was executed at 3680-3880 Voyager Street, bringing the property to 53% leased. The lease is expected to commence in 4Q-26.
(10)9400-9500 Santa Fe Springs Road totals 595,304 RSF and the proposed repositioning pertains to work at only one of the units, totaling 184,270 RSF. The purchase price shown in the table is for the entire property. The Actual Cash NOI referenced in aggregate is only for the one repositioning unit.
(11)1315 Storm Parkway was considered stabilized in 4Q-25, as one year had passed since construction completion. In 1Q-26 this project achieved 100% occupancy and for presentation purposes is reflected as stabilized in 1Q-26.
Second Quarter 2026
Supplemental Financial Reporting Package
Page 30
Current Year Investments and Dispositions Summary.
As of June 30, 2026
(unaudited results)
2026 Current Period Dispositions
Disposition Date
Property Address
Submarket
Asset Type
Rentable Square Feet
Gross Proceeds
($M)
Realized NOI Contribution in the Quarter of Sale ($M)
2/6/2026
14005 Live Oak Avenue
Los Angeles - San Gabriel Valley
Development
—
$
14.50
$
—
2/24/2026
18250 Euclid Street
Orange County Airport
Operating
62,838
$
26.71
$
0.1
3/17/2026
29010 Avenue Paine
Los Angeles - Greater San Fernando Valley
Operating
100,157
$
31.00
$
0.2
3/18/2026
13700-13738 Slover Avenue
San Bernardino - Inland Empire West
Operating
17,862
$
14.48
$
(0.1)
3/25/2026
600-708 Vermont Avenue
North Orange County
Development
133,836
$
40.70
$
—
4/16/2026
423-424 Berry Way
North Orange County
Development
101,380
$
16.51
$
—
5/1/2026
18455 Figueroa Street
Los Angeles - South Bay
Development
146,765
$
34.90
$
(0.1)
5/4/2026
17031-17037 Green Drive
Los Angeles - San Gabriel Valley
Operating
51,000
$
16.65
$
—
5/7/2026
19100 Susana Road
Los Angeles - South Bay
Operating
52,714
$
16.10
$
(0.1)
5/11/2026
13711 Freeway Drive
Los Angeles - Mid-Counties
Development
82,180
$
15.78
$
—
5/11/2026
3901 Via Oro Avenue
Los Angeles - South Bay
Development
53,817
$
10.28
$
—
6/2/2026
2610 S. Birch Street
Orange County Airport
Operating
83,852
$
27.68
$
0.2
Total 2026 Dispositions through June 30, 2026
886,401
$
265.29
Second Quarter 2026
Supplemental Financial Reporting Package
Page 31
Net Asset Value Components.
As of June 30, 2026
(unaudited and in thousands, except share data)
Net Operating Income
Pro Forma Net Operating Income (NOI)(1)
Three Months Ended Jun 30, 2026
Total operating rental income
$242,996
Property operating expenses
(56,214)
Pro forma effect of uncommenced leases(2)
182
Pro forma effect of dispositions(3)
68
Pro forma NOI effect of significant properties classified as current, lease-up, and stabilized repositioning and development(4)
11,883
Pro Forma NOI
198,915
Above/(below) market lease revenue adjustments
(3,805)
Straight line rental revenue adjustment
(9,967)
Pro Forma Cash NOI
$185,143
Balance Sheet Items
Other assets and liabilities
June 30, 2026
Cash and cash equivalents
$32,226
Loan receivable, net
123,934
Rents and other receivables, net
12,132
Other assets
16,987
Accounts payable, accrued expenses and other liabilities
(99,101)
Dividends payable
(100,960)
Tenant security deposits
(92,386)
Prepaid rents
(79,518)
Estimated remaining cost to complete repositioning/development projects(5)
(125,700)
Total other assets and liabilities
$(312,386)
Debt and Shares Outstanding
Total consolidated debt(6)
$3,285,503
Preferred stock/units - liquidation preference
$173,250
Common shares outstanding(7)
222,360,849
Operating partnership units outstanding(8)
8,716,332
Total common shares and operating partnership units outstanding
231,077,181
(1)For definition/discussion of non-GAAP financial measures and reconciliations to their nearest GAAP equivalents, see the definitions & reconciliation section beginning on page 33 and page 12 of this report, respectively.
(2)Represents the estimated incremental base rent from uncommenced new and renewal leases as if they had commenced as of April 1, 2026.
(3)Represents the deduction of actual 2Q'26 NOI for the properties that we sold during the current quarter. See page 31 for a detail of current year disposition properties.
(4)Represents the estimated incremental NOI from the properties that were classified as repositioning, development, lease-up or stabilized during the three months ended June 30, 2026, assuming that all repositioning/development work had been completed and all of the properties were fully stabilized as of April 1, 2026. Includes all properties that are separately listed on pages 26-28. We have made a number of assumptions in such estimates & there can be no assurance that we would have generated the projected levels of NOI had these properties actually been stabilized as of April 1, 2026.
(5)Reflects the estimated remaining costs for all repositioning, development, lease-up and stabilized properties that are listed on pages 26-28.
(7)Represents outstanding shares of common stock of the Company, which excludes 628,208 shares of unvested restricted stock.
(8)Represents outstanding common units of the Company’s operating partnership, Rexford Industrial Realty, L.P., that are owned by unit holders other than Rexford Industrial Realty, Inc. Includes 1,765,430 vested LTIP Units and 1,325,969 vested performance units and excludes 185,285 unvested LTIP Units and 2,011,382 unvested performance units.
Second Quarter 2026
Supplemental Financial Reporting Package
Page 32
Notes and Definitions.
`Adjusted Funds from Operations (“AFFO”): We calculate adjusted funds from operations, or AFFO, by adding to or subtracting from FFO, as defined below, the following items: (i) certain non-cash operating revenues and expenses, (ii) capitalized operating expenditures such as construction payroll, (iii) recurring capital expenditures required to maintain and re-tenant our properties, (iv) capitalized interest costs resulting from the repositioning/development of certain of our properties and (v) 2nd generation tenant improvements and leasing commissions. Management uses AFFO as a supplemental performance measure because it provides a performance measure that, when compared year over year, captures trends in portfolio operating results. We also believe that, as a widely recognized measure of the performance of REITs, AFFO will be used by investors as a basis to assess our performance in comparison to other REITs. However, because AFFO may exclude certain non-recurring capital expenditures and leasing costs, the utility of AFFO as a measure of our performance is limited. Additionally, other Equity REITs may not calculate AFFO using the method we do. As a result, our AFFO may not be comparable to such other Equity REITs’ AFFO. AFFO should be considered only as a supplement to net income or loss (as computed in accordance with GAAP) as a measure of our performance.
In-Place Annualized Base Rent and Uncommenced Annualized Base Rent:
•In-Place Annualized Base Rent (“In-Place ABR”): Calculated as the monthly contractual base rent (before rent abatements) per the terms of the lease, as of June 30, 2026, multiplied by 12. Includes leases that had commenced as of June 30, 2026 or leases where tenant had taken early possession of space as of June 30, 2026. Excludes tenant reimbursements.
•In-Place ABR per Square Foot: Calculated by dividing In-Place ABR for the lease by the occupied square feet of the lease, as of June 30, 2026.
•Combined In-Place and Uncommenced Annualized Base Rent (“In-Place + Uncommenced ABR”): Calculated by adding (i) In-Place ABR and (ii) ABR Under Uncommenced Leases (see definition below). Does not include adjustments for leases that expired and were not renewed subsequent to June 30, 2026, or adjustments for future known non-renewals.
•ABR Under Uncommenced Leases: Calculated by adding the following:
(i) ABR under Uncommenced New Leases = first full month of contractual base rents (before rent abatements) to be received under Uncommenced New Leases, multiplied by 12.
(ii) Incremental ABR under Uncommenced Renewal Leases = difference between: (a) the first full month of contractual base rents (before rent abatements) to be received under Uncommenced Renewal Leases and (b) the monthly In-Place ABR for the same space as of June 30, 2026, multiplied by 12.
•In-Place + Uncommenced ABR per Square Foot: Calculated by dividing (i) In-Place + Uncommenced ABR for the leases by (ii) the square footage under commenced and uncommenced leases (net of renewal space) as of June 30, 2026.
•Uncommenced New Leases: Reflects new leases (for vacant space) that have been signed but had not yet commenced as of June 30, 2026.
•Uncommenced Renewal Leases: Reflects renewal leases (for space occupied by renewing tenant) that had been signed but had not yet commenced as of June 30, 2026.
Capital Expenditures, Non-recurring: Expenditures made with respect to a property for repositioning, development, major property or unit upgrade or renovation, and further includes capital expenditures for seismic upgrades, roof or parking lot replacements and capital expenditures for deferred maintenance existing at the time such property was acquired.
Capital Expenditures, Recurring: Expenditures made with respect to a property for maintenance of such property and replacement of items due to ordinary wear and tear including, but not limited to, expenditures made for maintenance of parking lot, roofing materials, mechanical systems, HVAC systems and other structural systems. Recurring capital expenditures shall not include any of the following: (a) major upgrade or renovation of such property not necessary for proper maintenance or marketability of such property; (b) capital expenditures for seismic upgrades; (c) capital expenditures for deferred maintenance for such property existing at the time such property was acquired; or (d) replacements of either roof or parking lots.
Capital Expenditures, First Generation: Capital expenditures for newly acquired space, newly developed or redeveloped space, or change in use.
Cash NOI: Cash basis NOI is a non-GAAP measure, which we calculate by adding or subtracting from NOI (i) amortization of above/(below) market lease intangibles and amortization of other deferred rent resulting from sale leaseback transactions with below market leaseback payments and (ii) straight-line rent adjustment. We use Cash NOI, together with NOI, as a supplemental performance measure. Cash NOI should not be used as a measure of our liquidity, nor is it indicative of funds available to fund our cash needs. Cash NOI should not be used as a substitute for cash flow from operating activities computed in accordance with GAAP. We use Cash NOI to help evaluate the performance of the Company as a whole, as well as the performance of our Same Property Portfolio.
Core Funds from Operations (“Core FFO”): We calculate Core FFO by adjusting FFO for non-comparable items outlined in the “Non-GAAP FFO and Core FFO Reconciliations” on pages 12-13. We believe that Core FFO is a useful supplemental measure and that by adjusting for items that are not considered by us to be part of our ongoing operating performance, provides a more meaningful and consistent comparison of the Company’s operating and financial performance period-over-period. Because these adjustments have a real economic impact on our financial condition and results from operations, the utility of Core FFO as a measure of our performance is limited. Other REITs may not calculate Core FFO in a consistent manner. Accordingly, our Core FFO may not be comparable to other REITs' core FFO. Core FFO should be considered only as a supplement to net income or loss computed in accordance with GAAP as a measure of our performance. “Company Share of Core FFO” reflects Core FFO attributable to common stockholders, which excludes amounts allocable to noncontrolling interests, participating securities and preferred stockholders (which consists of preferred stock dividends, but excludes non-recurring preferred stock redemption charges related to the write-off of original issuance costs which we do not consider reflective of our core revenue or expense streams).
Second Quarter 2026
Supplemental Financial Reporting Package
Page 33
Notes and Definitions.
Debt Covenants ($ in thousands)
June 30, 2026
Current Period Covenant
Revolver, $300M & $400M Term Loan Facilities
Senior Notes ($125M, $25M, $75M)
Maximum Leverage Ratio
less than 60%
24.4%
27.8%
Maximum Secured Leverage Ratio
less than 45%
0.7%
N/A
Maximum Secured Leverage Ratio
less than 40%
N/A
0.8%
Maximum Secured Recourse Debt
less than 15%
N/A
—%
Minimum Tangible Net Worth
$7,266,909
N/A
$9,136,517
Minimum Fixed Charge Coverage Ratio
at least 1.50 to 1.00
5.44 to 1.0
5.38 to 1.00
Unencumbered Leverage Ratio
less than 60%
25.2%
29.0%
Unencumbered Interest Coverage Ratio
at least 1.75 to 1.00
5.95 to 1.00
5.95 to 1.00
June 30, 2026
Current Period Covenant
Senior Notes ($400M due 2030 & $400M due 2031)
Maximum Debt to Total Asset Ratio
less than 60%
25.6%
Maximum Secured Debt to Total Asset Ratio
less than 40%
0.8%
Minimum Debt Service Coverage Ratio
at least 1.50 to 1.00
5.31 to 1.00
Minimum Unencumbered Assets to Unsecured Debt Ratio
at least 1.50 to 1.00
3.96 to 1.00
Our actual performance for each covenant is calculated based on the definitions set forth in each loan agreement/indenture.
EBITDAre and Adjusted EBITDAre: We calculate EBITDAre in accordance with the standards established by the National Association of Real Estate Investment Trusts (“NAREIT”). EBITDAre is calculated as net income (loss) (computed in accordance with GAAP), before interest expense, tax expense, depreciation and amortization, gains (or losses) from sales of depreciable operating property, impairment losses of depreciable property and adjustments to reflect our proportionate share of EBITDAre from our unconsolidated joint venture. We calculate Adjusted EBITDAre by adding or subtracting from EBITDAre the following items: (i) non-cash stock based compensation expense, (ii) write-offs of below market lease intangibles related to unexercised renewal option, (iii) gain (loss) on debt extinguishment and debt modification expenses, (iv) acquisition expenses, (v) the pro-forma effects of acquisitions and dispositions and (vi) other nonrecurring expenses. We believe that EBITDAre and Adjusted EBITDAre are helpful to investors as a supplemental measure of our operating performance as a real estate company because it is a direct measure of the actual operating results of our industrial properties. We also use these measures in ratios to compare our performance to that of our industry peers. In addition, we believe EBITDAre and Adjusted EBITDAre are frequently used by securities analysts, investors and other interested parties in the evaluation of Equity REITs. However, because EBITDAre and Adjusted EBITDAre are calculated before recurring cash charges including interest expense and income taxes, and are not adjusted for capital expenditures or other recurring cash requirements of our business, their utility as a measure of our liquidity is limited. Accordingly, EBITDAre and Adjusted EBITDAre should not be considered alternatives to cash flow from operating activities (as computed in accordance with GAAP) as a
measure of our liquidity. EBITDAre and Adjusted EBITDAre should not be considered as alternatives to net income or loss as an indicator of our operating performance. Other Equity REITs may calculate EBITDAre and Adjusted EBITDAre differently than we do; accordingly, our EBITDAre and Adjusted EBITDAre may not be comparable to such other Equity REITs’ EBITDAre and Adjusted EBITDAre. EBITDAre and Adjusted EBITDAre should be considered only as supplements to net income or loss (as computed in accordance with GAAP) as a measure of our performance.
Ending occupancy excluding repositioning/development: Represents consolidated portfolio occupancy adjusted to exclude all vacant SF associated with repositioning and development projects.
Fixed Charge Coverage Ratio:
For the Three Months Ended
Jun 30, 2026
Mar 31, 2026
Dec 31, 2025
Sep 30, 2025
Jun 30, 2025
EBITDAre
$
181,100
$
174,638
$
103,701
$
171,108
$
173,922
Above/(below) market lease revenue adjustments
(3,805)
(4,647)
(4,129)
(5,254)
(5,788)
Non-cash stock compensation
3,666
4,063
8,537
10,485
10,091
Co-CEO transition costs
(2,330)
—
60,223
—
—
Debt extinguishment and modification expenses
—
—
—
—
291
Straight line rental revenue adj.
(9,967)
(15,136)
(9,073)
(8,164)
(6,918)
Capitalized payments
(4,586)
(5,851)
(6,013)
(6,516)
(5,304)
Accretion of net loan origination fees
(115)
(115)
(115)
(115)
(115)
Recurring capital expenditures
(4,750)
(2,314)
(2,566)
(3,563)
(5,887)
2nd gen. tenant improvements
(242)
(185)
(179)
(460)
(663)
2nd gen. leasing commissions
(4,942)
(8,193)
(6,324)
(8,007)
(4,162)
Cash flow for fixed charge coverage calculation
$
154,029
$
142,260
$
144,062
$
149,514
$
155,467
Cash interest expense calculation detail:
Interest expense
28,571
26,600
25,451
25,463
26,701
Capitalized interest
6,026
7,352
8,801
9,240
9,064
Note payable premium amort.
(1,662)
(1,641)
(1,616)
(1,597)
(1,579)
Amort. of deferred financing costs
(1,333)
(1,334)
(1,333)
(1,340)
(1,255)
Amort. of swap term fees & t-locks
(77)
(77)
(78)
(78)
(76)
Cash interest expense
31,525
30,900
31,225
31,688
32,855
Scheduled principal payments
217
215
247
244
242
Preferred stock/unit dividends
2,405
2,404
2,405
2,404
2,405
Fixed charges
$
34,147
$
33,519
$
33,877
$
34,336
$
35,502
Fixed Charge Coverage Ratio
4.5
x
4.2
x
4.3
x
4.4
x
4.4
x
Second Quarter 2026
Supplemental Financial Reporting Package
Page 34
Notes and Definitions.
NAREIT Defined Funds from Operations (“FFO”): We calculate FFO in accordance with the standards established by NAREIT. FFO represents net income (loss) (computed in accordance with GAAP), excluding gains (or losses) on sale of real estate assets, gains (or losses) on sale of assets incidental to our business, impairment losses of depreciable operating property or assets incidental to our business, real estate related depreciation and amortization (excluding amortization of deferred financing costs) and after adjustments for unconsolidated joint ventures. Management uses FFO as a supplemental performance measure because, in excluding real estate related depreciation and amortization, gains and losses from property dispositions or assets incidental to our business, other than temporary impairments of unconsolidated real estate entities, and impairment on our investment in real estate and other assets incidental to our business, it provides a performance measure that, when compared year over year, captures trends in occupancy rates, rental rates and operating costs. We also believe that, as a widely recognized measure of performance used by other REITs, FFO may be used by investors as a basis to compare our operating performance with that of other REITs. However, because FFO excludes depreciation and amortization and captures neither the changes in the value of our properties that result from use or market conditions nor the level of capital expenditures and leasing commissions necessary to maintain the operating performance of our properties, all of which have real economic effects and could materially impact our results from operations, the utility of FFO as a measure of our performance is limited. Other equity REITs may not calculate or interpret FFO in accordance with the NAREIT definition as we do, and, accordingly, our FFO may not be comparable to such other REITs’ FFO. FFO should not be used as a measure of our liquidity, and is not indicative of funds available for our cash needs, including our ability to pay dividends. FFO should be considered only as a supplement to net income or loss computed in accordance with GAAP as a measure of our performance. “Company Share of FFO” reflects FFO attributable to common stockholders, which excludes amounts allocable to noncontrolling interests, participating securities and preferred stockholders (which consists of preferred stock dividends and any preferred stock redemption charges related to the write-off of original issuance costs).
Net Operating Income (“NOI”): NOI is a non-GAAP measure which includes the revenue and expense directly attributable to our real estate properties. NOI is calculated as total revenue from real estate operations including i) rental revenue, ii) tenant reimbursements, and iii) other income less property expenses. We use NOI as a supplemental performance measure because, in excluding real estate depreciation and amortization expense, general and administrative expenses, interest expense, interest income, gains (or losses) on sale of real estate, impairment losses of depreciable operating property, and other non-operating items, it provides a performance measure that, when compared year over year, captures trends in occupancy rates, rental rates and operating costs. We also believe that NOI will be useful to investors as a basis to compare our operating performance with that of other REITs. However, because NOI excludes depreciation and amortization expense and captures neither the changes in the value of our properties that result from use or market conditions, nor the level of capital expenditures and leasing commissions necessary to maintain the operating performance of our properties (all of which have real economic effect and could materially impact our results from operations), the utility of NOI as a measure of our performance is limited. Other equity REITs may not calculate NOI in a similar manner and, accordingly, our NOI may not be comparable to such other REITs’ NOI. Accordingly, NOI should be considered only as a supplement to net income or loss as a measure of our performance. NOI should not be used as a measure of our liquidity, nor is it indicative of funds available to fund our cash needs. NOI should not be used as a substitute for cash flow from operating activities in accordance with GAAP. We use NOI to help evaluate the performance of the Company as a whole, as well as the performance of our Same Property Portfolio.
Proforma NOI: Proforma NOI is calculated by adding to NOI the following adjustments: (i) the estimated impact on NOI of uncommenced leases as if they had commenced at the beginning of the reportable period, (ii) the estimated impact on NOI of current period acquisitions as if they had been acquired at the beginning of the reportable period, (iii) the actual NOI of properties sold during the current period and (iv) the estimated incremental NOI from properties that were classified as repositioning, development and lease-up as of the end of the reporting period, assuming that all repositioning/development work had been completed and the properties/space were fully stabilized as of the beginning of the reportable period. These estimates do not purport to be indicative of what operating results would have been had the transactions actually occurred at the beginning of the reportable period and may not be indicative of future operating results.
Definitions Related to Properties and Space Under Repositioning/Development:
•Properties and Space Under Repositioning: Typically defined as properties or units where a significant amount of space is held vacant in order to implement capital improvements that improve the functionality (not including basic refurbishments, i.e., paint and carpet), cash flow and value of that space. A repositioning is generally considered complete once the investment is fully or nearly fully deployed and the property is available for occupancy.
•Properties Under Development: Typically defined as properties where we plan to fully or partially demolish an existing building(s) due to building obsolescence and/or a property with excess or vacant land where we plan to construct a ground-up building.
•Construction Period: The “Start” of the Construction Period is our current estimate of the period in which we will start physical construction on a property. The “Complete” of the Construction Period is our current estimate of the period in which we will have substantially completed a project and the project is made available for occupancy. We expect to update our timing estimates on a quarterly basis. For projects stabilized or in lease-up, represents the actual construction completion period.
•Purchase Price: Represents the contractual purchase price of the property plus closing costs.
•Estimated Project Costs: Represents the estimated costs to be incurred to complete construction and lease-up each repositioning/development project. Estimated costs include (i) nonrecurring capital expenditures, (ii) estimated tenant improvement allowances/costs and (iii) estimated leasing commissions. We expect to update our estimates upon completion of the project, or sooner if there are any significant changes to expected costs from quarter to quarter. Excludes capitalized costs including capitalized interest, property taxes, insurance and compensation.
•Estimated Total Investment: Includes the sum of the Purchase Price and Projected Repositioning/Development Costs.
•Estimated Remaining Costs: Calculated as the Estimated Total Investment less related costs incurred as of the reporting date.
•Annualized Stabilized Cash NOI: Represents management’s estimate of each project’s annual Cash NOI once the property has reached stabilization and initial rental concessions, if any, have elapsed. Actual results may vary materially from our estimates.
•Actual Cash NOI: Represents the actual cash NOI (a non-GAAP measure defined on page 33) for the repositioning/development property for the entire reported quarter or from the date of acquisition if such property was acquired during the current reported quarter.
Second Quarter 2026
Supplemental Financial Reporting Package
Page 35
Notes and Definitions.
•Estimated Stabilized Return on Cost: Calculated by dividing each project’s Annualized Stabilized Cash NOI by its Projected Total Investment.
•Stabilization Date - Properties and Space Under Repositioning/Development: We consider a repositioning/development property to be stabilized at the earlier of the following: (i) upon reaching 90% occupancy or (ii) one year from the date of completion of repositioning/development construction work.
Rental Income: See below for a breakdown of consolidated rental income for the last five trailing quarters. We believe this information is frequently used by management, investors, securities analysts and other interested parties to evaluate our performance.
Three Months Ended
Jun 30, 2026
Mar 31, 2026
Dec 31, 2025
Sep 30, 2025
Jun 30, 2025
Rental revenue (before collectability adjustment)
$
200,258
$
202,658
$
201,454
$
203,217
$
199,839
Tenant reimbursements
42,856
41,728
43,793
42,612
41,403
Other income
1,296
486
598
915
467
Increase (reduction) in revenue due to change in collectability assessment
(1,414)
(2,731)
(2,615)
13
(141)
Rental income
$
242,996
$
242,141
$
243,230
$
246,757
$
241,568
Cash Rent Change: Compares the first month cash rent excluding any abatement on new/renewal leases to the last month rent for the most recent expiring lease. Data included for comparable leases only. Comparable leases generally exclude: (i) space that has never been occupied under our ownership, (ii) repositioned/developed space, including space in pre-development/entitlement process, (iii) space that has been vacant for over one year or (iv) lease terms shorter than twelve months.
Net Effective Rent Change: Compares net effective rent, which straightlines rental rate increases and abatements, on new/renewal leases to net effective rent for the most recent expiring lease. Data included for comparable leases only. Comparable leases generally exclude: (i) space that has never been occupied under our ownership, (ii) repositioned/developed space, including space in pre-development/entitlement process, (iii) space that has been vacant for over one year or (iv) lease terms shorter than twelve months.
Same Property Portfolio (“SPP”): Our 2026 SPP is a subset of our consolidated portfolio and includes properties that were wholly owned by us for the period from January 1, 2025 through June 30, 2026, and excludes (i) properties that were acquired or sold during the period from January 1, 2025 through June 30, 2026, and (ii) properties acquired prior to January 1, 2025 that were or will be classified as repositioning/development (current and future) or lease-up during 2025 and 2026, which we believe will significantly affect the properties’ results during the comparative periods.
SPP Historical Information: The table below reflects selected information related to our SPP as initially reported in each quarter’s respective supplemental package. Within a given year, the SPP may reflect changes in repositioning/development properties or removal of sold properties.
Three Months Ended
Jun 30, 2026
Mar 31, 2026
Dec 31, 2025
Sep 30, 2025
Jun 30, 2025
# of Properties
341
342
287
288
289
Square Feet
41,633,904
41,727,325
37,466,856
37,916,326
37,991,248
Ending Occupancy
95.1
%
96.1
%
96.5
%
96.8
%
96.1
%
SPP NOI growth
(0.5)
%
0.9
%
0.4
%
1.9
%
1.1
%
SPP Cash NOI growth
1.5
%
(0.4)
%
2.8
%
5.5
%
3.9
%
Same Property Portfolio Rental Income: See below for a breakdown of 2026 and 2025 rental income for our SPP. We believe this information is frequently used by management, investors, securities analysts and other interested parties to evaluate our performance.
Three Months Ended June 30,
Six Months Ended June 30,
2026
2025
$ Change
% Change
2026
2025
$ Change
% Change
Rental revenue
$
173,640
$
174,948
$
(1,308)
(0.7)%
$
349,097
$
346,204
$
2,893
0.8%
Tenant reimbursements
36,320
35,481
839
2.4%
72,020
71,158
862
1.2%
Other income
1,014
458
556
121.4%
1,426
1,199
227
18.9%
Rental income
$
210,974
$
210,887
$
87
0.0%
$
422,543
$
418,561
$
3,982
1.0%
Reconciliation of Net Income (Loss) to NOI and Cash NOI (in thousands):
Three Months Ended
Jun 30, 2026
Mar 31, 2026
Dec 31, 2025
Sep 30, 2025
Jun 30, 2025
Net (Loss) Income
$
(523,811)
$
94,562
$
(67,735)
$
93,056
$
120,394
General and administrative
13,693
14,925
19,199
20,037
19,752
Depreciation & amortization
73,479
72,933
76,819
81,172
71,188
Other expenses, net
(2,001)
102
65,910
4,218
244
Interest expense
28,571
26,600
25,451
25,463
26,701
Debt extinguishment and modification expenses
—
—
—
—
291
Management & leasing services
—
—
(197)
(118)
(132)
Other income
(3,500)
(1,350)
—
—
—
Interest income
(2,510)
(2,937)
(4,670)
(6,367)
(7,807)
Impairment of real estate
624,754
6,824
89,097
—
—
Gains on sale of real estate
(21,893)
(26,281)
(19,931)
(28,583)
(44,361)
NOI
$
186,782
$
185,378
$
183,943
$
188,878
$
186,270
S/L rental revenue adj.
(9,967)
(15,136)
(9,073)
(8,164)
(6,918)
Above/(below) market lease revenue adjustments
(3,805)
(4,647)
(4,129)
(5,254)
(5,788)
Cash NOI
$
173,010
$
165,595
$
170,741
$
175,460
$
173,564
Second Quarter 2026
Supplemental Financial Reporting Package
Page 36
Notes and Definitions.
Reconciliation of Net (Loss) Income to Total Portfolio NOI, Same Property Portfolio NOI and Same Property Portfolio Cash NOI:
Three Months Ended June 30,
Six Months Ended June 30,
2026
2025
2026
2025
Net (loss) income
$
(523,811)
$
120,394
$
(429,249)
$
194,442
General and administrative
13,693
19,752
28,618
39,620
Depreciation and amortization
73,479
71,188
146,412
157,928
Other expenses, net
(2,001)
244
(1,899)
2,483
Interest expense
28,571
26,701
55,171
53,989
Debt extinguishment and modification expenses
—
291
—
291
Management and leasing services
—
(132)
—
(274)
Other income
(3,500)
—
(4,850)
—
Interest income
(2,510)
(7,807)
(5,447)
(11,131)
Impairment of real estate
624,754
—
631,578
—
Gains on sale of real estate
(21,893)
(44,361)
(48,174)
(57,518)
NOI
$
186,782
$
186,270
$
372,160
$
379,830
Non-Same Property Portfolio rental income
(32,022)
(30,681)
(62,594)
(71,828)
Non-Same Property Portfolio property exp.
9,403
9,405
18,932
19,388
Same Property Portfolio NOI
$
164,163
$
164,994
$
328,498
$
327,390
Straight line rental revenue adjustment
(4,938)
(6,328)
(15,235)
(13,835)
Above/(below) market lease revenue adjustments
(3,093)
(4,829)
(7,263)
(9,401)
Same Property Portfolio Cash NOI
$
156,132
$
153,837
$
306,000
$
304,154
Reconciliation of Net Loss Attributable to Common Stockholders per Diluted Share Guidance to Company share of Core FFO per Diluted Share Guidance:
2026 Estimate
Low
High
Net loss attributable to common stockholders
$
(1.32)
$
(1.27)
Company share of depreciation and amortization
1.21
1.21
Company share of impairment of real estate
2.71
2.71
Company share of gains on sale of real estate(1)
(0.21)
(0.21)
Company share of FFO
$
2.39
$
2.44
Add: Core FFO adjustments(2)
(0.01)
(0.01)
Company share of Core FFO
$
2.38
$
2.43
(1)Reflects dispositions through June 30, 2026. See details on page 31.
(2)Core FFO adjustments consist of (i) Co-CEO transition costs, (ii) severance costs, (iii) other nonrecurring expenses and (iv) write-offs of below-market lease intangibles related to unexercised renewal options.
Occupancy by County:
Jun 30, 2026
Mar 31, 2026
Dec 31, 2025
Sep 30, 2025
Jun 30, 2025
Ending Occupancy:
Los Angeles County
90.1%
89.8%
88.3%
90.9%
87.9%
Orange County
91.8%
92.2%
93.6%
93.7%
90.7%
Riverside / San Bernardino County
86.9%
91.2%
95.3%
94.4%
93.9%
San Diego County
90.4%
90.7%
85.9%
91.3%
86.7%
Ventura County
95.3%
94.5%
91.8%
89.8%
87.5%
Total/Weighted Average
90.0%
90.7%
90.2%
91.8%
89.2%
Total Portfolio RSF
49,934,203
50,445,312
51,161,188
50,850,824
51,021,897
Uncommenced Lease Data:
Total/Weighted Average
Occupied SF
44,942,906
Uncommenced Renewal Leases - Leased SF(1)
866,558
Uncommenced New Leases - Leased SF(1)
132,901
Leased SF
45,075,807
Percent Leased
90.3
%
In-Place ABR(2)
$
791,280
ABR Under Uncommenced Leases (in thousands)(2)(3)
2,046
In-Place + Uncommenced ABR (in thousands)(2)
$
793,326
In-Place + Uncommenced ABR per SF(2)
$
17.60
(1)Reflects the square footage of renewal and new leases, respectively, that have been signed but have not yet commenced as of June 30, 2026.
(2)See page 33 for further details on how these amounts are calculated.
(3)Includes $2.3 million of annualized base rent under Uncommenced New Leases and $(0.2) million of annualized base rent under Uncommenced Renewal Leases.