Strategic SHOP pipeline positioned to drive scale and growth Acquisition of 45 new, high-quality care homes across the UK October 2026 C A R E D E V E L O P M E N T S
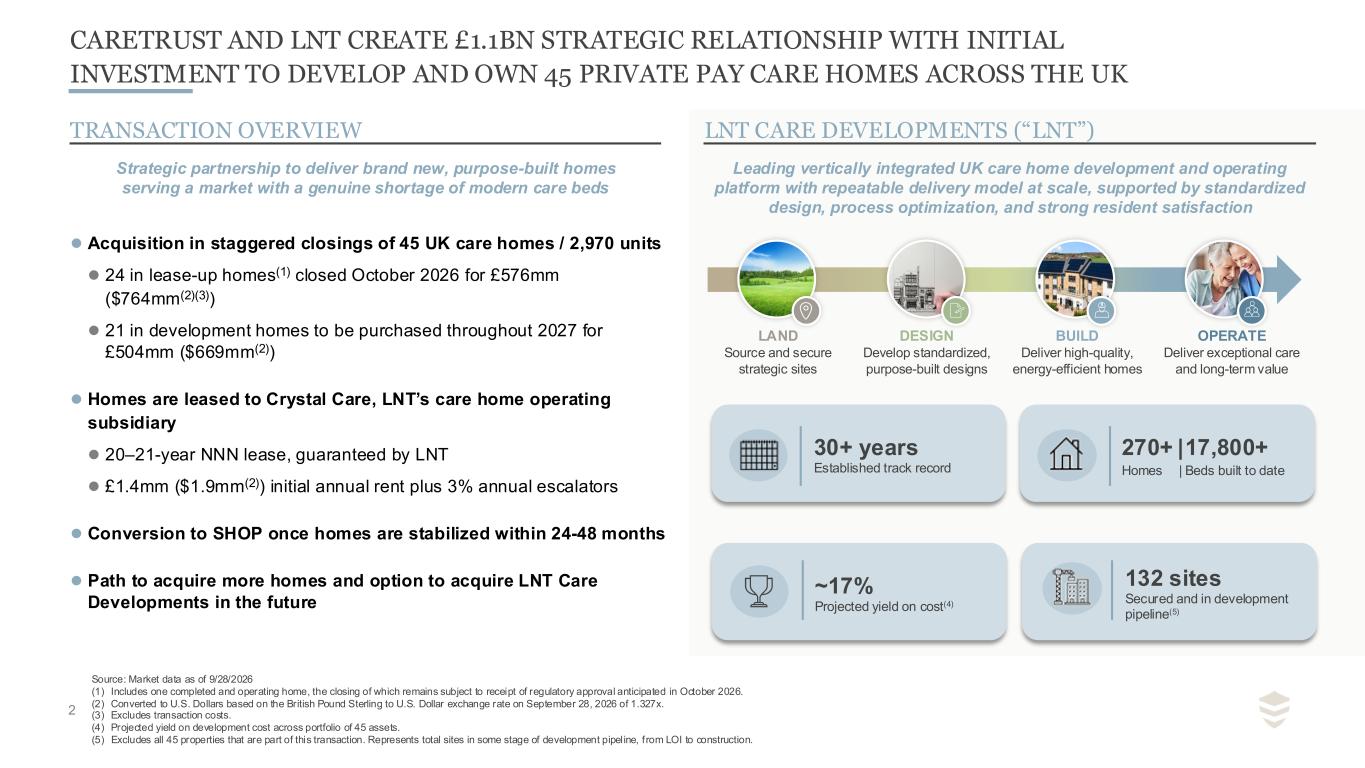
2 CARETRUST AND LNT CREATE £1.1BN STRATEGIC RELATIONSHIP WITH INITIAL INVESTMENT TO DEVELOP AND OWN 45 PRIVATE PAY CARE HOMES ACROSS THE UK TRANSACTION OVERVIEW Strategic partnership to deliver brand new, purpose-built homes serving a market with a genuine shortage of modern care beds LNT CARE DEVELOPMENTS (“LNT”) Leading vertically integrated UK care home development and operating platform with repeatable delivery model at scale, supported by standardized design, process optimization, and strong resident satisfaction 132 sites Secured and in development pipeline(5) ~17% Projected yield on cost(4) 30+ years Established track record Source: Market data as of 9/28/2026 (1) Includes one completed and operating home, the closing of which remains subject to receipt of regulatory approval anticipated in October 2026. (2) Converted to U.S. Dollars based on the British Pound Sterling to U.S. Dollar exchange rate on September 28, 2026 of 1.327x. (3) Excludes transaction costs. (4) Projected yield on development cost across portfolio of 45 assets. (5) Excludes all 45 properties that are part of this transaction. Represents total sites in some stage of development pipeline, from LOI to construction. LAND Source and secure strategic sites DESIGN Develop standardized, purpose-built designs BUILD Deliver high-quality, energy-efficient homes OPERATE Deliver exceptional care and long-term value 270+ |17,800+ Homes | Beds built to date ⚫ Acquisition in staggered closings of 45 UK care homes / 2,970 units ⚫ 24 in lease-up homes(1) closed October 2026 for £576mm ($764mm(2)(3)) ⚫ 21 in development homes to be purchased throughout 2027 for £504mm ($669mm(2)) ⚫ Homes are leased to Crystal Care, LNT’s care home operating subsidiary ⚫ 20–21-year NNN lease, guaranteed by LNT ⚫ £1.4mm ($1.9mm(2)) initial annual rent plus 3% annual escalators ⚫ Conversion to SHOP once homes are stabilized within 24-48 months ⚫ Path to acquire more homes and option to acquire LNT Care Developments in the future Leading vertically integrated UK care home development and operating platform with repeatable delivery model at scale through building standardization and process optimization
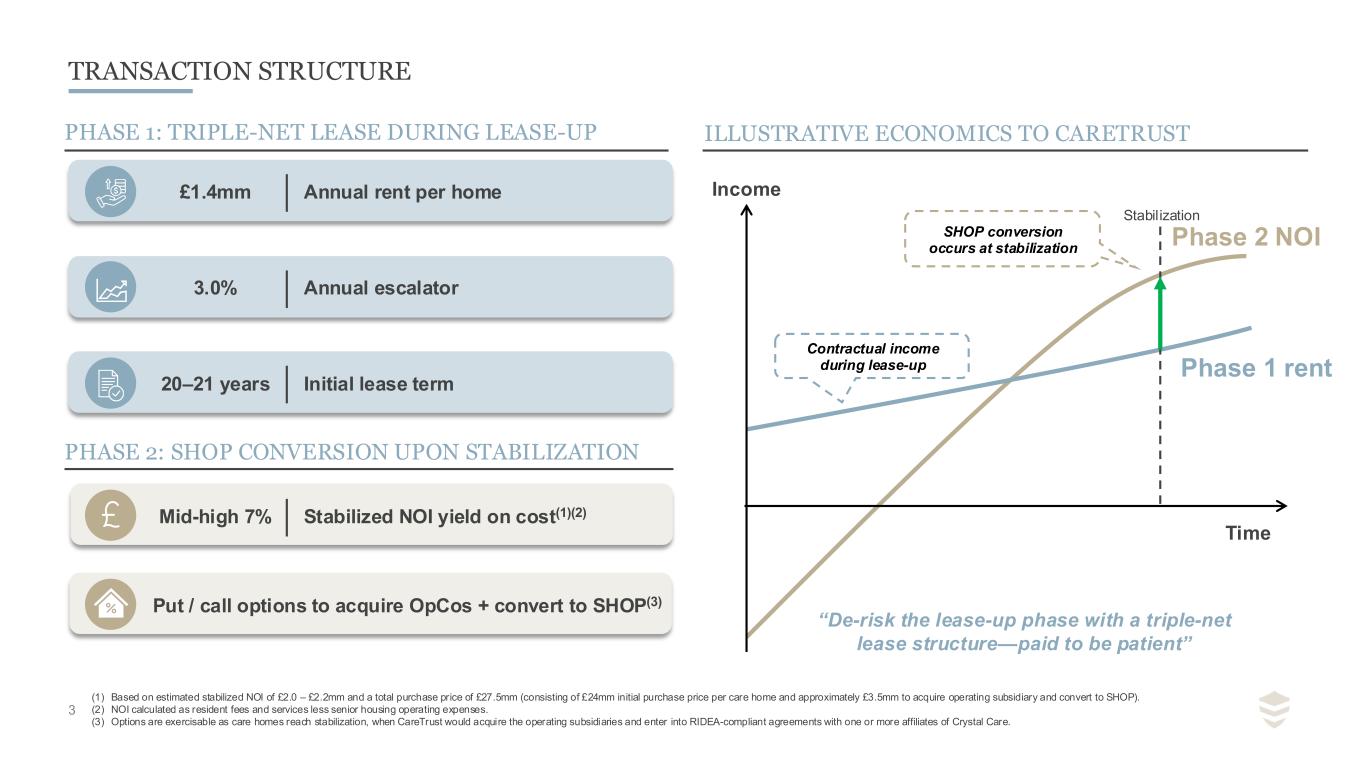
3 PHASE 1: TRIPLE-NET LEASE Source: Company information 1 Based on estimated stabilized NOI of £2.15mm and a total purchase price of £27.5mm PHASE 2: SHOP CONVERSION Annual rent per home£1.4mm Annual escalator3.0% Put / call options to acquire OpCos + convert to SHOP(3) Stabilized NOI yield on cost(1)(2)Mid-high 7% TRANSACTION STRUCTURE Initial lease term20–21 years PHASE 1: TRIPLE-NET LEASE DURING LEASE-UP PHASE 2: SHOP CONVERSION UPON STABILIZATION (1) Based on estimated stabilized NOI of £2.0 – £2.2mm and a total purchase price of £27.5mm (consisting of £24mm initial purchase price per care home and approximately £3.5mm to acquire operating subsidiary and convert to SHOP). (2) NOI calculated as resident fees and services less senior housing operating expenses. (3) Options are exercisable as care homes reach stabilization, when CareTrust would acquire the operating subsidiaries and enter into RIDEA-compliant agreements with one or more affiliates of Crystal Care. ILLUSTRATIVE ECONOMICS TO CARETRUST Income Time Phase 2 NOI Phase 1 rent SHOP conversion occurs at stabilization Stabilization “De-risk the lease-up phase with a triple-net lease structure—paid to be patient” Contractual income during lease-up
4 WHY THE STRATEGICALLY IMPORTANT LNT RELATIONSHIP? 1 Source: Knight Frank Healthcare Development Opportunities 2026 report Proven, prolific care home developer with a repeatable execution model ⚫ Vertically integrated capabilities from site selection to day-to-day management, optimized over 30 years 3 2 4 Scaled operator with embedded infrastructure to drive growth ⚫ National footprint and standardized, purpose-built assets enable consistent care delivery and efficient portfolio expansion Favorable UK senior housing dynamics ⚫ 80+ population projected to double by 2050 combined with structural supply constraints create a durable backdrop for occupancy and rate growth New, purpose-built portfolio to serve growing demand ⚫ Assets located in undersupplied markets with attractive demographics
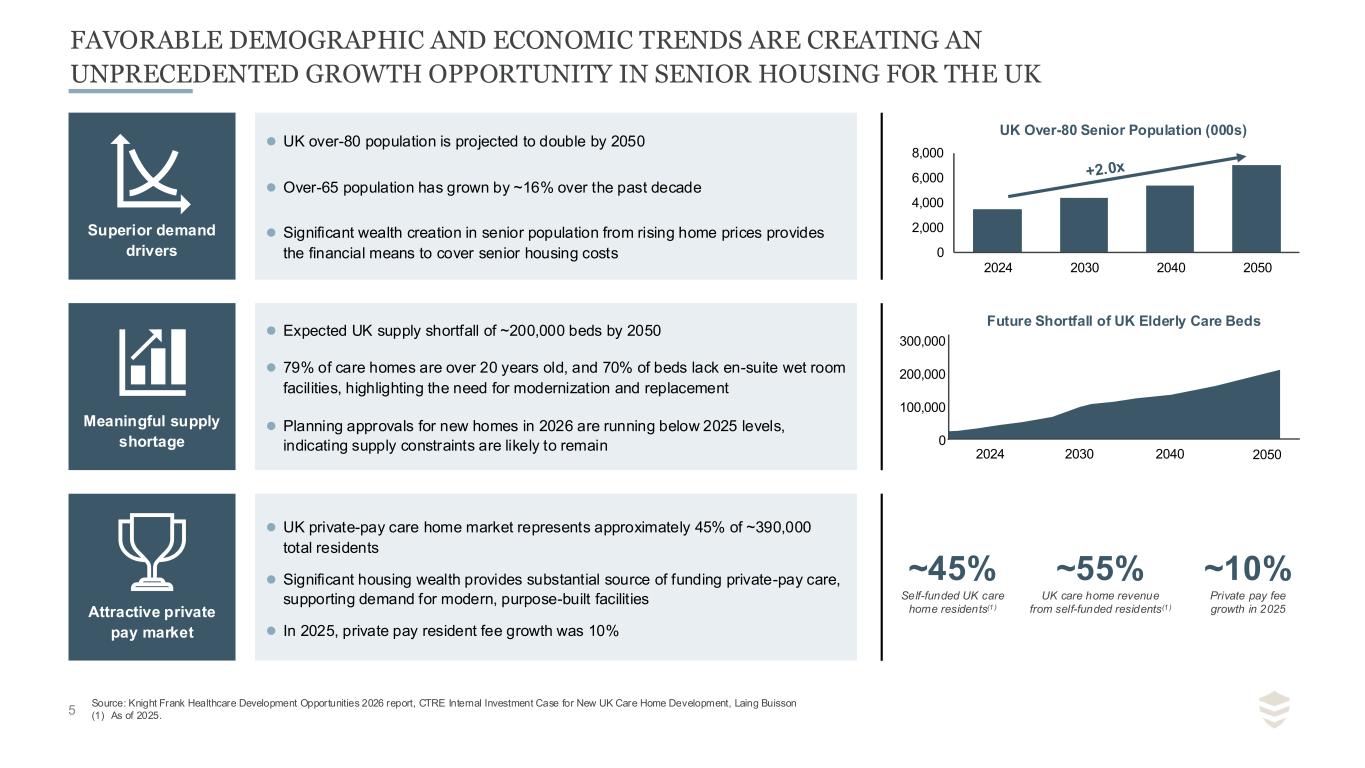
5 FAVORABLE DEMOGRAPHIC AND ECONOMIC TRENDS ARE CREATING AN UNPRECEDENTED GROWTH OPPORTUNITY IN SENIOR HOUSING FOR THE UK Source: Knight Frank Healthcare Development Opportunities 2026 report, CTRE Internal Investment Case for New UK Care Home Development, Laing Buisson (1) As of 2025. Superior demand drivers Meaningful supply shortage Attractive private pay market ⚫ UK over-80 population is projected to double by 2050 ⚫ Over-65 population has grown by ~16% over the past decade ⚫ Significant wealth creation in senior population from rising home prices provides the financial means to cover senior housing costs ⚫ Expected UK supply shortfall of ~200,000 beds by 2050 ⚫ 79% of care homes are over 20 years old, and 70% of beds lack en-suite wet room facilities, highlighting the need for modernization and replacement ⚫ Planning approvals for new homes in 2026 are running below 2025 levels, indicating supply constraints are likely to remain ⚫ UK private-pay care home market represents approximately 45% of ~390,000 total residents ⚫ Significant housing wealth provides substantial source of funding private-pay care, supporting demand for modern, purpose-built facilities ⚫ In 2025, private pay resident fee growth was 10% 0 2,000 4,000 6,000 8,000 2024 2030 2040 2050 UK Over-80 Senior Population (000s) ~45% Self-funded UK care home residents(1 ) ~55% UK care home revenue from self-funded residents(1 ) ~10% Private pay fee growth in 2025 Future Shortfall of UK Elderly Care Beds 0 100,000 200,000 300,000 2024 2030 2040 2050
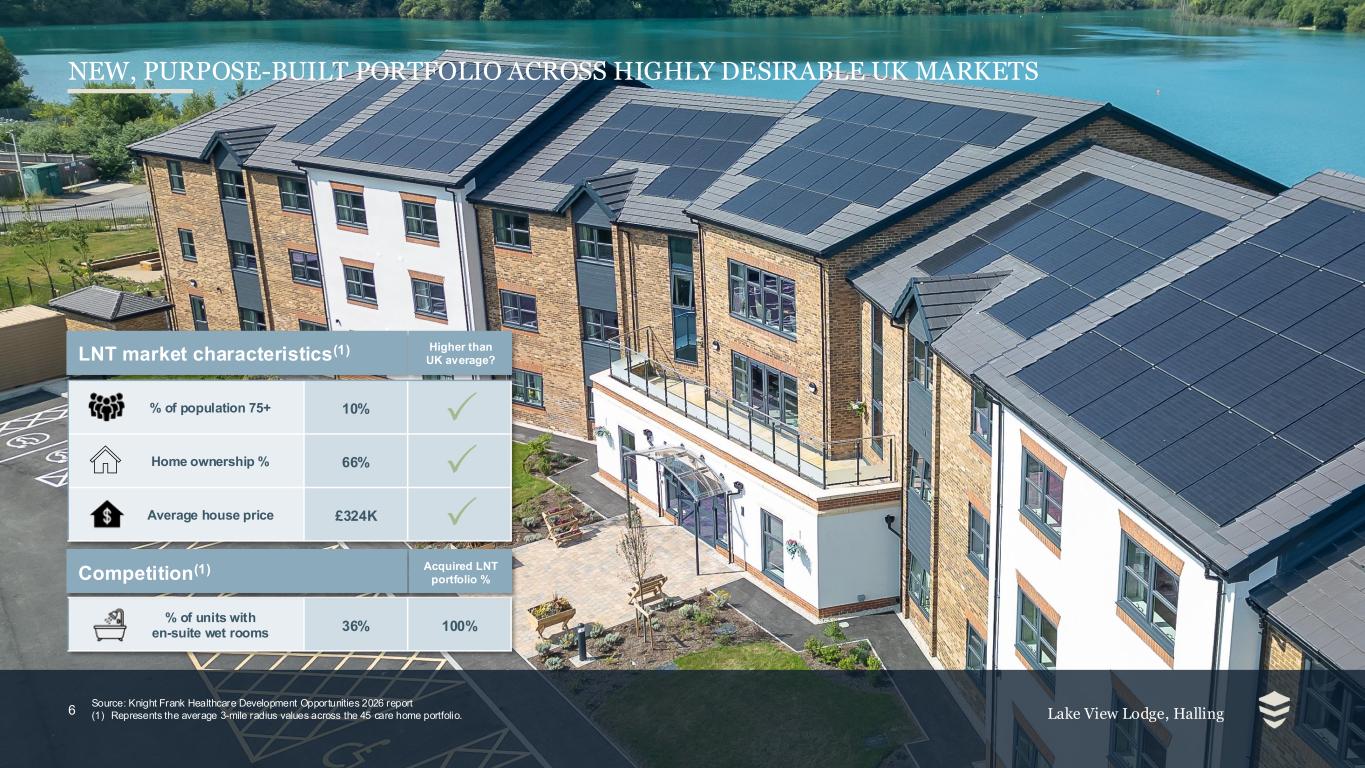
6 NEW, PURPOSE-BUILT PORTFOLIO ACROSS HIGHLY DESIRABLE UK MARKETS LNT market characteristics(1) % of population 75+ 10% Home ownership % 66% Average house price £324K Source: Knight Frank Healthcare Development Opportunities 2026 report (1) Represents the average 3-mile radius values across the 45 care home portfolio. Lake View Lodge, Halling Higher than UK average? . . . % of units with en-suite wet rooms 36% 100% Competition(1) Acquired LNT portfolio %
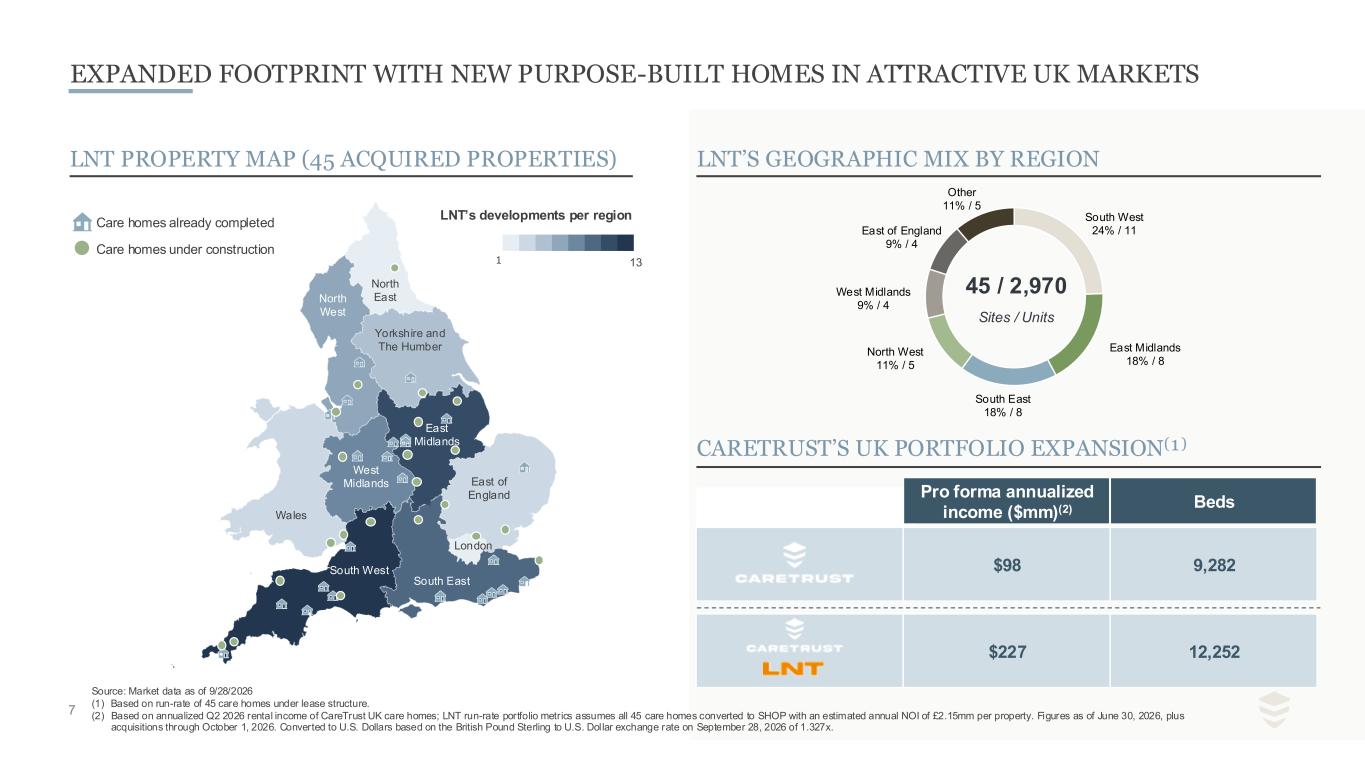
7 $227 12,252 LNT’S GEOGRAPHIC MIX BY REGION $98 9,282 Beds EXPANDED FOOTPRINT WITH NEW PURPOSE-BUILT HOMES IN ATTRACTIVE UK MARKETS South West 24% / 11 East Midlands 18% / 8 South East 18% / 8 North West 11% / 5 West Midlands 9% / 4 East of England 9% / 4 Other 11% / 5 45 / 2,970 Sites / Units Source: Market data as of 9/28/2026 (1) Based on run-rate of 45 care homes under lease structure. (2) Based on annualized Q2 2026 rental income of CareTrust UK care homes; LNT run-rate portfolio metrics assumes all 45 care homes converted to SHOP with an estimated annual NOI of £2.15mm per property. Figures as of June 30, 2026, plus acquisitions through October 1, 2026. Converted to U.S. Dollars based on the British Pound Sterling to U.S. Dollar exchange rate on September 28, 2026 of 1.327x. CARETRUST’S UK PORTFOLIO EXPANSION(¹) Pro forma annualized income ($mm)(2) LNT PROPERTY MAP (45 ACQUIRED PROPERTIES) Care homes already completed Care homes under construction LNT’s developments per region 1 13 North West East Midlands North East Yorkshire and The Humber West Midlands East of England Wales London South East South West
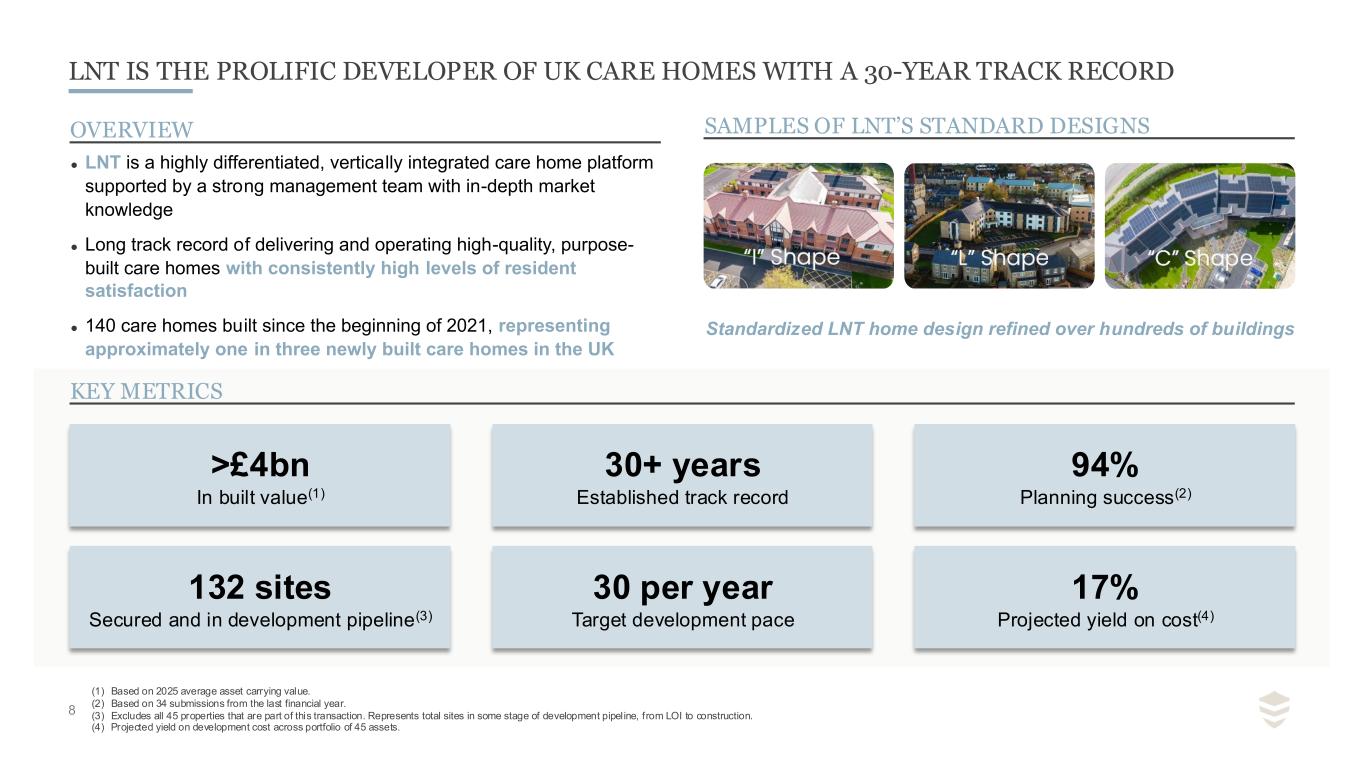
8 LNT IS THE PROLIFIC DEVELOPER OF UK CARE HOMES WITH A 30-YEAR TRACK RECORD (1) Based on 2025 average asset carrying value. (2) Based on 34 submissions from the last financial year. (3) Excludes all 45 properties that are part of this transaction. Represents total sites in some stage of development pipeline, from LOI to construction. (4) Projected yield on development cost across portfolio of 45 assets. OVERVIEW KEY METRICS SAMPLES OF LNT’S STANDARD DESIGNS ⚫ LNT is a highly differentiated, vertically integrated care home platform supported by a strong management team with in-depth market knowledge ⚫ Long track record of delivering and operating high-quality, purpose- built care homes with consistently high levels of resident satisfaction ⚫ 140 care homes built since the beginning of 2021, representing approximately one in three newly built care homes in the UK 94% Planning success(2) 30 per year Target development pace >£4bn In built value(1) 17% Projected yield on cost(4) 30+ years Established track record 132 sites Secured and in development pipeline(3) Standardized LNT home design refined over hundreds of buildings
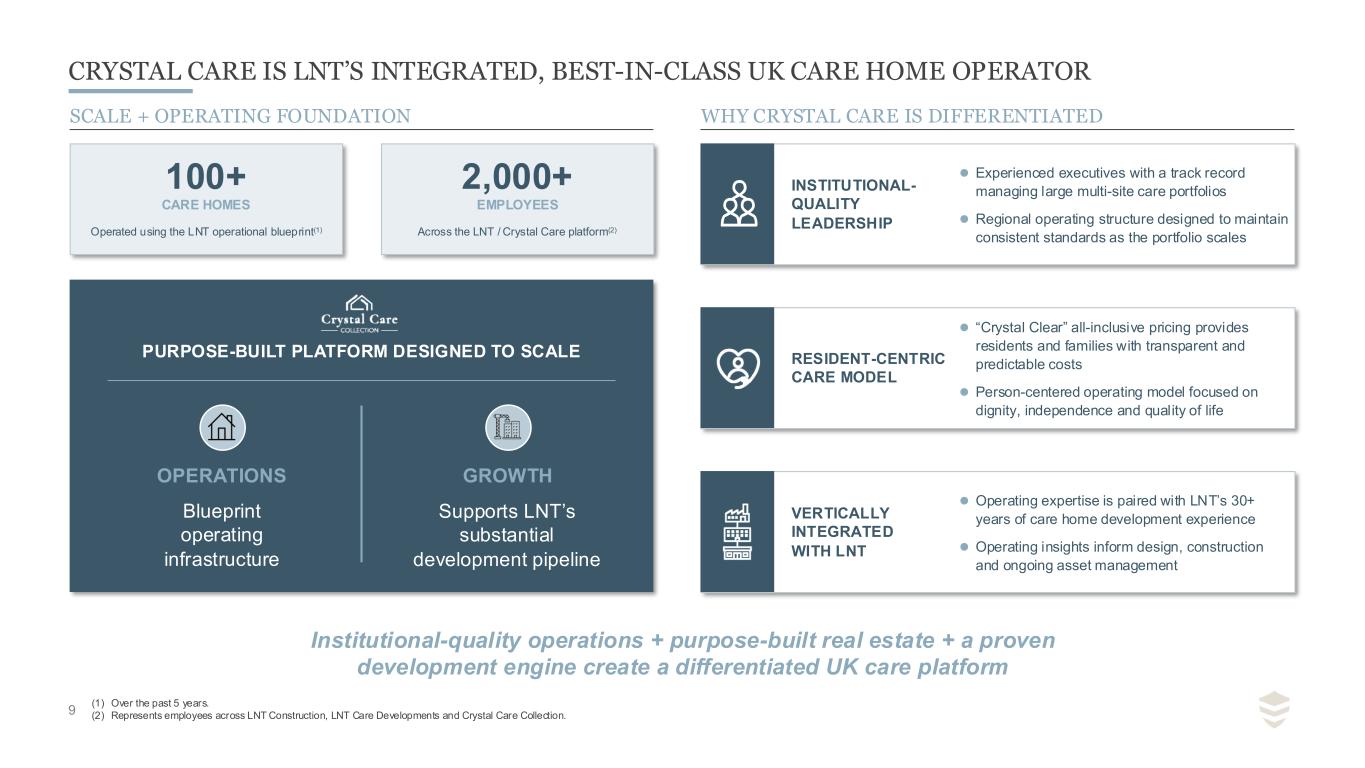
9 CRYSTAL CARE IS LNT’S INTEGRATED, BEST-IN-CLASS UK CARE HOME OPERATOR (1) Over the past 5 years. (2) Represents employees across LNT Construction, LNT Care Developments and Crystal Care Collection. SCALE + OPERATING FOUNDATION WHY CRYSTAL CARE IS DIFFERENTIATED 100+ CARE HOMES Operated using the LNT operational blueprint(1) 2,000+ EMPLOYEES Across the LNT / Crystal Care platform(2) PURPOSE-BUILT PLATFORM DESIGNED TO SCALE OPERATIONS Blueprint operating infrastructure GROWTH Supports LNT’s substantial development pipeline INSTITUTIONAL- QUALITY LEADERSHIP ⚫ Experienced executives with a track record managing large multi-site care portfolios ⚫ Regional operating structure designed to maintain consistent standards as the portfolio scales RESIDENT-CENTRIC CARE MODEL ⚫ “Crystal Clear” all-inclusive pricing provides residents and families with transparent and predictable costs ⚫ Person-centered operating model focused on dignity, independence and quality of life VERTICALLY INTEGRATED WITH LNT ⚫ Operating expertise is paired with LNT’s 30+ years of care home development experience ⚫ Operating insights inform design, construction and ongoing asset management Institutional-quality operations + purpose-built real estate + a proven development engine create a differentiated UK care platform
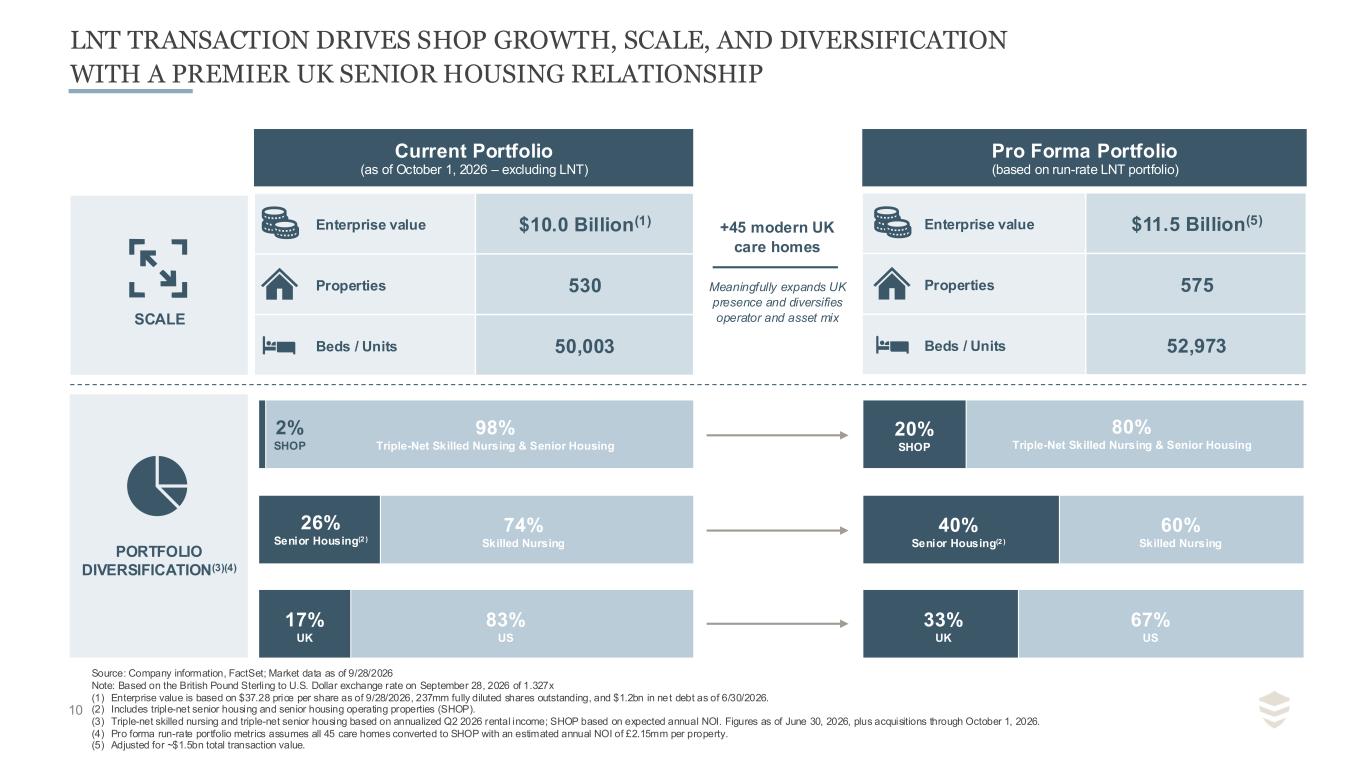
10 Source: Company information, FactSet; Market data as of 9/28/2026 Note: Based on the British Pound Sterling to U.S. Dollar exchange rate on September 28, 2026 of 1.327x (1) Enterprise value is based on $37.28 price per share as of 9/28/2026, 237mm fully diluted shares outstanding, and $1.2bn in net debt as of 6/30/2026. (2) Includes triple-net senior housing and senior housing operating properties (SHOP). (3) Triple-net skilled nursing and triple-net senior housing based on annualized Q2 2026 rental income; SHOP based on expected annual NOI. Figures as of June 30, 2026, plus acquisitions through October 1, 2026. (4) Pro forma run-rate portfolio metrics assumes all 45 care homes converted to SHOP with an estimated annual NOI of £2.15mm per property. (5) Adjusted for ~$1.5bn total transaction value. LNT TRANSACTION DRIVES SHOP GROWTH, SCALE, AND DIVERSIFICATION WITH A PREMIER UK SENIOR HOUSING RELATIONSHIP PORTFOLIO DIVERSIFICATION(3)(4) SCALE Current Portfolio (as of October 1, 2026 – excluding LNT) Pro Forma Portfolio (based on run-rate LNT portfolio) Enterprise value $10.0 Billion(1) Properties 530 Beds / Units 50,003 Enterprise value $11.5 Billion(5) Properties 575 Beds / Units 52,973 +45 modern UK care homes Meaningfully expands UK presence and diversifies operator and asset mix 83% US 26% Senior Housing(2 ) 74% Skilled Nursing 40% Senior Housing(2 ) 60% Skilled Nursing 17% UK 67% US 33% UK 20% SHOP 80% Triple-Net Skilled Nursing & Senior Housing 2% SHOP 98% Triple-Net Skilled Nursing & Senior Housing
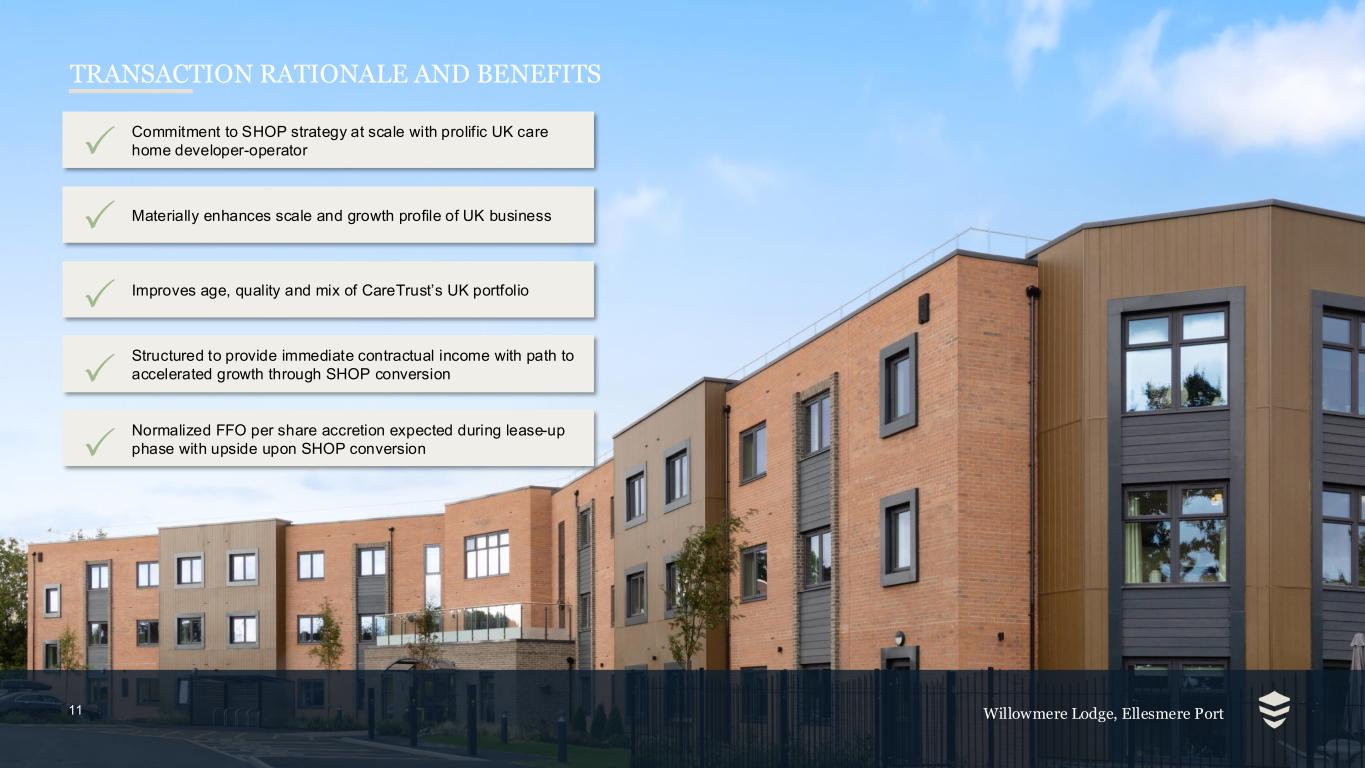
11 TRANSACTION RATIONALE AND BENEFITS Materially enhances scale and growth profile of UK business Normalized FFO per share accretion expected during lease-up phase with upside upon SHOP conversion Commitment to SHOP strategy at scale with prolific UK care home developer-operator Improves age, quality and mix of CareTrust’s UK portfolio Structured to provide immediate contractual income with path to accelerated growth through SHOP conversion . . . . . Willowmere Lodge, Ellesmere Port
12 The past, present, and future of the CareTrust-LNT SHOP pipeline C A R E D E V E L O P M E N T S For more color on the CareTrust and LNT relationship, visit the CareTrust YouTube Channel
13 DISCLAIMER This investor presentation contains forward-looking statements within the meaning of the Private Securities Lit igation Reform Act of 1995. Forward-looking statements include all statements that are not historical statements of fact and statements regarding our intent, belief or expectations, including, but not limited to, statements regarding the following: access to capital; investment activity; growth prospects; and operating and f inancial performance. Forward-looking statements also include, but are not limited to, statements regarding the expected timing and completion of the acquisition of the homes currently under development, the anticipated exercise of put and call rights with respect to the operating companies and the timing thereof, the anticipated conversion of the homes to a RIDEA structure, the Company’s expectations re garding stabilization, rental revenue, net operating income yields and accretion to normalized funds from operations, projected yields and returns on the LNT Care Developments (“LNT”) transaction, expected stabilization timelines and SHOP conversion economics, anticipated benefits of our strategic relationship with LNT, and the Company’s sources of financing. Words such as “anticipate,” “believe,” “could,” "expect,” “estimate,” “intend,” “may,” “plan,” “seek,” “should,” “will,” “wou ld,” and similar expressions, or the negative of these terms, are intended to identify such forward-looking statements, though not all forward-looking statements contain these identifying words. Our forward-looking statements are based on our current expectations and beliefs, and are subject to a number of risks and uncertainties that could lead to actual results differing materially from those projected, forecasted or expected. Although we believe that the assumptions underlying these forward-looking statements are reasonable, they are not guarantees and we can give no assurance that our expectations will be attained. Factors which could have a material adverse effect on the Company’s operations and future prospects or which could cause actual results to differ materially from our expectations include, but are not limited to: (i) the ability of our tenants, managers, and borrowers to successfully operate our properties and to meet and/or perform their obligations under the agreements we have entered into with them, including without limitation, their respective obligations to indemnify, defend and hold us harmless from and against various claims, litigation and liabilities; (ii) the impact of unstable market and economic conditions; (iii) the impact of healthcare reform legislation, including reimbursement rates and potential minimum staff ing level requirements, on the operating results and financial conditions of our tenants, managers, and borrowers; (iv) the consequences of bankruptcy, insolvency or f inancial deterioration of our tenants, managers and borrowers; (v) the ability and willingness of our tenants, managers and borrowers to renew their agreements with us, and our ability to reposition our properties on the same or better terms in the event of nonrenewal or in the event we replace an existing tenant or manager; (vi) the risk that we may have to incur impairment charges related to any asset sales if we are unable to sell such assets at the prices we expect; (vii) the impact of public health crises; (viii) the availability of and the ability to identify (a) tenants and managers who meet our credit and operating standards, and (b) suitable acquisition opportunit ies and the ability to acquire and lease the respective properties to such tenants and managers on favorable terms; (ix) the intended benefits of our acquisition of Care REIT plc (“Care REIT”) and of the transact ion with LNT may not be realized, and the additional risks we will be subject to from our investment in Care REIT, the LNT transaction and any other international investments; (x) the additional operational and legal risks associated with our properties managed in a RIDEA structure; (xi) the impact of the unfavorable resolution of litigation or disputes and rising liability and insurance costs as a result thereof or other market factors; (xii) the ability to retain our key management personnel; (xiii) the ability to maintain our status as a real estate investment trust (“REIT”); (xiv) changes in the U.S. and U.K. tax law and other state, federal or local laws, whether or not specif ic to REITs; (xv) the ability to generate sufficient cash flows to service our outstanding indebtedness; (xvi) access to debt and equity capital markets; (xvii) fluctuating interest and currency rates, including fluctuations in the exchange rate between the pound sterling and the U.S. dollar; (xviii) risks and challenges related to our use of, or inability to use, artificial intelligence; (xix) the risk that the homes currently under development are not completed on the expected timeline or at all, and that practical completion, regulatory registration and other closing conditions are delayed or not satisfied; (xx) the performance of the tenant operating companies during lease-up and the risk that stabilization and the anticipated net operating income yields and accretion are not achieved; (xxi) the risk that the put and call rights with respect to the operating companies are not exercised, or that the anticipated conversion of the homes to a RIDEA structure does not occur on the expected timeline or at all; (xxii) changes in the United Kingdom regulatory, reimbursement, labor and tax environment; and (xxiii) any additional factors included under Item 1A “Risk Factors” in our Annual Report on Form 10-K for the year ended December 31, 2025 and our Quarterly Report on Form 10-Q for the quarter ended June 30, 2026, as such risk factors may be amended, supplemented or superseded from time to time by other reports we file with the Securit ies and Exchange Commission. This investor presentation includes references to non-GAAP financial measures. We have not reconciled such non-GAAP financial measures guidance to the most directly comparable forward-looking GAAP measures because the timing and amount of material adjustments that impact these measures are not in our control and/or cannot be allocated or quantified wit h certainty or is dependent on the t iming and occurrence of certain actions and, accordingly, cannot be reasonably predicted or estimated without unreasonable efforts. This investor presentation also includes certain information regarding LNT and its affiliated operator, Crystal Care Collection, including development track record, pipeline, operating metrics, and projected yields and returns. Such information has been provided by LNT and has not been independently verified by us, but we have no reason to believe it is inaccurate in any material respect. This investor presentation also contains data and statistics from third-party sources. We have not independently verified such third-party data and make no representation as to its accuracy or completeness. This information in this investor presentation is provided as of the date hereof, unless specifically stated otherwise. We expressly disclaim any obligation to update or revise any information in this investor presentation (including forward-looking statements), whether to reflect any change in our expectations, any change in events, conditions or circumstances, or otherwise. As used in this investor presentation, unless the context requires otherwise, references to “CTRE,” “CareTrust,” “CareTrust REIT” or the “Company” refer to CareTrust REIT, Inc. and its consolidated subsidiaries. References to “LNT” refer to LNT Care Developments and its affiliates, including Crystal Care Collection. GAAP refers to generally accepted accounting principles in the United States of America.