Please wait
N-CSRSThe average market value per unit is calculated by taking the average of the closing price (or $25 principal value for unlisted securities) for each of (a) a share of the Preferred Shares (NYSE: ECCA, ECCB, ECCC, ECCF, ECC PRD; Unlisted: ECC AA, ECC AB) and (b) for each $25 principal amount of the Unsecured Notes (NYSE: ECCU, ECCV, ECCW, ECCX, ECCY, ECCZ) for each day during the years for which each applicable security was outstanding. A $25 market value was assumed for unlisted securities. The involuntary liquidating preference per unit is the amount to which a share of Preferred Shares would be entitled in preference to any security junior to it upon our involuntary liquidation. The asset coverage per unit figure is the ratio of the Company’s total consolidated assets, less all liabilities and indebtedness not represented by senior securities, to the aggregate dollar amount of outstanding applicable senior securities, as calculated separately for each of the Preferred Shares and the Unsecured Notes in accordance with section 18(h) of the 1940 Act. With respect to the Preferred Shares, the asset coverage per unit figure is expressed in terms of dollar amounts per share of outstanding preferred shares (based on a per share liquidation preference of $25.) With respect to the Unsecured Notes, the asset coverage per unit figure is expressed in terms of dollar amounts per $1,000 principal amount of such notes. 0001604174false 0001604174ck0001604174:CommonStocksMember 2026-01-01 2026-06-30 0001604174 2026-01-01 2026-06-30 0001604174 2025-12-31 0001604174 2026-06-30 0001604174 2026-07-31 2026-07-31 0001604174ck0001604174:PreferredStocksMember 2026-01-01 2026-06-30 0001604174ck0001604174:PreferredStocksMember 2026-06-30 0001604174ck0001604174:UnsecuredNotesMember 2026-01-01 2026-06-30 0001604174ck0001604174:UnsecuredNotesMember 2026-06-30 0001604174ck0001604174:PreferredStocksMember 2025-01-01 2025-12-31 0001604174ck0001604174:PreferredStocksMember 2025-12-31 0001604174ck0001604174:UnsecuredNotesMember 2025-01-01 2025-12-31 0001604174ck0001604174:UnsecuredNotesMember 2025-12-31 0001604174ck0001604174:PreferredStocksMember 2024-01-01 2024-12-31 0001604174ck0001604174:PreferredStocksMember 2024-12-31 0001604174ck0001604174:UnsecuredNotesMember 2024-01-01 2024-12-31 0001604174ck0001604174:UnsecuredNotesMember 2024-12-31 0001604174ck0001604174:PreferredStocksMember 2023-01-01 2023-12-31 0001604174ck0001604174:PreferredStocksMember 2023-12-31 0001604174ck0001604174:UnsecuredNotesMember 2023-01-01 2023-12-31 0001604174ck0001604174:UnsecuredNotesMember 2023-12-31 0001604174ck0001604174:PreferredStocksMember 2022-01-01 2022-12-31 0001604174ck0001604174:PreferredStocksMember 2022-12-31 0001604174ck0001604174:UnsecuredNotesMember 2022-01-01 2022-12-31 0001604174ck0001604174:UnsecuredNotesMember 2022-12-31 0001604174ck0001604174:PreferredStocksMember 2021-01-01 2021-12-31 0001604174ck0001604174:PreferredStocksMember 2021-12-31 0001604174ck0001604174:UnsecuredNotesMember 2021-01-01 2021-12-31 0001604174ck0001604174:UnsecuredNotesMember 2021-12-31 0001604174ck0001604174:PreferredStocksMember 2020-01-01 2020-12-31 0001604174ck0001604174:PreferredStocksMember 2020-12-31 0001604174ck0001604174:UnsecuredNotesMember 2020-01-01 2020-12-31 0001604174ck0001604174:UnsecuredNotesMember 2020-12-31 0001604174ck0001604174:PreferredStocksMember 2019-01-01 2019-12-31 0001604174ck0001604174:PreferredStocksMember 2019-12-31 0001604174ck0001604174:UnsecuredNotesMember 2019-01-01 2019-12-31 0001604174ck0001604174:UnsecuredNotesMember 2019-12-31 0001604174ck0001604174:PreferredStocksMember 2018-01-01 2018-12-31 0001604174ck0001604174:PreferredStocksMember 2018-12-31 0001604174ck0001604174:UnsecuredNotesMember 2018-01-01 2018-12-31 0001604174ck0001604174:UnsecuredNotesMember 2018-12-31 0001604174ck0001604174:PreferredStocksMember 2017-01-01 2017-12-31 0001604174ck0001604174:PreferredStocksMember 2017-12-31 0001604174ck0001604174:UnsecuredNotesMember 2017-01-01 2017-12-31 0001604174ck0001604174:UnsecuredNotesMember 2017-12-31 0001604174 2021-12-31 0001604174 2022-12-31 0001604174 2023-12-31 0001604174 2024-12-31 0001604174 2022-01-01 2022-12-31 0001604174 2023-01-01 2023-12-31 0001604174 2024-01-01 2024-12-31 0001604174 2025-01-01 2025-12-31 0001604174 2016-12-31 0001604174 2017-12-31 0001604174 2018-12-31 0001604174 2019-12-31 0001604174 2017-01-01 2017-12-31 0001604174 2018-01-01 2018-12-31 0001604174 2019-01-01 2019-12-31 0001604174 2020-01-01 2020-12-31 0001604174 2021-01-01 2021-12-31 0001604174 2020-12-31 0001604174ck0001604174:SeriesCTermPreferredStockMember 2026-01-01 2026-06-30 0001604174ck0001604174:SeriesDPreferredStocksMember 2026-01-01 2026-06-30 0001604174ck0001604174:SeriesAaConvertiblePerpetualPreferredStockMember 2026-01-01 2026-06-30 0001604174ck0001604174:SeriesAbConvertiblePerpetualPreferredStockMember 2026-01-01 2026-06-30 0001604174ck0001604174:NotesDue2029At5375PercentMember 2026-01-01 2026-06-30 0001604174ck0001604174:NotesDue2030At775PercentMember 2026-01-01 2026-06-30 0001604174ck0001604174:InvestingInCollateralizedLoanObligationsAndOtherStructuredDebtSecuritiesRiskMember 2026-01-01 2026-06-30 0001604174ck0001604174:SubordinatedSecuritiesRiskMember 2026-01-01 2026-06-30 0001604174ck0001604174:HighYieldInvestmentRiskMember 2026-01-01 2026-06-30 0001604174ck0001604174:LeverageRiskMember 2026-01-01 2026-06-30 0001604174ck0001604174:CreditsRiskMember 2026-01-01 2026-06-30 0001604174ck0001604174:RisksOfDefaultOnUnderlyingAssetsMember 2026-01-01 2026-06-30 0001604174ck0001604174:KeyPersonnelRiskMember 2026-01-01 2026-06-30 0001604174ck0001604174:ConflictsOfInterestRiskMember 2026-01-01 2026-06-30 0001604174ck0001604174:PrepaymentsRiskMember 2026-01-01 2026-06-30 0001604174ck0001604174:LiquidityRiskMember 2026-01-01 2026-06-30 0001604174ck0001604174:IncentiveFeeRiskMember 2026-01-01 2026-06-30 0001604174ck0001604174:FairValuationOfPortfolioInvestmentsRiskMember 2026-01-01 2026-06-30 0001604174ck0001604174:LimitedInvestmentOpportunitiesRiskMember 2026-01-01 2026-06-30 0001604174ck0001604174:NonDiversificationRiskMember 2026-01-01 2026-06-30 0001604174ck0001604174:MarketRiskMember 2026-01-01 2026-06-30 0001604174ck0001604174:LoanAccumulationFacilitiesRiskMember 2026-01-01 2026-06-30 0001604174ck0001604174:SyntheticInvestmentsRiskMember 2026-01-01 2026-06-30 0001604174ck0001604174:RegulatoryCapitalReliefInvestmentsRiskMember 2026-01-01 2026-06-30 0001604174ck0001604174:InfrastructureSectorRiskMember 2026-01-01 2026-06-30 0001604174ck0001604174:AssetBasedFinanceInvestmentsRiskMember 2026-01-01 2026-06-30 0001604174ck0001604174:RealEstateInvestmentRelatedRisksMember 2026-01-01 2026-06-30 0001604174ck0001604174:CurrencyRiskMember 2026-01-01 2026-06-30 0001604174ck0001604174:HedgingRiskMember 2026-01-01 2026-06-30 0001604174ck0001604174:ReinvestmentRiskMember 2026-01-01 2026-06-30 0001604174ck0001604174:InterestRatesRiskMember 2026-01-01 2026-06-30 0001604174ck0001604174:RefinancingRiskMember 2026-01-01 2026-06-30 0001604174ck0001604174:RisksRelatingToConvertiblePerpetualPreferredSharesConversionFeatureMember 2026-01-01 2026-06-30 0001604174ck0001604174:TaxRiskMember 2026-01-01 2026-06-30 0001604174ck0001604174:DerivativesRiskMember 2026-01-01 2026-06-30 0001604174ck0001604174:CounterpartyRiskMember 2026-01-01 2026-06-30 0001604174ck0001604174:PriceRiskMember 2026-01-01 2026-06-30 0001604174ck0001604174:NonUnitedStatesInvestingRiskMember 2026-01-01 2026-06-30 0001604174ck0001604174:GlobalRisksMember 2026-01-01 2026-06-30 0001604174ck0001604174:BankingRiskMember 2026-01-01 2026-06-30 xbrli:shares iso4217:USD iso4217:USDxbrli:shares


UNITED STATES

SECURITIES AND EXCHANGE COMMISSION

Washington, D.C. 20549


FORM N-CSR


CERTIFIED SHAREHOLDER REPORT OF REGISTERED

MANAGEMENT INVESTMENT COMPANIES


Investment Company Act File Number: 811-22974


Eagle Point Credit Company

(Exact name of registrant as specified in charter)


600 Steamboat Road, Suite 202

Greenwich, CT 06830

(Address of principal executive offices) (Zip code)


Thomas P. Majewski

c/o Eagle Point Credit Company

600 Steamboat Road, Suite 202

Greenwich, CT 06830

(Name and address of agent for service)


Copies to


Thomas J. Friedmann

Philip Hinkle
Dechert LLP
One International Place, 40th Floor

100 Oliver Street

Boston, MA 02110
(617) 728-7120


Registrant’s telephone number, including area code: (203) 340-8500


Date of fiscal year end: December 31


Date of reporting period: June 30, 2026


Item 1. Report to Stockholders


The Semiannual Report to stockholders of the registrant for the six months ending June 30, 2026, is filed herewith.


​
cv_ofc-4c.jpg

​​
​ FIRST HALF 2026 SHAREHOLDER LETTER AND SEMIANNUAL REPORT   |   Eagle Point Credit Company ​
Eagle Point Credit Company
Semiannual Report — June 30, 2026
Table of Contents​
​ ​ ​ ​ ​ 2 ​ ​
​ ​ ​ ​ ​ 9 ​ ​
​ ​ ​ ​ ​ 10 ​ ​
​ ​ ​ ​ ​ 13 ​ ​
​ ​ ​ ​ ​ 14 ​ ​
​ ​ ​ ​ ​ 69 ​ ​
​ ​ ​ ​ ​ 71 ​ ​
 
​   ​ ​
1
​

​​
​ FIRST HALF 2026 SHAREHOLDER LETTER AND SEMIANNUAL REPORT   |   Eagle Point Credit Company ​
Letter to Shareholders and Management Discussion of Company Performance
Dear Fellow Shareholders:
We are pleased to provide you with the enclosed report of Eagle Point Credit Company (“we,” “us,” “our” or the “Company”) for the six months ended June 30, 2026.
The Company is a closed-end management investment company registered under the Investment Company Act of 1940, as amended, and is advised by Eagle Point Credit Management LLC (the “Adviser”). The Company’s primary investment objective is to generate high current income, with a secondary objective to generate capital appreciation. We seek to achieve these objectives by investing primarily in the equity and junior debt tranches of collateralized loan obligations (“CLOs”). We may also invest in other securities or instruments that are consistent with our investment objectives, including portfolio debt securities, infrastructure credit, regulatory capital relief transactions, asset-backed securities and other credit instruments.
First Half 2026 Results
The first half of 2026 was characterized by significant market volatility in the first quarter, followed by a meaningful recovery in the second quarter. Uncertainty surrounding the potential impact of artificial intelligence on software borrowers, together with geopolitical developments, weighed on leveraged loan prices and CLO equity valuations during the first quarter. As market sentiment improved during the second quarter, loan prices and CLO equity valuations recovered meaningfully, while underlying credit fundamentals remained resilient throughout the period.
Throughout the first half of the year, we remained disciplined in our capital allocation, continuing to execute CLO resets and refinancings, rotating capital into higher-conviction opportunities and expanding our exposure to differentiated private credit investments by leveraging our Adviser’s specialized investment expertise across the broader Eagle Point platform. We believe these actions strengthened our investment portfolio, enhanced its long-term earnings potential and positioned the Company to capitalize on attractive opportunities across the broader credit markets and create long-term value for our shareholders.
For the six months ended June 30, 2026, the Company recorded a decrease in net assets resulting from operations of $78 million, or $0.59 per weighted average common share, primarily driven by unrealized losses resulting from mark-to-market changes in fair value of our investment portfolio.1 This represents a GAAP return on common equity of -10.0%.2 The Company’s net asset value (“NAV”) per common share decreased from $5.70 as of December 31, 2025, to $4.51 as of June 30, 2026. During the same period, we paid an aggregate of $0.60 per share in distributions to our common shareholders.3 We believe our current monthly distribution of $0.06 per common share is appropriately aligned with the Company’s earnings and reflects our commitment to maintaining a sustainable distribution over time.
Among the highlights for the six months ended June 30, 2026, we:
□
Actively deployed $211 million of gross capital into new investments. Of this amount, $35 million was invested in CLO equity securities, which had a weighted average effective yield (“WAEY”) of 22.2%, and $149 million was invested in other credit assets with a WAEY of 23.4%, in each case measured at the time of purchase.4 The remaining capital was deployed across CLO debt, loan accumulation facilities and other credit investments.
​
□
Received recurring cash flows from our investment portfolio of $124 million, or $0.94 per weighted average common share, exceeding the Company’s common share distributions and total expenses incurred by the Company during the period.
​
□
Continued to reposition the portfolio by rotating capital away from certain underperforming CLO collateral managers and selectively increasing exposure to asset classes beyond CLO equity, including infrastructure credit, portfolio debt securities, regulatory capital relief transactions and other opportunistic private credit investments, which complement our core CLO equity portfolio. As of June 30, 2026, non-CLO investments represented 38% of our total investment portfolio.
​
​
Past Performance is not indicative of, or a guarantee of, future performance.
See end notes on page 7.
​ ​
2
​

​
​ FIRST HALF 2026 SHAREHOLDER LETTER AND SEMIANNUAL REPORT   |   Eagle Point Credit Company ​
□
Completed 12 resets and 10 refinancings of CLOs in our portfolio. Each reset created a new 5-year reinvestment period and, when combined with refinancings, reduced CLO debt cost by an average of 28 bps for those CLOs. As majority CLO equity investors, our ability to direct resets and refinancings helped to mitigate some of the headwinds that CLO equity faced earlier in the year.
​
□
Successfully extended the weighted average remaining reinvestment period (“WARRP”) of our CLO equity portfolio to 3.4 years as of June 30, 2026 (compared to 3.3 years as of June 30, 2025), despite the passage of one year, through our proactive investing and reset activity. As of June 30, 2026, the WARRP of our CLO equity portfolio was 15% longer than the broader market average, providing greater protection against loan price volatility and enabling our CLOs to capitalize on periods of dislocation in the loan market.5
​
□
Expanded our strategic partnership with Muzinich into Europe through the successful pricing of its inaugural European CLO. Given Muzinich’s established presence in the European market, we believe the platform is well-positioned for continued growth, benefiting the Company through both the CLO equity investment returns and the value of the long-term revenue-sharing arrangement.
​
□
Announced a $100 million share repurchase program in response to the discounted trading levels of our common shares.6
​
During the first half of 2026, we actively managed the Company’s capital structure. In January, we completed the full redemption of our 8.00% Series F Term Preferred Stock, followed in May by the redemption of our 6.75% notes due 2031 and 6.6875% notes due 2028. Currently, we have no financing maturing prior to January 2029, and all of our debt and preferred stock is fixed rate. The weighted average maturity of our financing stood at 5.2 years, and the weighted average cost of our financing was 6.8% as of June 30, 2026.7 Our leverage was 47.3% of total assets (less current liabilities), which was above management’s long-term target leverage range of 27.5% to 37.5%, within which the Company expects to operate under normal market conditions. The Company intends to return leverage to within its target range over time.
Portfolio Update
As of June 30, 2026, our investment portfolio comprised 237 investments with an aggregate fair value of $1.0 billion. CLO investments represented 62% of the portfolio based on fair value, reflecting our continued focus on generating current income and attractive risk-adjusted returns through equity tranches of CLOs. The weighted average expected yield of our CLO equity portfolio (excluding called CLOs), based on current market values and expected future cash flows, was 24.2%4 as of June 30, 2026, which we believe represents an attractive potential return. Through our investments in CLO equity securities, we had indirect exposure to 1,838 unique corporate obligors. The largest look-through obligor represented 0.6% of the loans underlying our CLO equity portfolio, and the top 10 largest look-through obligors together represented 4.7% of the underlying loans.
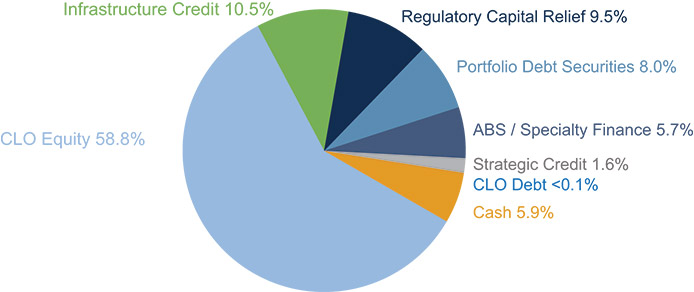
Non-CLO investments included infrastructure credit, portfolio debt securities, regulatory capital relief investments, asset-backed securities and strategic credit investments, which represented 11%, 9%, 10%, 6% and 2% of the portfolio, respectively, at fair value. Collectively, these non-CLO investments represented 38% of our total investment portfolio as of June 30, 2026, and reflect our continued effort to allocate capital to attractive risk-adjusted opportunities across the broader credit markets.
During the first half of 2026, the Company received $124 million of recurring cash distributions from our investment portfolio, excluding called CLOs, or $0.94 per weighted average common share. These recurring cash flows exceeded the Company’s common share distributions and total expenses incurred by the Company during the period. With the addition of recently acquired investments, we believe our investment portfolio remains well-positioned to generate strong cash flows.
Loan Market8
The US leveraged loan market delivered a positive return in the first half of 2026, supported by resilient credit fundamentals, despite continued dispersion across sectors and issuers. The S&P UBS Leveraged Loan Index, a broad index tracking the corporate loan market, generated a total return of 1.4% for the first half of 2026.9 Credit quality remained resilient, with the
​
Past Performance is not indicative of, or a guarantee of, future performance.
See end notes on page 7.
​ ​
3
​

​
​ FIRST HALF 2026 SHAREHOLDER LETTER AND SEMIANNUAL REPORT   |   Eagle Point Credit Company ​
trailing 12-month default rate at 1.0%, well below long-term averages.10 The limited number of defaults that occurred during the first half of 2026 were isolated and not a primary driver of market performance.
Total loan repayments reached $150 billion in the first half of 2026, resulting in a 12-month trailing repayment rate of 21.9%, while gross issuance of $440 billion translated into net new issuance of $131 billion. Importantly, the maturity profile of the loan market continues to improve, with just 1.8% of the overall market and 1.5% of the loans underlying the Company’s CLO equity positions scheduled to mature before 2028.
CLO Market8
The first half of 2026 reflected a tale of two markets, in some ways similar to the same period last year. Uncertainty surrounding the potential impact of artificial intelligence on software borrowers, together with geopolitical developments, weighed on leveraged loan prices and CLO equity valuations during the first quarter. Although market sentiment weakened significantly, we believe the first quarter decline in valuations reflected market-driven pricing pressure rather than a broad deterioration in underlying credit fundamentals. As sentiment improved during the second quarter, loan prices and CLO equity valuations recovered meaningfully, while underlying credit fundamentals remained resilient throughout the period.
While artificial intelligence will likely create both winners and losers over time, many software businesses continue to benefit from recurring revenue, sticky customer relationships and mission-critical products. We therefore believe the market reaction earlier in the year overstated the near-term impact on the broader software sector.
Our constructive outlook is further supported by healthy CLO market fundamentals. CLO issuance remained active during the first half of 2026, totaling $80 billion, while refinancings and resets reached $63 billion and $87 billion, respectively. These transactions continued to lower CLO liability costs and enhance the economics of existing CLO equity investments. As of June 30, 2026, the Company’s portfolio had a weighted average CLO AAA spread of 130 bps, compared to 124 bps for the broader market. Underlying credit quality also remained healthy, with market-wide CCC-rated loan exposure averaging 4.6% compared to 3.8% for the Company’s portfolio, while junior overcollateralization cushions remained strong at 3.8% across the market versus 4.4% within the Company’s portfolio.
In addition, we believe one of the most significant headwinds facing CLO equity over the last 18 months – loan spread compression – may be abating. The percentage of the loan market trading above par ended the first half at 21.7%. Typically, loan repricing activity tends to accelerate when the percentage of the loan market trading above par is greater than 50%. As loan spreads stabilize, we believe CLO equity cash flows and valuations are positioned to benefit.
Outlook
Throughout the first half of the year, we remained focused on enhancing the portfolio’s long-term earnings power. We continued to execute refinancings and resets across the CLO portfolio, while maintaining a robust pipeline of additional opportunities that we believe will further improve future earnings and cash flows. We also repositioned the portfolio by rotating capital away from a certain group of underperforming CLO collateral managers. While this resulted in realized losses during the period, those losses had largely been reflected in the unrealized losses from prior periods, resulting in a minimal impact on the Company’s NAV during the current period. Importantly, this repositioning allowed us to redeploy capital toward our core group of CLO collateral managers and selectively expand our exposure to other credit investments sourced through Eagle Point’s broader investment platform.
One recent example is our investment in Sports Illustrated Tickets, a specialty finance transaction secured by World Cup tickets that the Eagle Point team originated. Following a seven-month holding period, the investment generated a 1.2x multiple on invested capital when it was realized in June. We believe investments like this demonstrate the value of leveraging Eagle Point’s dedicated investment teams and origination capabilities to source differentiated credit opportunities that complement our core CLO investment strategy.
We also continue to build meaningful long-term value in our strategic partnership with Muzinich. The successful pricing of Muzinich’s inaugural European CLO marked an important milestone in the development of the European CLO platform. As
​
Past Performance is not indicative of, or a guarantee of, future performance.
See end notes on page 7.
​ ​
4
​

​
​ FIRST HALF 2026 SHAREHOLDER LETTER AND SEMIANNUAL REPORT   |   Eagle Point Credit Company ​
noted previously, this partnership allows the Company to participate in the economic upside through a long-term revenue-sharing arrangement that enables shareholders to benefit from the continued growth of the platform as more CLOs are issued over time. Given Muzinich’s established presence in the European market, we are excited about its growth trajectory.
Looking ahead, we remain constructive on the long-term outlook for CLO equity and the broader opportunity set available across Eagle Point’s investment platform. We believe continued refinancing and reset activity, opportunities to deploy capital into attractive investments and the ongoing expansion of our strategic partnerships and private credit capabilities position the portfolio well for the future. While periods of market uncertainty are inevitable, we believe the Company remains well-positioned to create long-term value for shareholders through disciplined portfolio management, active capital allocation and access to differentiated investment opportunities across our Adviser’s platform.
About Our Adviser
The Adviser is an investment manager focused on specialized private credit strategies in inefficient markets, including portfolio debt securities, regulatory capital relief transactions, infrastructure credit, strategic credit investments, specialty finance and CLO strategies. As of June 30, 2026, our Adviser and its affiliates have over $14 billion of assets under management (inclusive of undrawn capital commitments).11
Subsequent Developments
As of July 31, 2026, management’s unaudited estimate of the range of the Company’s NAV per common share was between $4.33 and $4.43.
The table below summarizes the Company’s common and preferred shares distributions that have been declared but remain unpaid as of the date of this letter:
​ ​
​
​ ​
​ ​
Security
​ ​ ​
Amount per Share
​ ​ ​
Record Dates
​ ​ ​
Payable Dates
​ ​
​ ​
Common Shares
​ ​ ​
$0.06
​ ​ ​
August 11, 2026
September 10, 2026
October 13, 2026
November 10, 2026
December 11, 2026
​ ​ ​
August 31, 2026
September 30, 2026
October 30, 2026
November 30, 2026
December 31, 2026
​ ​
​ ​
Series C Term Preferred Shares
​ ​ ​
$0.135417
​ ​
​ ​
Series D Preferred Shares
​ ​ ​
$0.140625
​ ​
​ ​
Series AA Convertible Perpetual Preferred Shares
​ ​ ​
$0.145834
​ ​
​ ​
Series AB Convertible Perpetual Preferred Shares
​ ​ ​
$0.145834
​ ​
* * * * *
Management remains keenly focused on continuing to create value for our fellow shareholders. We appreciate the trust and confidence our fellow shareholders have placed in the Company.
Thomas Majewski
Chief Executive Officer
​
Past Performance is not indicative of, or a guarantee of, future performance.
See end notes on page 7.
​ ​
5
​

​
​ FIRST HALF 2026 SHAREHOLDER LETTER AND SEMIANNUAL REPORT   |   Eagle Point Credit Company ​
This letter is intended to assist shareholders in understanding the Company’s performance during the six months ended June 30, 2026. The views and opinions in this letter were current as of August 11, 2026. Statements other than those of historical facts included herein may constitute forward-looking statements and are not guarantees of future performance or results and involve a number of risks and uncertainties. Actual results may differ materially from those in the forward-looking statements as a result of a number of factors. The Company undertakes no duty to update any forward-looking statement made herein. Information contained on our website is not incorporated by reference into this shareholder letter and you should not consider information contained on our website to be part of this shareholder letter or any other report we file with the SEC.
​
Past Performance is not indicative of, or a guarantee of, future performance.
See end notes on page 7.
​ ​
6
​

​
​ FIRST HALF 2026 SHAREHOLDER LETTER AND SEMIANNUAL REPORT   |   Eagle Point Credit Company ​
Notes
1.
“Weighted average common share” is calculated based on the average daily number of common shares outstanding during the period.
​
2.
Return on common equity reflects the Company’s cumulative monthly performance net of applicable expenses and fees measured against beginning capital adjusted for any common equity issued during the period.
​
3.
The actual components of the Company’s distributions for US tax reporting purposes can only be finally determined as of the end of each fiscal year of the Company and are thereafter reported on Form 1099-DIV. A distribution comprised in whole or in part by a return of capital does not necessarily reflect the Company’s investment performance and should not be confused with “yield” or “income.” Future distributions may consist of a return of capital. Not a guarantee of future distributions or yield.
​
4.
“Weighted average effective yield” is based on an investment’s amortized cost and expected future cash flows whereas “weighted average expected yield” is based on an investment’s fair market value and expected future cash flows as of the applicable period end as disclosed in the Company’s financial statements, which is subject to change from period to period.
​
5.
Source: Eagle Point and US BSL CLO Market. US BSL CLO Market is based on notional value. CLO equity portfolio based on fair value of investments.
​
6.
An investment company trades at a premium when the market price at which its shares trade is more than its net asset value per share. Alternatively, an investment company trades at a discount when the market price at which its shares trade is less than its net asset value per share.
​
7.
For purposes of the weighted average maturity calculation, a 10-year maturity from date of original issuance is assumed for the Series D Perpetual Preferred Shares and Series AA and Series AB Convertible Perpetual Preferred Shares.
​
8.
Market data and statistics summarized herein are sourced from Bloomberg, JP Morgan and Pitchbook LCD.
​
9.
The S&P UBS Leveraged Loan Index tracks the investable universe of the USD-denominated leveraged loan market. You cannot invest directly in an index.
​
10.
Default rate represents the rate of obligors who fail to remain current on their loans based on the par amount.
​
11.
Calculated in the aggregate with certain other affiliated advisers.
​
​
Past Performance is not indicative of, or a guarantee of, future performance.
 
 
​ ​
7
​

​
​ FIRST HALF 2026 SHAREHOLDER LETTER AND SEMIANNUAL REPORT   |   Eagle Point Credit Company ​
Page Intentionally Left Blank
​


​ ​
8
​

​​
​FIRST HALF 2026 SHAREHOLDER LETTER AND SEMIANNUAL REPORT   |   Eagle Point Credit Company​
Important Information about this Report and Eagle Point Credit Company
This report is transmitted to the shareholders of Eagle Point Credit Company (“we,” “us,” “our” or the “Company”) and is furnished pursuant to certain regulatory requirements. This report and the information and views herein do not constitute investment advice, or a recommendation or an offer to enter into any transaction with the Company or any of its affiliates. This report is provided for informational purposes only, does not constitute an offer to sell securities of the Company and is not a prospectus. From time to time, the Company may have a registration statement relating to one or more of its securities on file with the SEC. Any registration statement that has not yet been declared effective by the SEC, and any prospectus relating thereto, is not complete and may be changed. Any securities that are the subject of such a registration statement may not be sold until the registration statement filed with the SEC is effective.
The information and its contents are the property of Eagle Point Credit Management LLC (the “Adviser”) and/or the Company. Any unauthorized dissemination, copying or use of this report is strictly prohibited and may be in violation of law. This report is being provided for informational purposes only.
Investors should read the Company’s prospectus and SEC filings (which are publicly available on the EDGAR Database on the SEC website (www.sec.gov) carefully and consider their investment goals, time horizons and risk tolerance before investing in the Company. Investors should consider the Company’s investment objectives, risks, charges and expenses carefully before investing in securities of the Company. There is no guarantee that any of the goals, targets or objectives described in this report will be achieved.
An investment in the Company is not appropriate for all investors. The investment program of the Company is speculative, entails substantial risk and includes investment techniques not employed by traditional mutual funds. An investment in the Company is not intended to be a complete investment program. Shares of closed-end investment companies, such as the Company, frequently trade at a discount from their net asset values (“NAV”), which may increase investors’ risk of loss. Past performance is not indicative of, or a guarantee of, future performance. The performance and certain other portfolio information quoted herein represents information as of June 30, 2026. Nothing herein should be relied upon as a representation as to the future performance or portfolio holdings of the Company. Investment return and principal value of an investment will fluctuate, and shares, when sold, may be worth more or less than their original costs. The Company’s performance is subject to change since the end of the period noted in this report and may be lower or higher than the performance data shown herein.
Neither the Adviser nor the Company provides legal, accounting or tax advice. Any statement regarding such matters is explanatory and may not be relied upon as definitive advice. Investors should consult with their legal, accounting and tax advisors regarding any potential investment. The information presented herein is as of the dates noted herein and is derived from financial and other information of the Company, and, in certain cases, from third-party sources and reports (including reports of third-party custodians, CLO managers and trustees) that have not been independently verified by the Company. As noted herein, certain of this information is estimated and unaudited, and therefore subject to change. We do not represent that such information is accurate or complete, and it should not be relied upon as such.
Forward-Looking Statements
This report may contain “forward-looking statements” within the meaning of the Private Securities Litigation Reform Act of 1995. Statements other than statements of historical facts included in this report may constitute forward-looking statements and are not guarantees of future performance or results and involve a number of risks and uncertainties. Actual results may differ materially from those in the forward-looking statements as a result of a number of factors, including those described in the Company’s filings with the SEC. The Company undertakes no duty to update any forward-looking statement made herein. All forward-looking statements speak only as of the date of this report.
 
​ ​​
9
​

​​
​FIRST HALF 2026 SHAREHOLDER LETTER AND SEMIANNUAL REPORT   |   Eagle Point Credit Company​
SUMMARY OF CERTAIN UNAUDITED PORTFOLIO CHARACTERISTICS1
​
SUMMARY OF PORTFOLIO INVESTMENTS2
​
​
pc_portfolio-4c.jpg
​
​
SUMMARY OF CLO EQUITY UNDERLYING PORTFOLIO CHARACTERISTICS3
​
​
Number of Unique Underlying Loan Obligors
​​
1,838
​
​
Largest Exposure to an Individual Obligor
​​
0.62%
​
​
Average Individual Loan Obligor Exposure
​​
0.05%
​
​
Top 10 Loan Obligors Exposure
​​
4.69%
​
​
Currency: USD Exposure
​​
86.22%
​
​
Aggregate Indirect Exposure to Senior Secured Loans4
​​
95.07%
​
​
Weighted Average Junior Overcollateralization Cushion
​​
4.43%
​
​
Weighted Average Market Value of Loan Collateral
​​
95.99%
​
​
Weighted Average Stated Loan Spread
​​
3.15%
​
​
Weighted Average Loan Rating5
​​
B+/B
​
​
Weighted Average Loan Maturity
​​
4.7 years
​
​
Weighted Average Remaining CLO Reinvestment Period
​​
3.4 years
​
​
Please see footnote disclosures on page 12.
 
​​
10
​

​
​FIRST HALF 2026 SHAREHOLDER LETTER AND SEMIANNUAL REPORT   |   Eagle Point Credit Company​
​
Top 10 Underlying CLO Equity
Obligors
3
​
​
Obligor
​​
% of Total
​
​
Transdigm
​​
0.6%
​
​
Hologic
​​
0.5%
​
​
Virgin Media
​​
0.5%
​
​
Tibco Software
​​
0.5%
​
​
Electronic Arts
​​
0.4%
​
​
Froneri International
​​
0.4%
​
​
Belron Finance
​​
0.4%
​
​
Envestnet
​​
0.4%
​
​
Power Solutions
​​
0.4%
​
​
Focus Financial Partners
​​
0.4%
​
​
Total
​​
4.7%
​
​
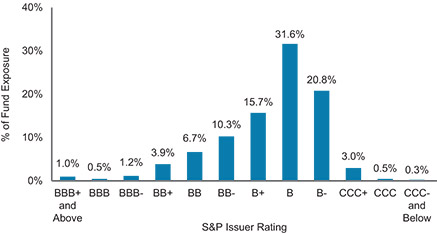
Rating Distribution of CLO Equity Underlying
Obligors
3,6
​
​
bc_rating-4c.jpg
​
​
Top 10 Industries of CLO Equity Underlying
Obligors
3,6
​
​
Industry
​​
% of Total
​
​
Technology: Software & Services
​​
10.4%
​
​
Diversified Financial Services
​​
6.0%
​
​
Health Care Providers & Services
​​
5.2%
​
​
Hotels, Restaurants & Leisure
​​
5.2%
​
​
Media
​​
5.0%
​
​
Professional Services
​​
4.1%
​
​
Technology: Hardware & Equipment
​​
4.0%
​
​
Insurance
​​
3.9%
​
​
Commercial Services & Supplies
​​
3.8%
​
​
Chemicals
​​
3.7%
​
​
Total
​​
51.3%
​
​
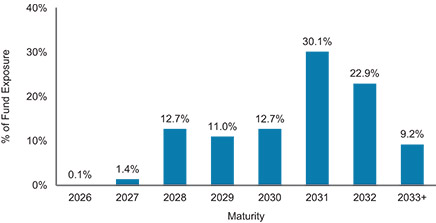
Maturity Distribution of CLO Equity Underlying
Obligors
3
​
​
bc_maturity-4c.jpg
​
​
​
Please see footnote disclosures on page 12.
 
​​
11
​

​
​FIRST HALF 2026 SHAREHOLDER LETTER AND SEMIANNUAL REPORT   |   Eagle Point Credit Company​
Notes
1.
The information presented is on a look-through basis to the collateralized loan obligation (“CLO”) equity held by the Company as of June 30, 2026 (except as otherwise noted) and reflects the aggregate underlying exposure of the Company based on the portfolios of those investments. The data is estimated and unaudited and is derived from CLO trustee reports received by the Company relating to June 2026 and from custody statements and/or other information received from CLO collateral managers or other third-party sources.
​
2.
The summary of portfolio investments shown is based on the estimated fair value of the underlying positions and cash net of pending settlements as of June 30, 2026. Cash excludes restricted cash.
​
3.
Information relating to the market price of underlying collateral is as of June 30, 2026; however, with respect to other information shown, depending on when such information was received, the data may reflect a lag in the information reported. As such, while this information was obtained from third-party data sources, June 2026 trustee reports and similar reports, other than market price, it does not reflect actual underlying portfolio characteristics as of June 30, 2026, and this data may not be representative of current or future holdings. The weighted average remaining reinvestment period information is based on the fair value of CLO equity investments held by the Company as of June 30, 2026.
​
4.
We obtain exposure in underlying senior secured loans indirectly through CLOs and related investments.
​
5.
Credit ratings shown are based on those assigned by Standard & Poor’s Rating Group, or “S&P,” or, for comparison and informational purposes, if S&P does not assign a rating to a particular obligor, the weighted average rating shown reflects the S&P equivalent rating of a rating agency that rated the obligor provided that such other rating is available with respect to a CLO equity or related investment held by us. In the event multiple ratings are available, the lowest S&P rating, or if there is no S&P rating, the lowest equivalent rating, is used. The ratings of specific borrowings by an obligor may differ from the rating assigned to the obligor and may differ among rating agencies. For certain obligors, no rating is available in the reports received by the Company. Such obligors are not shown in the graphs and, accordingly, the sum of the percentages in the graphs may not equal 100%. Ratings below BBB- are below investment grade. Further information regarding S&P’s rating methodology and definitions may be found on its website (www.standardandpoors.com). This data includes underlying portfolio characteristics of the Company’s CLO equity.
​
6.
Industry categories are based on the S&P industry categorization of each obligor as reported in CLO trustee reports to the extent so reported. Certain CLO trustee reports do not report the industry category of all of the underlying obligors and where such information is not reported, it is not included in the summary look-through industry information shown. As such, the Company’s exposure to a particular industry may be higher than that shown if industry categories were available for all underlying obligors. In addition, certain underlying obligors may be reclassified from time to time based on developments in their respective businesses and/or market practices. Accordingly, certain underlying borrowers that are currently, or were previously, summarized as a single borrower in a particular industry may in current or future periods be reflected as multiple borrowers or in a different industry, as applicable.
​
 
​ ​​
12
​

​​
​ FIRST HALF 2026 SHAREHOLDER LETTER AND SEMIANNUAL REPORT   |   Eagle Point Credit Company ​
ADDITIONAL COMPANY INFORMATION
Other Company Securities
As of June 30, 2026, in addition to its common shares, the Company had four other securities that trade on the NYSE and two other securities that are not exchange-traded:
​
Security
​ ​
NYSE
Symbol
​ ​
Par Amount
Outstanding
​ ​
Rate
​ ​
Payment
Frequency
​ ​
Callable
​ ​
Maturity
​
​
Series C Term
Preferred Shares due 2031
​ ​
ECCC
​ ​
$45.5 million
​ ​
6.50%
​ ​
Monthly
​ ​
Callable
​ ​
June 2031
​
​
Series D
Preferred Shares
​ ​
ECC PRD
​ ​
$105.5 million
​ ​
6.75%
​ ​
Monthly
​ ​
November 2026
​ ​
Perpetual
​
​
Series AA
Convertible
Perpetual
Preferred Shares
​ ​
N/A
​ ​
$145.8 million
​ ​
7.00%
​ ​
Monthly
​ ​
2 years from issuance
​ ​
Perpetual
​
​
Series AB
Convertible
Perpetual
Preferred Shares
​ ​
N/A
​ ​
$7.0 million
​ ​
7.00%
​ ​
Monthly
​ ​
2 years from issuance
​ ​
Perpetual
​
​
Notes due 2029
​ ​
ECCV
​ ​
$93.3 million
​ ​
5.375%
​ ​
Quarterly
​ ​
Callable
​ ​
January 2029
​
​
Notes due 2030
​ ​
ECCU
​ ​
$115.0 million
​ ​
7.75%
​ ​
Quarterly
​ ​
June 2027
​ ​
June 2030
​
 
​   ​ ​
13
​

​​​
​ FIRST HALF 2026 SHAREHOLDER LETTER AND SEMIANNUAL REPORT   |   Eagle Point Credit Company ​
CONSOLIDATED FINANCIAL STATEMENTS FOR THE SIX MONTHS ENDED
JUNE 30, 2026 (UNAUDITED)
​ ​ ​ ​ ​ 15 ​ ​
​ ​ ​ ​ ​ 16 ​ ​
​ ​ ​ ​ ​ 25 ​ ​
​ ​ ​ ​ ​ 26 ​ ​
​ ​ ​ ​ ​ 27 ​ ​
​ ​ ​ ​ ​ 29 ​ ​
​ ​ ​ ​ ​ 30 ​ ​
​ ​ ​ ​ ​ 31 ​ ​
​ ​ ​ ​ ​ 65 ​ ​
​ ​ ​ ​ ​ 68 ​ ​
 
​   ​ ​
14
​

​​
​ FIRST HALF 2026 SHAREHOLDER LETTER AND SEMIANNUAL REPORT   |   Eagle Point Credit Company ​
Eagle Point Credit Company & Subsidiaries
Consolidated Statement of Assets and Liabilities
As of June 30, 2026
(expressed in U.S. dollars)
(Unaudited)
​
​ ASSETS ​ ​ ​ ​ ​ ​ ​
​
Investments, at fair value (cost $1,283,085,263)(1)
​ ​ ​ $ 1,005,420,456 ​ ​
​
Unrealized appreciation on forward currency contracts
​ ​ ​ ​ 4,604,908 ​ ​
​
Cash and cash equivalents (restricted cash of $960,000)
​ ​ ​ ​ 58,840,031 ​ ​
​
Cash denominated in foreign currency (cost $616,117)
​ ​ ​ ​ 704,006 ​ ​
​
Interest receivable
​ ​ ​ ​ 45,837,278 ​ ​
​
Receivable for securities sold
​ ​ ​ ​ 24,404,624 ​ ​
​
Prepaid expenses
​ ​ ​ ​ 297,662 ​ ​
​
Total Assets
​ ​ ​ $ 1,140,108,965 ​ ​
​ LIABILITIES ​ ​ ​ ​ ​ ​ ​
​
Unsecured notes issued and outstanding, at fair value (aggregate principal amount of $208,250,000) (Note 8)
​ ​ ​ ​ 204,440,400 ​ ​
​
Mandatorily redeemable preferred shares, at fair value (1,820,190 shares issued and outstanding) (Note 7)
​ ​ ​ ​ 45,431,942 ​ ​
​
Investments sold under participation agreements, at fair value (Note 2)
​ ​ ​ ​ 19,995,891 ​ ​
​
Unrealized depreciation on forward currency contracts
​ ​ ​ ​ 113,877 ​ ​
​
Unfunded investment commitments, at fair value
​ ​ ​ ​ 97,654 ​ ​
​
Payable for securities purchased
​ ​ ​ ​ 20,292,214 ​ ​
​
Incentive fee payable
​ ​ ​ ​ 9,213,164 ​ ​
​
Management fee payable
​ ​ ​ ​ 3,702,650 ​ ​
​
Deferred tax liability
​ ​ ​ ​ 1,736,452 ​ ​
​
Professional fees payable
​ ​ ​ ​ 732,804 ​ ​
​
Administration fees payable
​ ​ ​ ​ 324,140 ​ ​
​
Trustees’ fees payable
​ ​ ​ ​ 198,750 ​ ​
​
Other expenses payable
​ ​ ​ ​ 229,089 ​ ​
​
Total Liabilities
​ ​ ​ ​ 306,509,027 ​ ​
​ TEMPORARY EQUITY (Note 2) ​ ​ ​ ​ ​ ​ ​
​
Perpetual Preferred Shares (Note 7)
​ ​ ​ ​ 234,117,006 ​ ​
​ COMMITMENTS AND CONTINGENCIES (Note 10) ​ ​ ​ ​ ​ ​ ​
​
NET ASSETS applicable to common shares, unlimited shares authorized, 133,010,748 shares issued and outstanding
​ ​ ​ $ 599,482,932 ​ ​
​ NET ASSETS consist of: ​ ​ ​ ​ ​ ​ ​
​
Paid-in capital
​ ​ ​ $ 1,279,165,576 ​ ​
​
Aggregate distributable earnings (losses)
​ ​ ​ ​ (673,208,489) ​ ​
​
Accumulated other comprehensive income (loss)
​ ​ ​ ​ (6,474,155) ​ ​
​
Total Net Assets
​ ​ ​ $ 599,482,932 ​ ​
​
Net asset value per share of common shares
​ ​ ​ $ 4.51 ​ ​
​
(1)
Includes $100,034,055 of affiliated investments at fair value (cost $101,617,763). See Note 5 “Related Party Transactions” for further discussion.
​
See accompanying notes to the consolidated financial statements
 
​   ​ ​
15
​

​​
​FIRST HALF 2026 SHAREHOLDER LETTER AND SEMIANNUAL REPORT   |   Eagle Point Credit Company​
Eagle Point Credit Company & Subsidiaries
Consolidated Schedule of Investments
As of June 30, 2026
(expressed in U.S. dollars)
(Unaudited)
​
Issuer(1)
​​
Investment Description
​​
Acquisition
Date
(2)
​​
Principal
Amount /
Shares
​​
Cost
​​
Fair Value(3)
​
Investments, at Fair Value – 167.71% of Net Assets(5)​
Collateralized Loan Obligation Debt – 0.08% of Net Assets(4)(6)
​
Structured Finance
​​​​​​​​​​​​​​​​​​​​​​​​​
United States
​​​​​​​​​​​​​​​​​​​​​​​​​
Ares LXI CLO Ltd.
​​Secured Note – Class F-R, 11.68% (3M SOFR + 8.00%, due 4/20/2037) ​​
3/27/2024
​​​$269,700​​​​$170,337​​​​$269,901​​
Dryden 53 CLO, Ltd.
​​Secured Note – Class F, 11.43% (3M SOFR + 7.76%, due 1/15/2031) ​​
11/28/2017
​​​​1,664,500​​​​​1,487,668​​​​​160,466​​
HarbourView CLO VII-R, Ltd.
​​Secured Note – Class F, 12.21% (3M SOFR + 8.53%, due 7/18/2031) ​​
5/17/2018
​​​​537,321​​​​​515,227​​​​​22,694​​
Octagon Investment Partners 27, Ltd.
​​Secured Note – Class F-R, 11.78% (3M SOFR + 8.11%, due 7/15/2030) ​​
7/5/2018
​​​​900,000​​​​​864,954​​​​​135​​
Total Collateralized Loan Obligation Debt
​​​​​​​​​​​​​​​​3,038,186​​​​​453,196​​
Collateralized Loan Obligation Equity – 97.81% of Net Assets(3)(4)(8)(9)​
​
Structured Finance
​​​​​​​​​​​​​​​​​​​​​​​​​
United States
​​​​​​​​​​​​​​​​​​​​​​​​​
1988 CLO 1 Ltd.
​​Income Note (effective yield 15.78%, maturity 10/15/2039)(10)​​
9/23/2022
​​​​7,599,000​​​​​4,631,252​​​​​4,006,645​​
1988 CLO 2 Ltd.
​​Income Note (effective yield 19.59%, maturity 4/15/2038)(10)​​
2/8/2023
​​​​5,532,000​​​​​3,148,530​​​​​3,094,041​​
1988 CLO 3 Ltd.
​​Income Note (effective yield 15.27%, maturity 10/15/2040)(10)​​
9/12/2023
​​​​8,735,000​​​​​5,452,321​​​​​4,703,884​​
1988 CLO 4 Ltd.
​​Income Note (effective yield 13.89%, maturity 4/15/2039)(10)​​
4/9/2024
​​​​8,078,000​​​​​5,822,057​​​​​5,286,236​​
1988 CLO 5 Ltd.
​​Income Note (effective yield 7.85%, maturity 7/15/2037)(10)​​
6/3/2024
​​​​7,541,000​​​​​4,862,671​​​​​3,891,822​​
1988 CLO 6 Ltd.
​​Income Note (effective yield 17.06%, maturity 4/15/2038)(10)​​
2/20/2025
​​​​4,557,000​​​​​3,693,028​​​​​3,627,829​​
1988 CLO 7 Ltd.
​​Class M1 Note (maturity 4/15/2039) ​​
2/26/2026
​​​​7,780,000​​​​​—​​​​​79,169​​
1988 CLO 7 Ltd.
​​Class M2 Note (maturity 4/15/2039) ​​
2/26/2026
​​​​7,780,000​​​​​—​​​​​158,400​​
1988 CLO 7 Ltd.
​​Class M3 Note (maturity 4/15/2039) ​​
2/26/2026
​​​​7,780,000​​​​​—​​​​​—​​
AMMC CLO 23, Limited
​​Subordinated Note (effective yield 14.81%, maturity 7/17/2038) ​​
9/19/2025
​​​​5,279,000​​​​​3,171,335​​​​​2,426,513​​
AMMC CLO 28, Limited
​​Subordinated Note (effective yield 11.50%, maturity 7/20/2037) ​​
1/28/2025
​​​​20,925,000​​​​​15,190,297​​​​​12,184,212​​
AMMC CLO 30, Limited
​​Subordinated Note (effective yield 18.02%, maturity 4/15/2039) ​​
12/10/2024
​​​​3,918,000​​​​​2,695,448​​​​​2,536,387​​
Anchorage Credit Funding 12, Ltd.
​​Income Note (effective yield 5.28%, maturity 10/25/2038) ​​
9/4/2020
​​​​9,264,455​​​​​6,006,107​​​​​4,279,598​​
Anchorage Credit Funding 13, Ltd.
​​Subordinated Note (effective yield 6.62%, maturity 7/27/2039) ​​
5/25/2021
​​​​1,200,000​​​​​931,389​​​​​621,895​​
Ares XXXIX CLO Ltd.
​​Subordinated Note (effective yield 4.34%, maturity 7/15/2039) ​​
11/1/2024
​​​​11,340,000​​​​​4,157,342​​​​​2,325,495​​
Ares XLIII CLO Ltd.
​​Income Note (effective yield 5.56%, maturity 1/15/2038)(10)​​
4/4/2017
​​​​43,860,000​​​​​15,393,024​​​​​8,613,238​​
Ares LI CLO Ltd.
​​Income Note (effective yield 6.42%, maturity 10/15/2037)(10)​​
1/25/2019
​​​​18,981,463​​​​​9,521,768​​​​​5,472,148​​
Ares LXI CLO Ltd.
​​Subordinated Note (effective yield 4.77%, maturity 4/20/2037) ​​
1/24/2024
​​​​4,650,000​​​​​2,674,387​​​​​1,240,412​​
Ares LXIV CLO Ltd.
​​Subordinated Note (effective yield 7.20%, maturity 10/22/2039) ​​
1/26/2023
​​​​28,159,000​​​​​15,907,019​​​​​8,679,709​​
Ares LXIX CLO Ltd.
​​Income Note (effective yield 8.88%, maturity 4/15/2036)(10)​​
1/31/2024
​​​​14,100,000​​​​​8,369,884​​​​​4,264,976​​
Ares LXXII CLO Ltd.
​​Income Note (effective yield 8.52%, maturity 7/15/2037)(10)​​
6/21/2024
​​​​33,950,000​​​​​21,825,964​​​​​11,866,534​​
Ares LXXIV CLO Ltd.
​​Subordinated Note (effective yield 9.07%, maturity 10/15/2037) ​​
7/23/2025
​​​​27,150,000​​​​​21,371,091​​​​​13,722,924​​
Ares LXXVI CLO Ltd.
​​Income Note (effective yield 13.98%, maturity 5/27/2038)(10)​​
4/14/2025
​​​​10,075,000​​​​​6,771,313​​​​​5,765,515​​
Ares Loan Funding V, Ltd.
​​Subordinated Note (effective yield 10.48%, maturity 7/25/2037) ​​
2/7/2025
​​​​12,400,000​​​​​8,311,686​​​​​5,409,192​​
Bardin Hill CLO 2021-2 Ltd.
​​Subordinated Note (effective yield 19.55%, maturity 4/17/2039)(10)​​
9/24/2021
​​​​5,550,000​​​​​3,124,002​​​​​2,383,491​​
Barings CLO Ltd. 2018-I
​​Income Note (effective yield 0.00%, maturity 4/15/2031)(10)(11)​​
2/23/2018
​​​​20,808,000​​​​​—​​​​​3,235​​
Barings CLO Ltd. 2019-I
​​Income Note (effective yield 10.36%, maturity 10/15/2038)(10)​​
2/12/2019
​​​​10,611,500​​​​​9,681,208​​​​​7,069,194​​
Barings CLO Ltd. 2019-II
​​Income Note (effective yield 7.70%, maturity 1/15/2038)(10)​​
3/15/2019
​​​​14,700,500​​​​​9,895,425​​​​​6,161,374​​
Barings CLO Ltd. 2020-I
​​Income Note (effective yield 19.99%, maturity 1/15/2038)(10)​​
9/4/2020
​​​​6,966,000​​​​​3,144,863​​​​​2,689,894​​
Barings CLO Ltd. 2021-I
​​Subordinated Note (effective yield 0.00%, maturity 4/25/2034)(11)​​
6/5/2024
​​​​20,000,000​​​​​2,180,000​​​​​1,480,000​​
Barings CLO Ltd. 2021-III
​​Subordinated Note (effective yield 0.00%, maturity 1/18/2035)(12)​​
11/17/2021
​​​​2,000,000​​​​​1,021,199​​​​​188,360​​
Barings CLO Ltd. 2022-I
​​Income Note (effective yield 7.86%, maturity 1/15/2039)(10)​​
3/18/2022
​​​​13,162,500​​​​​7,501,315​​​​​4,757,650​​
Barings CLO Ltd. 2022-II
​​Income Note (effective yield 25.01%, maturity 7/15/2039)(10)​​
6/21/2022
​​​​10,800,000​​​​​3,487,379​​​​​2,833,289​​
Barings CLO Ltd. 2024-II
​​Income Note (effective yield 13.61%, maturity 7/15/2039)(10)​​
5/31/2024
​​​​9,300,000​​​​​5,574,316​​​​​4,463,481​​
Barings CLO Ltd. 2025-IV
​​Income Note (effective yield 17.27%, maturity 10/15/2040)(10)​​
8/7/2025
​​​​10,575,000​​​​​6,805,605​​​​​6,754,637​​
Basswood Park CLO, Ltd.
​​Class M-1 Note (effective yield 0.00%, maturity 4/20/2034)(12)​​
2/15/2024
​​​​5,000,000​​​​​3,539​​​​​3,747​​
Basswood Park CLO, Ltd.
​​Class M-2 Note (effective yield 0.00%, maturity 4/20/2034)(12)​​
2/15/2024
​​​​5,000,000​​​​​7,743​​​​​8,742​​
Battalion CLO IX Ltd.
​​Income Note (effective yield 0.00%, maturity 7/15/2031)(10)(12)​​
7/9/2015
​​​​18,734,935​​​​​4,532,314​​​​​211,157​​
Battalion CLO 18 Ltd.
​​Income Note (effective yield 0.00%, maturity 10/15/2036)(10)(12)​​
8/25/2020
​​​​8,400,000​​​​​3,125,486​​​​​556,819​​
Battalion CLO XIX Ltd.
​​Income Note (effective yield 0.00%, maturity 4/15/2034)(10)(12)​​
3/11/2021
​​​​8,600,000​​​​​3,091,324​​​​​506,665​​
Battalion CLO XXIII Ltd.
​​Income Note (effective yield 6.45%, maturity 10/15/2037)(10)​​
5/19/2022
​​​​18,010,000​​​​​7,605,092​​​​​4,297,517​​
Bear Mountain Park CLO, Ltd.
​​Income Note (effective yield 16.66%, maturity 7/15/2037)(10)​​
7/13/2022
​​​​14,500,000​​​​​10,802,192​​​​​6,660,340​​
Belmont Park CLO, Ltd.
​​Income Note (effective yield 8.05%, maturity 4/15/2037)(10)​​
2/21/2024
​​​​14,950,000​​​​​9,164,423​​​​​5,449,537​​
Benefit Street Partners CLO XII, Ltd.
​​Subordinated Note (effective yield 9.60%, maturity 10/15/2037) ​​
12/12/2024
​​​​11,341,132​​​​​9,113,918​​​​​6,805,094​​
Bethpage Park CLO, Ltd.
​​Income Note (effective yield 0.00%, maturity 10/15/2035)(10)(12)​​
9/24/2021
​​​​14,750,000​​​​​6,624,156​​​​​1,928,700​​
BlueMountain CLO 2013-2 Ltd.
​​Subordinated Note (effective yield 0.00%, maturity 10/22/2030)(12)​​
10/21/2014
​​​​23,000,000​​​​​2,300​​​​​3,450​​
BlueMountain CLO 2018-1 Ltd.
​​Subordinated Note (effective yield 0.00%, maturity 7/30/2030)(12)​​
3/26/2020
​​​​5,550,000​​​​​—​​​​​16,617​​
BlueMountain CLO XXV Ltd.
​​Subordinated Note (effective yield 6.26%, maturity 1/15/2038)(10)​​
6/23/2020
​​​​675,000​​​​​421,401​​​​​328,346​​
Bristol Park CLO, Ltd.
​​Income Note (effective yield 0.00%, maturity 4/15/2029)(10)(11)​​
11/1/2016
​​​​34,250,000​​​​​85,625​​​​​34,888​​
See accompanying notes to the consolidated financial statements
 
​ ​​
16
​

​
​FIRST HALF 2026 SHAREHOLDER LETTER AND SEMIANNUAL REPORT   |   Eagle Point Credit Company​
Eagle Point Credit Company & Subsidiaries
Consolidated Schedule of Investments
As of June 30, 2026
(expressed in U.S. dollars)
(Unaudited)
Issuer(1)
​​
Investment Description
​​
Acquisition
Date
(2)
​​
Principal
Amount /
Shares
​​
Cost
​​
Fair Value(3)
​
Collateralized Loan Obligation Equity – 97.81% of
Net Assets(3)(4)(8)(9) (continued)
​
Structured Finance (continued)
​​​​​​​​​​​​​​​​​​​​​​​​​
United States (continued)
​​​​​​​​​​​​​​​​​​​​​​​​​
Carlyle Global Market Strategies CLO 2014-5, Ltd.
​​Subordinated Note (effective yield 0.00%, maturity 7/15/2031)(11)​​
6/2/2016
​​​$10,800,000​​​​$9,945​​​​$18,360​​
Carlyle US CLO 2018-1, Ltd.
​​Subordinated Note (effective yield 0.00%, maturity 4/20/2031)(11)​​
3/23/2021
​​​​4,730,000​​​​​19,488​​​​​11,825​​
Carlyle US CLO 2018-4, Ltd.
​​Subordinated Note (effective yield 8.01%, maturity 10/17/2037)(10)​​
2/18/2021
​​​​11,750,000​​​​​5,261,082​​​​​3,238,407​​
Carlyle US CLO 2019-4, Ltd.
​​Subordinated Note (effective yield 12.70%, maturity 6/22/2039)(10)​​
4/13/2021
​​​​7,659,500​​​​​6,960,394​​​​​5,182,541​​
Carlyle US CLO 2021-1, Ltd.
​​Income Note (effective yield 7.70%, maturity 1/15/2040)(10)​​
2/2/2021
​​​​14,175,000​​​​​6,980,465​​​​​4,061,143​​
Carlyle US CLO 2021-4, Ltd.
​​Subordinated Note (effective yield 0.00%, maturity 4/20/2034)(11)​​
11/17/2021
​​​​12,000,000​​​​​420,000​​​​​240,000​​
Carlyle US CLO 2021-7, Ltd.
​​Income Note (effective yield 8.34%, maturity 4/15/2040)(10)​​
8/11/2021
​​​​13,200,000​​​​​7,234,998​​​​​4,576,058​​
Carlyle US CLO 2022-1, Ltd.
​​Income Note (effective yield 0.00%, maturity 4/15/2035)(10)(12)​​
3/15/2022
​​​​8,150,000​​​​​4,830,290​​​​​2,192,012​​
Carlyle US CLO 2022-5, Ltd.
​​Subordinated Note (effective yield 11.02%, maturity 10/15/2037) ​​
5/2/2025
​​​​11,375,000​​​​​6,794,827​​​​​5,043,218​​
Carlyle US CLO 2023-3, Ltd.
​​Income Note (effective yield 10.69%, maturity 10/15/2040)(10)​​
7/6/2023
​​​​9,400,000​​​​​6,133,401​​​​​4,201,229​​
Carlyle US CLO 2024-1, Ltd.
​​Income Note (effective yield 8.16%, maturity 4/15/2039)(10)​​
1/26/2024
​​​​14,857,000​​​​​9,199,131​​​​​5,519,896​​
CBAM 2019-9, Ltd.
​​Subordinated Note (effective yield 5.96%, maturity 7/15/2037) ​​
11/1/2024
​​​​18,390,000​​​​​6,421,521​​​​​4,489,916​​
CIFC Funding 2013-II, Ltd.
​​Income Note (effective yield 0.00%, maturity 10/18/2030)(10)(11)​​
3/4/2016
​​​​17,265,625​​​​​22,445​​​​​2,590​​
CIFC Funding 2014, Ltd.
​​Income Note (effective yield 0.00%, maturity 1/18/2031)(10)(11)​​
9/12/2014
​​​​16,033,750​​​​​27,257​​​​​2,405​​
CIFC Funding 2014-III, Ltd.
​​Income Note (effective yield 9.47%, maturity 3/31/2038) ​​
2/17/2015
​​​​18,290,500​​​​​10,004,718​​​​​8,200,266​​
CIFC Funding 2014-IV-R, Ltd.
​​Income Note (effective yield 0.00%, maturity 1/17/2035)(12)​​
8/5/2014
​​​​8,457,500​​​​​2,667,432​​​​​1,376,558​​
CIFC Funding 2019-III, Ltd.
​​Subordinated Note (effective yield 10.61%, maturity 1/16/2038) ​​
4/18/2019
​​​​3,216,500​​​​​2,261,186​​​​​1,856,825​​
CIFC Funding 2019-IV, Ltd.
​​Income Note (effective yield 9.38%, maturity 7/15/2055)(10)​​
6/7/2019
​​​​17,648,000​​​​​10,699,324​​​​​8,650,068​​
CIFC Funding 2019-V, Ltd.
​​Income Note (effective yield 10.64%, maturity 10/15/2038) ​​
8/13/2025
​​​​21,020,000​​​​​13,060,500​​​​​11,103,564​​
CIFC Funding 2020-I, Ltd.
​​Income Note (effective yield 14.98%, maturity 7/15/2039)(10)​​
6/12/2020
​​​​9,600,000​​​​​7,610,585​​​​​6,952,650​​
CIFC Funding 2020-II, Ltd.
​​Income Note (effective yield 14.88%, maturity 4/16/2039) ​​
11/5/2024
​​​​17,552,000​​​​​7,835,606​​​​​7,728,814​​
CIFC Funding 2020-IV, Ltd.
​​Income Note (effective yield 11.97%, maturity 1/15/2040)(10)​​
12/11/2020
​​​​9,625,000​​​​​6,335,933​​​​​5,544,317​​
CIFC Funding 2021-III, Ltd.
​​Income Note (effective yield 9.81%, maturity 10/15/2038)(10)​​
4/23/2021
​​​​13,050,000​​​​​11,426,886​​​​​9,138,084​​
CIFC Funding 2021-VI, Ltd.
​​Income Note (effective yield 0.00%, maturity 7/15/2039)(10)(12)​​
9/22/2021
​​​​14,325,000​​​​​11,057,912​​​​​8,638,841​​
CIFC Funding 2022-I, Ltd.
​​Income Note (effective yield 1.72%, maturity 7/17/2041)(10)​​
1/27/2022
​​​​20,425,000​​​​​10,940,495​​​​​7,954,214​​
CIFC Funding 2022-VI, Ltd.
​​Income Note (effective yield 11.97%, maturity 10/16/2038)(10)​​
8/1/2022
​​​​10,700,000​​​​​7,403,120​​​​​6,439,755​​
CIFC Funding 2023-I, Ltd.
​​Income Note (effective yield 13.84%, maturity 10/15/2038)(10)​​
9/14/2023
​​​​13,475,000​​​​​9,662,682​​​​​9,100,656​​
CIFC Funding 2023-II, Ltd.
​​Subordinated Note (effective yield 14.16%, maturity 1/21/2037) ​​
5/16/2024
​​​​5,500,000​​​​​3,653,754​​​​​3,491,819​​
CIFC Funding 2025-II, Ltd.
​​Income Note (effective yield 12.51%, maturity 4/15/2038)(10)​​
2/7/2025
​​​​14,400,000​​​​​11,348,252​​​​​10,208,256​​
CIFC Funding 2025-V, Ltd.
​​Income Note (effective yield 10.95%, maturity 10/15/2038)(10)​​
7/30/2025
​​​​13,775,000​​​​​11,193,709​​​​​9,320,367​​
Danby Park CLO, Ltd.
​​Subordinated Note (effective yield 3.82%, maturity 10/21/2037) ​​
10/31/2024
​​​​5,150,000​​​​​4,402,993​​​​​1,627,788​​
Dryden 53 CLO, Ltd.
​​Income Note (effective yield 0.00%, maturity 1/15/2031)(12)​​
11/28/2017
​​​​7,684,999​​​​​936,162​​​​​38,294​​
Dryden 64 CLO, Ltd.
​​Subordinated Note (effective yield 0.00%, maturity 4/18/2031)(12)​​
5/11/2020
​​​​9,600,000​​​​​1,611,855​​​​​46,919​​
Dryden 68 CLO, Ltd.
​​Income Note (effective yield 0.00%, maturity 7/15/2035)(10)(12)​​
5/30/2019
​​​​14,080,000​​​​​6,359,846​​​​​1,830,356​​
Dryden 76 CLO, Ltd.
​​Subordinated Note (effective yield 18.29%, maturity 10/15/2037)(10)​​
5/14/2024
​​​​1,856,000​​​​​687,388​​​​​663,792​​
Dryden 78 CLO Ltd.
​​Subordinated Note (effective yield 12.20%, maturity 4/17/2037) ​​
7/31/2024
​​​​26,520,000​​​​​11,599,292​​​​​8,531,447​​
Dryden 85 CLO, Ltd.
​​Income Note (effective yield 22.51%, maturity 7/15/2037)(10)​​
9/17/2020
​​​​1,200,000​​​​​857,221​​​​​836,265​​
Dryden 90 CLO, Ltd.
​​Subordinated Note (effective yield 9.30%, maturity 11/15/2038)(10)​​
4/9/2024
​​​​18,873,000​​​​​16,354,000​​​​​11,818,308​​
Dryden 94 CLO, Ltd.
​​Income Note (effective yield 1.23%, maturity 10/15/2037)(10)​​
4/28/2022
​​​​19,425,000​​​​​10,242,229​​​​​5,981,234​​
Dryden 109 CLO, Ltd.
​​Subordinated Note (effective yield 20.56%, maturity 4/15/2038)(10)​​
2/15/2023
​​​​4,575,000​​​​​2,918,996​​​​​2,805,077​​
Eaton Vance CLO 2015-1, Ltd.
​​Subordinated Note (effective yield 0.00%, maturity 1/20/2030)(12)​​
6/5/2020
​​​​6,372,500​​​​​615,557​​​​​32,830​​
Eaton Vance CLO 2020-1, Ltd.
​​Subordinated Note (effective yield 5.46%, maturity 10/15/2037)(10)​​
8/8/2023
​​​​7,975,000​​​​​4,279,785​​​​​2,395,061​​
Eaton Vance CLO 2020-2, Ltd.
​​Subordinated Note (effective yield 4.33%, maturity 10/15/2037)(10)​​
9/16/2022
​​​​13,700,000​​​​​7,717,379​​​​​4,317,587​​
Invesco CLO 2022-2, Ltd.
​​Class Y Note (effective yield 58.14%, maturity 7/20/2035) ​​
8/14/2024
​​​​1,280,000​​​​​90,563​​​​​145,628​​
Lake George Park CLO, Ltd.
​​Income Note (effective yield 14.61%, maturity 4/15/2038)(10)​​
2/18/2025
​​​​20,850,000​​​​​16,302,309​​​​​13,783,696​​
Lake Shore MM CLO I Ltd.
​​Income Note (effective yield 0.00%, maturity 4/15/2033)(10)(12)​​
3/8/2019
​​​​14,550,000​​​​​9,296,070​​​​​3,155,818​​
Lodi Park CLO, Ltd.
​​Income Note (effective yield 6.51%, maturity 7/21/2036) ​​
11/13/2024
​​​​4,725,000​​​​​3,690,242​​​​​2,049,896​​
Lodi Park CLO, Ltd.
​​Subordinated Note (effective yield 6.51%, maturity 7/21/2036) ​​
11/13/2024
​​​​2,775,000​​​​​2,153,954​​​​​1,203,429​​
Madison Park Funding XX, Ltd.
​​Subordinated Note (effective yield 10.22%, maturity 10/27/2037) ​​
2/6/2025
​​​​35,450,000​​​​​8,230,585​​​​​3,381,986​​
Madison Park Funding XXI, Ltd.
​​Subordinated Note (effective yield 0.00%, maturity 10/15/2032)(11)​​
8/22/2016
​​​​6,462,500​​​​​148,111​​​​​174,488​​
Madison Park Funding XXII, Ltd.
​​Subordinated Note (effective yield 9.61%, maturity 1/15/2038) ​​
10/30/2018
​​​​11,731,082​​​​​5,714,994​​​​​3,438,821​​
Madison Park Funding XXXIV, Ltd.
​​Subordinated Note (effective yield 8.53%, maturity 10/16/2037) ​​
9/27/2022
​​​​12,825,000​​​​​5,983,687​​​​​2,976,755​​
Madison Park Funding XL, Ltd.
​​Subordinated Note (effective yield 0.00%, maturity 2/28/2047)(11)​​
6/2/2016
​​​​17,857,979​​​​​969,872​​​​​964,331​​
Madison Park Funding XL-R, Ltd.
​​Income Note (effective yield 11.93%, maturity 10/16/2038) ​​
9/5/2025
​​​​25,000,000​​​​​23,750,000​​​​​17,073,215​​
Madison Park Funding XLIV, Ltd.
​​Subordinated Note (effective yield 6.99%, maturity 7/16/2037) ​​
11/16/2018
​​​​9,919,821​​​​​4,100,045​​​​​1,751,233​​
Madison Park Funding XLVII, Ltd.
​​Subordinated Note (effective yield 3.89%, maturity 4/19/2037) ​​
4/29/2021
​​​​5,000,000​​​​​3,014,723​​​​​1,402,304​​
Madison Park Funding LXII, Ltd.
​​Subordinated Note (effective yield 10.60%, maturity 7/16/2038) ​​
7/27/2023
​​​​13,025,000​​​​​7,541,347​​​​​4,589,692​​
See accompanying notes to the consolidated financial statements
 
​ ​​
17
​

​
​FIRST HALF 2026 SHAREHOLDER LETTER AND SEMIANNUAL REPORT   |   Eagle Point Credit Company​
Eagle Point Credit Company & Subsidiaries
Consolidated Schedule of Investments
As of June 30, 2026
(expressed in U.S. dollars)
(Unaudited)
Issuer(1)
​​
Investment Description
​​
Acquisition
Date
(2)
​​
Principal
Amount /
Shares
​​
Cost
​​
Fair Value(3)
​
Collateralized Loan Obligation Equity – 97.81% of
Net Assets(3)(4)(8)(9) (continued)
​
Structured Finance (continued)
​​​​​​​​​​​​​​​​​​​​​​​​​
United States (continued)
​​​​​​​​​​​​​​​​​​​​​​​​​
Madison Park Funding LXIX, Ltd.
​​Subordinated Note (effective yield 11.92%, maturity 7/25/2037) ​​
5/22/2025
​​​$8,050,000​​​​$6,025,462​​​​$4,177,270​​
Meacham Park CLO, Ltd.
​​Subordinated Note (effective yield 8.82%, maturity 10/20/2037) ​​
1/24/2025
​​​​9,950,000​​​​​6,734,664​​​​​3,804,785​​
Muzinich & Co., Inc.
​​U.S. CLO Participation Share ​​
10/28/2021
​​​​200,006​​​​​—​​​​​3,281,293​​
Muzinich & Co., Inc.
​​Euro CLO Participation Share ​​
5/29/2026
​​​​200,000​​​​​—​​​​​—​​
Octagon 51, Ltd.
​​Income B Note (effective yield 0.58%, maturity 7/20/2034) ​​
4/16/2021
​​​​19,300,000​​​​​10,037,580​​​​​4,484,606​​
Octagon 58, Ltd.
​​Income Note (effective yield 7.53%, maturity 4/15/2038)(10)​​
4/21/2022
​​​​15,625,000​​​​​14,244,777​​​​​9,016,270​​
Octagon Investment Partners XIV, Ltd.
​​Income Note (effective yield 0.00%, maturity 7/15/2029)(10)(11)​​
6/6/2014
​​​​20,572,125​​​​​—​​​​​3,086​​
Octagon Investment Partners 26, Ltd.
​​Income Note (effective yield 0.00%, maturity 7/15/2030)(10)(12)​​
3/23/2016
​​​​13,750,000​​​​​1,616,495​​​​​62,900​​
Octagon Investment Partners 27, Ltd.
​​Income Note (effective yield 0.00%, maturity 7/15/2030)(10)(12)​​
5/25/2016
​​​​11,804,048​​​​​4,720​​​​​57,965​​
Octagon Investment Partners 29, Ltd.
​​Subordinated Note (effective yield 0.00%, maturity 7/18/2037)(10)(12)​​
5/5/2021
​​​​23,400,000​​​​​7,754,065​​​​​3,780,729​​
Octagon Investment Partners 37, Ltd.
​​Subordinated Note (effective yield 0.00%, maturity 7/25/2030)(11)​​
5/25/2021
​​​​1,550,000​​​​​3,410​​​​​233​​
Octagon Investment Partners 44, Ltd.
​​Income Note (effective yield 0.00%, maturity 10/15/2034)(10)(11)​​
6/19/2019
​​​​1,450,000​​​​​40,600​​​​​18,288​​
Octagon Investment Partners 45, Ltd.
​​Subordinated Note (effective yield 0.00%, maturity 4/15/2035)(12)​​
7/27/2023
​​​​18,155,000​​​​​7,942,335​​​​​1,209,887​​
Octagon Investment Partners 46, Ltd.
​​Income Note (effective yield 0.00%, maturity 7/15/2036)(10)(11)​​
6/26/2020
​​​​10,650,000​​​​​203,504​​​​​170,400​​
Octagon Investment Partners 48, Ltd.
​​Subordinated Note (effective yield 6.19%, maturity 1/15/2039)(10)​​
3/25/2022
​​​​13,875,000​​​​​7,764,036​​​​​4,459,394​​
Octagon Investment Partners 50, Ltd.
​​Income Note (effective yield 0.00%, maturity 1/15/2035)(10)(12)​​
10/6/2020
​​​​9,250,000​​​​​3,500,313​​​​​542,287​​
OFSI BSL VIII, Ltd.
​​Income Note (effective yield 0.00%, maturity 8/16/2029)(10)(11)​​
7/18/2017
​​​​7,719,320​​​​​490,849​​​​​385,966​​
RAD CLO 3, Ltd.
​​Subordinated Note (effective yield 8.95%, maturity 7/15/2037)(10)​​
9/30/2025
​​​​8,350,000​​​​​3,683,384​​​​​1,794,771​​
RAD CLO 27, Ltd.
​​Subordinated Note (effective yield 6.24%, maturity 1/15/2038) ​​
12/11/2024
​​​​10,800,000​​​​​9,381,157​​​​​5,172,369​​
Regatta VII Funding Ltd.
​​Class R1A Note (effective yield 62.13%, maturity 6/20/2034) ​​
10/1/2021
​​​​10,126,500​​​​​12,677​​​​​2,458​​
Regatta VII Funding Ltd.
​​Class R2 Note (effective yield 111.22%, maturity 6/20/2034) ​​
10/1/2021
​​​​10,126,500​​​​​86,153​​​​​22,115​​
Regatta XII Funding Ltd.
​​Class R1A Note (effective yield 36.42%, maturity 10/15/2037) ​​
12/12/2024
​​​​14,629,350​​​​​33,550​​​​​40,174​​
Regatta XII Funding Ltd.
​​Class R2 Note (effective yield 36.42%, maturity 10/15/2037) ​​
12/12/2024
​​​​14,629,350​​​​​301,945​​​​​361,559​​
Regatta XX Funding Ltd.
​​Income Note (effective yield 11.52%, maturity 1/15/2038)(10)​​
8/4/2021
​​​​11,000,000​​​​​6,726,151​​​​​4,672,885​​
Regatta XX Funding Ltd.
​​Subordinated Note (effective yield 11.52%, maturity 1/15/2038) ​​
3/4/2025
​​​​750,000​​​​​387,013​​​​​286,588​​
Regatta XXI Funding Ltd.
​​Subordinated Note (effective yield 8.31%, maturity 10/15/2037) ​​
6/10/2022
​​​​9,000,000​​​​​5,535,978​​​​​3,138,205​​
Regatta XXIV Funding Ltd.
​​Subordinated Note (effective yield 11.88%, maturity 1/20/2038) ​​
12/27/2024
​​​​5,800,000​​​​​3,200,820​​​​​2,153,921​​
Rockford Tower 2024-2 Ltd
​​Subordinated Note (effective yield 12.93%, maturity 10/20/2037) ​​
2/14/2025
​​​​11,050,000​​​​​8,142,523​​​​​4,841,658​​
Rockford Tower CLO 2022-3, Ltd.
​​Subordinated Note (effective yield 28.86%, maturity 7/20/2037)(10)​​
7/27/2023
​​​​3,600,000​​​​​1,493,796​​​​​1,312,414​​
Rockford Tower CLO 2023-1, Ltd.
​​Subordinated Note (effective yield 17.51%, maturity 3/15/2038)(10)​​
5/21/2024
​​​​7,280,000​​​​​5,106,676​​​​​3,818,076​​
Shackleton 2019-XIV CLO, Ltd.
​​Subordinated Note (effective yield 6.47%, maturity 7/20/2034) ​​
2/1/2024
​​​​5,525,000​​​​​3,238,028​​​​​1,961,068​​
Steele Creek CLO 2018-1, Ltd.
​​Income Note (effective yield 0.00%, maturity 4/15/2031)(10)(12)​​
3/28/2018
​​​​11,370,000​​​​​3,380,844​​​​​49,179​​
Steele Creek CLO 2019-1, Ltd.
​​Income Note (effective yield 0.00%, maturity 4/15/2032)(10)(12)​​
3/22/2019
​​​​8,500,000​​​​​3,518,639​​​​​51,727​​
Wellman Park CLO, Ltd.
​​Class M-1 Note (effective yield 41.92%, maturity 7/15/2037) ​​
9/20/2023
​​​​20,025,000​​​​​137,625​​​​​166,138​​
Wellman Park CLO, Ltd.
​​Class M-2 Note (effective yield 43.84%, maturity 7/15/2037) ​​
9/20/2023
​​​​24,205,000​​​​​502,312​​​​​462,902​​
Wind River 2013-2 CLO Ltd.
​​Income Note (effective yield 0.00%, maturity 10/18/2030)(10)(11)​​
6/6/2014
​​​​11,597,500​​​​​—​​​​​2,014​​
Wind River 2014-3 CLO Ltd.
​​Subordinated Note (effective yield 0.00%, maturity 10/22/2031)(12)​​
12/17/2014
​​​​11,000,000​​​​​1,100​​​​​1,654​​
Wind River 2017-1 CLO Ltd.
​​Income Note (effective yield 0.00%, maturity 4/18/2036)(10)(11)​​
2/2/2017
​​​​17,700,000​​​​​3,150,600​​​​​1,860,622​​
Wind River 2017-3 CLO Ltd.
​​Income Note (effective yield 0.00%, maturity 4/15/2035)(10)(12)​​
8/9/2017
​​​​23,940,000​​​​​10,530,755​​​​​3,766,432​​
Wind River 2018-1 CLO Ltd.
​​Income Note (effective yield 0.00%, maturity 7/15/2030)(10)(11)​​
6/22/2018
​​​​15,750,000​​​​​—​​​​​394,038​​
Wind River 2019-2 CLO Ltd.
​​Income Note (effective yield 0.00%, maturity 1/15/2035)(10)(11)​​
9/20/2019
​​​​13,470,000​​​​​2,357,250​​​​​1,212,300​​
Wind River 2022-2 CLO Ltd.
​​Income Note (effective yield 0.00%, maturity 7/20/2035)(10)(11)​​
6/3/2022
​​​​8,950,000​​​​​812,660​​​​​402,750​​
Zais CLO 7, Limited
​​Income Note (effective yield 0.00%, maturity 4/15/2030)(12)​​
9/11/2017
​​​​12,777,500​​​​​1,278​​​​​1,917​​
Total United States
​​​​​​​​​​​​​​​​772,035,005​​​​​504,759,195​​
Various
​​​​​​​​​​​​​​​​​​​​​​​​​
Aqueduct European CLO 5-2020 DAC
​​Subordinated Note (effective yield 35.50%, maturity 7/15/2039)(13)​​
6/26/2026
​​​​14,775,000​​​​​4,238,598​​​​​4,252,740​​
Aqueduct European CLO 5-2020 DAC
​​Class M-1 Note (effective yield 0.57%, maturity 4/20/2034)(10)(13)​​
12/27/2024
​​​​13,158,000​​​​​8,401,166​​​​​5,884,056​​
Aqueduct European CLO 5-2020 DAC
​​Class M-2 Note (effective yield 0.57%, maturity 4/20/2034)(13)​​
12/27/2024
​​​​13,304,000​​​​​7,962,634​​​​​5,880,062​​
Aurium CLO XIII DAC
​​Subordinated Note (effective yield 7.88%, maturity 4/15/2038)(13)​​
1/30/2025
​​​​3,277,500​​​​​3,079,405​​​​​2,578,554​​
Avoca CLO XXXI DAC
​​Subordinated Note (effective yield 6.90%, maturity 7/15/2038)(13)​​
2/12/2025
​​​​2,830,000​​​​​2,247,505​​​​​1,986,162​​
BBAM European CLO II DAC
​​Subordinated Note (effective yield 12.57%, maturity 10/15/2034)(10)(13)​​
11/5/2021
​​​​1,000,000​​​​​861,575​​​​​538,328​​
Blackrock European CLO XV DAC
​​Subordinated Note (effective yield 5.85%, maturity 1/28/2038)(13)​​
11/29/2024
​​​​3,250,000​​​​​2,968,455​​​​​2,347,679​​
Blackstone Blackthorn Park DAC
​​Subordinated Note (effective yield 18.90%, maturity 10/15/2039)(10)(13)​​
6/26/2026
​​​​15,500,000​​​​​13,378,583​​​​​13,423,223​​
CIFC European Funding VI DAC
​​Subordinated Note (effective yield 12.02%, maturity 10/15/2037)(13)​​
7/17/2024
​​​​5,000,000​​​​​4,259,511​​​​​3,883,139​​
Clonkeen Park CLO DAC
​​Subordinated Note (effective yield 8.37%, maturity 10/15/2037)(10)(13)​​
8/16/2024
​​​​33,291,000​​​​​23,413,845​​​​​17,683,125​​
CVC Cordatus Loan Fund XXXIII DAC
​​Subordinated Note (effective yield 10.25%, maturity 3/24/2038)(13)​​
10/18/2024
​​​​5,417,000​​​​​4,781,001​​​​​4,261,607​​
Dryden 88 Euro CLO 2020 DAC
​​Subordinated Note (effective yield 0.00%, maturity 7/20/2034)(12)(13)​​
4/23/2021
​​​​600,000​​​​​374,024​​​​​168,038​​
Dryden 125 Euro CLO 2024 DAC
​​Subordinated Note (effective yield 15.43%, maturity 11/15/2038)(10)(13)​​
10/3/2025
​​​​9,950,000​​​​​9,282,242​​​​​8,064,940​​
See accompanying notes to the consolidated financial statements
 
​ ​​
18
​

​
​FIRST HALF 2026 SHAREHOLDER LETTER AND SEMIANNUAL REPORT   |   Eagle Point Credit Company​
Eagle Point Credit Company & Subsidiaries
Consolidated Schedule of Investments
As of June 30, 2026
(expressed in U.S. dollars)
(Unaudited)
Issuer(1)
​​
Investment Description
​​
Acquisition
Date
(2)
​​
Principal
Amount /
Shares
​​
Cost
​​
Fair Value(3)
​
Collateralized Loan Obligation Equity – 97.81% of
Net Assets(3)(4)(8)(9) (continued)
​
Structured Finance (continued)
​​​​​​​​​​​​​​​​​​​​​​​​​
Various (continued)
​​​​​​​​​​​​​​​​​​​​​​​​​
Henley CLO XI DAC
​​Subordinated Note (effective yield 11.13%, maturity 4/25/2039)(13)​​
2/10/2025
​​​$1,500,000​​​​$1,451,987​​​​$1,394,168​​
OCP Euro CLO 2019-3 DAC
​​Subordinated Note (effective yield 1.10%, maturity 4/20/2033)(13)​​
5/26/2021
​​​​1,500,000​​​​​852,733​​​​​542,319​​
OCP Euro CLO 2022-6 DAC
​​Subordinated Note (effective yield 8.57%, maturity 7/20/2036)(13)​​
4/23/2024
​​​​1,125,000​​​​​916,277​​​​​792,326​​
OCP Euro CLO 2024-10 DAC
​​Subordinated Note (effective yield 3.64%, maturity 10/20/2037)(13)​​
7/10/2024
​​​​5,000,000​​​​​4,142,963​​​​​3,008,384​​
Sculptor European CLO XII DAC
​​Subordinated Note (effective yield 12.33%, maturity 1/15/2038)(13)​​
11/27/2024
​​​​7,050,000​​​​​5,578,893​​​​​4,932,854​​
Total Various
​​​​​​​​​​​​​​​​98,191,397​​​​​81,621,704​​
Total Collateralized Loan Obligation Equity
​​​​​​​​​​​​​​​​870,226,402​​​​​586,380,899​​
Loan Accumulation Facilities – 5.17% of Net Assets(4)(9)(15)
​
Structured Finance
​​​​​​​​​​​​​​​​​​​​​​​​​
United States
​​​​​​​​​​​​​​​​​​​​​​​​​
Steamboat LV Ltd.
​​Loan Accumulation Facility ​​
6/16/2025
​​​​9,305,250​​​​​9,305,250​​​​​9,332,938​​
Steamboat LVI Ltd.
​​Loan Accumulation Facility ​​
5/27/2025
​​​​3,324,900​​​​​3,324,900​​​​​3,286,334​​
Steamboat LVIII Ltd.
​​Loan Accumulation Facility ​​
6/4/2025
​​​​3,077,000​​​​​3,077,000​​​​​3,149,945​​
Steamboat LIX Ltd.
​​Loan Accumulation Facility ​​
6/23/2025
​​​​5,961,750​​​​​5,961,750​​​​​6,241,785​​
Steamboat LXII Ltd.
​​Loan Accumulation Facility ​​
10/8/2025
​​​​6,152,675​​​​​6,152,675​​​​​6,157,063​​
Steamboat LXIII Ltd.
​​Loan Accumulation Facility ​​
12/17/2025
​​​​2,831,950​​​​​2,831,950​​​​​2,843,589​​
Total Loan Accumulation Facilities
​​​​​​​​​​​​​​​​30,653,525​​​​​31,011,654​​
Asset Backed Securities – 10.11% of Net Assets(4)
​
Structured Finance
​​​​​​​​​​​​​​​​​​​​​​​​​
United States
​​​​​​​​​​​​​​​​​​​​​​​​​
Carmax Select Receivables Trust 2025-B
​​Class R Note (effective yield 26.02%, maturity 9/15/2032)(8)​​
9/17/2025
​​​​3,580​​​​​2,531,418​​​​​2,540,900​​
Carvana Auto Receivables Trust 2024-P2
​​Class R Note (effective yield 12.83%, maturity 6/10/2031)(8)​​
6/4/2024
​​​​23,083​​​​​4,438,142​​​​​4,308,165​​
Carvana Auto Receivables Trust 2024-P3
​​Class R Note (effective yield 9.98%, maturity 9/10/2032)(8)​​
9/10/2024
​​​​17,730​​​​​6,033,958​​​​​5,837,443​​
Carvana Auto Receivables Trust 2024-P4
​​Class R Note (effective yield 13.50%, maturity 12/10/2032)(8)​​
12/10/2024
​​​​15,578​​​​​4,732,705​​​​​4,942,470​​
Carvana Auto Receivables Trust 2025-N1
​​Class EX5 Note (effective yield 19.48%, maturity 8/10/2032)(8)​​
2/11/2025
​​​​12,500​​​​​2,227,808​​​​​2,233,416​​
Carvana Auto Receivables Trust 2025-P1
​​Class R Note (effective yield 9.99%, maturity 3/10/2033)(8)​​
3/11/2025
​​​​14,850​​​​​6,011,158​​​​​5,600,753​​
Carvana Auto Receivables Trust 2025-P3
​​Class R Note (effective yield 15.78%, maturity 9/12/2033)(8)​​
9/16/2025
​​​​16,180​​​​​10,199,886​​​​​10,097,515​​
Carvana Auto Receivables Trust 2025-P4
​​Class R Note (effective yield 20.14%, maturity 11/10/2033)(8)​​
11/18/2025
​​​​9,902​​​​​4,932,381​​​​​4,909,076​​
Chase Auto Owner Trust 2024-4
​​Class R1 Note (effective yield 9.77%, maturity 11/25/2031)(8)​​
7/25/2024
​​​​5,000​​​​​1,220,758​​​​​1,118,083​​
Chase Auto Owner Trust 2025-1
​​Class R1 Note (effective yield 13.86%, maturity 11/26/2032)(8)​​
7/24/2025
​​​​25,000​​​​​4,150,716​​​​​4,144,437​​
Chase Auto Owner Trust 2025-2
​​Class R1 Note (effective yield 22.26%, maturity 2/25/2033)(8)​​
10/17/2025
​​​​20,270​​​​​3,167,858​​​​​3,131,560​​
GoodLeap Home Improvement Solutions Trust 2025-2
​​Class R Note (effective yield 5.71%, maturity 6/20/2049)(8)​​
6/9/2025
​​​​1,184,151​​​​​2,150,567​​​​​1,800,299​​
Mercury Financial Credit Card Master Trust
Series 2024-VFN1
​​
Class B Note, 12.20% (1M SOFR + 8.50%, due 1/20/2028)(6)(9)(17)​
​​
9/20/2024
​​​​9,942,405​​​​​9,942,405​​​​​9,956,130​​
Total Asset Backed Securities
​​​​​​​​​​​​​​​​61,739,760​​​​​60,620,247​​
Collateralized Fund Obligation Equity – 8.27% of Net Assets(3)(4)(8)(9)​
​
Structured Finance
​​​​​​​​​​​​​​​​​​​​​​​​​
United States
​​​​​​​​​​​​​​​​​​​​​​​​​
ALP CFO 2024, L.P.
​​Subordinated Note (effective yield 25.18%, maturity 10/15/2036) ​​
10/21/2024
​​​​16,286,000​​​​​16,286,000​​​​​11,587,706​​
ALP CFO 2025, L.P.
​​Subordinated Note (effective yield 30.60%, maturity 7/15/2037) ​​
7/30/2025
​​​​21,671,000​​​​​21,671,000​​​​​19,113,720​​
Coller Private Equity Backed Notes & Loans
II-A L.P.
​​Preferred Equity (effective yield 21.33%, maturity 4/30/2037)(17)​​
7/21/2025
​​​​9,459,791​​​​​9,459,791​​​​​8,271,043​​
Glendower Capital Secondaries CFO, LLC
​​Subordinated Loan (effective yield 10.35%, maturity 7/13/2038) ​​
7/13/2023
​​​​2,203,689​​​​​2,203,689​​​​​980,823​​
StepStone Private Equity LP Secondary Opportunities Ltd.
​​Subordinated Note (effective yield 17.03%, maturity 12/28/2035)(17)​​
7/3/2024
​​​​14,250,803​​​​​14,250,803​​​​​9,651,536​​
Total Collateralized Fund Obligation Equity
​​​​​​​​​​​​​​​​63,871,283​​​​​49,604,828​​
See accompanying notes to the consolidated financial statements
 
​ ​​
19
​

​
​FIRST HALF 2026 SHAREHOLDER LETTER AND SEMIANNUAL REPORT   |   Eagle Point Credit Company​
Eagle Point Credit Company & Subsidiaries
Consolidated Schedule of Investments
As of June 30, 2026
(expressed in U.S. dollars)
(Unaudited)
Issuer(1)
​​
Investment Description
​​
Acquisition
Date
(2)
​​
Principal
Amount /
Shares
​​
Cost
​​
Fair Value(3)
​
Equity Securities – 15.24% of Net Assets
​
Banking
​​​​​​​​​​​​​​​​​​​​​​​​​
Various
​​​​​​​​​​​​​​​​​​​​​​​​​
Steamboat Credit Opportunities I LLC
​​
Common Units(4)(17)(19)​
​​
2/3/2026
​​​$67,025,000​​​​$79,346,041​​​​$77,010,727​​
Financial Services
​​​​​​​​​​​​​​​​​​​​​​​​​
United States
​​​​​​​​​​​​​​​​​​​​​​​​​
Delta Financial Holdings LLC
​​
Common Units(4)(9)(18)(19)​
​​
7/19/2023
​​​​1​​​​​1,147​​​​​574​​
Delta Leasing SPV III, LLC
​​
Common Equity(4)(9)(18)(19)​
​​
7/19/2023
​​​​18​​​​​18​​​​​589,867​​
Horizon Technology Finance Corporation
​​Common Equity ​​
11/12/2025
​​​​13,277​​​​​94,532​​​​​62,800​​
Pasadena Private Lending, Inc.
​​
Common Equity, Class A-2(4)(9)(18)​
​​
12/18/2025
​​​​13,909​​​​​129,945​​​​​148,061​​
Senior Credit Corp 2022 LLC
​​Common Equity(4)(19)​​
1/30/2023
​​​​2,950,684​​​​​2,950,684​​​​​3,112,676​​
Total Financial Services
​​​​​​​​​​​​​​​$3,176,326​​​​$3,913,978​​
Oil & Gas
​​​​​​​​​​​​​​​​​​​​​​​​​
United States
​​​​​​​​​​​​​​​​​​​​​​​​​
McDermott International Ltd
​​Common Equity(18)​​
12/4/2025
​​​​743​​​​​—​​​​​16,346​​
McDermott International Ltd
​​Common Equity(4)(18)​​
12/31/2020
​​​​1,951​​​​​121,936​​​​​9,755​​
Total Oil & Gas
​​​​​​​​​​​​​​​​121,936​​​​​26,101​​
Structured Finance
​​​​​​​​​​​​​​​​​​​​​​​​​
United States
​​​​​​​​​​​​​​​​​​​​​​​​​
1988 Strategic CLO Equity Fund I, LP
​​Limited Partnership Interest(4)​​
1/22/2026
​​​​5,998,099​​​​​5,998,062​​​​​5,998,099​​
Various
​​​​​​​​​​​​​​​​​​​​​​​​​
1988 CLO LP, Series R-1
​​Limited Partnership Interest(4)(13)​​
2/13/2026
​​​​3,870,968​​​​​4,537,978​​​​​4,417,294​​
Total Structured Finance
​​​​​​​​​​​​​​​​10,536,040​​​​​10,415,393​​
Total Equity Securities
​​​​​​​​​​​​​​​​93,180,343​​​​​91,366,199​​
Loans and Notes – 25.11% of Net Assets
​
Entertainment
​​​​​​​​​​​​​​​​​​​​​​​​​
United States
​​​​​​​​​​​​​​​​​​​​​​​​​
SI Tickets, Inc.
​​
Senior Secured Loan, 10.00% (due 8/30/2026)(4)(7)(9)(16)​
​​
11/12/2025
​​​​198,260​​​​​198,260​​​​​828,330​​
Financial Services
​​​​​​​​​​​​​​​​​​​​​​​​​
United States
​​​​​​​​​​​​​​​​​​​​​​​​​
BSD Capital Inc.
​​
Senior Unsecured Note, 6.34% (3M SOFR + 2.66%, due 10/31/2027)(4)(6)(9)​
​​
1/16/2025
​​​​10,726,000​​​​​9,766,359​​​​​9,916,219​​
Delta Leasing SPV III, LLC
​​
Senior Secured Note, 13.00% (due 7/18/2030)(4)(7)(9)(16)(17)(19)​
​​
7/19/2023
​​​​12,183,446​​​​​12,183,143​​​​​12,183,446​​
Horizon Technology Finance Corporation
​​
Convertible Senior Unsecured Note, 5.50% (due 9/4/2030)(4)(9)(16)​
​​
9/4/2025
​​​​3,310,670​​​​​3,053,786​​​​​3,009,565​​
Pasadena Private Lending, Inc.
​​
Senior Secured Loan, 13.48% (3M SOFR + 9.75%, due 1/31/2031)(4)(6)(9)(17)​
​​
12/18/2025
​​​​7,102,100​​​​​6,743,014​​​​​6,844,649​​
Senior Credit Corp 2022 LLC
​​
Senior Unsecured Note, 8.50% (due 12/5/2028)(4)(16)(19)​
​​
1/30/2023
​​​​6,884,929​​​​​6,884,929​​​​​6,884,929​​
Total United States
​​​​​​​​​​​​​​​​38,631,231​​​​​38,838,808​​
Total Financial Services
​​​​​​​​​​​​​​​​38,631,231​​​​​38,838,808​​
Infrastructure
​​​​​​​​​​​​​​​​​​​​​​​​​
United States
​​​​​​​​​​​​​​​​​​​​​​​​​
Heritage Energy Holdings, LLC
​​
Senior Secured Loan, 15.00% (due 6/30/2027)(4)(7)(9)(16)​
​​
12/31/2025
​​​​5,817,905​​​​​5,662,357​​​​​6,842,438​​
Integrated Modular Data Centers, LLC
​​
Senior Secured Loan, 11.00% (due 10/19/2026)(4)(7)(9)(16)​
​​
9/22/2025
​​​​5,909,577​​​​​5,909,577​​​​​6,736,918​​
Micro Parent, LLC
​​
Senior Secured Loan, 13.00% (due 4/29/2031)(4)(9)(16)(17)​
​​
4/27/2026
​​​​2,561,237​​​​​1,974,530​​​​​1,996,899​​
Nexus Apex Holdings, LLC
​​
Senior Secured Loan, Tranche B, 14.73% (3M SOFR + 11.00%, due 2/28/2029)(4)(6)(7)(9)(20)​
​​
2/26/2026
​​​​74,083,948​​​​​72,810,908​​​​​94,308,868​​
Total United States
​​​​​​​​​​​​​​​​86,357,372​​​​​109,885,123​​
Total Infrastructure
​​​​​​​​​​​​​​​​86,357,372​​​​​109,885,123​​
Structured Finance
​​​​​​​​​​​​​​​​​​​​​​​​​
United States
​​​​​​​​​​​​​​​​​​​​​​​​​
Glendower Capital Secondaries CFO, LLC
​​
Senior Secured CFO Debt, Class C Loan, 14.50% (due 7/13/2038)(4)(9)(16)​
​​
7/13/2023
​​​​966,685​​​​​957,018​​​​​979,271​​
Total Loans and Notes
​​​​​​​​​​​​​​​​126,143,881​​​​​150,531,532​​
Preferred Stock – 1.42% of Net Assets(3)(4)(9)
​
Financial Services
​​​​​​​​​​​​​​​​​​​​​​​​​
United States
​​​​​​​​​​​​​​​​​​​​​​​​​
Delta Financial Holdings LLC
​​Preferred Units(18)(19)​​
7/19/2023
​​​​252​​​​​251,801​​​​​251,836​​
NCS SPV LLC
​​Preferred Stock, 14.00%(16)(17)​​
12/24/2025
​​​​4,184​​​​​4,183,730​​​​​4,183,730​​
NCS SPV LLC
​​Preferred Stock(17)​​
12/24/2025
​​​​—​​​​​42​​​​​42​​
Pasadena Private Lending, Inc.
​​Preferred Stock, Class D, 15.00% (due 4/20/2031)(7)(16)​​
10/17/2025
​​​​2,536​​​​​2,353,665​​​​​2,402,027​​
Pasadena Private Lending, Inc.
​​Preferred Stock, Class C-2, 10.00% (due 12/22/2031)(7)(16)​​
12/18/2025
​​​​13,909​​​​​482,051​​​​​460,666​​
Total United States
​​​​​​​​​​​​​​​​7,271,289​​​​​7,298,301​​
Total Financial Services
​​​​​​​​​​​​​​​​7,271,289​​​​​7,298,301​​
See accompanying notes to the consolidated financial statements
 
​ ​​
20
​

​
​FIRST HALF 2026 SHAREHOLDER LETTER AND SEMIANNUAL REPORT   |   Eagle Point Credit Company​
Eagle Point Credit Company & Subsidiaries
Consolidated Schedule of Investments
As of June 30, 2026
(expressed in U.S. dollars)
(Unaudited)
Issuer(1)
​​
Investment Description
​​
Acquisition
Date
(2)
​​
Principal
Amount /
Shares
​​
Cost
​​
Fair Value(3)
​
Preferred Stock – 1.42% of Net Assets(3)(4)(9) (continued)
​
Infrastructure
​​​​​​​​​​​​​​​​​​​​​​​​​
United States
​​​​​​​​​​​​​​​​​​​​​​​​​
Micro Parent, LLC
​​Senior Preferred Equity(18)​​
4/28/2026
​​​$1,635,776​​​​$1,153,444​​​​$1,199,535​​
Total Preferred Stock
​​​​​​​​​​​​​​​​8,424,733​​​​​8,497,836​​
Rated Feeder Fund Equity – 0.29% of Net Assets(4)(8)(9)
​
Structured Finance
​​​​​​​​​​​​​​​​​​​​​​​​​
United States
​​​​​​​​​​​​​​​​​​​​​​​​​
CVC Structured Solutions 2, LLC
​​Subordinated Loan (effective yield 26.52%, maturity 9/3/2040)(17)​​
9/2/2025
​​​​2,000,000​​​​​2,000,000​​​​​1,730,398​​
Total Rated Feeder Fund Equity
​​​​​​​​​​​​​​​​2,000,000​​​​​1,730,398​​
Regulatory Capital Relief Securities – 4.00% of Net Assets(4)(9)
​
Banking
​​​​​​​​​​​​​​​​​​​​​​​​​
France
​​​​​​​​​​​​​​​​​​​​​​​​​
BNP Paribas, Marianne
​​Credit Linked Note, 11.65% (3M EURIBOR + 9.50%, due 10/12/2032)(6)(13)​​
9/22/2023
​​​​378,786​​​​​403,275​​​​​433,172​​
PSA Banque France, AASFL 2022-1
​​
Credit Linked Note – Class B, 14.47% (1M EURIBOR + 12.50%, due
12/27/2030)
(6)(13)
​​
11/22/2022
​​​​664,002​​​​​683,889​​​​​760,717​​
Total France
​​​​​​​​​​​​​​​​1,087,164​​​​​1,193,889​​
United States
​​​​​​​​​​​​​​​​​​​​​​​​​
Deutsche Bank AG, LOFT 2022-1
​​
Credit Linked Note – Class C, 22.76% (CD 3M SOFR + 19.00%, due
2/28/2032)
(6)
​​
8/22/2022
​​​​8,371,412​​​​​8,038,717​​​​​8,554,140​​
Various
​​​​​​​​​​​​​​​​​​​​​​​​​
Deutsche Bank AG, CRAFT 2022-1
​​Credit Linked Note, 15.64% (SOFR + 12.00%, due 4/21/2032)(6)​​
10/26/2022
​​​​2,720,191​​​​​2,619,730​​​​​2,826,680​​
Deutsche Bank AG, TRAFIN 2023-1
​​
Credit Linked Note – Class A, 13.69% (CD 3M SOFR + 10.00%, due 6/1/2029)(6)
​​
11/27/2023
​​​​2,375,000​​​​​2,375,000​​​​​2,413,643​​
HSBC Continental Europe, Pixel 2022-1
​​
Junior Credit Linked Note, 15.00% (3M EURIBOR + 12.88%, due
12/29/2029)
(6)(13)
​​
12/16/2022
​​​​2,817,321​​​​​2,883,115​​​​​3,387,835​​
Manitoulin USD Ltd., Muskoka
Series 2022-1
​​
Guarantee Linked Note – Class E, 13.82% (CD 3M SOFR + 10.25%, due
11/10/2027)
(6)
​​
10/12/2022
​​​​22,137​​​​​22,137​​​​​22,176​​
Standard Chartered Bank, Chakra 7
​​Class B Note, 14.67% (CD 3M SOFR + 11.00%, due 4/25/2031)(6)​​
10/7/2022
​​​​5,536,923​​​​​5,536,923​​​​​5,579,928​​
Total Various
​​​​​​​​​​​​​​​​13,436,905​​​​​14,230,262​​
Total Regulatory Capital Relief Securities
​​​​​​​​​​​​​​​​22,562,786​​​​​23,978,291​​
Royalties – 0.07% of Net Assets(4)(9)
​​​​​​​​​​​​​​​​​​​​​​​​​
Infrastructure
​​​​​​​​​​​​​​​​​​​​​​​​​
United States
​​​​​​​​​​​​​​​​​​​​​​​​​
Micro Parent, LLC
​​Royalty Fee ​​
5/12/2026
​​​​9,364,220​​​​​422,834​​​​​433,842​​
Total Royalties
​​​​​​​​​​​​​​​​422,834​​​​​433,842​​
Warrants – 0.14% of Net Assets(4)(9)(18)
​​​​​​​​​​​​​​​​​​​​​​​​​
Financial Services
​​​​​​​​​​​​​​​​​​​​​​​​​
United States
​​​​​​​​​​​​​​​​​​​​​​​​​
Pasadena Private Lending, Inc.
​​Warrants ​​
10/20/2025
​​​​32,342​​​​​302,155​​​​​344,119​​
Infrastructure
​​​​​​​​​​​​​​​​​​​​​​​​​
United States
​​​​​​​​​​​​​​​​​​​​​​​​​
Heritage Energy Holdings, LLC
​​Warrants ​​
12/31/2025
​​​​2,707,000​​​​​69,759​​​​​70,382​​
Micro Parent, LLC
​​Common Unit Warrant ​​
4/28/2026
​​​​669,293​​​​​327,292​​​​​289,015​​
Micro Parent, LLC
​​Series C Unit Warrant ​​
4/28/2026
​​​​388,476​​​​​122,324​​​​​108,018​​
Total United States
​​​​​​​​​​​​​​​​519,375​​​​​467,415​​
Total Infrastructure
​​​​​​​​​​​​​​​​519,375​​​​​467,415​​
Total Warrants
​​​​​​​​​​​​​​​​821,530​​​​​811,534​​
Total investments, at fair value June 30, 2026
​​​​​​​​​​​​​​​$1,283,085,263​​​​$1,005,420,456​​
Unfunded Loan Commitments – (0.02)% of Net Assets
​
Financial Services
​​​​​​​​​​​​​​​​​​​​​​​​​
United States
​​​​​​​​​​​​​​​​​​​​​​​​​
Pasadena Private Lending, Inc.
​​
Senior Secured Loan, 13.48% (3M SOFR + 9.75%, due 1/31/2031)(4)(6)(9)(17)​
​​
12/18/2025
​​​​2,693,900​​​​​—​​​​​(97,654)​​
Total Unfunded Loan Commitments
​​​​​​​​​​​​​​​​—​​​​​(97,654)​​
See accompanying notes to the consolidated financial statements
 
​ ​​
21
​

​
​FIRST HALF 2026 SHAREHOLDER LETTER AND SEMIANNUAL REPORT   |   Eagle Point Credit Company​
Eagle Point Credit Company & Subsidiaries
Consolidated Schedule of Investments
As of June 30, 2026
(expressed in U.S. dollars)
(Unaudited)
Issuer(1)
​​
Investment Description
​​
Acquisition
Date
(2)
​​
Principal
Amount /
Shares
​​
Cost
​​
Fair Value(3)
​
Term Preferred Shares and Unsecured Notes at Fair Value – (41.68)% of Net Assets(21)
​
5.375% Unsecured Notes due 2029
​​Unsecured Note ​​​​​​$(93,250,000)​​​​$(89,072,400)​​​​$(89,072,400)​​
7.75% Unsecured Notes due 2030
​​Unsecured Note ​​​​​​​(115,000,000)​​​​​(115,368,000)​​​​​(115,368,000)​​
6.50% Series C Term Preferred Shares due 2031
​​Preferred Shares ​​​​​​​(45,504,750)​​​​​(45,431,942)​​​​​(45,431,942)​​
Total Term Preferred Shares and Unsecured Notes at Fair Value
​​​​​​​​​​​​​​​
​
(249,872,342)
​​​​
​
(249,872,342)
​​
Total liabilities, at fair value June 30, 2026
​​​​​​​​​​​​​​​$(249,872,342)​​​​$(249,969,996)​​
Net assets above (below) fair value of investments and liabilities at fair value
​​​​​​​​​​​​​​​​​​​​​
​
(155,967,528)
​​
Net Assets as of June 30, 2026
​​​​​​​​​​​​​​​​​​​​​$599,482,932​​
​
See accompanying notes to the consolidated financial statements
 
​ ​​
22
​

​
​FIRST HALF 2026 SHAREHOLDER LETTER AND SEMIANNUAL REPORT   |   Eagle Point Credit Company​
Eagle Point Credit Company & Subsidiaries
Consolidated Schedule of Investments
As of June 30, 2026
(expressed in U.S. dollars)
(Unaudited)
​
Footnotes to the Consolidated Schedule of Investments:
​(1)​​
Unless otherwise noted, the Company is not affiliated with, nor does it “control” ​(as such term is defined in the Investment Company Act of 1940 (the “1940 Act”)), any of the issuers listed. In general, under the 1940 Act, the Company would be presumed to “control” issuers if it owned 25% or more of its voting securities.
​
​(2)​​
Acquisition date represents the initial date of purchase or the date the investment was contributed to the Company at the time of the Company’s formation.
​
​(3)​​
Fair value is determined by the Adviser in accordance with written valuation policies and procedures, subject to oversight by the Company’s Trustees, in accordance with Rule 2a-5 under the 1940 Act.
​
​(4)​​
Securities exempt from registration under the Securities Act of 1933, and are deemed to be “restricted securities”. As of June 30, 2026, the aggregate fair value of these securities is $1,005.3 million, or 167.7% of the Company’s net assets.
​
​(5)​​
Country represents the principal country of risk where the investment has exposure. Where “various” is noted, the security has exposure to more than one country, which may represent countries in North America, Europe, Latin America and Asia.
​
​(6)​​
Variable rate investment. Interest rate shown reflects the rate in effect at the reporting date. Investment description includes the reference rate and spread.
​
​(7)​​
As of June 30, 2026, the investment includes interest income capitalized as additional investment principal, referred to as “PIK” interest. The PIK interest rate represents the interest rate at payment date when PIK interest is received. See Note 2 “Summary of Significant Accounting Policies” for further discussion.
​
​(8)​​
Collateralized loan obligation (“CLO”) equity, Collateralized Fund Obligations equity, Rated Feeder Equity and Asset Backed Security residual tranches are entitled to recurring distributions which are generally equal to the remaining cash flow of payments made by underlying assets less contractual payments to debt holders and fund expenses. The effective yield is estimated based on the current projection of the amount and timing of these recurring distributions in addition to the estimated amount of terminal principal payment. The effective yield and investment cost may ultimately not be realized. As of June 30, 2026, the Company’s weighted average effective yield on its aggregate CLO equity positions based on current amortized cost, was 8.89%. When excluding called CLOs the Company’s weighted average effective yield on its CLO equity positions was 9.00%.
​
​(9)​​Classified as Level III investment. See Note 3 “Valuation of Investments” for further discussion. ​
​(10)​​Fair value includes the Company’s interest in fee rebates on CLO subordinated and income notes. ​
​(11)​​
As of June 30, 2026, the investment has been called. Expected value of residual distributions, once received, is anticipated to be recognized as return of capital, pending any remaining amortized cost, and/or realized gain for any amounts received in excess of such amortized cost.
​
​(12)​​
As of June 30, 2026, the effective yield has been estimated to be 0%. The aggregate projected amount of future recurring distributions and terminal principal payment is less than the amortized investment cost. Future recurring distributions, once received, will be recognized solely as return of capital until the aggregate projected amount of future recurring distributions and terminal principal payment exceeds the amortized investment cost.
​
​(13)​​Investment principal amount is denominated in EUR. ​
​(14)​​Investment principal amount is denominated in GBP. ​
​(15)​​
Loan accumulation facilities are financing structures intended to aggregate loans that may be used to form the basis of a CLO vehicle.
​
​(16)​​Fixed rate investment. ​
​(17)​​
This investment has an unfunded commitment as of June 30, 2026. See Note 10 “Commitments and Contingencies” for further discussion.
​
​(18)​​The following investment is not an income producing security. ​
​(19)​​
The following is an affiliated investment as defined under the 1940 Act, which represents investments in which the Company and other funds managed by the Adviser or its affiliates owns 5% or more of the outstanding voting securities under common ownership or control. See Note 5 “Related Party Transactions” for further discussion.
​
​(20)​​
The Company sold a participation interest in the following investment that did not qualify as a “sale” in accordance with U.S. generally accepted accounting principles. The Company recorded a liability titled “Investments sold under participation agreements, at fair value”, in the accompanying Consolidated Statement of Assets and Liabilities. As of June 30, 2026, this liability bears an interest rate of 12.55%.
​
​(21)​​
The Company has accounted for its unsecured notes and mandatorily redeemable preferred shares utilizing the fair value option election under ASC Topic 825. Accordingly, the aforementioned notes and preferred shares are carried at their fair value. See Note 2 “Summary of Significant Accounting Policies” for further discussion.
​
​​​​
Reference Key:
​​
​CD​​−​​Compounded Daily ​
​EUR​​−​​Euro ​
​EURIBOR​​−​​Euro Interbank Offered Rate ​
​SOFR​​−​​Secured Overnight Financing Rate ​
​USD​​−​​United States Dollar ​
​GBP​​−​​Great Britain Pound​
See accompanying notes to the consolidated financial statements
 
​ ​​
23
​

​
​FIRST HALF 2026 SHAREHOLDER LETTER AND SEMIANNUAL REPORT   |   Eagle Point Credit Company​
Eagle Point Credit Company & Subsidiaries
Consolidated Schedule of Investments
As of June 30, 2026
(expressed in U.S. dollars)
(Unaudited)
Forward Currency Contracts, at Fair Value(1)
​
Currency Purchased
​​
Currency Sold
​​
Counterparty
​​
Acquisition
Date
​​
Settlement
Date
​​
Fair Value
​
​Unrealized appreciation on forward currency contracts​
​USD ​​​​150,000,590​​​​​EUR​​​​​127,488,829​​​
Barclays Bank PLC
​​​​4/28/2026​​​​​7/31/2026​​​​$4,233,050​​
​USD ​​​​12,466,250​​​​​GBP​​​​​9,221,027​​​
Barclays Bank PLC
​​​​4/28/2026​​​​​7/31/2026​​​​​244,600​​
​USD ​​​​2,729,181​​​​​EUR​​​​​2,350,874​​​
Barclays Bank PLC
​​​​5/21/2026​​​​​7/31/2026​​​​​41,250​​
​USD ​​​​2,036,874​​​​​EUR​​​​​1,749,000​​​
Barclays Bank PLC
​​​​6/4/2026​​​​​7/31/2026​​​​​37,110​​
​USD ​​​​767,172​​​​​EUR​​​​​651,210​​​
Barclays Bank PLC
​​​​5/12/2026​​​​​7/31/2026​​​​​22,595​​
​USD ​​​​2,679,650​​​​​EUR​​​​​2,332,000​​​
Barclays Bank PLC
​​​​6/18/2026​​​​​7/31/2026​​​​​13,300​​
​USD ​​​​1,119,032​​​​​EUR​​​​​967,742​​​
Barclays Bank PLC
​​​​6/5/2026​​​​​7/31/2026​​​​​12,540​​
​EUR ​​​​192,154​​​​​USD​​​​​219,242​​​
Barclays Bank PLC
​​​​6/26/2026​​​​​7/31/2026​​​​​463​​
​​​​​​​​​​​​​​​​​​​​​​​​​​​​​​​​​​​​​​$4,604,908​​
​Unrealized depreciation on forward currency contracts​
​EUR ​​​​1,473,182​​​​​USD​​​​​1,733,967​​​
Barclays Bank PLC
​​​​4/30/2026​​​​​7/31/2026​​​​$(49,567)​​
​EUR ​​​​883,202​​​​​USD​​​​​1,043,010​​​
Barclays Bank PLC
​​​​5/11/2026​​​​​7/31/2026​​​​​(33,179)​​
​EUR ​​​​968,896​​​​​USD​​​​​1,126,265​​​
Barclays Bank PLC
​​​​5/19/2026​​​​​7/31/2026​​​​​(18,454)​​
​GBP ​​​​340,382​​​​​USD​​​​​462,598​​​
Barclays Bank PLC
​​​​4/30/2026​​​​​7/31/2026​​​​​(11,452)​​
​USD ​​​​1,943,790​​​​​EUR​​​​​1,701,117​​​
Barclays Bank PLC
​​​​6/29/2026​​​​​7/31/2026​​​​​(1,225)​​
​Total unrealized depreciation on forward currency contracts ​​​​​​​​​​​​​​​$(113,877)​​
​
(1)
See Note 4 “Derivative Contracts” for further discussion relating to forward currency contracts held by the Company.
​
See accompanying notes to the consolidated financial statements
 
​ ​​
24
​

​​
​FIRST HALF 2026 SHAREHOLDER LETTER AND SEMIANNUAL REPORT   |   Eagle Point Credit Company​
Eagle Point Credit Company & Subsidiaries
Consolidated Statement of Operations
For the six months ended June 30, 2026
(expressed in U.S. dollars)
(Unaudited)
​
​INVESTMENT INCOME ​​​​​​​
​
Interest income(1)
​​​$75,220,940​​
​
Other income
​​​​4,402,831​​
​
Dividend income(1)
​​​​628,051​​
​
Total Investment Income
​​​​80,251,822​​
​EXPENSES ​​​​​​​
​
Interest expense
​​​​10,631,605​​
​
Incentive fee
​​​​8,918,249​​
​
Management fee
​​​​7,663,283​​
​
Professional fees
​​​​1,291,955​​
​
Administration fees
​​​​757,522​​
​
Interest expense on investments sold under participation agreements
​​​​582,237​​
​
Trustees’ fees
​​​​200,276​​
​
Deferred tax expense
​​​​169,167​​
​
Tax expense
​​​​83,624​​
​
Other expenses
​​​​1,946,150​​
​
Total Expenses
​​​​32,244,068​​
​
NET INVESTMENT INCOME
​​​​48,007,754​​
​NET REALIZED AND UNREALIZED GAIN (LOSS) ​​​​​​​
​
Net realized gain (loss) on:
​​​​​​​
​
Investments, foreign currency and cash equivalents
​​​​(111,948,791)​​
​
Forward currency contracts
​​​​501,249​​
​
Retirement of Preferred Shares and Unsecured Notes
​​​​108,434​​
​
Redemption of Convertible Perpetual Preferred Shares
​​​​(6,457)​​
​
Net change in unrealized appreciation (depreciation) on:
​​​​​​​
​
Investments, foreign currency and cash equivalents(1)
​​​​(6,722,140)​​
​
Forward currency contracts
​​​​4,888,350​​
​
Net change in unrealized (appreciation) depreciation on liabilities at fair value under the fair value option
​​​​(883,843)​​
​
NET REALIZED AND UNREALIZED GAIN (LOSS)
​​​​(114,063,198)​​
​
NET INCREASE (DECREASE) IN NET ASSETS RESULTING FROM OPERATIONS
​​​​(66,055,444)​​
​DISTRIBUTIONS AND AMORTIZATION ON TEMPORARY EQUITY (NOTE 2) ​​​​​​​
​
Perpetual Preferred Shares
​​​​(12,361,175)​​
​
NET INCREASE (DECREASE) IN NET ASSETS RESULTING FROM OPERATIONS ATTRIBUTABLE TO COMMON SHAREHOLDERS
​​​$(78,416,619)​​
​
(1)
Interest income, dividend income and net unrealized appreciation (depreciation) on investment, foreign currency and cash equivalents include balances attributed to affiliated investments of $4,046,632, $557,710, and $(2,530,753), respectively. See Note 5 “Related Party Transactions” for further discussion.
​
See accompanying notes to the consolidated financial statements
 
​ ​​
25
​

​​
​FIRST HALF 2026 SHAREHOLDER LETTER AND SEMIANNUAL REPORT   |   Eagle Point Credit Company​
Eagle Point Credit Company & Subsidiaries
Consolidated Statement of Comprehensive Income
For the six months ended June 30, 2026
(expressed in U.S. dollars)
(Unaudited)
​
​
NET INCREASE (DECREASE) IN NET ASSETS RESULTING FROM OPERATIONS ATTRIBUTABLE TO COMMON SHAREHOLDERS
​​​$(78,416,619)​​
​OTHER COMPREHENSIVE INCOME (LOSS)(1)​​​​​​​
​
Change in unrealized (appreciation) depreciation on liabilities at fair value under the fair value option
​​​​927,075​​
​
NET INCREASE (DECREASE) IN NET ASSETS RESULTING FROM COMPREHENSIVE INCOME ATTRIBUTABLE TO COMMON SHAREHOLDERS
​​​$(77,489,544)​​
​
(1)
See Note 2 “Summary of Significant Accounting Policies — Other Financial Assets and Financial Liabilities at Fair Value” for further discussion relating to other comprehensive income.
​
See accompanying notes to the consolidated financial statements
 
​ ​​
26
​

​​
​FIRST HALF 2026 SHAREHOLDER LETTER AND SEMIANNUAL REPORT   |   Eagle Point Credit Company​
Eagle Point Credit Company & Subsidiaries
Consolidated Statements of Operations
(expressed in U.S. dollars)
(Unaudited)
​
​​​
For the
six months ended
June 30, 2026
​​
For the
six months ended
June 30, 2025
​
INVESTMENT INCOME ​​​​​​​​​​​​​
Interest income(1)
​​​$75,220,940​​​​$95,438,550​​
Other income
​​​​4,402,831​​​​​4,631,738​​
Dividend income(1)
​​​​628,051​​​​​694,633​​
Total Investment Income
​​​​80,251,822​​​​​100,764,921​​
EXPENSES ​​​​​​​​​​​​​
Interest expense
​​​​10,631,605​​​​​13,819,281​​
Incentive fee
​​​​8,918,249​​​​​13,255,282​​
Management fee
​​​​7,663,283​​​​​10,004,424​​
Professional fees
​​​​1,291,955​​​​​1,369,416​​
Administration fees
​​​​757,522​​​​​819,613​​
Interest expense on investments sold under participation agreements
​​​​582,237​​​​​—​​
Trustees’ fees
​​​​200,276​​​​​198,750​​
Deferred tax expense
​​​​169,167​​​​​—​​
Tax expense
​​​​83,624​​​​​50,025​​
Other expenses
​​​​1,946,150​​​​​865,926​​
Total Expenses
​​​​32,244,068​​​​​40,382,717​​
NET INVESTMENT INCOME
​​​​48,007,754​​​​​60,382,204​​
NET REALIZED AND UNREALIZED GAIN (LOSS) ​​​​​​​​​​​​​
Net realized gain (loss) on:
​​​​​​​​​​​​​
Investments, foreign currency and cash equivalents
​​​​(111,948,791)​​​​​(6,268,441)​​
Forward currency contracts
​​​​501,249​​​​​(6,436,739)​​
Retirement of Preferred Shares and Unsecured Notes
​​​​108,434​​​​​—​​
Redemption of Convertible Perpetual Preferred Shares
​​​​(6,457)​​​​​—​​
Net change in unrealized appreciation (depreciation) on:
​​​​​​​​​​​​​
Investments, foreign currency and cash equivalents⁽¹⁾
​​​​(6,722,140)​​​​​(60,408,393)​​
Forward currency contracts
​​​​4,888,350​​​​​(7,131,464)​​
Net change in unrealized (appreciation) depreciation on liabilities at fair value under the fair value option
​​​​(883,843)​​​​​(12,782,854)​​
NET REALIZED AND UNREALIZED GAIN (LOSS)
​​​​(114,063,198)​​​​​(93,027,891)​​
NET INCREASE (DECREASE) IN NET ASSETS RESULTING FROM OPERATIONS
​​​​(66,055,444)​​​​​(32,645,687)​​
DISTRIBUTIONS AND AMORTIZATION ON TEMPORARY EQUITY (NOTE 2) ​​​​​​​​​​​​​
Perpetual Preferred Shares
​​​​(12,361,175)​​​​​(7,361,075)​​
NET INCREASE (DECREASE) IN NET ASSETS RESULTING FROM OPERATIONS
ATTRIBUTABLE TO COMMON SHAREHOLDERS
​​​$(78,416,619)​​​​$(40,006,762)​​
​
(1)
Interest income, dividend income and net unrealized appreciation (depreciation) on investment, foreign currency and cash equivalents include balances attributed to affiliated investments of $4,046,632, $557,710, and $(2,530,753), respectively. See Note 5 “Related Party Transactions” for further discussion.
​
Note:
The above Consolidated Statement of Operations represents the six months ended June 30, 2026, and the six months ended June 30, 2025 and has been provided as supplemental information to the consolidated financial statements.
​
See accompanying notes to the consolidated financial statements
 
​ ​​
27
​

​
​FIRST HALF 2026 SHAREHOLDER LETTER AND SEMIANNUAL REPORT   |   Eagle Point Credit Company​
Eagle Point Credit Company & Subsidiaries
Consolidated Statements of Operations
(expressed in U.S. dollars)
(Unaudited)
​​​
For the
three months ended
June 30, 2026
​​
For the
three months ended
March 31, 2026
​​
For the
six months ended
June 30, 2026
​
INVESTMENT INCOME ​​​​​​​​​​​​​​​​​​​
Interest income
​​​$35,319,591​​​​$39,901,349​​​​$75,220,940​​
Other income
​​​​2,348,939​​​​​2,053,892​​​​​4,402,831​​
Dividend income
​​​​218,566​​​​​409,485​​​​​628,051​​
Total Investment Income
​​​​37,887,096​​​​​42,364,726​​​​​80,251,822​​
EXPENSES ​​​​​​​​​​​​​​​​​​​
Interest expense
​​​​4,735,972​​​​​5,895,633​​​​​10,631,605​​
Incentive fee
​​​​3,967,861​​​​​4,950,388​​​​​8,918,249​​
Management fee
​​​​3,702,650​​​​​3,960,633​​​​​7,663,283​​
Professional fees
​​​​870,141​​​​​421,814​​​​​1,291,955​​
Administration fees
​​​​356,226​​​​​401,296​​​​​757,522​​
Interest expense on investments sold under participation agreements
​​​​488,681​​​​​93,556​​​​​582,237​​
Trustees’ fees
​​​​100,901​​​​​99,375​​​​​200,276​​
Deferred tax expense
​​​​169,167​​​​​—​​​​​169,167​​
Tax expense
​​​​58,611​​​​​25,013​​​​​83,624​​
Other expenses
​​​​1,515,224​​​​​430,926​​​​​1,946,150​​
Total Expenses
​​​​15,965,434​​​​​16,278,634​​​​​32,244,068​​
NET INVESTMENT INCOME
​​​​21,921,662​​​​​26,086,092​​​​​48,007,754​​
NET REALIZED AND UNREALIZED GAIN (LOSS) ​​​​​​​​​​​​​​​​​​​
Net realized gain (loss) on:
​​​​​​​​​​​​​​​​​​​
Investments, foreign currency and cash equivalents
​​​​(104,375,841)​​​​​(7,572,950)​​​​​(111,948,791)​​
Forward currency contracts
​​​​3,902,816​​​​​(3,401,567)​​​​​501,249​​
Retirement of Preferred Shares and Unsecured
Notes
​​​​55,666​​​​​52,768​​​​​108,434​​
Redemption of Convertible Perpetual Preferred Shares
​​​​(3,714)​​​​​(2,743)​​​​​(6,457)​​
Net change in unrealized appreciation (depreciation) on:
​​​​​​​​​​​​​​​​​​​
Investments, foreign currency and cash equivalents
​​​​159,270,294​​​​​(165,992,434)​​​​​(6,722,140)​​
Forward currency contracts
​​​​(2,078,625)​​​​​6,966,975​​​​​4,888,350​​
Net change in unrealized (appreciation) depreciation on
liabilities at fair value under the fair value option
​​​​(2,597,535)​​​​​1,713,692​​​​​(883,843)​​
NET REALIZED AND UNREALIZED GAIN (LOSS)
​​​​54,173,061​​​​​(168,236,259)​​​​​(114,063,198)​​
NET INCREASE (DECREASE) IN NET ASSETS RESULTING FROM OPERATIONS
​​​​76,094,723​​​​​(142,150,167)​​​​​(66,055,444)​​
DISTRIBUTIONS AND AMORTIZATION ON TEMPORARY EQUITY (NOTE 2)
​​​​​​​​​​​​​​​​​​​
Perpetual Preferred Shares
​​​​(6,076,913)​​​​​(6,284,262)​​​​​(12,361,175)​​
TOTAL DISTRIBUTIONS AND AMORTIZATION ON TEMPORARY EQUITY
​​​​(6,076,913)​​​​​(6,284,262)​​​​​(12,361,175)​​
NET INCREASE (DECREASE) IN NET ASSETS
RESULTING FROM OPERATIONS ATTRIBUTABLE TO
COMMON SHAREHOLDERS
​​​$70,017,810​​​​$(148,434,429)​​​​$(78,416,619)​​
​
Note:
The above Consolidated Statement of Operations represents the three months ended June 30, 2026, the three months ended March 31, 2026 and the six months ended June 30, 2026 and has been provided as supplemental information to the consolidated financial statements.
​
See accompanying notes to the consolidated financial statements
 
​ ​​
28
​

​​
​FIRST HALF 2026 SHAREHOLDER LETTER AND SEMIANNUAL REPORT   |   Eagle Point Credit Company​
Eagle Point Credit Company & Subsidiaries
Consolidated Statements of Changes in Net Assets
(expressed in U.S. dollars, except share amounts)
(Unaudited)
​
​​​
For the
six months ended
June 30, 2026
​​
For the
year ended
December 31, 2025
​
NET INCREASE (DECREASE) IN NET ASSETS RESULTING FROM OPERATIONS
​​​​​​​​​​​​​
Net investment income
​​​$48,007,754​​​​$122,082,499​​
Net realized gain (loss) on:
​​​​​​​​​​​​​
Investments, foreign currency and cash equivalents
​​​​(111,948,791)​​​​​(80,494,176)​​
Forward currency contracts
​​​​501,249​​​​​(7,546,370)​​
Redemption of Convertible Perpetual Preferred Shares
​​​​(6,457)​​​​​(1,420)​​
Retirement of Preferred Shares and Unsecured Notes
​​​​108,434​​​​​141,297​​
Net change in unrealized appreciation (depreciation) on:
​​​​​​​​​​​​​
Investments, foreign currency and cash equivalents
​​​​(6,722,140)​​​​​(128,882,164)​​
Forward currency contracts
​​​​4,888,350​​​​​(4,503,071)​​
Net change in unrealized (appreciation) depreciation on liabilities at fair value under the fair value option
​​​​(883,843)​​​​​(15,797,301)​​
Total net increase (decrease) in net assets resulting from operations
​​​​(66,055,444)​​​​​(115,000,706)​​
NET INCREASE (DECREASE) IN NET ASSETS RESULTING FROM OTHER COMPREHENSIVE INCOME (LOSS)
​​​​​​​​​​​​​
Net change in unrealized (appreciation) depreciation on liabilities at fair value under the fair value option
​​​​927,075​​​​​1,374,564​​
Total net increase (decrease) in net assets resulting from other comprehensive income (loss)
​​​​927,075​​​​​1,374,564​​
COMMON SHARES DISTRIBUTIONS ​​​​​​​​​​​​​
Total earnings distributed
​​​​(79,320,289)​​​​​(94,369,065)​​
Common shares distributions from tax return of capital
​​​​—​​​​​(115,308,675)​​
Total common shares distributions
​​​​(79,320,289)​​​​​(209,677,740)​​
DISTRIBUTIONS AND AMORTIZATION ON TEMPORARY EQUITY ​​​​​​​​​​​​​
Perpetual Preferred Shares
​​​​(12,361,175)​​​​​(19,435,242)​​
CAPITAL SHARE TRANSACTIONS ​​​​​​​​​​​​​
Issuance of common shares pursuant to the Company’s “at the market” program,
net of commissions and offering expenses
​​​​—​​​​​132,638,287​​
Issuance of common shares pursuant to the Company’s dividend reinvestment plan
​​​​3,444,366​​​​​24,042,567​​
Issuance of common shares from conversion of Convertible Perpetual Preferred
Shares
​​​​1,912,349​​​​​126,561​​
Total increase in net assets from capital share transactions
​​​​5,356,715​​​​​156,807,415​​
TOTAL INCREASE (DECREASE) IN NET ASSETS
​​​​(151,453,118)​​​​​(185,931,709)​​
NET ASSETS AT BEGINNING OF PERIOD
​​​​750,936,050​​​​​936,867,759​​
NET ASSETS AT END OF PERIOD
​​​$599,482,932​​​​$750,936,050​​
CAPITAL SHARE ACTIVITY ​​​​​​​​​​​​​
Common shares issued pursuant to the Company’s “at the market” program
​​​​—​​​​​16,561,538​​
Common shares issued pursuant to the Company’s dividend reinvestment plan
​​​​730,122​​​​​3,393,867​​
Common shares issued from conversion of Convertible Perpetual Preferred Shares
​​​​470,603​​​​​19,614​​
Total increase (decrease) in capital share activity
​​​​1,200,725​​​​​19,975,019​​
See accompanying notes to the consolidated financial statements
 
​ ​​
29
​

​​
​FIRST HALF 2026 SHAREHOLDER LETTER AND SEMIANNUAL REPORT   |   Eagle Point Credit Company​
Eagle Point Credit Company & Subsidiaries
Consolidated Statement of Cash Flows
For the six months ended June 30, 2026
(expressed in U.S. dollars)
(Unaudited)
​
​CASH FLOWS FROM OPERATING ACTIVITIES ​​​​​​​
​
Net increase (decrease) in net assets resulting from operations
​​​$(66,055,444)​​
​
Adjustments to reconcile net increase (decrease) in net assets resulting from operations to net cash provided by (used in) operating activities:
​​​​​​​
​
Purchases of investments
​​​​(196,321,037)​​
​
Proceeds from sales of investments and repayments of principal(1)
​​​​366,575,552​​
​
Net proceeds from investments sold under participation agreements
​​​​17,419,943​​
​
Payment-in-kind interest
​​​​(2,527,971)​​
​
Net realized (gain) loss on:
​​​​​​​
​
Investments, foreign currency and cash equivalents
​​​​112,031,098​​
​
Retirement of Preferred Shares and Unsecured Notes
​​​​(108,434)​​
​
Redemption of Convertible Perpetual Preferred Shares
​​​​6,457​​
​
Net change in unrealized (appreciation) depreciation on:
​​​​​​​
​
Investments, foreign currency and cash equivalents
​​​​6,727,119​​
​
Forward currency contracts
​​​​(4,888,350)​​
​
Net change in unrealized appreciation (depreciation) on liabilities at fair value under the fair value option
​​​​883,843​​
​
Amortization (accretion) included in interest expense
​​​​811​​
​
Amortization (accretion) of premiums or discounts on investments
​​​​(597,964)​​
​
Interest receivable
​​​​965,208​​
​
Prepaid expenses
​​​​(104,329)​​
​
Incentive fee payable
​​​​429,177​​
​
Management fee payable
​​​​(1,082,732)​​
​
Deferred tax liability
​​​​169,167​​
​
Professional fees payable
​​​​225,438​​
​
Administration fees payable
​​​​50,844​​
​
Trustees’ fees payable
​​​​198,750​​
​
Other expenses payable
​​​​105,926​​
​
Net cash provided by (used in) operating activities
​​​​234,103,072​​
​CASH FLOWS FROM FINANCING ACTIVITIES ​​​​​​​
​
Common shares distributions, net of reinvestment and change in common shares distribution payable
​​​​(73,950,548)​​
​
Convertible Perpetual Preferred Shares issued pursuant to the Company’s dividend reinvestment plan
​​​​96,740​​
​
Redemption of Convertible Perpetual Preferred Shares
​​​​(421,634)​​
​
Redemption of Preferred Shares
​​​​(62,156,100)​​
​
Redemption of Unsecured Notes
​​​​(69,398,825)​​
​
Repurchase of Unsecured Notes and Preferred Shares
​​​​(7,169,291)​​
​
Perpetual Preferred Shares Distributions
​​​​(8,965,150)​​
​
Net cash provided by (used in) financing activities
​​​​(221,964,808)​​
​
NET INCREASE (DECREASE) IN CASH AND CASH EQUIVALENTS
​​​​12,138,264​​
​
CASH AND CASH EQUIVALENTS AND RESTRICTED CASH, BEGINNING OF PERIOD
​​​​47,405,773​​
​
CASH AND CASH EQUIVALENTS AND RESTRICTED CASH, END OF PERIOD
​​​$59,544,037​​
​
Supplemental disclosures:
​​​​​​​
​
Cash paid for interest expense
​​​$10,630,795​​
​
Cash paid for distributions on temporary equity
​​​$8,983,985​​
​
Cash paid for franchise taxes
​​​$103,541​​
​
Non-cash activities:
​​​​​​​
​
Issuance of common shares from conversion of Convertible Perpetual Preferred Shares
​​​$1,912,349​​
​
Transfer of assets in exchange for equity interest in joint venture
​​​$90,571,891​​
​
Transfer of assets in exchange for equity interest in investment company
​​​$3,998,617​​
​
(1)
Proceeds from sales and repayments of principal includes $63,083,395 of recurring cash flows which are considered return of capital on portfolio investments.
​
See accompanying notes to the consolidated financial statements
 
​ ​​
30
​

​​​
​ FIRST HALF 2026 SHAREHOLDER LETTER AND SEMIANNUAL REPORT   |   Eagle Point Credit Company ​
Eagle Point Credit Company & Subsidiaries
Notes to Consolidated Financial Statements
June 30, 2026
(Unaudited)
​
1.
ORGANIZATION
​
Eagle Point Credit Company (the “Company”) is an externally-managed, non-diversified closed-end management investment company registered under the Investment Company Act of 1940, as amended (the “1940 Act”). The Company has elected to be treated, and to qualify, as a regulated investment company (“RIC”) under Subchapter M of the Internal Revenue Code of 1986, as amended (the “Code”), for federal income tax purposes.
The Company’s primary investment objective is to generate high current income, with a secondary objective to generate capital appreciation. The Company seeks to achieve these objectives by investing primarily in equity and junior debt tranches of collateralized loan obligations (“CLOs”). The Company also invests in other credit-oriented securities and instruments.
The Company was initially formed on March 24, 2014, and commenced operations on June 6, 2014. The Company completed its initial public offering on October 7, 2014, and the Company’s common shares began trading on the New York Stock Exchange (the “NYSE”) under the symbol “ECC” on October 8, 2014.
On May 22, 2026, the Company converted from a Delaware corporation to a Delaware Statutory Trust.
Eagle Point Credit Management LLC (the “Adviser”) serves as the investment adviser of the Company and manages the Company’s investments, subject to the supervision of the Company’s Board of Trustees (the “Board”). The Adviser is registered as an investment adviser with the U.S. Securities and Exchange Commission (the “SEC”). Eagle Point Administration LLC, an affiliate of the Adviser, serves as the administrator of the Company (the “Administrator”).
The Company has three wholly-owned subsidiaries: Eagle Point Credit Company Sub (Cayman) Ltd. (“Sub I”), a Cayman Islands exempted company; Eagle Point Credit Company Sub II (Cayman) Ltd (“Sub II”), a Cayman Islands exempted company; and Eagle Point Credit Company Sub II (US) LLC (“Sub II US”), a Delaware limited liability company. These subsidiaries have been organized to hold certain of the Company’s investments for legal, regulatory and tax purposes. All intercompany accounts and transactions have been eliminated upon consolidation. As of June 30, 2026, Sub I, Sub II and Sub II US held 21%, 4% and 1% of the Company’s total assets, respectively.
2.
SUMMARY OF SIGNIFICANT ACCOUNTING POLICIES
​
Basis of Accounting
The consolidated financial statements have been prepared in conformity with U.S. generally accepted accounting principles (“U.S. GAAP”). The Company is an investment company and follows the accounting and reporting guidance applicable to investment companies in the Financial Accounting Standards Board (“FASB”) Accounting Standards Codification (“ASC”) Topic 946 Financial Services — Investment Companies. Items included in the consolidated financial statements are measured and presented in U.S. dollars.
Use of Estimates
The preparation of financial statements in conformity with U.S. GAAP requires management to make estimates and assumptions, which affect the reported amounts included in the consolidated financial statements and accompanying notes as of the reporting date. The most significant estimate inherent in the preparation of the consolidated financial statements is the valuation of the Company’s investments. Actual results may differ from those estimates.
Operating Segments
The Company has a single reportable segment with investment objectives described in Note 1 “Organization”. The chief operating decision maker (“CODM”) of the Company is comprised of the Company’s Chief Executive Officer and Chief Financial Officer.
 
​   ​ ​
31
​

​
​ FIRST HALF 2026 SHAREHOLDER LETTER AND SEMIANNUAL REPORT   |   Eagle Point Credit Company ​
Eagle Point Credit Company & Subsidiaries
Notes to Consolidated Financial Statements
June 30, 2026
(Unaudited)
Key financial information used by the CODM to assess the Company’s performance and make operational decisions, including the Company’s portfolio composition, total return, changes in net assets and expense ratios, is consistent with the presentation within the Company’s consolidated financial statements. Segment assets are reflected as “Total Assets” on the accompanying Consolidated Statement of Assets and Liabilities and significant segment expenses are listed on the Consolidated Statement of Operations.
Securities Transactions
The Company records the purchase and sale of securities on the trade date. Realized gains and losses on investments sold are recorded based on the specific identification method.
In certain circumstances where the Adviser determines it is unlikely to fully amortize a CLO equity or CLO debt investment’s remaining amortized cost, such remaining cost is written down to current fair value and recognized as a realized loss in the Consolidated Statement of Operations.
Foreign Currency Transactions
The Company does not isolate the portion of its results of operations attributable to changes in foreign exchange rates from those arising due to fluctuations in market prices of investments denominated in foreign currencies. These combined effects are included with the net change in unrealized appreciation (depreciation) on investments, foreign currency, cash and cash equivalents.
Reported net realized foreign exchange gains or losses may arise from sales of foreign currency, currency gains or losses occurring between trade and settlement dates on investment transactions and differences between the recorded amounts of dividends and interest income and the U.S. dollar equivalent of the amounts actually received.
Cash, Cash Equivalents and Restricted Cash
The Company defines cash and cash equivalents as cash and short-term, highly liquid investments with original maturities of three months or less from the date of purchase. The Company maintains its cash in bank accounts, which, at times, may exceed federal insured limits. The Adviser monitors the performance of the financial institutions where the accounts are held to manage associated risk.
Cash equivalents are carried at cost, plus accrued interest, which approximates fair value. Cash equivalents are held for meeting short-term liquidity requirements, rather than for investment purposes. Cash equivalents are classified as Level I in the fair value hierarchy. As of June 30, 2026, the Company held no cash equivalents.
Restricted cash represents amounts subject to legal or contractual restrictions imposed by third parties, including limitations on withdrawal or use. These restrictions may require the funds to be used for a specified purpose or limit the purpose for which the funds can be used. The Company considers cash collateral posted with counterparties in connection with foreign currency contracts to be restricted cash. As of June 30, 2026, the Company held restricted cash of $1.0 million associated with forward currency contracts.
Forward Currency Contracts
The Company may enter into forward currency contracts to manage the Company’s exposure to foreign currencies in which some of the Company’s investments are denominated. A forward currency contract is an agreement between the Company and a counterparty to buy and sell a currency at an agreed-upon exchange rate and on an agreed-upon future date.
 
​   ​ ​
32
​

​
​ FIRST HALF 2026 SHAREHOLDER LETTER AND SEMIANNUAL REPORT   |   Eagle Point Credit Company ​
Eagle Point Credit Company & Subsidiaries
Notes to Consolidated Financial Statements
June 30, 2026
(Unaudited)
Forward currency contracts are recorded at fair value, with the change in fair value recognized as unrealized appreciation (depreciation) on forward currency contracts on the Consolidated Statement of Assets and Liabilities. Realized gains or losses from the settlement of forward currency contracts are reported on the Consolidated Statement of Operations.
Cash amounts pledged as collateral in connection with forward currency contracts is considered restricted.
Participation Agreements
The Company enters into participation agreements whereby it transfers economic interests in certain portfolio investments to third-party participants while retaining legal title to the underlying assets. The accounting treatment for these arrangements depends on the specific terms and economic substance of each agreement.
For certain participation agreements, the Company records the proceeds received as a liability on the Consolidated Statement of Assets and Liabilities titled “Investments sold under participation agreements, at fair value” in accordance with ASC Topic 860, Transfers and Servicing. Under these arrangements, the underlying investments continue to be carried at fair value, and the Company recognizes interest income on the full investment amount while recording corresponding interest expense on the participation liability. The participation liabilities are carried at fair value and bear interest at rates determined by the underlying investment terms. Unrealized gains and losses on participation liabilities are included in net change in unrealized appreciation (depreciation) on investments, foreign currency and cash equivalents on the Consolidated Statement of Operations. Realized gains and losses on participation liabilities are included in net realized gain (loss) on investments, foreign currency and cash equivalents on the Consolidated Statement of Operations. As of June 30, 2026, participation liabilities totaled $20.0 million as a result of participation interests sold.
For other participation agreements where the economic terms result in a proportionate transfer of risk and reward, the Company reduces the carrying value of the underlying investment by the participation amount sold. Under these arrangements, no separate liability is recorded, and the net investment position reflects the Company’s retained economic interest. As of June 30, 2026, investments were reduced by $40.2 million as a result of participation interests sold.
The Company retains servicing responsibilities for all participation arrangements and has no obligation to repurchase participations or provide additional collateral beyond the investments subject to the participation agreements.
Temporary Equity
The Company’s “Perpetual Preferred Shares” ​(listed below) are accounted for in the Company’s Consolidated Statement of Assets and Liabilities as temporary equity in accordance with FASB ASC Topic 480-10-S99, Distinguishing Liabilities from Equity (“ASC 480”), which requires preferred stock that is contingently redeemable upon an occurrence of an event outside the Company’s control to be classified as temporary equity. The following are currently outstanding Perpetual Preferred Shares of the Company:
•
6.75% Series D Perpetual Preferred Shares (the “Series D Perpetual Preferred Shares”)
​
•
7.00% Series AA Convertible Perpetual Preferred Shares (the “Series AA Convertible Perpetual Preferred Shares”)
​
•
7.00% Series AB Convertible Perpetual Preferred Shares (the “Series AB Convertible Perpetual Preferred Shares” and collectively with the Series AA Convertible Perpetual Preferred Shares, the “Convertible Perpetual Preferred Shares”)
​
 
​   ​ ​
33
​

​
​ FIRST HALF 2026 SHAREHOLDER LETTER AND SEMIANNUAL REPORT   |   Eagle Point Credit Company ​
Eagle Point Credit Company & Subsidiaries
Notes to Consolidated Financial Statements
June 30, 2026
(Unaudited)
The Perpetual Preferred Shares are recorded net of deferred issuance cost, which consists of fees and expenses incurred in connection with the issuance of the Perpetual Preferred Shares, and net of issuance premiums or discounts, if any. Deferred issuance cost is amortized into expense when it is probable the Perpetual Preferred Shares become redeemable in the future.
Deferred issuance costs on the Convertible Perpetual Preferred Shares are amortized using the effective interest method due to the probable likelihood of holder optional or death related redemptions occurring. The Convertible Perpetual Preferred Shares are recorded net of unamortized deferred issuance costs.
As of June 30, 2026, no Series D Perpetual Preferred Shares deferred issuance costs have been amortized.
Distributions paid and amortization of deferred issuance costs on the preferred shares treated as temporary equity are included in the Consolidated Statement of Operations as a component of net increase (decrease) in net assets resulting from operations attributable to common shareholders.
The following table presents the distributions and amortization of deferred issuance cost related to the Perpetual Preferred Shares for the six months ended June 30, 2026:
Amounts in millions
​ ​ ​
Series D
Perpetual
Preferred Shares
​ ​
Series AA
Convertible
Perpetual
Preferred Shares
​ ​
Series AB
Convertible
Perpetual
Preferred Shares
​ ​
Total
​
Distributions (Including Accrued Distributions)
​ ​ ​ $ 3.6 ​ ​ ​ ​ $ 5.1 ​ ​ ​ ​ $ 0.3 ​ ​ ​ ​ $ 9.0 ​ ​
Amortization of Deferred Issuance Costs
​ ​ ​ ​ — ​ ​ ​ ​ ​ 3.3 ​ ​ ​ ​ ​ 0.1 ​ ​ ​ ​ ​ 3.4 ​ ​
Total Distributions (Including Accrued Distributions) and Amortization of Deferred Issuance Costs
​ ​ ​ $ 3.6 ​ ​ ​ ​ $ 8.4 ​ ​ ​ ​ $ 0.4 ​ ​ ​ ​ $ 12.4 ​ ​
See Note 7 “Preferred Shares” for further discussion relating to the Perpetual Preferred Shares issuances.
Other Financial Assets and Financial Liabilities at Fair Value
The Fair Value Option (“FVO”) under FASB ASC Subtopic 825-10, Fair Value Option (“ASC 825”), allows companies to make an irrevocable election to measure certain financial assets and liabilities at fair value on the initial and subsequent accounting reporting dates. This election is made on an instrument-by-instrument basis and must be applied to an entire instrument. Assets and liabilities measured at fair value are reported separately from those instruments measured using another accounting method. Additionally, changes in fair value attributable to instrument-specific credit risk on financial liabilities for which the FVO is elected are presented separately in other comprehensive income.
Upfront offering costs related to instruments for which the FVO is elected, including costs associated with issuances under the Company’s at-the-market (“ATM”) program, are recognized in earnings as incurred and are not deferred.
The Company has elected to apply the FVO under ASC 825 to the following instruments during the six months ended June 30, 2026:
•
6.6875% Unsecured Notes due 2028 (the “Series 2028 Notes”)
​
•
5.375% Unsecured Notes due 2029 (the “Series 2029 Notes”)
​
 
​   ​ ​
34
​

​
​ FIRST HALF 2026 SHAREHOLDER LETTER AND SEMIANNUAL REPORT   |   Eagle Point Credit Company ​
Eagle Point Credit Company & Subsidiaries
Notes to Consolidated Financial Statements
June 30, 2026
(Unaudited)
•
7.75% Unsecured Notes due 2030 (the “Series 2030 Notes”)
​
•
6.75% Unsecured Notes due 2031 (the “Series 2031 Notes” and collectively with the Series 2028 Notes, Series 2029 Notes and Series 2030 Notes, the “Unsecured Notes”)
​
•
6.50% Series C Term Preferred Shares due 2031 (the “Series C Term Preferred Shares”)
​
•
8.00% Series F Term Preferred Stock due 2029 (the “Series F Term Preferred Stock” and collectively with the Series C Term Preferred Shares, the “Term Preferred Shares”)
​
The primary reason for electing the FVO is to reflect economic events in the same period in which they occur and to simplify financial reporting and presentation.
Repurchase of Debt Securities
The Company records any gains resulting from the repurchase of the Company’s Preferred Shares and Unsecured Notes at a discount through open market transactions and subsequent redemptions or retirement as a realized gain or loss in the Consolidated Statement of Operations.
Investment Income Recognition
Interest Income from Investments
Interest income from debt securities is recorded using the accrual basis of accounting to the extent such amounts are expected to be collected.
Premiums and discounts on investments in debt securities are amortized or accreted, respectively, using the effective interest method and are included in interest income. The Company applies the provisions of Accounting Standards Update No. 2017-08 Premium Amortization on Purchased Callable Debt Securities (“ASU 2017-08”) in calculating amortization of premium for applicable investments.
In certain circumstances, all or a portion of interest income from a given investment may be paid in the form of additional investment principal, often referred to as payment-in-kind (“PIK”) interest. PIK interest is included in interest income and interest receivable through the PIK capitalization date. On the capitalization date, the PIK component of interest receivable is capitalized as additional principal of the investment, which is subject to fair value determination, and the PIK interest rate is applied to the entire principal balance of the applicable investment. To the extent the Company does not believe it will ultimately be able to collect capitalized PIK interest, the investment will be placed on non-accrual status, and previously recorded capitalized PIK interest will be reversed.
Investment income from investments in the equity tranche securities of CLO, Collateralized Fund Obligations (“CFO”), rated feeder funds, and certain other investments (such as fee rebates) is recognized using the effective interest method, in accordance with ASC Topic 325-40, Beneficial Interests in Securitized Financial Assets. Under the effective interest method, income is recognized based on an effective yield derived from cash flows projected to the expected call date, and any difference between cash distributed and income amount calculated pursuant to the effective interest method is recorded as an adjustment to the cost basis of the investment. It is the Adviser’s policy to update the effective yield for each CLO equity and fee rebate position held within the Company’s portfolio at the initiation of each investment and each subsequent quarter thereafter. For CFO equity, rated feeder fund equity and certain other investments, the effective yield is reviewed at each measurement date and updated periodically based on the facts and circumstances known to the Adviser.
The Company recognizes the interest income from Loan Accumulation Facilities (“LAFs”) in accordance with the guidance noted in ASC Topic 325-40-35-1, Beneficial Interest in Securitized Financial Assets, which states that the
 
​   ​ ​
35
​

​
​ FIRST HALF 2026 SHAREHOLDER LETTER AND SEMIANNUAL REPORT   |   Eagle Point Credit Company ​
Eagle Point Credit Company & Subsidiaries
Notes to Consolidated Financial Statements
June 30, 2026
(Unaudited)
holder of a beneficial interest in securitized financial assets shall determine interest income over the life of the beneficial interest in accordance with the effective yield method, provided such amounts are expected to be collected. FASB ASC 325-40-20 further defines “beneficial interests,” among other things, as “rights to receive all or portions of specified cash inflows received by a trust or other entity.” FASB ASC 325-40-15-7 also states that for income recognition purposes, beneficial interests in securitized financial assets (such as those in LAFs) are within the scope of ASC 325-40 because it is customary for certain industries, such as investment companies, to report interest income as a separate item in their income statements even though the investments are accounted for at fair value. For the six months ended June 30, 2026, the Company recorded $3.3 million in interest income from LAFs.
Other Income
Other income includes the Company’s share of income under the terms of fee rebate agreements and commitment fee income relating to securities paying a commitment fee on unfunded investment commitments.
Dividend Income
Dividend income represents dividend income from the Company’s investments in common stock and is recorded on the ex-dividend date.
Expenses, Offering Cost and Deferred Financing and Issuance Costs
Expense Recognition
Expenses are recorded on the accrual basis of accounting.
Offering Expenses
Offering expenses associated with the issuance of the Company’s common shares, inclusive of expenses incurred associated with offerings under the ATM program, are charged to paid-in-capital at the time the shares are sold in accordance with guidance noted in FASB ASC Topic 946-20-25-5, Investment Companies — Investment Company Activities — Recognition.
Interest Expense
Interest expense includes the distributions paid on the Company’s Term Preferred Shares and interest paid on the Company’s Unsecured Notes. Interest expense also includes the amortization of issuance premiums and discounts associated with the issuance of the Term Preferred Shares.
The following table summarizes the components of interest expense for the six months ended June 30, 2026:
Amounts in millions
​ ​ ​
Series C Term
Preferred Shares
​ ​
Series F Term
Preferred
Stock
​ ​
Series 2028
Notes
​ ​
Series 2029
Notes
​ ​
Series 2030
Notes
​ ​
Series 2031
Notes
​ ​
Total
​
Interest Expense
​ ​ ​ $ 1.6 ​ ​ ​ ​ $ 0.4 ​ ​ ​ ​ $ 0.8 ​ ​ ​ ​ $ 2.5 ​ ​ ​ ​ $ 4.5 ​ ​ ​ ​ $ 0.9 ​ ​ ​ ​ $ 10.7 ​ ​
Amortization of Issuance (Premium) Discount
​ ​ ​ ​ — ​ ​ ​ ​ ​ 0.0 ​ ​ ​ ​ ​ — ​ ​ ​ ​ ​ — ​ ​ ​ ​ ​ — ​ ​ ​ ​ ​ — ​ ​ ​ ​ ​ 0.0 ​ ​
Total Interest
Expense
(1)
​ ​ ​ $ 1.6 ​ ​ ​ ​ $ 0.4 ​ ​ ​ ​ $ 0.8 ​ ​ ​ ​ $ 2.5 ​ ​ ​ ​ $ 4.5 ​ ​ ​ ​ $ 0.9 ​ ​ ​ ​ $ 10.7 ​ ​
​
(1)
Amounts may not foot due to rounding.
​
See Note 7 “Preferred Shares” and Note 8 “Unsecured Notes” for further discussion relating to the Term Preferred Shares and Unsecured Notes, respectively.
 
​   ​ ​
36
​

​
​ FIRST HALF 2026 SHAREHOLDER LETTER AND SEMIANNUAL REPORT   |   Eagle Point Credit Company ​
Eagle Point Credit Company & Subsidiaries
Notes to Consolidated Financial Statements
June 30, 2026
(Unaudited)
Issuance Premiums and Discounts
Issuance premiums and discounts on liabilities consist of premiums received or discounts provided in connection with the issuance of the Term Preferred Shares as part of the Company’s ATM program. In accordance with FASB ASC Topic 835-30-35-2, the issuance premiums and discounts are capitalized at the time of issuance and amortized using the effective interest method over the term of the Term Preferred Shares. Amortization of issuance premiums or discounts are reflected in interest expense in the Consolidated Statement of Operations.
Prepaid Expenses
Prepaid expenses generally consist of insurance premiums, filing fees, shelf registration expenses and ATM program expenses. Prepaid shelf registration expenses and ATM program expenses represent fees and expenses incurred in connection with the initial registration of the Company’s current shelf registration and ATM program. Such costs are allocated pro-rata based on the amount issued relative to the total respective offering amount to paid-in-capital or expense depending on the security being issued pursuant to the shelf registration and ATM program. Subsequent costs incurred to maintain the Company’s ATM program are expensed as incurred. Any unallocated prepaid expense balance associated with the shelf registration and the ATM program is accelerated into expense at the earlier of the end of the program period or at the effective date of a new shelf registration or ATM program.
Federal and Other Taxes
The Company intends to operate so as to qualify to be taxed as a RIC under the Code and, as such, to not be subject to federal income tax on the portion of its taxable income and gains distributed to shareholders. To qualify for RIC tax treatment, among other requirements, the Company is required to distribute at least 90% of its investment company taxable income, as defined by the Code. The Company has adopted November 30th as its fiscal tax year end.
Because U.S. federal income tax regulations differ from U.S. GAAP, distributions in accordance with tax regulations may differ from net investment income and realized gains recognized for financial reporting purposes. These differences may be permanent or temporary. Permanent differences are reclassified among capital accounts in the consolidated financial statements to reflect their tax character. Temporary differences arise when certain items of income, expense, gain or loss are recognized at some time in the future. Differences in classification may also result from the treatment of short-term capital gains as ordinary income for federal income tax purposes. The tax basis components of distributable earnings may differ from the amounts reflected in the Consolidated Statement of Assets and Liabilities due to temporary book/tax differences arising primarily from partnerships and passive foreign investment company investments.
As of June 30, 2026, the federal income tax cost and net unrealized depreciation on securities were as follows:
Amounts in millions
​
Cost for federal income tax purposes
​ ​ ​ $ 1,365.7 ​ ​
​
Gross unrealized appreciation
​ ​ ​ $ 78.5 ​ ​
​
Gross unrealized depreciation
​ ​ ​ ​ (438.8) ​ ​
​
Net unrealized depreciation
​ ​ ​ $ (360.3) ​ ​
For the six months ended June 30, 2026, the Company incurred $83,624 in Delaware franchise tax expense related to the 2026 tax year.
The Company’s wholly-owned subsidiary, Sub II US, has elected to be treated as a corporation for U.S. tax purposes. As such, the subsidiary may be subject to federal, state and local tax in jurisdictions where it operates or is deemed to operate. Sub II US has recorded a deferred tax liability of $1.7 million as of June 30, 2026, which relates to the 2024 and 2025 tax years.
 
​   ​ ​
37
​

​
​ FIRST HALF 2026 SHAREHOLDER LETTER AND SEMIANNUAL REPORT   |   Eagle Point Credit Company ​
Eagle Point Credit Company & Subsidiaries
Notes to Consolidated Financial Statements
June 30, 2026
(Unaudited)
Distributions to Shareholders
The composition of distributions paid to common shareholders from net investment income and capital gains is determined in accordance with U.S. federal income tax regulations, which differ from U.S. GAAP. Distributions to common shareholders can be comprised of net investment income, net realized capital gains and return of capital for U.S. federal income tax purposes and are intended to be paid monthly.
Distributions payable to common shareholders are recorded as a liability on ex-dividend date. Common shareholders who participate in the Company’s distribution reinvestment plan (the “DRIP”) will have their distributions automatically reinvested in common shares of the Company as of the payment date pursuant to the DRIP. Common shareholders who do not participate in the DRIP generally will receive distributions in cash.
In addition to the regular monthly distributions, and subject to available taxable earnings of the Company, the Company may make periodic special and/or supplemental distributions representing the excess of the Company’s taxable income over the Company’s aggregate monthly distributions paid during the year.
The characterization of distributions paid to common shareholders, as set forth in the Consolidated Statements of Changes in Net Assets and Consolidated Financial Highlights, reflect estimates made by the Company for U.S. federal income tax purposes. These estimates are subject to change once the final determination of the source of all distributions has been made and the final tax return has been filed by the Company.
The following table summarizes the distributions declared and paid by the Company on common shares and preferred shares with record dates during the six months ended June 30, 2026:
Amounts in millions except per share amounts
​ ​ ​
Distribution
per Share
​ ​
Distribution
Amount
​
Common Shares
​ ​ ​ $ 0.60 ​ ​ ​ ​ $ 79.3 ​ ​
Series C Term Preferred Shares
​ ​ ​ ​ 0.81 ​ ​ ​ ​ ​ 1.6 ​ ​
Series D Perpetual Preferred Shares
​ ​ ​ ​ 0.84 ​ ​ ​ ​ ​ 3.6 ​ ​
Series F Term Preferred Stock
​ ​ ​ ​ 0.17 ​ ​ ​ ​ ​ 0.4 ​ ​
Series AA Convertible Perpetual Preferred Shares
​ ​ ​ ​ 0.88 ​ ​ ​ ​ ​ 5.1 ​ ​
Series AB Convertible Perpetual Preferred Shares
​ ​ ​ ​ 0.88 ​ ​ ​ ​ ​ 0.3 ​ ​
​
3.
VALUATION OF INVESTMENTS
​
The Company accounts for its investments in accordance with U.S. GAAP and determines fair values in accordance with the provisions of the FASB ASC Topic 820, Fair Value Measurements and Disclosures (“ASC 820”), which defines fair value, establishes a framework for measuring fair value and requires enhanced disclosures about fair value measurements. Investments are reflected in the consolidated financial statements at fair value, which represents the price that would be received to sell an asset, or paid to transfer a liability, in an orderly transaction between market participants at the measurement date (i.e., the exit price).
Pursuant to Rule 2a-5 under the 1940 Act (“Rule 2a-5”), the Board has designated the Adviser as “valuation designee” responsible for performing fair value determinations, subject to Board oversight and certain other conditions. In the absence of readily available market quotations, as defined by Rule 2a-5, the Adviser determines the fair value of the Company’s investments in accordance with its written valuation policy, which has been approved by the Board.
 
​   ​ ​
38
​

​
​ FIRST HALF 2026 SHAREHOLDER LETTER AND SEMIANNUAL REPORT   |   Eagle Point Credit Company ​
Eagle Point Credit Company & Subsidiaries
Notes to Consolidated Financial Statements
June 30, 2026
(Unaudited)
Fair value determinations require the application of judgment to the specific facts and circumstances of each investment. While the Company applies a consistent valuation process across similar investment types, there is no single method for determining fair value in good faith. Due to the uncertainty in estimating fair value, the values assigned to investments may differ materially from values that would have been used had an active market for the investments existed.
The Adviser determines fair value based on assumptions that market participants would use in pricing an asset or liability in an orderly transaction at the measurement date. When considering market participant assumptions in fair value measurements, the following fair value hierarchy prioritizes and ranks the level of market price observability used in measuring investments:
•
Level I — Unadjusted quoted prices in active markets for identical assets or liabilities that the Company is able to access as of the reporting date.
​
•
Level II — Inputs, other than quoted prices included in Level I, that are observable either directly or indirectly as of the reporting date. These inputs may include (a) quoted prices for similar assets in active markets, (b) quoted prices for identical or similar assets in markets that are not active, (c) inputs other than quoted prices that are observable for the asset, or (d) inputs derived principally from or corroborated by observable market data by correlation or other means.
​
•
Level III — Pricing inputs are unobservable for the investment and little, if any, active market exists as of the reporting date. Fair value inputs require significant judgment or estimation from the Adviser.
​
In certain cases where inputs used to measure fair value fall into multiple levels of the fair value hierarchy, the classification is based on the lowest level input that is significant to the overall fair value measurement. The assessment of the significance of a particular input to the fair value measurement in its entirety requires judgment and consideration of factors specific to the investment.
Market price observability is impacted by a number of factors, including the type of investment, the characteristics specific to the investment and the state of the marketplace (including the existence and transparency of transactions between market participants). Investments with readily available quoted prices in active market generally require a lesser degree of judgment and have a higher degree of market price observability. Conversely, investments lacking observable market data are valued using Level III inputs, which incorporate the Adviser’s own assumptions (including assumptions the Adviser believes market participants would use in valuing investments and assumptions relating to appropriate risk adjustments for nonperformance and lack of marketability), as outlined in the Adviser’s valuation policy.
In accordance with ASC Topic 820, the Company may use net asset value (“NAV”) as a practical expedient to estimate the fair value of certain investments that do not have a readily determinable fair value, such as the Company’s investment in Joint Ventures (“JV”) and limited partnerships. When NAV is used as a practical expedient, those investments are not categorized within the fair value hierarchy.
An estimate of fair value is made for each investment at least monthly taking into account information available as of the reporting date.
 
​   ​ ​
39
​

​
​ FIRST HALF 2026 SHAREHOLDER LETTER AND SEMIANNUAL REPORT   |   Eagle Point Credit Company ​
Eagle Point Credit Company & Subsidiaries
Notes to Consolidated Financial Statements
June 30, 2026
(Unaudited)
Fair Value Measurement
The following tables summarize the valuation of the Company’s investments measured and reported at fair value under the fair value hierarchy levels as of June 30, 2026:
Fair Value Measurement (in millions)
​ ​ ​
Level I
​ ​
Level II
​ ​
Level III
​ ​
Investments
measured at

NAV
​ ​
Total
​
Assets at Fair Value ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​
Investments at Fair Value ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​
CLO Debt
​ ​ ​ $ — ​ ​ ​ ​ $ 0.5 ​ ​ ​ ​ $ — ​ ​ ​ ​ $ — ​ ​ ​ ​ $ 0.5 ​ ​
CLO Equity
​ ​ ​ ​ — ​ ​ ​ ​ ​ — ​ ​ ​ ​ ​ 586.4 ​ ​ ​ ​ ​ — ​ ​ ​ ​ ​ 586.4 ​ ​
Loan Accumulation Facilities
​ ​ ​ ​ — ​ ​ ​ ​ ​ — ​ ​ ​ ​ ​ 31.0 ​ ​ ​ ​ ​ — ​ ​ ​ ​ ​ 31.0 ​ ​
Asset Backed Securities
​ ​ ​ ​ — ​ ​ ​ ​ ​ 50.7 ​ ​ ​ ​ ​ 10.0 ​ ​ ​ ​ ​ — ​ ​ ​ ​ ​ 60.7 ​ ​
CFO Equity
​ ​ ​ ​ — ​ ​ ​ ​ ​ — ​ ​ ​ ​ ​ 49.6 ​ ​ ​ ​ ​ — ​ ​ ​ ​ ​ 49.6 ​ ​
Equity Securities
​ ​ ​ ​ 0.1 ​ ​ ​ ​ ​ — ​ ​ ​ ​ ​ 0.7 ​ ​ ​ ​ ​ 90.5 ​ ​ ​ ​ ​ 91.3 ​ ​
Loans and Notes
​ ​ ​ ​ — ​ ​ ​ ​ ​ — ​ ​ ​ ​ ​ 143.6 ​ ​ ​ ​ ​ 6.9 ​ ​ ​ ​ ​ 150.5 ​ ​
Preferred Stock
​ ​ ​ ​ — ​ ​ ​ ​ ​ — ​ ​ ​ ​ ​ 8.5 ​ ​ ​ ​ ​ — ​ ​ ​ ​ ​ 8.5 ​ ​
Rated Feeder Fund Equity
​ ​ ​ ​ — ​ ​ ​ ​ ​ — ​ ​ ​ ​ ​ 1.7 ​ ​ ​ ​ ​ — ​ ​ ​ ​ ​ 1.7 ​ ​
Regulatory Capital Relief Securities
​ ​ ​ ​ — ​ ​ ​ ​ ​ — ​ ​ ​ ​ ​ 24.0 ​ ​ ​ ​ ​ — ​ ​ ​ ​ ​ 24.0 ​ ​
Royalties
​ ​ ​ ​ — ​ ​ ​ ​ ​ — ​ ​ ​ ​ ​ 0.4 ​ ​ ​ ​ ​ — ​ ​ ​ ​ ​ 0.4 ​ ​
Warrants
​ ​ ​ ​ — ​ ​ ​ ​ ​ — ​ ​ ​ ​ ​ 0.8 ​ ​ ​ ​ ​ — ​ ​ ​ ​ ​ 0.8 ​ ​
Total Investments at Fair Value(1)
​ ​ ​ $ 0.1 ​ ​ ​ ​ $ 51.2 ​ ​ ​ ​ $ 856.7 ​ ​ ​ ​ $ 97.4 ​ ​ ​ ​ $ 1,005.4 ​ ​
Other Financial Instruments at Fair Value(2) ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​
Forward Currency Contracts
​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​
Unrealized appreciation on forward currency contracts
​ ​ ​ $ — ​ ​ ​ ​ $ 4.6 ​ ​ ​ ​ $ — ​ ​ ​ ​ $ — ​ ​ ​ ​ $ 4.6 ​ ​
Total Forward Currency Contracts(1)
​ ​ ​ $ — ​ ​ ​ ​ $ 4.6 ​ ​ ​ ​ $ — ​ ​ ​ ​ $ — ​ ​ ​ ​ $ 4.6 ​ ​
Liabilities at Fair Value ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​
Unfunded Investment Commitments ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​
Unfunded liabilities, at fair value
​ ​ ​ $ — ​ ​ ​ ​ $ — ​ ​ ​ ​ $ 0.1 ​ ​ ​ ​ $ — ​ ​ ​ ​ $ 0.1 ​ ​
Total Unfunded Investment Commitments(1)
​ ​ ​ $ — ​ ​ ​ ​ $ — ​ ​ ​ ​ $ 0.1 ​ ​ ​ ​ $ — ​ ​ ​ ​ $ 0.1 ​ ​
Other Financial Instruments at Fair Value(2) ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​
Forward Currency Contracts
​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​
Unrealized depreciation on forward currency contracts
​ ​ ​ $ — ​ ​ ​ ​ $ 0.1 ​ ​ ​ ​ $ — ​ ​ ​ ​ $ — ​ ​ ​ ​ $ 0.1 ​ ​
Total Forward Currency Contracts(1)
​ ​ ​ $ — ​ ​ ​ ​ $ 0.1 ​ ​ ​ ​ $ — ​ ​ ​ ​ $ — ​ ​ ​ ​ $ 0.1 ​ ​
Term Preferred Shares and Unsecured Notes at Fair Value ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​
Series 2029 Notes
​ ​ ​ $ 89.1 ​ ​ ​ ​ $ — ​ ​ ​ ​ $ — ​ ​ ​ ​ $ — ​ ​ ​ ​ $ 89.1 ​ ​
Series 2030 Notes
​ ​ ​ ​ 115.4 ​ ​ ​ ​ ​ — ​ ​ ​ ​ ​ — ​ ​ ​ ​ ​ — ​ ​ ​ ​ ​ 115.4 ​ ​
Series C Term Preferred Shares
​ ​ ​ ​ 45.4 ​ ​ ​ ​ ​ — ​ ​ ​ ​ ​ — ​ ​ ​ ​ ​ — ​ ​ ​ ​ ​ 45.4 ​ ​
Total Term Preferred Shares and Unsecured Notes at Fair Value(1)
​ ​ ​ $ 249.9 ​ ​ ​ ​ $ — ​ ​ ​ ​ $ — ​ ​ ​ ​ $ — ​ ​ ​ ​ $ 249.9 ​ ​
​
(1)
Amounts may not foot due to rounding.
​
(2)
Other financial instruments at fair value are representative of derivative contracts, such as forward currency contracts. These instruments are reflected at the unrealized appreciation (depreciation) on the instrument.
​
 
​   ​ ​
40
​

​
​ FIRST HALF 2026 SHAREHOLDER LETTER AND SEMIANNUAL REPORT   |   Eagle Point Credit Company ​
Eagle Point Credit Company & Subsidiaries
Notes to Consolidated Financial Statements
June 30, 2026
(Unaudited)
Significant Unobservable Inputs
The following table summarizes the valuation techniques, quantitative inputs and assumptions used for investments categorized within Level III of the fair value hierarchy as of June 30, 2026:
​ ​ ​
Quantitative Information about Level III Fair Value Measurements
​
Assets
​ ​
Fair Value
(in millions)
​ ​
Valuation Techniques/​
Methodologies
​ ​
Unobservable Inputs
​ ​
Range / Weighted
Average
(1)
​
CLO Equity
​ ​ ​ $ 586.4 ​ ​ ​ Independent Pricing Service(2) ​ ​ Mid Price ​ ​
0.02% - 83.15% / 46.54%
​
Asset Backed Securities
​ ​ ​ ​ 9.9 ​ ​ ​ Discounted Cash Flow ​ ​ Discount Rate(3) ​ ​
8.53%
​
CFO Equity
​ ​ ​ ​ 49.6 ​ ​ ​ Discounted Cash Flow ​ ​ Discount Rate ​ ​
23.00% - 45.00% / 37.55%
​
Equity Securities
​ ​ ​ ​ 0.6 ​ ​ ​ Discounted Cash Flow ​ ​ Discount Rate(3) ​ ​
13.25%
​
Equity Securities
​ ​ ​ ​ 0.1 ​ ​ ​
Waterfall, Guideline Public Company Method
​ ​ Share Price(3) ​ ​
$10.65
​
Loans and Notes
​ ​ ​ ​ 140.6 ​ ​ ​ Discounted Cash Flow ​ ​ Discount Rate ​ ​
8.81% - 57.53% / 15.66%
​
Loans and Notes
​ ​ ​ ​ 3.0 ​ ​ ​
Discounted Cash Flow and Monte
Carlo Simulation Model
​ ​
Discount Rate(3)
​ ​
8.08%
​
​ ​ ​ ​ ​ ​ ​ ​ ​ Volatility(3) ​ ​
35.00%
​
​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ NAV per Share(3) ​ ​
$6.98
​
​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ Share Price(3) ​ ​
$4.41
​
​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ Dividend Rate(3) ​ ​
16.33%
​
​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ Risk Free Rate(3) ​ ​
4.14%
​
​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ Time to Liquidity (in years)(3) ​ ​
4.20
​
Preferred Stock
​ ​ ​ ​ 2.7 ​ ​ ​ Discounted Cash Flow ​ ​ Discount Rate ​ ​
12.00% - 17.72% / 17.18%
​
Preferred Stock
​ ​ ​ ​ 0.5 ​ ​ ​
FINCAD Convertible Model
​ ​
Discount Rate(3)
​ ​
18.66%
​
​ Volatility(3) ​ ​
40.00%
​
​ Share Price(3) ​ ​
$10.65
​
​ Risk Free Rate(3) ​ ​
4.18%
​
​ Time to Liquidity (in years)(3) ​ ​
5.48
​
Preferred Stock
​ ​ ​ ​ 1.2 ​ ​ ​ Guideline Public Company ​ ​ Next Fiscal Year Revenue Multiple(3) ​ ​
0.93x
​
​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ Next Fiscal Year Adj EBITDA Multiple(3) ​ ​
7.50x
​
​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ Volatility(3) ​ ​
60.00%
​
​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ Time to Expiry (in years)(3) ​ ​
5.00
​
​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ Risk Free Rate(3) ​ ​
4.19%
​
Rated Feeder Fund Equity
​ ​ ​ ​ 1.7 ​ ​ ​ Discounted Cash Flow ​ ​ Discount Rate(3) ​ ​
26.93%
​
Regulatory Capital
Relief Securities
​ ​ ​ ​ 24.0 ​ ​ ​ Discounted Cash Flow ​ ​ Discount Rate ​ ​
9.04% - 12.40% / 10.52%
​
​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ Constant Prepayment Rate ​ ​
5.08% - 18.87% / 12.06%
​
​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ Constant Default Rate ​ ​
0.17% - 5.54% / 3.40%
​
​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ Loss Severity ​ ​
25.49% - 48.49% / 31.66%
​
​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ Loss Rate ​ ​
0.07% - 1.41% / 0.97%
​
Royalties
​ ​ ​ ​ 0.4 ​ ​ ​ Discounted Cash Flow ​ ​ Discount Rate(3) ​ ​
18.00%
​
Warrants
​ ​ ​ ​ 0.4 ​ ​ ​ Guideline Public Company ​ ​ Next Fiscal Year Revenue Multiple(3) ​ ​
0.93x
​
​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ Next Fiscal Year Adj EBITDA Multiple(3) ​ ​
7.50x
​
​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ Volatility(3) ​ ​
60.00%
​
​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ Time to Expiry (in years)(3) ​ ​
5.00
​
​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ Risk Free Rate(3) ​ ​
4.19%
​
Warrants
​ ​ ​ ​ 0.1 ​ ​ ​ Scenario Analysis ​ ​ Probability Percentage(3) ​ ​
2.00%
​
​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​
Estimated Time to Conversion (in years)(3)
​ ​
0.50
​
​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ Enterprise Valuation (in millions)(3) ​ ​
$614.0
​
Warrants
​ ​ ​ ​ 0.3 ​ ​ ​
Waterfall, Guideline Public Company Method
​ ​
Share Price(3)
​ ​
$10.65
​
Total Fair Value of Level
III Investments
(4)
​ ​ ​ $ 821.5 ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​
 
​   ​ ​
41
​

​
​ FIRST HALF 2026 SHAREHOLDER LETTER AND SEMIANNUAL REPORT   |   Eagle Point Credit Company ​
Eagle Point Credit Company & Subsidiaries
Notes to Consolidated Financial Statements
June 30, 2026
(Unaudited)
(1)
Weighted average calculations are based on the fair value of investments.
​
(2)
The Company uses an independent pricing service to value CLO Equity investments. The pricing service applies a methodology incorporating market data, including trustee reporting, executable bids, broker quotes from dealers with two-sided markets and transaction activity from comparable securities to those being valued.
​
(3)
Range not shown as only one position is included in category.
​
(4)
Amounts may not foot due to rounding.
​
Unobservable inputs and assumptions are reviewed at each measurement date and updated as necessary to reflect current market conditions. The table presented is not intended to be all-inclusive, but rather provides information on significant Level III inputs relevant to the Company’s fair value measurements as of the reporting date. In addition to the techniques and inputs outlined in the preceding table, the Adviser may use other valuation techniques and methodologies when determining the fair value of the Company’s investments, as permitted under the Adviser’s valuation policy approved by the Board.
Changes in the unobservable inputs and assumptions can have an impact on the fair value measurement, specifically:
•
Increases (decreases) in the default rate and discount rate, in isolation, would generally result in a lower (higher) fair value measurement.
​
•
Changes in the prepayment rate may result in a higher or lower fair value, depending on the circumstances.
​
•
Generally, a change in the default rate assumption may be accompanied by a directionally opposite change in the assumption used for the prepayment and recovery.
​
Certain of the Company’s Level III investments have been valued using unadjusted inputs that have not been internally developed by the Adviser, including third-party transactions, recent market transactions and data reported by trustees. As a result, investments with a fair value of $35.2 million have been excluded from the preceding table.
Change in Investments Classified as Level III
The following table includes additional information pertaining to financial instruments classified within Level III for the six months ended June 30, 2026:
Amounts in millions
​ ​ ​
CLO Equity
​ ​
Loan
Accumulation
Facilities
​ ​
Asset Backed
Securities
​ ​
CFO Equity
​ ​
Equipment
Financing
​ ​
Equity
Securities
​
Balance as of January 1, 2026
​ ​ ​ $ 892.9 ​ ​ ​ ​ $ 55.2 ​ ​ ​ ​ $ 16.0 ​ ​ ​ ​ $ 57.7 ​ ​ ​ ​ $ 1.4 ​ ​ ​ ​ $ 0.8 ​ ​
Purchases of investments
​ ​ ​ ​ 35.4 ​ ​ ​ ​ ​ 16.5 ​ ​ ​ ​ ​ 10.0 ​ ​ ​ ​ ​ 2.5 ​ ​ ​ ​ ​ — ​ ​ ​ ​ ​ — ​ ​
Proceeds from sales or maturity of
investments
​ ​ ​ ​ (208.2)(1) ​ ​ ​ ​ ​ (40.6) ​ ​ ​ ​ ​ (16.0) ​ ​ ​ ​ ​ — ​ ​ ​ ​ ​ (1.4) ​ ​ ​ ​ ​ — ​ ​
Non-cash transfer of assets in exchange for equity interest in investment company
​ ​ ​ ​ (4.0) ​ ​ ​ ​ ​ — ​ ​ ​ ​ ​ — ​ ​ ​ ​ ​ — ​ ​ ​ ​ ​ — ​ ​ ​ ​ ​ — ​ ​
Payment-in-kind interest
​ ​ ​ ​ — ​ ​ ​ ​ ​ — ​ ​ ​ ​ ​ — ​ ​ ​ ​ ​ — ​ ​ ​ ​ ​ — ​ ​ ​ ​ ​ — ​ ​
Net realized gains (losses) and net change in unrealized appreciation (depreciation)
​ ​ ​ ​ (129.7) ​ ​ ​ ​ ​ (0.1) ​ ​ ​ ​ ​ — ​ ​ ​ ​ ​ (10.6) ​ ​ ​ ​ ​ — ​ ​ ​ ​ ​ (0.1) ​ ​
Balance as of June 30, 2026(2)
​ ​ ​ $ 586.4 ​ ​ ​ ​ $ 31.0 ​ ​ ​ ​ $ 10.0 ​ ​ ​ ​ $ 49.6 ​ ​ ​ ​ $ — ​ ​ ​ ​ $ 0.7 ​ ​
Change in unrealized appreciation
(depreciation) on investments
still held as June 30, 2026
​ ​ ​ $ (75.0) ​ ​ ​ ​ $ 0.1 ​ ​ ​ ​ $ — ​ ​ ​ ​ $ (10.6) ​ ​ ​ ​ $ — ​ ​ ​ ​ $ — ​ ​
 
​   ​ ​
42
​

​
​ FIRST HALF 2026 SHAREHOLDER LETTER AND SEMIANNUAL REPORT   |   Eagle Point Credit Company ​
Eagle Point Credit Company & Subsidiaries
Notes to Consolidated Financial Statements
June 30, 2026
(Unaudited)
​ ​ ​
Loans and
Notes
​ ​
Preferred
Stock
​ ​
Rated Feeder
Fund Equity
​ ​
Regulatory
Capital Relief
Securities
​ ​
Royalties
​ ​
Warrants
​ ​
Total
​
Balance as of January 1, 2026
​ ​ ​ $ 67.8 ​ ​ ​ ​ $ 3.0 ​ ​ ​ ​ $ 1.2 ​ ​ ​ ​ $ 107.6 ​ ​ ​ ​ $ — ​ ​ ​ ​ $ 0.3 ​ ​ ​ ​ $ 1,203.9 ​ ​
Purchases of investments
​ ​ ​ ​ 115.8 ​ ​ ​ ​ ​ 5.3 ​ ​ ​ ​ ​ 0.7 ​ ​ ​ ​ ​ 10.0 ​ ​ ​ ​ ​ 0.4 ​ ​ ​ ​ ​ 0.5 ​ ​ ​ ​ ​ 197.1 ​ ​
Proceeds from sales or maturity of investments
​ ​ ​ ​ (70.4) ​ ​ ​ ​ ​ 0.0 ​ ​ ​ ​ ​ — ​ ​ ​ ​ ​ (2.6) ​ ​ ​ ​ ​ — ​ ​ ​ ​ ​ — ​ ​ ​ ​ ​ (339.2) ​ ​
Non-cash transfer of assets
in exchange for equity
interest in investment
company
​ ​ ​ ​ — ​ ​ ​ ​ ​ — ​ ​ ​ ​ ​ — ​ ​ ​ ​ ​ (90.6) ​ ​ ​ ​ ​ — ​ ​ ​ ​ ​ — ​ ​ ​ ​ ​ (94.6) ​ ​
Payment-in-kind interest
​ ​ ​ ​ 2.9 ​ ​ ​ ​ ​ 0.1 ​ ​ ​ ​ ​ — ​ ​ ​ ​ ​ — ​ ​ ​ ​ ​ — ​ ​ ​ ​ ​ — ​ ​ ​ ​ ​ 3.0 ​ ​
Net realized gains (losses) and net change in unrealized appreciation (depreciation)
​ ​ ​ ​ 27.5 ​ ​ ​ ​ ​ 0.1 ​ ​ ​ ​ ​ (0.2) ​ ​ ​ ​ ​ (0.4) ​ ​ ​ ​ ​ — ​ ​ ​ ​ ​ — ​ ​ ​ ​ ​ (113.5) ​ ​
Balance as of June 30, 2026(2)
​ ​ ​ $ 143.6 ​ ​ ​ ​ $ 8.5 ​ ​ ​ ​ $ 1.7 ​ ​ ​ ​ $ 24.0 ​ ​ ​ ​ $ 0.4 ​ ​ ​ ​ $ 0.8 ​ ​ ​ ​ $ 856.7 ​ ​
Change in unrealized
appreciation (depreciation)
on investments still held as
June 30, 2026
​ ​ ​ $ 23.5 ​ ​ ​ ​ $ 0.1 ​ ​ ​ ​ $ (0.2) ​ ​ ​ ​ $ (0.8) ​ ​ ​ ​ $ — ​ ​ ​ ​ $ — ​ ​ ​ ​ $ (62.9) ​ ​
​
(1)
Includes $63.1 million of return of capital on CLO equity investments from recurring cash flows and distributions from called deals.
​
(2)
Amounts may not foot due to rounding.
​
Net realized gains or losses recorded for Level III investments are reported in the net realized gain (loss) on investments, foreign currency and cash equivalents balance in the Consolidated Statement of Operations. Net changes in unrealized appreciation or depreciation are reported in the net change in unrealized appreciation (depreciation) on investments, foreign currency and cash equivalents balance in the Consolidated Statement of Operations.
Fair Value — Valuation Techniques and Inputs
The Adviser has established valuation processes and procedures to ensure the valuation techniques are fair and consistent, and valuation inputs are supportable. Oversight of the valuation process is conducted by the Adviser’s Valuation Committee, comprised of senior personnel of the Adviser, the majority of which are not members of the Company’s portfolio management function. The Valuation Committee is responsible for overseeing the implementation of the Adviser’s written valuation policies, which have been approved by the Board, and evaluating the overall fairness and consistency of the valuation process. The Valuation Committee reviews and approves the fair value determinations of the Company’s portfolio investments on a monthly basis.
Valuation of CLO Equity
The Company’s investments in CLO equity have been valued using an independent pricing service, in accordance with the Adviser’s valuation policy approved by the Board. The independent pricing service applies a methodology incorporating market data, including reporting from trustees, executable bids, broker quotes from dealers with two-sided markets and transaction activity from comparable securities to those being valued.
To monitor the accuracy of the marks provided by the pricing service, the Adviser utilizes a third-party financial tool that projects future cash flows of CLO equity tranches based on detailed CLO-specific data, such as asset and liability information sourced from trustee reports, and market assumptions. Key inputs include, but are not limited to,
 
​   ​ ​
43
​

​
​ FIRST HALF 2026 SHAREHOLDER LETTER AND SEMIANNUAL REPORT   |   Eagle Point Credit Company ​
Eagle Point Credit Company & Subsidiaries
Notes to Consolidated Financial Statements
June 30, 2026
(Unaudited)
assumptions for loan default rates, recovery rates, prepayment rates, reinvestment rates and discount rates. These assumptions are determined by considering both observable and third-party market data, prevailing general market assumptions and conventions, and the Adviser’s own analysis.
While an active market may exist for CLO equity securities, it may not be active or observable for the specific investments held by the Company as of the reporting date, as such the Adviser categorizes CLO equity as level III within the fair value hierarchy.
Valuation of CLO Debt
The Company’s investments in CLO debt have been valued using an independent pricing service. The valuation methodology of the independent pricing service includes incorporating data comprised of observable market transactions, executable bids, broker quotes from dealers with two sided markets, as well as transaction activity from comparable securities to those being valued. As the independent pricing service contemplates real time market data and no unobservable inputs or significant judgment has been used by the Adviser in the valuation of the Company’s investment in CLO debt, such investments are considered Level II assets.
Valuation of Loan Accumulation Facilities
The Company’s investments in LAFs are valued in accordance with ASC 820, using the income approach, which reflects current market expectations of future cash flows (i.e., exit price).
LAFs are typically short to medium-term in nature and formed to acquire loans on an interim basis that are expected to form part of a specific CLO transaction. When the LAF governing documents require loans to be transferred to the CLO at original cost plus accrued interest, the Adviser determines the fair value based on the cost of the Company’s investment (i.e., the principal amount invested) and the Company’s attributable share of net investment income and any realized gains or losses reported by the trustee during the applicable reporting period.
If the loans are expected to be transferred to the CLO at market value due to provisions in the LAF governing documents or because the Adviser determines a CLO transaction is no longer anticipated, the Adviser will continue to fair value the LAF consistent using the income approach, but will modify the fair value measurement to reflect the change in exit strategy of the LAF to incorporate market expectations of the receipt of future amounts (i.e., exit price). In such cases, the fair value of the LAF will include the cost of the Company’s investment (i.e., the principal amount invested), the Company’s attributable share of unrealized gains or losses on the LAF’s underlying loan assets, net investment income and any realized gains or losses reported by the trustee during the applicable reporting period.
Due to the absence of an active market and the use of unobservable inputs, the Adviser categorizes LAFs as Level III investments within the fair value hierarchy.
Valuation of ABS, CFO Equity, Equipment Financing, Equity Securities, Loans and Notes, Preferred Stock, Rated Feeder Fund Equity, Regulatory Capital Relief Securities, Royalties and Warrants
The Adviser generally engages a nationally recognized independent valuation agent to determine fair value for the Company’s investments in ABS, CFO equity, equipment financing, equity securities, loans and notes, preferred stock, rated feeder fund equity, regulatory capital relief securities, royalties and warrants. The independent valuation agent typically performs a discounted cash flow analysis or other valuation technique appropriate for the facts and circumstances, to determine the fair value of such investments, ultimately providing a high and low valuation for each investment. The final valuation recorded by the Company falls within this range.
Due to the lack of observable inputs, the Adviser categorizes these investments as Level III investments within the fair value hierarchy.
 
​   ​ ​
44
​

​
​ FIRST HALF 2026 SHAREHOLDER LETTER AND SEMIANNUAL REPORT   |   Eagle Point Credit Company ​
Eagle Point Credit Company & Subsidiaries
Notes to Consolidated Financial Statements
June 30, 2026
(Unaudited)
Where available, the Adviser may also utilize the mid-point of an indicative broker quotation or independent pricing service quotation to value such investments as of the reporting date. Depending on the availability of an active market as of the reporting date, these investments may be classified as Level II or Level III within the fair value hierarchy.
Valuation of Exchange-Traded Investments
The Adviser values investments that are traded on a national securities exchange at their last reported closing price from the applicable exchange as of the measurement date. Due to their observability and active market, the Adviser categorizes such investments as Level I within the fair value hierarchy.
Valuation of Joint Venture Investments and Limited Partnership Interests
JV investments consist of common stock and senior unsecured notes issued by a JV entity. Limited partnership interests consist of limited partnership interests in investment funds. The Company values such investments using NAV as a practical expedient, unless it is probable that the Company will sell a portion of the investment at an amount different from NAV.
Valuation of Unsecured Notes and Term Preferred Shares
The Unsecured Notes and Term Preferred Shares are classified as Level I within the fair value hierarchy and are valued at their official closing price, as reported by the NYSE.
Investment Risk Factors
The following list is not intended to be a comprehensive list of the potential risks associated with the Company. The Company’s prospectus provides a detailed discussion of the Company’s risks and considerations. The risks described in the prospectus are not the only risks the Company faces. Additional risks and uncertainties not currently known to the Company or that are currently deemed to be immaterial also may materially and adversely affect its business, financial condition and/or operating results.
Risks of Investing in CLOs and Other Structured Debt Securities
CLOs and similar structured finance securities in which the Company invests are backed by a pool of credit-related assets that serve as collateral. Accordingly, such securities present risks similar to those of other types of credit investments, including default (credit), interest rate and prepayment risks. Adverse credit events impacting a CLO’s or structured finance security’s underlying collateral would be expected to reduce cash flows payable to the Company as investor in the equity tranche. Compression of credit spreads on a CLO’s underlying senior secured loans, absent a commensurate (in timing or magnitude) refinancing or reset of the CLO’s liabilities, would generally reduce the residual cash flows available to the CLO equity. In addition, there is a risk that majority lenders to an underlying loan or other debt instrument held by a CLO or structured finance security could amend or otherwise modify the loan or debt instrument to the detriment of the CLO or structured finance security (including, for example, by transferring collateral or otherwise reducing the priority of the CLO’s or structured finance security’s investment within the borrower’s capital structure). Such actions would impair the value of the CLO’s or structured finance security’s investment and, ultimately, the Company. In addition, CLOs and structured finance securities present risks related to the capability of the servicer of the securitized assets. CLOs and other structured finance securities are often governed by a complex series of legal documents and contracts, which increases the risk of dispute over the interpretation and enforceability of such documents relative to other types of investments. There is also a risk that the trustee or other servicer does not properly carry out its duties to the CLO or structured finance security, potentially resulting in loss. CLOs and certain structured finance securities are also inherently leveraged vehicles and therefore subject to leverage risk.
The Company may also invest in structured securities that are collateralized by other types of assets. For example, the Company may invest in collateralized fund obligations (“CFOs”) or rated feeders, which typically consist of tranches of
 
​   ​ ​
45
​

​
​ FIRST HALF 2026 SHAREHOLDER LETTER AND SEMIANNUAL REPORT   |   Eagle Point Credit Company ​
Eagle Point Credit Company & Subsidiaries
Notes to Consolidated Financial Statements
June 30, 2026
(Unaudited)
notes and/or equity issued by a special purpose vehicle that holds limited partnership interests in one or more private funds. Investments in CFOs and rated feeders are generally subject to the risks applicable to the underlying fund collateral, including uncertainty as to the amount and timing of underlying fund distributions, transfer restrictions and general illiquidity of underlying fund investments, dependence of the performance of the underlying funds’ general partner and key personnel, leverage risks, and general market and economic factors.
Subordinated Securities Risk
Certain securities in which the Company invests, including equity and junior debt tranches of CLOs, CFOs, and other structured securities, are subordinate to more senior tranches. These securities are subject to increased risks of default relative to the holders of superior priority interests in the same issuer. In addition, at the time of issuance, certain securities, including CLO equity securities and certain CFO securities, are under-collateralized in that the face amount of the debt and equity at inception exceeds the issuer’s total assets. The Company will typically be in a subordinated or first loss position with respect to realized losses on the underlying assets held by the CLOs, CFOs, and similar securities in which the Company is invested.
High Yield Investment Risk
Certain investments of the Company, including CLO equity and junior debt securities, are rated below investment grade or unrated. Such securities are sometimes referred to as “higher yield” or “junk” securities and are considered speculative with respect to timely payment of interest and repayment of principal. The senior secured loans and other credit-related assets underlying certain investments, including CLOs, may also be higher yield investments. Investing in such investments involves greater credit and liquidity risk than investment grade obligations, which may adversely impact our performance.
Leverage Risk
The use of leverage, whether directly or indirectly through investments such as CLOs, CFOs, and other subordinated instruments that inherently involve leverage, may magnify the Company’s risk of loss. CLO equity or junior debt securities, in particular, are very highly leveraged (with CLO equity securities typically being leveraged ten times). The CLO securities and other inherently leveraged instruments in which the Company invests are subject to a high degree of risk of loss.
Credit Risk
If (1) a CLO in which the Company invests, (2) an underlying asset of any such CLO or (3) any other type of credit investment in the Company’s portfolio declines in price or fails to pay interest or principal when due because the issuer or debtor, as the case may be, experiences a decline in its financial status, the Company’s income, NAV and/or market price would be adversely impacted. Additionally, interest on a CLO or other credit investment may be paid in kind or deferred and capitalized (paid in the form of obligations of the same type rather than cash), which involves continued exposure to default risk with respect to such payments.
Risks of Default on Underlying Assets
A default and any resulting loss on an underlying asset will reduce its fair value and, consequently, the fair value of the related investment and the Company’s portfolio. A wide range of factors could adversely affect the ability of the issuer of an underlying asset to make interest or other payments on that asset. Any defaults and losses will have a negative impact on the fair value of the Company’s investments and will reduce the cash flows that the Company receives from its investments.
Key Personnel Risk
The Adviser manages our investments. Consequently, the Company’s success depends, in large part, upon the services of the Adviser and the skill and expertise of the Adviser’s professional personnel. There can be no assurance that the
 
​   ​ ​
46
​

​
​ FIRST HALF 2026 SHAREHOLDER LETTER AND SEMIANNUAL REPORT   |   Eagle Point Credit Company ​
Eagle Point Credit Company & Subsidiaries
Notes to Consolidated Financial Statements
June 30, 2026
(Unaudited)
professional personnel of the Adviser will continue to serve in their current positions or continue to be employed by the Adviser. We can offer no assurance that their services will be available for any length of time or that the Adviser will continue indefinitely as the Company’s investment adviser.
Conflicts of Interest Risk
The Company’s executive officers and trustees, and the Adviser and certain of its affiliates and their officers and employees, including the members of the Adviser’s Senior Investment Team, have several conflicts of interest as a result of the other activities in which they engage. For example, the members of the Adviser’s investment team are and may in the future become affiliated with entities engaged in business activities similar to ours and may have conflicts of interest in allocating their time. Moreover, each member of the Adviser’s Senior Investment Team is engaged in other business activities which divert their time and attention from the Company. As a result of these separate business activities, the Adviser has conflicts of interest in allocating management time, services and functions among us, other advisory clients and other business ventures.
Prepayment Risk
The assets underlying the CLO securities and certain other asset-backed issuers in which the Company invests are subject to prepayment by the underlying corporate borrowers. As such, these securities are subject to prepayment risk. If the Company or a CLO collateral manager (or other applicable asset manager) are unable to reinvest prepaid amounts in a new investment with an expected rate of return at least equal to that of the investment repaid, the Company’s investment performance will be adversely impacted. Other debt instruments in which the Company invests are also subject to prepayment risk, particularly where the instrument has passed or is not subject to a “non-call” period.
Liquidity Risk
Generally, there is no public market for the CLO investments and certain other credit assets in which the Company invests. As such, the Company may not be able to sell such investments quickly, or at all. If the Company is able to sell such investments, the prices the Company receives may not reflect the Adviser’s assessment of their fair value or the amount paid for such investments by the Company.
Incentive Fee Risk
The Company’s incentive fee structure and the formula for calculating the fee payable to the Adviser may incentivize the Adviser to pursue speculative investments and use leverage in a manner that adversely impacts the Company’s performance.
Fair Valuation of the Company’s Portfolio Investments
Generally, there is no public market for the CLO investments and certain other credit assets in which the Company may invest. The Adviser values these securities at least quarterly, or more frequently as may be required from time to time, at fair value. The Adviser’s determinations of the fair value of the Company’s investments have a material impact on the Company’s net earnings through the recording of unrealized appreciation or depreciation of investments and may cause the Company’s NAV on a given date to understate or overstate, possibly materially, the value that the Company ultimately realizes on one or more of the Company’s investments.
Limited Investment Opportunities Risk
The market for CLO securities and certain other credit assets in which the Company invests is more limited than the market for other credit-related investments. The Company can offer no assurances that sufficient investment opportunities for the Company’s capital will be available. An increase in the number of, and flow of capital into, investment vehicles established to pursue investments in CLO securities may result in greater competition for investment opportunities, which may result in an increase in the price of such investments relative to the risk taken on by holders of
 
​   ​ ​
47
​

​
​ FIRST HALF 2026 SHAREHOLDER LETTER AND SEMIANNUAL REPORT   |   Eagle Point Credit Company ​
Eagle Point Credit Company & Subsidiaries
Notes to Consolidated Financial Statements
June 30, 2026
(Unaudited)
such investments. Such competition may also result under certain circumstances in increased price volatility or decreased liquidity with respect to certain positions.
Non-Diversification Risk
The Company is a non-diversified investment company under the 1940 Act and expects to hold fewer investments than a diversified fund under the 1940 Act.
Market Risk
Political, regulatory, economic and social developments, and developments that impact specific economic sectors, industries or segments of the market, can affect the value of the Company’s investments. A disruption or downturn in the capital markets and the credit markets could impair the Company’s ability to raise capital, reduce the availability of suitable investment opportunities for the Company, or adversely and materially affect the value of the Company’s investments, any of which would negatively affect the Company’s business. These risks may be magnified if certain events or developments adversely interrupt the global supply chain and could affect companies worldwide.
Loan Accumulation Facilities Risk
The Company may invest in loan accumulation facilities (“LAFs”), which are short to medium term facilities often provided by the bank that will serve as placement agent or arranger on a CLO transaction and which acquire loans on an interim basis which are expected to form part of the portfolio of a future CLO. Investments in LAFs have risks similar to those applicable to investments in CLOs. Leverage is typically utilized in such a facility and as such the potential risk of loss will be increased for such facilities employing leverage. In the event a planned CLO is not consummated, or the loans are not eligible for purchase by the CLO, the Company may be responsible for either holding or disposing of the loans. This could expose the Company to credit and/or mark-to-market losses, and other risks.
Synthetic Investments Risk
The Company may invest in synthetic investments, such as significant risk transfer securities and credit risk transfer securities issued by banks or other financial institutions, or acquire interests in lease agreements that have the general characteristics of loans and are treated as loans for withholding tax purposes. In addition to the credit risks associated with the applicable reference assets, the Company will usually have a contractual relationship only with the counterparty of such synthetic investment, and not with the reference obligor of the reference asset. Accordingly, the Company generally will have no right to directly enforce compliance by the reference obligor with the terms of the reference asset nor will it have any rights of setoff against the reference obligor or rights with respect to the reference asset. The Company will not directly benefit from the collateral supporting the reference asset and will not have the benefit of the remedies that would normally be available to a holder of such reference asset. In addition, in the event of the insolvency of the counterparty, the Company may be treated as a general creditor of such counterparty, and will not have any claim with respect to the reference asset. Consequently, the Company will be subject to the credit risk of the counterparty as well as that of the reference obligor. As a result, concentrations of synthetic securities in any one counterparty subjects the Company to an additional degree of risk with respect to defaults by such counterparty as well as by the reference obligor.
Regulatory Capital Relief Investments Risk
Regulatory capital relief investments are credit risk transfers (“CRTs”) or significant risk transfers (“SRTs”). These transactions enable a bank or other issuer to transfer the credit risk associated with a pool of underlying obligations (or “reference assets”) to investors, such as the Company, in order to obtain regulatory capital relief, risk limit relief, and/or credit risk hedging with respect to the reference assets. Under these transactions, a third-party investor (e.g., the Company), agrees to absorb losses on a designated loan portfolio in exchange for a protection payment. By transferring the risk of credit losses from these assets away from a bank’s balance sheet, the bank can reduce the amount of
 
​   ​ ​
48
​

​
​ FIRST HALF 2026 SHAREHOLDER LETTER AND SEMIANNUAL REPORT   |   Eagle Point Credit Company ​
Eagle Point Credit Company & Subsidiaries
Notes to Consolidated Financial Statements
June 30, 2026
(Unaudited)
regulatory capital it is required to hold against the reference assets without having to take actions such as selling assets or raising equity capital. Under any such trades into which the Company enters, the Company will be exposed to the credit risk of the underlying portfolio, and if the loans in the portfolio default, which may be more likely if there is a general deterioration in credit markets, the principal of the Company’s credit-linked notes will be used to cover the losses. There may be a risk that the international regulatory framework for banks (known as “Basel III”) of the Bank for International Settlements, when fully implemented, may discourage such regulatory capital relief trades and/or may force banks to unwind some or all existing transactions.
Infrastructure Sector Risk
Infrastructure asset investments (“Infrastructure Assets”) may be subject to a variety of risks, not all of which can be foreseen or quantified, including: (i) the burdens of ownership of infrastructure: (ii) local, national and international political and economic conditions; (iii) the supply and demand for services from and access to infrastructure; (iv) the financial condition of users and suppliers of Infrastructure Assets; (v) changes in interest rates and the availability of funds which may render the purchase, sale or refinancing of Infrastructure Assets difficult or impracticable; (vi) changes in regulations, planning laws and other governmental rules; (vii) changes in fiscal and monetary policies; (viii) under-insured or uninsurable losses, such as force majeure acts and terrorist events; (ix) reduced investment in public and private infrastructure projects; and (x) other factors which are beyond the reasonable control of the Company. Many of the foregoing factors could cause fluctuations in usage, expenses and revenues, increasing the risk of default of the Company’s debt investments in Infrastructure Assets and causing the value of any related equity investments to decline. This could have a material adverse effect on the Company’s performance.
Asset-Based Finance Investments Risk
The Company may invest in asset-based finance (“ABF”) investments, which are credit instruments in which repayment is supported by cash flows generated by a defined pool of financial or operating assets rather than the general credit of a corporate borrower. ABF investments may include, among others, loans, notes, receivables, leases, and other structured credit instruments backed by assets such as equipment, vehicles, inventory, intellectual property, payment streams, contractual receivables, or other assets. These investments may be originated directly or acquired through secondary transactions and may be held in various forms, including whole loans, loan participations, asset-backed securities, or other structured instruments. The value of ABF investments is subject to the risk that the underlying obligors will be unable or unwilling to make principal or interest payments as they come due. ABF investments are also subject to the risk that the value of the collateral securing the obligations will decline or that the Company may be unable to realize the expected value of the collateral because of difficulties in liquidating or enforcing rights in the collateral. In addition, cash flows associated with ABF investments may be affected by factors such as the creditworthiness of the servicer, changes in prepayment rates, fluctuations in interest rates, structural features of the investment, and broader economic and market conditions. These factors may reduce the Company’s returns or result in losses.
Real Estate Investment-Related Risks
The Company may invest in securities or instruments backed by real estate or issued by REITs or other real estate-related issuers, which investments will be subject to the risks incident to the ownership and operation of real estate. Such risks include the risks associated with both the domestic and international general economic climates; local real estate conditions; risks due to dependence on cash flow; risks and operating problems arising out of the absence of certain construction materials; changes in supply of, or demand for, competing properties in an area (as a result, for instance, of over-building); the financial condition of tenants, buyers and sellers of properties; changes in availability of debt financing; energy and supply shortages; changes in the tax, real estate, environmental, and zoning laws and regulations; various uninsured or uninsurable risks; the ability of clients or third-party borrowers to manage the real
 
​   ​ ​
49
​

​
​ FIRST HALF 2026 SHAREHOLDER LETTER AND SEMIANNUAL REPORT   |   Eagle Point Credit Company ​
Eagle Point Credit Company & Subsidiaries
Notes to Consolidated Financial Statements
June 30, 2026
(Unaudited)
properties; and natural disasters and events such as COVID-19. Developments such as migration away from urban centers, an increase in work-from-home and greater reliance on telecommuting technologies, e-commerce and remote learning may result in long-lasting and fundamental changes in the demand for residential and commercial real estate in various locales. A shrinking tax base and a rise in budget deficits may compel certain state and local governments to implement property tax increases, which may have a detrimental effect on companies in the real-estate related sector.
Investments in Unsecured Debt
Certain of the Company’s investments are expected to constitute unsecured debt. While unsecured debt ranks senior to common stock or preferred equity of an issuer, unsecured debt effectively ranks subordinate in priority of payment to secured debt and may not have the benefit of financial covenants common for secured debt. Unlike secured debt, unsecured debt does not have the benefit of a lien with respect to specific collateral. In any liquidation, dissolution, bankruptcy or similar proceeding involving an issuer, the holders of the issuer’s secured debt may assert rights against the assets pledged to secure that debt in order to receive full payment of their debt before the assets may be used to pay other creditors of the issuer, including the Company. Accordingly, unsecured debt typically involves a heightened level of risk of loss of principal.
Investments in Secured Debt
The assets of the portfolio of the Company may include secured debt, which involve various degrees of risk of a loss of capital. The factors affecting an issuer’s secured debt, and its overall capital structure, are complex. Some secured loans may not necessarily have priority over all other debt of an issuer. For example, some secured loans may permit other secured obligations (such as overdrafts, swaps or other derivatives made available by members of the syndicate to the company), or involve secured loans only on specified assets of an issuer. Issuers of secured loans may have two tranches of secured debt outstanding each with secured debt on separate collateral. In the event of Chapter 11 filing by an issuer, the U.S. Bankruptcy Reform Act of 1978, as amended, authorizes the issuer to use a creditor’s collateral and to obtain additional credit by grant of a priority lien on its property, senior even to liens that were first in priority prior to the filing, as long as the issuer provides what the presiding bankruptcy judge considers to be “adequate protection” which may but need not always consist of the grant of replacement or additional liens or the making of cash payments to the affected secured creditor. The imposition of priority liens on the Company’s collateral would adversely affect the priority of the liens and claims held by the Company and could adversely affect the Company’s recovery on the affected debt. Any secured debt is secured only to the extent of its lien and only to the extent of underlying assets or incremental proceeds on already secured assets. Moreover, underlying assets are subject to credit, liquidity, and interest rate risk.
Currency Risk
Although the Company primarily makes investments denominated in U.S. dollars, the Company may make investments denominated in other currencies. The Company’s investments denominated in currencies other than U.S. dollars will be subject to the risk that the value of such currency will decrease in relation to the U.S. dollar. The Company may or may not hedge currency risk.
Hedging Risk
Hedging transactions seeking to reduce risks may result in poorer overall performance than if the Company had not engaged in such hedging transactions. Additionally, such transactions may not fully hedge the Company’s risks.
Reinvestment Risk
CLOs will typically generate cash from asset repayments and sales that may be reinvested in substitute assets, subject to compliance with applicable investment tests. If the CLO collateral manager causes the CLO to purchase substitute assets at a lower yield than those initially acquired or sale proceeds are maintained temporarily in cash, it would reduce the excess interest-related cash flow, thereby having a negative effect on the fair value of the Company’s assets and the
 
​   ​ ​
50
​

​
​ FIRST HALF 2026 SHAREHOLDER LETTER AND SEMIANNUAL REPORT   |   Eagle Point Credit Company ​
Eagle Point Credit Company & Subsidiaries
Notes to Consolidated Financial Statements
June 30, 2026
(Unaudited)
market value of the Company’s securities. In addition, the reinvestment period for a CLO may terminate early, which would cause the holders of the CLO’s securities to receive principal payments earlier than anticipated. There can be no assurance that the Company will be able to reinvest such amounts in an alternative investment that provides a comparable return relative to the credit risk assumed.
Interest Rate Risk
Fluctuations in interest rates, whether driven by governmental policy, inflation expectations, or other market factors, could adversely affect the Company’s results, including both the level of cash flows the Company generates and the market value of its portfolio investments.
Income from the Company’s investments in floating-rate instruments (including CLO debt securities) will generally rise or fall with changes in the Secured Overnight Financing Rate (“SOFR”) or another applicable benchmark rate.
In a sustained period of elevated interest rates and/or an economic downturn, loan default rates could rise, leading to higher credit losses that may reduce the Company’s cash flow, the fair value of its assets, and its operating results. Conversely, a significant decline in interest rates could decrease portfolio income over time as loans reprice at lower coupons.
An increase in interest rates may also negatively affect the value of the Company’s fixed-rate investments, such as high-yield bonds, and could increase the Company’s own financing costs to the extent it issues floating rate debt or refinances fixed-rate debt or preferred equity at higher rates in the future, thereby reducing net investment income.
Refinancing Risk
If the Company incurs debt financing and subsequently refinances such debt, the replacement debt may be at a higher cost and on less favorable terms and conditions. If the Company fails to extend, refinance or replace such debt financings prior to their maturity on commercially reasonable terms, the Company’s liquidity will be lower than it would have been with the benefit of such financings, which would limit the Company’s ability to grow, and holders of the Company’s common shares would not benefit from the potential for increased returns on equity that incurring leverage creates.
Risks relating to the Convertible Perpetual Preferred Shares Conversion Feature
The price of the Company’s common shares on the NYSE constantly fluctuates. Because the Convertible Perpetual Preferred Shares are convertible into the Company’s common shares based on a conversion price, which in turn is based on the price of the Company’s common shares, volatility or declining prices for the Company’s common shares during the period between when a holder delivers a notice of conversion (including the period in which the conversion price is determined) and the date shares delivered as settlement on conversion (which settlement may be in cash, the Company’s common shares or a combination thereof) are actually received by the holder could result in a holder receiving such shares at a time when the trading price thereof is significantly lower than the trading price of the Company’s common shares was at the time such holder delivered such notice of conversion or significantly lower than the trailing five-day volume weighted average price used to calculate the conversion price (as described further in the prospectus supplement for the Convertible Perpetual Preferred Shares). Such volatility or declining prices could also have a similar effect on the value of the Convertible Perpetual Preferred Shares or the trading price thereof, when and if the Convertible Perpetual Preferred Shares are listed on a national securities exchange.
The price of the Company’s common shares may fluctuate as a result of a variety of factors, many of which are beyond the Company’s control and may not be directly related to the Company’s ongoing performance. The factors include, but
 
​   ​ ​
51
​

​
​ FIRST HALF 2026 SHAREHOLDER LETTER AND SEMIANNUAL REPORT   |   Eagle Point Credit Company ​
Eagle Point Credit Company & Subsidiaries
Notes to Consolidated Financial Statements
June 30, 2026
(Unaudited)
are not limited to: price and volume fluctuations in the overall stock market from time to time; investor demand for the Company’s common shares; significant volatility in the market price and trading volume of securities of registered closed-end management investment companies or other companies in the Company’s sector, which are not necessarily related to the operating performance of these companies; changes in regulatory policies or tax guidelines with respect to RICs or registered closed-end management investment companies; the Company’s failure to qualify as a RIC or the loss of RIC status; any shortfall in revenue or net income or any increase in losses from levels expected by investors or securities analysts; changes, or perceived changes, in the value of our portfolio investments; departures of any members of the Adviser’s Senior Investment Team; operating performance of companies comparable to the Company; or general economic conditions and trends and other external factors.
The Company intends to settle conversions by paying or delivering, as applicable, cash, common shares or a combination thereof on or about the second business day following the determination of the settlement amount. However, the settlement period may be longer for operational reasons outside of the Company’s control, including extended processing times by the Company’s service providers and/or the converting holder’s custodial platform.
Tax Risk
If the Company fails to qualify for tax treatment as a RIC under Subchapter M of the Code for any reason, or otherwise becomes subject to corporate income tax, the resulting corporate taxes (and any related penalties) could substantially reduce the Company’s net assets, the amount of income available for distributions to the Company’s shareholders, and the amount of income available for payment of the Company’s other liabilities.
Derivatives Risk
Derivative instruments in which the Company may invest may be volatile and involve various risks different from, and in certain cases greater than, the risks presented by other instruments. The primary risks related to derivative transactions include counterparty, correlation, liquidity, leverage, volatility, over-the-counter trading, operational and legal risks. In addition, a small investment in derivatives could have a large potential impact on the Company’s performance, effecting a form of investment leverage on the Company’s portfolio. In certain types of derivative transactions, the Company could lose the entire amount of the Company’s investment; in other types of derivative transactions the potential loss is theoretically unlimited.
Counterparty Risk
The Company may be exposed to counterparty risk, which could make it difficult for the Company or the issuers in which the Company invests to collect on obligations, thereby resulting in potentially significant losses.
Price Risk
Investors who buy shares at different times will likely pay different prices.
Non-U.S. Investing Risk
Investing in foreign entities or issuers with underlying non-U.S. assets may expose us to additional risks not typically associated with investing in U.S. entities and issuers. These risks include changes in exchange control regulations, political and social instability, restrictions on the types or amounts of investment, the imposition of sanctions, tariffs, or other governmental restrictions, expropriation, imposition of foreign taxes, less liquid markets and less available information than is generally the case in the U.S., higher transaction costs, less government supervision of exchanges, brokers and issuers, less developed bankruptcy laws, difficulty in enforcing contractual obligations, lack of uniform accounting and auditing standards, currency fluctuations and greater price volatility. Further, we, and the issuers in which we invest, may have difficulty enforcing creditor’s rights in foreign jurisdictions.
 
​   ​ ​
52
​

​
​ FIRST HALF 2026 SHAREHOLDER LETTER AND SEMIANNUAL REPORT   |   Eagle Point Credit Company ​
Eagle Point Credit Company & Subsidiaries
Notes to Consolidated Financial Statements
June 30, 2026
(Unaudited)
Global Risk
Due to highly interconnected global economies and financial markets, the value of the Company’s securities and its underlying investments may go up or down in response to governmental actions and/or general economic conditions throughout the world. Events such as war, military conflict, acts of terrorism, social unrest, natural disasters, recessions, inflation, rapid interest rate changes, supply chain disruptions, sanctions, the enactment of trade tariffs, the spread of infectious illness or other public health threats could also significantly impact the Company and its investments.
Banking Risk
The possibility of future bank failures poses risks of reduced financial market liquidity at clearing, cash management and other custodial financial institutions. The failure of banks which hold cash on behalf of the Company, the Company’s underlying obligors, the collateral managers of the CLOs in which the Company invests (or managers of other securitized or pooled vehicles in which the Company invests), or the Company’s service providers could adversely affect the Company’s ability to pursue its investment strategies and objectives. For example, if an underlying obligor has a commercial relationship with a bank that has failed or is otherwise distressed, such obligor may experience delays or other disruptions in meeting its obligations and consummating business transactions. Additionally, if a collateral manager has a commercial relationship with a distressed bank, the manager may experience issues conducting its operations or consummating transactions on behalf of the CLOs it manages, which could negatively affect the performance of such CLOs (and, therefore, the performance of the Company).
4.
DERIVATIVE CONTRACTS
​
Forward Currency Contracts
The Company enters into forward currency contracts to manage its exposure to the foreign currencies in which certain investments are denominated. Risks associated with forward currency contracts include the potential inability of counterparties to meet the terms of their respective contracts and movements in fair value and exchange rates.
Warrants
The Company may receive warrants from issuers upon an investment in the debt or equity of an issuer. Warrants provide the Company with exposure to and potential gains upon equity appreciation of the issuer’s share price.
The value of a warrant has two components: time value and intrinsic value. A warrant has a limited life and expires on a certain date. As the expiration date of a warrant approaches, the time value declines. In addition, if the stock underlying the warrant declines in price, the intrinsic value of an in-the-money warrant will also decline. Furthermore, at expiration, if the price of the stock underlying the warrant does not exceed the warrant’s strike price, the warrant will expire worthless. As a result, the Company could potentially lose its entire investment in a warrant.
The Company is also exposed to counterparty risk, which arises from the potential failure of an issuer of warrants to settle exercised warrants. The maximum potential loss to the Company from counterparty risk is limited to the fair value of the contracts.
Volume of Derivative Activities
The Company considers the notional amounts, categorized by primary underlying risk, to be representative of the volume of its derivative activity during the six months ended as of June 30, 2026:
 
​   ​ ​
53
​

​
​ FIRST HALF 2026 SHAREHOLDER LETTER AND SEMIANNUAL REPORT   |   Eagle Point Credit Company ​
Eagle Point Credit Company & Subsidiaries
Notes to Consolidated Financial Statements
June 30, 2026
(Unaudited)
Amounts in millions
​ ​ ​
Notional amounts
​
Primary Underlying Risk
​ ​
Long Exposure
​ ​
Short exposure
​
Foreign Exchange Risk ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​
Forward Currency Contracts
​ ​ ​ $ 173.7 ​ ​ ​ ​ $ 4.6 ​ ​
Equity Price Risk ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​
Warrants(1) ​ ​ ​ ​ 0.8 ​ ​ ​ ​ ​ — ​ ​
​
(1)
Notional amounts presented for warrants is based on the fair value warrants at June 30, 2026.
​
Effect of Derivatives on the Consolidated Statement of Assets and Liabilities and Consolidated Statement of Operations
The following table presents the fair value amounts of derivative contracts included in the Consolidated Statement of Assets and Liabilities, categorized by type of contract, as of June 30, 2026. Balances are presented on a gross basis, prior to the application of counterparty and collateral netting. Additionally, the table identifies the realized and unrealized gain and loss amounts included in the Consolidated Statement of Operations, categorized by type of contract, for the six months ended June 30, 2026:
Amounts in millions
Type of Contracts
​ ​
Derivative
Assets
​ ​
Derivative
Liabilities
​ ​
Realized
Gain (Loss)
​ ​
Unrealized
Gain (Loss)
​
Forward Currency Contracts
​ ​ ​ $ 4.6 ​ ​ ​ ​ $ (0.1) ​ ​ ​ ​ $ 0.5 ​ ​ ​ ​ $ 4.9 ​ ​
Warrants
​ ​ ​ ​ 0.8 ​ ​ ​ ​ ​ — ​ ​ ​ ​ ​ — ​ ​ ​ ​ ​ — ​ ​
Offsetting of Assets and Liabilities
The Company is subject to master netting agreements with one counterparty. These agreements govern the terms of certain transactions and reduce the counterparty risk associated with relevant transactions by specifying offsetting mechanisms and collateral posting arrangements at prearranged exposure levels.
The following table presents potential effects of netting arrangements for derivative contracts, by counterparty, as reported in the Consolidated Statement of Assets and Liabilities as of June 30, 2026:
Amounts in millions
Type of Contracts
​ ​
Presented on the Consolidated Statement
of Assets and Liabilities
​ ​
Net Amount
​ ​
Collateral
(Received)
Pledged
​ ​
Aggregate
Counterparty
Exposure
​
​
Derivative Assets
​ ​
Derivative Liabilities
​
Counterparty 1
​ ​ ​ $ 4.6 ​ ​ ​ ​ $ (0.1) ​ ​ ​ ​ $ 4.5 ​ ​ ​ ​ $ 1.0 ​ ​ ​ ​ $ 5.5 ​ ​
​
5.
RELATED PARTY TRANSACTIONS
​
Investment Advisory Agreement
On June 6, 2014, the Company entered into an investment advisory agreement with the Adviser, which was amended and restated on May 16, 2017 (the “Advisory Agreement”). Pursuant to the terms of the Advisory Agreement, the Company pays the Adviser a management fee and an incentive fee for its services.
Management fee
The management fee is calculated at an annual rate equal to 1.75% of the Company’s “total equity base” and payable quarterly in arrears. “Total equity base” means the net asset value attributable to the common shares and the paid-in, or
 
​   ​ ​
54
​

​
​ FIRST HALF 2026 SHAREHOLDER LETTER AND SEMIANNUAL REPORT   |   Eagle Point Credit Company ​
Eagle Point Credit Company & Subsidiaries
Notes to Consolidated Financial Statements
June 30, 2026
(Unaudited)
stated, capital of the preferred shares. For the six months ended June 30, 2026, the Company incurred a management fee of $7.7 million, with a payable balance of $3.7 million as of June 30, 2026.
Incentive fee
The incentive fee is calculated and payable quarterly, in arrears, based on the Company’s pre-incentive fee net investment income (“PNII”) for the immediately preceding calendar quarter, and is subject to a hurdle rate, expressed as a rate of return on the value of the Company’s net assets, equal to 2.00% per quarter (8.00% annualized), and a “catch-up” feature. For this purpose, PNII means interest income, dividend income and any other income (including any other fees, such as commitment, origination, structuring, diligence and consulting fees or other fees the Company receives from an investment) accrued during the calendar quarter, minus the Company’s operating expenses for the quarter (including the management fee, expenses payable under the Administration Agreement (as defined below) and any interest expense and distributions paid on any issued and outstanding preferred shares or debt, but excluding the incentive fee). PNII includes, in the case of investments with a deferred interest feature (such as original issue discount, debt instruments with payment in-kind interest and zero coupon securities), accrued income that the Company has not yet received in cash. PNII excludes any realized or unrealized capital gains or losses. The portion of incentive fee that is attributable to deferred interest (such as payment-in-kind interest or original issue discount) will be paid to the Adviser, without interest, only if and to the extent the Company actually receives such deferred interest in cash, and any accrual thereof will be reversed if and to the extent such interest is reversed in connection with any write-off or similar treatment of the investment giving rise to any deferred interest accrual.
The Company pays the Adviser an incentive fee with respect to the Company’s PNII in each calendar quarter as follows:
(1)
no incentive fee if the Company’s PNII does not exceed the hurdle rate of 2.00%;
​
(2)
100% of the Company’s PNII with respect to that portion of such PNII, if any, exceeding the hurdle rate but equal to or less than 2.50% (the “catch-up”)
​
(3)
20% of the amount of the Company’s PNII, if any, exceeding 2.50%
​
For the six months ended June 30, 2026, the Company incurred an incentive fee of $8.9 million, with a payable balance of $9.2 million as of June 30, 2026.
Administration Agreement
On June 6, 2014, the Company entered into an administration agreement (the “Administration Agreement”) with the Administrator, an affiliate of the Adviser. Pursuant to the Administration Agreement, the Administrator provides a range of administrative services to the Company, including maintaining financial records, providing accounting services, calculating NAV, overseeing the preparation and filing of the Company’s tax returns, monitoring compliance with tax laws and regulations, assisting with audits conducted by an independent public accounting firm, managing the printing and disseminating reports to the Company’s shareholders, maintaining the Company’s website, supporting investor relations, overseeing the payment of the Company’s expenses, coordinating the performance of administrative and professional services rendered to the Company by third parties, and providing other administrative services as the Company may designate from time to time.
Payments under the Administration Agreement are equal to an amount based upon the Company’s allocable portion of the Administrator’s overhead incurred in performing its obligations under the Administration Agreement, including rent, compliance-related fees and expenses, and the Company’s allocable portion of the compensation of the Company’s
 
​   ​ ​
55
​

​
​ FIRST HALF 2026 SHAREHOLDER LETTER AND SEMIANNUAL REPORT   |   Eagle Point Credit Company ​
Eagle Point Credit Company & Subsidiaries
Notes to Consolidated Financial Statements
June 30, 2026
(Unaudited)
chief compliance officer, chief financial officer, chief operating officer and related support staff. The Company’s allocable portion of such compensation is based on an allocation of the time spent on the Company-related matters.
Certain accounting and other administrative services were delegated by the Administrator to SS&C Technologies, Inc. (“SS&C”). To the extent the Administrator outsources any of its functions, the Company pays the fees on a direct basis, without profit to the Administrator.
The Administration Agreement may be terminated by the Company without penalty upon not less than sixty days’ written notice to the Administrator and by the Administrator upon not less than ninety days’ written notice to the Company. The Administration Agreement is approved by the Board on an annual basis.
For the six months ended June 30, 2026, the Company was charged a total of $0.8 million in administration fees consisting of $0.5 million and $0.3 million, relating to services provided by the Administrator and SS&C, respectively, which are included in the Consolidated Statement of Operations and, of which $0.3 million was payable as of June 30, 2026.
Dealer Manager Agreement
On March 22, 2024, the Company entered into a dealer manager agreement (the “Dealer Manager Agreement”) with Eagle Point Securities LLC (the “Dealer Manager”), a registered broker-dealer and an affiliate of the Adviser, with respect to the offering of the Company’s Convertible Perpetual Preferred Shares. Pursuant to the terms of the Dealer Manager Agreement, the Dealer Manager acts as a distributor of the Company’s Convertible Perpetual Preferred Shares on a best-efforts basis, subject to various conditions. The Company’s Convertible Perpetual Preferred Shares are offered for sale through the Dealer Manager at a public offering price of $25.00 per share (the “Convertible Perpetual Preferred Shares Liquidation Preference”), subject to certain reductions. Under the Dealer Manager Agreement, the Dealer Manager also provides certain marketing and wholesale services in consideration of its receipt of a dealer manager fee.
The Company pays the Dealer Manager a selling commission of up to 6.0% of the Convertible Perpetual Preferred Shares Liquidation Preference for each share of the Series AA Convertible Perpetual Preferred Shares sold and a dealer manager fee of up to 2.0% of the Convertible Perpetual Preferred Shares Liquidation Preference for each share of the Series AA Convertible Perpetual Preferred Shares and Series AB Convertible Perpetual Preferred Shares sold. The Dealer Manager may reallow a portion or all of the selling commissions and/or the dealer manager fees to selling agents for selling the Convertible Perpetual Preferred Shares to customers. For the six months ended June 30, 2026, the Company did not incur commissions under the Dealer Manager Agreement.
On April 11, 2025, the Company entered into an At Market Issuance Dealer Manager Agreement, or the “ATM Dealer Manager Agreement,” with the Dealer Manager. Pursuant to the ATM Dealer Manager Agreement, the Company may offer and sell its common shares and Preferred Shares from time to time through the Dealer Manager (including through any sub-placement agent chosen by the Dealer Manager). For the six months ended June 30, 2026, the Company did not incur commissions under the ATM Dealer Manager Agreement.
Affiliated Ownership
As of June 30, 2026, the Adviser and senior investment team held an aggregate of 1.2% of the Company’s common shares, 0.2% of the Series C Term Preferred Shares and 0.02% of the Convertible Perpetual Preferred Shares. This represented 1.1% of the total outstanding voting shares of the Company as of June 30, 2026.
 
​   ​ ​
56
​

​
​ FIRST HALF 2026 SHAREHOLDER LETTER AND SEMIANNUAL REPORT   |   Eagle Point Credit Company ​
Eagle Point Credit Company & Subsidiaries
Notes to Consolidated Financial Statements
June 30, 2026
(Unaudited)
Joint Ventures
Senior Credit Corp 2022 LLC
On December 5, 2022, the Company (and certain other accounts managed by the Adviser) acquired unsecured notes and equity interests in a JV with a third-party internally-managed business development company (the “JV Partner”). The JV, Senior Credit Corp 2022 LLC, invests in secured loans and equipment financings to growth-stage companies that have been originated by the JV Partner. As of June 30, 2026, the Company held 6.68% of the JV’s outstanding equity.
Steamboat Credit Opportunities I LLC
On February 4, 2026, the Company entered into an agreement with a third-party investment firm to form Steamboat Credit Opportunities I LLC (“Steamboat Credit”), a JV that invests in certain regulatory capital relief securities. Steamboat Credit may incur leverage from time to time to finance its investment activities and for other corporate purposes. The Administrator serves as the administrator to Steamboat Credit. The Company has committed to fund up to $210 million of capital into Steamboat Credit, representing 87.5% of the vehicle’s economic ownership. On February 4, 2026, the Company made an in-kind capital contribution of regulatory capital relief securities with a fair value of approximately $90.6 million into Steamboat Credit. Subsequently, the Company received a return of capital distribution of $11.3 million, representing the capital of the third-party investment firm. Please refer to “Affiliated Investments” for further details on Steamboat Credit for the six months ended June 30, 2026.
Exemptive Relief
On July 18, 2025, the SEC issued an order granting the Company exemptive relief to co-invest in certain negotiated investments with affiliated investment funds managed by the Adviser, subject to certain conditions. Prior to July 18, 2025, the Company operated under exemptive relief from a previous order issued on March 17, 2015.
Affiliated Investments
The Company has investments that are considered affiliated investments, as defined under the 1940 Act. These represent investments in issuers where the Company and other funds managed by the Adviser or its affiliates collectively own 5% or more of the issuer’s outstanding voting securities.
The following investments were considered affiliated investments as of June 30, 2026:
Amounts in millions
Issuer
​ ​
Investment Description
​ ​
Interest
Income
​ ​
Dividend
Income
​ ​
Net Unrealized
Appreciation
(Depreciation) on
Investments, Foreign
Currency and Cash
Equivalents
​ ​
Fair
Value
​ ​
Funded
Commitment
​ ​
Unfunded
Commitment
​
Delta Leasing SPV III, LLC
​ ​
Senior Secured
Note, DD, 13.00%
(due 07/18/2030)
​ ​ ​ $ 0.8 ​ ​ ​ ​ $ — ​ ​ ​ ​ $ (0.0) ​ ​ ​ ​ $ 12.2 ​ ​ ​ ​ $ 12.2 ​ ​ ​ ​ $ 5.2 ​ ​
Delta Financial Holdings LLC
​ ​ Preferred Units ​ ​ ​ ​ — ​ ​ ​ ​ ​ — ​ ​ ​ ​ ​ (0.0) ​ ​ ​ ​ ​ 0.3 ​ ​ ​ ​ ​ 0.3 ​ ​ ​ ​ ​ N/A ​ ​
Delta Financial Holdings LLC
​ ​ Common Units ​ ​ ​ ​ — ​ ​ ​ ​ ​ — ​ ​ ​ ​ ​ — ​ ​ ​ ​ ​ 0.0 ​ ​ ​ ​ ​ 0.0 ​ ​ ​ ​ ​ N/A ​ ​
Delta Leasing SPV III, LLC
​ ​ Common Equity ​ ​ ​ ​ — ​ ​ ​ ​ ​ — ​ ​ ​ ​ ​ (0.0) ​ ​ ​ ​ ​ 0.6 ​ ​ ​ ​ ​ 0.0 ​ ​ ​ ​ ​ N/A ​ ​
Senior Credit Corp 2022 LLC
​ ​
Senior Unsecured
Note, 8.50%
(due 12/05/2028)
​ ​ ​ ​ 0.3 ​ ​ ​ ​ ​ — ​ ​ ​ ​ ​ — ​ ​ ​ ​ ​ 6.9 ​ ​ ​ ​ ​ 6.9 ​ ​ ​ ​ ​ N/A ​ ​
Senior Credit Corp 2022 LLC
​ ​ Common Stock ​ ​ ​ ​ — ​ ​ ​ ​ ​ 0.6 ​ ​ ​ ​ ​ (0.2) ​ ​ ​ ​ ​ 3.1 ​ ​ ​ ​ ​ 3.0 ​ ​ ​ ​ ​ N/A ​ ​
Steamboat Credit
Opportunities I LLC
​ ​
Common Units
​ ​ ​ ​ 3.0 ​ ​ ​ ​ ​ — ​ ​ ​ ​ ​ (2.3) ​ ​ ​ ​ ​ 77.0 ​ ​ ​ ​ ​ 79.3 ​ ​ ​ ​ ​ 130.7 ​ ​
Total(1) ​ ​ ​ ​ ​ ​ $ 4.1 ​ ​ ​ ​ $ 0.6 ​ ​ ​ ​ $ (2.5) ​ ​ ​ ​ $ 100.1 ​ ​ ​ ​ $ 101.7 ​ ​ ​ ​ $ 135.9 ​ ​
​
(1)
Amounts may not foot due to rounding.
​
 
​   ​ ​
57
​

​
​FIRST HALF 2026 SHAREHOLDER LETTER AND SEMIANNUAL REPORT   |   Eagle Point Credit Company​
Eagle Point Credit Company & Subsidiaries
Notes to Consolidated Financial Statements
June 30, 2026
(Unaudited)
6.
COMMON SHARES
​
As of June 30, 2026, an unlimited number of common shares were authorized, of which 133,010,748 shares were issued and outstanding.
Pursuant to a prospectus supplement filed with the SEC on April 11, 2025, the Company launched an ATM offering to sell up to $500 million aggregate amount of its common shares.
For the six months ended June 30, 2026, the following was issued in connection with the ATM offerings and DRIP:
Amounts in millions except share amounts
Security
​​
Shares sold
​​
Net Proceeds
​​
Sales Agent
Commissions
​
ATM Offerings​​​​​​​​​​​​​​​​
Common Shares
​​​​0​​​​$—​​​
$—
​
DRIP​​​​​​​​​​​​​​​​
Common Shares
​​​​730,122​​​​$3.4​​​
N/A
​
The Company announced on February 17, 2026, that its Board has authorized a program to repurchase up to $100 million of the Company’s common shares in the open market.
The repurchase program will remain in effect for one year, unless otherwise extended or earlier discontinued. The timing, manner, price and amount of any repurchases will depend on the Company’s common share price, market conditions, applicable legal requirements and other factors. The repurchase program does not require the Company to repurchase any common shares, and the program may be suspended, extended, modified or discontinued at any time. No repurchases have been made for the six months ended June 30, 2026.
7.
PREFERRED SHARES
​
As of June 30, 2026, the following preferred shares were issued and outstanding:
​​​
Mandatorily Redeemable
Preferred Shares
​​
Perpetual Preferred Shares
​
​
Series C Term
Preferred Shares
​​
Series D Perpetual
Preferred Shares
​​
Series AA
Convertible Perpetual
Preferred Shares
​​
Series AB
Convertible Perpetual
Preferred Shares
​
Shares Issued and Outstanding
​​​​1,820,190​​​​​4,218,232​​​​​5,832,236​​​​​278,368​​
Except as otherwise stated in the 1940 Act or the Company’s Declaration of Trust, each holder of a Preferred Share is entitled to one vote for each Preferred Share held on each matter submitted to a vote of the Company’s shareholders. The Company’s preferred and common shareholders vote together as a single class on all matters submitted to the Company’s shareholders, except that the Company’s preferred shareholders have the right to elect two trustees at all times. The remaining members of the Board are elected jointly by the Company’s preferred and common shareholders voting as a single class.
Mandatorily Redeemable Preferred Shares
The Company has accounted for its Term Preferred Shares as a liability under ASC 480 due to their mandatory redemption requirements. The Company has also elected the FVO under ASC 825 for each of its Term Preferred
 
​ ​​
58
​

​
​FIRST HALF 2026 SHAREHOLDER LETTER AND SEMIANNUAL REPORT   |   Eagle Point Credit Company​
Eagle Point Credit Company & Subsidiaries
Notes to Consolidated Financial Statements
June 30, 2026
(Unaudited)
Shares issuances. Accordingly, the Term Preferred Shares are reflected as a liability at fair value in the Consolidated Statement of Assets and Liabilities. The following table summarizes certain information as of and for six months ended June 30, 2026 pertaining to the Term Preferred Shares:
Amounts in millions
​​​​​​​​​​​​​​​
Change in fair value due to:
​
Security
​​
Maturity Date(1)
​​
Callable Date(2)
​​
Liquidation
Preference
​​
Fair
Value
(3)
​​
Market
Risk
(4)
​​
Instrument-
Specific Credit
Risk
(5)
​
Series C Term Preferred Shares
​​
June 30, 2031
​​
Callable
​​​$45.5​​​​$45.4​​​​$0.0​​​​$(0.3)​​
​
(1)
The date which the Company is required to redeem all outstanding Term Preferred Shares, at a redemption price of $25 per share (the “Liquidation Preference”), plus accumulated but unpaid dividends, if any.
​
(2)
The date which the Company may, at its sole option, redeem the outstanding Term Preferred Shares in whole or in part from time to time.
​
(3)
The Company has elected the FVO under ASC 825. Accordingly, the Term Preferred Shares are measured at fair value. Amounts are net of issuance premiums/discounts, if any.
​
(4)
Amounts are recorded as unrealized (appreciation) depreciation on liabilities at fair value under the FVO on the Consolidated Statement of Operations.
​
(5)
Amounts are recorded as unrealized (appreciation) depreciation on liabilities at fair value under the FVO on the Consolidated Statement of Comprehensive Income. The Company defines the change in fair value attributable to instrument-specific credit risk as the excess of the total change in fair value over the change in fair value attributable to changes in a base market rate, such as a U.S. treasury bond index with a similar maturity to the instrument being valued.
​
On January 30, 2026, the Company redeemed all of the outstanding shares of its Series F Term Preferred Stock. The Series F Term Preferred Stock was redeemed at a redemption price of $25, which totaled $62.2 million.
Perpetual Preferred Shares
The Company has accounted for its Series D Perpetual Preferred Shares and Convertible Perpetual Preferred Shares as temporary equity under ASC 480. Accordingly, the Perpetual Preferred Shares are reflected in the Consolidated Statement of Assets and Liabilities at its $25 per share liquidation preference, net of unamortized deferred issuance costs.
The following table summarizes certain information as of June 30, 2026 pertaining to the Perpetual Preferred Shares:
Amounts in millions
Security
​​
Maturity
Date
(1)
​​
Callable Date(2)
​​
Liquidation
Preference
​​
Deferred
Issuance
Costs
(3)
​​
Carrying
Value
(3)
​
Series D Perpetual Preferred Shares
​​
Perpetual
​​
November 29, 2026
​​​$105.5​​​​$(19.5)​​​​$86.0​​
Series AA Convertible Perpetual Preferred Shares
​​
Perpetual
​​
2 Years After Issuance
​​​​145.8​​​​​(4.6)​​​​​141.2​​
Series AB Convertible Perpetual Preferred Shares
​​
Perpetual
​​
2 Years After Issuance
​​​​7.0​​​​​(0.1)​​​​​6.9​​
Total
​​​​​​​​​$258.3​​​​$(24.2)​​​​$234.1​​
​
(1)
The Perpetual Preferred Shares do not have a stated maturity date.
​
(2)
The date which the Company may, at its option, redeem the outstanding Perpetual Preferred Shares in whole or in part from time to time. At any time on or after two years a share of Convertible Perpetual Preferred Shares has been outstanding, the Company may, at its sole option, convert to common shares or redeem in cash the outstanding shares at the Convertible Perpetual Preferred Shares Liquidation Preference, plus accrued but unpaid dividends. Under a conversion, the conversion price will represent the arithmetic average of the volume weighted average price per share of the Company’s common shares over each of the five consecutive trading days ending on the date of the conversion (the “Conversion Price”).
​
 
​ ​​
59
​

​
​FIRST HALF 2026 SHAREHOLDER LETTER AND SEMIANNUAL REPORT   |   Eagle Point Credit Company​
Eagle Point Credit Company & Subsidiaries
Notes to Consolidated Financial Statements
June 30, 2026
(Unaudited)
(3)
The Perpetual Preferred Shares are recorded net of deferred issuance cost, which consists of fees and expenses incurred in connection with the issuance of the Perpetual Preferred Shares and net of issuance premiums/(discounts), if any. Deferred issuance cost is amortized into expense when it is probable the Perpetual Preferred Shares become redeemable in the future.
​
Series AA Convertible Perpetual Preferred shareholders may elect to convert their Convertible Perpetual Preferred Shares at any time by delivering to the Company a notice of conversion, subject to a conversion fee of between 0% and 8%.
Series AB Convertible Perpetual Preferred shareholders may elect to convert their Convertible Perpetual Preferred Shares at any time by delivering to the Company a notice of conversion, subject to a clawback provision of three full months of earned interest in the first year of ownership.
For the six months ended June 30, 2026, 32,764 Series AA Convertible Perpetual Preferred Shares were converted by shareholders. As a result of the conversions, $0.8 million of carrying value was contributed to paid-in-capital and 186,123 common shares were issued.
For the six months ended June 30, 2026, 45,284 Series AB Convertible Perpetual Preferred Shares were converted by shareholders. As a result of the conversions, $1.1 million of carrying value was contributed to paid-in-capital and 284,480 common shares were issued.
For the six months ended June 30, 2026, 14,000 Series AA Convertible Perpetual Preferred Shares were redeemed by shareholders. As a result of the redemption, $0.4 million in redemption proceeds were paid realizing a loss of $6,457 reflected in realized gain (loss) on redemption of Convertible Perpetual Preferred Shares on the Consolidated Statement of Operations.
The Company may elect to settle the Convertible Perpetual Preferred Shares shareholder optional conversions in either cash or shares at the Conversion Price.
For the six months ended June 30, 2026, the Company issued 4,073 Series AA Convertible Perpetual Preferred Shares under the Company’s Convertible Perpetual Preferred Shares distribution reinvestment plan for total net proceeds to the Company of $0.1 million.
The Company has consolidated the issuance date and CUSIP numbers for certain shares of Series AA Convertible Perpetual Preferred Shares and Series AB Convertible Perpetual Preferred Shares for enhanced operational efficiency. Further information is available in the prospectus supplement relating to the offering and on the Company’s website at www.eaglepointcreditcompany.com.
See Note 2 “Summary of Significant Accounting Policies, Temporary Equity,” for additional information relating to the outstanding Perpetual Preferred Shares.
ATM Program
Pursuant to a prospectus supplement filed with the SEC on April 11, 2025, the Company launched an ATM offering to sell up to 927,447 Series C Term Preferred Shares, 1,681,768 Series D Preferred Shares and 513,756 shares of Series F Term Preferred Stock, excluding amounts sold under the previous program.
For the six months ended June 30, 2026, the Company did not sell Preferred Shares under the ATM program.
The Company has engaged a broker-dealer to repurchase opportunistically, on the Company’s behalf, the Company’s listed Preferred Shares through open market transactions. The price and other terms of any such repurchases will
 
​ ​​
60
​

​
​FIRST HALF 2026 SHAREHOLDER LETTER AND SEMIANNUAL REPORT   |   Eagle Point Credit Company​
Eagle Point Credit Company & Subsidiaries
Notes to Consolidated Financial Statements
June 30, 2026
(Unaudited)
depend on prevailing market conditions, the Company’s liquidity and other factors. Depending on market conditions, the amount of Preferred Shares repurchases may be material. Any Preferred Shares repurchases will comply with the provisions of the 1940 Act and the Securities Exchange Act of 1934. The repurchase of any such Preferred Shares would reduce the Company’s outstanding leverage.
For the six months ended June 30, 2026, the Company repurchased on the open market and subsequently retired 201,027 Series C Term Preferred Shares, representing $5.0 million in aggregate principal amount, for a total cost of $4.9 million, reflecting an approximate 2.1% discount to the Series C Term Preferred Shares’ principal amount.
See Note 9 “Asset Coverage” for further discussion on the Company’s calculation of asset coverage with respect to its Preferred Shares.
8.
UNSECURED NOTES
​
The following table summarizes the Unsecured Notes outstanding as of and for the six months ended June 30, 2026 and certain information associated with such Unsecured Notes:
Amounts in millions
​​​​​​​​​​​​​​​
Change in fair value due to:
​
Security
​​
Maturity Date(1)
​​
Callable Date(2)
​​
Principal
Amount
​​
Fair Value(3)
​​
Market Risk(4)
​​
Instrument-
Specific Credit
Risk
(5)
​
Series 2029 Notes
​​
January 31, 2029
​​
Callable
​​​$93.3​​​​$89.1​​​​$0.6​​​​$(0.6)​​
Series 2030 Notes
​​
June 30, 2030
​​
June 30, 2027
​​​​115.0​​​​​115.4​​​​​2.3​​​​​(2.2)​​
Total
​​​​​​​​​$208.3​​​​$204.5​​​​$2.9​​​​$(2.8)​​
​
(1)
The date which the Company is required to redeem outstanding Unsecured Notes.
​
(2)
The date which the Company may, at its sole option, redeem the outstanding Unsecured Notes in whole or in part from time to time at the Company’s option.
​
(3)
The Company has elected the FVO under ASC 825. Accordingly, the Unsecured Notes are measured at fair value.
​
(4)
Amounts are recorded as unrealized (appreciation) depreciation on liabilities at fair value under the FVO on the Consolidated Statement of Operations.
​
(5)
Amounts are recorded as unrealized (appreciation) depreciation on liabilities at fair value under the FVO on the Consolidated Statement of Comprehensive Income. The Company defines the change in fair value attributable to instrument-specific credit risk as the excess of the total change in fair value over the change in fair value attributable to changes in a base market rate, such as a U.S. Treasury bond index with a similar maturity to the instrument being valued.
​
The Company has engaged a broker-dealer to repurchase opportunistically, on the Company’s behalf, a portion of the Company’s Unsecured Notes through open market transactions. The price and other terms of any such repurchases will depend on prevailing market conditions, the Company’s liquidity and other factors. Depending on market conditions, the amount of Unsecured Note repurchases may be material. Any Unsecured Note repurchases will comply with the provisions of the 1940 Act and the Securities Exchange Act of 1934. Upon repurchase, the Company intends to retire the Unsecured Notes reducing the Company’s outstanding leverage.
For the six months ended June 30, 2026, the Company repurchased on the open market and subsequently retired $0.7 million in aggregate principal amount of the Series 2028 Notes for a total cost approximating par value. As a result of the repurchase and retirement of the Series 2028 Notes, the Company recognized a $251 realized gain on Preferred Shares and Unsecured Notes, which is reflected in the Consolidated Statement of Operations.
For the six months ended June 30, 2026, the Company repurchased on the open market and subsequently retired $1.5 million in aggregate principal amount of the Series 2031 Notes for a total cost approximating par value. As a result
 
​ ​​
61
​

​
​FIRST HALF 2026 SHAREHOLDER LETTER AND SEMIANNUAL REPORT   |   Eagle Point Credit Company​
Eagle Point Credit Company & Subsidiaries
Notes to Consolidated Financial Statements
June 30, 2026
(Unaudited)
of the repurchase and retirement of the Series 2031 Notes, the Company recognized a $1,430 realized gain on Preferred Shares and Unsecured Notes, which is reflected in the Consolidated Statement of Operations.
On May 8, 2026, the Company redeemed all of the outstanding principal amount of its Series 2028 Notes and 2031 Notes for redemption proceeds before interest of $31.7 million and $37.7 million, respectively.
See Note 9 “Asset Coverage” for further discussion on the Company’s calculation of asset coverage with respect to its Unsecured Notes.
9.
ASSET COVERAGE
​
Under the provisions of the 1940 Act, the Company is permitted to issue senior securities, including debt securities and preferred stock, and borrow from banks or other financial institutions, provided that the Company satisfies certain asset coverage requirements.
With respect to senior securities that are stocks, such as the Preferred Shares, the Company is required to have asset coverage of at least 200%, as measured at the time of issuance of any such senior securities that are stocks and calculated as the ratio of the Company’s total consolidated assets, less all liabilities and indebtedness not represented by senior securities, over the aggregate amount of the Company’s outstanding senior securities representing indebtedness plus the aggregate liquidation preference of any outstanding shares of senior securities that are stocks.
With respect to senior securities representing indebtedness, such as the Unsecured Notes or any bank borrowings (other than temporary borrowings as defined under the 1940 Act), the Company is required to have asset coverage of at least 300%, as measured at the time of borrowing and calculated as the ratio of the Company’s total consolidated assets, less all liabilities and indebtedness not represented by senior securities, over the aggregate amount of the Company’s outstanding senior securities representing indebtedness.
If the Company’s asset coverage declines below 300% (or 200%, as applicable), the Company would be prohibited under the 1940 Act from incurring additional debt or issuing additional preferred stock and from declaring certain distributions to its shareholders. In addition, the terms of the Preferred Shares and the Unsecured Notes require the Company to redeem the Preferred Shares and/or a certain principal amount of the Unsecured Notes, if such failure to maintain the applicable asset coverage is not cured by a certain date.
The following table summarizes the Company’s asset coverage with respect to its Preferred Shares and Unsecured Notes, as of June 30, 2026, and as of December 31, 2025:
Asset Coverage of Preferred Shares and Debt Securities
Amounts in millions
​​
As of
June 30, 2026
​​
As of
December 31, 2025
​
Total assets
​​​$1,140.1​​​​$1,394.9​​
Less liabilities and indebtedness not represented by senior securities
​​​​(56.6)​​​​​(22.2)​​
Net total assets and liabilities
​​​$1,083.5​​​​$1,372.7​​
Preferred Shares
​​​$303.7​​​​$373.1​​
Unsecured Notes
​​​​208.3​​​​​279.9​​
Total Preferred Shares and Unsecured Notes
​​​$512.0​​​​$653.0​​
Asset coverage of preferred shares(1)
​​​​212%​​​​​210%​​
Asset coverage of debt securities(2)
​​​​520%​​​​​490%​​
 
​ ​​
62
​

​
​FIRST HALF 2026 SHAREHOLDER LETTER AND SEMIANNUAL REPORT   |   Eagle Point Credit Company​
Eagle Point Credit Company & Subsidiaries
Notes to Consolidated Financial Statements
June 30, 2026
(Unaudited)
(1)
The asset coverage of preferred shares is calculated in accordance with section 18(h) of the 1940 Act, as generally described above.
​
(2)
The asset coverage ratio of debt securities is calculated in accordance with section 18(h) of the 1940 Act, as generally described above.
​
10.
COMMITMENTS AND CONTINGENCIES
​
The Company is not currently subject to any material legal proceedings. From time to time, the Company may be a party to certain legal proceedings in the ordinary course of business, including proceedings relating to the enforcement of the Company’s rights under contracts. While the outcome of these legal proceedings cannot be predicted with certainty, the Company does not expect these proceedings will have a material effect upon its financial condition or results of operations.
As of June 30, 2026, the Company had total unfunded investment commitments of $212.0 million arising from certain ABS, CFO equity, equity securities, loans and notes, preferred stock and rated feeder fund equity investments. As of June 30, 2026, the Company had recorded $0.1 million in liabilities at fair value for these unfunded investment commitments.
11.
INDEMNIFICATIONS
​
Under the Company’s organizational documents, its officers and trustees are indemnified against certain liabilities arising out of the performance of their duties to the Company. In addition, during the normal course of business, the Company enters into contracts containing a variety of representations which provide general indemnifications. The Company’s maximum exposure under these agreements cannot be known; however, the Company expects any risk of loss to be remote.
12.
SUBSEQUENT EVENTS
​
On July 31, 2026, the Company paid a monthly distribution of $0.06 per share of its common Shares, a monthly distribution of $0.135417 per share of its Series C Term Preferred Shares, a monthly distribution of $0.140625 per share of its Series D Perpetual Preferred Shares, and a monthly distribution of $0.145834 per share of its Convertible Perpetual Preferred Shares to holders of record as of July 13, 2026.
For the period from July 1, 2026 to July 31, 2026, the Company repurchased and subsequently retired 15,050 Series C Term Preferred Shares for total net cost of $0.4 million.
Management’s unaudited estimate of the range of the Company’s NAV per common share as of July 31, 2026, was between $4.33 and $4.43.
 
​ ​​
63
​

​
​FIRST HALF 2026 SHAREHOLDER LETTER AND SEMIANNUAL REPORT   |   Eagle Point Credit Company​
Eagle Point Credit Company & Subsidiaries
Notes to Consolidated Financial Statements
June 30, 2026
(Unaudited)
On August 13, 2026, the Company declared the following monthly distributions on its common shares and Preferred Shares.
​​
Security
​​​
Amount per
Share
​​​
Record Dates
​​​
Payable Dates
​​
​​
Common Shares
​​​
$0.06
​​​
October 13, 2026
November 10, 2026
December 11, 2026
​​​
October 30, 2026
November 30, 2026
December 31, 2026
​​
​​
Series C Term Preferred Shares
​​​
$0.135417
​​
​​
Series D Perpetual Preferred Shares
​​​
$0.140625
​​
​​
Series AA Convertible
Perpetual Preferred Shares
​​​
$0.145834
​​
​​
Series AB Convertible
Perpetual Preferred Shares
​​​
$0.145834
​​
Management of the Company has evaluated the need for disclosures and/or adjustments resulting from subsequent events through the date of release of this report. Management has determined there are no events in addition to those described above which would require adjustment to or disclosure in the consolidated financial statements and related notes through the date of release of this report.
 
​ ​​
64
​

​​​
​ FIRST HALF 2026 SHAREHOLDER LETTER AND SEMIANNUAL REPORT   |   Eagle Point Credit Company ​
Eagle Point Credit Company & Subsidiaries
Consolidated Financial Highlights
(Unaudited)​
 
​
Per Share Data
​ ​
For the six months
ended
June 30, 2026
​ ​
For the year
ended
December 31, 2025
​ ​
For the year
ended
December 31, 2024
​ ​
For the year
ended
December 31, 2023
​ ​
For the year
ended
December 31, 2022
​
​
Net asset value at beginning of period
​ ​ ​ $ 5.70 ​ ​ ​ ​ $ 8.38 ​ ​ ​ ​ $ 9.21 ​ ​ ​ ​ $ 9.07 ​ ​ ​ ​ $ 13.39 ​ ​
​
Net investment income(1)(2)
​ ​ ​ ​ 0.37 ​ ​ ​ ​ ​ 0.98 ​ ​ ​ ​ ​ 1.10 ​ ​ ​ ​ ​ 1.36 ​ ​ ​ ​ ​ 1.53 ​ ​
​
Perpetual Preferred Share distributions(2)
​ ​ ​ ​ (0.03) ​ ​ ​ ​ ​ (0.06) ​ ​ ​ ​ ​ (0.04) ​ ​ ​ ​ ​ (0.03) ​ ​ ​ ​ ​ (0.04) ​ ​
​
Convertible Perpetual Preferred Shares distributions and
amortization of offering costs
(2)
​ ​ ​ ​ (0.07) ​ ​ ​ ​ ​ (0.09) ​ ​ ​ ​ ​ (0.01) ​ ​ ​ ​ ​ — ​ ​ ​ ​ ​ — ​ ​
​
Net realized gain (loss) and change in unrealized appreciation (depreciation) on:
​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​
​
Investments, foreign currency and cash equivalents(2)(3)
​ ​ ​ ​ (0.90) ​ ​ ​ ​ ​ (1.65) ​ ​ ​ ​ ​ (0.31) ​ ​ ​ ​ ​ 0.48 ​ ​ ​ ​ ​ (4.39) ​ ​
​
Forward currency contracts(2)
​ ​ ​ ​ 0.04 ​ ​ ​ ​ ​ (0.10) ​ ​ ​ ​ ​ 0.06 ​ ​ ​ ​ ​ (0.02) ​ ​ ​ ​ ​ — ​ ​
​
Retirement of Preferred Shares and Unsecured Notes
​ ​ ​ ​ — ​ ​ ​ ​ ​ — ​ ​ ​ ​ ​ — ​ ​ ​ ​ ​ — ​ ​ ​ ​ ​ — ​ ​
​
Net change in unrealized (appreciation) depreciation on liabilities at fair value under the fair value option(2)
​ ​ ​ ​ (0.01) ​ ​ ​ ​ ​ (0.13) ​ ​ ​ ​ ​ 0.06 ​ ​ ​ ​ ​ (0.05) ​ ​ ​ ​ ​ 0.69 ​ ​
​
Net income (loss) and net increase (decrease) in net assets resulting from operations(2)
​ ​ ​ ​ (0.60) ​ ​ ​ ​ ​ (1.05) ​ ​ ​ ​ ​ 0.86 ​ ​ ​ ​ ​ 1.74 ​ ​ ​ ​ ​ (2.21) ​ ​
​
Common shares distributions from net investment
income
(4)
​ ​ ​ ​ (0.60) ​ ​ ​ ​ ​ (0.76) ​ ​ ​ ​ ​ (1.82) ​ ​ ​ ​ ​ (1.86) ​ ​ ​ ​ ​ (2.37) ​ ​
​
Common shares distributions from net realized gains on investments(4)
​ ​ ​ ​ — ​ ​ ​ ​ ​ — ​ ​ ​ ​ ​ — ​ ​ ​ ​ ​ — ​ ​ ​ ​ ​ — ​ ​
​
Common shares distributions from tax return of capital(4)
​ ​ ​ ​ — ​ ​ ​ ​ ​ (0.92) ​ ​ ​ ​ ​ (0.10) ​ ​ ​ ​ ​ — ​ ​ ​ ​ ​ — ​ ​
​
Total common shares distributions declared to
shareholders
(4)
​ ​ ​ ​ (0.60) ​ ​ ​ ​ ​ (1.68) ​ ​ ​ ​ ​ (1.92) ​ ​ ​ ​ ​ (1.86) ​ ​ ​ ​ ​ (2.37) ​ ​
​
Common shares distributions based on weighted average
shares impact
(5)
​ ​ ​ ​ 0.00 ​ ​ ​ ​ ​ 0.00 ​ ​ ​ ​ ​ 0.01 ​ ​ ​ ​ ​ — ​ ​ ​ ​ ​ (0.13) ​ ​
​
Total common shares distributions
​ ​ ​ ​ (0.60) ​ ​ ​ ​ ​ (1.68) ​ ​ ​ ​ ​ (1.91) ​ ​ ​ ​ ​ (1.86) ​ ​ ​ ​ ​ (2.50) ​ ​
​
Effect of other comprehensive income(2)(6)
​ ​ ​ ​ 0.01 ​ ​ ​ ​ ​ 0.01 ​ ​ ​ ​ ​ (0.08) ​ ​ ​ ​ ​ (0.09) ​ ​ ​ ​ ​ 0.15 ​ ​
​
Effect of paid-in capital contribution(2)
​ ​ ​ ​ — ​ ​ ​ ​ ​ — ​ ​ ​ ​ ​ — ​ ​ ​ ​ ​ — ​ ​ ​ ​ ​ — ​ ​
​
Effect of shares issued(7)
​ ​ ​ ​ — ​ ​ ​ ​ ​ 0.06 ​ ​ ​ ​ ​ 0.36 ​ ​ ​ ​ ​ 0.39 ​ ​ ​ ​ ​ 0.32 ​ ​
​
Effect of underwriting discounts, commissions and offering expenses associated with shares issued(7)
​ ​ ​ ​ — ​ ​ ​ ​ ​ (0.02) ​ ​ ​ ​ ​ (0.07) ​ ​ ​ ​ ​ (0.06) ​ ​ ​ ​ ​ (0.08) ​ ​
​
Effect of shares issued in accordance with the Company’s dividend reinvestment plan
​ ​ ​ ​ — ​ ​ ​ ​ ​ 0.00 ​ ​ ​ ​ ​ 0.01 ​ ​ ​ ​ ​ 0.02 ​ ​ ​ ​ ​ — ​ ​
​
Net effect of shares issued
​ ​ ​ ​ — ​ ​ ​ ​ ​ 0.04 ​ ​ ​ ​ ​ 0.30 ​ ​ ​ ​ ​ 0.35 ​ ​ ​ ​ ​ 0.24 ​ ​
​
Net asset value at end of period
​ ​ ​ $ 4.51 ​ ​ ​ ​ $ 5.70 ​ ​ ​ ​ $ 8.38 ​ ​ ​ ​ $ 9.21 ​ ​ ​ ​ $ 9.07 ​ ​
​
Per share market value at beginning of period
​ ​ ​ $ 5.76 ​ ​ ​ ​ $ 8.88 ​ ​ ​ ​ $ 9.50 ​ ​ ​ ​ $ 10.12 ​ ​ ​ ​ $ 14.00 ​ ​
​
Per share market value at end of period
​ ​ ​ $ 3.72 ​ ​ ​ ​ $ 5.76 ​ ​ ​ ​ $ 8.88 ​ ​ ​ ​ $ 9.50 ​ ​ ​ ​ $ 10.12 ​ ​
​
Total return based on market value(8)
​ ​ ​ ​ (25.62)% ​ ​ ​ ​ ​ (17.97)% ​ ​ ​ ​ ​ 14.66% ​ ​ ​ ​ ​ 18.92% ​ ​ ​ ​ ​ (11.60)% ​ ​
​
Common shares outstanding at end of period
​ ​ ​ ​ 133,010,748 ​ ​ ​ ​ ​ 131,810,023 ​ ​ ​ ​ ​ 111,835,004 ​ ​ ​ ​ ​ 76,948,138 ​ ​ ​ ​ ​ 55,045,981 ​ ​
​ Ratios and Supplemental Data: ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​
​
Net asset value at end of period
​ ​ ​ $ 599,482,932 ​ ​ ​ ​ $ 750,936,050 ​ ​ ​ ​ $ 936,867,759 ​ ​ ​ ​ $ 708,343,567 ​ ​ ​ ​ $ 499,265,764 ​ ​
​
Ratio of expenses to average net assets(9)(10)
​ ​ ​ ​ 10.36% ​ ​ ​ ​ ​ 9.21% ​ ​ ​ ​ ​ 8.58% ​ ​ ​ ​ ​ 8.51% ​ ​ ​ ​ ​ 9.94% ​ ​
​
Ratio of net investment income to average net assets(9)(10)
​ ​ ​ ​ 15.93% ​ ​ ​ ​ ​ 13.73% ​ ​ ​ ​ ​ 12.45% ​ ​ ​ ​ ​ 14.73% ​ ​ ​ ​ ​ 13.80% ​ ​
​
Portfolio turnover rate(11)
​ ​ ​ ​ 18.96% ​ ​ ​ ​ ​ 41.12% ​ ​ ​ ​ ​ 37.13% ​ ​ ​ ​ ​ 19.79% ​ ​ ​ ​ ​ 30.19% ​ ​
​
Asset coverage for preferred shares
​ ​ ​ ​ 212% ​ ​ ​ ​ ​ 210% ​ ​ ​ ​ ​ 263% ​ ​ ​ ​ ​ 371% ​ ​ ​ ​ ​ 286% ​ ​
​
Asset coverage for debt securities
​ ​ ​ ​ 520% ​ ​ ​ ​ ​ 490% ​ ​ ​ ​ ​ 506% ​ ​ ​ ​ ​ 551% ​ ​ ​ ​ ​ 423% ​ ​
See accompanying footnotes to the financial highlights on the following page.
 
​   ​ ​
65
​

​
​ FIRST HALF 2026 SHAREHOLDER LETTER AND SEMIANNUAL REPORT   |   Eagle Point Credit Company ​
Eagle Point Credit Company & Subsidiaries
Consolidated Financial Highlights
(Unaudited)
​
Per Share Data
​ ​
For the year ended
December 31, 2021
​ ​
For the year ended
December 31, 2020
​ ​
For the year ended
December 31, 2019
​ ​
For the year ended
December 31, 2018
​ ​
For the year ended
December 31, 2017
​
​
Net asset value at beginning of period
​ ​ ​ $ 11.18 ​ ​ ​ ​ $ 10.59 ​ ​ ​ ​ $ 12.40 ​ ​ ​ ​ $ 16.77 ​ ​ ​ ​ $ 17.48 ​ ​
​
Net investment income(1)(2)
​ ​ ​ ​ 1.31 ​ ​ ​ ​ ​ 1.15 ​ ​ ​ ​ ​ 1.34 ​ ​ ​ ​ ​ 1.59 ​ ​ ​ ​ ​ 1.88 ​ ​
​
Perpetual Preferred Share distributions(2)
​ ​ ​ ​ — ​ ​ ​ ​ ​ — ​ ​ ​ ​ ​ — ​ ​ ​ ​ ​ — ​ ​ ​ ​ ​ — ​ ​
​
Convertible Perpetual Preferred Shares distributions and
amortization of offering costs
(2)
​ ​ ​ ​ — ​ ​ ​ ​ ​ — ​ ​ ​ ​ ​ — ​ ​ ​ ​ ​ — ​ ​ ​ ​ ​ — ​ ​
​
Net realized gain (loss) and change in unrealized appreciation (depreciation) on:
​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​
​
Investments, foreign currency and cash
equivalents
(2)(3)
​ ​ ​ ​ 2.65 ​ ​ ​ ​ ​ 0.49 ​ ​ ​ ​ ​ (1.29) ​ ​ ​ ​ ​ (3.92) ​ ​ ​ ​ ​ 0.12 ​ ​
​
Forward currency contracts(2)
​ ​ ​ ​ — ​ ​ ​ ​ ​ — ​ ​ ​ ​ ​ — ​ ​ ​ ​ ​ — ​ ​ ​ ​ ​ — ​ ​
​
Retirement of Preferred Shares and Unsecured Notes
​ ​ ​ ​ — ​ ​ ​ ​ ​ — ​ ​ ​ ​ ​ — ​ ​ ​ ​ ​ — ​ ​ ​ ​ ​ — ​ ​
​
Net change in unrealized (appreciation) depreciation on liabilities at fair value under the fair value option(2)
​ ​ ​ ​ (0.02) ​ ​ ​ ​ ​ 0.01 ​ ​ ​ ​ ​ (0.08) ​ ​ ​ ​ ​ 0.06 ​ ​ ​ ​ ​ — ​ ​
​
Net income (loss) and net increase (decrease) in net assets resulting from operations(2)
​ ​ ​ ​ 3.94 ​ ​ ​ ​ ​ 1.65 ​ ​ ​ ​ ​ (0.03) ​ ​ ​ ​ ​ (2.27) ​ ​ ​ ​ ​ 2.00 ​ ​
​
Common shares distributions from net investment
income
(4)
​ ​ ​ ​ (1.64) ​ ​ ​ ​ ​ (0.26) ​ ​ ​ ​ ​ (1.40) ​ ​ ​ ​ ​ (1.51) ​ ​ ​ ​ ​ (2.60) ​ ​
​
Common shares distributions from net realized gains on investments(4)
​ ​ ​ ​ — ​ ​ ​ ​ ​ — ​ ​ ​ ​ ​ — ​ ​ ​ ​ ​ — ​ ​ ​ ​ ​ — ​ ​
​
Common shares distributions from tax return of
capital
(4)
​ ​ ​ ​ — ​ ​ ​ ​ ​ (1.06) ​ ​ ​ ​ ​ (1.00) ​ ​ ​ ​ ​ (0.89) ​ ​ ​ ​ ​ (0.05) ​ ​
​
Total common shares distributions declared to shareholders(4)
​ ​ ​ ​ (1.64) ​ ​ ​ ​ ​ (1.32) ​ ​ ​ ​ ​ (2.40) ​ ​ ​ ​ ​ (2.40) ​ ​ ​ ​ ​ (2.65) ​ ​
​
Common shares distributions based on weighted average
shares impact
(5)
​ ​ ​ ​ (0.04) ​ ​ ​ ​ ​ 0.02 ​ ​ ​ ​ ​ — ​ ​ ​ ​ ​ 0.01 ​ ​ ​ ​ ​ — ​ ​
​
Total common shares distributions
​ ​ ​ ​ (1.68) ​ ​ ​ ​ ​ (1.30) ​ ​ ​ ​ ​ (2.40) ​ ​ ​ ​ ​ (2.39) ​ ​ ​ ​ ​ (2.65) ​ ​
​
Effect of other comprehensive income(2)(6)
​ ​ ​ ​ (0.08) ​ ​ ​ ​ ​ 0.05 ​ ​ ​ ​ ​ (0.10) ​ ​ ​ ​ ​ 0.06 ​ ​ ​ ​ ​ — ​ ​
​
Effect of paid-in capital contribution(2)
​ ​ ​ ​ — ​ ​ ​ ​ ​ — ​ ​ ​ ​ ​ — ​ ​ ​ ​ ​ 0.06 ​ ​ ​ ​ ​ — ​ ​
​
Effect of shares issued(7)
​ ​ ​ ​ 0.06 ​ ​ ​ ​ ​ 0.20 ​ ​ ​ ​ ​ 0.77 ​ ​ ​ ​ ​ 0.29 ​ ​ ​ ​ ​ 0.27 ​ ​
​
Effect of underwriting discounts, commissions and offering expenses associated with shares issued(7)
​ ​ ​ ​ (0.03) ​ ​ ​ ​ ​ (0.02) ​ ​ ​ ​ ​ (0.07) ​ ​ ​ ​ ​ (0.12) ​ ​ ​ ​ ​ (0.11) ​ ​
​
Effect of shares issued in accordance with the Company’s dividend reinvestment plan
​ ​ ​ ​ — ​ ​ ​ ​ ​ 0.01 ​ ​ ​ ​ ​ 0.02 ​ ​ ​ ​ ​ — ​ ​ ​ ​ ​ 0.02 ​ ​
​
Net effect of shares issued
​ ​ ​ ​ 0.03 ​ ​ ​ ​ ​ 0.19 ​ ​ ​ ​ ​ 0.72 ​ ​ ​ ​ ​ 0.17 ​ ​ ​ ​ ​ 0.18 ​ ​
​
Net asset value at end of period
​ ​ ​ $ 13.39 ​ ​ ​ ​ $ 11.18 ​ ​ ​ ​ $ 10.59 ​ ​ ​ ​ $ 12.40 ​ ​ ​ ​ $ 16.77 ​ ​
​
Per share market value at beginning of period
​ ​ ​ $ 10.09 ​ ​ ​ ​ $ 14.61 ​ ​ ​ ​ $ 14.21 ​ ​ ​ ​ $ 18.81 ​ ​ ​ ​ $ 16.71 ​ ​
​
Per share market value at end of period
​ ​ ​ $ 14.00 ​ ​ ​ ​ $ 10.09 ​ ​ ​ ​ $ 14.61 ​ ​ ​ ​ $ 14.21 ​ ​ ​ ​ $ 18.81 ​ ​
​
Total return based on market value(8)
​ ​ ​ ​ 51.60% ​ ​ ​ ​ ​ (19.76)% ​ ​ ​ ​ ​ 20.15% ​ ​ ​ ​ ​ (13.33)% ​ ​ ​ ​ ​ 29.45% ​ ​
​
Common shares outstanding at end of period
​ ​ ​ ​ 37,526,810 ​ ​ ​ ​ ​ 32,354,890 ​ ​ ​ ​ ​ 28,632,119 ​ ​ ​ ​ ​ 23,153,319 ​ ​ ​ ​ ​ 18,798,815 ​ ​
​ Ratios and Supplemental Data: ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​
​
Net asset value at end of period
​ ​ ​ $ 502,304,335 ​ ​ ​ ​ $ 361,660,688 ​ ​ ​ ​ $ 303,272,860 ​ ​ ​ ​ $ 287,127,842 ​ ​ ​ ​ $ 315,256,439 ​ ​
​
Ratio of expenses to average net assets(9)(10)
​ ​ ​ ​ 9.71% ​ ​ ​ ​ ​ 10.56% ​ ​ ​ ​ ​ 10.00% ​ ​ ​ ​ ​ 9.85% ​ ​ ​ ​ ​ 10.43% ​ ​
​
Ratio of net investment income to average net assets(9)(10)
​ ​ ​ ​ 9.90% ​ ​ ​ ​ ​ 13.44% ​ ​ ​ ​ ​ 10.64% ​ ​ ​ ​ ​ 9.76% ​ ​ ​ ​ ​ 10.77% ​ ​
​
Portfolio turnover rate(11)
​ ​ ​ ​ 51.56% ​ ​ ​ ​ ​ 52.80% ​ ​ ​ ​ ​ 34.83% ​ ​ ​ ​ ​ 40.91% ​ ​ ​ ​ ​ 41.16% ​ ​
​
Asset coverage for preferred shares
​ ​ ​ ​ 313% ​ ​ ​ ​ ​ 354% ​ ​ ​ ​ ​ 279% ​ ​ ​ ​ ​ 246% ​ ​ ​ ​ ​ 268% ​ ​
​
Asset coverage for debt securities
​ ​ ​ ​ 534% ​ ​ ​ ​ ​ 534% ​ ​ ​ ​ ​ 476% ​ ​ ​ ​ ​ 477% ​ ​ ​ ​ ​ 537% ​ ​
See accompanying footnotes to the financial highlights on the following page.
 
​   ​ ​
66
​

​
​ FIRST HALF 2026 SHAREHOLDER LETTER AND SEMIANNUAL REPORT   |   Eagle Point Credit Company ​
Eagle Point Credit Company & Subsidiaries
Consolidated Financial Highlights
(Unaudited)
Footnotes to the Financial Highlights:
(1)
Per share distributions paid to Series A Term Preferred Stock, Series B Term Preferred Stock, Series C Term Preferred Shares and Series F Term Preferred Stock, and the aggregate amount of amortized deferred issuance costs and share issuance premiums associated with the Series A Term Preferred Stock, Series B Term Preferred Stock, Series C Term Preferred Shares and Series F Term Preferred Stock are reflected in net investment income, and totaled ($0.02) and ($0.00) per share of common shares, respectively, for the six months ended June 30, 2026, ($0.07) and ($0.00) per share of common shares, respectively, for the year ended December 31, 2025, ($0.08) and ($0.00) per share of common shares, respectively, for the year ended December 31, 2024, ($0.05) and ($0.00) per share of common shares, respectively, for the year ended December 31, 2023, ($0.08) and ($0.00) per share of common shares, respectively, for the year ended December 31, 2022, ($0.16) and ($0.01) per share of common shares, respectively, for the year ended December 31, 2021, ($0.12) and ($0.01) per share of common shares, respectively, for the year ended December 31, 2020, ($0.25) and ($0.02) per share of common shares, respectively, for the year ended December 31, 2019, ($0.33) and ($0.02) per share of common shares, respectively, for the year ended December 31, 2018, and ($0.40) and ($0.02) per share of common shares, respectively, for the year ended December 31, 2017.
​
(2)
Per share amounts are based on weighted average of common shares outstanding for the period.
​
(3)
Net realized gain (loss) and change in unrealized appreciation (depreciation) on investments, foreign currency and cash equivalents includes a balancing figure to reconcile to the change in net asset value (“NAV”) per share at the end of each period. The amount per share may not agree with the change in the aggregate net realized gain (loss) and change in unrealized appreciation (depreciation) on investments, foreign currency and cash equivalents for the period because of the timing of issuance of the Company’s common shares in relation to fluctuating market values for the portfolio.
​
(4)
The information provided is based on estimates available at each respective period. The Company’s final taxable income and the actual amount required to be distributed will be finally determined when the Company files its final tax returns and may vary from these estimates. The year ended December 31, 2022 includes a special distribution of $0.50 per share of common shares paid on January 24, 2023 to shareholders of record on December 23, 2022. The year ended December 31, 2021 includes a special distribution of $0.50 per share of common shares paid on January 24, 2022 to shareholders of record on December 23, 2021.
​
(5)
Represents the difference between the per share amount distributed to common shareholders of record and the per share amount distributed based on the weighted average of common shares outstanding for the period.
​
(6)
Effect of other comprehensive income is related to income/(loss) deemed attributable to instrument specific credit risk derived from changes in fair value associated with liabilities valued under the fair value option (ASC 825.)
​
(7)
Represents the effect per share of the Company’s ATM offerings, follow-on offerings and initial public offering. Effect of shares issued reflect the excess of offering price over management’s estimated NAV per share at the time of each respective offering.
​
(8)
Total return based on market value is calculated assuming the Company’s common shares were purchased at the market price as of the beginning of the period, and distributions paid to common shareholders during the period were reinvested at prices obtained by the Company’s dividend reinvestment plan, and the total number of shares were sold at the closing market price per share on the last day of the period. Total return does not reflect any sales load. Total return for the six months ended June 30, 2026 is not annualized.
​
(9)
Ratios for the six months ended June 30, 2026 are annualized. Ratios for the years ended December 31, 2022, December 31, 2021, December 31, 2020, December 31, 2019 and December 31, 2018 reflect the portion of incentive fee voluntarily waived by the Adviser of 0.06%, 0.03%, 0.06%, 0.03% and 0.09% of average net assets, respectively. Ratios for the years ended December 31, 2024, December 31, 2022, December 31, 2021 include excise tax of 0.03%, 0.41% and 0.49% of average net assets, respectively. Ratios for the year ended December 31, 2023 include excise tax refund of -0.12%.
​
(10)
Ratios for the six months ended June 30, 2026 are annualized. Ratios for the six months ended June 30, 2026 and the years ended December 31, 2025, December 31, 2024, December 31, 2023, December 31, 2022, December 31, 2021, December 31, 2020, December 31, 2019, December 31, 2018 and December 31, 2017, include interest expense on the Company’s Series A Term Preferred Stock, Series B Term Preferred Stock, Series C Term Preferred Shares, Series F Term Preferred Stock and the Unsecured Notes of 3.51%, 3.08%, 2.15%, 2.28%, 2.83%, 3.24%, 3.97%, 4.18%, 4.16% and 4.20% of average net assets, respectively. Ratios do not include distribution and amortization of offering cost on the Series D Perpetual Preferred Shares, Series AA Convertible Perpetual Preferred Shares and Series AB Convertible Perpetual Preferred Shares for the six months ended June 30, 2026 and the years ended December 31, 2025, December 31, 2024, December 31, 2023, December 31, 2022 and December 31, 2021 of 4.06%, 2.17%, 0.61%. 0.31%, 0.37% and 0.03%, respectively, of average net assets.
​
(11)
The portfolio turnover rate is calculated as the lesser of total investment purchases executed during the period or the total investment sales executed during the period and repayments of principal, divided by the average fair value of investments for the same period.
​
   
 
​   ​ ​
67
​

​​
​ FIRST HALF 2026 SHAREHOLDER LETTER AND SEMIANNUAL REPORT   |   Eagle Point Credit Company ​
Eagle Point Credit Company & Subsidiaries
Supplemental Information
(Unaudited)​
Class
​ ​
Total Amount Outstanding
Exclusive of Treasury
Securities
​ ​
Asset Coverage
Per Unit
(1)
​ ​
Involuntary Liquidating
Preference Per Unit
(2)
​ ​
Average Market
Value Per Unit
(3)
​ ​
For the six months ended June 30, 2026 ​ ​ ​ ​ ​ ​ ​ ​ ​ ​
Preferred Shares ​ ​ ​ $ 303,725,658 ​ ​ ​ ​ $ 52.91 ​ ​ ​ ​ $ 25 ​ ​ ​ ​ $ 23.00 ​ ​ ​
Unsecured Notes ​ ​ ​ $ 208,250,000 ​ ​ ​ ​ $ 5,202.70 ​ ​ ​
N/A
​ ​ ​ $ 24.62 ​ ​ ​
For the year ended December 31, 2025 ​ ​ ​ ​ ​
Preferred Shares ​ ​ ​ $ 373,106,809 ​ ​ ​ ​ $ 52.55 ​ ​ ​ ​ $ 25 ​ ​ ​ ​ $ 22.88 ​ ​ ​
Unsecured Notes ​ ​ ​ $ 279,900,875 ​ ​ ​ ​ $ 4,904.03 ​ ​ ​
N/A
​ ​ ​ $ 24.15 ​ ​ ​
For the year ended December 31, 2024 ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​
Preferred Shares ​ ​ ​ $ 264,232,758 ​ ​ ​ ​ $ 65.74 ​ ​ ​ ​ $ 25 ​ ​ ​ ​ $ 22.51 ​ ​ ​
Unsecured Notes ​ ​ ​ $ 285,523,800 ​ ​ ​ ​ $ 5,062.81 ​ ​ ​
N/A
​ ​ ​ $ 23.50 ​ ​ ​
For the year ended December 31, 2023 ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​
Preferred Shares ​ ​ ​ $ 83,223,700 ​ ​ ​ ​ $ 92.65 ​ ​ ​ ​ $ 25 ​ ​ ​ ​ $ 21.04 ​ ​ ​
Unsecured Notes ​ ​ ​ $ 170,523,800 ​ ​ ​ ​ $ 5,514.93 ​ ​ ​
N/A
​ ​ ​ $ 22.51 ​ ​ ​
For the year ended December 31, 2022 ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​
Preferred Shares ​ ​ ​ $ 81,587,250 ​ ​ ​ ​ $ 71.47 ​ ​ ​ ​ $ 25 ​ ​ ​ ​ $ 23.25 ​ ​ ​
Unsecured Notes ​ ​ ​ $ 170,523,800 ​ ​ ​ ​ $ 4,226.70 ​ ​ ​
N/A
​ ​ ​ $ 23.67 ​ ​ ​
For the year ended December 31, 2021 ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​
Preferred Shares ​ ​ ​ $ 98,130,500 ​ ​ ​ ​ $ 78.16 ​ ​ ​ ​ $ 25 ​ ​ ​ ​ $ 25.48 ​ ​ ​
Unsecured Notes ​ ​ ​ $ 138,584,775 ​ ​ ​ ​ $ 5,339.86 ​ ​ ​
N/A
​ ​ ​ $ 25.58 ​ ​ ​
For the year ended December 31, 2020 ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​
Preferred Shares ​ ​ ​ $ 47,862,425 ​ ​ ​ ​ $ 88.39 ​ ​ ​ ​ $ 25 ​ ​ ​ ​ $ 24.25 ​ ​ ​
Unsecured Notes ​ ​ ​ $ 93,734,775 ​ ​ ​ ​ $ 5,340.98 ​ ​ ​
N/A
​ ​ ​ $ 23.93 ​ ​ ​
For the year ended December 31, 2019 ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​
Preferred Shares ​ ​ ​ $ 69,843,150 ​ ​ ​ ​ $ 69.71 ​ ​ ​ ​ $ 25 ​ ​ ​ ​ $ 26.04 ​ ​ ​
Unsecured Notes ​ ​ ​ $ 98,902,675 ​ ​ ​ ​ $ 4,757.42 ​ ​ ​
N/A
​ ​ ​ $ 25.47 ​ ​ ​
For the year ended December 31, 2018 ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​
Preferred Shares ​ ​ ​ $ 92,568,150 ​ ​ ​ ​ $ 61.55 ​ ​ ​ ​ $ 25 ​ ​ ​ ​ $ 25.78 ​ ​ ​
Unsecured Notes ​ ​ ​ $ 98,902,675 ​ ​ ​ ​ $ 4,766.23 ​ ​ ​
N/A
​ ​ ​ $ 25.08 ​ ​ ​
For the year ended December 31, 2017 ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​ ​
Preferred Shares ​ ​ ​ $ 92,139,600 ​ ​ ​ ​ $ 66.97 ​ ​ ​ ​ $ 25 ​ ​ ​ ​ $ 25.75 ​ ​ ​
Unsecured Notes ​ ​ ​ $ 91,623,750 ​ ​ ​ ​ $ 5,372.28 ​ ​ ​
N/A
​ ​ ​ $ 25.96 ​ ​ ​
​
(1)
The asset coverage per unit figure is the ratio of the Company’s total consolidated assets, less all liabilities and indebtedness not represented by senior securities, to the aggregate dollar amount of outstanding applicable senior securities, as calculated separately for each of the Preferred Shares and the Unsecured Notes in accordance with section 18(h) of the 1940 Act. With respect to the Preferred Shares, the asset coverage per unit figure is expressed in terms of dollar amounts per share of outstanding preferred shares (based on a per share liquidation preference of $25.) With respect to the Unsecured Notes, the asset coverage per unit figure is expressed in terms of dollar amounts per $1,000 principal amount of such notes.
​
(2)
The involuntary liquidating preference per unit is the amount to which a share of Preferred Shares would be entitled in preference to any security junior to it upon our involuntary liquidation.
​
(3)
The average market value per unit is calculated by taking the average of the closing price (or $25 principal value for unlisted securities) for each of (a) a share of the Preferred Shares (NYSE: ECCA, ECCB, ECCC, ECCF, ECC PRD; Unlisted: ECC AA, ECC AB) and (b) for each $25 principal amount of the Unsecured Notes (NYSE: ECCU, ECCV, ECCW, ECCX, ECCY, ECCZ) for each day during the years for which each applicable security was outstanding. A $25 market value was assumed for unlisted securities.
​
   
 
​   ​ ​
68
​

​​
​ FIRST HALF 2026 SHAREHOLDER LETTER AND SEMIANNUAL REPORT   |   Eagle Point Credit Company ​
DIVIDEND REINVESTMENT PLANS
Dividend Reinvestment Plan for Common Shareholders
The Company has adopted a dividend reinvestment plan (“DRIP”) applicable to our common shares. Under the DRIP, each registered holder of at least one full common share will be automatically enrolled in the DRIP and distributions on the Company’s common shares are automatically reinvested in additional common shares of the Company by Equiniti Trust Company, LLC (the “DRIP Agent”) unless a shareholder “opts-out” of the DRIP. Common shareholders of the Company who receive distributions in the form of additional common shares of the Company are nonetheless required to pay applicable federal, state or local taxes on the reinvested distribution but will not receive a corresponding cash distribution with which to pay any applicable tax. Distributions that are reinvested through the issuance of new shares increase the Company’s shareholders’ equity on which a management fee is payable to the Adviser. If we declare a distribution payable in cash, common shareholders of the Company who opt-out of participation in the DRIP (including those holders whose shares are held through a broker or other nominee who has opted out of participation in the DRIP) generally will receive such distributions in cash.
The DRIP Agent, on the Company’s behalf, will primarily use newly-issued, authorized common shares to implement reinvestment of distributions under the DRIP (regardless of whether the outstanding shares are trading at a premium or at a discount to the Company’s NAV). However, the Company reserves the right to instruct the DRIP Agent to purchase common shares of the Company on the open market (on the NYSE or elsewhere) in connection with the reinvestment of distributions under the DRIP to the extent that the Company’s common shares are trading at a discount to NAV per share.
The number of common shares to be credited to each participant’s account will be determined based on the closing market price per common share on the payment date (the “Market Price”). If 95% of the Market Price is greater than the Company’s last determined NAV per share, the number of shares to be credited to each participant’s account pursuant to DRIP will be determined by dividing the aggregate dollar amount of the distribution by 95% of the Market Price. If 95% of the Market Price is less than the Company’s last determined NAV per share, the number of shares to be credited to each participant’s account pursuant to DRIP will be determined by dividing the aggregate dollar amount of the distribution by the lesser of (i) the last determined NAV per share and (ii) the Market Price.
In the event that the DRIP Agent is instructed to buy common shares on the open market, any shares so purchased will be allocated to each participant based upon the average purchase price (excluding any brokerage charges or other fees) of all shares purchased with respect to the distribution. In any case, the DRIP Agent (or the DRIP Agent’s broker) will have until the last business day before the next date on which the shares trade on an “ex-dividend” basis or 30 days after the payment date for the applicable distribution, whichever is sooner, to invest the distribution amount in shares acquired on the open market. To the extent that the DRIP Agent is unable to reinvest the full amount of the distribution through open market purchases, the balance shall be credited to participants’ accounts in the form of newly-issued common shares, in accordance with the procedures described above. Open market purchases may be made on any securities exchange where common shares are traded, in the over-the-counter market or in negotiated transactions, and may be on such terms as to price, delivery and otherwise as the DRIP Agent shall determine.
There are no brokerage charges with respect to common shares issued directly by the Company. However, whenever shares are purchased or sold on the NYSE or otherwise on the open market, each participant will pay a pro rata portion of brokerage trading fees, currently $0.07 per share purchased or sold. Brokerage trading fees will be deducted from amounts to be invested.
Common shareholders can also sell shares held in the DRIP account at any time by contacting the DRIP Agent in writing at Equiniti Trust Company, LLC, PO Box 10027, Newark, NJ 07101. The DRIP Agent will mail a check to such holder (less applicable brokerage trading fees) on the settlement date, which is three business days after the shares have been sold. If a shareholder chooses to sell its shares through a broker, the holder will need to request that the DRIP Agent electronically transfer their shares to the broker through the Direct Registration System.
 
​   ​ ​
69
​

​
​ FIRST HALF 2026 SHAREHOLDER LETTER AND SEMIANNUAL REPORT   |   Eagle Point Credit Company ​
Shareholders participating in the DRIP may withdraw from the DRIP at any time by contacting the DRIP Agent in writing at Equiniti Trust Company, LLC, PO Box 10027, Newark, NJ 07101. Such termination will be effective immediately if the notice is received by the DRIP Agent prior to any dividend or distribution record date; otherwise, such termination will be effective on the first trading day after the payment date for such dividend or distribution and thus apply to any subsequent dividend or distribution. If a holder of the Company’s common shares withdraws, full shares will be credited to their account, and the shareholder will be sent a check for the cash adjustment of any fractional share at the market value per share of the Company’s common shares as of the close of business on the day the termination is effective, less any applicable fees. Alternatively, if the shareholder wishes, the DRIP Agent will sell their full and fractional shares and send the shareholder the proceeds, less a transaction fee of $15.00 and less brokerage trading fees of $0.07 per share. If a shareholder does not maintain at least one whole common share in the DRIP account, the DRIP Agent may terminate such shareholder’s participation in the DRIP after written notice. Upon termination, shareholders will be sent a check for the cash value of any fractional share in the DRIP account, less any applicable broker commissions and taxes.
Shareholders who are not participants in the DRIP but hold at least one full common share may join the DRIP by notifying the DRIP Agent in writing at Equiniti Trust Company, LLC, PO Box 10027, Newark, NJ 07101. If received in proper form by the DRIP Agent before the record date of a dividend, the election will be effective with respect to all dividends paid after such record date. If a shareholder wishes to participate in the DRIP and their shares are held in the name of a brokerage firm, bank or other nominee, the shareholder should contact their nominee to see if it will participate in the DRIP. If a shareholder wishes to participate in the DRIP, but the brokerage firm, bank or other nominee is unable to participate on their behalf, the shareholder will need to request that their shares be re-registered in their own name, or the shareholder will not be able to participate. The DRIP Agent will administer the DRIP on the basis of the number of shares certified from time to time by the shareholder as representing the total amount registered in their name and held for their account by their nominee.
The Company and the DRIP Agent reserve the right to amend or terminate the DRIP upon written notice to each participant at least 30 days before the record date for the payment of any dividend or distribution by the Company.
All correspondence or additional information about the DRIP should be directed to Equiniti Trust Company, LLC, PO Box 10027, Newark, NJ 07101.
Dividend Reinvestment Plan for Convertible Perpetual Preferred Shareholders
The Company has adopted a DRIP applicable to our Convertible Perpetual Preferred Shares. Under this DRIP, each holder of at least one full share of our Convertible Perpetual Preferred Shares will be automatically enrolled in our DRIP and distributions on shares of our Convertible Perpetual Preferred Shares are automatically reinvested in additional shares of the applicable series of Convertible Perpetual Preferred Shares at a 5% discount to the liquidation preference by Computershare Trust Company, N.A. (as the DRIP agent) unless the holder opts out of our DRIP. Holders of our Convertible Perpetual Preferred Shares who receive distributions in the form of additional shares of our Convertible Perpetual Preferred Shares are nonetheless subject to the applicable federal, state or local taxes on the reinvested distribution but will not receive a corresponding cash distribution with which to pay any applicable tax. Shares of Convertible Perpetual Preferred Shares received through our DRIP will have the same original issue date for purposes of the Holder Optional Conversion Fee (as described in the prospectus supplement for the offering) and for other terms of the Convertible Perpetual Preferred Shares based on issuance date as the Convertible Perpetual Preferred Shares for which the dividend was declared. For more information on our DRIP, please contact Computershare Trust Company, N.A. at Computershare Trust Company, N.A., P.O. Box 43007 Providence, RI 02940-3006.
 
​   ​ ​
70
​

​​
​FIRST HALF 2026 SHAREHOLDER LETTER AND SEMIANNUAL REPORT   |   Eagle Point Credit Company​
ADDITIONAL INFORMATION
Shareholder Meeting Information
At a special meeting of shareholders of the Company held on March 12, 2026, the common and preferred shareholders of the Company, voting together as a single class, approved a change in the Company’s legal form from a Delaware corporation to a Delaware statutory trust. The voting results were as follows:
​
Shares Voted “For”
​​
Shares Voted “Against”
​​
Shares Voted “Abstain”
​
​
73,296,555
​​
14,911,655
​​
3,688,755
​
At the annual meeting of shareholders of the Company held on May 12, 2026, the shareholders of the Company voted to elect two trustees, with each trustee to serve until the Company’s 2029 annual meeting of shareholders or until his successor is duly elected and qualifies. The voting results were as follows:
Nominee
​​
Shares Voted “For”
​​
Shares “Withheld”
​​
Broker Non-Votes
​
Kevin F. McDonald(1)
​​​​83,312,971​​​​​10,204,242​​​​​0​​
Thomas P. Majewski(2)
​​​​8,619,048​​​​​650,286​​​​​0​​
​
(1)
Elected by the holders of the outstanding shares of the Company’s common shares and preferred shares, voting together as a single class.
​
(2)
Elected by the holders of the outstanding shares of the Company’s preferred shares, voting separately as a single class.
​
The following individuals’ terms of office as directors also continued after the annual meeting given that each person was not up for election at the annual meeting: Scott W. Appleby, James R. Matthews, Paul E. Tramontano and Jeffrey L. Weiss.
Investment Advisory Agreement
At a meeting held on May 12, 2026, the Board of Trustees (the “Board”) of Eagle Point Credit Company (the “Company”), including all of the trustees that are not interested persons of the Company (voting separately), unanimously voted to approve the continuation and renewal of the existing investment advisory agreement (the “Investment Advisory Agreement”) by and between the Company and Eagle Point Credit Management LLC (the “Adviser”) for an additional one-year period.
In reaching a decision to approve the continuation and renewal of the Investment Advisory Agreement, the Board, assisted by the advice of fund counsel, requested and received information and considered all the factors the Board believed relevant, including, among other things, the following: (1) the nature, extent and quality of services performed by the Adviser, including the investment performance of the Company, other comparable registered investment companies and a certain other account advised by the Adviser; (2) information regarding the fees and other expenses paid by the Company, including the cost of serv ices provided by the Adviser and its affiliates; (3) the profitability to the Adviser of its relationship with the Company, including certain ancillary and other benefits received by the Adviser; (4) comparative information on fees and expenses borne by other comparable registered investment companies and certain other accounts advised by the Adviser; (5) the extent to which economies of scale would be realized as the Company grows and whether fee levels reflect these economies of scale for the benefit of the Company’s investors; and (6) various other factors.
The Board’s decision to renew the Investment Advisory Agreement was not based on any single factor, but rather was based on a comprehensive consideration of the information provided to the Board at its meetings throughout the year. The Board did not assign relative weights to the factors considered by it as the Board conducted an overall analysis of these factors. Individual members of the Board may have given different weights to different factors.
The Board requested, considered and evaluated information regarding the following factors, among others:
Nature, Extent and Quality of Services and Performance
The Board reviewed and considered the nature, extent and quality of the services provided by the Adviser under the Investment Advisory Agreement. Among other things, the Board reviewed the most recent Form ADV for the Adviser and
 
​ ​​
71
​

​
​FIRST HALF 2026 SHAREHOLDER LETTER AND SEMIANNUAL REPORT   |   Eagle Point Credit Company​
information about the background and experience of the key personnel of the Adviser primarily responsible for the day-to-day portfolio management of the Company, including their experience in managing portfolios of CLO securities and the CLO industry knowledge of the Adviser’s senior investment team.
The Board also evaluated the ability of the Adviser to attract and retain high-caliber personnel. In this regard, the Board considered information regarding the Adviser’s compensation program, which is designed to provide both annual and long-term incentives for its personnel and to align personnel interests with the long-term success of the Adviser’s clients, including the Company.
In addition, the Board reviewed information about the Adviser’s investment process, financial stability, investment and risk management programs, the legal and compliance programs of the Adviser, and the Company’s use of leverage, the forms of leverage used by the Company and the effect of such leverage on the Company’s portfolio and performance and the Adviser’s profitability.
The Board then reviewed and considered the Company’s performance in terms of both (1) total return on a net asset value basis and (2) total return to common shareholders (assuming reinvestment of dividends), each during the 1-, 3-, 5- and 10-year periods ended December 31, 2025, and considered such performance in light of the Company’s investment objectives, strategies and risks.
The Board also considered and discussed the Company’s performance in comparison to the performance for various relevant periods of (1) six publicly listed, registered closed-end investment companies that have an investment strategy comparable to that of the Company (“Peer Group Companies”), (2) publicly listed, registered closed-end investment companies that have a portion of their assets invested in the types of securities in which the Company primarily invests (the “Peer Universe Companies” and together with the Peer Group Companies, the “Peer Companies”), (3) an account managed by the Adviser that is comparable to the Company in investment strategy and policy (“Comparable Account”), (4) a composite of estimates of CLO equity performance published by several Wall Street research firms and (5) an index deemed relevant by the Adviser. The Board considered the Adviser’s explanation of the differences between the Company’s and the Peer Companies’ strategies and portfolios. The Board also discussed and considered the Company’s recent performance in light of recent and current market conditions.
Based on the above factors, together with those referenced below, the Board concluded that it was generally satisfied with, and that the Company should continue to benefit from, the nature, extent and quality of services provided to the Company by the Adviser.
Investment Advisory Fee Rates and Total Expense Ratio
The Board then reviewed and considered the advisory fee rates, including the base management fee and incentive fee, payable by the Company to the Adviser under the Investment Advisory Agreement, and the total expense ratio of the Company. Additionally, the Board received and considered information comparing the advisory fee rates and total expense ratio of the Company with those of the Peer Companies and the advisory fee rates of the Comparable Account and an account managed by the Adviser that is comparable to the Company in investment strategy and policy (“CLO Equity Account”).
The Board noted that the Company’s contractual management fee rate was lower than or the same as that of four of the Peer Group Companies, higher than that of two of the Peer Group Companies and higher than the average contractual management fee rate of the Peer Group Companies. The Board considered that the Company’s net expense ratio was lower than the average of the Peer Group Companies. The Board further noted that the Company’s effective incentive fee rate was lower than two of the five Peer Group Companies that have an incentive fee.
The Board also considered the Company’s fees and expenses as compared to those of the Peer Universe Companies. The Board noted that the fee structures and the investment strategies and portfolios of the Peer Universe Companies are
 
​ ​​
72
​

​
​FIRST HALF 2026 SHAREHOLDER LETTER AND SEMIANNUAL REPORT   |   Eagle Point Credit Company​
materially different than those of the Company, and, therefore, the comparisons of the advisory fee rates and total expense ratios to such Peer Universe Companies were not particularly meaningful.
The Board also compared the advisory fee rates paid to the Adviser by each of the Company, the CLO Equity Account and the Comparable Account. The Board noted the differences in the management fee structures of the Company, the CLO Equity Account and the Comparable Account and that such differences could cause the Company to pay a higher or lower effective advisory fee rate than the CLO Equity Account and the Comparable Account in certain circumstances. The Board considered that the different rate structures are driven by investor expectations for the different fund/account structures, the additional complexity of the Adviser’s investment strategy in the regulatory and tax environment applicable to the Company’s portfolio and the costs associated with operating as an investment adviser for a publicly-listed registered investment company.
In considering the advisory fee rates, the Board also discussed the Company’s use of leverage, including the Company’s issuance of preferred shares and debt securities. The Board noted that while the Adviser believes that the prudent use of leverage is in the best interests of the Company and its shareholders, the use of leverage has the potential to increase the incentive fee paid by the Fund to the Adviser and, with respect to preferred shares, increases the base management fee paid by the Fund to the Adviser, and therefore creates a conflict of interest.
Based on its review, the Board concluded that each of the Company’s advisory fee rates and total expense ratio is fair and reasonable in light of the services provided to the Company and other factors considered.
Profitability
The Board also considered a profitability analysis of the Adviser and its affiliates with respect to the Company and the changes in such profitability over time. The Board concluded that, in light of the profitability information presented and other factors considered, the Adviser’s profitability was not excessive.
Economies of Scale
The Board considered information regarding whether the Investment Advisory Agreement reflects economies of scale for the benefit of the Company’s investors. The Board considered that given (1) the complexity and time required to manage and monitor the types of securities in which the Company invests, (2) the resource-intensive nature of acquiring and disposing of certain of the Company’s investments in the primary markets (particularly with respect to CLO equity and other structured investments) and (3) the limited size of individual transactions, any growth in the Company’s assets would be expected to require and had required additional investment resources, including personnel, and therefore generally would not meaningfully reduce the per unit cost of managing the Company’s portfolio. Based on the foregoing, the Board concluded that the opportunity of the Company to realize significant economies of scale is limited and the fee structure was appropriate given the Company’s investment objectives and strategies.
Other Benefits
The Board considered other benefits to the Adviser and its affiliates derived from their relationship with the Company. The Board considered the Adviser’s representation that these ancillary benefits could not be appropriately valued. The Board also considered that Eagle Point Securities LLC, an affiliate of the Adviser, serves as the dealer manager of the Company’s offering of unlisted convertible preferred shares and also of the Company’s at-the-market offering of common shares and listed preferred shares. The Board noted that, as dealer manager, Eagle Point Securities LLC generally receives a dealer manager fee in connection with sales of the convertible preferred shares and in connection with sales of shares in the at-the-market offering; however, the Board noted that generally all or a substantial portion of Eagle Point Securities LLC’s compensation is waived or re-allowed to the applicable third-party selling intermediary.
Based on the information reviewed and the discussions detailed above, the Board reached a determination, through the exercise of its business judgment, that the compensation payable to the Adviser pursuant to the Investment Advisory Agreement was fair and reasonable in light of the services provided to the Company by the Adviser and other factors considered.
 
​ ​​
73
​

​
​FIRST HALF 2026 SHAREHOLDER LETTER AND SEMIANNUAL REPORT   |   Eagle Point Credit Company​
Portfolio Information
The Company files its complete schedule of portfolio holdings with the SEC for the first and third quarters of each fiscal year as an exhibit to its reports on Form N-PORT. The Company’s Form N-PORT is available without charge, upon request by calling (844) 810-6501, or from the EDGAR Database on the SEC’s website (www.sec.gov).
Proxy Information
The Company has delegated its proxy voting responsibility to the Adviser. A description of these policies and procedures is available (1) without charge, upon request, by calling toll free (844) 810-6501; and (2) in the Company’s registration statement filed with the SEC on Form N-2 on April 11, 2025, which can be found on the SEC’s website (www.sec.gov).
Information regarding how the Company voted proxies relating to portfolio securities for the 12-month period ending June 30, 2026, is available: (1) without charge, upon request, by calling toll free (844) 810-6501; and (2) in the Company’s Form N-PX filing, which can be found on the SEC’s website (www.sec.gov). The Company also makes this information available on its website at www.EaglePointCreditCompany.com.
Privacy Notice
The Company is committed to protecting your privacy. This privacy notice explains the privacy policies of Eagle Point Credit Company and its affiliated companies. The terms of this notice apply to both current and former shareholders. The Company will safeguard, according to strict standards of security and confidentiality, all information it receives about you. With regard to this information, the Company maintains procedural safeguards that are reasonably designed to comply with federal standards. We have implemented procedures that are designed to restrict access to your personal information to authorized employees of the Company’s investment adviser, Eagle Point Credit Management LLC, and its affiliates who need to know your personal information to perform their jobs, and in connection with servicing your account. The Company’s goal is to limit the collection and use of information about you. While we may share your personal information with our affiliates in connection with servicing your account, our affiliates are not permitted to share your information with non-affiliated entities, except as permitted or required by law.
When you purchase the Company’s common shares and in the course of providing you with products and services, we and certain of our service providers, such as a transfer agent, may collect personal information about you, such as your name, address, social security number or tax identification number. This information may come from sources such as account applications and other forms, from other written, electronic or verbal correspondence, from your transactions, from your brokerage or financial advisory firm, financial adviser or consultant, and/or information captured on applicable websites.
We do not disclose any personal information provided by you or gathered by us to non-affiliated third parties, except as permitted or required by law or for our everyday business purposes, such as to process transactions or service your account. For example, we may share your personal information in order to send you annual and semiannual reports, proxy statements and other information required by law, and to send you information the Company believes may be of interest to you. We may disclose your personal information to unaffiliated third-party financial service providers (which may include a custodian, transfer agent, accountant or financial printer) who need to know that information in order to provide services to you or to the Company. These companies are required to protect your information and use it solely for the purpose for which they received it or as otherwise permitted by law. We may also provide your personal information to your brokerage or financial advisory firm and/or to your financial adviser or consultant, as well as to professional advisors, such as accountants, lawyers and consultants.
We reserve the right to disclose or report personal or account information to non-affiliated third parties in limited circumstances where we believe in good faith that disclosure is required by law, such as in accordance with a court order or at the request of government regulators or law enforcement authorities or to protect our rights or property. We may also disclose your personal information to a non-affiliated third party at your request or if you consent in writing to the disclosure.
 
​ ​​
74
​

​
​FIRST HALF 2026 SHAREHOLDER LETTER AND SEMIANNUAL REPORT   |   Eagle Point Credit Company​
If you have any questions or concerns about the privacy of your personal information, please contact our investor relations team at (203) 340-8510 or (844) 810-6501.
We will review this policy from time to time and may update it at our discretion.
* * * * *
 
​ ​​
75
​

​
​FIRST HALF 2026 SHAREHOLDER LETTER AND SEMIANNUAL REPORT   |   Eagle Point Credit Company​
End of Semiannual Report. Back Cover Follows.
 
​ ​​
76
​

​
cv_obc-4clr.jpg


Item 2. Code of Ethics


The information required by this Item is only required in an annual report on this Form N-CSR.


Item 3. Audit Committee Financial Expert


The information required by this Item is only required in an annual report on this Form N-CSR.


Item 4. Principal Accountant Fees and Services


The information required by this Item is only required in an annual report on this Form N-CSR.


Item 5. Audit Committee of Listed Registrant


The information required by this Item is only required in an annual report on this Form N-CSR.


Item 6. Investments


(a)A schedule of investments is included in the registrant’s report to stockholders under Item 1.


(b)Not applicable.


Item 7. Financial Statements and Financial Highlights For Open-End Management Investment Companies


Not applicable.


Item 8. Changes in and Disagreements With Accountants For Open-End Management Investment Companies


Not applicable.


Item 9. Proxy Disclosures for Open-End Management Investment Companies


Not applicable.


Item 10. Remuneration Paid to Directors, Officers, and Others of Open-End Management Investment Companies


Not applicable.


Item 11. Statement Regarding Basis For Approval of Investment Advisory Contract


Not applicable.


Item 12. Disclosure of Proxy Voting Policies and Procedures for Closed-End Management Investment Companies


The information required by this Item is only required in an annual report on this Form N-CSR.


Item 13. Portfolio Managers of Closed-End Investment Companies


(a)The information required by this Item is only required in an annual report on this Form N-CSR.


(b)There has been no change, as of the date of the filing of this N-CSR, to any of the portfolio managers identified in response to this item in the Registrant’s most recent annual report on Form N-CSR.


Item 14. Purchases of Equity Securities by Closed-End Management Investment Company and Affiliated Purchases


There have been no purchases by or on behalf of the registrant of shares or other units of any class of the registrant’s equity securities that are registered pursuant to Section 12 of the Exchange Act during the period covered by this report.


Item 15. Submission of Matters to a Vote of Security Holders


There have been no material changes to the procedures by which stockholders may recommend nominees to the registrant’s board of trustees.


Item 16. Controls and Procedures


(a)The registrant’s principal executive and principal financial officers, or persons performing similar functions, have concluded that the registrant’s disclosure controls and procedures (as defined in Rule 30(a)-3(c) under the Investment Company Act of 1940, as amended (the “1940 Act”)) are effective as of a date within 90 days of the filing of this report, based on the evaluation of these controls and procedures required by Rule 30a-3(b) under the 1940 Act and Rules 13a-15(b) or 15d-15(b) under the Exchange Act.


(b)There were no changes in the registrant’s internal control over financial reporting (as defined in Rule 30a-3(d) under the 1940 Act) that occurred during the period covered by this report that have materially affected, or are reasonably likely to materially affect, the registrant’s internal control over financial reporting.


Item 17. Disclosure of Securities Lending Activities for Closed-End Management Investment Companies


The registrant did not engage in securities lending activity during its most recent fiscal year.


Item 18. Recovery of Erroneously Awarded Compensation


Not applicable.


Item 19. Exhibits


(a) (3) Certifications pursuant to Section 302 of the Sarbanes-Oxley Act of 2002 filed herewith.


(b) Certifications pursuant to Section 906 of the Sarbanes-Oxley Act of 2002 filed herewith.


SIGNATURES


Pursuant to the requirements of the Securities Exchange Act of 1934 and the Investment Company Act of 1940, the registrant has duly caused this report to be signed on its behalf by the undersigned, thereunto duly authorized.


  EAGLE POINT CREDIT COMPANY
     
By:/s/ Thomas P. Majewski
    Thomas P. Majewski
    Chief Executive Officer (Principal Executive Officer)
Date:August 13, 2026


Pursuant to the requirements of the Securities Exchange Act of 1934 and the Investment Company Act of 1940, this report has been signed below by the following persons on behalf of the registrant and in the capacity and on the dates indicated.


By: /s/ Thomas P. Majewski  
  Thomas P. Majewski  
  Chief Executive Officer (Principal Executive Officer)  
Date: August 13, 2026  


By: /s/ Kenneth P. Onorio  
  Kenneth P. Onorio  
  Chief Financial Officer (Principal Financial Officer)  
Date: August 13, 2026