January 12, 2024
Mr. John Coleman
Division of Corporation Finance
Office of Energy & Transportation
Securities and Exchange Commission
Washington, DC 20549
| Re: | Jupiter Gold Corporation |
| Form 20-F for the Fiscal Year ended December 31, 2022 | |
| Filed April 28, 2023 | |
| File No. 333-214872 |
Dear Mr. Coleman,
Reference is made to the comment letter dated December 12, 2023 (the “Comment Letter”), sent by the staff of the Division of Corporation Finance, Office of Energy & Transportation (the “Staff”) of the Securities and Exchange Commission (the “SEC”) to Jupiter Gold Corporation (the “Company” or “Jupiter Gold”), relating to the Company’s annual report on Form 20-F for fiscal year ended December 31, 2022 (the “2022 Form 20-F”).
Below we copy in italics each comment from the Staff’s Comment Letter, followed by our response.
Form 20-F for the Fiscal Year ended December 31, 2022
Information on the Company, page 7
| 1. | We note that you have not provided the information about your Property, Plants and Equipment under the heading Information on the Company, as prescribed by Item 4.D of Form 20-F, though have included limited details regarding your mineral properties under Management’s Discussion and Analysis instead. |
Instruction 3 to Item 4 of Form 20-F requires issuers engaged in mining operations to provide the disclosures outlined in Subpart 1300 of Regulation S-K. We suggest that you reposition the mineral property disclosures to Item 4 to provide greater clarity, focus, and differentiation between such property details, and the discussion and analysis that is required by Item 5, regarding your financial condition and results of operations.
The disclosures pertaining to your mineral properties will need to be revised and expanded to clearly identify and distinguish between material properties and non material properties to address the requirements under Item 1303 and Item 1304 of Regulation S-K, as referenced in Item 1301(d) of Regulation S-K.
The summary disclosure should include a map of all properties to comply with Item 1303(b)(1) while the individual property disclosures should include the following details for each material property to comply with Item 1304(b) of Regulation S-K:
| ● | a map showing the location of the property that is accurate to within one mile using an easily recognizable coordinate system, | |
| ● | a description of infrastructure, | |
| ● | a description of the mineral rights, | |
| ● | a description of the work that you have completed on each property, | |
| ● | a description of the exploration plan, including timeframe and cost, and | |
| ● | the total cost or book value of the property at the end of the period. |
The summary disclosures should encompass all of your properties, including both material and non-material properties, and should appear in advance of and incremental to the individual property disclosures. The information required for the individual property disclosures are more extensive and detailed in comparison.
Please revise your filing to include and differentiate between the summary and individual property disclosures to comply with the aforementioned guidance.
We respectfully acknowledge the Staff’s comment and inform the Staff that the Company has two material properties, the Alpha Project and the Quartzite Project, as described in the 2022 Form 20-F. The Company will revise its disclosures under Property Plan and Equipment in its Form 20-F for the fiscal year ended December 31, 2023, to be filed on or before April 29, 2024, to reposition the mineral properties disclosures to be responsive to the Form 20-F requirements as well as to the requirements of Items 1303 and 1304 of Regulation S-K, and to ensure that the disclosure requirements of Items 1303 and 1304 of Regulation S-K are addressed in full. No other properties are considered material properties.
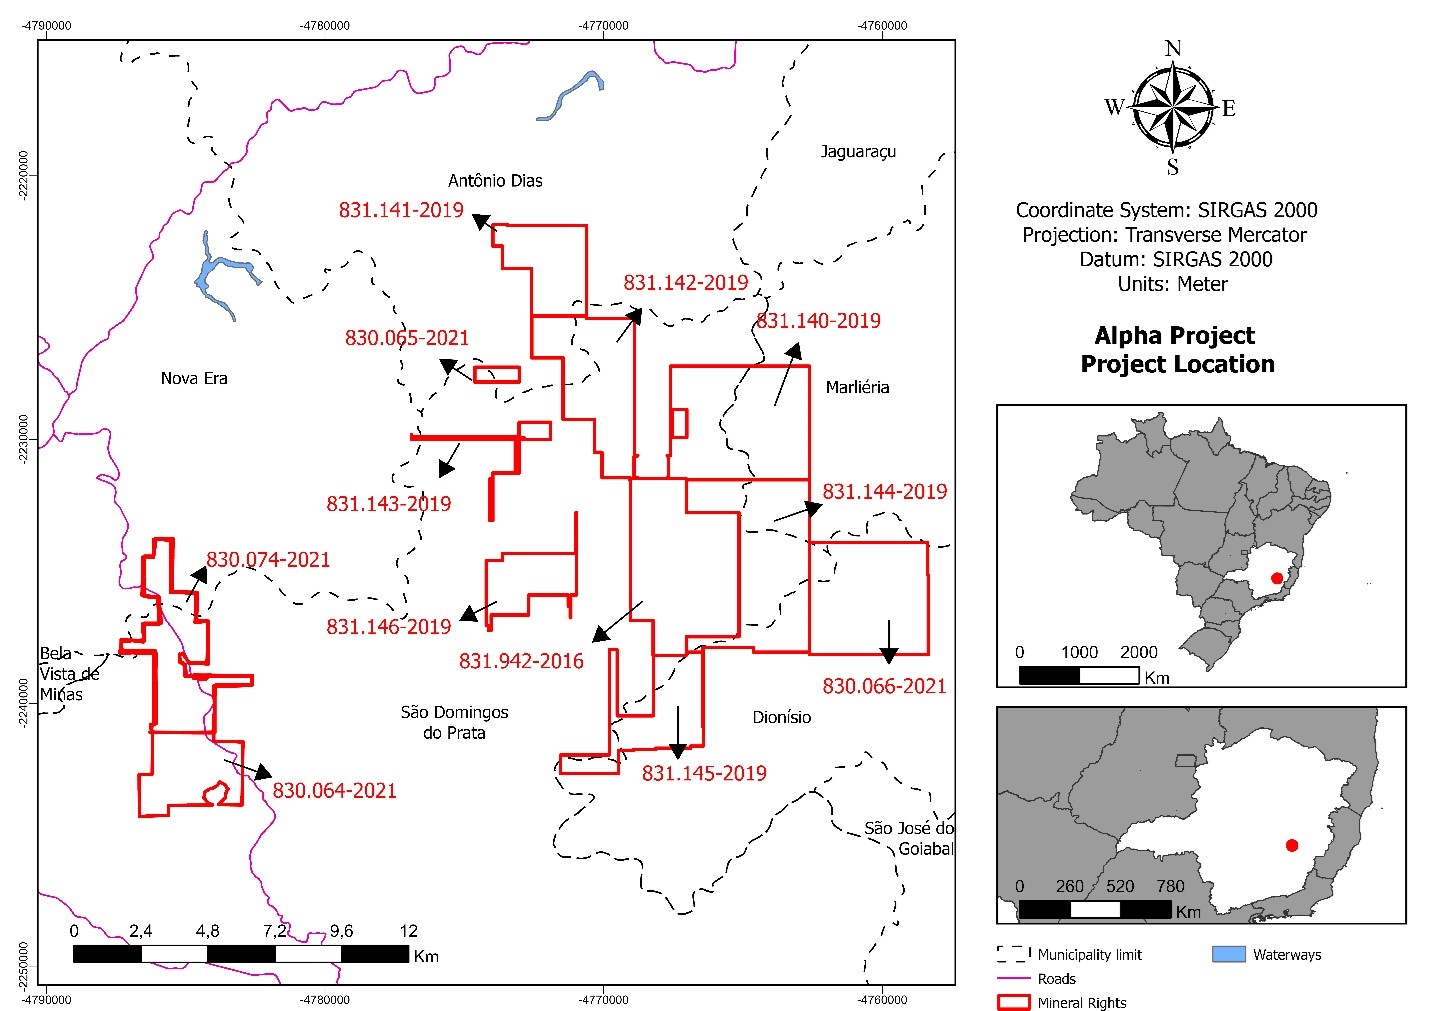
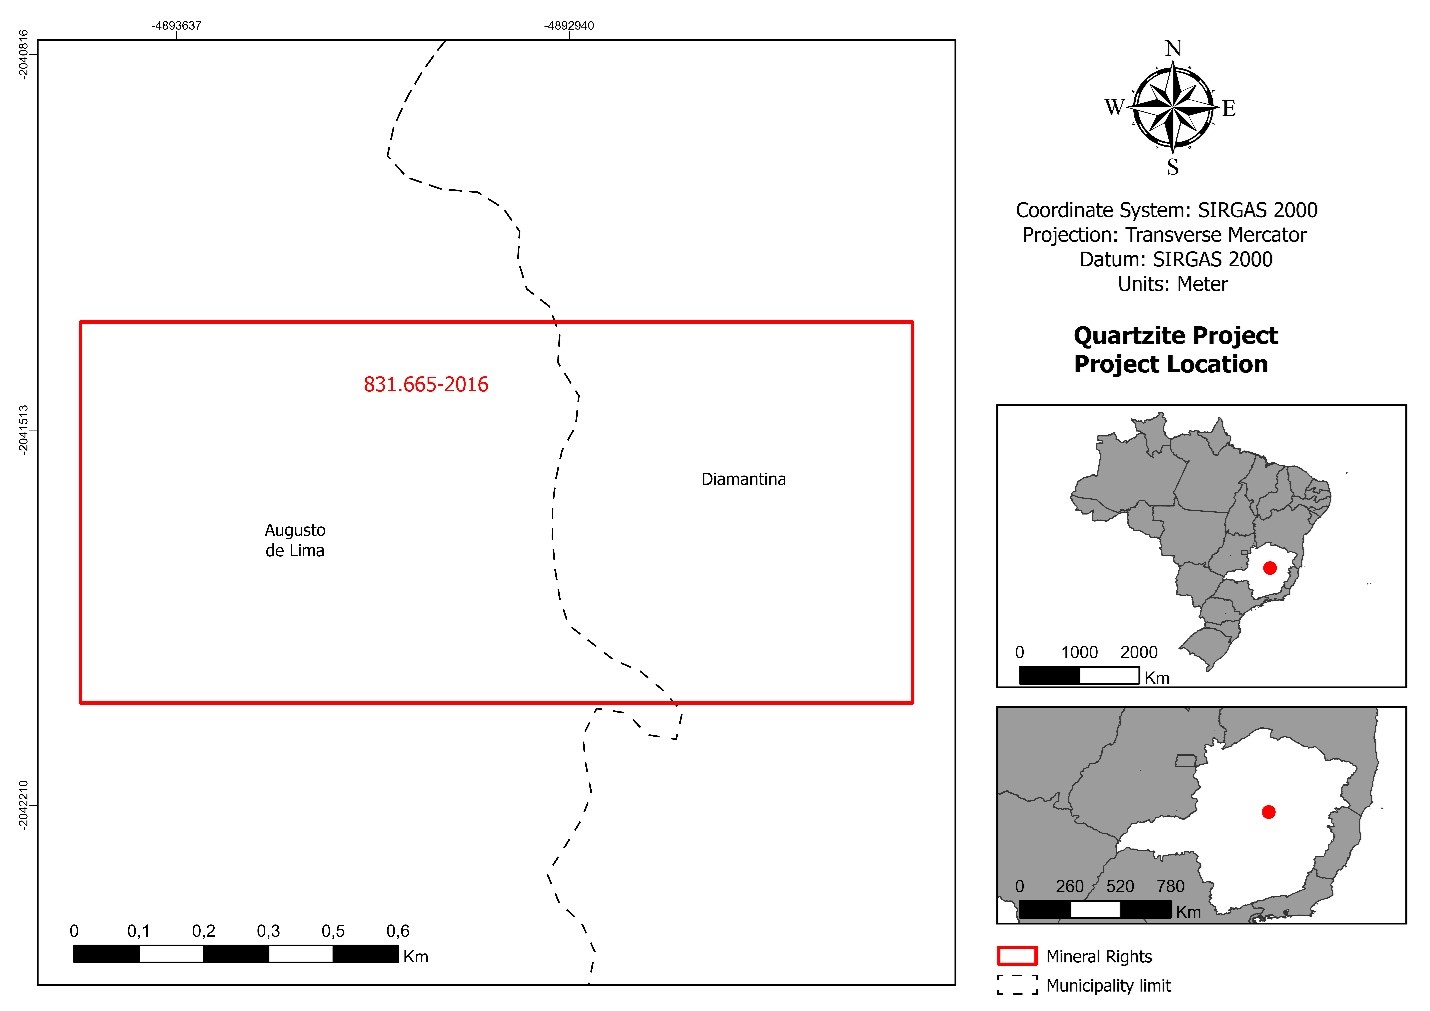
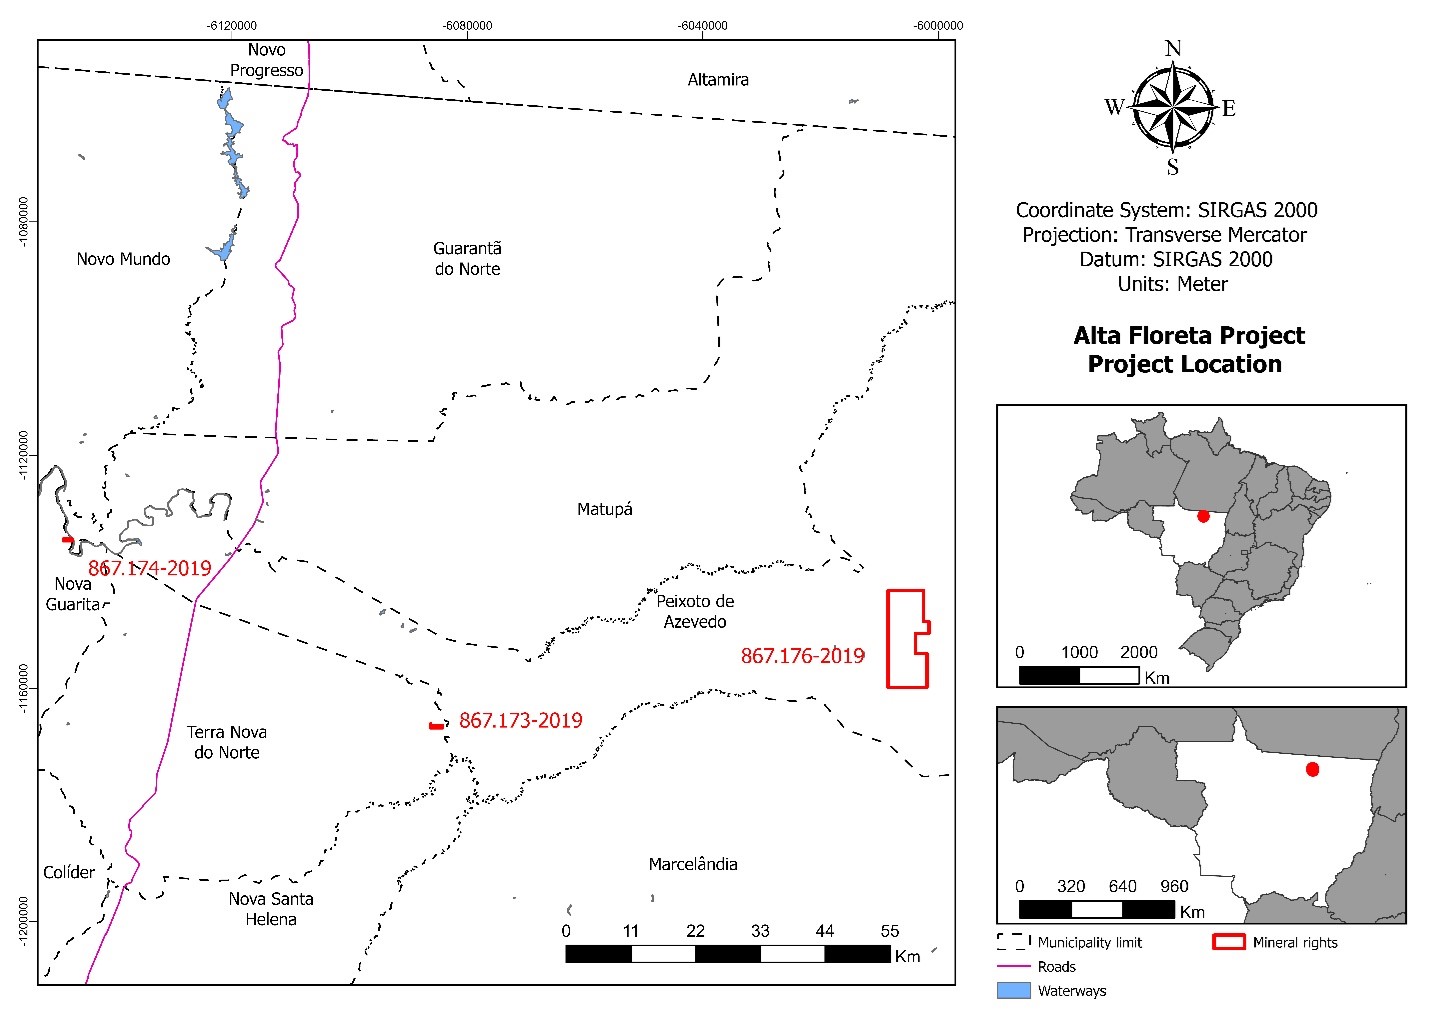
Further, we plan to include in our Form 20-F for the fiscal year ended December 31, 2023, summary tables and maps similar to the ones presented below.
Material Properties
Summary of Material Properties
| Project | Mineral Right Number | Area (hectares) | Mineral | Municipalities | State, Country | |||||
| Alpha Project | 831.942/2016 | 1,883.01 | gold | Dionisio, Marlieria, Sao Domingos do Prata | Minas Gerais, Brazil | |||||
| Alpha Project | 831.140/2019 | 1,859.51 | gold | Marlieria, Sao Domingos do Prata | Minas Gerais, Brazil | |||||
| Alpha Project | 831.141/2019 | 777.94 | gold | Antonio Dias, Sao Domingos do Prata | Minas Gerais, Brazil | |||||
| Alpha Project | 831.142/2019 | 1,294.65 | gold | Antonio Dias, Sao Domingos do Prata | Minas Gerais, Brazil | |||||
| Alpha Project | 831.143/2019 | 50.68 | gold | Sao Domingos do Prata | Minas Gerais, Brazil | |||||
| Alpha Project | 831.144/2019 | 1,739.78 | gold | Dionisio, Marlieria, Sao Domingos do Prata | Minas Gerais, Brazil | |||||
| Alpha Project | 831.145/2019 | 936.01 | gold | Dionisio, Sao Domingos do Prata | Minas Gerais, Brazil | |||||
| Alpha Project | 831.146/2019 | 557.57 | gold | Sao Domingos do Prata | Minas Gerais, Brazil | |||||
| Alpha Project | 830.064/2021 | 301.31 | gold | Sao Domingos do Prata | Minas Gerais, Brazil | |||||
| Alpha Project | 830.065/2021 | 7.6 | gold | Antonio Dias, Nova Era, Sao Domingos do Prata | Minas Gerais, Brazil | |||||
| Alpha Project | 830.066/2021 | 1,603.58 | gold | Dionisio, Marlieria, Sao Domingos do Prata | Minas Gerais, Brazil | |||||
| Alpha Project | 830.074/2021 | 211.48 | gold | Nova Era, Sao Domingos do Prata | Minas Gerais, Brazil | |||||
| Quartzite Project | 831.665/2016 | 94.44 | quartzite | Augusto de Lima, Diamantina | Minas Gerais, Brazil |
Maps of Material Properties
Alpha Project mineral rights
Quartzite Project mineral right
Non-Material Properties
Summary of Non-Material Properties
| Project | Mineral Right Number | Area (hectares) | Mineral | Municipality | State, Country | |||||
| Alta Floresta Project | 867.176/2019 | 9,740.91 | gold | Peixoto de Azevedo | Mato Grosso, Brazil | |||||
| Alta Floresta Project | 867.173/2019 | 83.99 | gold | Terra Nova do Norte | Mato Grosso, Brazil | |||||
| Alta Floresta Project | 867.174/2019 | 47.55 | gold | Matupa, Nova Guarita | Mato Grosso, Brazil | |||||
| Apui Project | 880.133/2016 | 9,325.31 | gold | Apui | Amazonas, Brazil | |||||
| Apui Project | 880.134/2016 | 9,391.67 | gold | Apui | Amazonas, Brazil | |||||
| Apui Project | 880.135/2016 | 9,340.04 | gold | Apui | Amazonas, Brazil | |||||
| Brotas de Macauba Project | 870.400/2019 | 1,951.18 | gold, palladium, platinum | Brotas de Macauba | Bahia, Brazil | |||||
| Cavalcante Project | 860.479/2019 | 1,930.79 | gold | Parana (TO), Cavalcante (GO) | Goias and Tocantins, Brazil | |||||
| Crixas Project | 860.807/2016 | 1,241.63 | gold | Crixas, Uirapuru | Goias, Brazil | |||||
| Paracatu Project | 831.883/2016 | 312.66 | gold | Paracatu | Minas Gerais, Brazil |
Maps of Non-Material Properties
Alta Floresta Project
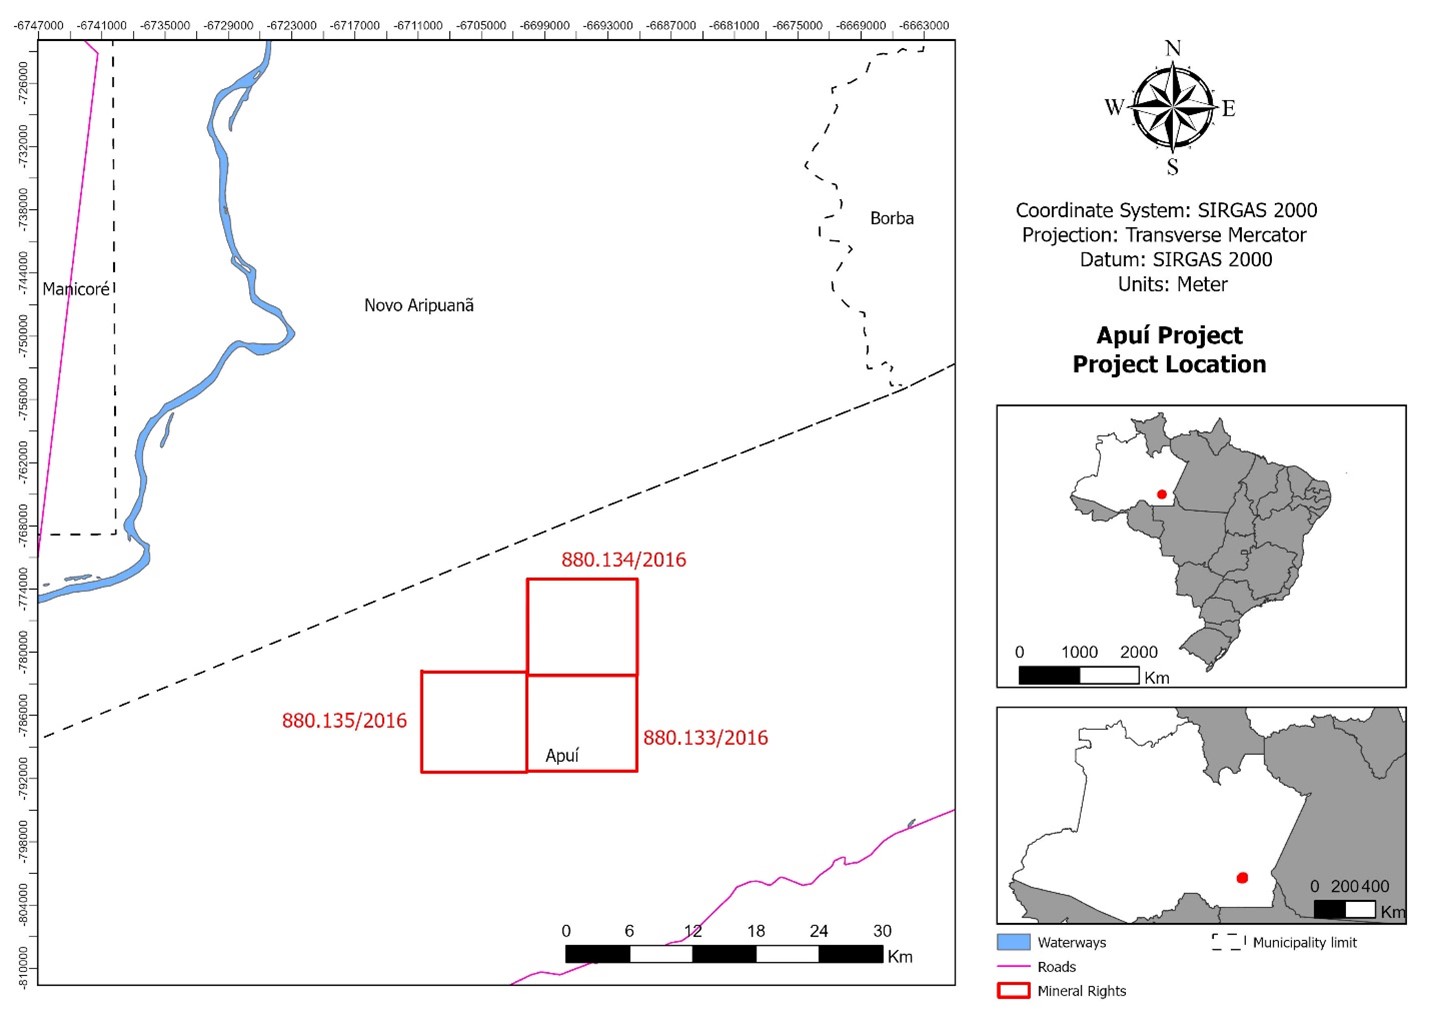
Apui Project
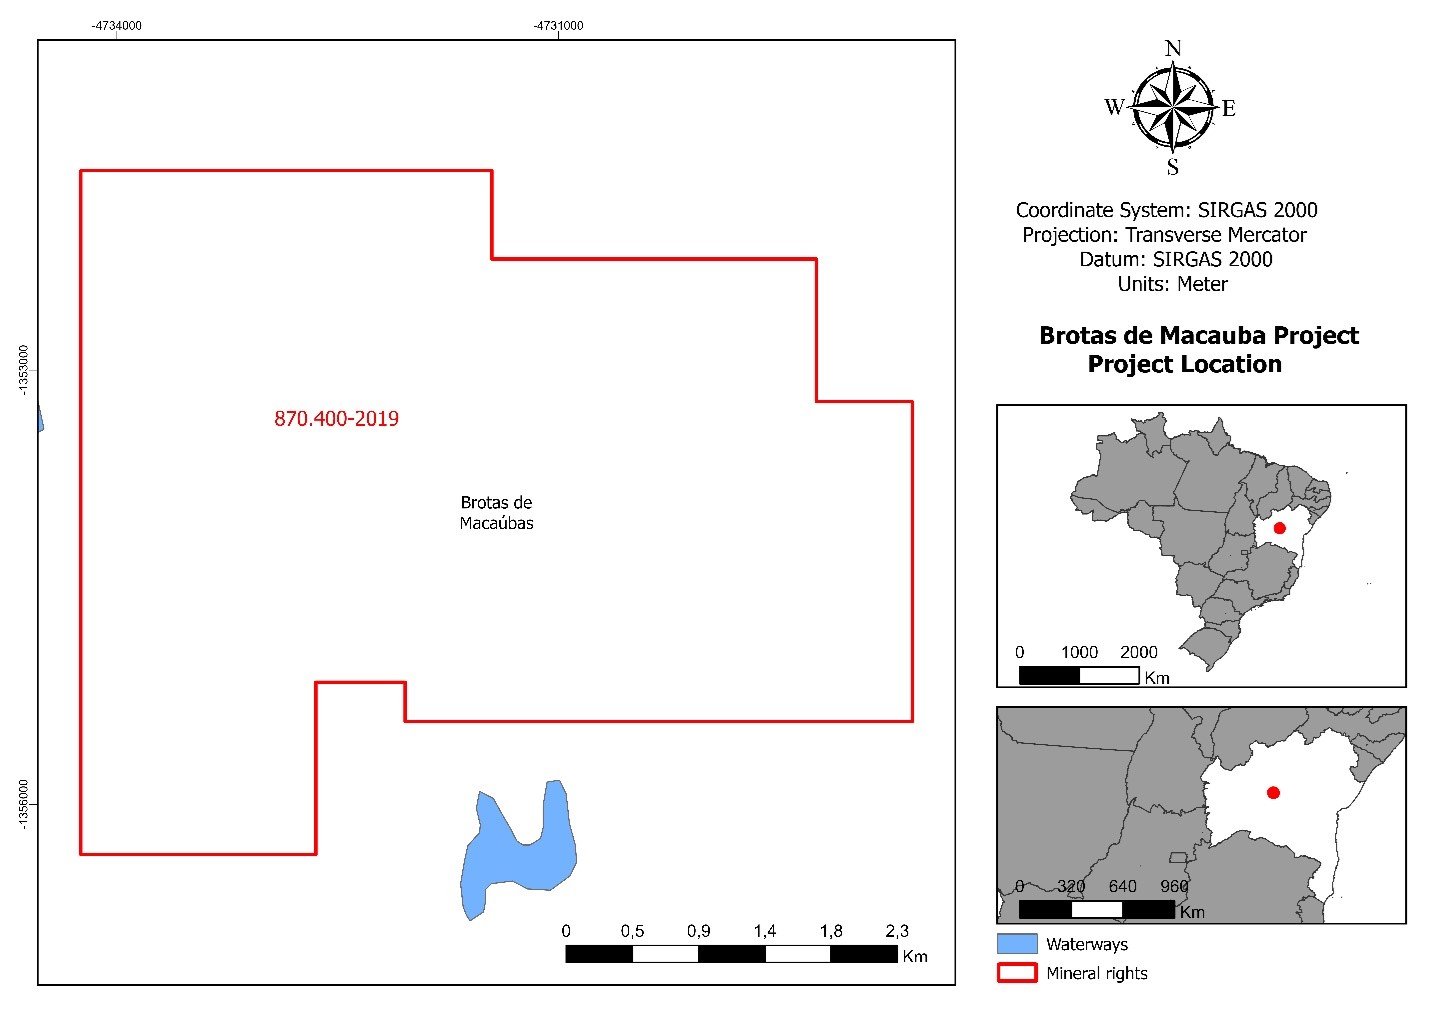
Brotas de Macauba Project
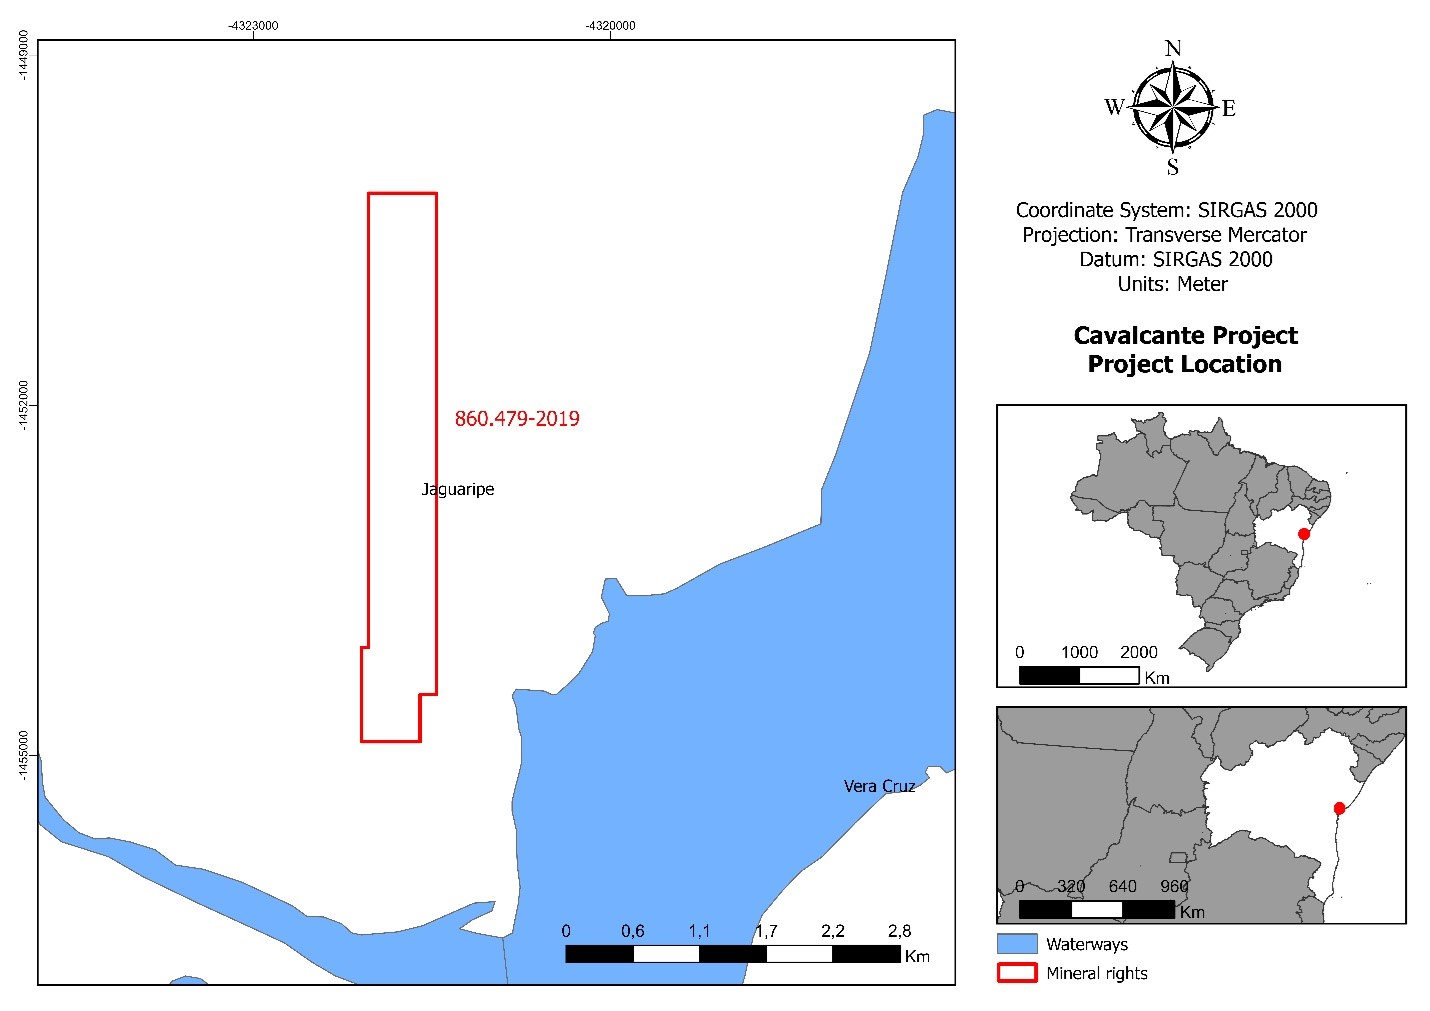
Cavalcante Project
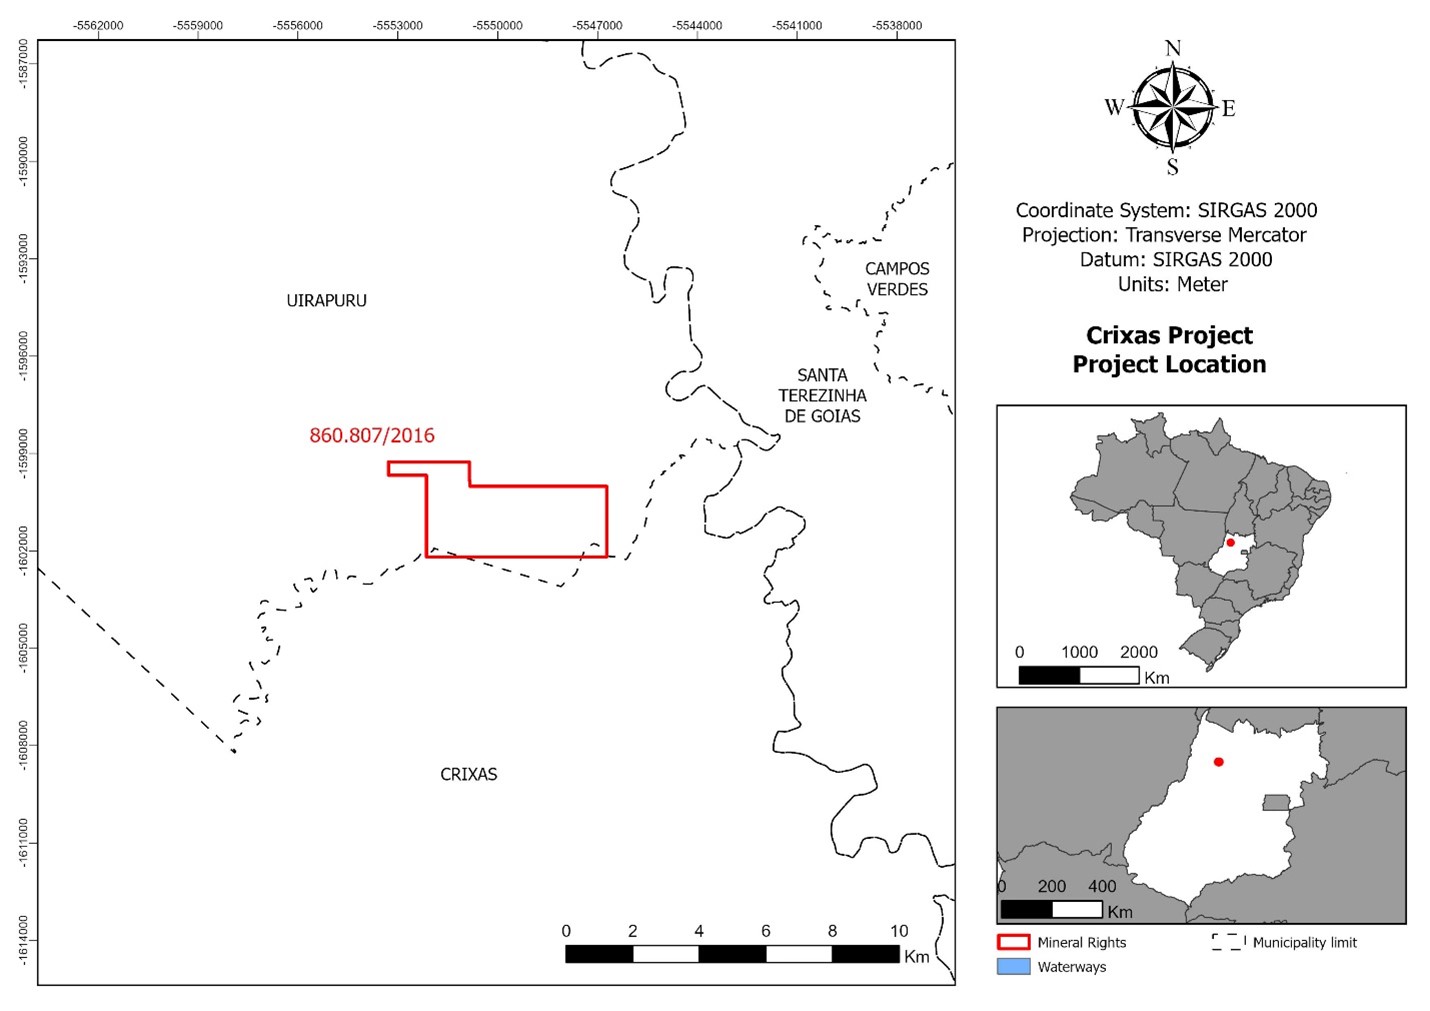
Crixas Project
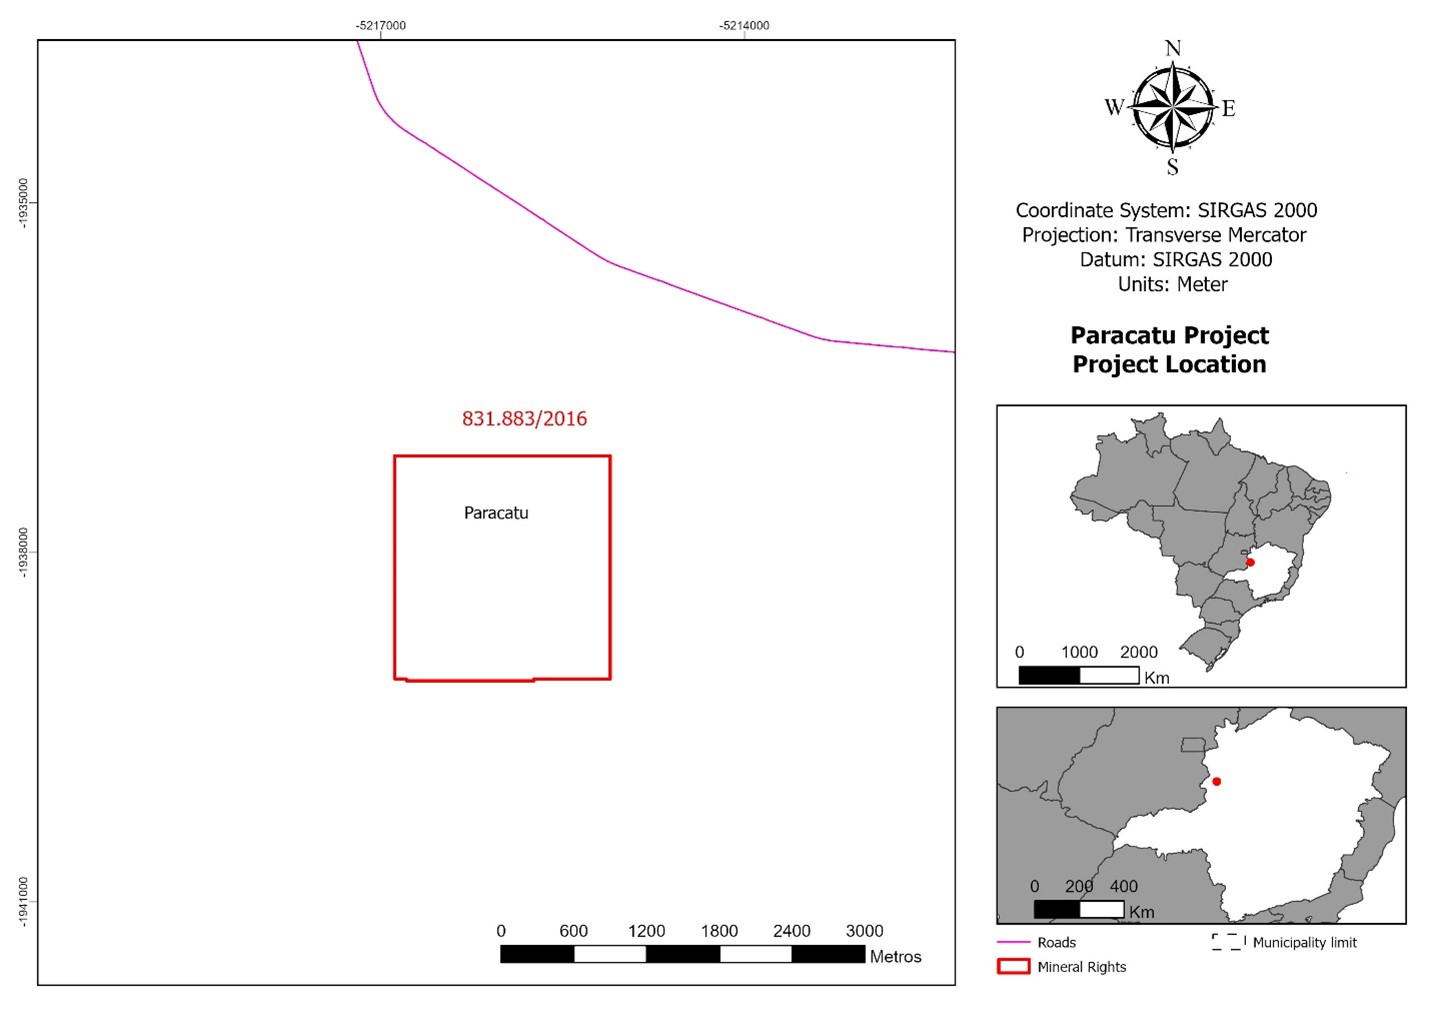
Paracatu Project
We believe that this additional information will not materially change the information we have disclosed about our material properties in our 2022 Form 20-F.
| 2. | We note your disclosures on pages 9 and 13, quantifying gold mineralization at the Alpha project, and quantifying mineralization of quartzite, respectively, notwithstanding your disclosure on page 6 clarifying that you have not established reserves. |
Please remove and refrain from disclosing estimates of mineralization that do not meet the resource or reserve definitions in Item 1300 of Regulation S-K, and that you are unable to support in accordance with Item 1302(a)(1) of Regulation S-K.
We inform the Staff that in our next Form 20-F for the fiscal year ended December 31, 2023, we will remove any disclosures that are not supportable pursuant to the requirements of Item 1302(a)(1) of Regulation S-K. We note that the existing disclosures identified by the Staff that quantify gold mineralization at the Alpha Project and mineralization of quartzite, are derived from publicly available reports filed with “Agência Nacional de Mineração”, the national mining agency of Brazil, for work performed under such regulatory body standards. In the next Form 20-F for the fiscal year ended December 31, 2023, we will make clear that such information does not meet the requirements of Item 1302(a)(1) of Regulation S-K, but it represents information which is publicly available and prepared in accordance with the reporting standards of the Brazilian national mining agency. We believe that investors would benefit from such additional information given the local nature of these projects.
| 3. | Please expand your disclosures to include the information regarding your exploration program internal controls to comply with Item 1305 of Regulation S-K, or if you have not established these controls, to include a clear statement to this effect. |
We respectfully inform the Staff that we have not implemented formal exploration program internal controls to comply with Item 1305 of Regulation S-K, but we have engaged a qualified person for gold and a qualified person for quartzite, as such term is defined in Subpart 1300 of Regulation S-K, for both the Alpha Project and the Quartzite Project. Given that during fiscal year 2022 we effectuated no drilling campaigns in any material or non-material project, no such plans were detailed on the 2022 Form 20-F. We will ensure that the Form 20-F for fiscal year ended December 31, 2023, complies with the requirements of Item 1305 of Regulation S-K, to the extent applicable.
| 4. | We note that you include a picture of a gold bar on page 27 that you indicate was obtained from processing materials in your plant. |
Please expand your disclosures to clarify whether such materials were obtained from properties in which you have an ownership or economic interest and if this is the case, also identify the particular properties involved and explain when the material was recovered and how the associated costs and gold inventories or proceeds from sales or gold have been recorded in your financial statements.
However, if the gold bar is not from you own materials but is representative of work that either was or is being performed at your plant for other persons, provide further details of the arrangements including the relevant dates, properties and persons involved, and explain how you had or are accounting for these transactions.
Otherwise, if there is no relevant correlation with your properties or work that is being performed for other persons we suggest that you either remove the picture or include disclosure clarifying why you believe it is properly associated with your plan.
The photograph of the gold bar was taken by an employee of Jupiter Gold and is an example of a product from the Company’s portable alluvial gold processing plant. In light of the Staff comment, we will consider whether in our Form 20-F for fiscal year ended December 31, 2023, to remove the photograph, or to add clarifying disclosures explaining association with the Company’s plant.
Very Truly Yours,
| /s/ Marc Fogassa | |
| Marc Fogassa | |
| Chairman & CEO | |
| Jupiter Gold Corporation |