Shareholder Letter Q3 2026 1
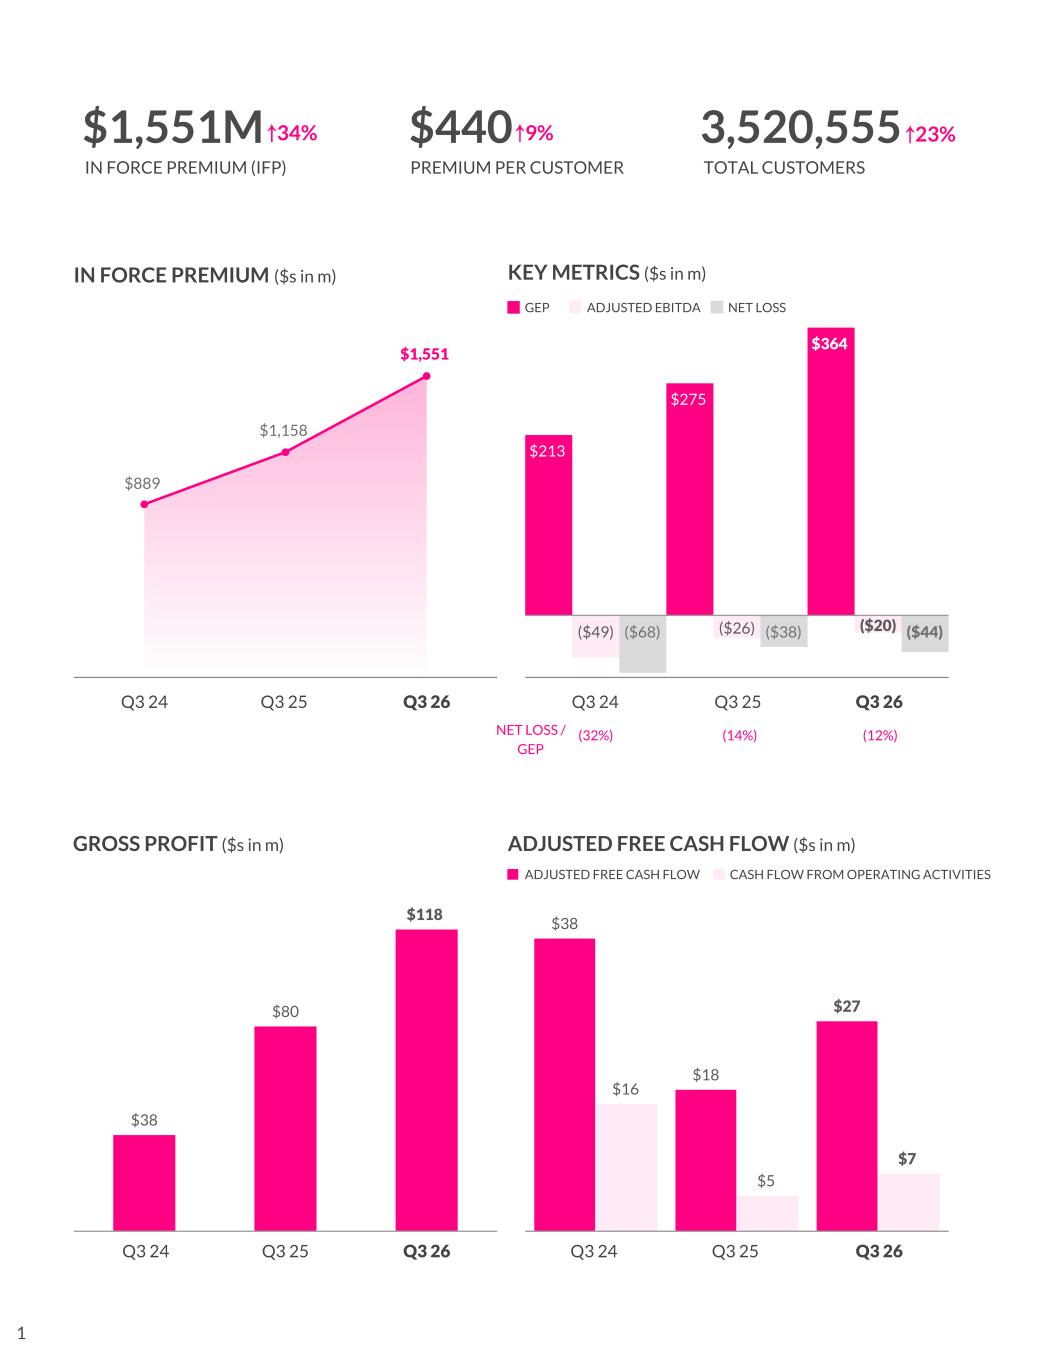
$889 $1,158 $1,551 $213 $275 $364 ($49) ($26) ($20)($68) ($38) ($44) $38 $80 $118 $38 $18 $27 $16 $5 $7 2 $440 3,520,555$1,551M IN FORCE PREMIUM (IFP) PREMIUM PER CUSTOMER TOTAL CUSTOMERS ↑34% ↑9% ↑23% IN FORCE PREMIUM ($s in m) KEY METRICS ($s in m) Q3 24 Q3 26Q3 25 GEP ADJUSTED EBITDA NET LOSS Q3 24 Q3 26Q3 25 GROSS PROFIT ($s in m) ADJUSTED FREE CASH FLOW ($s in m) ADJUSTED FREE CASH FLOW CASH FLOW FROM OPERATING ACTIVITIES Q3 24 Q3 26Q3 25 Q3 24 Q3 26Q3 25 (32%) (14%) (12%) NET LOSS / GEP 1
Dear Shareholders, Our third quarter results were excellent, once again characterized by accelerating topline growth and healthy underwriting performance. We reiterate our expectation of generating positive Adjusted EBITDA for the first time in Q4 2026, an expectation we first outlined for investors in 2022. Since that time, amid considerable macroeconomic volatility and uncertainty, we have consistently delivered against our financial ambitions, accelerating growth beyond prior expectations while remaining firmly on track with our profitability commitments. This track record underscores the predictability and resilience of our business model, reinforcing our confidence in our ability to sustain industry-leading growth while expanding profitability in the years ahead. Here’s a look at the key metrics for the third quarter: • Top Line: At $1.55 billion, In Force Premium grew 34%, our 12th consecutive quarter of acceleration. Revenue grew faster still, by 73% to $336 million. • Gross Profit: increased 48% YoY to a record $118 million. • Bottom Line: Net loss was ($44) million, while our Adj. EBITDA loss was ($20) million, in line with our expectations. • Cash Flow: Adj. Free Cash Flow of $27 million was $9 million improved YoY; Cash Flow from Ops of $7 million was $3 million improved. Our upcoming investor day is right around the corner, and will take place in NYC on November 17 at 9:00 am ET, where we will provide a comprehensive update on our strategy, growth aspirations, differentiated AI capabilities, and more. We look forward to seeing many of you there in person; for those who are unable to attend, you can access the event online. 2
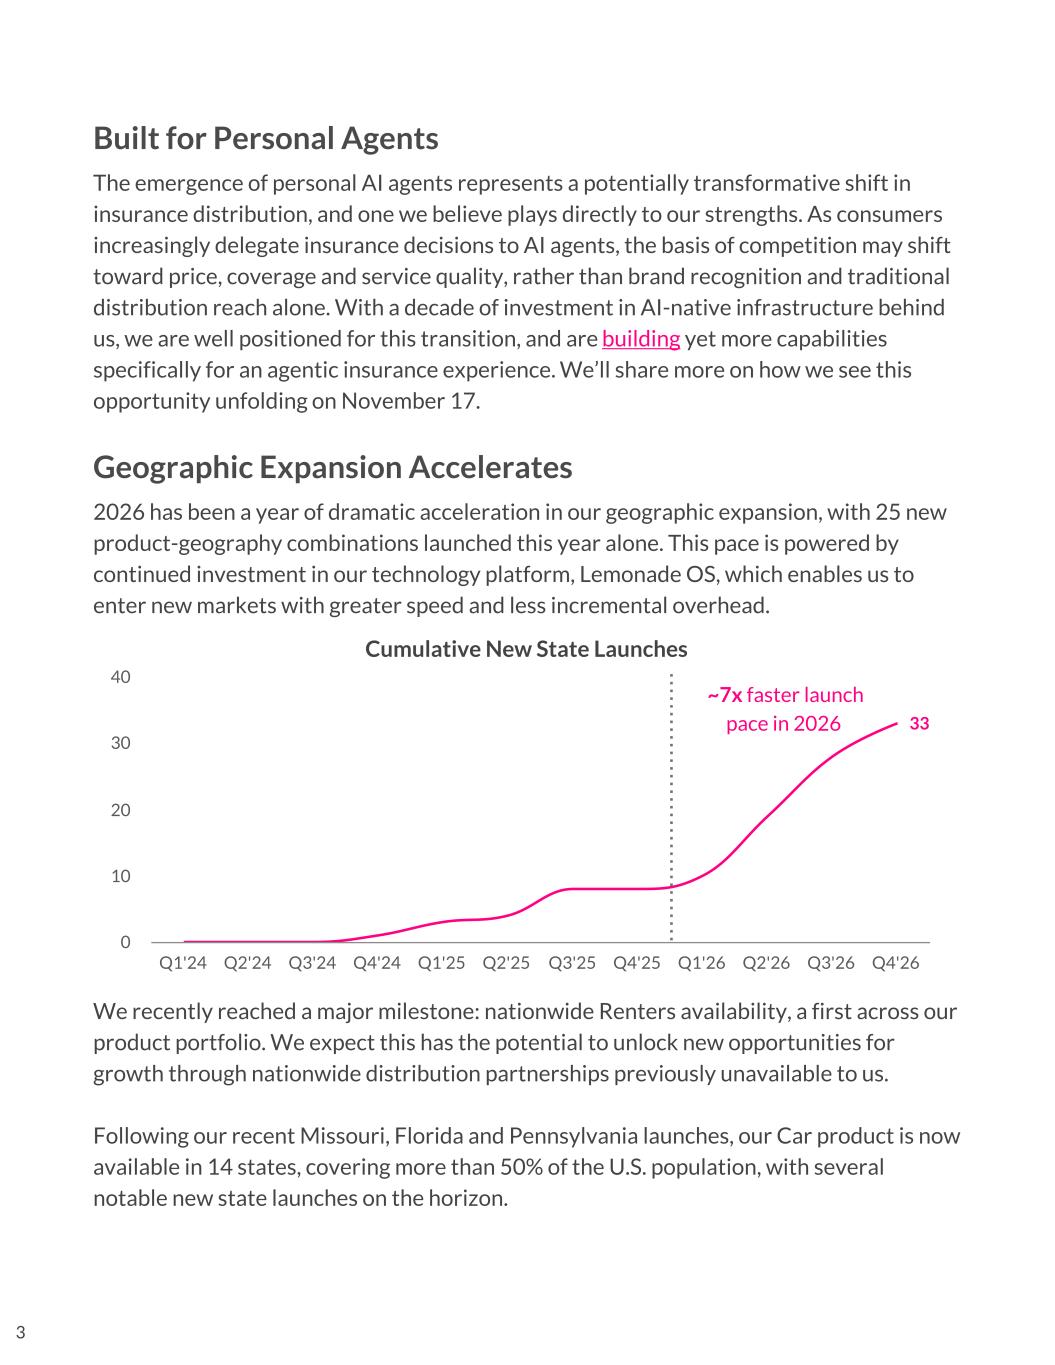
Built for Personal Agents The emergence of personal AI agents represents a potentially transformative shift in insurance distribution, and one we believe plays directly to our strengths. As consumers increasingly delegate insurance decisions to AI agents, the basis of competition may shift toward price, coverage and service quality, rather than brand recognition and traditional distribution reach alone. With a decade of investment in AI-native infrastructure behind us, we are well positioned for this transition, and are building yet more capabilities specifically for an agentic insurance experience. We’ll share more on how we see this opportunity unfolding on November 17. Geographic Expansion Accelerates 2026 has been a year of dramatic acceleration in our geographic expansion, with 25 new product-geography combinations launched this year alone. This pace is powered by continued investment in our technology platform, Lemonade OS, which enables us to enter new markets with greater speed and less incremental overhead. 33 Q1'24 Q2'24 Q3'24 Q4'24 Q1'25 Q2'25 Q3'25 Q4'25 Q1'26 Q2'26 Q3'26 Q4'26 0 10 20 30 40 We recently reached a major milestone: nationwide Renters availability, a first across our product portfolio. We expect this has the potential to unlock new opportunities for growth through nationwide distribution partnerships previously unavailable to us. Following our recent Missouri, Florida and Pennsylvania launches, our Car product is now available in 14 states, covering more than 50% of the U.S. population, with several notable new state launches on the horizon. 3 ~7x faster launch pace in 2026 Cumulative New State Launches
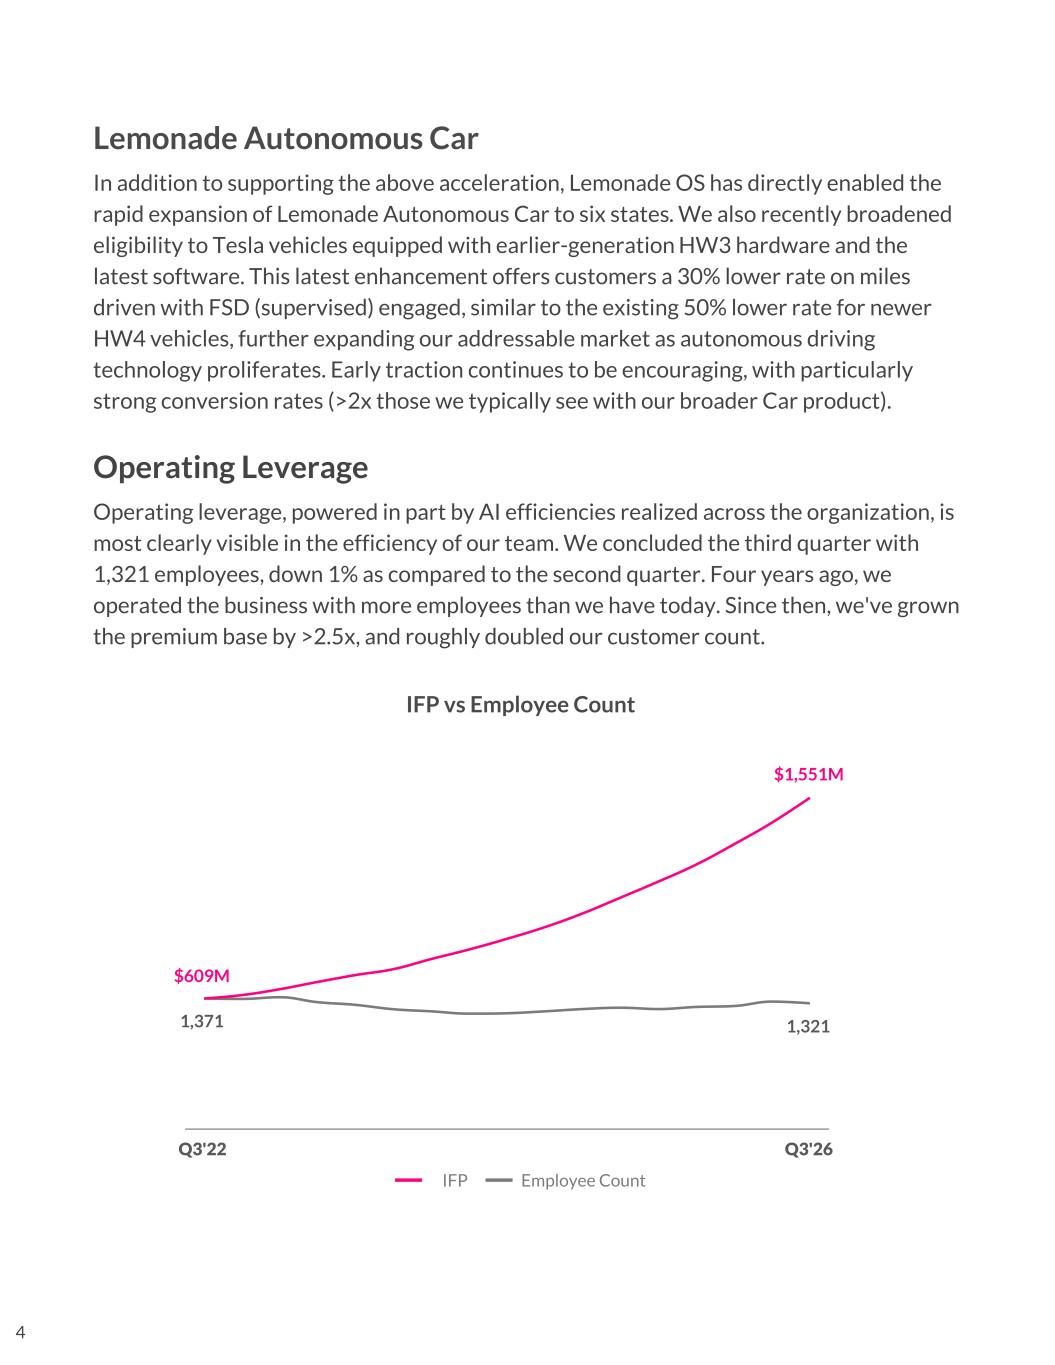
Lemonade Autonomous Car In addition to supporting the above acceleration, Lemonade OS has directly enabled the rapid expansion of Lemonade Autonomous Car to six states. We also recently broadened eligibility to Tesla vehicles equipped with earlier-generation HW3 hardware and the latest software. This latest enhancement offers customers a 30% lower rate on miles driven with FSD (supervised) engaged, similar to the existing 50% lower rate for newer HW4 vehicles, further expanding our addressable market as autonomous driving technology proliferates. Early traction continues to be encouraging, with particularly strong conversion rates (>2x those we typically see with our broader Car product). Operating Leverage Operating leverage, powered in part by AI efficiencies realized across the organization, is most clearly visible in the efficiency of our team. We concluded the third quarter with 1,321 employees, down 1% as compared to the second quarter. Four years ago, we operated the business with more employees than we have today. Since then, we've grown the premium base by >2.5x, and roughly doubled our customer count. 4 1,371 1,321 $609M $1,551M Q3'22 Q3'26 IFP vs Employee Count IFP Employee Count
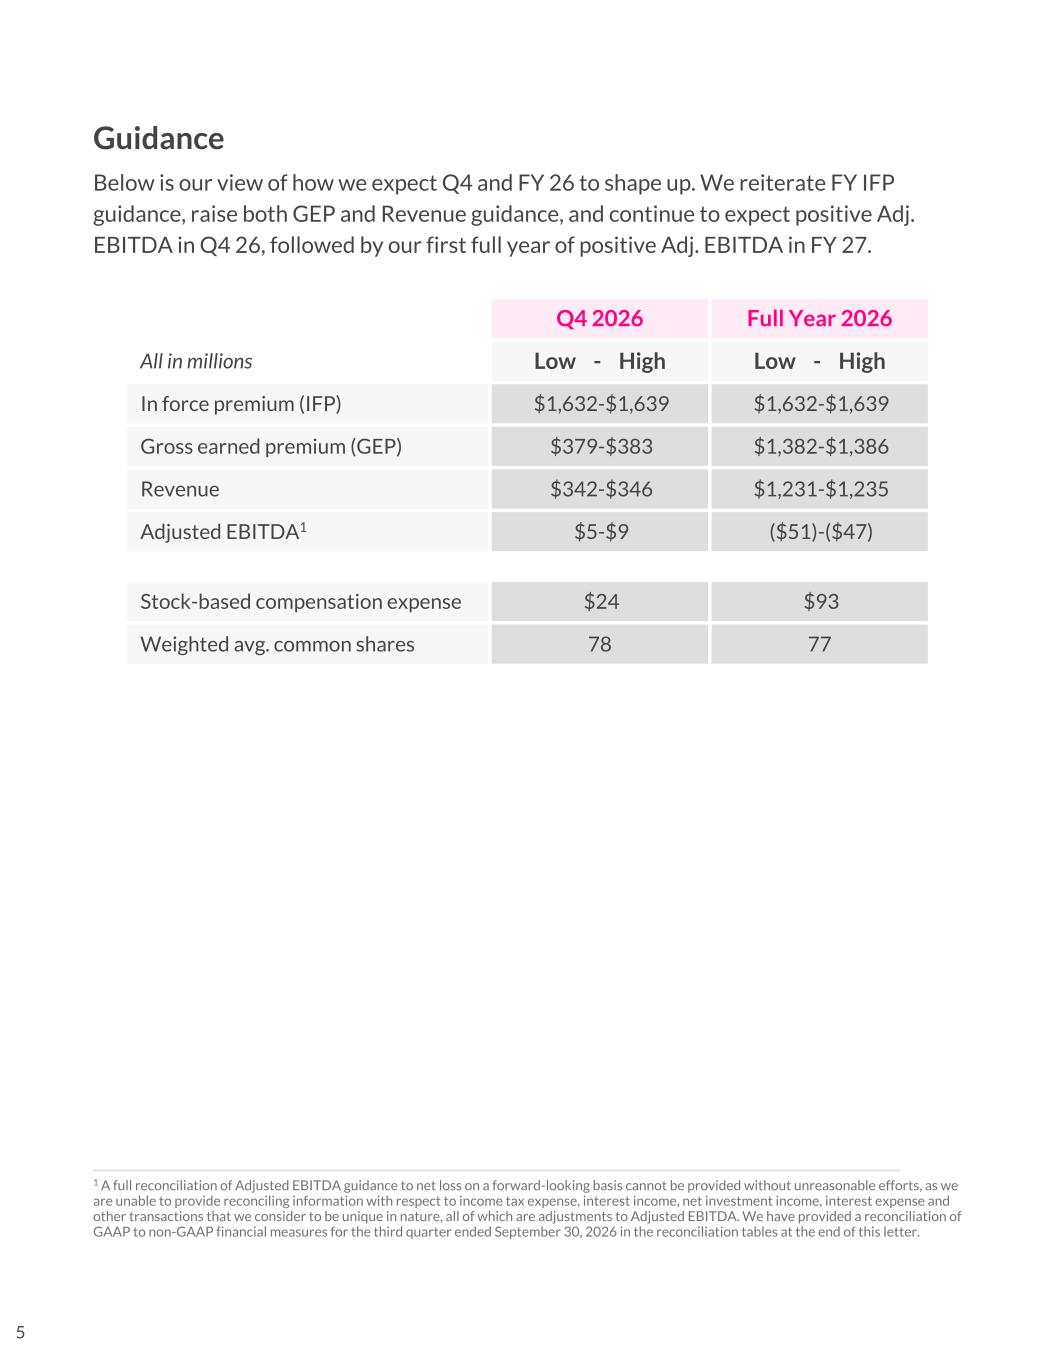
Guidance Below is our view of how we expect Q4 and FY 26 to shape up. We reiterate FY IFP guidance, raise both GEP and Revenue guidance, and continue to expect positive Adj. EBITDA in Q4 26, followed by our first full year of positive Adj. EBITDA in FY 27. Q4 2026 Full Year 2026 All in millions Low - High Low - High In force premium (IFP) $1,632-$1,639 $1,632-$1,639 Gross earned premium (GEP) $379-$383 $1,382-$1,386 Revenue $342-$346 $1,231-$1,235 Adjusted EBITDA1 $5-$9 ($51)-($47) Stock-based compensation expense $24 $93 Weighted avg. common shares 78 77 5 1 A full reconciliation of Adjusted EBITDA guidance to net loss on a forward-looking basis cannot be provided without unreasonable efforts, as we are unable to provide reconciling information with respect to income tax expense, interest income, net investment income, interest expense and other transactions that we consider to be unique in nature, all of which are adjustments to Adjusted EBITDA. We have provided a reconciliation of GAAP to non-GAAP financial measures for the third quarter ended September 30, 2026 in the reconciliation tables at the end of this letter.
Q3 2026 Results, KPIs and Non-GAAP Financial Measures In Force Premium IFP, defined as the aggregate annualized premium for customers as of the period end date, increased by 34% to $1.55 billion as compared to the third quarter of 2025. Customers Customer count increased by 23% to 3,520,555 as compared to the third quarter of 2025. Premium per Customer Premium per customer, defined as in force premium divided by customers, was $440 at the end of the third quarter, up 9% from the third quarter of 2025. Annual Dollar Retention ADR, defined as the percentage of IFP retained over a twelve month period, inclusive of changes in policy value, changes in number of policies, changes in policy type, and churn, was 86%, a 1 percentage point increase from both the third quarter of 2025 and the second quarter of 2026. Gross Earned Premium Third quarter gross earned premium of $364.1 million increased by $89.4 million or 33% as compared to the third quarter of 2025, primarily due to the increase of IFP earned during the quarter. 6
Revenue Third quarter revenue of $336.1 million increased by $141.6 million or 73% as compared to the third quarter of 2025, primarily driven by growth in gross earned premium and higher premium retention rate due to reduced quota share cession rates. Gross Profit Third quarter gross profit of $118.1 million increased by $38.2 million or 48% as compared to the third quarter of 2025, primarily due to the 73% increase in revenue. Adjusted Gross Profit Third quarter adjusted gross profit of $120.5 million increased by $39.6 million or 49% as compared to the third quarter of 2025, primarily due to the 73% increase in revenue. Operating Expense Operating expense, excluding loss and loss adjustment expense, net, of $191.9 million increased by $50.7 million or 36% as compared to the third quarter of 2025. The increase reflects the following identifiable drivers, most of which we expect to moderate materially going forward. • Growth spend and interest expense grew by $28.0 million1, which reflects our decision to lean into customer acquisition due to strong marketing efficiency. We expect the growth rate of IFP to notably outpace that of growth spend from Q4 2026 onward, a key driver of operating leverage and profitability. • Stock-based compensation expense (“SBC”) grew by $6.1 million, primarily due to multi-year awards granted to our founders and executives in Q1 this year. We do not expect SBC to be a material driver of YoY expense growth beginning in Q2 2027. • Other insurance expense grew by $5.1 million, primarily due to payment processing fees, premium taxes, and underwriting data costs. These expenses are variable in nature and expected to grow roughly in line with gross earned premium. Compared to Q2 2026, operating expense grew by $9.7 million, primarily due to a $7.3 million2 increase in growth spend and interest expense, and a $2.5 million increase in other insurance expense. 7 1 Growth spend increased by $24.5 million and interest expense increased by $3.5 million as compared to the third quarter of 2025. 2 Growth spend increased by $6.2 million and interest expense increased by $1.1 million as compared to the second quarter of 2026.
Net Loss Net loss in the third quarter was ($43.7) million, or ($0.56) per share, as compared to ($37.5) million, or ($0.51) per share, in the third quarter of 2025, primarily due to increased stock-based compensation expense and interest expense. Adjusted EBITDA Adjusted EBITDA loss was ($20.4) million, as compared to an Adjusted EBITDA loss of ($25.6) million in the third quarter of 2025, primarily due to the $38.2 million increase in gross profit, partially offset by higher operating expense, including a $24.5 million increase in growth spend. Adjusted EBITDA is a non-GAAP measure. Cash & Investments The Company’s cash, cash equivalents, and investments totaled approximately $1.2 billion at September 30, 2026. As of September 30, 2026, we were required to hold approximately $350 million of regulatory surplus at our insurance subsidiaries. Adjusted Free Cash Flow Adjusted free cash flow in the third quarter was $27.0 million, as compared to $18.1 million in the third quarter of 2025. Adjusted free cash flow is a non-GAAP measure. Reconciliations of GAAP to non-GAAP financial measures, as well as definitions for the non-GAAP financial measures and the reasons for their use, are presented at the end of this letter. 8
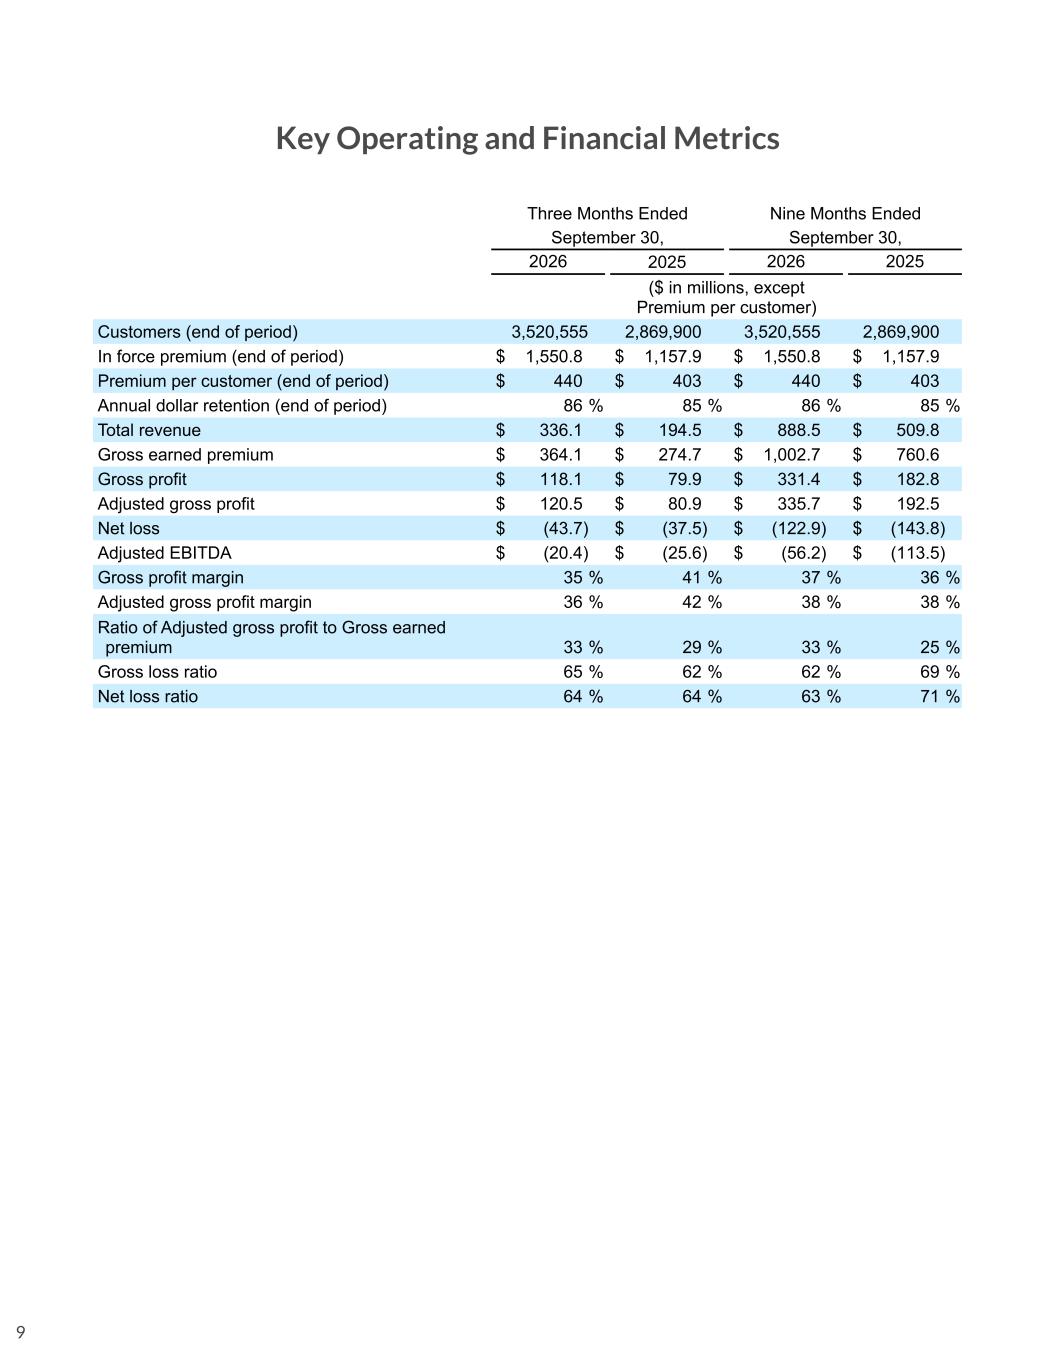
Key Operating and Financial Metrics Three Months Ended September 30, Nine Months Ended September 30, 2026 2025 2026 2025 ($ in millions, except Premium per customer) Customers (end of period) 3,520,555 2,869,900 3,520,555 2,869,900 In force premium (end of period) $ 1,550.8 $ 1,157.9 $ 1,550.8 $ 1,157.9 Premium per customer (end of period) $ 440 $ 403 $ 440 $ 403 Annual dollar retention (end of period) 86 % 85 % 86 % 85 % Total revenue $ 336.1 $ 194.5 $ 888.5 $ 509.8 Gross earned premium $ 364.1 $ 274.7 $ 1,002.7 $ 760.6 Gross profit $ 118.1 $ 79.9 $ 331.4 $ 182.8 Adjusted gross profit $ 120.5 $ 80.9 $ 335.7 $ 192.5 Net loss $ (43.7) $ (37.5) $ (122.9) $ (143.8) Adjusted EBITDA $ (20.4) $ (25.6) $ (56.2) $ (113.5) Gross profit margin 35 % 41 % 37 % 36 % Adjusted gross profit margin 36 % 42 % 38 % 38 % Ratio of Adjusted gross profit to Gross earned premium 33 % 29 % 33 % 25 % Gross loss ratio 65 % 62 % 62 % 69 % Net loss ratio 64 % 64 % 63 % 71 % 9
Non-GAAP financial measures and key operating metrics The non-GAAP financial measures used in this shareholder letter are Adjusted EBITDA, Adjusted gross profit, Adjusted gross profit margin, Ratio of Adjusted Gross Profit to Gross earned premium, Free cash flow, and Adjusted free cash flow. We define Adjusted EBITDA, a non-GAAP financial measure, as net loss excluding income tax expense, depreciation and amortization, stock-based compensation, interest expense, interest income and others, net investment income, amortization of fair value adjustment on insurance contract intangible liability relating to the Metromile Acquisition, and other one-time and non-cash adjustments and other transactions that we consider to be unique in nature. We exclude these items from Adjusted EBITDA because we do not consider them to be directly attributable to our underlying operating performance. We use Adjusted EBITDA as an internal performance measure in the management of our operations because we believe it gives our management and other users of our financial information useful insight into our results of operations and our underlying business performance. Adjusted EBITDA should not be viewed as a substitute for net loss calculated in accordance with U.S. GAAP, and other companies may define Adjusted EBITDA differently. We define Adjusted gross profit, a non-GAAP financial measure, as gross profit excluding net investment income, interest income and other income, plus fixed costs and overhead associated with our underwriting operations including employee-related expense, professional fees and other, and depreciation and amortization allocated to cost of revenue, and other adjustments that we consider to be unique in nature. After these adjustments, the resulting calculation is inclusive of only those variable costs of revenue incurred on the successful acquisition of business and without the volatility of investment income. We use adjusted gross profit as a key measure of our progress towards profitability and to consistently evaluate the variable contribution to our business from underwriting operations from period to period. We define the Ratio of Adjusted Gross Profit to Gross Earned Premium as the ratio of Adjusted Gross Profit divided by Gross Earned Premium. The Ratio of Adjusted Gross Profit to Gross Earned Premium measures the relationship between the underlying business volume and gross economic benefit generated by our underwriting operations, on the one hand, and our underlying profitability trends, on the other. We rely on this 10
measure, which supplements our gross profit ratio as calculated in accordance with U.S. GAAP, because it provides management with insight into our underlying profitability trends over time. The non-GAAP financial measures used in this shareholder letter have not been calculated in accordance with GAAP and should be considered in addition to results prepared in accordance with GAAP and should not be considered as a substitute for, or superior to, GAAP results. In addition, Adjusted gross profit, and Adjusted gross profit margin, Ratio of Adjusted Gross Profit to Gross earned premium, and Adjusted EBITDA should not be construed as indicators of our operating performance, liquidity or cash flows generated by operating, investing and financing activities, as there may be significant factors or trends that they fail to address. We caution investors that non- GAAP financial information, by its nature, departs from traditional accounting conventions. Therefore, its use can make it difficult to compare our current results with our results from other reporting periods and with the results of other companies. Our management uses these non-GAAP financial measures, in conjunction with GAAP financial measures, as an integral part of managing our business and to, among other things: (i) monitor and evaluate the performance of our business operations and financial performance; (ii) facilitate internal comparisons of the historical operating performance of our business operations; (iii) facilitate external comparisons of the results of our overall business to the historical operating performance of other companies that may have different capital structures and debt levels; (iv) review and assess the operating performance of our management team; (v) analyze and evaluate financial and strategic planning decisions regarding future operating investments; and (vi) plan for and prepare future annual operating budgets and determine appropriate levels of operating investments. Investors are encouraged to review the reconciliation of these non-GAAP financial measures to their most directly comparable GAAP financial measures as provided in the tables accompanying this shareholder letter. This shareholder letter also includes key performance indicators, including customers, In Force Premium, Premium Per Customer, Annual Dollar Retention, Gross Earned Premium, Gross Loss Ratio, Net Loss Ratio and Gross Loss Ratio ex-CAT. 11
We define Customers as the number of current policyholders underwritten by us or placed by us with third-party insurance partners (who pay us recurring commissions) as of the period end date. A customer that has more than one policy counts as a single customer for the purposes of this metric. We view customers as an important metric to assess our financial performance because customer growth drives our revenue, expands brand awareness, deepens our market penetration, creates additional upsell and cross- sell opportunities and generates additional data to continue to improve the functioning of our platform. We define In force premium ("IFP") as the aggregate annualized premium for customers as of the period end date. At each period end date, we calculate IFP as the sum of: (i) In force written premium — the annualized premium of in force policies underwritten by us; and (ii) In force placed premium — the annualized premium of in force policies placed with third party insurance companies for which we earn a recurring commission payment. In force placed premium currently reflects approximately 4% of IFP. The annualized value of premiums is a legal and contractual determination made by assessing the contractual terms with our customers. The annualized value of contracts is not determined by reference to historical revenues, deferred revenues or any other GAAP financial measure over any period. IFP is not a forecast of future revenues nor is it a reliable indicator of revenue expected to be earned in any given period. We believe that our calculation of IFP is useful to analysts and investors because it captures the impact of growth in customers and premium per customer at the end of each reported period, without adjusting for known or projected policy updates, cancellations, rescissions and non-renewals. We use IFP because we believe it gives our management useful insight into the total reach of our platform by showing all in force policies underwritten and placed by us. Other companies, including companies in our industry, may calculate IFP differently or not at all, which reduces the usefulness of IFP as a tool for comparison. We define Premium per customer as the average annualized premium customers pay for products underwritten by us or placed by us with third-party insurance partners. We calculate premium per customer by dividing IFP by customers. We view premium per customer as an important metric to assess our financial performance because premium per customer reflects the average amount of money our customers spend on our products, which helps drive strategic initiatives. 12
We define Annual dollar retention ("ADR"), as the percentage of IFP retained over a twelve month period, inclusive of changes in policy value, changes in number of policies, changes in policy type, and churn. To calculate ADR we first aggregate the IFP from all active customers at the beginning of the period and then aggregate the IFP from those same customers at the end of the period. ADR is then equal to the ratio of ending IFP to beginning IFP. We believe that our calculation of ADR is useful to analysts and investors because it captures our ability to retain customers and sell additional products and coverage to them over time. We view ADR as an important metric to measure our ability to provide a delightful end-to-end customer experience, satisfy our customers’ evolving insurance needs and maintain our customers’ trust in our products. Our customers become more valuable to us every year they continue to subscribe to our products. Other companies, including companies in our industry, may calculate ADR differently or not at all, which reduces the usefulness of ADR as a tool for comparison. Gross earned premium ("GEP") is the earned portion of our gross written premium. Gross earned premium includes direct and assumed premium. We use this operating metric as we believe it gives our management and other users of our financial information useful insight into the gross economic benefit generated by our business operations and allows us to evaluate our underwriting performance without regard to changes in our underlying reinsurance structure. Unlike net earned premium, gross earned premium excludes the impact of premiums ceded to reinsurers, and therefore should not be used as a substitute for net earned premium, total revenue, or any other measure presented in accordance with GAAP. We define Gross loss ratio, expressed as a percentage, as the ratio of gross losses and loss adjustment expense to gross earned premium. We define Net loss ratio, expressed as a percentage, as the ratio of losses and loss adjustment expense, less amounts ceded to reinsurers, to net earned premium. We define Gross loss ratio ex-CAT, expressed as a percentage, as the ratio of gross losses and loss adjustment expense, excluding catastrophe losses, to gross earned premium. We define Trailing twelve month ("TTM") gross loss ratio, expressed as a percentage, as the ratio of gross losses and loss adjustment expense to gross earned premium for the past twelve months. 13
We define Opex excluding growth spend, as total expense less loss and loss adjustment expenses, net, and growth spend. We define Growth spend as advertising expense related to acquiring policies, included in “Sales and marketing expenses” in the consolidated financial statements. We define Free cash flow ("FCF") as cash flow from operating activities, less capital expenditures. We define Adjusted free cash flow ("Adj. FCF") as cash flow from operating activities, less capital expenditures, plus net borrowings under financing agreement. 14
Links The information contained on, or that can be accessed through, hyperlinks included herein is deemed not to be incorporated in or part of this shareholder letter. Earnings teleconference information The Company will discuss its third quarter 2026 financial results and business outlook during a teleconference on November 5, 2026, at 8:00 AM ET. The conference call (access code 540569867) can be accessed toll-free at 833-461-5787 or at 585-542-9983. A live audio webcast of the call will be available simultaneously at www.lemonade.com/ investor Following completion of the call, a recorded replay of the webcast will be available on the investor relations section of Lemonade’s website. Additional investor information can be accessed at www.lemonade.com/investor About Lemonade Lemonade offers renters, homeowners, pet, car, and life insurance. Powered by artificial intelligence and behavioral economics, Lemonade’s full stack insurance carriers in the US, the UK and Europe replace brokers and bureaucracy with bots and machine learning, aiming for zero paperwork and instant everything. A Certified B-Corp, Lemonade donates to nonprofits selected by its community, during its annual Giveback. Lemonade is currently available in the United States, the UK, Germany, the Netherlands, and France, and continues to expand globally. For more information, visit www.lemonade.com and follow Lemonade on X or Instagram. Media inquiries: press@lemonade.com Investor contact: ir@lemonade.com 15
Forward-looking statement safe harbor This shareholder letter contains forward-looking statements within the meaning of the Private Securities Litigation Reform Act of 1995. All statements contained in this shareholder letter that do not relate to matters of historical fact should be considered forward-looking statements, including statements regarding our financial outlook for the fourth quarter and full year 2026, 2027 and beyond, IFP growth, Adjusted EBITDA, profitability and operating leverage, growth spend and marketing efficiency, expected trends in operating expenses and stock-based compensation, AI-driven operating efficiencies, geographic expansion and new state launches, nationwide distribution partnerships for Renters, growth trajectory for our products, including but not limited to car and our autonomous car product, and the impact of personal AI agents and agentic insurance experience on our business. These statements are neither promises nor guarantees, but involve known and unknown risks, uncertainties and other important factors that may cause our actual results, performance or achievements to be materially different from any future results, performance or achievements expressed or implied by the forward-looking statements, including but not limited to, the following: our history of losses and that we may not achieve or maintain profitability in the future; our success and ability to retain and expand our customer base; the denial of claims or our failure to accurately and timely pay claims; our ability to attain greater value from each user; the intense competition in the segments of the insurance industry in which we operate; our proprietary artificial intelligence algorithms may not operate properly or as expected; our ability to maintain our risk-based capital at the required levels; our ability to maintain and implement relationships with third-party service providers; our ability to expand our product offerings or penetrate new markets; availability of reinsurance at current levels and prices; our reliance on artificial intelligence, telematics, mobile technology, and our digital platforms to collect data; our pricing models, including for Full Self Driving (Supervised) and reliance on direct vehicle telemetry may not function as expected; our ability to obtain additional capital to the extent required to grow our business; interruptions or delays in services provided by third-party data centers; security incidents or real or perceived errors, failures or bugs in our systems, website or app; our actual or perceived failure to protect customer information and other data; periodic examinations by state insurance regulators; privacy, data security, and data protection risks related to our 16
expansion into Europe and the UK; evolving privacy laws on cookies, tracking technologies and e-marketing; our ability to prevent misappropriation of our data; claims that our policies failed to provide adequate coverage; our ability to underwrite risks accurately and charge competitive yet profitable rates; potentially significant expenses incurred in connection with any new products before generating revenue; litigation and legal proceedings filed by or against us; the "Lemonade" brand may not become as widely known as incumbents' brands or the brand may become tarnished; risks associated with our expansion in the U.S. and internationally; the adverse impact of the Customer Investment Agreement; our ability to comply with extensive insurance industry regulations; our ability to predict the impacts of severe weather events and catastrophes; our utilization of customer and third party data in underwriting our policies; limitations in the analytical models used to assess and predict our exposure to catastrophe losses; potential losses could be greater than our loss and loss adjustment expense reserves; and the minimum capital and surplus requirements our insurance subsidiaries are required to have. These and other important factors are discussed under the caption “Risk Factors” in our most recent Form 10-K filed with the SEC and in our other subsequent filings with the SEC. These factors could cause actual results to differ materially from those indicated by the forward-looking statements made in this shareholder letter. Any such forward- looking statements represent management’s beliefs as of the date of this shareholder letter. While we may elect to update such forward-looking statements at some point in the future, we disclaim any obligation to do so, even if subsequent events cause our views to change. News & Information Disclosure Investors should note that we may use our website (investor.lemonade.com), blog (lemonade.com/blog), and our company account on X, Instagram and LinkedIn as a means of disclosing information and for complying with our disclosure obligations under Regulation FD. The information we post through these channels may be deemed material. Investors should monitor these channels in addition to reviewing our press releases, SEC filings, and public conference calls. 17
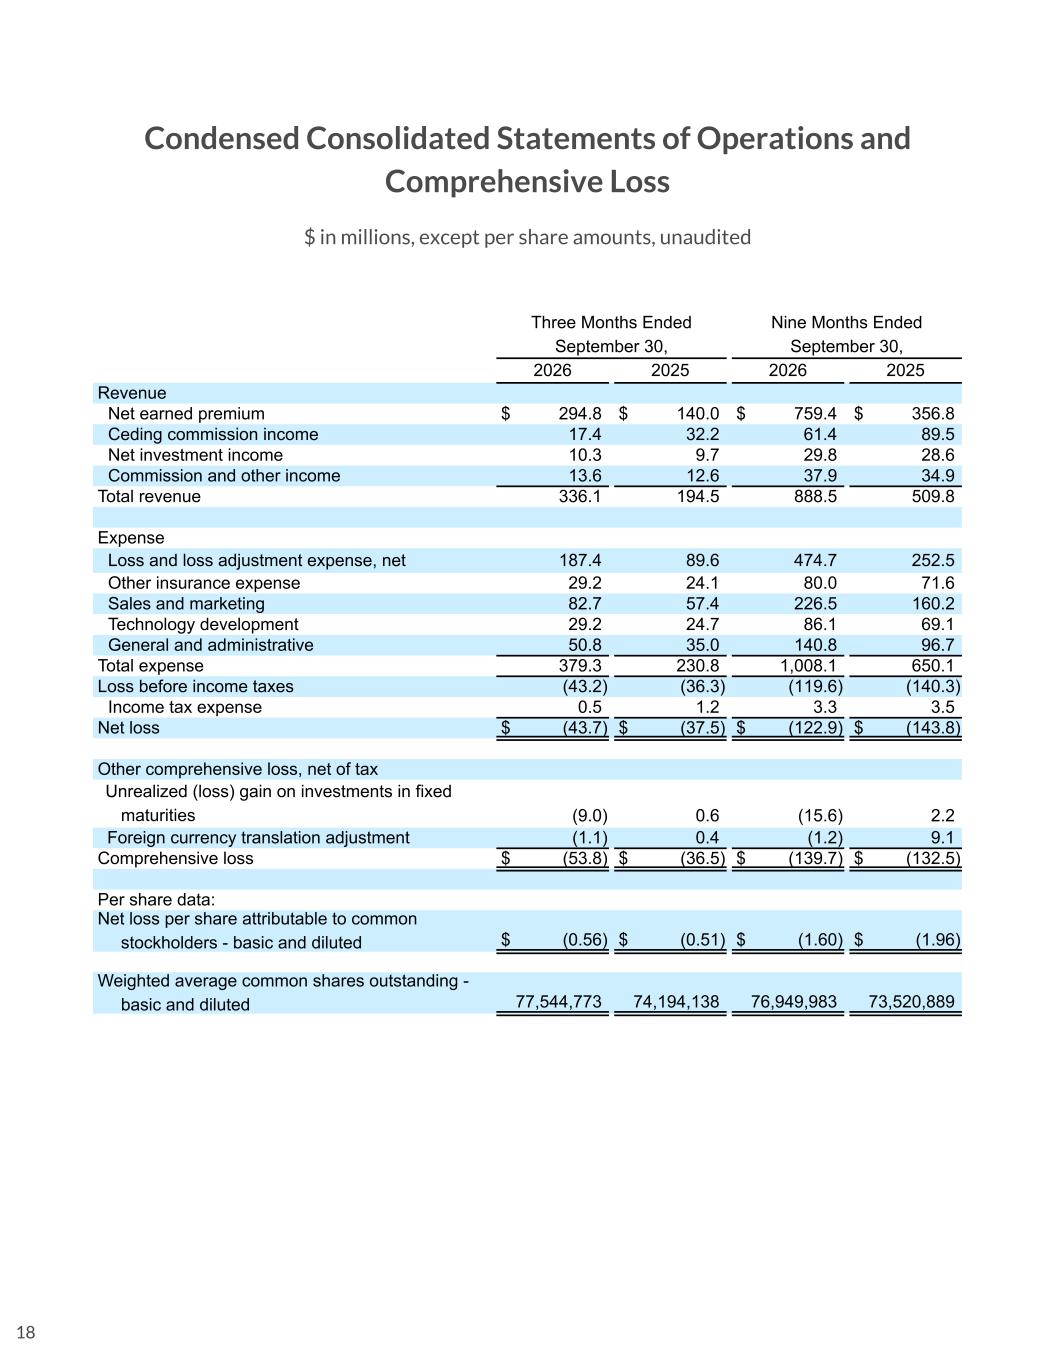
Condensed Consolidated Statements of Operations and Comprehensive Loss $ in millions, except per share amounts, unaudited Three Months Ended September 30, Nine Months Ended September 30, 2026 2025 2026 2025 Revenue Net earned premium $ 294.8 $ 140.0 $ 759.4 $ 356.8 Ceding commission income 17.4 32.2 61.4 89.5 Net investment income 10.3 9.7 29.8 28.6 Commission and other income 13.6 12.6 37.9 34.9 Total revenue 336.1 194.5 888.5 509.8 Expense Loss and loss adjustment expense, net 187.4 89.6 474.7 252.5 Other insurance expense 29.2 24.1 80.0 71.6 Sales and marketing 82.7 57.4 226.5 160.2 Technology development 29.2 24.7 86.1 69.1 General and administrative 50.8 35.0 140.8 96.7 Total expense 379.3 230.8 1,008.1 650.1 Loss before income taxes (43.2) (36.3) (119.6) (140.3) Income tax expense 0.5 1.2 3.3 3.5 Net loss $ (43.7) $ (37.5) $ (122.9) $ (143.8) Other comprehensive loss, net of tax Unrealized (loss) gain on investments in fixed maturities (9.0) 0.6 (15.6) 2.2 Foreign currency translation adjustment (1.1) 0.4 (1.2) 9.1 Comprehensive loss $ (53.8) $ (36.5) $ (139.7) $ (132.5) Per share data: Net loss per share attributable to common stockholders - basic and diluted $ (0.56) $ (0.51) $ (1.60) $ (1.96) Weighted average common shares outstanding - basic and diluted 77,544,773 74,194,138 76,949,983 73,520,889 18
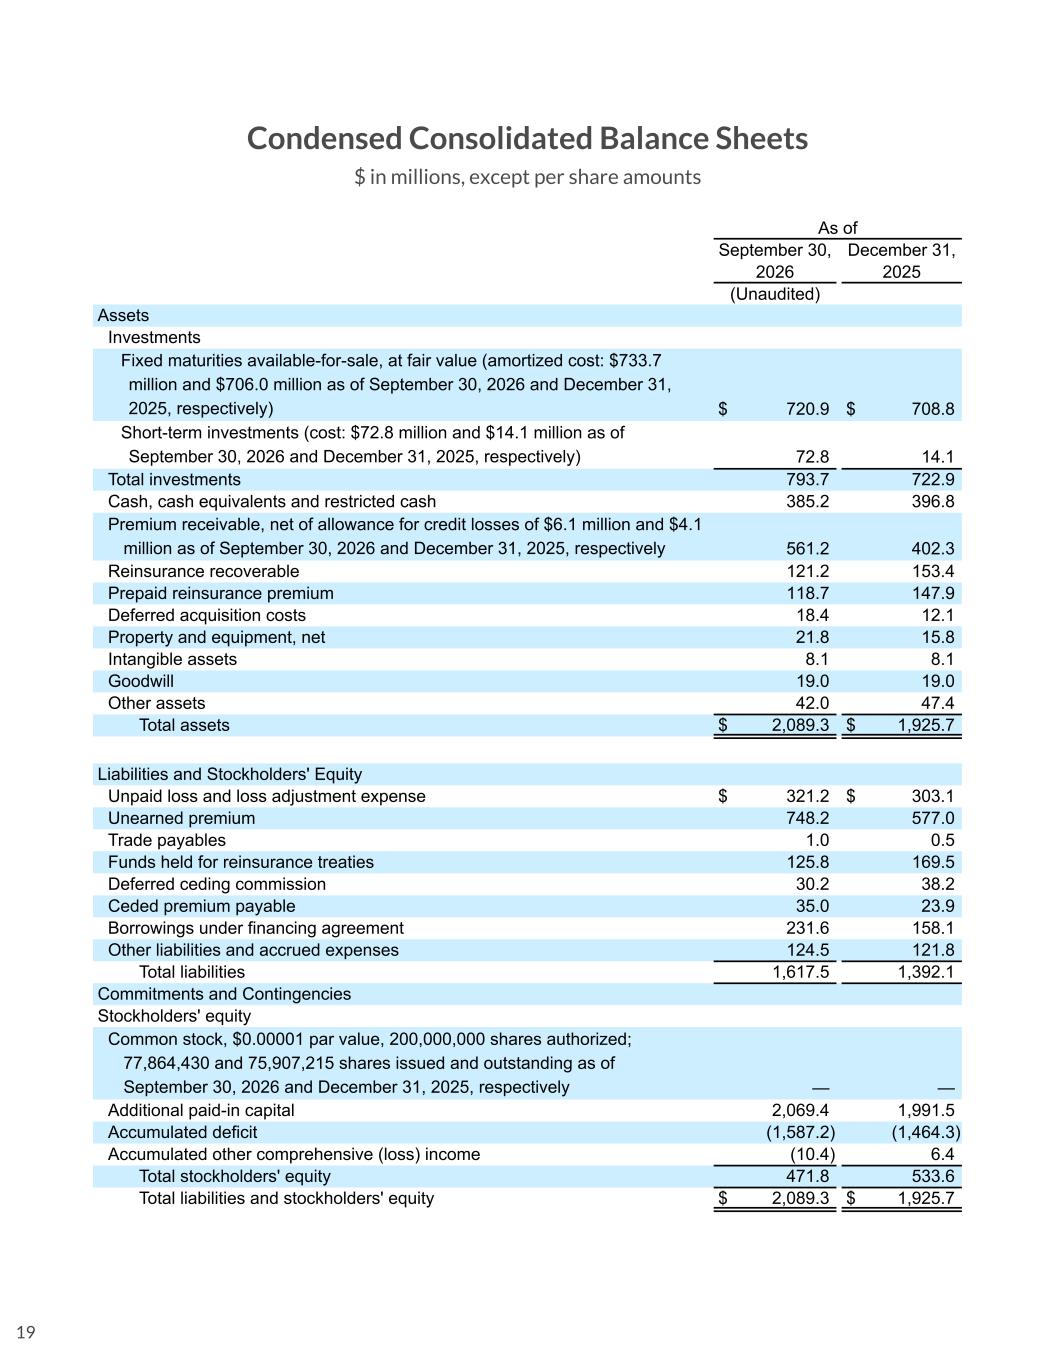
Condensed Consolidated Balance Sheets $ in millions, except per share amounts As of September 30, December 31, 2026 2025 (Unaudited) Assets Investments Fixed maturities available-for-sale, at fair value (amortized cost: $733.7 million and $706.0 million as of September 30, 2026 and December 31, 2025, respectively) $ 720.9 $ 708.8 Short-term investments (cost: $72.8 million and $14.1 million as of September 30, 2026 and December 31, 2025, respectively) 72.8 14.1 Total investments 793.7 722.9 Cash, cash equivalents and restricted cash 385.2 396.8 Premium receivable, net of allowance for credit losses of $6.1 million and $4.1 million as of September 30, 2026 and December 31, 2025, respectively 561.2 402.3 Reinsurance recoverable 121.2 153.4 Prepaid reinsurance premium 118.7 147.9 Deferred acquisition costs 18.4 12.1 Property and equipment, net 21.8 15.8 Intangible assets 8.1 8.1 Goodwill 19.0 19.0 Other assets 42.0 47.4 Total assets $ 2,089.3 $ 1,925.7 Liabilities and Stockholders' Equity Unpaid loss and loss adjustment expense $ 321.2 $ 303.1 Unearned premium 748.2 577.0 Trade payables 1.0 0.5 Funds held for reinsurance treaties 125.8 169.5 Deferred ceding commission 30.2 38.2 Ceded premium payable 35.0 23.9 Borrowings under financing agreement 231.6 158.1 Other liabilities and accrued expenses 124.5 121.8 Total liabilities 1,617.5 1,392.1 Commitments and Contingencies Stockholders' equity Common stock, $0.00001 par value, 200,000,000 shares authorized; 77,864,430 and 75,907,215 shares issued and outstanding as of September 30, 2026 and December 31, 2025, respectively — — Additional paid-in capital 2,069.4 1,991.5 Accumulated deficit (1,587.2) (1,464.3) Accumulated other comprehensive (loss) income (10.4) 6.4 Total stockholders' equity 471.8 533.6 Total liabilities and stockholders' equity $ 2,089.3 $ 1,925.7 19
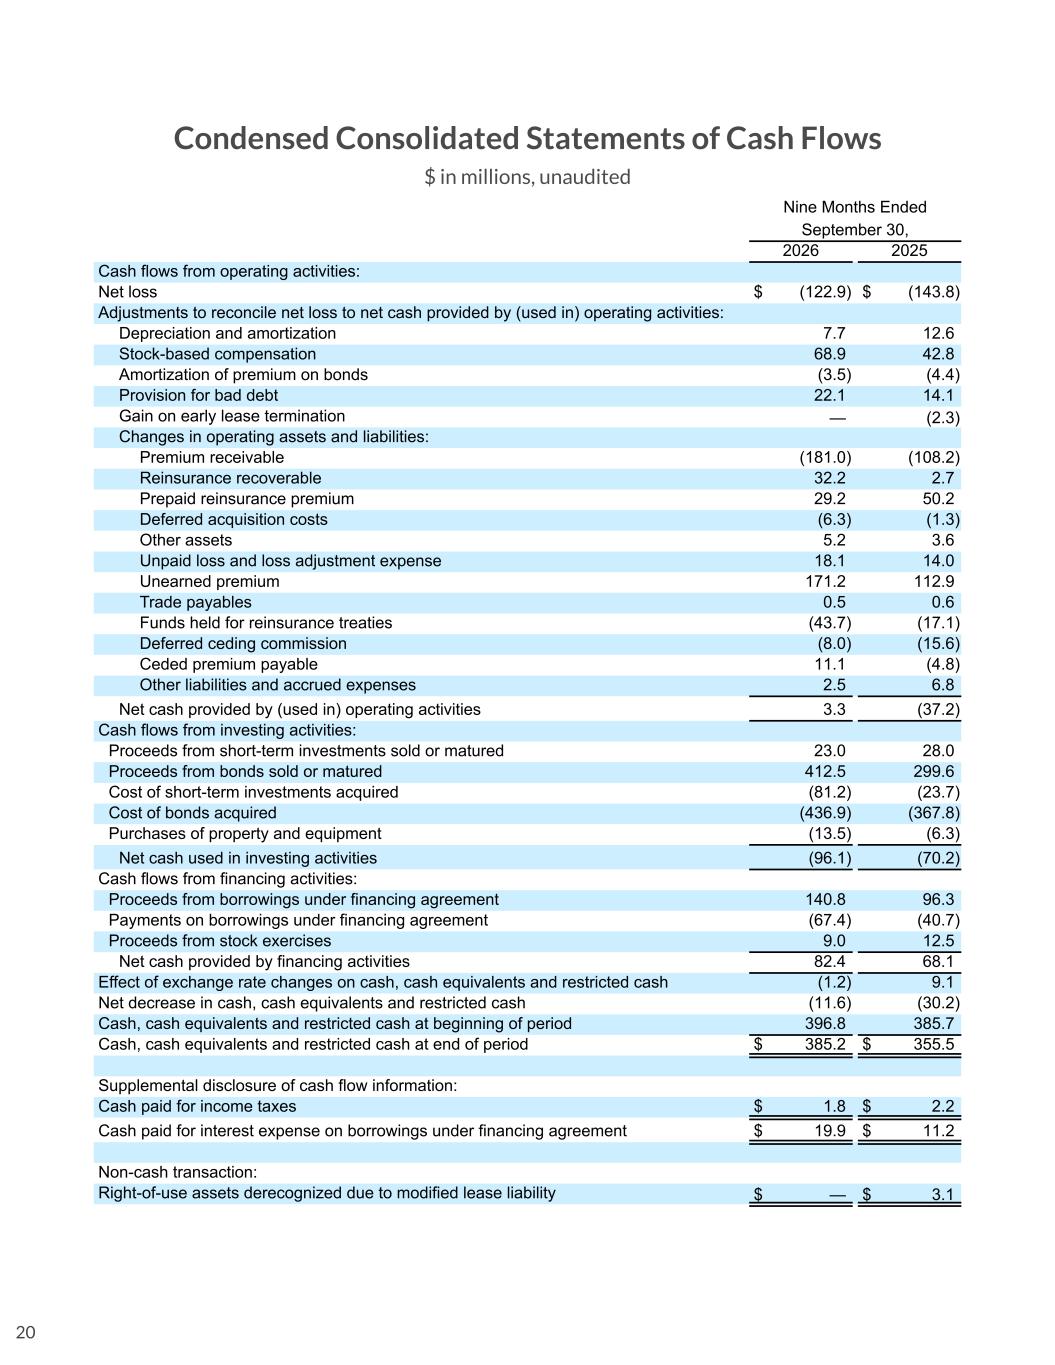
Condensed Consolidated Statements of Cash Flows $ in millions, unaudited Nine Months Ended September 30, 2026 2025 Cash flows from operating activities: Net loss $ (122.9) $ (143.8) Adjustments to reconcile net loss to net cash provided by (used in) operating activities: Depreciation and amortization 7.7 12.6 Stock-based compensation 68.9 42.8 Amortization of premium on bonds (3.5) (4.4) Provision for bad debt 22.1 14.1 Gain on early lease termination — (2.3) Changes in operating assets and liabilities: Premium receivable (181.0) (108.2) Reinsurance recoverable 32.2 2.7 Prepaid reinsurance premium 29.2 50.2 Deferred acquisition costs (6.3) (1.3) Other assets 5.2 3.6 Unpaid loss and loss adjustment expense 18.1 14.0 Unearned premium 171.2 112.9 Trade payables 0.5 0.6 Funds held for reinsurance treaties (43.7) (17.1) Deferred ceding commission (8.0) (15.6) Ceded premium payable 11.1 (4.8) Other liabilities and accrued expenses 2.5 6.8 Net cash provided by (used in) operating activities 3.3 (37.2) Cash flows from investing activities: Proceeds from short-term investments sold or matured 23.0 28.0 Proceeds from bonds sold or matured 412.5 299.6 Cost of short-term investments acquired (81.2) (23.7) Cost of bonds acquired (436.9) (367.8) Purchases of property and equipment (13.5) (6.3) Net cash used in investing activities (96.1) (70.2) Cash flows from financing activities: Proceeds from borrowings under financing agreement 140.8 96.3 Payments on borrowings under financing agreement (67.4) (40.7) Proceeds from stock exercises 9.0 12.5 Net cash provided by financing activities 82.4 68.1 Effect of exchange rate changes on cash, cash equivalents and restricted cash (1.2) 9.1 Net decrease in cash, cash equivalents and restricted cash (11.6) (30.2) Cash, cash equivalents and restricted cash at beginning of period 396.8 385.7 Cash, cash equivalents and restricted cash at end of period $ 385.2 $ 355.5 Supplemental disclosure of cash flow information: Cash paid for income taxes $ 1.8 $ 2.2 Cash paid for interest expense on borrowings under financing agreement $ 19.9 $ 11.2 Non-cash transaction: Right-of-use assets derecognized due to modified lease liability $ — $ 3.1 20
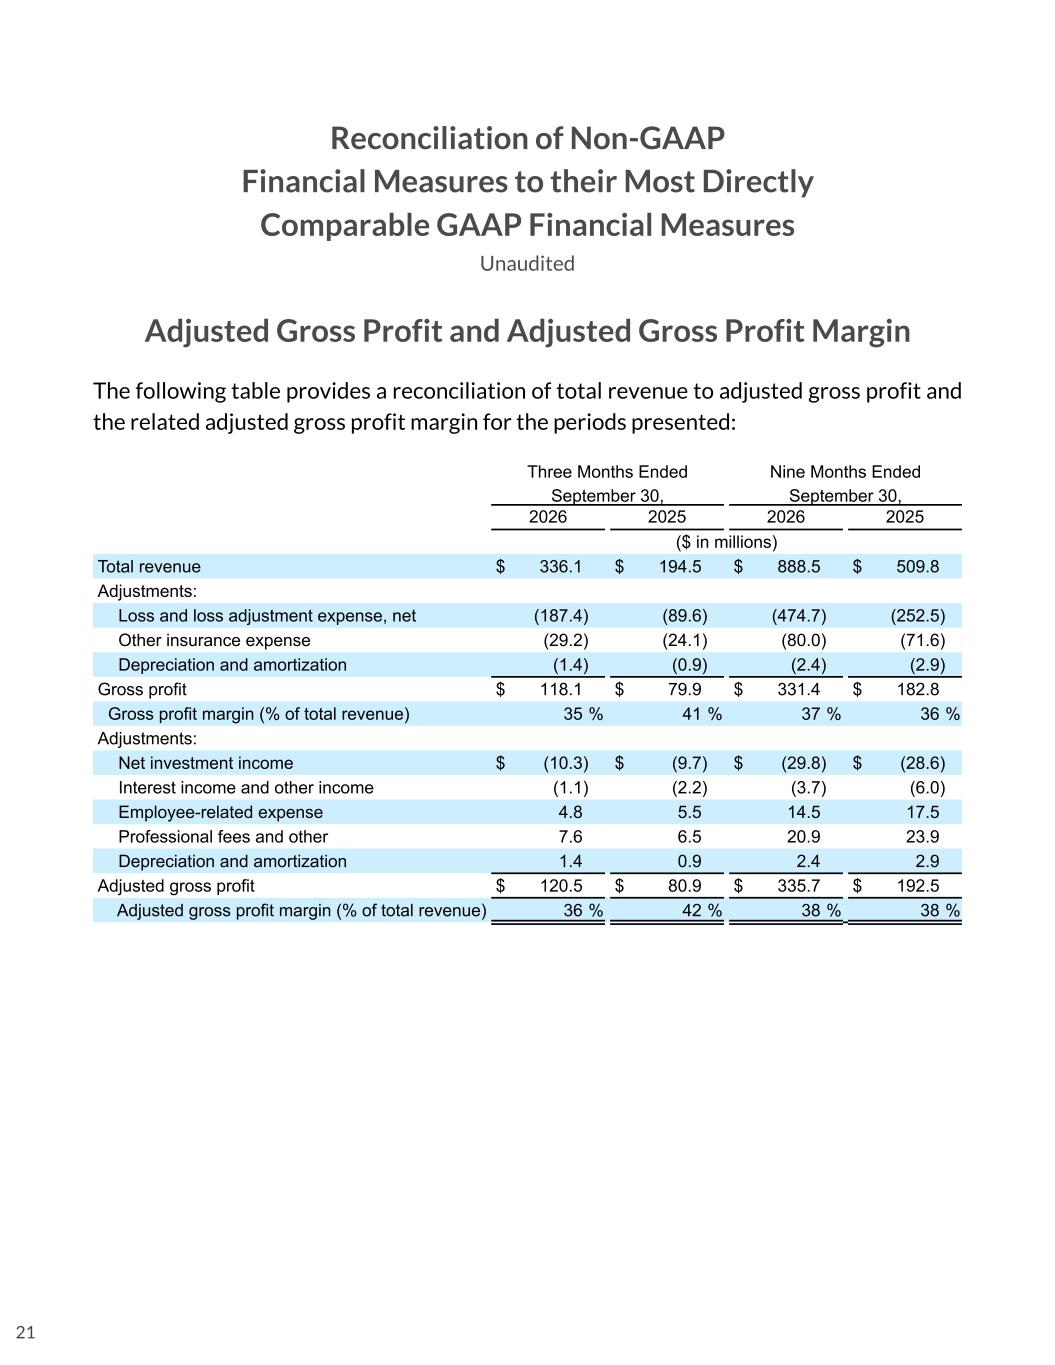
Reconciliation of Non-GAAP Financial Measures to their Most Directly Comparable GAAP Financial Measures Unaudited Adjusted Gross Profit and Adjusted Gross Profit Margin The following table provides a reconciliation of total revenue to adjusted gross profit and the related adjusted gross profit margin for the periods presented: Three Months Ended September 30, Nine Months Ended September 30, 2026 2025 2026 2025 ($ in millions) Total revenue $ 336.1 $ 194.5 $ 888.5 $ 509.8 Adjustments: Loss and loss adjustment expense, net (187.4) (89.6) (474.7) (252.5) Other insurance expense (29.2) (24.1) (80.0) (71.6) Depreciation and amortization (1.4) (0.9) (2.4) (2.9) Gross profit $ 118.1 $ 79.9 $ 331.4 $ 182.8 Gross profit margin (% of total revenue) 35 % 41 % 37 % 36 % Adjustments: Net investment income $ (10.3) $ (9.7) $ (29.8) $ (28.6) Interest income and other income (1.1) (2.2) (3.7) (6.0) Employee-related expense 4.8 5.5 14.5 17.5 Professional fees and other 7.6 6.5 20.9 23.9 Depreciation and amortization 1.4 0.9 2.4 2.9 Adjusted gross profit $ 120.5 $ 80.9 $ 335.7 $ 192.5 Adjusted gross profit margin (% of total revenue) 36 % 42 % 38 % 38 % 21
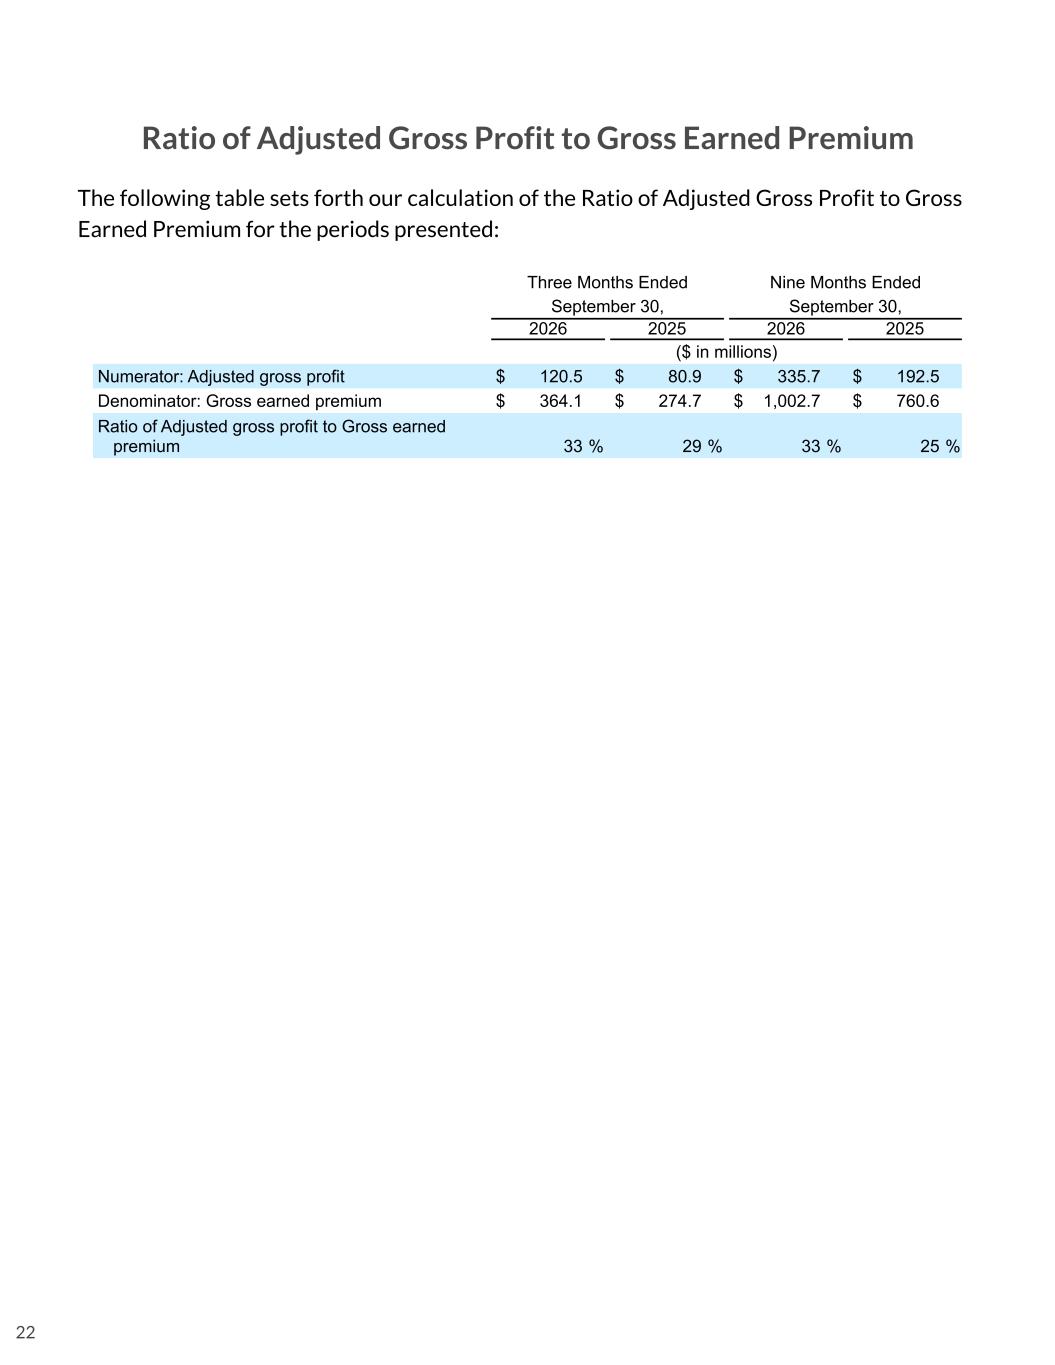
Ratio of Adjusted Gross Profit to Gross Earned Premium The following table sets forth our calculation of the Ratio of Adjusted Gross Profit to Gross Earned Premium for the periods presented: Three Months Ended September 30, Nine Months Ended September 30, 2026 2025 2026 2025 ($ in millions) Numerator: Adjusted gross profit $ 120.5 $ 80.9 $ 335.7 $ 192.5 Denominator: Gross earned premium $ 364.1 $ 274.7 $ 1,002.7 $ 760.6 Ratio of Adjusted gross profit to Gross earned premium 33 % 29 % 33 % 25 % 22
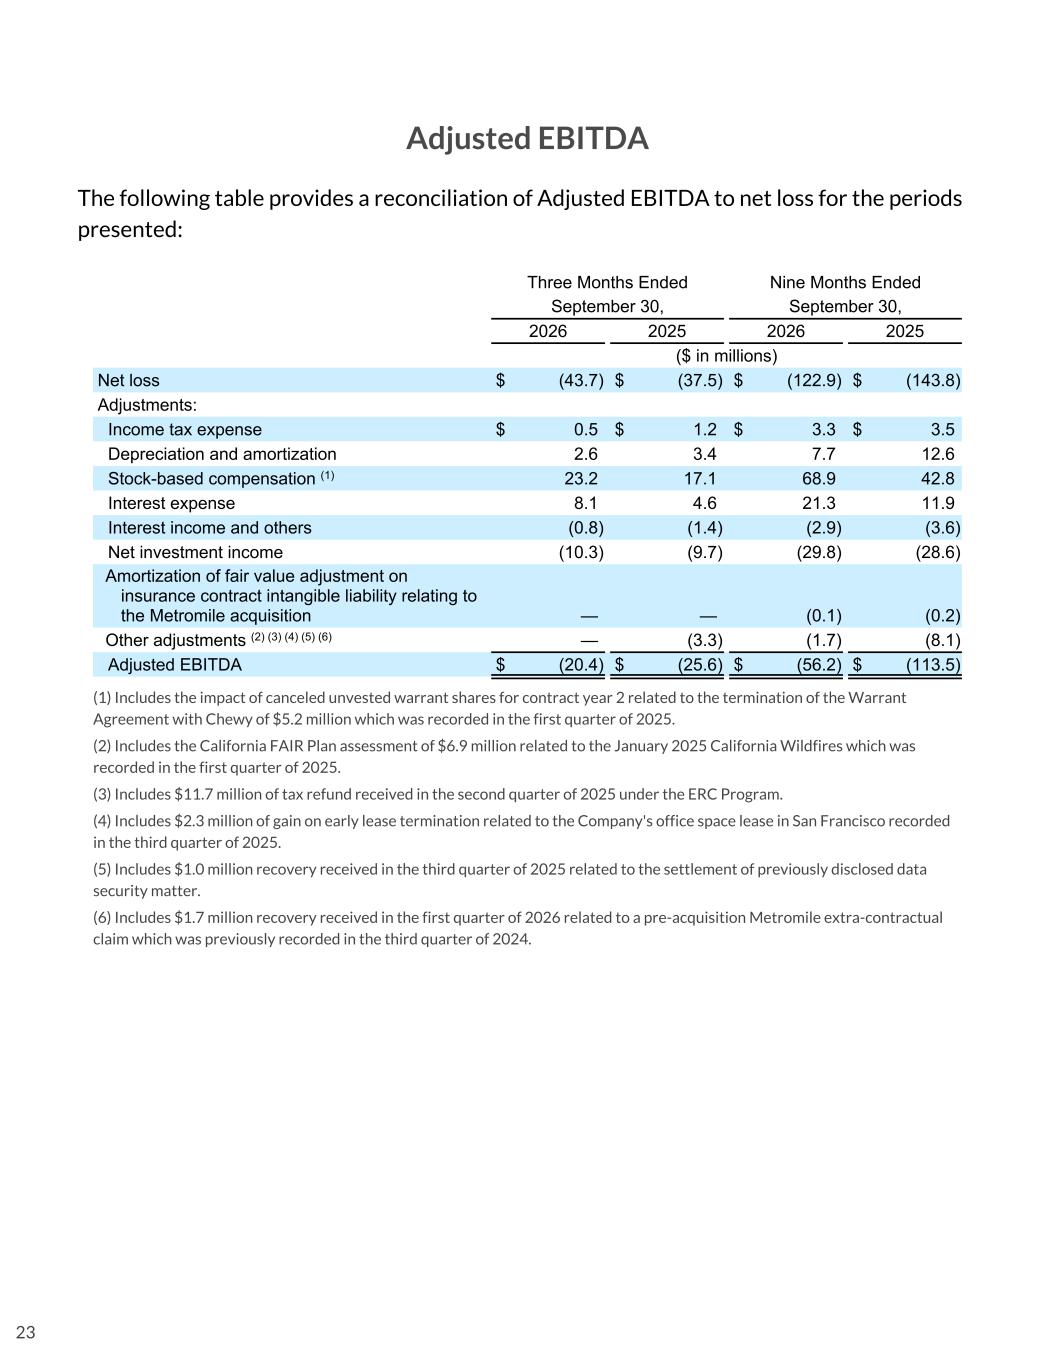
Adjusted EBITDA The following table provides a reconciliation of Adjusted EBITDA to net loss for the periods presented: Three Months Ended September 30, Nine Months Ended September 30, 2026 2025 2026 2025 ($ in millions) Net loss $ (43.7) $ (37.5) $ (122.9) $ (143.8) Adjustments: Income tax expense $ 0.5 $ 1.2 $ 3.3 $ 3.5 Depreciation and amortization 2.6 3.4 7.7 12.6 Stock-based compensation (1) 23.2 17.1 68.9 42.8 Interest expense 8.1 4.6 21.3 11.9 Interest income and others (0.8) (1.4) (2.9) (3.6) Net investment income (10.3) (9.7) (29.8) (28.6) Amortization of fair value adjustment on insurance contract intangible liability relating to the Metromile acquisition — — (0.1) (0.2) Other adjustments (2) (3) (4) (5) (6) — (3.3) (1.7) (8.1) Adjusted EBITDA $ (20.4) $ (25.6) $ (56.2) $ (113.5) (1) Includes the impact of canceled unvested warrant shares for contract year 2 related to the termination of the Warrant Agreement with Chewy of $5.2 million which was recorded in the first quarter of 2025. (2) Includes the California FAIR Plan assessment of $6.9 million related to the January 2025 California Wildfires which was recorded in the first quarter of 2025. (3) Includes $11.7 million of tax refund received in the second quarter of 2025 under the ERC Program. (4) Includes $2.3 million of gain on early lease termination related to the Company's office space lease in San Francisco recorded in the third quarter of 2025. (5) Includes $1.0 million recovery received in the third quarter of 2025 related to the settlement of previously disclosed data security matter. (6) Includes $1.7 million recovery received in the first quarter of 2026 related to a pre-acquisition Metromile extra-contractual claim which was previously recorded in the third quarter of 2024. 23
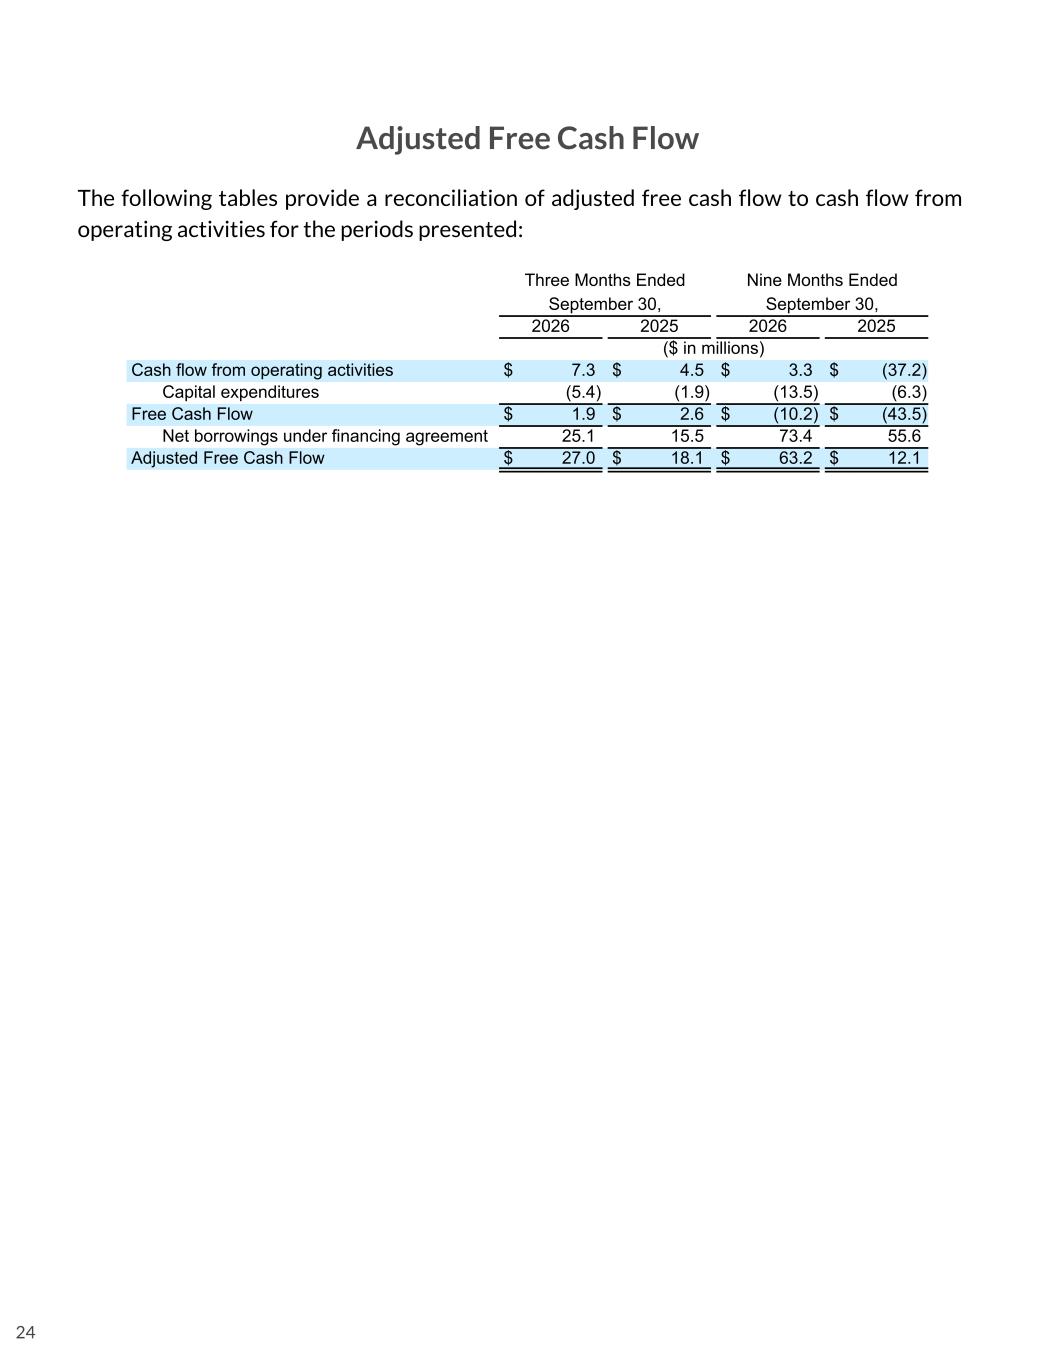
Adjusted Free Cash Flow The following tables provide a reconciliation of adjusted free cash flow to cash flow from operating activities for the periods presented: Three Months Ended September 30, Nine Months Ended September 30, 2026 2025 2026 2025 ($ in millions) Cash flow from operating activities $ 7.3 $ 4.5 $ 3.3 $ (37.2) Capital expenditures (5.4) (1.9) (13.5) (6.3) Free Cash Flow $ 1.9 $ 2.6 $ (10.2) $ (43.5) Net borrowings under financing agreement 25.1 15.5 73.4 55.6 Adjusted Free Cash Flow $ 27.0 $ 18.1 $ 63.2 $ 12.1 24
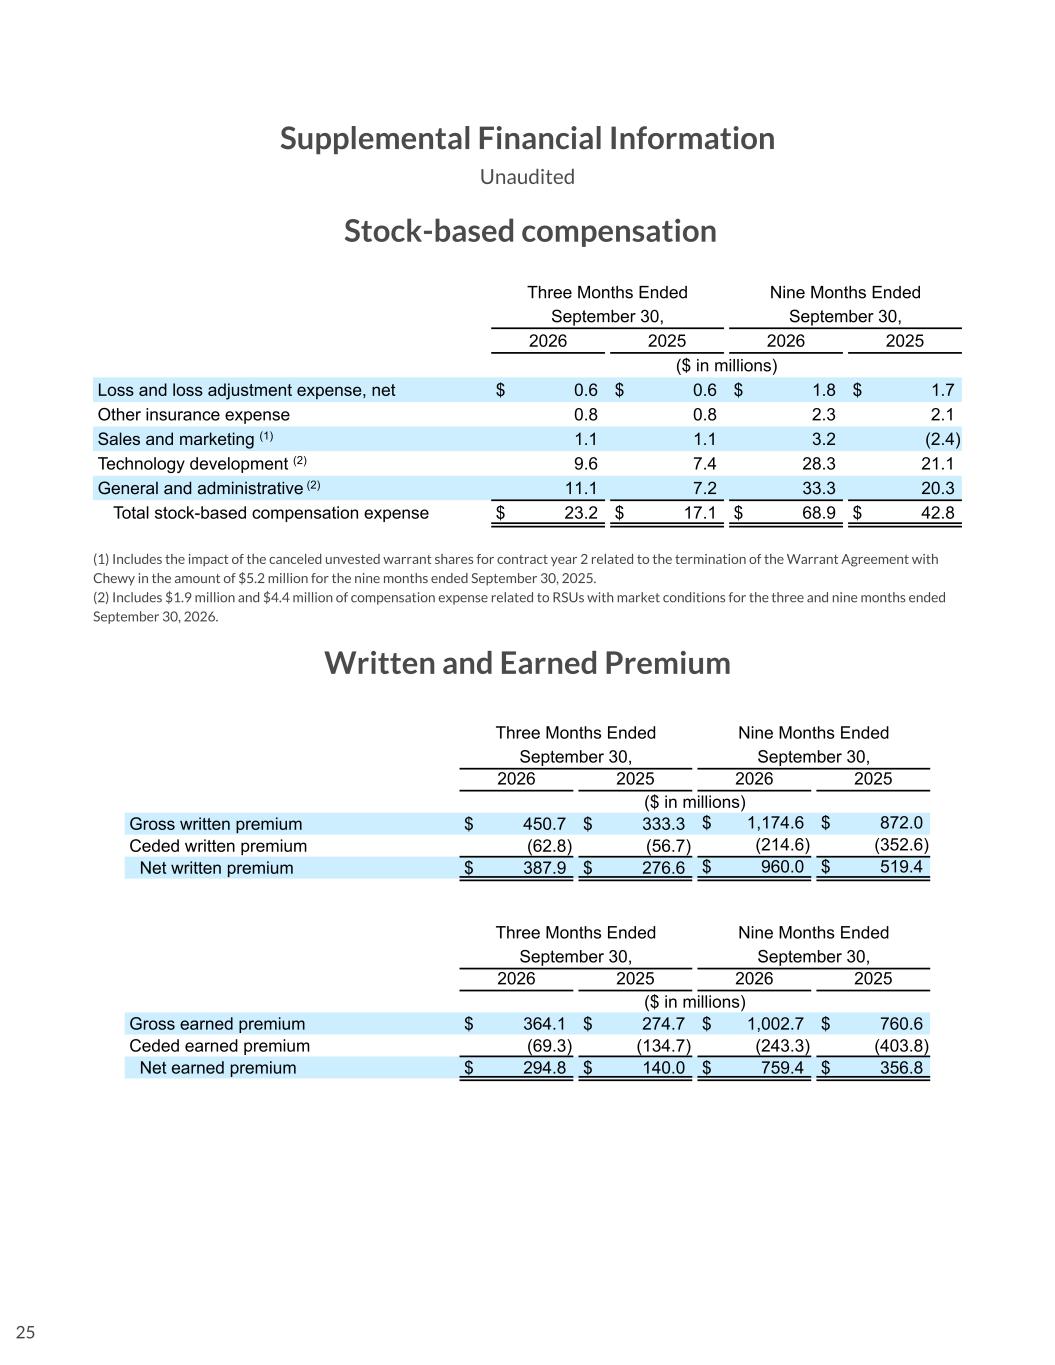
Supplemental Financial Information Unaudited Stock-based compensation Three Months Ended September 30, Nine Months Ended September 30, 2026 2025 2026 2025 ($ in millions) Loss and loss adjustment expense, net $ 0.6 $ 0.6 $ 1.8 $ 1.7 Other insurance expense 0.8 0.8 2.3 2.1 Sales and marketing (1) 1.1 1.1 3.2 (2.4) Technology development (2) 9.6 7.4 28.3 21.1 General and administrative (2) 11.1 7.2 33.3 20.3 Total stock-based compensation expense $ 23.2 $ 17.1 $ 68.9 $ 42.8 (1) Includes the impact of the canceled unvested warrant shares for contract year 2 related to the termination of the Warrant Agreement with Chewy in the amount of $5.2 million for the nine months ended September 30, 2025. (2) Includes $1.9 million and $4.4 million of compensation expense related to RSUs with market conditions for the three and nine months ended September 30, 2026. Written and Earned Premium Three Months Ended September 30, Nine Months Ended September 30, 2026 2025 2026 2025 ($ in millions) Gross written premium $ 450.7 $ 333.3 $ 1,174.6 $ 872.0 Ceded written premium (62.8) (56.7) (214.6) (352.6) Net written premium $ 387.9 $ 276.6 $ 960.0 $ 519.4 Three Months Ended September 30, Nine Months Ended September 30, 2026 2025 2026 2025 ($ in millions) Gross earned premium $ 364.1 $ 274.7 $ 1,002.7 $ 760.6 Ceded earned premium (69.3) (134.7) (243.3) (403.8) Net earned premium $ 294.8 $ 140.0 $ 759.4 $ 356.8 25
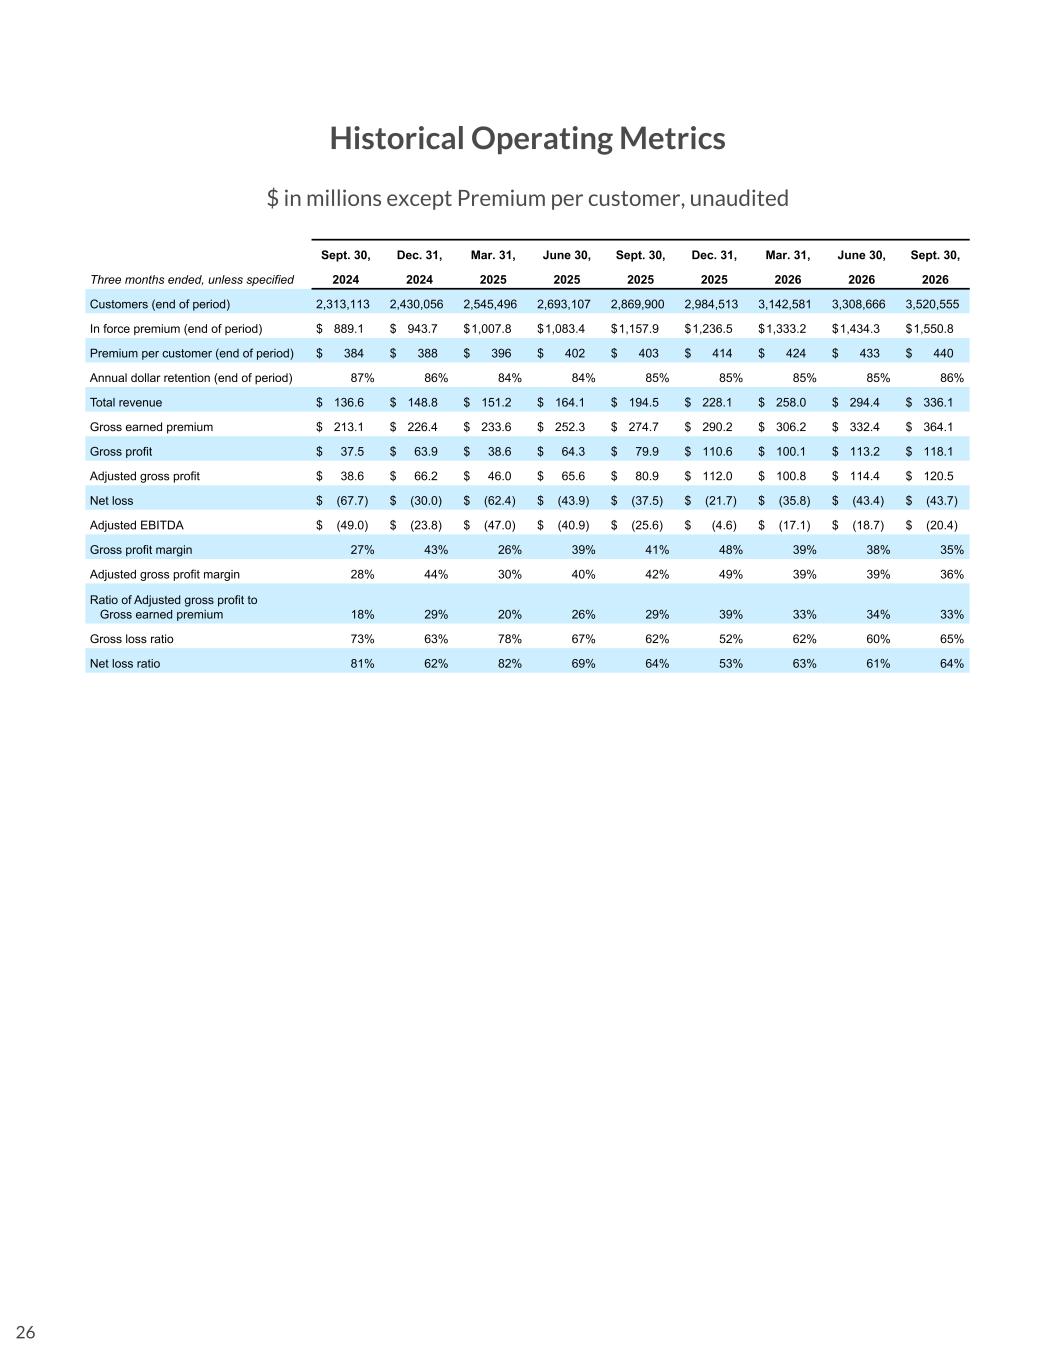
Historical Operating Metrics $ in millions except Premium per customer, unaudited Sept. 30, Dec. 31, Mar. 31, June 30, Sept. 30, Dec. 31, Mar. 31, June 30, Sept. 30, Three months ended, unless specified 2024 2024 2025 2025 2025 2025 2026 2026 2026 Customers (end of period) 2,313,113 2,430,056 2,545,496 2,693,107 2,869,900 2,984,513 3,142,581 3,308,666 3,520,555 In force premium (end of period) $ 889.1 $ 943.7 $ 1,007.8 $ 1,083.4 $ 1,157.9 $ 1,236.5 $ 1,333.2 $ 1,434.3 $ 1,550.8 Premium per customer (end of period) $ 384 $ 388 $ 396 $ 402 $ 403 $ 414 $ 424 $ 433 $ 440 Annual dollar retention (end of period) 87% 86% 84% 84% 85% 85% 85% 85% 86% Total revenue $ 136.6 $ 148.8 $ 151.2 $ 164.1 $ 194.5 $ 228.1 $ 258.0 $ 294.4 $ 336.1 Gross earned premium $ 213.1 $ 226.4 $ 233.6 $ 252.3 $ 274.7 $ 290.2 $ 306.2 $ 332.4 $ 364.1 Gross profit $ 37.5 $ 63.9 $ 38.6 $ 64.3 $ 79.9 $ 110.6 $ 100.1 $ 113.2 $ 118.1 Adjusted gross profit $ 38.6 $ 66.2 $ 46.0 $ 65.6 $ 80.9 $ 112.0 $ 100.8 $ 114.4 $ 120.5 Net loss $ (67.7) $ (30.0) $ (62.4) $ (43.9) $ (37.5) $ (21.7) $ (35.8) $ (43.4) $ (43.7) Adjusted EBITDA $ (49.0) $ (23.8) $ (47.0) $ (40.9) $ (25.6) $ (4.6) $ (17.1) $ (18.7) $ (20.4) Gross profit margin 27% 43% 26% 39% 41% 48% 39% 38% 35% Adjusted gross profit margin 28% 44% 30% 40% 42% 49% 39% 39% 36% Ratio of Adjusted gross profit to Gross earned premium 18% 29% 20% 26% 29% 39% 33% 34% 33% Gross loss ratio 73% 63% 78% 67% 62% 52% 62% 60% 65% Net loss ratio 81% 62% 82% 69% 64% 53% 63% 61% 64% 26
Trends Q3 2026 27
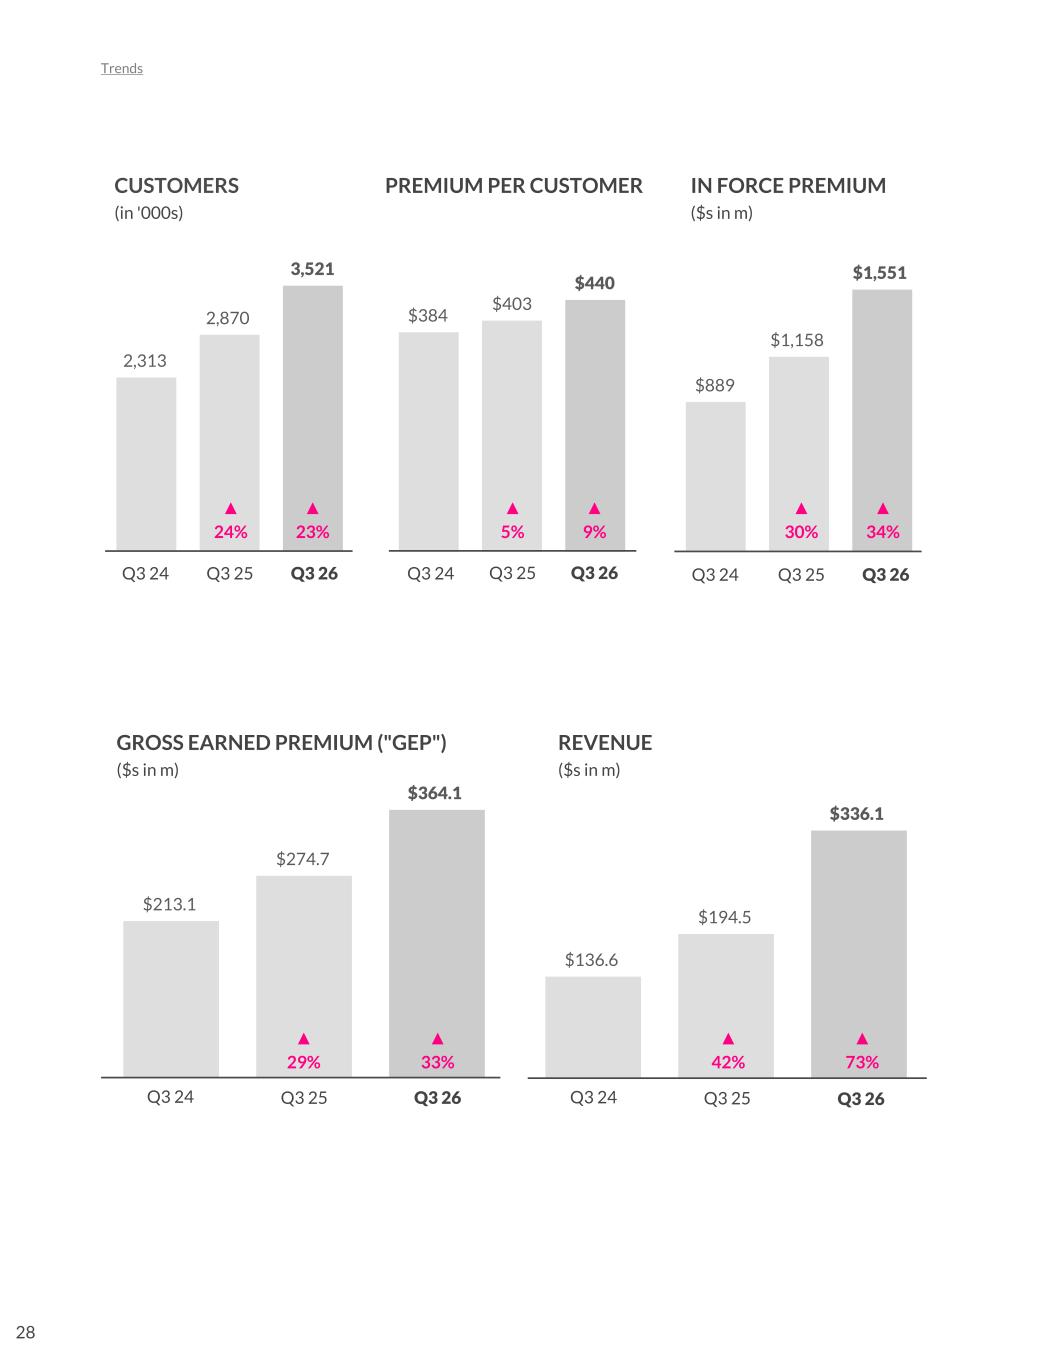
2,313 2,870 3,521 $384 $403 $440 $889 $1,158 $1,551 $213.1 $274.7 $364.1 $136.6 $194.5 $336.1 Trends 28 CUSTOMERS (in '000s) PREMIUM PER CUSTOMER IN FORCE PREMIUM ($s in m) ▲ 24% Q3 24 Q3 25 Q3 26 Q3 24 Q3 25 Q3 26 Q3 24 Q3 25 Q3 26 ▲ 23% ▲ 5% ▲ 9% ▲ 30% ▲ 34% GROSS EARNED PREMIUM ("GEP") ($s in m) REVENUE ($s in m) ▲ 29% ▲ 33% ▲ 42% ▲ 73% Q3 24 Q3 25 Q3 26 Q3 24 Q3 25 Q3 26
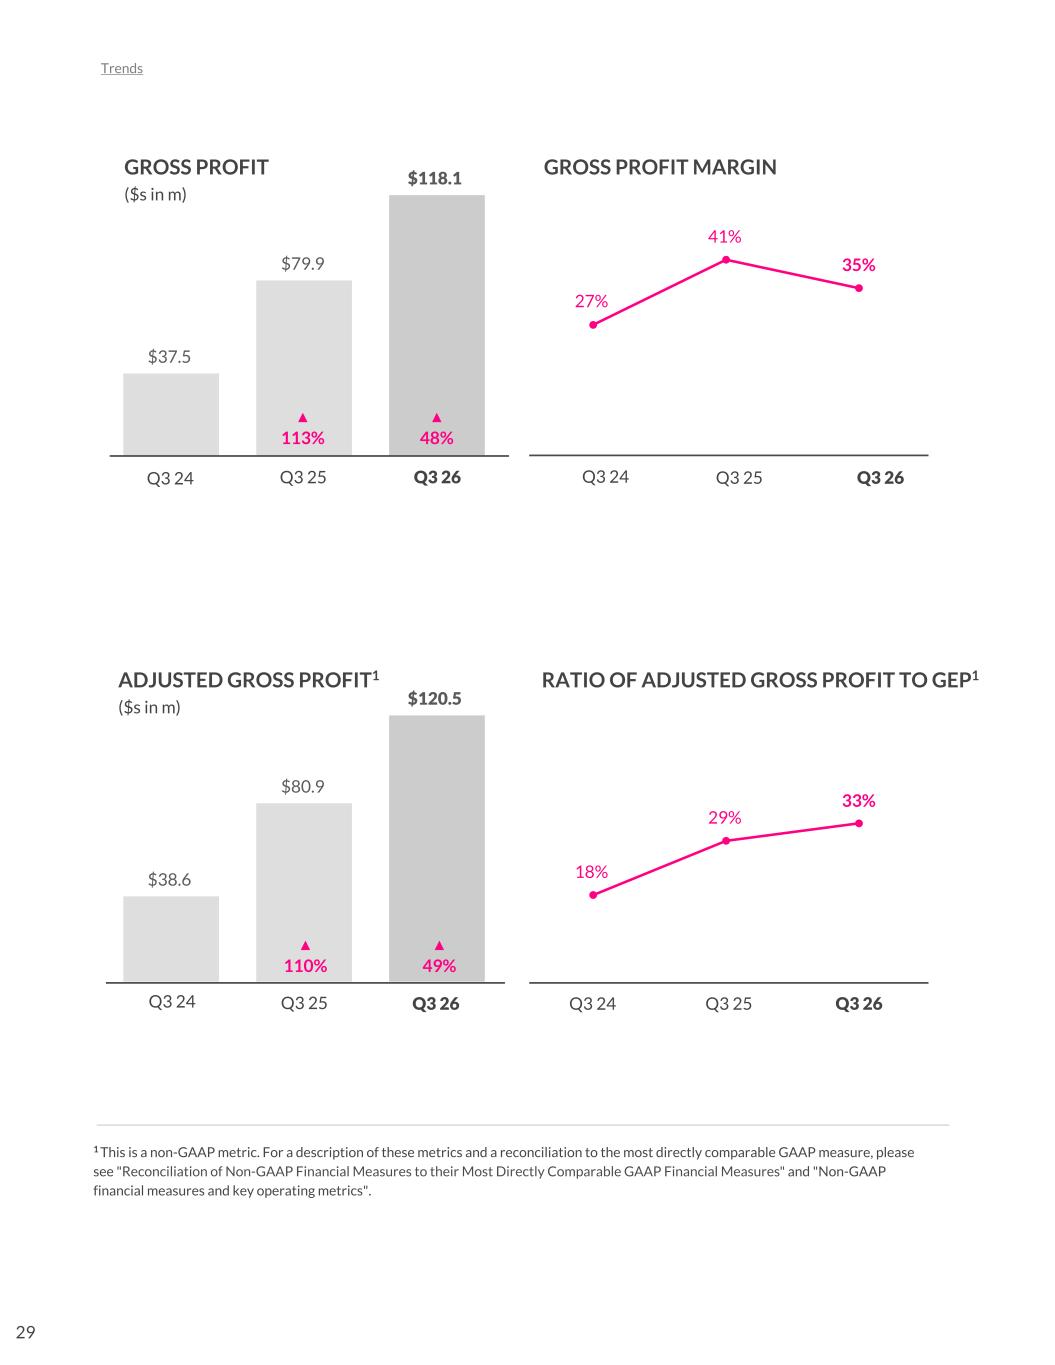
$37.5 $79.9 $118.1 27% 41% 35% $38.6 $80.9 $120.5 18% 29% 33% Trends 29 GROSS PROFIT ($s in m) GROSS PROFIT MARGIN ▲ 113% ▲ 48% Q3 24 Q3 25 Q3 26 Q3 24 Q3 25 Q3 26 ADJUSTED GROSS PROFIT1 ($s in m) RATIO OF ADJUSTED GROSS PROFIT TO GEP1 ▲ 110% ▲ 49% Q3 24 Q3 25 Q3 26 Q3 24 Q3 26 1 This is a non-GAAP metric. For a description of these metrics and a reconciliation to the most directly comparable GAAP measure, please see "Reconciliation of Non-GAAP Financial Measures to their Most Directly Comparable GAAP Financial Measures" and "Non-GAAP financial measures and key operating metrics". Q3 25
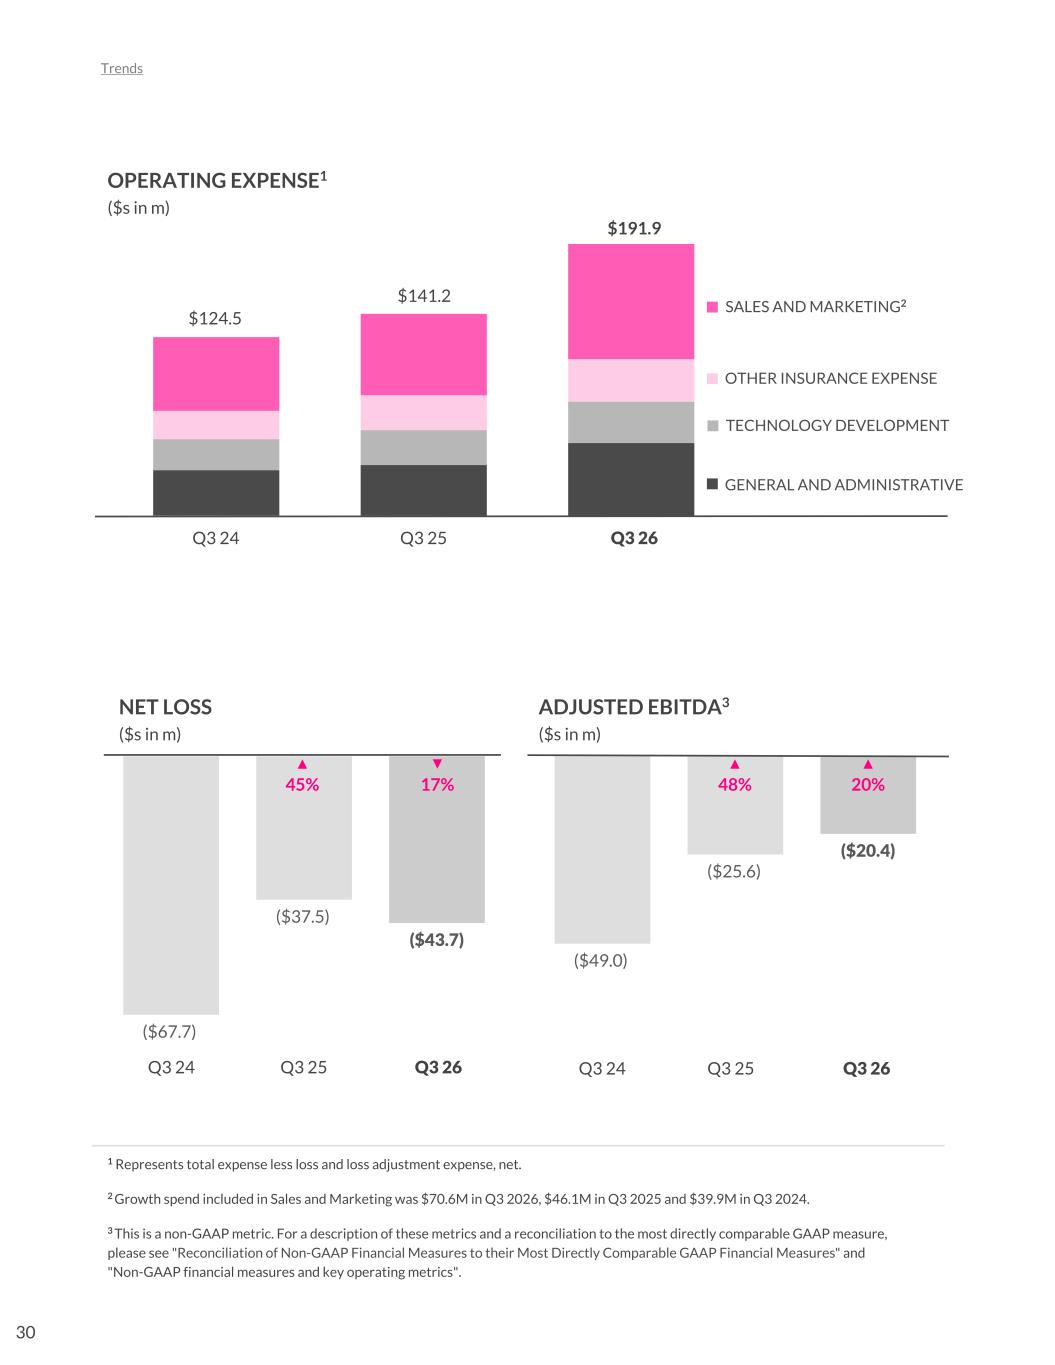
($67.7) ($37.5) ($43.7) ($49.0) ($25.6) ($20.4) Trends 30 OPERATING EXPENSE1 ($s in m) Q3 24 Q3 25 Q3 26 $124.5 $141.2 $191.9 NET LOSS ($s in m) Q3 24 Q3 25 Q3 26 ▲ 45% ▼ 17% 1 Represents total expense less loss and loss adjustment expense, net. 2 Growth spend included in Sales and Marketing was $70.6M in Q3 2026, $46.1M in Q3 2025 and $39.9M in Q3 2024. 3 This is a non-GAAP metric. For a description of these metrics and a reconciliation to the most directly comparable GAAP measure, please see "Reconciliation of Non-GAAP Financial Measures to their Most Directly Comparable GAAP Financial Measures" and "Non-GAAP financial measures and key operating metrics". ADJUSTED EBITDA3 ($s in m) Q3 24 Q3 25 Q3 26 ▲ 48% ▲ 20% SALES AND MARKETING2 OTHER INSURANCE EXPENSE TECHNOLOGY DEVELOPMENT GENERAL AND ADMINISTRATIVE
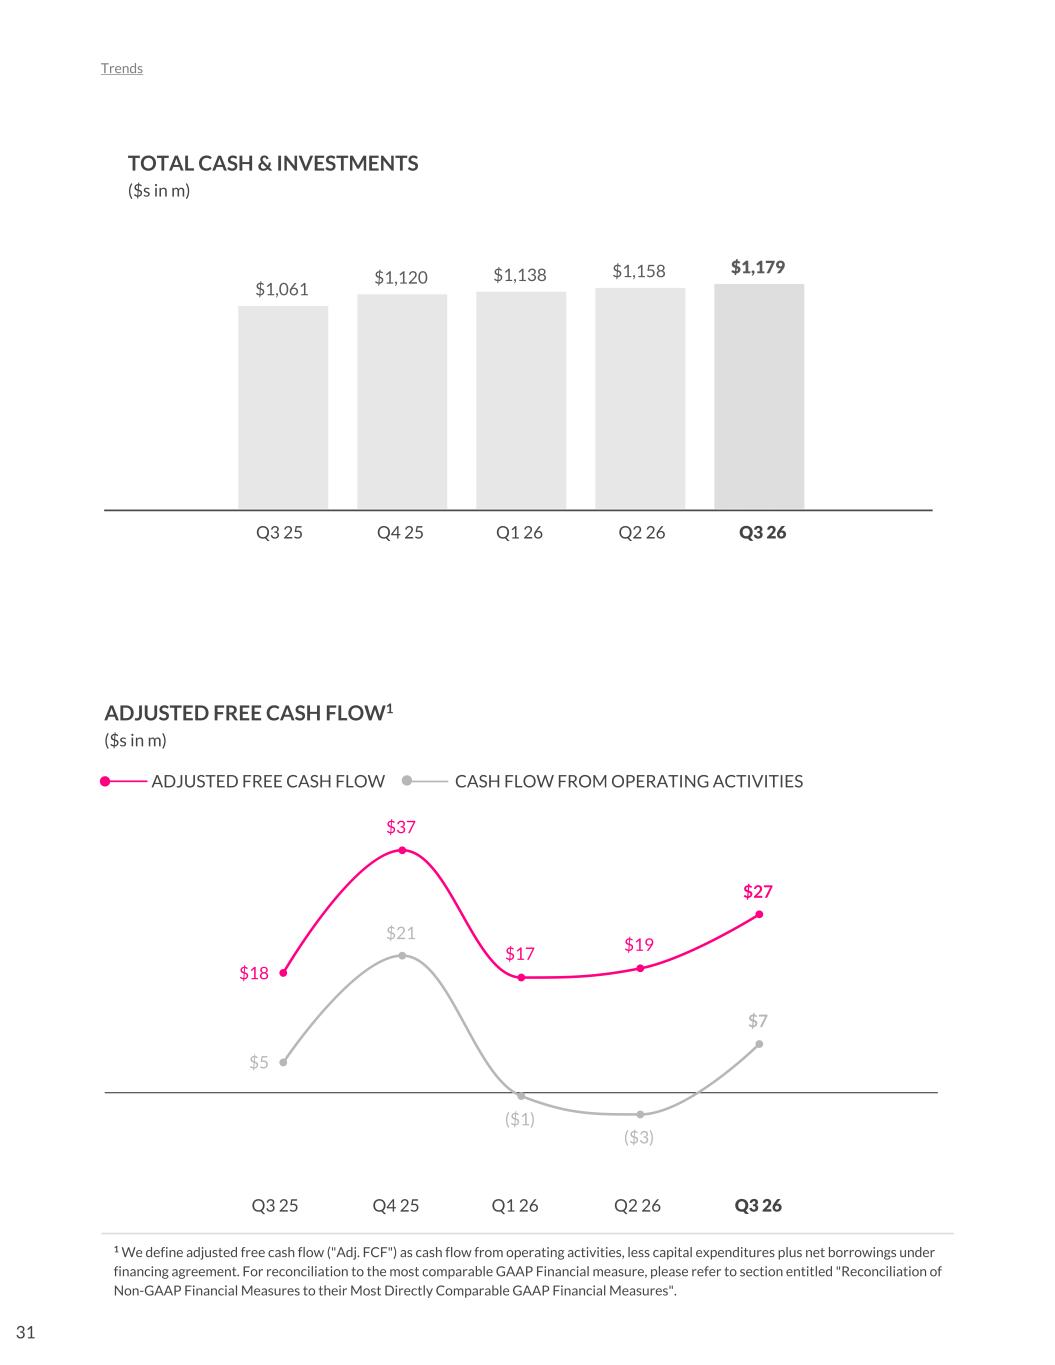
$1,061 $1,120 $1,138 $1,158 $1,179 $18 $37 $17 $19 $27 $5 $21 ($1) ($3) $7 Trends 31 TOTAL CASH & INVESTMENTS ($s in m) Q1 26 Q2 26 Q3 26Q4 25Q3 25 ADJUSTED FREE CASH FLOW1 ($s in m) 1 We define adjusted free cash flow ("Adj. FCF") as cash flow from operating activities, less capital expenditures plus net borrowings under financing agreement. For reconciliation to the most comparable GAAP Financial measure, please refer to section entitled "Reconciliation of Non-GAAP Financial Measures to their Most Directly Comparable GAAP Financial Measures". ADJUSTED FREE CASH FLOW CASH FLOW FROM OPERATING ACTIVITIES Q1 26 Q2 26 Q3 26Q4 25Q3 25
Insurance Supplement Q3 2026 32
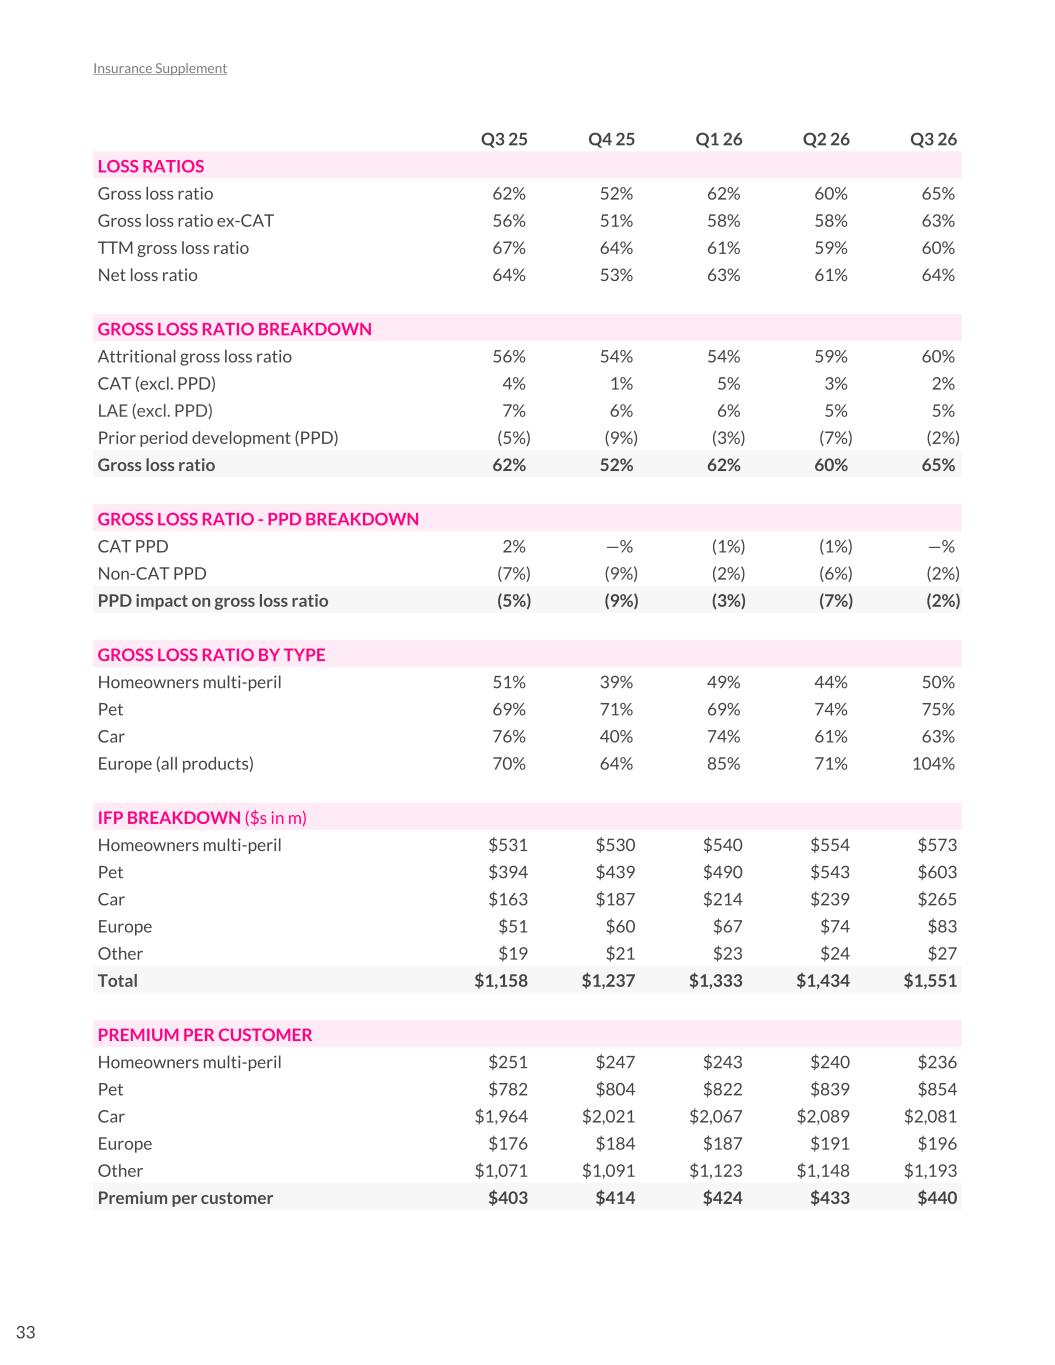
Q3 25 Q4 25 Q1 26 Q2 26 Q3 26 LOSS RATIOS Gross loss ratio 62% 52% 62% 60% 65% Gross loss ratio ex-CAT 56% 51% 58% 58% 63% TTM gross loss ratio 67% 64% 61% 59% 60% Net loss ratio 64% 53% 63% 61% 64% GROSS LOSS RATIO BREAKDOWN Attritional gross loss ratio 56% 54% 54% 59% 60% CAT (excl. PPD) 4% 1% 5% 3% 2% LAE (excl. PPD) 7% 6% 6% 5% 5% Prior period development (PPD) (5%) (9%) (3%) (7%) (2%) Gross loss ratio 62% 52% 62% 60% 65% GROSS LOSS RATIO - PPD BREAKDOWN CAT PPD 2% —% (1%) (1%) —% Non-CAT PPD (7%) (9%) (2%) (6%) (2%) PPD impact on gross loss ratio (5%) (9%) (3%) (7%) (2%) GROSS LOSS RATIO BY TYPE Homeowners multi-peril 51% 39% 49% 44% 50% Pet 69% 71% 69% 74% 75% Car 76% 40% 74% 61% 63% Europe (all products) 70% 64% 85% 71% 104% IFP BREAKDOWN ($s in m) Homeowners multi-peril $531 $530 $540 $554 $573 Pet $394 $439 $490 $543 $603 Car $163 $187 $214 $239 $265 Europe $51 $60 $67 $74 $83 Other $19 $21 $23 $24 $27 Total $1,158 $1,237 $1,333 $1,434 $1,551 PREMIUM PER CUSTOMER Homeowners multi-peril $251 $247 $243 $240 $236 Pet $782 $804 $822 $839 $854 Car $1,964 $2,021 $2,067 $2,089 $2,081 Europe $176 $184 $187 $191 $196 Other $1,071 $1,091 $1,123 $1,148 $1,193 Premium per customer $403 $414 $424 $433 $440 Insurance Supplement 33
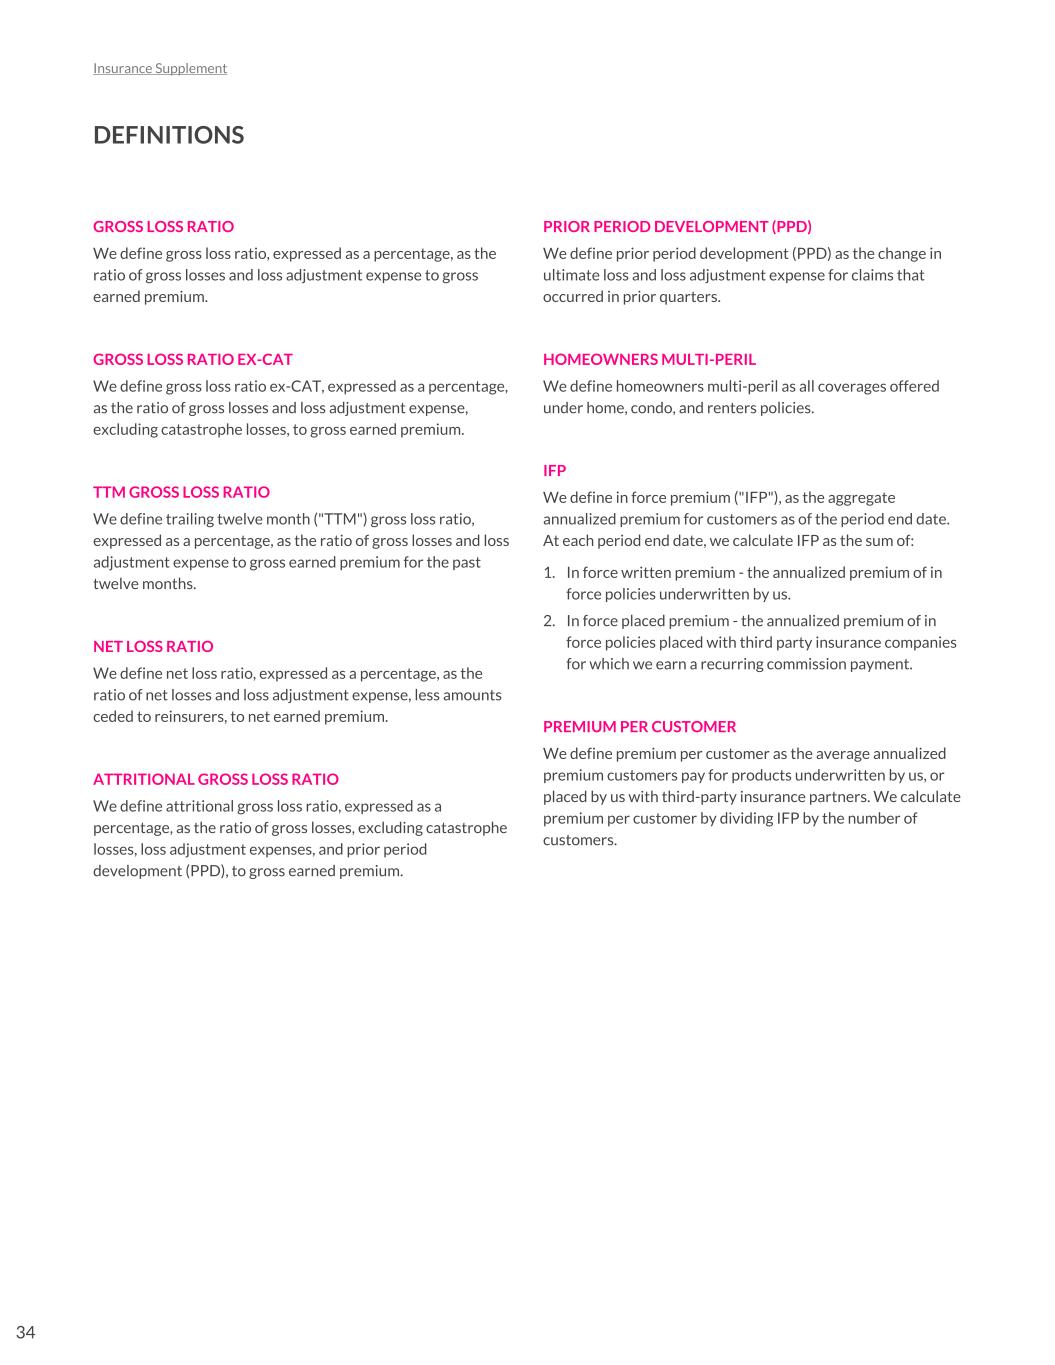
DEFINITIONS GROSS LOSS RATIO We define gross loss ratio, expressed as a percentage, as the ratio of gross losses and loss adjustment expense to gross earned premium. GROSS LOSS RATIO EX-CAT We define gross loss ratio ex-CAT, expressed as a percentage, as the ratio of gross losses and loss adjustment expense, excluding catastrophe losses, to gross earned premium. TTM GROSS LOSS RATIO We define trailing twelve month ("TTM") gross loss ratio, expressed as a percentage, as the ratio of gross losses and loss adjustment expense to gross earned premium for the past twelve months. NET LOSS RATIO We define net loss ratio, expressed as a percentage, as the ratio of net losses and loss adjustment expense, less amounts ceded to reinsurers, to net earned premium. ATTRITIONAL GROSS LOSS RATIO We define attritional gross loss ratio, expressed as a percentage, as the ratio of gross losses, excluding catastrophe losses, loss adjustment expenses, and prior period development (PPD), to gross earned premium. PRIOR PERIOD DEVELOPMENT (PPD) We define prior period development (PPD) as the change in ultimate loss and loss adjustment expense for claims that occurred in prior quarters. HOMEOWNERS MULTI-PERIL We define homeowners multi-peril as all coverages offered under home, condo, and renters policies. IFP We define in force premium ("IFP"), as the aggregate annualized premium for customers as of the period end date. At each period end date, we calculate IFP as the sum of: 1. In force written premium - the annualized premium of in force policies underwritten by us. 2. In force placed premium - the annualized premium of in force policies placed with third party insurance companies for which we earn a recurring commission payment. PREMIUM PER CUSTOMER We define premium per customer as the average annualized premium customers pay for products underwritten by us, or placed by us with third-party insurance partners. We calculate premium per customer by dividing IFP by the number of customers. Insurance Supplement 34