.2
| 1 Q3 2026 Investor Presentation |
| 2 Forward Looking Statements Statements in this press release that are not historical facts are forward-looking statements within the meaning of Section 27A of the Securities Act of 1933, as amended, and Section 21E of the Securities Exchange Act of 1934, as amended, and are intended to be covered by the safe harbor provisions of the Private Securities Litigation Reform Act of 1995. We may also make forward-looking statements in other documents we file with the Securities and Exchange Commission (the “SEC”), in our annual reports to our stockholders, in press releases and other written materials, and in oral statements made by our officers, directors or employees. You can identify forward-looking statements by the use of the words “believe,” “expect,” “anticipate,” “intend,” “estimate,” “assume,” “outlook,” “will,” “should,” and other expressions that predict or indicate future events and trends and which do not relate to historical matters. Although the Company believes that these forward-looking statements are based on reasonable estimates and assumptions, they are not guarantees of future performance and are subject to known and unknown risks, uncertainties, and other factors. You should not place undue reliance on our forward-looking statements. You should exercise caution in interpreting and relying on forward-looking statements because they are subject to significant risks, uncertainties and other factors which are, in some cases, beyond the Company’s control. The Company’s actual results could differ materially from those projected in the forward-looking statements as a result of, among other factors, changes in general business and economic conditions on a national basis and in the local markets in which the Company operates, including changes which adversely affect borrowers’ ability to service and repay loans; changes in customer behavior due to political, business and economic conditions, including inflation and concerns about liquidity; turbulence in the capital and debt markets; reductions in net interest income resulting from interest rate volatility as well as changes in the balances and mix of loans and deposits; changes in interest rates and real estate values; changes in loan collectability and increases in defaults and charge-off rates; decreases in the value of securities and other assets, adequacy of credit loss reserves, or deposit levels necessitating increased borrowing to fund loans and investments; risks related to the Company’s acquisitions generally, including disruption to current plans and operations; difficulties in customer and employee retention; fees, expenses and charges related to these transactions being significantly higher than anticipated; unforeseen integration issues or impairment of other intangibles; and the Company’s inability to achieve expected revenues, cost savings, synergies, and other benefits at levels or within the timeframes originally anticipated; changing government regulation; competitive pressures from other financial institutions; changes in legislation or regulation and accounting principles, policies and guidelines; cybersecurity incidents, fraud, natural disasters, and future pandemics; the risk that the Company may not be successful in the implementation of its business strategy; the risk that intangibles recorded in the Company’s financial statements will become impaired; changes in assumptions used in making such forward-looking statements; and the other risks and uncertainties detailed in the Company’s Form 10-K and updated by our Quarterly Report on Form 10-Q and other filings submitted to the SEC. These statements speak only as of the date of this release and the Company does not undertake any obligation to update or revise any of these forward-looking statements to reflect events or circumstances occurring after the date of this communication or to reflect the occurrence of unanticipated events. 2 |
| 3 NB Bancorp, Inc. Overview |
| 4 Overview of NB Bancorp, Inc. Total Assets $7.7B Total Gross Loans $6.8B Total Deposits $6.5B Total Equity $857M TCE/ TA 10.82%² Tier 1 Leverage Ratio 11.25%¹ Tier 1 Capital Ratio 11.64%¹ Total Capital Ratio 12.42%¹ Q3’26 Operating ROAA 1.26%² Q3’26 Operating ROATCE 11.05%² Q3’26 NIM 3.97% Q3’26 Operating Efficiency Ratio 59.32%² Balance Sheet Profitability Capital 1) Financials reflect regulatory holding company data; estimated prior to filing of call report 2) See Appendix for reconciliation of non-GAAP financial metrics 4 NASDAQCM: NBBK Headquartered: Needham, MA IPO: December 2023; Raised ~$410M in gross proceeds BankProv: Acquisition Closed November 15, 2025 Fourth largest public community bank headquartered in Massachusetts The “Builder’s Bank” with deep community relationships and extensive expertise Full-service bank with an array of commercial banking products for retail and business customers Founded in 1892 to help businesses and customers build their futures |
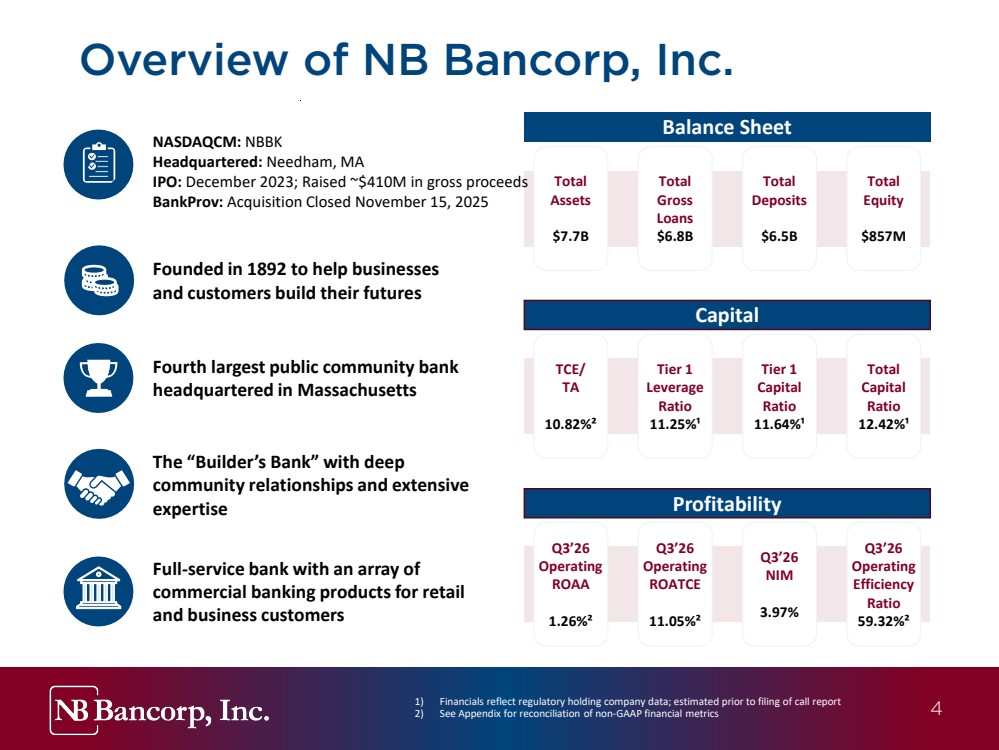
| 5 Performance Post-IPO 1) See Appendix for reconciliation of non-GAAP financial metrics 5 Asset Growth in $M +49.0% Deposits in $M +50.5% YTD Operating EPS1 +484.6% Net Interest Margin +14.1% Operating ROAA1 +46.4% Share Price +12.1% $5,158 $7,684 IPO Q3'26 $4,333 $6,521 IPO Q3'26 $0.26 $1.52 IPO Q3'26 3.48% 3.97% IPO Q3'26 0.86% 1.26% IPO Q3'26 $10.00 $22.12 IPO Q3'26 |
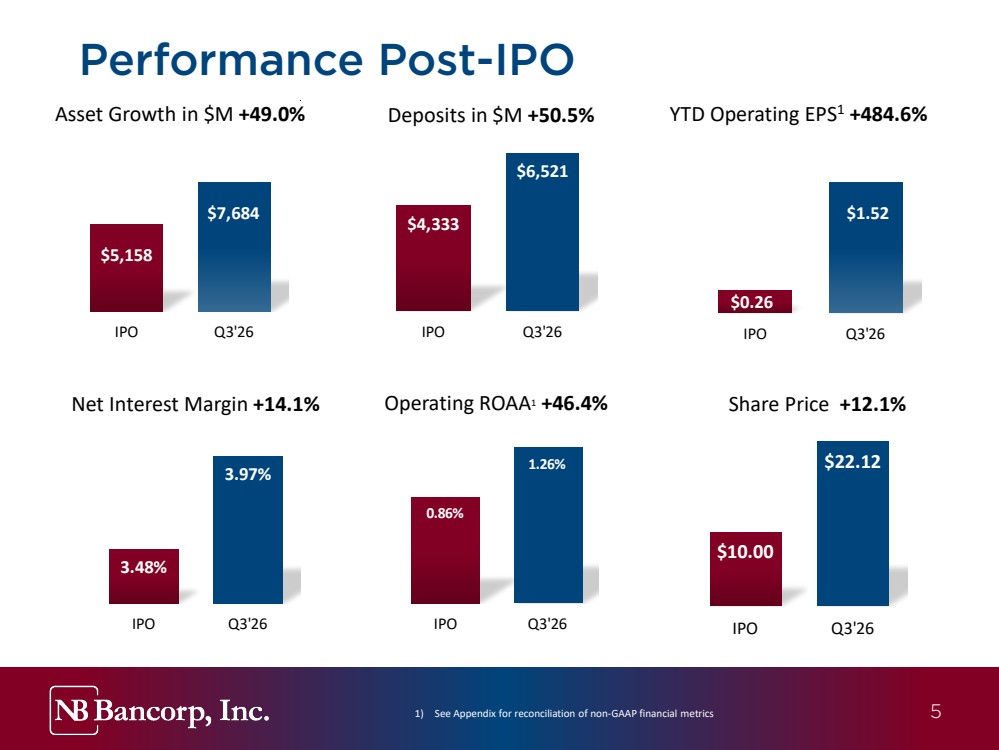
| 6 Our branch network covers the metro-west area of Boston, southern New Hampshire and surrounding communities which are our primary deposit market areas. We consider our primary lending market area to be the Greater Boston metropolitan area and surrounding communities in Massachusetts, eastern Connecticut, southern New Hampshire and Rhode Island. 6 MA NH Springfield Manchester Concord Boston Lowell Plymouth NBBK (21) Keene Gardner Brockton Pittsfield Worcester Gloucester Dover Boston MSA Community Bank Deposit Market Share¹ Total Deps. 2025 2026 in Market Rank Rank Institution ($M) 3 1 NB Bancorp Inc. 6,237 2 2 Salem Five Bancorp 6,045 1 3 Cambridge Financial Group Inc. 5,823 4 4 Middlesex Bancorp MHC 4,695 6 5 Charlesbridge MHC 4,276 5 6 Leader Bancorp Inc. 4,262 7 7 IFS 1820 Bancorp MHC 3,367 9 8 Northern Bancorp Inc. 2,823 8 9 Hometown Financial Group MHC 2,749 10 10 River Run Bancorp MHC 2,247 All Other Market Participants 31,738 Market Total 74,261 1) Excludes banks with total assets greater than $10 billion; FDIC deposit data as of June 30, 2026 Source: S&P Capital IQ Pro 6 Boston-Cambridge-Newton, MA-NH MSA Total Population: 5,065,382 ‘26-’31 Proj. Pop. Change: 2.14% Median HHI: $121,960 Proj. HHI Change: 12.10% Well Positioned in Highly Attractive Markets |
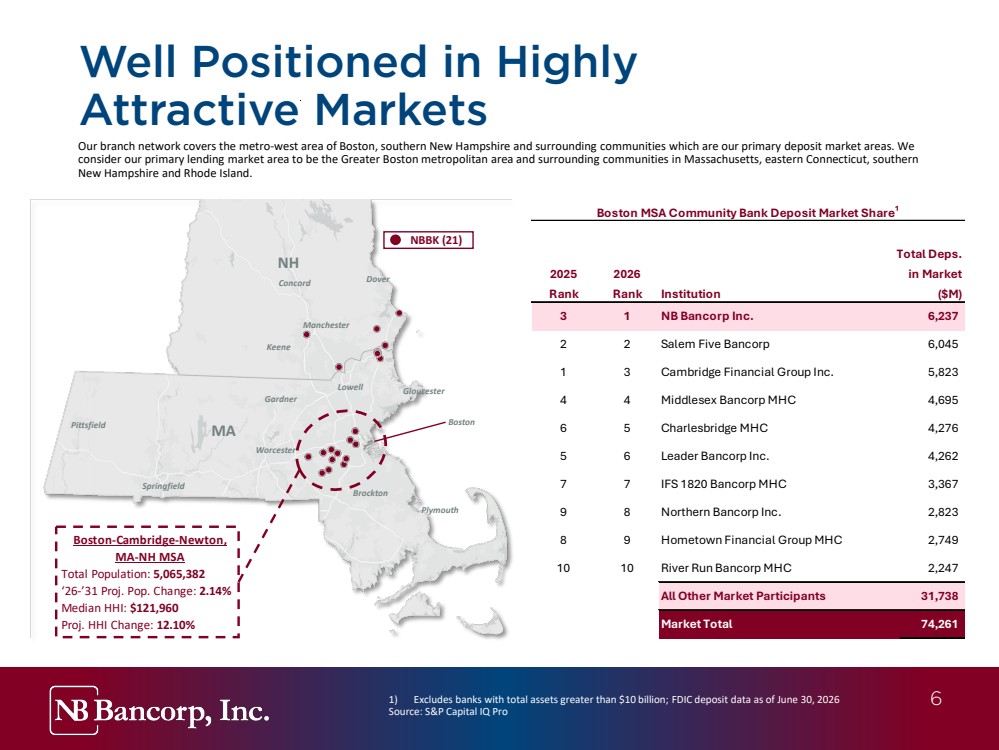
| 7 Strength of Growing Deposit Base Over the two-year period ended June 30, 2026 (latest market data available), each Needham Bank branch experienced growth that matched or exceeded growth in its respective market. In aggregate, Needham Bank achieved growth at over 9 times the overall market growth during this period. 7 Branch June 2024 - June 2026 Deposit Growth June 2024 - June 2026 Market Growth* NB Performance Needham Main Office 16% 5% 348% Ashland 41% 1% 5327% Dedham 30% 7% 445% Dover 17% 4% 442% Medfield** 7% -17% N/A Medford Retail 18% 13% 139% Millis 29% 15% 191% Mission Hill 21% 2% 931% Natick 27% 1% 2127% Wellesley** 14% -11% N/A Westwood 20% 10% 197% All NB Branches (Excludes BP) 20% 2% 962% *Market Grow th Source: S&P Capital IQ **Incalculable as market contracted |
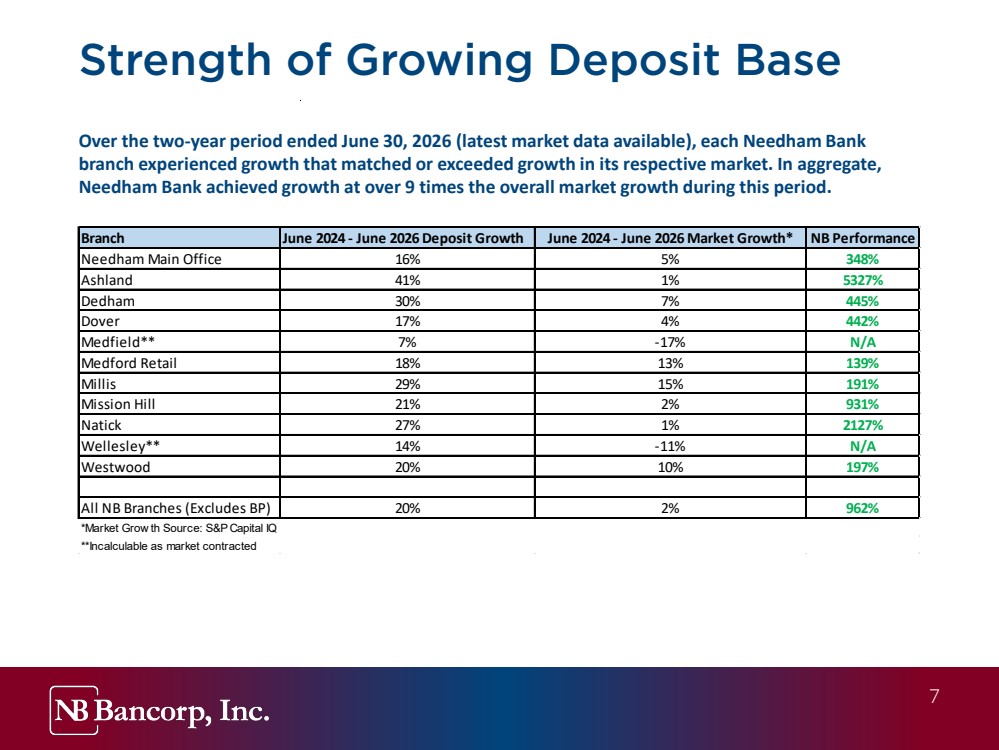
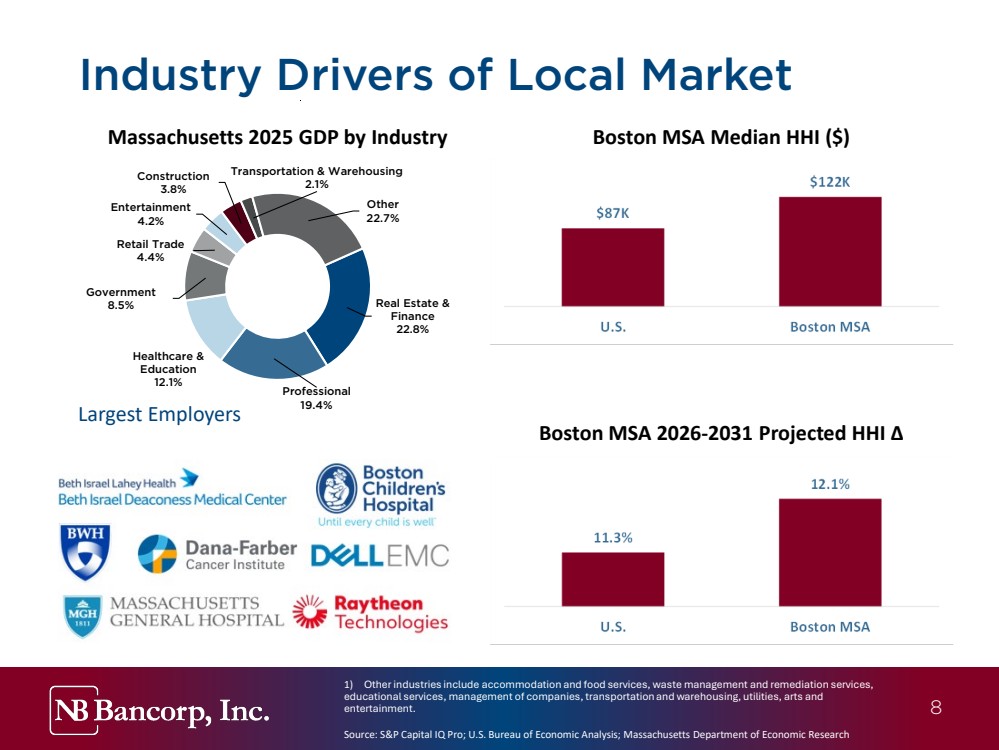
| 8 Largest Employers Boston MSA 2026-2031 Projected HHI Δ Massachusetts 2025 GDP by Industry Boston MSA Median HHI ($) Industry Drivers of Local Market 1) Other industries include accommodation and food services, waste management and remediation services, educational services, management of companies, transportation and warehousing, utilities, arts and entertainment. Source: S&P Capital IQ Pro; U.S. Bureau of Economic Analysis; Massachusetts Department of Economic Research 8 Real Estate & Finance 22.8% Professional 19.4% Healthcare & Education 12.1% Government 8.5% Retail Trade 4.4% Entertainment 4.2% Construction 3.8% Transportation & Warehousing 2.1% Other 22.7% |
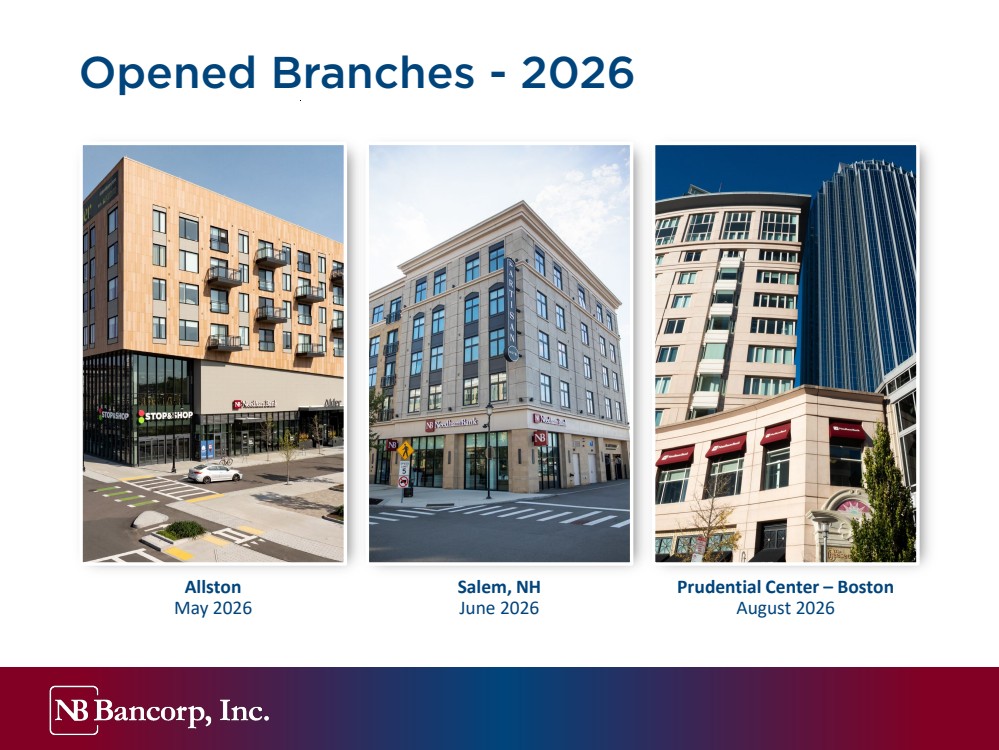
| 9 Allston May 2026 Salem, NH June 2026 Prudential Center – Boston August 2026 Opened Branches - 2026 |
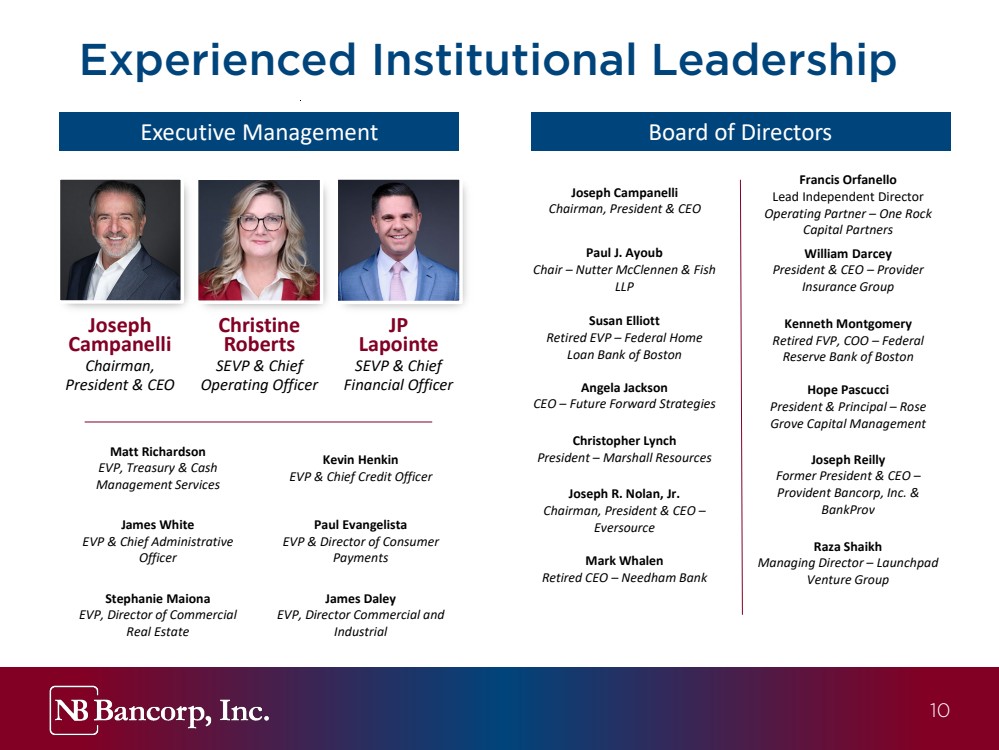
| 10 Experienced Institutional Leadership Joseph Campanelli Chairman, President & CEO William Darcey President & CEO – Provider Insurance Group Paul J. Ayoub Chair – Nutter McClennen & Fish LLP Susan Elliott Retired EVP – Federal Home Loan Bank of Boston Angela Jackson CEO – Future Forward Strategies Christopher Lynch President – Marshall Resources Joseph R. Nolan, Jr. Chairman, President & CEO – Eversource Francis Orfanello Lead Independent Director Operating Partner – One Rock Capital Partners Hope Pascucci President & Principal – Rose Grove Capital Management Raza Shaikh Managing Director – Launchpad Venture Group Mark Whalen Retired CEO – Needham Bank Joseph Campanelli Chairman, President & CEO Christine Roberts SEVP & Chief Operating Officer James White EVP & Chief Administrative Officer Paul Evangelista EVP & Director of Consumer Payments Kevin Henkin EVP & Chief Credit Officer Stephanie Maiona EVP, Director of Commercial Real Estate James Daley EVP, Director Commercial and Industrial Executive Management Board of Directors JP Lapointe SEVP & Chief Financial Officer 10 Kenneth Montgomery Retired FVP, COO – Federal Reserve Bank of Boston Matt Richardson EVP, Treasury & Cash Management Services Joseph Reilly Former President & CEO – Provident Bancorp, Inc. & BankProv |
| 11 Investment Highlights 11 Experienced management team and talent base to grow market share, invest for the future and serve the community Focused on driving franchise value via relationship-based banking and active community involvement History of consistent earnings through various market cycles Excellent credit profile reflective of a diligent and conservative risk management culture Prudent stewards of capital – committed to responsible lending, driving organic growth and investing in the future Strong and stable deposit base with 130+ year history of banking in the communities served Attractive markets of operation to continue generating core loans and deposits |
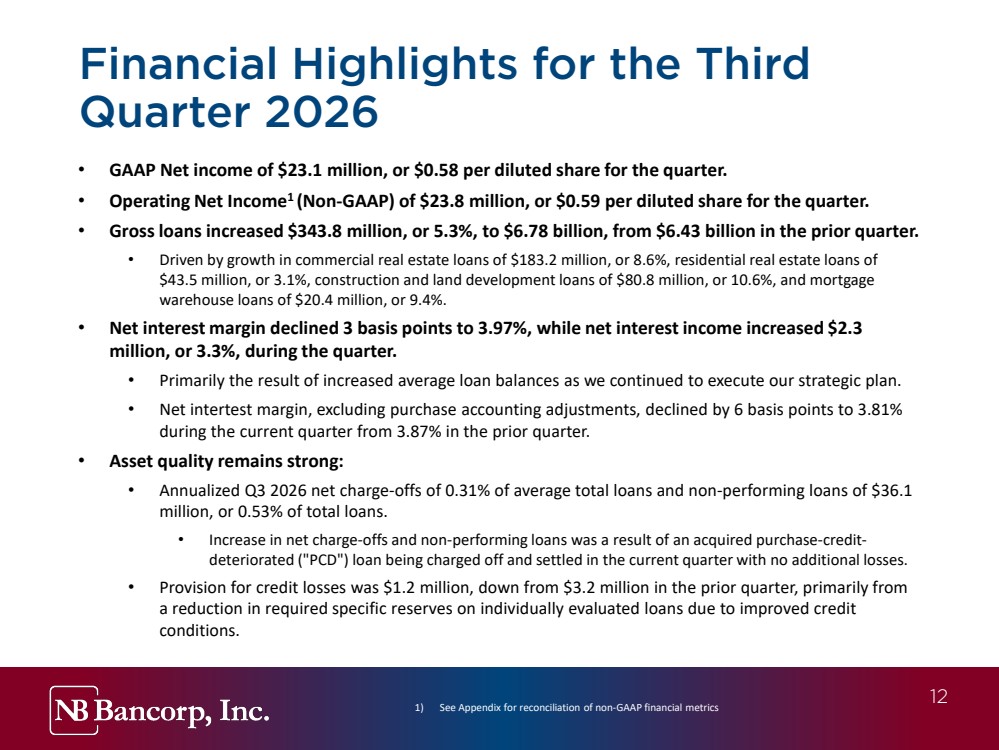
| 12 Financial Highlights for the Third Quarter 2026 • GAAP Net income of $23.1 million, or $0.58 per diluted share for the quarter. • Operating Net Income1 (Non-GAAP) of $23.8 million, or $0.59 per diluted share for the quarter. • Gross loans increased $343.8 million, or 5.3%, to $6.78 billion, from $6.43 billion in the prior quarter. • Driven by growth in commercial real estate loans of $183.2 million, or 8.6%, residential real estate loans of $43.5 million, or 3.1%, construction and land development loans of $80.8 million, or 10.6%, and mortgage warehouse loans of $20.4 million, or 9.4%. • Net interest margin declined 3 basis points to 3.97%, while net interest income increased $2.3 million, or 3.3%, during the quarter. • Primarily the result of increased average loan balances as we continued to execute our strategic plan. • Net intertest margin, excluding purchase accounting adjustments, declined by 6 basis points to 3.81% during the current quarter from 3.87% in the prior quarter. • Asset quality remains strong: • Annualized Q3 2026 net charge-offs of 0.31% of average total loans and non-performing loans of $36.1 million, or 0.53% of total loans. • Increase in net charge-offs and non-performing loans was a result of an acquired purchase-credit-deteriorated ("PCD") loan being charged off and settled in the current quarter with no additional losses. • Provision for credit losses was $1.2 million, down from $3.2 million in the prior quarter, primarily from a reduction in required specific reserves on individually evaluated loans due to improved credit conditions. 1) See Appendix for reconciliation of non-GAAP financial metrics 12 |
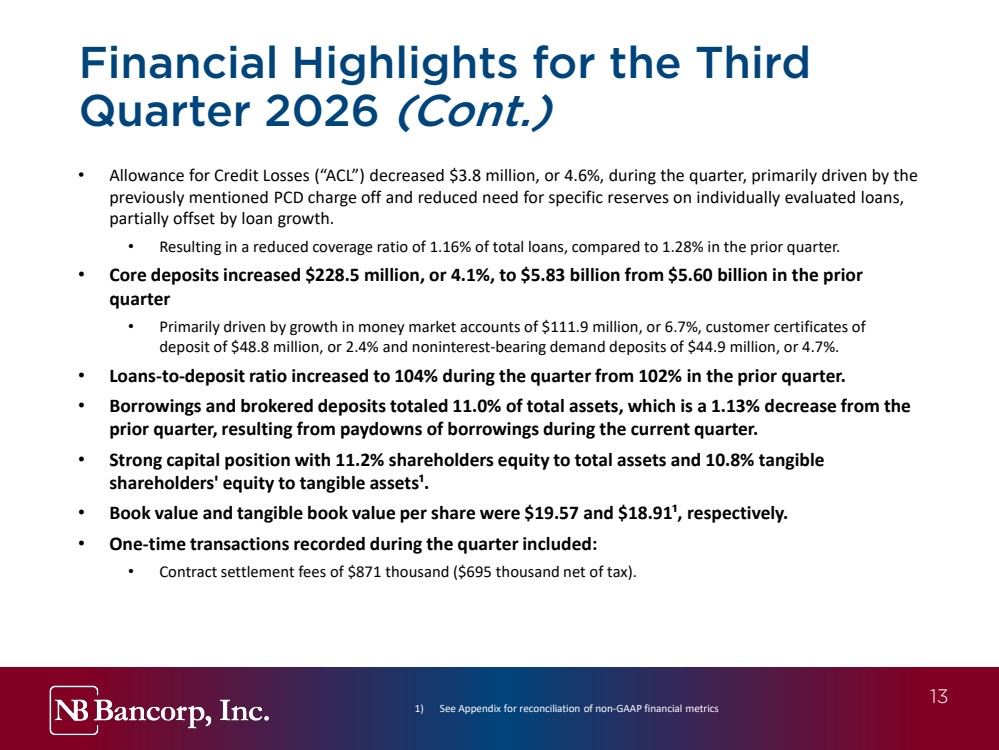
| 13 Financial Highlights for the Third Quarter 2026 (Cont.) • Allowance for Credit Losses (“ACL”) decreased $3.8 million, or 4.6%, during the quarter, primarily driven by the previously mentioned PCD charge off and reduced need for specific reserves on individually evaluated loans, partially offset by loan growth. • Resulting in a reduced coverage ratio of 1.16% of total loans, compared to 1.28% in the prior quarter. • Core deposits increased $228.5 million, or 4.1%, to $5.83 billion from $5.60 billion in the prior quarter • Primarily driven by growth in money market accounts of $111.9 million, or 6.7%, customer certificates of deposit of $48.8 million, or 2.4% and noninterest-bearing demand deposits of $44.9 million, or 4.7%. • Loans-to-deposit ratio increased to 104% during the quarter from 102% in the prior quarter. • Borrowings and brokered deposits totaled 11.0% of total assets, which is a 1.13% decrease from the prior quarter, resulting from paydowns of borrowings during the current quarter. • Strong capital position with 11.2% shareholders equity to total assets and 10.8% tangible shareholders' equity to tangible assets¹. • Book value and tangible book value per share were $19.57 and $18.91¹, respectively. • One-time transactions recorded during the quarter included: • Contract settlement fees of $871 thousand ($695 thousand net of tax). 1) See Appendix for reconciliation of non-GAAP financial metrics 13 |
| 14 Financial Overview |
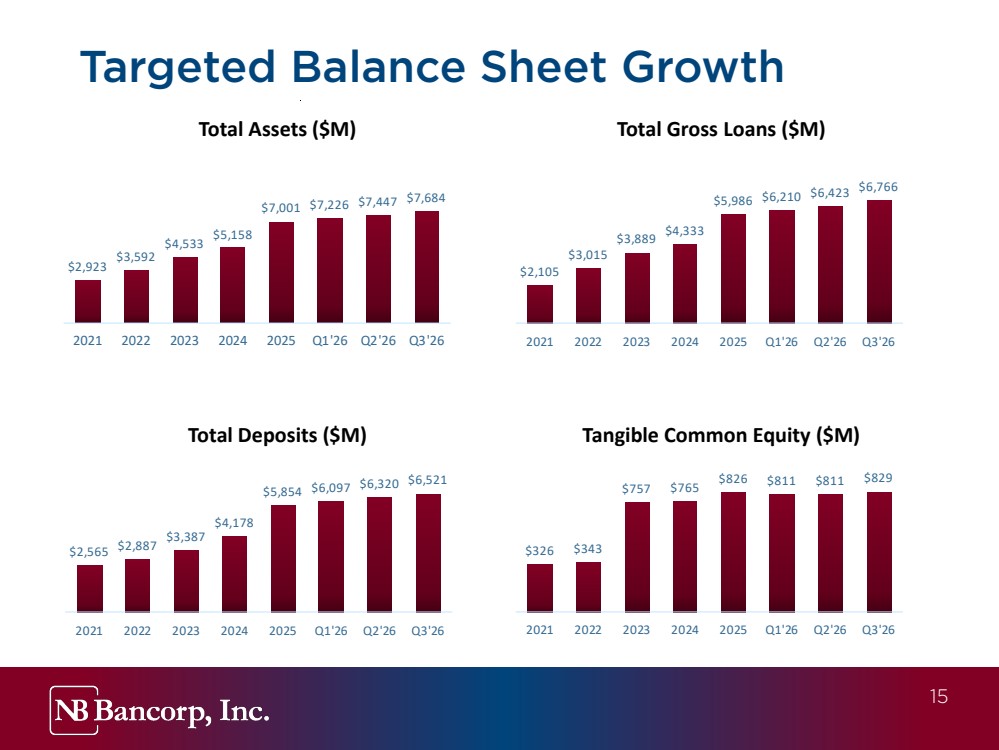
| 15 Total Deposits ($M) Tangible Common Equity ($M) Total Assets ($M) Total Gross Loans ($M) Targeted Balance Sheet Growth 15 $2,923 $3,592 $4,533 $5,158 $7,001 $7,226 $7,447 $7,684 2021 2022 2023 2024 2025 Q1'26 Q2'26 Q3'26 $2,105 $3,015 $3,889 $4,333 $5,986 $6,210 $6,423 $6,766 2021 2022 2023 2024 2025 Q1'26 Q2'26 Q3'26 $2,565 $2,887 $3,387 $4,178 $5,854 $6,097 $6,320 $6,521 2021 2022 2023 2024 2025 Q1'26 Q2'26 Q3'26 $326 $343 $757 $765 $826 $811 $811 $829 2021 2022 2023 2024 2025 Q1'26 Q2'26 Q3'26 |
| 16 Operating Return on Avg. Tangible Common Equity (%)1 Operating Net Income ($M)1, 2 Operating Return on Average Assets (%)¹ Operating Return on Average Equity (%)¹ Track Record of Strong Performance 1) See Appendix for reconciliation of non-GAAP financial metrics 2) Q1, Q2 and Q3 ’26 operating net income reflects annualized totals 16 0.77% 0.96% 0.86% 0.95% 1.21% 0.92% 1.21% 1.26% 2021 2022 2023 2024 2025 Q1'26 Q2'26 Q3'26 6.81% 9.06% 9.40% 6.09% 8.73% 7.43% 10.39% 11.05% 2021 2022 2023 2024 2025 Q1'26 Q2'26 Q3'26 6.81% 9.08% 9.43% 6.10% 8.93% 7.72% 10.79%11.45% 2021 2022 2023 2024 2025 Q1'26 Q2'26 Q3'26 $21.6 $30.1 $34.3 $45.5 $66.2 $64.0 $87.7 $94.5 2021 2022 2023 2024 2025 Q1'26 Q2'26 Q3'26 |
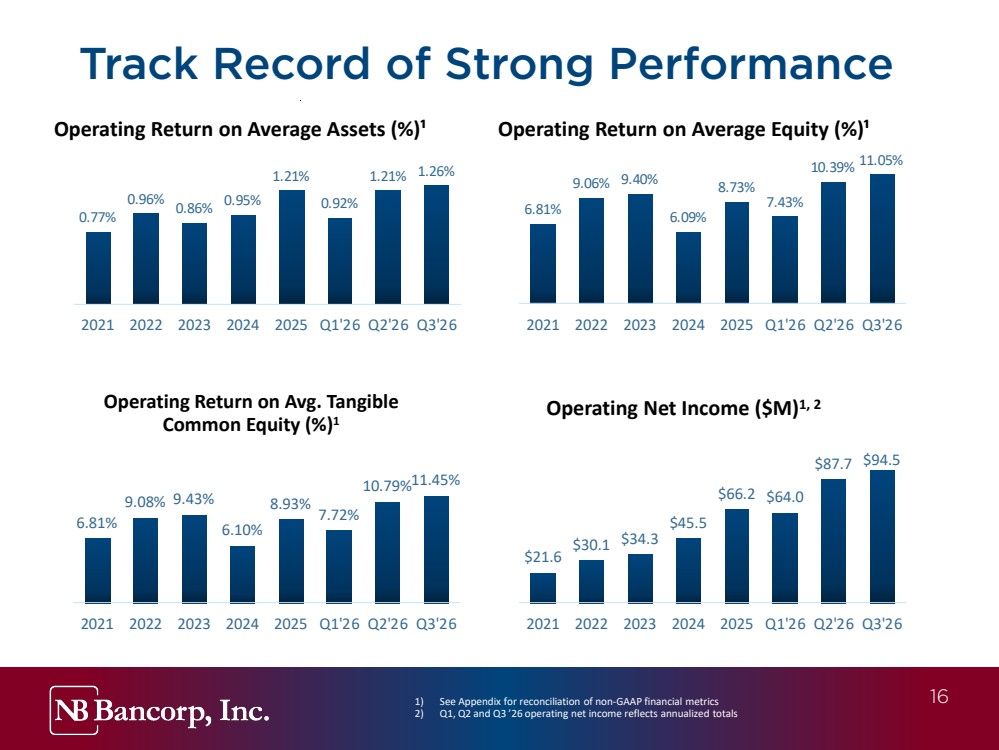
| 17 Operating Noninterest Income / Average Assets (%)¹ Operating Noninterest Expense / Average Assets (%)¹ Net Interest Margin (%) Operating Efficiency Ratio (%)¹ Track Record of Strong Performance (Cont.) 1) See Appendix for reconciliation of non-GAAP financial metrics 17 2.81% 3.49% 3.41% 3.53% 3.79% 3.93% 4.00% 3.97% 2021 2022 2023 2024 2025 Q1'26 Q2'26 Q3'26 65.8% 62.3% 60.0% 58.2% 56.2% 60.1% 57.7% 59.3% 2021 2022 2023 2024 2025 Q1'26 Q2'26 Q3'26 0.27% 0.26% 0.31% 0.28% 0.30% 0.26% 0.31% 0.27% 2021 2022 2023 2024 2025 Q1'26 Q2'26 Q3'26 2.00% 2.28% 2.29% 2.12% 2.20% 2.42% 2.39% 2.41% 2021 2022 2023 2024 2025 Q1'26 Q2'26 Q3'26 |
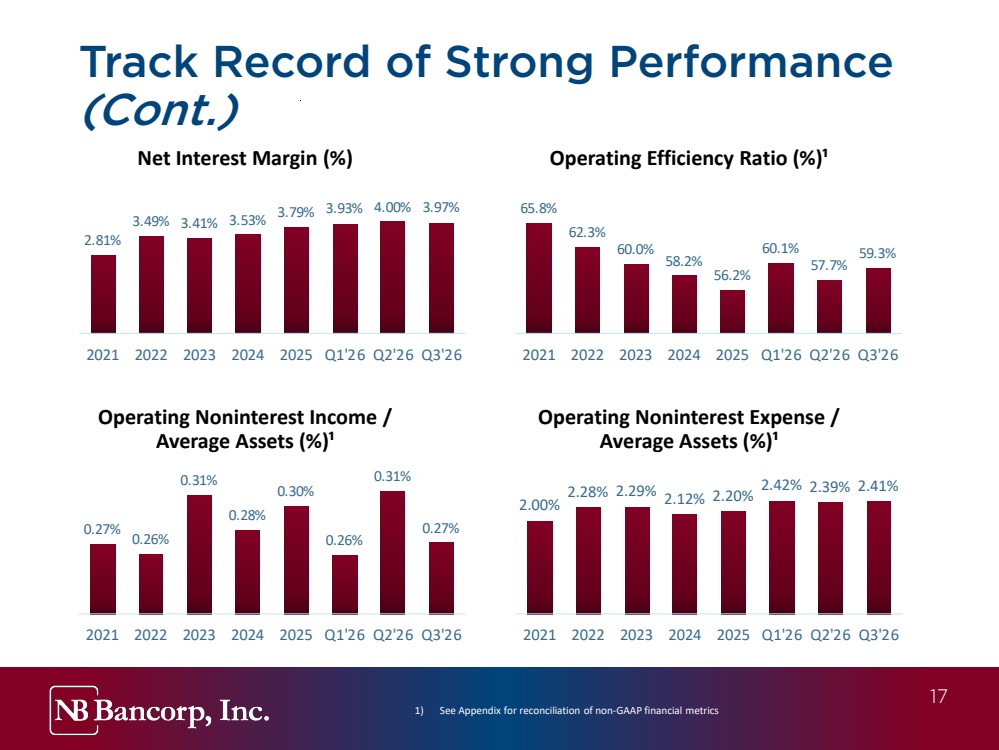
| 18 11.28%¹ 17.41%² 13.59%² 13.00%² 12.76%² 12.42%² 2021 2022 2023 2024 2025 Q1'26 Q2'26 Q3'26 10.54%¹ 16.51%² 12.83%² 12.19%² 11.95%² 11.64%² 2021 2022 2023 2024 2025 Q1'26 Q2'26 Q3'26 Tier 1 Capital Ratio (%) Total Capital Ratio (%) Tangible Common Equity / Tangible Assets (%) Leverage Ratio (%) Capital Ratios 1) Financials reflect indicative bank level call report data 2) Financials reflect indicative regulatory holding company data • Note: “NR” stands for “Not Reported” denoting the Bank’s election into the Community Bank Leverage Ratio framework; See Appendix for reconciliation of non-GAAP financial metrics NR NR NR NR 18 11.16%² 9.54%² 16.70%² 14.82%² 11.85%² 11.27%² 10.94%² 10.82%² 2021 2022 2023 2024 2025 Q1'26 Q2'26 Q3'26 11.23%¹ 10.49%¹ 17.71%² 15.29%² 13.28%² 11.68%² 11.26%² 11.25%² 2021 2022 2023 2024 2025 Q1'26 Q2'26 Q3'26 |
| 19 Loan Portfolio & Asset Quality |
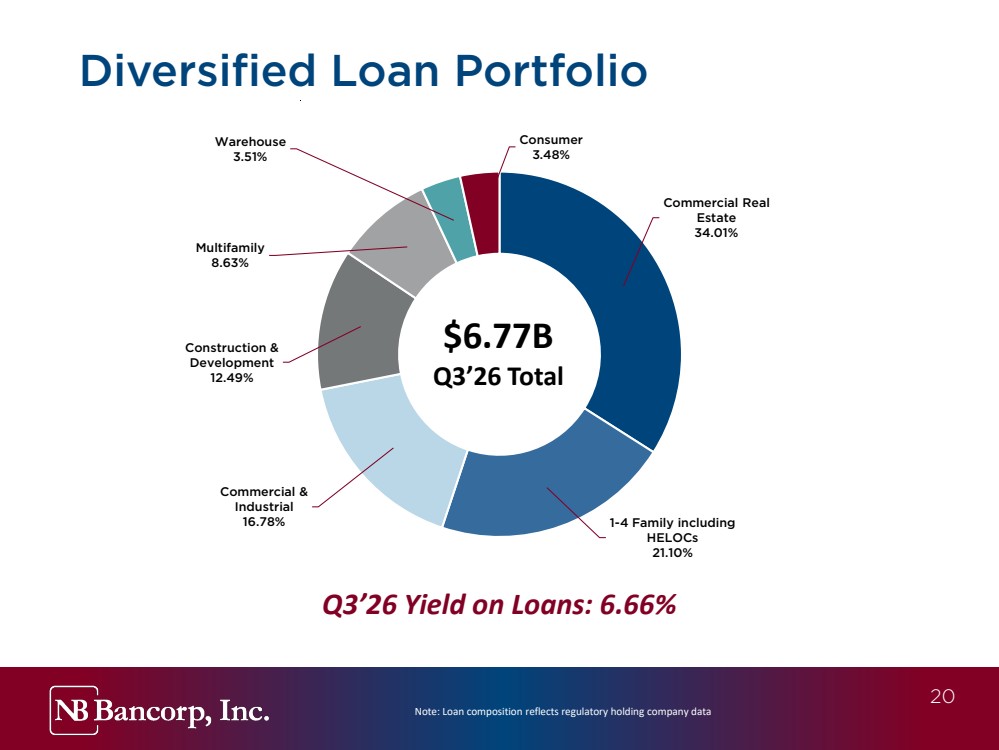
| 20 Commercial Real Estate 34.01% 1-4 Family including HELOCs 21.10% Commercial & Industrial 16.78% Construction & Development 12.49% Multifamily 8.63% Warehouse 3.51% Consumer 3.48% Note: Loan composition reflects regulatory holding company data Diversified Loan Portfolio Q3’26 Yield on Loans: 6.66% $6.77B Q3’26 Total 20 |
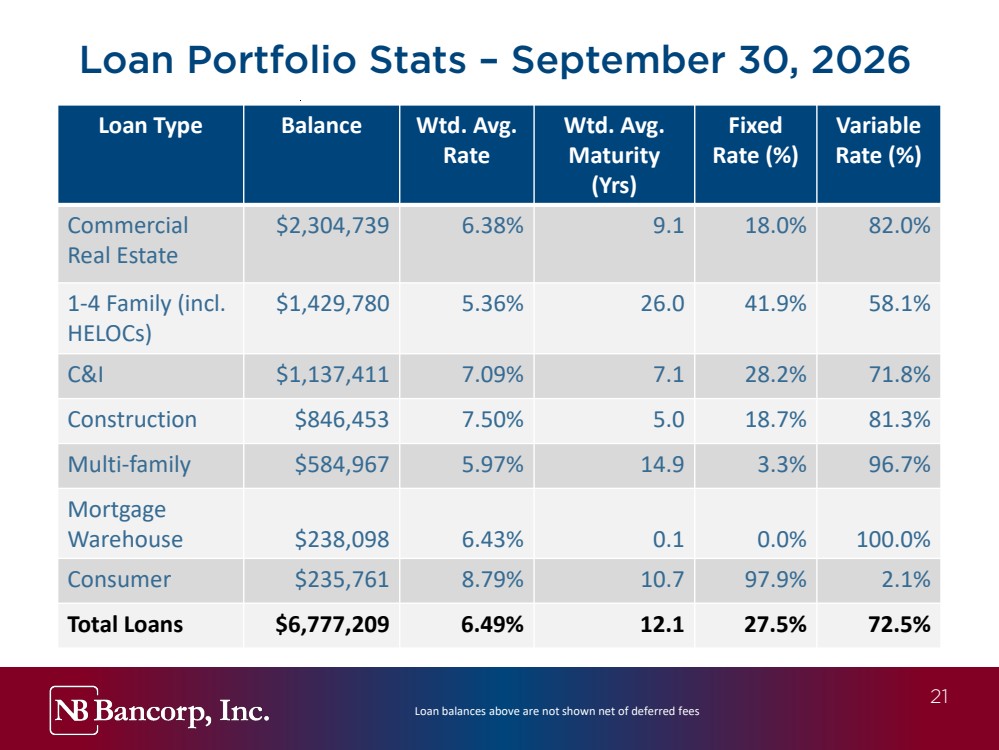
| 21 Loan balances above are not shown net of deferred fees Loan Portfolio Stats – September 30, 2026 Loan Type Balance Wtd. Avg. Rate Wtd. Avg. Maturity (Yrs) Fixed Rate (%) Variable Rate (%) Commercial Real Estate $2,304,739 6.38% 9.1 18.0% 82.0% 1-4 Family (incl. HELOCs) $1,429,780 5.36% 26.0 41.9% 58.1% C&I $1,137,411 7.09% 7.1 28.2% 71.8% Construction $846,453 7.50% 5.0 18.7% 81.3% Multi-family $584,967 5.97% 14.9 3.3% 96.7% Mortgage Warehouse $238,098 6.43% 0.1 0.0% 100.0% Consumer $235,761 8.79% 10.7 97.9% 2.1% Total Loans $6,777,209 6.49% 12.1 27.5% 72.5% 21 |
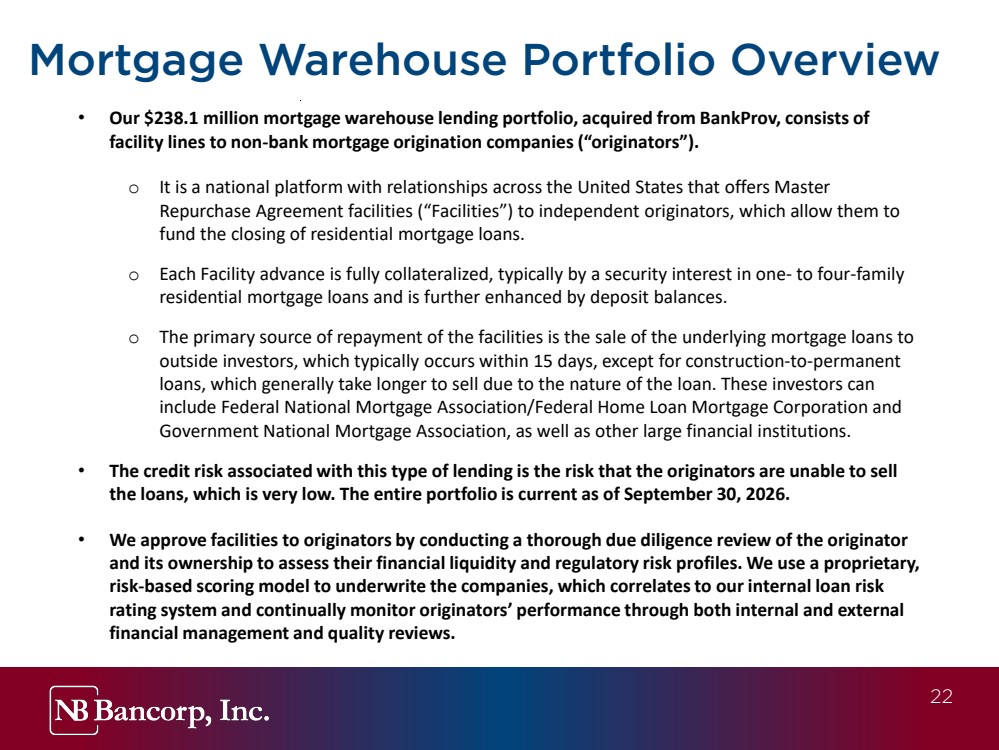
| 22 Mortgage Warehouse Portfolio Overview • Our $238.1 million mortgage warehouse lending portfolio, acquired from BankProv, consists of facility lines to non-bank mortgage origination companies (“originators”). o It is a national platform with relationships across the United States that offers Master Repurchase Agreement facilities (“Facilities”) to independent originators, which allow them to fund the closing of residential mortgage loans. o Each Facility advance is fully collateralized, typically by a security interest in one- to four-family residential mortgage loans and is further enhanced by deposit balances. o The primary source of repayment of the facilities is the sale of the underlying mortgage loans to outside investors, which typically occurs within 15 days, except for construction-to-permanent loans, which generally take longer to sell due to the nature of the loan. These investors can include Federal National Mortgage Association/Federal Home Loan Mortgage Corporation and Government National Mortgage Association, as well as other large financial institutions. • The credit risk associated with this type of lending is the risk that the originators are unable to sell the loans, which is very low. The entire portfolio is current as of September 30, 2026. • We approve facilities to originators by conducting a thorough due diligence review of the originator and its ownership to assess their financial liquidity and regulatory risk profiles. We use a proprietary, risk-based scoring model to underwrite the companies, which correlates to our internal loan risk rating system and continually monitor originators’ performance through both internal and external financial management and quality reviews. 22 |
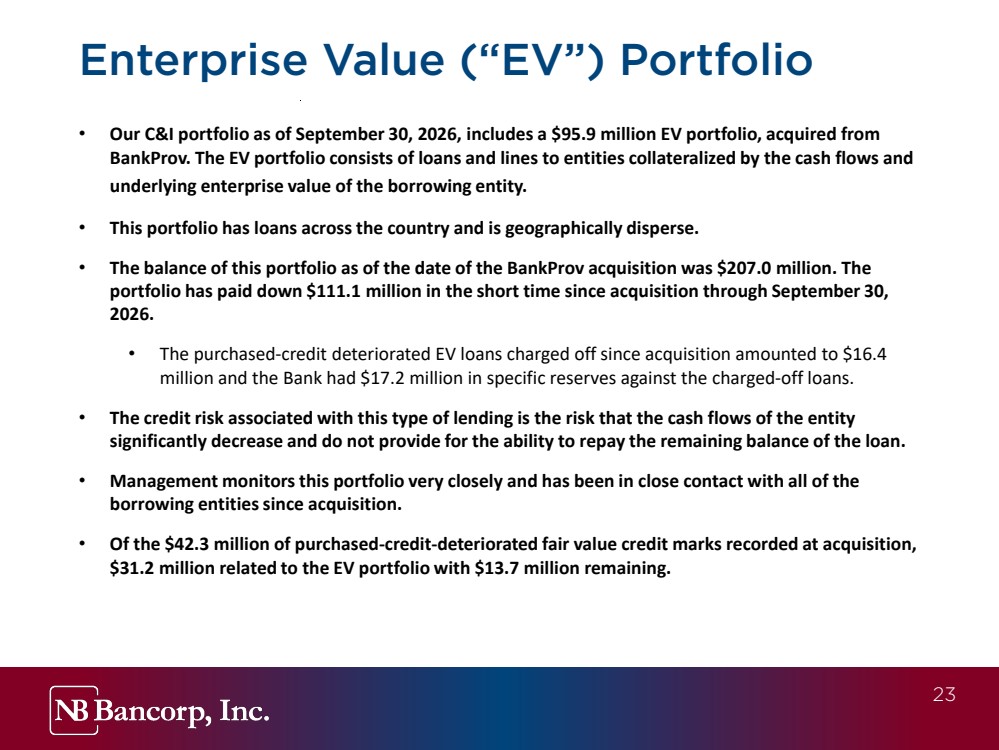
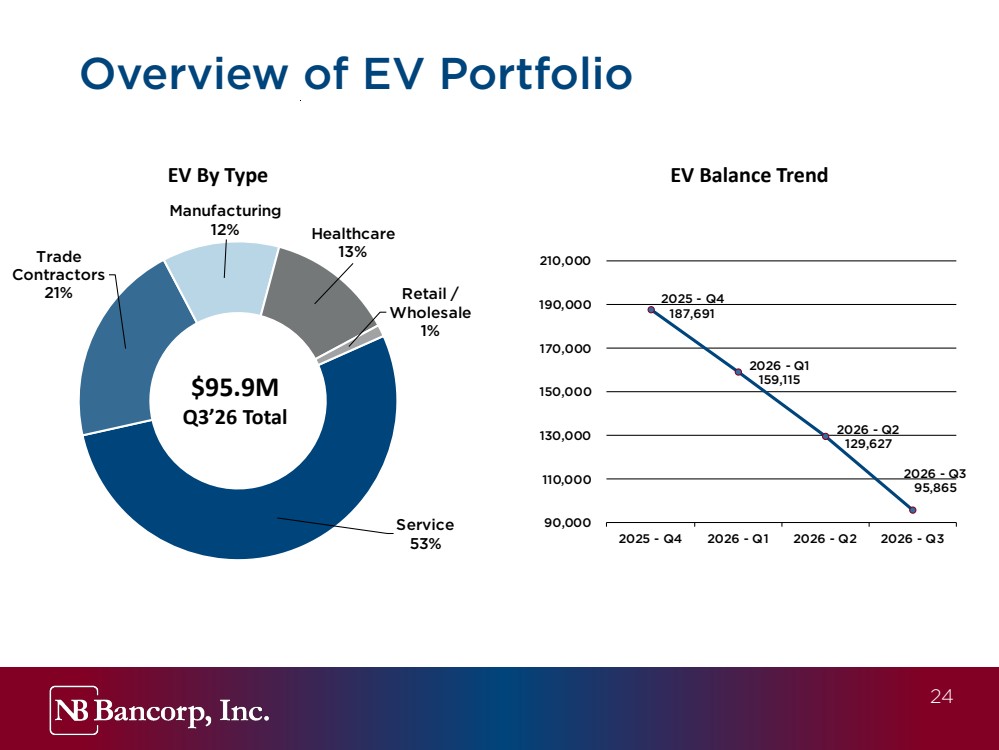
| 23 Enterprise Value (“EV”) Portfolio • Our C&I portfolio as of September 30, 2026, includes a $95.9 million EV portfolio, acquired from BankProv. The EV portfolio consists of loans and lines to entities collateralized by the cash flows and underlying enterprise value of the borrowing entity. • This portfolio has loans across the country and is geographically disperse. • The balance of this portfolio as of the date of the BankProv acquisition was $207.0 million. The portfolio has paid down $111.1 million in the short time since acquisition through September 30, 2026. • The purchased-credit deteriorated EV loans charged off since acquisition amounted to $16.4 million and the Bank had $17.2 million in specific reserves against the charged-off loans. • The credit risk associated with this type of lending is the risk that the cash flows of the entity significantly decrease and do not provide for the ability to repay the remaining balance of the loan. • Management monitors this portfolio very closely and has been in close contact with all of the borrowing entities since acquisition. • Of the $42.3 million of purchased-credit-deteriorated fair value credit marks recorded at acquisition, $31.2 million related to the EV portfolio with $13.7 million remaining. 23 |
| 24 Service 53% Trade Contractors 21% Manufacturing 12% Healthcare 13% Retail / Wholesale 1% EV By Type Overview of EV Portfolio $95.9M Q3’26 Total 24 EV Balance Trend 2025 - Q4 187,691 2026 - Q1 159,115 2026 - Q2 129,627 2026 - Q3 95,865 90,000 110,000 130,000 150,000 170,000 190,000 210,000 2025 - Q4 2026 - Q1 2026 - Q2 2026 - Q3 |
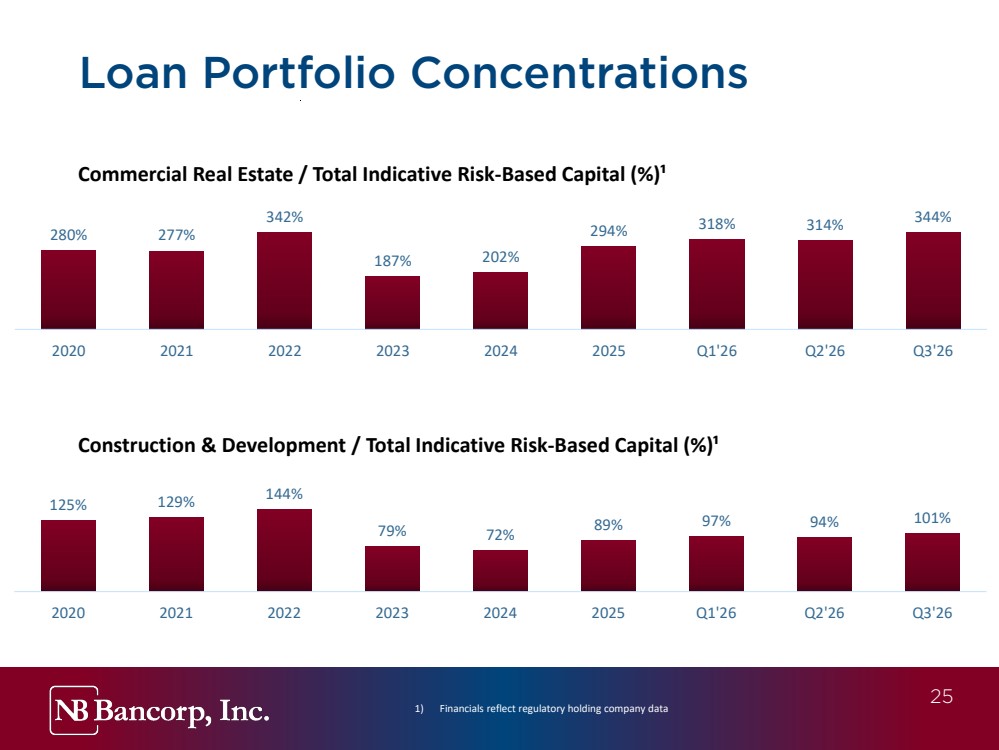
| 25 Construction & Development / Total Indicative Risk-Based Capital (%)¹ Commercial Real Estate / Total Indicative Risk-Based Capital (%)¹ Loan Portfolio Concentrations 1) Financials reflect regulatory holding company data 25 280% 277% 342% 187% 202% 294% 318% 314% 344% 2020 2021 2022 2023 2024 2025 Q1'26 Q2'26 Q3'26 125% 129% 144% 79% 72% 89% 97% 94% 101% 2020 2021 2022 2023 2024 2025 Q1'26 Q2'26 Q3'26 |
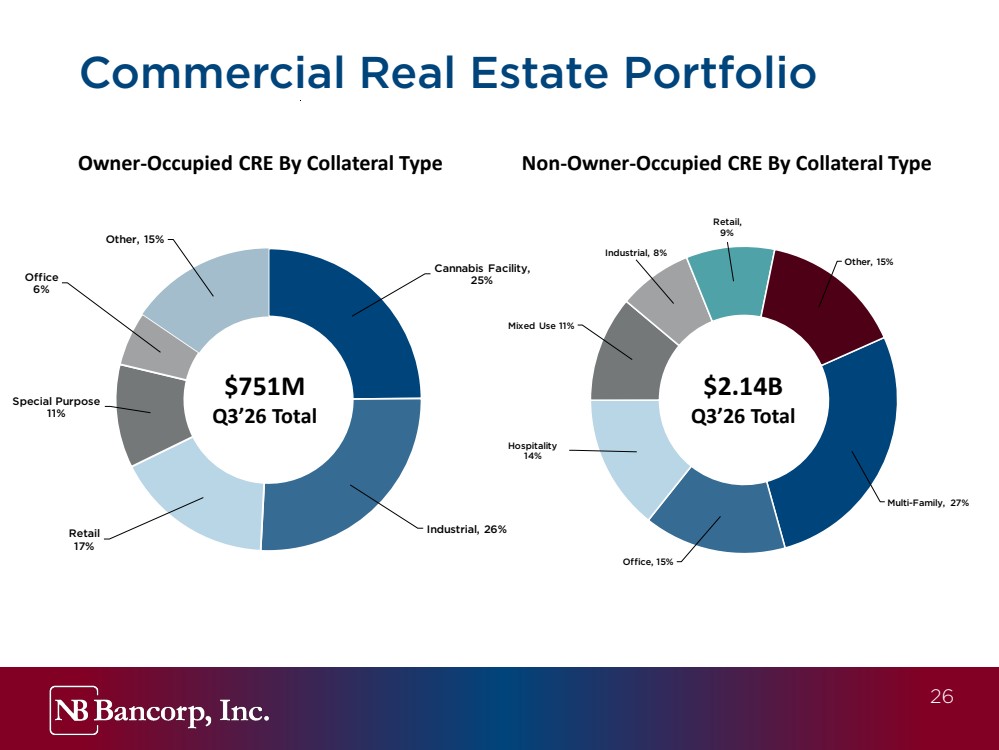
| 26 Multi-Family, 27% Office, 15% Hospitality 14% Mixed Use 11% Industrial, 8% Retail, 9% Other, 15% Cannabis Facility, 25% Retail Industrial, 26% 17% Special Purpose 11% Office 6% Other, 15% Owner-Occupied CRE By Collateral Type Non-Owner-Occupied CRE By Collateral Type Commercial Real Estate Portfolio $751M Q3’26 Total $2.14B Q3’26 Total 26 |
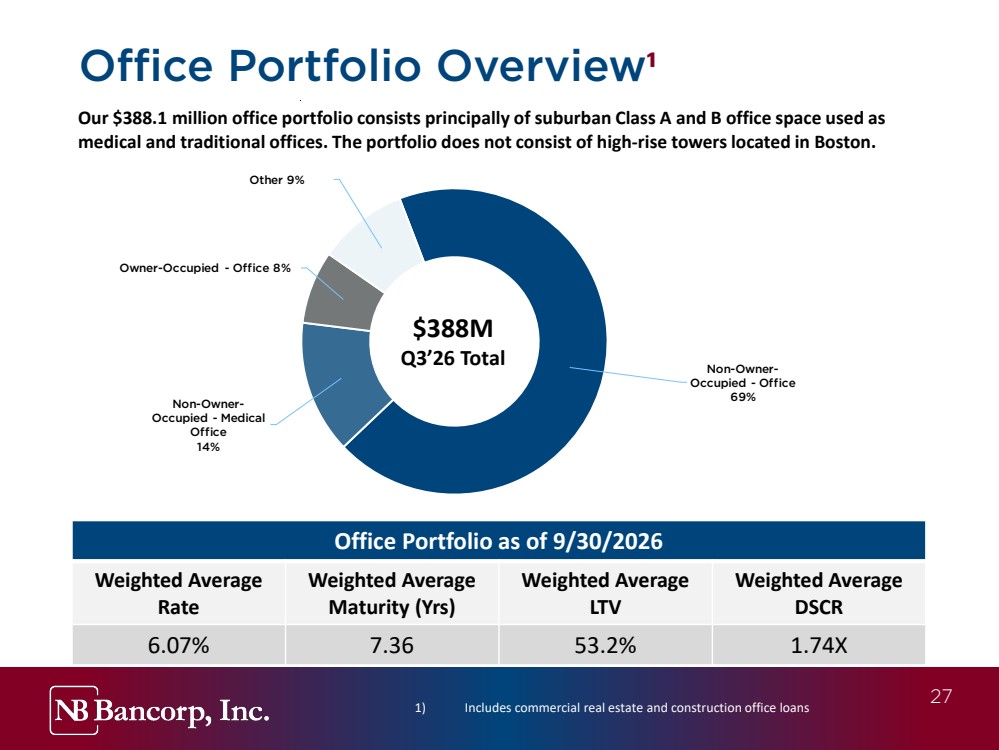
| 27 Non-Owner-Occupied - Office 69% Non-Owner-Occupied - Medical Office 14% Owner-Occupied - Office 8% Other 9% 1) Includes commercial real estate and construction office loans Office Portfolio Overview¹ Our $388.1 million office portfolio consists principally of suburban Class A and B office space used as medical and traditional offices. The portfolio does not consist of high-rise towers located in Boston. $388M Q3’26 Total 27 Office Portfolio as of 9/30/2026 Weighted Average Rate Weighted Average Maturity (Yrs) Weighted Average LTV Weighted Average DSCR 6.07% 7.36 53.2% 1.74X |
| 28 Chicago, IL 15% Boston 8% Newport Beach, CA 8% New York, NY 6% Other 63% Structured Finance 26% Middle Market 17% Renewable Energy 16% Cannabis 14% Cannabis Bridge Financing 11% Bridge Financing 6% Small Business / Other 11% C&I By Type C&I By Geography Overview of C&I Portfolio $1.14B Q3’26 Total $1.14B Q3’26 Total 28 |
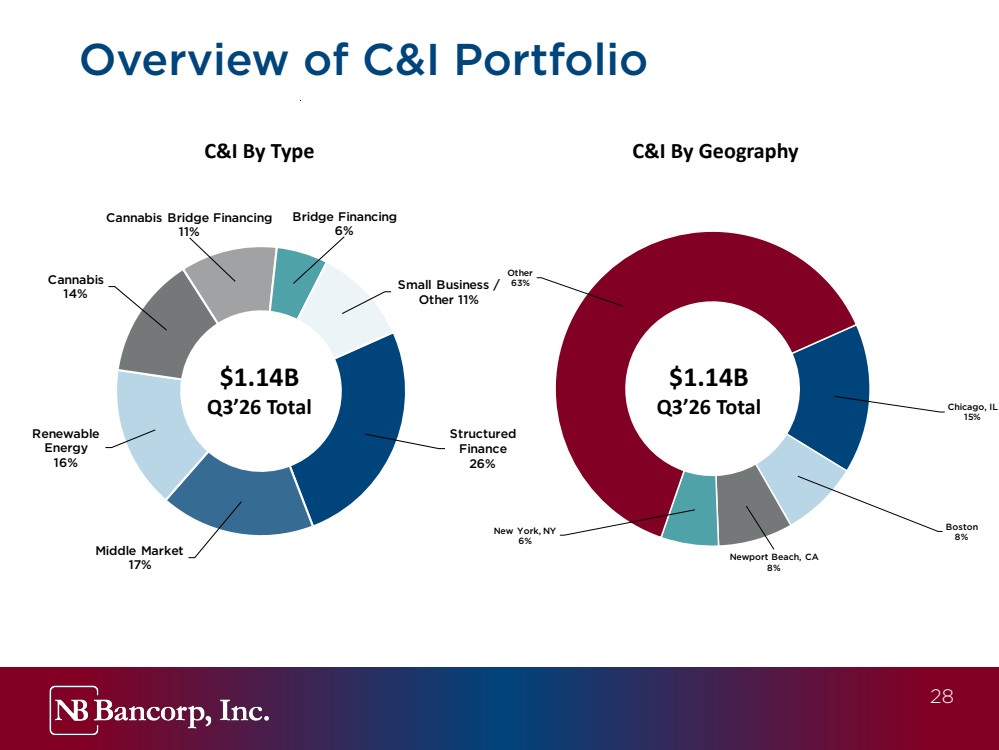
| 29 Boston, MA 19% Weston, MA 8% Milton, MA 7% Salem, NH 5% Needham, MA 5% Cambridge, MA 5% Other 50% Condos 27% Land 16% Multi-Family 12% Single Family 10% Hotel/Motel 7% Other 28% Construction By Type Construction By Geography Overview of Construction Lending $846M Q3’26 Total $846M Q3’26 Total 29 |
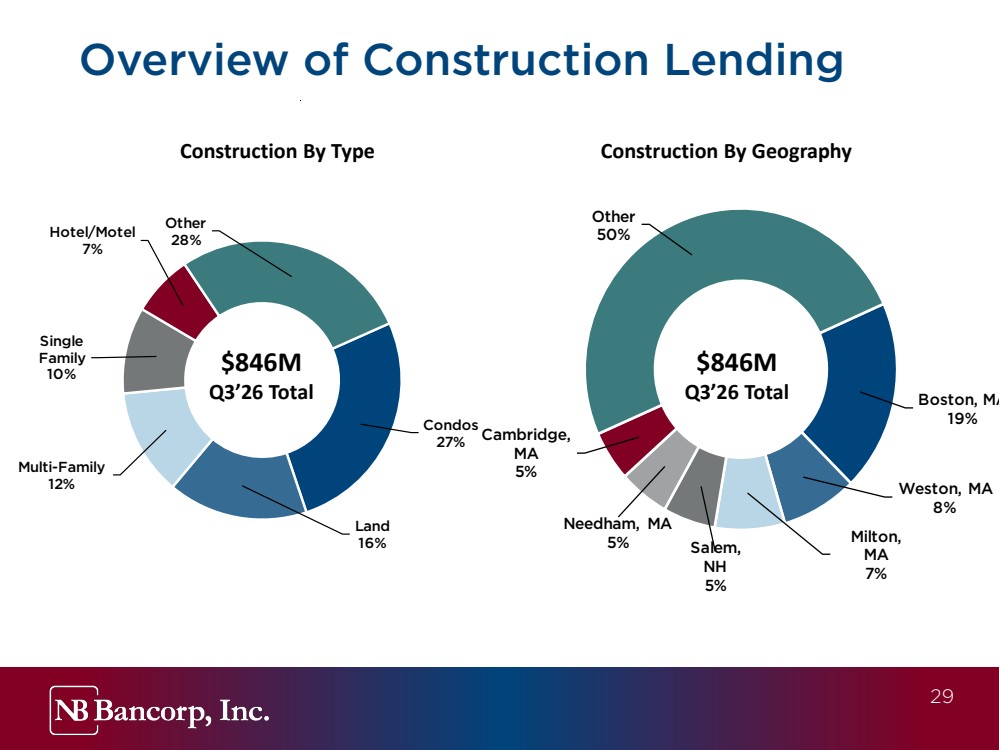
| 30 Consumer Loans Overview • Amounts above exclude purchased premiums or discounts 30 Loan Type Q3 2025 Q4 2025 Q1 2026 Q2 2026 Q3 2026 Purchased: Solar $ 45,678 $ 44,410 $ 43,080 $ 41,150 $ 39,398 Loans Held for Sale - Boat Loans - 63,447 63,971 59,927 55,906 Boat Loans 42,487 238 - - - Home Improvement 37,753 35,832 34,084 32,426 30,480 Student Loans 5,768 5,455 5,029 4,702 4,436 Total Purchased Balance (incl. LHFS) $ 131,686 $ 149,382 $ 146,164 $ 138,205 $ 130,220 Originated: Auto Loans $ 68,307 $ 75,560 $ 82,167 $ 88,735 $ 94,422 Boat Loans 57,570 35,967 41,228 51,653 57,130 Other 5,696 6,035 5,773 6,537 8,186 Total Originated Balance $ 131,573 $ 117,562 $ 129,168 $ 146,925 $ 159,738 Net Charge Offs - Purchased (3ME) $458 $1,130 $385 $1,965 $1,141 Net Charge Offs - Originated (3ME) $144 $8 $636 $20 $2 |
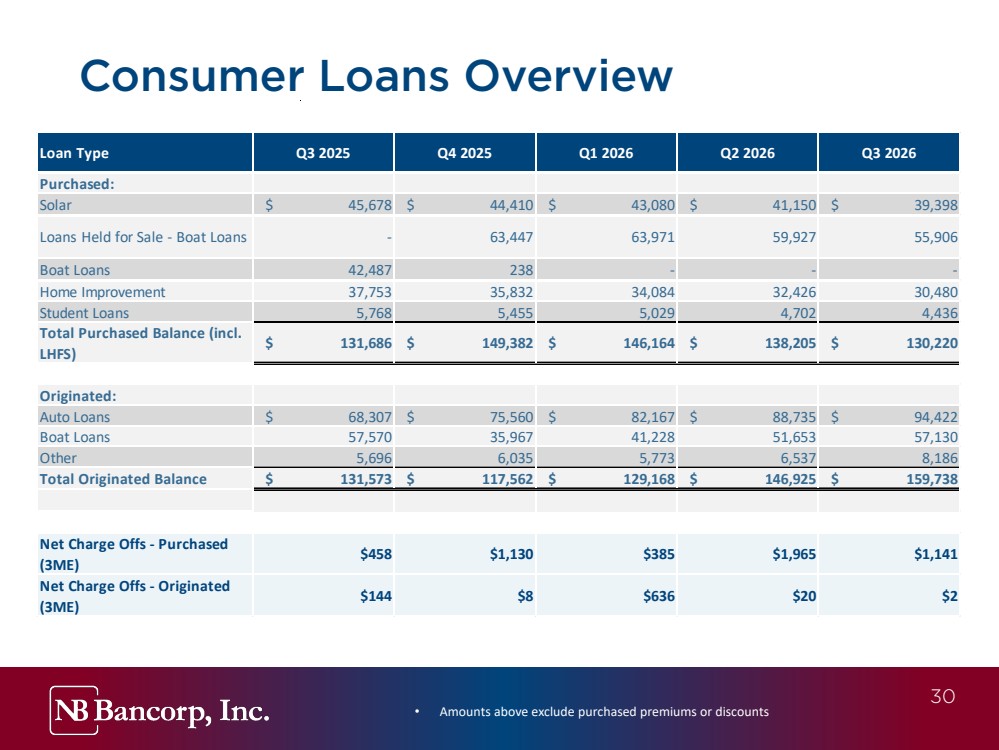
| 31 Consumer Loans Trends 31 $0 $500 $1,000 $1,500 $2,000 $2,500 $3,000 $- $20,000 $40,000 $60,000 $80,000 $100,000 $120,000 $140,000 $160,000 $180,000 Q3 2025 Q4 2025 Q1 2026 Q2 2026 Q3 2026 Balance (thousands) Period Overview of Purchased Consumer Loans Net Charge Offs - Purchased (3ME) Net Charge Offs - Originated (3ME) Total Purchased Balance (incl. LHFS) Total Originated Balance |
| 32 Cannabis Business Highlights • As of September 30, 2026, we had outstanding loan balances of $576.3 million to cannabis businesses: • $401.3 million was direct to cannabis entities; • $175.0 million was indirect to cannabis entities; • Weighted average LTV and DSCR was 46.8% and 3.22, respectively; and, • 74.37% of the total outstanding loans were collateralized by real estate, including 100% of the direct cannabis loans • As of September 30, 2026, the Company had $575.1 million in cannabis deposits • $427.5 million in cannabis-direct and $147.6 million in cannabis-indirect Cannabis Business Loans ($M) Cannabis Business Deposits ($M) 32 61.8% 56.5% 68.8% 69.0% 69.6% 38.2% 43.5% 31.2% 31.0% 30.4% 09/2025 12/2025 03/2026 06/2026 09/2026 Cannabis Direct Cannabis Indirect $408.9M $466.8M $455.6M $522.1M $575.1M 09/2025 12/2025 03/2026 06/2026 09/2026 |
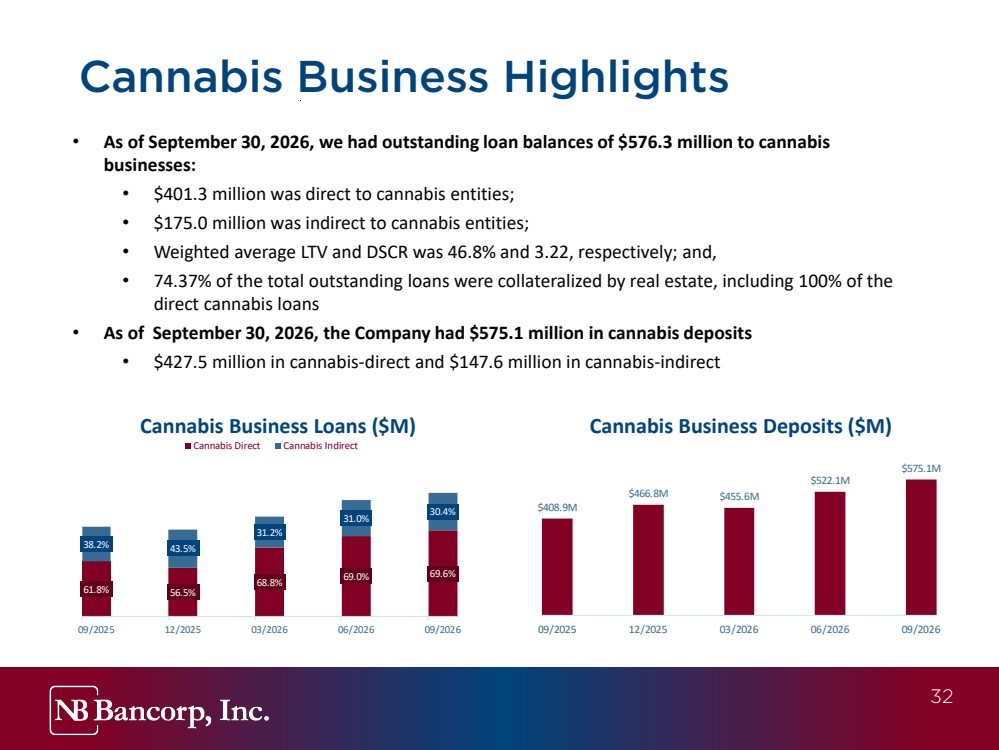
| 33 $6.0 $13.0 $10.8 $13.9 $7.5 $15.3 $13.2 $12.8 $35.9 $30.3 $14.5 $23.3 $4.5 $8.3 $0.0 2021 2022 2023 2024 2025 Q1'26 Q2'26 Q3'26 NBBK Nonaccruals ($M) BankProv Nonaccruals ($M) TDRs ($M) OREO ($M) 0.87% 0.83% 0.83% 0.89% 1.46% 1.29% 1.28% 1.16% 175% 117% 298% 280% 201% 176% 297% 217% 0.0% 100.0% 200.0% 300.0% 400.0% 0.50% 1.00% 1.50% 2.00% 2021 2022 2023 2024 2025 Q1'26 Q2'26 Q3'26 Reserves / Loans Reserves / NPLs Reserves / Loans (%) & Reserves / NPLs (%) NPA Trends Asset Quality 1) Financials reflect bank level call report data 2) Financials reflect regulatory holding company data NPAs / Assets 0.36%¹ 0.56%¹ 0.24%¹ 0.27%² 33 0.62%² 0.63%² 0.37%² 0.48%² |
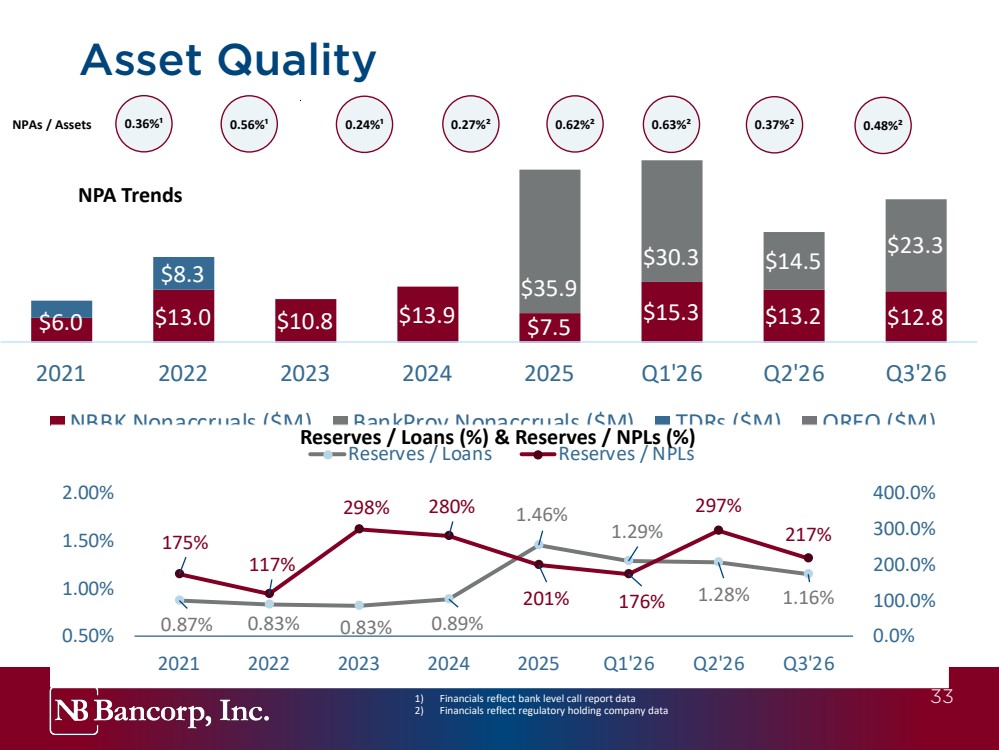
| 34 1) Reflects annualized metrics • Note: Values may not sum due to rounding Historically Strong Credit Culture NCOs / Average Loans (%)¹ • Our loan portfolio consists primarily of commercial real estate and multifamily loans, one-to four-family residential real estate loans, construction and land development loans, commercial and industrial loans, mortgage warehouse loans and consumer loans. These loans are primarily made to individuals and businesses located in our primary lending market area, which is the Greater Boston metropolitan area and surrounding communities in Massachusetts, Eastern Connecticut, Southern New Hampshire and Rhode Island. • For the quarter ended September 30, 2026, the Company’s NCOs / Average Loans were primarily composed of a $4.0 million charge off on an acquired purchased-credit-deteriorated C&I loan and charge offs on purchased consumer loans. 34 0.16 0.00 0.10 0.22 0.18 0.91 0.07 0.3 %) % % % 2021 2022 2023 2024 2025 Q1'26 Q2'26 Q3'26 |
| 35 Funding & Liquidity Management |
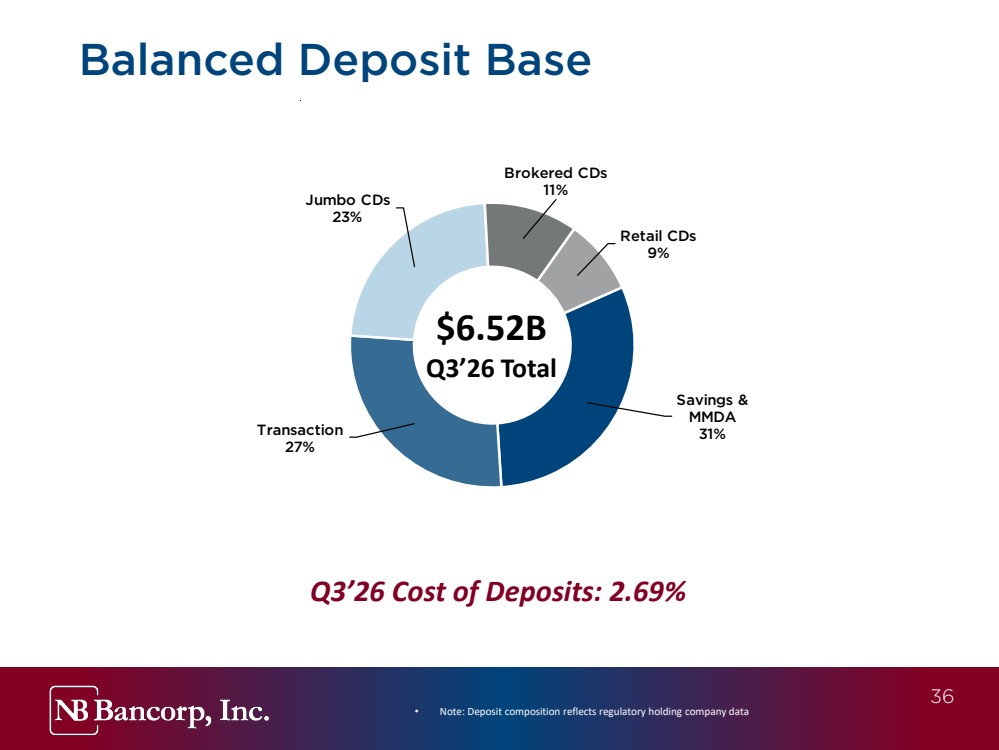
| 36 Savings & MMDA Transaction 31% 27% Jumbo CDs 23% Brokered CDs 11% Retail CDs 9% • Note: Deposit composition reflects regulatory holding company data Balanced Deposit Base Q3’26 Cost of Deposits: 2.69% $6.52B Q3’26 Total 36 |
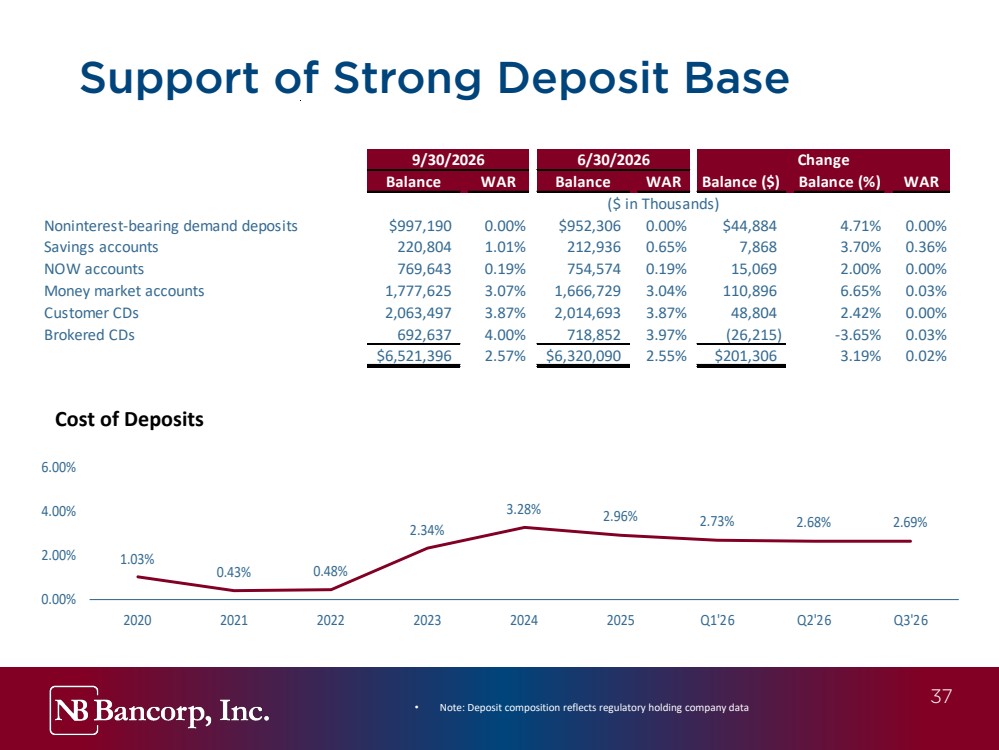
| 37 • Note: Deposit composition reflects regulatory holding company data Support of Strong Deposit Base Cost of Deposits 37 1.03% 0.43% 0.48% 2.34% 3.28% 2.96% 2.73% 2.68% 2.69% 0.00% 2.00% 4.00% 6.00% 2020 2021 2022 2023 2024 2025 Q1'26 Q2'26 Q3'26 Balance WAR Balance WAR Balance ($) Balance (%) WAR Noninterest-bearing demand deposits $997,190 0.00% $952,306 0.00% $44,884 4.71% 0.00% Savings accounts 220,804 1.01% 212,936 0.65% 7,868 3.70% 0.36% NOW accounts 769,643 0.19% 754,574 0.19% 15,069 2.00% 0.00% Money market accounts 1,777,625 3.07% 1,666,729 3.04% 110,896 6.65% 0.03% Customer CDs 2,063,497 3.87% 2,014,693 3.87% 48,804 2.42% 0.00% Brokered CDs 692,637 4.00% 718,852 3.97% (26,215) -3.65% 0.03% $6,521,396 2.57% $6,320,090 2.55% $201,306 3.19% 0.02% 9/30/2026 6/30/2026 Change ($ in Thousands) |
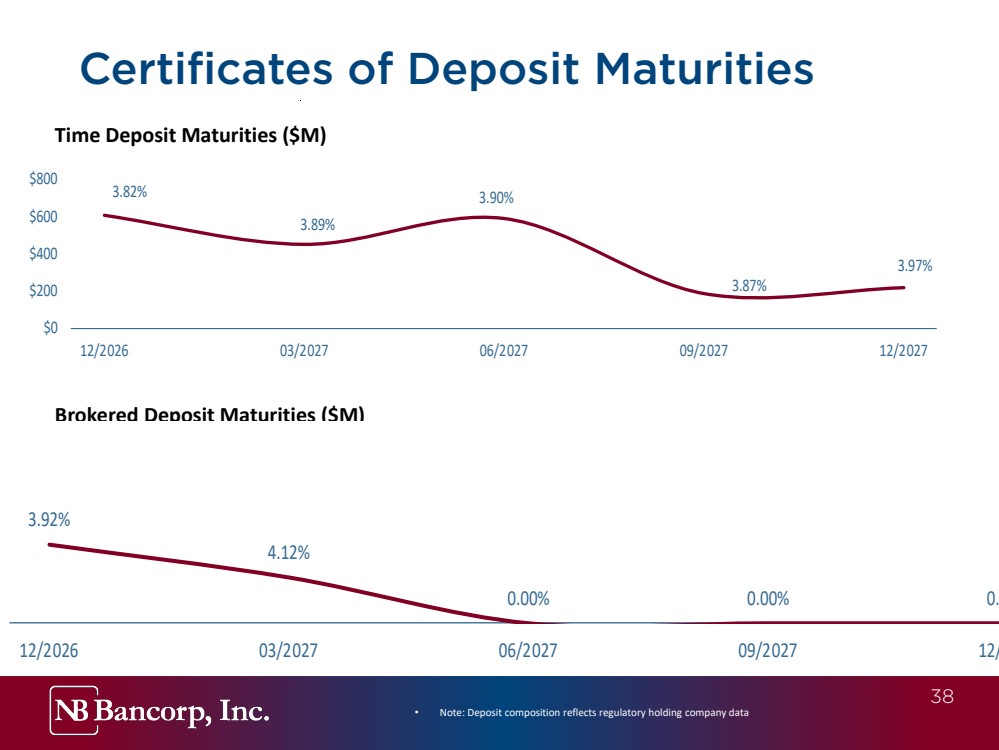
| 38 • Note: Deposit composition reflects regulatory holding company data Certificates of Deposit Maturities 38 Time Deposit Maturities ($M) Brokered Deposit Maturities ($M) 3.82% 3.89% 3.90% 3.87% 3.97% $0 $200 $400 $600 $800 12/2026 03/2027 06/2027 09/2027 12/2027 3.92% 4.12% 0.00% 0.00% 0. 12/2026 03/2027 06/2027 09/2027 12/ |
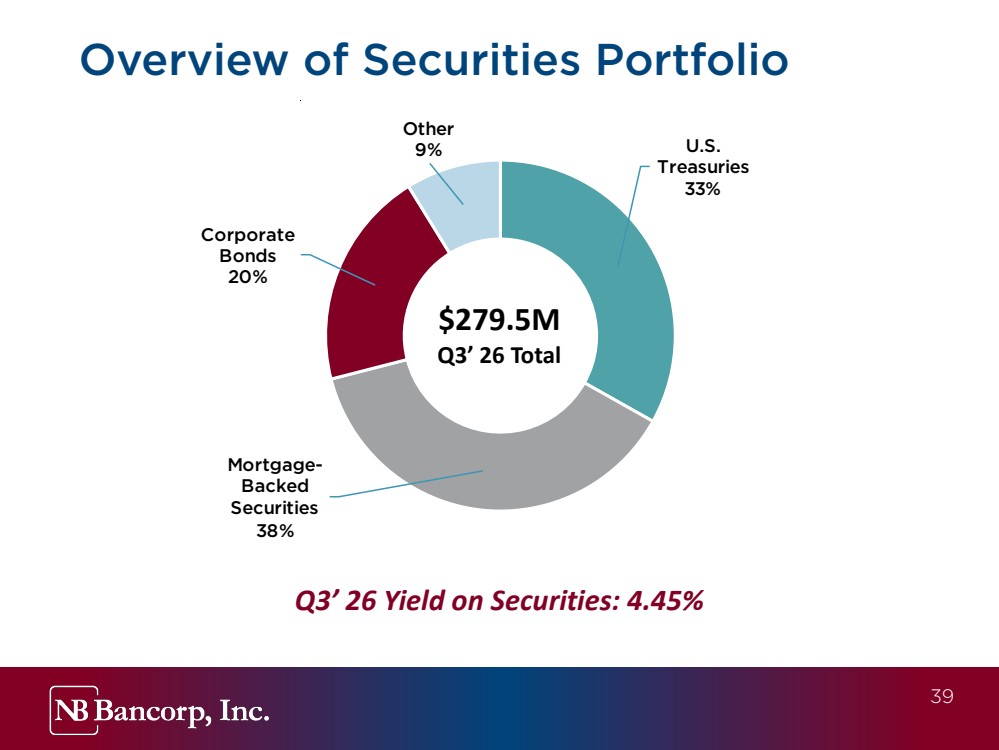
| 39 U.S. Treasuries 33% Mortgage-Backed Securities 38% Corporate Bonds 20% Other 9% Overview of Securities Portfolio $279.5M Q3’ 26 Total Q3’ 26 Yield on Securities: 4.45% 39 |
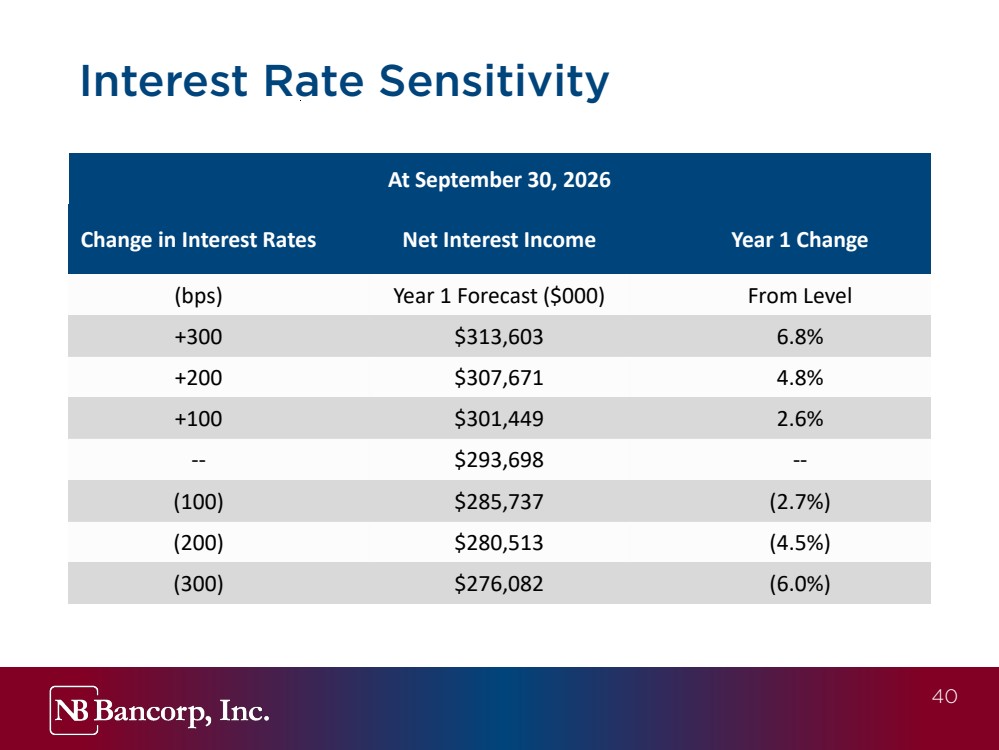
| 40 Interest Rate Sensitivity At September 30, 2026 Change in Interest Rates Net Interest Income Year 1 Change (bps) Year 1 Forecast ($000) From Level +300 $313,603 6.8% +200 $307,671 4.8% +100 $301,449 2.6% -- $293,698 -- (100) $285,737 (2.7%) (200) $280,513 (4.5%) (300) $276,082 (6.0%) 40 |
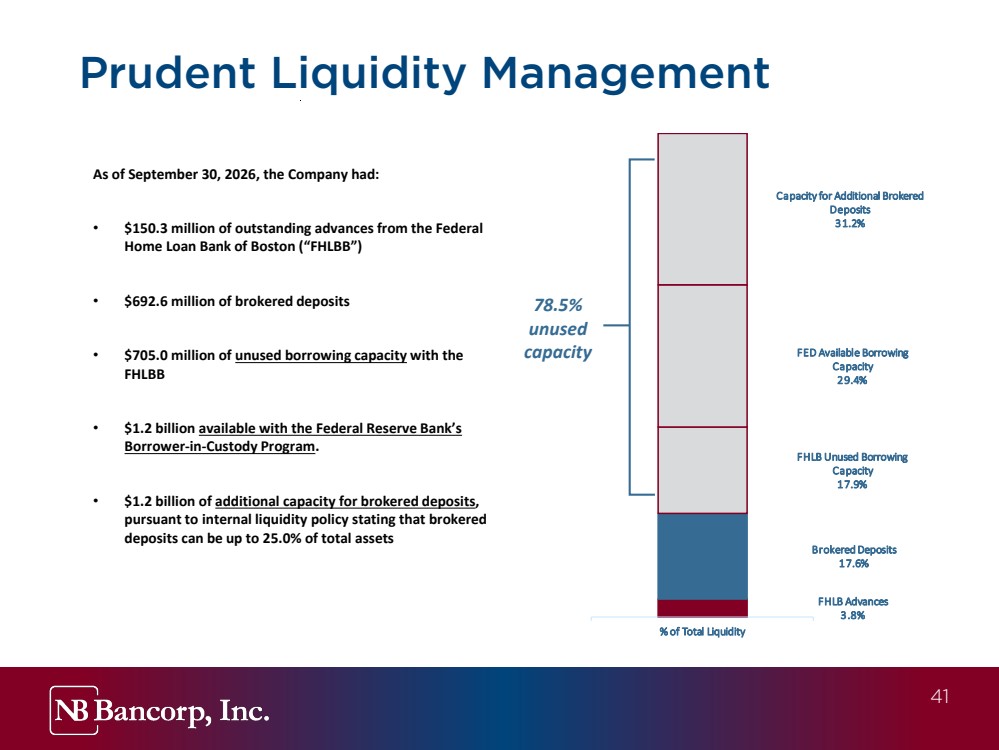
| 41 FHLB Advances 3.8% Brokered Deposits 17.6% FHLB Unused Borrowing Capacity 17.9% FED Available Borrowing Capacity 29.4% Capacity for Additional Brokered Deposits 31.2% % of Total Liquidity Prudent Liquidity Management As of September 30, 2026, the Company had: • $150.3 million of outstanding advances from the Federal Home Loan Bank of Boston (“FHLBB”) • $692.6 million of brokered deposits • $705.0 million of unused borrowing capacity with the FHLBB • $1.2 billion available with the Federal Reserve Bank’s Borrower-in-Custody Program. • $1.2 billion of additional capacity for brokered deposits, pursuant to internal liquidity policy stating that brokered deposits can be up to 25.0% of total assets 78.5% unused capacity 41 |
| 42 Appendix |
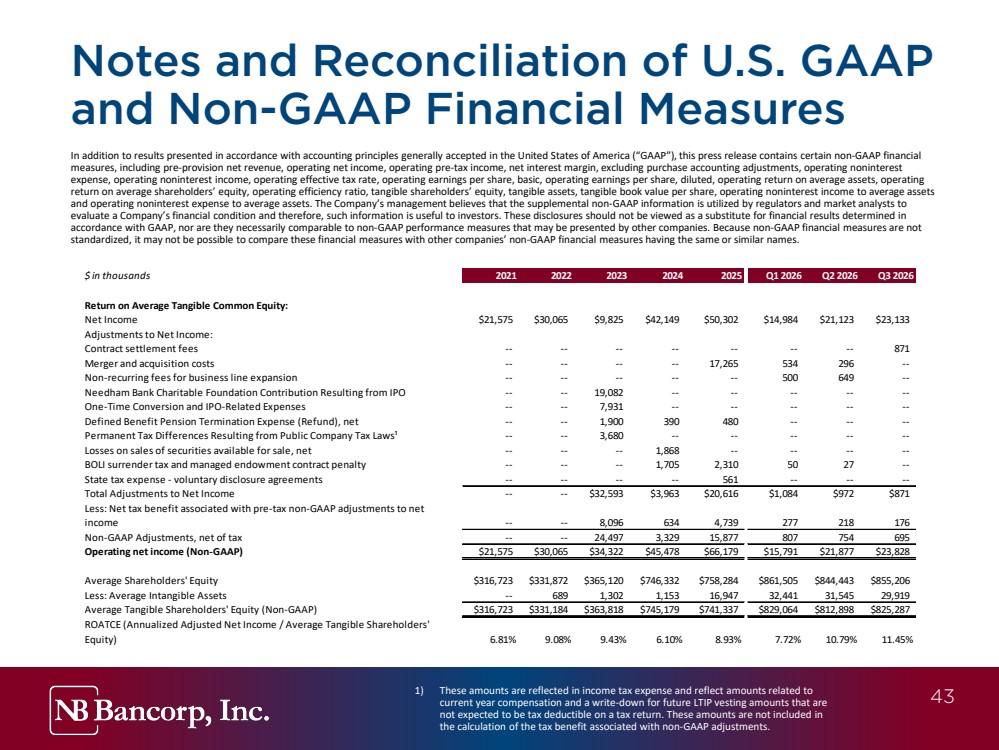
| 43 Notes and Reconciliation of U.S. GAAP and Non-GAAP Financial Measures In addition to results presented in accordance with accounting principles generally accepted in the United States of America (“GAAP”), this press release contains certain non-GAAP financial measures, including pre-provision net revenue, operating net income, operating pre-tax income, net interest margin, excluding purchase accounting adjustments, operating noninterest expense, operating noninterest income, operating effective tax rate, operating earnings per share, basic, operating earnings per share, diluted, operating return on average assets, operating return on average shareholders’ equity, operating efficiency ratio, tangible shareholders’ equity, tangible assets, tangible book value per share, operating noninterest income to average assets and operating noninterest expense to average assets. The Company’s management believes that the supplemental non-GAAP information is utilized by regulators and market analysts to evaluate a Company’s financial condition and therefore, such information is useful to investors. These disclosures should not be viewed as a substitute for financial results determined in accordance with GAAP, nor are they necessarily comparable to non-GAAP performance measures that may be presented by other companies. Because non-GAAP financial measures are not standardized, it may not be possible to compare these financial measures with other companies’ non-GAAP financial measures having the same or similar names. 1) These amounts are reflected in income tax expense and reflect amounts related to current year compensation and a write-down for future LTIP vesting amounts that are not expected to be tax deductible on a tax return. These amounts are not included in the calculation of the tax benefit associated with non-GAAP adjustments. 43 $ in thousands 2021 2022 2023 2024 2025 Q1 2026 Q2 2026 Q3 2026 Return on Average Tangible Common Equity: Net Income $21,575 $30,065 $9,825 $42,149 $50,302 $14,984 $21,123 $23,133 Adjustments to Net Income: Contract settlement fees -- -- -- -- -- -- -- 871 Merger and acquisition costs -- -- -- -- 17,265 534 296 -- Non-recurring fees for business line expansion -- -- -- -- -- 500 649 -- Needham Bank Charitable Foundation Contribution Resulting from IPO -- -- 19,082 -- -- -- -- -- One-Time Conversion and IPO-Related Expenses -- -- 7,931 -- -- -- -- -- Defined Benefit Pension Termination Expense (Refund), net -- -- 1,900 390 480 -- -- -- Permanent Tax Differences Resulting from Public Company Tax Laws¹ -- -- 3,680 -- -- -- -- -- Losses on sales of securities available for sale, net -- -- -- 1,868 -- -- -- -- BOLI surrender tax and managed endowment contract penalty -- -- -- 1,705 2,310 50 27 -- State tax expense - voluntary disclosure agreements -- -- -- -- 561 -- -- -- Total Adjustments to Net Income -- -- $32,593 $3,963 $20,616 $1,084 $972 $871 Less: Net tax benefit associated with pre-tax non-GAAP adjustments to net income -- -- 8,096 634 4,739 277 218 176 Non-GAAP Adjustments, net of tax -- -- 24,497 3,329 15,877 807 754 695 Operating net income (Non-GAAP) $21,575 $30,065 $34,322 $45,478 $66,179 $15,791 $21,877 $23,828 Average Shareholders' Equity $316,723 $331,872 $365,120 $746,332 $758,284 $861,505 $844,443 $855,206 Less: Average Intangible Assets -- 689 1,302 1,153 16,947 32,441 31,545 29,919 Average Tangible Shareholders' Equity (Non-GAAP) $316,723 $331,184 $363,818 $745,179 $741,337 $829,064 $812,898 $825,287 ROATCE (Annualized Adjusted Net Income / Average Tangible Shareholders' Equity) 6.81% 9.08% 9.43% 6.10% 8.93% 7.72% 10.79% 11.45% |
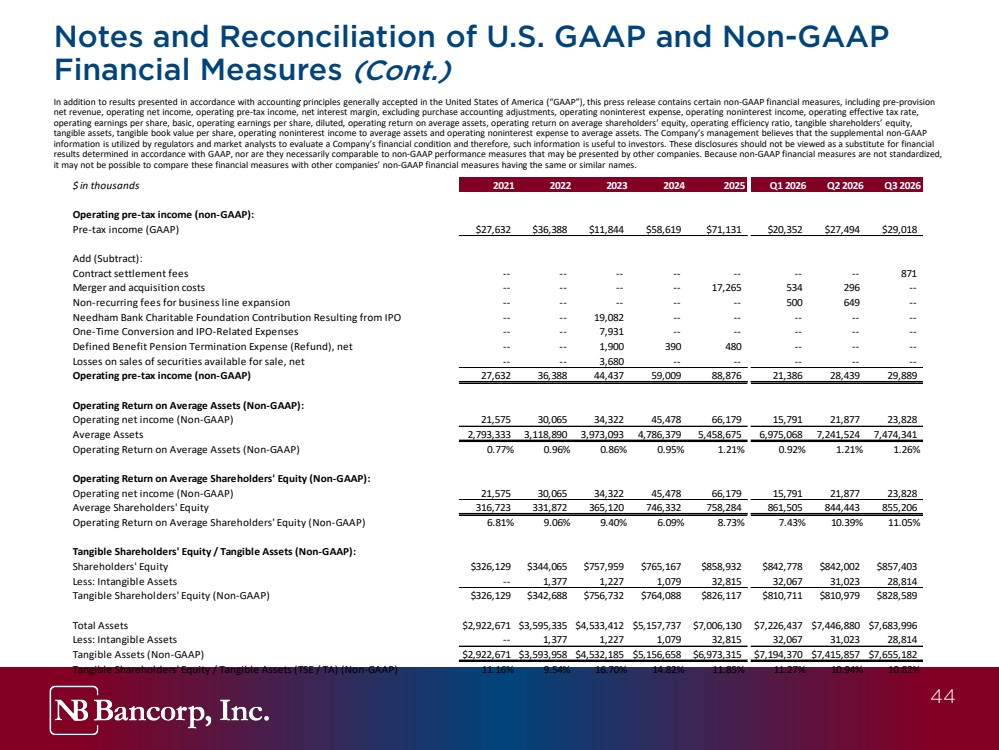
| 44 Notes and Reconciliation of U.S. GAAP and Non-GAAP Financial Measures (Cont.) 44 In addition to results presented in accordance with accounting principles generally accepted in the United States of America (“GAAP”), this press release contains certain non-GAAP financial measures, including pre-provision net revenue, operating net income, operating pre-tax income, net interest margin, excluding purchase accounting adjustments, operating noninterest expense, operating noninterest income, operating effective tax rate, operating earnings per share, basic, operating earnings per share, diluted, operating return on average assets, operating return on average shareholders’ equity, operating efficiency ratio, tangible shareholders’ equity, tangible assets, tangible book value per share, operating noninterest income to average assets and operating noninterest expense to average assets. The Company’s management believes that the supplemental non-GAAP information is utilized by regulators and market analysts to evaluate a Company’s financial condition and therefore, such information is useful to investors. These disclosures should not be viewed as a substitute for financial results determined in accordance with GAAP, nor are they necessarily comparable to non-GAAP performance measures that may be presented by other companies. Because non-GAAP financial measures are not standardized, it may not be possible to compare these financial measures with other companies’ non-GAAP financial measures having the same or similar names. $ in thousands 2021 2022 2023 2024 2025 Q1 2026 Q2 2026 Q3 2026 Operating pre-tax income (non-GAAP): Pre-tax income (GAAP) $27,632 $36,388 $11,844 $58,619 $71,131 $20,352 $27,494 $29,018 Add (Subtract): Contract settlement fees -- -- -- -- -- -- -- 871 Merger and acquisition costs -- -- -- -- 17,265 534 296 -- Non-recurring fees for business line expansion -- -- -- -- -- 500 649 -- Needham Bank Charitable Foundation Contribution Resulting from IPO -- -- 19,082 -- -- -- -- -- One-Time Conversion and IPO-Related Expenses -- -- 7,931 -- -- -- -- -- Defined Benefit Pension Termination Expense (Refund), net -- -- 1,900 390 480 -- -- -- Losses on sales of securities available for sale, net -- -- 3,680 -- -- -- -- -- Operating pre-tax income (non-GAAP) 27,632 36,388 44,437 59,009 88,876 21,386 28,439 29,889 Operating Return on Average Assets (Non-GAAP): Operating net income (Non-GAAP) 21,575 30,065 34,322 45,478 66,179 15,791 21,877 23,828 Average Assets 2,793,333 3,118,890 3,973,093 4,786,379 5,458,675 6,975,068 7,241,524 7,474,341 Operating Return on Average Assets (Non-GAAP) 0.77% 0.96% 0.86% 0.95% 1.21% 0.92% 1.21% 1.26% Operating Return on Average Shareholders' Equity (Non-GAAP): Operating net income (Non-GAAP) 21,575 30,065 34,322 45,478 66,179 15,791 21,877 23,828 Average Shareholders' Equity 316,723 331,872 365,120 746,332 758,284 861,505 844,443 855,206 Operating Return on Average Shareholders' Equity (Non-GAAP) 6.81% 9.06% 9.40% 6.09% 8.73% 7.43% 10.39% 11.05% Tangible Shareholders' Equity / Tangible Assets (Non-GAAP): Shareholders' Equity $326,129 $344,065 $757,959 $765,167 $858,932 $842,778 $842,002 $857,403 Less: Intangible Assets -- 1,377 1,227 1,079 32,815 32,067 31,023 28,814 Tangible Shareholders' Equity (Non-GAAP) $326,129 $342,688 $756,732 $764,088 $826,117 $810,711 $810,979 $828,589 Total Assets $2,922,671 $3,595,335 $4,533,412 $5,157,737 $7,006,130 $7,226,437 $7,446,880 $7,683,996 Less: Intangible Assets -- 1,377 1,227 1,079 32,815 32,067 31,023 28,814 Tangible Assets (Non-GAAP) $2,922,671 $3,593,958 $4,532,185 $5,156,658 $6,973,315 $7,194,370 $7,415,857 $7,655,182 Tangible Shareholders' Equity / Tangible Assets (TSE / TA) (Non-GAAP) 11.16% 9.54% 16.70% 14.82% 11.85% 11.27% 10.94% 10.82% |
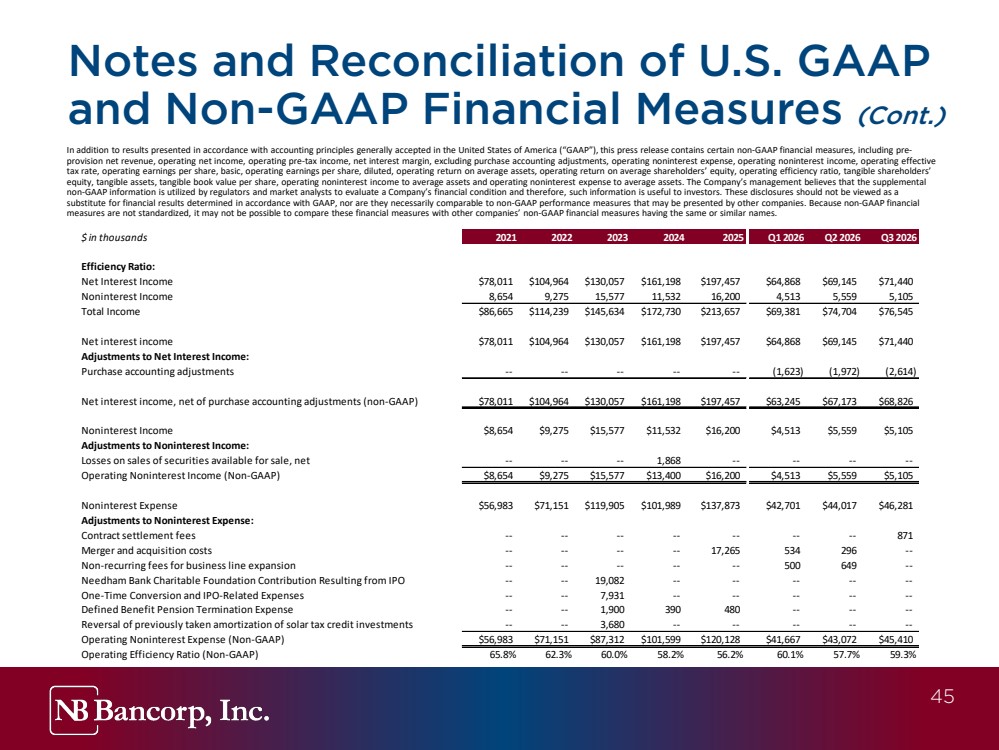
| 45 Notes and Reconciliation of U.S. GAAP and Non-GAAP Financial Measures (Cont.) 45 In addition to results presented in accordance with accounting principles generally accepted in the United States of America (“GAAP”), this press release contains certain non-GAAP financial measures, including pre-provision net revenue, operating net income, operating pre-tax income, net interest margin, excluding purchase accounting adjustments, operating noninterest expense, operating noninterest income, operating effective tax rate, operating earnings per share, basic, operating earnings per share, diluted, operating return on average assets, operating return on average shareholders’ equity, operating efficiency ratio, tangible shareholders’ equity, tangible assets, tangible book value per share, operating noninterest income to average assets and operating noninterest expense to average assets. The Company’s management believes that the supplemental non-GAAP information is utilized by regulators and market analysts to evaluate a Company’s financial condition and therefore, such information is useful to investors. These disclosures should not be viewed as a substitute for financial results determined in accordance with GAAP, nor are they necessarily comparable to non-GAAP performance measures that may be presented by other companies. Because non-GAAP financial measures are not standardized, it may not be possible to compare these financial measures with other companies’ non-GAAP financial measures having the same or similar names. $ in thousands 2021 2022 2023 2024 2025 Q1 2026 Q2 2026 Q3 2026 Efficiency Ratio: Net Interest Income $78,011 $104,964 $130,057 $161,198 $197,457 $64,868 $69,145 $71,440 Noninterest Income 8,654 9,275 15,577 11,532 16,200 4,513 5,559 5,105 Total Income $86,665 $114,239 $145,634 $172,730 $213,657 $69,381 $74,704 $76,545 Net interest income $78,011 $104,964 $130,057 $161,198 $197,457 $64,868 $69,145 $71,440 Adjustments to Net Interest Income: Purchase accounting adjustments -- -- -- -- -- (1,623) (1,972) (2,614) Net interest income, net of purchase accounting adjustments (non-GAAP) $78,011 $104,964 $130,057 $161,198 $197,457 $63,245 $67,173 $68,826 Noninterest Income $8,654 $9,275 $15,577 $11,532 $16,200 $4,513 $5,559 $5,105 Adjustments to Noninterest Income: Losses on sales of securities available for sale, net -- -- -- 1,868 -- -- -- -- Operating Noninterest Income (Non-GAAP) $8,654 $9,275 $15,577 $13,400 $16,200 $4,513 $5,559 $5,105 Noninterest Expense $56,983 $71,151 $119,905 $101,989 $137,873 $42,701 $44,017 $46,281 Adjustments to Noninterest Expense: Contract settlement fees -- -- -- -- -- -- -- 871 Merger and acquisition costs -- -- -- -- 17,265 534 296 -- Non-recurring fees for business line expansion -- -- -- -- -- 500 649 -- Needham Bank Charitable Foundation Contribution Resulting from IPO -- -- 19,082 -- -- -- -- -- One-Time Conversion and IPO-Related Expenses -- -- 7,931 -- -- -- -- -- Defined Benefit Pension Termination Expense -- -- 1,900 390 480 -- -- -- Reversal of previously taken amortization of solar tax credit investments -- -- 3,680 -- -- -- -- -- Operating Noninterest Expense (Non-GAAP) $56,983 $71,151 $87,312 $101,599 $120,128 $41,667 $43,072 $45,410 Operating Efficiency Ratio (Non-GAAP) 65.8% 62.3% 60.0% 58.2% 56.2% 60.1% 57.7% 59.3% |
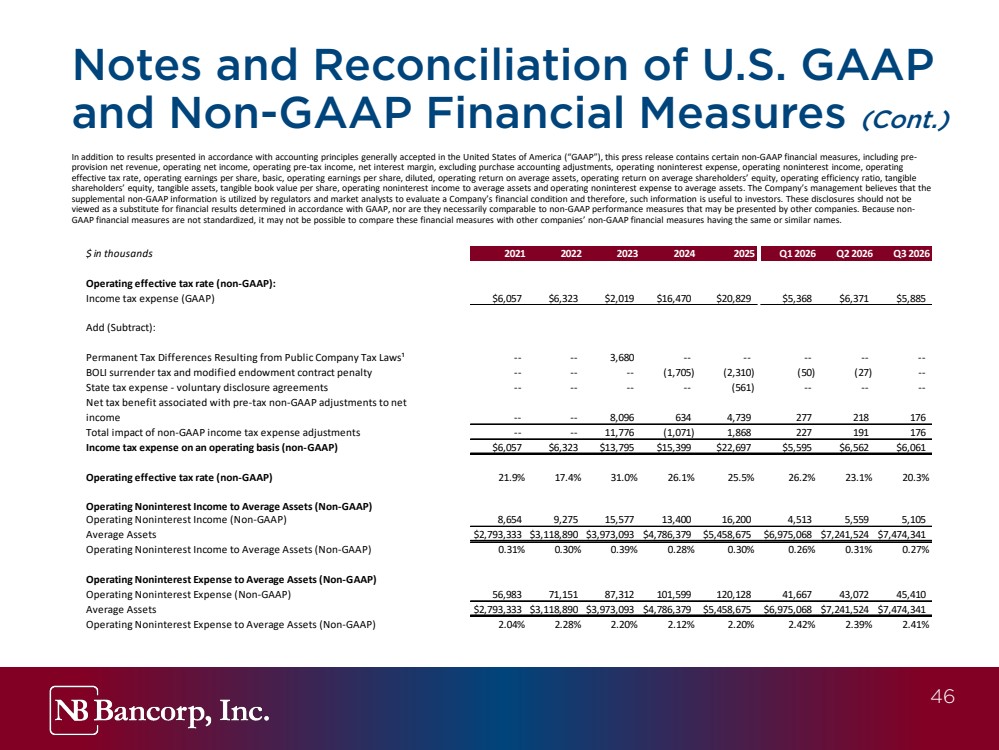
| 46 Notes and Reconciliation of U.S. GAAP and Non-GAAP Financial Measures (Cont.) 46 In addition to results presented in accordance with accounting principles generally accepted in the United States of America (“GAAP”), this press release contains certain non-GAAP financial measures, including pre-provision net revenue, operating net income, operating pre-tax income, net interest margin, excluding purchase accounting adjustments, operating noninterest expense, operating noninterest income, operating effective tax rate, operating earnings per share, basic, operating earnings per share, diluted, operating return on average assets, operating return on average shareholders’ equity, operating efficiency ratio, tangible shareholders’ equity, tangible assets, tangible book value per share, operating noninterest income to average assets and operating noninterest expense to average assets. The Company’s management believes that the supplemental non-GAAP information is utilized by regulators and market analysts to evaluate a Company’s financial condition and therefore, such information is useful to investors. These disclosures should not be viewed as a substitute for financial results determined in accordance with GAAP, nor are they necessarily comparable to non-GAAP performance measures that may be presented by other companies. Because non-GAAP financial measures are not standardized, it may not be possible to compare these financial measures with other companies’ non-GAAP financial measures having the same or similar names. $ in thousands 2021 2022 2023 2024 2025 Q1 2026 Q2 2026 Q3 2026 Operating effective tax rate (non-GAAP): Income tax expense (GAAP) $6,057 $6,323 $2,019 $16,470 $20,829 $5,368 $6,371 $5,885 Add (Subtract): Permanent Tax Differences Resulting from Public Company Tax Laws¹ -- -- 3,680 -- -- -- -- -- BOLI surrender tax and modified endowment contract penalty -- -- -- (1,705) (2,310) (50) (27) -- State tax expense - voluntary disclosure agreements -- -- -- -- (561) -- -- -- Net tax benefit associated with pre-tax non-GAAP adjustments to net income -- -- 8,096 634 4,739 277 218 176 Total impact of non-GAAP income tax expense adjustments -- -- 11,776 (1,071) 1,868 227 191 176 Income tax expense on an operating basis (non-GAAP) $6,057 $6,323 $13,795 $15,399 $22,697 $5,595 $6,562 $6,061 Operating effective tax rate (non-GAAP) 21.9% 17.4% 31.0% 26.1% 25.5% 26.2% 23.1% 20.3% Operating Noninterest Income to Average Assets (Non-GAAP) Operating Noninterest Income (Non-GAAP) 8,654 9,275 15,577 13,400 16,200 4,513 5,559 5,105 Average Assets $2,793,333 $3,118,890 $3,973,093 $4,786,379 $5,458,675 $6,975,068 $7,241,524 $7,474,341 Operating Noninterest Income to Average Assets (Non-GAAP) 0.31% 0.30% 0.39% 0.28% 0.30% 0.26% 0.31% 0.27% Operating Noninterest Expense to Average Assets (Non-GAAP) Operating Noninterest Expense (Non-GAAP) 56,983 71,151 87,312 101,599 120,128 41,667 43,072 45,410 Average Assets $2,793,333 $3,118,890 $3,973,093 $4,786,379 $5,458,675 $6,975,068 $7,241,524 $7,474,341 Operating Noninterest Expense to Average Assets (Non-GAAP) 2.04% 2.28% 2.20% 2.12% 2.20% 2.42% 2.39% 2.41% |
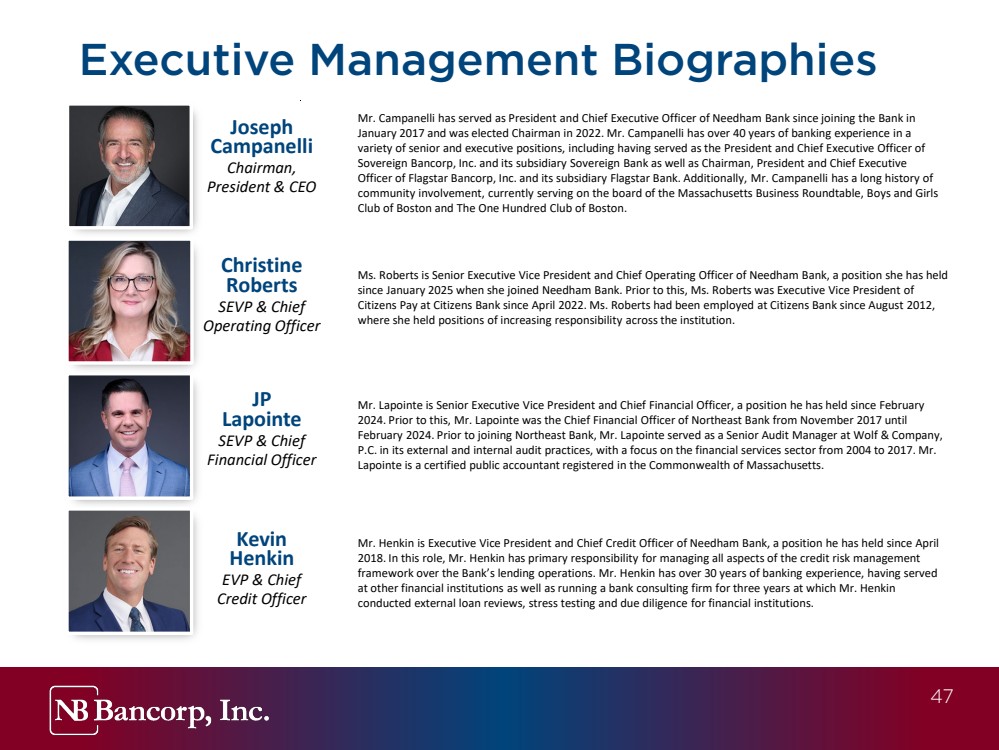
| 47 Executive Management Biographies Joseph Campanelli Chairman, President & CEO Christine Roberts SEVP & Chief Operating Officer JP Lapointe SEVP & Chief Financial Officer Mr. Campanelli has served as President and Chief Executive Officer of Needham Bank since joining the Bank in January 2017 and was elected Chairman in 2022. Mr. Campanelli has over 40 years of banking experience in a variety of senior and executive positions, including having served as the President and Chief Executive Officer of Sovereign Bancorp, Inc. and its subsidiary Sovereign Bank as well as Chairman, President and Chief Executive Officer of Flagstar Bancorp, Inc. and its subsidiary Flagstar Bank. Additionally, Mr. Campanelli has a long history of community involvement, currently serving on the board of the Massachusetts Business Roundtable, Boys and Girls Club of Boston and The One Hundred Club of Boston. Ms. Roberts is Senior Executive Vice President and Chief Operating Officer of Needham Bank, a position she has held since January 2025 when she joined Needham Bank. Prior to this, Ms. Roberts was Executive Vice President of Citizens Pay at Citizens Bank since April 2022. Ms. Roberts had been employed at Citizens Bank since August 2012, where she held positions of increasing responsibility across the institution. Mr. Lapointe is Senior Executive Vice President and Chief Financial Officer, a position he has held since February 2024. Prior to this, Mr. Lapointe was the Chief Financial Officer of Northeast Bank from November 2017 until February 2024. Prior to joining Northeast Bank, Mr. Lapointe served as a Senior Audit Manager at Wolf & Company, P.C. in its external and internal audit practices, with a focus on the financial services sector from 2004 to 2017. Mr. Lapointe is a certified public accountant registered in the Commonwealth of Massachusetts. Kevin Henkin EVP & Chief Credit Officer Mr. Henkin is Executive Vice President and Chief Credit Officer of Needham Bank, a position he has held since April 2018. In this role, Mr. Henkin has primary responsibility for managing all aspects of the credit risk management framework over the Bank’s lending operations. Mr. Henkin has over 30 years of banking experience, having served at other financial institutions as well as running a bank consulting firm for three years at which Mr. Henkin conducted external loan reviews, stress testing and due diligence for financial institutions. 47 |
| 48 Thank You |